
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Pea Proteins Market Size 2024 | USD 65.48 million |
| India Pea Proteins Market, CAGR | 14.43% |
| India Pea Proteins Market Size 2032 | USD 192.52 million |
Market Overview:
The India Pea Proteins Market is projected to grow from USD 65.48 million in 2024 to an estimated USD 192.52 million by 2032, with a compound annual growth rate (CAGR) of 14.43% from 2024 to 2032.
Several key factors are driving the growth of the pea proteins market in India. Firstly, there is an increasing demand for plant-based protein sources, particularly among consumers who are adopting vegetarian or vegan lifestyles. This is coupled with growing awareness about the health benefits of plant-based proteins, such as lower fat content, higher fiber, and essential amino acids. Additionally, concerns over the environmental impact of animal agriculture and its contribution to climate change have prompted consumers to shift towards more sustainable protein sources like peas. The expanding demand for vegan and plant-based alternatives in sectors like food and beverages, sports nutrition, and snacks is expected to boost market growth. Furthermore, the rising number of health-conscious individuals who are turning to plant-based diets for weight management, improved digestion, and overall health benefits is propelling the demand for pea protein products.
The India pea proteins market is witnessing robust growth across different regions of the country, although urban areas are the primary drivers of the market. Major cities like Mumbai, Delhi, Bangalore, and Chennai have experienced heightened demand for plant-based protein products, owing to the growing awareness of health and wellness trends among urban consumers. Additionally, these cities have a large number of health-conscious individuals and fitness enthusiasts, which further promotes the demand for plant-based proteins in sports nutrition products. However, the market is also expanding to semi-urban and rural areas as awareness of plant-based diets and the associated health benefits spreads beyond metropolitan areas. Regionally, the northern and southern parts of India are the most prominent in terms of market growth, driven by a strong tradition of vegetarian diets and the rising popularity of veganism and plant-based products.
Market Insights:
- The India pea proteins market is projected to grow from USD 48.46 million in 2024 to USD 147.89 million by 2032, reflecting a CAGR of 14.97%.
- Growing demand for plant-based proteins, particularly among vegetarians and vegans, is a key driver of market expansion.
- The increasing awareness of health benefits, including lower fat and higher fiber content in pea proteins, is contributing to the market's growth.
- Environmental concerns about animal agriculture, such as carbon footprint and water usage, are leading consumers to opt for sustainable alternatives like pea protein.
- Innovation in food products, particularly in plant-based meats and dairy alternatives, is helping to expand the pea proteins market.
- High production costs, including raw material procurement and processing, remain a significant challenge for the market's growth.
- Regional growth is strong in urban areas like Mumbai, Delhi, and Bangalore, but semi-urban and rural regions are also witnessing an increase in pea protein awareness.
Report scope
This reports segments are India Pea Proteins Market as follows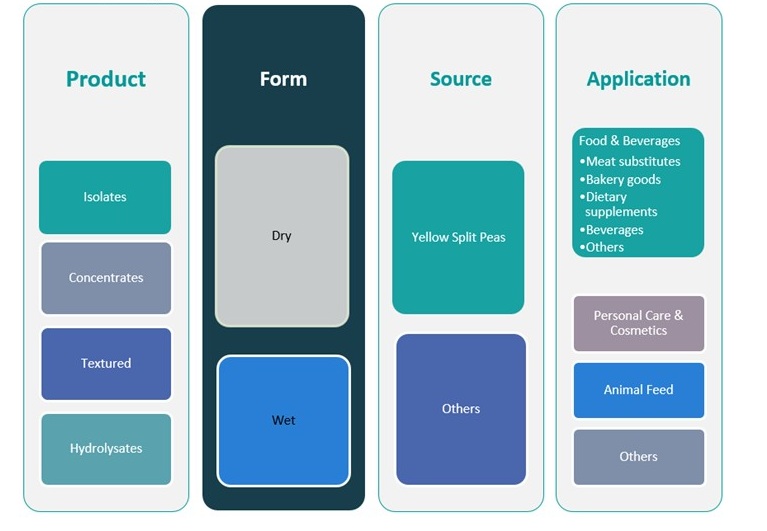
Market Drivers:
Growing Demand for Plant-Based Proteins
One of the primary drivers of the India pea proteins market is the increasing demand for plant-based proteins. As consumers shift toward plant-based diets for health, ethical, and environmental reasons, plant-based protein sources such as pea protein are gaining prominence. This demand is particularly noticeable among younger generations and health-conscious individuals who are adopting vegetarian or vegan lifestyles. Pea protein, with its high nutritional profile, including essential amino acids, is perceived as an ideal alternative to animal-based proteins. As the awareness of the health benefits of plant-based diets continues to rise, the demand for pea protein products across various sectors, such as food and beverages, snacks, and sports nutrition, is expected to increase significantly.
Health and Wellness Trends
The growing focus on health and wellness is another significant driver for the pea proteins market in India. With rising concerns about lifestyle diseases, including obesity, diabetes, and cardiovascular conditions, consumers are increasingly adopting cleaner and healthier diets. Pea protein, which is rich in fiber and low in fat, is perceived as a healthier option compared to animal-derived protein sources. Its digestibility and hypoallergenic properties further contribute to its appeal among individuals with food sensitivities. For instance, companies like Beyond Meat have expanded their offerings with pea protein-based chicken substitutes to meet this demand for clean-label vegan options. As more consumers seek functional foods that offer both taste and nutritional benefits, pea protein has become an essential ingredient in various food products, including protein bars, shakes, and meat alternatives. This trend is expected to continue to fuel the market's growth.
Environmental Sustainability and Ethical Considerations
The growing awareness of environmental sustainability and ethical considerations surrounding animal agriculture has spurred the demand for plant-based proteins, including pea protein. The environmental impact of meat production, such as greenhouse gas emissions, deforestation, and water usage, has prompted many consumers to seek more sustainable alternatives. Pea protein offers a eco-friendlier solution as it requires fewer resources, such as water and land, and produces a lower carbon footprint compared to animal-based proteins. Moreover, pea protein is non-GMO and allergen-free, which further appeals to consumers who prioritize sustainability and ethical sourcing. As sustainability becomes a key factor in purchasing decisions, the demand for pea protein is expected to grow, particularly among environmentally-conscious consumers.
Innovation in Food and Beverage Products
Innovation in food and beverage products is also playing a significant role in driving the India pea proteins market. As manufacturers explore new ways to incorporate plant-based proteins into everyday food products, pea protein is increasingly being included in a wide range of offerings, from dairy alternatives to ready-to-eat meals and snacks. For instance, pea protein’s functional properties and its fractions’ ability to form soft gels help develop and produce dairy analog drinks, fermented products, and curd. This innovation is helping to expand the market by making pea protein products more accessible and appealing to mainstream consumers. Additionally, the development of new and improved processing techniques has enhanced the taste and texture of pea protein, making it more attractive as a meat substitute in plant-based products. As the food industry continues to innovate and introduce new pea protein-based products, the market is expected to experience sustained growth.
Market Trends:
Rising Popularity of Vegan and Plant-Based Diets
A significant trend driving the India pea proteins market is the rising popularity of vegan and plant-based diets. Over the past decade, the number of individuals adopting plant-based or flexitarian diets has grown substantially. This shift toward plant-based eating, driven by concerns over health, animal welfare, and sustainability, has significantly boosted the demand for pea protein as a key ingredient in plant-based food products. Consumers are increasingly seeking protein alternatives that align with their dietary choices, and pea protein, with its complete amino acid profile and digestibility, is emerging as a popular solution.
Growth of Plant-Based Meat Alternatives
The growing popularity of plant-based meat alternatives is another major trend influencing the India pea proteins market. As more consumers choose plant-based diets or reduce their meat consumption, the demand for plant-based meat alternatives is escalating. Pea protein, due to its neutral flavor and functional properties, is increasingly being used in plant-based meat products like burgers, sausages, and nuggets. For instance, companies like Beyond Meat have expanded their offerings with pea protein-based chicken substitutes to meet this demand for clean-label vegan options. The advancement of food technology and innovation in plant-based meat alternatives is enabling manufacturers to create products that closely resemble the texture and taste of traditional meat, driving the adoption of pea protein in this sector.
Clean Label and Transparency Trends
The growing demand for clean-label products is another notable trend in the Indian pea proteins market. Indian consumers are becoming increasingly conscious of the ingredients in their food and prefer products that are natural, non-GMO, and free from artificial additives or preservatives. For instance, Radipure™ pea protein also has label-friendly, low allergenic, and non-GMO features. Pea protein fits well within this trend, as it is considered a clean and natural ingredient, aligning with consumer preferences for products that are simple, transparent, and healthier. The rise in clean-label products has led to a surge in the use of pea protein in a wide array of food categories, including bakery, beverages, and snacks.
Increased Focus on Functional Foods and Nutritional Products
As health-conscious consumers seek products that not only provide nutrition but also offer functional benefits, the demand for pea protein in functional foods and nutritional products is growing. Pea protein is increasingly incorporated into protein powders, bars, and supplements due to its high protein content, digestive benefits, and ability to support muscle growth and recovery. Additionally, the rise of fitness culture, especially among the urban youth, has contributed to the popularity of pea protein-based nutritional products. The functional foods market in India, which includes products with added health benefits, is expected to grow at a steady pace, providing further opportunities for pea protein to be used as a key ingredient in the formulation of products targeting specific health and wellness needs, such as weight management and sports performance.
Market Challenges Analysis:
High Cost of Production
One of the key challenges facing the India pea proteins market is the relatively high cost of production. While pea protein offers several benefits in terms of health and sustainability, the process of extracting protein from peas can be expensive. This includes costs associated with raw material procurement, processing, and packaging. Additionally, compared to traditional animal-based proteins, pea protein production remains costlier, which can affect the price point for end consumers. For instance, setting up a pea protein manufacturing plant requires capital investments ranging from USD 1 million to USD 5 million, depending on scale and technology used. As a result, higher prices for pea protein-based products may limit their accessibility and appeal, particularly in price-sensitive markets within India.
Supply Chain and Raw Material Limitations
The availability and consistency of pea supply are another challenge in the Indian pea proteins market. Peas are not a staple crop in India, and the country’s domestic production of peas is limited compared to global producers like Canada and Russia. This dependency on imports can lead to fluctuations in the availability and cost of raw peas, which directly affects the production and pricing of pea protein. Moreover, limited local cultivation infrastructure and seasonality of pea farming can create supply chain issues, potentially leading to supply disruptions and impacting the overall market growth.
Consumer Awareness and Education
While pea protein is gaining popularity, a significant barrier to its widespread adoption is the lack of consumer awareness regarding its nutritional benefits and versatility. Many consumers in India remain unfamiliar with plant-based proteins and may be hesitant to switch from traditional animal-based proteins to alternatives like pea protein. Educating the consumer base on the benefits of pea protein, such as its amino acid profile and digestibility, is essential for market expansion. This requires significant investment in marketing and awareness campaigns by manufacturers to overcome skepticism and build consumer trust.
Regulatory Challenges
The regulatory environment for plant-based proteins in India is still evolving, which can pose challenges for market players. The absence of standardized regulations for labeling and quality control of plant-based products may lead to inconsistencies and regulatory hurdles. Companies may face difficulties in ensuring compliance with evolving standards, particularly in areas related to food safety, health claims, and ingredient sourcing. As the market grows, stricter regulations may be introduced, requiring companies to adapt quickly and manage compliance costs effectively.
Market Opportunities:
The India pea proteins market presents significant opportunities, driven by the increasing shift toward plant-based diets and the growing demand for sustainable protein alternatives. As more Indian consumers adopt vegan and vegetarian lifestyles, there is a rising need for plant-based protein sources that align with health, environmental, and ethical considerations. Pea protein, with its high protein content, essential amino acids, and hypoallergenic properties, is well-positioned to meet this demand. The growing trend of health-conscious consumers, particularly among the urban youth, opens up substantial opportunities for manufacturers to introduce pea protein-based products in various categories, including snacks, beverages, and ready-to-eat meals. Moreover, the increasing awareness about the benefits of plant-based proteins further bolsters market growth potential.
Additionally, the expanding plant-based meat sector presents a significant growth avenue for pea proteins in India. As plant-based meat alternatives gain popularity in the country, driven by the rise in flexitarian diets and ethical concerns regarding meat production, pea protein’s functional properties make it an ideal ingredient in plant-based meat products. The innovation in food technologies to improve the taste, texture, and appearance of plant-based meats also creates room for more widespread adoption of pea protein. Furthermore, with increasing investments in research and development and the expansion of distribution channels, manufacturers can tap into previously underserved markets, including semi-urban and rural regions, creating further growth opportunities for pea protein-based products.
Market Segmentation Analysis:
The India pea proteins market is segmented across various categories, including product type, application, form, and source, each contributing to the market’s growth and expansion.
By Product Segment:
Pea protein isolates dominate the market due to their high protein content and versatility, making them suitable for a wide range of applications, especially in food and beverages. Pea protein concentrates follow in demand, providing a cost-effective option for various formulations. Textured pea proteins are gaining traction in the plant-based meat substitute sector, driven by their ability to mimic meat textures. Hydrolysates, with their digestibility and functional properties, are increasingly used in sports nutrition and health supplements.
By Application Segment:
The food and beverages segment leads the market, with meat substitutes being the largest contributor. Plant-based meats made from pea proteins are becoming increasingly popular among Indian consumers. The bakery goods and beverages sectors are also significant due to rising consumer demand for plant-based products. Dietary supplements are witnessing growth, with pea protein being incorporated into protein powders and shakes. The personal care and cosmetics segment is gaining momentum as pea protein is used for its skin-conditioning benefits. Additionally, animal feed applications are growing as pea protein serves as a sustainable alternative to animal-based protein sources.
By Form Segment:
Dry pea protein holds the largest share, primarily due to its ease of use in various formulations and longer shelf life. Wet pea protein, though less prevalent, is gaining traction in the food industry for its higher solubility and functional properties.
By Source Segment:
Yellow split peas are the most commonly used source of pea protein, offering a high yield of protein content. Other sources include various leguminous plants, although their share in the market is smaller compared to yellow split peas.
Segmentation:
By Product Segment:
- Isolates
- Concentrates
- Textured
- Hydrolysates
By Application Segment:
- Food & Beverages
- Meat substitutes
- Bakery goods
- Dietary supplements
- Beverages
- Others
- Personal Care & Cosmetics
- Animal Feed
- Others
By Form Segment:
- Dry
- Wet
By Source Segment:
- Yellow Split Peas
- others
Regional Analysis:
The India pea proteins market exhibits diverse growth patterns across different regions, driven by varying consumer preferences, dietary trends, and market dynamics. The northern and southern regions of India are the primary drivers of the pea proteins market, with the western and eastern regions showing steady growth.
Northern Region (Market Share: 35%)
The northern region, encompassing major metropolitan areas such as Delhi, Chandigarh, and Jaipur, holds the largest market share in the India pea proteins market. The demand in this region is driven by an increasing number of health-conscious consumers and the growing popularity of plant-based diets, particularly among urban populations. Additionally, the rising number of fitness enthusiasts and the expansion of the plant-based meat market in cities like Delhi contribute to the strong demand for pea protein. The region also benefits from a growing awareness of sustainability and clean-label products, which supports the adoption of pea protein as a healthier and environmentally friendly alternative to animal-based proteins.
Southern Region (Market Share: 30%)
The southern region, which includes major cities like Bangalore, Chennai, and Hyderabad, is another key player in the pea proteins market. This region has witnessed a surge in demand for plant-based products due to the increasing adoption of vegetarian diets and the rise of veganism, particularly in urban areas. The southern part of India has a strong tradition of plant-based eating, and the trend toward plant-based proteins is further driven by consumer interest in healthy, sustainable, and functional foods. The growing focus on fitness, wellness, and weight management in southern cities has also spurred the demand for pea protein, especially in sports nutrition products.
Western Region (Market Share: 20%)
The western region, including cities like Mumbai, Pune, and Ahmedabad, holds a significant but slightly smaller market share compared to the north and south. However, this region is witnessing rapid growth due to the increasing awareness of plant-based diets and the expanding plant-based food market. Mumbai, as a major commercial hub, is home to several food innovation centers and R&D labs focused on plant-based alternatives, including pea protein-based products. The growth of the foodservice sector and the rise of plant-based cafes and restaurants in the region contribute to the demand for pea protein.
Eastern Region (Market Share: 15%)
The eastern region, which includes cities like Kolkata and Bhubaneswar, currently holds the smallest market share in the pea proteins market. However, this region shows potential for growth, especially as awareness of plant-based diets continues to spread. Traditional diets in eastern India are heavily reliant on rice and pulses, which creates a foundation for the adoption of pea protein in local diets. As distribution networks improve and consumer education initiatives increase, the eastern region is expected to witness a gradual rise in demand for pea protein-based products in the coming years.
Key Player Analysis:
- Archer Daniels Midland Company
- Cargill, Incorporated
- DuPont de Nemours Inc.
- Ingredion Incorporated
- Rajvi Enterprise
Competitive Analysis:
The India pea proteins market is highly competitive, with both global and domestic players striving to capture market share. Key players in the market include international companies such as Roquette, Cargill, and Ingredion, which have established a strong foothold due to their advanced technology, extensive distribution networks, and broad product offerings. These companies leverage their global supply chains and expertise to cater to the growing demand for plant-based protein solutions in India. Domestic players are also emerging in the market, with companies like Prolgae and Vegpro focusing on offering locally sourced pea protein products. These companies have an advantage in terms of cost-effectiveness and the ability to cater to regional preferences. Competition is intensifying as new entrants enter the market, driven by rising consumer awareness and the growing trend of plant-based nutrition. The emphasis on product innovation, quality, and sustainability will continue to shape the competitive landscape.
Recent Developments:
- In January 2025, the Emsland Group announced a new distribution partnership with UniBourne Food Ingredients, LLP, for the Indian market. As a leading solutions provider of food ingredients with a wide portfolio and strong customer base in India, UniBourne is well-positioned to aid in the distribution of Emsland Group's plant-based ingredients in the region. This partnership aims to strengthen Emsland Group's commitment to delivering high-quality products and excellent service to customers worldwide.
- In November 2024, Ingredion Incorporated and Lantmännen announced a new long-term collaboration to accelerate the development of plant-based proteins. As part of this partnership, Lantmännen will invest more than 100 million euros in a state-of-the-art factory in Sweden, while collaborating with Ingredion to develop a differentiated portfolio of plant-based protein isolates based on yellow peas.
- In December 2022, Royal DSM introduced Vertis, an innovative textured pea canola protein containing all nine essential amino acids needed for a complete protein. This groundbreaking plant protein offers distinct textural benefits while being soy-free, gluten-free, and dairy-free.
Market Concentration & Characteristics:
The India pea proteins market exhibits moderate concentration, with a mix of large multinational companies and emerging domestic players. Global companies such as Roquette, Cargill, and Ingredion hold a significant share of the market, leveraging their advanced technologies, large-scale production capabilities, and established supply chains to maintain a strong market presence. These companies also benefit from economies of scale, enabling them to offer competitive pricing and a diverse range of products. On the other hand, domestic players are gaining traction by offering regionally tailored products at more affordable price points. Companies like Prolgae and Vegpro are capitalizing on India’s increasing demand for plant-based proteins by focusing on local sourcing and production. The market is characterized by continuous innovation in product offerings, particularly in plant-based meat substitutes and functional foods. As consumer awareness and demand for sustainable, clean-label products rise, both multinational and domestic players are expected to intensify their efforts to capture market share.
Report Coverage:
The research report offers an in-depth analysis based on By Product Segment, By Application Segment, By Form Segment and By Source Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The India pea proteins market is expected to grow significantly from 2024 to 2032, driven by increasing demand for plant-based proteins.
- Consumer awareness of health and sustainability will continue to propel demand for pea protein in food, beverages, and nutrition products.
- The plant-based meat sector will drive significant growth in pea protein applications, particularly in meat substitutes and processed foods.
- Innovation in product formulations, such as improved taste and texture of plant-based meats, will enhance market penetration.
- Regional growth will expand as urban areas increasingly embrace plant-based diets, while semi-urban and rural regions catch up.
- Pea protein will gain traction in sports nutrition and functional foods, catering to fitness enthusiasts and health-conscious consumers.
- The rising popularity of clean-label and allergen-free products will encourage further adoption of pea protein in the food industry.
- Increasing investments in research and development will lead to better processing technologies, improving cost-efficiency and product quality.
- Regulatory support for plant-based food products in India will foster market expansion and encourage more entrants.
- Domestic pea protein production will increase, reducing dependency on imports and improving market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Pea Proteins Market?
What factors are driving the growth of the India Pea Proteins Market?
What are some challenges faced by the India Pea Proteins Market?
Who are the major players in the India Pea Proteins Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Pea Proteins Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2024)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Pea Proteins Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2024) (base year: USD 65.48 million → 2024: USD 65.48 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Pea Proteins Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2024
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Pea Proteins Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Pea Proteins Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Pea Proteins Market Drivers
- 3.3 India Pea Proteins Market Restraints & Challenges
- 3.4 India Pea Proteins Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Pea Proteins Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Pea Proteins Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Pea Proteins category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Pea Proteins Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2024
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2024
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Pea Proteins Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Pea Proteins market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Pea Proteins Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Pea Proteins Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Pea Proteins Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Pea Proteins (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Pea Proteins Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Pea Proteins Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2024)
- 7.1.2 Channel Mix Evolution (2024)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2024
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Pea Proteins Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Pea Proteins Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Pea Proteins Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Pea Proteins Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Pea Proteins Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Pea Proteins Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Pea Proteins Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
