
Market Overview:
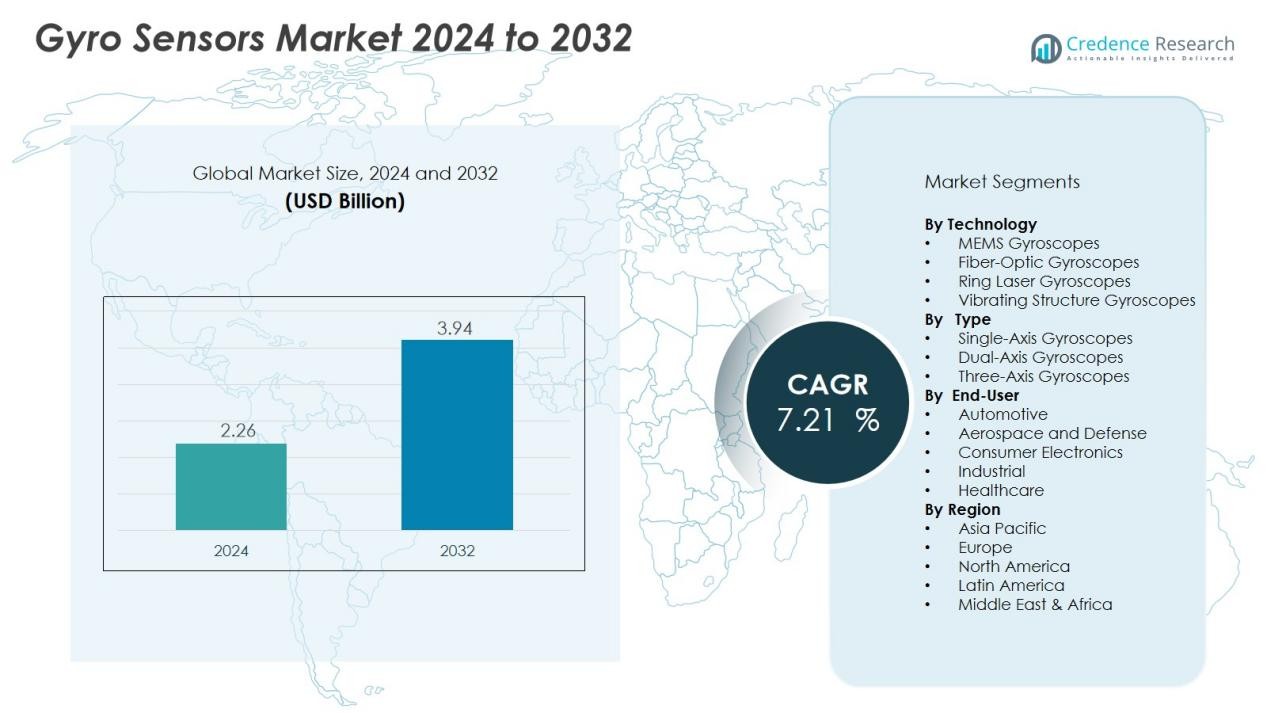
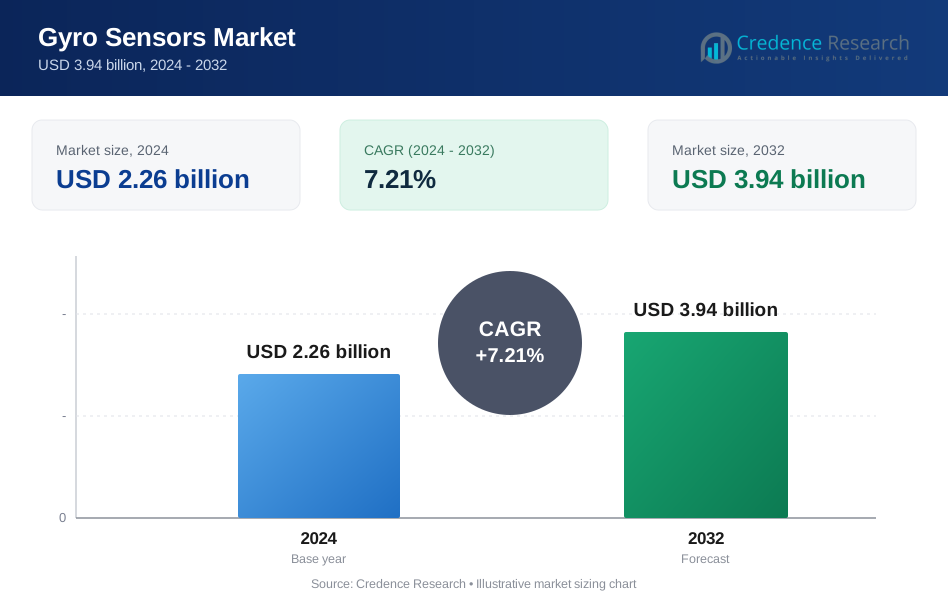
The Gyro Sensors Market size was valued at USD 2.26 billion in 2024 and is anticipated to reach USD 3.94 billion by 2032, at a CAGR of 7.21 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gyro Sensors Market Size 2024 | USD 2.26 Billion |
| Gyro Sensors Market, CAGR | 30.2 % |
| Gyro Sensors Market Size 2032 | USD 3.94 Billion |
Rising demand for autonomous vehicles and advanced driver assistance systems (ADAS) drives the need for precision navigation and orientation measurement. The growing use of robotics, UAVs, and industrial automation further accelerates market expansion. Technological advancements in fiber-optic and ring laser gyroscopes, coupled with cost reduction in MEMS sensors, are creating broad commercial opportunities.
Regionally, Asia-Pacific dominates the global gyro sensors market with over 40% share, driven by large-scale electronics manufacturing in China, Japan, and South Korea. North America follows, supported by strong defense investments and the rapid adoption of autonomous technologies. Europe maintains a solid position due to demand from automotive OEMs and industrial robotics applications. Emerging economies in the Middle East and Latin America are also adopting gyro sensor technologies in smart mobility and security systems.
Market Insights:
- The Gyro Sensors Market was valued at USD 1.48 billion in 2018 and USD 2.26 billion in 2024, projected to reach USD 3.94 billion by 2032, growing at a CAGR of 7.21% during the forecast period.
- Asia-Pacific leads with over 40% share due to large-scale electronics manufacturing in China, Japan, and South Korea. North America holds 36% supported by defense investments and autonomous technology adoption. Europe accounts for 28%, driven by automotive OEM demand and industrial robotics integration.
- Asia-Pacific is the fastest-growing region with 26% share, fueled by rising smartphone, automotive, drone, and robotics adoption. Government initiatives and strong manufacturing ecosystems accelerate growth.
- By technology, MEMS gyroscopes dominate with the largest share due to compact size, low cost, and integration capability, while fiber-optic and ring laser gyroscopes hold significant share in aerospace, defense, and navigation applications.
- By end-user, the automotive segment leads with major adoption in ADAS and vehicle stability systems, followed by consumer electronics, industrial automation, and UAV applications, reflecting diverse demand and broad commercial opportunities.
Market Drivers:
Rising Integration of Gyro Sensors in Automotive Safety and ADAS Applications
The Gyro Sensors Market grows with expanding use in advanced driver assistance systems (ADAS) and autonomous vehicles. These sensors improve vehicle stability, navigation, and motion control by detecting angular velocity and orientation. Leading automotive OEMs use multi-axis MEMS gyroscopes to enhance steering response, electronic stability control, and rollover detection. Growing emphasis on passenger safety standards and automated driving technology continues to increase product demand.
- For instance, Murata Manufacturing's SCH1633-D01 sensor employs a SafeSPI 2.0 interface with a 20-bit data frame for high-resolution output and includes over 200 self-diagnostic monitoring signals, delivering precision performance for vehicle stability control, GNSS integration, and camera alignment applications in zonal architecture.
Expanding Adoption Across Consumer Electronics and Wearable Devices
Consumer electronics manufacturers increasingly incorporate gyro sensors to improve motion sensing and user interaction. Smartphones, tablets, cameras, and gaming devices rely on gyroscopes for accurate motion tracking and screen orientation. The rise of wearable fitness and AR/VR devices strengthens demand for compact, low-power gyroscopes. It drives mass production and encourages continuous innovation in microelectromechanical system (MEMS) technology.
- For instance, Apple’s iPhone 15 utilizes a 6-axis MEMS gyroscope from suppliers like STMicroelectronics (among others), which provides the necessary data for core functions like orientation tracking, gaming, and camera stabilization.
Technological Advancements in MEMS, Fiber-Optic, and Ring Laser Gyroscopes
Continuous innovation in sensor miniaturization and precision contributes significantly to market expansion. MEMS-based sensors now deliver high sensitivity and low noise levels suitable for navigation, robotics, and aerospace use. Fiber-optic and ring laser gyroscopes offer superior accuracy for defense and aviation systems. These advancements support integration into diverse industrial applications requiring real-time orientation and motion feedback.
Growing Utilization in Industrial Automation, UAVs, and Robotics
Industrial automation and unmanned systems heavily depend on gyro sensors for precise control and positioning. It ensures stability in drones, robotic arms, and automated machinery under dynamic conditions. Demand for autonomous inspection and delivery drones is accelerating sensor adoption. Expanding factory automation, combined with robotics innovation, continues to reinforce the global demand for gyro sensors.
Market Trends:
Increasing Transition Toward Miniaturized and High-Precision MEMS Technology
The Gyro Sensors Market witnesses a strong shift toward compact and power-efficient MEMS-based sensors. Manufacturers focus on achieving higher sensitivity and stability while reducing cost and power consumption. Miniaturization allows integration into smartphones, drones, and autonomous systems without compromising accuracy. Multi-axis MEMS gyroscopes now deliver reliable performance for motion detection, gesture recognition, and navigation control. It drives mass production, improving supply chain efficiency and enabling broad consumer adoption. Continuous research on advanced materials and sensor fusion technologies further refines output stability and reduces drift errors.
- For Instance, STMicroelectronics' LSM6DSOX iNEMO inertial module operates at 0.55 mA in high-performance mode for applications like gesture recognition and navigation in smartphones and IoT devices.
Growing Use of Gyro Sensors in Autonomous Systems, Robotics, and Industrial Equipment
The increasing automation of vehicles, factories, and service robots propels sensor innovation. Gyroscopes enable accurate motion control, balancing, and orientation tracking in dynamic environments. Demand from unmanned aerial vehicles, automated guided vehicles, and industrial robots continues to rise across logistics, defense, and manufacturing sectors. It encourages manufacturers to develop rugged sensors capable of handling high vibration and temperature variations. Integration with AI-based control systems enhances real-time data processing and decision-making accuracy. The growing ecosystem of smart robotics and Industry 4.0 strengthens long-term opportunities for gyro sensor providers worldwide.
- For instance, the TDK InvenSense IIM-46234 gyroscope is deployed in autonomous industrial robots to deliver precise orientation tracking in high-vibration factory automation zones. This industrial-grade sensor features a high survivability of 2000g shock and a programmable full-scale range (FSR) up to ±480°/second, with typical sensitivities and noise performance suited for demanding industrial navigation and condition monitoring applications.
Market Challenges Analysis:
High Manufacturing Costs and Complex Calibration Requirements
The Gyro Sensors Market faces cost challenges linked to precision manufacturing and calibration. MEMS, fiber-optic, and ring laser gyroscopes require sophisticated fabrication equipment and cleanroom facilities. It increases production expenses and limits scalability for smaller manufacturers. The need for frequent calibration to maintain accuracy under varying environmental conditions adds operational complexity. Small deviations in alignment or temperature can cause measurement drift, affecting sensor reliability. High setup and testing costs restrict the widespread use of premium-grade sensors in low-cost applications.
Sensitivity to Environmental Factors and Signal Interference
Gyro sensors are highly sensitive to vibration, magnetic fields, and temperature changes, creating performance inconsistencies. It demands advanced compensation algorithms and protective enclosures, raising development time and cost. Harsh industrial or outdoor conditions often degrade sensor stability and accuracy. Signal interference also impacts data precision in autonomous systems and aircraft navigation. Manufacturers must balance performance with durability to meet industry-specific reliability standards. Overcoming these technical limitations remains critical for ensuring consistent sensor functionality across diverse environments.
Market Opportunities:
Expanding Role in Autonomous Vehicles, UAVs, and Smart Mobility Solutions
The Gyro Sensors Market benefits from rising demand in autonomous vehicles and unmanned systems. These sensors enable precise navigation, lane-keeping, and motion control in driverless cars and drones. It supports rapid advancements in intelligent transportation, defense surveillance, and delivery applications. The growing focus on safety, localization, and sensor fusion technology enhances integration with accelerometers and GPS modules. Increasing investments in smart mobility projects by governments and automotive OEMs open strong growth avenues. Continuous improvements in low-drift MEMS gyroscopes strengthen the commercial adoption of these sensors across mobility ecosystems.
Rising Adoption in Healthcare, Robotics, and Industrial Automation
The growing use of motion-tracking technology in surgical robotics and rehabilitation devices creates new opportunities for manufacturers. It provides accurate spatial awareness in robotic-assisted surgery and wearable health systems. Expanding industrial automation also drives deployment in robotic arms, drones, and precision equipment. Demand for compact and high-performance sensors supports next-generation robotics in assembly and inspection lines. Collaborations between sensor developers and AI technology firms promote intelligent motion control systems. Emerging applications across healthcare and manufacturing sectors are expected to accelerate market expansion over the forecast period.
Market Segmentation Analysis:
By Technology
The Gyro Sensors Market is segmented by technology into MEMS, fiber-optic, ring laser, and vibrating structure gyroscopes. MEMS technology holds the largest share due to its compact size, low cost, and integration capability with electronic devices. It dominates applications in smartphones, drones, and automotive systems. Fiber-optic and ring laser gyroscopes offer superior accuracy and are widely used in defense, aerospace, and navigation systems. Advancements in miniaturization and noise reduction continue to expand their use across commercial and industrial sectors.
- For Instance, Honeywell's ring laser gyroscopes (RLGs) are used in tens of thousands of commercial aircraft and other platforms. The company produced its 500,000th unit in 2019, with these systems achieving a typical navigational accuracy with a bias instability of around 0.0035° per hour.
By Type
Based on type, the market includes single-axis, dual-axis, and three-axis gyroscopes. Three-axis sensors lead the segment, providing multi-directional motion detection for robotics, gaming, and autonomous systems. Single-axis gyros remain relevant for applications requiring basic angular velocity measurement. It offers cost efficiency and stable performance in compact devices. Dual-axis variants balance performance and size, appealing to mid-range consumer electronics and industrial tools.
- For instance, Murata Manufacturing's single-axis gyro (GYROSTAR ENV-05D) is used in various applications such as navigation systems and platform stabilizing, with a typical sensitivity (scale factor) of 25 mV/(deg/s), enabling precise motion detection in portable systems
By End-User
By end-user, the market covers automotive, aerospace and defense, consumer electronics, industrial, and healthcare sectors. The automotive segment leads due to growing ADAS and vehicle stability applications. Consumer electronics follow with strong demand from smartphones and wearables. Aerospace and defense sectors continue investing in precision navigation technologies, while industrial automation and healthcare create emerging opportunities for growth. It highlights a diverse demand base supporting continuous product innovation.
Segmentations:
By Technology
- MEMS Gyroscopes
- Fiber-Optic Gyroscopes
- Ring Laser Gyroscopes
- Vibrating Structure Gyroscopes
By Type
- Single-Axis Gyroscopes
- Dual-Axis Gyroscopes
- Three-Axis Gyroscopes
By End-User
- Automotive
- Aerospace and Defense
- Consumer Electronics
- Industrial
- Healthcare
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Holds Dominant Position with Strong Industrial and Aerospace Adoption
North America commands 36% of the Gyro Sensors Market, led by the United States. It benefits from advanced aerospace, defense, and automotive sectors that heavily deploy gyro sensors for navigation, stability, and control systems. The presence of leading sensor manufacturers and early adoption of MEMS technology strengthens regional growth. It experiences high demand in autonomous vehicles, drones, and industrial robotics. Robust R&D infrastructure drives innovations in miniaturization and precision. Government investments in defense and space programs support ongoing sensor integration. North America maintains strong export potential, enhancing revenue streams.
Europe Demonstrates Significant Share Driven by Automotive and Industrial Applications
Europe accounts for 28% of the Gyro Sensors Market, supported by Germany, France, and the UK. It experiences substantial use in automotive safety systems, aircraft navigation, and industrial automation. It benefits from stringent safety regulations, encouraging sensor incorporation in vehicles and machinery. Leading research institutions and electronics manufacturers contribute to advanced sensor development. Demand for high-precision fiber-optic and ring laser gyroscopes strengthens regional market growth. Investment in smart transportation and robotics further drives adoption. Continuous upgrades in aerospace and defense platforms sustain sensor deployment.
Asia-Pacific Records Rapid Growth Fueled by Manufacturing and Consumer Electronics
Asia-Pacific holds 26% of the Gyro Sensors Market, with China, Japan, and South Korea as key contributors. It experiences increasing integration in smartphones, consumer electronics, and automotive systems. It benefits from strong manufacturing ecosystems, cost-effective production, and supportive government initiatives. Expanding drone, robotics, and unmanned vehicle sectors drive sensor adoption. MEMS gyroscopes dominate due to affordability and compact size. Rising demand for automotive stability control and wearable devices strengthens regional expansion. Rapid urbanization and infrastructure projects further stimulate market growth.
Key Player Analysis:
- Murata Manufacturing
- MELEXIS
- STMicroelectronics
- Colibrys Ltd
- Fizoptika Corp
- Honeywell International Inc
- InvenSense, Inc
- KVH Industries, Inc
- NXP Semiconductors N.V
- Robert Bosch GmbH
- Analog Devices Inc
Competitive Analysis:
The competitive landscape of the Gyro Sensors Market shows that industry leaders deploy diversified strategies to win across applications and segments. Murata Manufacturing leads in high‑performance 3D MEMS gyros and accelerometers, offering series like SCC2000 and SCH16T for automotive and industrial markets. It holds a strong position due to early MEMS investment and wide distribution. MELEXIS emphasizes cost‑efficient sensing solutions for automotive position and angle detection. While its core portfolio centres on magnetic sensors, it competes indirectly by addressing system‑level motion sensing needs. STMicroelectronics occupies a leading role in MEMS gyros with a broad product range that targets high stability and multi‑axis performance for consumer, automotive, and industrial uses. In the precision inertial class, Honeywell International Inc. builds on heritage ring‑laser and fiber‑optic gyros such as the GG1320 for aerospace and defence applications. Meanwhile, InvenSense, Inc. (now part of TDK) focuses on ultra‑low‑power multi‑axis motion sensors for consumer electronics, using BalancedGyro™ technology and high integration. Colibrys Ltd and Fizoptika Corp serve niche segments with high‑precision gyros and IMU modules for industrial and aerospace niches. These firms maintain competitive edge through specialised performance rather than mass consumer scale. Together, these key players drive innovation, scale production, and focus on application‑specific differentiation in the Gyro Sensors Market.
Recent Developments:
- In October 2025, Melexis and Google Cloud announced an expanded multi-year strategic partnership to deploy artificial intelligence across Melexis’s global operations.
- In July 2025, STMicroelectronics entered into an agreement to acquire NXP Semiconductors' MEMS sensor business to reinforce its position in automotive, industrial, and consumer sensors, in a deal valued up to $950 million.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Type, End-User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Gyro Sensors Market will expand with increasing adoption in autonomous vehicles and drones.
- Advancements in MEMS technology will enable smaller, more precise, and energy-efficient sensors.
- Integration in consumer electronics, including smartphones and wearables, will drive widespread deployment.
- Industrial automation and robotics will require high-performance gyros for stability and motion control.
- Aerospace and defense sectors will continue to invest in ring-laser and fiber-optic gyros for navigation.
- Emerging markets in Asia-Pacific will witness rapid growth due to expanding manufacturing and smart infrastructure.
- Automotive applications, including stability control and ADAS, will create consistent demand for multi-axis gyros.
- Collaborations between sensor manufacturers and OEMs will foster innovation and faster product rollouts.
- IoT-enabled gyroscopes will gain traction in smart homes, smart factories, and connected devices.
- Focus on cost-effective production and miniaturization will make advanced gyros accessible to new consumer and industrial segments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Gyro Sensors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Gyro Sensors Market expected to grow during 2024–2032?
Which technology segment held the largest share of the Gyro Sensors Market in 2024?
What are the key factors driving the growth of the Gyro Sensors Market?
Who are the leading companies operating in the Gyro Sensors Market?
Which region held the largest share of the Gyro Sensors Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Gyro Sensors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Gyro Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.26 billion → 2032: USD 3.94 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Gyro Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Gyro Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Gyro Sensors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Gyro Sensors Market Drivers
- 3.3 Gyro Sensors Market Restraints & Challenges
- 3.4 Gyro Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Gyro Sensors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Gyro Sensors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Gyro Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Gyro Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Gyro Sensors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Gyro Sensors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Gyro Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Gyro Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Gyro Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Gyro Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Gyro Sensors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Gyro Sensors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Gyro Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Gyro Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Gyro Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Gyro Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Gyro Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Gyro Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Gyro Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
