
Market Overview:
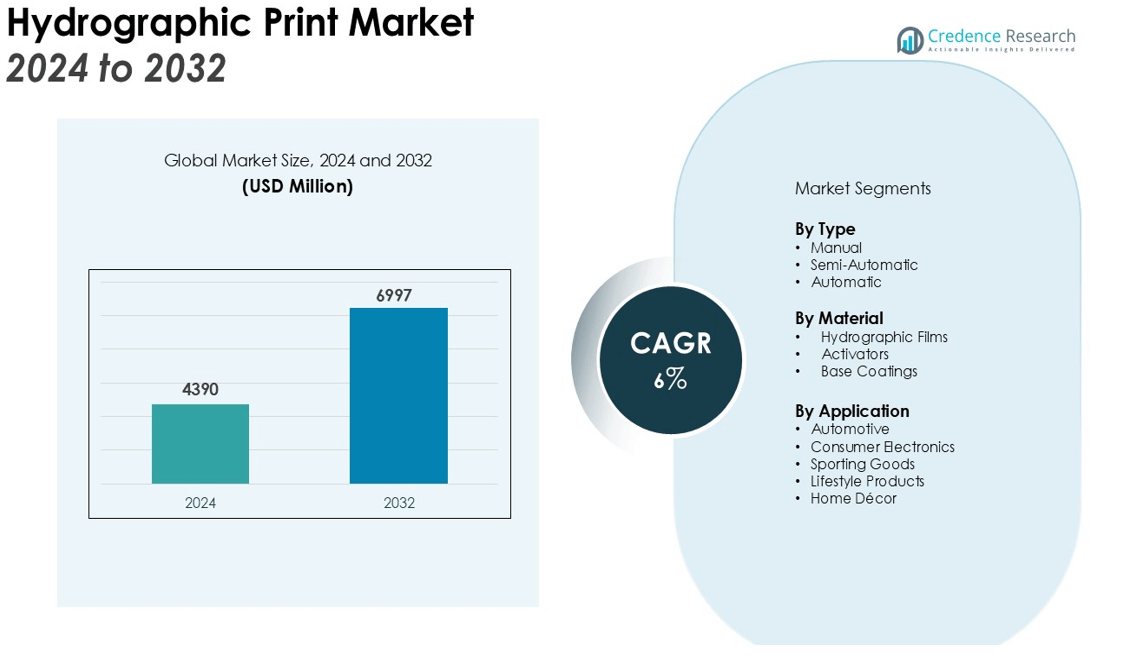
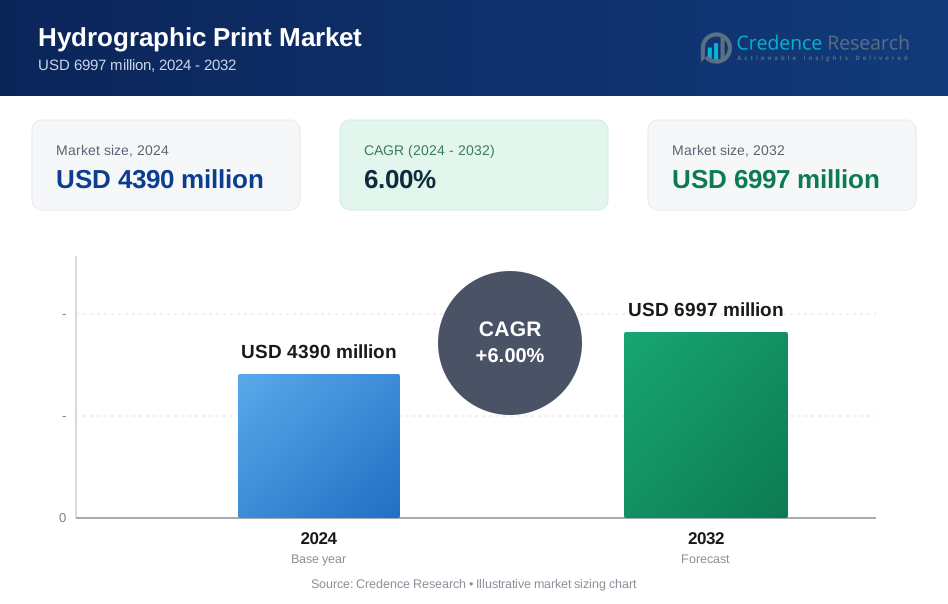
The Hydrographic Print Market size was valued at USD 4390 million in 2024 and is anticipated to reach USD 6997 million by 2032, at a CAGR of 6% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydrographic Print Market Size 2024 | USD 4390 million |
| Hydrographic Print Market, CAGR | 6% |
| Hydrographic Print Market Size 2032 | USD 6997 million |
The hydrographic print market is expanding as demand for product personalization increases. Brands prioritize unique finishes on automotive components, electronics, and lifestyle products to attract consumers. Advances in hydrographic film and dipping technologies improve efficiency, reduce waste, and enhance durability. Supportive regulations promoting water-based coatings further encourage adoption, while companies highlight eco-friendly materials to align with sustainability goals. These factors collectively drive market growth across industries.
North America dominates the market, supported by strong automotive and consumer goods applications. Asia Pacific records the fastest growth, led by rapid investments in automotive and electronics manufacturing in China and India. Europe continues to show steady demand, particularly within luxury vehicles and sporting goods segments. Meanwhile, Latin America and the Middle East are gradually embracing hydrographic printing, driven by infrastructure development and increasing interest in product customization. Rising collaborations between technology providers and manufacturers further strengthen innovation and global adoption.
Market Insights:
- The Hydrographic Print Market was valued at USD 4390 million and is projected to reach USD 6997 million by 2032, growing at a CAGR of 6%.
- Rising consumer demand for personalized designs in automotive interiors, electronics, and lifestyle goods drives adoption.
- Advances in hydrographic films and dipping technologies improve durability, reduce waste, and enhance production efficiency.
- Strict environmental regulations promote water-based coatings, pushing firms toward sustainable practices and eco-friendly materials.
- High operational costs, skilled labor needs, and waste management remain major challenges for broader market penetration.
- North America holds 32% share, Europe contributes 28%, and both maintain steady demand through automotive and lifestyle applications.
- Asia Pacific holds 27% share and leads future growth, while Latin America at 7% and Middle East & Africa at 6% show gradual but rising uptake.
Market Drivers:
Growing Consumer Preference for Personalization and Aesthetics
The Hydrographic Print Market benefits from rising consumer demand for personalized products. Customers seek unique patterns and designs on automotive interiors, consumer electronics, and lifestyle accessories. It helps manufacturers deliver appealing finishes that differentiate products in competitive markets. Strong aesthetic appeal drives adoption across both premium and mass-market segments. This demand for personalization continues to be a central growth driver.
- For instance, the drive for flawless aesthetic finishes has pushed for greater technical precision, with leaders like Miraclon engineering its FLEXCEL NX System to produce photopolymer plates with a thickness consistency, particularly floor height, controlled to within a 0.025 mm (0.001 in.) tolerance.
Advancements in Film and Printing Technologies Enhancing Efficiency
Innovation in hydrographic film materials and dipping systems strengthens the market’s value proposition. It improves print durability, reduces material waste, and enables faster production cycles. Advanced machinery allows precision printing on complex surfaces, expanding application areas. These technological upgrades help manufacturers lower operational costs while maintaining high-quality finishes. The result is a broader adoption of hydrographic solutions across diverse industries.
- For instance, specialists at Liquid Concepts state that a properly applied hydrographic finish using an automotive-grade clear coat can have a functional lifespan of up to 15 years, depending on the item's exposure to wear and environmental conditions.
Regulatory Push Toward Eco-Friendly and Water-Based Solutions
The Hydrographic Print Market gains momentum from strict environmental regulations. It encourages the use of water-based inks and sustainable coating materials. Governments and industry bodies promote low-emission processes to reduce environmental impact. Companies align strategies with eco-friendly practices to strengthen compliance and consumer trust. These measures create opportunities for sustainable growth in the sector.
Expansion of End-Use Applications Across Key Industries
The Hydrographic Print Market expands through demand from automotive, sporting goods, and electronics. It provides durable decorative coatings that withstand wear in high-use applications. Automakers apply hydrographic prints to dashboards, trims, and consoles for premium aesthetics. Electronics manufacturers adopt these finishes to enhance product design and consumer appeal. Broader end-use adoption continues to drive steady market penetration worldwide.
Market Trends:
Integration of Advanced Materials and Smart Printing Processes
The Hydrographic Print Market is witnessing a clear trend toward the adoption of advanced films and coatings that improve durability, precision, and aesthetic quality. Manufacturers are focusing on films that resist fading, scratching, and chemical exposure to ensure longer product life. It allows industries such as automotive and electronics to use hydrographic prints in high-contact areas with confidence. Smart printing processes supported by automation and digital control systems are also gaining traction, enhancing consistency and reducing errors. Growing emphasis on customization is driving investment in innovative film patterns that cater to evolving consumer tastes. This integration of material advancements and smarter processes continues to strengthen the value proposition of hydrographic printing in global markets.
- For instance, YHT, a company with over 30 years of experience, provides high-quality hydro dipping films and water transfer printing machines for industries like automotive, aerospace, and consumer electronics, ensuring durable and vibrant results on complex 3D objects.
Rising Adoption Across Automotive, Electronics, and Lifestyle Segments
The Hydrographic Print Market is expanding its footprint across automotive, consumer electronics, sporting goods, and home décor applications. Automakers are integrating hydrographic finishes in dashboards, consoles, and trims to enhance interior appeal. Electronics companies are using hydrographic prints to improve product design and differentiate offerings in crowded markets. It also supports demand from lifestyle products such as helmets, eyewear, and household goods where decorative finishes play a key role. Sustainability remains a growing trend, with companies developing eco-friendly inks and films to align with regulatory frameworks. Strong interest in premium aesthetics across industries is creating opportunities for manufacturers to scale operations. These adoption patterns reflect the increasing role of hydrographic printing in shaping product value and consumer experience.
- For instance, Hydrokon has developed a customizable blank hydrographic film that is compatible with 3 different types of printers (eco-solvent, latex, and pigment-based), a technological achievement that makes custom printing more versatile and accessible.
Market Challenges Analysis:
High Operational Costs and Process Limitations
The Hydrographic Print Market faces challenges from high operational costs and process inefficiencies. Equipment setup, skilled labor, and specialized films increase overall production expenses. It creates barriers for small and medium enterprises seeking to adopt hydrographic printing. Complex dipping processes require precision, and errors often lead to material wastage. Limited scalability also restricts its adoption in high-volume production lines. These operational constraints hinder wider market penetration and slow down growth opportunities.
Environmental Concerns and Regulatory Pressures
The Hydrographic Print Market also struggles with environmental challenges tied to chemical use and waste management. It relies on coatings and inks that must comply with strict environmental regulations. Growing pressure from governments to minimize volatile organic compounds forces companies to reformulate materials. Failure to adapt to eco-friendly standards risks penalties and reduced consumer trust. Waste disposal from dipping processes requires strict handling to avoid ecological impact. These regulatory and environmental hurdles continue to challenge the market’s long-term sustainability.
Market Opportunities:
Growing Demand for Customization Across Industries
The Hydrographic Print Market holds significant opportunity through rising consumer demand for personalized and decorative finishes. Automotive companies are expanding use of hydrographic films for dashboards, trims, and consoles to enhance interior appeal. Electronics brands leverage it to create unique designs that differentiate devices in highly competitive markets. Sporting goods, eyewear, and household products also benefit from custom patterns that improve consumer perception. Expanding consumer preference for distinctive product aesthetics opens new revenue streams. This focus on customization continues to create favorable conditions for market growth.
Advancements in Eco-Friendly Materials and Digital Processes
The Hydrographic Print Market is positioned to benefit from innovation in sustainable and digital solutions. It aligns with regulatory standards by adopting water-based inks and low-emission coatings that reduce environmental impact. Companies introducing biodegradable films and recyclable substrates gain a competitive edge in global markets. Integration of digital imaging and automation enables higher accuracy and faster production cycles. These advancements expand adoption in industries seeking efficiency without compromising quality. The shift toward eco-friendly and digital processes presents long-term growth opportunities for hydrographic printing worldwide.
Market Segmentation Analysis:
By Type
The Hydrographic Print Market is segmented into manual, semi-automatic, and automatic systems. Manual systems remain cost-effective for small-scale applications but require skilled labor and time. Semi-automatic equipment balances efficiency with flexibility, making it suitable for medium-scale production. Automatic systems dominate large-scale operations due to speed, precision, and reduced waste. It continues to attract investment from manufacturers seeking scalable solutions.
- For instance, the TSAUTOP Industrial 9m Fully Automatic Film Flowing Machine showcases remarkable efficiency, capable of processing up to 200 frames per hour for large-scale factory production.
By Material
The market uses hydrographic films, activators, and base coatings as core materials. Hydrographic films with advanced designs provide aesthetic value and customization. Activators improve adhesion between film and substrate, ensuring durability. Base coatings enhance visual effects and protect the printed surface from wear. It drives steady demand across industries focusing on quality and long-term product performance.
- For instance, the improved formula of Gluetec Group’s WIKO® ACTIVATORS is designed for application from an optimal spray distance of 30 cm to ensure reliable activation.
By Application
The Hydrographic Print Market finds applications in automotive, consumer electronics, sporting goods, and lifestyle products. Automotive interiors such as dashboards, trims, and consoles lead adoption for aesthetic upgrades. Electronics manufacturers use hydrographic prints to differentiate devices through unique patterns. Sporting goods and home décor items also adopt these finishes to improve market appeal. It supports wide penetration by meeting consumer preference for personalized and premium designs.
Segmentations:
By Type
- Manual
- Semi-Automatic
- Automatic
By Material
- Hydrographic Films
- Activators
- Base Coatings
By Application
- Automotive
- Consumer Electronics
- Sporting Goods
- Lifestyle Products
- Home Décor
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America and Europe Driving Steady Growth Through Automotive and Lifestyle Segments
North America holds 32% share of the Hydrographic Print Market. Europe contributes 28% share, supported by its strong luxury automotive and sporting goods sectors. Automakers in the United States and Canada integrate hydrographic finishes into dashboards, trims, and consoles to enhance product appeal. Lifestyle goods such as eyewear and sporting equipment also use hydrographic films to improve aesthetics. It shows steady adoption driven by design innovation and consumer preference for premium finishes. Together, these regions continue to represent mature markets with strong emphasis on quality and customization.
Asia Pacific Emerging as the Fastest Growing Regional Market
Asia Pacific holds 27% share of the Hydrographic Print Market and is expanding rapidly. China, India, and Japan drive regional dominance through large-scale automotive and electronics manufacturing. Strong consumer preference for customized products accelerates adoption across mass-market and premium segments. It benefits from rising investments in advanced printing technologies that improve cost efficiency. Government initiatives supporting sustainable coatings further strengthen adoption across industrial applications. Asia Pacific is positioned as the fastest growing regional hub for hydrographic printing worldwide.
Latin America and Middle East & Africa Showing Gradual Uptake
Latin America represents 7% share of the Hydrographic Print Market, while the Middle East & Africa hold 6% share. Growth in these regions is fueled by automotive customization and rising consumer demand for decorative finishes. Brazil, Mexico, and GCC countries lead adoption, supported by increasing disposable incomes. It gains momentum from small-scale applications in consumer goods and localized automotive parts. Limited awareness and higher operational costs restrict larger-scale penetration but leave space for niche opportunities. These regions continue to present emerging potential with rising customization and aesthetic trends.
Key Player Analysis:
- Shenzhen Zhichao Water Transfer Printing Co., Ltd.
- H2O Graphix
- Ozarks Hydrographics
- Kustom Inc.
- Hydro‑Dip, Inc.
- TWN Industries, Inc.
- PA Hydrographics
- TSAUTOP Machinery Co., Ltd.
- Unique Hydrographic
- TrueTimber Outdoors Holding Company
- Aikka Paints Sdn Bhd
- Dongguan Xuancai Transfer Printing Materials Co., Ltd.
Competitive Analysis:
The Hydrographic PrintMarket is fragmented, with regional specialists and integrated providers. Competitors win on film design depth, finish durability, and cost per part. Speed, quality control, and certification also shape buyer choice. Equipment OEMs, film suppliers, and service bureaus compete across the stack. Partnerships with automakers and electronics brands secure repeat volumes. It strengthens positions through approved vendor lists and long terms. Sustainability credentials matter, including water-based inks and low-VOC coatings. Substitutes create pressure, including vinyl wraps, pad printing, laser texturing, and decals. Large players scale with automation, robotics, and digital workflows. Small shops focus on niche patterns, rapid prototyping, and flexible runs. Price competition intensifies in Asia, but service and training drive loyalty. After-sales support, training academies, and on-site audits reinforce retention. IP on exclusive patterns and licensing agreements protects premium margin tiers. Vendors pursue M&A to expand geographies, add films, and integrate equipment. Buyer scorecards favor uptime, traceability, and predictable global delivery. Service quality often decides contracts.
Recent Developments:
- In July 2025, TrueTimber launched its all-new SHADOWBARK camouflage pattern, designed for waterfowl hunters in dark, wooded environments like flooded timber.
- In February 2025, TrueTimber announced a new partnership with Michael Waddell and the Bone Collector brand, with collaborative products expected to come to market in 2025.
Report Coverage:
The research report offers an in-depth analysis based on Type, Material, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for personalized and decorative finishes will continue to expand across consumer and industrial sectors.
- Automakers will increase adoption of hydrographic printing for dashboards, trims, and premium interior parts.
- Electronics manufacturers will use hydrographic films to differentiate designs and enhance brand appeal.
- Advancements in automation and robotics will improve production speed, consistency, and cost efficiency.
- Development of eco-friendly water-based coatings and biodegradable films will strengthen compliance with environmental regulations.
- Regional expansion in Asia Pacific will accelerate, supported by investments in automotive and electronics manufacturing.
- Small and medium enterprises will explore niche applications in lifestyle goods, eyewear, and sporting equipment.
- Strategic collaborations between technology providers and film manufacturers will expand design portfolios and market reach.
- Digital imaging and pattern innovation will drive higher levels of customization and consumer engagement.
- Growing awareness of sustainable materials and efficient processes will guide long-term industry competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Consumer Preference for Personalization and Aesthetics
Consumers increasingly seek unique, customized designs on automotive interiors, electronics, and lifestyle products, driving manufacturers to adopt hydrographic printing for its ability to deliver visually distinctive finishes that enhance product appeal and differentiation.
Advancements in Film and Printing Technologies
Innovations in hydrographic films and dipping systems have improved print durability, reduced material waste, and enabled faster, more precise production, making hydrographic printing more attractive for a wider range of applications and industries.
Regulatory Push Toward Eco-Friendly and Water-Based Solutions
Stricter environmental regulations are encouraging the use of water-based inks and sustainable coating materials, prompting companies to adopt hydrographic printing processes that align with eco-friendly standards and reduce environmental impact.
Expansion of End-Use Applications Across Key Industries
The versatility and durability of hydrographic prints are leading to broader adoption in automotive, sporting goods, electronics, and lifestyle sectors, as manufacturers leverage the technology to enhance both functional and aesthetic product attributes.
Integration of Automation and Digital Processes
The adoption of automated and digitally controlled hydrographic printing systems is increasing production efficiency, consistency, and scalability, enabling manufacturers to meet growing demand for high-quality, customized finishes while controlling operational costs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hydrographic Print, and what is its projected size in 2032?
Which Hydrographic Print market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hydrographic Print market?
Who are the leading companies in the Hydrographic Print market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Manual
- 1.2.2 Semi-Automatic
- 1.2.3 Automatic
- 1.3 By Material
- 1.3.1 Hydrographic Films
- 1.3.2 Activators
- 1.3.3 Base Coatings
- 1.4 By Application
- 1.4.1 Automotive
- 1.4.2 Consumer Electronics
- 1.4.3 Sporting Goods
- 1.4.4 Lifestyle Products
- 1.4.5 Home Décor
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4390 million → 2032: USD 6997 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hydrographic Print Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hydrographic Print Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hydrographic Print Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hydrographic Print Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hydrographic Print Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hydrographic Print Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hydrographic Print Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hydrographic Print Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4390 million → 2032: USD 6997 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hydrographic Print Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Manual
- 12.3.7.2 Semi-Automatic
- 12.3.7.3 Automatic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hydrographic Films
- 12.4.7.2 Activators
- 12.4.7.3 Base Coatings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Consumer Electronics
- 12.5.7.3 Sporting Goods
- 12.5.7.4 Lifestyle Products
- 12.5.7.5 Home Décor
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hydrographic Print End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hydrographic Print Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hydrographic Print Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hydrographic Print Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Shenzhen Zhichao Water Transfer Printing Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 H2O Graphix
- 18.4 Ozarks Hydrographics
- 18.5 Kustom Inc.
- 18.6 Hydro‑Dip, Inc.
- 18.7 TWN Industries, Inc.
- 18.8 PA Hydrographics
- 18.9 TSAUTOP Machinery Co., Ltd.
- 18.10 Unique Hydrographic
- 18.11 TrueTimber Outdoors Holding Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

