
Market Overview
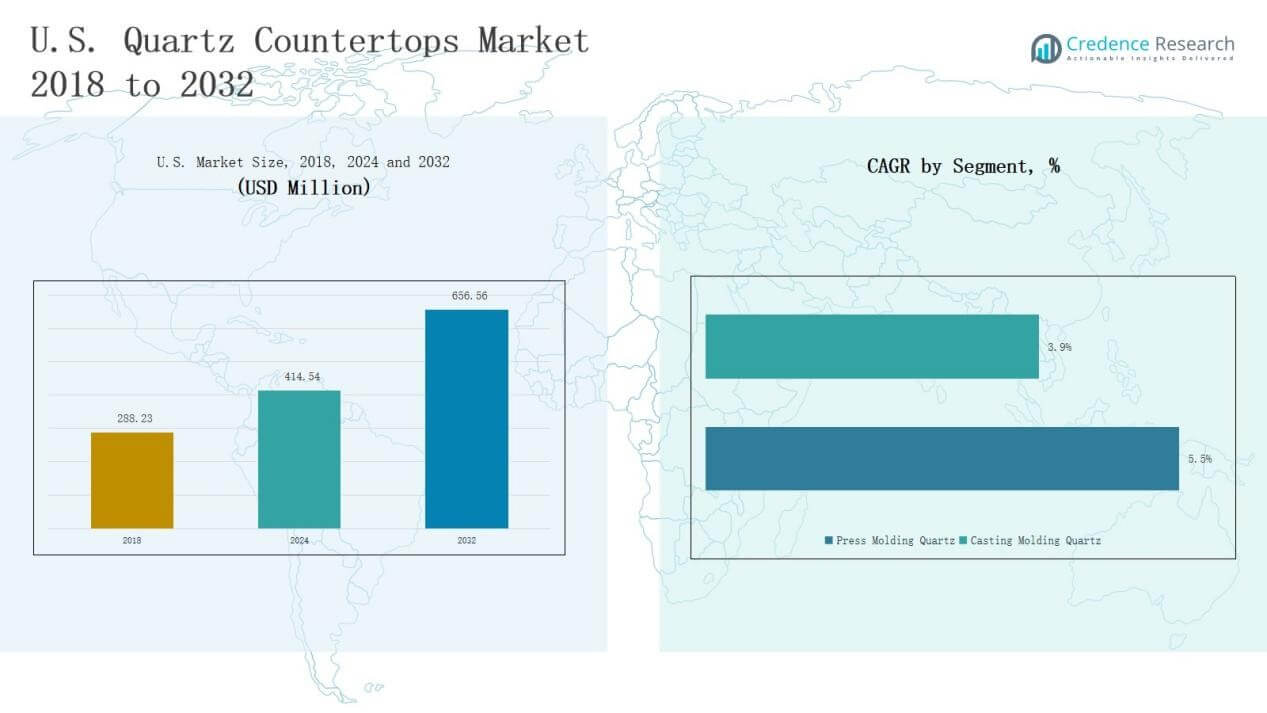
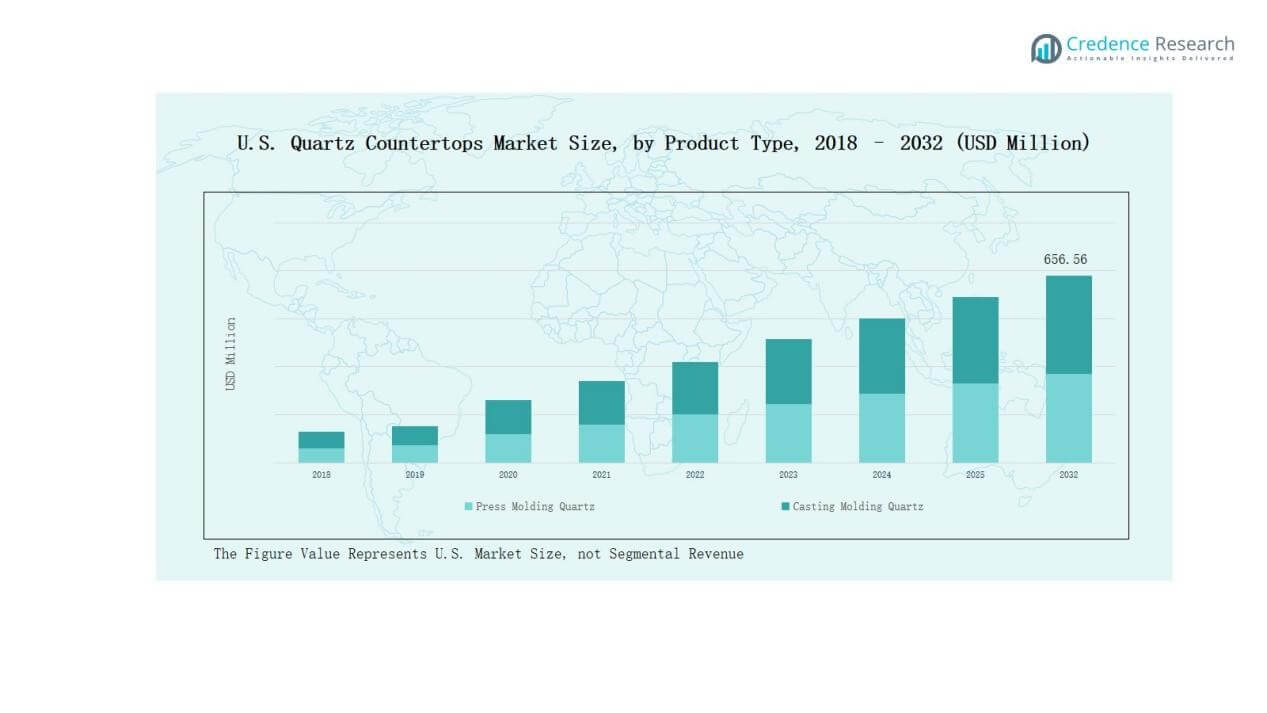
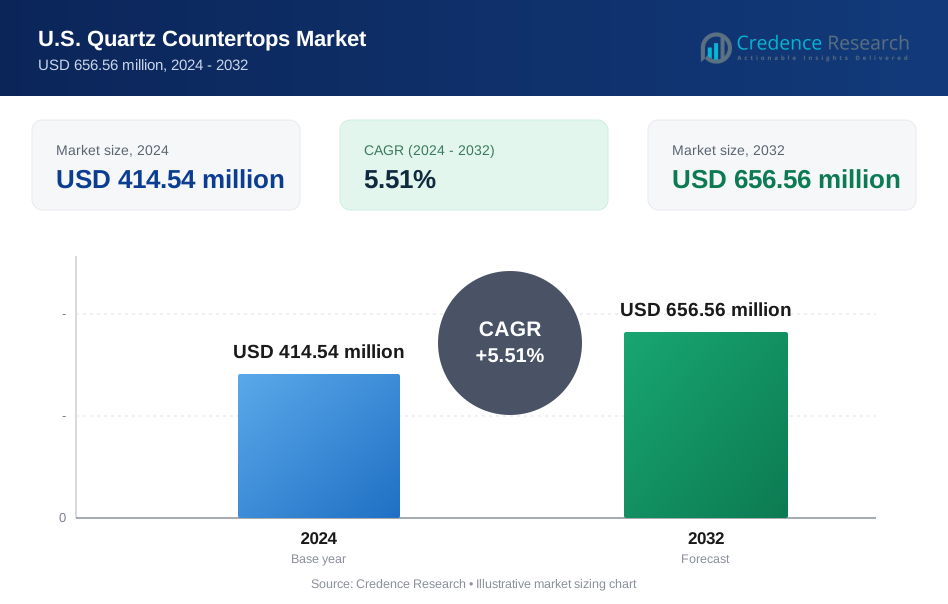
The U.S. Quartz Countertops Market size was valued at USD 288.23 million in 2018, reached USD 414.54 million in 2024, and is anticipated to reach USD 656.56 million by 2032, at a CAGR of 5.51% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Quartz Countertops Market Size 2024 | USD 414.54 Million |
| U.S. Quartz Countertops Market, CAGR | 5.51% |
| U.S. Quartz Countertops Market Size 2032 | USD 656.56 Million |
The U.S. Quartz Countertops Market is shaped by strong competition among leading players such as Cambria, MSI Surfaces, Caesarstone, Silestone (Cosentino), Daltile ONE Quartz, LX Hausys Viatera, Corian Quartz (DuPont), Vicostone USA, Wilsonart Quartz, and Meta Surfaces. These companies strengthen their positions through wide product portfolios, innovative designs, sustainable offerings, and strong distribution networks targeting both residential and commercial segments. The South region led the market with 31% share in 2024, supported by robust housing construction, large-scale remodeling activity, and expanding commercial real estate investments.
 Market Insights
- The U.S. Quartz Countertops Market was USD 288.23 million in 2018, reached USD 414.54 million in 2024, and is expected at USD 656.56 million by 2032, growing at 5.51% CAGR.
- Leading players include Cambria, MSI Surfaces, Caesarstone, Silestone (Cosentino), Daltile ONE Quartz, LX Hausys Viatera, Corian Quartz (DuPont), Vicostone USA, Wilsonart Quartz, and Meta Surfaces, competing with innovation and sustainable offerings.
- By product type, press molding quartz held 62% share in 2024, driven by strength and affordability, while casting molding quartz gained traction through premium customization and luxury appeal.
- By application, the residential segment dominated with 64% share in 2024, followed by commercial at 28% and others at 8%, supported by institutional and healthcare usage.
- Regionally, the South led with 31% share in 2024, followed by the Northeast at 27%, Midwest at 22%, and West at 20%, highlighting diverse regional growth drivers.
Market Segment Insights
By Product Type
Press molding quartz dominated the U.S. Quartz Countertops Market with nearly 62% share in 2024, driven by its strength, uniform finish, and suitability for both residential and commercial installations. Casting molding quartz accounted for the remaining share, supported by its flexibility in creating customized designs and premium aesthetics. Growing demand for personalized interiors and luxury projects is expected to enhance adoption of casting molding quartz, although press molding remains the most cost-effective and widely accepted option.
For instance, Cambria introduced its Inverness collection of press‑molded quartz surfaces in 2024, offering durability and seamless looks tailored for high‑use kitchens.
By Application
The residential segment led with around 64% share in 2024, supported by demand in kitchens, bathrooms, and home renovation projects. Its stain resistance, low maintenance, and variety of finishes make quartz the preferred household surface material. The commercial segment held about 28%, with usage in hotels, offices, and restaurants requiring durable and premium finishes. The “Others” category contributed 8%, including institutional and healthcare applications, where hygienic surfaces and long-term performance continue to drive adoption.
For instance, Cambria partnered with Marriott hotels to feature its surfaces in lobby and bar designs, highlighting quartz’s premium look in hospitality spaces.
Key Growth Drivers
Rising Demand for Home Renovation Projects
The U.S. Quartz Countertops Market benefits from increasing home remodeling and renovation activities, particularly kitchen and bathroom upgrades. Homeowners prioritize materials that combine durability, aesthetic appeal, and low maintenance. Quartz provides stain resistance and a wide range of design options, making it a preferred choice over natural stone. Rising disposable income, coupled with growing interest in premium finishes, continues to fuel residential adoption. Renovation trends in urban and suburban areas remain a key growth driver, sustaining strong market demand.
For instance, quartz countertops are recognized for resisting stains, scratches, and heat better than traditional surfaces, which encourages busy homeowners to choose them for high-traffic kitchen areas.
Expansion of Commercial Real Estate and Hospitality Sector
Commercial real estate growth, especially in offices, hotels, and retail interiors, significantly supports quartz countertop adoption. Developers and architects favor quartz for its durability, modern design appeal, and long lifecycle performance in high-traffic areas. Hospitality investments in premium interiors, particularly in luxury hotels, further drive demand. Increasing use in reception counters, restaurants, and workspaces strengthens quartz’s position as a reliable surface material. This ongoing expansion of commercial construction projects acts as a vital driver in boosting market growth.
For instance, Imperial Vanities highlights quartz’s popularity in office buildings where quartz surfaces create a professional atmosphere in reception and meeting areas while enduring heavy daily use.
Shift Toward Sustainable and Eco-Friendly Materials
Sustainability has become a central driver in the U.S. Quartz Countertops Market. Manufacturers increasingly promote quartz surfaces made with recycled content, eco-friendly resins, and energy-efficient production processes. Consumers prioritize sustainable materials without compromising performance, encouraging wider adoption. Green building certifications and rising awareness of environmental impact push builders and homeowners toward quartz as a viable alternative to natural stone. This eco-conscious shift not only enhances brand reputation but also expands the customer base among environmentally aware buyers.
Key Trends & Opportunities
Growing Popularity of Customization and Premium Designs
Consumers are demanding greater customization in countertop designs, colors, and textures, creating opportunities for manufacturers to diversify portfolios. Digital fabrication and advanced casting methods enable marble-look, matte, and textured finishes that mimic natural stone while retaining quartz durability. Premium aesthetics attract both residential and commercial buyers seeking unique interiors. This trend supports stronger competition among leading brands and encourages product innovation. The increasing preference for tailored surfaces positions customization as a major growth opportunity in the market.
For instance, Caesarstone introduced its Pebbles Collection with soft earth-inspired hues and unique textures, catering to the demand for nature-inspired customization.
Rising E-Commerce Distribution Channels
Online platforms are emerging as important sales channels, offering consumers greater access to product information, pricing, and design visualization tools. Virtual showrooms and augmented reality applications allow homeowners to preview quartz countertops in their spaces before purchase. This digital shift expands reach beyond traditional specialty stores and distributors, creating new growth avenues. Retailers and manufacturers adopting omnichannel strategies can capture a broader audience, particularly younger homeowners who prefer online research and direct purchasing options for home improvement materials.
For instance, Ultra Decking, a UK-based e-commerce platform, specializes in composite decking by providing detailed product descriptions, side-by-side comparisons, and expert installation guides, enabling customers to make confident purchasing decisions from home.
Key Challenges
High Manufacturing and Installation Costs
Quartz countertops remain more expensive than laminate or solid surface alternatives, creating affordability barriers for price-sensitive customers. Production involves advanced equipment and resins, while installation requires skilled labor, further increasing overall project costs. Although durability offsets long-term expenses, upfront investment often limits adoption in mid-range housing projects. Competition from lower-cost substitutes poses a challenge for manufacturers targeting broad consumer segments. Balancing premium features with competitive pricing continues to be a critical challenge for market expansion.
Supply Chain Disruptions and Raw Material Dependence
The U.S. Quartz Countertops Market faces supply chain constraints linked to raw material sourcing and international trade dynamics. Quartz slabs and resins are often imported, exposing the industry to tariffs, shipping delays, and fluctuating costs. Geopolitical issues and global disruptions, such as container shortages, further impact availability and pricing. These uncertainties create challenges for manufacturers in maintaining consistent supply and meeting growing demand. Developing localized production and diversifying supply networks remain essential to mitigate these risks.
Competition from Natural Stone and Alternative Surfaces
Despite quartz’s rising popularity, competition from granite, marble, and engineered alternatives persists. Natural stone appeals to customers seeking authenticity and uniqueness, while solid surfaces and laminates offer affordability. Some high-end consumers still view natural marble as more prestigious, limiting quartz penetration in luxury projects. Continuous innovation in alternative materials, including porcelain slabs and sintered stone, intensifies competition. To sustain growth, quartz manufacturers must emphasize design innovation, sustainability, and performance advantages to differentiate against rival surface materials.
 Regional Analysis
Northeast
The Northeast held 27% share in 2024, supported by high demand from urban housing and luxury remodeling projects. The region benefits from dense metropolitan areas where homeowners seek durable and modern finishes for kitchens and bathrooms. Growth in premium residential projects and strong adoption in commercial spaces such as hotels and offices drive quartz usage. The U.S. Quartz Countertops Market in the Northeast is also shaped by eco-friendly preferences, encouraging sustainable product adoption. It remains a critical hub for market expansion.
Midwest
The Midwest accounted for 22% share in 2024, driven by steady construction activity and home improvement demand. Consumers favor quartz for its affordability compared to natural stone while maintaining design appeal. The region’s mix of suburban housing and commercial development supports balanced growth across residential and commercial applications. The U.S. Quartz Countertops Market in the Midwest benefits from strong distribution networks and growing acceptance of engineered surfaces. It continues to show consistent demand supported by lifestyle upgrades and durability needs.
South
The South led with 31% share in 2024, reflecting robust housing construction, large-scale remodeling, and expanding commercial real estate. Demand is fueled by population growth, rising disposable incomes, and preference for low-maintenance surfaces in fast-growing cities. Builders increasingly specify quartz countertops for residential and mixed-use projects, strengthening regional dominance. The U.S. Quartz Countertops Market in the South also benefits from strong retail presence and competitive pricing options. It is expected to maintain leadership due to ongoing infrastructure and housing investments.
West
The West held 20% share in 2024, supported by demand in luxury housing, hospitality projects, and modern office interiors. High consumer focus on premium finishes and sustainable materials strengthens quartz adoption. The region’s design-conscious population drives preference for marble-look and customized surfaces. The U.S. Quartz Countertops Market in the West also benefits from green building initiatives and strong remodeling activity. It continues to expand with innovation-led adoption, particularly in metropolitan areas like California and Washington.
 Market Segmentations:
By Product Type
- Press Molding Quartz
- Casting Molding Quartz
By Application
- Residential
- Commercial
- Others
By Region
- Midwest
- South
- West
Competitive Landscape
The U.S. Quartz Countertops Market is highly competitive, with a mix of global brands and strong domestic players. Leading companies such as Cambria, MSI Surfaces, Caesarstone, Silestone (Cosentino), and Daltile ONE Quartz maintain significant presence through extensive product portfolios and robust distribution networks. LX Hausys Viatera, Corian Quartz (DuPont), Vicostone USA, Wilsonart Quartz, and Meta Surfaces further strengthen the landscape by offering diverse designs and customized solutions. Competition focuses on premium finishes, sustainability, and technological advancements in fabrication. Companies emphasize durable, stain-resistant, and eco-friendly products to address consumer demand across residential and commercial applications. Strategic investments in showrooms, digital sales platforms, and partnerships with builders and distributors enhance visibility and market penetration. Innovation in textures, colors, and sustainable resins continues to differentiate offerings. The market reflects strong rivalry, with companies competing on design variety, pricing, and service quality to capture share in both mainstream and luxury countertop segments.
Key Players
- Cambria
- MSI Surfaces
- Caesarstone
- Silestone (Cosentino)
- Daltile ONE Quartz
- LX Hausys Viatera
- Corian Quartz (DuPont)
- Vicostone USA
- Wilsonart Quartz
- Meta Surfaces
Recent Developments
- In August 2024, Vadara Quartz Surfaces launched four new distribution partnerships to strengthen its presence in U.S. East Coast markets.
- In August 2025, Cambria announced an $80 million quartz processing plant and rail center in Dakota County, U.S., while also reshoring some operations from Canada.
- In May 2025, LX Hausys launched the Taj Duna color in its Viatera Quartzite collection and enhanced Cloud Ridge in Suprema.
- In early 2025, Wilsonart introduced new Quartz designs with bold greens and blues at KBIS.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise in residential remodeling, especially kitchens and bathrooms.
- Commercial adoption will expand with growth in hospitality and office interiors.
- Sustainable and eco-friendly quartz surfaces will gain stronger preference.
- Customized finishes and marble-look designs will see higher consumer interest.
- Digital fabrication and advanced casting will improve design flexibility.
- Online and omnichannel sales platforms will strengthen market access.
- Luxury housing projects will continue to boost premium quartz demand.
- Local production and supply chain diversification will reduce import reliance.
- Innovation in antibacterial and hygienic surfaces will expand institutional adoption.
- Competitive differentiation will focus on product variety, sustainability, and service quality.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Quartz Countertops Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Quartz Countertops Market projected to grow between 2025 and 2032?
Which U.S. Quartz Countertops Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Quartz Countertops Market?
Who are the leading companies in the U.S. Quartz Countertops Market?
Which region commanded the largest share of the U.S. Quartz Countertops Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Quartz Countertops Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 U.S. Quartz Countertops Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 414.54 million → 2032: USD 656.56 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Quartz Countertops Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Quartz Countertops Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Quartz Countertops Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 U.S. Quartz Countertops Drivers
- 3.3 U.S. Quartz Countertops Restraints & Challenges
- 3.4 U.S. Quartz Countertops Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Quartz Countertops Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Quartz Countertops Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Quartz Countertops category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Quartz Countertops Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. U.S. Quartz Countertops Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to U.S. Quartz Countertops in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Quartz Countertops Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 U.S. Quartz Countertops Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 U.S. Quartz Countertops Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Quartz Countertops (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in U.S. Quartz Countertops
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. U.S. Quartz Countertops – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. U.S. Quartz Countertops – Priority Domestic Market 1
Chapter 10. U.S. Quartz Countertops – Priority Domestic Market 2
Chapter 11. U.S. Quartz Countertops – Priority Domestic Market 3
Chapter 12. U.S. Quartz Countertops – Priority Domestic Market 4
Chapter 13. U.S. Quartz Countertops Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
