
Market Overview
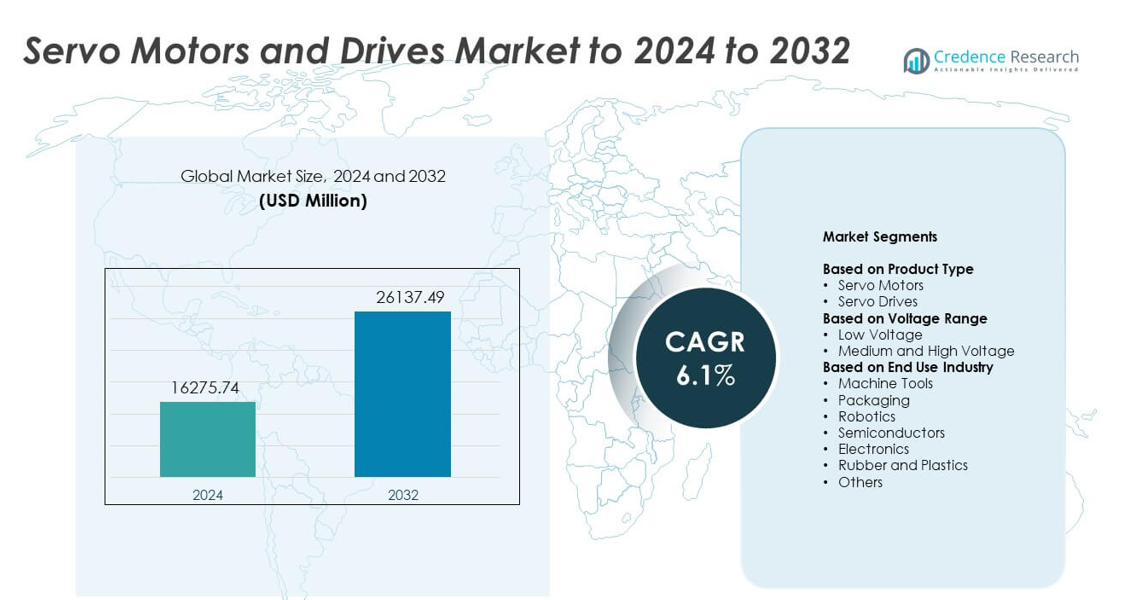
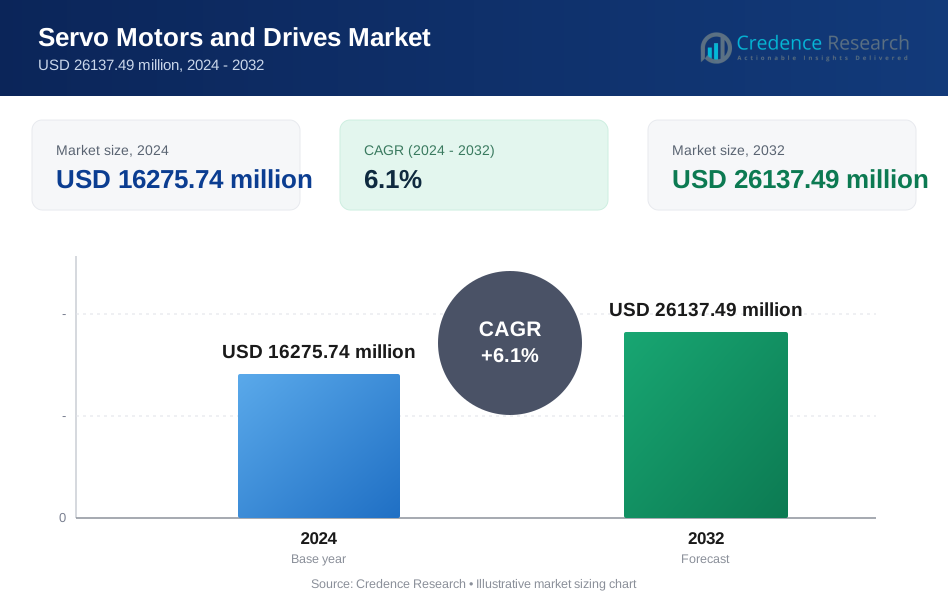
Servo Motors and Drives Market size was valued USD 16275.74 million in 2024 and is anticipated to reach USD 26137.49 million by 2032, at a CAGR of 6.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| SServo Motors and Drives Market Size 2024 | USD 16275.74 million |
| Servo Motors and Drives Market, CAGR | 6.1% |
| Servo Motors and Drives Market Size 2032 | USD 26137.49 million |
The Servo Motors and Drives Market includes leading players such as ABB, Delta Electronics, Fuji Electric, Danfoss, Bosch Rexroth, Advanced Motion Controls, Hitachi, Baumueller, Allied Motion, and Ingenia Cat. These companies compete through high-precision motion systems, energy-efficient drives, and digital control platforms designed for modern automation. Their focus on robotics, semiconductor tools, and advanced manufacturing lines supports steady global demand. Asia Pacific led the market in 2024 with about 34% share due to large-scale industrial expansion, followed by North America with roughly 32% share and Europe with nearly 29% share, reflecting strong adoption across mature automation ecosystems.
Market Insights
- The Servo Motors and Drives Market reached USD 16275.74 million in 2024 and is projected to reach USD 26137.49 million by 2032, growing at a CAGR of 6.1%.
- Rising automation in robotics, packaging, machine tools, and semiconductor equipment drives strong demand, with robotics holding the largest end-use share at about 28% in 2024.
- Key trends include adoption of smart servo drives with real-time monitoring, growing demand for compact high-torque designs, and wider use of energy-efficient systems across digital factories.
- The market remains competitive as major vendors expand digital control platforms, improve encoder accuracy, and form partnerships with automation integrators to strengthen global presence.
- Asia Pacific led the market with 34% share in 2024, followed by North America at 32% and Europe at 29%, while servo drives dominated the product segment with about 58% share.
Market Segmentation Analysis:
By Product Type
Servo drives held the dominant position in 2024 with about 58% share. Strong adoption came from rising demand for precise motion control across automated production lines. Servo drives support faster response, higher torque accuracy, and better energy use, which helped manufacturers upgrade legacy systems. Servo motors saw steady growth due to increased use in compact machinery and robotics, but their share stayed lower than drives because many industries replaced only control units rather than full motor-drive assemblies.
- For instance, Mitsubishi Electric’s MELSERVO-J5 servo amplifiers provide 3.5 kHz speed frequency response. They support rated outputs from 0.1 kW to 7 kW for servo drive control.
By Voltage Range
Low-voltage units led the Servo Motors and Drives Market in 2024 with nearly 71% share. Broad use in packaging, electronics assembly, and light industrial systems supported this lead. Low-voltage solutions offer safer operation, easier integration, and lower installation costs, which encourages adoption in small and mid-scale automation projects. Medium and high-voltage units grew in heavy industries but remained smaller due to higher cost and limited use in specialized high-power applications such as metal forming and large conveyor systems.
- For instance, Omron’s 1S servo system covers a power range from 50 W to 15 kW. It uses a 23-bit high-resolution absolute encoder for precise low-voltage motion control.
By End Use Industry
Robotics emerged as the leading end-use segment in 2024 with nearly 28% share. Strong demand came from rising factory automation, growing cobot installations, and higher precision needs in electronics and automotive assembly. Robotics applications rely heavily on servo systems for accuracy, repeatability, and smooth motion, which boosted segment growth. Machine tools, packaging, and semiconductor equipment followed due to rapid modernization of production lines, while rubber, plastics, and other industries continued gradual adoption with lower volumes.
Key Growth Drivers
Rising Industrial Automation Demand
Automation expansion across manufacturing, electronics, and logistics drives strong uptake of servo motors and drives. Companies modernize plants to improve accuracy, reduce waste, and boost speed, which increases reliance on high-precision motion systems. Growth in robotics, CNC tools, and automated packaging lines also strengthens demand. Many industries shift from manual processes to smart production, and this shift positions servo systems as essential components for stable, efficient, and repeatable motion control.
- For instance, Panasonic’s MINAS A6 servo drives reach a 3.2 kHz response bandwidth for fast control. Selected A6 motors run at speeds up to 6500 rpm with 23-bit encoders.
Advancement in Precision Motion Technologies
Improved encoder systems, compact motor designs, and digital control platforms support wider use of servo solutions. Modern production requires tighter tolerances and dynamic speed control, which increases the appeal of advanced servo architectures. High-resolution feedback and real-time monitoring enhance performance across various machines. These innovations reduce downtime, sharpen accuracy, and help operators maintain product quality, pushing businesses to replace older technologies with new servo-based motion systems.
- For instance, Renishaw’s RESOLUTE absolute encoder offers linear resolution down to 1 nm. It maintains this fine resolution at speeds up to 100 m/s in servo axes.
Growth in Robotics Across Industries
Rising use of industrial and collaborative robots strengthens demand for servo motors and drives. Robotics applications depend on fast response, high torque density, and stable multi-axis control, which match servo capabilities. Automotive, electronics, and warehousing firms deploy robots to boost efficiency and handle repetitive or high-risk tasks. This rise in robot installations, combined with expanding small-scale automation projects, places servo systems at the core of modern robotic motion control.
Key Trends and Opportunities
Shift Toward Energy-Efficient Servo Systems
Manufacturers adopt energy-saving servo drives with regenerative features to cut power use and support sustainability goals. This trend aligns with rising electricity costs and environmental standards across regions. Advanced motors with lower heat loss and higher efficiency attract industries aiming to reduce operational expenses. Growing government focus on energy-efficient machinery expands opportunities for vendors offering optimized servo technologies.
- For instance, Bosch Rexroth’s IndraDrive M power units span from 18 kW to 120 kW. They use energy-saving line regeneration to feed braking energy back into the supply network.
Integration of IIoT and Smart Monitoring
Servo systems increasingly connect with industrial networks to support predictive maintenance and real-time diagnostics. Smart drives help operators track load conditions, speed patterns, and fault history, improving production planning and reducing downtime risks. Adoption of cloud-linked and Ethernet-based servo platforms grows as factories shift toward digital workflows. This integration creates new opportunities for advanced analytics and remote control capabilities.
- For instance, Rockwell Automation’s Kinetix 5700 with Integrated Motion supports a 1 ms minimum base update rate. This fast EtherNet/IP cycle enables tight servo monitoring and real-time diagnostics for each axis.
Expansion of Compact and Lightweight Designs
Miniaturized servo motors address the needs of electronics assembly, medical devices, and compact robotics. Manufacturers seek smaller devices with high torque density and stable positioning accuracy. This trend supports flexible production layouts and space-constrained machines. Growing demand for portable automation tools and precision micro-machinery accelerates adoption of these compact servo solutions.
Key Challenges
High Initial Investment in Advanced Systems
Servo motors and drives carry higher upfront costs than conventional motion equipment, which limits adoption among small and mid-scale manufacturers. Installation, tuning, and integration require specialized skills, adding to the overall project cost. Companies with limited budgets delay upgrades despite efficiency gains. This cost barrier slows modernization in developing regions and affects replacement cycles.
Complex Installation and Technical Expertise Needs
Servo systems require precise setup, parameter tuning, and continuous monitoring for optimal performance. Many facilities lack trained technicians, which increases the risk of errors and downtime during deployment. Compatibility issues with older machines also create integration challenges. These technical hurdles slow adoption in industries transitioning from basic automation to advanced motion control.
Regional Analysis
North America
North America held about 32% share in the Servo Motors and Drives Market in 2024. Strong adoption came from advanced automation in automotive, electronics, and aerospace manufacturing. The region benefits from widespread use of robotics, CNC machines, and motion control platforms across large production facilities. Growing investments in digital factories and rising demand for high-precision equipment continue to support market expansion. The presence of major technology providers and strong industrial modernization trends keeps North America a leading contributor to servo system deployment.
Europe
Europe captured nearly 29% share in 2024, driven by strong automation maturity in Germany, Italy, and France. High demand in automotive plants, packaging lines, and semiconductor operations supports servo adoption. The region’s focus on energy-efficient machinery and Industry 4.0 accelerates upgrades to advanced servo drives. Strong regulatory pressure for high-performance, low-emission industrial equipment boosts the use of precision motion systems. Heavy manufacturing and robotics deployment further reinforce Europe’s position as a key market for servo technologies.
Asia Pacific
Asia Pacific led growth momentum with about 34% share in 2024, supported by large-scale manufacturing hubs in China, Japan, South Korea, and India. Expanding electronics production, rising robotics installations, and strong investment in factory automation drive rapid adoption. The region’s growing semiconductor and packaging sectors rely heavily on high-precision servo systems. Government incentives for smart factories and increasing labor cost pressures encourage faster mechanization. These factors make Asia Pacific the most dynamic and fast-expanding regional market.
Latin America
Latin America accounted for around 3% share in 2024, with demand rising steadily across automotive parts, food processing, and packaging plants. Countries such as Brazil and Mexico continue to automate production lines to improve efficiency and reduce operational losses. Adoption remains gradual due to budget constraints, but modernization programs in industrial clusters support market expansion. Growing import of industrial robots and CNC machinery also increases the need for advanced servo drives and motors in regional manufacturing.
Middle East and Africa
Middle East and Africa held nearly 2% share in 2024, reflecting early-stage but growing adoption of automation. Demand strengthens in sectors such as oil and gas, metals, and logistics, where precision control enhances operational safety and productivity. Investments in new manufacturing zones, especially in Gulf countries, support increased use of servo systems. Limited technical expertise and higher installation costs slow broader penetration, but ongoing industrial diversification efforts continue to create long-term growth opportunities.
Market Segmentations:
By Product Type
- Servo Motors
- Servo Drives
By Voltage Range
- Low Voltage
- Medium and High Voltage
By End Use Industry
- Machine Tools
- Packaging
- Robotics
- Semiconductors
- Electronics
- Rubber and Plastics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Servo Motors and Drives Market features key players such as ABB, Delta Electronics, Fuji Electric, Danfoss, Bosch Rexroth, Advanced Motion Controls, Hitachi, Baumueller, Allied Motion, and Ingenia Cat. The market shows strong competition as companies focus on advanced motion control technologies, energy-efficient architectures, and digital drive platforms that support real-time monitoring. Vendors strengthen their portfolios through improved torque density, faster response systems, and compact motor designs suited for automated equipment. Many manufacturers invest in software-driven control features and integrated safety functions to meet modern production needs. Strategic partnerships with robotics firms, machine builders, and automation integrators help widen their market reach. Continuous upgrades in encoder accuracy, communication protocols, and power optimization also support stronger differentiation in a rapidly evolving industrial automation environment.
Key Player Analysis
- ABB
- Delta Electronics
- Fuji Electric
- Danfoss
- Bosch Rexroth
- Advanced Motion Controls
- Hitachi
- Baumueller
- Allied Motion
- Ingenia Cat
Recent Developments
- In 2025, Allient launched the Pyxmos servo drive family to expand its high-performance motion-control portfolio for robotics and industrial automation
- In 2025, Bosch Rexroth introduced the ctrlX DRIVE cabinet-free IP65 servo drive system, which moves drives out of the control cabinet and cuts space and cabling needs by up to 90 %.
- In 2024, ABB issued an updated ACS180 machinery-drive catalog, positioning the compact drive platform for precise speed and torque control in small machinery and OEM motion applications.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Voltage Range, End-Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as factories increase automation across production lines.
- Robotics adoption will rise and boost demand for high-precision servo systems.
- Compact and lightweight servo designs will gain wider use in space-limited machinery.
- Energy-efficient drives will see stronger uptake due to rising power-saving needs.
- Smart servo platforms with real-time monitoring will grow with digital factory adoption.
- Semiconductor and electronics manufacturing will drive higher multi-axis servo demand.
- Growth in electric vehicle production will increase servo use in assembly and testing.
- Replacement of legacy motion systems will accelerate in aging industrial plants.
- Servo vendors will expand service-based models such as predictive maintenance support.
- Emerging markets will adopt servo systems faster as labor costs and automation needs
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Servo Motors and Drives Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Servo Motors and Drives Market projected to grow between 2024 and 2032?
Which Servo Motors and Drives Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Servo Motors and Drives Market?
Who are the leading companies in the Servo Motors and Drives Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Servo Motors and Drives Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Servo Motors and Drives Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 16275.74 million → 2032: USD 26137.49 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Servo Motors and Drives Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Servo Motors and Drives Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Servo Motors and Drives Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Servo Motors and Drives Market Drivers
- 3.3 Servo Motors and Drives Market Restraints & Challenges
- 3.4 Servo Motors and Drives Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Servo Motors and Drives Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Servo Motors and Drives Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Servo Motors and Drives category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Servo Motors and Drives Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Servo Motors and Drives Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Servo Motors and Drives market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Servo Motors and Drives Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Servo Motors and Drives Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Servo Motors and Drives Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Servo Motors and Drives (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Servo Motors and Drives Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Servo Motors and Drives Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Servo Motors and Drives Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Servo Motors and Drives Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Servo Motors and Drives Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Servo Motors and Drives Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Servo Motors and Drives Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Servo Motors and Drives Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Servo Motors and Drives Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
