
Market Overview:
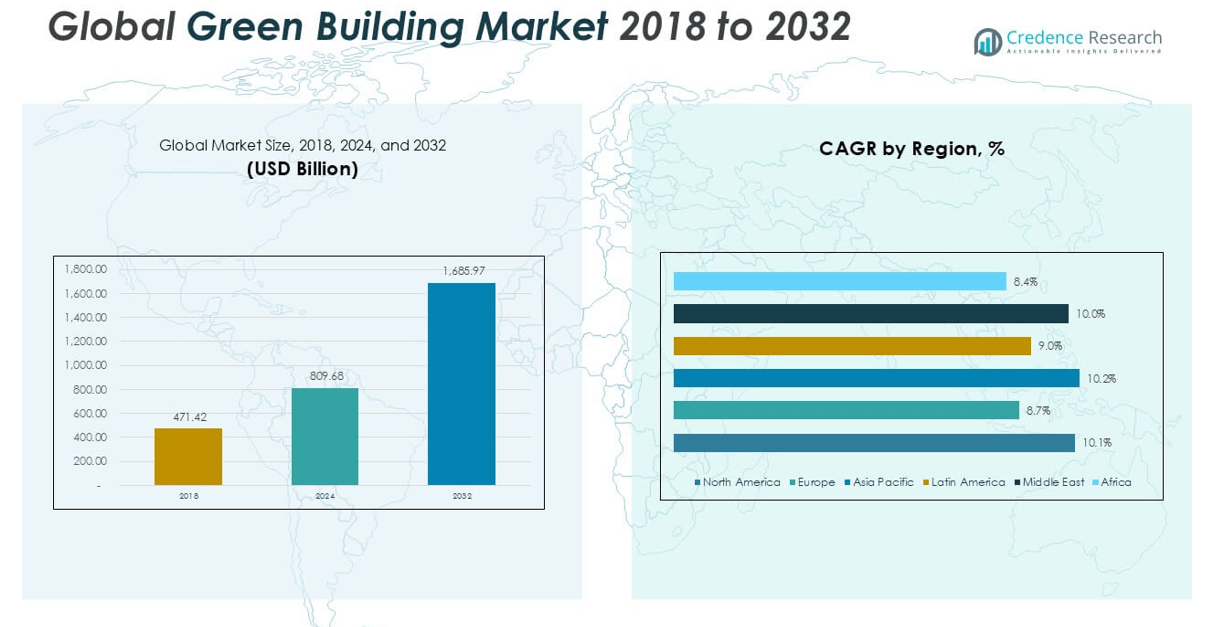
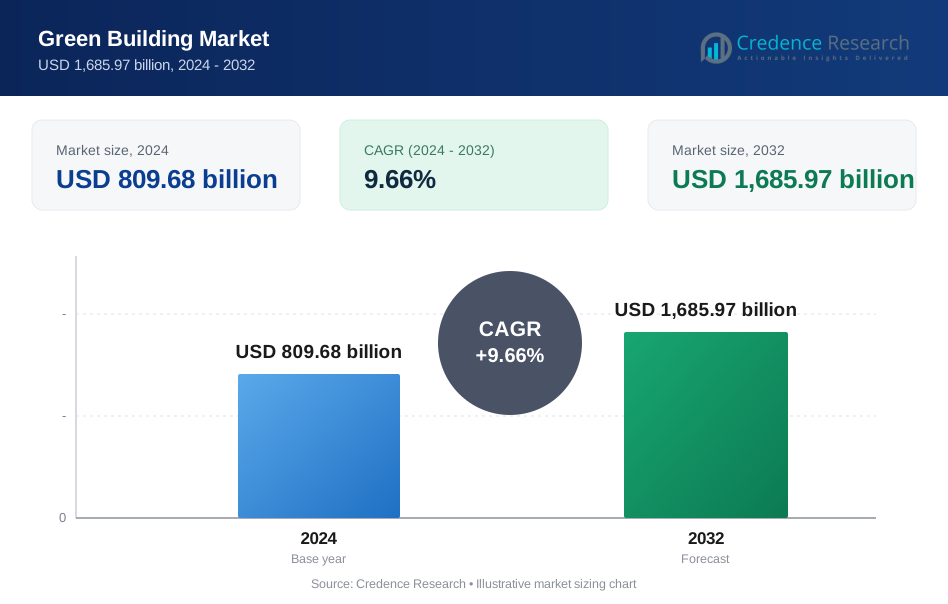
The Green Building market size was valued at USD 471.42 million in 2018 and grew to USD 809.68 billion in 2024. It is anticipated to reach USD 1,685.97 billion by 2032, at a CAGR of 9.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Green Building Market Size 2024 | USD 809.68 billion |
| Green Building Market, CAGR | 9.66% |
| Green Building Market Size 2032 | USD 1,685.97 billion |
Top players in the Green Building market include BASF SE, Owens Corning SA, CEMEX, Cisco Systems, Inc., and Interface Inc., all of which lead through innovation, sustainable product development, and strategic collaborations. These companies are actively investing in eco-friendly materials, energy-efficient systems, and smart building technologies to meet growing global demand. Among regions, Asia Pacific dominates the market with a 32.4% share in 2024, driven by rapid urbanization, supportive government policies, and large-scale green infrastructure projects in countries such as China, India, and Japan. North America and Europe follow closely, supported by regulatory mandates and high adoption of green certifications.
Market Insights
- The Green Building market was valued at USD 809.68 billion in 2024 and is projected to reach USD 1,685.97 billion by 2032, growing at a CAGR of 9.66% during the forecast period.
- Growth is driven by stringent environmental regulations, rising demand for energy-efficient buildings, and increasing adoption of green certifications such as LEED and BREEAM across commercial and residential sectors.
- A key trend includes the integration of smart technologies and IoT in green buildings, along with a growing preference for sustainable and recycled construction materials to meet climate goals.
- Major players like BASF SE, Owens Corning SA, and CEMEX dominate the competitive landscape by offering innovative, eco-friendly products, while high initial costs and limited awareness of long-term ROI remain key restraints.
- Asia Pacific held the largest regional share at 32.4% in 2024, followed by North America at 25.6%, with Building Systems emerging as the leading product segment due to rising demand for smart and efficient infrastructure.
Market Segmentation Analysis:
By Product
The Green Building market, segmented by product, is led by the Building Systems sub-segment, which held the largest market share in 2024. This dominance is attributed to the growing adoption of energy-efficient HVAC, lighting, and water management systems in sustainable construction. As regulations around environmental standards tighten, building systems designed for minimal resource consumption and smart integration are gaining significant traction. Interior and exterior products are also experiencing steady growth due to increasing consumer demand for non-toxic, recycled, and low-VOC materials that enhance indoor air quality and overall occupant well-being.
- For instance, Owens Corning’s advanced HVAC control upgrade at two manufacturing facilities generated combined savings of USD 350,000 per year, optimizing outside‑air usage and equipment sequencing.
By End Use
Within the end-use segmentation, the Commercial sector emerged as the dominant sub-segment in 2024, accounting for the highest market share. This is driven by increased investment in green-certified office spaces, retail establishments, and institutional buildings to reduce operational costs and meet corporate sustainability goals. Rising awareness of long-term energy savings and favorable government incentives for sustainable development have further boosted adoption in the commercial segment. The residential segment is rapidly growing as homeowners seek eco-friendly housing options, while the industrial sector is integrating green building practices to improve efficiency and comply with environmental standards.
- For instance, Cisco certified 55 buildings across global offices (San Jose, Chicago, New York City, Bangalore, London) under WELL Health‑Safety Rating by January 2022, demonstrating adoption in institutional and corporate facilities
Market Overview
Stringent Environmental Regulations and Green Building Certifications
Governments worldwide are implementing stringent environmental regulations and promoting green building certifications such as LEED, BREEAM, and IGBC. These standards drive the adoption of energy-efficient construction practices and environmentally responsible materials. Developers and building owners are increasingly compelled to comply with these regulations to gain project approvals and incentives. This regulatory push not only encourages sustainable practices but also enhances property value, positioning green buildings as a preferred choice in both commercial and residential construction projects.
- For instance, Skanska, one of the world’s largest construction and development companies, has developed over 200 LEED-certified projects across the U.S., including the Bank of America Tower in Houston, which achieved LEED Platinum status and reduced energy use intensity by 36.5 kBtu/sq ft/year compared to the baseline.
Rising Demand for Energy Efficiency and Cost Savings
Energy efficiency remains a critical driver in the green building market, as property owners seek to reduce long-term operating costs. Green buildings, with optimized HVAC systems, insulated materials, and smart technologies, consume significantly less energy compared to traditional structures. The financial appeal of lower utility bills, combined with improved occupancy comfort and reduced maintenance, continues to drive demand. Corporations and individuals alike view green buildings as a viable investment for achieving both sustainability targets and economic returns.
- For instance, Owens Corning implemented 77 energy efficiency projects across its facilities, resulting in an annual reduction of 51,000 megawatt-hours of energy usage and a corresponding decrease of 25,000 metric tons of carbon emissions.
Increasing Urbanization and Sustainable Development Initiatives
Rapid urbanization, especially in emerging economies, is fueling demand for sustainable infrastructure solutions. Governments and urban planners are integrating green building principles into city development projects to reduce environmental impact and support sustainable living. Smart city initiatives and rising awareness of climate change among stakeholders are further accelerating this trend. These efforts are creating ample growth opportunities for eco-friendly construction technologies, materials, and design methodologies across both new constructions and retrofitting projects.
Key Trends & Opportunities
Integration of Smart and IoT-Enabled Building Systems
The convergence of green building technologies with IoT and smart systems is a notable trend. Advanced sensors, automation, and real-time data analytics are being used to optimize energy consumption, water usage, and indoor air quality. This integration enhances building performance and supports predictive maintenance. As more developers and facility managers adopt smart building solutions, this trend is creating new opportunities for innovation and efficiency in the green construction market.
- For instance, Siemens deployed its Desigo CC building management system in The Crystal, London-one of the world's most sustainable buildings-achieving a 50% reduction in water consumption and cutting carbon dioxide emissions to 70 metric tons per year, supported by 2,500 data points for building system monitoring.
Growing Preference for Sustainable Building Materials
There is a rising preference for environmentally friendly building materials such as recycled steel, bamboo, reclaimed wood, and low-VOC paints. These materials not only reduce the environmental footprint but also improve occupant health. Innovations in green materials are enabling durable, cost-effective, and aesthetic construction solutions. This trend is opening up significant opportunities for manufacturers and suppliers to develop and scale eco-conscious products to meet rising demand across residential, commercial, and industrial segments.
- For instance, Interface Inc. developed its Carbon Neutral Floors™ which prevented 402,000 metric tons of CO₂ emissions from entering the atmosphere in a single year equivalent to the annual emissions of 87,000 passenger cars by using recycled yarns and bio-based backing in its carpet tiles.
Key Challenges
High Initial Costs and Limited ROI Awareness
One of the main challenges in the green building market is the high upfront investment associated with sustainable construction materials and technologies. Although green buildings offer long-term cost savings, many developers and property owners are hesitant due to the lack of immediate financial returns. Additionally, limited awareness about the lifecycle cost benefits and return on investment (ROI) continues to hinder wider adoption, especially in price-sensitive markets.
Lack of Skilled Workforce and Technical Knowledge
Implementing green building projects requires specialized knowledge in sustainable design, material selection, and system integration. However, the construction industry still faces a shortage of trained professionals and architects proficient in green building practices. This gap limits the scalability of sustainable construction, particularly in developing regions. Addressing this challenge necessitates greater investment in training programs, technical education, and industry collaborations to build capacity.
Complex Certification Processes and Regulatory Variability
Navigating green building certification processes can be time-consuming and costly. The complexity of meeting various local and international standards often deters small and mid-size developers. Additionally, regulatory frameworks vary significantly between regions, leading to inconsistencies in compliance requirements. These barriers can delay project timelines and increase administrative burdens, thereby impacting overall market growth and efficiency.
Regional Analysis
North America
North America held a significant share of the global Green Building market in 2024, accounting for approximately 25.6% of the total market. Valued at USD 206.94 billion in 2024, up from USD 117.34 billion in 2018, the region is projected to reach USD 445.94 billion by 2032, registering a CAGR of 10.1%. The market is driven by well-established sustainability policies, advanced construction practices, and growing demand for energy-efficient buildings across the U.S. and Canada. Government incentives, along with LEED certifications, continue to support adoption, particularly in the commercial sector where companies seek to reduce operational costs and carbon footprints.
Europe
Europe accounted for roughly 24.5% of the Green Building market in 2024, with a value of USD 227.28 billion, increasing from USD 138.83 billion in 2018. The market is expected to reach USD 442.23 billion by 2032, growing at a CAGR of 8.7%. The region’s market growth is supported by stringent EU regulations on building emissions, the European Green Deal, and growing investment in retrofitting aging infrastructure. Countries such as Germany, France, and the UK are at the forefront of adopting sustainable materials and building standards, with strong participation from both residential and institutional segments driving the momentum.
Asia Pacific
Asia Pacific emerged as the leading regional market in 2024, capturing the largest share at 32.4%, valued at USD 262.17 billion, up from USD 147.69 billion in 2018. With a robust CAGR of 10.2%, the market is anticipated to reach USD 569.52 billion by 2032. The region’s growth is propelled by rapid urbanization, supportive government regulations, and rising environmental awareness in countries such as China, India, and Japan. Ongoing infrastructure expansion, green city initiatives, and high energy demand are encouraging the integration of eco-friendly practices and sustainable materials across commercial and residential construction projects.
Latin America
In 2024, Latin America contributed approximately 8.2% to the global Green Building market, with a market value of USD 66.16 billion, rising from USD 39.83 billion in 2018. The region is forecasted to reach USD 131.51 billion by 2032, at a CAGR of 9.0%. Brazil and Mexico are major contributors, backed by increasing urban development and green building awareness. Growth in the commercial and public infrastructure sectors, along with international partnerships promoting sustainability standards, are driving regional adoption. However, challenges such as limited funding and inconsistent policy implementation across countries slightly temper the overall growth pace.
Middle East
The Middle East accounted for around 3.9% of the Green Building market in 2024, with a market value of USD 31.85 billion, growing from USD 18.24 billion in 2018. The market is projected to reach USD 67.78 billion by 2032, expanding at a CAGR of 10.0%. High energy consumption rates, combined with rising environmental concerns, are encouraging governments in the UAE, Saudi Arabia, and Qatar to invest in sustainable construction practices. Mega infrastructure projects and smart city developments are prioritizing green certification standards, especially in commercial and hospitality segments, to support regional environmental goals and global climate commitments.
Africa
Africa held the smallest share of the Green Building market in 2024, accounting for about 1.9%, with a market size of USD 15.27 billion, up from USD 9.48 billion in 2018. The market is expected to reach USD 29.00 billion by 2032, growing at a CAGR of 8.4%. While growth remains modest, increasing urban population, housing needs, and donor-backed green construction initiatives are fostering momentum in key regions like South Africa and Kenya. However, limited financial resources, lack of regulatory enforcement, and insufficient awareness of long-term benefits continue to pose challenges to widespread adoption across the continent.
Market Segmentations:
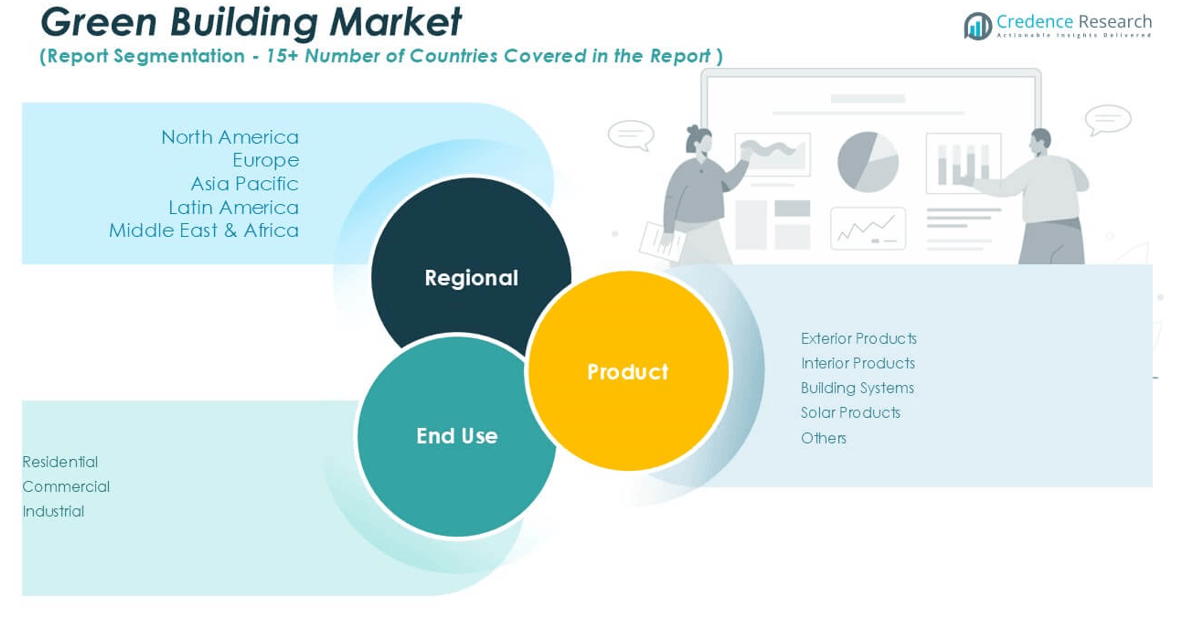
By Product
- Exterior Products
- Interior Products
- Building Systems
- Solar Products
- Others
By End Use
- Residential
- Commercial
- Industrial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Green Building market is characterized by the presence of both global conglomerates and specialized regional players actively innovating to capture market share. Key companies such as BASF SE, Owens Corning SA, CEMEX, and Cisco Systems, Inc. are focusing on developing advanced eco-friendly construction materials, energy-efficient systems, and smart building technologies. These players invest heavily in R&D, strategic mergers, and sustainability-driven partnerships to strengthen their product portfolios and expand their global footprint. Additionally, companies like Amvik Systems, Alumasc Group PLC, and Bauder Limited are leveraging niche expertise in insulation, roofing, and green infrastructure to cater to the rising demand for low-carbon solutions. The market also sees increasing collaboration between technology providers and construction firms to integrate IoT and automation in sustainable buildings. As environmental regulations become more stringent, competition is intensifying, prompting firms to differentiate through innovation, green certifications, and cost-effective, high-performance building products.
Key Player Analysis
- Amvik Systems
- Alumasc Group PLC
- BASF SE
- Binderholz GmbH
- Bauder Limited
- Cisco Systems, Inc.
- Interface Inc
- Forbo International SA
- Owens Corning SA
- CEMEX
Recent Developments
- In August 2024, Bauder released guidance on using green roofs to comply with the UK's new Biodiversity Net Gain (BNG) legislation. The guidance emphasizes BauderBIODIVERSE Green Roofs as a solution for creating habitats that support a variety of flora and fauna, aligning with BREEAM, UGF, and local Biodiversity Action Plans. This new legislation mandates measurable biodiversity improvements in new developments.
- In June 2023, Accenture announced the acquisition of Green Domus, the Brazilian sustainability consultancy that assists clients in formulating and implementing various sustainability strategies, in particular the measurable decarbonization efforts.
- In March 2023, BlocPower, a green building technology startup, obtained almost USD 25 million in equity and USD 130 million in debt funding to undertake retrofitting of hundreds of thousands of homes and other structures with energy-efficient gadgets.
- In 2022, Binderholz GmbH, the subsidiary of the Austrian Binderholz Group, has moved a step further in expanding over BSW Timber Ltd. This move gave Binderholz GmbH the largest sawmill and solid wood processor in Europe and increased its annual manufacturing capacity of sawn timber by more than 1.2 million.
Market Concentration & Characteristics
The Green Building market exhibits moderate to high market concentration, with a mix of established global players and emerging regional companies competing across product and end-use segments. Large corporations such as BASF SE, CEMEX, and Owens Corning SA hold significant shares due to their extensive product portfolios, R&D capabilities, and global distribution networks. It reflects strong entry barriers created by the need for technological expertise, compliance with stringent environmental standards, and green certification requirements. The market demonstrates a strong focus on innovation, especially in sustainable materials, energy-efficient systems, and smart building technologies. Product differentiation and sustainability credentials influence purchasing decisions across commercial, residential, and industrial sectors. Demand is concentrated in urban centers and regions with supportive regulatory frameworks, especially in Asia Pacific, North America, and Europe. It also shows characteristics of a demand-driven market where customer awareness, long-term cost savings, and government incentives shape investment and construction decisions.
Report Coverage
The research report offers an in-depth analysis based on Product, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Green Building market will continue expanding due to increasing global emphasis on energy efficiency and carbon reduction.
- Demand for sustainable construction materials will rise, driven by evolving environmental regulations and consumer awareness.
- Smart building integration with IoT and AI technologies will become standard in new green construction projects.
- Retrofitting of existing buildings with green technologies will gain momentum across both developed and developing regions.
- Government incentives and mandatory green certifications will further encourage adoption of eco-friendly building practices.
- Asia Pacific will maintain its lead in market share, supported by rapid urbanization and infrastructure development.
- North America and Europe will experience steady growth due to advanced construction technologies and strict environmental policies.
- The residential sector will witness faster adoption of green practices as homeowners seek long-term cost savings and healthier living environments.
- Innovations in solar products and building systems will drive product-level advancements in the market.
- Increased collaboration between construction firms and technology providers will shape the future of green infrastructure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations and Green Certifications
Governments worldwide are enforcing strict environmental standards and promoting certifications such as LEED and BREEAM, compelling developers to adopt green building practices to gain project approvals and incentives. This regulatory push is accelerating the adoption of sustainable construction methods and materials.
Demand for Energy Efficiency and Cost Savings
Building owners and developers are increasingly seeking energy-efficient solutions to reduce long-term operational costs. Green buildings, with optimized HVAC, insulation, and smart technologies, offer significant utility savings and improved occupant comfort, making them attractive investments.
Rapid Urbanization and Sustainable Infrastructure Initiatives
Emerging economies, particularly in Asia Pacific, are experiencing rapid urban growth, driving the need for sustainable infrastructure. Governments and urban planners are integrating green building principles into city development projects to minimize environmental impact and support sustainable living.
Integration of Smart and IoT-Enabled Building Systems
The adoption of advanced sensors, automation, and real-time analytics in building systems is optimizing resource consumption and enhancing building performance. This trend is creating new opportunities for innovation and efficiency in green construction.
Growing Preference for Sustainable and Recycled Materials
There is increasing demand for eco-friendly construction materials such as recycled steel, bamboo, and low-VOC paints, which reduce environmental footprint and improve occupant health. Innovations in green materials are enabling durable and cost-effective solutions, further driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Green Building Market?
What factors are driving the growth of the Green Building Market?
What are some challenges faced by the Green Building Market?
Who are the major players in the Green Building Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Product
- 1.3.1 Exterior Products
- 1.3.2 Interior Products
- 1.3.3 Building Systems
- 1.3.4 Solar Products
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 809.68 billion → 2032: USD 1,685.97 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Green Building Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Green Building Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Green Building Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Green Building Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Green Building Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Green Building Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Green Building Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Green Building Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 809.68 billion → 2032: USD 1,685.97 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Green Building Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Exterior Products
- 12.4.7.2 Interior Products
- 12.4.7.3 Building Systems
- 12.4.7.4 Solar Products
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Green Building End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Green Building Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Green Building Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Green Building Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Owens Corning SA
- 18.4 CEMEX
- 18.5 Cisco Systems, Inc.
- 18.6 Interface Inc.
- 18.7 Amvik Systems
- 18.8 Alumasc Group PLC
- 18.9 Binderholz GmbH
- 18.10 Bauder Limited
- 18.11 Forbo International SA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

