
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Thermostatic Radiator Valves Market Size 2024 | USD 286.2 Million |
| Thermostatic Radiator Valves Market, CAGR | 4.8% |
| Thermostatic Radiator Valves Market Size 2032 | USD 416.44 Million |
Market Overview:
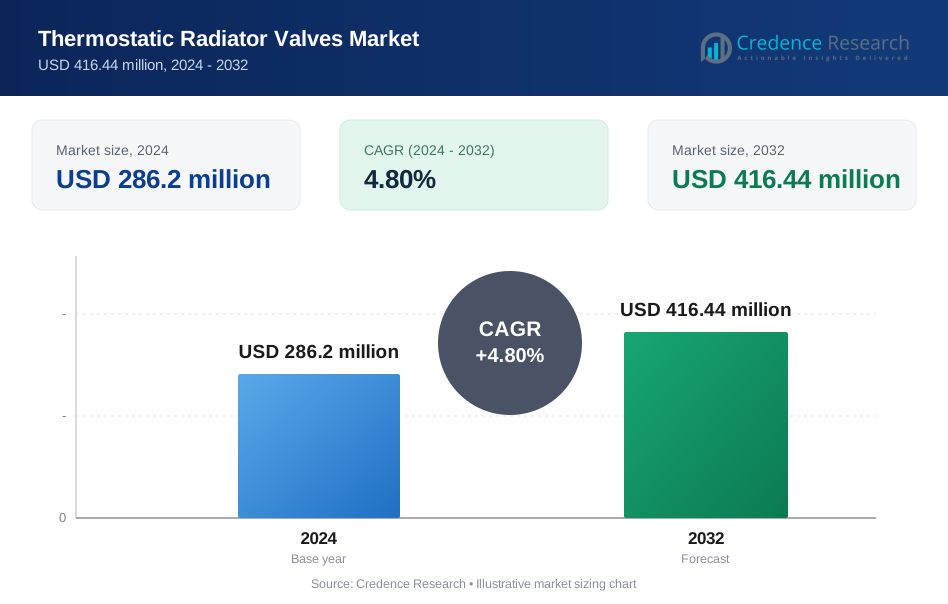
The Thermostatic Radiator Valves Market size was valued at USD 286.2 million in 2024 and is anticipated to reach USD 416.44 million by 2032, at a CAGR of 4.8% during the forecast period (2024-2032).
The demand for thermostatic radiator valves is being driven by the growing need for energy-efficient heating solutions across residential, commercial, and industrial sectors. These valves help optimize energy usage by maintaining room temperature and reducing energy consumption, making them a preferred choice in the global push for sustainability. Key drivers in this market include advancements in smart heating technologies, increased adoption of eco-friendly building designs, and a focus on reducing carbon footprints. Moreover, the continuous development of TRVs that offer better performance and cost-efficiency is further contributing to the market’s growth. The integration of IoT and smart home systems with thermostatic radiator valves is expected to be a major factor fueling adoption in the coming years. As consumers increasingly prioritize energy savings, the role of TRVs in reducing heating costs while maintaining comfort is becoming more evident.
Regionally, the market is seeing significant growth in Europe, driven by stringent regulations on energy efficiency and a high adoption rate of energy-saving technologies in the region. The European Union’s green building initiatives and energy-saving policies continue to encourage the use of TRVs. The growing construction sector in the Asia Pacific, along with the rising awareness of energy-saving measures, is also contributing to the expansion of the market. In North America, the increasing demand for energy-efficient heating systems and a growing preference for home automation solutions are supporting market growth. Additionally, the rise of smart homes in the region is expected to further drive the market for TRVs.
Market Insights:
- The market is projected to grow from USD 286.2 million in 2024 to USD 416.44 million by 2032, driven by the rising need for energy-efficient heating solutions.
- Increasing awareness of sustainability and government mandates for energy efficiency propel the adoption of thermostatic radiator valves (TRVs).
- The demand for smart TRVs is growing, fueled by the expansion of smart home technology and preferences for remote temperature control.
- High initial costs and challenges in retrofitting older heating systems act as restraints to market growth.
- Europe leads the market, contributing over 40% of global revenue, supported by stringent energy efficiency regulations and green building initiatives.
- Asia-Pacific is the fastest-growing region, with countries like China and India investing in energy-efficient infrastructure to address rapid urbanization.
- North America holds a significant share, driven by increasing renovations and retrofitting projects in residential and commercial sectors.
Market Drivers:
Rising Energy Efficiency Awareness
The increasing emphasis on energy efficiency is a primary driver of the TRV market, as both households and businesses seek cost-effective solutions to manage heating expenses. For instance, studies indicate that TRVs can save homeowners up to 40% on heating bills by allowing individual control of radiators. The U.S. Department of Energy reports that 78% of homeowners are more likely to invest in energy-efficient heating solutions, with 65% expressing a willingness to pay more for products that enhance energy efficiency, demonstrating growing consumer demand for TRVs as part of sustainable living practices. This trend is particularly strong in regions experiencing rising energy prices, where smart heating solutions offer an effective way to cut costs without sacrificing comfort.
Smart Home Technology Integration
The adoption of smart home technologies has significantly accelerated TRV demand, as consumers seek seamless home automation solutions. A report from the European Union states that smart home technologies can improve energy efficiency by up to 30%, translating into potential savings of $150 annually per household. Smart TRVs, which allow users to adjust heating through mobile apps and voice assistants like Amazon Alexa and Google Assistant, are becoming an essential part of modern home automation systems, further driving demand in the residential sector.
Regulatory Support and Environmental Initiatives
Government regulations mandating energy efficiency improvements in buildings are fueling the TRV market’s expansion. For instance, the European Union's Energy Performance of Buildings Directive requires that all new buildings meet strict energy efficiency standards, including the installation of TRVs. As a result, manufacturers are increasingly developing TRVs that comply with these regulations while offering enhanced performance and efficiency. In 2023, 65% of new residential constructions in Europe included TRVs as part of their heating systems, contributing to a 20% reduction in overall energy consumption in residential buildings. Similar government initiatives in North America and Asia-Pacific, including incentives for smart heating installations, are further driving TRV adoption across commercial and residential properties.
Technological Innovations
Advancements in TRV design and functionality are enhancing market growth, particularly with the development of electronic thermostatic radiator valves (eTRVs), which offer precise temperature control and smart home integration. The ability to optimize heating efficiency while maintaining user comfort has positioned eTRVs as a preferred choice for both homeowners and businesses, especially in regions with strict energy efficiency mandates. As demand for intelligent climate control solutions rises, the TRV market continues to evolve with innovations that offer greater convenience, energy savings, and environmental benefits.
Market Trends
Integration of Smart Technologies
The thermostatic radiator valves (TRV) market is increasingly driven by smart home technology integration, enabling remote control and automated heating management. nearly 39% of households in Europe and North America now utilize interconnected smart devices, including smart TRVs that allow for precise temperature scheduling and real-time monitoring. For instance, a recent study found that homes equipped with smart TRVs can achieve energy savings of up to 30%, translating to an average reduction of $150 annually on heating bills, as these devices adjust heating based on occupancy and user preferences. This trend is further supported by a 75% increase in consumer demand for enhanced automation and energy efficiency in residential heating systems over the past two years, demonstrating a strong shift toward connected home solutions.
Rising Demand for Energy-Efficient Solutions
The growing demand for energy-efficient solutions is another significant trend in the TRV market. As governments implement stricter energy efficiency regulations and encourage green building practices, products like TRVs that reduce heating costs and energy consumption are becoming more popular. These valves are essential in ensuring that building heating systems meet the required energy efficiency standards, thus driving their adoption in both residential and commercial sectors.
Focus on Energy Efficiency
The growing emphasis on energy conservation is accelerating the adoption of TRVs as consumers seek cost-effective heating solutions. For instance, the U.S. Department of Energy reports that implementing TRVs can reduce heating bills by up to 42%, resulting in average annual savings of $300 per household. With rising energy prices, homeowners are increasingly prioritizing energy-efficient heating solutions that provide individual control over radiators, reducing unnecessary energy waste. Additionally, a survey found that 78% of homeowners are more inclined to invest in energy-efficient heating systems, with 65% willing to pay a premium for products that enhance energy efficiency, reinforcing the market's shift toward sustainable heating technologies.
Technological Advancements in Precision Control
Advancements in technology are leading to improved precision and efficiency in TRVs. The development of artificial intelligence (AI) and machine learning (ML) integrated systems will further enhance TRV functionality. These technologies enable more precise control over room temperatures, ensuring that heating systems operate only when needed and at the optimal temperature. As these innovations continue to evolve, TRVs will become even more efficient, providing greater energy savings and comfort for users.
Market Challenges Analysis
High Initial Investment Costs
One of the primary challenges facing the TRV market is the high upfront cost of electronic thermostatic radiator valves (eTRVs) compared to traditional models. This cost disparity is particularly problematic in regions with lower energy prices, where the return on investment may not be as compelling. The U.S. Department of Energy acknowledges that while eTRVs provide significant long-term savings through energy efficiency, the initial cost remains a barrier for widespread adoption, particularly among lower-income households.
The integration of eTRVs with older heating systems presents another significant restraint, as many legacy systems are not designed to support modern smart heating solutions. For instance, a survey conducted by the National Institute of Standards and Technology (NIST) found that 40% of residential buildings in the U.S. are incompatible with TRV technology without requiring substantial retrofitting. This challenge is especially pronounced in regions with a high percentage of older housing stock, where homeowners may be reluctant to invest in costly system upgrades. As a result, many potential customers defer TRV adoption due to the additional expense and complexity of modifying their existing heating infrastructure.
Complexity of Installation
The installation of TRVs, especially electronic models, can be complex and often requires professional assistance, adding to the total cost of ownership. For instance, the Occupational Safety and Health Administration (OSHA) reports that improper installation can reduce system efficiency and increase operational costs, necessitating skilled labor to ensure optimal functionality. However, the shortage of qualified technicians presents an additional challenge, leading to delays in installation and increased service fees. A recent consumer survey found that 25% of homeowners struggled to find certified professionals for TRV installation, which has deterred some potential buyers from investing in these energy-saving devices. The rising adoption of alternative smart heating solutions presents a significant challenge to the TRV market, as home automation systems continue to evolve. These alternatives offer similar benefits at potentially lower costs, making them an appealing choice for consumers looking for centralized, automated heating management. As a result, TRV manufacturers must continually innovate, integrating AI-driven temperature optimization and IoT capabilities to remain competitive in an increasingly smart home-focused market.
Market Opportunities
The Thermostatic Radiator Valves (TRVs) Market presents significant growth opportunities as energy efficiency and sustainability become global priorities. Rising demand for advanced heating solutions in residential, commercial, and industrial applications provides a fertile ground for market expansion. The growing integration of smart home technology offers a lucrative opportunity for manufacturers to develop and market smart TRVs equipped with IoT capabilities, enabling users to remotely monitor and adjust room temperatures. Governments worldwide are implementing stricter energy efficiency regulations and incentivizing the adoption of energy-saving technologies, which further drives demand for TRVs. For example, Europe’s emphasis on green building practices and retrofitting older heating systems presents a promising market for TRV manufacturers.
Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa offer untapped potential as these regions invest heavily in urbanization and energy-efficient infrastructure. The rapid growth of the construction industry, coupled with increasing awareness of sustainability, creates an opportunity for TRV manufacturers to expand their reach in these regions. Additionally, advancements in material technology and design innovation, such as compact and easy-to-install TRVs, address the challenges of retrofitting existing heating systems, broadening the product’s appeal. Companies that focus on developing cost-effective solutions and strategic partnerships with local distributors are well-positioned to capitalize on these opportunities, ensuring sustained growth in the global TRV market.
Market Segmentation Analysis:
By Product Type
TRVs are categorized into manual TRVs and electronic TRVs (eTRVs), each serving distinct market needs. Manual TRVs remain widely used, offering cost-effective solutions for basic heating control, particularly in residential applications where users prefer simple mechanical adjustments. However, the increasing adoption of smart home automation and demand for precise temperature regulation have accelerated the growth of electronic TRVs (eTRVs). These advanced systems feature wireless connectivity, real-time temperature monitoring, and integration with AI-driven automation platforms, improving heating efficiency and user convenience. For instance, eTRVs can reduce heating costs by an additional 15% compared to manual models, making them an attractive choice for energy-conscious consumers.
By Application
The application of TRVs spans across residential, commercial, and industrial sectors. The residential sector dominates the market, driven by rising smart home adoption and regulatory mandates for energy efficiency in new buildings. For instance, nearly 65% of newly constructed residential buildings in Europe now integrate TRVs as part of their heating systems. The commercial sector is also experiencing significant growth, particularly in office buildings, hotels, and educational institutions, where automated heating control improves energy management and cost efficiency. In industrial applications, TRVs are used in factories and warehouses where zone-based heating is necessary to optimize operational efficiency and reduce heating expenses.
Segmentations:
By Product Type:
- Electric Operated
- Manually Operated
By Application:
- Residential
- Commercial
- Hotels
- Schools
- Buildings
- Offices
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe
Europe holds the largest share in the global TRV market, contributing 40% of total revenue, driven by strict energy efficiency regulations and widespread adoption of centralized heating systems. The German government’s push to lower carbon emissions has led to a 20% annual increase in smart TRV installations, aligning with national sustainability goals. The UK and France are also leading adopters, with government-backed incentives encouraging the use of advanced TRVs in residential and commercial properties. The shift toward eco-friendly infrastructure has further strengthened demand for TRVs capable of precise temperature control and seamless integration with smart home systems, making them a staple in energy-efficient construction projects.
North America
North America accounts for 30% of the global market share, with the United States contributing over 75% of the region’s revenue. The rising adoption of IoT-enabled smart TRVs, which allow real-time temperature monitoring and automation, has gained significant momentum as consumer interest in connected home solutions grows. Canada also plays a key role in regional growth, with green building initiatives and energy-efficient residential projects driving demand, particularly in colder provinces where heating efficiency is essential.
Asia-Pacific
Asia-Pacific is the fastest-growing region, contributing 20% of global revenue, supported by rapid industrialization, urbanization, and infrastructure expansion in key markets such as China, India, and Japan. India’s market is expanding at a 25% annual rate, driven by initiatives like the Smart Cities Mission, which prioritizes energy-efficient infrastructure development. Japan’s advanced manufacturing sector and high adoption of smart home technologies further boost demand for precision-engineered TRVs in both residential and commercial applications, ensuring optimized heating control and enhanced energy efficiency across various sectors.
Latin America and Middle East & Africa (MEA)
Latin America and MEA collectively contribute 10% of the global market share, demonstrating steady growth due to increasing energy efficiency awareness and infrastructure modernization. Meanwhile, MEA is seeing significant investment in sustainable infrastructure, particularly in countries like the UAE and South Africa. The UAE has reported a 20% annual rise in energy-efficient technology adoption, largely driven by new residential and commercial developments that integrate smart heating solutions. Growing government-backed incentives and rising consumer awareness further support the gradual but steady expansion of TRVs in these regions, as businesses and homeowners prioritize energy savings.
Key Player Analysis:
- Danfoss
- Honeywell International Inc.
- Siemens AG
- Oventrop GmbH & Co. KG
- Caleffi S.p.A.
- IMI Hydronic Engineering
- Pegler Yorkshire Group Limited
- Giacomini S.p.A.
- Drayton (part of Schneider Electric)
- Herz Armaturen GmbH
Competitive Analysis:
The thermostatic radiator valves (TRVs) market is characterized by a moderately competitive landscape, with key players prioritizing innovation, energy efficiency, and regulatory compliance to maintain a competitive advantage. Leading companies such as Danfoss, Honeywell International, and Siemens AG dominate the market, leveraging their extensive product portfolios and global reach to cater to diverse consumer needs. Meanwhile, emerging players in Asia-Pacific are introducing cost-effective and smart TRV systems, aiming to capture the rising demand in rapidly urbanizing regions where governments are investing in energy-efficient infrastructure. Technological advancements, particularly IoT-enabled and wireless TRVs, have intensified competition, with over 30% of new TRV products launched in the past two years integrating smart home capabilities for enhanced automation and user control. The increasing emphasis on sustainability and green building practices further drives product differentiation, compelling manufacturers to develop advanced TRVs that optimize energy consumption while meeting evolving regulatory standards.
Recent Developments:
- In January 2024, Danfoss launched its innovative Dynamic Valve™, a 2-in-1 solution that combines a thermostatic radiator valve with a built-in differential pressure controller. This design allows for accurate temperature control and automatic hydronic balancing, significantly improving heating efficiency.
- In March 2023, Drayton, part of Schneider Electric, launched its Auto-balancing TRV, which simplifies the balancing process in heating systems. This innovative valve automatically adjusts flow rates according to pressure changes, resulting in an average energy use reduction of 8.8%. The Auto-balancing TRV has been particularly well-received in the UK market for its ease of installation and ability to eliminate cold spots in homes.
Market Concentration & Characteristics:
The thermostatic radiator valves (TRVs) market exhibits a moderately concentrated structure, with a mix of global leaders and regional players driving competition. Established companies such as Danfoss, Honeywell International, and Siemens AG hold significant market shares, benefiting from extensive distribution networks and comprehensive product portfolios tailored to energy efficiency standards. The market's concentration is primarily influenced by stringent energy regulations in regions like Europe and North America, which encourage the adoption of advanced TRVs. Meanwhile, regional players in Asia-Pacific and Latin America focus on providing cost-effective solutions to cater to price-sensitive markets. Product innovation, particularly in IoT-enabled and wireless TRVs, plays a pivotal role in shaping market dynamics, with smart TRVs accounting for over 25% of new installations globally. The market is also characterized by high growth potential in emerging economies, driven by urbanization and green infrastructure initiatives, which create opportunities for both established and new entrants.
Report Coverage:
The research report offers an in-depth analysis based on product type, application, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing global emphasis on energy efficiency and sustainability will drive widespread adoption of thermostatic radiator valves (TRVs) across residential and commercial buildings.
- Integration of IoT and smart home technologies will lead to the development of advanced TRVs with remote control and automated temperature adjustment capabilities.
- Growing government regulations and green building certifications will promote retrofitting of older heating systems with energy-efficient TRVs, particularly in Europe and North America.
- Asia-Pacific will emerge as a key growth region due to rapid urbanization, infrastructure development, and increasing awareness of energy conservation practices.
- Rising demand for smart TRVs will create opportunities for manufacturers to introduce innovative features such as wireless connectivity and compatibility with AI-driven home ecosystems.
- Expansion of district heating systems in urban areas will boost the installation of TRVs to ensure precise temperature control and energy savings.
- Increased focus on reducing carbon emissions in the heating sector will encourage the transition to eco-friendly TRVs with recyclable materials and sustainable designs.
- Enhanced demand for personalized comfort solutions in modern housing will accelerate the adoption of TRVs with advanced sensor technologies.
- The shift toward modular heating solutions will open avenues for manufacturers to design compact and efficient TRVs suitable for varied heating systems.
- Collaboration between TRV manufacturers and smart home technology providers will foster innovation and improve market competitiveness, benefiting consumers with cutting-edge solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Energy Efficiency Awareness
Growing emphasis on reducing energy consumption and heating costs is driving adoption of thermostatic radiator valves, as they enable precise temperature control and can significantly lower energy bills in both residential and commercial settings.
Smart Home Technology Integration
The increasing penetration of smart home systems and IoT devices is fueling demand for electronic TRVs that offer remote control, automation, and integration with platforms like Amazon Alexa and Google Assistant, enhancing user convenience and energy management.
Regulatory Support and Green Building Initiatives
Stringent government regulations and building codes, especially in Europe and North America, mandate energy-efficient heating solutions, making TRVs a required or highly incentivized component in new constructions and retrofits.
Technological Advancements in TRVs
Innovations such as electronic TRVs with wireless connectivity, AI-driven automation, and improved precision are making these products more attractive by offering greater energy savings, easier installation, and enhanced comfort.
Urbanization and Infrastructure Development in Emerging Markets
Rapid urbanization and the expansion of energy-efficient infrastructure in Asia-Pacific, Latin America, and the Middle East & Africa are creating new opportunities for TRV adoption, particularly as governments and developers prioritize sustainability in new projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Thermostatic Radiator Valves (TRVs) Market?
What factors are driving the growth of the TRVs Market?
What are some challenges faced by the TRVs Market?
Who are the major players in the TRVs Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Product Type
- 1.3.1 Electric Operated
- 1.3.2 Manually Operated
- 1.4 By Commercial Sub-Application
- 1.4.1 Hotels
- 1.4.2 Schools
- 1.4.3 Buildings
- 1.4.4 Offices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 286.2 million → 2032: USD 416.44 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Thermostatic Radiator Valves Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Thermostatic Radiator Valves Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Thermostatic Radiator Valves Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Thermostatic Radiator Valves Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Thermostatic Radiator Valves Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Thermostatic Radiator Valves Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Thermostatic Radiator Valves Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Thermostatic Radiator Valves Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 286.2 million → 2032: USD 416.44 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Thermostatic Radiator Valves Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Electric Operated
- 12.4.7.2 Manually Operated
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Commercial Sub-Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hotels
- 12.5.7.2 Schools
- 12.5.7.3 Buildings
- 12.5.7.4 Offices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Thermostatic Radiator Valves End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Thermostatic Radiator Valves Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Thermostatic Radiator Valves Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Thermostatic Radiator Valves Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Danfoss
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Inc.
- 18.4 Siemens AG
- 18.5 Oventrop GmbH & Co. KG
- 18.6 Caleffi S.p.A.
- 18.7 IMI Hydronic Engineering
- 18.8 Pegler Yorkshire Group Limited
- 18.9 Giacomini S.p.A.
- 18.10 Drayton (Schneider Electric)
- 18.11 Herz Armaturen GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

