
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Artificial Intelligence Sensors Market Size 2024 | USD 4,575.00 Million |
| Artificial Intelligence Sensors Market, CAGR | 43% |
| Artificial Intelligence Sensors Market Size 2032 | USD 79998 Million |
Market Overview:
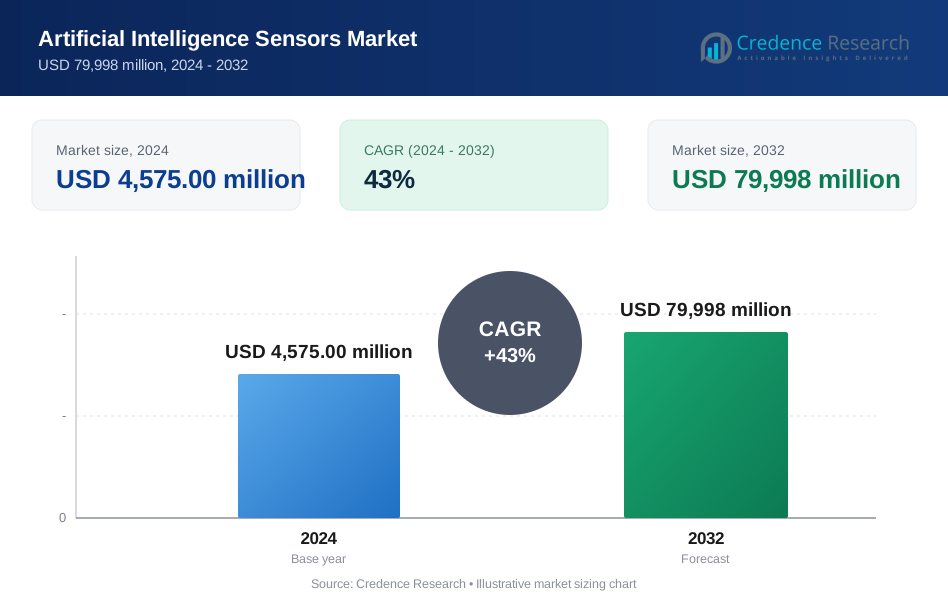
The Artificial Intelligence Sensors Market is projected to grow from USD 4,575.00 million in 2024 to an estimated USD 79998 million by 2032, with a compound annual growth rate (CAGR) of 43% from 2024 to 2032.
Multiple drivers are contributing to the robust growth of the AI Sensors Market. One of the most significant is the widespread adoption of automation and Industry 4.0 practices, where AI sensors are vital for real-time monitoring, predictive maintenance, and autonomous operation. These sensors allow for advanced data collection and interpretation at the edge, reducing latency and enhancing decision-making in critical applications. The rapid proliferation of the Internet of Things (IoT) has also created a strong foundation for AI sensors, particularly in smart homes, industrial automation, and connected infrastructure. In the automotive sector, AI-enabled sensors play a central role in Advanced Driver Assistance Systems (ADAS) and autonomous vehicles by facilitating functions such as lane detection, obstacle recognition, and collision avoidance. Technological advancements in sensor miniaturization, edge AI computing, and wireless communication, along with growing government initiatives and R&D investments, are further accelerating the adoption and evolution of AI sensors.
Regionally, North America holds the largest share of the global AI Sensors Market. This dominance is attributed to the presence of major technology companies, strong infrastructure, early adoption of AI-driven solutions, and supportive regulatory frameworks. The United States, in particular, is a leader in both AI sensor development and deployment across sectors such as defense, automotive, and healthcare. Asia-Pacific is the fastest-growing region, with countries like China, Japan, South Korea, and India making significant investments in AI and smart technology ecosystems. China leads in AI policy implementation and industrial automation, while Japan and South Korea are advancing in automotive and electronics applications. India is emerging rapidly, driven by government initiatives and an expanding tech startup ecosystem. Europe also maintains a strong presence, with notable activity in industrial automation, environmental monitoring, and smart infrastructure. Meanwhile, Latin America and the Middle East & Africa, though smaller in current market share, are expected to witness steady growth due to increasing infrastructure development, urbanization, and gradual adoption of smart technologies. Collectively, these regional dynamics underscore a global trend toward the accelerated deployment of AI sensors across diverse applications and geographies.
Market Insights:
- The Artificial Intelligence Sensors Market is projected to grow from USD 4,575.00 million in 2024 to an estimated USD 79,998 million by 2032, registering a strong CAGR of 43% during the forecast period.
- Adoption of Industry 4.0 and smart manufacturing solutions is accelerating the demand for AI sensors that support real-time data monitoring, predictive maintenance, and automated operations across industrial environments.
- Increasing integration of AI-enabled sensors in autonomous vehicles, particularly in ADAS systems for lane detection, collision avoidance, and navigation, is expanding their application in automotive safety and mobility innovations.
- The proliferation of IoT-connected devices and the rise of edge computing are fueling the need for intelligent sensors capable of decentralized data processing, faster decision-making, and enhanced energy efficiency in real-time applications.
- AI sensor adoption is rising rapidly in healthcare for continuous monitoring and diagnostics, in agriculture for crop and soil analysis, and in security for intelligent surveillance, creating new vertical growth avenues.
- High deployment costs, infrastructure requirements, and interoperability issues are key challenges restricting adoption among small and medium enterprises and limiting broader scalability.
- North America dominates the global market due to early technology adoption and strong infrastructure, while Asia-Pacific leads in growth rate with aggressive investments in smart technologies across China, Japan, South Korea, and India.
Market Drivers:
Integration of Industry 4.0 and Smart Manufacturing Boosts Sensor Deployment:
The rise of Industry 4.0 initiatives across manufacturing sectors is a major growth catalyst for the Artificial Intelligence Sensors Market. Manufacturers seek to optimize productivity, reduce downtime, and increase automation across production environments. AI sensors offer real-time insights, predictive maintenance capabilities, and intelligent monitoring, enabling smarter and more responsive operations. By integrating AI with sensor technologies, companies are creating adaptive systems that react instantly to operational anomalies. It allows equipment to self-monitor and communicate performance metrics, improving efficiency across the supply chain. The trend toward smart factories and digital twins reinforces demand for high-precision and self-learning sensors. This shift is particularly evident in automotive, electronics, and aerospace manufacturing hubs.
- For instance, a 2024 German government survey found that 68 out of every 100 large manufacturers have adopted AI-powered sensor systems to support predictive maintenance and digital twin initiatives.
Advancements in Autonomous Vehicles and Mobility Solutions Expand Application Scope:
The automotive sector is a key contributor to the expansion of the Artificial Intelligence Sensors Market. Autonomous driving technologies, such as Advanced Driver Assistance Systems (ADAS), require continuous input from AI-integrated sensors to ensure road safety, navigation accuracy, and object detection. It supports functions like adaptive cruise control, lane-keeping assistance, pedestrian recognition, and blind-spot monitoring. OEMs and Tier-1 suppliers are investing heavily in sensor fusion platforms to deliver enhanced situational awareness and faster decision-making. Increasing regulatory mandates around vehicle safety and emissions are also accelerating the inclusion of smart sensor technologies. The convergence of AI, connectivity, and electrification in next-generation vehicles creates a high-demand environment for intelligent sensing systems.
- For example, Sony’s collaboration with aiMotive in 2024 enabled its IMX728 sensor to support object detection accuracy above 95 in ADAS simulations, while Bosch’s acquisition of Five in 2025 accelerated the deployment of sensor fusion platforms in European autonomous vehicle projects.
Proliferation of IoT Devices and Edge Computing Spurs Intelligent Sensing Demand:
The growing adoption of IoT devices across homes, industrial systems, and infrastructure is a powerful driver for the Artificial Intelligence Sensors Market. AI sensors enable edge computing, where data is processed locally rather than in the cloud, reducing latency and enhancing data security. It enhances performance in real-time applications such as smart surveillance, smart grids, and automated building systems. Consumer electronics, including smartphones, wearables, and smart appliances, also rely on AI-enhanced sensors for gesture recognition, environmental monitoring, and user behavior analysis. Edge AI capabilities support lower energy consumption and decentralized intelligence, making devices more autonomous. These factors push manufacturers to embed AI-driven sensing technologies into a broadening array of smart products.
Growing Use in Healthcare, Agriculture, and Security Strengthens Market Adoption:
Emerging applications in healthcare, agriculture, and security sectors are broadening the functional relevance of AI sensors. In healthcare, AI-enabled sensors assist in remote diagnostics, continuous vital sign monitoring, and early disease detection. It contributes to better patient outcomes and supports telemedicine and elderly care models. Precision agriculture benefits from AI sensors through real-time analysis of soil conditions, crop health, and weather patterns. In security, intelligent sensors improve facial recognition, threat detection, and behavioral analysis across surveillance networks. Governments and enterprises are turning to these applications to meet growing demands for efficiency, safety, and sustainability. This wide-scale utility ensures long-term growth opportunities across non-industrial domains.
Market Trends:
Edge AI Integration Is Shaping Next-Generation Sensor Architectures:
One of the most prominent trends in the Artificial Intelligence Sensors Market is the integration of AI capabilities directly into edge devices. Edge AI enables real-time processing without reliance on cloud infrastructure, which reduces latency and enhances responsiveness in mission-critical applications. It improves energy efficiency, data privacy, and bandwidth optimization, making it ideal for sectors such as healthcare, automotive, and industrial automation. Manufacturers are embedding lightweight neural networks and advanced microprocessors into sensors to allow local decision-making. This trend supports the development of autonomous systems that operate independently of centralized computing resources. It also drives innovation in compact, low-power hardware suited for mobile and embedded use.
- For instance, a 2025 Japanese government technology survey found that 54 out of every 100 new healthcare devices now use edge AI sensors for real-time patient monitoring, improving response times and data privacy.
Multi-Sensor Fusion Platforms Enhance Precision and Context Awareness:
Multi-sensor fusion is gaining strong traction in the Artificial Intelligence Sensors Market. Combining inputs from various sensor types-such as LiDAR, radar, infrared, and accelerometers-creates a more accurate and comprehensive picture of the surrounding environment. It is critical in applications such as autonomous vehicles, robotics, and surveillance systems, where contextual awareness and redundancy are essential for safety and functionality. Advances in sensor fusion algorithms powered by AI enable systems to interpret complex environments more accurately. This approach minimizes false positives and improves detection reliability under dynamic and uncertain conditions. It is fostering the design of robust and adaptable sensor platforms across industries.
- For instance, Teledyne Technologies’ sensors used in NASA’s 2025 PUNCH mission combined optical, infrared, and accelerometer data to achieve a 99.8 accuracy rate in solar event detection.
Focus on Miniaturization and Low-Power Consumption Drives Innovation:
Sensor manufacturers are prioritizing miniaturization and energy efficiency to meet the needs of compact and portable devices. The Artificial Intelligence Sensors Market is responding to demand from consumer electronics, medical wearables, and smart home systems, where size and power constraints are critical. Companies are developing ultra-small, AI-enabled sensors that deliver high performance while consuming minimal power. It extends the battery life of host devices and supports continuous operation in resource-constrained environments. Innovations in semiconductor fabrication and AI model compression techniques are key enablers of this trend. These efforts are helping sensors integrate more easily into a wider range of applications.
Customized AI Sensor Solutions Cater to Industry-Specific Requirements:
Another emerging trend is the development of AI sensors tailored for specific industrial needs. The Artificial Intelligence Sensors Market is moving toward vertical specialization, with customized solutions designed for healthcare, agriculture, defense, and logistics. These sensors incorporate domain-specific algorithms and hardware configurations that meet targeted operational demands. It increases deployment efficiency and accelerates value generation for end users. For example, AI sensors for agriculture focus on soil analysis and irrigation control, while medical sensors prioritize real-time monitoring of physiological data. This trend highlights the market’s shift toward delivering specialized, purpose-built sensor ecosystems rather than generic, one-size-fits-all products.
Market Challenges Analysis:
High Cost of Integration and Infrastructure Limits Adoption Across Small Enterprises:
One of the primary challenges facing the Artificial Intelligence Sensors Market is the high cost associated with deploying advanced sensor systems. Integrating AI capabilities into sensors requires significant investment in specialized hardware, software development, and supporting infrastructure. It increases the total cost of ownership, making it difficult for small and medium enterprises to justify adoption, especially in cost-sensitive industries. The need for high-performance computing, edge AI accelerators, and compatible connectivity frameworks adds further complexity. Many organizations also face financial constraints in upgrading legacy systems to accommodate intelligent sensing solutions. Without scalable and cost-effective alternatives, adoption across broader market segments remains limited.
Data Privacy, Security, and Technical Limitations Impact Widespread Implementation:
Data privacy and security concerns present another major obstacle for the Artificial Intelligence Sensors Market. AI-enabled sensors generate and process large volumes of sensitive data, particularly in healthcare, smart cities, and surveillance applications. It increases the risk of unauthorized access, data breaches, and misuse, prompting stricter compliance requirements. Ensuring end-to-end data encryption, secure edge processing, and regulatory alignment remains a significant technical and operational challenge. In parallel, limited standardization and interoperability across AI platforms and sensor ecosystems hinder smooth integration and scalability. Some sensors also face performance limitations in extreme environmental conditions, affecting their reliability in critical deployments. These barriers can slow the pace of innovation and adoption across key industries.
Market Opportunities:
Expansion of Smart Infrastructure and Urban Mobility Unlocks New Demand:
The increasing development of smart cities and connected infrastructure creates substantial growth opportunities for the Artificial Intelligence Sensors Market. Governments and urban planners are investing in intelligent traffic systems, energy-efficient buildings, and public safety technologies that rely on real-time data inputs. AI sensors enable automated lighting, congestion monitoring, pollution control, and emergency response coordination. It supports the shift toward sustainable, data-driven urban management. The growing focus on mobility solutions-such as electric vehicles, shared transportation, and autonomous transit-further expands the use of intelligent sensing technologies. These applications require scalable and reliable sensors that process and act on data in real time.
Emerging Use Cases in Healthcare and Environmental Monitoring Drive Market Expansion:
Healthcare and environmental sectors offer high-impact, untapped potential for AI sensor deployment. The Artificial Intelligence Sensors Market can address critical needs in remote diagnostics, patient monitoring, and chronic disease management by enabling continuous and precise data capture. It enhances care delivery and supports early intervention in both clinical and home settings. In environmental monitoring, AI sensors play a role in tracking air and water quality, detecting natural hazards, and improving resource management. Demand from public health agencies, research institutions, and sustainability initiatives is expected to rise. These sectors present long-term opportunities for growth and innovation across global markets.
Market Segmentation Analysis:
By Sensor Type
The Artificial Intelligence Sensors Market is led by optical sensors, which hold the largest market share due to their critical role in autonomous vehicles, robotics, and consumer electronics. Motion sensors follow closely, supported by widespread use in fitness devices, gaming, and industrial automation. Pressure and temperature sensors serve key functions in automotive, healthcare, and environmental monitoring. Ultrasonic and position sensors are gaining traction in safety systems and robotic applications, while navigation and biometric sensors are essential for drones, autonomous systems, and security-enabled consumer devices.
- For instance, Bosch reporting that 34 out of every 100 of its AI sensor shipments in 2024 were optical, followed by motion sensors at 28.
By Technology
Machine learning dominates the market, accounting for over 29–31% of the technology segment. It supports predictive analytics and real-time data interpretation across industries. Computer vision is central to visual data processing in optical sensors and robotics. Natural Language Processing (NLP) enables voice-activated controls in smart assistants. Context-aware computing represents the fastest-growing segment, driven by demand for intelligent responsiveness in smart home and industrial environments.
- For instance, Context-aware computing is the fastest-growing segment, as evidenced by Sensirion 2025 partnership with Sintropy.ai to deliver adaptive environmental monitoring solutions for smart buildings and industrial environments.
By Application
Consumer electronics lead the market, with AI sensors embedded in smartphones, wearables, and smart devices. The automotive segment is expanding rapidly due to ADAS and vehicle automation technologies. Industrial automation leverages AI sensors for predictive maintenance and quality control. Smart home automation, healthcare, and robotics present strong demand for intelligent sensing solutions. Aerospace, defense, agriculture, and cognitive science offer emerging opportunities driven by precision and innovation needs.
Segmentation:
By Sensor Type:
- Optical Sensors
- Motion Sensors
- Pressure Sensors
- Temperature Sensors
- Ultrasonic Sensors
- Position Sensors
- Navigation Sensors
- Biometric Sensors
By Technology:
- Machine Learning
- Natural Language Processing (NLP)
- Computer Vision
- Context-Aware Computing
By Application:
- Consumer Electronics
- Automotive
- Industrial Automation/Manufacturing
- Smart Home Automation
- Healthcare
- Robotics
- Aerospace & Defense
- Agriculture
- Cognitive Science & Natural Interface
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leads with Technological Maturity and Early Adoption
North America holds the largest share in the Artificial Intelligence Sensors Market, accounting for approximately 37% to 43% of global revenue. The United States drives regional dominance through strong R&D investments, presence of leading tech companies, and rapid deployment of AI-based solutions across automotive, healthcare, defense, and consumer electronics. It benefits from well-established digital infrastructure and favorable regulatory policies that support AI integration across sectors. Adoption of autonomous vehicles and smart home technologies further strengthens demand for AI-enabled sensors. Canada contributes to growth through innovation in industrial automation and medical applications. The region’s maturity in AI deployment ensures continued leadership in global market dynamics.
Asia-Pacific Emerges as the Fastest-Growing Market
Asia-Pacific represents the fastest-growing region in the Artificial Intelligence Sensors Market, projected to expand at a CAGR exceeding 45% during the forecast period. It holds approximately 26% to 30% of the global share, driven by rapid industrialization, strong IoT adoption, and significant government backing for smart technologies. China leads the region with aggressive AI policy implementation and widespread adoption in manufacturing, transportation, and surveillance. Japan and South Korea support growth with advancements in automotive sensors, robotics, and consumer electronics. India shows growing momentum through digital transformation initiatives and a thriving technology startup ecosystem. The region is a hub for manufacturing and electronics, fueling large-scale demand for smart sensing technologies.
Europe, Latin America, and MEA Show Steady and Emerging Growth
Europe maintains a solid share of around 20% to 23%, supported by demand for AI sensors in automotive safety, industrial automation, and environmental monitoring. Germany, France, and the UK lead regional adoption, especially in electric mobility and precision manufacturing. The Artificial Intelligence Sensors Market in Latin America and the Middle East & Africa (MEA) remains smaller in current share-roughly 4% to 6% combined-but shows promising growth. Countries such as Brazil, the UAE, and South Africa are exploring AI-based applications in agriculture, infrastructure, and public safety. Limited infrastructure and funding constraints temper growth in these regions, but targeted investments and urbanization efforts are expected to improve adoption over time. These regions represent emerging frontiers for future expansion.
Key Player Analysis:
- Robert Bosch GmbH
- Teledyne Technologies Incorporated
- Sensirion AG
- Sensata Technologies, Inc.
- Sony Corporation
- STMicroelectronics N.V.
- Goertek Inc.
- Hokuriku Electric Industry Co., Ltd.
- MEMSIC Semiconductor Co., Ltd.
- TE Connectivity Ltd.
- Baidu, Inc.
- Excelitas Technologies Corp.
- Yokogawa Electric Corporation
- Silicon Sensing Systems Limited
Competitive Analysis:
The Artificial Intelligence Sensors Market features a competitive landscape marked by strong innovation, strategic collaborations, and a focus on product diversification. Leading players such as Robert Bosch GmbH, Sony Corporation, and STMicroelectronics N.V. invest heavily in R&D to enhance sensor performance, energy efficiency, and AI integration. Companies like Teledyne Technologies and Sensirion AG expand their portfolios through advanced sensing platforms tailored to automotive, healthcare, and industrial applications. Baidu, Inc. and Goertek Inc. leverage AI expertise to enter high-growth segments such as autonomous systems and consumer electronics. The market also sees rising activity from MEMSIC Semiconductor and Silicon Sensing Systems, which offer niche and application-specific solutions. It remains highly dynamic, with players focusing on miniaturization, edge AI processing, and scalable production. Partnerships and acquisitions continue to shape the competitive strategy as firms aim to strengthen their presence across regional and vertical markets.
Recent Developments:
- In April 2025, Robert Bosch GmbH significantly expanded its presence in quantum sensing by establishing a joint venture with Element Six, forming Bosch Quantum Sensing. This partnership leverages synthetic diamond technology to develop advanced quantum sensors targeting applications in medicine and mobility, aiming to commercialize these innovations for industrial-scale use.
- In May 2025, Teledyne Technologies Incorporated launched three new industrial CMOS image sensors designed for space applications, with resolutions ranging from 1.3MP to 67MP, targeting the New Space market. These sensors are engineered for high-demand uses such as Earth observation and space situational awareness.
- In June 2025, Sensirion AG announced a partnership with Sintropy.ai and Repcom to drive innovation in AI-driven sensor technology, integrating Sensirion’s high-precision sensors into advanced automation and environmental monitoring solutions.
- In February 2025, Sony Corporation showcased its new AI Analytics technology, AITRIOS, at ISE 2025, demonstrating advanced AI-powered features for professional displays and PTZ cameras.
Market Concentration & Characteristics:
The Artificial Intelligence Sensors Market exhibits moderate to high market concentration, with a core group of established players dominating global supply and innovation. It features a mix of multinational corporations and specialized technology firms, each focusing on distinct application areas such as automotive, healthcare, consumer electronics, and industrial automation. The market is characterized by rapid technological advancements, short product life cycles, and strong emphasis on miniaturization, power efficiency, and edge processing capabilities. Companies actively pursue patents, strategic partnerships, and vertical integration to maintain competitive advantages. It requires high capital investment and technical expertise, creating moderate entry barriers for new participants. Standardization challenges and evolving regulatory landscapes further define market dynamics.
Report Coverage:
The research report offers an in-depth analysis based on By Sensor Type, By Technology, By Application and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Deployment of AI sensors in autonomous vehicles will accelerate to support safety, navigation, and driver-assist systems.
- Edge AI will become critical, enabling faster local data processing and reducing reliance on cloud infrastructure.
- Healthcare applications will expand, with sensors supporting remote diagnostics, real-time monitoring, and wearable technologies.
- Industrial sectors will adopt AI sensors to enhance predictive maintenance, improve quality control, and reduce downtime.
- Sensor miniaturization will drive integration into compact consumer electronics and IoT-enabled devices.
- Smart home systems will increasingly use AI sensors for automation, energy efficiency, and security functions.
- Growth in emerging economies will be fueled by rising digital infrastructure and government-led smart technology initiatives.
- Advanced sensor fusion will improve performance in robotics, drones, and mobility systems operating in complex environments.
- Companies will focus on developing application-specific sensors tailored for agriculture, defense, and environmental monitoring.
- The competitive landscape will intensify with innovation, strategic collaborations, and expansion into new verticals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Artificial Intelligence Sensors Market?
What factors are driving the growth of the Artificial Intelligence Sensors Market?
What are the key segments within the Artificial Intelligence Sensors Market?
What are some challenges faced by the Artificial Intelligence Sensors Market?
Who are the major players in the Artificial Intelligence Sensors Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Artificial Intelligence Sensors Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Artificial Intelligence Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,575.00 million → 2032: USD 79,998 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Artificial Intelligence Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Artificial Intelligence Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Artificial Intelligence Sensors Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Artificial Intelligence Sensors Market Drivers
- 3.3 Artificial Intelligence Sensors Market Restraints & Challenges
- 3.4 Artificial Intelligence Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Artificial Intelligence Sensors Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Artificial Intelligence Sensors Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Artificial Intelligence Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Artificial Intelligence Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Artificial Intelligence Sensors Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Artificial Intelligence Sensors. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Artificial Intelligence Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Artificial Intelligence Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Artificial Intelligence Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Artificial Intelligence Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Artificial Intelligence Sensors
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Artificial Intelligence Sensors Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Artificial Intelligence Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Artificial Intelligence Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Artificial Intelligence Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Artificial Intelligence Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Artificial Intelligence Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Artificial Intelligence Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Artificial Intelligence Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
