
Market Overview
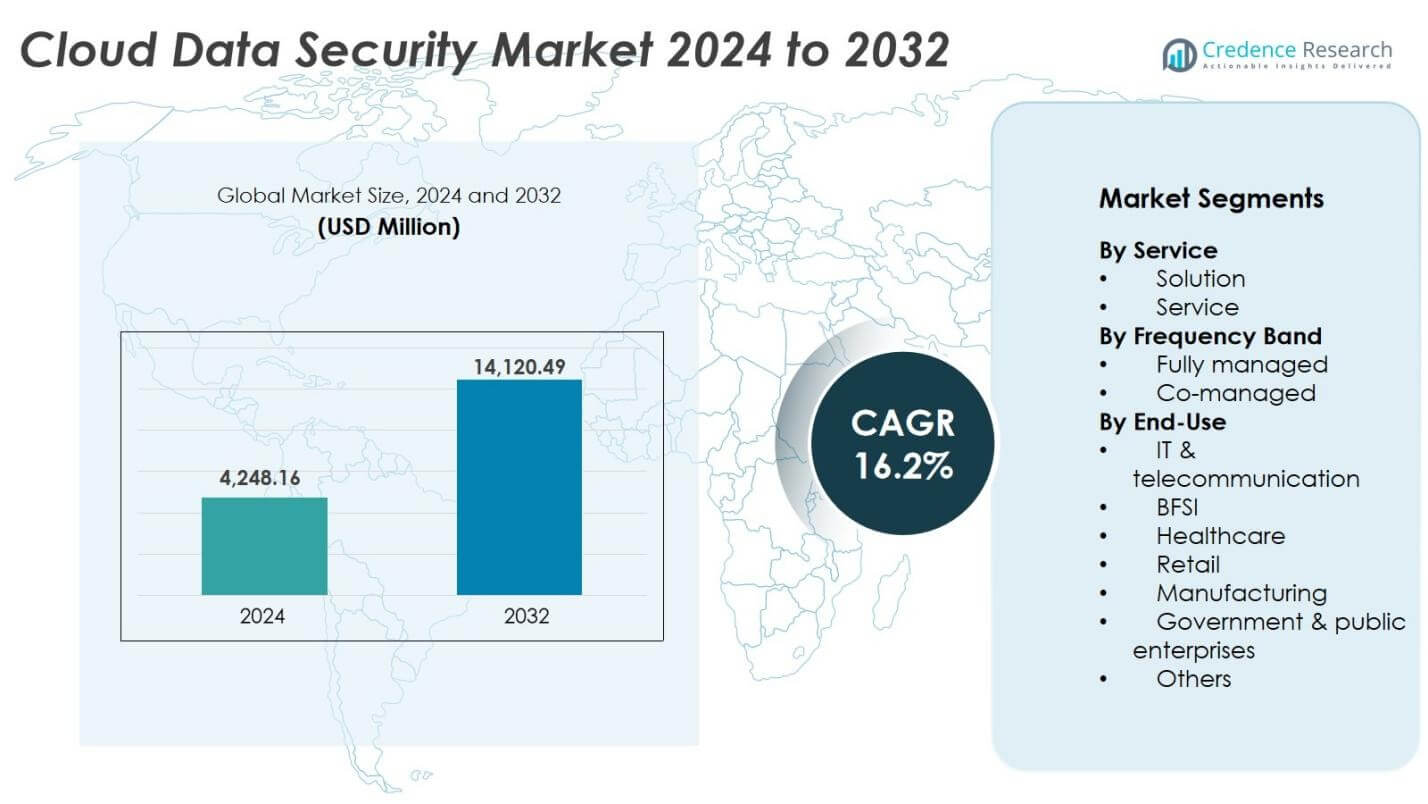
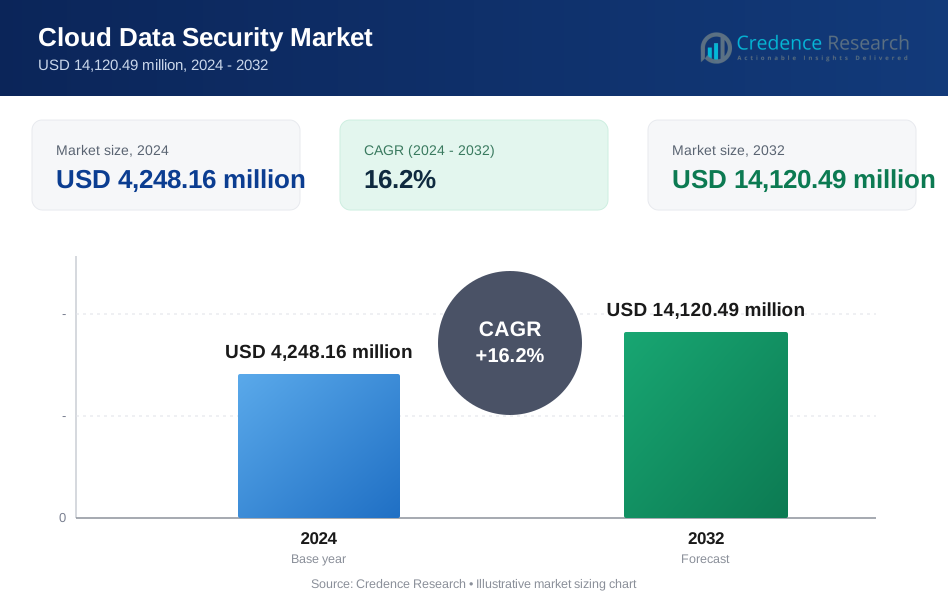
Cloud data security market size was valued USD 4,248.16 million in 2024 and is anticipated to reach USD 14,120.49 million by 2032, at a CAGR of 16.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cloud Data Security Market Size 2024 | USD 4,248.16 million |
| Cloud Data Security Market, CAGR | 16.2% |
| Cloud Data Security Market Size 2032 | USD 14,120.49 million |
Top players in the cloud data security market include Microsoft Corporation, Amazon Web Services, Cisco Systems, IBM Corporation, Check Point Software Technologies, Fortinet, Palo Alto Networks, Imperva, Commvault, and Orca Security. These vendors offer encryption, identity management, workload protection, and automated compliance monitoring for multi-cloud environments. North America remains the leading region with a 38% market share in 2024, driven by advanced cloud adoption, high cybersecurity spending, and strict regulatory compliance in BFSI, healthcare, and government sectors. Europe and Asia-Pacific follow, supported by growing digital transformation and increased investment in cloud governance and threat prevention.
Market Insights
- The cloud data security market was valued at USD 4,248.16 million in 2024 and is projected to reach USD 14,120.49 million by 2032, registering a CAGR of 16.2%.
- Demand continues to rise as enterprises migrate to public and hybrid cloud platforms and require encryption, identity access management, and automated compliance to protect sensitive workloads.
- AI-driven threat detection, zero-trust architecture, and cloud security posture management are key trends, with vendors focusing on real-time monitoring, tokenization, agentless scanning, and multi-cloud visibility.
- The market remains competitive, with Microsoft, AWS, Cisco, IBM, Palo Alto Networks, and Fortinet offering integrated security suites, while startups such as Orca Security and Polar Security gain adoption with specialized agentless solutions. High deployment costs and a shortage of cybersecurity talent act as restraints for small enterprises.
- North America leads with a 38% share, followed by Europe at 26% and Asia-Pacific at 23%. On the service side, solutions dominate due to strong demand for encryption, DLP, and compliance automation.
Market Segmentation Analysis:
By Service
Solutions held the largest share of 63% in the Cloud Data Security Market in 2024, driven by rising demand for encryption, data loss prevention, and compliance automation. Organizations are adopting AI-enabled threat detection and zero-trust architectures to counter ransomware, insider breaches, and cloud misconfigurations. Enterprises prefer integrated platforms that support multi-cloud workloads with real-time monitoring. The adoption of data classification and tokenization tools has grown as regulatory frameworks tighten globally. Service offerings such as consulting, deployment, and managed security continue to expand, but solutions remain dominant due to heavy investments in automation and advanced analytics.
- For instance, Microsoft introduced AI-powered encryption and data loss prevention features within its Microsoft Purview platform, enhancing real-time threat detection and regulatory compliance for cloud data workloads.
By Frequency Band
Fully managed services accounted for a 58% share in 2024 as enterprises increasingly outsource complex cloud security operations to external providers. Managed offerings deliver 24/7 threat monitoring, incident response, and compliance management while easing internal resource burdens. The shortage of cybersecurity professionals and the rising sophistication of attacks further encourage outsourcing. Co-managed services gained a 27% share as large firms maintain partial control over policies while using expert assistance. Fully managed services dominate due to faster deployment, reduced overhead costs, and improved compliance across multi-cloud environments.
- For instance, IBM's co-managed security solutions enable enterprises to share responsibility by combining internal security teams with IBM’s advanced threat management and incident response capabilities, improving security posture while maintaining policy control.
By End-Use
The BFSI sector represented a 34% share in the Cloud Data Security Market in 2024, driven by strict data protection regulations, high transaction volumes, and secure digital banking operations. Financial institutions deploy advanced encryption, identity management, and continuous auditing to safeguard customer data. Healthcare held a 19% share, supported by electronic health record protection and HIPAA compliance efforts. IT & telecom followed with 17%, backed by massive data traffic and cloud-native infrastructure. Retail, manufacturing, and government sectors collectively contributed 30%, focusing on securing consumer information and critical operational systems.
Key Growth Drivers
Growing Cloud Adoption Across Enterprises
Rapid migration from on-premise data centers to cloud environments drives demand for advanced data protection tools. Enterprises adopt public and hybrid cloud platforms for scalability, cost efficiency, and global accessibility, increasing the need for encryption, access control, and automated threat detection. As multi-cloud usage rises, businesses require centralized security that covers diverse workloads, APIs, and storage layers. Regulatory mandates around customer data, especially in finance, healthcare, and e-commerce, push companies to invest in security posture management and data loss prevention. The growth of remote workforces further accelerates the shift, as organizations must safeguard data accessed from multiple endpoints and networks. This convergence of cloud-first IT strategies and expanding digital ecosystems continues to boost the adoption of cloud data security solutions.
- For instance, IBM's Cloud Data Shield, powered by Fortanix, automatically encrypts data at rest, in transit, and while in use, protecting sensitive financial and healthcare applications in the public cloud.
Rising Cyber Threats and Data Breaches
Complex cyberattacks, including ransomware, insider threats, and phishing, increase the need for cloud-based monitoring and real-time analytics. Organizations store confidential data-financial transactions, customer information, intellectual property-across distributed cloud environments, making security a top priority. Attackers now target misconfigured storage buckets, weak authentication, and unsecured APIs. As threats evolve, security teams implement zero-trust frameworks, identity access management, and AI-based anomaly detection to prevent data exposure. High-profile breaches in banking, healthcare, and government sectors push enterprises to upgrade cloud security architecture. The rising cost of breaches, reputational damage, and legal penalties intensifies the requirement for automated response tools and continuous compliance monitoring.
- For instance, Google’s BeyondCorp zero-trust architecture replaces traditional VPNs, providing secure user and device-based access to cloud resources without relying on network location.
Strict Regulatory Compliance Requirements
Global data protection laws, such as GDPR, HIPAA, PCI-DSS, and national cybersecurity frameworks, require strong cloud data governance. Enterprises must ensure secure data residency, encryption, auditing, and access control to meet compliance standards. Cloud data security tools provide automated reporting, real-time policy enforcement, and continuous risk scoring to avoid fines and policy violations. Sectors like BFSI, government, and telecom adopt advanced classification, tokenization, and key management solutions to protect high-value data. As digital payments, cloud banking, telemedicine, and e-governance expand, regulatory pressures become stricter. This compliance-driven approach remains a major growth factor for cloud data security adoption.
Key Trends & Opportunities
Integration of AI and Zero-Trust Architecture
AI and machine learning enhance cloud data security by enabling behavioral analytics, automated incident response, and predictive threat detection. Enterprises adopt zero-trust models to eliminate reliance on perimeter security and enforce strict identity verification. Cloud Access Security Brokers (CASB) and Secure Access Service Edge (SASE) platforms gain traction, offering unified control across networks and cloud applications. Automation reduces manual workload for security teams dealing with rising alert volumes. Vendors find opportunities in developing AI-driven security posture management, anomaly detection, and automated remediation workflows, especially for large enterprises operating multi-cloud systems.
- For instance, Palo Alto Networks enhanced its Prisma SASE platform with AI-based anomaly detection and adaptive access controls, reducing manual workloads for cybersecurity teams and ensuring stricter identity verification for users accessing cloud applications.
Growth of Data Security in Multi-Cloud and Hybrid Deployments
Large enterprises distribute workloads across AWS, Azure, Google Cloud, and private cloud infrastructures. This trend creates new opportunities for cloud security platforms that provide centralized visibility, unified encryption, and real-time compliance tracking. Organizations seek tools that secure data movement between clouds, prevent unauthorized access, and monitor API interactions. Demand rises for container security, serverless protection, and workload segmentation as DevOps adoption grows. Vendors offering cross-platform security analytics and cloud-native integrations benefit most from this expanding requirement.
- For instance, Cisco’s Multicloud Defense integrates with AWS APIs to provide end-to-end orchestration and autoscaling of security gateways within customer AWS accounts, enabling centralized inspection without forwarding traffic externally and meeting data sovereignty requirements.
Key Challenges
Shortage of Cybersecurity Professionals
Organizations face a global skill gap in cloud security expertise, limiting their ability to manage threats and implement advanced tools. Security teams struggle with configuration, compliance audits, and 24/7 monitoring due to limited resources. As cloud ecosystems grow more complex, handling identity management, encryption keys, and policy enforcement becomes difficult without trained personnel. This challenge drives demand for managed security services, but increases dependency on third-party providers and raises concerns around data control and privacy.
Rising Complexity in Multi-Cloud Environments
Using multiple cloud providers improves scalability and redundancy but complicates data security management. Each platform uses different security controls, access policies, and encryption standards, making unified monitoring difficult. Misconfigured storage, unsecured APIs, and inconsistent identity rules lead to vulnerabilities. Enterprises require centralized dashboards and automated risk assessment tools to handle diverse workloads. Vendors that fail to offer seamless multi-cloud compatibility face adoption barriers, slowing deployment for organizations with diverse digital ecosystems.
Regional Analysis
North America
North America held the largest share of the cloud data security market in 2024, accounting for 38% of global revenue. Strong adoption of public and hybrid cloud platforms, combined with high cybersecurity spending, drives market leadership. Enterprises across BFSI, healthcare, and government sectors invest heavily in encryption, identity management, and zero-trust models. The U.S. leads due to advanced cloud infrastructure and a high volume of data-intensive industries. Strict compliance frameworks, including HIPAA, PCI-DSS, and federal cybersecurity mandates, further accelerate demand for real-time monitoring and automated threat response.
Europe
Europe captured 26% of the market share in 2024, supported by GDPR enforcement and rising investments in cloud modernization. Countries such as Germany, the U.K., and France deploy advanced cloud security platforms to protect financial transactions, healthcare data, and e-commerce operations. Enterprises adopt data localization, encryption, and automated compliance reporting to meet strict regulatory mandates. The region sees rising adoption of identity access solutions and AI-based analytics across banking, manufacturing, and telecom sectors. Growing cloud migration in small and medium enterprises further strengthens market expansion.
Asia-Pacific
Asia-Pacific accounted for 23% of the market share in 2024 and is the fastest-growing region due to rapid digitalization and large-scale cloud adoption. China, India, Japan, and South Korea drive demand for secure cloud platforms across banking, telecom, and e-commerce. Government-led cloud initiatives and increasing cyberattacks push enterprises to adopt encryption, CASB solutions, and threat monitoring tools. The growth of fintech, 5G deployments, and data centers boosts market potential. Expanding adoption among SMEs and cloud-native startups also contributes to strong regional momentum.
Latin America
Latin America held a 7% market share in 2024, driven by growing cloud adoption in banking, retail, and telecom sectors. Countries like Brazil, Mexico, and Colombia invest in data protection tools to counter rising cyberattacks and regulatory initiatives. Cloud security solutions gain traction due to digital banking, online payments, and e-commerce expansion. However, budget constraints and skill shortages limit adoption for smaller enterprises. Vendors offering managed cloud security services see strong opportunities in the region.
Middle East & Africa
The Middle East & Africa region accounted for 6% of the global market share in 2024, supported by cloud transformation in government, oil & gas, and telecom sectors. Countries including the UAE, Saudi Arabia, and South Africa invest in data encryption, identity management, and compliance-driven security platforms. Digital banking growth and smart city projects increase demand for secure multi-cloud deployments. Although adoption is at an early stage, rising cybercrime and data protection laws create strong future prospects for cloud data security vendors.
Market Segmentations:
By Service
- Solution
- Service
By Frequency Band
- Fully managed
- Co-managed
By End-Use
- IT & telecommunication
- BFSI
- Healthcare
- Retail
- Manufacturing
- Government & public enterprises
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The cloud data security market features strong competition among global cybersecurity vendors, cloud service providers, and specialized data protection companies. Major players focus on encryption, identity access management, cloud workload protection, and security posture management to support multi-cloud and hybrid deployments. Leading companies such as Microsoft, Amazon Web Services, IBM, Cisco Systems, Palo Alto Networks, Check Point Software Technologies, and Fortinet strengthen their portfolios with AI-driven analytics, zero-trust frameworks, and automated compliance monitoring. Startups like Orca Security and Polar Security gain traction with agentless scanning and real-time risk prioritization for cloud workloads. Vendors use mergers, product integrations, and managed security services to expand market reach. Strategic partnerships with cloud providers, fintech organizations, and healthcare platforms enhance adoption across high-risk sectors. Pricing flexibility and bundled cloud-security offerings help target small and medium-sized businesses. As demand rises, competition intensifies around automation, unified dashboards, and multi-cloud visibility to reduce operational complexity and improve threat response times.
Key Player Analysis
- Palo Alto Networks, Inc
- Orca Security
- Fortinet Inc.
- Microsoft Corporation
- Commvault
- Imperva
- Cisco Systems, Inc.
- Polar Security
- Check Point Software Technologies Ltd.
- IBM Corporation
Recent Developments
- In February 2025, Check Point Software Technologies entered a strategic partnership with Wiz to offer end-to-end cloud security solutions combining CNAPP and network protection under a unified framework.
- In January 2025, Darktrace announced the acquisition of Cado Security, a cloud investigation and response specialist focused on multi-cloud environments to enhance its threat detection capabilities.
- In September 2023, IBMannounced the expansion of its IBM Cloud Security and Compliance Center, an updated solution designed to assist enterprises in reducing risk and safeguarding data across hybrid, multi-cloud environments and workloads.
- In February 2023, Orca Security launched new Data Security Posture Management (DSPM) capabilities as an extension of the Orca Cloud Security Platform. This latest offering builds on Orca's comprehensive cloud security approach and significantly enhances its existing features.
Report Coverage
The research report offers an in-depth analysis based on Service, Frequency Band, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Enterprises will increase investment in zero-trust frameworks to reduce unauthorized access.
- AI-driven threat analytics will become a core part of cloud security platforms.
- Demand for security posture management will grow as multi-cloud use expands.
- Managed security services will rise due to the shortage of skilled cybersecurity professionals.
- Data classification and tokenization tools will gain adoption in regulated sectors like BFSI and healthcare.
- Agentless cloud scanning will strengthen as organizations seek rapid deployment and low maintenance.
- Hybrid and multi-cloud security solutions will dominate as organizations avoid vendor lock-in.
- Compliance automation will expand to help enterprises meet diverse regional data protection laws.
- SMEs will adopt cost-effective cloud security bundles offered by large cloud providers.
- Integration between cloud security and DevOps pipelines will increase to protect containerized and serverless workloads.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cloud Data Security market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cloud Data Security market projected to grow between 2025 and 2032?
Which Cloud Data Security market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cloud Data Security market?
Who are the leading companies in the Cloud Data Security market?
Which region commanded the largest share of the Cloud Data Security market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,248.16 million → 2032: USD 14,120.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cloud Data Security Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cloud Data Security Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cloud Data Security Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cloud Data Security Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cloud Data Security Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cloud Data Security Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cloud Data Security Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cloud Data Security Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,248.16 million → 2032: USD 14,120.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cloud Data Security Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cloud Data Security Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cloud Data Security Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cloud Data Security Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

