
Licensed SOC rules turn Saudi cyber defense into a service
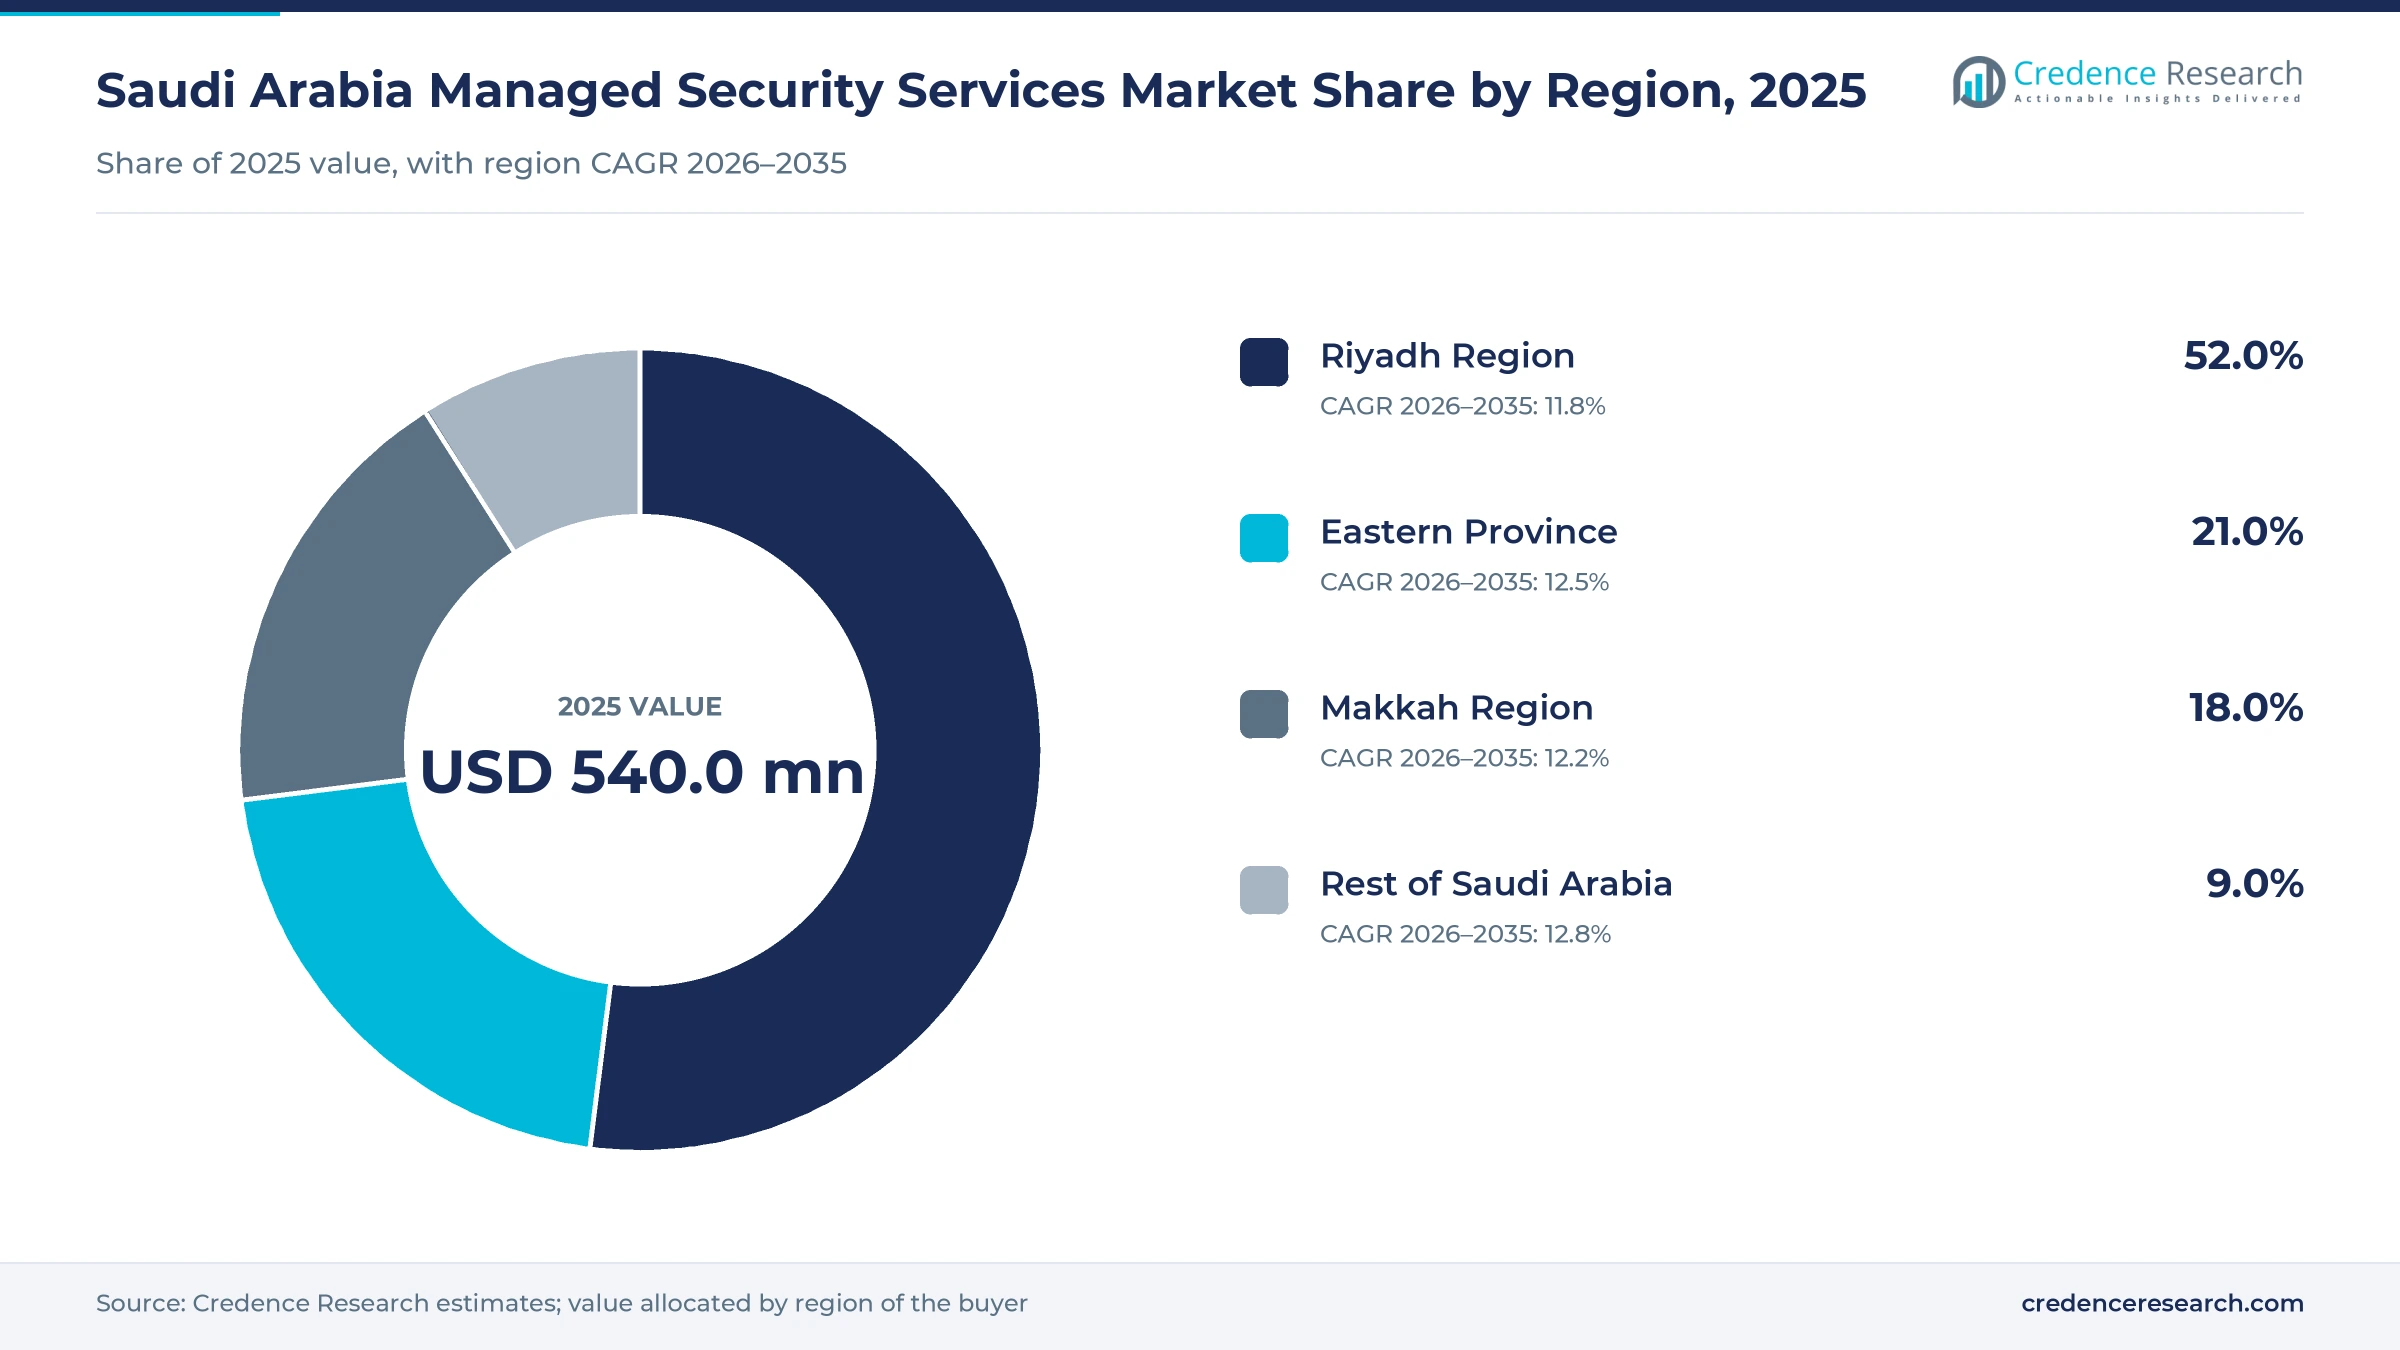
The Saudi Arabia managed security services market was valued at USD 540.0 million in 2025 and is projected to increase from USD 605.3 million in 2026 to USD 1.69 billion by 2035, registering a CAGR of 12.10% during 2026–2035. Demand comes from ministries, banks, energy groups and large private estates that now buy round-the-clock monitoring, detection and response from licensed providers rather than staffing full security operations centers themselves. Riyadh Region held the largest share, 52.0% in 2025, because government entities, bank head offices and regional headquarters concentrate their security purchasing in the capital. Rest of Saudi Arabia is the fastest-growing zone at 12.8% a year from a small base, as licensed providers extend remote monitoring to regional entities. The most important commercial change is national licensing, which requires government and critical infrastructure operators to run cybersecurity operations through licensed in-Kingdom providers. Zone shares are Credence Research estimates built from census and buyer location data.
Which outsourced cyber functions does the estimate count?
The estimate counts recurring fees that organizations pay to external providers for managed detection and response, security operations center monitoring, managed vulnerability management, managed identity and access, managed risk and compliance, and managed firewall and log services. Buyers usually sign one- to three-year contracts priced per endpoint, per asset, per identity or per monitored log volume, and government buyers often purchase through licensed national providers.
Cloud-delivered security as a service, such as SOC-as-a-service subscriptions, is counted when a provider runs the monitoring, while platform licenses bought alone are not. Security product licenses, one-off penetration tests, consulting projects and training are excluded, although many providers bundle them with monitoring contracts. The value chain runs from global platform vendors through licensed Saudi operators to in-house teams that keep governance, and one evidence gap remains, because no public body publishes managed services spending separately from total cybersecurity services.
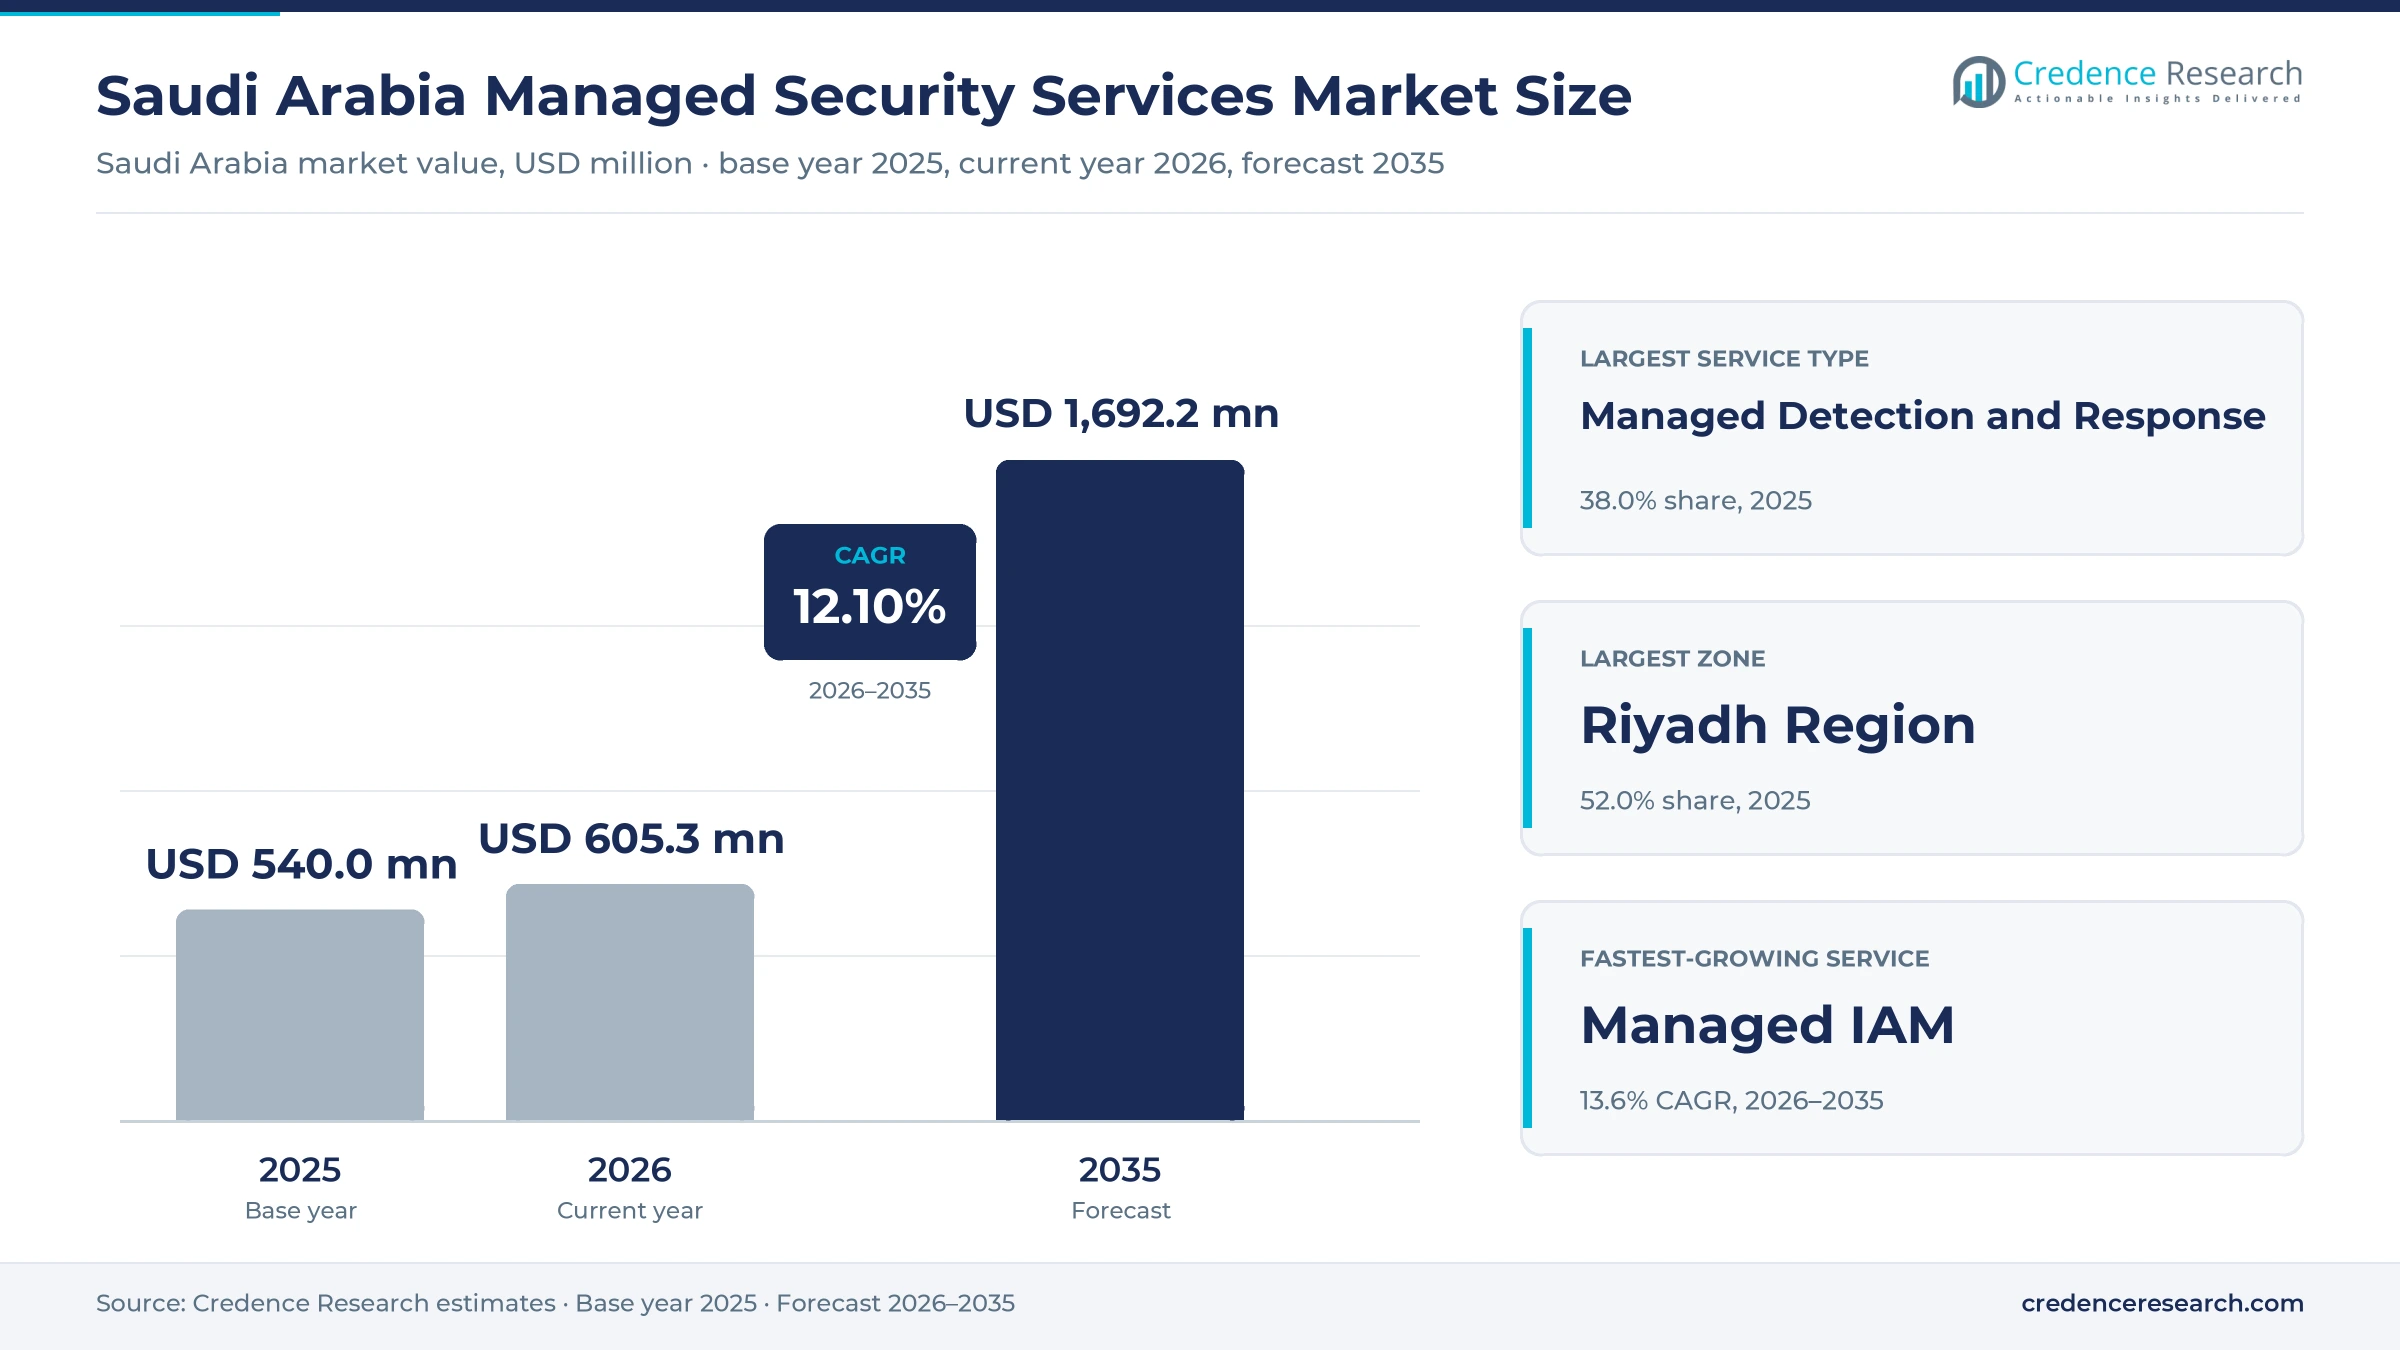
Saudi Arabia Managed Security Services Market Insights
- The market grows from USD 540.0 million in 2025 to USD 1.69 billion by 2035, a 12.10% CAGR, as licensed in-Kingdom monitoring replaces in-house and offshore security operations.
- Riyadh Region led with 52.0% of 2025 value because ministries, bank head offices and regional headquarters buy security operations from the capital.
- Managed detection and response held 38.0% in 2025, since round-the-clock monitoring is the core service that licensed operators sell to government and critical infrastructure.
- The National Cybersecurity Authority granted Tier-1 managed SOC licenses to six providers on March 18, 2025, which concentrates government and critical infrastructure work among state-linked operators.
- Global platform vendors now host detection workloads inside the kingdom, with CrowdStrike launching a sovereign Falcon deployment in Saudi Arabia on Nov. 4, 2026.
Detection and response leads as identity work grows fastest
Which managed service captures the largest budgets?
Based on service type, the market is categorized into managed detection and response, managed vulnerability management, managed IAM, managed risk and compliance, and others. Managed Detection and Response led with 38.0% of 2025 value because continuous monitoring is the anchor contract, as when sirar by stc agreed on Aug. 31, 2025, to protect KAFD systems through its Tier-1 licensed detection and response center around the clock. Managed IAM grows fastest at 13.6% a year as Personal Data Protection Law enforcement, which began on Sept. 14, 2024, under SDAIA, pushes firms to outsource identity and access management controls.
How do fully managed and co-managed contracts differ?
Based on type, the market is categorized into fully managed and co-managed. Fully Managed led with 61.0% of 2025 value because asset-heavy operators hand over entire environments, as the National Water Company did when sirar by stc agreed in November 2024 to deliver managed and integrated protection for its operational technology networks. Co-Managed grows fastest at 12.9% a year because the 2024 controls require every cybersecurity position to be held by a full-time Saudi professional, according to the Clyde & Co review of the 2024 Essential Cybersecurity Controls, so entities keep internal teams and buy provider support around them.
How do large enterprises and smaller firms buy differently?
Based on organization size, the market is categorized into large enterprises and SMEs. Large Enterprises led with 72.0% of 2025 value because complex estates need custom monitoring, shown when Riyadh Airports signed with sirar by stc at Black Hat in Riyadh on Nov. 29, 2024, to protect the digital systems that run airport operations. SMEs grow fastest at 13.2% a year as telecom operators package monitoring for smaller buyers, and Mobily markets its Next Generation managed SOC with 24/7 coverage to organizations of all sizes through its business sales channel.
Which verticals commission the most managed security?
Based on vertical, the market is categorized into government, BFSI, energy and utilities, IT and ITES, healthcare and life sciences, and others. Government led with 30.0% of 2025 value because public entities spent SAR 5.1 billion on cybersecurity in 2025, 31% of national spending, according to the National Cybersecurity Authority, and they must use Tier-1 licensed operators. Energy and Utilities grows fastest at 13.3% a year as industrial operators open their networks to providers, and CrowdStrike signed a memorandum with Aramco on Feb. 5, 2026, covering critical infrastructure and operational technology.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Managed Detection and Response | 38.0% | Managed IAM | 13.6% |
| By Type | Fully Managed | 61.0% | Co-Managed | 12.9% |
| By Organization Size | Large Enterprises | 72.0% | SMEs | 13.2% |
| By Vertical | Government | 30.0% | Energy and Utilities | 13.3% |
Per-endpoint and per-log fees set the price of monitoring
Pricing is mostly recurring and scales with what the provider watches, measured per endpoint, per asset, per identity or per monitored log volume. No Saudi provider publishes a public price list, so the ranges below are Credence Research estimates and should be read as an evidence gap rather than quoted tariffs. Tier-1 contracts carry the highest fees because licensing requires in-Kingdom facilities, local data processing and Saudi analysts. Against the breach costs described in the drivers, buyers usually accept these premiums, although mid-market clients press Tier-2 operators for bundled fixed fees.
| Service or contract | Typical price or fee | Basis |
|---|---|---|
| Managed detection and response, 1,000-endpoint estate | USD 8–15 per endpoint per month | Credence Research estimate from provider scoping norms and in-Kingdom staffing costs |
| 24/7 managed SOC monitoring, Tier-2 provider | USD 15,000–40,000 per month | Credence Research estimate from analyst headcount and log volume |
| Tier-1 managed SOC for a government or infrastructure entity | USD 60,000–200,000 per month | Credence Research estimate from licensing, facility and staffing requirements |
| Managed vulnerability management | USD 3–8 per asset per month | Credence Research estimate from scanning and remediation scope |
| Managed identity and access | USD 2–6 per identity per month | Credence Research estimate from directory size and privileged account scope |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Licensing, spending and breach costs push work to providers
National SOC licensing makes outsourcing a compliance step
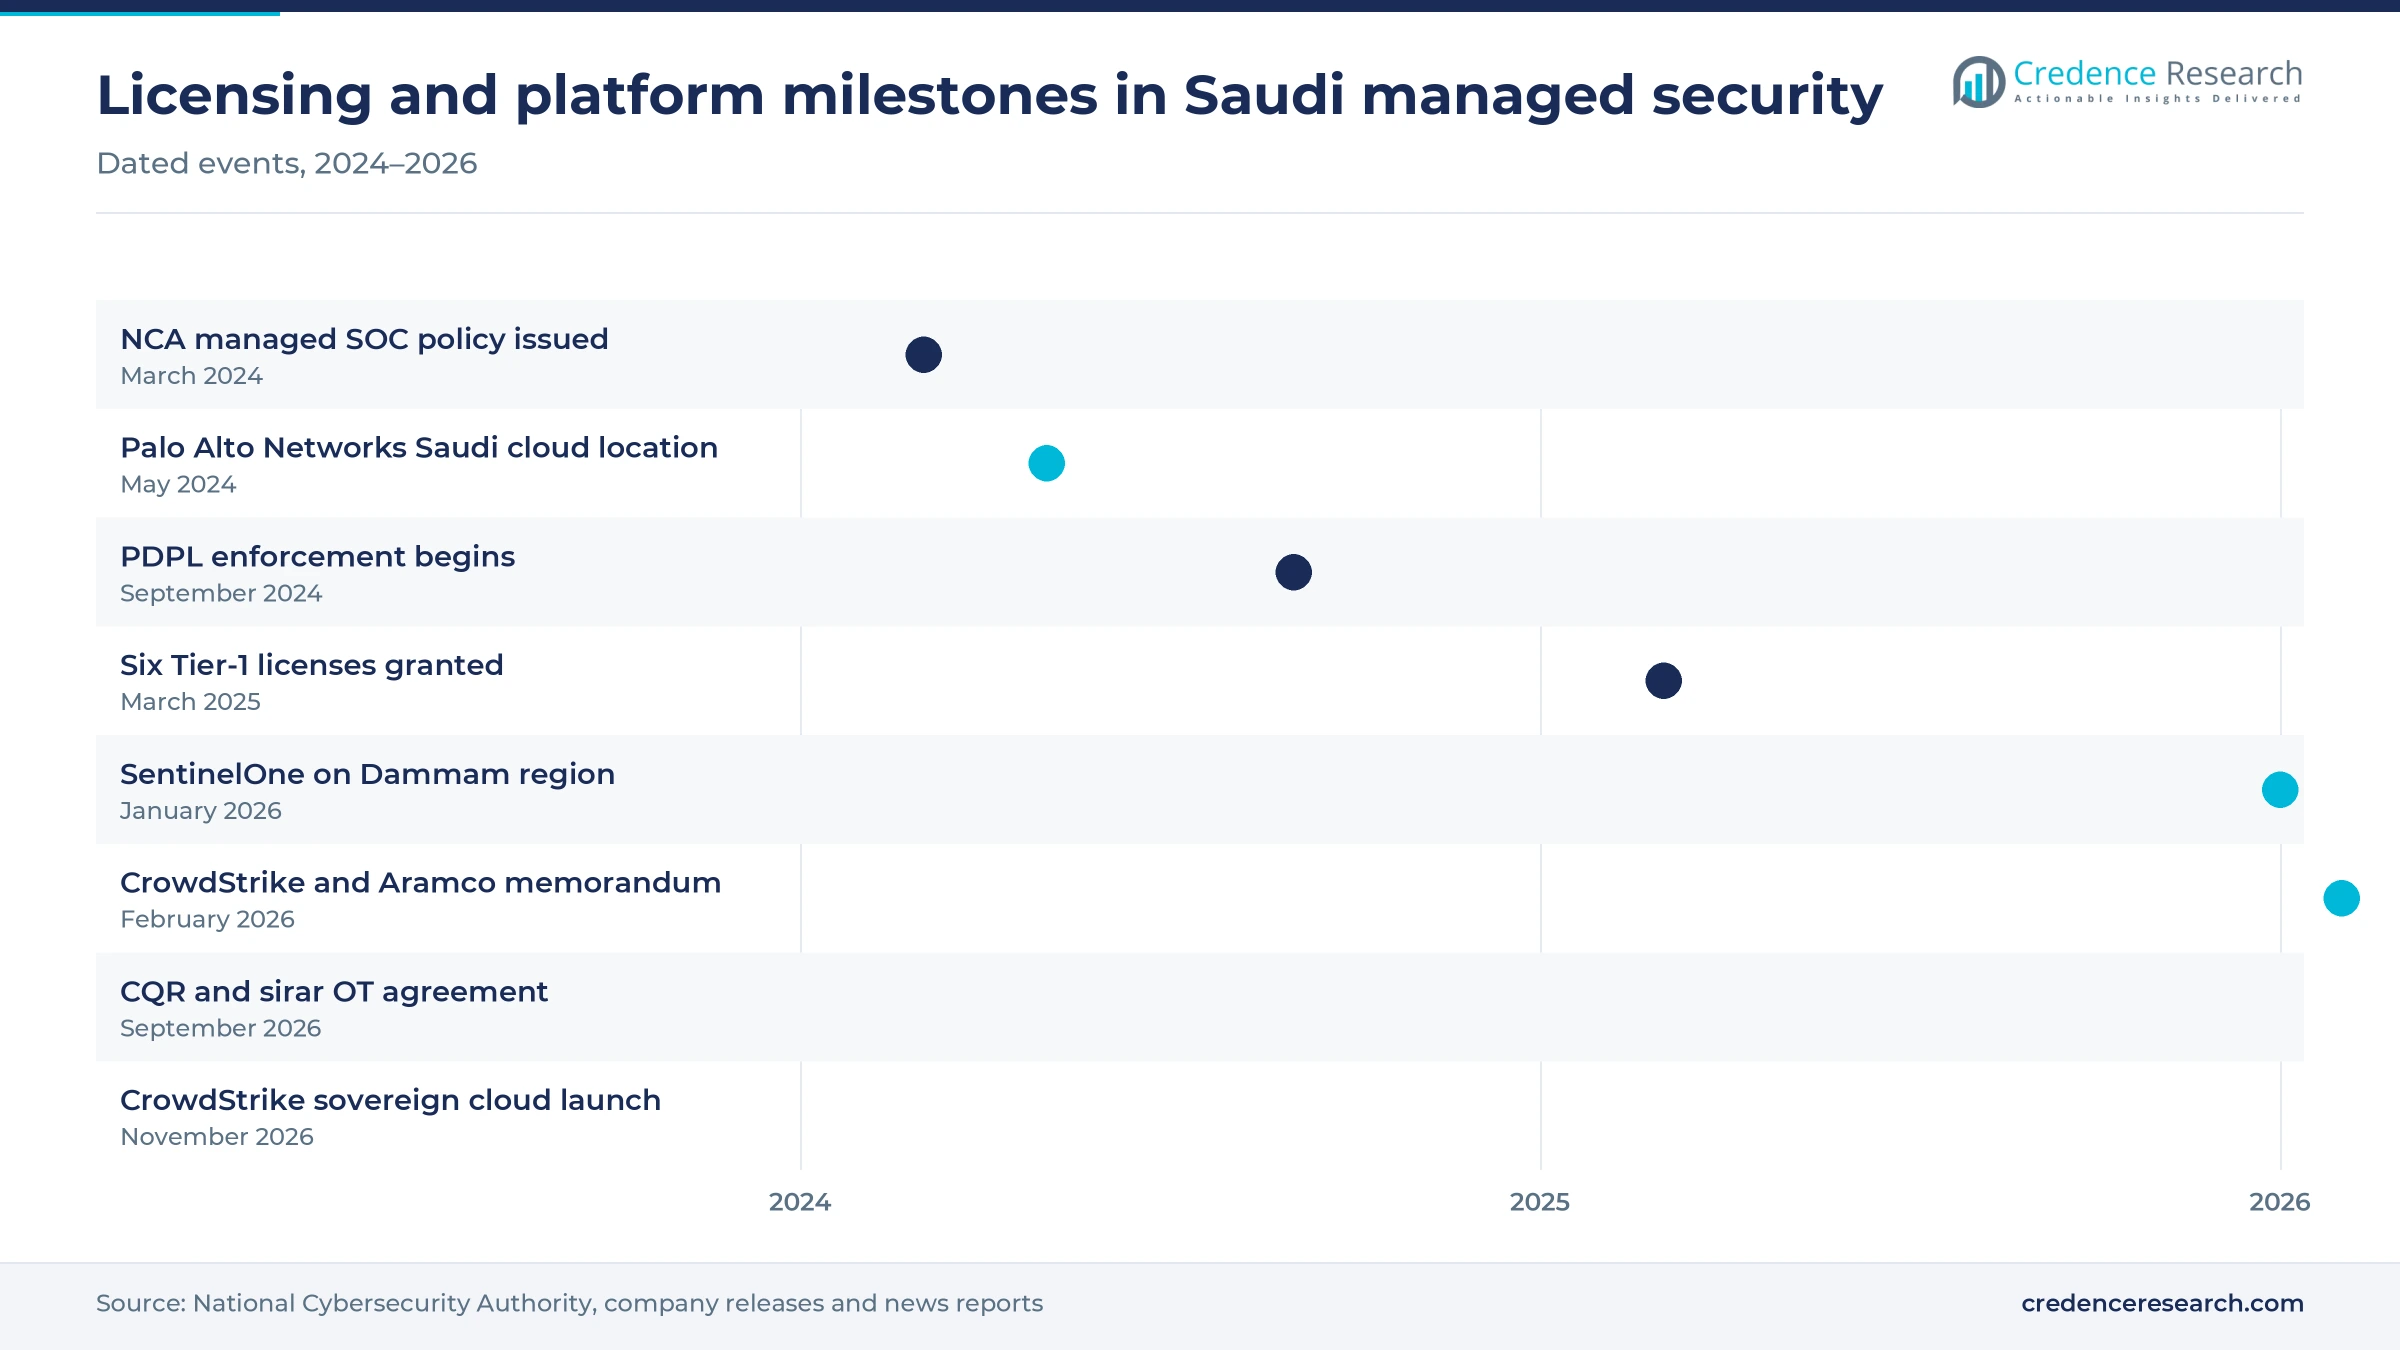
Licensing is the strongest demand mechanism because it turns outsourced monitoring from an option into a requirement for the largest buyers. The National Cybersecurity Authority issued its national policy and regulatory framework for managed security operations centers on March 10, 2024, and began accepting license applications through its Haseen portal that month. It then granted Tier-1 licenses to six providers on March 18, 2025, among them sirar by stc, SITE, Haboob, Cyberani, Tahakom and Advanced Electronics Company. Government entities and critical infrastructure operators must run their cybersecurity operations through those Tier-1 licensees, which locks a stable contract base into the licensed segment. The ITU Global Cybersecurity Index 2024 placed Saudi Arabia in its top role-modeling tier, and that regulatory depth helps Managed Detection and Response hold 38.0% of 2025 value.
Cyber budgets keep rising and services take half
Spending growth gives providers a widening pool to win, and services already absorb almost half of every riyal spent on cybersecurity. The key economic indicators report of the National Cybersecurity Authority put total cybersecurity spending at SAR 16.3 billion in 2025, after a 10.7% compound annual rise over three years. Services accounted for SAR 7.9 billion, or 49% of that total, while products took the remainder. The authority put private sector spending at SAR 11.2 billion, which means banks, energy groups and large companies fund most demand outside the government mandate. Because managed monitoring is the recurring part of services spending, providers that convert one-off projects into multi-year contracts capture the most durable share of this growth.
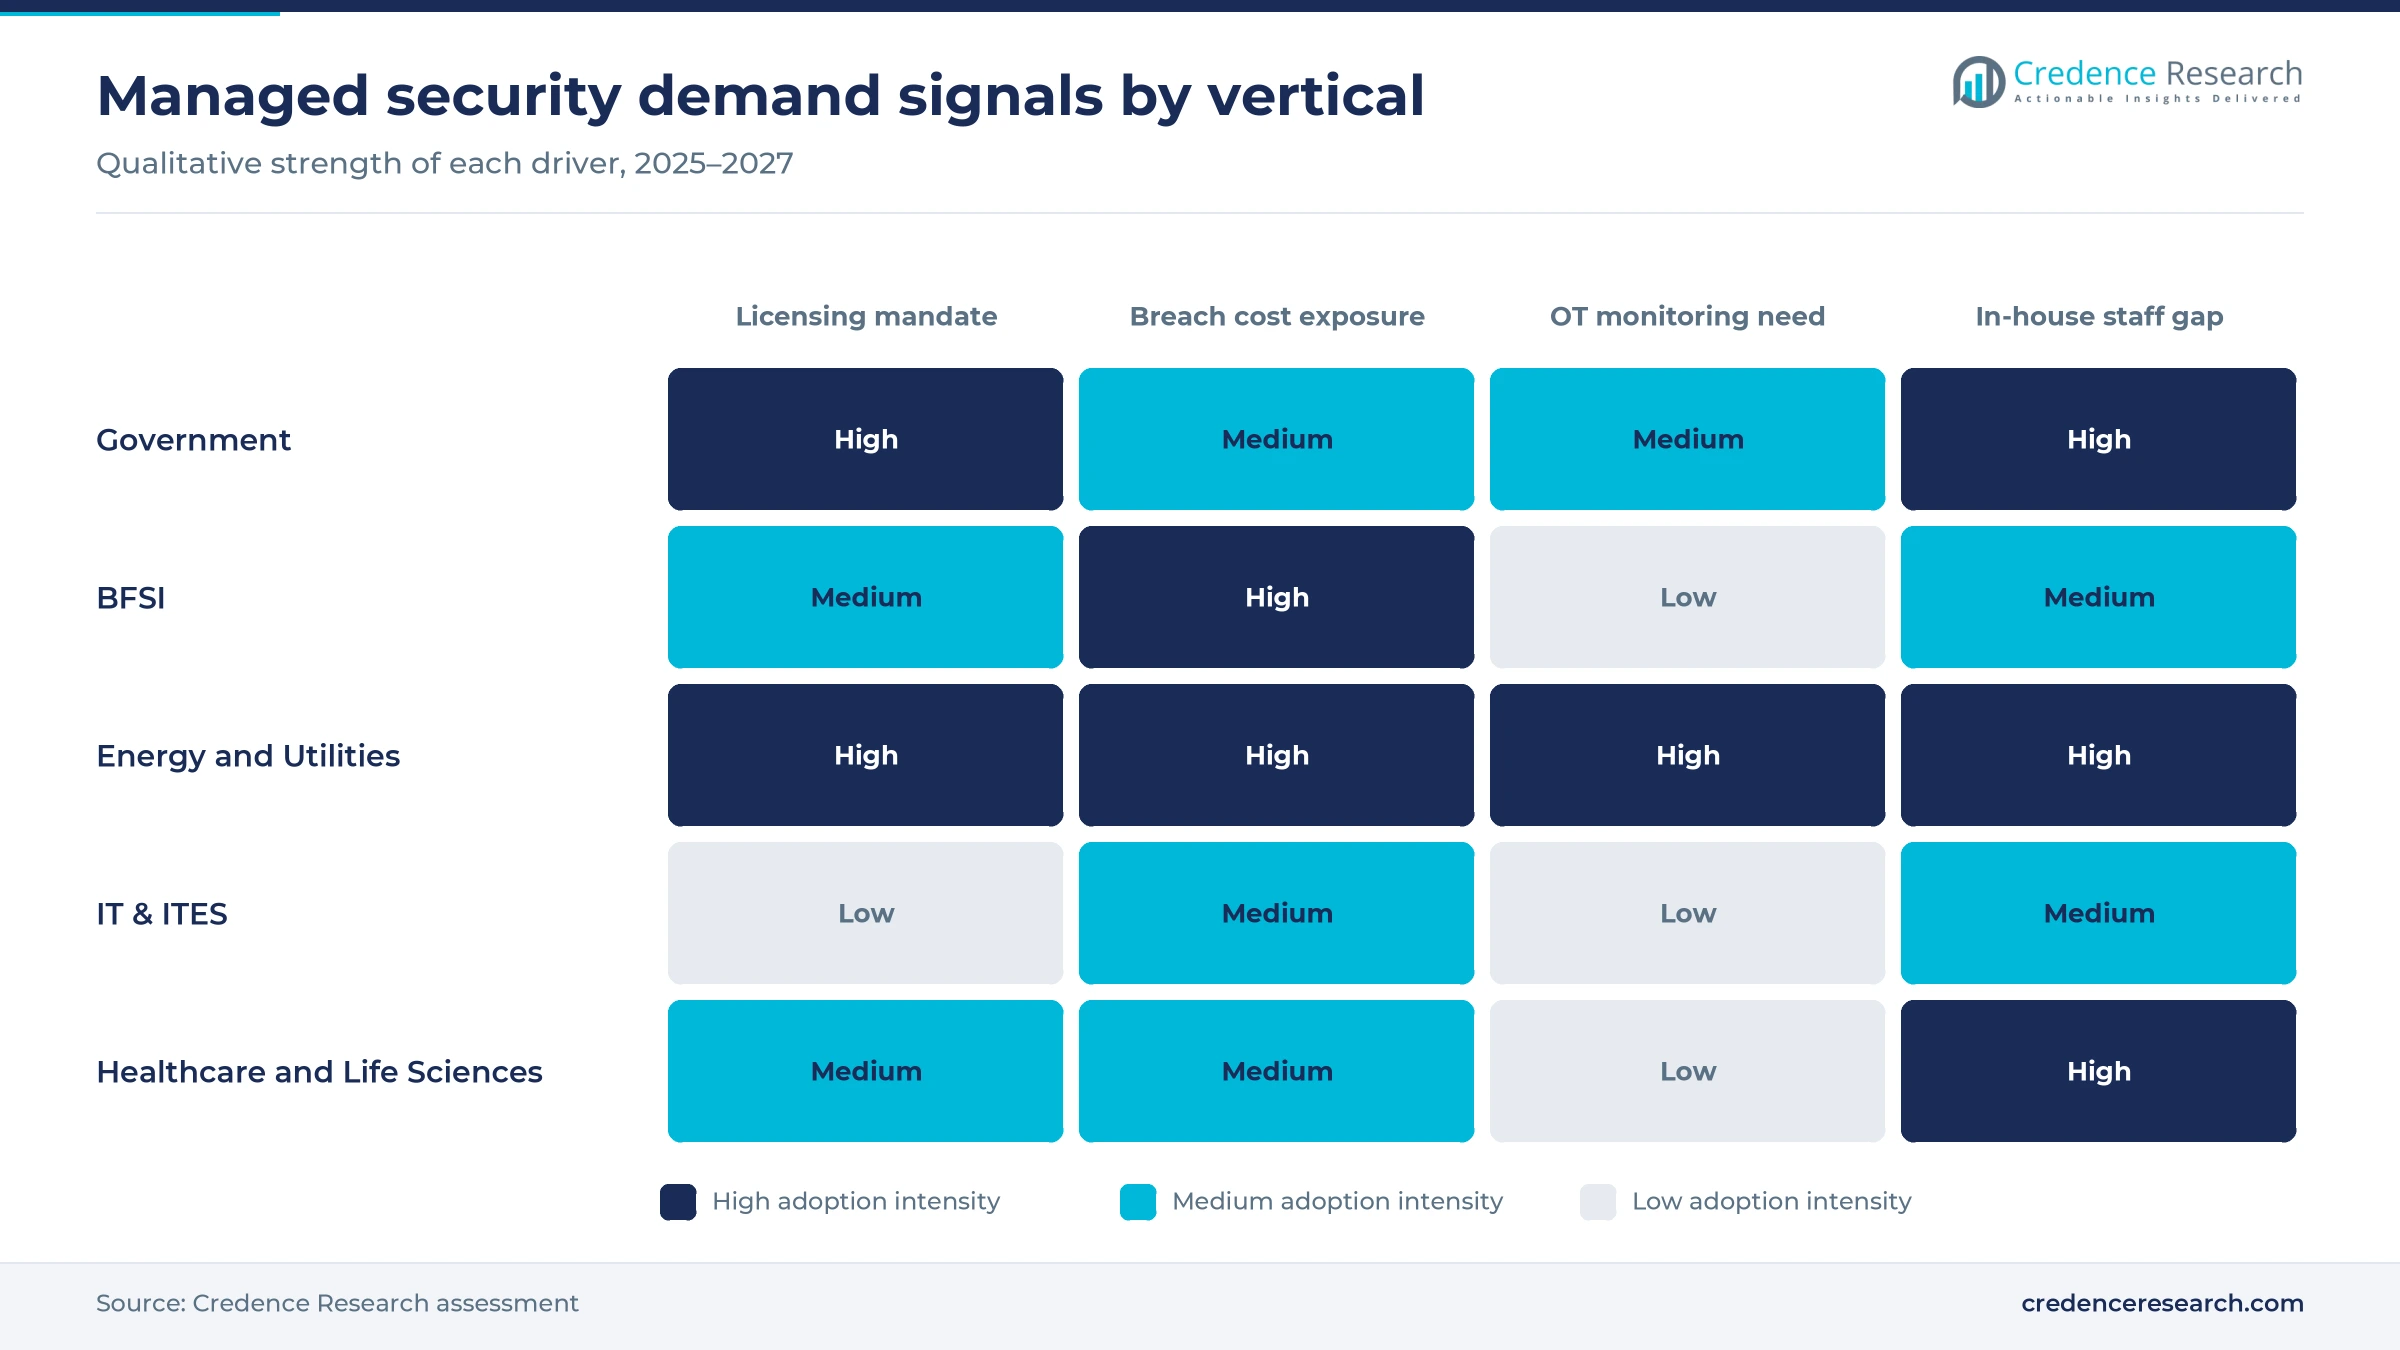
Breach costs justify paying for round-the-clock detection
Breach economics support the business case for outsourced detection because a single incident costs far more than years of monitoring fees. The IBM Cost of a Data Breach findings for the Middle East put the average breach in Saudi Arabia and the UAE at SAR 27.0 million in 2025, down about 18% from SAR 32.8 million a year earlier. Financial firms faced the highest average at SAR 34.0 million, keeping banks and insurers steady buyers. IBM named AI and machine learning driven insights among the top three factors that reduced costs, and providers now sell them inside detection contracts. Because IBM links part of the decline to AI-driven detection, providers can present lower breach costs as evidence that monitored defenses work rather than as a reason to spend less.
A thin specialist workforce pushes firms toward providers
Talent scarcity sustains outsourcing because most organizations cannot staff a round-the-clock security operations center on their own. The National Cybersecurity Authority counted more than 22,000 cybersecurity specialists in the kingdom in 2025, with the workforce growing at a 5.9% compound annual rate, according to the authority's 2026 indicators report. That pool must cover thousands of government entities, banks and industrial sites at once. Licensed providers pool scarce analysts across many clients, and the framework requires each licensee to employ a minimum number of NCA-licensed analysts. These conditions favor Fully Managed contracts, which held 61.0% of 2025 value.
Sovereign hosting and telecom scale reshape provider choice
Shift toward sovereign hosting of detection platforms
Global security vendors are shifting detection workloads into the kingdom to meet residency expectations, which changes how managed services are built and sold. Palo Alto Networks opened a local cloud location on May 30, 2024, hosting Cortex XDR, XSOAR and XSIAM, so logs and analytics stay in Saudi Arabia. Kaspersky had already launched its managed detection and response service on SCCC Alibaba Cloud in November 2023 for the same reason. CrowdStrike went further on Nov. 4, 2026, launching a sovereign Falcon deployment with telemetry and management infrastructure hosted locally. Licensed operators can therefore build extended detection and response offers on in-country platforms, while vendors without local hosting face growing exclusion from regulated tenders.
Rise of telecom and state-linked providers at scale
Ownership is shifting the field toward telecom groups and state-linked firms that combine licensing, local staff and network visibility. Sirar by stc builds its managed services on threat intelligence drawn from stc's national telecom network, an asset that independent providers cannot replicate. The same company signed a memorandum with Microsoft at Black Hat MEA in December 2025 covering advanced security services and joint skills programs. The Public Investment Fund appointed Riyad Capital and Morgan Stanley to advise on a planned listing of SITE, according to Argaam in October 2025, and SITE already held a Tier-1 license from March 2025. Scale and capital access let these providers fund new monitoring centers, which raises the bar for smaller private competitors.
Opening in industrial and operational technology monitoring
Industrial networks represent a clear opening because plant and utility assets are only starting to feed licensed monitoring centers, although no official count of covered sites exists. CQR and sirar by stc signed a master services agreement on Sept. 4, 2026, combining CQR's FENNEC platform with sirar's managed operations for energy, utilities and manufacturing clients. The partners also proposed a sovereign OT and IoT monitoring and assurance center and a device testing lab, neither yet confirmed as operational. Their platform is designed to cover assets on the planned 450 MHz industrial networks as well. Providers with operational technology protection skills can win this work, and Energy and Utilities grows at 13.3% a year.
Opening in the mid-market through tier-2 licenses
Mid-sized companies offer the largest untapped client pool, because Tier-2 licensing creates a regulated route for providers to serve buyers outside the government mandate. NourNet said on June 4, 2025, that it was one of only eight entities authorized to provide Tier-2 managed SOC services, and it targets organizations from large enterprises to small businesses. Salam, a Saudi telecom provider, secured its own Tier-2 license in August 2026, according to MEA Tech Watch. Infratech expanded its NCA-licensed managed SOC services on Sept. 1, 2026, adding monitoring, threat hunting and incident response. Providers that package fixed-price monitoring can lift SMEs demand at 13.2% a year.
Offshore limits, fiscal pauses and AI attacks test providers
Offshore delivery is no longer allowed for Saudi clients
Localization rules shut out providers that serve Saudi clients from regional hubs abroad. According to the Addleshaw Goddard summary of the licensing framework published on March 15, 2024, licensed providers must be established in the kingdom, operate from within it and process data locally, while Tier-1 applicants also need a set level of Saudi ownership and a regional headquarters. Global firms without Saudi entities are most exposed, and they now compete mainly as technology suppliers to licensed local operators.
AI-assisted social engineering raises the cost of defense
Attackers are using artificial intelligence to scale intrusion attempts, which raises the analyst effort required per client contract. SITE's chief product development officer said on Oct. 2, 2025, according to Sharikat Mubasher, that attackers increasingly use AI to automate intrusions and that social engineering is a growing challenge. Providers on fixed monthly fees absorb the extra investigation workload, and smaller licensees face the most margin pressure unless they automate triage and response.
State spending pauses can delay new contract awards
Fiscal tightening can slow approvals for providers that depend on government accounts. Consultancy-me.com reported on May 22, 2026, citing the Financial Times, that new consulting contracts had largely paused against a first-quarter deficit of more than USD 33 billion, although the Ministry of Finance disputed that account. Managed monitoring is harder to pause than advisory work, yet expansions and new scopes can still wait, so providers with balanced private sector pipelines are less exposed.
Shifting data residency rules complicate platform choices
Regulatory overlap makes platform decisions harder for buyers and providers alike. Clyde & Co noted in January 2025 that the 2024 controls cut the control count to 108 from 114 and removed the explicit in-country hosting control, moving data localization to the National Data Management Office. Buyers must still check sector rules before approving cloud-based detection, which lengthens procurement for multinational vendors and favors providers that already host every workload inside the kingdom.
Riyadh buys most as Eastern Province adds industrial demand
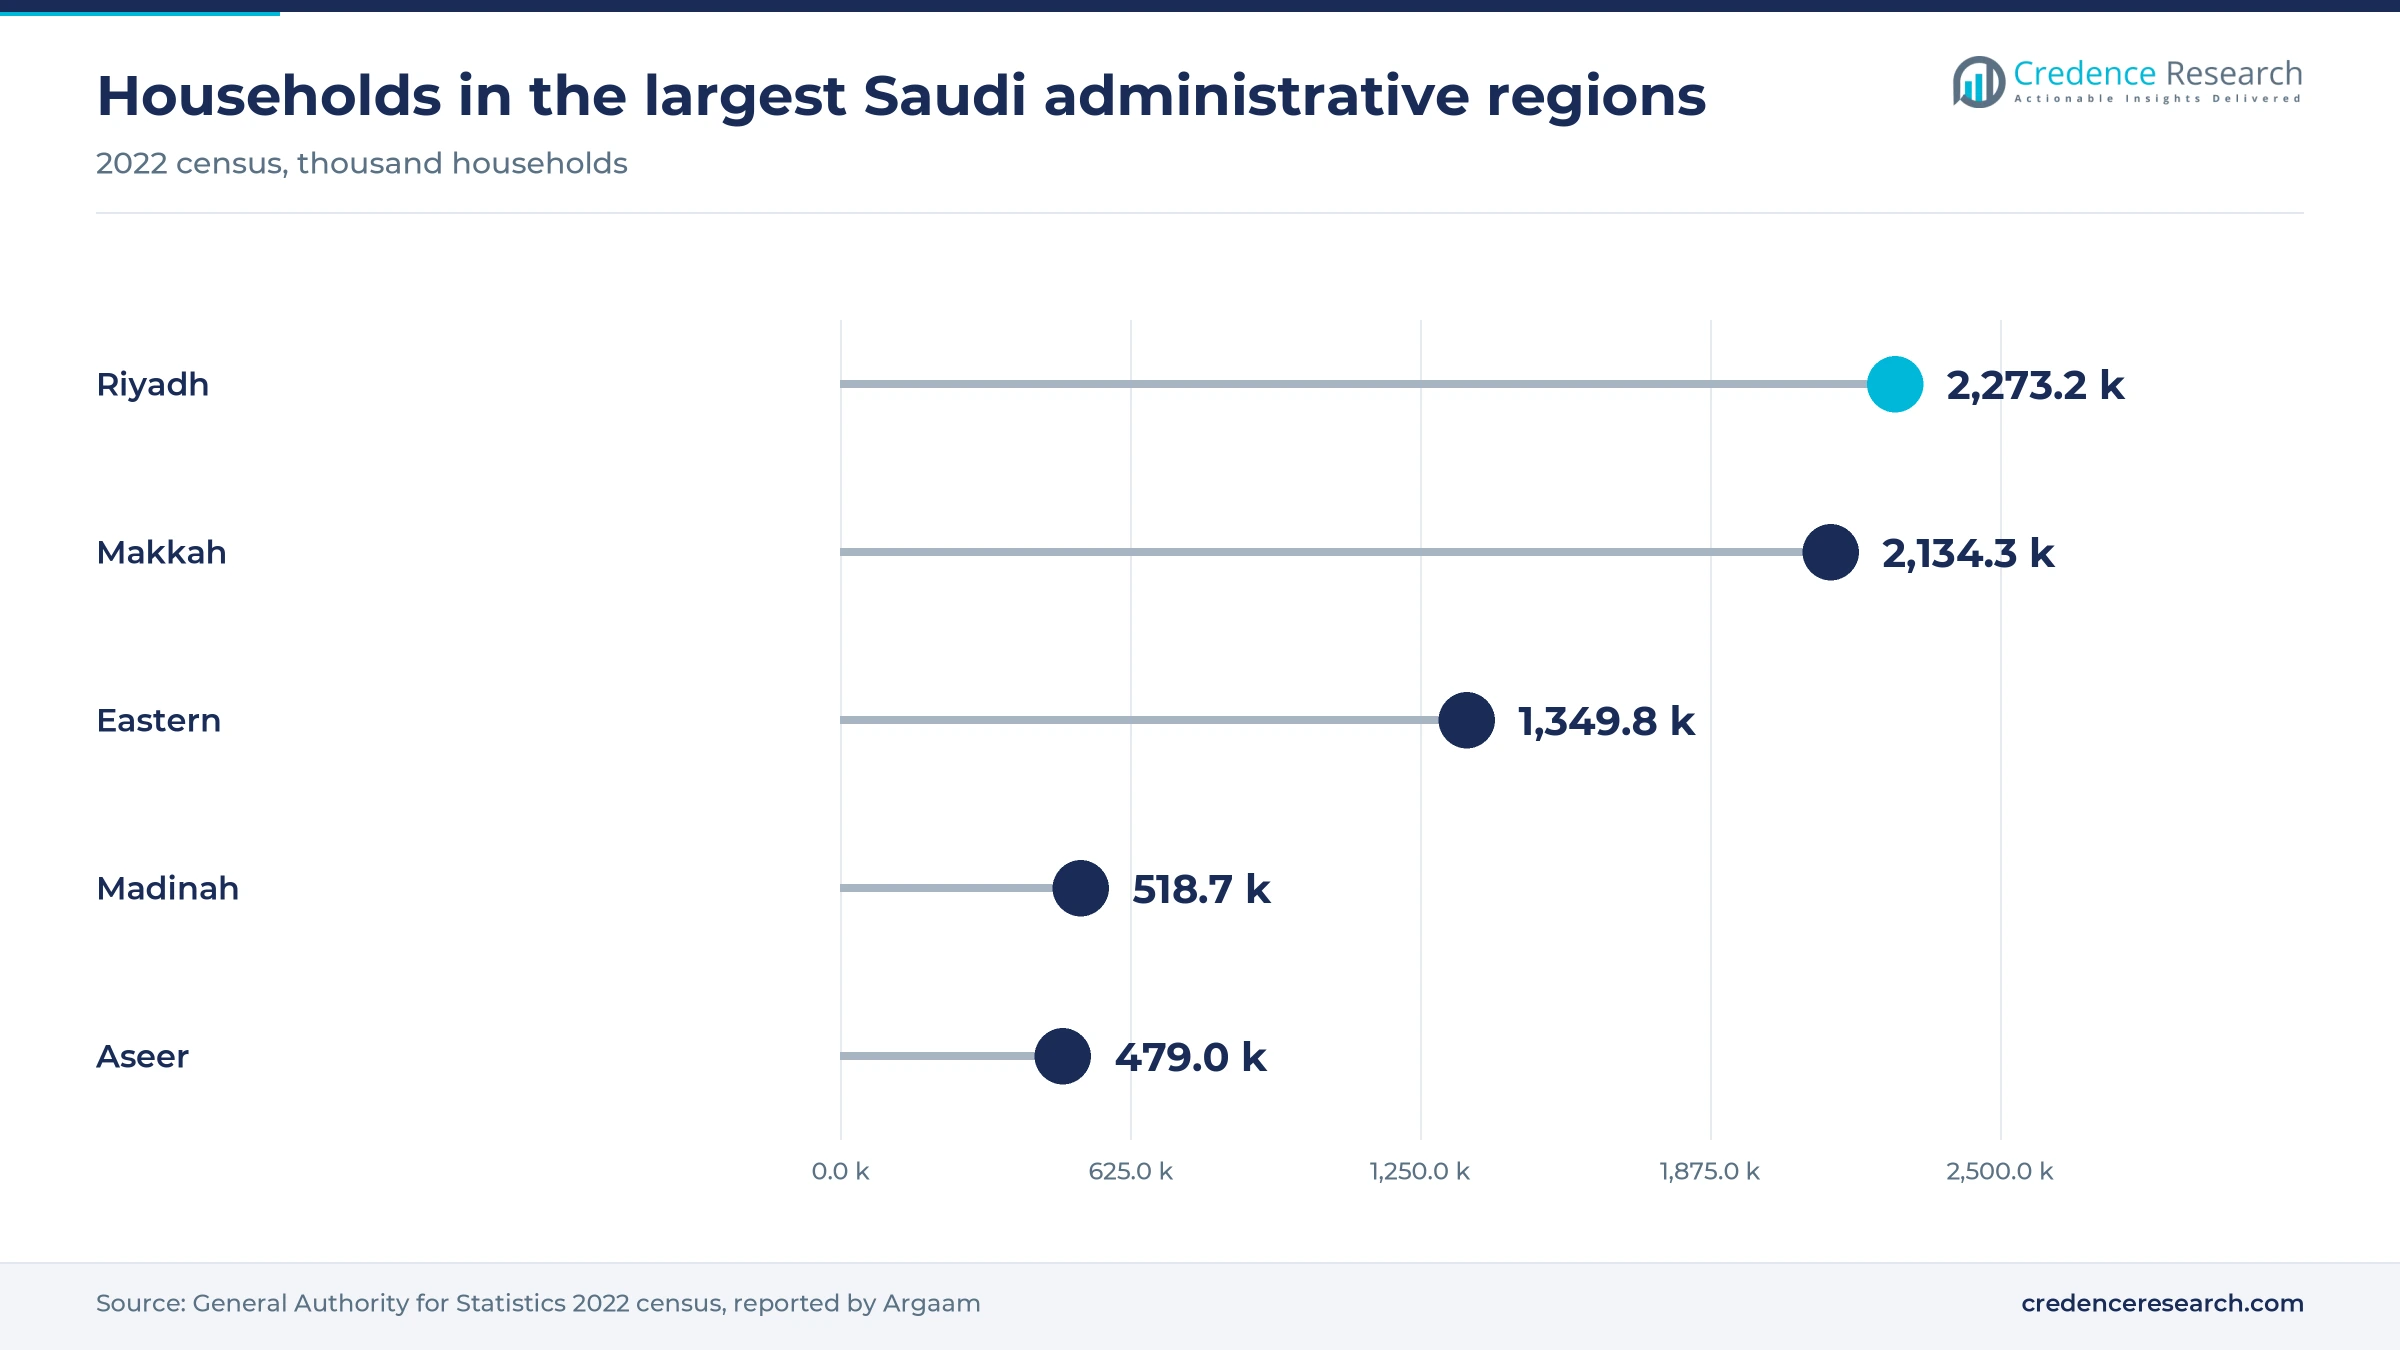
Zone shares are Credence Research estimates built from 2022 census household counts and the location of named buyers, licensed providers and hosting sites. Riyadh Region, Eastern Province and Makkah Region together account for most managed security spending in the kingdom.
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Riyadh Region | 280.8 | 52.0% | 11.8% |
| Eastern Province | 113.4 | 21.0% | 12.5% |
| Makkah Region | 97.2 | 18.0% | 12.2% |
| Rest of Saudi Arabia | 48.6 | 9.0% | 12.8% |
Riyadh region concentrates buyers and licensed providers
Riyadh Region held 52.0% of 2025 value and grows at 11.8% a year, because ministries, bank head offices and most licensed operators are based in the capital. The Ministry of Investment announced more than USD 140 million of cybersecurity investments at Black Hat MEA in Riyadh in December 2025, including regional headquarters openings. Kaspersky also received its regional headquarters license on March 4, 2024, adding vendor support for managed service providers in Riyadh.
Eastern Province adds energy demand and local hosting
Eastern Province held 21.0% of 2025 value and grows at 12.5% a year, supported by energy operators and new hosting capacity. Aramco's Dhahran base and the plant networks of the Gulf coast make the province the main test bed for operational technology monitoring. SentinelOne made its Singularity platform available on Google Cloud's Dammam region on Jan. 19, 2026, keeping logs and telemetry in the kingdom. That data center capacity brings detection workloads closer to oil, gas and utility networks.
Makkah Region needs surge capacity for pilgrim seasons
Makkah Region held 18.0% of 2025 value and grows at 12.2% a year, driven by Jeddah commerce and religious tourism systems. Sirar by stc said on June 5, 2025, that it had doubled protection capacity for Hajj digital infrastructure and activated its managed SOC with detection and response services. Seasonal peaks of this kind favor providers that can scale monitoring quickly without permanent staff increases.
Rest of Saudi Arabia grows through remote monitoring
Rest of Saudi Arabia held 9.0% of 2025 value and is the fastest zone at 12.8% a year, growing from a small base. The zone covers Madinah, Aseer and eight smaller regions, where most public entities rely on central ministries for security operations. Haboob has led a nationwide rollout of a modernized government security operations center on Google Cloud's Chronicle CyberShield since November 2023. Remote monitoring of this kind lets regional entities buy licensed services without building local security teams.
Licenses, sovereign clouds and OT deals mark 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In November 2026, CrowdStrike launched a sovereign cloud deployment of its Falcon platform in Saudi Arabia, with telemetry and management hosted locally. | Launched; available to customers and authorized partners |
| In September 2026, CQR and sirar by stc signed a master services agreement for OT and IoT security, proposing a sovereign monitoring center. | Agreement signed; monitoring center and lab still proposed |
| In August 2026, Salam secured a Tier-2 managed SOC license from the National Cybersecurity Authority to expand managed cybersecurity services. | License granted; widens mid-market supply |
| In February 2026, CrowdStrike and Aramco signed a memorandum covering critical infrastructure security and in-country cloud capabilities. | Memorandum signed; no final contract disclosed |
| In March 2025, the National Cybersecurity Authority granted Tier-1 managed SOC licenses to six providers serving government and critical infrastructure. | Licenses issued; mandate in force |
In-country platforms and OT telemetry define the stack
- In-country detection platforms keep logs and telemetry inside the kingdom, which licensed operators need for regulated government and banking clients.
- Security orchestration and automation lets providers handle more alerts per analyst, a priority given the limited specialist workforce in the kingdom.
- OT and IoT telemetry extends monitoring from offices to plants, pipelines and smart districts, where many legacy devices lack native logging.
- Threat intelligence sharing links provider centers to national security operations, which the licensing framework requires for routine data exchange.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
State-linked tier-1 licensees anchor a concentrated field
Competition splits between state-linked Tier-1 licensees, telecom operators, Tier-2 specialists and global platform vendors that sell through them. Sirar by stc combines a Tier-1 license with telecom network visibility and the widest set of named public references, from KAFD to Hajj systems. SITE, owned by the Public Investment Fund, pairs managed services with its own cloud and is preparing a listing. Haboob, Cyberani, Tahakom and Advanced Electronics Company hold Tier-1 licenses and serve government and critical infrastructure accounts. Mobily and NourNet target the wider private market with packaged monitoring. Palo Alto Networks, CrowdStrike, Kaspersky and Fortinet compete on detection platforms, local hosting and threat research rather than on license status. Buyers weigh Saudi analyst headcount, license tier, in-Kingdom hosting and references from comparable national systems more heavily than price.
How concentrated is the provider base?
The supply side is concentrated at the top and fragmented below it. Six Tier-1 licensees, most of them state-owned or state-linked, hold the mandated government and critical infrastructure work, while a wider group of Tier-2 operators competes for private sector clients. Entry barriers are high, since a license requires a Saudi entity, local facilities, in-Kingdom data processing and licensed analysts. Global vendors such as Palo Alto Networks, CrowdStrike and Fortinet mostly earn platform subscriptions through licensed operators. Margins sit with providers that own long Tier-1 contracts and spread analysts across many clients.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| sirar by stc (stc Group) | Tier-1 licensed provider | Managed SOC and MDR for KAFD, Hajj systems and utilities |
| Saudi Information Technology Company (SITE) | Tier-1 licensed provider | PIF-owned managed security, cloud hosting and threat detection services |
| Haboob | Tier-1 licensed provider | Government security operations center rollout on Chronicle CyberShield |
| Cyberani | Tier-1 licensed provider | Managed SOC services for government and critical infrastructure clients |
| Tahakom | Tier-1 licensed provider | Managed SOC services licensed for government and critical infrastructure |
| Mobily | Telecom operator | Next Generation managed SOC with 24/7 monitoring for business clients |
| NourNet | Tier-2 licensed provider | Managed threat monitoring, detection and response for private organizations |
| Advanced Electronics Company | Tier-1 licensed provider | Managed SOC services licensed for government and critical infrastructure |
| Palo Alto Networks | Platform vendor | Cortex XDR, XSOAR and XSIAM hosted in a Saudi cloud location |
| CrowdStrike | Platform vendor | Sovereign Falcon deployment in Saudi Arabia; Aramco memorandum |
| Kaspersky | Platform vendor | Managed detection and response hosted on SCCC Alibaba Cloud |
| Fortinet | Platform vendor | FortiGuard SOC-as-a-Service with multivendor monitoring added in 2026 |
Licensed local capacity will decide contract winners
Credence Research's view is that licensing has already decided the shape of this market, and the next phase will reward delivery capacity rather than new entrants. Tier-1 holders have a protected base, but they must still prove they can monitor industrial networks and absorb AI-assisted attacks without margin erosion. Tier-2 operators face the opposite problem, with open demand but thinner contracts. The main assumption behind the forecast is that the government mandate stays firm through budget cycles, and the largest evidence gap is the absence of an official managed services spending series.
NCA spending data and provider records anchor this estimate
The report uses 2025 as the base year and 2035 as the final forecast year, with market values from the Credence Research model. The 2025 value was rebuilt top-down from National Cybersecurity Authority spending data, applying an estimated managed services share of cybersecurity services spending. Segment and zone splits are Credence Research estimates, informed by regulator notices, licensing announcements, company releases, census household counts and news coverage. No interviews or surveys were conducted, and the splits should be read as analytical estimates.
Infrastructure and mid-market demand carry growth to 2035
The market is forecast to reach USD 1.69 billion by 2035 from USD 605.3 million in 2026, a 12.10% CAGR over 2026–2035. Early years should bring steady government and banking renewals under the licensing mandate, while private sector demand builds as Tier-2 operators package fixed-fee monitoring. Later in the period, growth should shift toward industrial and operational technology monitoring, identity services tied to data protection rules, and AI-assisted response. Riyadh Region should remain the commercial center, although Eastern Province gains share as energy operators extend monitoring to plant networks. Providers with licensed Saudi analysts and in-Kingdom platforms should capture most of this growth.
What decides the range of 2035 outcomes?
The range of outcomes depends on how quickly critical infrastructure operators extend monitoring to industrial networks and how fast mid-market firms buy Tier-2 services. A downside case assumes longer state budget pauses and slow licensing of new operators. The upside case assumes OT monitoring centers become operational and sovereign platforms cut onboarding time for smaller clients.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 10.1% | USD 1.44 billion | State contract pauses extend and few new operators receive Tier-2 licenses |
| Base | 12.10% | USD 1.69 billion | Licensing mandate holds and private sector outsourcing grows steadily |
| Upside | 13.9% | USD 1.95 billion | OT monitoring centers go live and mid-market firms adopt fixed-fee monitoring |
Frequently Asked Questions
How big is the Saudi Arabia managed security services market?
Which service type leads the market?
Which companies hold Tier-1 managed SOC licenses?
What does SITE do in this market?
Is managed detection and response available locally in Saudi Arabia?
Which region holds the largest share?
How do the 2024 controls affect outsourcing?
What is the main risk for providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Managed Detection and Response
- 1.2.2 Managed Vulnerability Management
- 1.2.3 Managed IAM
- 1.2.4 Managed Risk and Compliance
- 1.2.5 Others
- 1.3 By Type
- 1.3.1 Fully Managed
- 1.3.2 Co-Managed
- 1.4 By Organization Size
- 1.4.1 Large Enterprises
- 1.4.2 SMEs
- 1.5 By Vertical
- 1.5.1 Government
- 1.5.2 BFSI
- 1.5.3 Energy and Utilities
- 1.5.4 IT & ITES
- 1.5.5 Healthcare and Life Sciences
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 540.0 million → 2035: USD 1.69 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Saudi Arabia Managed Security Services Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Saudi Arabia Managed Security Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Saudi Arabia Managed Security Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Saudi Arabia Managed Security Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Saudi Arabia Managed Security Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Saudi Arabia Managed Security Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Saudi Arabia Managed Security Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Saudi Arabia Managed Security Services Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 540.0 million → 2035: USD 1.69 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Saudi Arabia Managed Security Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Managed Detection and Response
- 12.3.6.2 Managed Vulnerability Management
- 12.3.6.3 Managed IAM
- 12.3.6.4 Managed Risk and Compliance
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Fully Managed
- 12.4.6.2 Co-Managed
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Organization Size - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Large Enterprises
- 12.5.6.2 SMEs
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Vertical - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Government
- 12.6.6.2 BFSI
- 12.6.6.3 Energy and Utilities
- 12.6.6.4 IT & ITES
- 12.6.6.5 Healthcare and Life Sciences
- 12.6.6.6 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Saudi Arabia Managed Security Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Saudi Arabia Managed Security Services Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Saudi Arabia Managed Security Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Saudi Arabia Managed Security Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 sirar by stc (stc Group)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Saudi Information Technology Company (SITE)
- 18.4 Haboob
- 18.5 Cyberani
- 18.6 Tahakom
- 18.7 Mobily
- 18.8 NourNet
- 18.9 Advanced Electronics Company
- 18.10 Palo Alto Networks
- 18.11 CrowdStrike
- 18.12 Kaspersky
- 18.13 Fortinet
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

