
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
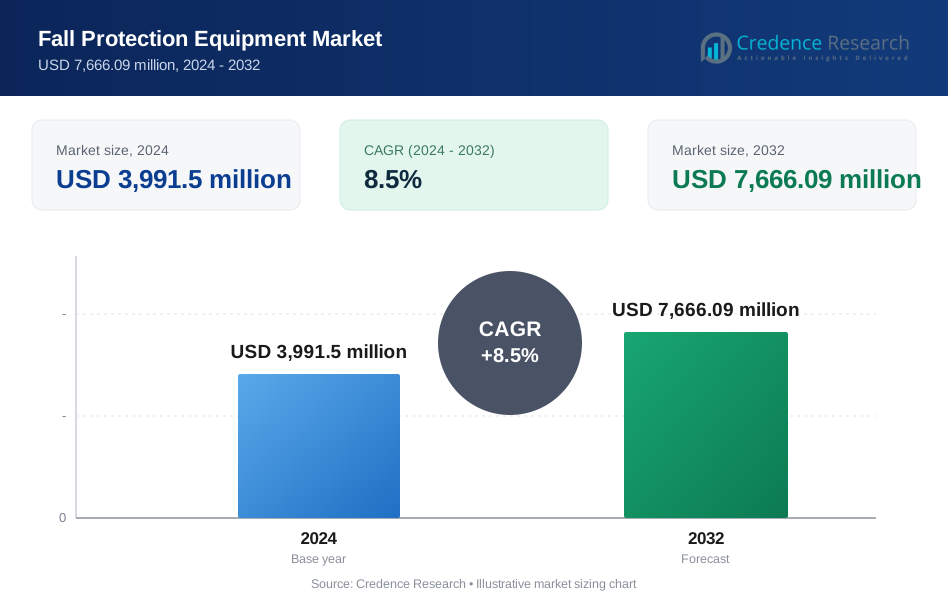
| Fall Protection Equipment Market Size 2024 | USD 3,991.5 million |
| Fall Protection Equipment Market, CAGR | 8.5% |
| Fall Protection Equipment Market Size 2032 | USD 7,666.09 million |
Market Overview
The Fall Protection Equipment Market is expected to grow from USD 3,991.5 million in 2024 to USD 7,666.09 million by 2032, reflecting a CAGR of 8.5%.
The Fall Protection Equipment Market is driven by increasing safety regulations across industries, such as construction, manufacturing, and oil & gas, which prioritize worker protection. As workplace safety standards tighten globally, the demand for fall protection solutions is rising. The market is also benefiting from technological advancements in equipment, such as harnesses, lanyards, and rescue systems, designed for greater comfort, durability, and ease of use. Additionally, the growing focus on worker safety amid rising workplace accidents further fuels the adoption of fall protection gear. Urbanization and infrastructure development, particularly in emerging economies, are also contributing to market growth, as these sectors require robust safety measures for workers at height. Furthermore, the trend toward personalized safety solutions, incorporating wearable technology and real-time monitoring systems, is gaining traction, enhancing the effectiveness of fall protection equipment and driving market expansion. As a result, the market is poised for sustained growth over the coming years.
The Fall Protection Equipment Market exhibits strong regional growth, with North America and Europe leading the charge due to stringent safety regulations and an increased focus on worker protection. North America holds the largest market share, driven by rigorous OSHA standards, while Europe sees steady growth, fueled by safety laws across industries like construction and energy. The Asia Pacific region is witnessing rapid expansion due to growing industrial activity and infrastructure development. Key players in the market include renowned companies like Honeywell International, MSA Safety, Petzl, FallTech, and WernerCo., among others. These companies are focusing on innovations, such as IoT-enabled devices, ergonomic designs, and lightweight materials, to meet the evolving safety needs of various industries, further strengthening their position in the global market.
Market Drivers
Stringent Government Regulations
Governments around the world are increasingly implementing and enforcing stringent safety regulations to reduce workplace accidents and fatalities. For instance, the Occupational Safety and Health Administration (OSHA) in the United States has established comprehensive standards that require industries like construction, manufacturing, and oil and gas to implement fall protection measures. These regulations aim to ensure that workers are adequately protected while working at height, compelling businesses to invest in reliable fall protection solutions to comply with safety laws and avoid penalties.
Rising Awareness of Workplace Safety
There has been a significant rise in awareness regarding workplace safety, with both employers and employees acknowledging the importance of risk mitigation. For instance, reports indicate that more than 5,500 fatal workplace accidents occurred in a recent year in the U.S., highlighting the urgent need for effective safety measures. As industries recognize the severe consequences of accidents and fatalities, they are adopting comprehensive safety measures, driving the need for advanced fall protection solutions to safeguard workers operating at elevated heights.
Increasing Construction and Infrastructure Projects
The global boom in construction and infrastructure development is another major driver for the fall protection equipment market. As large-scale projects continue to expand across both developed and emerging markets, the demand for safety measures becomes crucial. The complexity and size of modern construction projects often involve workers at significant heights, making the use of fall protection equipment essential to maintaining workplace safety standards and preventing accidents.
Technological Advancements
Technological innovations are transforming the fall protection equipment landscape. Self-retracting lifelines, advanced harnesses, and wearable safety devices are improving both safety and convenience for workers. These developments offer enhanced functionality, providing workers with greater mobility and ease of use while ensuring superior protection. The ongoing evolution of fall protection technologies is fueling market growth, as companies increasingly seek cutting-edge solutions to address safety concerns efficiently.
Market Trends
Technological Advancements in Fall Protection Equipment
The integration of advanced technologies is a key trend in the fall protection equipment market. One of the most notable developments is the incorporation of smart and connected safety gear, with Internet of Things (IoT) capabilities and wearable technology that enable real-time monitoring, alerts, and location tracking. This allows for immediate responses in case of emergencies, enhancing overall worker safety. Additionally, fall protection gear is becoming increasingly lightweight and ergonomic, with manufacturers designing harnesses and other equipment that reduce user fatigue and improve comfort. This is essential for ensuring worker acceptance and long-term use. Moreover, advancements in materials and manufacturing techniques have led to improvements in durability and weather resistance. These new materials ensure that fall protection equipment can withstand harsh working conditions, including extreme temperatures and heavy-duty environments, which is especially important in industries like construction and oil and gas where workers face rigorous conditions daily.
Increasing Demand for Specialized Solutions and Sustainability
There is a growing demand for industry-specific fall protection solutions, tailored to meet the unique challenges and risks associated with sectors such as construction, oil and gas, utilities, and manufacturing. These specialized solutions are designed to provide effective protection against fall hazards unique to each industry. For instance, a report from the U.S. Bureau of Labor Statistics revealed that falls accounted for 36.5% of all workplace fatalities in 2022, driving companies to develop advanced equipment to ensure efficient, swift, and safe responses to fall incidents. Alongside these developments, there is an increasing emphasis on sustainability in the fall protection sector. Manufacturers are turning to eco-friendly materials and energy-efficient solutions, such as solar-powered devices, to reduce environmental impact. Additionally, comprehensive training programs and awareness campaigns are becoming standard practice, ensuring workers understand the correct usage, inspection, and maintenance of their safety gear. Lastly, regulatory compliance and adherence to global safety standards remain at the forefront, with continuous updates and certifications to meet evolving safety regulations and ensure high-quality, reliable products. By staying ahead of these trends, manufacturers and suppliers can better address the diverse and evolving needs of the market, while contributing to a safer and more sustainable workplace environment.
Market Challenges Analysis
High Initial Costs and Training Requirements
One of the significant challenges in the fall protection equipment market is the high initial cost associated with the purchase and installation of comprehensive fall protection systems. These systems, especially in large-scale construction projects or high-risk industries, can involve substantial investments in equipment, safety gear, and installation. Additionally, the cost of training and certification for workers to properly use and maintain this equipment further increases overall expenses. Proper training is crucial not only for compliance but also for ensuring that the equipment is used correctly to maximize its effectiveness. These high costs can be a barrier for smaller businesses or organizations in developing economies, slowing down the adoption of fall protection equipment and hindering overall market growth.
User Comfort, Regulatory Challenges, and Counterfeit Risks
User comfort is another key challenge facing the market. Fall protection equipment, particularly full-body harnesses, can be uncomfortable to wear, especially in hot and humid conditions. This discomfort can lead to reduced compliance, as workers may be less inclined to wear the equipment properly, increasing the risk of accidents. For instance, a report from the European Agency for Safety and Health at Work noted that discomfort can significantly affect workers' willingness to wear safety gear properly, thereby increasing accident risks. Moreover, workers with physical limitations may face difficulties in using certain types of fall protection gear, further complicating efforts to ensure widespread usage. Compounding these issues is the complex regulatory landscape that varies by region and industry. Different safety standards and frequent updates to regulations can create confusion, making it challenging for manufacturers and users to remain compliant without incurring additional costs for new equipment and training. Finally, the market faces risks from counterfeit and substandard products. These fake products can compromise worker safety and undermine the reputation of the industry, disrupting the market for genuine, high-quality fall protection equipment. This highlights the need for stringent regulation and quality control to protect both businesses and workers.
Market Segmentation Analysis:
By Type:
The Fall Protection Equipment Market is segmented based on the type of equipment used to ensure worker safety at heights. Key categories include harnesses, lanyards, anchor points, self-retracting lifelines, and fall arrest systems. Among these, harnesses are the most widely used, as they provide essential support and security for workers in high-risk environments. Lanyards, often used in conjunction with harnesses, play a crucial role in limiting the distance a worker falls by tethering them securely to an anchor point. Self-retracting lifelines are gaining traction due to their advanced design, which allows for greater mobility and automatic tensioning to reduce slack. Fall arrest systems, including horizontal and vertical systems, are designed to prevent fatal falls by safely halting a worker's descent. The increasing demand for more sophisticated and technologically advanced fall protection systems is driving innovation in this segment, with a focus on improving safety and enhancing user comfort.
By End-use:
The Fall Protection Equipment Market is also segmented by end-use industries, including construction, oil and gas, manufacturing, utilities, and transportation. The construction sector leads this market segment due to its high number of workers operating at significant heights, creating a strong demand for reliable fall protection solutions. Oil and gas, especially in offshore and high-altitude operations, also represents a key market for fall protection equipment, where stringent safety measures are critical. Manufacturing facilities, including warehouses and factories, require fall protection systems for workers operating at elevated platforms or in hazardous environments. The utilities sector, including energy and power transmission, demands robust fall protection systems due to the elevated nature of infrastructure, such as power lines and wind turbines. The transportation sector, with its operations involving loading docks and high-positioned cargo, also contributes significantly to the market. As safety regulations tighten across all these industries, the demand for specialized fall protection equipment is expected to continue growing.
Segments:
Based on Type:
- Soft Goods
- Hard Goods
- Installed System
- Access System
- Rescue Kit
- Services
Based on End-use:
- Construction
- General Industry
- Oil & Gas
- Energy & Utilities
- Telecom
- Transportation
- Mining
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Fall Protection Equipment Market, driven by strict safety regulations and a strong focus on worker protection. The United States, in particular, is the largest market due to its stringent Occupational Safety and Health Administration (OSHA) standards, which require industries like construction, oil and gas, and manufacturing to use fall protection systems. The market in this region is expected to maintain its dominance with increasing investments in worker safety initiatives and infrastructure development. In 2023, North America accounted for approximately 35% of the global market share. The region's high level of industrial activity, coupled with a strong emphasis on safety, creates consistent demand for advanced fall protection equipment. Furthermore, technological advancements such as IoT-enabled devices and ergonomic designs are seeing increased adoption, further driving growth.
Europe
Europe represents another key region in the Fall Protection Equipment Market, contributing around 25% of the global market share. The region’s market growth is fueled by strict regulatory frameworks and a growing focus on worker health and safety. Countries like Germany, the UK, and France have stringent safety standards for industries such as construction and energy, which are major consumers of fall protection equipment. Additionally, the rise of infrastructure projects, particularly in Eastern Europe, has increased the demand for reliable safety gear. Europe’s market is also benefiting from innovations in fall protection technology, such as wearable safety devices and lightweight harnesses, which are expected to increase market adoption. As regulations become more uniform across the European Union, the demand for compliance-driven fall protection solutions is expected to rise, ensuring sustained growth in the coming years.
Key Player Analysis
- W.W. Grainger Inc.
- SKYLOTEC
- Honeywell International
- MSA Safety
- Petzl
- Gravitec Systems Inc.
- Guardian Fall
- FallTech
- WernerCo.
Competitive Analysis
The Fall Protection Equipment Market is highly competitive, with leading players such as Honeywell International, MSA Safety, Petzl, FallTech, WernerCo., SKYLOTEC, Guardian Fall, W.W. Grainger Inc., and Gravitec Systems Inc. Leading players invest heavily in R&D to develop advanced safety equipment, such as harnesses, lanyards, and self-retracting lifelines, tailored to meet evolving industry standards and regulations. These manufacturers emphasize product durability, comfort, and ease of use to cater to diverse industries, including construction, oil and gas, and manufacturing. The market dynamics are further shaped by partnerships and collaborations to expand geographic reach and strengthen distribution networks. Companies are also leveraging digital technologies, like IoT-enabled fall protection systems, to enhance safety monitoring and compliance. Amid growing regulatory scrutiny and increasing awareness of workplace safety, competitors are diversifying their offerings to include training services and after-sales support, ensuring comprehensive safety solutions. This strategic focus underscores their commitment to addressing end-user needs and maintaining a competitive edge.
Recent Developments
- In January 2024, WernerCo launched a fall protection utility lifeline designed for utility workers and linemen. Featuring an anchor strap fall arrest system, it enhances climbing safety and addresses the unique requirements of professionals working on utility poles and similar structures.
- In December 2023, Guardian Fall announced a partnership with Twiceme Technology to integrate advanced technology into the B7-Comfort Harness, enhancing functionality and safety.
- In March 2023, Petzl introduced the ASAP & ASAP LOCK kits, pre-equipped with connectors, mobile fall arresters, and energy absorbers. Compliant with OSHA and ANSI Z359.15 standards, these kits offer a reliable fall protection solution when paired with RAY 11 lifelines.
- In January 2023, Guardian Fall launched the B7-Comfort Harness, anchor additions, and self-retracting lifelines at World of Concrete 2023. Additionally, the company introduced a tool for customizing harnesses with company-specific colors and logos, improving safety, branding, and visibility.
Market Concentration & Characteristics
The Fall Protection Equipment Market is characterized by moderate concentration, with a mix of established global players and regional companies driving competition. Leading manufacturers dominate the market, particularly in North America and Europe, where stringent safety regulations create a strong demand for fall protection solutions. These companies invest heavily in research and development to enhance product offerings, focusing on innovation, ergonomics, and advanced technologies like IoT-enabled safety gear. While large players such as Honeywell International, and MSA Safety hold substantial market shares, there is room for smaller, specialized companies that cater to niche industries or offer tailored solutions. The market is also marked by high product differentiation, with offerings varying based on industry-specific needs, such as construction, oil and gas, and utilities. Additionally, the focus on safety, compliance with regulatory standards, and technological advancements contribute to the growing market dynamics and the evolution of customer expectations.
Report Coverage
The research report offers an in-depth analysis based on Type, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global Fall Protection Equipment Market is expected to grow steadily due to increased safety awareness and stricter regulations.
- Technological advancements, including IoT-enabled devices and wearable safety gear, will drive market innovation and adoption.
- Growing infrastructure development, particularly in emerging economies, will boost demand for fall protection equipment in construction and manufacturing.
- The market will continue to see an emphasis on ergonomic, lightweight designs to improve worker comfort and compliance.
- Regulations regarding workplace safety, especially in high-risk industries like oil and gas, will lead to increased market penetration.
- The adoption of eco-friendly materials and energy-efficient solutions will align with global sustainability trends in the market.
- Specialized fall protection systems tailored to industry-specific needs, such as for transportation and utilities, will gain traction.
- The increasing focus on comprehensive worker training and certification will be crucial for market growth.
- Advancements in rescue and emergency response equipment will enhance overall safety measures, further driving market expansion.
- Strong competition among global and regional players will lead to further innovation and product differentiation in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Fall Protection Equipment Market?
What factors are driving the growth of the Fall Protection Equipment Market?
What are the key segments within the Fall Protection Equipment Market?
What are some challenges faced by the Fall Protection Equipment Market?
Who are the major players in the Fall Protection Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fall Protection Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fall Protection Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,991.5 million → 2032: USD 7,666.09 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fall Protection Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fall Protection Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fall Protection Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fall Protection Equipment Market Drivers
- 3.3 Fall Protection Equipment Market Restraints & Challenges
- 3.4 Fall Protection Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fall Protection Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fall Protection Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fall Protection Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fall Protection Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Fall Protection Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Fall Protection Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fall Protection Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fall Protection Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Fall Protection Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fall Protection Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Fall Protection Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fall Protection Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Fall Protection Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fall Protection Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fall Protection Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fall Protection Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fall Protection Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fall Protection Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fall Protection Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
