
Market Overview:
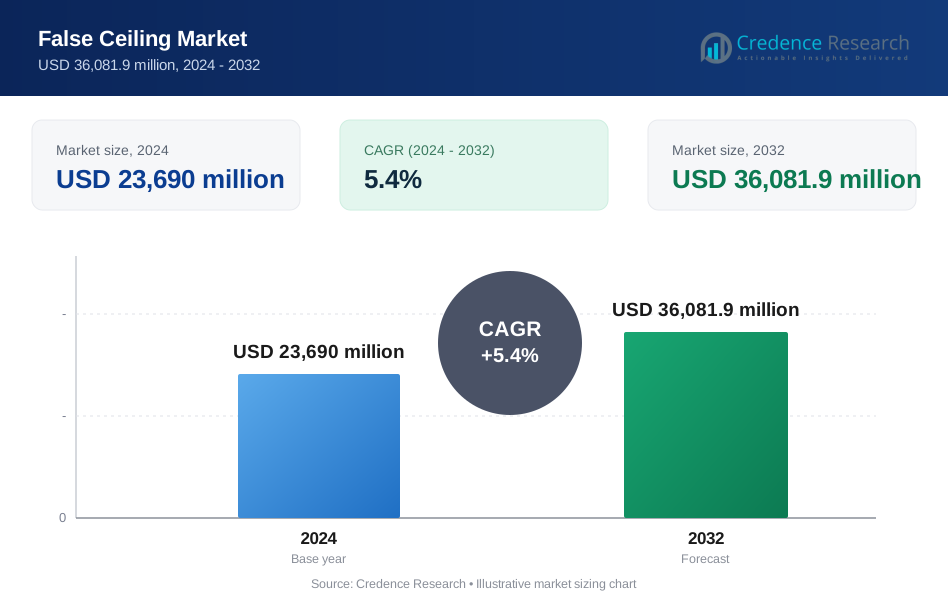
The false ceiling market size was valued at USD 23690 million in 2024 and is anticipated to reach USD 36081.9 million by 2032, at a CAGR of 5.4 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| False Ceiling Market Size 2024 | USD 23690 Million |
| False Ceiling Market, CAGR | 5.4 % |
| False Ceiling Market Size 2032 | USD 36081.9 Million |
Market drivers include the rising construction of office complexes, malls, and high-end residential projects, coupled with growing consumer preference for stylish interiors that improve lighting and insulation. False ceilings provide enhanced energy efficiency by reducing heat load and improving air conditioning performance, making them highly popular in urban developments. Increasing renovation activities and demand for noise reduction in commercial and institutional settings further stimulate adoption. Smart ceilings integrated with lighting and sensors are also emerging as a key growth factor.
Regionally, Asia-Pacific dominates the false ceiling market, fueled by rapid urbanization, infrastructure investments, and rising disposable incomes in countries such as China and India. North America and Europe hold significant shares due to established construction sectors and strong demand for energy-efficient building solutions, while the Middle East shows high potential driven by luxury real estate and hospitality projects.
Market Insights:
- The false ceiling market was valued at USD 23,690 million in 2024 and is projected to reach USD 36,081.9 million by 2032, growing at a CAGR of 4% during 2024–2032.
- Demand is fueled by rising construction of office complexes, malls, and premium residential projects, supported by urbanization and lifestyle upgrades.
- Energy efficiency is a key driver, with false ceilings reducing heat loads, optimizing air circulation, and lowering power consumption for cooling and heating.
- Growing renovation projects and the need for noise reduction in commercial and institutional settings accelerate adoption across developed markets.
- Smart ceilings integrated with lighting, modular systems, and sensors are gaining traction, aligning with the rise of smart buildings and digital infrastructure.
- Asia-Pacific holds 42% market share, led by China and India, while North America accounts for 28% and Europe holds 22%, reflecting regional construction dynamics.
- High installation and maintenance costs and vulnerability to humidity and structural concerns remain challenges, but technological advancements and eco-friendly materials create strong growth opportunities.

Market Drivers:
Rising Demand for Modern Interior Design and Aesthetic Appeal:
The false ceiling market is driven by the increasing emphasis on stylish and functional interiors in both residential and commercial spaces. Consumers prefer ceilings that enhance aesthetics while concealing wiring, ductwork, and structural elements. It provides a clean and modern look, improving the overall appeal of offices, retail outlets, and homes. The demand for customized designs, patterns, and finishes is expanding as architects and interior designers integrate ceilings into broader design concepts.
- For instance, USG Corporation delivered integrated ceiling systems to more than 300 healthcare and educational facilities in 2024, installing over 2 million square feet of acoustic ceiling panels that achieve Class A fire performance ratings while maintaining superior sound absorption properties.
Growing Focus on Energy Efficiency and Thermal Insulation:
Energy-efficient buildings are creating strong demand for false ceilings due to their ability to improve insulation and reduce heat loads. By lowering the room height and optimizing air circulation, it supports reduced energy consumption for cooling and heating. This feature makes false ceilings a preferred choice in urban high-rise constructions and large commercial complexes. Increasing awareness of sustainability and green building certifications further strengthens their adoption.
- For instance, Armstrong's Templok energy saving ceiling panels integrate Phase Change Material technology and can reduce building HVAC energy costs and consumption by up to 15 percent.
Expansion of Commercial Infrastructure and Institutional Projects:
The rapid growth of commercial establishments such as malls, airports, hospitals, and educational institutions fuels the false ceiling market. False ceilings improve acoustic performance and create a comfortable indoor environment for high-traffic spaces. It also enhances the integration of lighting, air conditioning, and fire safety systems, making them essential in large-scale projects. Government-led infrastructure development and corporate investments continue to accelerate demand in this segment.
Technological Advancements and Adoption of Smart Ceilings:
Innovations in materials and design are shaping the future of the false ceiling market, with rising adoption of lightweight, durable, and eco-friendly options. Smart false ceilings equipped with sensors, modular lighting systems, and integrated controls are gaining traction in modern construction. It supports better space utilization and energy management in smart homes and commercial spaces. The combination of advanced technology and sustainability is positioning false ceilings as a critical component of next-generation buildings.
Market Trends:
Increasing Preference for Sustainable and Eco-Friendly Materials:
A major trend shaping the false ceiling market is the rising adoption of sustainable materials such as gypsum boards, mineral fiber, metal, and wood composites that align with green building standards. Developers and consumers are prioritizing eco-friendly options that reduce environmental impact while maintaining durability and functionality. It supports energy efficiency by providing better thermal insulation and contributes to achieving certifications like LEED and BREEAM. Recyclable and low-VOC materials are becoming the norm in both commercial and residential projects. Manufacturers are also innovating with lightweight panels that reduce transportation costs and simplify installation, further driving adoption across regions.
- For instance, Armstrong's ULTIMA Low Embodied Carbon ceiling panels deliver 43 percent reduction in embodied carbon compared to standard mineral fiber acoustical ceilings.
Integration of Smart Features and Growth of Modular Ceiling Systems:
Technological integration is emerging as a key trend, with smart false ceilings equipped with embedded lighting, climate control sensors, and acoustic management systems gaining popularity. The demand for modular and customizable designs is growing, allowing easier installation and flexibility in layout changes. It enables architects and contractors to combine aesthetics with functionality, making ceilings an integral part of modern infrastructure. Acoustic-friendly ceiling tiles are widely used in offices, hospitals, and educational facilities to enhance productivity and comfort. The false ceiling market is also witnessing a shift toward prefabricated solutions that reduce construction time and labor costs. This evolution reflects the move toward intelligent, efficient, and adaptable building systems.
- For instance, Philips Dynalite's DUS360CR-DA ceiling sensor combines motion detection, infrared remote control reception, and ambient light level detection into one device with 360-degree coverage for comprehensive environmental monitoring.
Market Challenges Analysis:
High Installation and Maintenance Costs Limiting Adoption:
One of the major challenges in the false ceiling market is the high cost associated with installation and ongoing maintenance. Premium materials such as metal and wood, along with advanced designs, increase project expenses, making them less affordable for budget-conscious consumers. It also requires skilled labor for proper fitting, which raises costs further in regions with limited expertise. Regular maintenance is necessary to prevent issues like sagging, staining, or damage from moisture, adding to lifecycle expenses. These factors discourage adoption in low- and middle-income residential segments where cost sensitivity is high.
Vulnerability to Environmental Factors and Structural Concerns:
False ceilings face challenges related to durability under varying environmental conditions such as humidity, temperature fluctuations, and water leakage. In tropical regions, moisture seepage can damage materials like gypsum and fiberboard, reducing their lifespan. It also creates safety risks if not properly designed or installed, particularly in large commercial spaces. Concerns about reduced ceiling height and limited structural compatibility with older buildings further restrict market penetration. Strict compliance with building codes and fire safety standards adds complexity for manufacturers and contractors, creating barriers for widespread adoption.
Market Opportunities:
Rising Demand from Smart Cities and Green Building Projects:
The false ceiling market is positioned to benefit from the global push toward smart cities and sustainable construction. Growing investments in energy-efficient buildings create opportunities for ceilings that improve thermal insulation, lighting efficiency, and acoustic comfort. It supports the integration of eco-friendly materials that align with green certifications and environmental regulations. Developers and governments are adopting innovative ceiling solutions in public infrastructure such as airports, metro stations, and educational facilities. Expanding urbanization and demand for modern interiors in residential projects further amplify growth potential.
Expansion of Modular and Customized Ceiling Solutions:
Increasing preference for modular, prefabricated, and customizable ceiling systems opens new avenues for the false ceiling market. These solutions reduce installation time, minimize labor costs, and offer flexibility in design for diverse applications. It enables architects and designers to deliver tailored aesthetics while integrating lighting, HVAC, and safety systems seamlessly. The rising popularity of premium interior finishes in commercial and luxury residential spaces is creating strong demand. Advancements in lightweight materials and digital design tools also allow manufacturers to cater to evolving customer preferences. Growing adoption in emerging economies presents a significant opportunity for long-term expansion.
Market Segmentation Analysis:
By Material:
The false ceiling market is segmented by material into gypsum, mineral fiber, metal, wood, and others. Gypsum dominates due to its cost-effectiveness, smooth finish, and versatility in design applications. Mineral fiber ceilings hold strong demand in offices and institutions for their superior acoustic properties. It also benefits from metal ceilings, which are gaining traction in industrial and commercial projects for their durability and fire resistance. Wood-based false ceilings cater to premium residential and luxury projects, driven by aesthetic appeal and natural finishes.
- For instance, Saint-Gobain introduced its Gyproc Habito board for false ceilings, which supports a load of up to 15 kilograms on a single screw, significantly enhancing functional applications in commercial spaces.
By Installation:
The market is categorized into suspended and non-suspended installations. Suspended false ceilings represent the leading segment, widely used in commercial complexes, airports, malls, and office spaces. It is preferred for concealing wiring, HVAC ducts, and fire safety systems, while also improving energy efficiency. Non-suspended ceilings are growing in demand for smaller residential projects where quick installation and lower cost are priorities. The choice of installation often depends on project scale, design requirements, and budget considerations.
- For instance, Rondo's KEY-LOCK Direct Fix Ceiling System utilizes direct fixing clips that can accommodate suspension depths up to 180mm for residential applications, while Saint-Gobain's Gyproc Grid Ceiling system creates modular grids of 1200mm by 600mm dimensions for streamlined installations
By Application:
The false ceiling market finds application across residential, commercial, and industrial sectors. Commercial projects dominate due to the growing construction of offices, educational institutions, and healthcare facilities that require noise reduction and energy efficiency. It is also expanding in residential spaces with rising demand for modern interiors and customized designs. Industrial applications focus on functional benefits such as durability and integration of utility systems. Growth in each segment is influenced by urbanization, lifestyle upgrades, and technological integration in construction.
Segmentations:
By Material:
- Gypsum
- Mineral Fiber
- Metal
- Wood
- Others
By Installation:
- Suspended
- Non-Suspended
By Application:
- Residential
- Commercial
- Industrial
By Region:
- Asia-Pacific
- North America
- Europe
- Middle East & Africa
- Latin America
Regional Analysis:
Asia-Pacific :
Asia-Pacific holds the largest market share of the false ceiling market at 42%, supported by rapid urbanization, infrastructure development, and rising disposable incomes. Countries such as China, India, and Japan are witnessing strong demand from residential and commercial construction projects. It benefits from large-scale government investments in smart cities and sustainable building initiatives. The growing popularity of modern interiors in high-rise apartments and office complexes further fuels adoption. Expanding retail, hospitality, and healthcare sectors also drive installations of energy-efficient and acoustic ceiling systems. Local manufacturers offering cost-effective solutions enhance market penetration in this region.
North America :
North America accounts for 28% market share in the false ceiling market, backed by advanced construction practices and strong demand for renovation projects. The United States leads adoption with rising preference for energy-efficient interiors and integration of smart ceiling technologies. It is driven by consumer focus on sustainability and the use of recyclable materials in residential and commercial buildings. The presence of global and regional players fosters innovation and enhances product availability. Growth in office renovations, educational institutions, and healthcare facilities supports demand for acoustic and modular ceiling systems. Regulatory frameworks promoting green buildings further strengthen the regional outlook.
Europe :
Europe commands 22% market share of the false ceiling market, reinforced by stringent environmental regulations and growing adoption of eco-friendly materials. Countries such as Germany, the United Kingdom, and France are at the forefront of sustainable construction trends. It benefits from high consumer awareness and established infrastructure in commercial and public buildings. Renovation of historical structures and modern office complexes creates steady demand for ceiling solutions. Acoustic-friendly and thermally efficient systems are particularly sought after in educational and corporate facilities. Government emphasis on reducing carbon footprints and achieving energy efficiency goals ensures long-term growth in the region.
Key Player Analysis:
- Armstrong World Industries, Inc.
- Saint-Gobain S.A.
- USG Corporation
- Knauf Gips KG
- Hunter Douglas N.V.
- Rockfon (ROCKWOOL International A/S)
- Odenwald Faserplattenwerk GmbH (OWA)
- SAS International Ltd.
- Georgia-Pacific LLC
- Burgess CEP
- Gypsemna
- Everest Industries Ltd.
Competitive Analysis:
The false ceiling market is moderately competitive, with global players focusing on innovation, sustainability, and expansion strategies. Key companies include Armstrong World Industries, Inc., Saint-Gobain S.A., USG Corporation, Knauf Gips KG, Hunter Douglas N.V., Rockfon (ROCKWOOL International A/S), Odenwald Faserplattenwerk GmbH (OWA), and SAS International Ltd. It is characterized by product differentiation, where leading firms invest in eco-friendly materials, acoustic solutions, and modular ceiling systems to cater to diverse applications. Partnerships with construction firms and distributors help strengthen market presence across developed and emerging regions. Companies emphasize R&D to integrate smart technologies and lightweight materials, enhancing energy efficiency and design flexibility. Competition also intensifies through acquisitions and regional expansions, as firms seek to capture growing demand from commercial and residential sectors. The focus on sustainable construction practices and premium interior solutions positions established players to maintain leadership while creating opportunities for regional entrants.
Recent Developments:
- In February 2024, Armstrong World Industries acquired BŌK Modern, a designer of integrated architectural metal systems, and the Templok business from Insolcorp, expanding Armstrong's portfolio in metal and phase change material ceiling products.
- In July 2025, Saint-Gobain S.A. announced the acquisition of Interstar Materials Inc., a North American leader in granular pigment systems for concrete, strengthening its construction chemicals portfolio in the US and Canada and adding three production facilities to its operations.
- In April 2025, Knauf North America launched the Performance+® Pipe & Tank Insulation, expanding its Performance+® product lineup with a new formaldehyde-free solution for thermal and acoustical fiberglass insulation applications.
Market Concentration & Characteristics:
The false ceiling market exhibits moderate concentration, with a mix of global players and regional manufacturers competing on design innovation, material quality, and pricing strategies. It is characterized by the growing adoption of sustainable materials, modular systems, and advanced acoustic solutions tailored for residential, commercial, and institutional projects. Large players focus on R&D, brand positioning, and partnerships with construction firms, while regional companies cater to cost-sensitive markets with localized offerings. The market reflects steady demand from infrastructure development, renovation activities, and smart building initiatives, creating opportunities for differentiation through eco-friendly, customizable, and technology-integrated ceiling solutions.
Report Coverage:
The research report offers an in-depth analysis based on Material, Installation, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The false ceiling market will witness rising demand from smart cities and modern infrastructure projects worldwide.
- Sustainability will remain a priority, with manufacturers focusing on recyclable, low-VOC, and eco-friendly materials.
- Energy-efficient ceiling systems that improve thermal performance and reduce power consumption will gain wider adoption.
- Smart ceilings integrated with sensors, modular lighting, and climate control features will see strong growth in commercial and residential spaces.
- Acoustic-friendly ceiling panels will experience increasing demand from offices, hospitals, and educational institutions to enhance productivity and comfort.
- Prefabricated and modular false ceilings will expand due to their faster installation, lower labor requirements, and cost efficiency.
- Growing disposable incomes in emerging economies will drive demand for premium and aesthetic ceiling solutions in luxury housing projects.
- Renovation activities across developed regions will fuel replacement demand for advanced and durable ceiling systems.
- Strategic collaborations between manufacturers, architects, and real estate developers will accelerate product innovation and market penetration.
- The market will continue to evolve with digital design tools, offering customized patterns and layouts to meet diverse consumer preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Commercial Infrastructure
Rapid construction of office complexes, malls, airports, and institutional buildings is driving demand for false ceilings, which offer acoustic control, energy efficiency, and integration of lighting and HVAC systems in large-scale projects.
Focus on Energy Efficiency and Thermal Insulation
False ceilings help reduce heat loads and optimize air circulation, supporting lower energy consumption for cooling and heating, which is increasingly important in urban high-rise and green building projects.
Rising Demand for Modern Interior Design
Consumers and developers are prioritizing stylish, functional interiors that conceal wiring and ductwork, with false ceilings providing customizable designs and finishes that enhance the aesthetic appeal of residential and commercial spaces.
Technological Advancements and Smart Ceilings
Innovations such as smart ceilings with integrated lighting, sensors, and modular systems are gaining traction, supporting the trend toward smart buildings and enabling better space utilization and energy management.
Growth in Renovation and Retrofit Activities
Increasing renovation of existing buildings, especially in developed markets, is fueling replacement demand for advanced, durable, and acoustic-friendly false ceiling systems that improve comfort and building performance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the false ceiling market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the false ceiling market projected to grow between 2024 and 2032?
Which false ceiling market segment held the largest share in 2024?
What are the primary factors fueling the growth of the false ceiling market?
Who are the leading companies in the false ceiling market?
Which region commanded the largest share of the false ceiling market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Gypsum
- 1.2.2 Mineral Fiber
- 1.2.3 Metal
- 1.2.4 Wood
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Industrial
- 1.4 By Installation
- 1.4.1 Suspended
- 1.4.2 Non-Suspended
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23,690 million → 2032: USD 36,081.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global False Ceiling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global False Ceiling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global False Ceiling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global False Ceiling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global False Ceiling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global False Ceiling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global False Ceiling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global False Ceiling Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23,690 million → 2032: USD 36,081.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global False Ceiling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gypsum
- 12.3.7.2 Mineral Fiber
- 12.3.7.3 Metal
- 12.3.7.4 Wood
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Industrial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Installation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Suspended
- 12.5.7.2 Non-Suspended
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global False Ceiling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global False Ceiling Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global False Ceiling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global False Ceiling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Armstrong World Industries, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Saint-Gobain S.A.
- 18.4 USG Corporation
- 18.5 Knauf Gips KG
- 18.6 Hunter Douglas N.V.
- 18.7 Rockfon (ROCKWOOL International A/S)
- 18.8 Odenwald Faserplattenwerk GmbH (OWA)
- 18.9 SAS International Ltd.
- 18.10 Georgia-Pacific LLC
- 18.11 Everest Industries Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

