
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| K-Beauty Product Market Size 2023 | USD 14,123.95 Million |
| K-Beauty Product Market, CAGR | 7.90% |
| K-Beauty Product Market Size 2032 | USD 27,999.43 Million |
Market Overview
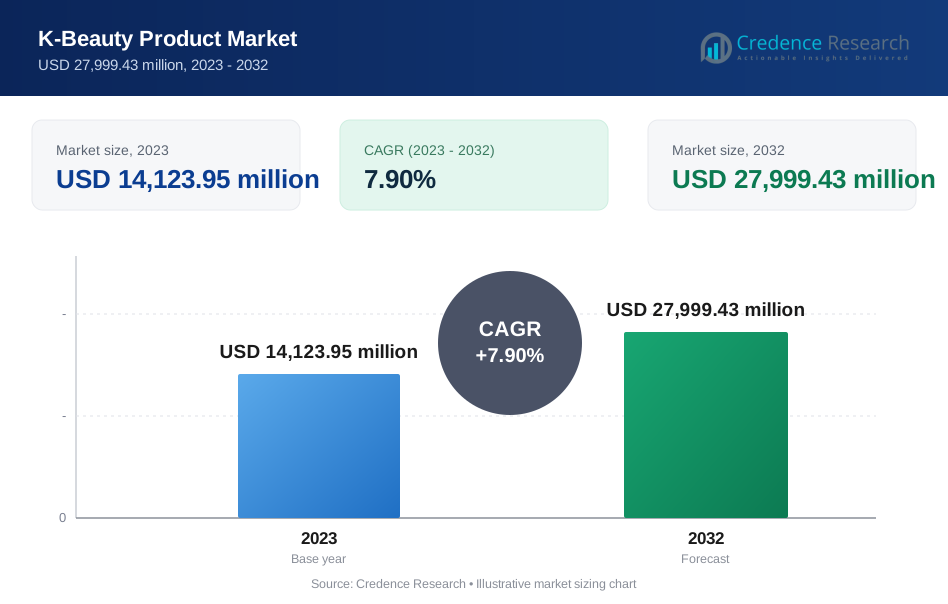
The K-Beauty Product Market is projected to grow from USD 14,123.95 million in 2023 to an estimated USD 27,999.43 million by 2032, registering a compound annual growth rate (CAGR) of 7.90% from 2024 to 2032.
This substantial growth is driven by the increasing popularity of innovative skincare and cosmetic solutions that emphasize natural ingredients, advanced formulations, and unique product offerings.
Key drivers for the market include the growing awareness of skincare and personal grooming, the rising preference for organic and cruelty-free products, and the increasing adoption of K-beauty routines among younger consumers worldwide. Emerging trends, such as the integration of sustainable practices and eco-friendly packaging, are reshaping the market landscape. Additionally, technological advancements in product formulations, including the use of fermented ingredients and skin microbiome care, are attracting a wider audience, enhancing product demand.
Geographically, the Asia-Pacific region dominates the market, led by South Korea's innovative beauty industry, which sets global standards for trends and product launches. North America and Europe are witnessing significant adoption of K-beauty products, supported by an expanding distribution network and rising consumer awareness. Key players in the market include AmorePacific Corporation, LG Household & Health Care, The Face Shop, Innisfree, and COSRX, among others, who continue to drive market growth through product innovation and strategic partnerships.
Market Insights
- The Global K-Beauty product market is projected to expand from USD 14,123.95 million in 2023 to USD 27,999.43 million by 2032, achieving a compound annual growth rate (CAGR) of 7.90%.
- Increasing consumer demand for innovative skincare and cosmetic solutions, emphasizing natural ingredients and advanced formulations, is a primary driver of market growth.
- The global popularity of K-pop culture significantly boosts the adoption of K-Beauty products, as fans seek to emulate the beauty standards promoted by their favorite idols.
- Rising consumer preference for organic, cruelty-free, and sustainable beauty products propels the demand for K-Beauty brands that prioritize ethical and eco-friendly practices.
- Technological innovations, including the use of fermented ingredients and skin microbiome care, enhance product efficacy and attract a broader consumer base.
- The Asia-Pacific region leads the Global K-Beauty market with a 45% share, driven by South Korea's pioneering beauty industry and strong consumer bases in China, Japan, and Southeast Asia.
- North America and Europe hold substantial market shares of 25% and 20% respectively, supported by expanding distribution networks, increasing consumer awareness, and the integration of K-Beauty trends into mainstream beauty routines.
Market Drivers
Increasing Consumer Focus on Skincare and Personal Grooming
Rising awareness of skin health-shaped by concerns around pollution, lifestyle stress, and visible signs of aging-has pushed more consumers toward structured, results-led skincare routines. K-beauty benefits from this shift because its category DNA is built around routine-led usage, where cleansing, hydration, targeted treatment, and protection work together across multiple steps rather than a single “hero” product. This routine mindset supports higher purchase frequency and encourages consumers to add specialized formats such as sheet masks, essences, and ampoules to address specific concerns while maintaining overall skin balance.
The broader move toward self-care and preventive skincare further reinforces demand for products positioned around long-term skin maintenance instead of quick fixes. In parallel, rising disposable incomes in developing markets are expanding the addressable base for premium and performance-driven skincare, reflecting a wider global preference for clinically positioned solutions-illustrated by L’Oréal reporting 9.8% like-for-like growth in 2024 in its Dermatological Beauty division.
Adoption of Innovative and Natural Ingredients
K-beauty’s global traction is closely linked to its pace of formulation innovation and its ability to turn distinctive ingredients into mainstream demand drivers. Brands frequently differentiate through advanced actives and textures ranging from fermented ingredients and probiotics to snail mucin often packaged into gentle, layerable products that fit multi-step routines.
At the same time, the market is aligning more closely with clean beauty expectations, with greater emphasis on ingredient transparency, cruelty-free positioning, and skin-friendly formulations that appeal to sensitive-skin consumers. Sustainability is reinforcing this momentum through growing interest in eco-friendly packaging and ethically sourced inputs, which strengthens brand loyalty and supports premium pricing where credibility is high. This direction is consistent with global consumer intent signals: a YouGov study across 17 markets found 54% of consumers planned to buy more sustainable products.
Influence of Korean Culture and Globalization
The international reach of K-pop, K-dramas, and Korean fashion has created a powerful cultural pipeline that continuously introduces K-beauty routines, looks, and product formats to new audiences. Celebrity influence and fan-driven discovery have made it easier for K-beauty trends-such as “glass skin”-to move quickly from content to commerce, especially as tutorials and product reviews circulate across social platforms. As awareness builds, brands have expanded access through local distribution partnerships and cross-border e-commerce, turning cultural visibility into repeatable retail demand in North America, Europe, and Southeast Asia. South Korea’s export performance underscores how strongly this cultural-commercial flywheel is working at scale, with cosmetics exports reported at USD 10.2 billion in 2024, ranking third worldwide.
Rise in E-commerce Penetration and Digital Marketing
E-commerce has become a structural growth engine for K-beauty by removing geographic barriers and making product discovery frictionless. Online channels allow consumers to compare ingredients, watch routine demonstrations, and purchase curated bundles-behaviors that naturally support multi-step regimens and increase basket size.
Brands are also leveraging influencer partnerships, short-form video, and personalized recommendations to convert attention into sales, particularly among younger buyers who prefer research-led purchases and rapid trend adoption. As online retail ecosystems expand, K-beauty gains a scalable route to international growth without relying solely on physical store footprints. The size of the broader digital commerce runway remains substantial: UN Trade and Development estimates business e-commerce sales approached USD 25 trillion in 2021 and were estimated to rise to almost USD 27 trillion in 2022, highlighting the scale of the channels that help consumers discover and buy K-beauty globally.
Market Trends
Emphasis on Sustainable and Eco-Friendly Products
Sustainability is becoming a stronger purchase filter in K-beauty as consumers weigh packaging waste, ingredient sourcing, and ethical brand practices alongside performance. This shift is pushing brands to redesign packs around recyclable or refillable formats, reduce secondary packaging, and spotlight responsibly sourced ingredients that support “clean beauty” expectations. Several Korean brands are reinforcing this positioning through minimal-packaging approaches, cruelty-free claims, and take-back or recycling initiatives, which helps convert sustainability from a marketing message into a visible product experience.
Demand is strongest among Millennials and Gen Z shoppers, who increasingly link beauty routines with personal values and are more likely to reward brands that demonstrate measurable environmental intent. As a result, sustainability is evolving into both a differentiator and a retention lever, supporting premiumization and repeat purchase when eco-friendly claims align with product efficacy.
Rise of Personalized Skincare Solutions
Personalization is reshaping K-beauty’s growth pathway by making routine building more targeted and less trial-and-error for consumers. Brands are increasingly using digital diagnostics, skin-analysis tools, and AI-driven recommendations to match products to individual skin type, sensitivity, and goals, which improves perceived effectiveness and encourages longer regimen adherence.
Customized solutions such as made-to-order boosters or tailored serum combinations also deepen engagement by turning skincare into an interactive, guided experience rather than a standard shelf purchase. This dynamic strengthens brand loyalty because consumers who see improved outcomes are more likely to repurchase within the same ecosystem and add adjacent steps over time. In a crowded market where product launches are frequent, personalization helps brands stand out by shifting the value proposition from “new” to “made for me.”
Focus on Multi-Functional and Minimalist Products
While K-beauty is known for multi-step routines, changing lifestyles are accelerating demand for simplified regimens that still deliver results. Multi-functional products-combining benefits such as hydration, barrier support, brightening, and SPF-are gaining traction because they reduce the time and complexity of daily routines without abandoning performance expectations. Minimalist formulas also appeal to consumers who prefer fewer ingredients, lower irritation risk, and clearer product purpose, particularly as sensitive-skin claims become more mainstream. This trend supports market expansion in two ways: it brings in time-constrained users who might not adopt full routines, and it increases conversion by making regimen entry easier. It also aligns with sustainability preferences, since fewer products can translate into less packaging and reduced wastage.
Integration of Innovative Ingredients and Technologies
Innovation remains a core engine of K-beauty demand, with brands continuously refreshing product excitement through distinctive ingredients and delivery formats. Soothing and repair-focused actives such as Centella Asiatica (cica), mugwort, snail mucin, probiotics, and fermented extracts are widely used to address barrier stress, hydration, and sensitivity-concerns that have become more prominent in modern skincare routines. At the same time, formulation and packaging technologies are elevating user experience and performance, seen in advanced mask formats (e.g., hydrogel and sculpted sheet masks) and improved delivery systems designed to enhance absorption and wear comfort. Many brands are also using data-driven insights to track emerging preferences and accelerate concept-to-launch cycles, which helps them stay ahead of fast-moving global trends. Together, ingredient novelty plus technology-led performance supports premium pricing, frequent new-product adoption, and sustained international interest in K-beauty innovation.
Market Challenges
Intense Market Competition
The K-beauty market is characterized by fierce competition, both domestically and internationally. Numerous well-established companies like Cosrx, Laneige, and Innisfree have solidified their positions, while new entrants continuously emerge, striving to capture consumer attention with innovative products and competitive pricing. This influx of brands has led to market saturation, making it increasingly challenging for companies to differentiate themselves amid a plethora of similar offerings. Additionally, the prevalence of counterfeit products in online marketplaces poses a significant threat.
These low-cost imitations not only dilute the market but also undermine consumer trust in authentic K-beauty brands. As a response, companies must prioritize brand authenticity and invest in robust marketing strategies to maintain their competitive edge. This includes enhancing product quality, leveraging unique selling propositions, and engaging with consumers through effective storytelling. By focusing on innovation and authenticity, K-beauty brands can navigate the intense competition and continue to thrive in a crowded marketplace.
Complexities of Global Regulatory Compliance
Expanding into international markets presents significant regulatory hurdles for K-beauty brands. Different countries have unique cosmetic regulations, including ingredient restrictions, labeling requirements, and product testing standards. For instance, while South Korea allows certain traditional ingredients in cosmetics, these same ingredients may face restrictions or require additional certifications in regions such as the European Union or the United States. Adapting to these diverse regulations necessitates substantial investment in research and product reformulation to ensure compliance.
Non-compliance can result in product recalls, reputational damage, and financial losses, making it imperative for brands to navigate these complexities carefully. Furthermore, the growing demand for cruelty-free and vegan certifications adds another layer of complexity for brands aiming to cater to ethical consumer preferences. To succeed in global markets, K-beauty brands must not only meet regulatory requirements but also align their products with evolving consumer values and expectations. This strategic approach will enable them to establish a strong presence across diverse markets while maintaining their commitment to quality and ethical practices.
Market Opportunities
Rising Demand for Customized Skincare Solutions
The growing consumer inclination toward personalized skincare represents a substantial opportunity for K-beauty brands. With advancements in artificial intelligence (AI) and skin analysis technologies, brands can now offer tailored product recommendations and formulations based on individual skin types and concerns. For instance, many K-beauty brands leverage these technologies to provide personalized serums designed to target specific issues like dark spots and wrinkles. This shift towards customization not only enhances user satisfaction but also fosters long-term brand loyalty by addressing specific needs that generic products often fail to meet.
Additionally, the demand for products catering to niche concerns, such as anti-pollution, blue light protection, and microbiome care, is on the rise. K-beauty’s reputation for innovation positions it well to capture this segment by introducing unique, science-backed solutions. As consumers increasingly seek products that align with their individual skincare journeys, K-beauty brands are well-equipped to lead the charge in delivering customized experiences that resonate deeply with their audience. By focusing on personalization and niche solutions, these brands can effectively differentiate themselves in a competitive market, ensuring sustained growth and consumer engagement.
Untapped Potential in Emerging Markets
Emerging markets in regions such as Southeast Asia, Latin America, and the Middle East offer untapped opportunities for K-beauty brands. These regions are experiencing increasing urbanization and rising disposable incomes, leading to a growing interest in premium beauty products. For instance, countries in Southeast Asia have seen a notable increase in online beauty shopping, driven by a tech-savvy population eager to explore global beauty trends. By leveraging strategic partnerships with local distributors and e-commerce platforms, K-beauty brands can establish a strong foothold in these markets.
Moreover, targeted marketing campaigns that highlight the cultural appeal of K-beauty’s holistic approach to skincare can resonate deeply with consumers in these regions. By emphasizing the benefits of natural ingredients and innovative formulations, K-beauty brands can effectively engage local audiences and drive adoption. As these markets continue to grow, the potential for K-beauty brands is significant; by aligning their offerings with local preferences and leveraging digital channels, they can tap into a burgeoning consumer base eager for high-quality skincare solutions.
Market Segmentation Analysis
By Type
The global K-beauty product market is segmented into sheet masks, cleansers, moisturizers, and others, with each category supporting overall market growth. Sheet masks remain a signature K-beauty format due to their convenience, product variety, and quick, visible skin benefits, with demand reinforced by ongoing innovation in fabrics and active ingredients. Cleansers account for a meaningful share as consumers adopt more structured skincare routines, supported by product advances such as oil-based and foam cleanser variants tailored to different skin types and use preferences.
Moisturizers continue to be a core category, offering formulations focused on hydration, anti-aging, and skin-barrier support, while interest in lightweight and multi-functional products is rising. The “others” segment-including serums, essences, sunscreens, and specialized treatments-adds depth to skincare regimens by addressing targeted concerns, helping expand usage occasions and product adoption across consumer groups.
By Application
K-beauty products are widely used across daily skincare routines, with applications centered on cleansing, hydration and moisturization, nourishment and repair, sun protection, and targeted skin concerns such as acne care, brightening, anti-aging, and sensitivity management. Usage is influenced by routine layering practices and demand for personalized outcomes, which supports repeat purchases and cross-category adoption (e.g., cleanser + serum/essence + moisturizer + sunscreen).
Segments
Based on Type
- Sheet Masks
- Cleansers
- Moisturizers
- Others
Based on Application
- Beauty Business
- Personal
- Others
Based on End User
- Male
- Female
- Children and Teenage
Based on Distribution Channel
- Online Retail
- Supermarket/Hypermarket
- Specialty/Monobrand Stores
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia Pacific (45%)
Asia Pacific dominates the Global K-Beauty market with a substantial 45% share, primarily driven by South Korea, China, Japan, and Southeast Asian countries. South Korea remains the epicenter of K-Beauty innovation, continuously introducing cutting-edge products and setting global beauty trends. The region’s cultural affinity for skincare and beauty, coupled with rapid urbanization and increasing disposable incomes, fuels robust demand. Additionally, the widespread adoption of digital platforms and social media in Asia Pacific enhances brand visibility and consumer engagement, further solidifying the region’s leadership in the K-Beauty market.
North America (25%)
North America holds a significant 25% share of the Global K-Beauty market, propelled by growing consumer interest in high-quality and innovative skincare products. The presence of a large, diverse population and the influence of social media and beauty influencers contribute to the region’s strong market growth. Consumers in North America are increasingly seeking personalized and effective beauty solutions, aligning well with K-Beauty’s emphasis on advanced formulations and multi-step skincare routines. Moreover, the expansion of e-commerce and the availability of K-Beauty products through major retailers and specialty stores enhance accessibility and drive sales in this region.
Key players
- Able C & C Ltd
- Adwin Korea Corporation
- Amorepacific Corporation
- CLIO COSMETICS Co. Ltd
- Cosrx Inc
- LG H&H Co. Ltd. (LG Corporation)
- The Crème Shop Inc
- The Face Shop Inc
- Tonymoly Co. Ltd
Competitive Analysis
The Global K-Beauty product market is highly competitive, featuring a blend of established industry leaders and innovative niche brands. Amorepacific Corporation and LG H&H Co. Ltd. dominate the market with their extensive product portfolios, strong brand recognition, and significant investment in research and development. These giants leverage their advanced technologies and comprehensive marketing strategies to maintain their leading positions. Cosrx Inc and The Face Shop Inc compete effectively by focusing on targeted skincare solutions and maintaining a loyal customer base through robust social media engagement and influencer partnerships.
Emerging brands like CLIO COSMETICS Co. Ltd and Tonymoly Co. Ltd differentiate themselves with unique product offerings and vibrant packaging, appealing to younger demographics. Able C & C Ltd and Adwin Korea Corporation enhance their competitive edge by emphasizing natural ingredients and sustainable practices, catering to the increasing demand for clean beauty products. Additionally, The Crème Shop Inc utilizes strategic retail placements and omnichannel distribution to maximize market presence.
The competitive landscape is further intensified by continuous innovation, frequent product launches, and the ability to swiftly adapt to changing consumer preferences, ensuring that K-Beauty remains a dynamic and resilient segment within the global beauty industry. This intensity is reinforced by South Korea’s government-reported cosmetics exports of USD 10.2 billion in 2024, ranking third worldwide and signaling a large, globally contested arena that rewards both scale players and fast-moving specialists..
Recent Developments
- In January 2026, Goodai Global acquired Serin Company and its K-beauty brand Round Lab, adding another globally popular skincare franchise into its acquisition-led portfolio.
- In January 2026, LANEIGE launched its JuicePop Box Lip Tint line and announced KATSEYE as a global partner for the product campaign, with the collection slated for rollout across major global-facing retail channels including Sephora.
- In December 2025, CJ Olive Young announced it will open its first U.S. brick-and-mortar stores in Pasadena and at Westfield Century City (Los Angeles area) in May 2026, while building U.S. logistics/sourcing capabilities and finalizing a broad brand assortment for the launch.
- In November 2025, Goodai Global acquired K-beauty heritage brand Skinfood, continuing its “house of brands” expansion that aggregates and scales Korean beauty brands internationally.
Market Concentration and Characteristics
The Global K-Beauty product market exhibits a moderately concentrated structure, dominated by a few key players such as Amorepacific Corporation, LG H&H Co. Ltd., and Cosrx Inc, which collectively hold a significant market share through extensive product portfolios and strong brand recognition. These industry leaders leverage advanced research and development capabilities, innovative formulations, and strategic marketing initiatives to maintain their dominant positions.
Additionally, the market is characterized by a high degree of innovation, with continuous introductions of cutting-edge skincare technologies and unique ingredients that cater to diverse consumer preferences. Emerging niche brands also contribute to the competitive landscape by offering specialized products and vibrant packaging, appealing to younger and trend-conscious demographics. Sustainability and clean beauty practices are increasingly prominent, reflecting the growing global consumer demand for environmentally friendly and ethically produced cosmetics.
The integration of digital transformation, including robust e-commerce platforms and influencer-driven marketing, further enhances market accessibility and consumer engagement. Moreover, regional variations in consumer behavior and regulatory environments necessitate localized strategies, fostering a dynamic and resilient market environment. Overall, the Global K-Beauty product market is defined by its blend of established industry giants and innovative newcomers, driving sustained growth and adaptability in response to evolving beauty trends and consumer needs.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global K-Beauty market is projected to maintain a robust growth trajectory, driven by increasing global consumer interest in innovative and high-quality skincare solutions. This sustained expansion is expected to be supported by rising disposable incomes and expanding middle-class populations in emerging markets.
- K-Beauty brands will continue to prioritize product innovation, introducing advanced formulations and novel ingredients to meet diverse consumer needs. Innovations such as bioactive compounds and multifunctional products will further differentiate K-Beauty offerings in the competitive beauty landscape.
- The demand for clean and sustainable beauty products will intensify, with K-Beauty brands increasingly adopting eco-friendly packaging and ethically sourced ingredients. Sustainability initiatives will become a key differentiator, aligning with the growing global emphasis on environmental responsibility.
- K-Beauty brands will expand their presence in emerging markets across Latin America, the Middle East, and Africa, tapping into new consumer bases and leveraging localized marketing strategies. This geographical diversification will drive significant market growth and enhance global brand recognition.
- Personalized skincare solutions will gain prominence, with brands utilizing data analytics and artificial intelligence to offer tailored products and recommendations. Customization will cater to individual skincare needs, enhancing consumer satisfaction and loyalty.
- The male grooming segment will experience substantial growth as more men embrace skincare and beauty routines. K-Beauty brands will develop specialized products targeting male consumers, addressing specific skin concerns and preferences.
- The integration of advanced technologies such as augmented reality (AR) for virtual try-ons and AI-driven skin analysis tools will enhance the consumer shopping experience. These technologies will facilitate informed purchasing decisions and increase online engagement.
- E-commerce will continue to play a pivotal role in the distribution of K-Beauty products, with brands investing in robust online platforms and seamless user experiences. Enhanced digital marketing strategies and efficient logistics will support the growth of online sales channels.
- K-Beauty brands will form strategic partnerships with local retailers, beauty influencers, and digital platforms to strengthen their market presence. Collaborations will enhance brand visibility, credibility, and consumer trust in diverse regions.
- K-Beauty brands will need to stay abreast of evolving regulatory standards across different regions to ensure compliance and maintain market access. Proactive adaptation to regulatory changes will be crucial for sustaining growth and avoiding potential legal challenges.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumer Focus on Skincare and Personal Grooming
Consumers are adopting structured, multi-step skincare routines to address concerns like pollution, stress, and aging, which aligns with K-Beauty’s routine-led approach and drives higher product adoption and purchase frequency.
Adoption of Innovative and Natural Ingredients
K-Beauty brands differentiate through advanced actives, unique textures, and natural ingredients such as fermented extracts and snail mucin, appealing to consumers seeking gentle, effective, and clean beauty solutions.
Influence of Korean Culture and Globalization
The global popularity of K-pop, K-dramas, and Korean fashion has amplified awareness and desirability of K-Beauty products, with social media and celebrity endorsements accelerating international adoption.
Rise in E-commerce Penetration and Digital Marketing
Online channels and influencer-driven marketing have made K-Beauty products more accessible worldwide, supporting rapid trend adoption and enabling brands to reach new consumer segments without heavy reliance on physical retail.
Emphasis on Sustainable and Eco-Friendly Products
Growing consumer demand for sustainability is pushing K-Beauty brands to innovate with recyclable packaging and ethically sourced ingredients, strengthening brand loyalty and supporting premium positioning.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Global K-Beauty product market in 2023 and 2032, and what is the expected CAGR?
What are the primary drivers of growth in the Global K-Beauty product market?
How are technological advancements influencing the Global K-Beauty product market?
Which regions are leading the Global K-Beauty product market and why?
Who are the key players in the Global K-Beauty product market, and how are they driving growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sheet Masks
- 1.2.2 Cleansers
- 1.2.3 Moisturizers
- 1.2.4 Others
- 1.3 By End User
- 1.3.1 Male
- 1.3.2 Female
- 1.3.3 Children and Teenage
- 1.4 By Application
- 1.4.1 Beauty Business
- 1.4.2 Personal
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 14,123.95 million → 2032: USD 27,999.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global K-Beauty Product Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global K-Beauty Product Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global K-Beauty Product Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global K-Beauty Product Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global K-Beauty Product Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global K-Beauty Product Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global K-Beauty Product Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global K-Beauty Product Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 14,123.95 million → 2032: USD 27,999.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global K-Beauty Product Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sheet Masks
- 12.3.7.2 Cleansers
- 12.3.7.3 Moisturizers
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Male
- 12.4.7.2 Female
- 12.4.7.3 Children and Teenage
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Beauty Business
- 12.5.7.2 Personal
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global K-Beauty Product End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global K-Beauty Product Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global K-Beauty Product Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global K-Beauty Product Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amorepacific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Household & Health Care
- 18.4 Cosrx Inc
- 18.5 The Face Shop Inc
- 18.6 Tonymoly Co. Ltd
- 18.7 CLIO COSMETICS Co. Ltd
- 18.8 Able C & C Ltd
- 18.9 Adwin Korea Corporation
- 18.10 The Crème Shop Inc
- 18.11 Innisfree
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

