
Hot and cold circuits move from spas to city studios
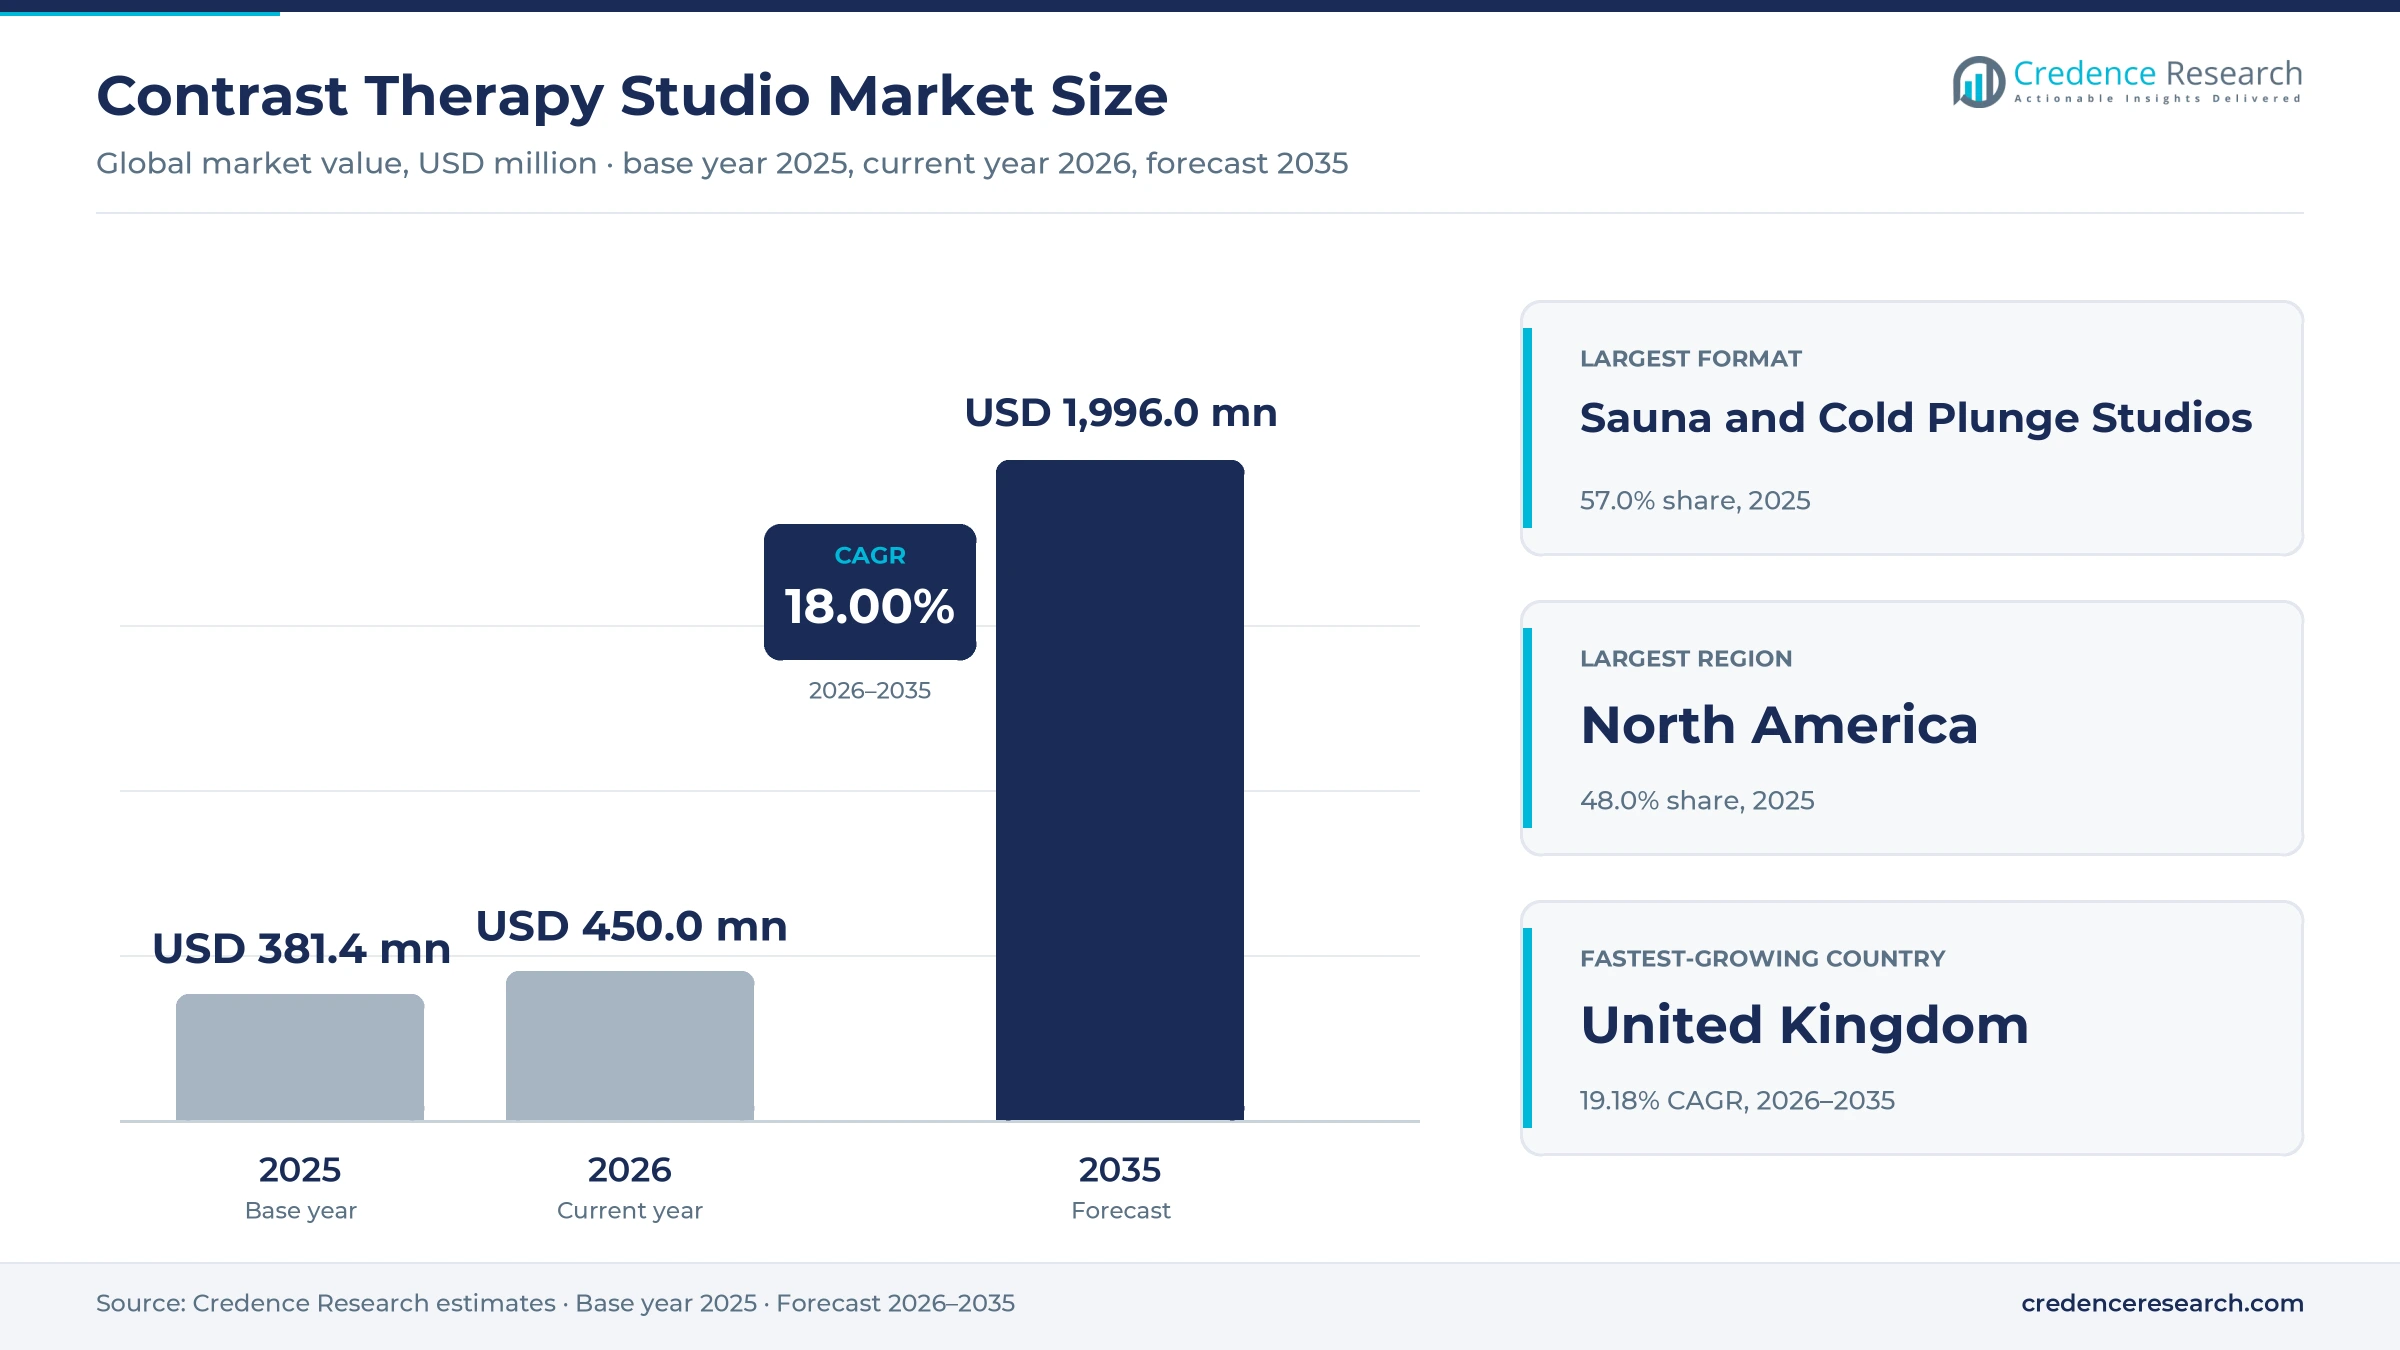
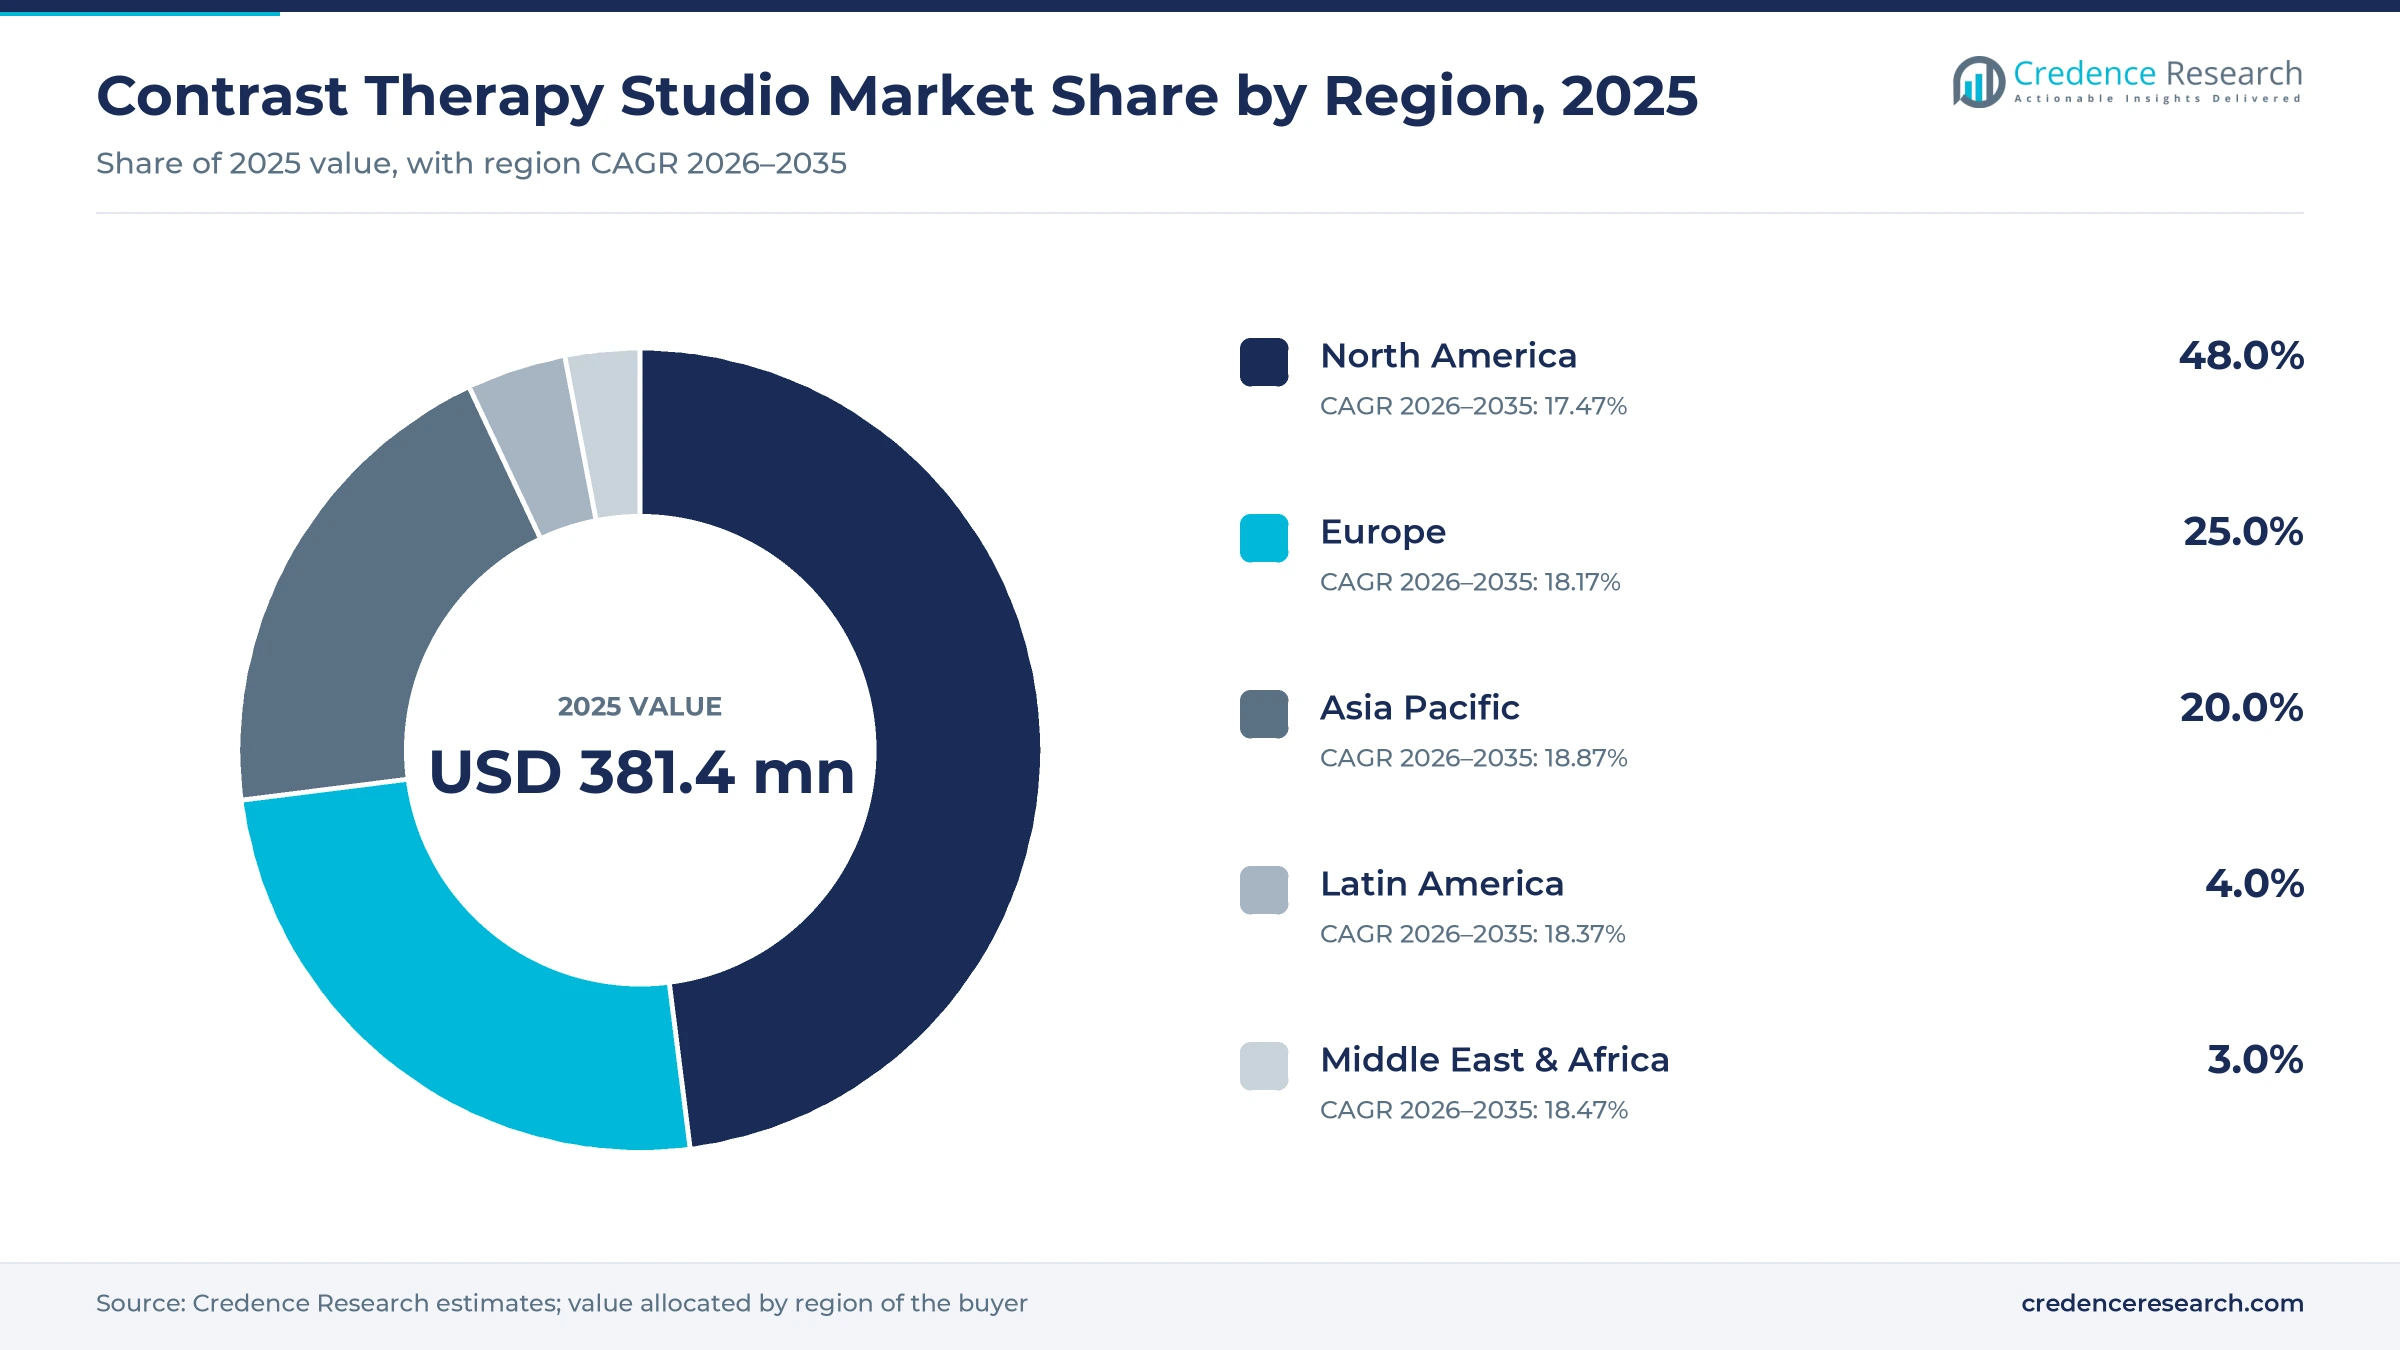
The global contrast therapy studio market was valued at USD 381.4 million in 2025 and is projected to increase from USD 450.0 million in 2026 to USD 2.00 billion by 2035, registering a CAGR of 18.00% during 2026–2035. Demand comes from adults who pay for sauna and cold plunge circuits as a recovery routine and as a social night out, either through monthly memberships or single-visit passes. North America held the largest regional share, 48.0% in 2025, because SWTHZ and Perspire Sauna Studio each passed 100 U.S. locations in 2026 and New York hosts the largest social bathhouses. Europe ranks second, led by a U.K. sauna scene that the British Sauna Society counted at 640 saunas in March 2026. Asia Pacific is the fastest-growing region at 18.87% a year, as Australian operators such as Alchemy Saunas and Soak Bathhouse add new sites. The main commercial change is scale, because venture-backed bathhouses now plan multi-city rollouts while franchise brands open studios every week.
What do contrast therapy studios sell to their guests?
The report counts consumer spending at commercial venues whose main offer is alternating heat and cold, including private-suite studios with infrared saunas and cold plunges and large social bathhouses with shared saunas, ice baths and guided rituals. Guests pay through monthly memberships, class packs, day passes and private bookings, usually made through an app. Revenue from food, drinks and add-on treatments sold inside these venues is included.
Home saunas and cold plunge tubs, hotel spas sold mainly to room guests, medical cryotherapy clinics and traditional public baths without a contrast circuit are excluded from the market value. The value chain runs from sauna, chiller and plunge equipment makers and landlords, through franchisors, franchisees and independent operators, to booking platforms and corporate wellness buyers.
Contrast Therapy Studio Market Insights
- The market is projected to rise from USD 381.4 million in 2025 to USD 2.00 billion by 2035 at an 18.00% CAGR, as franchise studios and social bathhouses open in new cities.
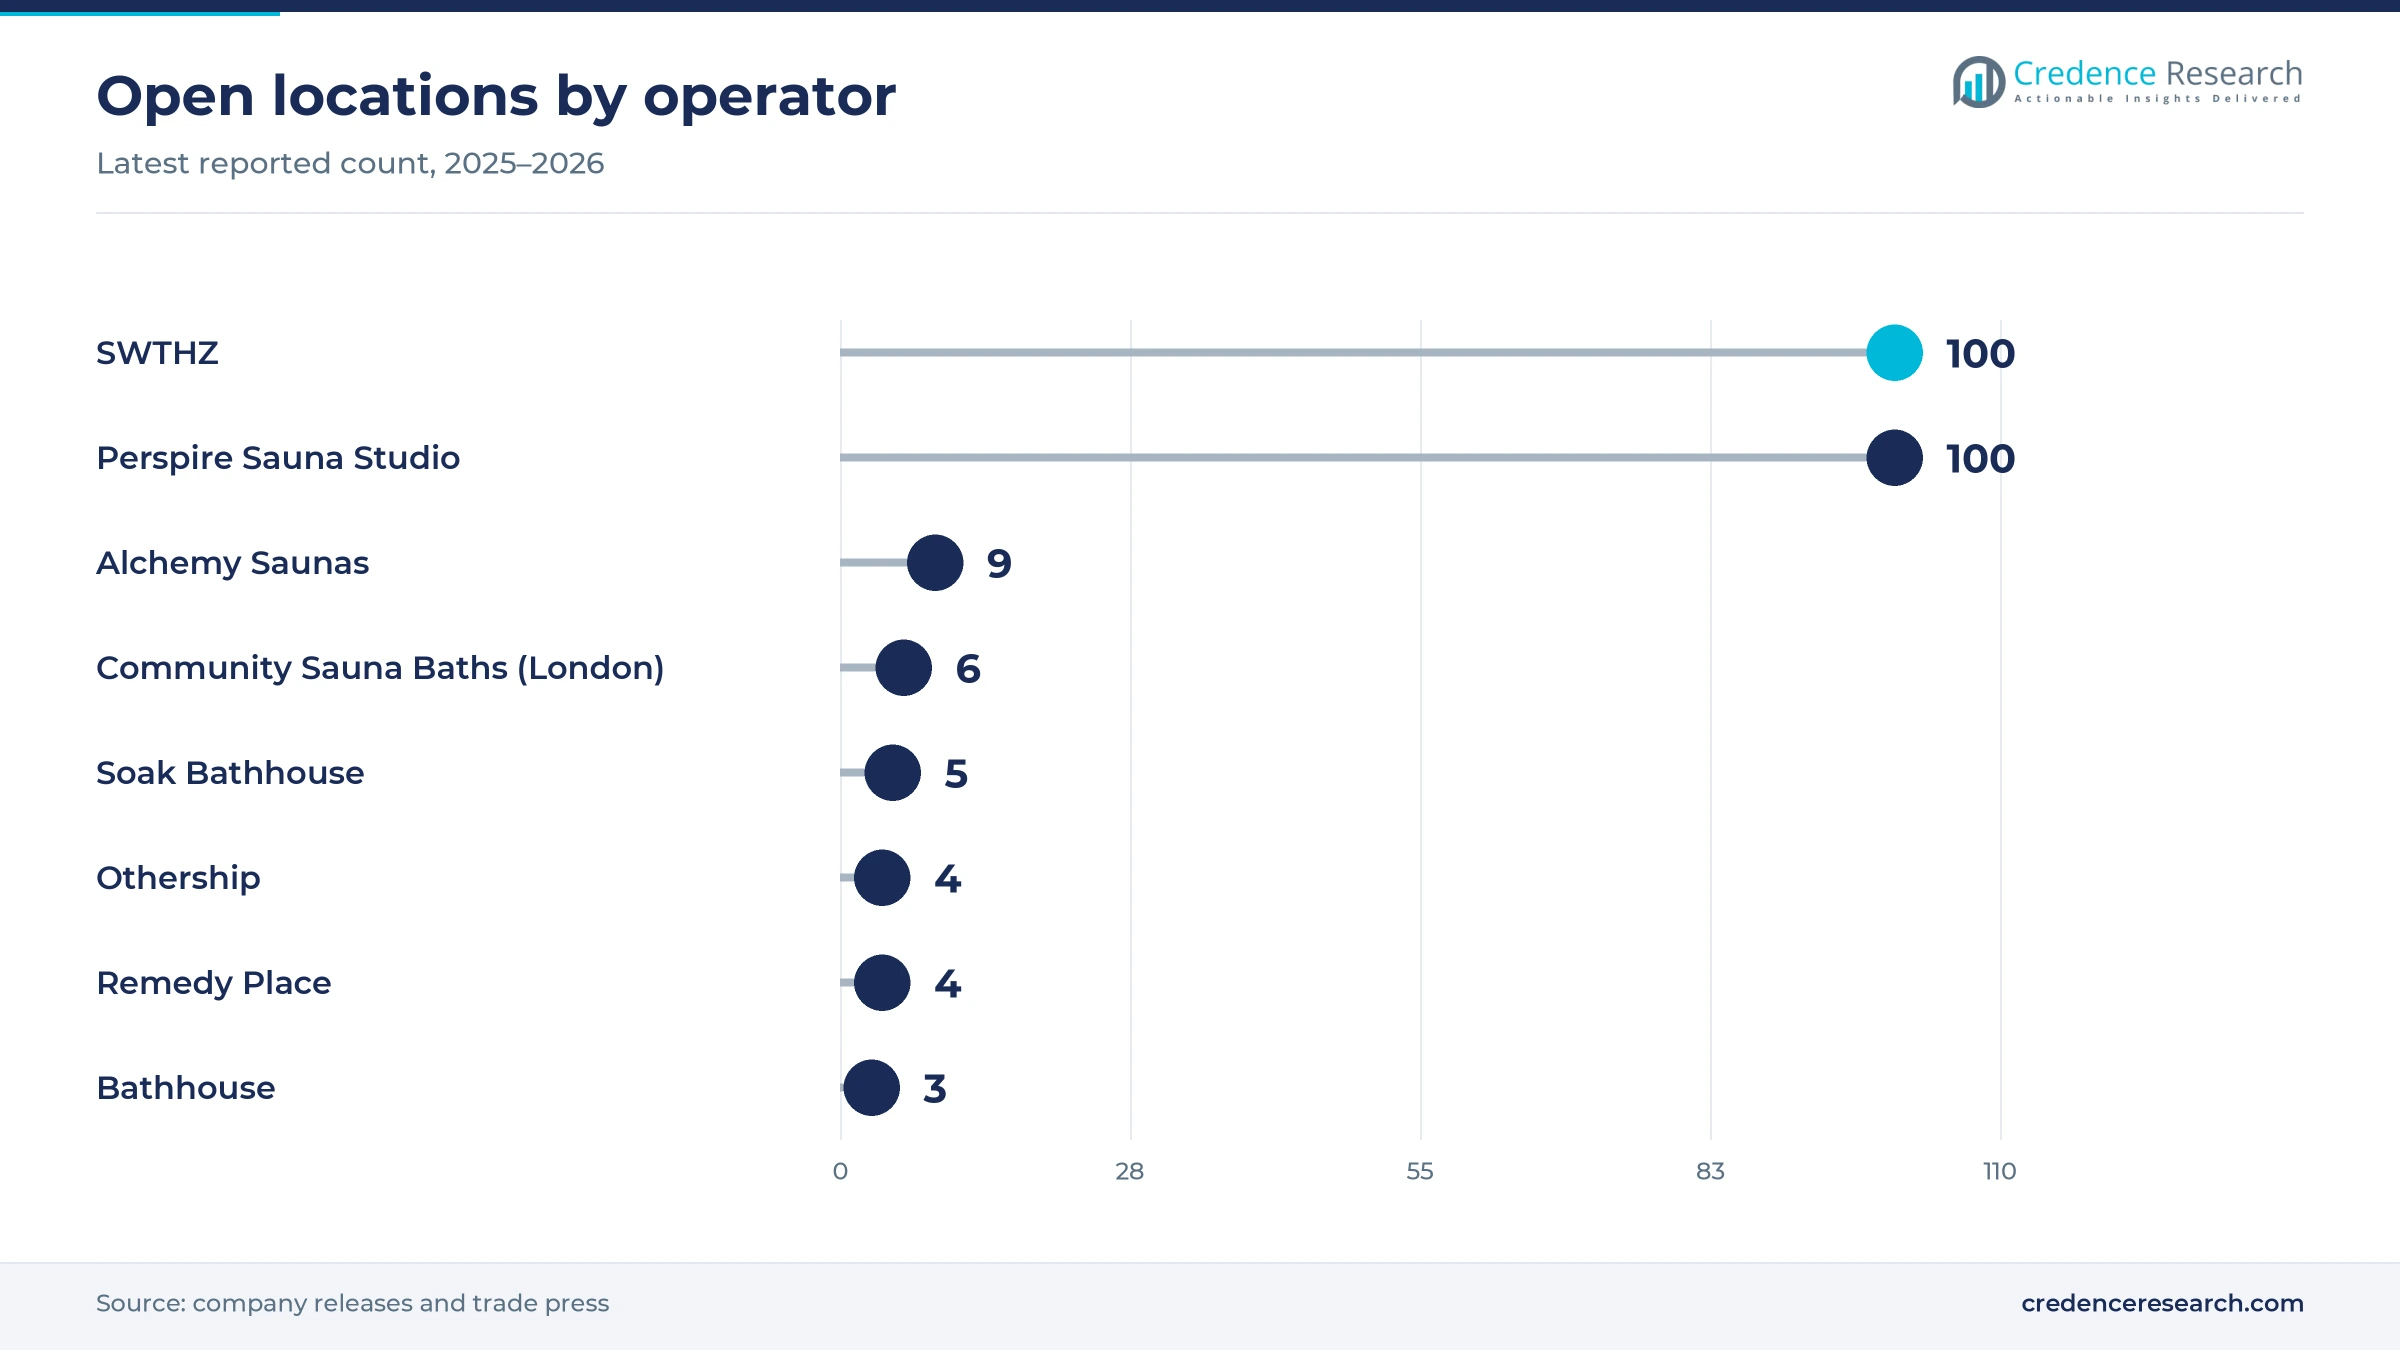
- North America held the largest regional share in 2025, as SWTHZ reached 100 U.S. studios in March 2026 and Perspire Sauna Studio reached 100 locations in May 2026.
- Sauna and cold plunge studios are the largest format, because private-suite franchise brands run far more sites than the large social bathhouses.
- Large event saunas are changing the format, as Othership opened a 100-guest sauna in Brooklyn in September 2025 and Arc opened a 65-person sauna in London.
- Capital is flowing in, with Bathhouse raising $35 million, Othership raising $11.3 million in July 2025 and Sauna House committing $9.6 million to new sites.
Private-suite studios lead as bathhouses grow fastest
Private-suite studios lead as social bathhouses grow fastest
Based on format, the market is categorized into sauna and cold plunge studios and social bathhouses. Sauna and Cold Plunge Studios led with 57.0% of 2025 value because franchise brands run far more sites, and SWTHZ opened its 100th studio in Kansas City on March 13, 2026, according to Market Realist, while Perspire Sauna Studio reached 100 locations in May 2026. Social Bathhouses grow fastest at 19.05% a year, as 29 of 47 operators in the Global Wellness Institute bathhouse benchmarking survey expect two or more locations within three years, against only 10 that run multiple sites today.
Memberships lead revenue as drop-in visits grow fastest
Based on business model, the market is categorized into membership and drop-in. Membership led with 62.0% of 2025 value because private-suite studios sell recurring plans, and SWTHZ memberships ran from about $149 to $249 a month across four tiers in December 2025, according to Franchise Times. Remedy Place also charges from $550 a month at its Boston club. Drop-In grows fastest at 18.79% a year, as 23 of 47 bathhouse operators named the day pass their most important access model, according to the Global Wellness Institute.
The U.S. leads while the U.K. grows fastest
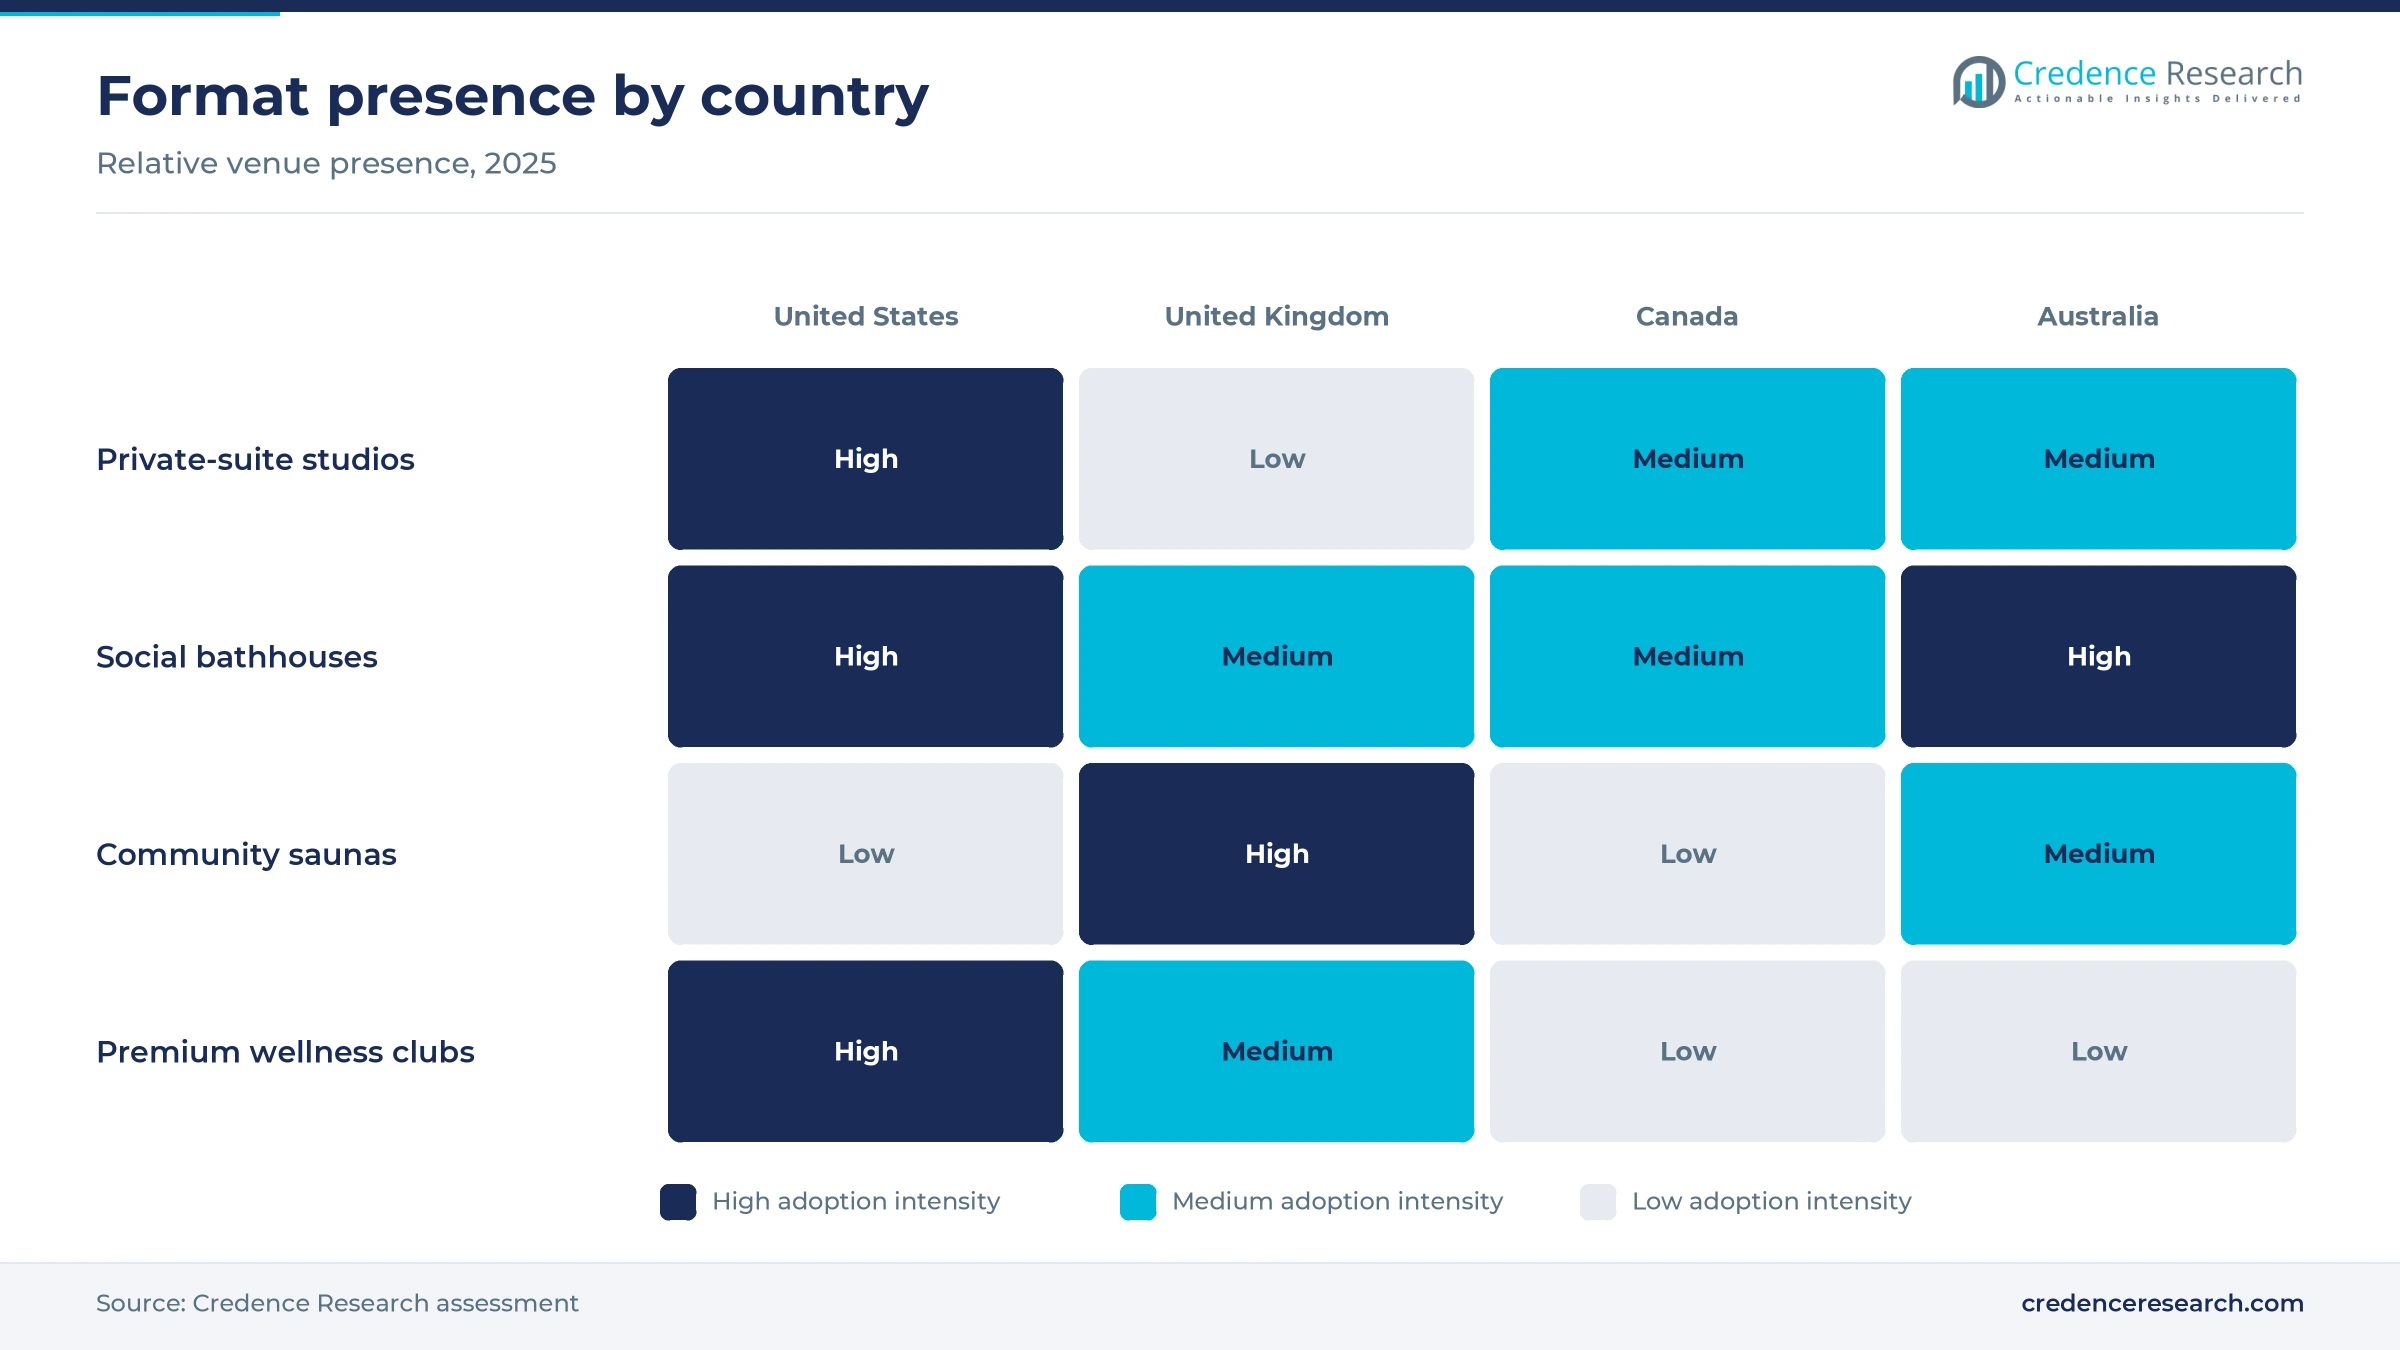
Based on country, the market is categorized into the United States, the United Kingdom, Canada, Australia and the rest of the world. The United States led with 41.0% of 2025 value because the largest franchise estates are American, and Perspire Sauna Studio operates in more than 27 states after awarding over 280 franchise licenses, according to Athletech News. The United Kingdom grows fastest at 19.18% a year, as the British Sauna Society counted 640 saunas in March 2026, up from 540 earlier in the year. Glasgow Community Sauna also opened on Nov. 7, 2025, with £10 sessions.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Format | Sauna and Cold Plunge Studios | 57.0% | Social Bathhouses | 19.05% |
| By Business Model | Membership | 62.0% | Drop-In | 18.79% |
| By Country | United States | 41.0% | United Kingdom | 19.18% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Memberships, recovery habits and franchising lift visits
Wellness operators add hot-cold suites to memberships
Gyms, recovery clubs and wellness brands now bundle sauna and cold plunge circuits into membership plans, which turns contrast bathing into a routine monthly purchase. Remedy Place opened its fourth club in Boston in March 2025 with a communal contrast suite for up to 10 people and memberships from $550 a month, according to Spa Business. Life Time is adding co-ed wet suites with sauna and steam to an upcoming Brooklyn club, while TMPL introduced TMPL Baths at a New York gym, according to Fitt Insider in January 2026. SWTHZ also sells four membership tiers priced from about $149 to $249 a month. In the Credence Research model this driver adds about 6.66 percentage points to annual growth to 2035, with the largest effect on memberships.
Athletic recovery and social wellness lift visit counts
Athletes use heat and cold for recovery, while many other adults use shared sauna sessions to meet people, and both groups raise visit frequency. About 32.1% of U.S. adults reported loneliness in 2022, according to a June 2024 report from the Centers for Disease Control and Prevention. In Canada, 13% of people aged 15 and older said in 2021 that they always or often felt lonely, according to Statistics Canada. SWTHZ delivered more than 1.52 million hours of private recovery sessions in 2025, according to Market Realist. Bathhouse also counts NBA players Klay Thompson and Marcus Smart among investors in its $35 million round, according to Athletech News. In the Credence Research model this driver adds about 4.86 percentage points to annual growth to 2035.
Multi-location franchising expands studio capacity
Franchising lets brands add studios faster than owner-operators could fund them, which expands capacity in suburban retail centers across the United States. Perspire Sauna Studio opened its 100th location in Del Mar, California, in May 2026, after awarding more than 280 franchise licenses since it began franchising in 2018. SWTHZ opened two locations a week through the end of 2025, and in December 2025 franchisees Ethan Lewis and Brian Massoll signed a 30-unit agreement for Florida's west coast. SweatHouz also reported more than 500 franchise licenses awarded by October 2026, according to Health Club Management. In the Credence Research model this driver adds about 3.60 percentage points to annual growth to 2035, mainly through private-suite studios.
Venture funding backs large social bathhouses
Large social bathhouses cost millions to build, and new venture rounds are now funding multi-city pipelines. Bathhouse raised $35 million in a round led by Imaginary Ventures and plans 10 locations nationwide, starting on Sunset Boulevard in Los Angeles, according to Athletech News in May 2026. Othership raised $11.3 million in July 2025 from backers including Shawn Mendes and SoulCycle co-founder Elizabeth Cutler, according to Spa Business. Sauna House has committed $9.6 million to open at least three new locations a year for five years. Because 14 of 47 operators in the Global Wellness Institute survey reported opening investments of at least $5 million, this capital mainly lifts social bathhouses, which grow at 19.05% a year.
Event saunas and community bathing reshape the sector
Event saunas and guided Aufguss rituals rise
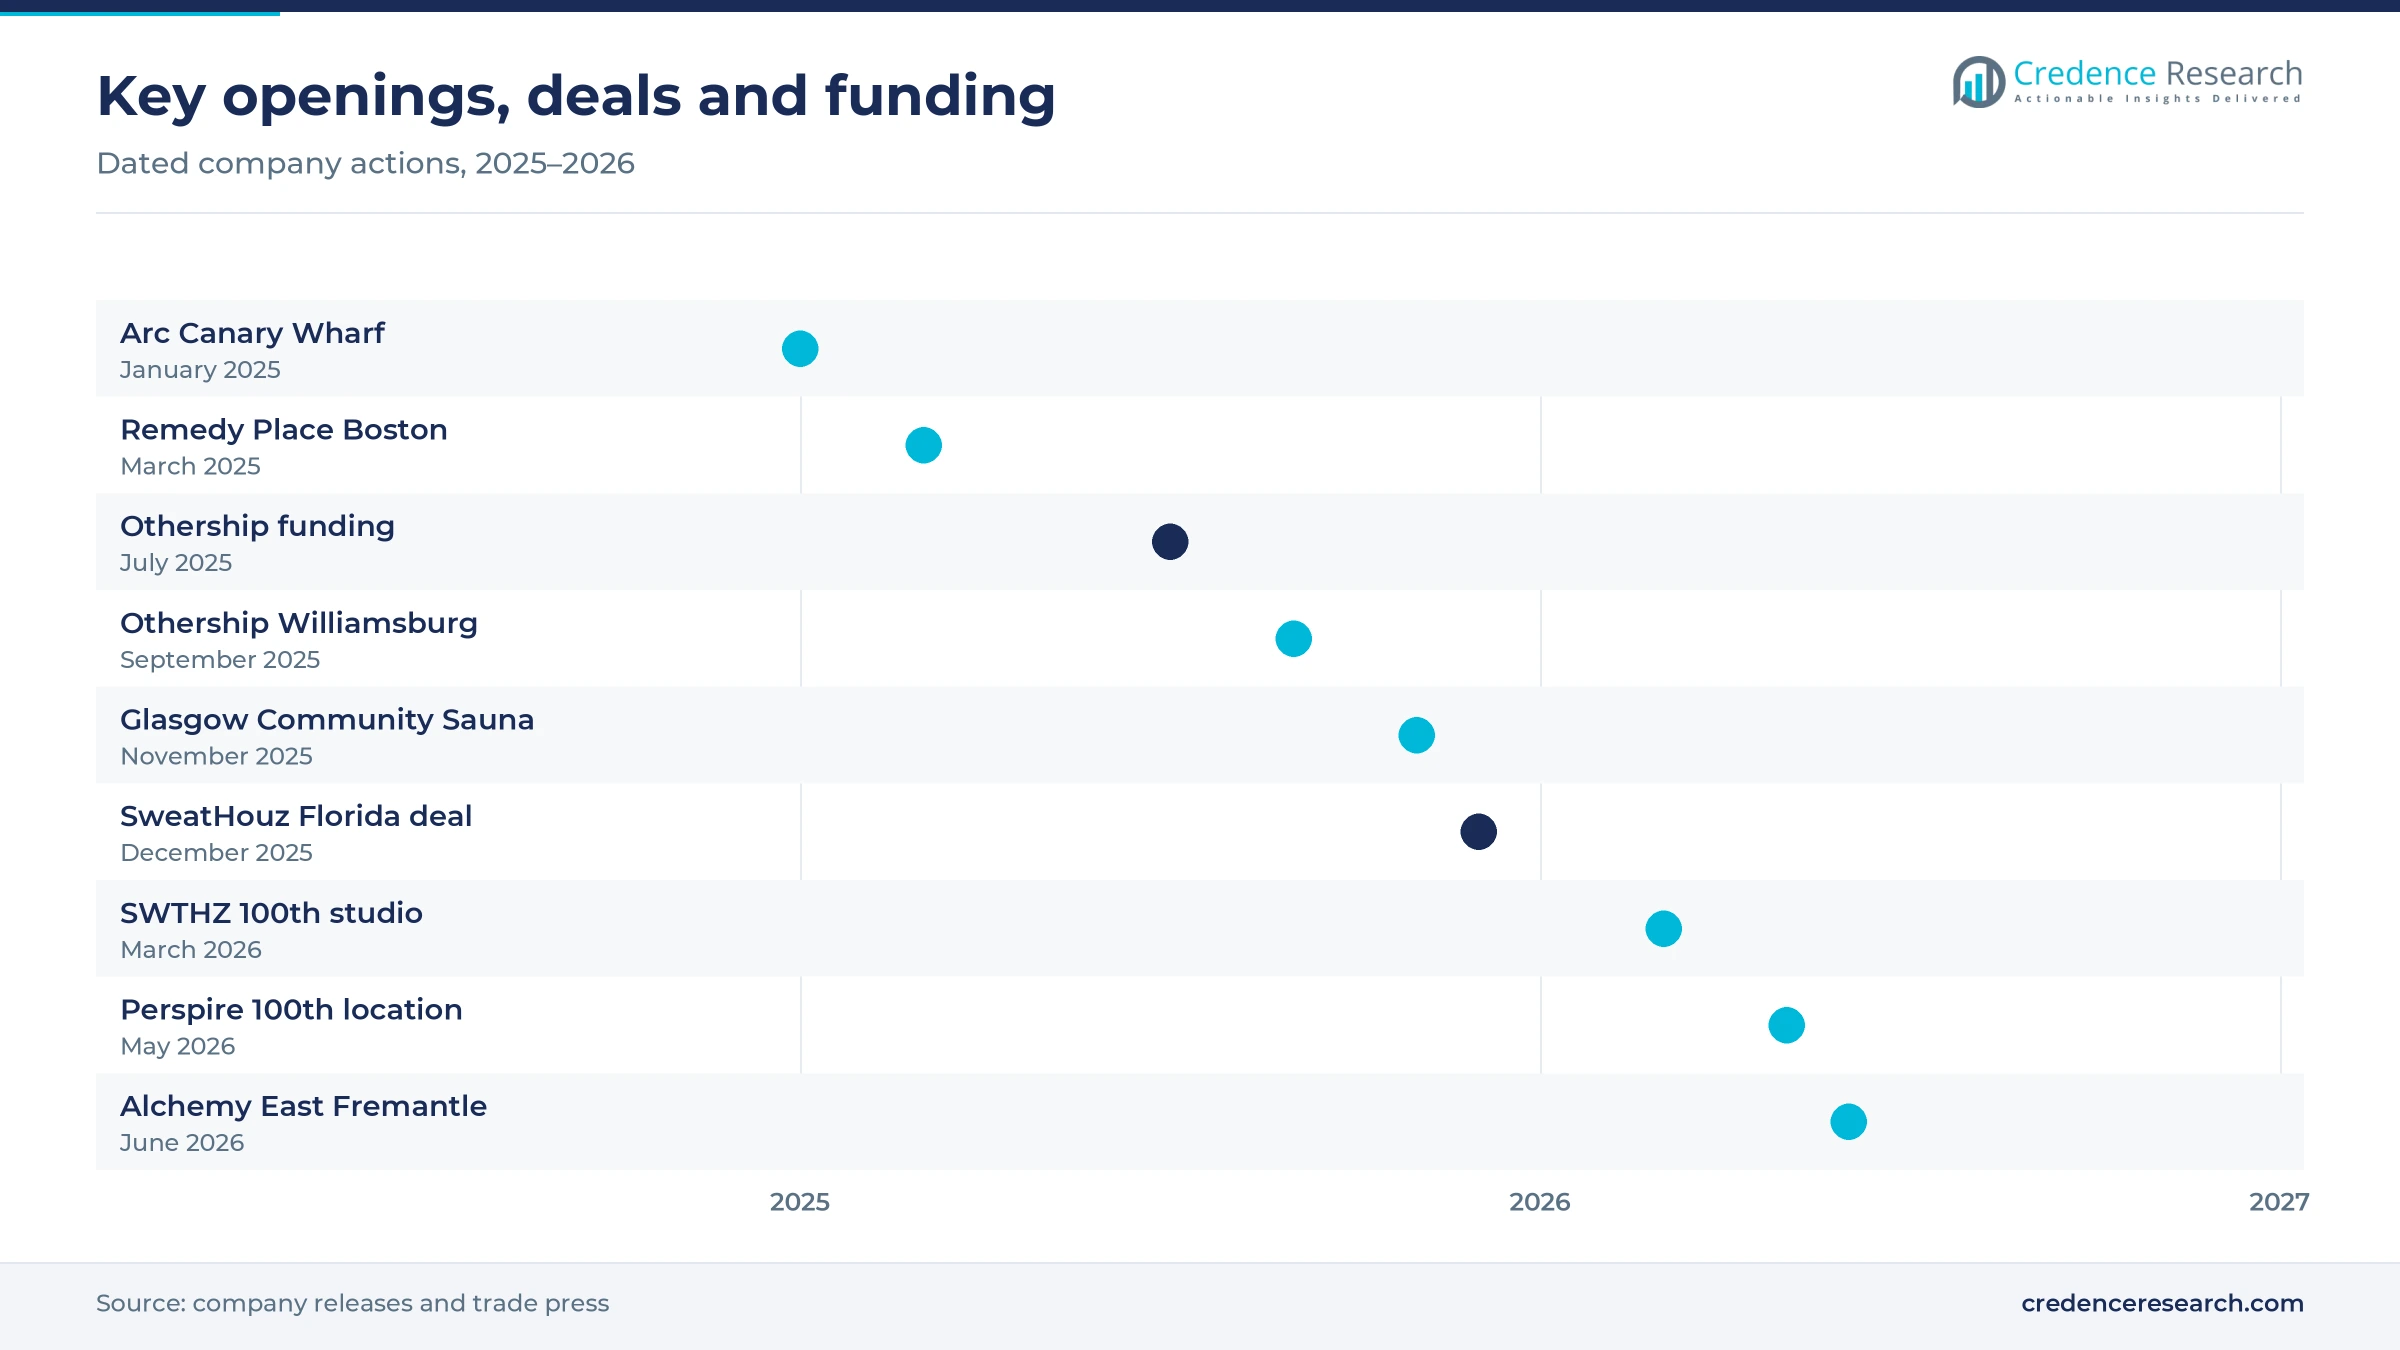
Operators are shifting from small cabins to large event saunas that host guided Aufguss rituals with music, scent and towel work. According to the Global Wellness Institute survey, 21 of 47 operators already run a large-format event sauna, eight more plan one, and 36 of 47 offer or plan guided thermal programming. Othership opened in Williamsburg in September 2025 with a cedar sauna for up to 100 guests, 20% larger than its Flatiron sauna, according to Athletech News. Arc opened in Canary Wharf on Jan. 31, 2025, with a 65-person sauna, the largest in the U.K., according to Spa Business. FlowHaus also opened in Pleasant Grove, Utah, in April 2025 with a 50-person sauna and Aufguss ceremonies.
Low-cost community saunas spread across the U.K.
Community-run saunas are shifting contrast bathing in the U.K. from luxury spas to low-cost neighborhood sessions. The British Sauna Society counted 640 saunas in March 2026, up from 540 earlier in the year, according to Pulse. Community Sauna Baths operates six sites across London and supported the opening of Glasgow Community Sauna on Nov. 7, 2025, where a 75-minute sauna and cold plunge session costs £10, according to Time Out. Arc also moved away from a traditional membership model, selling one-off sessions and multi-class packages instead. As a result, drop-in visits grow at 18.79% a year in the Credence Research model, faster than memberships across the market.
Australian bathhouse rollouts open a new growth market
Australia offers an opening for operators that pair bathhouses with local beach and cafe culture. Alchemy Saunas opened its ninth Perth site in the heritage-listed Royal George Hotel in East Fremantle in June 2026 and plans 30 sites across greater Perth within two years, according to The Nightly. Soak Bathhouse planned its fifth site, a 700-square-meter bathhouse in Alexandria, Sydney, for April 2025, with 90-minute sessions at AUD 49 on weekdays, according to Spa Business. Sense of Self, founded in Melbourne's Collingwood, was due to open in Surry Hills, Sydney, in September 2026. Because supply is still thin outside a few cities, Asia Pacific is the fastest-growing region in the Credence Research model.
Private group suites open event and corporate demand
Private group suites and event rooms offer an opening to sell birthdays, team outings and wellness workshops at a higher spend per booking. SweatHouz planned an 8,000-square-foot Tribeca flagship with eight private suites and an event room for sound baths, breathwork and private events, plus a group suite called PentHouz for four to six people, according to Health Club Management in October 2026. Private events were selected by 15 of 47 operators as an access model in the Global Wellness Institute survey, the same count as memberships. Glasgow Community Sauna also sells private sessions for up to seven people at £60. Employers that already fund workplace wellness programs give studios a channel for midweek group bookings.
Build costs, staffing and pipelines test operators
High build costs and long lead times slow openings
Large bathhouses need heavy upfront spending and long approval and build periods. In the Global Wellness Institute survey, 14 of 47 operators reported opening investments of at least $5 million, and 15 of 31 operating respondents took two years or longer from concept to opening. A SweatHouz franchise studio also needs about $570,000 to $1.19 million of initial investment, according to SharpSheets. These costs limit new entrants to well-funded brands, so operators phase sites and use franchise capital to share the risk.
Staffing and training needs are often underestimated
Guided rituals, cold plunge supervision and hygiene checks make bathhouses more staff-heavy than self-service studios. According to the Global Wellness Institute survey released in October 2026, 25 of 47 operators said prospective owners often underestimate staffing and training. This matters because 36 of 47 offer or plan guided thermal programming that needs trained sauna masters. Shortages raise payroll and can limit session schedules at new sites. In response, many operators favor app booking and private suites that need fewer staff on the floor.
Equipment safety recalls raise operating scrutiny
Heaters and chillers run at extreme temperatures, so equipment faults carry safety and reputational risks. DIY Cold Plunge recalled sauna heater kits sold from March 2025 through February 2026 for $400 to $500 after 12 reports of overheating, under U.S. Consumer Product Safety Commission recall number 26349, according to ConsumerRecallsUSA. The recall involved consumer kits, yet it draws insurer and inspector attention to commercial installations as well. Operators therefore buy certified commercial heaters and log water temperature and sanitation checks.
Unopened franchise licenses test pipeline delivery
Franchise brands have sold far more licenses than they have open studios, which leaves growth dependent on franchisee financing and site approvals. Perspire Sauna Studio had 100 locations open against more than 280 licenses awarded in May 2026, and SweatHouz reported more than 500 licenses against just over 100 studios in October 2026. Any slowdown in lending or retail leasing would delay openings and frustrate territory buyers. Franchisors therefore favor experienced multi-unit operators, such as the SweatHouz franchisees behind a 30-unit Florida agreement.
North America leads while Australia drives Asia Pacific
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 183.1 | 48.0% | 17.47% |
| Europe | 95.3 | 25.0% | 18.17% |
| Asia Pacific | 76.3 | 20.0% | 18.87% |
| Latin America | 15.3 | 4.0% | 18.37% |
| Middle East & Africa | 11.4 | 3.0% | 18.47% |
North America leads on franchise studios and NYC bathhouses
North America held 48.0% of 2025 value and grows at 17.47% a year. The United States hosts the largest estates, as SWTHZ reached 100 studios in more than 25 states in March 2026 and Perspire Sauna Studio reached 100 locations in May 2026. New York is the main bathhouse hub, where Othership, Bathhouse and Remedy Place operate, and Bathhouse plans eight openings over two years, according to Fitt Insider. In Canada, Othership runs two Toronto bathhouses, including the first, which opened in 2022 with a 50-person sauna and four ice baths.
Europe grows on the U.K. sauna boom
Europe held 25.0% of 2025 value and grows at 18.17% a year. The United Kingdom leads regional growth, where the British Sauna Society counted 640 saunas in March 2026 and Arc opened a contrast club in Canary Wharf on Jan. 31, 2025, with eight two-person Brass Monkey ice baths. Arc planned a second London site in Marylebone, and Community Sauna Baths runs six London sites plus supported venues in Bristol and Glasgow. Continental Europe has a long public bathing tradition, so new urban studios compete with established thermal baths and spa resorts there.
Asia Pacific grows fastest on Australian rollouts
Asia Pacific held 20.0% of 2025 value and grows at 18.87% a year, the fastest of any region. Australia drives the regional market, where Alchemy Saunas runs nine Perth sites and Soak Bathhouse has grown from a Gold Coast flagship launched in November 2020 to sites in Brisbane, Melbourne and Sydney. Capybara Bathing in Surry Hills and Hepburn Bathhouse in Daylesford add more bathhouse capacity, according to Australasian Leisure Management. Japan and South Korea have older bathing cultures, but the modern contrast therapy studio format is still concentrated in Australia.
Latin America builds on Mexico City studios
Latin America held 4.0% of 2025 value and grows at 18.37% a year. The main urban market is Mexico City, where Tērmique in Polanco and CUULT in Lomas de Chapultepec run sauna and ice tub contrast sessions, and Casa Koti in Condesa offers sauna and ice tubs to members, according to Food and Pleasure in April 2025. Supply is mostly independent single-site studios, so growth depends on affluent districts in large capital cities rather than on franchise networks.
Middle East & Africa starts from Dubai wellness clubs
Middle East & Africa held 3.0% of 2025 value and grows at 18.47% a year. Dubai leads the region, where the PEAQ social wellness club opened in November 2024 with ice baths among its services, according to TradeArabia. Hotel spas and fitness clubs in the United Arab Emirates also add cold plunge and sauna circuits for residents and visitors. Demand elsewhere in the region remains small and concentrated in luxury hotels, so the region keeps a modest share through 2035.
Openings, funding rounds and franchise deals since 2025
| Development | Status and market relevance |
|---|---|
| In March 2025, Remedy Place opened its fourth social wellness club in Boston, a 10,000-square-foot site with a communal contrast suite for up to 10 people. | Open; it is the first Remedy Place club outside New York City and Los Angeles. |
| In September 2025, Othership opened a 6,500-square-foot bathhouse at 25 Kent Avenue in Williamsburg, Brooklyn, with a sauna for up to 100 guests. | Open; a 13,500-square-foot Upper East Side site is planned for 2027. |
| In December 2025, SweatHouz franchisees signed a 30-unit development agreement covering Florida's west coast from Tampa to Naples. | In development; the first Naples studio opened on Dec. 3, 2025. |
| In March 2026, SWTHZ opened its 100th studio in Kansas City's Power & Light District. | Open; the brand opened two locations a week through the end of 2025. |
| In May 2026, Perspire Sauna Studio opened its 100th location in Del Mar, California. | Open; more than 280 franchise licenses have been awarded. |
Infrared suites and event saunas define the format
- Infrared saunas heat the body at lower air temperatures than Finnish saunas, and SWTHZ pairs them with cold plunges and vitamin C showers in private suites.
- Cold rainfall showers such as the SNØ Shower that Perspire Sauna Studio introduced in 2024 pair infrared heat with a 45-degree rainfall shower inside each suite.
- Event sauna sound systems with subwoofers and seat-rumblers synced to music power guided sessions in the 50-person sauna at FlowHaus in Utah.
- Cryotherapy cabins sit beside ice baths and hyperbaric chambers at Remedy Place clubs, which links premium studios with the whole-body cryotherapy category.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Franchise studios and venture-backed bathhouses compete
Competition among contrast therapy studio operators is fragmented, with a few franchise brands leading private-suite studios and venture-backed operators leading large social bathhouses. SweatHouz, which also trades as SWTHZ, and Perspire Sauna Studio each passed 100 U.S. locations in 2026 and compete on suite design, membership tiers and franchise support. Othership, Bathhouse and Sauna House compete in communal bathing with event saunas, guided rituals and day passes, while Remedy Place sells high-priced memberships that combine contrast bathing with medical and recovery services. In the U.K., Arc and Community Sauna Baths compete at opposite price points, and Alchemy Saunas and Soak Bathhouse lead in Australia. Operators also compete for recovery spending with physiotherapy and sports medicine clinics that offer cold immersion. Access to prime leases and franchise capital is now the main barrier to scale.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| SweatHouz (SWTHZ) | Private-suite franchise | Runs 100+ U.S. studios with infrared saunas and cold plunges |
| Perspire Sauna Studio | Infrared sauna franchise | Runs 100 studios in 27+ states with SNØ cold showers |
| Othership | Social bathhouse operator | Runs bathhouses in Toronto, Flatiron and Williamsburg |
| Bathhouse | Social bathhouse operator | Runs New York bathhouses and plans 10 sites nationwide |
| Remedy Place | Social wellness club | Runs four clubs with contrast suites and premium memberships |
| Sauna House | Bathhouse franchise | Opens communal sauna and cold plunge sites in Southern states |
| Arc | U.K. contrast club | Runs a Canary Wharf club with a 65-person sauna |
| Alchemy Saunas | Australian sauna operator | Runs nine Perth sites and targets 30 |
Day passes and events will decide bathhouse winners
Credence Research's view is that day passes, guided rituals and private events, not memberships alone, will decide which bathhouse and contrast therapy studio operators grow to 2035. Private-suite franchise studios will keep the largest share because they open quickly in suburban retail centers, but social bathhouses will grow faster as large event saunas turn a visit into a night out. The gap between licenses sold and studios open is the main risk for franchise brands. Operators with funded pipelines, trained ritual staff and flexible pricing are better placed, especially in the U.K. and Australia.
How Credence Research sized the market
The report uses 2025 as the base year and forecasts to 2035, with 2026 to 2035 as the growth period. Market values come from the Credence Research model, built from studio and bathhouse counts, typical revenue per site and visit patterns by region. Regional and segment shares are Credence Research estimates derived from venue counts by country. Sources used include company press releases, franchise disclosure summaries, an operator benchmarking survey, official statistics from the Centers for Disease Control and Prevention and Statistics Canada, a product recall notice and trade press coverage of openings, funding rounds and franchise deals. No interviews or surveys were conducted for this edition of the report.
Franchise pipelines carry the format to new cities
The market is expected to grow quickly to 2035 as franchise pipelines turn signed licenses into open studios and venture capital funds new social bathhouses. Perspire Sauna Studio and SweatHouz together hold several hundred unopened licenses, while Bathhouse plans 10 locations and Othership a fifth site in 2027. Australia and the U.K. are likely to add the most new venues outside the United States. However, growth will depend on build costs, trained staff and lending conditions, so operators are likely to favor smaller formats and event-led sites in new cities.
Frequently Asked Questions
How big is the contrast therapy studio market?
Which region leads the market?
Which region grows fastest?
Which format holds the largest share?
Which business model grows fastest?
What are the main drivers of the market?
What are the main challenges?
Who are the key companies in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Format
- 1.2.1 Sauna and Cold Plunge Studios
- 1.2.2 Social Bathhouses
- 1.3 By Business Model
- 1.3.1 Membership
- 1.3.2 Drop-In
- 1.4 By Country
- 1.4.1 United States
- 1.4.2 United Kingdom
- 1.4.3 Canada
- 1.4.4 Australia
- 1.4.5 Rest of World
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 381.4 million → 2035: USD 2.00 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Contrast Therapy Studio Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Contrast Therapy Studio Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Contrast Therapy Studio Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Contrast Therapy Studio Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Contrast Therapy Studio Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Contrast Therapy Studio Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Contrast Therapy Studio Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Contrast Therapy Studio Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 381.4 million → 2035: USD 2.00 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Contrast Therapy Studio Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Format - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sauna and Cold Plunge Studios
- 12.3.7.2 Social Bathhouses
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Business Model - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Membership
- 12.4.7.2 Drop-In
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Country - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 United States
- 12.5.7.2 United Kingdom
- 12.5.7.3 Canada
- 12.5.7.4 Australia
- 12.5.7.5 Rest of World
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Contrast Therapy Studio Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Contrast Therapy Studio Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Contrast Therapy Studio Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Othership
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 SweatHouz
- 17.4 Perspire Sauna Studio
- 17.5 Remedy Place
- 17.6 Bathhouse
- 17.7 Sauna House
- 17.8 Arc
- 17.9 Community Sauna Baths
- 17.10 Alchemy Saunas
- 17.11 Soak Bathhouse
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

