
Meters now sell on data capture as much as on range
The global laser distance measurers market was valued at USD 2.08 billion in 2025 and is projected to increase from USD 2.21 billion in 2026 to USD 3.87 billion by 2035, registering a CAGR of 6.40% during 2026–2035. Demand comes from contractors, fit-out trades, surveyors, facility managers and home improvers who replace tape measures with meters that read distances, areas and angles in seconds and send them to estimating or floor-plan software. North America held the largest regional share, 32.0% in 2025, because U.S. trades buy professional meters through tool platforms and big-box retailers. Asia Pacific is the fastest-growing region at 7.4% a year as Indian public works expand and Chinese brands scale low-cost models for export. The main commercial change is that premium meters now compete on cameras, green beams and app links rather than on range alone, a shift that raises average prices while total construction activity stays weak in the U.S. and Europe.
Handheld meters for trades and facility work define the market
The market counts handheld and tripod-mounted laser distance meters, from pocket units that read about 17 meters to professional models with cameras, inclination sensors and Bluetooth that reach 250 meters. Buyers are electricians, plumbers, flooring and window installers, estimators, surveyors and facility managers, plus homeowners who buy entry-level units in hardware stores and online.
Industrial laser distance sensors built into machines, golf and hunting rangefinders, laser trackers and total stations are excluded. Value is measured at manufacturer selling prices, so retailer margins sit outside the figures, while value inside the chain concentrates in brand owners that control apps, dealer networks and battery platforms.

Laser Distance Measurers Market Insights
- The global laser distance measurers market was valued at USD 2.08 billion in 2025 and is projected to reach USD 3.87 billion by 2035, growing at a 6.40% CAGR during 2026–2035.
- North America held 32.0% of 2025 value because U.S. trades buy professional meters through tool platforms, dealers and big-box retailers.
- Building and construction held 57.0% of 2025 value, as fit-out trades, estimators and installers use meters on every room they quote.
- Leica Geosystems launched the DISTO D2 and D2G on Nov. 25, 2025, adding NFC transfer and inertial floor-plan capture to mid-priced meters.
- Bosch introduced its EXPERT EXLM100-39CG in July 2026 with sensor fusion modes, raising the feature bar for professional meters.
Standard meters lead while long-range units grow fastest
Standard handheld meters lead as professional models gain on features
Based on product type, the market is categorized into standard handheld and advanced professional-grade meters. The Standard Handheld tier led with 63.0% of 2025 value because electricians, installers and home improvers buy them as tape replacements, and the Klein Tools 93LDM100C, launched in April 2022, reads about 30 meters with a Class 2 laser at a list price near USD 40. The Advanced Professional-Grade tier grows fastest at 7.2% a year as outdoor work needs aiming aids, and Hilti lists its PD-E at 200 meters with 1.0 mm accuracy, an optical viewfinder and a sunlight-readable display. Professional buyers pay for those features once accuracy limits their work.
Mid-range meters lead while long-range units grow fastest
Based on distance range, the market is categorized into units up to 50 meters, 50 to 200 meters and longer ranges. Meters in the 50 to 200 Meters band led with 47.0% of 2025 value because most site jobs fall inside that band, and models such as the Bosch GLM 150-27 C in the price table reach 150 meters, enough for facades and roof lines without paying for the longest-range optics. Units in the Above 200 Meters band grow fastest at 7.7% a year as site surveys move to camera models, and Leica builds its DISTO X6 for that reach, with a pointfinder camera that finds sunlit targets.
Construction trades lead as facility and real estate use grows fastest
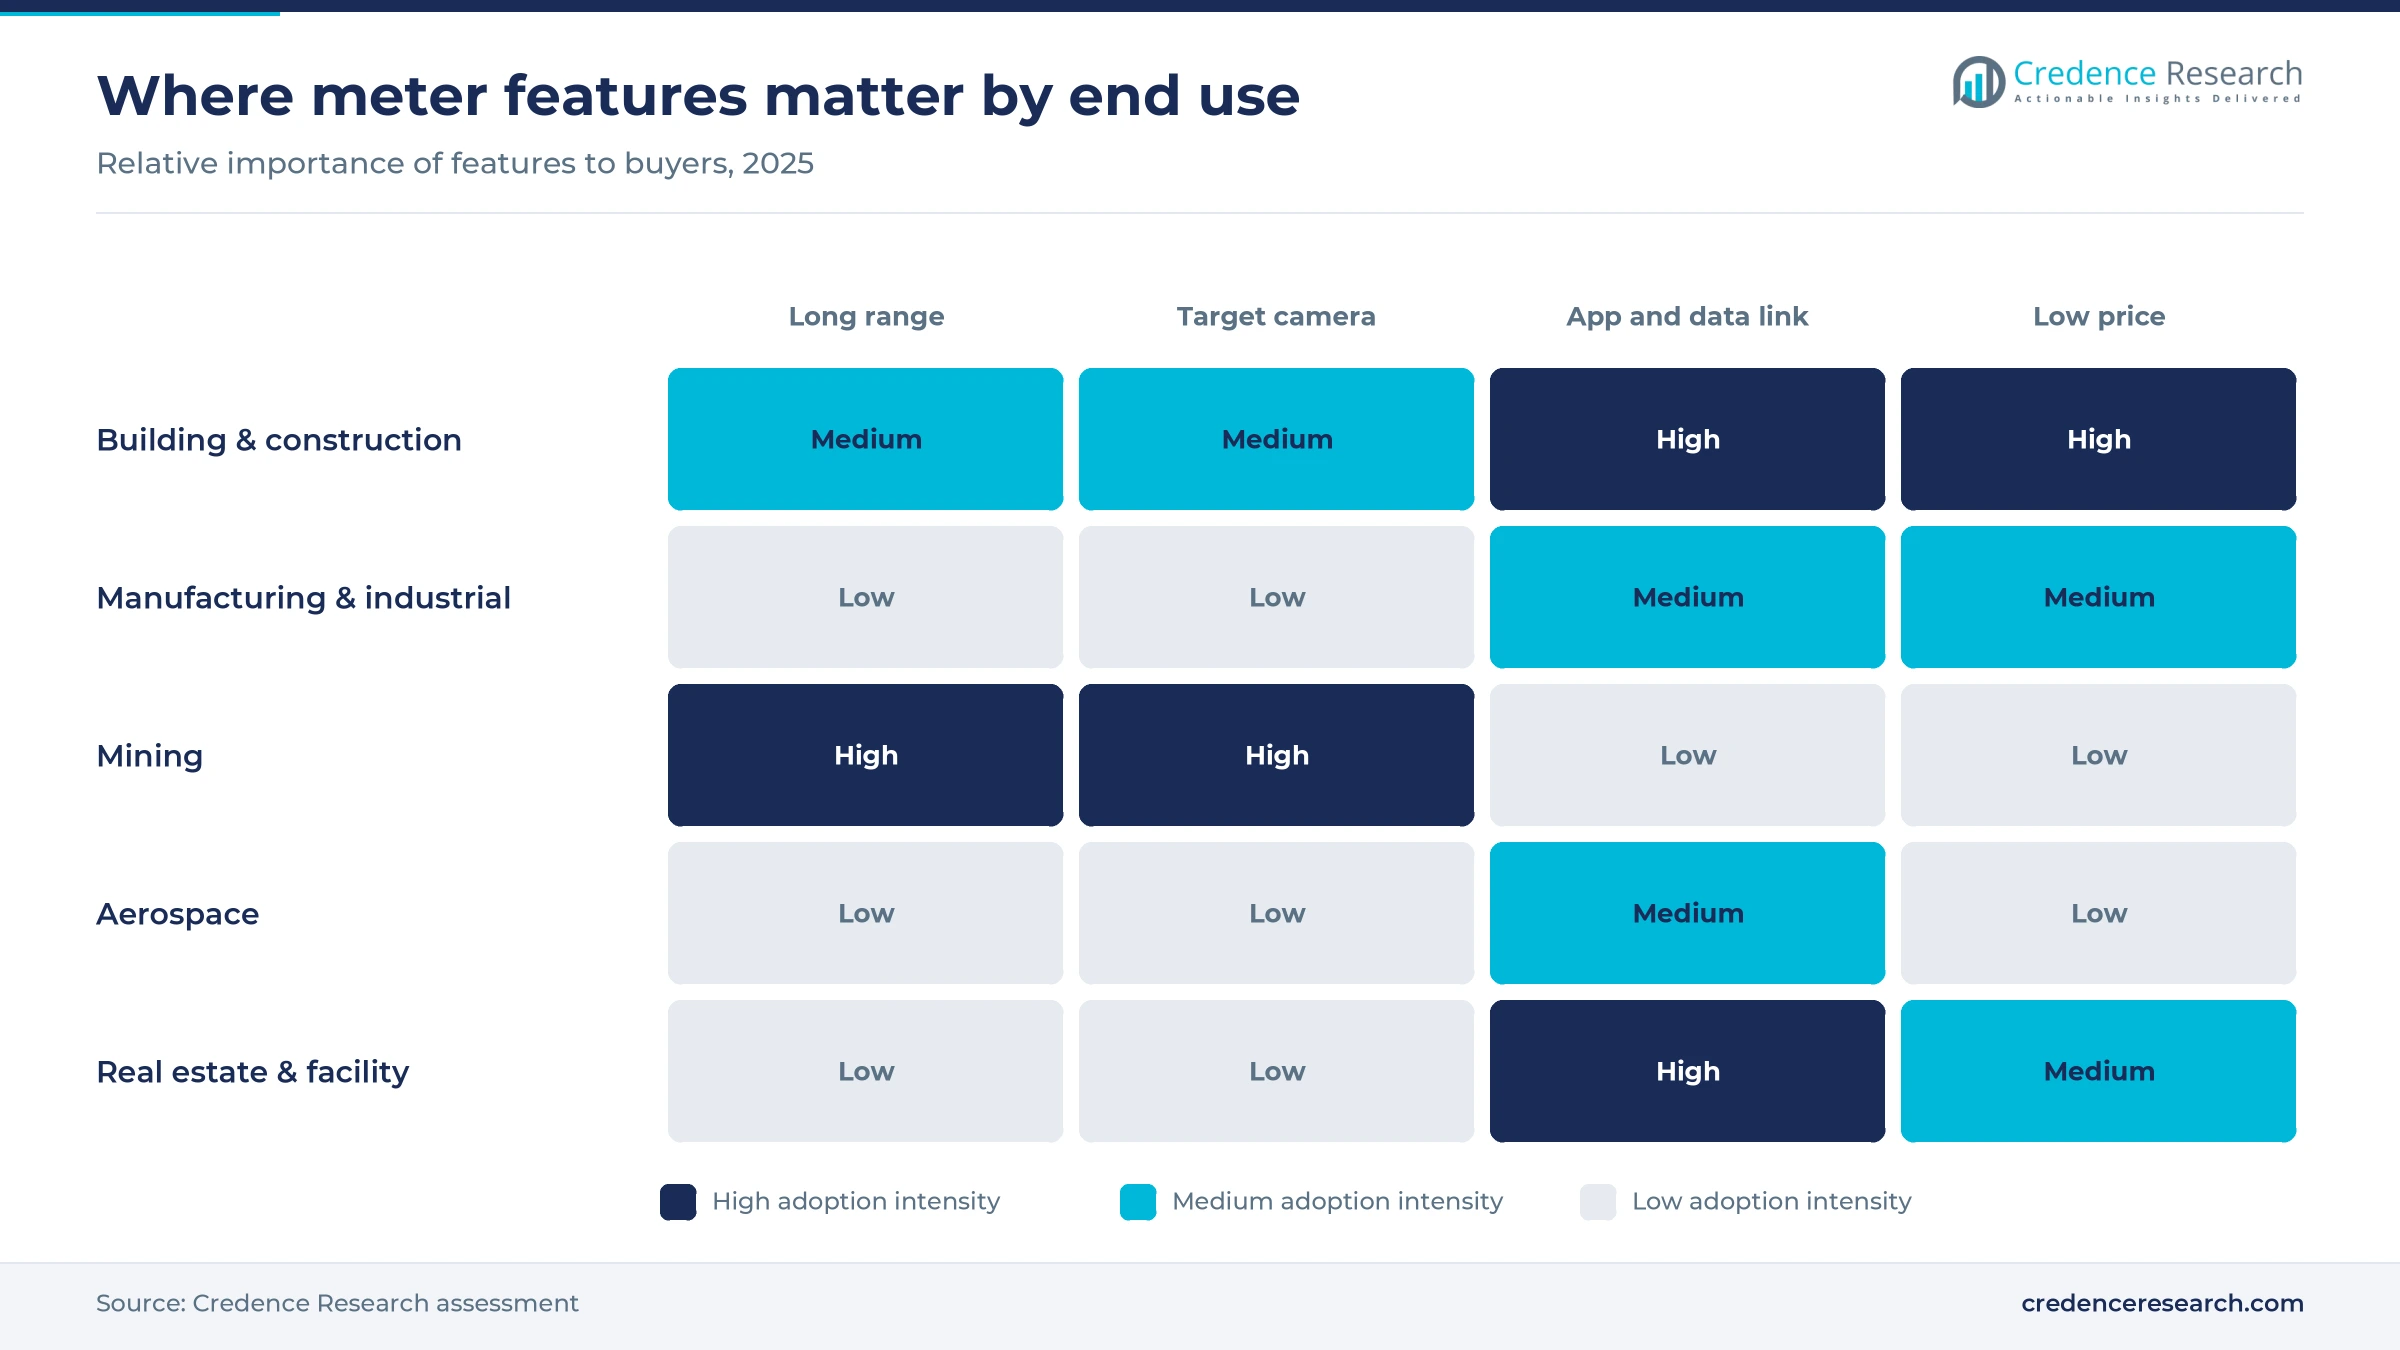
Based on end use, the market is categorized into building and construction, manufacturing and industrial, mining, aerospace and others, including agriculture and real estate. Building & Construction led with 57.0% of 2025 value because installers measure every room before ordering material, and DEWALT positions its Atomic Compact DW055PL 55-foot pocket meter for electrical, plumbing and basic home measuring. Others (Agriculture, Real Estate) grow fastest at 7.5% a year as property and facility teams digitize floor plans, and Leica aims the DISTO D2G at window and door fitting and facility management. Industrial and mining use stays smaller because fixed sensors do most automated measuring there.
Dealers and retailers lead while direct online sales grow fastest
Based on distribution channel, the market is categorized into offline and online. Offline channels led with 62.0% of 2025 value because professionals buy meters with batteries and other tools at trade counters and big-box stores, where The Home Depot listed the Milwaukee 48-22-9802 150-foot meter at USD 89.97 in November 2026. Online sales grow fastest at 7.5% a year as Chinese brands sell direct, and Mileseey runs its own web store with U.S. delivery while claiming more than 10% of global meter sales. Direct sellers gain margin but carry returns, warranty and laser compliance costs themselves.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Standard Handheld | 63.0% | Advanced Professional-Grade | 7.2% |
| By Distance Range | 50 to 200 Meters | 47.0% | Above 200 Meters | 7.7% |
| By End Use | Building & Construction | 57.0% | Others (Agriculture, Real Estate) | 7.5% |
| By Distribution Channel | Offline | 62.0% | Online | 7.5% |
Cameras and range set three clear price tiers
Meter prices fall into three tiers that track range and aiming aids rather than laser cost. Pocket meters for indoor work sell near USD 40, mid-range trade meters near USD 90 to USD 115, and camera models with 200-meter ranges at USD 575 to USD 745. The laser and receiver module costs a small share of each price, so margins rise with cameras, inclination sensors and apps. Big-box promotions compress the middle tier, while premium brands defend prices through dealer service and software. Buyers who only need room measurements gain most from the low entry prices.
| Model or tier | Typical price or fee | Basis |
|---|---|---|
| Klein Tools 93LDM100C, 30 m | USD 39.98 | The Power Tool Store listing, November 2026 |
| Milwaukee 48-22-9802, 150 ft | USD 89.97 (list USD 114.97) | The Home Depot listing, November 2026 |
| Bosch GLM 150-27 C, 150 m with camera | EUR 309 recommended retail, excluding VAT | Bosch press release, April 2022 |
| STABILA LD 530 BT, 200 m with camera | USD 575.00 | Ace Tool listing, November 2026 |
| Leica DISTO X6, 250 m with camera | USD 742.71 | Benchmark Supply listing, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Floor-plan apps and civil works lift professional demand
Floor-plan capture turns meters into drafting tools
Meters that build floor plans let estimators and installers skip the sketch-and-transcribe step, and that shift favors connected mid-priced models over basic units. Leica Geosystems launched the DISTO D2 on Nov. 25, 2025, and its Smart Room function uses an inertial measurement unit to build a floor plan that the DISTO Plan app exports as PDF, DXF or DWG files. The same meter sends readings by NFC without Bluetooth pairing and reaches 150 meters at 1.5 mm accuracy. Plans in DWG can move straight into building information modeling and quoting software, so contractors save drafting hours on each job. Vendors that own the app gain recurring customer contact, while meter makers without software compete on price alone.
Photo-linked records cut disputes and back charges
Trades increasingly need proof of site conditions before work starts, which favors meters that attach readings to photos and send them to the general contractor. Rich Morse of STABILA told Contractor Supply magazine in its October-November 2025 issue that users photograph a field condition, attach the measurement in the app over the meter's Bluetooth 5.0 link and email it to the contractor or architect to avoid downtime and back charges. STABILA updated its Measures II app in 2025 to add remote triggering from a phone or tablet. Hilti set the pattern earlier, and On-Site magazine reported in October 2017 that its PD-CS used two 5 MP cameras, measured to 1 mm and saved readings onto photos for PDF or CSV reports. Subcontractors working on fixed-price fit-out contracts benefit most, and facility teams reuse the same records at handover.
Civil works keep professional demand steadier than housing
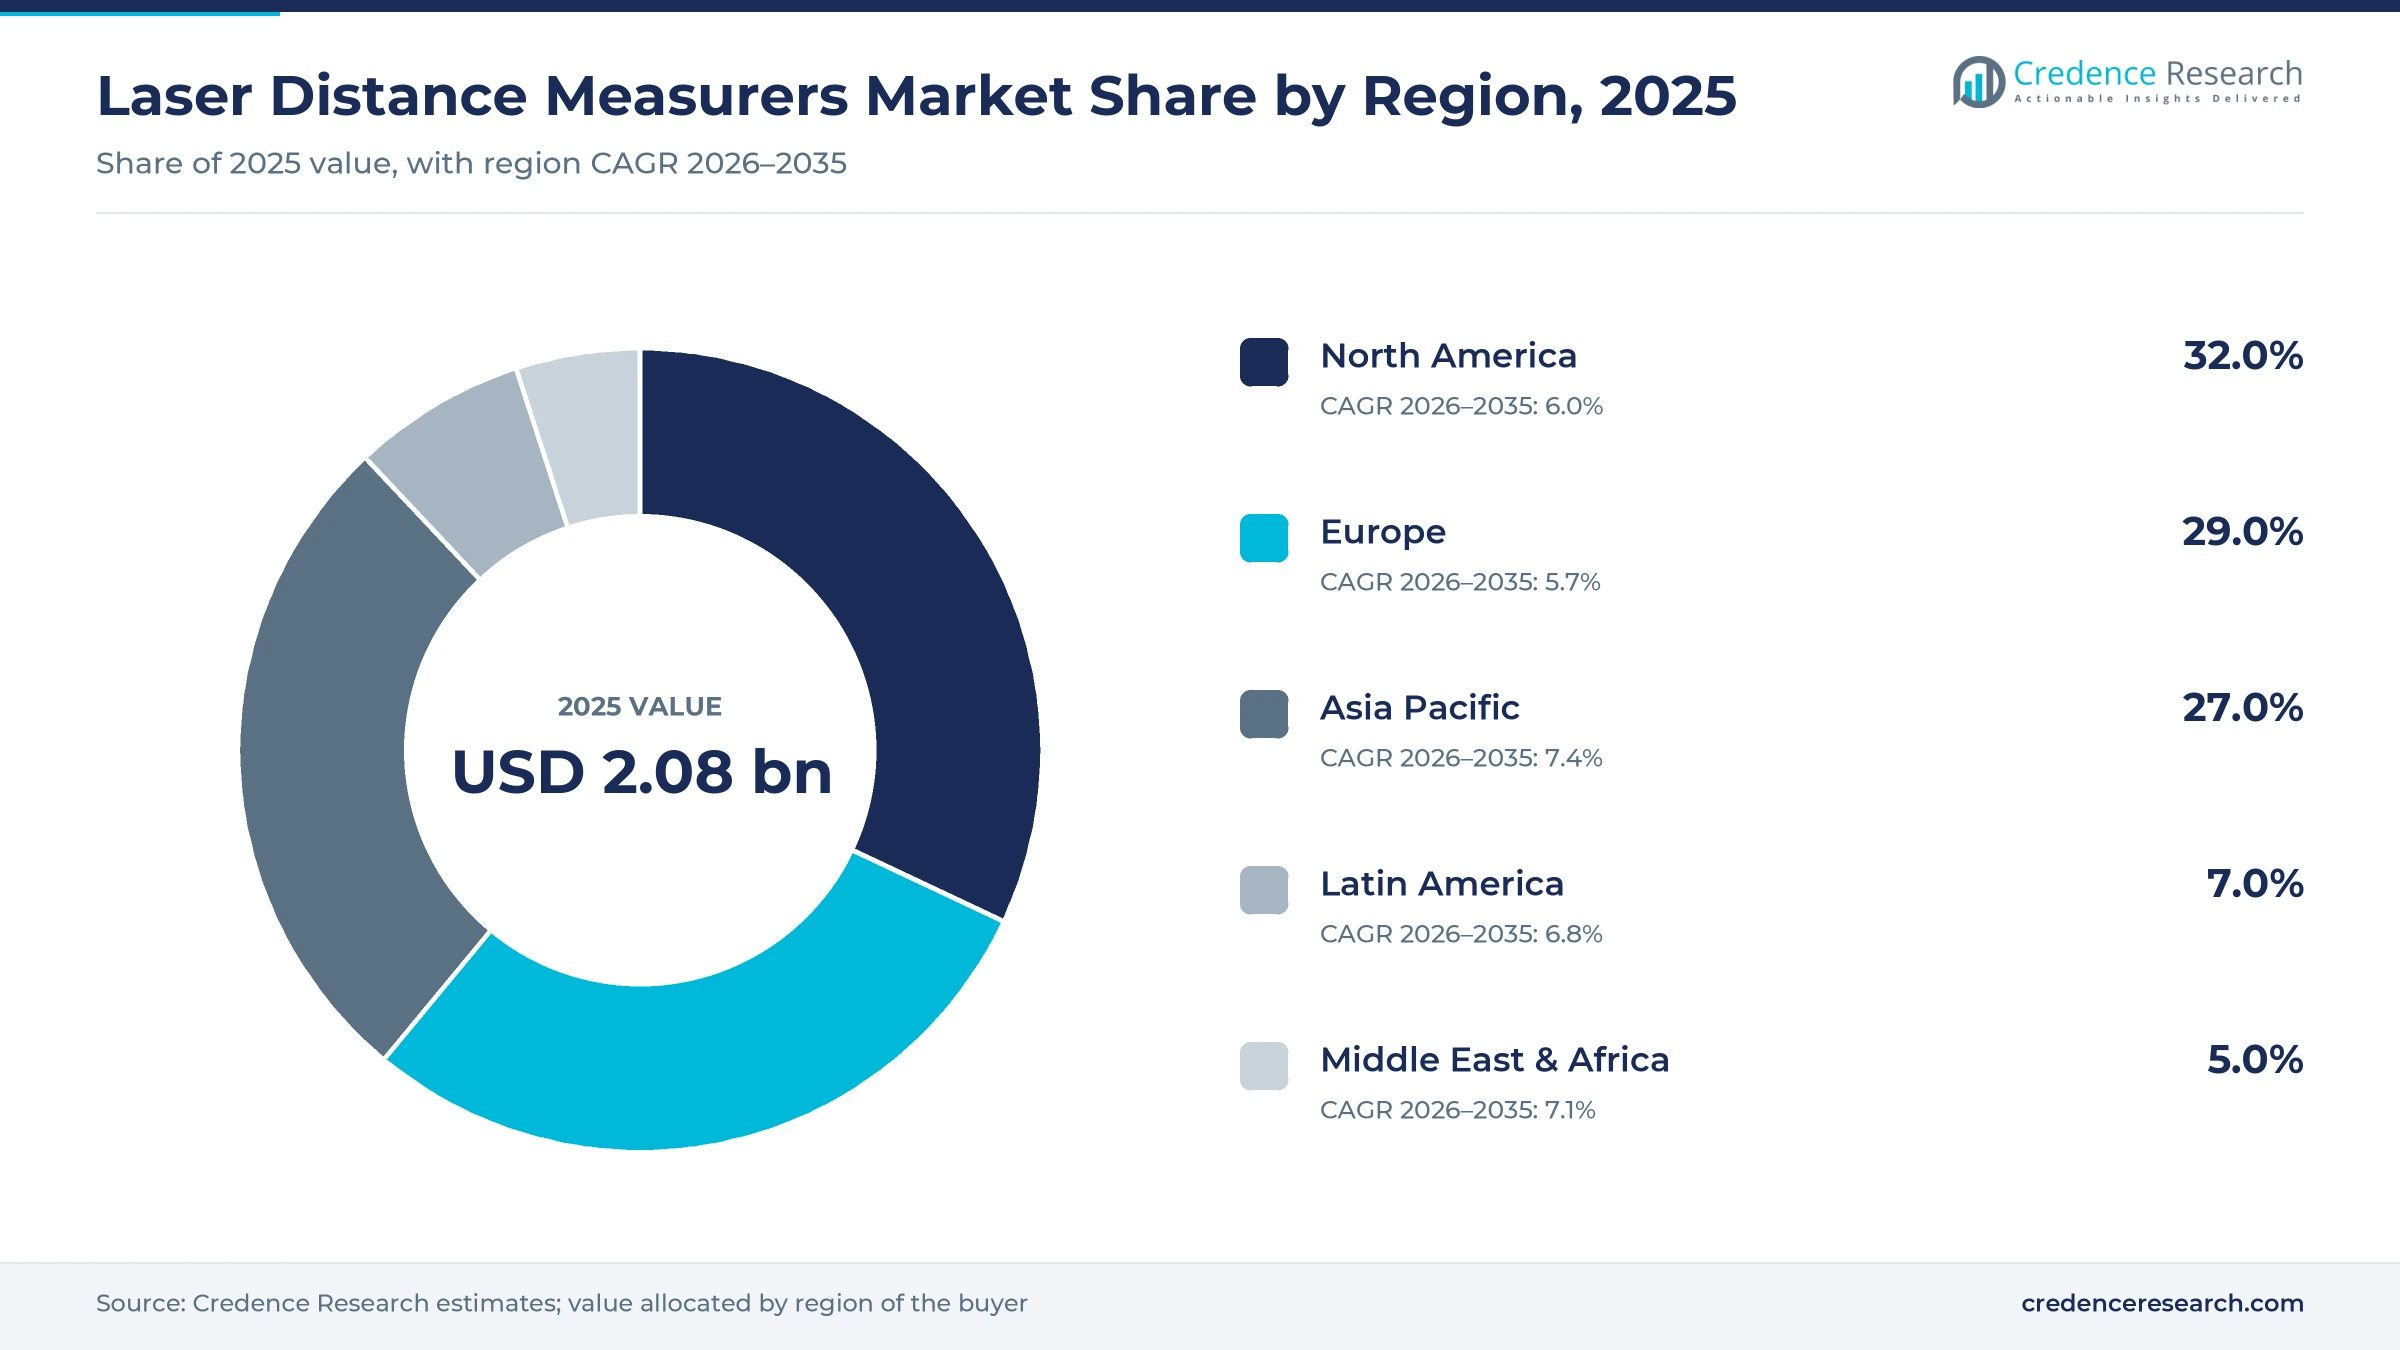
Public and nonresidential work holds up better than homebuilding, so professional buyers keep ordering long-range and camera models. U.S. Census Bureau data show nonresidential construction slipped only 0.6% to USD 1,247.0 billion in 2025, while residential spending fell 2.5%. Eurostat reported that euro area civil engineering output rose 1.6% in December 2025 from a year earlier, while building output fell 3.3%. Road, rail and utility crews measure embankments, tunnels, shafts and long plant rooms, where tape measures are impractical. Suppliers with dealer networks serving civil contractors, such as Hilti and Leica Geosystems, gain most from that shift in the work mix.
Labor shortages favor one-person measuring
Contractors short of skilled workers buy tools that let one person do work that used to need two, and a laser meter replaces the second person holding a tape. Associated Builders and Contractors estimated in January 2025 that the U.S. construction industry needed to attract 439,000 additional workers in 2025 to meet demand. Milwaukee Tool's Kenan McCutcheon told Contractor Supply magazine that Bluetooth control and automatic alignment are turning layout from a two-person task into a one-person operation. Milwaukee's M12 line alone spans more than 150 compatible tools, and its meters sell through the same trade counters, where the low price of a meter makes the payback quick for small firms. Standard handheld meters, which held 63.0% of 2025 value, gain most because firms equip each crew member rather than each site.
Green beams, sensor fusion and renovation rules shape demand
Green beams and lithium-ion packs move into mid-priced meters
Meter makers are shifting toward green beams and rechargeable lithium-ion batteries to address visibility in bright rooms and outdoors, creating openings for higher-priced models across window, facade and site work. Leica says the DISTO D2G green laser is four times more visible than a classic red laser at up to 120 meters. Mileseey Tools launched its S50 green-beam meter on Oct. 3, 2025, with a 400-foot range, an IP54 rating and app syncing. Milwaukee Tool's Kenan McCutcheon said in late 2025 that green lasers are becoming more common, and that lithium-ion batteries replaced alkaline cells to meet their higher power draw. Brands with shared battery platforms gain most, because buyers already own the chargers.
Sensor fusion and contact-free triggering emerge in professional meters
Professional meters are shifting toward combining laser readings with motion and tilt sensors to address awkward measurements, creating openings for premium models across fit-out and inspection work. Bosch announced the EXPERT EXLM100-39CG on July 27, 2026, and its Dynamic Sensor Fusion Technology enables three measurement modes, including multipoint area capture of up to 30 corner points, at 100 meters with 1.5 mm accuracy. STABILA added gesture control that triggers readings without touching the LD 530 BT, which reduces hand shake over long distances. These features copy capabilities found in 3D scanning at a fraction of the price, so meters gain ground in quick surveys that do not justify a scanner.
EU renovation rules open demand from energy assessors
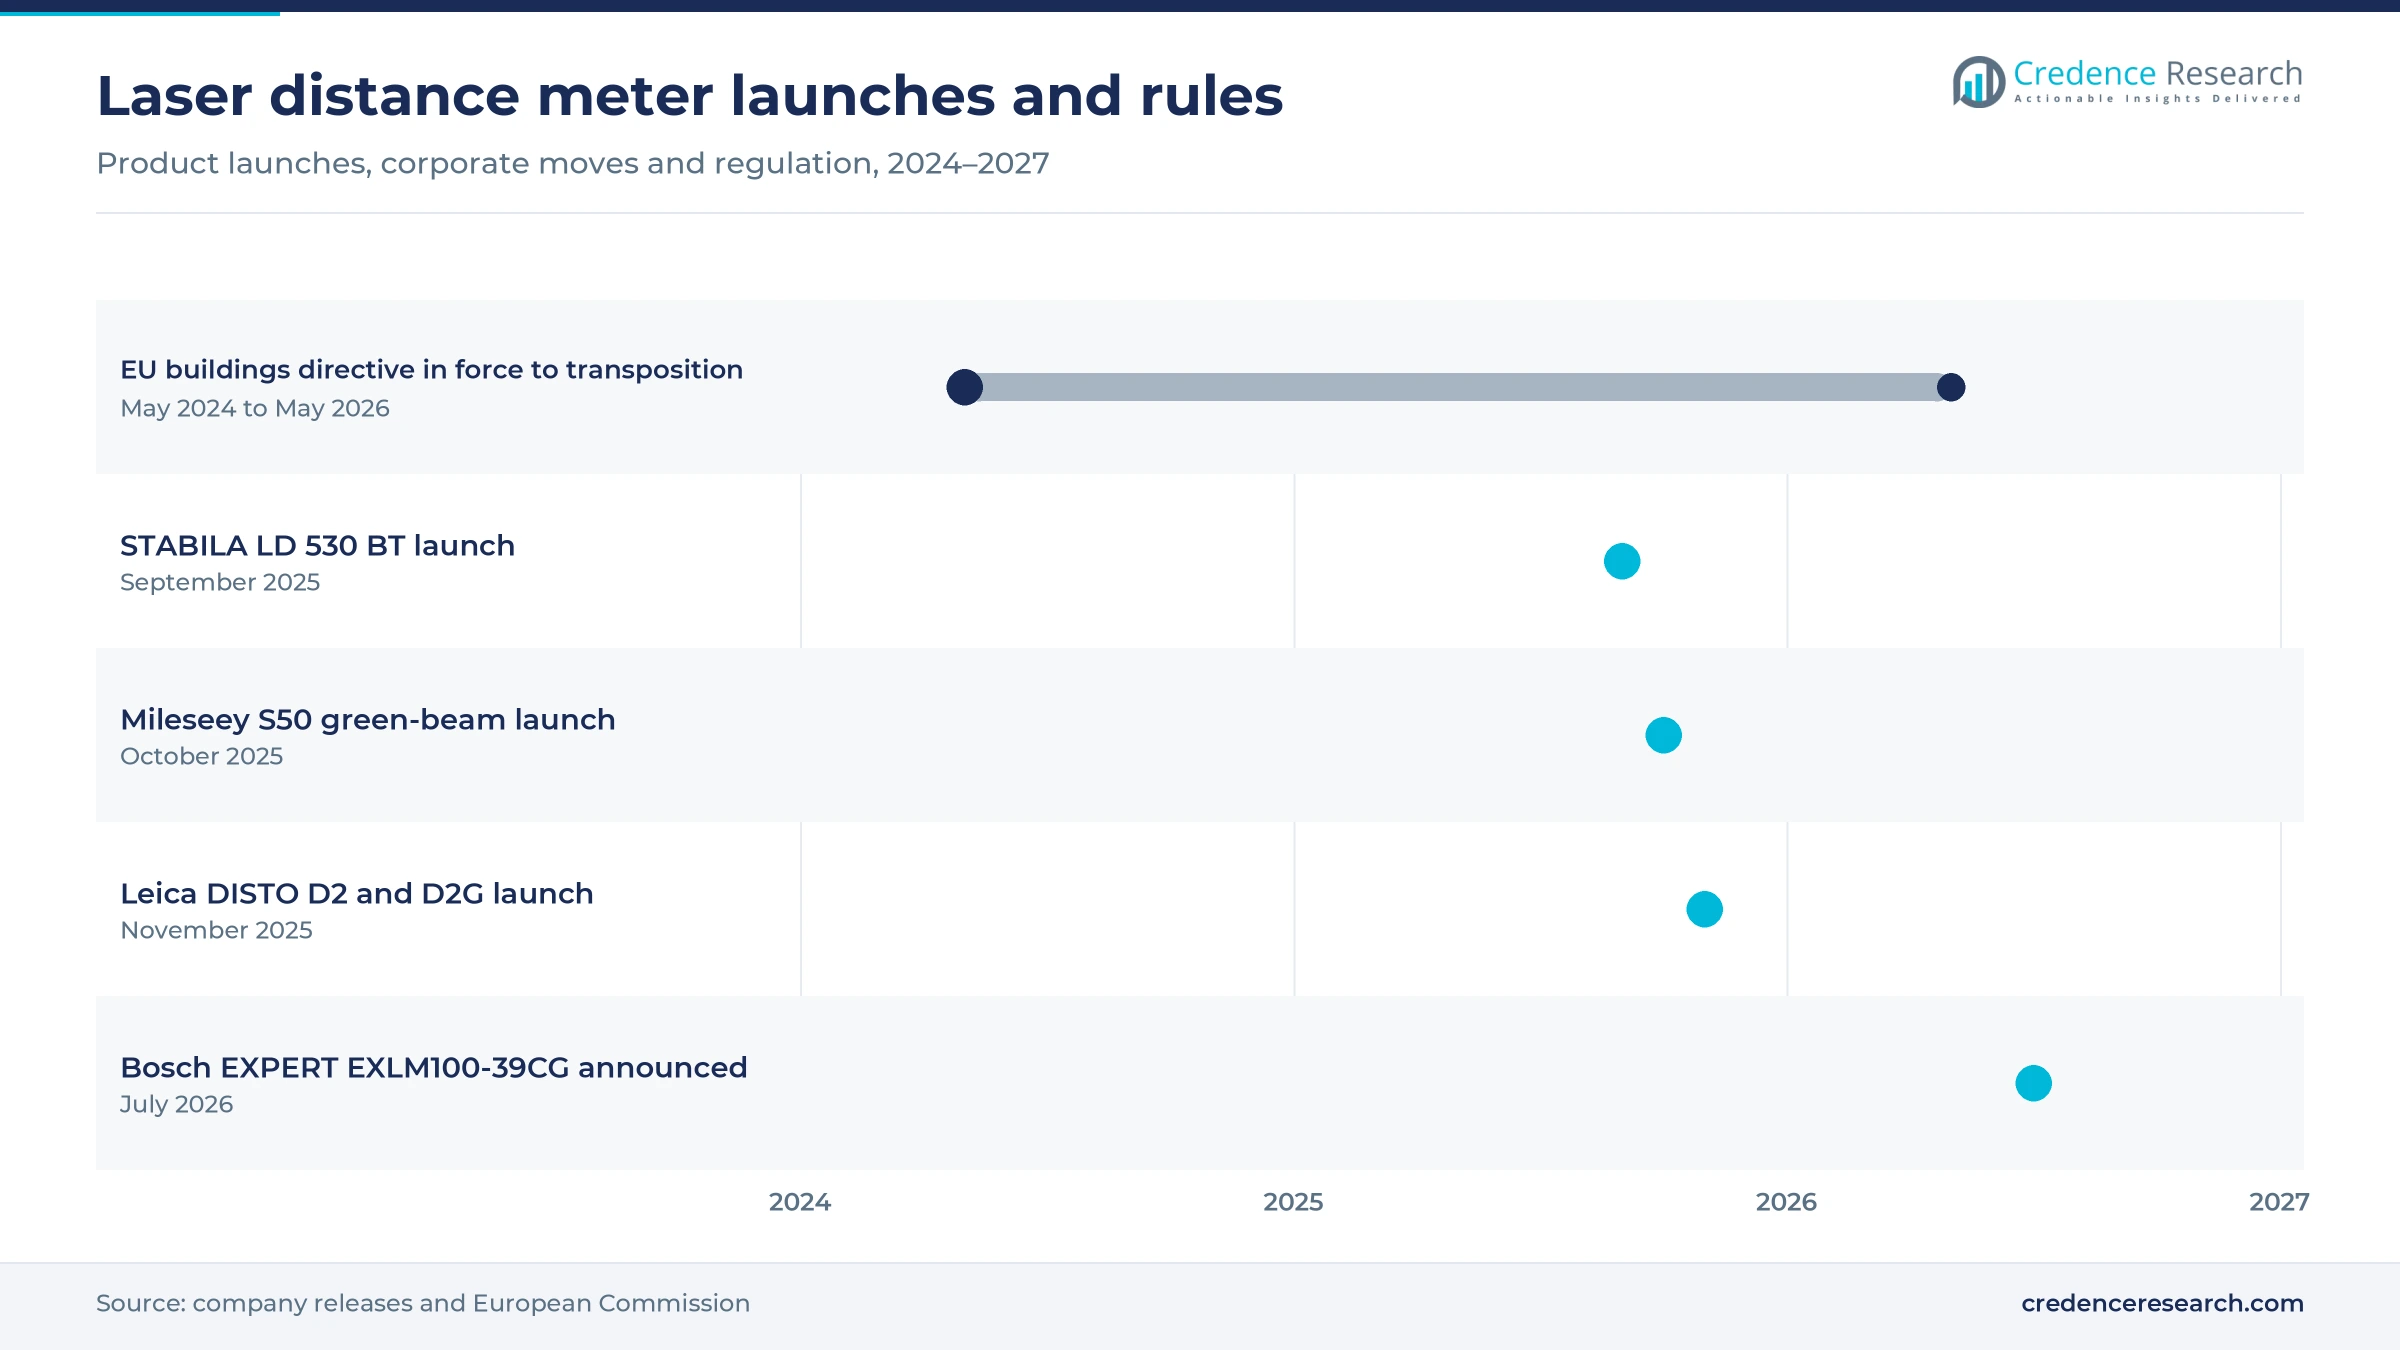
The revised EU buildings directive creates a clear opening for meter suppliers, because renovation programs start with surveys of floor areas, window openings and wall lengths. Directive (EU) 2024/1275 entered into force on May 28, 2024, and member states had to transpose it by May 29, 2026. Minimum standards are expected to trigger renovation of the 16% worst-performing nonresidential buildings by 2030 and the 26% worst by 2033, while residential primary energy use must fall 16% by 2030. Buildings account for about 40% of EU energy use, according to the European Commission. Energy assessors, retrofit contractors and window installers are the customer groups, and meters with floor-plan export cut survey time.
Indian public works offer a volume opening for value brands
Large Indian public works programs offer an opening for suppliers that can sell durable meters at low prices through contractor dealers. The Union Budget for 2025-26 allocated Rs 11.21 lakh crore to capital expenditure, according to All India Radio, and railway gross budgetary support exceeded Rs 2.52 lakh crore. Rail stations, metro lines and housing projects need site engineers and finishing crews who measure daily, and most still use tapes. Asia Pacific is the fastest-growing region in the Credence Research estimate, with India adding the most first-time buyers. Suppliers that combine local service with entry prices near the USD 40 level shown in the price table can capture first-time professional buyers.
Housing slump, phone apps and tariffs restrain volume
Housing downturns cut entry-level and DIY volume
Weak homebuilding reduces the number of new installers and home improvers buying entry meters. U.S. single-family starts fell 6.9% in 2025 and total housing completions fell 7.9%, according to the Census Bureau. In China, real estate development investment fell 17.2% in 2025 and new construction starts by floor area fell 20.4%, according to National Bureau of Statistics data. Brands that depend on residential trades and big-box sales are most exposed, while suppliers selling to civil contractors feel less pressure.
Smartphone measuring apps replace meters for rough jobs
Phones with depth sensors now handle many rough measurements that once justified a basic meter. SlashGear tested an iPhone 14 Pro in June 2025 and found that its Measure app stayed within 3% to 5% of a tape, good enough for home decorating but not for exact work. That level of error removes part of the casual DIY buyer base, which hurts low-priced online brands most. Professional trades still need millimeter accuracy, so mid-range and premium meters are less exposed.
Tariffs on Chinese-made tools raise landed costs
Much of the world supply of meters is assembled in China, so U.S. tariffs raise landed cost for brands that import finished units. Stanley Black & Decker, which owns DEWALT, told investors in February 2025 that tariffs on Chinese imports would raise its U.S. tool costs and that it would offset them with price increases and supply-chain moves. Brands without non-China assembly face margin loss or price increases, which slows replacement buying.
Laser safety rules raise entry costs for small importers
Laser meters fall under U.S. radiation-emitting product rules, which add paperwork for every new model and importer. Products must meet 21 CFR 1040.10 and 1040.11, carry Class II warning labels for outputs up to about 1 mW and be reported to the FDA on Form 2877 at import, according to a ComplianceGate summary of the federal rules. Marketplace sellers of unbranded meters are most exposed, because customs holds or listing removals interrupt sales, while established brands absorb the cost across many models.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
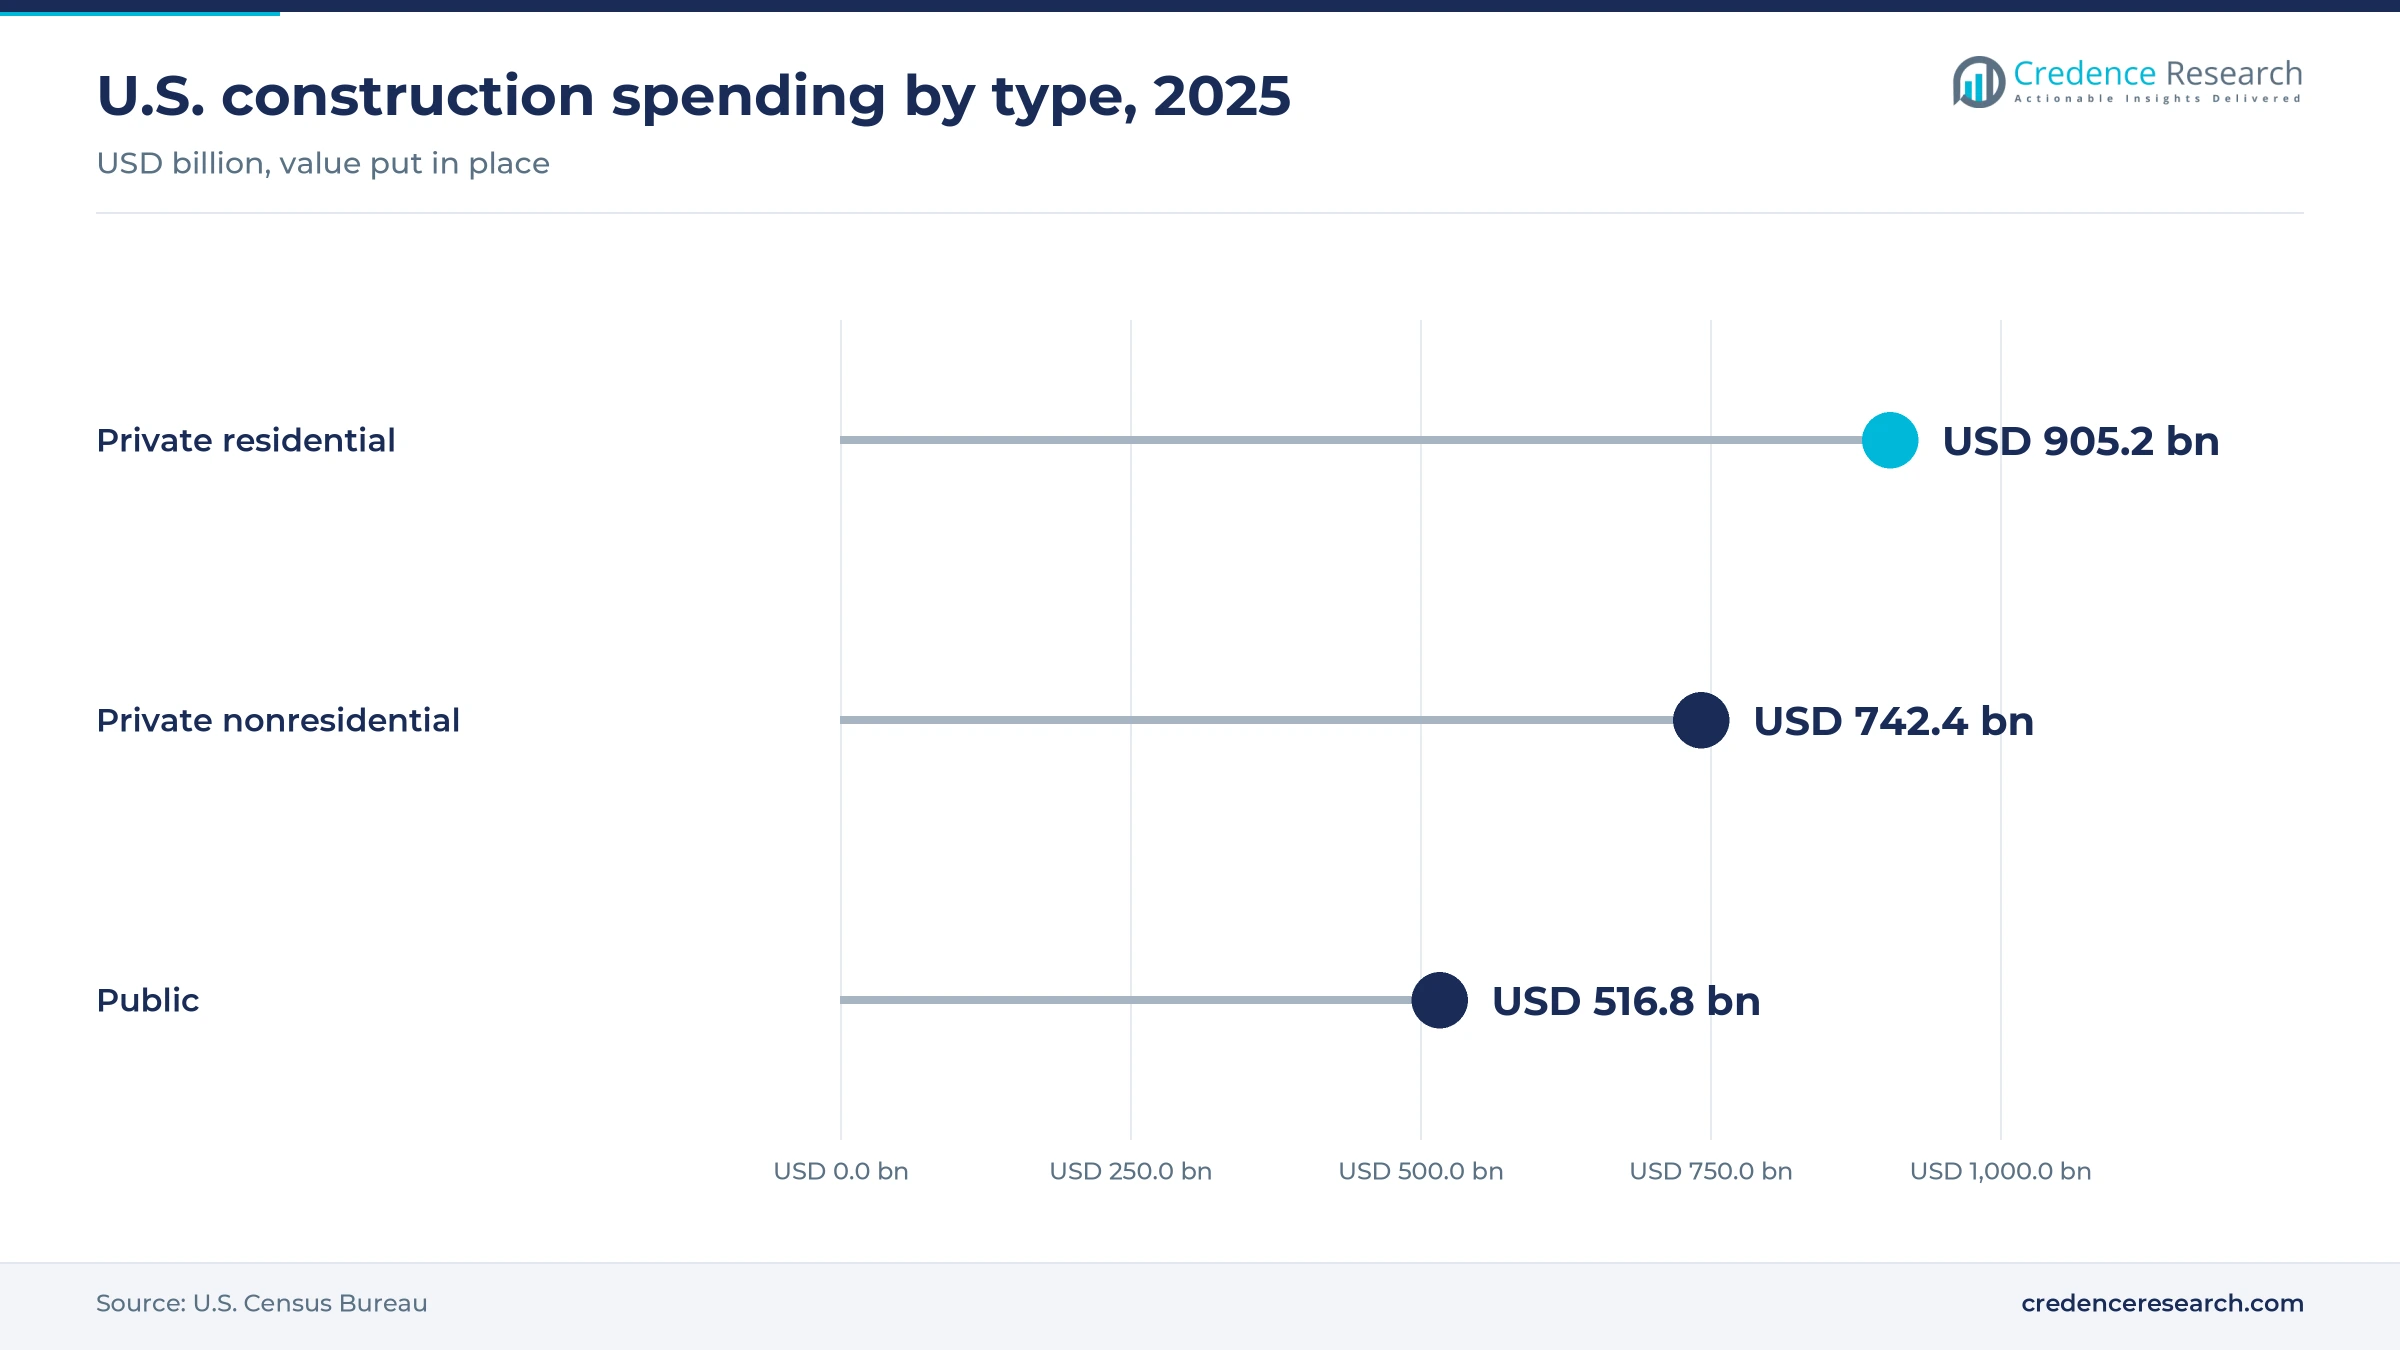
| North America | 0.67 | 32.0% | 6.0% |
| Europe | 0.60 | 29.0% | 5.7% |
| Asia Pacific | 0.56 | 27.0% | 7.4% |
| Latin America | 0.15 | 7.0% | 6.8% |
| Middle East & Africa | 0.10 | 5.0% | 7.1% |
North America leads on professional trades and big-box retail
North America held 32.0% of 2025 value and grows at 6.0% a year. U.S. construction spending totaled USD 2,164.4 billion in 2025, down 1.4% from 2024, according to the Census Bureau, so unit demand from new building is flat. Value still leads because U.S. trades buy professional meters tied to battery platforms from Milwaukee Tool, DEWALT and Bosch, and big-box retailers stock dozens of models. Canada adds smaller volumes through the same brands, while Mexico buys mostly entry-level imports, a Credence Research estimate.
Europe holds premium brands but faces flat building output
Europe held 29.0% of 2025 value and grows at 5.7% a year, the slowest regional rate. Eurostat reported that construction output was unchanged in the euro area in 2025 and rose 0.5% across the EU, and that leaves unit demand subdued. The region still carries high value per unit because Bosch, STABILA, Hilti and Leica Geosystems design premium meters there and sell them through specialist dealers. The renovation rules described above give Germany, France and the Nordic countries the clearest new source of assessor and retrofit demand.
Asia Pacific grows fastest as Chinese brands scale and India builds
Asia Pacific held 27.0% of 2025 value and grows fastest at 7.4% a year. China is the main production base, and Mileseey says it holds more than 30% of the Chinese domestic market. Chinese demand is weak after the property slump described above, with total fixed-asset investment down 3.8% in 2025, according to China Briefing citing official data. Growth therefore comes from India, Southeast Asia and Australia, where public works and finishing trades are moving from tapes to entry-level and mid-range meters.
Latin America buys mainly entry-level imports
Latin America held 7.0% of 2025 value and grows at 6.8% a year. Brazil and Mexico account for most demand, served by global tool brands through hardware chains and by Chinese brands through online marketplaces. Public data on meter sales in the region are thin, so the split across countries rests on Credence Research estimates, and price sensitivity keeps most purchases in the standard handheld tier.
Middle East and Africa grow on Gulf projects
The Middle East and Africa held 5.0% of 2025 value and grow at 7.1% a year. Gulf construction and fit-out contractors buy professional meters through Hilti and regional tool distributors, while African demand is small and concentrated in South Africa. No public statistic measures meter sales in the region, so the estimate relies on Credence Research modeling of construction activity and tool imports.
Camera, green-beam and sensor-fusion launches mark 2025-26
| Development | Status and market relevance |
|---|---|
| In September 2025, STABILA launched the LD 530 BT with a 200-meter range, a 4x zoom target camera and gesture-controlled triggering. | Product launch, commercially available; it brings contact-free triggering to a mid-priced professional meter. |
| In October 2025, Mileseey Tools launched its S50 green-beam meter with a 400-foot range and app syncing. | Product launch; it extends green-beam visibility into the value price tier sold online. |
| In November 2025, Leica Geosystems launched the DISTO D2 and D2G, adding inertial floor-plan capture and NFC transfer. | Product launch, available through Leica online shops; it moves floor-plan features into mid-priced meters. |
| In July 2026, Bosch announced the EXPERT EXLM100-39CG with Dynamic Sensor Fusion and three new measurement modes. | Announcement, availability date not stated; it raises the feature bar for professional meters. |
Aiming aids and data links now separate the price tiers
- Phase-shift ranging measures the phase difference of a modulated beam and gives most handheld meters millimeter accuracy at short and medium range.
- Pulse ranging times reflected pulses in the way time-of-flight sensors do, which helps long-range outdoor models read dark or distant targets.
- Digital target cameras show the target on a zoomable screen when the dot disappears in sunlight, which makes 200-meter readings practical outdoors.
- Inertial and tilt sensors compute horizontal distances over obstacles and build floor plans as the user walks through a room.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Tool brands compete on platforms, dealers and apps
Competition runs on three axes, aiming and accuracy features, battery and tool platforms, and the app that holds the user's measurements. Leica Geosystems, part of Hexagon, anchors the premium tier with the DISTO range and floor-plan software, while Hilti sells through its direct sales force to large contractors. Bosch covers every tier from DIY to professional and brings sensor fusion into its EXPERT line. Milwaukee Tool and DEWALT sell meters alongside cordless power tool platforms, which gives them shelf space in big-box stores and trade counters. STABILA and Fluke sell precision instruments to trades and maintenance teams, Makita and Klein Tools serve electricians and installers, and Mileseey competes on price through direct online sales and retailer partnerships. Chinese private-label suppliers keep entry prices low, which pushes branded vendors toward features buyers can see.
How concentrated is the supply side?
Supply splits between a few premium brand owners and a large base of Chinese manufacturers that build own-brand and private-label meters. China exported USD 363 million of rangefinders under HS code 901510 in 2023, down from USD 380 million in 2022, according to UN Comtrade data published by TrendEconomy, and that code also covers golf and hunting units. Barriers sit in brands, dealer access, battery platforms and apps rather than in the laser module itself. Margins are highest for camera and software-linked models and thinnest for marketplace pocket meters.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Hexagon AB (Leica Geosystems) | Premium specialist | DISTO meters with cameras, floor-plan capture and DISTO Plan app |
| Robert Bosch GmbH (Bosch Power Tools) | Full-line supplier | GLM and EXPERT meters from DIY to professional camera models |
| Hilti Group | Direct-sales specialist | PD series meters sold to contractors through direct sales and stores |
| Stanley Black & Decker (DEWALT) | Tool platform brand | DEWALT and STANLEY pocket and professional meters for trades |
| Techtronic Industries (Milwaukee Tool) | Tool platform brand | Milwaukee laser distance meters sold with trade tool platforms |
| Fluke Corporation (Fortive) | Instrument specialist | Laser distance meters for electrical and maintenance teams |
| Makita Corporation | Tool platform brand | Laser distance meters sold alongside Makita cordless tools |
| STABILA Messgeräte | Precision specialist | LD series meters with cameras, Bluetooth and Measures II app |
| Klein Tools | Trade hand-tool brand | Compact and Bluetooth meters for electricians and installers |
| Mileseey Tools | Value manufacturer | Own-brand and partner meters, green-beam models sold online |
Value is moving from the laser module to the workflow
Credence Research's view is that value in this market is moving from the laser module to the workflow around it. Range and accuracy are now similar across brands, so buyers choose on cameras, green beams, battery platforms and the app that turns readings into plans or reports. That favors Leica Geosystems, Bosch and STABILA in the premium tier, and tool-platform brands in the trade tier. Chinese manufacturers will keep entry prices low, so suppliers without a software or platform advantage face steady margin pressure.
Trade data and price points anchor the estimate
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which replaces the earlier 2024 estimate on this page after checking it against trade data, retail price points and unit estimates. Regional and segment splits are Credence Research estimates built from public construction and trade data. Sources include UN Comtrade data, the U.S. Census Bureau, Eurostat, the European Commission, company releases, retailer listings and trade press. No interviews or surveys were conducted for this edition of the report. No public statistic separates handheld meters from golf and hunting rangefinders, so the trade-based check carries the most uncertainty.
Mix upgrades carry value faster than unit volume
Through 2035, the value of laser distance measurers should grow faster than unit volume, because buyers keep trading up to camera, green-beam and app-linked meters. Mature markets will add few new users, while India and Southeast Asia bring first-time professional buyers. European renovation surveys and civil works support premium demand, and smartphone apps take more of the casual market. Brands that own battery platforms or measurement software are best placed, while private-label suppliers compete mainly on price.
Construction recovery and feature mix decide the range to 2035
The outcome depends on two variables, how quickly housing and building output recovers in the U.S., Europe and China, and how fast buyers trade up to camera and app-linked meters. The downside case assumes a prolonged housing slump and wider smartphone substitution in the entry tier. The upside case assumes renovation programs in Europe and public works in India lift professional purchases faster than expected. The base case sits between them, with flat unit volume offset by steady trade-up to premium features.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.9% | USD 3.40 billion | Housing stays weak and phone apps take most casual measuring |
| Base | 6.40% | USD 3.87 billion | Flat unit volume in mature markets with steady trade-up to premium features |
| Upside | 7.8% | USD 4.35 billion | EU renovation surveys and Indian public works accelerate professional buying |
Frequently Asked Questions
How big is the laser distance measurers market?
What does the handheld laser meter market include?
Which end use holds the largest share?
Which region leads the laser distance measurers market?
How does a laser measuring instrument differ from a phone app?
Who are the leading companies in this market?
How much does a laser distance meter cost?
What are the main trends in laser measurement systems?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Standard Handheld
- 1.2.2 Advanced Professional-Grade
- 1.3 By Distance Range
- 1.3.1 Up to 50 Meters
- 1.3.2 50 to 200 Meters
- 1.3.3 Above 200 Meters
- 1.4 By End Use
- 1.4.1 Building & Construction
- 1.4.2 Manufacturing & Industrial
- 1.4.3 Mining
- 1.4.4 Aerospace
- 1.4.5 Others (Agriculture, Real Estate)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.08 billion → 2035: USD 3.87 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laser Distance Measurers Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laser Distance Measurers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laser Distance Measurers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laser Distance Measurers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laser Distance Measurers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laser Distance Measurers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laser Distance Measurers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laser Distance Measurers Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.08 billion → 2035: USD 3.87 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laser Distance Measurers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Standard Handheld
- 12.3.7.2 Advanced Professional-Grade
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Distance Range - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Up to 50 Meters
- 12.4.7.2 50 to 200 Meters
- 12.4.7.3 Above 200 Meters
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Building & Construction
- 12.5.7.2 Manufacturing & Industrial
- 12.5.7.3 Mining
- 12.5.7.4 Aerospace
- 12.5.7.5 Others (Agriculture, Real Estate)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laser Distance Measurers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Laser Distance Measurers Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Laser Distance Measurers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Laser Distance Measurers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hexagon AB (Leica Geosystems)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Robert Bosch GmbH (Bosch Power Tools)
- 18.4 Hilti Group
- 18.5 Stanley Black & Decker (DEWALT)
- 18.6 Techtronic Industries (Milwaukee Tool)
- 18.7 Fluke Corporation (Fortive)
- 18.8 Makita Corporation
- 18.9 STABILA Messgeräte
- 18.10 Klein Tools
- 18.11 Mileseey Tools
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

