
Market Overview:
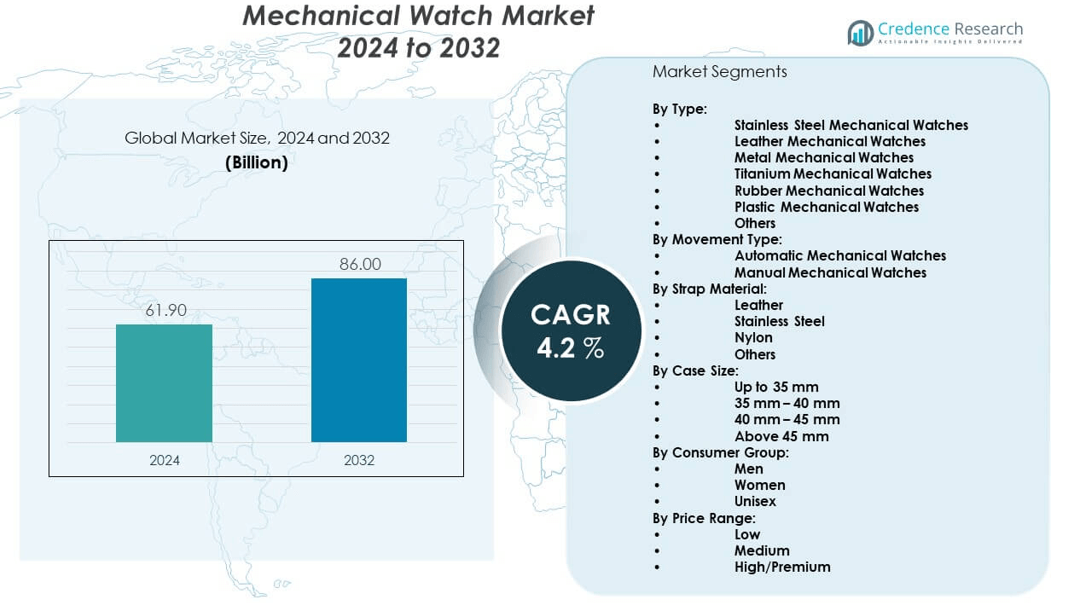
The Mechanical watch market is projected to grow from USD 61.9 billion in 2024 to an estimated USD 86.0 billion by 2032, with a compound annual growth rate (CAGR) of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mechanical Watch Market Size 2024 | USD 61.9 billion |
| Mechanical Watch Market, CAGR | 4.2% |
| Mechanical Watch Market Size 2032 | USD 86.0 billion |
The mechanical watch market is fueled by increasing consumer preference for luxury accessories and rising brand heritage value. Collectors and enthusiasts drive demand for high-end models, while innovations in design and customization expand consumer reach. Marketing strategies by luxury houses strengthen brand exclusivity and attract new buyers. Growing disposable incomes in emerging markets increase purchasing capacity, and demand for limited-edition watches fuels brand competitiveness. Mechanical watches are increasingly seen as investment pieces, boosting secondary market growth.
Europe leads the mechanical watch market due to Switzerland’s dominance in production and heritage brands. North America follows with strong consumer appetite for luxury watches, supported by established retail and online distribution. Asia Pacific is emerging as the fastest-growing region, driven by rising wealth in China and India alongside growing brand penetration. Middle East markets, supported by luxury retail hubs, contribute to steady demand. Latin America and Africa remain smaller but are gradually witnessing interest from affluent urban consumers.
Market Insights:
- The mechanical watch market is projected to grow from USD 61.9 billion in 2024 to USD 86.0 billion by 2032, at a CAGR of 2%.
- Growing demand for luxury and heritage timepieces drives consumer preference for artisanal craftsmanship and exclusivity.
- Rising disposable incomes in emerging economies such as China and India fuel luxury watch adoption.
- Increasing competition from smartwatches and connected devices restrains growth among younger demographics.
- Supply chain complexities, rising raw material costs, and the threat of counterfeits challenge market expansion.
- Europe dominates the global market due to Switzerland’s heritage brands and strong production ecosystem.
- Asia Pacific is the fastest-growing region, driven by rising affluence, urbanization, and expanding luxury retail networks.
Market Drivers:
Rising Demand for Luxury and Heritage Watches:
The mechanical watch market is driven by the growing demand for luxury timepieces that embody heritage and craftsmanship. Consumers view these watches as symbols of prestige, wealth, and refined taste. The continued focus on artisanal production and handmade detailing appeals to collectors and enthusiasts worldwide. High-end watchmakers leverage their heritage value to strengthen brand positioning and consumer loyalty. Marketing campaigns highlight heritage, tradition, and exclusivity, creating strong emotional appeal. Growing interest in limited editions adds scarcity-driven value, further fueling demand. Rising global wealth among affluent consumers supports the purchasing power for premium watches. The ability of mechanical watches to retain and appreciate in value makes them attractive as investments.
- For instance, Rolex introduced the Land-Dweller in 2025, featuring the new Caliber 7135, a high-frequency mechanical movement beating at 36,000 vibrations per hour with a 66-hour power reserve, showcasing advanced craftsmanship and technical innovation.
Influence of Emerging Economies and Consumer Affluence:
Expanding disposable incomes in emerging economies strongly influence the growth of the mechanical watch market. Countries such as China, India, and Brazil witness a rising population of affluent consumers with luxury aspirations. Demand for high-end accessories increases alongside expanding urbanization and lifestyle shifts. International brands expand their retail networks in these regions to capture rising demand. Younger generations in emerging economies increasingly embrace luxury fashion, fueling purchases of premium timepieces. Cultural emphasis on status and lifestyle positioning drives adoption of watches as identity symbols. Mechanical watches serve as aspirational products for growing middle-class consumers. Strong demand for international brands creates opportunities for both flagship stores and e-commerce distribution.
- For instance, luxury brands like Patek Philippe have introduced highly complicated models such as the Quadruple Complication Reference 5308G-001, powered by a self-winding movement with 799 components, appealing to discerning affluent buyers in emerging markets.
Expansion of Personalization and Customization in Luxury Watches:
The growing trend of personalization significantly drives adoption across the mechanical watch market. Consumers desire products that reflect their identity, leading to demand for customized dials, straps, and engravings. Brands expand offerings with bespoke services to meet evolving consumer expectations. Customization enhances exclusivity, reinforcing the unique value of mechanical timepieces. Premium watchmakers increasingly highlight limited-edition personalized collections that appeal to collectors. Personalized design options support brand differentiation in a competitive luxury landscape. Expanding online platforms offer digital tools that allow customers to design unique elements. Growing appeal of tailored luxury strengthens long-term customer engagement and brand loyalty.
Perception of Watches as Collectible and Investment Assets:
The perception of mechanical watches as long-term investments drives demand in global markets. Collectors and enthusiasts view rare models as appreciating assets with significant resale value. Auctions of vintage and limited-edition watches further highlight the profitability of collecting. Luxury watchmakers intentionally design scarce models to enhance long-term value retention. Rising investor interest in tangible assets encourages purchases beyond traditional financial instruments. Brands emphasize craftsmanship and longevity to reinforce the appeal of watches as heirlooms. High-profile auctions and celebrity endorsements amplify consumer interest in collectible watches. It positions mechanical timepieces as both functional accessories and strategic investment assets.
Market Trends:
Digital Integration in Luxury Watch Retail:
The mechanical watch market is witnessing a growing trend toward digital retail channels and online platforms. Luxury brands strengthen e-commerce presence to connect with global consumers more effectively. Exclusive online launches and digital marketing campaigns attract younger audiences. Virtual showrooms and augmented reality experiences allow customers to preview watches remotely. Social media plays a key role in shaping consumer awareness and influencing purchase decisions. Digital communities and forums drive engagement among collectors and enthusiasts. Rising demand for seamless online transactions encourages luxury houses to integrate secure payment systems. Online distribution strategies expand consumer reach and strengthen brand accessibility.
- For instance, TAG Heuer launched nine new Formula 1 Solargraph watches in 2025, featuring a 38 mm case and powered by an eco-friendly solar movement, leveraging digital marketing to reach a younger, tech-savvy demographic.
Focus on Sustainability and Ethical Sourcing:
Sustainability emerges as a significant trend shaping the mechanical watch market. Consumers increasingly prefer brands that adopt ethical sourcing of materials such as gold and leather. Watchmakers introduce eco-friendly straps and recycled materials to meet rising demand. Transparency in supply chains builds consumer trust and enhances brand reputation. Sustainability certifications and eco-conscious branding strengthen differentiation in the luxury segment. Awareness of environmental impacts influences younger buyers, prompting a shift in purchasing patterns. Partnerships with sustainability organizations reinforce brand positioning in ethical markets. It aligns consumer values with luxury purchasing behavior, ensuring long-term brand credibility.
- For instance, the Swatch Sistem51 collaboration uses an automatic movement constructed from 51 components welded together via friction welding, reducing material waste and energy consumption.
Rising Popularity of Vintage and Retro-Inspired Watches:
Vintage-inspired designs shape demand trends within the mechanical watch market. Consumers increasingly value retro styling and classic aesthetics linked to brand heritage. Watchmakers revive archival models to appeal to nostalgic and design-conscious buyers. Vintage pieces command high resale value in auctions, strengthening their popularity. Retro-themed limited editions enhance exclusivity and fuel collector interest. Millennials and Gen Z audiences embrace retro designs as fashionable lifestyle choices. The blending of modern mechanics with vintage aesthetics strengthens product appeal. Heritage-focused strategies build stronger consumer engagement across diverse demographic groups.
Expansion of Secondary Luxury Watch Marketplaces:
The secondary market for mechanical watches grows rapidly, supported by rising collector demand. Platforms specializing in resale and auctions expand global accessibility of pre-owned luxury models. Authentication services and warranties strengthen buyer confidence in secondary transactions. Watch brands engage directly with resale platforms to regulate and control brand image. Growth of secondary markets reinforces the investment value of rare mechanical watches. E-commerce channels drive international resale opportunities, reaching younger consumers. Consumer trust in resale platforms grows due to improved transparency and certification. The expansion of the resale market reshapes luxury consumption and supports long-term market growth.
Market Challenges Analysis:
Rising Competition from Smartwatches and Digital Devices:
The mechanical watch market faces significant challenges from the rapid growth of smartwatches and connected devices. Consumers seeking advanced features such as health monitoring, GPS, and connectivity often prefer digital alternatives. Younger audiences show a strong preference for multifunctional smartwatches, reducing interest in traditional models. High adoption rates of wearable technology in Asia and North America add pressure to luxury watchmakers. The need to balance heritage-driven mechanical designs with modern relevance creates strategic difficulties. Luxury brands attempt to counter this trend by emphasizing craftsmanship, legacy, and emotional value. It highlights the need for strong brand differentiation to retain market position. Long-term risks exist if the generational shift toward digital devices continues unchecked.
Rising Costs and Supply Chain Complexities in Luxury Production
Supply chain challenges and rising costs represent major hurdles for the mechanical watch market. Luxury watchmakers depend on rare materials, specialized components, and skilled labor. Fluctuations in raw material prices, including gold and steel, directly affect profitability. Skilled artisans are limited, making scaling production without quality loss difficult. Global disruptions such as trade conflicts and logistic delays intensify production uncertainties. High regulatory requirements for exports also add complexity to cross-border sales. Counterfeit watches create brand dilution and threaten market integrity. It underscores the importance of stronger supply chain resilience and authenticity controls to secure long-term growth.
Market Opportunities:
Expansion into Emerging Markets with Rising Luxury Aspirations:
Expanding into emerging markets presents strong opportunities for the mechanical watch market. Rising affluence in Asia, the Middle East, and Latin America fuels luxury purchases. Urbanization and lifestyle upgrades increase consumer interest in high-end accessories. Global brands open flagship boutiques and retail partnerships to capture this demand. E-commerce and cross-border platforms further ease entry into these regions. Younger consumers view mechanical watches as aspirational products symbolizing achievement and success. It creates long-term revenue opportunities and strengthens global brand presence. Strong growth potential exists as wealth and disposable income continue to rise.
Leveraging Collaborations and Limited-Edition Launches for Brand Differentiation:
Collaborations and exclusive launches provide opportunities to strengthen brand appeal within the mechanical watch market. Partnerships with fashion houses, automotive brands, and celebrities enhance product visibility. Limited editions create scarcity value and fuel collector-driven demand. Creative collaborations appeal to younger demographics seeking unique luxury experiences. Exclusive launches expand brand storytelling and marketing opportunities. The resale market amplifies the value of limited-edition collaborations. Strong collaborative strategies secure lasting customer engagement and reinforce luxury brand loyalty.
Market Segmentation Analysis:
By Type
Stainless steel mechanical watches lead the market due to strength, durability, and timeless appeal. Leather variants attract traditional buyers who value elegance and craftsmanship. Titanium and metal models appeal to premium consumers seeking lightweight and durable options. Rubber and plastic watches cater to sporty or affordable categories, while niche demand exists for others such as ceramic or hybrid materials.
- For instance, Panerai’s 2025 Luminor Marina collection features titanium and steel cases with enhanced water resistance up to 500 meters and the new P.980 automatic movement, balancing durability with sophisticated engineering.
By Movement Type
Automatic mechanical watches dominate as they combine convenience with prestige and collector appeal. Manual watches hold a smaller yet loyal segment, appealing to enthusiasts who appreciate heritage and craftsmanship in winding mechanisms.
- For instance, Rolex’s newly introduced Caliber 7135 automatic movement boasts a high beat rate of 36,000 bph and a robust 66-hour power reserve, integrating the patented Dynapulse escapement for improved efficiency and precision.
By Strap Material
Leather and stainless steel straps lead due to sophistication, comfort, and longevity. Nylon options attract younger buyers seeking casual and practical styles. Other strap materials serve niche preferences and limited editions.
By Case Size
Watches sized 40 mm–45 mm dominate men’s collections, reflecting bold and modern tastes. Smaller cases up to 35 mm remain popular among women and minimalistic buyers. Medium sizes of 35 mm–40 mm serve balanced unisex preferences, while above 45 mm caters to luxury and statement models.
By Shape
Rectangular and round watches dominate sales, linked to tradition and versatility. Square models appeal to design-focused consumers seeking unique aesthetics.
By Consumer Group
Men account for the largest share, supported by strong luxury demand. Women’s and unisex categories expand steadily as fashion-driven demand rises globally.
By Price Range and Distribution
High and premium watches drive growth in the mechanical watch market, supported by luxury aspirations. Medium and low ranges attract aspirational buyers. Offline boutiques dominate, though online channels gain traction with global accessibility and digital engagement.
Segmentation:
By Type:
- Stainless Steel Mechanical Watches
- Leather Mechanical Watches
- Metal Mechanical Watches
- Titanium Mechanical Watches
- Rubber Mechanical Watches
- Plastic Mechanical Watches
- Others
By Movement Type:
- Automatic Mechanical Watches
- Manual Mechanical Watches
By Strap Material:
- Leather
- Stainless Steel
- Nylon
- Others
By Case Size:
- Up to 35 mm
- 35 mm – 40 mm
- 40 mm – 45 mm
- Above 45 mm
By Shape:
- Rectangular and Round
- Square
By Consumer Group:
- Men
- Women
- Unisex
By Price Range:
- Low
- Medium
- High/Premium
By Distribution Channel:
- Online
- Offline
Regional Analysis:
North America and Europe
North America accounts for 28% of the mechanical watch market, supported by strong demand in the United States and Canada. Luxury timepieces remain popular among affluent consumers seeking heritage and brand prestige. The presence of established retail networks, high disposable income, and digital luxury platforms drives steady growth. Europe holds the largest share at 36%, led by Switzerland, France, and Germany. Switzerland dominates global production with brands such as Rolex, Omega, and Patek Philippe, strengthening Europe’s leadership. Fashion-conscious buyers in Western Europe and tourist-driven luxury purchases continue to sustain the regional advantage. Both regions benefit from brand heritage, investment appeal, and a stable consumer base.
Asia Pacific
Asia Pacific captures 24% of the mechanical watch market, making it the fastest-growing region. Rising affluence in China, India, and Southeast Asia fuels demand for luxury watches. Expanding urbanization and a growing middle class create opportunities for premium and aspirational models. Global brands strengthen presence with flagship boutiques and partnerships in leading cities. Younger generations in Asia embrace watches as symbols of achievement and lifestyle enhancement. It highlights the potential for long-term dominance as wealth expands across regional economies. The combination of aspirational demand and retail expansion continues to accelerate growth.
Middle East, Latin America, and Africa
The Middle East contributes 7% of the mechanical watch market, driven by luxury hubs in the UAE and Saudi Arabia. Demand is supported by affluent consumers who value exclusivity and premium brands. Latin America holds 3%, with Brazil and Mexico leading sales through rising urban luxury consumption. Africa accounts for 2%, supported by niche demand in South Africa and growing interest in premium fashion accessories. It remains a smaller share but reflects untapped potential with emerging urban centers. The regions together highlight opportunities for market expansion through targeted luxury marketing and boutique investments. Growth depends on rising wealth concentration and consumer access to global watch brands.
Key Player Analysis:
- Rolex
- Patek Philippe
- TAG Heuer
- IWC
- Omega
- Tudor
- Blancpain
- Panerai
- Jaeger-LeCoultre (JLC)
- Cartier
- Richard Mille
- Piaget
- Chopard
- Hublot
- Breitling
- Rado
- Fossil Group
- Seiko Holdings Corporation
- Casio
- The Swatch Group Ltd
Competitive Analysis:
The mechanical watch market is highly competitive, with dominance by luxury brands and established global players. Companies such as Rolex, Omega, Patek Philippe, and Cartier maintain strong positions through heritage, craftsmanship, and exclusivity. Swiss brands lead with innovation, legacy, and investment-driven appeal, while Japanese groups like Seiko and Casio capture mass and mid-tier segments. The Swatch Group consolidates multiple brands across price ranges, reinforcing its global reach. Fossil Group targets fashion-conscious consumers through accessible premium designs. It remains a market where brand equity, distribution strategies, and product differentiation define long-term competitiveness.
Recent Developments:
- Panerai revealed a revamped Luminor Marina collection with titanium and steel models featuring Super-LumiNova X2, enhanced water resistance up to 500 meters, and the new P.980 automatic movement. They also released the high-complication Luminor Perpetual Calendar GMT Platinumtech with a sapphire crystal dial and intuitive perpetual calendar.
- In 2025, Rolex launched the new Land-Dweller model during Watches and Wonders, featuring an ultra-thin case 20% thinner than the Datejust and Rolex’s first high-frequency mechanical movement, Caliber 7135, available in 36 mm and 40 mm sizes with Oystersteel, Everose gold, and Platinum options.
- In 2025, Patek Philippe introduced 15 new models including the Quadruple Complication Reference 5308G-001 with minute repeater, perpetual calendar, and split-seconds chronograph, powered by a new self-winding movement with 799 components and patented energy management technologies.
Market Concentration & Characteristics:
The mechanical watch market is moderately concentrated, with Switzerland-based brands commanding the largest share of global revenues. It is characterized by strong brand loyalty, limited-edition launches, and a focus on heritage-driven marketing. High barriers to entry exist due to the craftsmanship, legacy value, and distribution networks required to compete. Mid-tier and entry-level segments remain fragmented, supported by Asian and fashion-focused brands. It reflects a blend of luxury dominance, niche artisanal makers, and affordable mechanical watch producers.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Movement Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing consumer interest in heritage craftsmanship will sustain demand for premium models.
- Expansion in Asia Pacific will drive the fastest regional growth.
- Online retail and digital showrooms will strengthen brand accessibility.
- Rising demand for customization will shape product development strategies.
- Collaborations and limited editions will fuel collector-driven sales.
- Vintage-inspired designs will appeal to younger and nostalgic buyers.
- Sustainability and ethical sourcing will influence purchase decisions.
- Secondary resale markets will expand, reinforcing watches as investment assets.
- Competition with smartwatches will continue to pressure entry-level models.
- Luxury houses will strengthen exclusivity through flagship stores and boutique expansions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Luxury and Heritage Appeal
Mechanical watches are seen as symbols of prestige, craftsmanship, and tradition, attracting collectors and affluent consumers who value exclusivity and brand heritage. This perception drives demand for high-end and limited-edition models.
Rising Affluence in Emerging Markets
Increasing disposable incomes in countries like China, India, and Brazil are expanding the consumer base for luxury mechanical watches, as more individuals aspire to own premium accessories that signify status and achievement.
Customization and Personalization Trends
Consumers are seeking unique, personalized timepieces that reflect their individual style, prompting brands to offer bespoke services and limited-edition collections, which enhances exclusivity and customer loyalty.
Mechanical Watches as Investment Assets
The growing view of mechanical watches as collectible investment pieces with strong resale value is fueling demand, especially for rare and vintage models, and supporting the expansion of secondary luxury watch marketplaces.
Expansion of Digital and Online Retail Channels
Luxury watch brands are leveraging e-commerce, virtual showrooms, and digital marketing to reach new demographics and global markets, making mechanical watches more accessible and appealing to younger, tech-savvy buyers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Mechanical watch market, and what is its projected size in 2032?
Which Mechanical watch market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mechanical watch market?
Who are the leading companies in the Mechanical watch market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Stainless Steel Mechanical Watches
- 1.2.2 Leather Mechanical Watches
- 1.2.3 Metal Mechanical Watches
- 1.2.4 Titanium Mechanical Watches
- 1.2.5 Rubber Mechanical Watches
- 1.2.6 Plastic Mechanical Watches
- 1.2.7 Others
- 1.3 By Price Range
- 1.3.1 Low
- 1.3.2 Medium
- 1.3.3 High/Premium
- 1.4 By Movement Type
- 1.4.1 Automatic Mechanical Watches
- 1.4.2 Manual Mechanical Watches
- 1.5 By Strap Material
- 1.5.1 Leather
- 1.5.2 Stainless Steel
- 1.5.3 Nylon
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 61.9 billion → 2032: USD 86.0 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mechanical Watch Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mechanical Watch Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mechanical Watch Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mechanical Watch Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mechanical Watch Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mechanical Watch Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mechanical Watch Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mechanical Watch Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 61.9 billion → 2032: USD 86.0 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mechanical Watch Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Stainless Steel Mechanical Watches
- 12.3.7.2 Leather Mechanical Watches
- 12.3.7.3 Metal Mechanical Watches
- 12.3.7.4 Titanium Mechanical Watches
- 12.3.7.5 Rubber Mechanical Watches
- 12.3.7.6 Plastic Mechanical Watches
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low
- 12.4.7.2 Medium
- 12.4.7.3 High/Premium
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Movement Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automatic Mechanical Watches
- 12.5.7.2 Manual Mechanical Watches
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Strap Material - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Leather
- 12.6.7.2 Stainless Steel
- 12.6.7.3 Nylon
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mechanical Watch Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Mechanical Watch Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Mechanical Watch Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Rolex
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Patek Philippe
- 17.4 Omega
- 17.5 TAG Heuer
- 17.6 Cartier
- 17.7 Seiko Holdings Corporation
- 17.8 The Swatch Group Ltd
- 17.9 Panerai
- 17.10 Breitling
- 17.11 Fossil Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

