
Eye screening moves retinal cameras into primary care
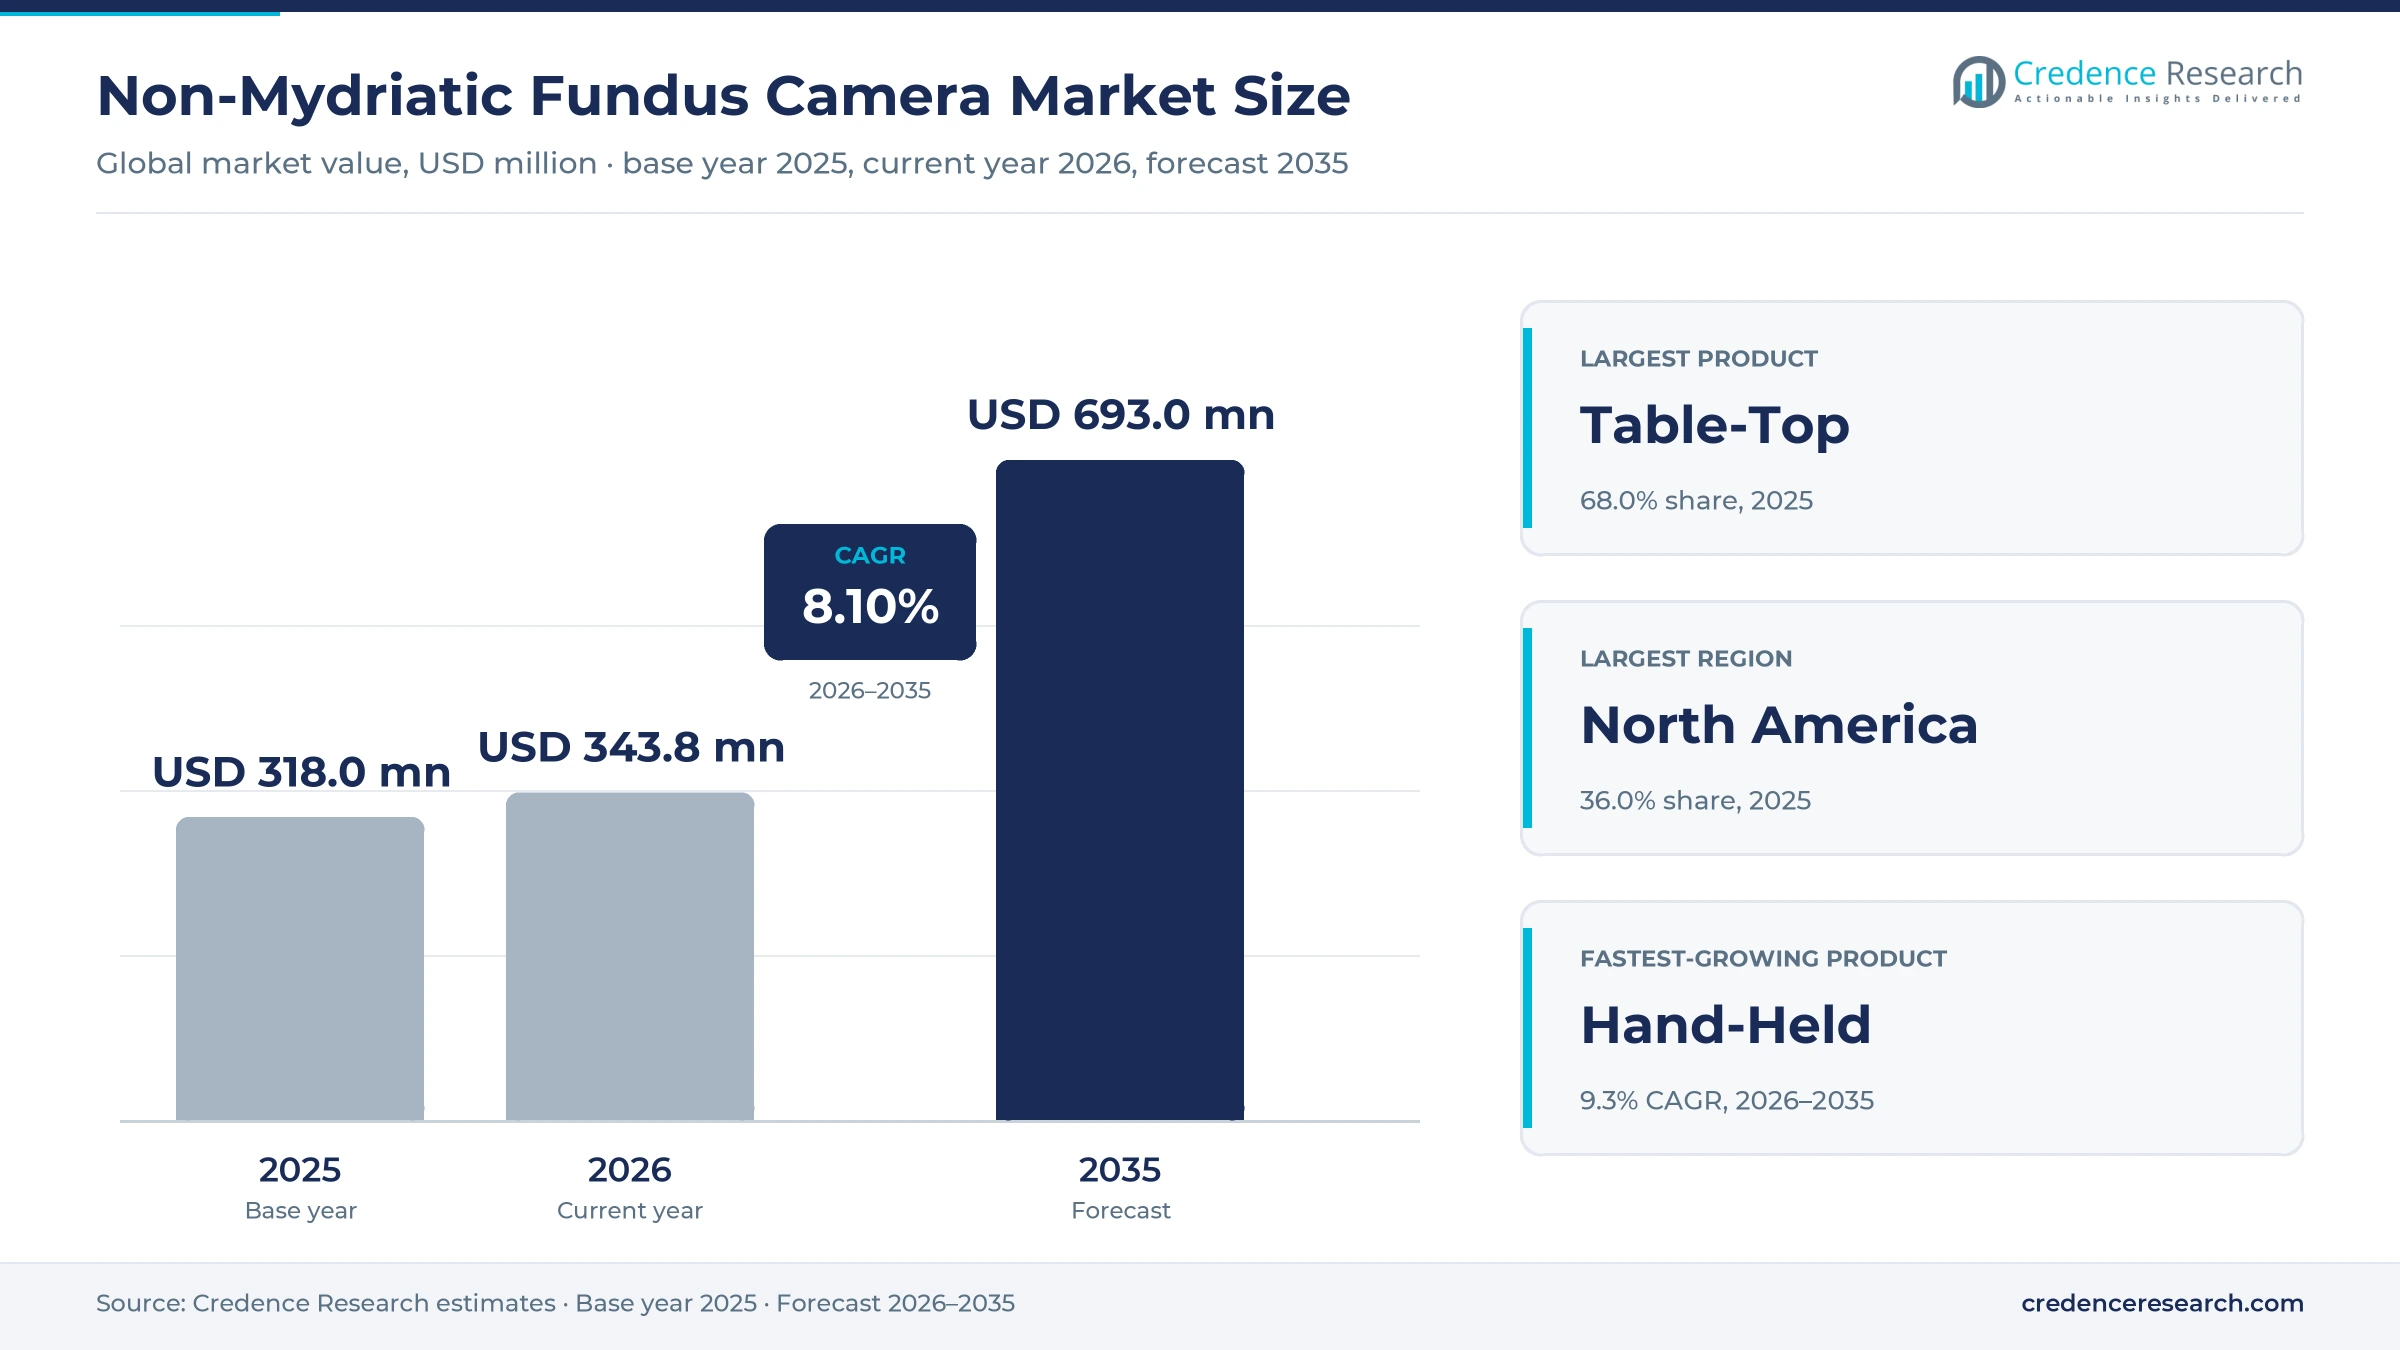
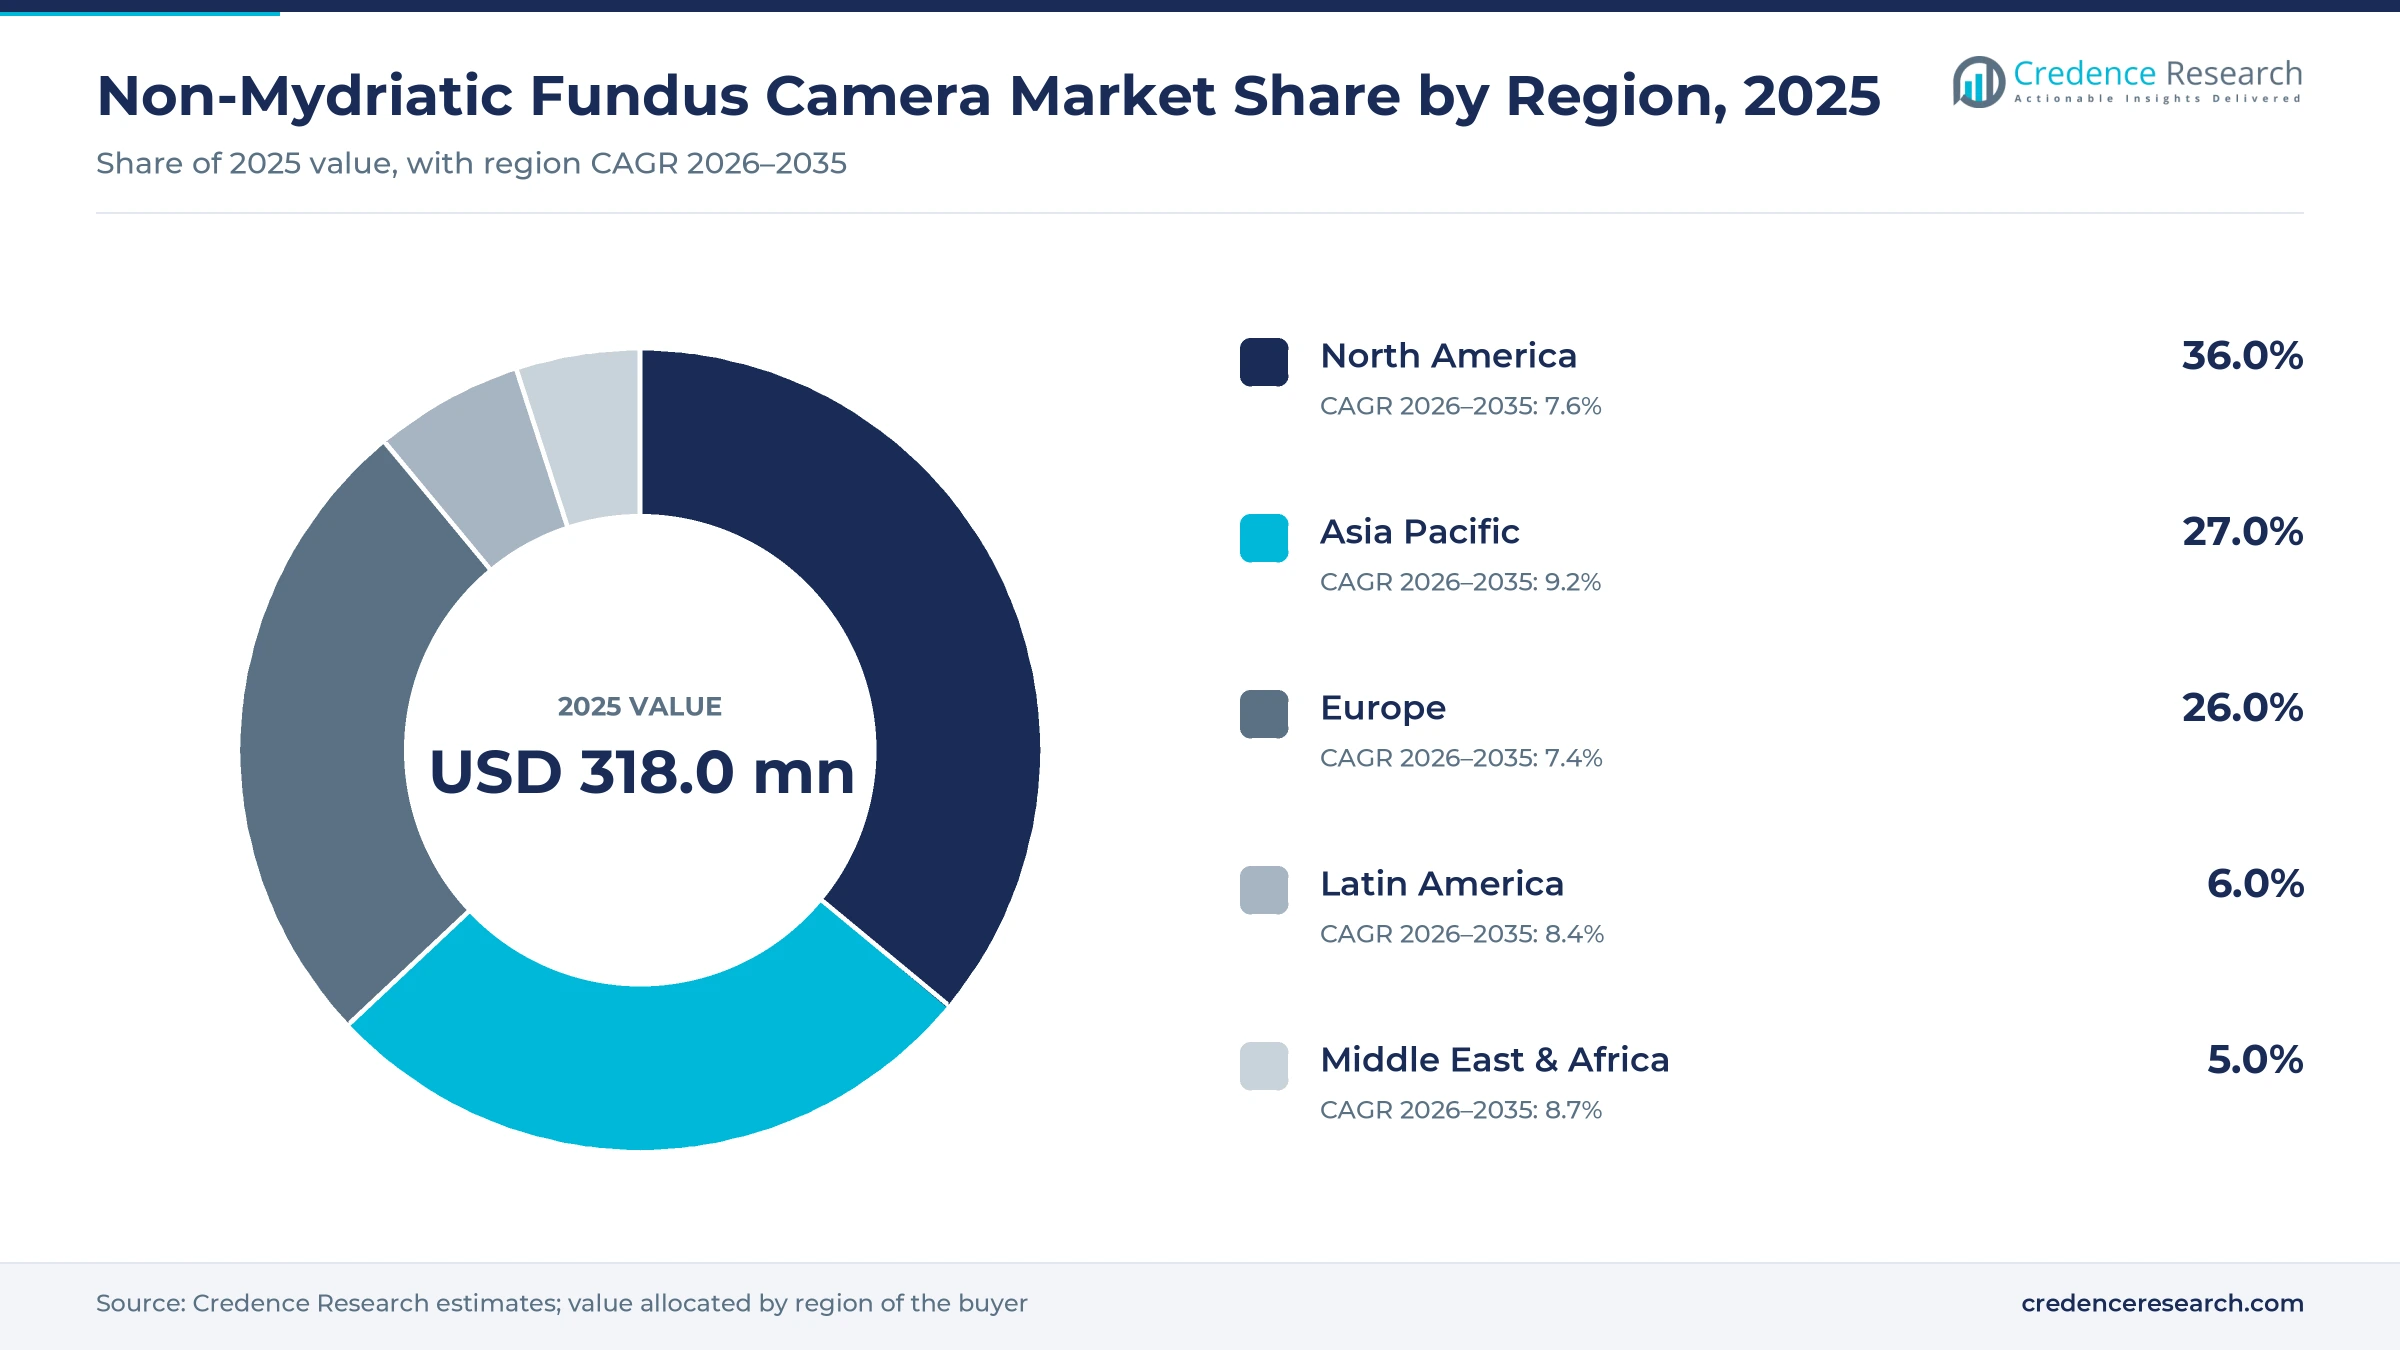
The global non-mydriatic fundus camera market was valued at USD 318.0 million in 2025 and is projected to increase from USD 343.8 million in 2026 to USD 693.0 million by 2035, registering a CAGR of 8.10% during 2026–2035. Demand comes from ophthalmology and optometry practices that photograph the retina at routine visits, hospital eye departments, national diabetic eye screening programs, and primary care sites that now pair cameras with autonomous grading software. North America held the largest regional share, 36.0% in 2025, because U.S. payers reimburse AI diabetic eye exams and health plans track retinal exam rates in quality scores. Asia Pacific is the fastest-growing region at 9.2% a year, as India and China screen large diabetic populations with low-cost hand-held devices. Regulatory clearances for hand-held cameras from Indian makers in 2025 have widened the choice of portable devices available to U.S. buyers.
Which devices and buyers does the estimate cover?
The estimate counts new table-top and hand-held retinal cameras that image the fundus through an undilated pupil, using infrared alignment and a short white flash. Buyers include eye clinics, hospitals, screening programs, optical retailers and primary care groups, which purchase outright, lease or pay a monthly fee that bundles the camera with grading software.
Mydriatic research cameras used for angiography, stand-alone optical coherence tomography systems and second-hand devices sit outside the estimate. AI grading subscriptions are treated as a separate revenue stream, although they increasingly decide which camera a primary care buyer chooses, because each algorithm is cleared for named camera models only.
Non-Mydriatic Fundus Camera Market Insights
- The market is valued at USD 318.0 million in 2025 and is projected to reach USD 693.0 million by 2035, growing at an 8.10% CAGR as diabetic eye screening shifts toward primary care.
- North America led with 36.0% of 2025 value, because autonomous AI eye exams carry a billing code and health plans measure diabetic eye exam completion.
- Table-Top cameras held 68.0% of 2025 value, while Hand-Held devices grow fastest at 9.3% a year on outreach and pharmacy screening.
- The FDA cleared hand-held cameras from Forus Health in August 2025 and Remidio in December 2025, adding low-cost Indian devices to the U.S. market.
- KKR completed its tender offer for Topcon in September 2025, taking an 80.32% stake in one of the largest retinal camera suppliers.
Table-top units lead while hand-held cameras grow fastest
Why do table-top cameras lead while hand-held units grow faster?
Based on product, the market is categorized into table-top and hand-held cameras. Table-Top units led with 68.0% of 2025 value because automated alignment, autofocus and a fixed chin rest give the most consistent two-field images, and Canon received FDA 510(k) clearance for its compact CR-10 table-top camera in May 2024. Hand-Held cameras grow fastest at 9.3% a year as screening moves to homes, vans and community sites, and Zeiss lists its VISUSCOUT 100 at 800 grams with a 3.5-millimeter minimum pupil for outreach and pediatric imaging. Hand-held images still need more operator skill, which limits their use in specialist clinics.
How do CMOS sensors and confocal imagers divide the market?
Based on sensor technology, the market is categorized into CMOS sensors, CCD sensors and others, mainly confocal scanning and laser ophthalmoscope imagers. CMOS Sensor designs led with 74.0% of 2025 value because they draw less power and cost less, and Optomed built its 2025 Lumo hand-held camera around a 12-megapixel low-noise CMOS sensor with a 50-degree field. Confocal and other imagers, grouped as Others, grow fastest at 9.8% a year as confocal devices image through small pupils, and Revenio reported very strong fourth-quarter 2025 sales of its iCare DRSplus confocal camera. CCD models are fading as makers retire older platforms and stop supporting them.
Why do eye clinics lead while primary care sites grow fastest?
Based on end user, the market is categorized into hospitals, ophthalmology clinics, ambulatory surgical centers and others, which include primary care, pharmacies and screening centers. Ophthalmology Clinics led with 42.0% of 2025 value because optometrists and ophthalmologists photograph the retina at routine visits, and Revenio said nearly 350 European customer sites used its iCare ILLUME screening software in 2025. Primary care and other sites, grouped as Others, grow fastest at 9.6% a year as health systems test autonomous exams, and Digital Diagnostics said Banner Health began testing its AI system for vision loss in September 2025. Sustained primary care use depends on staff training and on stable payer rates.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Table-Top | 68.0% | Hand-Held | 9.3% |
| By Sensor Technology | CMOS Sensor | 74.0% | Others | 9.8% |
| By End User | Ophthalmology Clinics | 42.0% | Others | 9.6% |
Cameras sell as capital, fees and per-exam payments
Pricing for retinal cameras follows three distinct commercial models today. Specialist clinics still buy table-top cameras as capital equipment, typically through distributors that bundle installation, software and service. Hand-held devices cost a fraction of that, but grading quality and connectivity vary widely between the cheapest smartphone adapters and medical-grade cameras. Primary care buyers increasingly pay a monthly fee that covers the camera, warranty and AI reads, and then recover the cost through per-exam payments. The gap between the AI exam payment and the lower payment for image capture alone is what makes the subscription model work, so any change in payer rates would move camera demand in primary care.
| Offer or reference | Typical price or fee | Basis |
|---|---|---|
| Table-top non-mydriatic retinal camera (Topcon) | About USD 19,900 list | Cited in PLOS Digital Health, November 2022 |
| Hand-held medical-grade camera (Pictor Plus) | About USD 6,800 | PLOS Digital Health, November 2022 |
| Smartphone retinal adapter (iNview) | USD 800-1,000 incl. phone | PLOS Digital Health, November 2022 |
| Hand-held camera with AI reads, service contract (Optomed Aurora) | USD 1,350 per month, unlimited use | Optomed listing via CHCANYS, November 2026 |
| Autonomous AI diabetic eye exam, CPT 92229 | About USD 45-55 per exam, 2025 average | AEYE Health, 2025 |
| Retinal image capture only, CPT 92227 or 92250-TC | About USD 17-18 per exam | AEYE Health, 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Diabetes burden, AI reimbursement and screening programs
Rising diabetes numbers enlarge the screening pool
The size of the diabetic population sets the floor for retinal camera demand, because each person with diabetes needs regular retinal exams to catch retinopathy before vision loss. The International Diabetes Federation estimated in April 2025 that about 589 million adults live with diabetes and projected 853 million by 2050, while about 252 million remain undiagnosed. In the United States, CDC modeled estimates for 2021 put people with diabetic retinopathy at about 9.6 million, including about 1.84 million with vision-threatening disease. Undilated imaging suits practices that want short visits, which favors non-mydriatic cameras over dilated exams. Screening capacity has not kept up with this pool, so each new program or payer incentive converts directly into camera orders.
Autonomous AI exams turn cameras into a billable service
Reimbursement for autonomous AI exams has changed how primary care buys retinal cameras, because a clinic can now bill for a complete diabetic eye exam without an eye specialist reading the image. The FDA cleared AEYE Health's AEYE-DS software for fully autonomous screening with the Optomed Aurora hand-held camera in April 2024, citing sensitivity of 92% to 93% and specificity of 89% to 94%. Optomed said in February 2026 that Aurora AEYE was still the only FDA-cleared AI solution for a hand-held fundus camera, and that recurring revenue from it grew in every quarter of 2025. The per-exam payment gap shown in the pricing table funds the monthly fee, which shifts camera purchases from capital budgets to operating budgets.
Camera-agnostic AI widens the installed base for screening
AI developers now clear their software on several camera models, which lets clinics add autonomous grading to table-top cameras they already own or plan to buy. Eyenuk said its EyeArt system was cleared in June 2023 for the Topcon NW400 after the Canon CR-2 AF and CR-2 Plus AF, making it the first AI system cleared on cameras from different makers. In its trial, results were conclusive for 90.4% of cases without dilation, and real-time image quality feedback aimed to cut the need for drops. Eyenuk also said hundreds of clinics had screened more than 230,000 patients. Wider camera compatibility favors makers whose models already sit on AI clearance lists.
National screening programs set the purchase lists
Organized screening programs are concentrated buyers that specify camera models centrally, so a place on an approved list is worth more than any single sale. According to the University of Birmingham in October 2026, England's diabetic eye screening program serves almost 4 million people with diabetes, a large and steady source of camera demand. NHS England assesses new cameras at a yearly assessment day, and NHS Supply Chain adds approved units to a purchasing framework at pre-negotiated prices, with Topcon and Haag-Streit among the brands currently available to buy. In South-East Asia, WHO member states adopted a target in March 2023 to screen at least 80% of people with diabetes regularly by 2030, according to the IAPB. Approved suppliers gain repeat replacement orders as programs refresh fleets.
Hand-held clearances, widefield imaging and pharmacy uptake
Hand-held cameras gain U.S. clearances from Indian makers
Indian manufacturers are shifting from domestic screening toward regulated export markets, creating lower-cost choices for U.S. outreach programs and primary care groups. Forus Health received FDA 510(k) clearance for its 3nethra neo HD cameras on Aug. 14, 2025, and Remidio's FOP NM-10 smartphone-based non-mydriatic camera was cleared on Dec. 12, 2025. Inviga Healthcare Fund then took a 21% stake in Forus Health in November 2025 to scale its AI-integrated screening platforms. These entrants compete on price and portability rather than optics, which puts pressure on Japanese and European hand-held models in community health centers. Their success will depend on pairing the cameras with cleared AI grading.
Widefield and multimodal imagers rise at the specialist end
Specialist clinics are shifting toward single-capture widefield images and combined imaging and scanning devices to detect peripheral lesions without dilation. Optos, part of Nikon, said in February 2024 that more than 25,000 of its ultra-widefield devices were installed worldwide, and it launched Silverstone RGB in October 2025, pairing 200-degree true-color imaging with swept-source optical coherence tomography. Topcon Healthcare announced in September 2026 that it would unveil GAIA, a fully automated ultra-widefield device with a 209-degree field, at ESCRS in London. The trend lifts average selling prices in clinics while conventional 45-degree cameras move toward screening uses.
Pharmacies and retail clinics open a new buyer group
Retail pharmacies and nonacute care centers are an underserved channel for autonomous AI in medical imaging, because many people with diabetes visit them far more often than an eye clinic. AEYE Health and distributor Ford Medical announced a partnership in July 2025 to bring autonomous diabetic eye exams to pharmacies and nonacute centers across the United States. AEYE Health then expanded its integration with the Epic electronic health record nationwide in February 2026, so clinicians can order a portable screening that takes about 1 minute inside existing workflows. The USD 1,350 monthly contract in the pricing table suits this demand, because it removes the capital purchase. Digital Diagnostics said a Utah clinic began offering AI diabetic eye exams on site in November 2025. Hand-held suppliers with service contracts stand to gain most from this channel.
Community screening in low-income regions needs rugged low-cost cameras
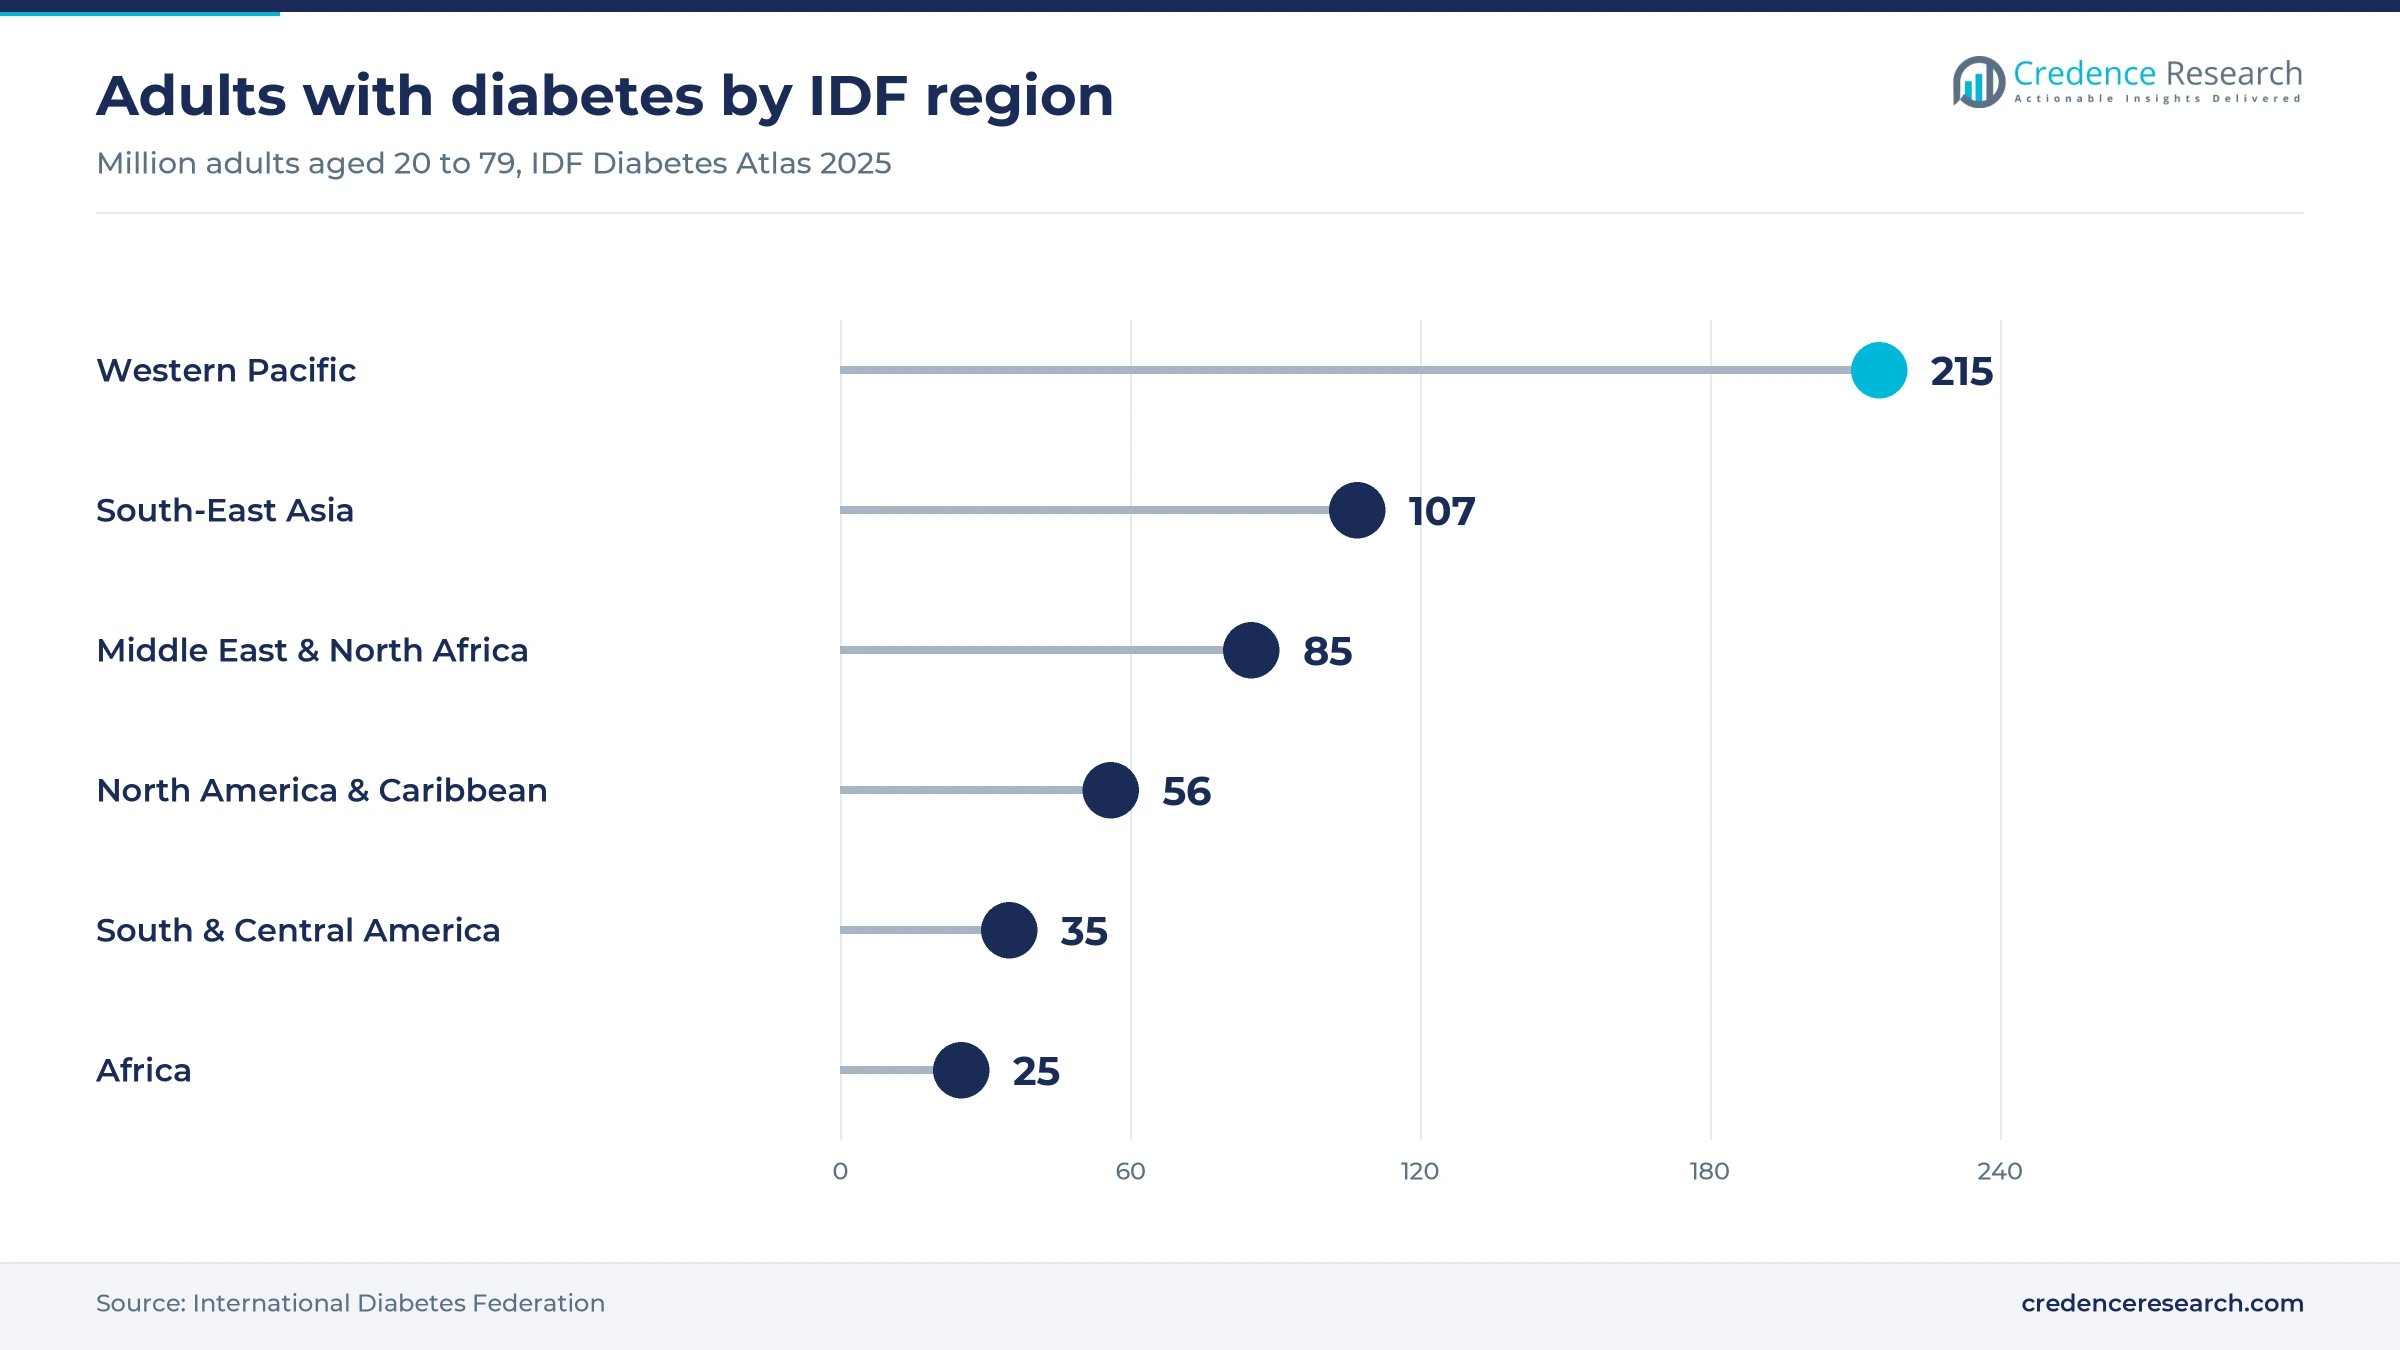
Low- and middle-income countries hold the largest unmet screening need, and they reward suppliers that combine portable cameras, offline AI and training. About three in four adults with diabetes live in low- and middle-income countries, according to the International Diabetes Federation, and its Africa region counts 25 million adults with diabetes, 73% of them undiagnosed. Digital Diagnostics and Google Cloud announced a collaboration in November 2024 to combat diabetic retinopathy in Saudi Arabia through cloud-based grading that suits telehealth models. A Global Summit for Eye Health was announced at the UN General Assembly in September 2025 for November 2026. Suppliers that offer tender pricing and local service gain most where ministries fund screening.
Tariffs, image quality and AI procurement rules slow buyers
U.S. tariffs raise landed costs for imported cameras
Most table-top cameras are made in Japan or Europe, so U.S. import duties raise landed costs for clinics that already face tight capital budgets. Executive Order 14345 of September 2025 set a 15% tariff on most imports from Japan, according to the Congressional Research Service, which raises the landed cost of Japanese table-top cameras. Optomed said U.S. tariffs began to cut its gross margin in the second half of 2025, and Revenio said delayed price increases lowered its fourth-quarter margin by about two percentage points. Distributors that hold inventory bought before the tariff are the most exposed to margin loss.
Ungradable images limit low-cost hand-held devices
Image quality remains the main limit on cheap hand-held devices, because an ungradable image forces a repeat visit or a specialist referral for suspected diabetic retinopathy that erases the cost saving. A comparative study in PLOS Digital Health in November 2022 found ungradable rates of 6% for iNview, 12% for Pictor Plus and 18% for Peek Retina images. Community programs that rely on lay operators are most exposed, especially with older patients and small pupils. Training, automatic capture and real-time quality checks reduce the risk.
Longer U.S. sales cycles cloud near-term orders
U.S. buyers have slowed capital decisions, which delays camera orders even where screening demand is clear. Optomed said in February 2026 that U.S. market conditions in 2025 were more turbulent than anticipated, that sales cycles for Aurora AEYE were longer than expected and that visibility would stay weak in 2026. It also warned that changes to reimbursement or quality scoring for AI screening could affect U.S. revenue. Smaller suppliers that depend on one AI partner carry the most risk.
Strict AI procurement standards slow program adoption
Public screening programs are setting demanding standards before they buy AI grading, which delays the camera refreshes tied to it. University of Birmingham researchers published a target product profile with 35 consensus requirements for AI tools in English diabetic eye screening in October 2026, covering safety, cybersecurity, value for money and NHS integration. The framework is guidance, and no completed national procurement has been reported. Camera makers whose models lack validated AI pairings are exposed in these tenders.
North America leads as Asia Pacific grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 114.5 | 36.0% | 7.6% |
| Asia Pacific | 85.9 | 27.0% | 9.2% |
| Europe | 82.7 | 26.0% | 7.4% |
| Latin America | 19.1 | 6.0% | 8.4% |
| Middle East & Africa | 15.9 | 5.0% | 8.7% |
North America leads on reimbursed AI eye exams
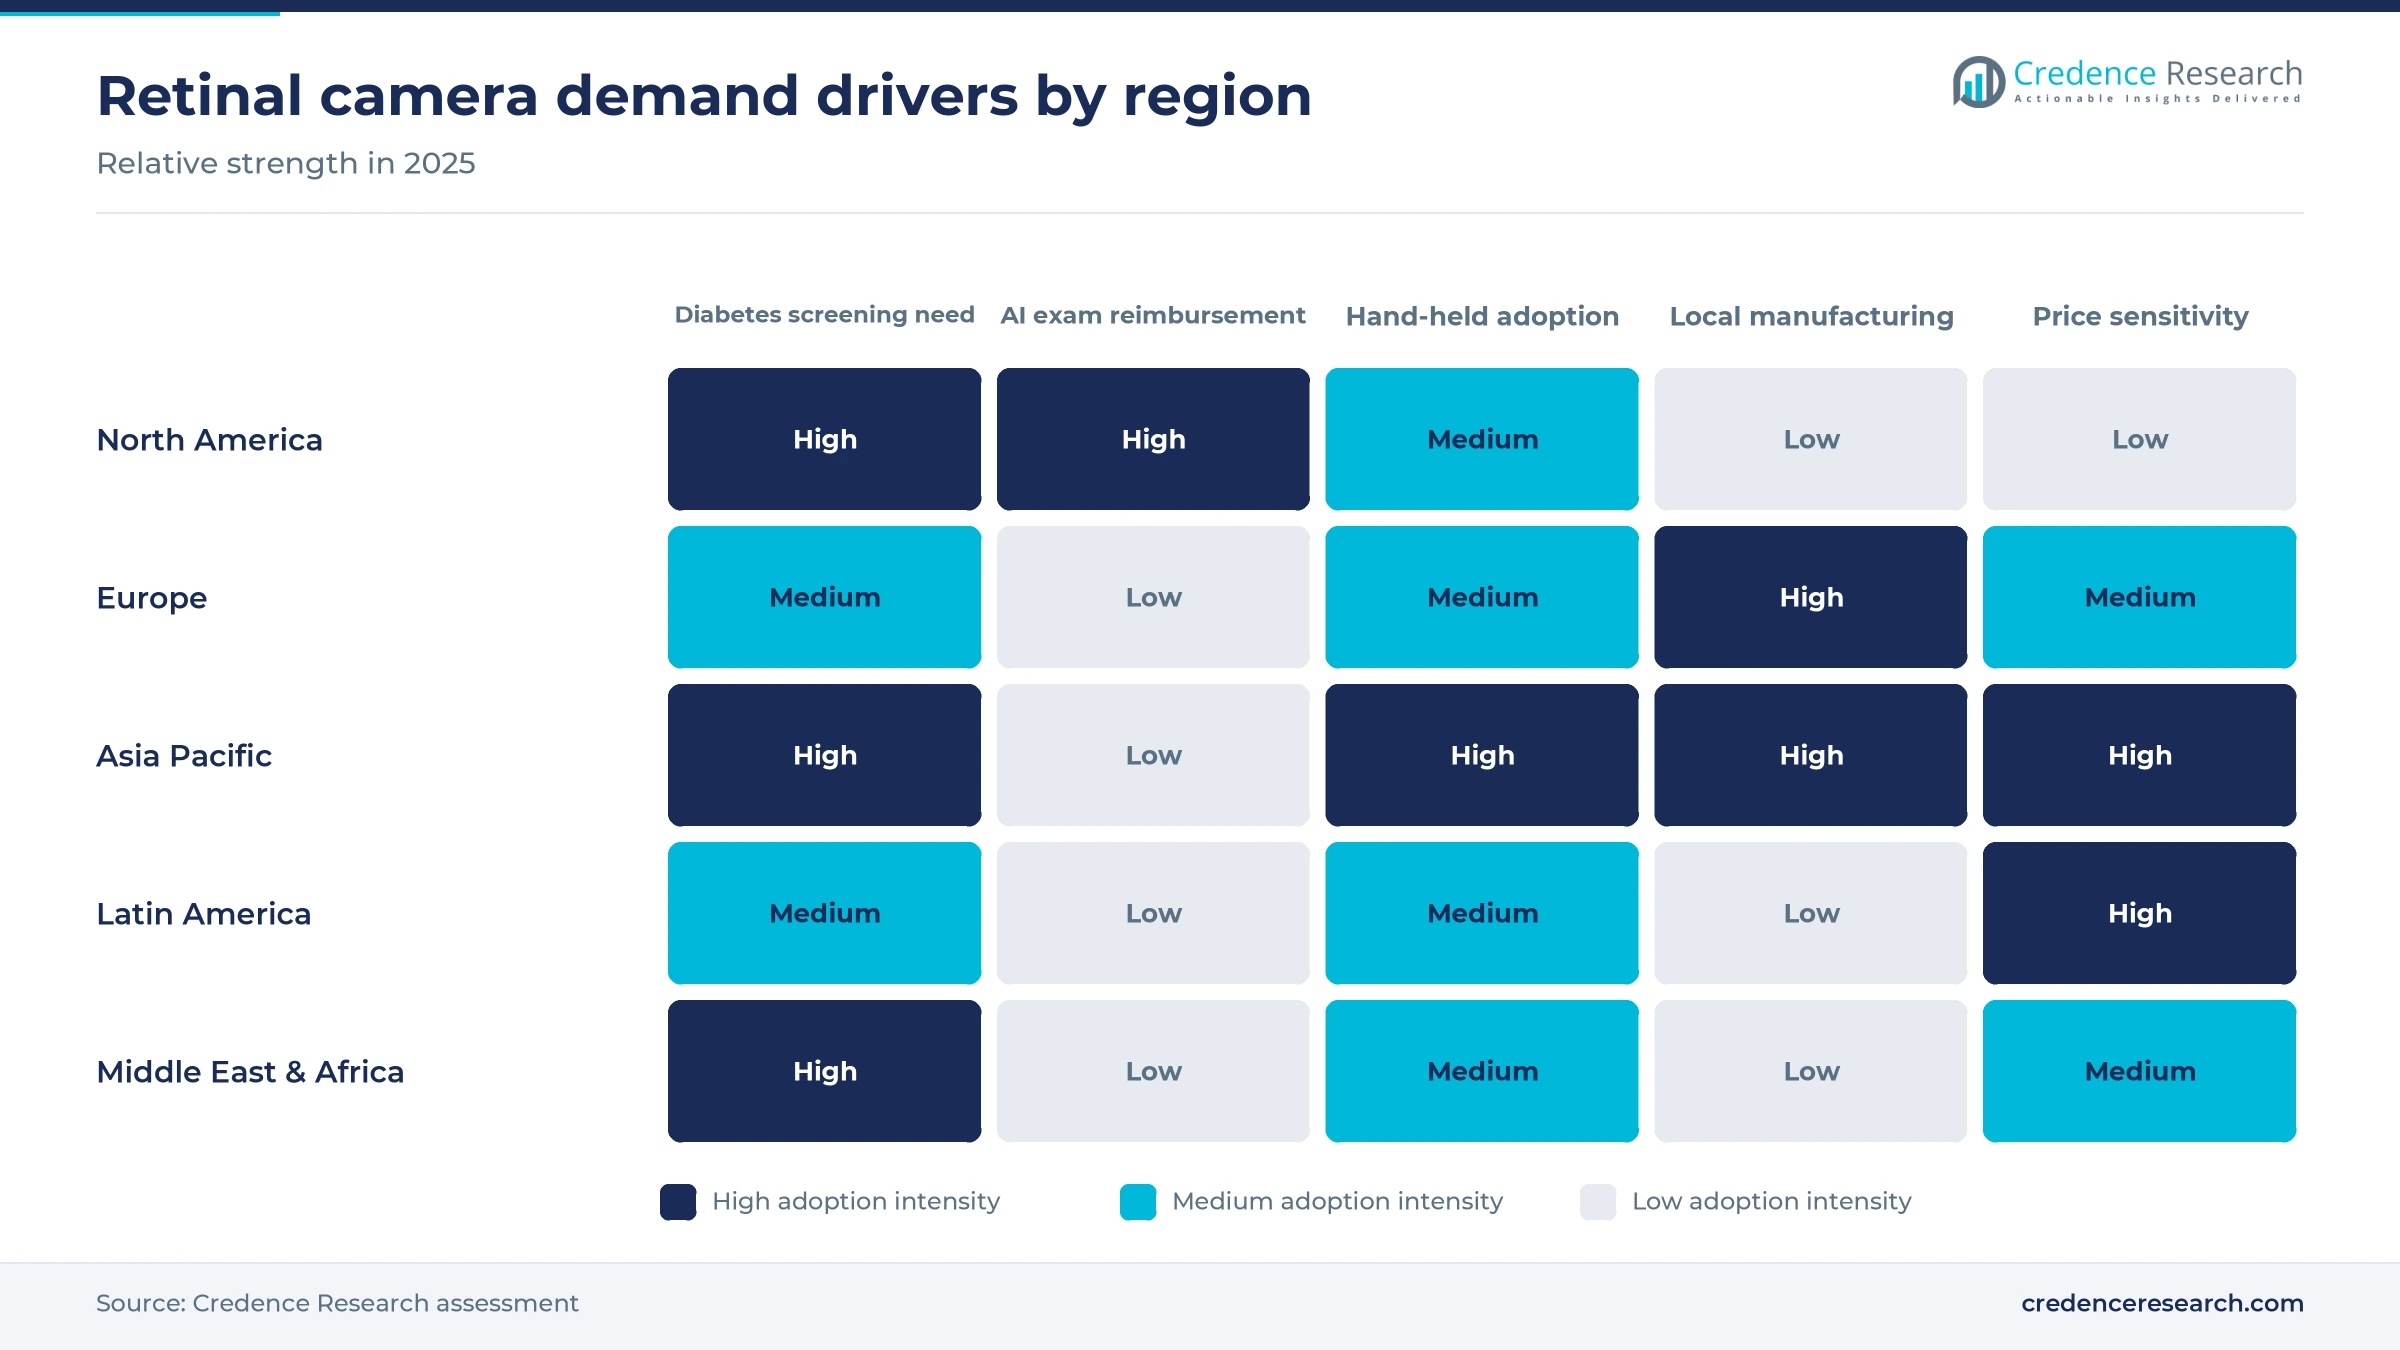
North America held 36.0% of 2025 value and grows at 7.6% a year, because U.S. payers reimburse autonomous diabetic eye exams and health plans report diabetic eye exam completion through HEDIS quality measures. Optomed notes that these HEDIS scores and reimbursement shape AI screening demand, which pushes primary care groups to place cameras in their own clinics. Revenio reported an all-time record for U.S. sales in December 2025. Tariffs on Japanese and European imports and slower capital approvals are the main brakes in 2026.
Asia Pacific grows fastest on large-scale community screening
Asia Pacific held 27.0% of 2025 value and grows fastest at 9.2% a year, because India and China carry the largest diabetic populations and are adopting hand-held cameras for community screening. India's armed forces medical services, AIIMS and the health ministry launched the MadhuNetrAI screening program on Dec. 16, 2025, using hand-held cameras at seven pilot sites. Japan hosts Topcon, Canon, Nidek and Kowa, while India supplies low-cost hand-held devices. Optomed said its China joint venture would bring no revenue for several quarters, which shows how slowly foreign entrants gain access there.
Europe relies on program-specified table-top fleets
Europe held 26.0% of 2025 value and grows at 7.4% a year, because national screening programs and optometry chains buy approved table-top cameras on long replacement cycles. England alone screens almost 4 million people with diabetes, which anchors regional demand for approved cameras. The region also hosts Zeiss in Germany, Haag-Streit in Switzerland, Optos in Scotland and Optomed and iCare in Finland, which shortens service routes. The GAIA unveiling noted above shows that premium imagers now debut at European congresses. Slower growth reflects mature screening coverage and tight hospital budgets.
Latin America expands through distributor networks
Latin America held 6.0% of 2025 value and grows at 8.4% a year, as private eye clinic chains and public diabetes programs add retinal imaging. The International Diabetes Federation counts about 35 million adults with diabetes in South and Central America, the regional demand base, and says one in three is undiagnosed. Revenio said it expanded distribution in Latin America during 2025. Currency swings and import duties keep price-sensitive buyers on refurbished and hand-held units.
Middle East & Africa builds national screening programs
Middle East & Africa held 5.0% of 2025 value and grows at 8.7% a year, as Gulf health systems fund national retinopathy screening. The International Diabetes Federation counts about 85 million adults with diabetes in the Middle East and North Africa, one in three undiagnosed. Revenio said it won new national screening programs in the Middle East in 2025. Sub-Saharan demand remains donor-led, so the regional estimate carries a wide error range.
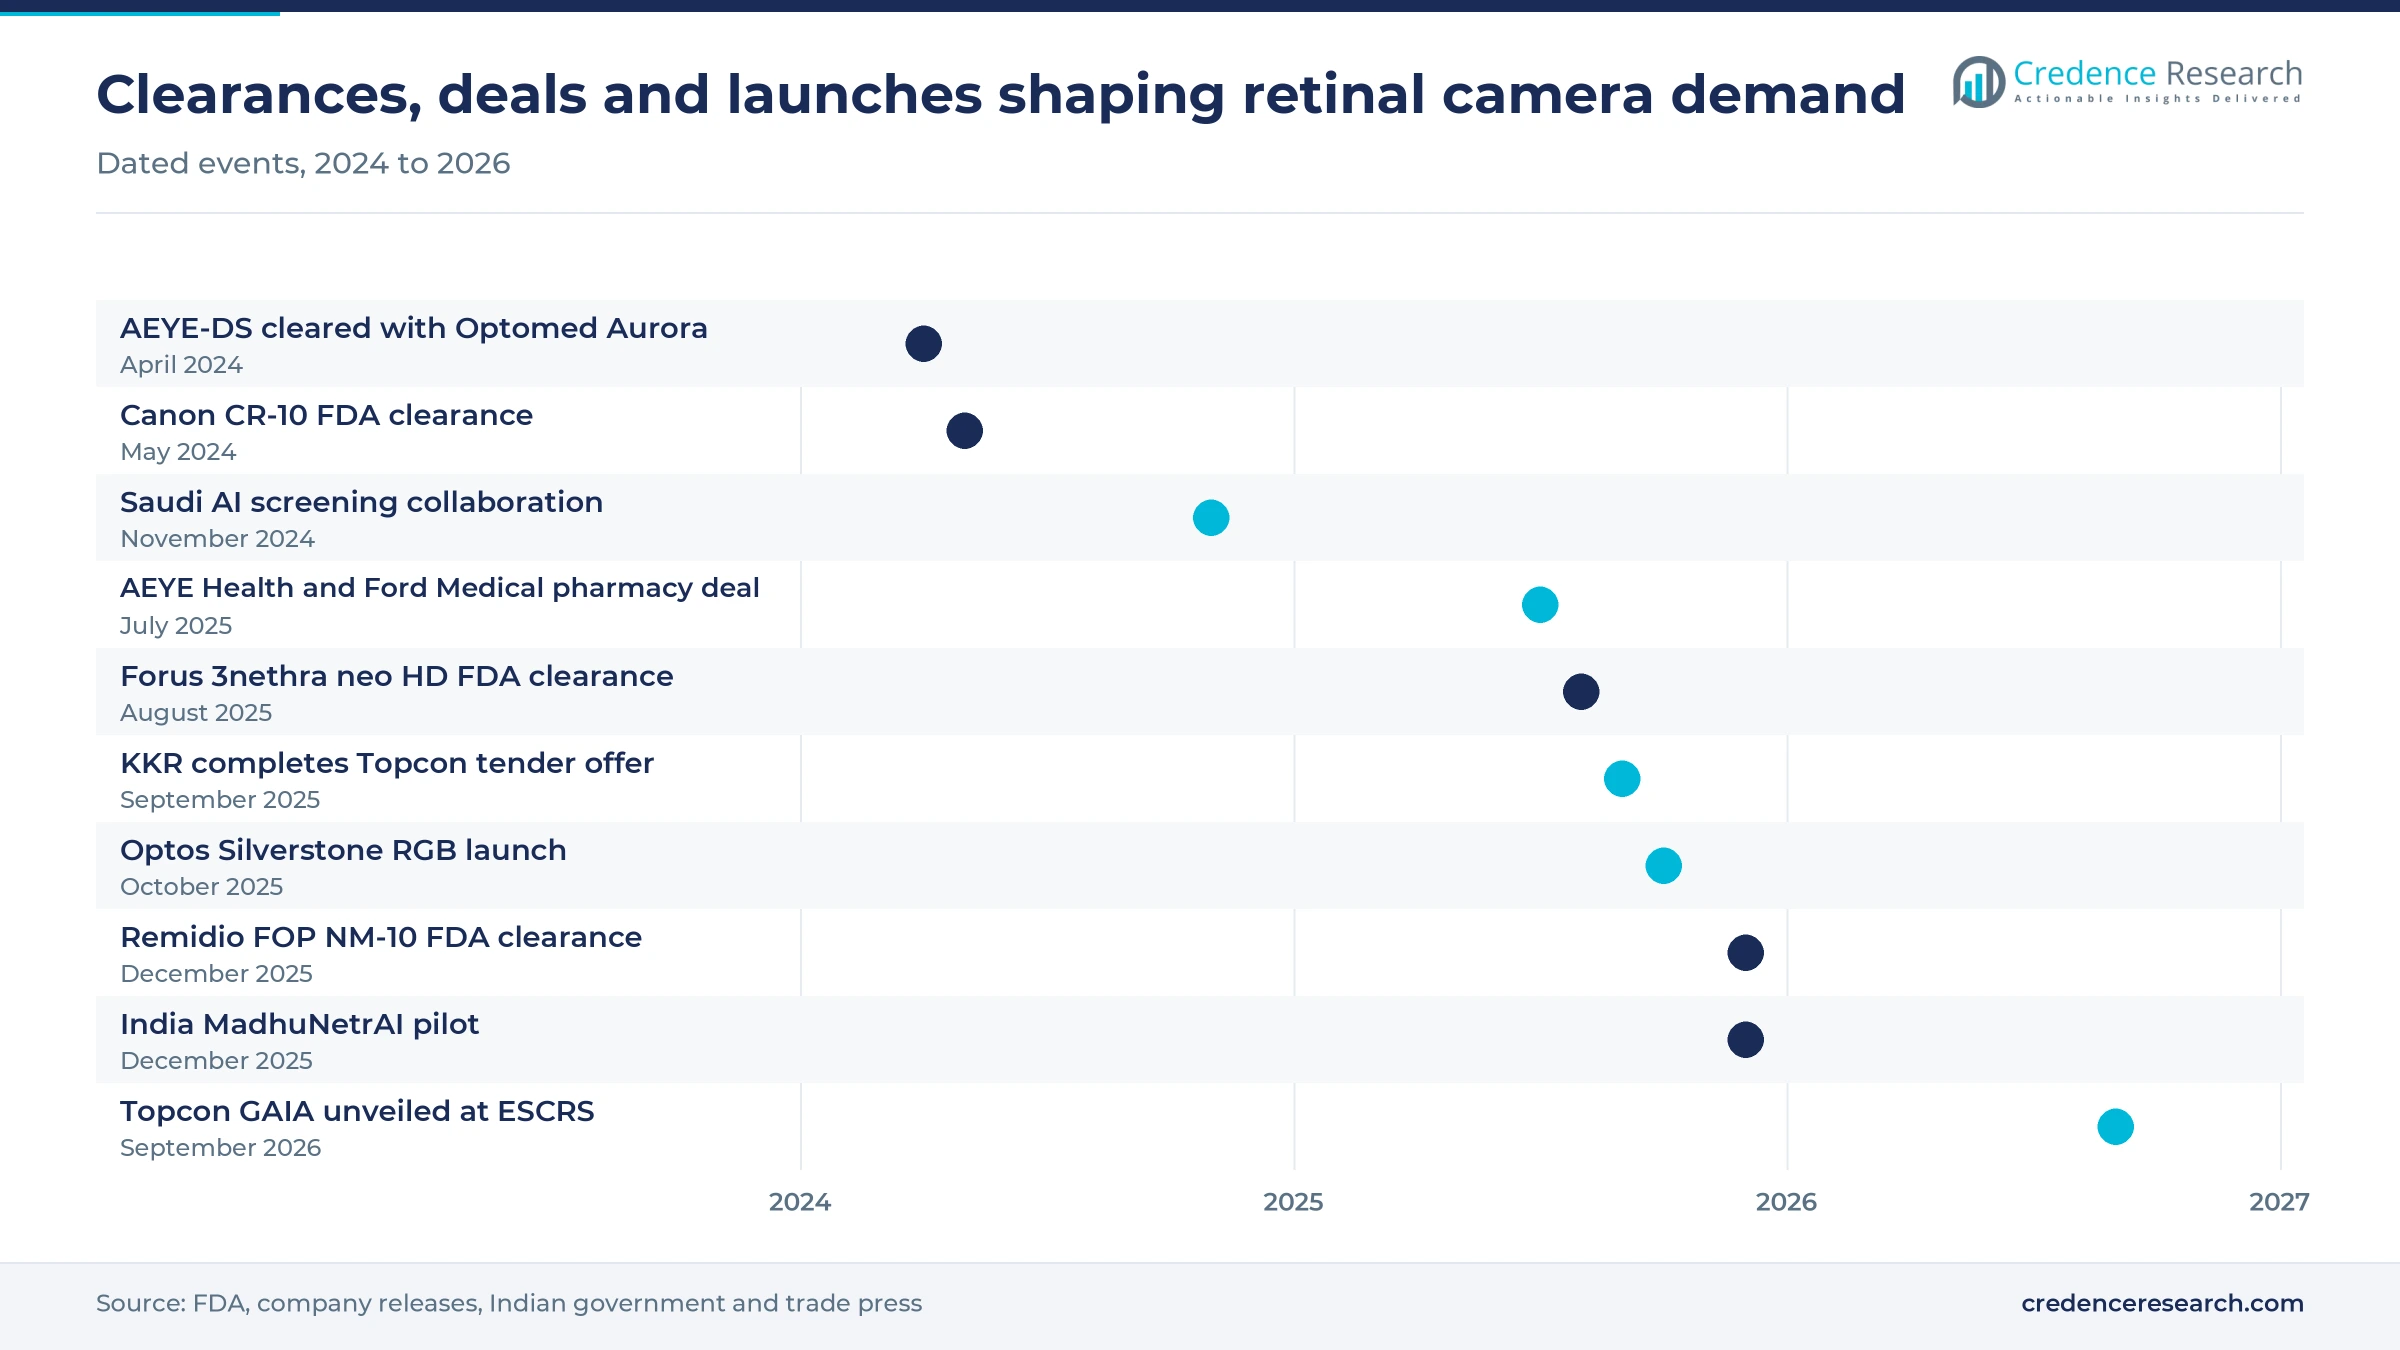
Clearances, a take-private and widefield launches, 2024-2026
| Development | Status and market relevance |
|---|---|
| In August 2025, Forus Health received FDA 510(k) clearance for its 3nethra neo HD and 3nethra neo HD FA retinal cameras. | Regulatory clearance completed on Aug. 14, 2025; it allows U.S. sales and strengthens the case for the November 2025 equity investment by Inviga Healthcare Fund. |
| In September 2025, KKR completed its tender offer for Topcon Corporation, reaching an 80.32% ownership ratio. | Completed tender offer; KKR planned to buy the remaining shares and take the company private, which removes quarterly reporting on one of the largest camera suppliers. |
| In October 2025, Optos launched Silverstone RGB, combining 200-degree true-color ultra-widefield imaging with swept-source OCT. | Commercial launch; it raises the price ceiling for multimodal devices in retina clinics and competes with high-end table-top cameras. |
| In December 2025, Remidio received FDA 510(k) clearance for the Fundus On Phone Non Mydriatic (FOP NM-10) camera. | Regulatory clearance completed on Dec. 12, 2025; it adds a smartphone-based, battery-powered device to U.S. primary care choices. |
| In September 2026, Topcon Healthcare announced the unveiling of GAIA, a fully automated ultra-widefield retinal imager with a 209-degree field. | Product announcement for ESCRS in London, Sept. 11 to 15, 2026; availability and regulatory status by country were not stated. |
Autofocus, infrared alignment and AI grading cut dilation
- Infrared alignment and autofocus let the camera find the pupil and focus without visible light, so the pupil stays wide until a short flash takes the image.
- Automated capture and tracking move the optical head toward the eye and fire when alignment is correct, which lets lay staff in primary care take gradable images.
- Confocal scanning builds the image line by line with white light, reducing glare from cataracts and allowing imaging through pupils smaller than standard cameras need.
- Ultra-widefield optics capture up to about 200 degrees of retina in one shot, so peripheral lesions appear without dilation or montage imaging.
- On-device image quality checks and AI grading tell the operator at once whether an image can be graded and, where cleared, return a diabetic retinopathy result within minutes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Japanese optics makers face AI-ready hand-held entrants
Competition among camera makers, most of which also sell broader ophthalmic equipment, turns on image consistency, regulatory clearances for AI pairings and service reach more than on optics alone. Topcon sells the NW400 and NW500 table-top cameras, with the NW400 cleared for EyeArt AI grading, and has been under KKR ownership since 2025. Canon competes with the CR-2 AF family and the CR-10, while Nidek and Kowa reach screening programs through distributors such as Birmingham Optical Group and Sense Medical. Zeiss and Haag-Streit sell into European hospitals, and iCare differentiates with confocal imaging and screening software. Optos holds the ultra-widefield niche with its scanning laser devices in retina clinics. Optomed leads hand-held devices in the United States through its AEYE pairing, while Remidio and Forus compete on price and smartphone connectivity, and Huvitz sells the HFC-1 through distributors such as Coburn Technologies.
Who keeps the margin between optics makers, AI vendors and distributors?
Supply is split between a few Japanese optics groups and a fast-growing tier of hand-held specialists. Topcon, Canon, Nidek and Kowa make many of the table-top models on approved lists and sell through national distributors that bundle service, which protects margins through installed-base loyalty. Zeiss, Haag-Streit and iCare compete in Europe, while Optos holds a distinct ultra-widefield niche. Optomed, Remidio and Forus sell hand-held devices and increasingly earn recurring fees from AI-linked service contracts. Entry barriers are regulatory, since each camera needs clearance and each AI pairing needs its own validation, so the highest margins sit with suppliers that control both.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Topcon Corporation (Topcon Healthcare) | Table-top leader | Sells NW400 and NW500 automated cameras; owned by KKR since 2025 |
| Canon Inc. | Table-top maker | Sells CR-2 AF, CR-2 Plus AF and the FDA-cleared CR-10 |
| Carl Zeiss Meditec AG | Diversified ophthalmic supplier | Sells VISUSCOUT 100 hand-held and CLARUS widefield cameras |
| NIDEK Co., Ltd. | Table-top maker | Sells AFC-330 automated non-mydriatic cameras through distributors such as Birmingham Optical Group |
| Kowa Company, Ltd. | Table-top maker | Sells nonmyd-series non-mydriatic cameras, distributed in the U.K. by Sense Medical |
| Optos plc (Nikon Corporation) | Ultra-widefield specialist | More than 25,000 ultra-widefield devices installed worldwide |
| Optomed Plc | Hand-held specialist | Aurora, Aurora AEYE and Lumo hand-held cameras with service contracts |
| iCare Finland Oy (Revenio Group) | Confocal imaging specialist | Sells DRSplus and EIDON confocal cameras and ILLUME software |
| Haag-Streit Group (Metall Zug) | Diagnostics supplier | Sells the iCam camera on the NHS approved list |
| Huvitz Co., Ltd. | Table-top maker | Sells the FDA-cleared HFC-1 non-mydriatic camera |
| Remidio Innovative Solutions Pvt. Ltd. | Hand-held specialist | Smartphone-based FOP NM-10, FDA-cleared in December 2025 |
| Forus Health Pvt. Ltd. | Hand-held and portable maker | 3nethra neo HD cameras, FDA-cleared in August 2025 |
Value shifts from camera optics to screening workflows
Credence Research's view is that value in this market is shifting from camera optics toward complete screening workflows. Table-top cameras will keep most revenue in eye clinics, but the incremental volume sits in primary care, pharmacies and community programs, where buyers choose a camera because of the AI result, the service contract and record integration. Suppliers without cleared AI pairings risk becoming component vendors to software firms. Buyers should check which algorithm each camera is cleared with, model the payment gap shown in the pricing table, and budget for tariff-driven price increases on imported table-top units.
Earlier estimate rolled forward and tested on unit pricing
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested against published camera prices, likely annual unit volumes and the value of the wider retinal camera category. Regional and segment shares are Credence Research estimates based on diabetes prevalence, reimbursement rules, screening programs, approved camera lists and company disclosures. Sources include IDF, CDC, FDA, NHS England, Indian government releases, company filings and trade press. No interviews or surveys were conducted for this update of the estimate.
Primary care screening carries growth through 2035
Growth to 2035 depends on how far autonomous AI screening spreads beyond U.S. primary care and how quickly public programs in Europe, India, China and the Gulf adopt it. The base case assumes current U.S. exam payments hold, tariffs stay near today's levels and more AI tools gain clearance on several camera brands. Hand-Held cameras should grow at 9.3% a year as pharmacies and community programs scale, while table-top replacement cycles keep clinic demand steady. Suppliers that pair devices with validated AI and service contracts should hold the strongest pricing.
Reimbursement and AI pairings set the range of outcomes
The range of outcomes depends mainly on whether payers keep rewarding autonomous diabetic eye exams and on how quickly public programs approve AI grading linked to specific cameras. Faster growth needs more AI clearances for hand-held devices and funded screening in India, China and the Gulf. Slower growth would follow lower U.S. payment rates, higher tariffs on Japanese and European cameras, or long delays in national AI procurement.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 6.3% | USD 595.8 million | U.S. exam payments fall and tariffs keep clinic capital budgets tight through 2028 |
| Base | 8.10% | USD 693.0 million | Current reimbursement holds and AI pairings expand gradually across camera brands |
| Upside | 9.3% | USD 765.4 million | National programs in Asia and the Gulf adopt AI screening with hand-held cameras at scale |
Frequently Asked Questions
How big is the non-mydriatic fundus camera market?
What is a non-mydriatic fundus camera used for?
Which product type leads the market?
Which region leads the market?
Which hand-held fundus cameras are FDA-cleared?
How much does a non-mydriatic retinal camera cost?
How does AI change demand for retinal cameras?
Who are the main fundus camera brands?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Table-Top
- 1.2.2 Hand-Held
- 1.3 By Sensor Technology
- 1.3.1 CMOS Sensor
- 1.3.2 CCD Sensor
- 1.3.3 Others
- 1.4 By End User
- 1.4.1 Hospitals
- 1.4.2 Ophthalmology Clinics
- 1.4.3 Ambulatory Surgical Centers
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 318.0 million → 2035: USD 693.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Non-Mydriatic Fundus Camera Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Non-Mydriatic Fundus Camera Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Non-Mydriatic Fundus Camera Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Non-Mydriatic Fundus Camera Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Non-Mydriatic Fundus Camera Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Non-Mydriatic Fundus Camera Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Non-Mydriatic Fundus Camera Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Non-Mydriatic Fundus Camera Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 318.0 million → 2035: USD 693.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Non-Mydriatic Fundus Camera Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Table-Top
- 12.3.7.2 Hand-Held
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Sensor Technology - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 CMOS Sensor
- 12.4.7.2 CCD Sensor
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Ophthalmology Clinics
- 12.5.7.3 Ambulatory Surgical Centers
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Non-Mydriatic Fundus Camera End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Non-Mydriatic Fundus Camera Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Non-Mydriatic Fundus Camera Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Non-Mydriatic Fundus Camera Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Topcon Corporation (Topcon Healthcare)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Canon Inc.
- 18.4 Carl Zeiss Meditec AG
- 18.5 NIDEK Co., Ltd.
- 18.6 Kowa Company, Ltd.
- 18.7 Optos plc (Nikon Corporation)
- 18.8 Optomed Plc
- 18.9 iCare Finland Oy (Revenio Group)
- 18.10 Haag-Streit Group (Metall Zug)
- 18.11 Huvitz Co., Ltd.
- 18.12 Remidio Innovative Solutions Pvt. Ltd.
- 18.13 Forus Health Pvt. Ltd.
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

