
Market Overview:
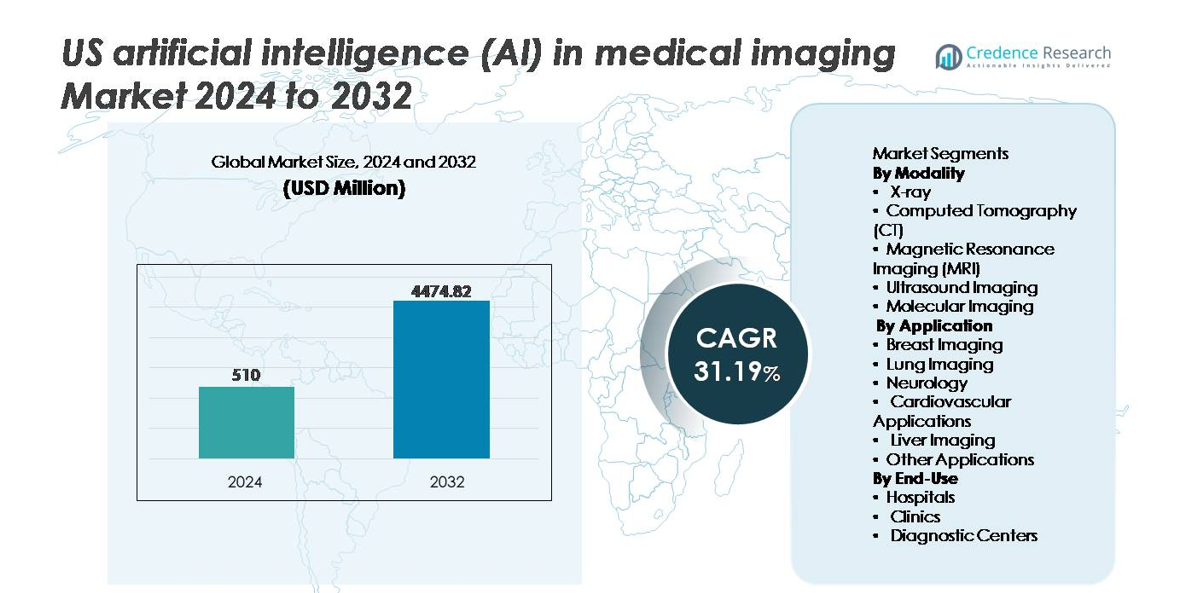
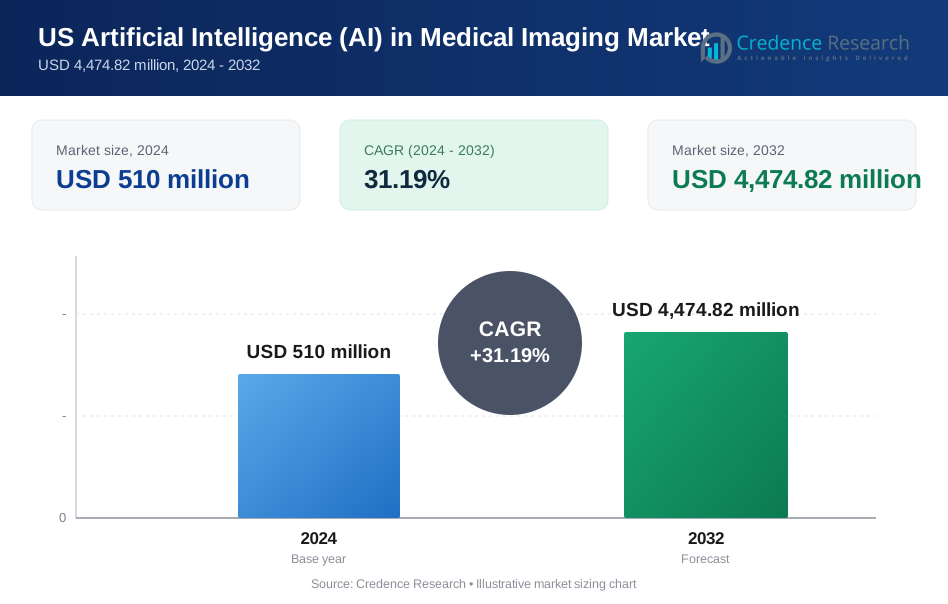
The U.S. artificial intelligence (AI) in medical imaging market was valued at USD 510 million in 2024 and is projected to reach USD 4,474.82 million by 2032, registering a robust CAGR of 31.19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| US Artificial Intelligence (AI) in Medical Imaging Market Size 2024 | USD 510 million |
| US Artificial Intelligence (AI) in Medical Imaging Market, CAGR | 31.19% |
| US Artificial Intelligence (AI) in Medical Imaging Market Size 2032 | USD 4,474.82 million |
The U.S. artificial intelligence (AI) in medical imaging market is shaped by a mix of global healthcare technology leaders and specialized AI innovators, including Nanox Imaging LTD., GE Healthcare, Lunit Inc., IBM Watson Health, InformAI LLC, Intel Corporation, and Koninklijke Philips N.V. These companies focus on developing AI-powered image interpretation, workflow automation, and predictive diagnostic solutions across CT, MRI, X-ray, and multimodal platforms. Strategic partnerships with healthcare systems, expanding FDA clearances, and cloud-enabled deployment models strengthen their competitive position. Regionally, the South leads the market with approximately 28% share, driven by a high number of diagnostic centers, rapid hospital expansion, and strong adoption of AI-assisted imaging for chronic disease management and high-volume screening.
Market Insights:
- The U.S. AI in medical imaging market was valued at USD 510 million in 2024 and is projected to reach USD 4,474.82 million by 2032, growing at a CAGR of 31.19% during the forecast period.
- Market growth is driven by rising demand for early diagnostics, automation of radiology workflows, and AI-powered decision support tools that reduce reporting times and improve diagnostic accuracy across CT, MRI, and X-ray modalities, with CT holding the dominant segment share.
- Key market trends include the expansion of cloud-based AI platforms, generative AI for automated reporting, and multimodal diagnostic intelligence integrating imaging with clinical and genomic data for precision treatment planning.
- Competitive activity intensifies as major players and specialized vendors compete through FDA approvals, hospital partnerships, and AI marketplace integration, while high integration costs and interoperability challenges remain core restraints.
- Regionally, the South leads with 28% market share, followed by the West at 22%, Northeast at 20%, and Midwest at 18%, reflecting varied healthcare infrastructure and adoption maturity.
Market Segmentation Analysis:
By Modality
Computed Tomography (CT) represents the dominant modality segment in the U.S. AI medical imaging market, accounting for the largest share due to its extensive utilization in cancer detection, stroke evaluation, and trauma diagnostics. AI-powered CT platforms support workflow automation, rapid image reconstruction, and improved lesion characterization, significantly reducing reporting time and diagnostic variability. MRI and X-ray follow as fast-growing sub-segments driven by AI-enabled noise reduction and enhanced contrast analytics. Meanwhile, ultrasound and molecular imaging increasingly adopt AI for real-time decision support and pathology quantification, expanding clinical utility across cardiology and oncology.
- For instance, GE HealthCare’s Revolution Apex platform integrates its Deep Learning Image Reconstruction (DLIR) engine, which can generate high-resolution CT images from raw data at up to 1024 matrix output, enhancing clarity for small-structure evaluation while reducing the need for repeat scans.
By Application
Breast imaging holds the highest market share within the application segment, largely attributed to AI deployment in mammography, tomosynthesis interpretation, and early tumor detection. High screening volumes and regulatory support for computer-aided detection accelerate adoption and reimbursement alignment. Lung imaging follows closely, driven by AI–assisted nodule triaging and incidental finding management in COPD and lung cancer screening programs. Neurology, cardiovascular, and liver imaging leverage AI for anatomical modeling, perfusion analytics, and fibrosis scoring, while other emerging applications expand toward orthopedic, dental, and gastroenterology decision-support systems.
- For instance, Lunit Inc. reports that its INSIGHT MMG AI algorithm achieved an AUC of 0.99 in a real-world validation study of over 240,000 mammography cases, improving cancer detection sensitivity while helping reduce false-negative outcomes for dense-breast populations.
By End-Use
Hospitals dominate the end-use segmentation due to higher imaging volumes, larger integration budgets, and advanced IT infrastructure supporting AI-enabled PACS, workflow orchestration, and cross-departmental data exchange. AI adoption in hospitals also accelerates through enterprise-wide diagnostic pathways and precision-medicine programs, particularly for oncology and neurology. Diagnostic centers exhibit expanding uptake as providers prioritize rapid turnaround and competitive differentiation through AI-enabled triage and reporting optimization. Clinics adopt AI at a smaller yet growing scale, driven by cloud-based imaging analytics and reduced hardware dependency, enabling decentralized diagnostic capability.
Key Growth Drivers:
Rising Demand for Early Diagnostics and Precision Imaging
The growing emphasis on early disease detection, precision medicine, and targeted therapies drives rapid adoption of AI in U.S. medical imaging. Healthcare systems increasingly prioritize the reduction of diagnostic errors, accelerated report turnaround, and enhanced detection sensitivity for chronic conditions such as cancer, neurological disorders, and cardiovascular diseases. AI algorithms support radiologists with automated triaging, lesion quantification, risk stratification, and predictive analytics based on large image datasets. Hospitals benefit from improved workflow efficiency by reducing radiologist burdens and eliminating repetitive manual tasks. Moreover, AI platforms improve diagnostic consistency across complex multispecialty networks and facilitate earlier intervention through anomaly detection that surpasses conventional visual interpretation. As value-based care and quality-linked reimbursement models expand, providers continue to adopt AI-driven tools that demonstrate measurable clinical outcome improvements and resource optimization.
- For instance, Lunit’s INSIGHT MMG demonstrated improved early detection by correctly localizing 31.3% of mammographically occult breast cancers in a specific study, including cases that were originally overlooked by human readers. The AI tool has been confirmed in various large-scale, real-world evaluations to help radiologists find cancers that were previously missed, increasing overall cancer detection rates.
Integration of AI-Enabled Clinical Decision Support (CDS)
AI-assisted clinical decision support systems transform radiology workflows by providing real-time alerts, prioritization recommendations, and contextual information to support more informed and timely decisions. Integration with PACS, EHRs, and RIS platforms enables radiologists to access consolidated patient histories, imaging comparisons, and risk indicators within the same interface. These CDS capabilities are particularly impactful in emergency and critical care settings where speed and accuracy are essential. Predictive AI models help forecast disease progression, recommend additional scans, or highlight urgent abnormalities requiring immediate review. As healthcare organizations expand tele-radiology services and distributed reading networks become more common, AI-enabled CDS platforms ensure consistent interpretation quality regardless of location. The move toward autonomous reporting assistants further strengthens AI’s role, improving throughput without compromising clinical accuracy.
- "For instance, Aidoc’s AI triage system supports 18FDA-cleared clinical indications and processes imaging data to deliver critical condition alerts, including intracranial hemorrhage and pulmonary embolism, with notifications reaching care teams in under two minutes from scan acquisition.
Expansion of Cloud-Based AI Imaging Platforms
Cloud-native AI architecture significantly reduces capital expenditure and enables scalable deployments across large health systems, imaging chains, and independent clinics. Cloud platforms facilitate rapid software updates, continuous model learning, and multi-institutional data aggregation for improved algorithm accuracy. This model supports remote diagnostics, allowing sub-specialist interpretation across geographically dispersed facilities without latency or storage constraints. Vendor-neutral cloud ecosystems also ensure compatibility with diverse imaging equipment, extending AI access beyond high-end radiology departments to smaller and rural facilities. The proliferation of cybersecurity frameworks, federated learning, and HIPAA-compliant data management boosts provider confidence in cloud adoption. Subscription-based pricing models improve affordability and democratize AI access, fostering broader market penetration across U.S. healthcare infrastructure.
Key Trends & Opportunities:
AI-Enabled Multimodal Diagnostic Intelligence
A key emerging opportunity lies in the integration of imaging data with genomics, pathology, and clinical records, forming multimodal diagnostic ecosystems. AI platforms combine structured and unstructured data to create comprehensive patient profiles that support disease risk prediction, treatment planning, and response monitoring. Oncology care benefits greatly as AI-enabled radiomics translates image-derived patterns into biomarkers that correlate with tumor aggressiveness and therapy effectiveness. Multimodal intelligence reduces reliance on invasive biopsies and helps clinicians intervene earlier. Partnerships between imaging vendors, biotech companies, and genomic research institutions accelerate the commercialization of integrated diagnostic solutions, unlocking new reimbursement paths and strengthening precision-medicine initiatives.
- For instance, Tempus’ multimodal AI platform analyzed more than 6 million de-identified clinical records and over 50 petabytes of oncology data to generate predictive models that correlate imaging signals with genomic mutations for precision therapy selection.
Generative AI and Automation of Radiology Reporting
Generative AI introduces compelling opportunities by automating structured report creation, summarizing radiology findings, and converting images into contextual written analyses. These models shorten reporting cycles, standardize terminology, and reduce administrative workloads for radiologists. Automation extends into appointment scheduling, protocol selection, and study prioritization, further optimizing department operations. The technology enhances training and knowledge transfer by helping junior clinicians learn interpretation patterns and differential diagnosis methodologies. Additionally, generative AI supports patient-facing communication by simplifying complex imaging results into plain-language summaries, improving engagement and comprehension. As validation frameworks for generative AI evolve, its broader clinical adoption will accelerate across hospitals, tele-radiology services, and urgent care centers.
- For instance, Nuance’s PowerScribe platform, enhanced by its AI-driven reporting engine, supports more than 6,500 U.S. healthcare facilities and automates voice-driven report creation for over 80% of radiologists across its network, demonstrating scale in generative documentation workflows.
Growing Adoption of AI in Remote and Point-of-Care Imaging
Remote diagnostics and point-of-care ultrasound present significant growth opportunities for AI imaging solutions, particularly in underserved and rural U.S. regions. AI enhances the acquisition and interpretation of non-specialist imaging, enabling emergency physicians, primary care providers, and paramedics to perform scanning with decision-support guidance. The trend aligns with evolving care models that emphasize decentralization, home-based care, and rapid-response medical services. Portable imaging integrated with AI helps expedite care pathways for trauma, stroke, and cardiac events by enabling earlier triage before hospital arrival. As telehealth reimbursement expands and point-of-care devices become more affordable, AI-supported imaging will gain broader uptake beyond traditional radiology departments.
Key Challenges:
Regulatory Complexity and Validation Requirements
The regulatory environment for AI in medical imaging remains a significant challenge as the industry shifts from static algorithms to continuously learning models. Regulatory bodies require stringent clinical validation to ensure patient safety, algorithm reliability, and equitable performance across diverse demographic profiles. AI developers must address bias mitigation, explainability, and traceability of decision-making processes. Recertification requirements increase as models evolve through real-world data exposure. Compliance with HIPAA, FDA guidance, and state-by-state regulations adds cost and time to commercialization. These hurdles slow adoption and create barriers for smaller innovators facing resource constraints in regulatory navigation and documentation.
Interoperability, Data Fragmentation, and Integration Costs
Despite clear clinical value, successful AI adoption depends heavily on seamless interoperability with existing hospital IT ecosystems. Data fragmentation across disparate PACS, EHR, and RIS systems limits algorithm training quality and restricts real-time analytics. Retrofitting AI within aging legacy infrastructure imposes integration expenses that may deter smaller providers. Standardization gaps in imaging formats, labeling practices, and annotation datasets hinder cross-institutional model scalability. Concerns around data sharing, cybersecurity, and patient consent contribute to operational complexity. Without structured data governance frameworks, healthcare organizations risk inconsistent results, workflow disruptions, and incomplete clinical benefits from AI deployments.
Regional Analysis:
Northeast
The Northeast region accounts for approximately 20% of the U.S. AI in medical imaging market. High concentration of academic medical centers, leading research hospitals, and strong adoption of advanced radiology services support AI penetration. Large health systems in urban hubs drive early adoption of AI-based CT, MRI and mammography technologies, enabling fast triage and diagnostic workflows. Additionally, dense population and high screening volumes for cancer and cardiovascular diseases increase demand for AI-enabled imaging, making the Northeast a core region for growth and innovation.
Midwest
The Midwest holds around 18% market share in U.S. AI medical imaging. This region benefits from a robust network of community and regional hospitals, along with a growing number of diagnostic imaging centers spread across smaller cities and suburban areas. The high number of imaging centers (~3,304 as recently reported) provides a large base for deploying AI-powered imaging solutions. Providers in the Midwest increasingly adopt cloud-based AI platforms to modernize legacy imaging systems and improve diagnostic throughput, particularly for CT and ultrasound, meeting rising demand for chronic disease screening.
South (including Southeast)
The South, including the Southeast, represents roughly 28% of the U.S. AI in medical imaging market - the largest regional share among U.S. regions. The region hosts the greatest number of imaging centers (≈ 4,169), reflecting high demand for diagnostic services. Rapid population growth, rising prevalence of chronic illnesses, and expanding hospital infrastructure stimulate AI adoption across modalities (CT, X-ray, ultrasound) and applications (cardiovascular, oncology, general diagnostics). Many healthcare chains in the South implement AI to standardize imaging quality and handle large patient volumes efficiently, making it a major growth engine.
West
The Western region captures about 22% share of the U.S. AI imaging market. The West features a mix of large metropolitan hospitals, regional health networks, and an increasing number of outpatient diagnostic centers. Adoption of AI in imaging is driven by innovation hubs, technology-savvy healthcare providers, and early adoption of cloud-native imaging platforms. Growing demand in urban and suburban areas, particularly in states with expanding populations and modern healthcare infrastructure, fuels uptake of AI-enabled MRI, CT, and molecular imaging solutions. The West’s balanced distribution of hospitals and diagnostic centers positions it as a strong growth region.
Southwest & Other Regions (incl. rural / smaller states)
The Southwest and smaller U.S. regions together hold about 12% of the market. Though infrastructure is more fragmented and fewer high-end imaging centers exist compared to major metro regions, there is steady growth fueled by rural hospital upgrades and diagnostic center expansions. AI adoption in these areas is rising thanks to cloud-delivered AI services and mobile imaging solutions, which lower the barrier to entry for smaller facilities. As rural populations age and demand for imaging increases, these regions are poised to contribute modest but growing portions of overall market revenue.
Market Segmentations:
By Modality
- X-ray
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Ultrasound Imaging
- Molecular Imaging
By Application
- Breast Imaging
- Lung Imaging
- Neurology
- Cardiovascular Applications
- Liver Imaging
- Other Applications
By End-Use
- Hospitals
- Clinics
- Diagnostic Centers
By Geography
- Northeast
- Midwest
- South
- West
- Southwest
Competitive Landscape:
The U.S. artificial intelligence (AI) in medical imaging market exhibits a highly competitive and rapidly evolving landscape, characterized by collaboration between global imaging OEMs, pure-play AI vendors, cloud providers, and health IT companies. Large imaging manufacturers and platform players focus on integrating FDA-cleared AI applications directly into PACS, scanners, and enterprise imaging suites, strengthening their position with end-to-end workflow solutions. Specialized AI firms concentrate on niche use cases such as stroke detection, lung nodule analysis, breast cancer screening, and triage tools, often partnering with hospitals and radiology groups for clinical validation and scaled deployment. Cloud and analytics providers enable secure, vendor-neutral AI marketplaces and subscription-based models that lower adoption barriers for mid-sized hospitals and diagnostic centers. Mergers, acquisitions, and strategic alliances remain frequent as companies seek to expand modality coverage, broaden indication portfolios, and achieve interoperability across heterogeneous imaging and health record environments.
Key Player Analysis:
- Nanox Imaging LTD.
- GE Healthcare
- Lunit Inc.
- IBM Watson Health
- InformAI LLC
- Intel Corporation
- Koninklijke Philips N.V.
Recent Developments:
- In November 2025, Nanox announced a strategic partnership with 3DR® Labs, under which 3DR Labs will distribute Nanox.AI’s FDA-cleared imaging solutions to its network of 1,800+ hospitals and imaging centers across the U.S.
- In 2025, GE Healthcare announced that it will acquire Intelerad - a medical-imaging software provider - for about $2.3 billion, a strategic move that boosts GE’s cloud-based and AI-enabled imaging offerings for outpatient care markets.
- In December 2024, Nanox Imaging LTD. obtained FDA clearance for its Nanox.ARC imaging system for general use (including pulmonary indications).
Report Coverage:
The research report offers an in-depth analysis based on Modality, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI will become integral to diagnostic decision support, improving accuracy and reducing interpretation errors across major imaging modalities.
- Generative AI will automate structured reporting and enhance clinical documentation efficiency for radiologists.
- Multimodal AI platforms will integrate imaging, genomics, and electronic health records to support precision medicine.
- Adoption of cloud-based AI solutions will expand, enabling scalable deployments across hospitals and diagnostic centers.
- Real-time AI-assisted imaging at point-of-care settings will increase, supporting remote and rural healthcare delivery.
- AI-driven predictive analytics will assist clinicians in forecasting disease progression and treatment response.
- Federated learning will strengthen algorithm performance without compromising patient data privacy.
- Regulatory frameworks for adaptive AI models will evolve, accelerating approvals while ensuring safety.
- AI marketplaces will grow, offering plug-and-play diagnostic applications integrated into PACS and imaging systems.
- Partnerships between healthcare providers, technology firms, and research organizations will accelerate innovation and adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Early Diagnostics and Precision Imaging
The push for early disease detection and precision medicine is accelerating AI adoption in medical imaging, as healthcare providers seek to reduce diagnostic errors, improve sensitivity for chronic conditions, and enable earlier intervention through advanced image analysis.
Integration of AI-Enabled Clinical Decision Support
AI-powered clinical decision support systems are transforming radiology workflows by providing real-time alerts, prioritization, and contextual recommendations, which help radiologists make faster, more accurate decisions and improve patient outcomes, especially in emergency and critical care settings.
Expansion of Cloud-Based AI Imaging Platforms
Cloud-native AI solutions lower capital expenditure, enable scalable deployments, and facilitate remote diagnostics, making advanced imaging analytics accessible to a broader range of hospitals, clinics, and rural providers while supporting continuous model improvement and secure data management.
Regulatory Support and FDA Clearances
Increasing FDA approvals for AI-based imaging solutions and supportive reimbursement policies are boosting provider confidence and accelerating the integration of AI tools into clinical practice, particularly for high-volume applications like breast and lung cancer screening.
Growth of Multimodal and Generative AI Technologies
The emergence of multimodal AI platforms that integrate imaging, genomics, and clinical data, along with generative AI for automated reporting, is enhancing diagnostic accuracy, streamlining workflows, and supporting the shift toward precision medicine and value-based care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the U.S. artificial intelligence (AI) in medical imaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. AI in medical imaging market expected to grow between 2024 and 2032?
Which market category is in the lead for the imaging modality?
Which segment is leading the market in terms of application?
Which end-user segment is estimated to have the highest CAGR throughout the forecast period?
Who are the leading companies in the U.S. AI in medical imaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Diagnostic Centers
- 1.3 By Modality
- 1.3.1 X-ray
- 1.3.2 Computed Tomography (CT)
- 1.3.3 Magnetic Resonance Imaging (MRI)
- 1.3.4 Ultrasound Imaging
- 1.3.5 Molecular Imaging
- 1.4 By Application
- 1.4.1 Breast Imaging
- 1.4.2 Lung Imaging
- 1.4.3 Neurology
- 1.4.4 Cardiovascular Applications
- 1.4.5 Liver Imaging
- 1.4.6 Other Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 510 million → 2032: USD 4,474.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 US Artificial Intelligence (AI) in Medical Imaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 US Artificial Intelligence (AI) in Medical Imaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 US Artificial Intelligence (AI) in Medical Imaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 US Artificial Intelligence (AI) in Medical Imaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 US Artificial Intelligence (AI) in Medical Imaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 US Artificial Intelligence (AI) in Medical Imaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 US Artificial Intelligence (AI) in Medical Imaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 US Artificial Intelligence (AI) in Medical Imaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 510 million → 2032: USD 4,474.82 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 US Artificial Intelligence (AI) in Medical Imaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Diagnostic Centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Modality - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 X-ray
- 12.4.7.2 Computed Tomography (CT)
- 12.4.7.3 Magnetic Resonance Imaging (MRI)
- 12.4.7.4 Ultrasound Imaging
- 12.4.7.5 Molecular Imaging
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Breast Imaging
- 12.5.7.2 Lung Imaging
- 12.5.7.3 Neurology
- 12.5.7.4 Cardiovascular Applications
- 12.5.7.5 Liver Imaging
- 12.5.7.6 Other Applications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 US Artificial Intelligence (AI) in Medical Imaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 US Artificial Intelligence (AI) in Medical Imaging Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 US Artificial Intelligence (AI) in Medical Imaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 US Artificial Intelligence (AI) in Medical Imaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nanox Imaging LTD.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE Healthcare
- 18.4 Lunit Inc.
- 18.5 IBM Watson Health
- 18.6 InformAI LLC
- 18.7 Intel Corporation
- 18.8 Koninklijke Philips N.V.
- 18.9 Aidoc
- 18.10 Nuance Communications
- 18.11 Tempus
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

