
Console replacement, not case growth, drives bypass spending
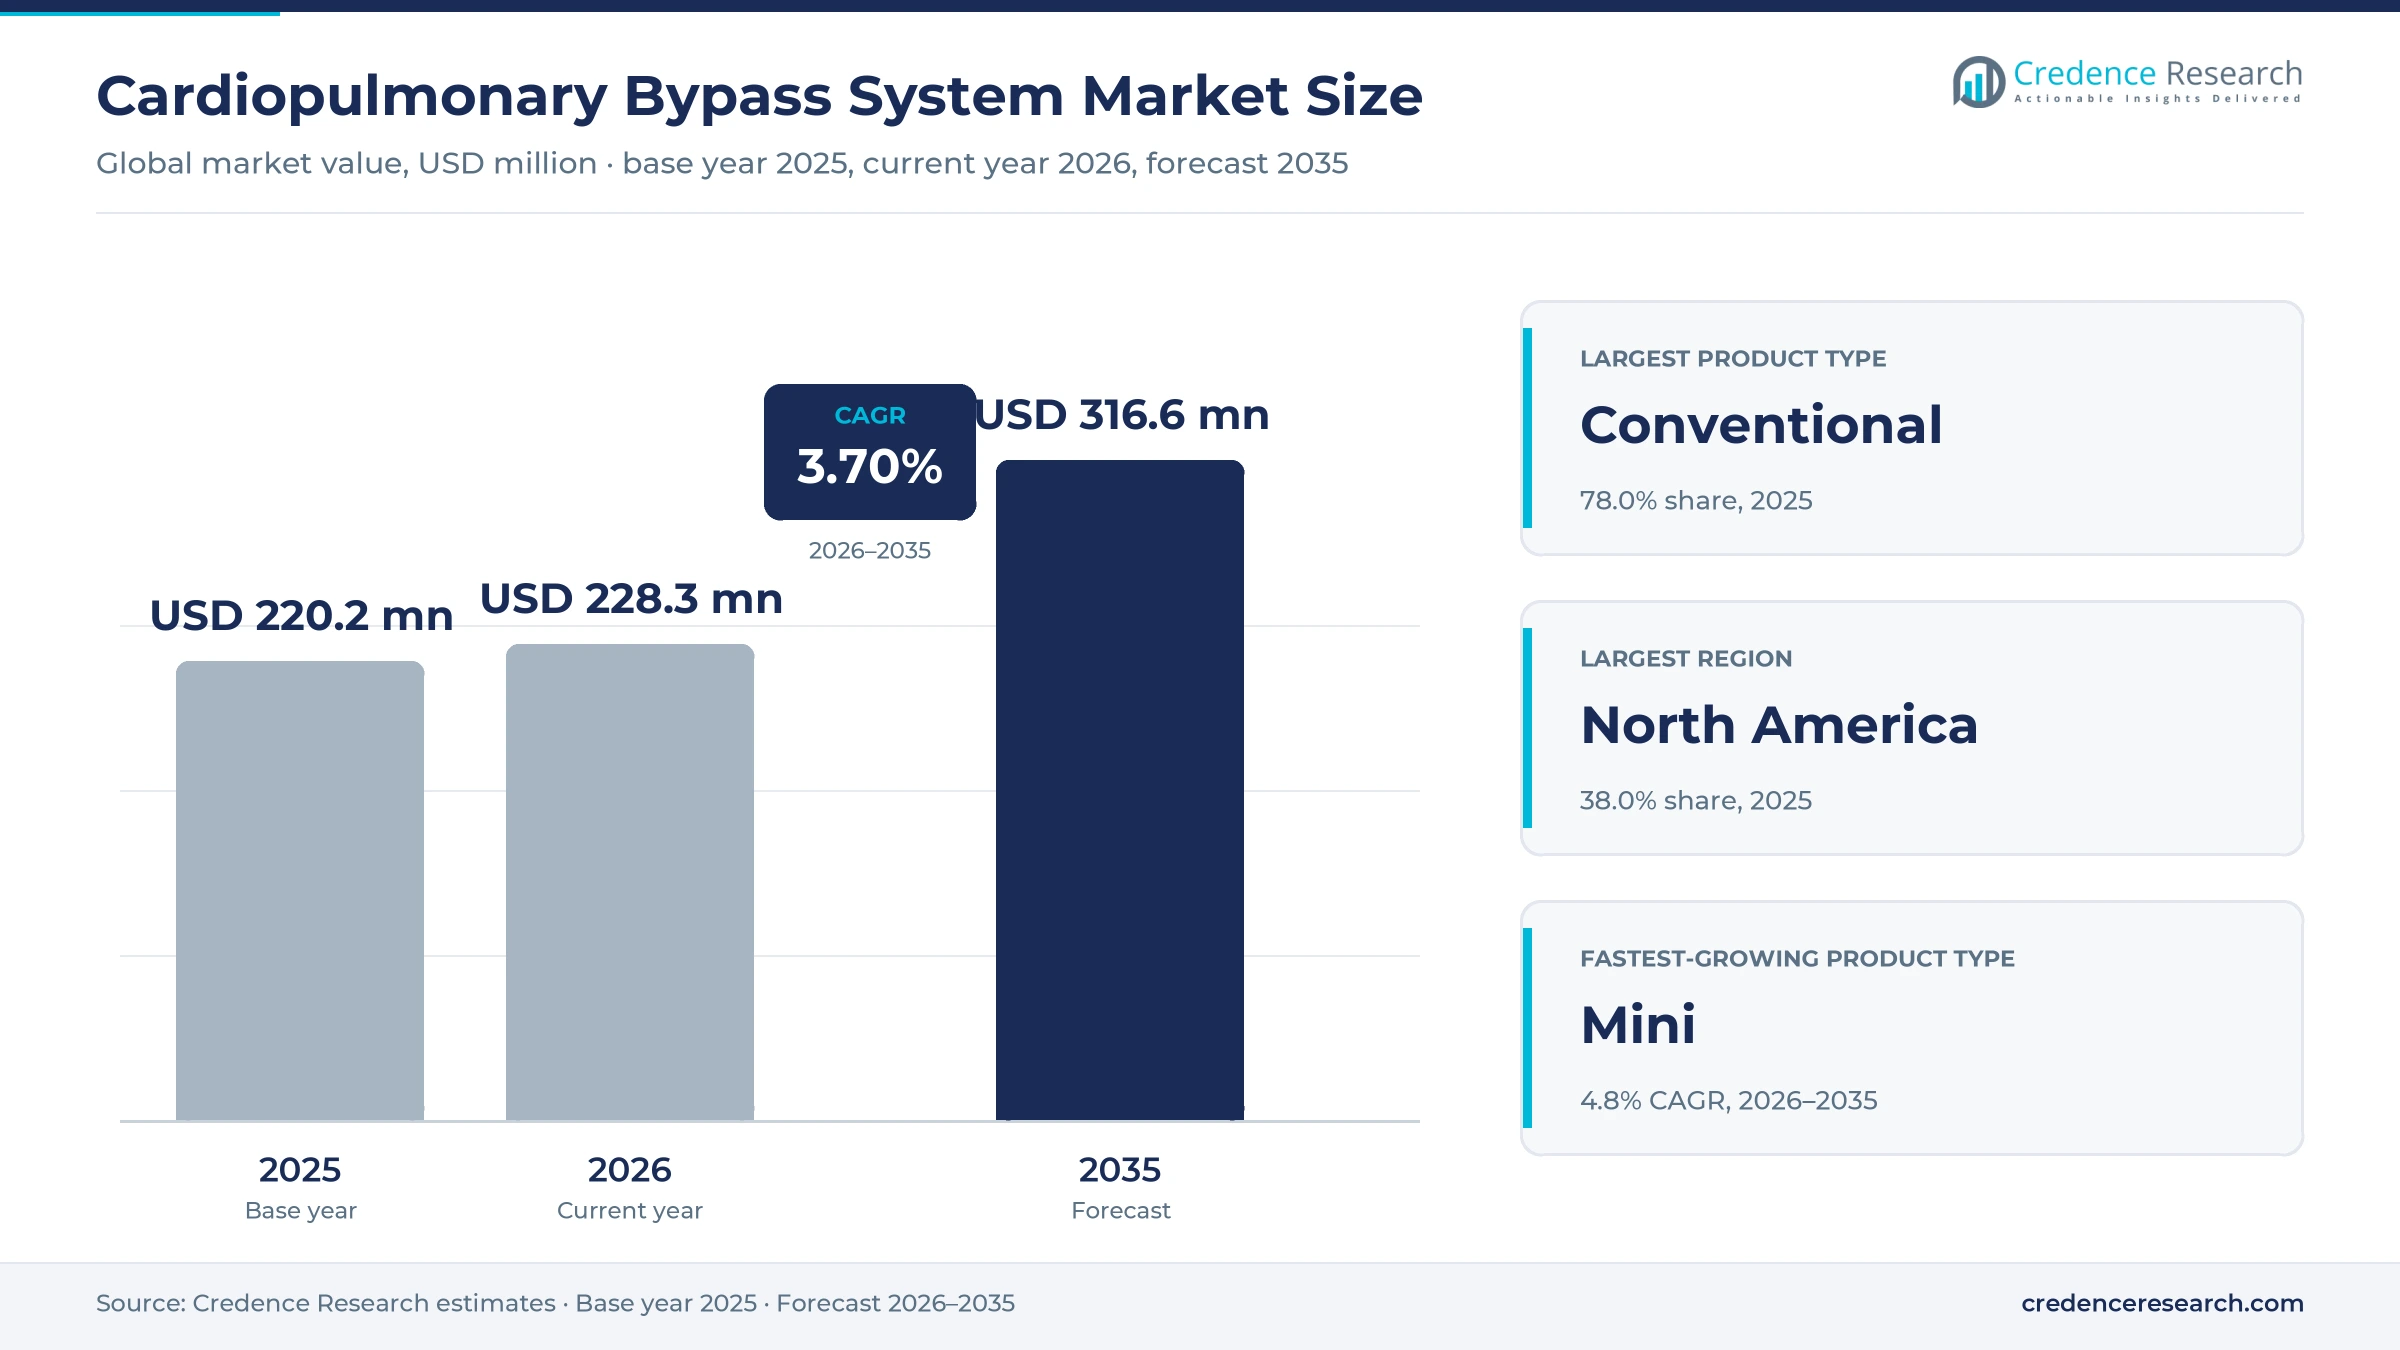
The global cardiopulmonary bypass system market was valued at USD 220.2 million in 2025 and is projected to increase from USD 228.3 million in 2026 to USD 316.6 million by 2035, registering a CAGR of 3.70% during 2026–2035. Demand comes from the replacement of aging heart-lung machines in cardiac surgery programs, from new open-heart capacity in China and India, and from perfusion teams that want integrated monitoring and automated safety controls. North America held the largest regional share, 38.0% in 2025, because the United States runs the largest base of cardiac surgery programs and pays the highest prices per console. Asia Pacific is the fastest-growing region at 5.2% a year, as Chinese hospitals add cardiac surgery capacity and buy next-generation consoles. The most important commercial change is Getinge's exit from surgical perfusion, which hands its installed base to the remaining suppliers. A shrinking perfusionist workforce and the shift of aortic valve cases to transcatheter therapy are the main restraints on new purchases.
Consoles, pump modules and service define the counted value
The estimate counts cardiopulmonary bypass equipment, meaning heart-lung machine consoles with their roller and centrifugal pump modules, control and safety modules, integrated patient monitors, heater-cooler units sold with the console, and the software and service contracts attached to them. Single-use oxygenators, tubing packs, cannulae and cardioplegia sets are excluded, which is why the value is a fraction of the broader cardiopulmonary category that LivaNova describes as a USD 2 billion global market. Hospitals buy consoles as capital equipment, usually through tenders or group purchasing frameworks that bundle long maintenance terms.
The value chain runs from pump, sensor and control-electronics makers through a few console brands to perfusion departments, which usually standardize on one platform so that staff training and disposables stay consistent. A console normally stays in service for a decade or more, so spending follows hospital replacement cycles and new cardiac programs rather than yearly procedure counts. Margins sit with suppliers that pair the console with proprietary disposables, data software and field service.
Cardiopulmonary Bypass System Market Insights
- The market rises from USD 220.2 million in 2025 to USD 316.6 million by 2035, a 3.70% CAGR, as hospitals replace aging consoles and Chinese cardiac programs buy integrated systems.
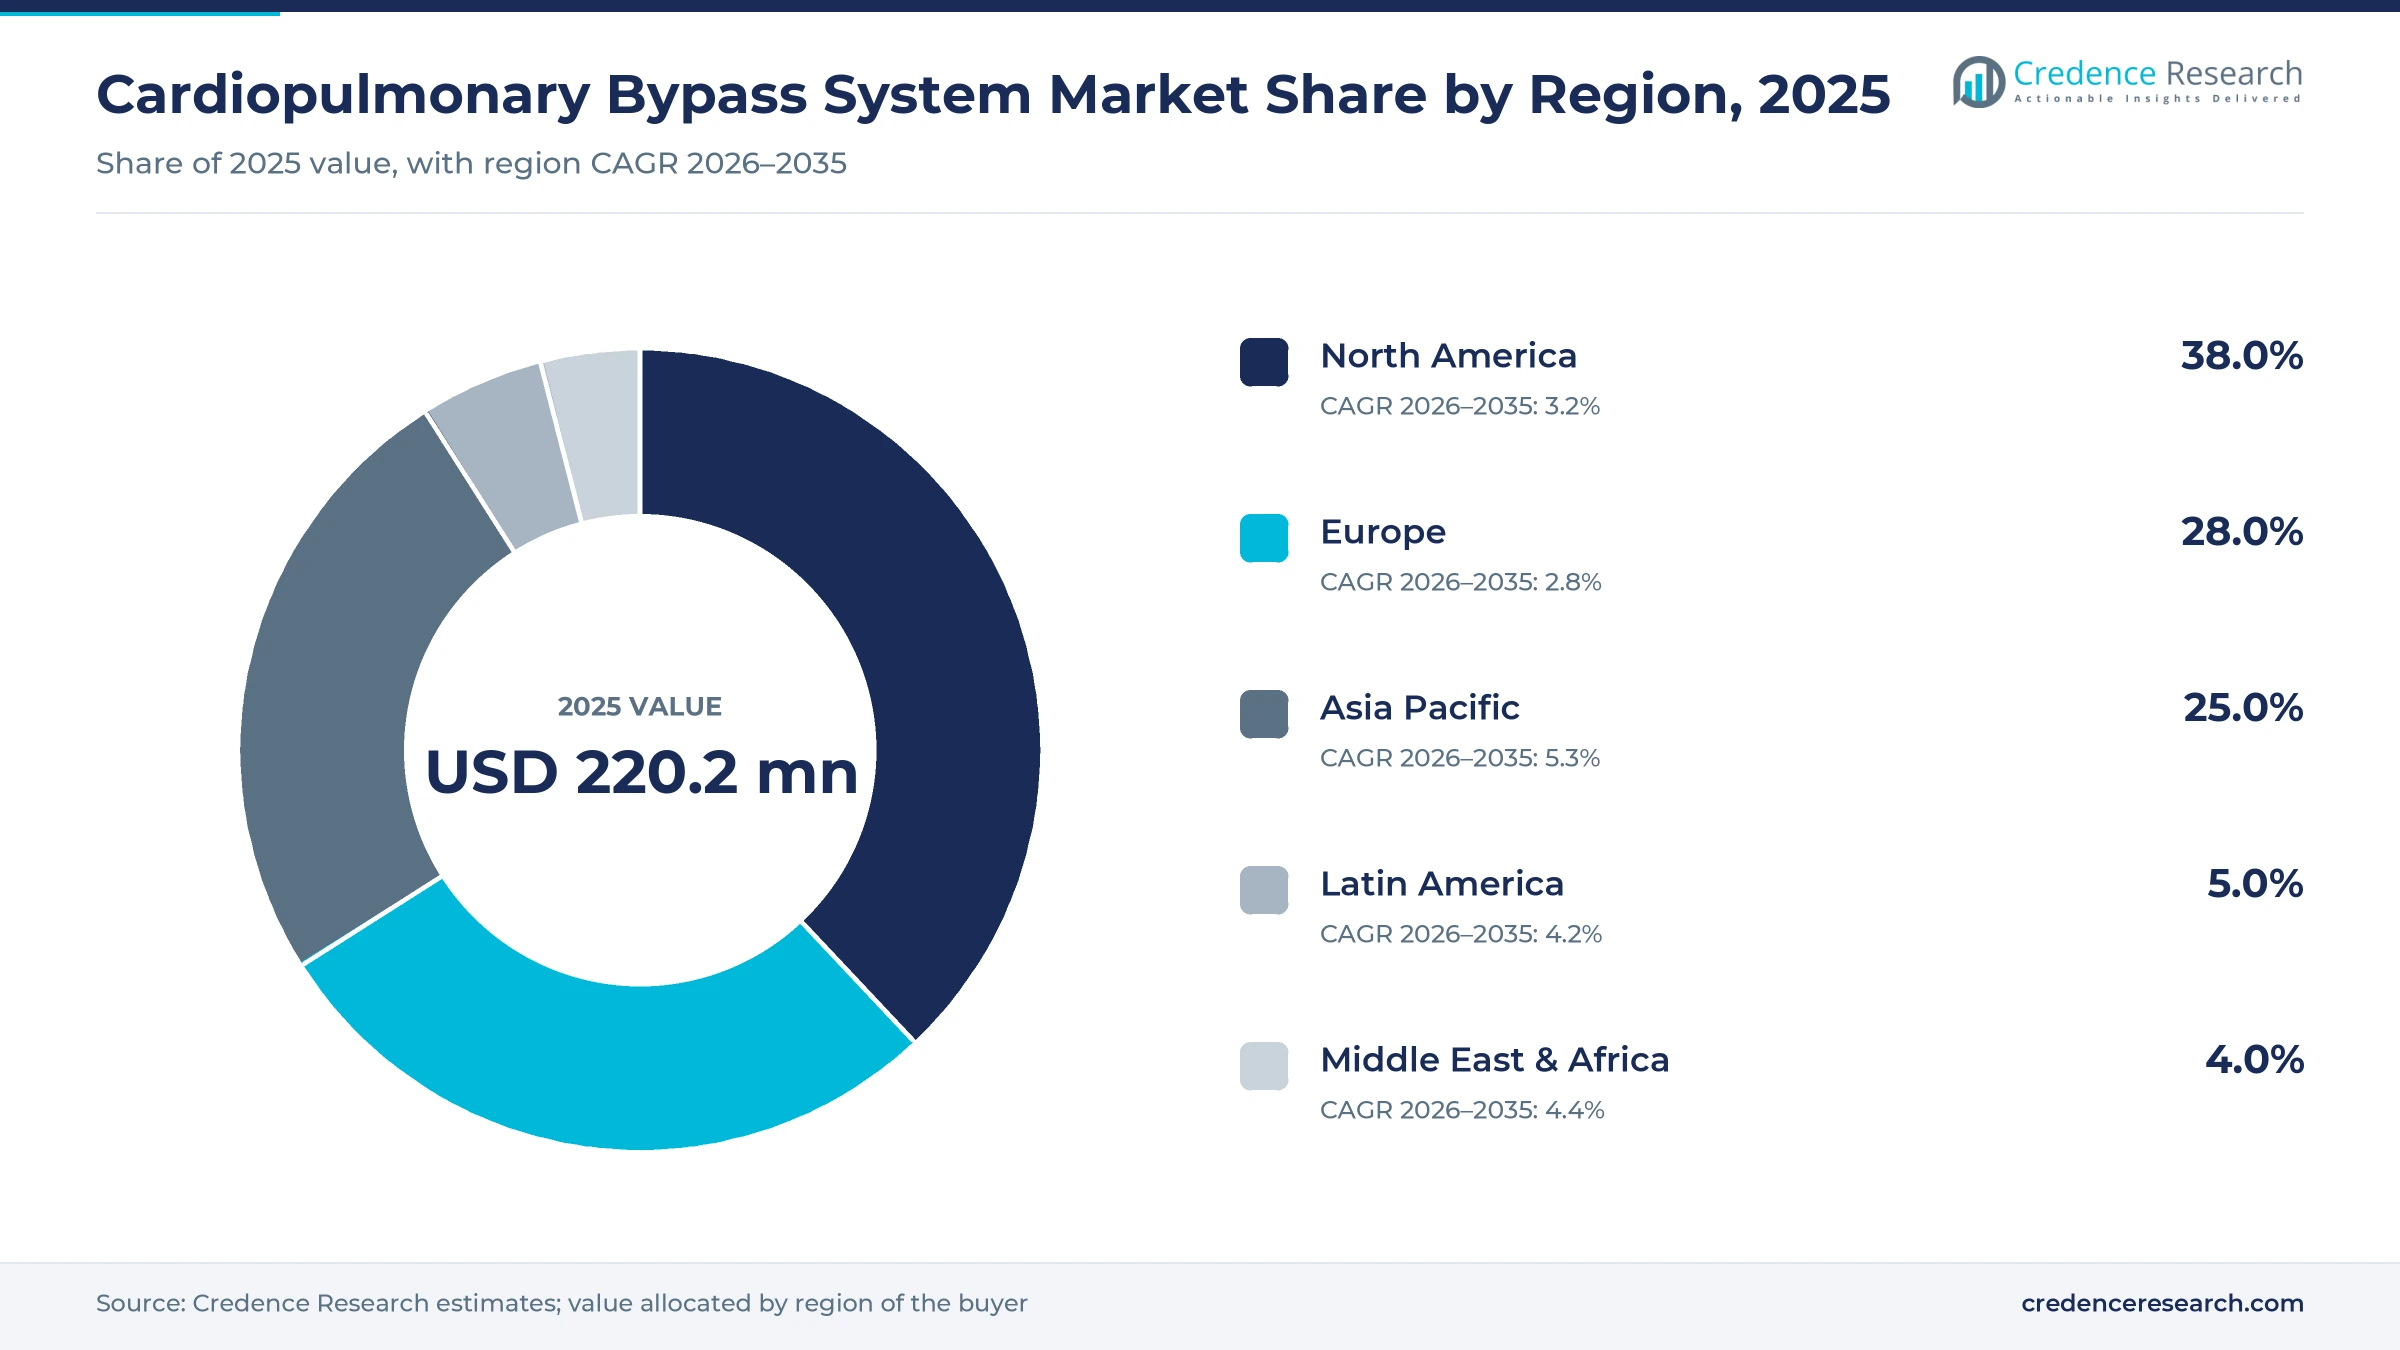
- North America held 38.0% of 2025 value, because the United States runs more than 1,000 cardiac surgery programs and pays the highest prices per console.
- Conventional systems took 78.0% of 2025 value, because most perfusion teams still run full-size circuits with open venous reservoirs for valve, aortic and redo surgery.
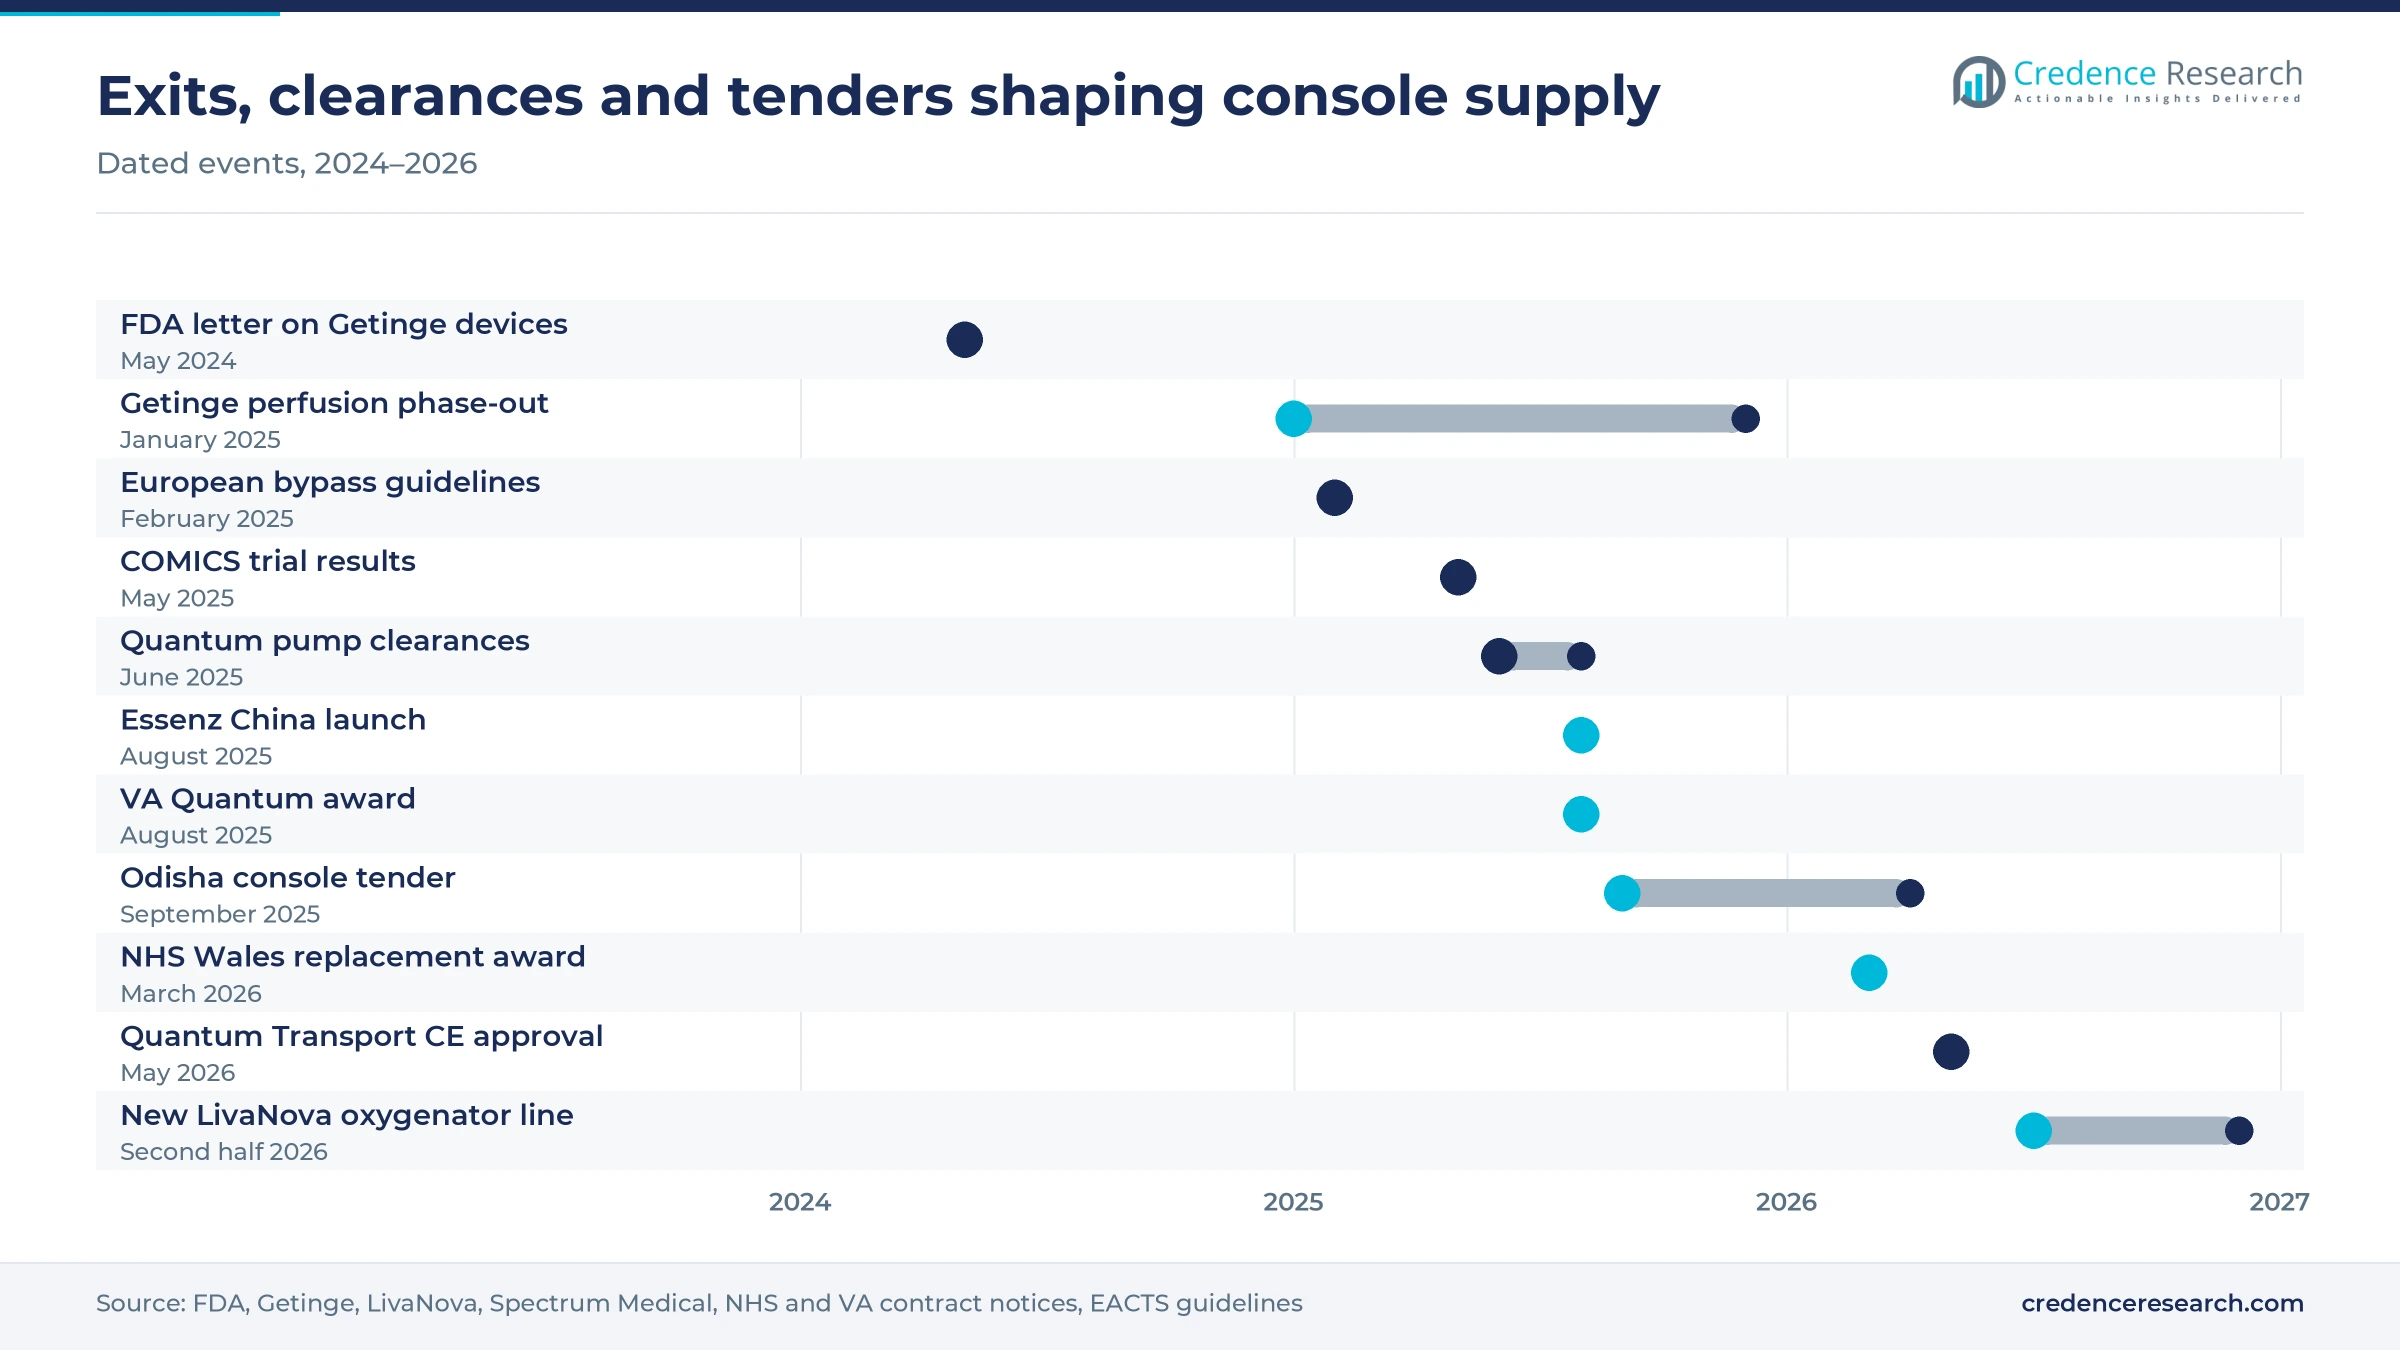
- Getinge said on Jan. 28, 2025, that it would phase out its surgical perfusion product category, leaving LivaNova, Terumo and Spectrum Medical as the main console suppliers.
- LivaNova expected its Essenz platform to reach about 80% of its heart-lung machine placements in 2026, up from about 40% in 2024.
Conventional circuits lead as mini systems grow fastest
Conventional circuits dominate as mini systems gain evidence
Based on product type, the market is categorized into conventional and mini systems. Conventional systems led with 78.0% of 2025 value because full-size open circuits remain the default for valve, aortic and redo operations. The 2024 European guidelines state that roller pumps remain standard wherever both negative and positive pressures are needed. Mini systems grow fastest at 4.8% a year, as the COMICS trial of 1,071 patients reported serious adverse events in 9.7% of minimally invasive cases against 13.2% with conventional circuits in May 2025, a gap short of statistical significance. Because circuit packs are excluded, the mini share reflects consoles and pump modules configured for minimally invasive circuits.
Standalone consoles lead while portable units grow fastest
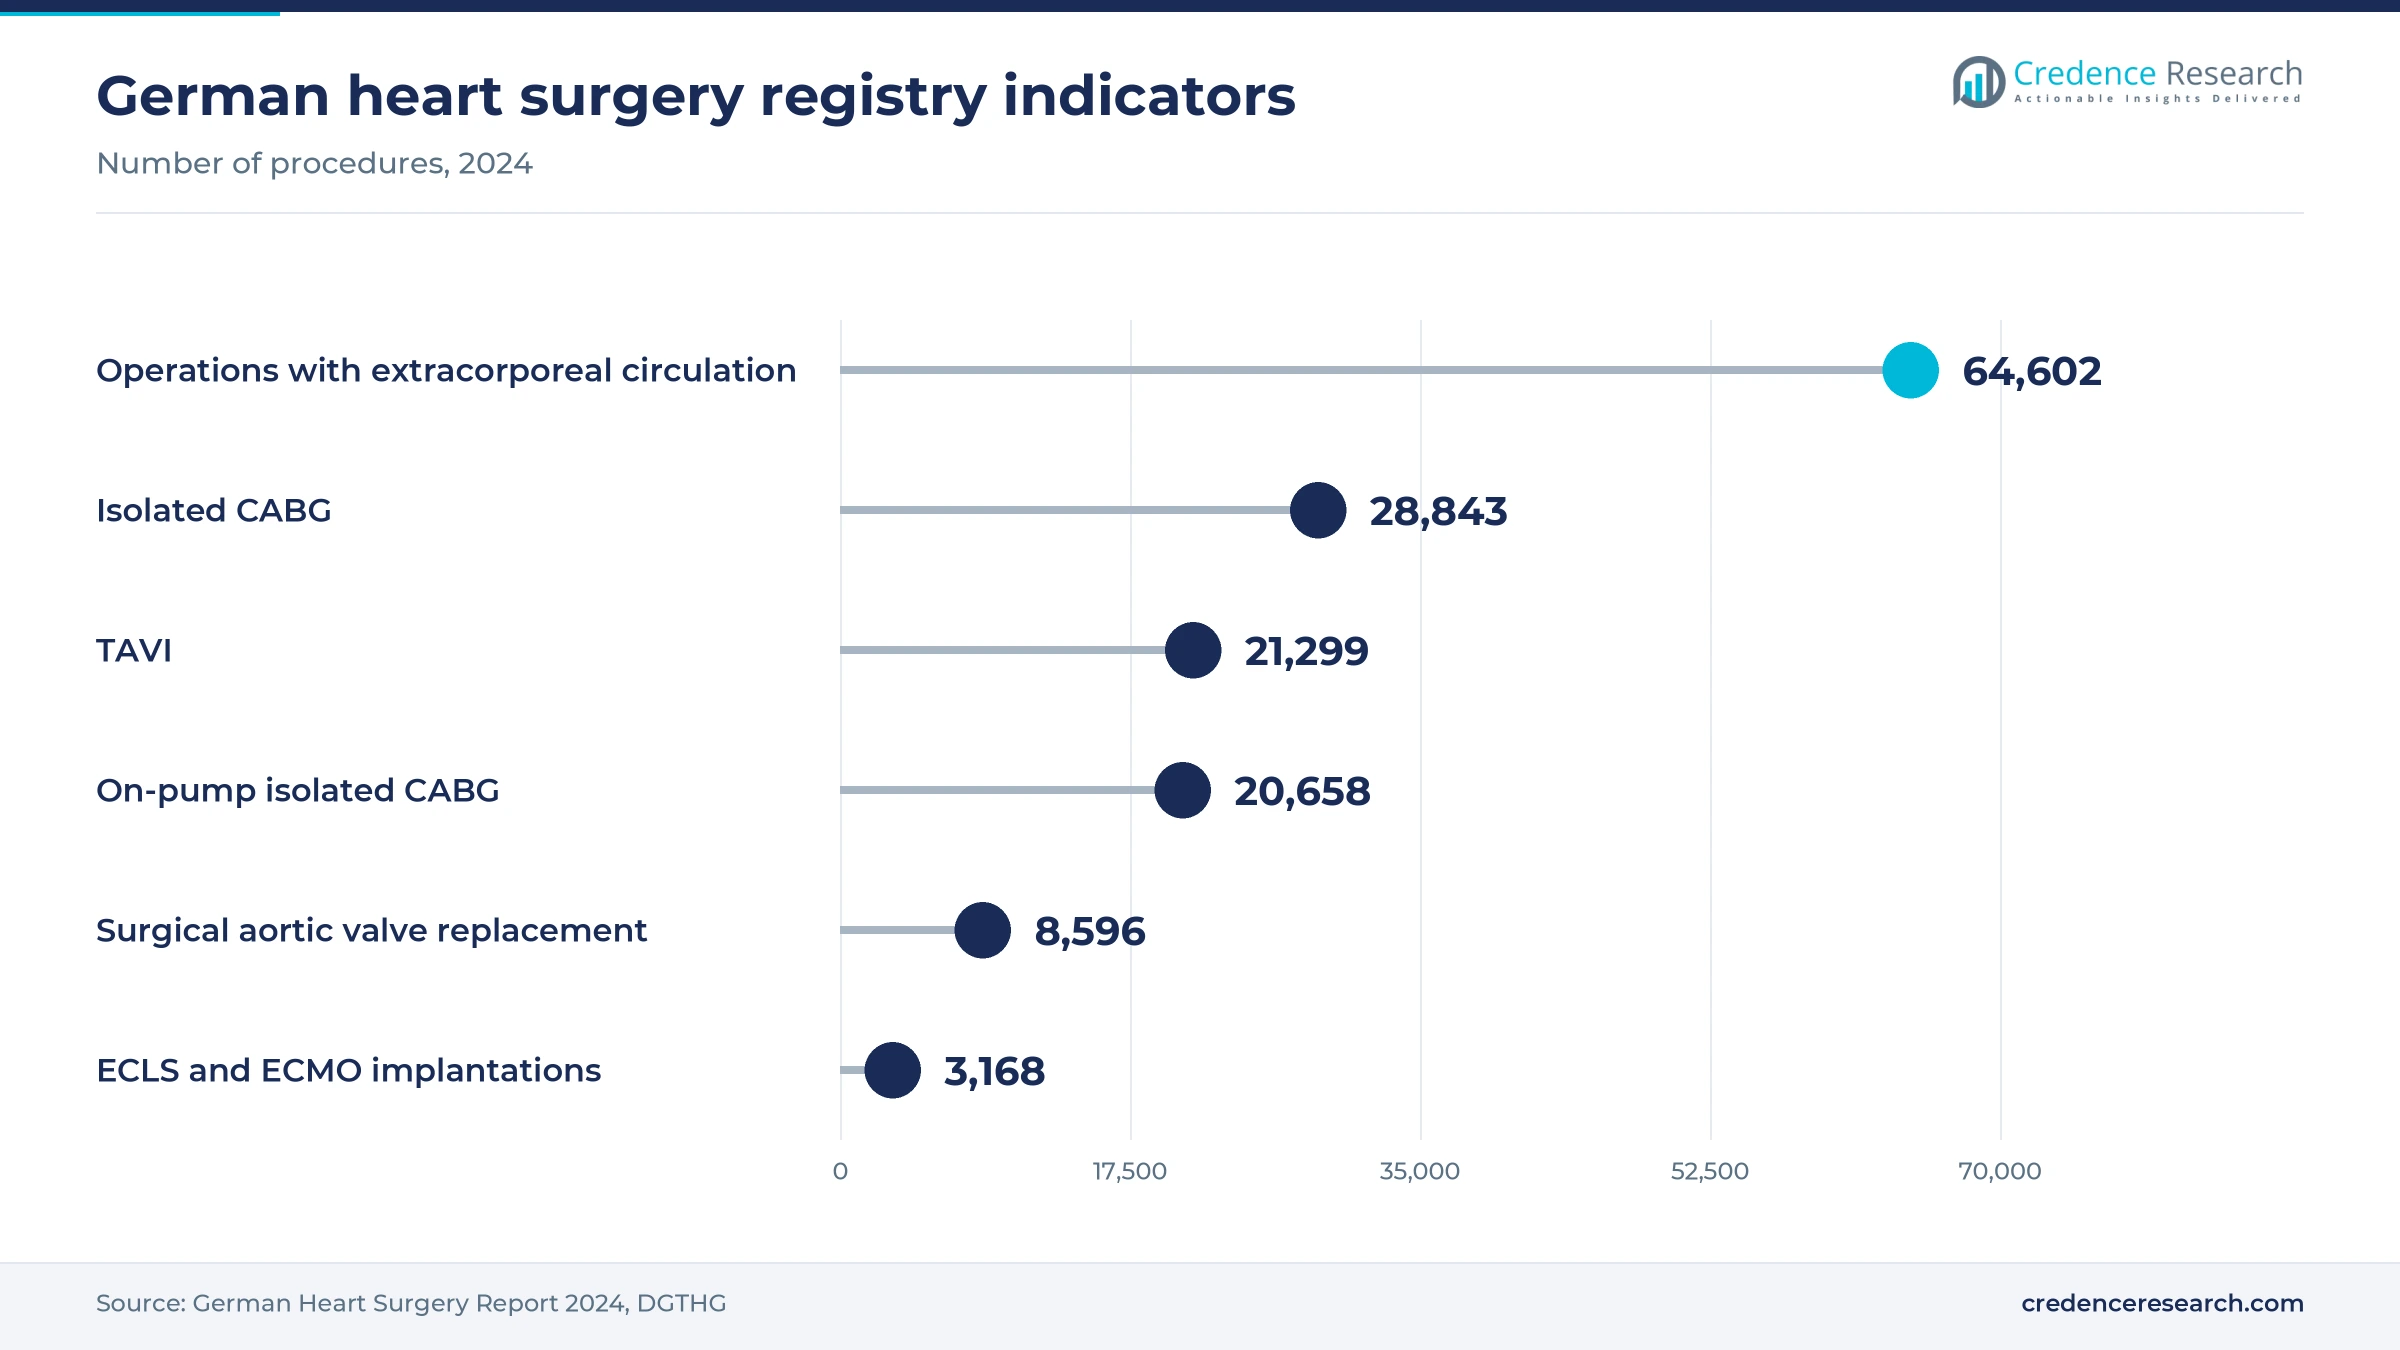
Based on modality, the market is categorized into standalone and portable systems. Standalone consoles led with 88.0% of 2025 value because operating-room heart-lung machines carry four or five pump modules, heater-cooler connections and patient monitors on one base. Braile Biomédica's BEC console, for example, mounts four double-roller pump modules with two backup batteries. Portable systems grow fastest at 5.1% a year, as hospitals extend extracorporeal support beyond the operating room. German centers recorded 3,168 ECLS and ECMO implantations in 2024, and total temporary circulatory support rose 10.6%, according to the German heart surgery registry.
Hospitals lead as teaching centers drive new tenders
Based on end user, the market is categorized into hospitals, academic medical centers and specialty cardiac centers. Hospitals led with 61.0% of 2025 value because most cardiac surgery still happens in general hospital programs, and the STS database covers more than 1,000 participating U.S. institutions and over 97% of U.S. cardiac surgery. Academic Medical Centers grow fastest at 4.5% a year, as teaching hospitals and medical colleges lead current tenders. Odisha State Medical Corporation sought heart-lung machines with heater-cooler units for medical colleges and hospitals in September 2025, with an estimated value of INR 9.92 crore.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Conventional | 78.0% | Mini | 4.8% |
| By Modality | Standalone | 88.0% | Portable | 5.1% |
| By End User | Hospitals | 61.0% | Academic Medical Centers | 4.5% |
Public tenders put premium consoles near USD 300,000
Heart-lung machines sell as capital equipment through tenders and group purchasing frameworks, and buyers usually price the console together with heater-cooler units, monitors and multi-year service. A U.S. Department of Veterans Affairs award in August 2025 paid USD 710,972 for two Spectrum Medical Quantum systems, close to USD 355,000 each, against a pre-award estimate near USD 296,000 per unit. Price moves with the number of pump modules, integrated monitoring, data software and service length. Lowest-price awards under NHS frameworks limit premiums in Europe, and LivaNova expects the Essenz premium over its older S5 platform to moderate.
| Purchase or indicator | Typical price or fee | Basis |
|---|---|---|
| Two Quantum heart-lung systems, VA Connecticut | USD 710,972 award, about USD 355,000 each | U.S. federal contract award, August 2025 |
| Replacement consoles, heater-coolers and 10-year service, Cardiff | About GBP 3.17 million contract value | NHS Wales award notice, March 2026 |
| Basic roller-pump console for emerging-market hospitals | USD 90,000–180,000 per console | Credence Research estimate, 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Getinge exit, China programs and monitoring lift demand
Getinge's exit forces hospitals to replace consoles
Getinge's withdrawal from surgical perfusion is creating a forced replacement cycle, because hospitals that run its HL 40 consoles must move to another platform before service and spare parts run down. Getinge said in its year-end report on Jan. 28, 2025 that its surgical perfusion share was not satisfactory and market growth was limited, and Cardiovascular Business reported that HL 40 and HCU 40 production would end by the close of 2025. Its share had already fallen from about 15% in 2018 to about 7% in 2023, according to Cardiovascular Business. Most of the affected installed base is likely to sit in Europe and Asia, since the products have not been sold in the United States since 2015. LivaNova, Terumo and Spectrum Medical are best placed to win these conversion tenders.
Chinese cardiac programs open a large console market
China is now the second-largest heart-lung machine market after the United States, according to LivaNova management in November 2025, and its demand rests on new and upgraded cardiac surgery programs. LivaNova's August 2025 launch material projected about 185,000 adult and 23,500 pediatric extracorporeal circulation procedures in China in 2025, across more than 700 hospitals equipped for cardiac surgery. NMPA approval allowed the Essenz launch to begin that month, about six months ahead of the company's internal target. LivaNova then reported a win rate above 80% in China in February 2026. Asia Pacific's regional lead in growth reflects this procurement, although long equipment sales cycles push most orders into 2026 and later.
Goal-directed perfusion pulls demand toward integrated consoles
Perfusion teams are replacing separate pumps and monitors with consoles that measure oxygen delivery, venous saturation and hemoglobin in line, because guidelines now treat these readings as part of safe bypass. The 2024 EACTS, EACTAIC and EBCP guidelines, published in February 2025, say level sensors and bubble detectors should trigger alarms and automatically control the pumps. They also discuss oxygen delivery monitoring as a proposed global standard that only 38% of surveyed respondents tracked regularly. LivaNova's Essenz system, cleared by the FDA in March 2023 and approved in Japan and Canada, pairs the heart-lung machine with a patient monitor built for goal-directed perfusion. Hospitals that still run older consoles must therefore buy new hardware to meet these practices.
Aged consoles are reaching replacement in public hospitals
Public hospitals are retiring consoles bought a decade or more ago, and their tenders now bundle heater-cooler units and long service terms with the purchase, as the Cardiff replacement contract in the price table shows. Hull University Teaching Hospitals funded its Essenz purchase in August 2026 through a capital replacement program. Within its own installed base, LivaNova expected Essenz to rise from about 40% of its heart-lung machine placements in 2024 to about 60% in 2025 and 80% in 2026, as S5 users upgrade. Suppliers with a large legacy base gain most from these cycles, while challengers win where hospitals want to change platforms.
Sensor pumps, ECLS platforms and service openings
Sensor-integrated centrifugal pumps are moving onto consoles
Console makers are shifting toward centrifugal pump heads with built-in pressure and flow sensors to reduce separate sensors and tubing connections, creating openings for modular arterial pump upgrades across adult and pediatric programs. The FDA cleared two Quantum perfusion centrifugal blood pumps with integrated sensors in 2025, the CP22V-NG on June 24 and the CP20V-NG on Aug. 4, according to agency 510(k) records. The 2024 European guidelines found no outcome difference between centrifugal and roller pumps in a meta-analysis, although one large single-center trial favored centrifugal pumps on chest tube drainage and massive transfusion. Roller heads stay in use for suction and cardioplegia, so the shift adds pump modules rather than replacing whole consoles.
Suppliers are redirecting platforms toward ECLS and transport
Perfusion suppliers are shifting engineering budgets toward extracorporeal life support and transport consoles to address demand for circulatory support outside the operating room, creating openings for compact portable units across intensive care and interhospital transfer. Getinge said in January 2025 that resources freed by its surgical perfusion exit would go to ECLS and transplant care. Medtronic received CE Mark on July 1, 2025, for VitalFlow, one of the newest ECMO machines in Europe, and Spectrum Medical received CE approval for its Quantum Transport System on May 6, 2026. The same pump, sensor and software families increasingly span surgical bypass and ECMO, so a perfusion department can standardize training across both uses.
Heater-cooler replacement opens a bundled upgrade
Heater-cooler units give console suppliers a measurable opening, because infection-control rules push hospitals to replace older units and to buy them together with the console. After the Mycobacterium chimaera outbreak, the 2024 European guidelines recommended rigorous decontamination and placing heater-cooler units outside operating rooms. Getinge's HCU 40 belongs to the product family that Getinge began phasing out in January 2025, so its users need a new thermal unit as well as a new pump base. Public tenders already bundle both items, as the Odisha and Cardiff contracts described above show. Suppliers that sell a matched console, heater-cooler and service contract earn more per tender and secure later orders for membrane oxygenators.
Software and service contracts offer recurring income
Installed consoles offer an opening for recurring software and service income, because hospitals now expect data links, upgrades and long maintenance from the same supplier. LivaNova told investors at its November 2025 Investor Day that growth would come from the Essenz replacement cycle, consumables share gains and recurring software and service revenue. The VA's August 2025 award required compatibility with existing Quantum workstations and the VISION data server, which shows data platforms entering purchase criteria. LivaNova also ran a printed circuit board conversion through its service organization in the fourth quarter of 2025. Perfusion departments gain remote updates and audit data, while suppliers lock in service revenue for the life of each console.
Perfusionist shortages and transcatheter care restrain
A shrinking perfusionist workforce caps new programs
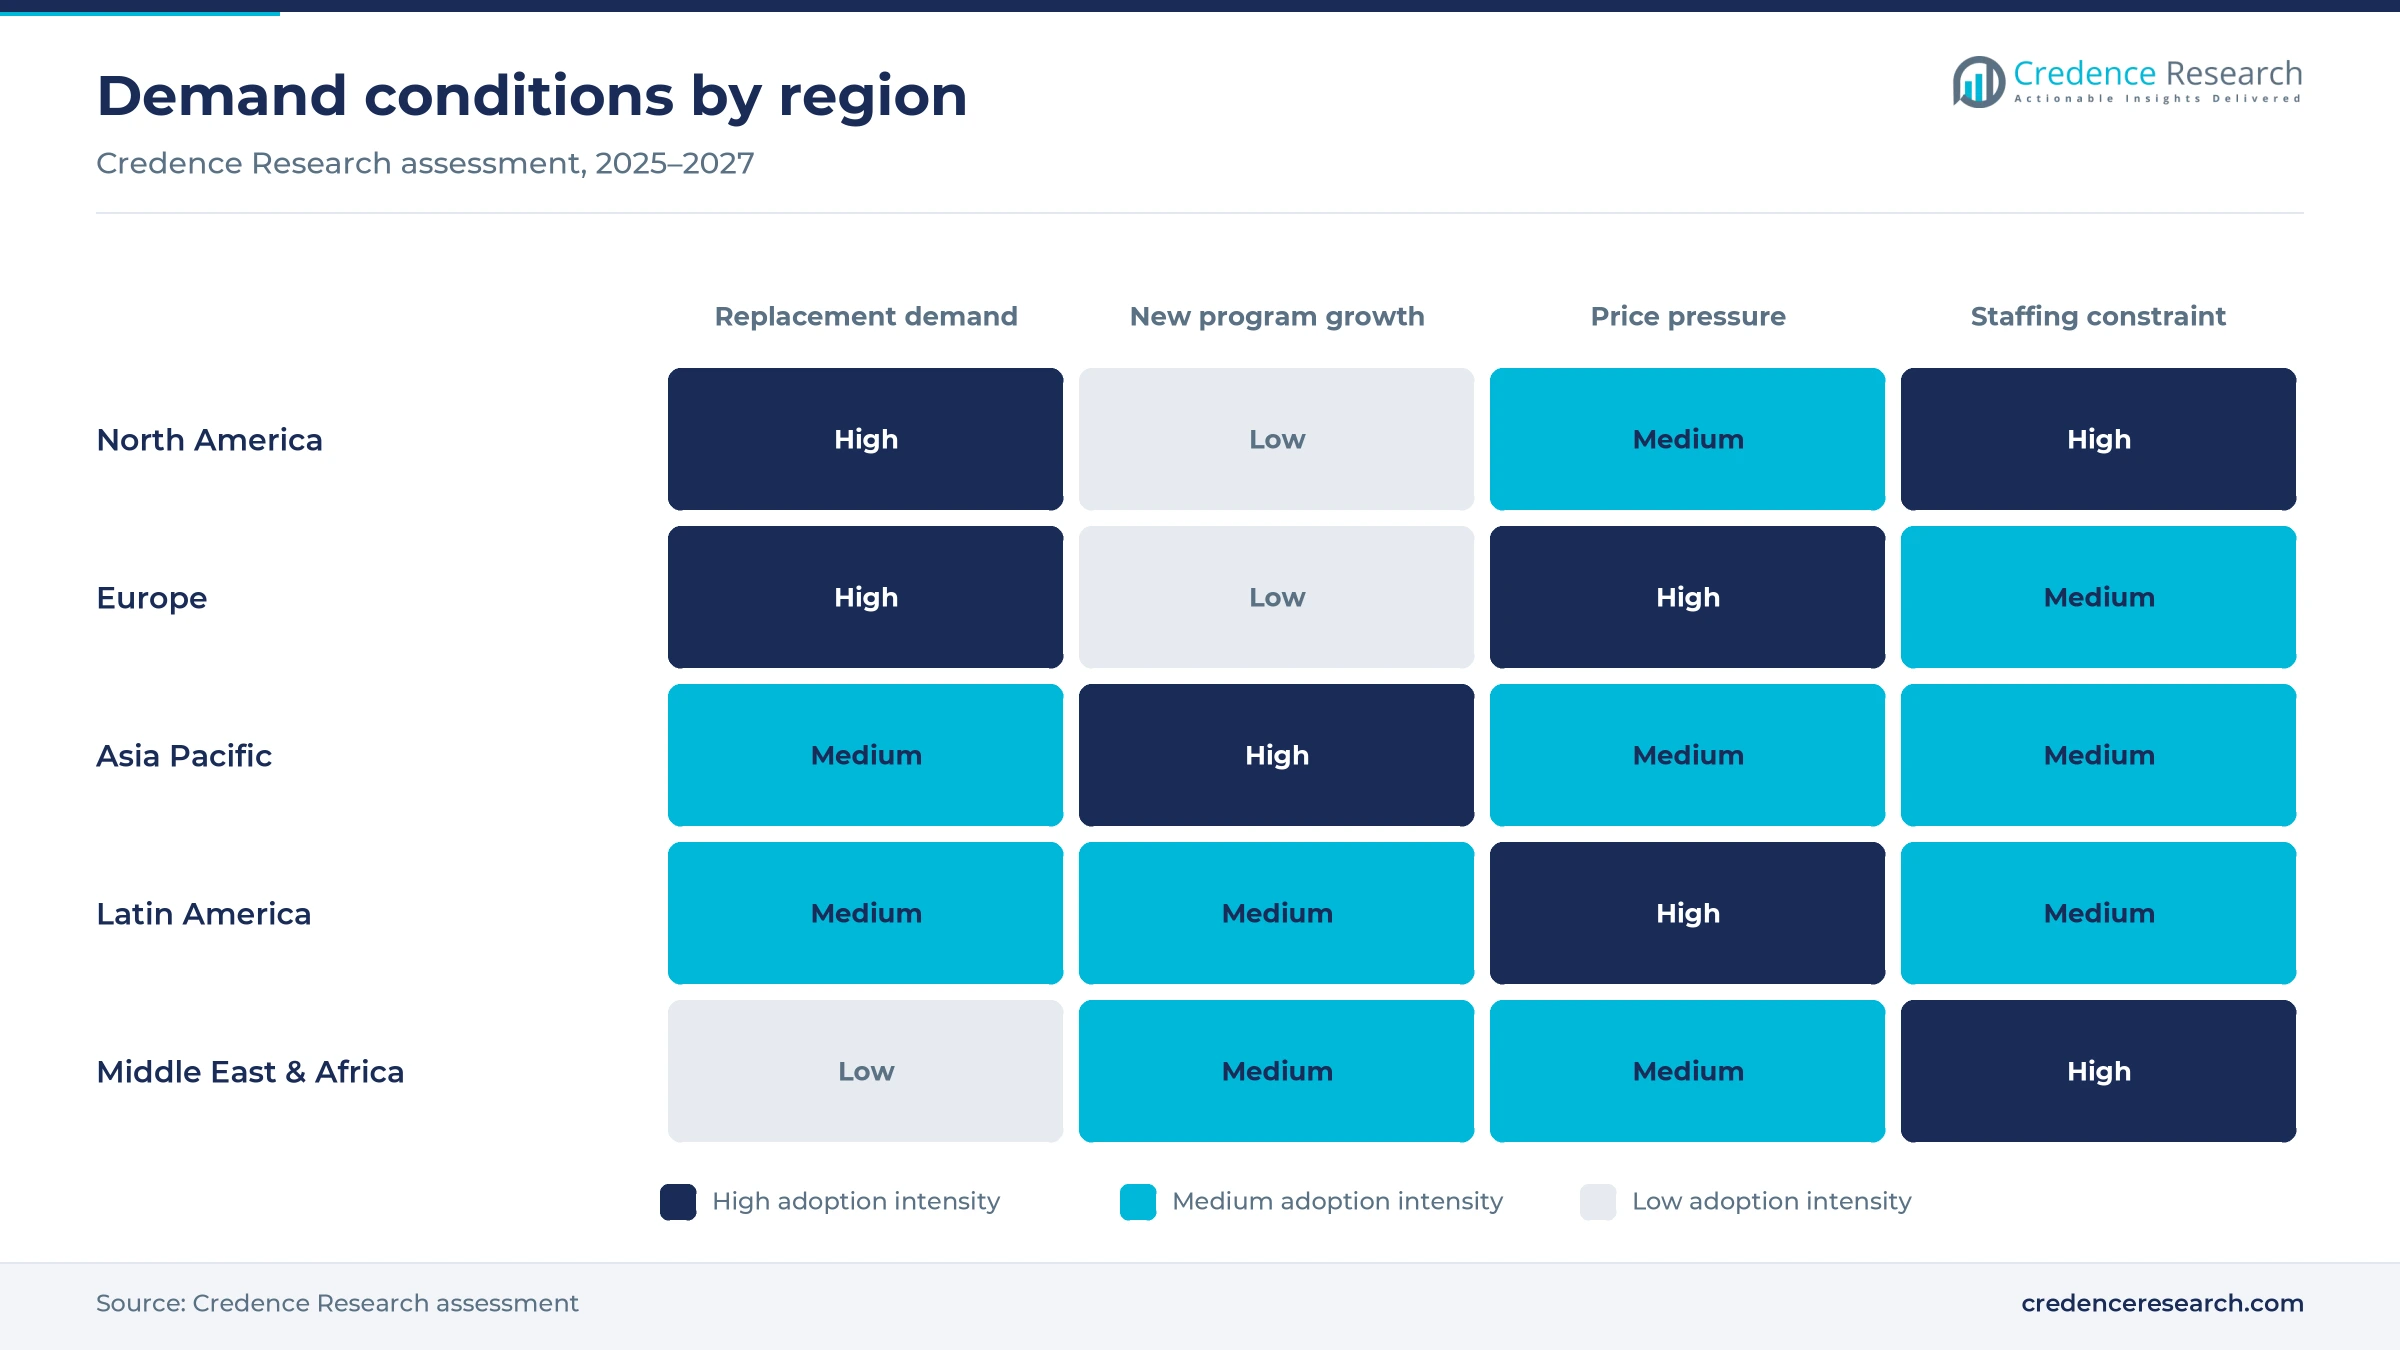
Staffing, not hardware, limits how fast hospitals can add bypass capacity. Nearly 44% of certified U.S. perfusionists are over 50, about 140 to 150 students graduate each year and about 300 leave the field annually, according to a 2026 Journal of ExtraCorporeal Technology study. European guidelines also call for n + 1 certified perfusionists per day for n running bypass rooms. Hospitals planning new cardiac programs are most exposed, and some may delay console orders until teams are hired.
Transcatheter valves remove cases from the pump
Transcatheter therapy is moving aortic valve patients away from bypass, which slows console utilization in mature markets. In Germany, TAVI accounted for 71.2% of isolated aortic valve procedures in 2024, against 28.8% for surgical replacement, according to the German Heart Surgery Report 2024. Hospitals with large transcatheter heart valve programs are most exposed, because they can run existing consoles longer. Suppliers must win on replacement and upgrades rather than added capacity.
Off-pump and falling CABG volumes trim demand in Japan
Coronary surgery volumes are falling in Japan, and most remaining cases avoid the pump entirely. Isolated CABG fell to 10,097 cases in 2023, only 65.9% of the 2013 level, and 58.7% of those cases were off-pump, according to the Japanese Association for Thoracic Surgery. Transcatheter aortic valve replacement reached 15,019 cases in the same year. Console suppliers that rely on Japanese coronary programs face slower replacement demand than in valve or congenital surgery.
Quality failures and disposables shortages disrupt supply
Quality and supply failures can strand hospitals on a single platform. The FDA said in May 2024 that Getinge's cardiopulmonary facilities had not met consent decree requirements and that its Quadrox oxygenators left the U.S. market in May 2023. LivaNova reported in November 2025 that demand for its oxygenators outpaced supply, with back orders until a new line in the second half of 2026. Perfusion departments that depend on one supplier of oxygenators are most exposed.
North America leads while China lifts Asia Pacific
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 83.7 | 38.0% | 3.1% |
| Europe | 61.6 | 28.0% | 2.8% |
| Asia Pacific | 55.0 | 25.0% | 5.2% |
| Latin America | 11.0 | 5.0% | 4.2% |
| Middle East & Africa | 8.8 | 4.0% | 4.3% |
North America leads on program count and console prices
North America held 38.0% of 2025 value and grows at 3.1% a year, with the United States accounting for most of it. The country runs the largest base of cardiac surgery programs, reported to an STS database that holds more than 8.3 million procedures, and federal awards price premium consoles above USD 300,000. Getinge's absence since 2015 leaves LivaNova, Terumo and Spectrum Medical as the main U.S. console brands. Eurosets launched U.S. sales of its Trilly and Horizon oxygenators in March 2026 after FDA clearance, a sign that disposables competition is widening even though console choice stays narrow.
Europe grows slowest as Getinge users convert
Europe held 28.0% of 2025 value and grows at 2.8% a year, the slowest rate, because procedure volumes are flat and transcatheter therapy takes valve cases. Germany's 77 heart surgery departments performed 64,602 operations with extracorporeal circulation in 2024, up from 63,683 in 2023 but still below prepandemic levels. Europe, Getinge's home region, likely holds much of the HL 40 base, so conversion tenders support spending through 2027. NHS lowest-price frameworks keep steady pressure on supplier margins in the region.
Asia Pacific grows fastest on Chinese program expansion
Asia Pacific held 25.0% of 2025 value and grows fastest at 5.2% a year, led by the Chinese program growth described in the drivers. Japan adds a stable replacement market, with 63,427 cardiovascular operations in 2023, up 3.0% from 2022, according to its national surgical registry. In India, Odisha's state medical corporation is buying consoles for medical colleges through a rate-contract tender. Chinese domestic makers have entered ECMO since an emergency approval for Shenzhen Hanuo in January 2023, which could pressure imported console prices later in the forecast.
Latin America relies on Brazilian production and imports
Latin America held 5.0% of 2025 value and grows at 4.2% a year. Brazil has a domestic console maker in Braile Biomédica, whose roller-pump BEC console carries ANVISA registration and serves price-sensitive public hospitals. Mexican and Colombian programs rely more on imported LivaNova and Terumo systems. Published data on regional bypass volumes and console tenders are scarce, so this estimate carries wider uncertainty than those for the larger regions.
Middle East & Africa grows on Gulf hospital projects
Middle East & Africa held 4.0% of 2025 value and grows at 4.3% a year, with demand likely concentrated in Gulf hospital groups and South African private programs. LivaNova lists the United Arab Emirates among the markets where its Essenz system is available. Outside the Gulf and South Africa, few hospitals run cardiac surgery, and published procedure data are thin, so this estimate rests mainly on hospital capacity rather than on registry counts.
Exit, clearances and a China launch reset supply
| Development | Status and market relevance |
|---|---|
| In January 2025, Getinge announced a plan to phase out its surgical perfusion product category, including the HL 40 heart-lung machine and HCU 40 heater-cooler. | Announced plan; production was set to end by late 2025, opening its installed base to rivals. |
| In June 2025, the FDA cleared the Quantum CP22V-NG centrifugal blood pump with integrated sensors for Spectrum Medical consoles, followed by the CP20V-NG in August 2025. | Regulatory clearance; it widens the U.S. pump options of a challenger brand. |
| In August 2025, LivaNova began the commercial launch of its Essenz perfusion system in China after NMPA approval. | Operational launch; most orders are expected from 2026 because of long sales cycles. |
| In November 2025, LivaNova set out its long-range plan at an investor day, with a next-generation oxygenator estimated to launch in 2028. | Announced plan; the oxygenator is still in development. |
| In May 2026, Spectrum Medical received CE approval for its Quantum Transport System for extracorporeal support outside the operating room. | Regulatory approval; it extends the Quantum platform into portable use in Europe. |
Integrated monitoring and safety automation shape value
- Integrated patient monitoring tracks oxygen delivery, venous saturation and hemoglobin on the console screen, which supports goal-directed perfusion without separate devices.
- Automated safety control links level sensors and bubble detectors to the pumps so that the console alarms and slows or stops flow when air or low reservoir levels appear.
- Sensor-integrated centrifugal pumps build pressure and flow measurement into the pump head, which cuts separate sensors and tubing connections on the arterial line.
- Minimally invasive extracorporeal circuits close the circuit and shorten tubing to lower priming volume and blood contact, which reduces hemodilution during bypass.
- Mast-mounted modular design lets perfusionists position pumps close to the patient and add modules for cardioplegia, suction or venting as cases require.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Three console brands compete for the Getinge base
Competition turns on installed base, service coverage and the ability to bundle disposables with the console. LivaNova, which describes itself as the cardiopulmonary leader, runs a large base through its S5 and Essenz platforms and supports it with service engineers in more than 100 countries. Terumo sells its Advanced Perfusion System 1, whose latest FDA 510(k) clearance came on April 18, 2023, alongside its own oxygenators. Spectrum Medical competes as a challenger with its Quantum platform, which combines heart-lung machines with data software and centrifugal pumps. Medtronic supplies the Bio-Console 560 centrifugal pump console and oxygenators, while Braile Biomédica serves Brazilian and price-led buyers with roller-pump consoles. Hospitals rarely switch brands outside a replacement tender, so Getinge's exit is the main chance for share shifts this decade.
High switching costs keep console supply concentrated
Console supply is concentrated among LivaNova, Terumo and Spectrum Medical now that Getinge is leaving, with Medtronic supplying centrifugal pump consoles and regional makers such as Braile serving price-led buyers. LivaNova reported in November 2025 that its oxygenator share had risen from the low 30s to the very high 30s percent, which shows how a console base pulls disposables demand. Entry barriers are FDA and MDR clearance, a field service network, perfusionist training and the cost of switching platforms. Margins sit in disposables and multi-year service rather than in the console itself.
Leading console suppliers and their roles
| Company | Type | Role in the market |
|---|---|---|
| LivaNova PLC | Market leader | S5 and Essenz heart-lung machines, patient monitors and heater-coolers |
| Terumo Corporation | Integrated supplier | Advanced Perfusion System 1 consoles alongside its oxygenators |
| Spectrum Medical | Challenger | Quantum heart-lung machines, centrifugal pumps, transport and data software |
| Medtronic plc | Pump specialist | Bio-Console 560 centrifugal pump console and oxygenators |
| Braile Biomédica | Regional manufacturer | BEC roller-pump heart-lung machine for Brazilian and Latin American hospitals |
Share shifts matter more than procedure growth
Credence Research's view is that share shifts will matter more than procedure growth in the cardiopulmonary bypass system market through 2035. Bypass volumes in Germany, Japan and the United States are flat or falling, so revenue growth depends on replacing aging consoles and winning the former Getinge base. LivaNova enters this cycle with a large installed base and a newer platform, while Spectrum Medical has the clearest opening as a challenger in data-led tenders. Hospital buyers have a short window to negotiate long service terms and upgrade rights before the remaining suppliers consolidate their positions.
Procedure counts and tender prices anchor the model
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which carries this report's earlier 2024 estimate forward with its stated growth rate and checks the result against procedure registries, installed-base assumptions and public tender prices. Inputs include national surgical registries, regulator databases and safety letters, company releases and investor material, peer-reviewed guidelines and trials, and public procurement notices. Segment and regional splits are Credence Research estimates from these inputs. No interviews or surveys were used to build the estimates.
Replacement cycles and Asian programs set the pace
Through 2035, spending should come mainly from console replacement in North America and Europe, the conversion of former Getinge sites and new cardiac programs in China and India. Integrated monitoring and automated safety controls will become standard features in tenders, which supports prices even as procedure counts stay flat in mature markets. Growth in pediatric perfusion and portable support adds smaller but faster demand pools. The main uncertainty is staffing, because hospitals cannot open programs without perfusionists, a range the scenarios below quantify.
Conversion speed and Asian programs decide the range
The range of outcomes depends mainly on how quickly Getinge users and older S5 sites convert, and on whether Chinese and Indian programs keep opening at the recent pace. Procedure volumes in mature markets add little to the outcome either way. Staffing shortages and transcatheter growth would hold the market near the downside, while faster Chinese tenders and early adoption of integrated monitoring would lift it toward the upside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 2.5% | USD 285.1 million | Chinese tenders slip and perfusionist shortages delay new cardiac programs past 2030 |
| Base | 3.70% | USD 316.6 million | Getinge sites convert by 2028 and Chinese program growth continues at the recent pace |
| Upside | 4.7% | USD 345.2 million | Integrated monitoring becomes a guideline standard and Asian programs open faster than expected |
Frequently Asked Questions
How big is the cardiopulmonary bypass system market?
How many cardiopulmonary bypass procedures are performed in the United States each year?
What does the cardiopulmonary bypass equipment market include?
How much does a heart-lung machine cost?
Why is Getinge leaving the surgical perfusion market?
What is a mini cardiopulmonary bypass system?
Which region leads the market?
Who are the leading cardiopulmonary bypass system suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Conventional
- 1.2.2 Mini
- 1.3 By Modality
- 1.3.1 Standalone
- 1.3.2 Portable
- 1.4 By End User
- 1.4.1 Hospitals
- 1.4.2 Academic Medical Centers
- 1.4.3 Specialty Cardiac Centers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 220.2 million → 2035: USD 316.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cardiopulmonary Bypass System Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cardiopulmonary Bypass System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cardiopulmonary Bypass System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cardiopulmonary Bypass System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cardiopulmonary Bypass System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cardiopulmonary Bypass System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cardiopulmonary Bypass System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cardiopulmonary Bypass System Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 220.2 million → 2035: USD 316.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cardiopulmonary Bypass System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Conventional
- 12.3.7.2 Mini
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Modality - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Standalone
- 12.4.7.2 Portable
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Academic Medical Centers
- 12.5.7.3 Specialty Cardiac Centers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cardiopulmonary Bypass System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cardiopulmonary Bypass System Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cardiopulmonary Bypass System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cardiopulmonary Bypass System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 LivaNova PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Terumo Corporation
- 18.4 Spectrum Medical
- 18.5 Medtronic plc
- 18.6 Braile Biomédica
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

