
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Pollution Absorbing Bricks Market Size 2024 | USD 469123.7 million |
| Pollution Absorbing Bricks Market, CAGR | 7.1% |
| Pollution Absorbing Bricks Market Size 2032 | USD 812088.09 million |
Market Overview:
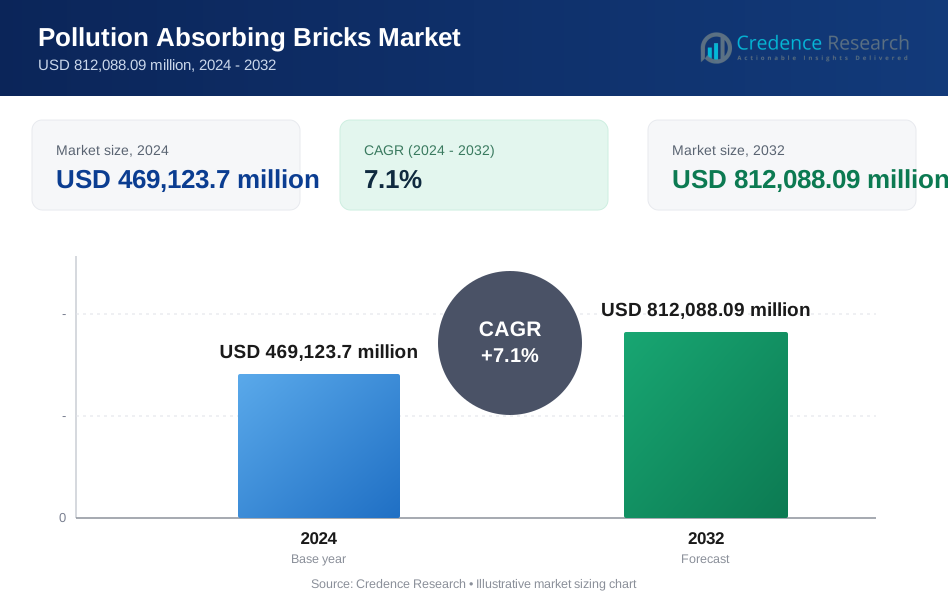
The Pollution Absorbing Bricks Market is projected to grow from USD 469123.7 million in 2024 to an estimated USD 812088.09 million by 2032, with a compound annual growth rate (CAGR) of 7.1% from 2024 to 2032.
One of the primary drivers for the pollution absorbing bricks market is the growing awareness of air pollution and its adverse effects on public health and the environment. Urban areas, in particular, face significant pollution challenges due to high vehicle emissions and industrial activities. Pollution absorbing bricks are designed to capture and neutralize harmful pollutants such as nitrogen oxides, particulate matter, and carbon dioxide, thus improving air quality. Furthermore, the construction industry is increasingly adopting sustainable building practices in response to government regulations and consumer demand for green buildings. Technological advancements in building materials, along with rising investments in smart city projects, are further propelling market growth. Additionally, the emphasis on corporate social responsibility (CSR) and sustainability is pushing manufacturers to develop eco-friendly solutions, creating a positive outlook for this market.
Regionally, North America and Europe are leading the pollution absorbing bricks market due to stringent environmental regulations and a strong focus on sustainable construction practices. In North America, the U.S. dominates the market, driven by government initiatives promoting green infrastructure. In Europe, countries such as Germany, France, and the U.K. are adopting pollution-absorbing bricks as part of their broader efforts to reduce urban pollution. Meanwhile, the Asia-Pacific region is expected to experience the fastest growth over the forecast period due to rapid urbanization, particularly in China and India. These countries are increasingly implementing pollution control measures to combat severe air quality issues, providing opportunities for market expansion.
Market Drivers:
Increasing Environmental Awareness and Air Pollution Concerns:
One of the major drivers of the pollution absorbing bricks market is the growing awareness about environmental degradation and the adverse effects of air pollution on human health. With rising levels of pollution in urban areas due to vehicular emissions, industrial activities, and construction dust, there is a heightened focus on reducing air pollutants. For instance, according to the World Health Organization, 99% of the global population breathes air that exceeds WHO guideline limits for pollutants, with low- and middle-income countries suffering from the highest exposures. As a result, there is a strong demand for sustainable solutions like pollution absorbing bricks, which can capture harmful pollutants and improve air quality in densely populated regions. For example, Heidelberg Materials reports that their photocatalytic concrete products can reduce nitrogen oxides (NOx) by up to 40% in urban areas.
Government Regulations and Policies Favoring Sustainable Construction:
Government policies and regulations aimed at reducing carbon emissions and promoting eco-friendly building materials are key drivers of the pollution absorbing bricks market. Various countries, especially in North America and Europe, have implemented stringent building codes that encourage the use of sustainable and green construction materials. These regulations often mandate the inclusion of air-purifying technologies or materials in urban infrastructure projects. Pollution absorbing bricks, which neutralize airborne pollutants, align with these policy frameworks, making them an attractive option for public and private construction projects. For instance, the European Union's Green Deal aims to reduce net greenhouse gas emissions by at least 55% by 2030, compared to 1990 levels, driving the adoption of sustainable construction materials.
Rising Demand for Sustainable Building Materials:
The construction industry is increasingly focused on sustainable development, driven by both regulatory requirements and consumer preferences for environmentally friendly products. Pollution absorbing bricks are a prime example of an innovative building material that addresses the growing demand for sustainable solutions. These bricks not only contribute to the structural integrity of buildings but also help in reducing pollution levels in urban areas. As more companies adopt Corporate Social Responsibility (CSR) initiatives, there is a growing emphasis on green construction practices, further driving the demand for pollution absorbing bricks. Additionally, as industries and governments prioritize sustainability in large infrastructure projects, the market for pollution absorbing bricks is expected to expand.
Technological Advancements in Air-Purifying Building Materials:
Advancements in material science and air-purifying technologies are significantly contributing to the growth of the pollution absorbing bricks market. Innovations in nanotechnology and photocatalytic coatings have enabled manufacturers to create bricks that are more efficient at absorbing pollutants such as nitrogen oxides and particulate matter. These technological developments are not only improving the performance of pollution absorbing bricks but also making them more cost-effective and scalable for mass production. As research continues, it is anticipated that these bricks will become more widely adopted in various construction applications, from residential buildings to large-scale infrastructure projects, further boosting the market's growth trajectory.
Market Trends:
Growing Adoption of Green Building Practices:
One of the significant trends in the pollution absorbing bricks market is the increasing adoption of green building practices worldwide. As environmental concerns become more pronounced, construction companies and developers are prioritizing sustainability in their projects. For instance, according to the World Green Building Council, green building certifications have increased by 19% globally since 2021. Pollution absorbing bricks offer a dual benefit: they contribute to structural integrity while also mitigating the environmental impact by reducing air pollution. Governments and industry leaders are promoting the use of such eco-friendly materials in urban infrastructure, and this shift is fostering the growth of the market. Additionally, rising consumer awareness about sustainable living is driving demand for buildings that incorporate green technologies, positioning pollution absorbing bricks as a vital element in modern construction.
Technological Advancements in Smart Building Materials:
Technological innovations are reshaping the pollution absorbing bricks market. Advances in material science, particularly in nanotechnology and photocatalytic materials, have led to the development of more efficient bricks that can capture and neutralize pollutants like nitrogen oxides and volatile organic compounds (VOCs). For instance, Heidelberg Materials reports that their photocatalytic concrete products can reduce nitrogen oxides (NOx) by up to 40% in urban areas. These breakthroughs are enhancing the effectiveness of pollution absorbing bricks and making them more accessible for large-scale applications. Furthermore, the integration of smart technology in building materials, such as sensors that monitor air quality, is becoming more common. These innovations are not only improving the functionality of pollution absorbing bricks but also aligning them with broader trends in smart city development and environmentally responsive construction.
Increasing Focus on Urban Air Quality Improvement:
As cities continue to grow and urbanization accelerates, air quality has become a critical issue for both policymakers and citizens. The trend of improving urban air quality is driving the demand for pollution absorbing bricks, particularly in areas with high levels of vehicular and industrial emissions. Cities in regions like North America, Europe, and parts of Asia-Pacific are facing significant pressure to implement solutions that address pollution. Governments and municipal bodies are increasingly incorporating pollution absorbing bricks into their urban planning strategies to combat air pollution. This trend is likely to accelerate as cities seek to meet stringent air quality standards and enhance the quality of life for residents.
Sustainability as a Key Market Differentiator:
Sustainability is emerging as a key differentiator in the pollution absorbing bricks market. Manufacturers are not only focusing on the pollution-absorbing capabilities of these bricks but also on the entire lifecycle of the product, from production to disposal. The use of recycled materials in the manufacturing process, energy-efficient production methods, and the potential for future recyclability are becoming important considerations for buyers. Companies that prioritize sustainability throughout their value chain are gaining a competitive advantage as both government regulations and consumer expectations favor environmentally responsible products. This trend is encouraging further innovation in the development of greener, more sustainable pollution absorbing bricks, ensuring the market remains dynamic and competitive.
Market Restraints and Challenges:
High Production Costs:
One of the major restraints in the pollution absorbing bricks market is the high production cost associated with these materials. The integration of advanced technologies such as photocatalytic coatings and nanomaterials into the bricks significantly increases their manufacturing expenses compared to traditional construction materials. These technologies require specialized raw materials and complex production processes, which can be costly. As a result, the high price of pollution absorbing bricks may deter some developers, particularly in cost-sensitive markets, from adopting them on a large scale. This poses a challenge to the widespread commercialization of these eco-friendly bricks.
Limited Awareness and Adoption in Developing Regions:
While pollution absorbing bricks are gaining traction in developed regions such as North America and Europe, awareness and adoption remain limited in developing countries. In many emerging markets, the primary focus is on affordable housing and rapid urbanization, often sidelining sustainable building materials due to cost concerns. The lack of stringent environmental regulations in certain regions further limits the demand for such innovative materials. Moreover, many construction companies in developing economies are not fully aware of the long-term benefits of pollution absorbing bricks, hindering their potential market growth in these areas.
Challenges in Performance and Durability:
Another challenge for the pollution absorbing bricks market is ensuring the long-term performance and durability of the bricks in various environmental conditions. While these bricks are effective in absorbing pollutants, their performance may be affected by factors such as weathering, moisture, and exposure to harsh environmental conditions over time. Ensuring consistent performance across different climates and applications is crucial for the market's long-term success. Addressing these durability challenges requires continuous research and development efforts, which may further increase costs and delay mass-market adoption.
Market Segmentation Analysis:
By Material Type, the market is categorized into clay, concrete, and recycled materials. Clay-based bricks dominate due to their traditional use and widespread availability. However, concrete and recycled materials are gaining traction due to their durability and eco-friendly properties. Recycled materials, in particular, align with sustainability goals and are expected to see significant growth as environmental concerns increase.
By Application, the market is divided into residential, commercial, and infrastructure. The infrastructure segment holds the largest share, driven by urban development projects and government initiatives promoting green buildings. The commercial sector is also seeing rapid adoption of pollution absorbing bricks, particularly in office spaces and retail centers, where air quality improvement is becoming a priority. The residential segment, while smaller, is growing as consumers become more environmentally conscious.
By End User, the market is segmented into construction companies, government bodies, and individual buyers. Construction companies lead the market due to the rising demand for sustainable materials in large-scale projects. Government bodies play a crucial role by implementing regulations and green building standards, further driving adoption. Individual buyers are a smaller segment but are expected to grow as awareness of eco-friendly construction materials increases.
Segmentation:
By Material Type,
- Clay,
- Concrete,
- Recycled materials.
By Application,
- Residential,
- Commercial,
- Infrastructure.
By End User,
- Construction companies,
- Government bodies,
- Individual buyers.
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the pollution absorbing bricks market, accounting for approximately 30% of the global market in 2023. The region's market growth is driven by strict environmental regulations and increasing demand for sustainable building materials. The United States leads the market in North America, with growing adoption of eco-friendly construction practices and government initiatives aimed at reducing carbon emissions. Cities like New York and Los Angeles are incorporating pollution absorbing bricks into their infrastructure projects as part of broader efforts to improve air quality. Canada is also contributing to regional market growth, driven by its strong focus on green construction and environmental sustainability.
Europe
Europe follows closely, representing around 28% of the global pollution absorbing bricks market. The region is known for its proactive stance on environmental issues and sustainability, with stringent building regulations that promote the use of green construction materials. Countries such as Germany, France, and the U.K. are leading the adoption of pollution absorbing bricks as part of their efforts to reduce urban pollution and meet ambitious climate goals. In particular, Germany has been at the forefront of incorporating eco-friendly technologies into construction, supported by government incentives and regulations. The European Union’s commitment to reducing carbon emissions and improving urban air quality is a key factor driving the market in this region.
Asia-Pacific
Asia-Pacific is expected to be the fastest-growing region, with a market share of approximately 25% in 2023, and projected to grow significantly over the next decade. The region’s rapid urbanization, particularly in countries like China and India, has led to worsening air pollution, making pollution absorbing bricks an increasingly viable solution. Governments in these countries are implementing stricter air quality standards and investing in sustainable infrastructure to combat pollution. China, in particular, is witnessing increased adoption of pollution absorbing bricks due to severe urban pollution and the government's push for green building practices as part of its broader environmental policy.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively account for about 17% of the global pollution absorbing bricks market. In Latin America, countries like Brazil and Mexico are gradually adopting green construction materials as urbanization accelerates and awareness of environmental issues rises. However, the market in this region is still developing due to limited regulations and high costs associated with sustainable materials. In the Middle East & Africa, the adoption of pollution absorbing bricks is growing slowly, with countries like the UAE focusing on sustainable urban development projects. However, overall growth in this region remains constrained by economic challenges and limited infrastructure investments.
Key Player Analysis:
- Boral Limited (Australia)
- CalStar Products Inc. (USA)
- Carbon Craft Design(USA)
- CarbonCure Technologies Inc. (Canada)
- Ceramica Fondovalle SpA(Italy)
- ClearVue Technologies Ltd(Australia)
- Compac Sorting Equipment (Netherlands)
- Echoview Fiber Mill (USA)
- Ecological Building Systems (Ireland)
- Emmedue S.p.A. (Italy)
- Epuron Pty Ltd (Australia)
- EXEED Industries (UAE)
- GCI Envirolutions Inc. (USA)
- Green Distillation Technologies Corporation (Australia)
- GreenWay Environmental Technologies (USA)
- Lucem GmbH (Germany)
- Novacem Limited (UK)
- Rieder Smart Elements GmbH (Austria)
- Sun Economy (USA)
- Titan Block (USA)
- Urban Blox (USA)
- Wienerberger AG (Austria)
Competitive Analysis:
The pollution absorbing bricks market is characterized by increasing competition as both established companies and emerging players strive to capitalize on the growing demand for sustainable building materials. Key players include industry leaders such as LafargeHolcim, Boral Limited, and HeidelbergCement, who leverage their global presence and advanced R&D capabilities to develop innovative products. These companies focus on integrating cutting-edge technologies, such as photocatalytic coatings and nanomaterials, to enhance the pollution absorption efficiency of their bricks. Smaller companies and startups are also entering the market, offering niche solutions and eco-friendly alternatives that cater to specific regional demands. Competitive strategies include partnerships with construction firms, collaborations with governments for green infrastructure projects, and expanding product portfolios to differentiate themselves. The market’s competitive landscape is expected to intensify as environmental regulations tighten and the demand for sustainable construction materials continues to grow globally.
Market Concentration & Characteristics:
The pollution absorbing bricks market is moderately concentrated, with a few large multinational companies dominating the landscape alongside smaller, specialized players. Major firms like LafargeHolcim and HeidelbergCement hold significant market shares due to their strong global distribution networks, advanced technological capabilities, and established brand reputation. These companies are heavily involved in research and development, which allows them to maintain a competitive edge through innovative products. At the same time, the market is characterized by the presence of regional players and startups that offer tailored solutions for specific markets, especially in developing regions. These smaller firms often focus on eco-friendly materials and cost-effective production techniques to compete with larger players. The market is also shaped by high barriers to entry, such as the need for technological expertise and adherence to stringent environmental regulations, which limits the entry of new competitors. As demand for sustainable construction grows, market concentration may gradually shift toward increased competition.
Report Coverage:
The research report offers an in-depth analysis based on By Material Type, By Application, By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The pollution absorbing bricks market is expected to grow steadily due to rising environmental awareness and air quality concerns.
- Technological advancements in photocatalytic materials will drive innovation and improve product efficiency.
- Increasing government regulations on urban pollution control will boost demand for eco-friendly construction materials.
- Growing adoption of green building practices in developed regions will further accelerate market expansion.
- Asia-Pacific, led by China and India, will witness the fastest growth due to rapid urbanization and pollution mitigation efforts.
- Rising corporate focus on sustainability and Corporate Social Responsibility (CSR) initiatives will support market growth.
- High production costs may continue to pose challenges but will likely decrease as manufacturing processes advance.
- Strategic partnerships between construction firms and brick manufacturers will enhance product adoption in large-scale infrastructure projects.
- Continued urbanization and smart city development globally will create new opportunities for market penetration.
- Increased investment in research and development will lead to product diversification and market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the pollution absorbing bricks market?
What is driving the growth of the pollution absorbing bricks market?
Which region is expected to grow the fastest?
What are the key challenges in the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pollution Absorbing Bricks Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pollution Absorbing Bricks Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 469,123.7 million → 2032: USD 812,088.09 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pollution Absorbing Bricks Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pollution Absorbing Bricks Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pollution Absorbing Bricks Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pollution Absorbing Bricks Market Drivers
- 3.3 Pollution Absorbing Bricks Market Restraints & Challenges
- 3.4 Pollution Absorbing Bricks Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pollution Absorbing Bricks Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pollution Absorbing Bricks Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pollution Absorbing Bricks category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pollution Absorbing Bricks Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pollution Absorbing Bricks Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pollution Absorbing Bricks market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pollution Absorbing Bricks Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pollution Absorbing Bricks Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pollution Absorbing Bricks Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pollution Absorbing Bricks (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pollution Absorbing Bricks Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pollution Absorbing Bricks Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pollution Absorbing Bricks Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pollution Absorbing Bricks Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pollution Absorbing Bricks Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pollution Absorbing Bricks Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pollution Absorbing Bricks Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pollution Absorbing Bricks Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pollution Absorbing Bricks Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
