
Disposable glucose sensors anchor chip demand
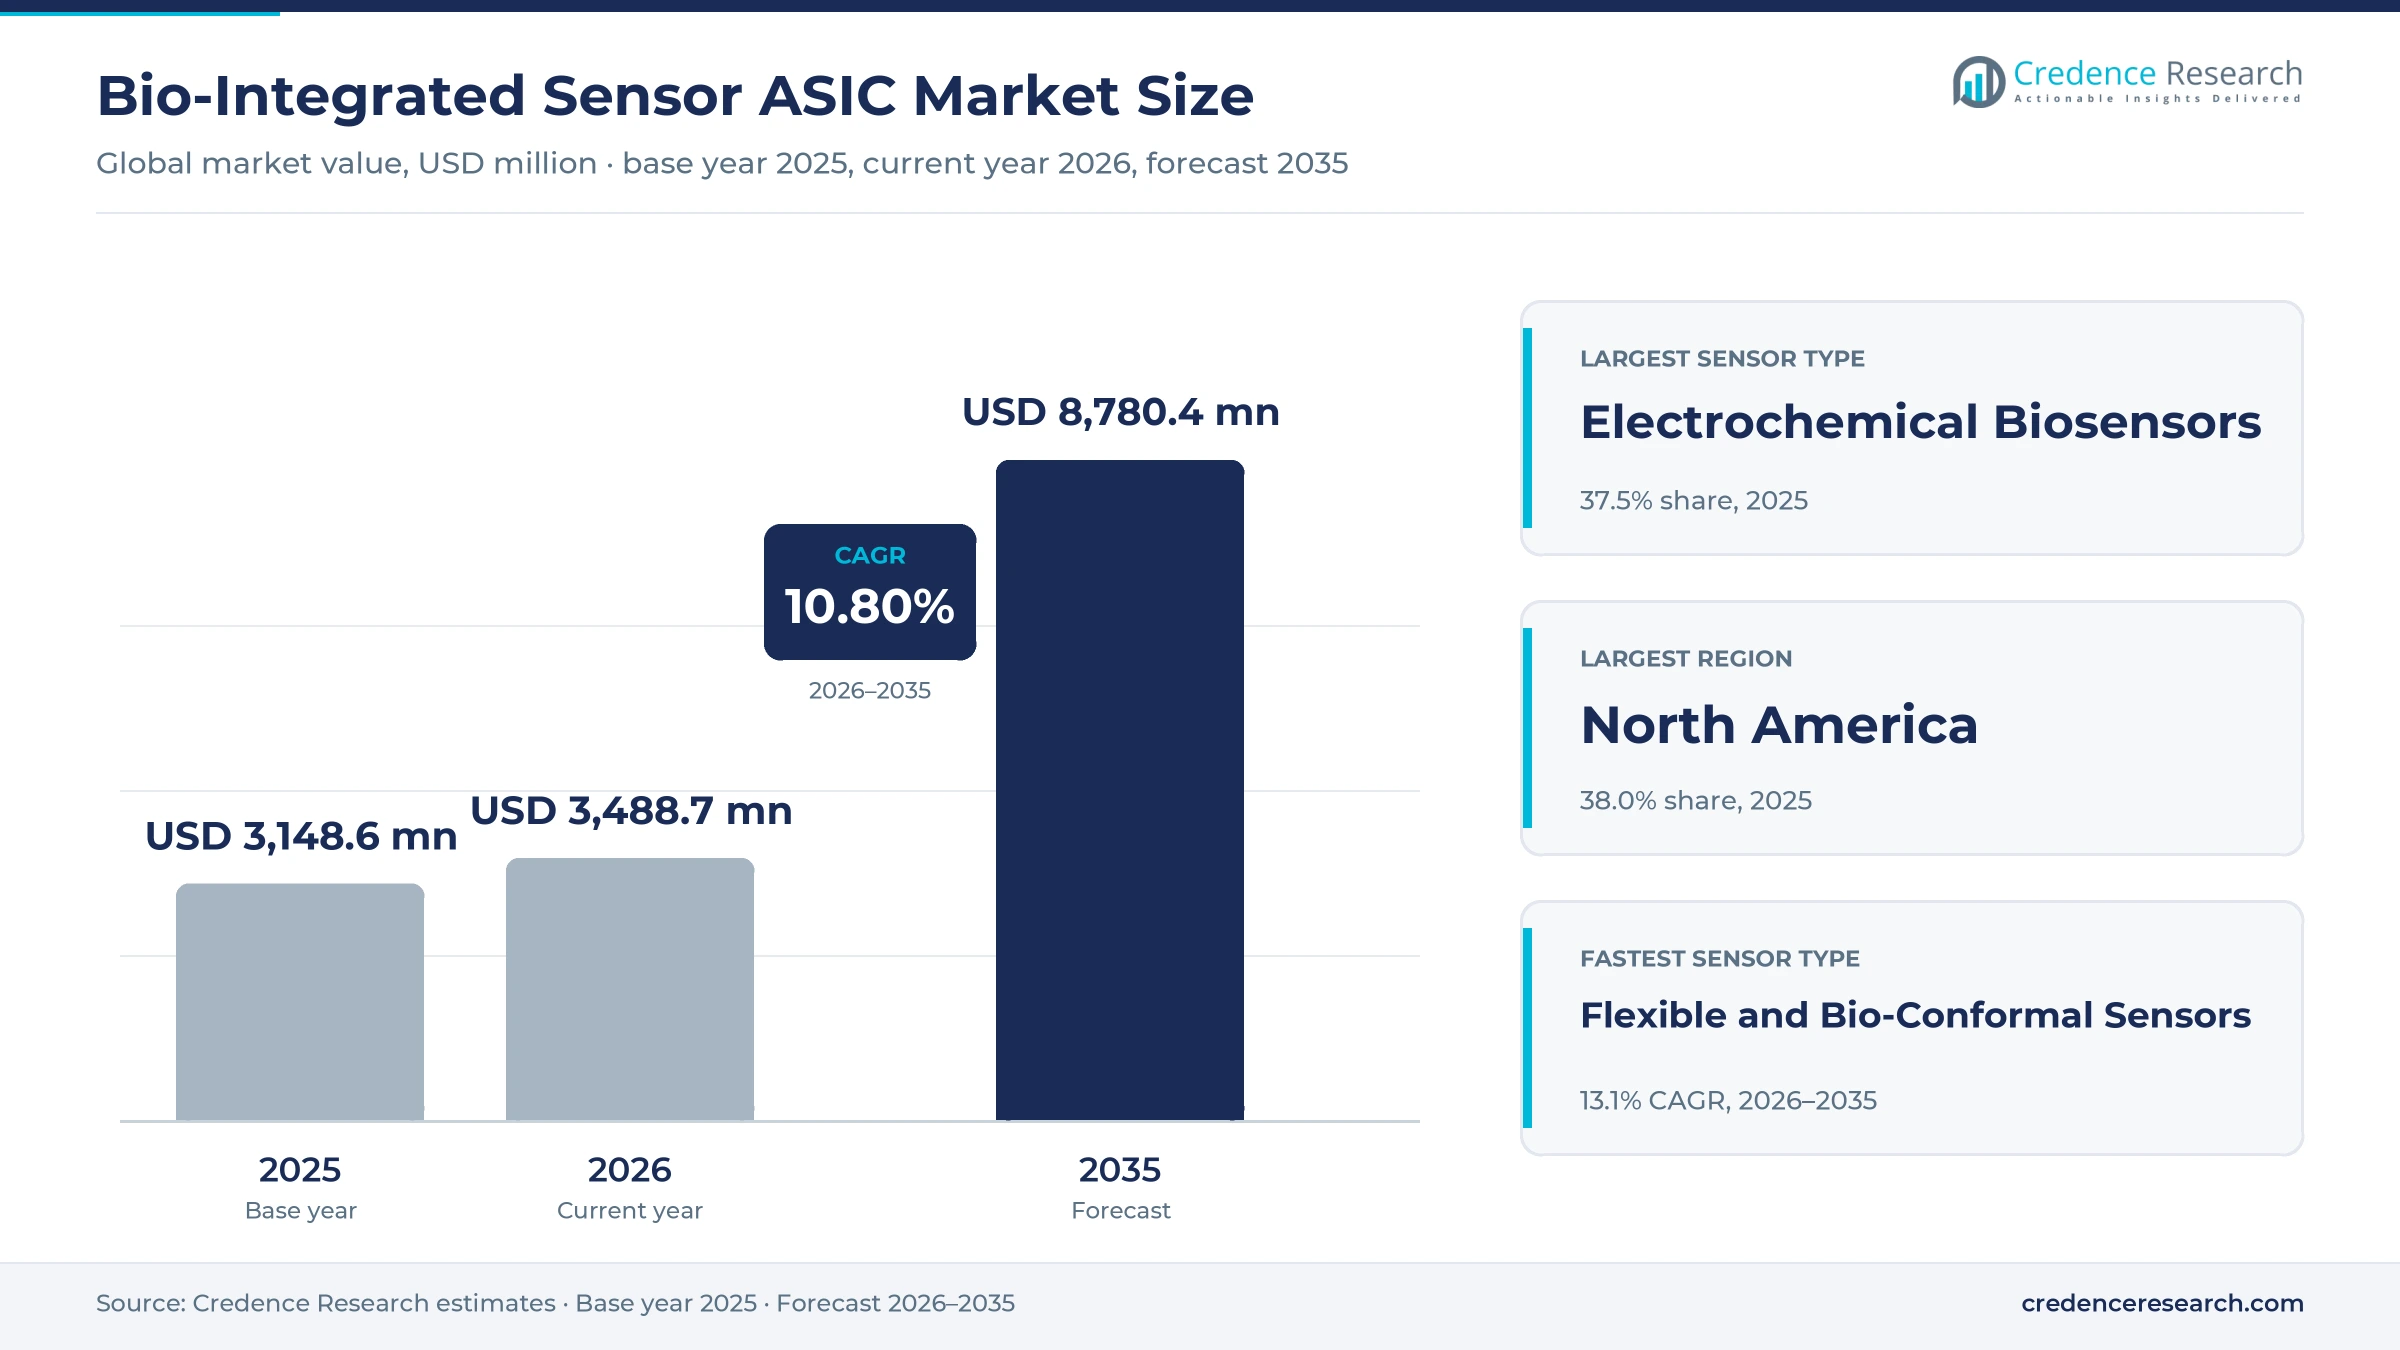
The global bio-integrated sensor ASIC market was valued at USD 3.15 billion in 2025 and is projected to increase from USD 3.49 billion in 2026 to USD 8.78 billion by 2035, registering a CAGR of 10.80% during 2026–2035. Demand comes mainly from continuous glucose monitors, whose disposable sensors each carry their own measurement and radio electronics, and from smartwatches, rings and medical patches that read optical, ECG and bioimpedance signals. North America held the largest regional share, 38.0% in 2025, because most CGM approvals and device design teams sit in the United States. Asia Pacific is the fastest-growing region at 12.0% a year, as the Western Pacific and South-East Asia hold more than half of all adults with diabetes. Over-the-counter glucose sensors cleared in the United States since 2024 widen use beyond insulin users. Long custom-chip design and medical qualification cycles remain the main restraint for new entrants.
Chips inside the sensor, not the finished device, define scope
The market counts application-specific integrated circuits and dedicated analog front ends that convert biological signals into data inside a sensing device. This includes potentiostat and readout chips for electrochemical glucose and lactate sensors, optical front ends for heart rate and blood oxygen, ECG and bioimpedance channels, and the power and radio blocks integrated with them in wearables, implants and point-of-care instruments.
Finished devices, test strips, general-purpose microcontrollers and stand-alone wireless chips are excluded unless they are integrated on the same die as the sensor interface. Value flows from fabless design houses and analog chip makers through foundries and test sites to device makers, which qualify each chip under medical device rules before volume production starts.
Bio-Integrated Sensor ASIC Market Insights
- The bio-integrated sensor ASIC market rises from USD 3.15 billion in 2025 to USD 8.78 billion by 2035, a 10.80% CAGR during 2026–2035, as glucose sensors and wearable front ends scale.
- North America held 38.0% of 2025 value, because most CGM clearances, including OTC devices since March 2024, were granted by the FDA first.
- Electrochemical Biosensors led with 37.5% of 2025 value, because every disposable glucose sensor needs its own potentiostat and radio chip.
- Abbott reports more than seven million FreeStyle Libre customers, and each user replaces a disposable sensor about every two weeks.
- Catalog optical front ends list at about USD 3 to USD 8 per unit on TI.com, while custom programs carry six- and seven-figure design fees.
Electrochemical chips lead while flexible patches gain
Electrochemical chips lead while flexible patches grow fastest
Based on sensor type, the market is categorized into electrochemical biosensors, optical biosensors, piezoelectric biosensors, thermal biosensors, flexible and bio-conformal sensors, and implantable sensor systems. Electrochemical Biosensors led with 37.5% of 2025 value because glucose sensors are disposable, and Abbott alone reports more than seven million Libre customers who replace sensors about every two weeks. Flexible and Bio-Conformal Sensors grow fastest at 13.1% a year, as Biolinq Shine, granted FDA De Novo classification in September 2025, uses a semiconductor microsensor array up to 20 times shallower than conventional glucose sensors.
Clinical monitoring leads while consumer wearables gain
Based on application, the market is categorized into medical diagnostics and monitoring, wearable health devices and continuous monitoring, point-of-care testing, environmental monitoring and others. Medical Diagnostics and Monitoring led with 40.0% of 2025 value because prescription CGM, insulin pump sensors and hospital vital-sign monitors carry the highest chip content, and Medtronic received FDA approval for its Simplera Sync pump sensor in April 2025. Wearable Health Devices and Continuous Monitoring grow fastest at 11.9% a year, as Apple expects its hypertension notifications, cleared by the FDA in September 2025, to alert more than one million people in the first year.
Standard CMOS leads while low-power CMOS gains
Based on technology, the market is categorized into standard CMOS, low-power CMOS, silicon-on-insulator, MEMS and NEMS integration, flexible substrates and hybrid nanomaterial integration. Standard CMOS led with 45.0% of 2025 value because mature mixed-signal nodes carry most high-volume readout chips, and ICsense said in October 2022 that several hundred million units of one chemical sensor interface chip would ship over four years. Low-Power CMOS grows fastest at 12.1% a year, as longer wear periods stretch battery budgets, and the Analog Devices MAX86178 draws about 100 microamps for its optical channel.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Sensor Type | Electrochemical Biosensors | 37.5% | Flexible and Bio-Conformal Sensors | 13.1% |
| By Application | Medical Diagnostics and Monitoring | 40.0% | Wearable Health Devices and Continuous Monitoring | 11.9% |
| By Technology | Standard CMOS | 45.0% | Low-Power CMOS | 12.1% |
Catalog front ends sell for dollars, custom chips by program
Pricing in this market runs on two separate commercial models. Catalog analog front ends are sold per unit through distributors, and TI.com lists its AFE4950 optical heart-rate and blood-oxygen front end at about USD 7.86, according to its product page. Custom ASICs carry engineering fees for feasibility, design and tape-out, then per-wafer or per-unit supply prices that fall as volumes rise. Disposable glucose sensors push per-unit chip prices toward the low end, because the chip is thrown away every two weeks. High-volume device makers therefore move to custom silicon, while smaller makers keep paying catalog prices.
| Offer or chip type | Typical price or fee | Basis |
|---|---|---|
| Entry optical heart-rate front end (TI AFE4410) | About USD 3.06 per unit | TI.com list price, November 2026 |
| Wearable heart-rate and SpO2 front end (TI AFE4950) | About USD 7.86 per unit | TI.com list price, November 2026 |
| ECG and respiration front end (TI ADS1292R) | About USD 7.48 to USD 9.72 per unit | TI.com list price, November 2026 |
| Electrochemical potentiostat front end (TI LMP91000) | About USD 2.49 per unit | TI.com list price, November 2026 |
| Custom biosensing ASIC feasibility study | About USD 200,000 per study | EnSilica, March 2026 |
| Custom life-science chip design and prototype wafers | About USD 1.6 million initial contract | EnSilica, March 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Recurring sensor volumes and wider access lift chip demand
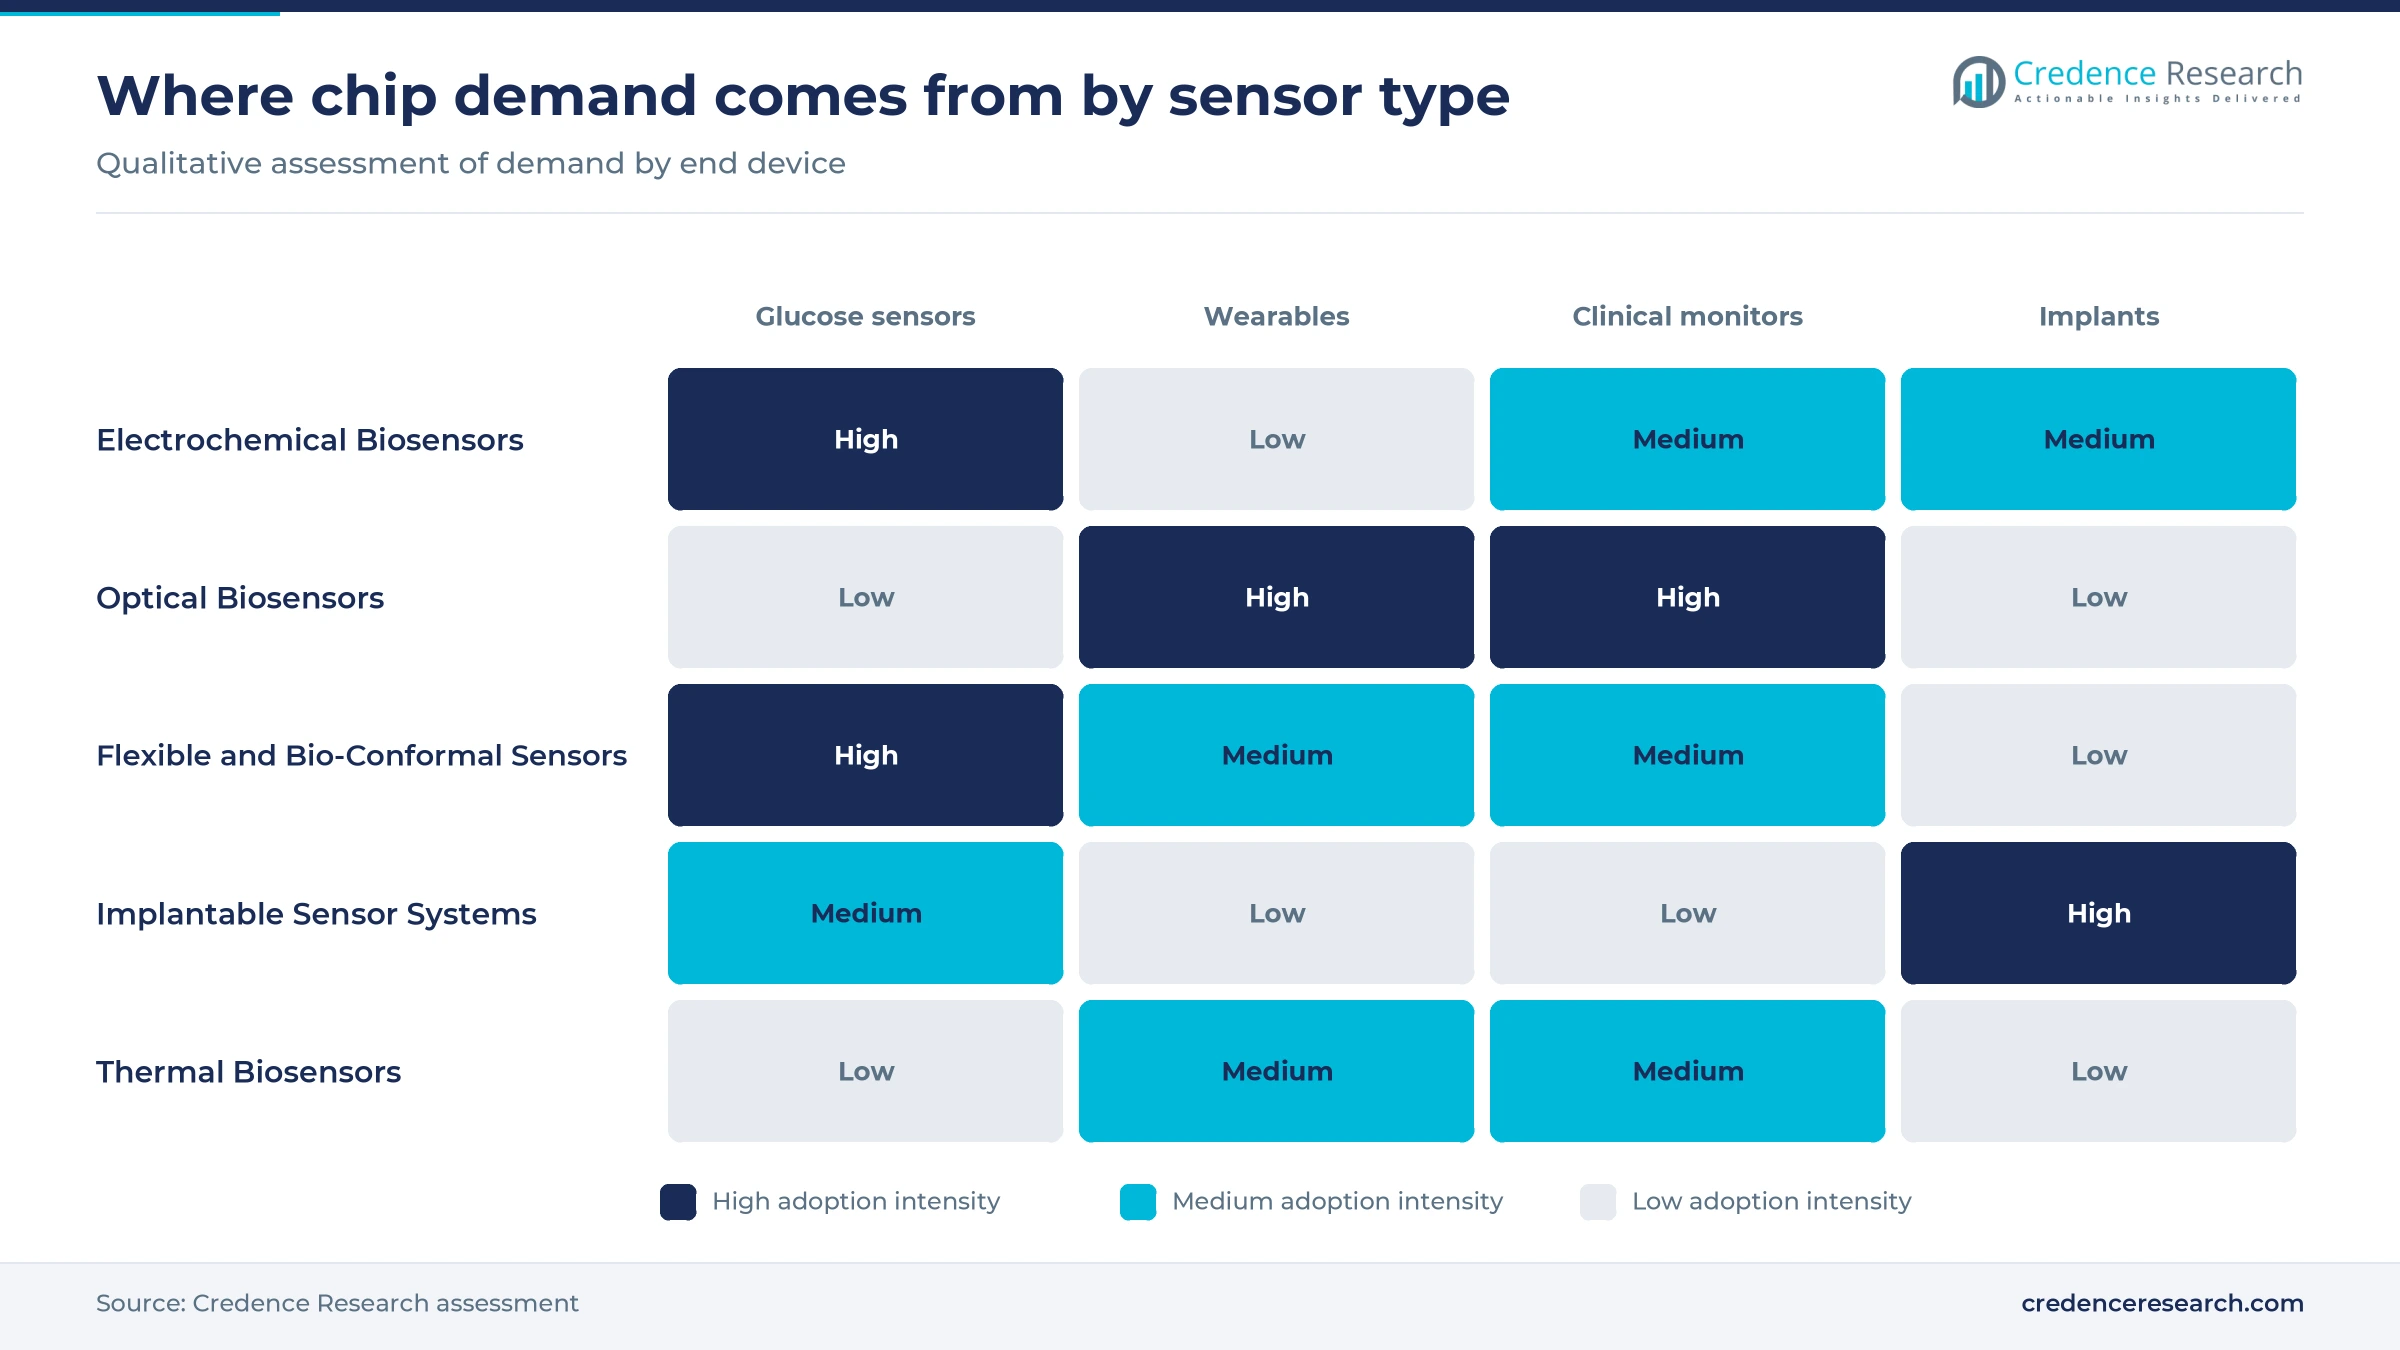
Disposable glucose sensors create recurring chip volume
Continuous glucose monitors turn chip demand into a recurring purchase, because the sensor electronics are thrown away with each patch rather than bought once. Abbott reports more than seven million FreeStyle Libre customers worldwide, and in November 2024 it opened a 323,000-square-foot sensor plant in Kilkenny, Ireland, that will employ more than 800 people. Dexcom said its G7 15 Day sensor, cleared by the FDA in April 2025, lasts 15.5 days with an overall MARD of 8.0%, according to Dexcom. Longer wear trims sensors per user each year, so chip volume grows with the user base rather than with wear time. Suppliers with CGM design wins hold multi-year volume that few other medical chips offer.
Over-the-counter and non-insulin use widen the user base
Regulators have opened glucose sensing to people who do not use insulin, which multiplies the pool of potential sensor wearers. The FDA cleared Dexcom Stelo as the first over-the-counter glucose biosensor in March 2024, and Dexcom said about 25 million people in the United States have type 2 diabetes, do not use insulin and could benefit. Biolinq raised USD 100 million in a Series C round in 2025 before its De Novo grant, MedTech Dive reported. Abbott's chief executive expects proposed CMS coverage for type 2 non-insulin users sometime in 2026, Drug Delivery Business reported in October 2025. Each new wearer adds disposable sensors, which favors chip suppliers with low unit costs.
Multi-signal wearables need integrated front ends
Watches, rings and patches now measure several signals at once, which pushes device makers toward single front-end chips that combine optical, ECG and impedance channels. The ams OSRAM AS7058, released in November 2023, combines PPG, ECG, bioimpedance and electrodermal channels in a 2.8 mm by 2.5 mm package with a 120 dB optical signal-to-noise ratio, the company said. The Analog Devices MAX86178 runs optical, ECG and bioimpedance channels at the same time, eeNews Europe reported. The FDA cleared Apple's hypertension notifications in September 2025, and Apple planned the feature for more than 150 countries and regions, 9to5Mac reported, which shows how smartwatch features now depend on medical-grade signal chains.
Automated insulin delivery ties sensors to pumps
Automated insulin delivery systems link glucose sensors directly to pumps, which tightens the accuracy, latency and radio requirements placed on the sensor chip. Medtronic received FDA approval for the disposable all-in-one Simplera Sync sensor for its MiniMed 780G system in April 2025, with a limited launch from fall 2025. Senseonics and Ascensia announced FDA clearance of the 365-day Eversense implant in September 2024, including integration with compatible pumps, HIT Consultant reported. Abbott has agreed integrations with five pump and algorithm makers, including Tandem Diabetes Care, Beta Bionics and Ypsomed, for its continuous glucose monitoring devices, Drug Delivery Business reported. Chips qualified for these closed loops stay in place for years, because any change means new interoperability testing.
Single-chip designs and longer wear reshape specifications
Device makers are shifting to single-die mixed-signal ASICs
Device makers are shifting from boards of separate front-end, processing and radio chips toward single mixed-signal ASICs to address size, noise and battery limits, creating openings for custom designs across patches and disposables. EnSilica's eSi-MediSense platform measures ECG, heart rate, respiration, blood oxygen, temperature and electrochemical signals on one chip with standby current below 1 microamp, New Electronics reported. EnSilica's chief executive argued in Electronic Design in October 2025 that a single mixed-signal die improves noise, power and size. ICsense's NFC sensor interface chip for a large U.S. client entered full-scale production in October 2022. Catalog front-end vendors lose sockets in wearable medical devices when high-volume makers move to custom silicon.
Longer wear and implants are rising as design targets
Device makers are extending wear time from days to weeks, and to a full year for implants, which shifts chip design toward lower leakage, smaller batteries and more stable calibration. Dexcom's 15-day G7 clearance noted above extends wear, while the Eversense implant needs one insertion and one calibration a year, HIT Consultant reported in September 2024. ICsense, part of TDK since 2017, lists implant power management and ultra-low-power NFC among its ISO 13485 medical ASIC work, its company page says. For implantable glucose monitors and long-wear patches, longer wear lowers sensor counts per user, so chip suppliers gain value per unit and lose some volume, which favors designers with deep low-power expertise over suppliers that compete only on price.
Closed-loop and multi-analyte chips open new sockets
Sensors that read more than glucose, or that also control therapy, need new readout channels and control logic, which opens sockets that existing CGM chips cannot fill. EnSilica won a fully funded USD 200,000 feasibility study for a wireless biosensing and therapeutic controller ASIC, due to start in May 2026, and expects a successful study to lead to a multi-million-dollar design and supply agreement, EnSilica said. Abbott plans to launch a combined glucose and ketone sensor in 2026, and Biolinq plans to measure ketones and lactate in future devices. Chip houses with multi-channel electrochemical front ends can win these programs before volumes start.
Life-science instruments offer high-value chip programs
Sequencing, cell analysis and lab-on-a-chip instruments use custom sensor chips with large dies and low volumes, which gives design houses high value per program. EnSilica won an initial contract of about USD 1.6 million in March 2026 for design, tape-out management and wafer supply of a next-generation chip for a U.K. life-science analysis company, with material revenue expected from fiscal 2027. About 252 million adults with diabetes are undiagnosed, according to the IDF in April 2025, so point-of-care testing chips that screen for glucose and related markers stay in demand in clinics and pharmacies. The opening rewards suppliers that can manage wafer supply and yield, not only design, because instrument makers buy few chips but need them for a decade.
Recalls, EU certification and long design cycles weigh
Sensor recalls raise qualification and liability costs
Abbott began removing certain FreeStyle Libre 3 and Libre 3 Plus sensors in November 2025 after they reported glucose lower than actual levels, and the FDA classed the recall as Class I in February 2026 with seven deaths and 860 serious injuries reported, the FDA said. Recalls lengthen device-maker audits of every component in the signal chain and raise liability risk for suppliers. Chip suppliers in disposable sensors face longer lot traceability and test demands, so compliance costs rise fastest for them, and that risk is highest for small fabless suppliers.
EU certification deadlines freeze chip redesigns
Under Regulation (EU) 2023/607, legacy class III and implantable class IIb devices must move to MDR certificates by 2027 and most other classes by 2028, and the extension applies only when the design does not change significantly, the Irish regulator HPRA says. A new sensor chip can count as a significant change, which constrains redesigns until certificates are issued. Chip suppliers waiting for European redesign orders face slower conversion of design wins.
Long design cycles delay revenue from custom chips
Custom biosensing chips take years from first contract to volume, a barrier that strains smaller design houses. The EnSilica contracts noted in the trends show the lag, with the life-science chip won in March 2026 bringing material revenue only from fiscal 2027 and the healthcare controller still at the feasibility stage. Fabless firms with few programs are most exposed, because a delayed device approval pushes back wafer orders and engineering fees.
Consumer wearable volumes are uneven by country
Consumer wearables supply much of the optical front-end volume, and orders from low-cost brands swing with demand in price-sensitive markets. Low-cost watch and band brands buy entry optical front ends mainly on price, and an entry heart-rate front end lists at about USD 3.06 on TI.com, which leaves catalog suppliers little room when those brands cut orders. Suppliers tied to those brands are most exposed, because lower volumes speed price cuts on catalog chips.
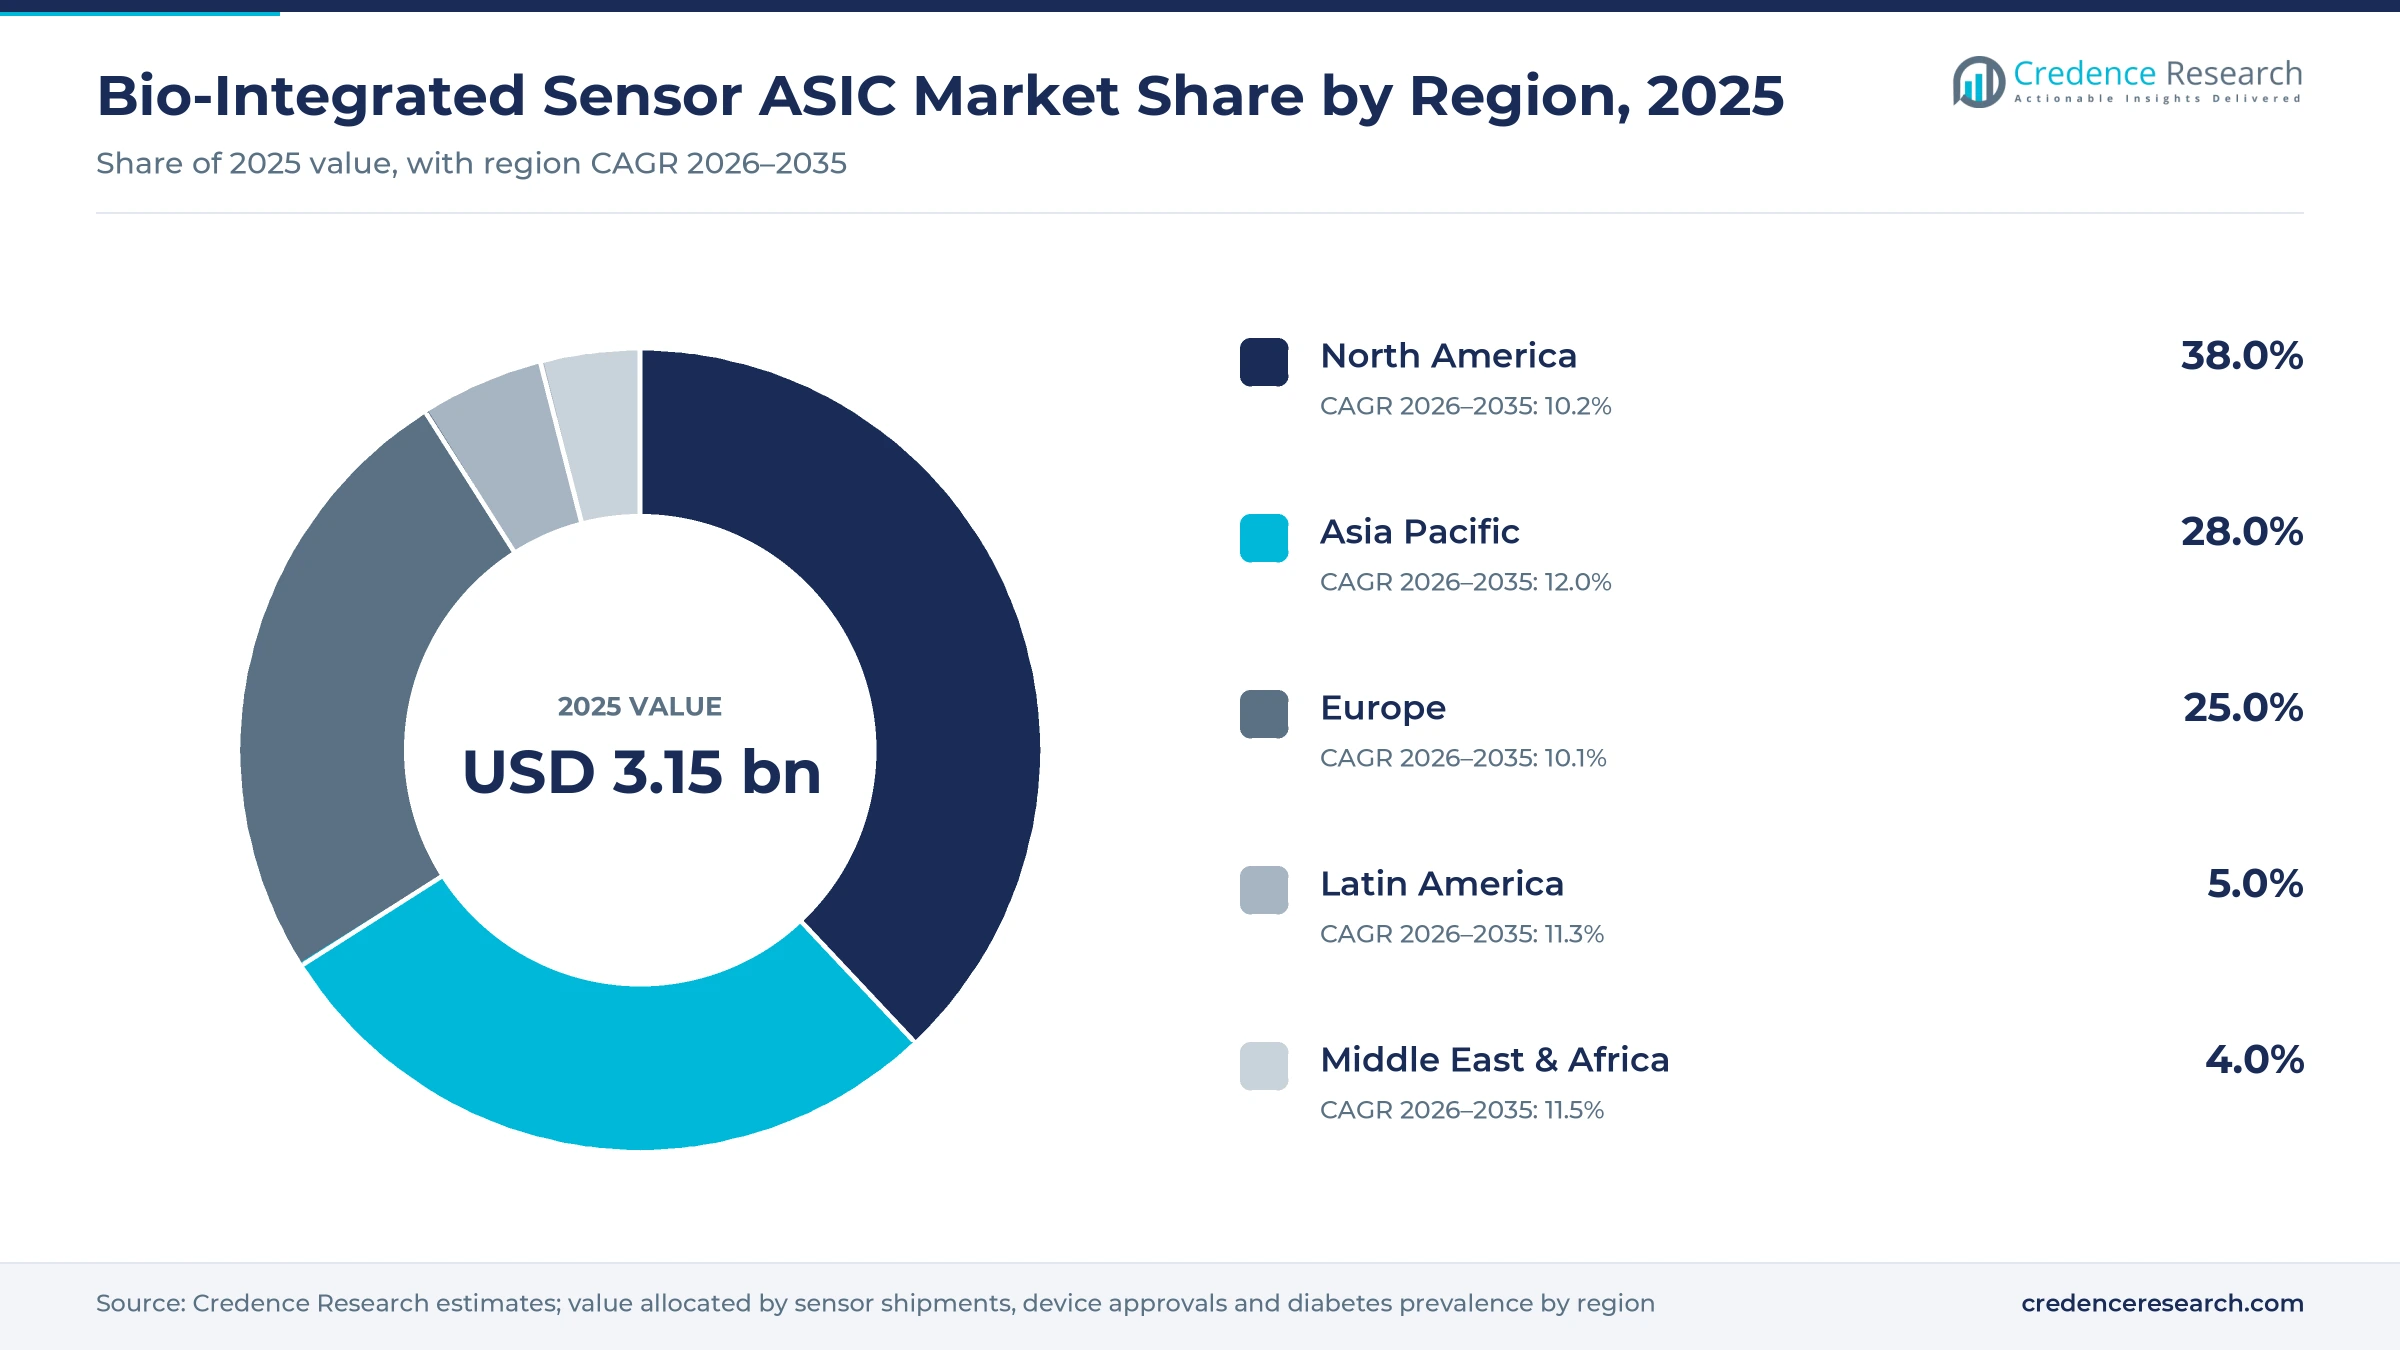
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 1.20 | 38.0% | 10.2% |
| Asia Pacific | 0.88 | 28.0% | 12.0% |
| Europe | 0.79 | 25.0% | 10.1% |
| Latin America | 0.16 | 5.0% | 11.3% |
| Middle East & Africa | 0.13 | 4.0% | 11.5% |
North America leads on CGM approvals and design teams
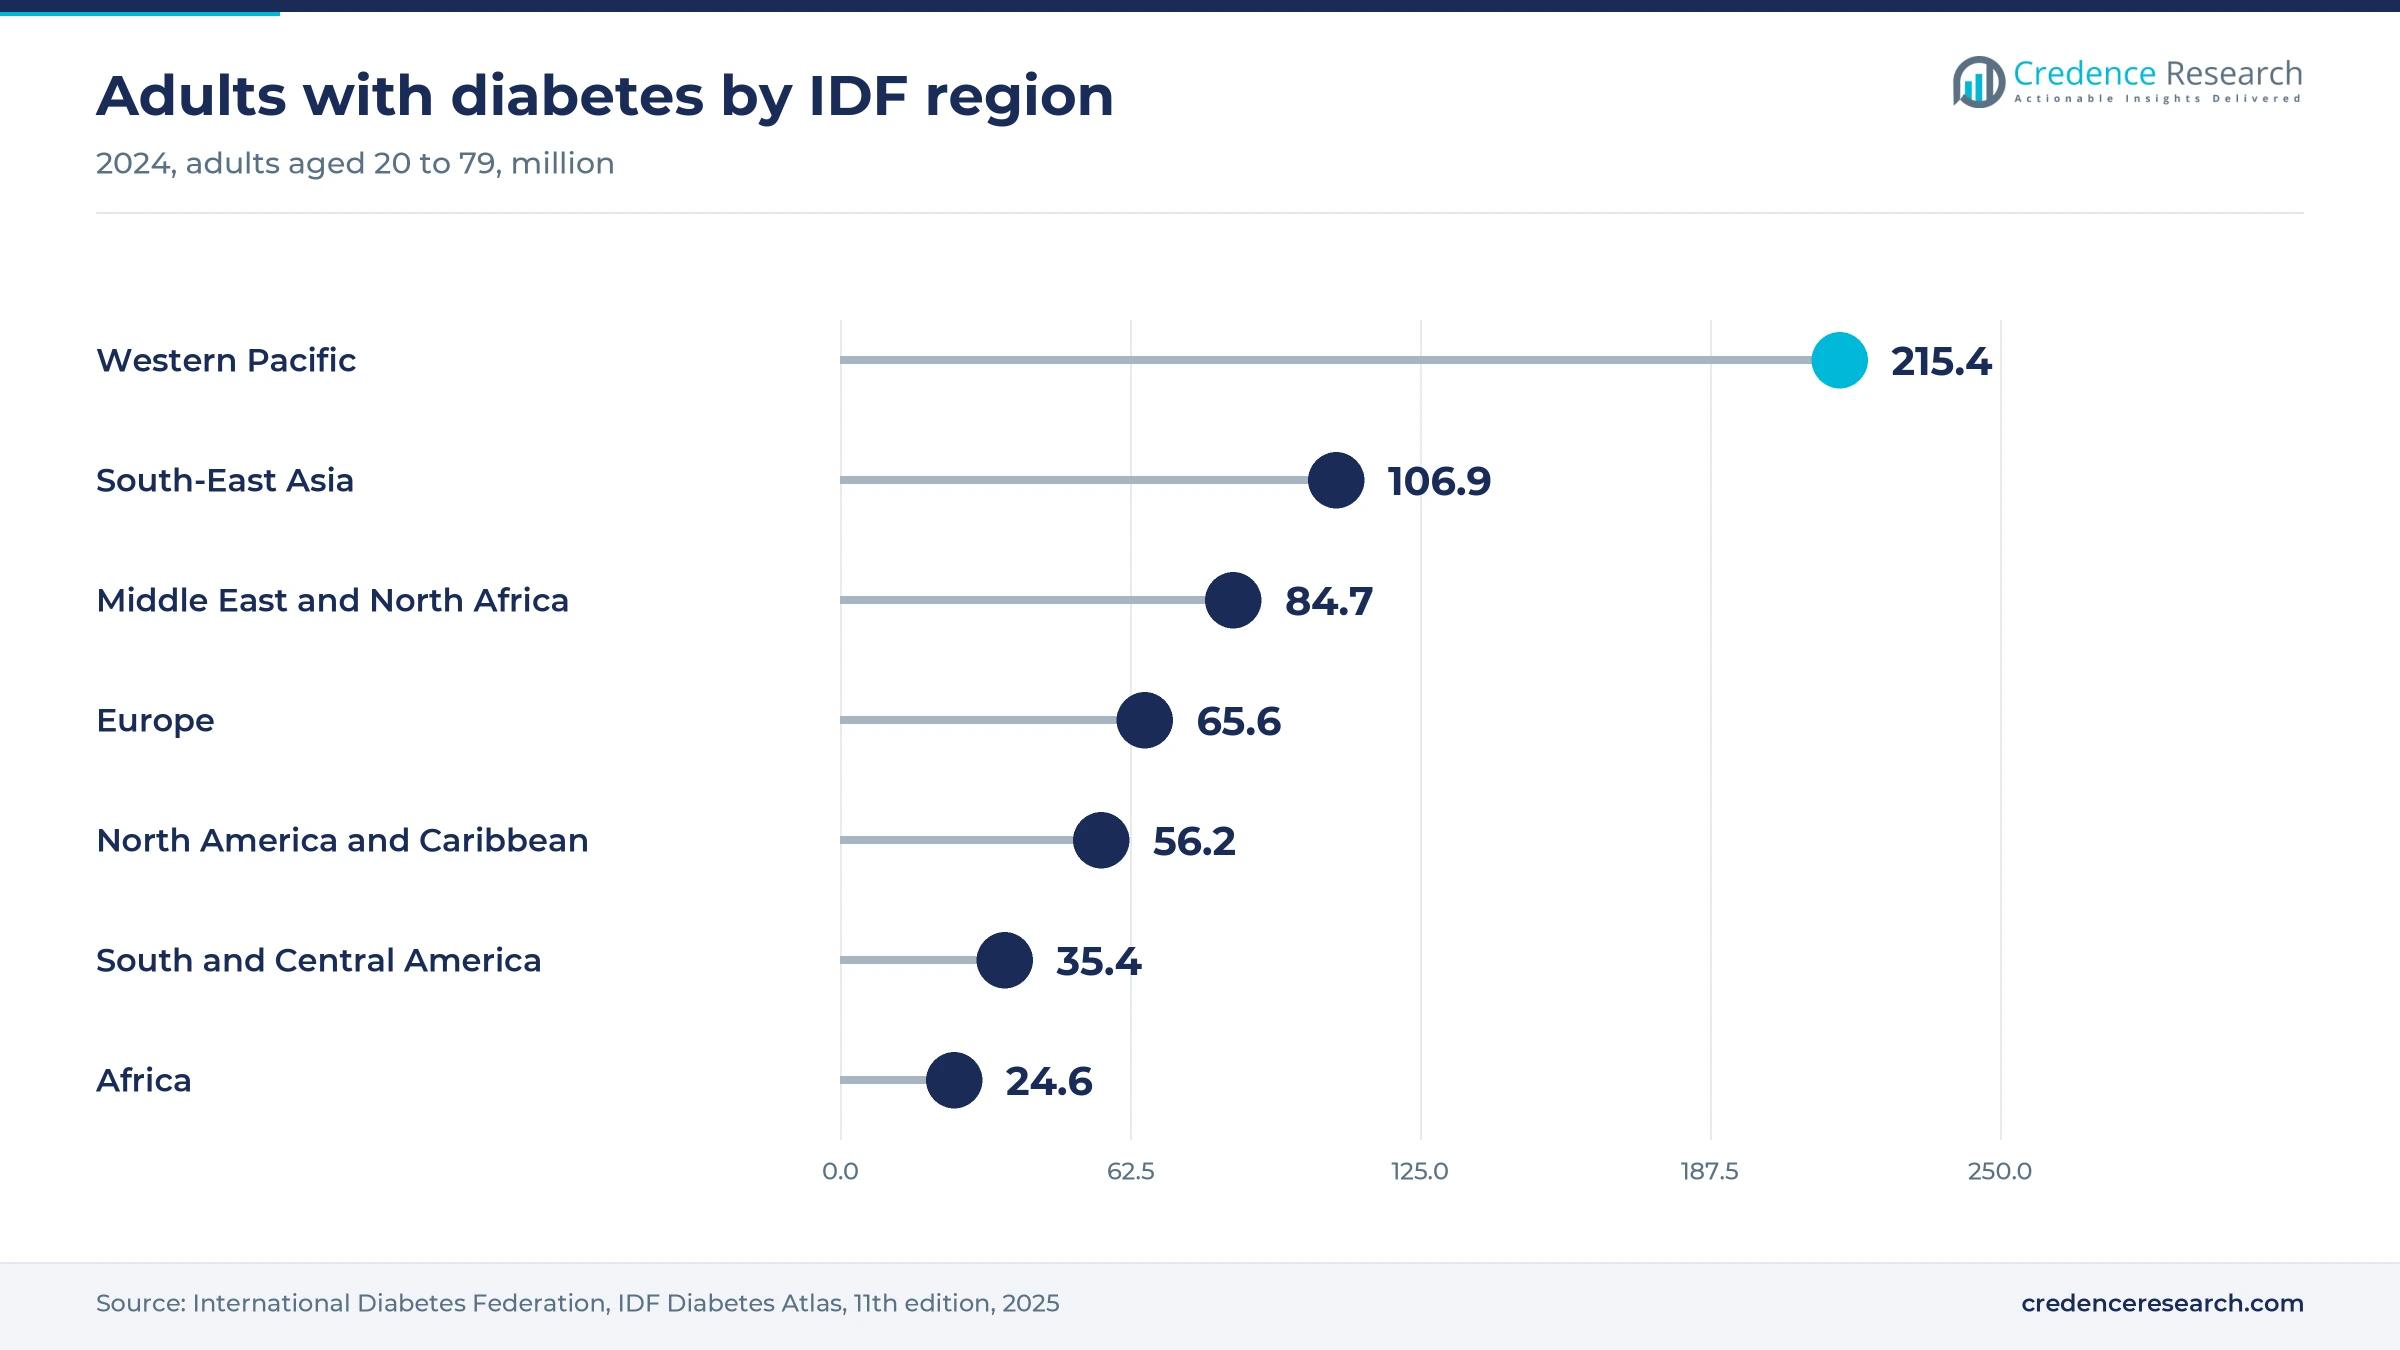
North America held a regional share of 38.0% in 2025 and grows at 10.2% a year. The FDA cleared over-the-counter glucose sensing, a two-week Dexcom sensor and a year-long implant between 2024 and 2025, so most new sensor programs launch in the United States first. The IDF counts 56.2 million adults with diabetes in North America and the Caribbean in 2024. Texas Instruments, Analog Devices and Sigenics design front ends and custom chips close to device makers, so most design wins stay in the region.
Asia Pacific grows fastest on diabetes prevalence
Asia Pacific held a regional share of 28.0% in 2025 and grows at 12.0% a year, the fastest of the five regions. The IDF counts 215.4 million adults with diabetes in the Western Pacific and 106.9 million in South-East Asia in 2024, more than half the world total. Much watch and band assembly takes place in China and India, so the region sets volume for optical front ends. Public data on local CGM chip sourcing are thin, which is an evidence gap in the regional split.
Europe combines sensor plants and chip design houses
Europe held a regional share of 25.0% in 2025 and grows at 10.1% a year. Abbott's Kilkenny site in Ireland is set to produce more Libre sensors than any other plant, and the IDF counts 65.6 million adults with diabetes in Europe in 2024. Custom medical chip design sits with ICsense and AnSem in Belgium, EnSilica in the United Kingdom and STMicroelectronics in France and Italy. MDR certification deadlines in 2027 and 2028 slow redesigns, so growth stays below the global rate.
Latin America builds on a large diabetes base
Latin America held a regional share of 5.0% in 2025 and grows at 11.3% a year. The IDF counts 35.4 million adults with diabetes in South and Central America in 2024, about 6% of the world total of 588.7 million. Sensors and wearables arrive finished, so regional chip value rises only when public payers such as Brazil's and Mexico's health systems widen CGM coverage. Reimbursement for CGM varies widely by country, and public data on sensor volumes are limited, which is an evidence gap.
Middle East and Africa start from a low device base
Middle East & Africa held a regional share of 4.0% in 2025 and grows at 11.5% a year. The IDF counts 84.7 million adults with diabetes in the Middle East and North Africa and 24.6 million in Africa in 2024. Public data on CGM and wearable chip volumes in the region are limited, which is an evidence gap in this estimate. Gulf health systems and private insurers decide CGM uptake, so chip value tracks reimbursement in Saudi Arabia and the UAE more than the larger diabetes counts in Africa.
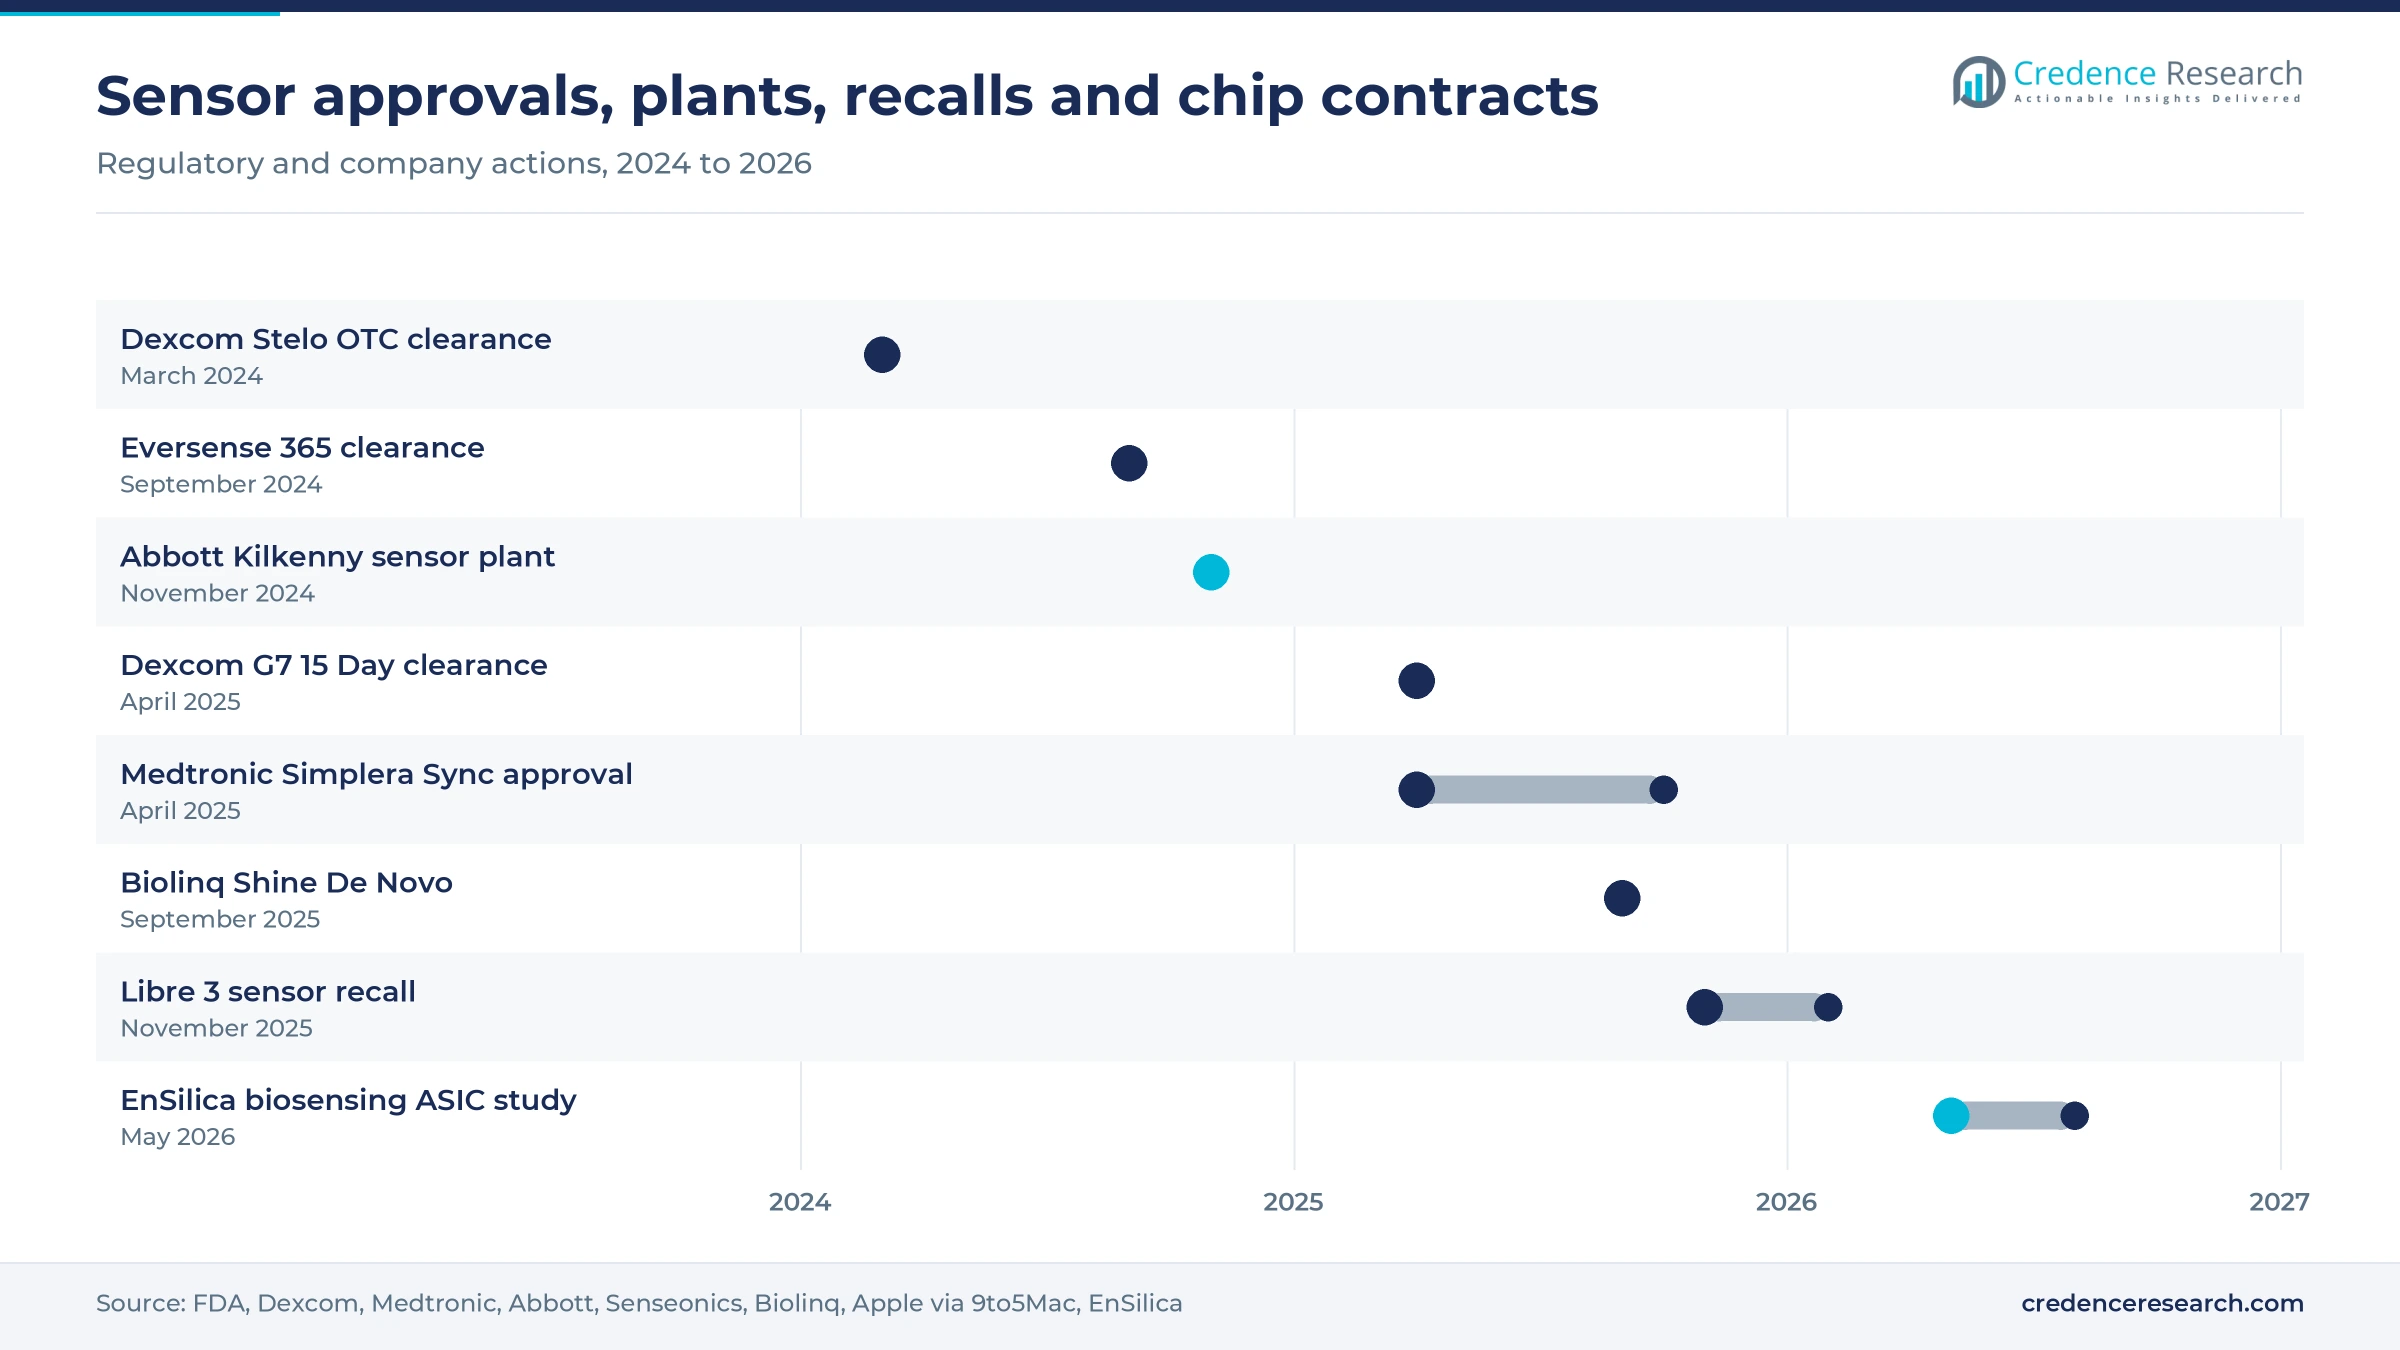
Approvals, recalls and new custom chip contracts
| Development | Status and market relevance |
|---|---|
| In March 2024, the FDA cleared Dexcom Stelo as the first over-the-counter glucose biosensor for adults not using insulin. | Regulatory clearance; commercial launch followed in the United States. |
| In November 2024, Abbott opened its Kilkenny, Ireland, plant for FreeStyle Libre 3 sensors. | Completed facility; now operating and employing more than 800 people. |
| In April 2025, the FDA cleared the Dexcom G7 15 Day sensor and approved Medtronic's Simplera Sync sensor. | Regulatory clearances; U.S. launches planned for the second half of 2025. |
| In September 2025, the FDA granted De Novo classification to Biolinq Shine, a semiconductor microsensor array patch. | Regulatory grant; launch date not disclosed. |
| In March 2026, EnSilica won a life-science chip contract and a healthcare biosensing ASIC feasibility study. | Orders secured; study scheduled to start in May 2026. |
Front-end, power and wireless blocks on one die
- Potentiostat readout channels hold a fixed voltage on electrochemical electrodes and measure picoamp to nanoamp currents, which sets glucose and ketone accuracy.
- Optical front ends drive LEDs and digitize photodiode signals for heart rate and blood oxygen, and a higher signal-to-noise ratio lets designers cut LED current.
- Biopotential and bioimpedance channels read ECG signals below 1 millivolt and body impedance, enabling rhythm, respiration and blood pressure features.
- Integrated power and radio blocks manage tiny batteries and Bluetooth or NFC links on the same die, which shrinks disposables and extends wear time.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Catalog front ends compete with custom medical ASICs
Competition in the bio-integrated sensor ASIC market splits between broad-line analog makers that sell catalog front ends and custom design houses that build one chip for one device. Texas Instruments sells optical, ECG and potentiostat front ends through its own store and distributors, while Analog Devices offers the MAX86178 three-channel front end for wearables. ams OSRAM pairs its AS7058 front end with its own LEDs and photodiodes. TDK's ICsense, EnSilica, Cyient Semiconductors' AnSem and Sigenics compete for custom programs in glucose sensors, implants and life-science instruments, where low-power design skill and an ISO 13485 quality system decide shortlists. STMicroelectronics competes by combining sensing front ends with microcontrollers and MEMS sensors in one supply relationship. Device makers choose on noise, power, package size and supply security over a product life of many years.
How is the supply side organized?
The supply side of this market runs in two distinct tiers. Broad-line analog makers such as Texas Instruments, Analog Devices, STMicroelectronics and ams OSRAM sell catalog front ends to many device makers and earn margins on scale and long product lives. Custom design houses such as ICsense, EnSilica, AnSem and Sigenics build chips for one client, earning engineering fees first and supply revenue later. Foundries make the wafers, and the largest CGM makers often own the chip specification. Entry barriers sit in ISO 13485 quality systems, low-noise analog design skills and the multi-year qualification each device demands.
Analog front-end suppliers and custom medical ASIC houses
| Company | Type | Role in the market |
|---|---|---|
| Texas Instruments | Broad-line analog supplier | Sells optical heart-rate, ECG and electrochemical potentiostat front ends for medical devices |
| Analog Devices | Broad-line analog supplier | Sells PPG, ECG and bioimpedance front ends such as the MAX86178 |
| STMicroelectronics | Broad-line supplier | Supplies biosensing front ends, MEMS sensors and microcontrollers for medical wearables |
| ams OSRAM | Optical sensing specialist | Sells the AS7058 multi-vital-sign front end with its LEDs and photodiodes |
| TDK Corporation (ICsense) | Custom ASIC house | Designs and produces custom sensor interface ASICs for medical wearables and implants |
| EnSilica | Custom ASIC house | Designs and supplies custom biosensing, wearable and life-science chips |
| Cyient Semiconductors (AnSem) | Custom ASIC house | Designs custom analog and mixed-signal ASICs for medical and other clients |
| Sigenics Inc. | Custom ASIC house | Designs custom mixed-signal ASICs for medical and sensor applications |
Value shifts to low-power, multi-analyte chips
Credence Research's view is that chip value in biosensing is moving from general front ends toward custom low-power designs built for one disposable or implant, as glucose sensors spread beyond insulin users and wear periods lengthen. Electrochemical readout keeps the largest share, but flexible patches, multi-analyte sensors and closed-loop controllers add value faster. Recalls and EU certification deadlines are the main near-term risks, because both slow redesigns. Suppliers that combine analog design skill, a medical quality system and secure wafer supply should gain the most share.
Estimates rest on sensor volumes and chip content
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The 2025 value is a new Credence Research estimate that replaces the earlier figure after a check of sensor shipments and chip content per device across glucose monitors, wearables, patient monitors, implants and point-of-care instruments. Market values come from the Credence Research model, and the regional, sensor type, application and technology splits are Credence Research estimates informed by public data. Sources include FDA and EU regulatory releases, IDF diabetes statistics, company releases, chip maker product pages and list prices, and trade publishers. No interviews or surveys were used to build these estimates.
CGM reach, wearables and closed loops set the path
Credence Research expects the market to reach USD 8.78 billion by 2035 as disposable glucose sensors reach people who do not use insulin, wearables add medical-grade channels and closed-loop systems tie sensors to pumps. Growth is strongest in flexible patches, low-power CMOS and consumer continuous monitoring, and in Asia Pacific, while thermal sensing and standard CMOS grow more slowly. Multi-analyte sensors measuring ketones and lactate could open the next wave of design wins. Sensor recalls, slower EU certification and weak wearable shipments are the main risks to that path.
CGM reach, wearable volumes and approvals set the range
The range to 2035 depends on how fast glucose sensing spreads to people who do not use insulin, whether consumer wearable shipments recover, and how quickly new sensor designs clear the FDA and EU notified bodies. Broad reimbursement for non-insulin users would lift sensor volumes, while further recalls or slower MDR certification would delay redesigns and hold chip demand near current programs.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 8.8% | USD 7.45 billion | Recalls slow CGM uptake, wearables stay flat and EU redesigns wait for MDR certificates |
| Base | 10.80% | USD 8.78 billion | CGM user bases keep growing and multi-signal wearables keep adding medical-grade channels |
| Upside | 12.6% | USD 10.15 billion | Coverage for non-insulin users arrives and multi-analyte and closed-loop sensors launch on time |
Frequently Asked Questions
How big is the bio-integrated sensor ASIC market?
What is a patient monitoring ASIC?
Which companies design sensor ASICs for medical devices?
How does Sigenics compare with other medical ASIC designers?
How much does a biosensing front-end chip cost?
Are sensor ASICs used in consumer devices?
Why does Asia Pacific grow fastest?
What risks could slow the bio-integrated sensor ASIC market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Sensor Type
- 1.2.1 Electrochemical Biosensors
- 1.2.2 Optical Biosensors
- 1.2.3 Piezoelectric Biosensors
- 1.2.4 Thermal Biosensors
- 1.2.5 Flexible and Bio-Conformal Sensors
- 1.2.6 Implantable Sensor Systems
- 1.3 By Application
- 1.3.1 Medical Diagnostics and Monitoring
- 1.3.2 Wearable Health Devices and Continuous Monitoring
- 1.3.3 Point-of-Care Testing
- 1.3.4 Environmental Monitoring
- 1.3.5 Others
- 1.4 By Technology
- 1.4.1 Standard CMOS
- 1.4.2 Low-Power CMOS
- 1.4.3 Silicon-on-Insulator
- 1.4.4 MEMS and NEMS Integration
- 1.4.5 Flexible Substrates
- 1.4.6 Hybrid Nanomaterial Integration
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3.15 billion → 2035: USD 8.78 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bio-Integrated Sensor ASIC Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bio-Integrated Sensor ASIC Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bio-Integrated Sensor ASIC Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bio-Integrated Sensor ASIC Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bio-Integrated Sensor ASIC Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bio-Integrated Sensor ASIC Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bio-Integrated Sensor ASIC Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bio-Integrated Sensor ASIC Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3.15 billion → 2035: USD 8.78 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bio-Integrated Sensor ASIC Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Sensor Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Electrochemical Biosensors
- 12.3.7.2 Optical Biosensors
- 12.3.7.3 Piezoelectric Biosensors
- 12.3.7.4 Thermal Biosensors
- 12.3.7.5 Flexible and Bio-Conformal Sensors
- 12.3.7.6 Implantable Sensor Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Medical Diagnostics and Monitoring
- 12.4.7.2 Wearable Health Devices and Continuous Monitoring
- 12.4.7.3 Point-of-Care Testing
- 12.4.7.4 Environmental Monitoring
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Standard CMOS
- 12.5.7.2 Low-Power CMOS
- 12.5.7.3 Silicon-on-Insulator
- 12.5.7.4 MEMS and NEMS Integration
- 12.5.7.5 Flexible Substrates
- 12.5.7.6 Hybrid Nanomaterial Integration
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bio-Integrated Sensor ASIC End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bio-Integrated Sensor ASIC Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bio-Integrated Sensor ASIC Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bio-Integrated Sensor ASIC Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Texas Instruments
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Analog Devices
- 18.4 STMicroelectronics
- 18.5 ams OSRAM
- 18.6 TDK Corporation (ICsense)
- 18.7 EnSilica
- 18.8 Cyient Semiconductors (AnSem)
- 18.9 Sigenics Inc.
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

