
Olfactory sensing ASICs move from air purifiers to clinics
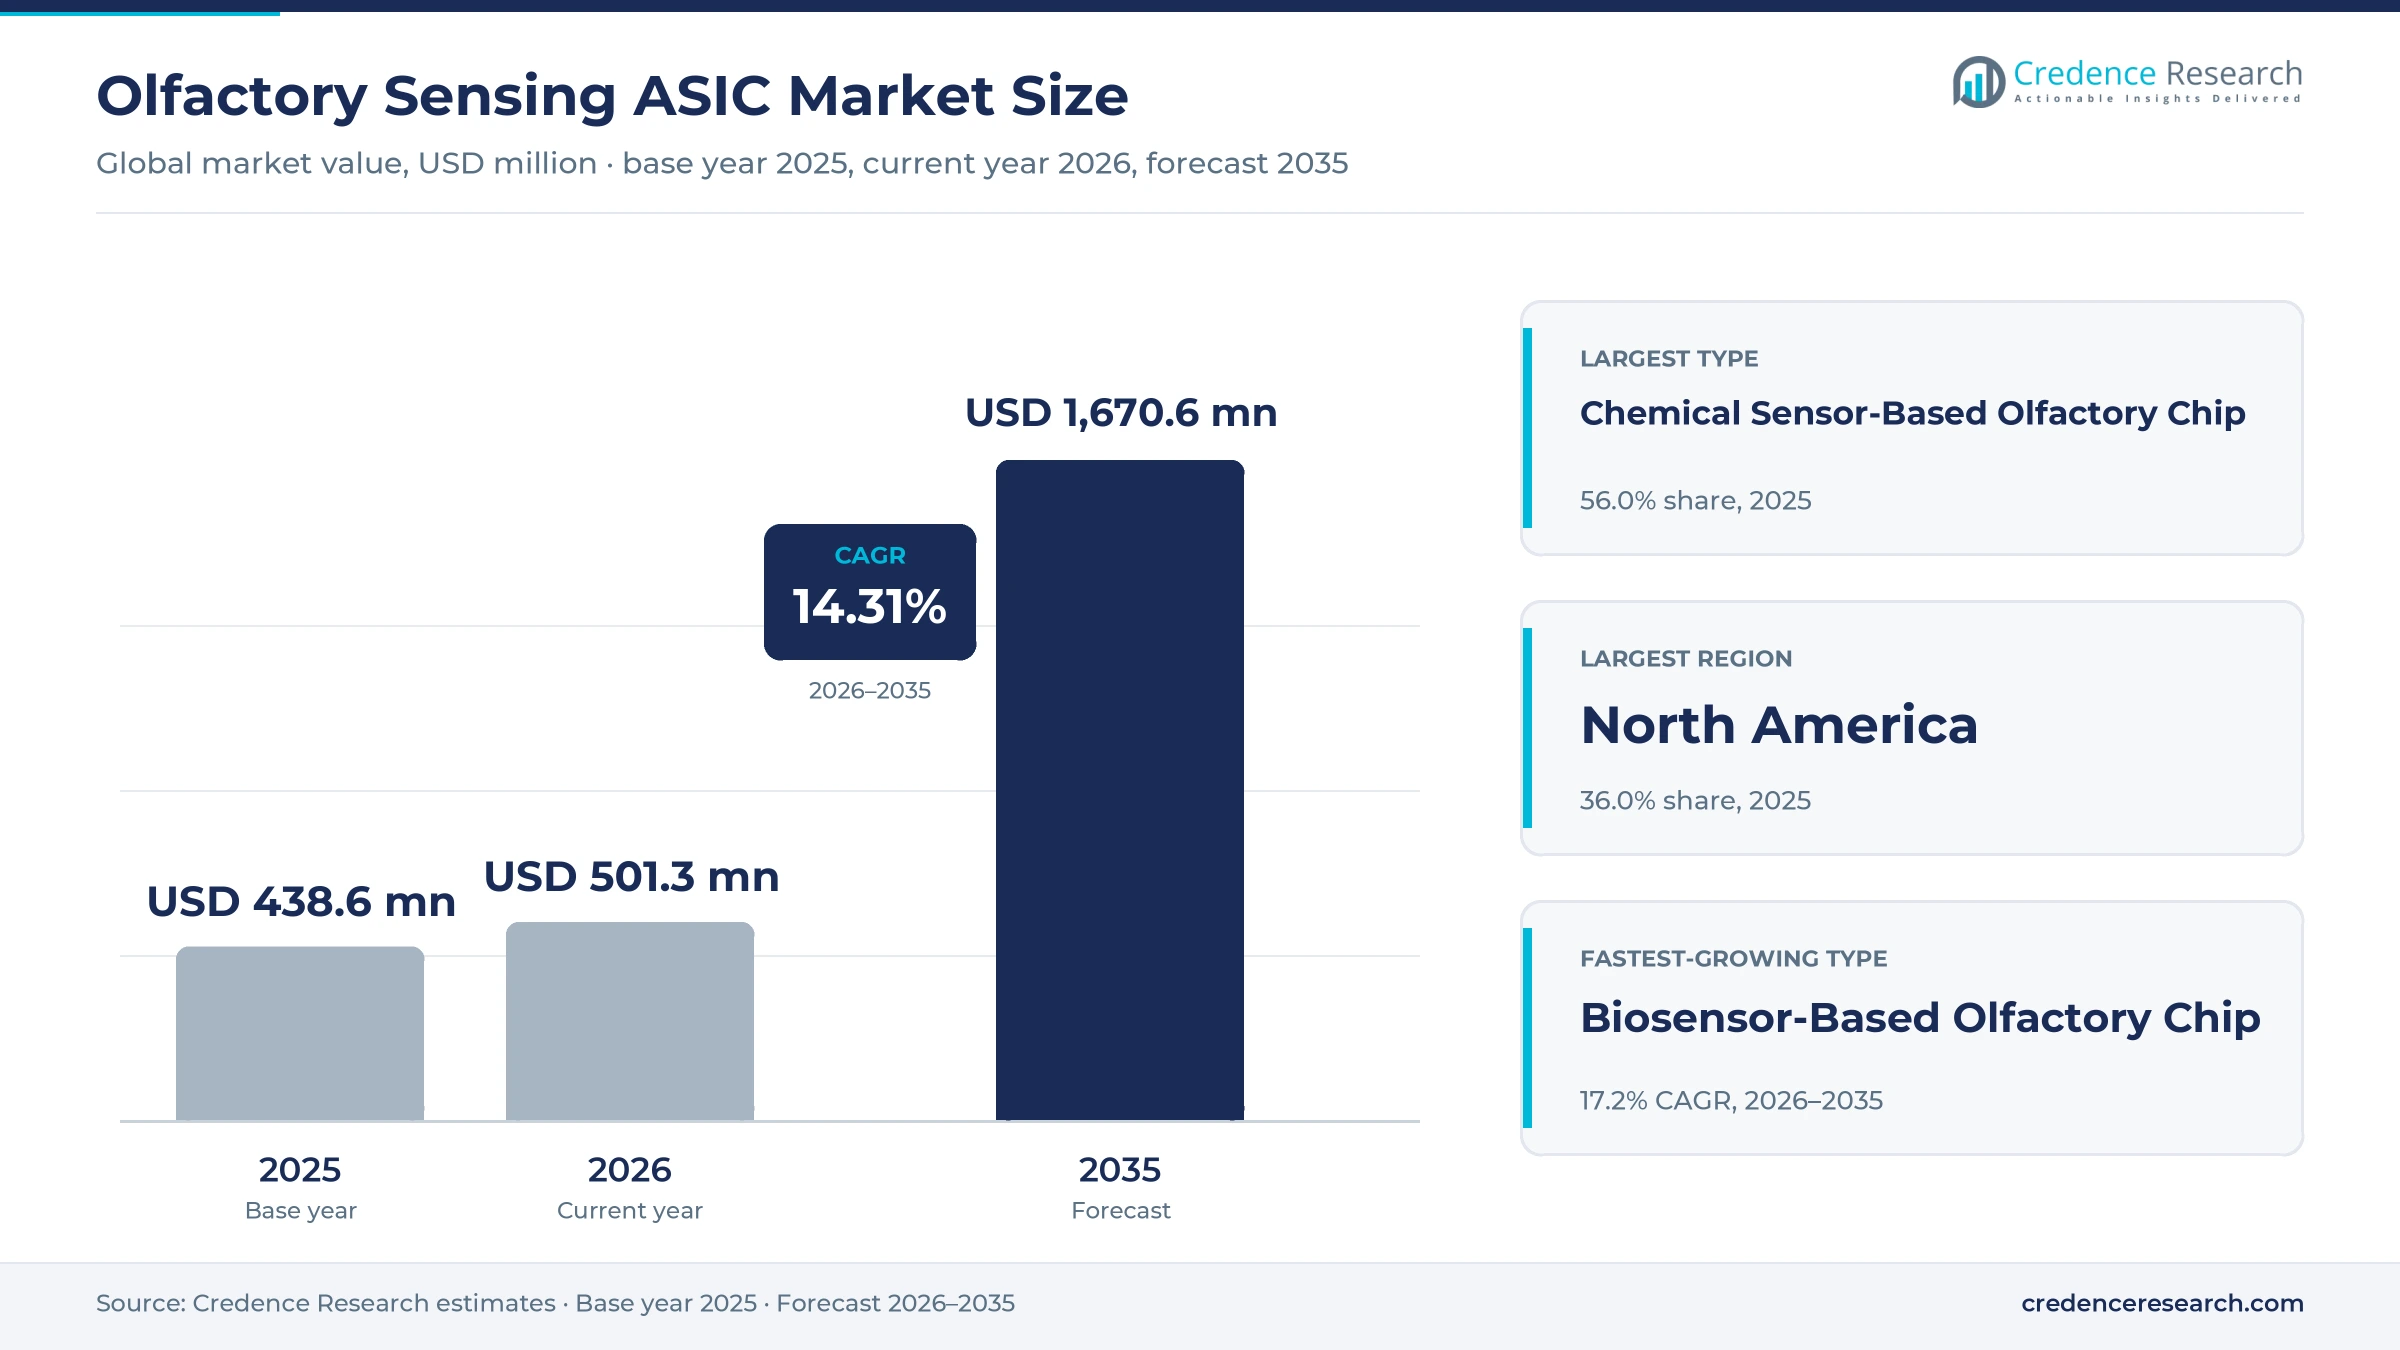
The global olfactory sensing ASIC market was valued at USD 438.6 million in 2025 and is projected to increase from USD 501.3 million in 2026 to USD 1.67 billion by 2035, registering a CAGR of 14.31% during 2026–2035. Demand comes from appliance, HVAC and smart home brands that build VOC and odor readings into purifiers, thermostats and monitors, and from food, medical and industrial buyers that want a chip-scale substitute for laboratory odor analysis. North America held the largest regional share, 36.0% in 2025, because medical, security and building certification buyers pay for higher-value modules. Asia Pacific is the fastest-growing region at 15.4% a year, as Chinese indoor air rules and Japanese robot pilots widen use. The main commercial change is the move from bare sensors to trainable chips that run smell classification on the device. Limited selectivity between similar compounds remains the main restraint on clinical use.
Which odor-sensing chips does the estimate count?
The estimate counts sensor chips and chip-scale modules that pair an odor or VOC sensing element with an application-specific readout or signal-processing circuit, including metal oxide multi-pixel gas sensors, electrochemical olfactory chips, receptor-based biosensors and photonic olfaction cores. It values them at the price that the chip or module maker receives from device builders.
Finished electronic nose instruments, air purifiers and laboratory gas chromatography systems sit outside the estimate, although they are the main channels through which these chips reach end users. Most volume is bought by appliance and electronics brands under annual supply contracts, while food, medical and industrial buyers purchase smaller lots of trainable modules.
Olfactory Sensing ASIC Market Insights
- The market is valued at USD 438.6 million in 2025 and should reach USD 1.67 billion by 2035, growing at a 14.31% CAGR as VOC and odor chips enter more devices.
- North America led with 36.0% of 2025 value, supported by medical research, security screening and building certification buyers that pay for higher-value modules.
- Chemical Sensor-Based Olfactory Chip held 56.0% of 2025 value, because metal oxide chips from Bosch, Sensirion, Renesas and ScioSense ship in standard 3 mm packages.
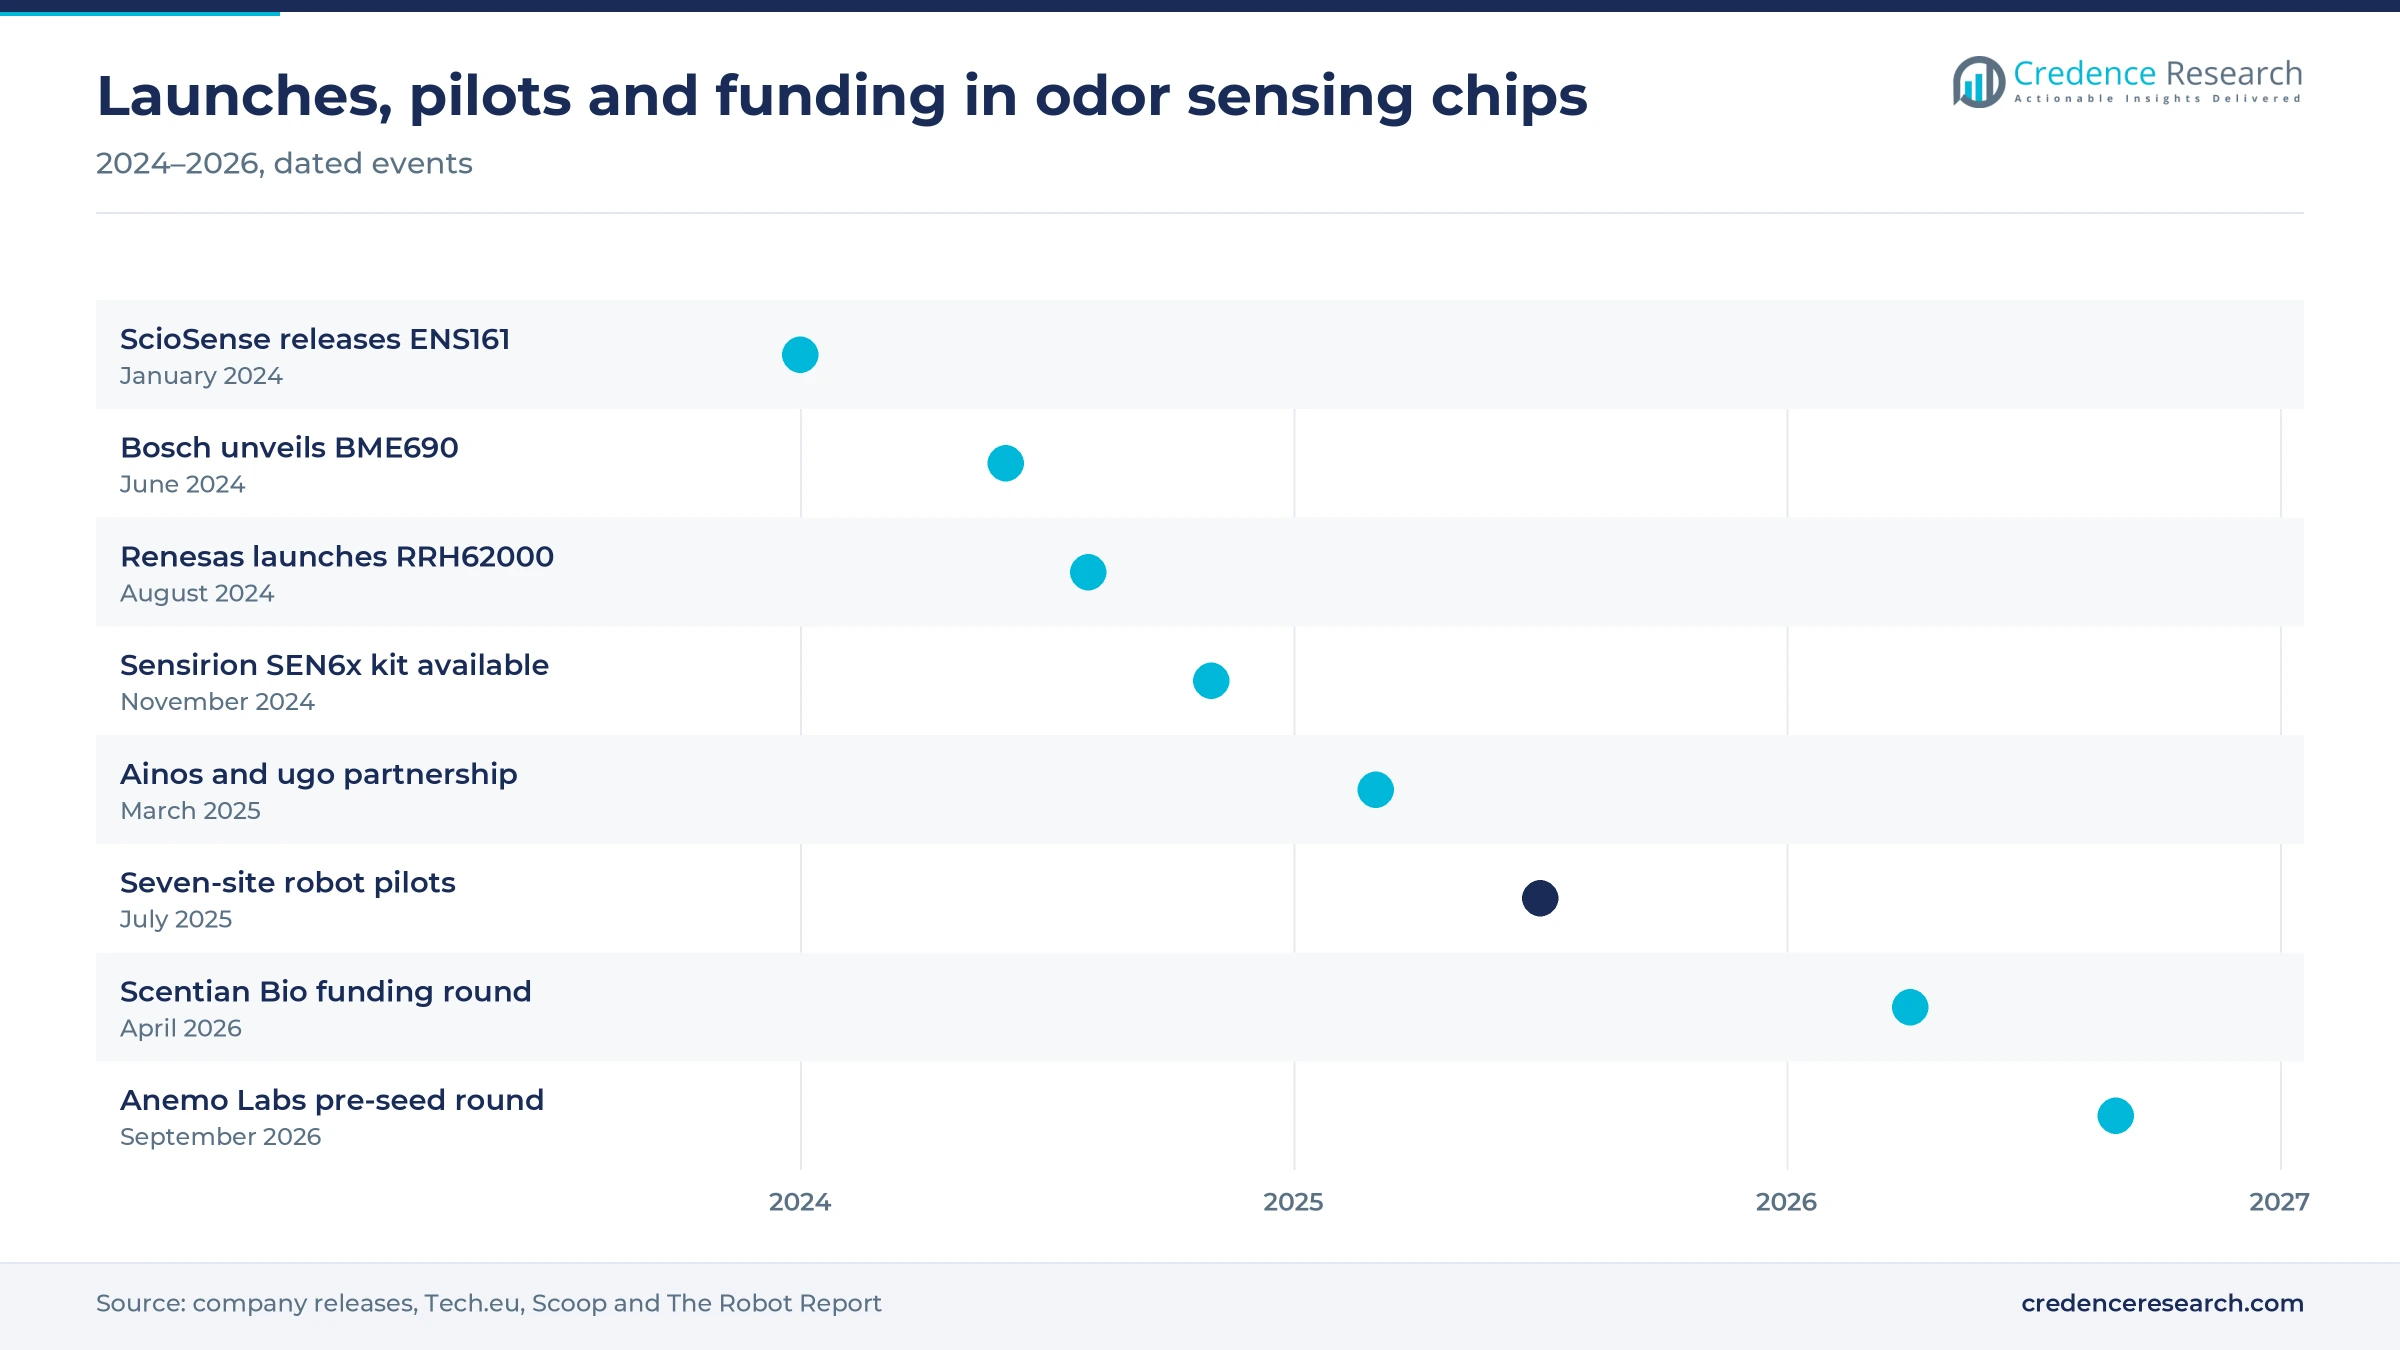
- Bosch unveiled the BME690 in June 2024 with up to 50% lower power than the BME688, which opens battery wearables to on-chip smell classification.
- Ainos and ugo began AI Nose robot pilots at seven Japanese industrial sites in July 2025, a test of odor chips in factory patrol work.
Metal oxide chips lead while receptor biosensors gain
Why do metal oxide chips lead while receptor biosensors grow fastest?
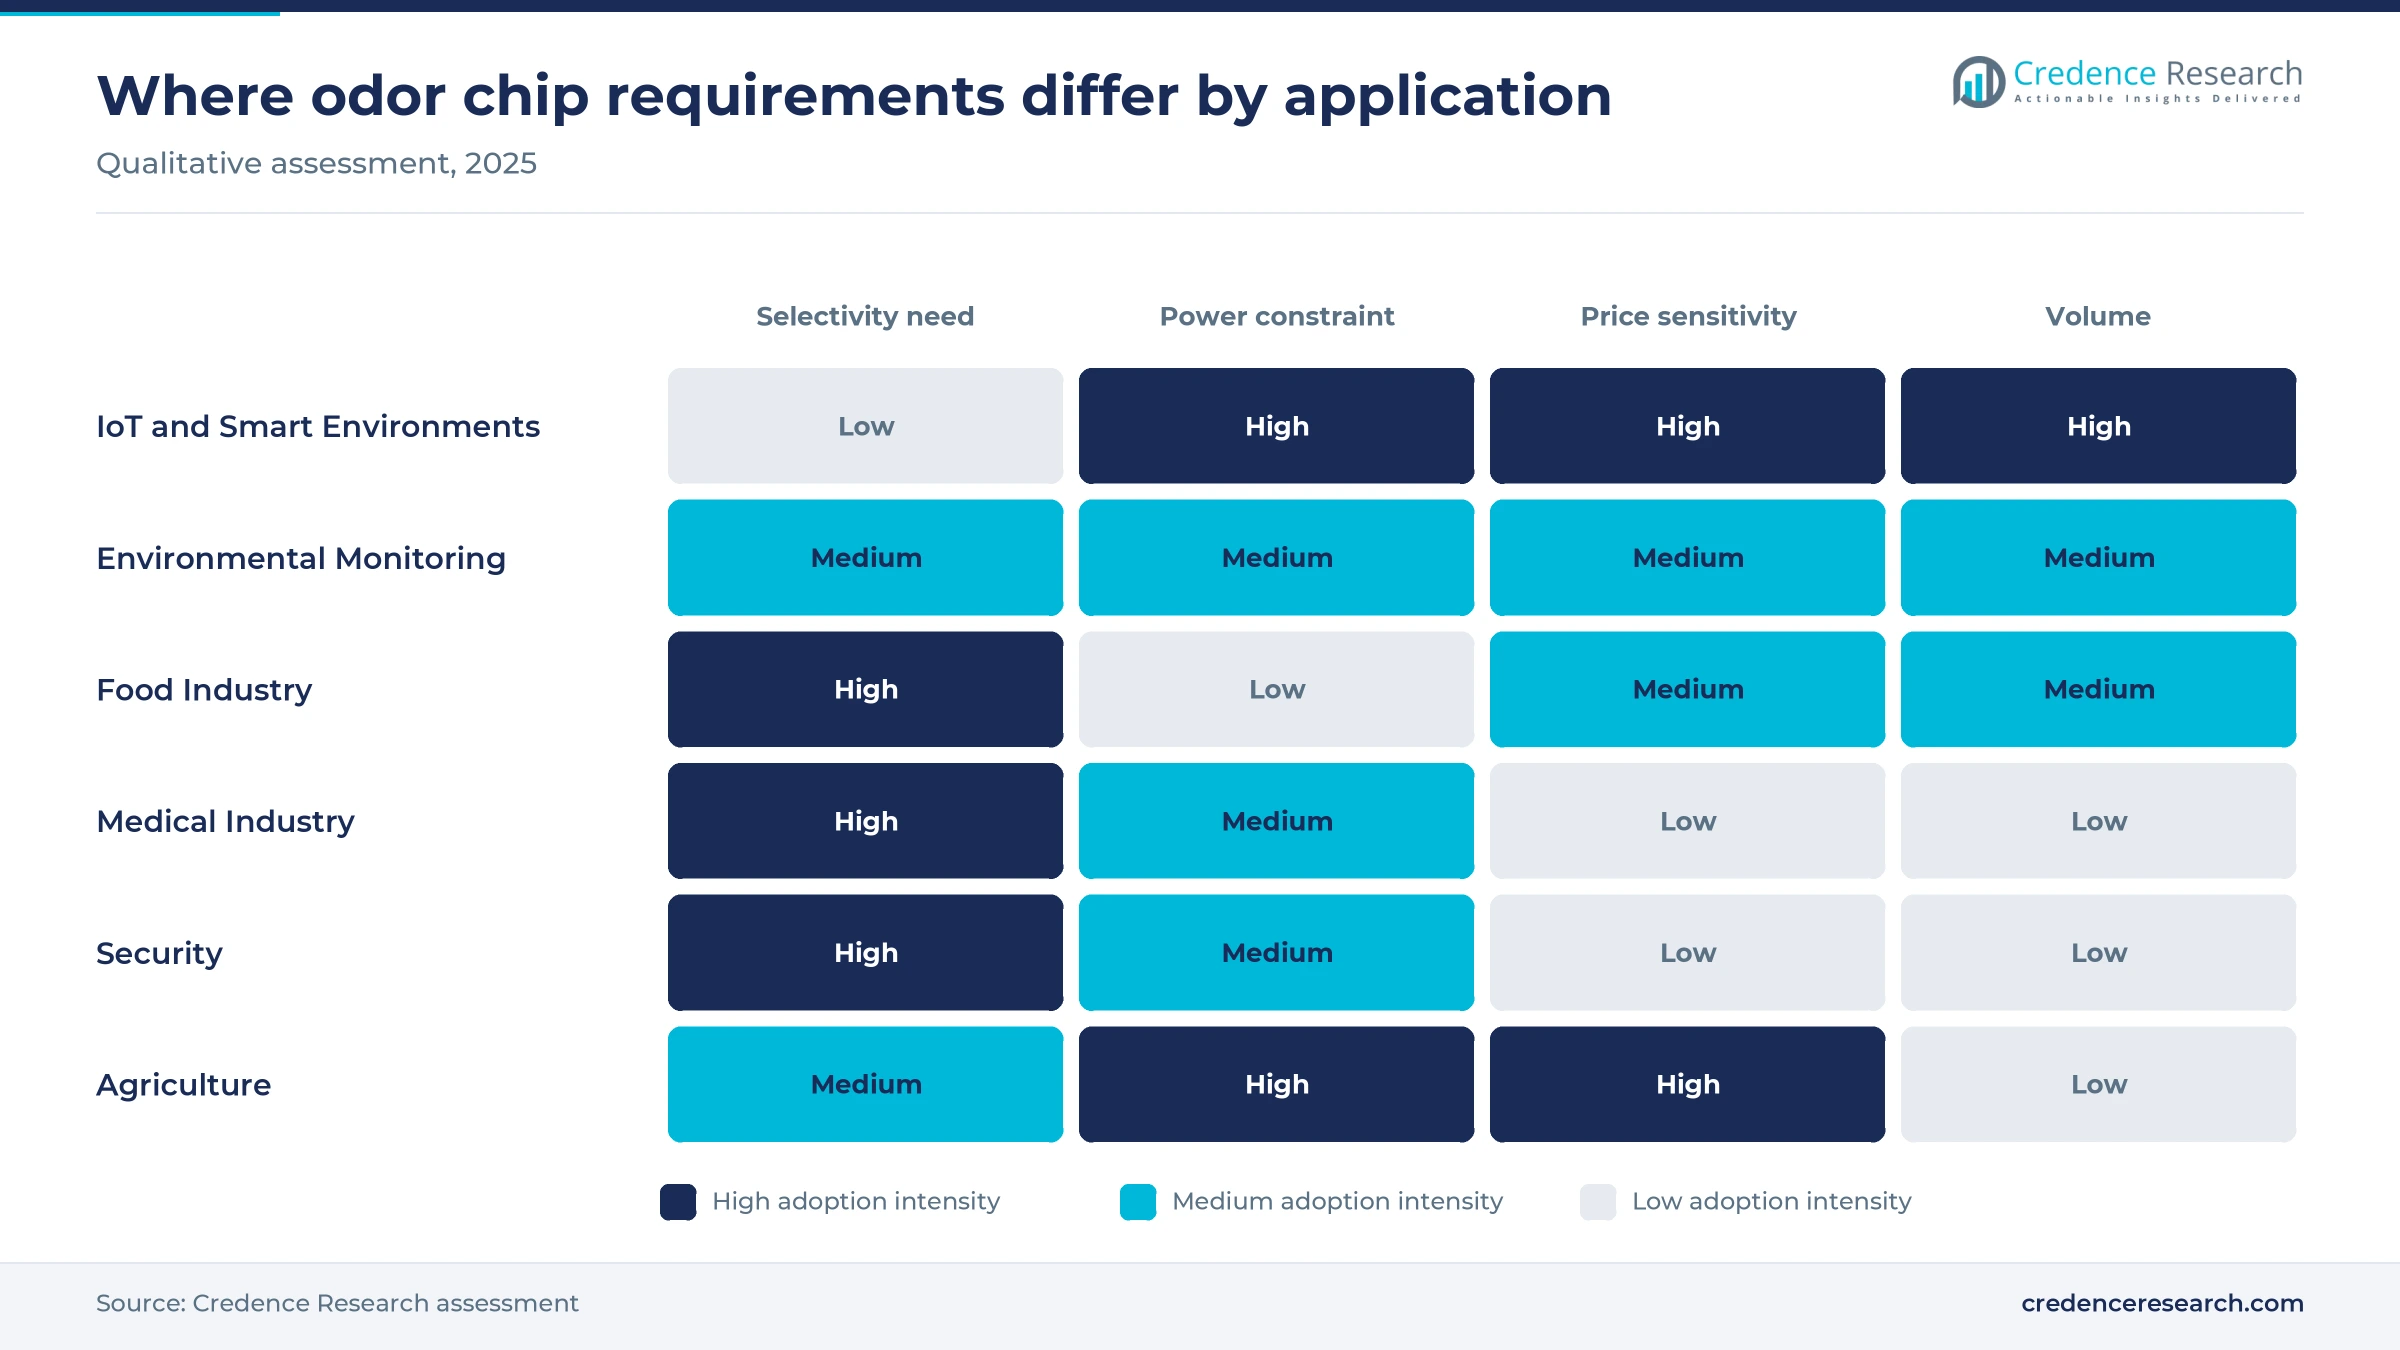
Based on type, the market is categorized into chemical sensor-based olfactory chips, biosensor-based olfactory chips, electrochemical sensor-based olfactory chips and other types. Chemical Sensor-Based Olfactory Chip led with 56.0% of 2025 value, because metal oxide arrays drop into existing boards at appliance cost, as the four-element ScioSense ENS161 does in a 3 mm by 3 mm package. Biosensor-Based Olfactory Chip grows fastest at 17.2% a year because synthetic odorant receptors bind specific compounds, which metal oxide films cannot do, and Scentian Bio closed a funding round in April 2026 to launch such a device, although from a small base.
Why do IoT devices lead while medical uses grow fastest?
Based on application, the market is categorized into the food industry, medical industry, agriculture, environmental monitoring, security, IoT and smart environments and other applications. IoT and Smart Environments led with 33.0% of 2025 value, because purifiers, thermostats and monitors need only a broad VOC index, so commodity chips suffice, as in the Ruuvi Air monitor built on Sensirion's SEN66 module in December 2025. Medical Industry grows fastest at 16.4% a year because each test carries far higher value per chip than an appliance socket, and New Cosmos unit Figaro Engineering presented its TGS 1820 acetone sensor for diabetes control in February 2025.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Chemical Sensor-Based Olfactory Chip | 56.0% | Biosensor-Based Olfactory Chip | 17.2% |
| By Application | IoT and Smart Environments | 33.0% | Medical Industry | 16.4% |
Volume breaks cut digital VOC chip prices by nearly half
Pricing splits between commodity metal oxide chips and trainable specialist modules. Digital VOC chips are sold per unit on reels, and distributor price breaks show how quickly cost falls with volume, from GBP 6.89 for a single Sensirion SGP41 to GBP 4.86 at 1,000 units at RS Components. Appliance brands negotiate below these list levels, which keeps margins thin for undifferentiated chips. Specialist olfaction cores carry far higher prices because buyers pay for trained models and support. Chip makers protect margin by bundling algorithms, humidity compensation and module integration.
| Product or reference | Typical price or fee | Basis |
|---|---|---|
| Sensirion SGP41 VOC and NOx sensor, fewer than 10 units | GBP 6.89 per unit | RS Components list price, November 2026 |
| Sensirion SGP41 VOC and NOx sensor, 1,000+ units | GBP 4.86 per unit | RS Components list price, November 2026 |
| Sensirion SGP41, 2,500-unit reel | GBP 3.95 per unit | Farnell U.K. list price, November 2026 |
| Metal oxide VOC chip, appliance supply contract | About USD 1.50–3.50 per chip | Credence Research estimate from distributor price breaks |
| Photonic or receptor olfaction core module | About USD 300–3,000 per module | Credence Research estimate from module scope and volumes |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Air standards, health data and low power lift chip demand
Indoor air rules turn VOC readings into a building requirement
Building rules now ask owners to measure indoor air continuously, which converts odor and VOC chips from optional features into specified components. The recast EU Energy Performance of Buildings Directive requires devices that monitor key indoor air quality parameters in large non-residential buildings, and member states must transpose it by May 2026, the European Commission's BUILD UP portal says. China's GB/T 18883-2022 standard sets an 8-hour TVOC limit of 600 micrograms per cubic meter, according to RESET. RESET's own acceptable TVOC level is 500 micrograms per cubic meter, matching the WELL threshold. Chip makers whose readings map to these thresholds win design slots in ventilation controls and building monitors.
Health evidence pushes appliance brands to add VOC sensing
Health data on indoor pollution give appliance and HVAC brands a reason to put VOC chips into purifiers, range hoods and thermostats. Household air pollution caused an estimated 2.9 million deaths in 2021, according to the World Health Organization. Renesas notes that indoor pollutants are typically six to ten times more concentrated than outdoor levels, and its RRH62000 module, launched in August 2024, combines a ZMOD4410 metal oxide gas sensor with particle, humidity and temperature sensing for seven outputs. Device brands gain a selling point they can display on the product, while chip makers with ready modules shorten their customers' design cycles.
Lower power draw opens wearables and battery devices
Lower heater power is widening odor sensing from plugged-in appliances to wearables and battery-powered trackers, where metal oxide chips were once too hungry. Bosch Sensortec says its BME690, unveiled in June 2024, cuts power consumption by up to 50% against the BME688 while keeping the same 3 by 3 by 0.93 mm footprint. ScioSense lists an ultra-low-power mode of 150 microamps average current for its ENS161, released in January 2024. ScioSense names activity trackers, smartwatches and smart glasses among target devices. Chip makers that keep pin compatibility let device brands upgrade without new boards, which favors incumbents.
Breath and body odor screening pulls chips toward diagnostics
Clinical interest in breath and body odor screening is pulling odor chips toward diagnostics, where each test carries higher value than an appliance socket. London start-up Anemo Labs raised GBP 700,000 in September 2026 for an electronic nose that screens urine samples, and reported 84.15% classification accuracy across 12 scent categories in early testing, Tech.eu said. Bosch lists breath analysis and hydrogen sulfide detection among BME690 uses. The EU-funded SMELLODI project on electronic olfaction for body odor diagnostics ran until March 2025, CORDIS reported. Makers of breath analyzers are the most likely early buyers of chips that can pass clinical validation.
Chip makers sell modules and trainable smell models
Chip makers are shifting from bare sensors to complete modules
Sensor makers are shifting from bare VOC chips toward complete modules with built-in algorithms, which moves more of the device value to the chip supplier. Sensirion announced global availability of its SEN6x evaluation kit in November 2024, covering SEN65, SEN66 and SEN68 modules that report VOC and NOx indices, with formaldehyde on the SEN68. Sensirion says the modules handle data processing internally, so manufacturers skip custom optimization. Ruuvi put the SEN66 into its Ruuvi Air monitor in December 2025, about a year after the kit release. The seven-output Renesas module launched in August 2024 follows the same pattern with an integrated microcontroller. Makers of indoor air quality monitors gain faster launches, while brands that once wrote their own sensor firmware lose a point of difference.
Trainable smell models are shifting classification onto the chip
Suppliers are shifting from fixed TVOC indices toward smell classes that customers train themselves, which lets one chip serve many products. Bosch has supported custom BME690 features since June 2024 through its BME AI-Studio tool, so developers can train the sensor for food freshness or breath patterns. The ScioSense ENS161, released in January 2024, runs on-chip algorithms that calculate TVOC and CO2 equivalents and compensate for humidity and temperature. Ainos describes a Smell ID layer built on 13 years of scent data, and in July 2025 it reported Smell ID accuracy above 90% on food and beverage scents. Suppliers that own labeled scent data build switching costs, while buyers without data teams depend on vendor models.
Factory patrol robots offer an opening for industrial smell detection
Service robots that patrol plants offer odor chip makers a new channel into industrial safety, where a robot can sniff leaks and contamination along fixed routes. Ainos and Japanese robot maker ugo agreed in March 2025 to integrate the AI Nose into ugo robots, The Robot Report said. In July 2025 the partners announced pilots at seven Japanese sites in pharmaceutical manufacturing, energy, substations and water treatment. Ainos also cited a pilot of about 1,400 AI Nose units with ASE and a planned first phase of about 5,000 units. Makers of service robots gain a sensing feature that cameras cannot supply, provided field accuracy holds.
Food quality checks on the line offer an opening for receptor chips
Food producers that test aroma and spoilage in laboratories offer an opening for portable receptor chips that give readings on the processing line. Scentian Bio, a New Zealand synthetic biology firm, closed an oversubscribed pre-Series A round in April 2026 to launch its digital nose, Scoop reported. Its platform draws on more than 20 years of insect research, and the company has seven food-sector pilot customers and plans manufacturing in Auckland, with shipping to those pilots expected within months of the April 2026 announcement. Aryballe sells its NeOse device for field use and NeOse Advance for laboratory odor analysis. Buyers of food safety testing services could cut sample turnaround if chip results match panel and laboratory methods.
Selectivity, field accuracy and humidity limit adoption
Broad VOC response limits compound-level answers
Metal oxide chips react to whole families of gases, so they report a mixed TVOC signal rather than the identity of one compound. ScioSense lists ethanol, hydrogen, toluene and oxidizing gases among the targets of a single ENS161. A graphene olfaction sensor described by CORDIS in July 2023 reached 97.5% identification accuracy in analysis but only about 83.3% precision across four odors. Food and medical buyers that need compound-specific results are most exposed to this limit.
Field accuracy still trails laboratory instrument benchmarks
Accuracy in real plants and care homes remains below the levels that safety and clinical buyers expect from laboratory instruments. Ainos reported about 80% accuracy across 22 industrial scent types at Japanese semiconductor facilities and about 85% in senior care hygiene pilots. These figures are reported by the company and still lack independent validation. Buyers that would act on a single alert, such as security or quality teams, face false alarm costs and keep laboratory checks in place.
Building guidance does not yet make VOC sensing mandatory
Building regulation favors carbon dioxide and particle monitors over VOC chips, which caps mandated demand for odor sensing. European Commission guidance on the recast EPBD suggests a minimum of carbon dioxide, temperature and relative humidity, plus PM2.5 where outdoor pollution is a concern, according to BUILD UP. VOC readings are not on that minimum list of parameters. Chip makers that rely on building demand therefore depend on voluntary WELL and RESET certification for VOC sockets.
Humidity and condensation degrade readings in kitchens
Moisture shifts the baseline of metal oxide sensors, which complicates use in kitchens, bathrooms and humid climates. Bosch designed the BME690 for white goods and kitchen range hoods that face high condensation, a sign that earlier parts struggled there. ScioSense adds humidity and temperature compensation in its on-chip algorithms. Appliance brands in humid markets carry the highest service risk, and suppliers without compensation firmware lose these sockets.
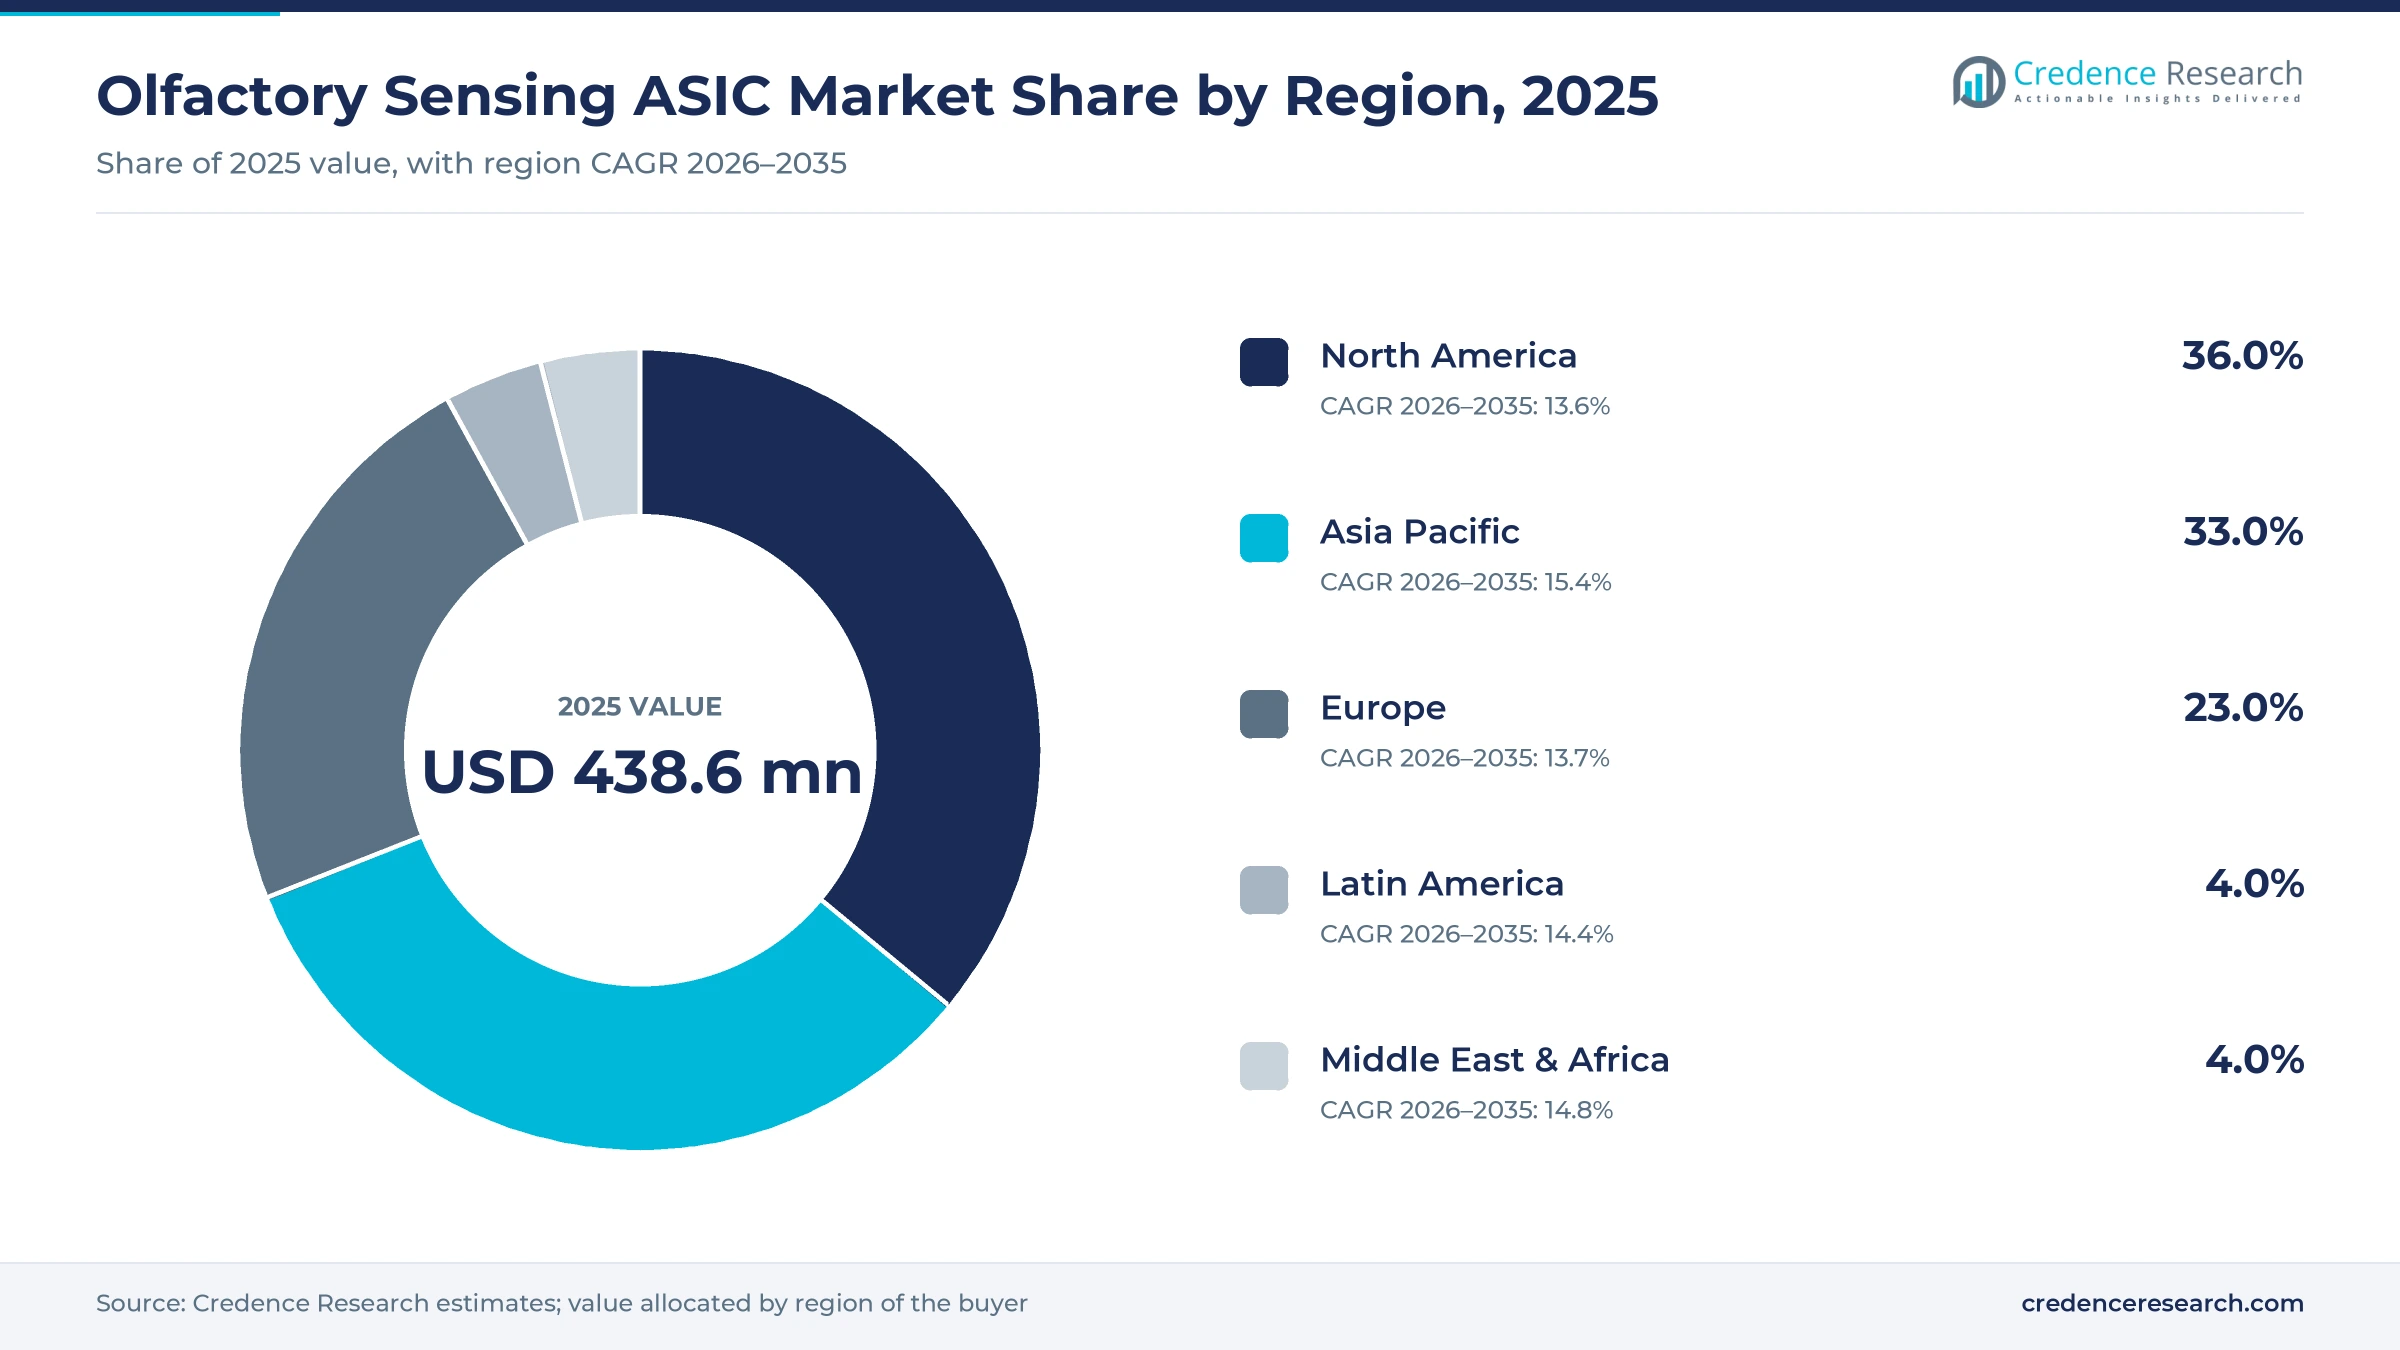
North America leads on value, Asia Pacific on growth
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 157.9 | 36.0% | 13.6% |
| Asia Pacific | 144.7 | 33.0% | 15.4% |
| Europe | 100.9 | 23.0% | 13.7% |
| Latin America | 17.5 | 4.0% | 14.4% |
| Middle East & Africa | 17.5 | 4.0% | 14.8% |
North America leads on medical, security and certified buildings
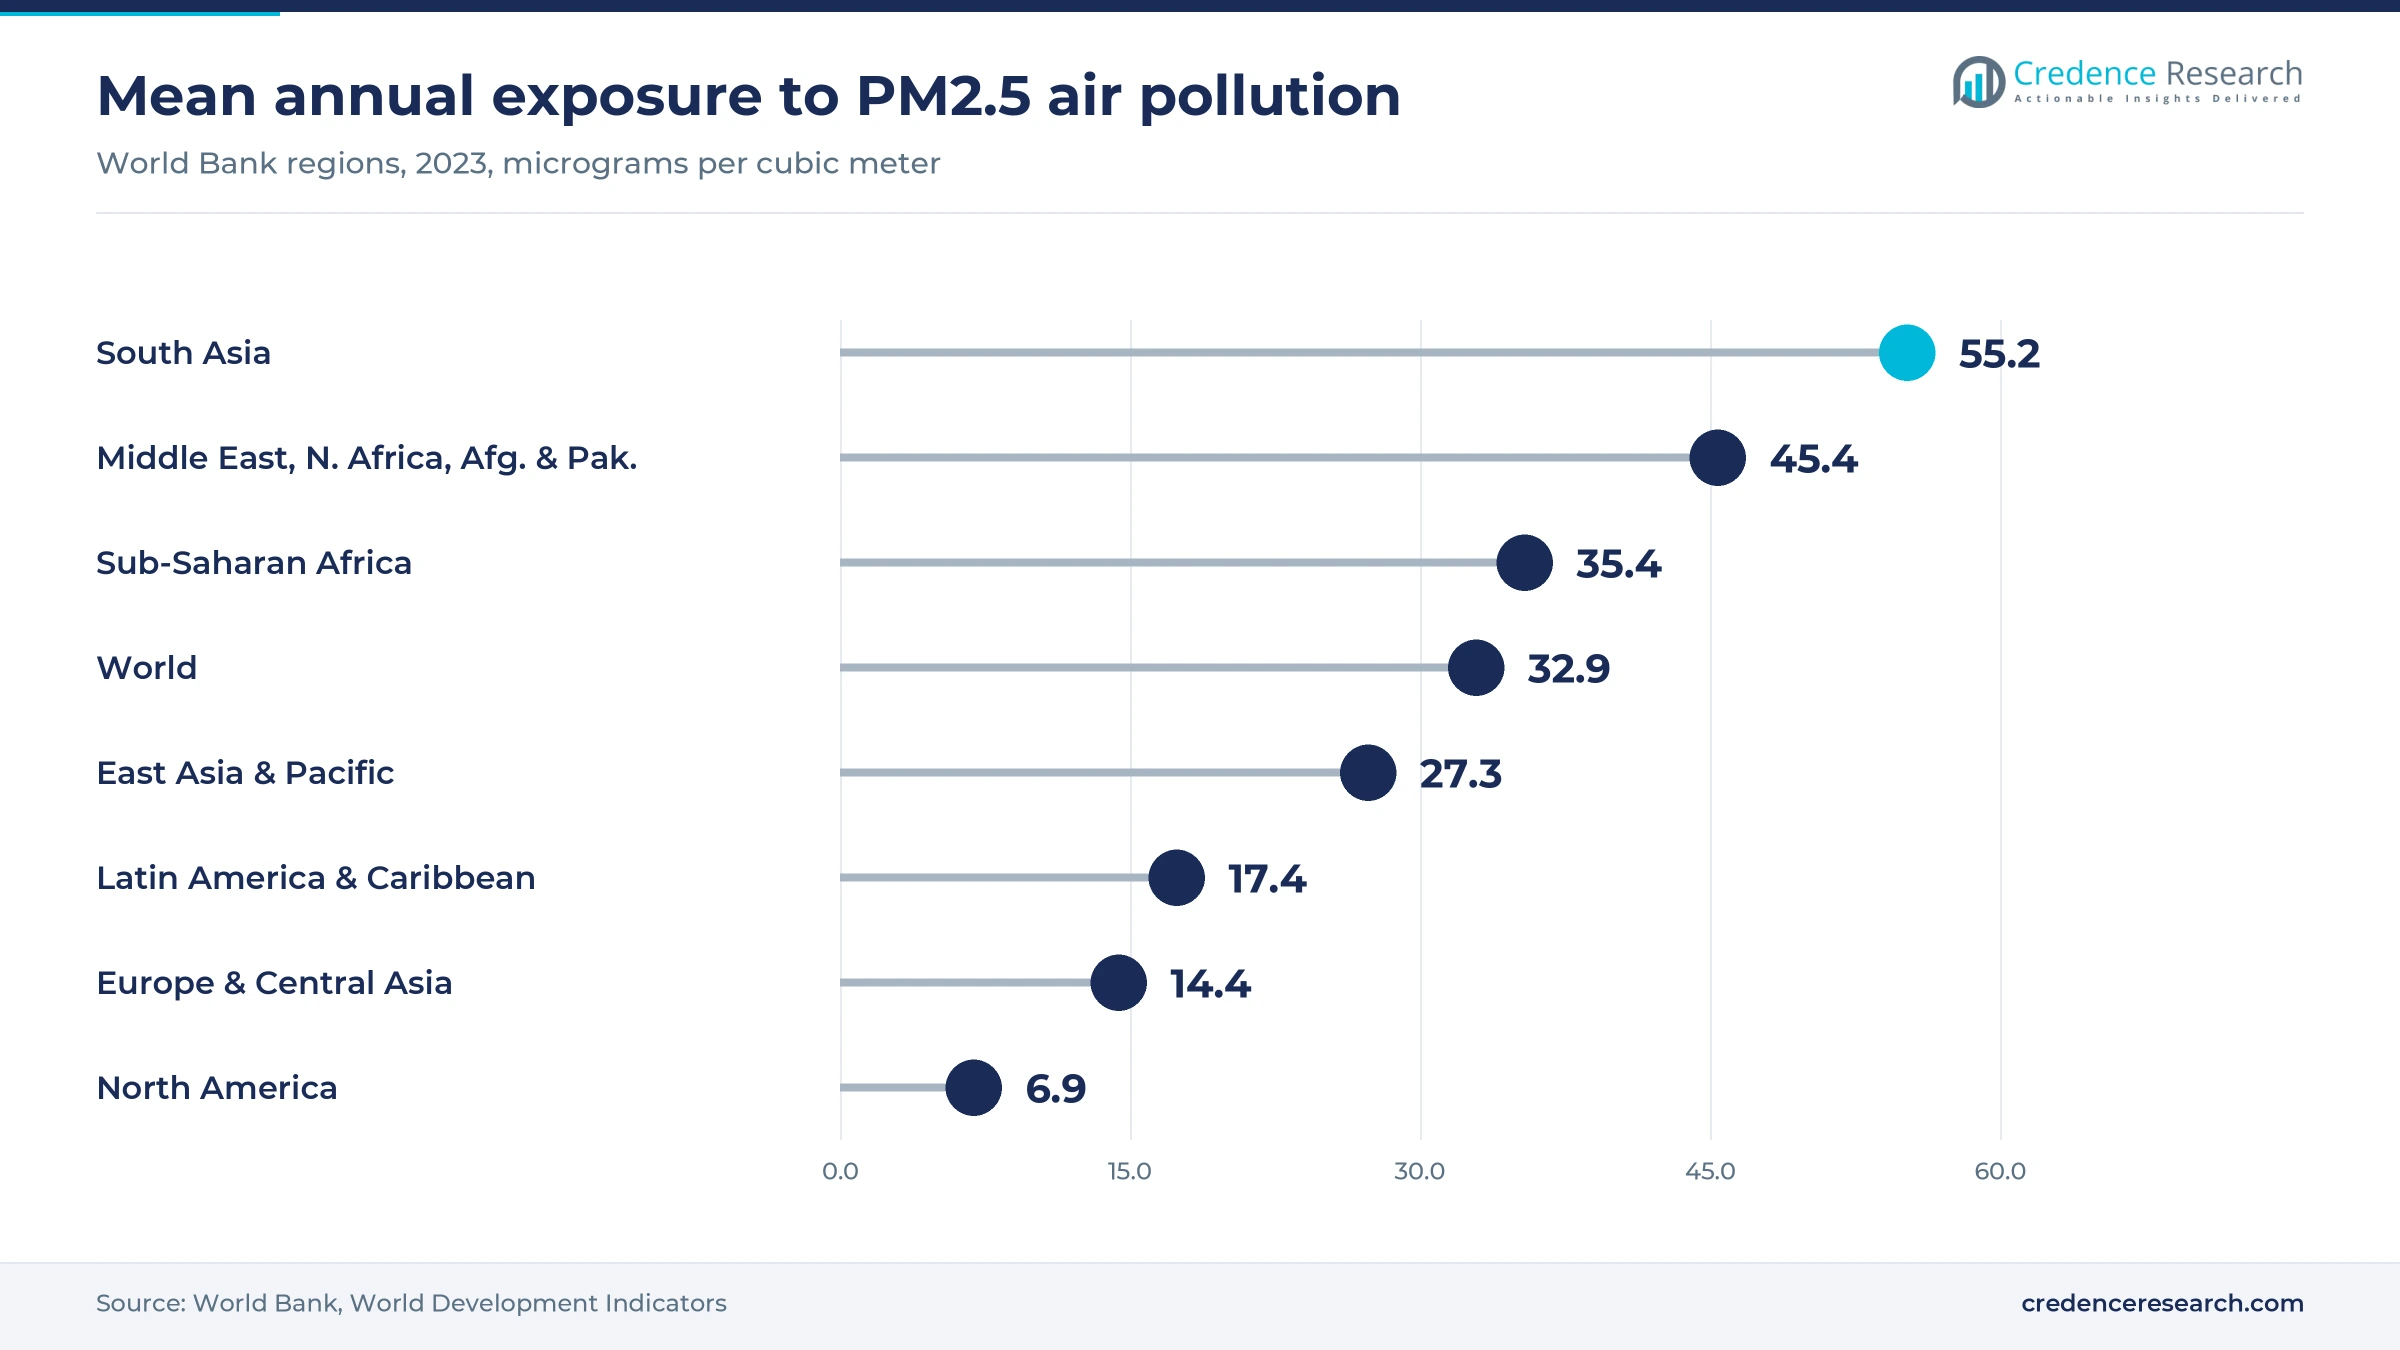
North America held 36.0% of 2025 value and grows at 13.6% a year. The lead rests on value per chip rather than volume, because buyers here purchase trained modules for breath research, security screening and buildings seeking WELL certification. Breath-analysis developers are the likeliest buyers of clinically validated chips, so regional growth depends on clinical validation that no chip supplier has yet published. Average exposure to PM2.5 was only 6.9 micrograms per cubic meter in 2023, the World Bank reports, so demand follows health and certification rather than outdoor pollution. Public data on regional chip sales remain thin, so this share is an estimate.
Asia Pacific grows fastest on Chinese rules and Japanese robots
Asia Pacific held 33.0% of 2025 value and grows fastest at 15.4% a year. China's TVOC limit under GB/T 18883-2022 gives purifier and appliance makers a reading to display, which makes the region the largest buyer of chip volume. Chinese purifier and appliance brands buy most of this volume on annual contracts, so their pricing sets the region's chip margins. Japan adds higher-value industrial demand through the ugo robot pilots noted above, and New Cosmos Electric, which owns a majority of Figaro Engineering, supplies odor sensors to Japanese buyers.
Europe builds on sensor makers and the recast EPBD
Europe held 23.0% of 2025 value and grows at 13.7% a year. The region hosts leading chip suppliers, including Bosch Sensortec, Sensirion, ScioSense and Aryballe, which design and qualify odor chips close to European appliance brands. The recast EPBD monitoring duty for large non-residential buildings creates ventilation control sockets after May 2026, although its minimum list leaves VOC sensing optional, which tempers growth. Clinical start-ups add demand, with London-based Anemo Labs funded in September 2026 to validate urine odor screening.
Middle East & Africa gains from Gulf indoor air monitoring
Middle East & Africa held 4.0% of 2025 value and grows at 14.8% a year. Gulf health agencies now track indoor air, and the Abu Dhabi Public Health Centre runs more than 330 smart monitoring devices across schools, homes and commercial sites, Gulf News reported in February 2026. Public programs of this kind buy finished networked monitors, so they lift demand for multi-gas modules rather than for single chips. Most chips arrive in the region inside imported monitors and HVAC equipment, so local value stays low.
Latin America remains an import market for odor chips
Latin America held 4.0% of 2025 value and grows at 14.4% a year. The region has no publicly identified producer of olfactory chips, so demand arrives inside imported purifiers, monitors and food testing devices. Regional value therefore tracks imports of finished purifiers and monitors rather than local design-ins. Regional shares are a Credence Research estimate with a wide margin because local sales data are not published.
Launches, pilots and funding rounds from 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In June 2024, Bosch Sensortec unveiled the BME690, a 4-in-1 MEMS air quality sensor with AI features and up to 50% lower power than the BME688. | Product launch; Mouser began stocking it in February 2025, giving designers volume access. |
| In August 2024, Renesas launched the RRH62000 module, combining a ZMOD4410 gas sensor, particle sensing and an RA microcontroller. | Product launch; targets homes, schools and public buildings that follow WELL and RESET. |
| In November 2024, Sensirion announced global availability of its SEK-SEN66 evaluation kit for SEN6x air quality modules with VOC and NOx outputs. | Commercial availability; lets device brands evaluate the modules before design-in. |
| In July 2025, Ainos and ugo announced AI Nose robot pilots at seven industrial sites in Japan. | Testing milestone; pilots follow a March 2025 partnership agreement, with results pending. |
| In April 2026, Scentian Bio closed an oversubscribed pre-Series A round to launch its receptor-based digital nose for food quality. | Funding completed; commercial launch planned with seven food-sector pilot customers. |
Four sensing principles compete for odor detection
- Metal oxide arrays heat several sensing films on a micro hotplate and read resistance changes, which suits low-cost VOC chips in appliances and wearables.
- Electrochemical cells measure current from gas reactions at electrodes, which gives better selectivity for specific gases in safety and food applications.
- Receptor biosensors attach synthetic odorant receptors to a transducer, which promises compound-level detection but needs stable biology at production scale.
- Photonic and graphene sensors read binding events through light or graphene channels, which supports laboratory-grade analysis in compact devices such as Aryballe's NeOse Advance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
MEMS sensor majors hold volume, specialists hold depth
Competition in the olfactory sensing ASIC market turns on package size, power, algorithm support and qualification in customer devices rather than on raw sensitivity. Bosch Sensortec competes on pin-compatible upgrades and trainable AI features, while Sensirion competes on complete modules that output ready indices. Renesas pairs its ZMOD gas sensors with its own microcontrollers, and ScioSense, which took over the ams environmental sensor portfolio, sells MOX chips and automotive-qualified cabin modules. New Cosmos Electric, which owns a majority of Figaro Engineering, holds Japan's main odor sensor lines. Aryballe and Ainos compete with trained olfaction platforms for industrial, food and medical buyers. Chinese metal oxide producers also compete on price, an evidence gap because their shipments are not published.
How do sensor majors, specialists and start-ups split the value?
The supply side of this market has three layers with different economics. MEMS and CMOS sensor majors such as Bosch Sensortec, Sensirion, Renesas and ScioSense make metal oxide chips in their own or partner fabs and sell them by the reel, which gives scale but thin margins. New Cosmos Electric, which owns a majority of Figaro Engineering, holds Japan's main odor sensor lines. Platform firms such as Aryballe and Ainos sell trained modules and data services at higher prices. Entry barriers sit in process know-how and labeled scent libraries, and margins sit where algorithms are bundled with the chip.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Robert Bosch GmbH (Bosch Sensortec) | MEMS sensor major | Sells BME688 and BME690 gas sensors with trainable AI features |
| Sensirion AG | Sensor major | Sells SGP41 VOC and NOx chips and SEN6x air quality modules |
| Renesas Electronics Corporation | Semiconductor major | Sells ZMOD gas sensors and the RRH62000 air quality module |
| ScioSense B.V. | Specialist | Sells ENS16x metal oxide VOC sensors and automotive cabin air modules |
| New Cosmos Electric Co., Ltd. (Figaro Engineering) | Specialist | Sells semiconductor odor and gas sensors, including the TGS 1820 acetone sensor |
| Aryballe | Olfaction platform | Sells NeOse devices and core sensor modules for odor analysis |
| Ainos, Inc. | Olfaction platform | Licenses AI Nose MEMS sensor arrays and smell models for robots |
Algorithms and qualification decide who wins share
Credence Research's view is that algorithms and qualification in customer devices, more than sensor chemistry, will decide share in the olfactory sensing ASIC market. Commodity VOC chips already sell for a few pounds, so suppliers that bundle trained models and modules keep margin while bare chips face price pressure. Diagnostics offer the highest value per chip but require independent validation that no supplier has yet published. Buyers should test field accuracy on their own samples and keep a second pin-compatible source qualified.
Earlier estimate tested against chip volumes and prices
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was carried forward one year at its own growth rate and tested against an estimate built from metal oxide chip volumes, distributor price breaks and specialist module activity. Regional and segment shares are Credence Research estimates based on device production locations, indoor air rules and research spending. Sources include World Health Organization and World Bank statistics, European Commission material, company releases and distributor price lists. No interviews or surveys were conducted for this update of the estimate.
Medical screening and building rules carry growth
Growth of the olfactory sensing ASIC market to 2035 depends on building rules, appliance volumes and the pace of clinical validation. The base case assumes that metal oxide chips keep most volume through purifiers, HVAC and smart home devices, while modules with built-in algorithms take a rising share of value. Receptor biosensors and photonic cores should gain share in food and medical testing if pilot results hold. Medical Industry demand grows fastest at 16.4% a year, the clearest sign that value is moving toward diagnostic odor tests. A chip-based breath test approval would be the largest single upside for suppliers.
Clinical validation and building rules set the range
The range of outcomes depends on whether odor chips pass clinical and food validation, and on whether building rules add VOC readings to the minimum monitoring list. Weak appliance demand and price erosion in commodity chips would pull growth down. Regulatory approval of a chip-based breath test or a VOC monitoring duty in a large market is the main upside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 11.3% | USD 1.32 billion | Appliance demand stalls, chip prices fall and clinical pilots fail to reach approval |
| Base | 14.31% | USD 1.67 billion | Modules spread in buildings and devices while diagnostics advance through pilots |
| Upside | 16.8% | USD 2.03 billion | A chip-based breath test gains approval and VOC monitoring becomes mandatory in a large market |
Frequently Asked Questions
How big is the olfactory sensing ASIC market?
Which sensor ASICs are used for odor detection in consumer devices?
Which type leads the olfactory sensing ASIC market?
Which region leads demand for olfactory sensing chips?
Is there demand for olfactory and indoor air sensing in the GCC?
How much does a digital VOC sensor chip cost?
Who are the main suppliers of olfactory sensing chips?
What restrains the olfactory sensing ASIC market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Chemical Sensor-Based Olfactory Chip
- 1.2.2 Electrochemical Sensor-Based Olfactory Chip
- 1.2.3 Biosensor-Based Olfactory Chip
- 1.2.4 Other Types
- 1.3 By Application
- 1.3.1 IoT and Smart Environments
- 1.3.2 Environmental Monitoring
- 1.3.3 Food Industry
- 1.3.4 Medical Industry
- 1.3.5 Security
- 1.3.6 Agriculture
- 1.3.7 Other Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 438.6 million → 2035: USD 1.67 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Olfactory Sensing ASIC Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Olfactory Sensing ASIC Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Olfactory Sensing ASIC Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Olfactory Sensing ASIC Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Olfactory Sensing ASIC Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Olfactory Sensing ASIC Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Olfactory Sensing ASIC Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Olfactory Sensing ASIC Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 438.6 million → 2035: USD 1.67 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Olfactory Sensing ASIC Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Chemical Sensor-Based Olfactory Chip
- 12.3.7.2 Electrochemical Sensor-Based Olfactory Chip
- 12.3.7.3 Biosensor-Based Olfactory Chip
- 12.3.7.4 Other Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 IoT and Smart Environments
- 12.4.7.2 Environmental Monitoring
- 12.4.7.3 Food Industry
- 12.4.7.4 Medical Industry
- 12.4.7.5 Security
- 12.4.7.6 Agriculture
- 12.4.7.7 Other Applications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Olfactory Sensing ASIC End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Olfactory Sensing ASIC Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Olfactory Sensing ASIC Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Olfactory Sensing ASIC Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Robert Bosch GmbH (Bosch Sensortec)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sensirion AG
- 18.4 Renesas Electronics Corporation
- 18.5 ScioSense B.V.
- 18.6 New Cosmos Electric Co., Ltd. (Figaro Engineering)
- 18.7 Aryballe
- 18.8 Ainos, Inc.
- 18.9 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

