
Market Overview:
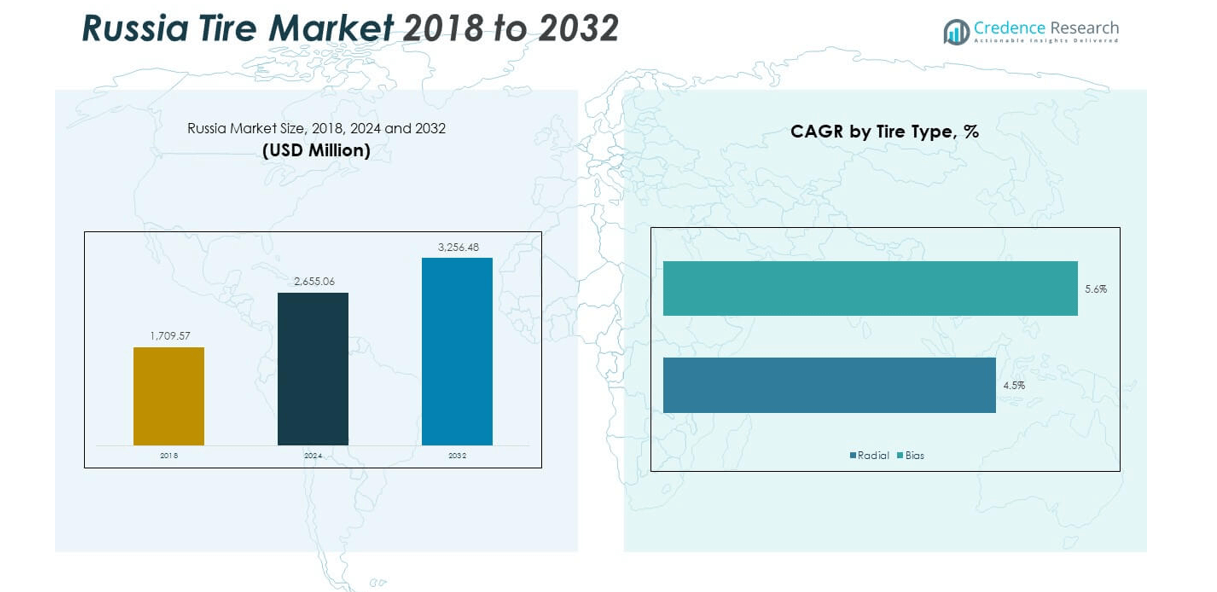
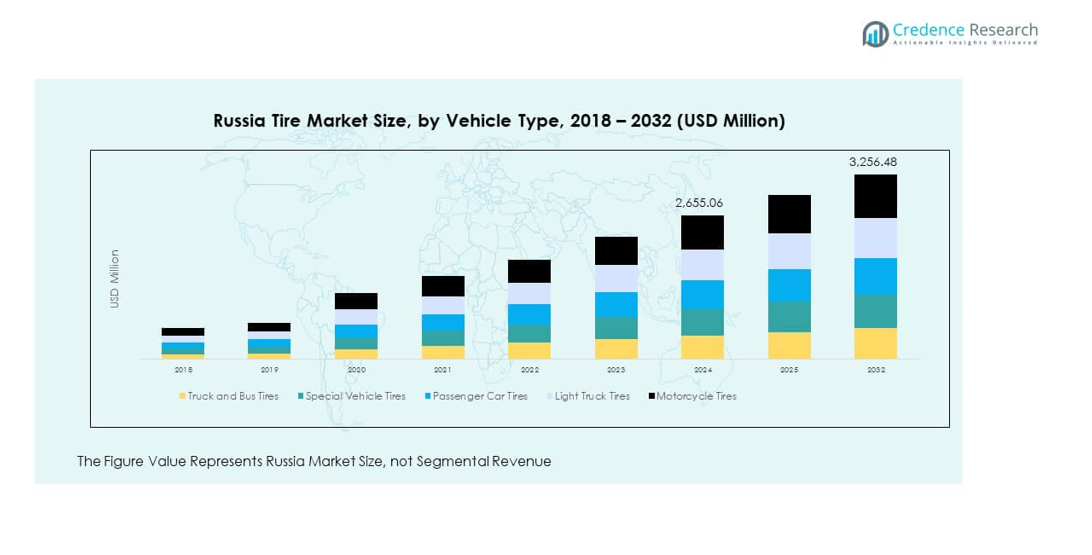
The Russia Tire Market size was valued at USD 1,709.57 million in 2018 to USD 2,655.06 million in 2024 and is anticipated to reach USD 3,256.48 million by 2032, at a CAGR of 2.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Russia Tire Market Size 2024 | USD 2,655.06 million |
| Russia Tire Market, CAGR | 2.59% |
| Russia Tire Market Size 2032 | USD 3,256.48 million |
The Russia Tire Market is driven by steady vehicle ownership growth, rising replacement cycles, and strong demand for winter tires. Expanding road infrastructure and industrial development create consistent need for commercial and heavy-duty vehicle tires. Consumers increasingly prefer advanced radial and tubeless designs that enhance performance, safety, and fuel efficiency. Strict safety regulations and mandatory winter tire usage further accelerate demand. It also benefits from e-commerce expansion, which strengthens product accessibility across urban and rural areas. Manufacturers focus on product innovation and localized production to capture market share.
Western Russia remains the leading region due to high population density, modern infrastructure, and strong consumer purchasing power. Moscow and St. Petersburg dominate with large fleets of passenger and commercial vehicles, supported by organized dealership networks. Central Russia holds a strong share, with industrial hubs and logistics driving truck and bus tire demand. Eastern Russia emerges gradually, supported by infrastructure projects, resource exploration, and seasonal tire replacement requirements. It holds strong potential for long-term growth as distribution networks improve and consumer demand diversifies across rural and urban centers.
Market Insights
- The Russia Tire Market size was USD 1,709.57 million in 2018, reached USD 2,655.06 million in 2024, and is projected to hit USD 3,256.48 million by 2032, growing at a CAGR of 2.59%.
- Western Russia held the largest share at 42% in 2024, driven by higher vehicle density and strong purchasing power. Central Russia followed with 35%, supported by industrial hubs and logistics activity. Eastern Russia contributed 23%, reflecting infrastructure expansion and mining operations.
- Eastern Russia is the fastest-growing region with 23% share, supported by trade routes, construction projects, and resource-driven industries that demand specialized tires.
- Passenger car tires held the largest segment share at 46% in 2024, supported by high ownership rates and frequent replacement cycles.
- Truck and bus tires accounted for 27% share, fueled by logistics, freight transport, and heavy construction demand across industrial corridors.
Market Drivers
Rising Vehicle Ownership and Expanding Replacement Demand
The Russia Tire Market is strongly influenced by the steady increase in vehicle ownership. More households purchase cars, raising demand for both new and replacement tires. It benefits from growing disposable income in urban regions where personal mobility is a priority. Higher replacement cycles boost sales, especially for winter tires that wear quickly under severe conditions. Passenger vehicle growth is a consistent driver, supported by financing and dealership promotions. Commercial fleet operators also contribute, replacing tires regularly to ensure safety standards. The replacement segment forms a large portion of the market’s revenue base. Strong consumer awareness of tire performance and safety sustains steady product turnover.
- For example, Cordiant introduced the Polar SL winter tire with its two-component SMART-MIX compound, designed to enhance grip on ice and snow by 7% compared with previous models (Cordiant official product description).
Infrastructure Development and Expansion of Commercial Transport Networks
Infrastructure development across Russia is shaping demand for commercial and heavy-duty tires. Road construction projects expand long-distance freight networks, increasing stress on logistics vehicles. It creates higher consumption of durable and specialized truck tires suited for rough terrains. Government focus on modernizing highways and intercity transport corridors adds to sustained demand. Mining and construction activities in remote regions also elevate tire requirements for heavy equipment. The Russia Tire Market benefits from reliable demand generated by industrial expansion. Transport companies aim for tires that improve fuel efficiency and reduce downtime. The commercial vehicle fleet continues to expand, reinforcing long-term growth in the tire sector.
Technological Advancement in Tire Manufacturing and Product Innovation
Tire manufacturers introduce advanced designs that strengthen traction, durability, and fuel efficiency. The Russia Tire Market experiences demand for radial and tubeless tires that enhance performance. Consumers prefer tires with improved safety features, particularly in icy and wet conditions. It drives producers to focus on tread patterns and advanced rubber compounds. Local manufacturing bases collaborate with global players to integrate modern production technologies. Advanced testing facilities allow companies to validate performance under extreme weather. Higher adoption of smart tires with embedded sensors signals a shift toward connected mobility. Consumers adopt such products for monitoring tire health and preventing accidents. Tire innovations help improve customer satisfaction and brand loyalty.
- For instance, Bridgestone’s Ecopia ENLITEN range, launched in November 2023, delivers a 12% reduction in rolling resistance for truck drive axles and 8% for steer axles compared to the previous Ecopia generation, boosting fuel efficiency for commercial fleets.
Regulatory Influence and Focus on Road Safety Standards
Government regulations on vehicle safety encourage consistent tire replacements. The Russia Tire Market gains from rules enforcing winter tire usage during harsh months. Road safety campaigns raise awareness about the role of tire performance in accident prevention. Consumers respond by purchasing quality products certified under local and international standards. It strengthens the position of companies offering reliable safety-compliant tires. Import restrictions on certain categories also stimulate domestic production and sourcing. Policy frameworks promote innovation in environmentally sustainable tire designs. Strict compliance pressures ensure that producers continuously adapt to evolving market regulations. The regulatory framework aligns consumer behavior with safer tire adoption.
Market Trends
Growing Adoption of Winter-Specific and All-Season Tire Solutions
Consumer preference is shifting toward winter-specific and all-season tires. The Russia Tire Market reflects strong demand in regions with prolonged cold seasons. It shows growth in specialized tires offering grip and safety in snow. Global and domestic producers target urban and rural markets with seasonal variants. Consumers increasingly value safety and adaptability over low-cost alternatives. Fleet operators purchase winter tires in bulk to meet compliance standards. Availability of premium tread compounds ensures steady adoption of innovative solutions. Seasonal patterns of demand make winter and all-season products key growth drivers for suppliers.
- For instance, Nokian Tyres captured a 19% share of studded winter tire sales on Avito in Russia in September 2024 more than double Pirelli’s 8% highlighting its advanced grip and winter technology performance favored by Russian consumers.
Increasing Popularity of Online Retail Channels for Tire Purchases
The retail landscape is changing with the growth of online tire sales. The Russia Tire Market is supported by digital platforms offering a wide range of models. Consumers use online tools to compare performance, price, and warranty options. It allows easy scheduling of installation services through integrated dealer networks. E-commerce growth ensures wider product accessibility, especially outside urban centers. Price transparency drives competition, encouraging manufacturers to enhance product visibility. Digital promotions increase consumer trust and adoption of premium brands. Rising internet penetration across regions enhances the long-term potential of online tire distribution.
Emphasis on Sustainable Tire Manufacturing and Eco-Friendly Materials
Tire producers are investing in sustainable designs and raw materials. The Russia Tire Market reflects rising demand for eco-friendly products. It leads to development of tires with reduced rolling resistance and recyclable content. Regulations push manufacturers to minimize carbon emissions in production. Consumers show preference for brands highlighting environmental responsibility. Global firms share expertise in integrating renewable materials into manufacturing processes. Domestic companies adapt to eco-driven preferences by innovating designs. A strong focus on sustainability sets a long-term trend shaping consumer and producer strategies.
- For instance, EcoStar Factory LLC opened the largest tire recycling facility in Russia’s Far East near Vladivostok in June 2024, with an annual capacity to recycle up to 10,000 tonnes of end-of-life tires into rubber crumb, demonstrating significant progress in regional tire recycling infrastructure.
Adoption of Smart Tire Technologies and Connected Mobility Solutions
Smart tire technologies are gaining attention in commercial and passenger segments. The Russia Tire Market benefits from the rise of digital monitoring solutions. It improves safety through sensors that track tire pressure and tread wear. Fleet operators adopt smart tires to reduce downtime and increase efficiency. Automakers integrate connected tires into new vehicle models, enhancing performance and control. Consumers embrace advanced technology for real-time monitoring of driving safety. Manufacturers collaborate with tech firms to deliver embedded sensor solutions. Smart tires mark the beginning of a trend aligning the market with intelligent mobility systems.
Market Challenges Analysis
Geopolitical Tensions and Supply Chain Disruptions Impacting Market Stability
The Russia Tire Market faces challenges linked to geopolitical conditions and trade restrictions. Sanctions and import limitations disrupt supply chains, affecting raw material availability. It pushes manufacturers to rely on local suppliers, raising production costs. Foreign investment in tire production declines due to political uncertainties. Logistics networks experience volatility, delaying distribution schedules. Small-scale producers find it difficult to compete with established players. Dependence on external machinery and technologies creates risks of operational inefficiency. These challenges make stability and consistent supply a pressing concern for the industry.
Intense Competition and Price Pressure Affecting Profit Margins
High competition among domestic and international tire manufacturers creates pricing pressure. The Russia Tire Market sees new entrants offering budget-friendly alternatives to established brands. It forces companies to cut costs while sustaining quality. Premium tire brands face difficulty in convincing consumers to pay higher prices. Rising material and energy costs strain margins further. Producers seek to differentiate through innovation, yet consumers remain highly price-sensitive. Smaller firms lack the capacity to invest in research or advanced facilities. Competition creates a market environment where profit margins remain under pressure.
Market Opportunities
Expansion of Local Manufacturing and Strengthening of Domestic Capabilities
Investment in domestic production offers strong opportunities for the Russia Tire Market. It reduces reliance on imports and improves supply chain resilience. Companies expand factories to meet rising demand for passenger and commercial vehicle tires. Modernization of facilities with automation enhances efficiency and cost competitiveness. Local producers strengthen partnerships with international firms for knowledge transfer. Government support in terms of subsidies encourages capacity expansion. Tire manufacturers that invest in regional hubs secure better access to emerging markets. Domestic expansion opens pathways for sustainable long-term growth in the sector.
Innovation in Premium and Specialized Tire Segments for Long-Term Growth
Demand for premium and specialized tires creates space for innovation. The Russia Tire Market benefits from consumer preference for safety, performance, and durability. It pushes companies to focus on advanced winter tires, eco-friendly options, and smart solutions. Premium brands differentiate themselves by highlighting unique performance features. Niche segments like off-road and heavy-duty equipment tires present growth opportunities. Collaboration with automotive manufacturers strengthens innovation pipelines. Companies offering specialized products build strong consumer trust and higher brand recognition. Premiumization offers a route for sustainable revenue growth in a competitive environment.
Market Segmentation Analysis
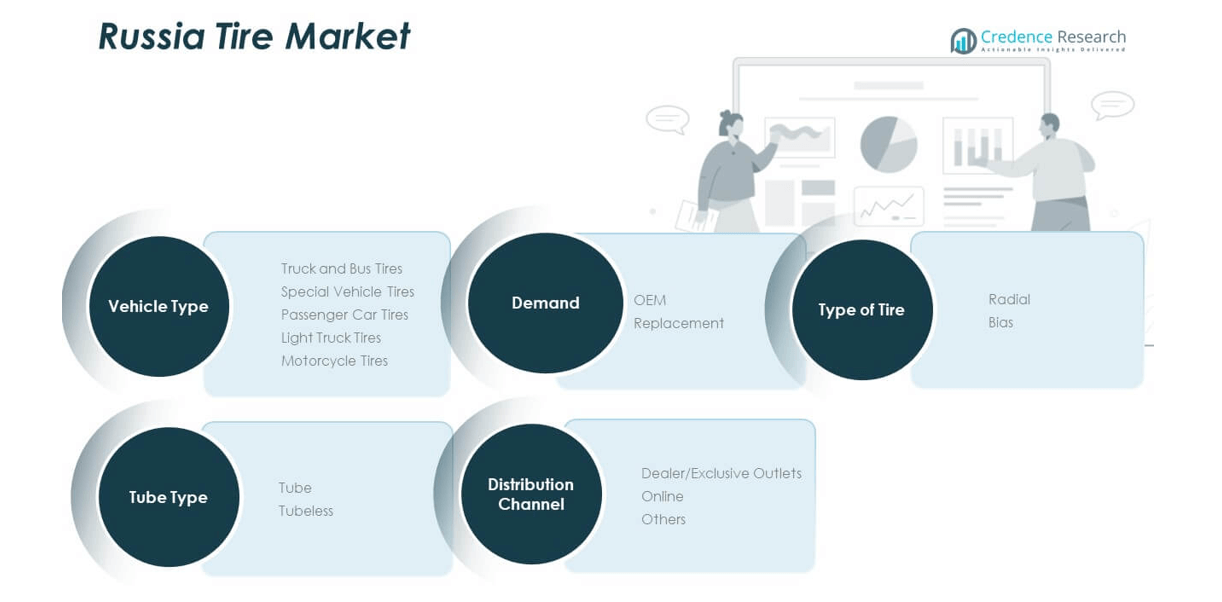
By vehicle type, passenger car tires dominate the Russia Tire Market, supported by high ownership rates and frequent replacement cycles. Truck and bus tires form the next significant category, driven by logistics, freight transport, and construction activities. Light truck tires gain momentum through rising demand for small commercial vehicles, while motorcycle tires remain niche with steady adoption. Special vehicle tires serve industries like mining and agriculture, creating consistent demand for durable and heavy-duty designs.
- For example, Nokian Tyres launched the Hakkapeliitta R5 in 2022, featuring a tread design that shortens braking distance on ice by up to 6 metres (0–80 km/h) compared to its predecessor, with an overall 4% improvement in winter performance.
By demand, the replacement segment leads the market, reflecting the country’s harsh climate and seasonal need for winter tires. It generates recurring sales as consumers replace worn products more frequently. OEM demand remains stable, supported by ongoing automotive manufacturing and assembly operations in domestic plants. Vehicle production levels influence this segment’s performance but replacement maintains dominance due to established cycles.
By type of tires, radial tires hold the majority share, driven by superior performance, fuel efficiency, and safety. Bias tires still find applications in heavy-duty and off-road vehicles where durability under extreme conditions is required.
By tube type, tubeless tires gain preference for passenger and light vehicles because of safety and convenience, while tube tires maintain use in commercial fleets and rural areas.
- For example, Bridgestone Americas launched the W920 tire in August 2025, built with next-generation ENLITEN technology to provide extended wear life and improved traction for commercial fleet trucks, replacing the previous W919 model.
By distribution channel, dealer and exclusive outlets dominate through established networks offering reliability and service. Online channels expand steadily, offering convenience, price comparison, and wider product access. Other channels include retail partnerships in regional markets, ensuring broader accessibility to diverse consumer groups.
Segmentation
By Vehicle Type
- Truck and Bus Tires
- Special Vehicle Tires
- Passenger Car Tires
- Light Truck Tires
- Motorcycle Tires
By Demand
- OEM (Original Equipment Manufacturer)
- Replacement
By Type of Tires
- Radial
- Bias
By Tube Type
- Tube
- Tubeless
By Distribution Channel
- Dealer/Exclusive Outlets
- Online
- Others
Regional Analysis
Western Russia holds the largest share of the Russia Tire Market, accounting for 42%. The region benefits from higher population density, advanced infrastructure, and strong vehicle ownership. Moscow and St. Petersburg remain the main hubs of demand, with passenger and commercial segments driving sales. Strong economic activity in these cities ensures steady replacement demand. It maintains dominance through high purchasing power and strong dealership networks. Global tire manufacturers prioritize this region for premium and mid-range product lines.
Central Russia captures 35% of the market, supported by industrial hubs and logistics operations. The segment grows on the back of road freight and heavy-duty vehicle activity. OEM demand remains stable with automobile plants located in key cities. Tire sales are influenced by strong activity in mining and manufacturing sectors. It also benefits from replacement cycles in both passenger and commercial categories. Consumers in these regions value durable and cost-effective tire solutions. Central Russia continues to strengthen its market base by balancing industrial and consumer demand.
Eastern Russia contributes 23% share, with rising activity in trade, resource exploration, and infrastructure expansion. The vast geography requires specialized tires for heavy vehicles, particularly in construction and mining. Demand is also supported by growing mobility in regional cities. It shows strong opportunities for growth as infrastructure projects increase. Seasonal tire demand remains high due to extreme climatic conditions. Distribution networks are less developed, but digital platforms expand accessibility. Eastern Russia is gradually emerging as a high-potential growth corridor.
Key Player Analysis
- Goodyear Dunlop Tires
- Kumho
- Nokian
- Michelin
- Continental
- Bridgestone
- Pirelli
- Hankook
Competitive Analysis
The Russia Tire Market features strong competition between global and domestic players. Leading companies such as Michelin, Bridgestone, Continental, and Pirelli maintain a solid presence by offering premium and mid-range solutions. Domestic producers and regional brands compete aggressively in price-sensitive segments, targeting replacement demand. It benefits from consumer diversity, where some prioritize safety and performance while others seek affordability. Global players leverage advanced technologies, eco-friendly materials, and smart tire innovations to maintain their edge. Local manufacturers, however, respond by expanding production capacity and improving distribution networks. Strong competition pushes companies to strengthen after-sales services and warranty offerings. The market structure remains fragmented, with both established leaders and niche specialists competing for share. Tire manufacturers focus on building customer loyalty and expanding into underserved regions. Competitive intensity ensures innovation and cost optimization stay central to growth strategies.
Recent Developments
- In March 2025, JSC Cordiant launched commercial tire production at the former Bridgestone facility in Ulyanovsk, Russia, following the acquisition of the plant after Bridgestone's exit from the country. This restart allows the renamed Gislaved Ulyanovsk factory to deliver up to 2.4 million passenger vehicle tires annually, boosting Cordiant’s ability to meet the rising domestic demand and stabilizing the Russian tire market during a period of significant transition.
- In June 2024, Ecostar Factory opened a second facility in Vladivostok, aiming to recycle more than 10,000 tonnes of end-of-life tires per year and tripling its capacity in five years. This expansion, with a total investment of USD 500,000, highlights Russia’s growing emphasis on sustainability and the burgeoning demand for eco-friendly and retreaded tires within the market.
- In March 2023, Nokian Tyres completed the sale of its Russian operations to Tatneft PJSC, fully exiting the market and transferring all local personnel to the new owner. The company has since increased capacity at its Finnish and U.S. factories and invested €650 million in new zero-carbon supply capability to strengthen its European supply network.
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, Demand, Type of Tires, Tube Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Russia Tire Market will witness steady growth supported by passenger and commercial vehicle expansion.
- Seasonal demand for winter and all-season tires will remain a consistent driver of replacement sales.
- Local manufacturing will strengthen as producers reduce reliance on imports and build resilience.
- Premium tire adoption will increase, driven by urban consumers prioritizing safety and performance.
- Online retail channels will expand reach, offering competitive prices and wider product accessibility.
- Technological integration such as smart tire sensors will gain traction among fleets and high-end consumers.
- Sustainability initiatives will shape product development, with eco-friendly designs gaining broader acceptance.
- Competition will intensify, pushing companies to focus on after-sales service and brand loyalty.
- Regional expansion into eastern territories will create long-term opportunities through infrastructure projects.
- Innovation in specialized categories such as off-road and heavy-duty equipment tires will enhance growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Vehicle Ownership and Replacement Demand
Increasing car ownership and higher disposable incomes in urban Russia are driving demand for both new and replacement tires, especially as harsh winters accelerate tire wear and replacement cycles.
Mandatory Winter Tire Regulations
Strict government regulations requiring winter tire usage during cold months significantly boost seasonal demand, ensuring recurring sales and supporting the replacement segment.
Expansion of Road Infrastructure and Industrial Activity
Ongoing investments in road construction, logistics, and industrial projects across Russia are increasing the need for commercial and heavy-duty vehicle tires, particularly in emerging regions like Eastern Russia.
Technological Advancements and Product Innovation
Consumer preference for advanced radial, tubeless, and smart tire technologies is pushing manufacturers to innovate, offering products with improved safety, fuel efficiency, and performance tailored to Russia’s challenging climate.
Growth of Online Retail and E-Commerce Channels
The expansion of digital sales platforms is making tires more accessible to consumers in both urban and rural areas, increasing market reach and enabling price transparency and convenience.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Russia Tire Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Russia Tire Market projected to grow between 2024 and 2032?
Which Russia Tire Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Russia Tire Market?
Who are the leading companies in the Russia Tire Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Demand
- 1.2.1 OEM (Original Equipment Manufacturer)
- 1.2.2 Replacement
- 1.3 By Vehicle Type
- 1.3.1 Passenger Car Tires
- 1.3.2 Truck and Bus Tires
- 1.3.3 Light Truck Tires
- 1.3.4 Special Vehicle Tires
- 1.3.5 Motorcycle Tires
- 1.4 By Type of Tires
- 1.4.1 Radial
- 1.4.2 Bias
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,655.06 million → 2032: USD 3,256.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Russia Tire Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Russia Tire Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Russia Tire Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Russia Tire Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Russia Tire Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Russia Tire Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Russia Tire Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Russia Tire Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,655.06 million → 2032: USD 3,256.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Russia Tire Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Demand - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 OEM (Original Equipment Manufacturer)
- 12.3.7.2 Replacement
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Car Tires
- 12.4.7.2 Truck and Bus Tires
- 12.4.7.3 Light Truck Tires
- 12.4.7.4 Special Vehicle Tires
- 12.4.7.5 Motorcycle Tires
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Tires - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Radial
- 12.5.7.2 Bias
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Russia Tire Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Russia Tire Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Russia Tire Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Cordiant
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Nokian
- 17.4 Michelin
- 17.5 Continental
- 17.6 Bridgestone
- 17.7 Pirelli
- 17.8 Hankook
- 17.9 Goodyear Dunlop Tires
- 17.10 Kumho
- 17.11 Tatneft
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

