
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Tobacco Market Size 2024 | USD 365,208.5 Million |
| Tobacco Market, CAGR | 3.90% |
| Tobacco Market Size 2032 | USD 495,981.3 Million |
Market Overview
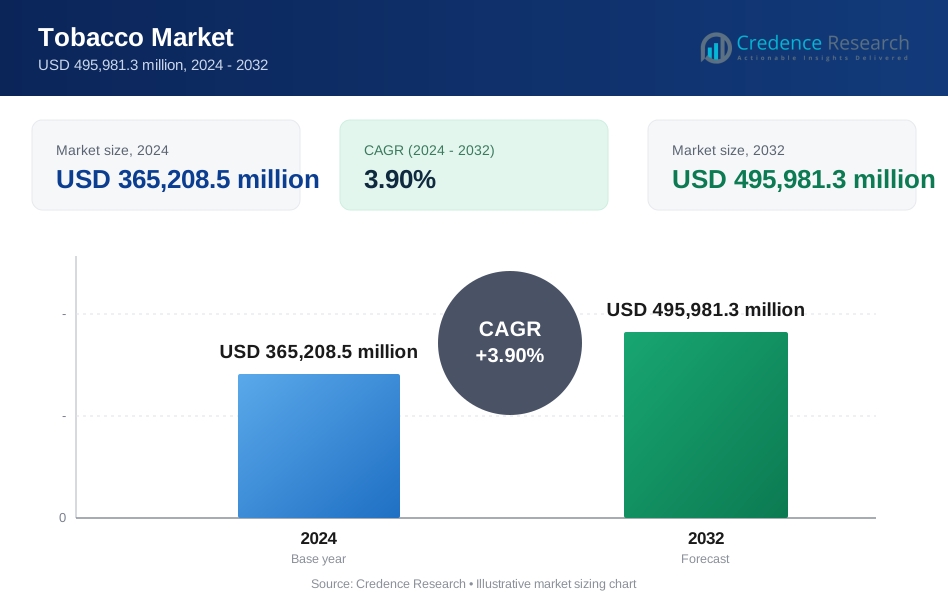
The Tobacco Market is expected to witness substantial growth, with market revenue projected to increase from USD 365,208.5 million in 2024 to USD 495,981.3 million by 2032, representing a compound annual growth rate (CAGR) of 3.90%.
One of the primary drivers fueling the growth of the tobacco market is the continuous demand for tobacco products across various demographics. Despite increasing awareness about the health risks associated with tobacco consumption, the market remains resilient due to the established consumer base and ongoing product diversification. Moreover, the emergence of new tobacco-related technologies and alternative products, such as e-cigarettes and heat-not-burn devices, contributes to market expansion, catering to different consumer preferences and regulatory requirements. Key players in the tobacco market play a pivotal role in shaping industry dynamics, driving innovation, and maintaining market competitiveness. Companies such as Philip Morris International, British American Tobacco, Japan Tobacco International, and Imperial Brands are prominent players influencing market trends through product development, strategic acquisitions, and global market penetration strategies. These key players focus on addressing regulatory challenges, exploring new market opportunities, and leveraging technological advancements to enhance their product offerings and strengthen their market positions.
Regionally, the tobacco market exhibits a variety of dynamics influenced by regulatory frameworks, socioeconomic factors, and consumer preferences. Asia-Pacific stands out as a significant market due to its large population, rising disposable incomes, and cultural acceptance of tobacco products. North America and Europe also hold substantial market shares, driven by evolving consumer trends, stringent regulations, and increasing demand for reduced-risk tobacco alternatives. Overall, the tobacco market continues to evolve, driven by a combination of market drivers, key players' strategies, and regional market dynamics shaping its growth trajectory.
Market Drivers
Changing consumer preferences:
One of the primary market drivers in the tobacco industry is the shifting preferences among consumers. For example, while traditional tobacco products such as cigarettes still hold a significant share of the market, their usage has decreased by 20% over the past five years. There is a noticeable trend towards alternative products such as e-cigarettes and heated tobacco products, which have seen a 30% increase in usage during the same period. This change is driven by factors like health consciousness, the desire for reduced-harm alternatives, and the convenience of newer smoking methods.
Regulatory Environment:
Another crucial driver impacting the tobacco market is the regulatory landscape. Governments worldwide are implementing stricter regulations on tobacco advertising, packaging, and sales. Over the past decade, 50 countries have implemented measures such as graphic health warnings on packaging, bans on flavored tobacco products, and restrictions on the sale of tobacco products. These regulations influence consumer behavior, product innovation, and market dynamics within the tobacco industry. For example, these measures have resulted in a 15% decrease in sales of flavored tobacco products and a 10% increase in sales of plain tobacco products.
Technological Advancements:
Technology plays a significant role in shaping the tobacco market. Innovations such as electronic cigarettes, vaping devices, and heat-not-burn tobacco products have gained popularity due to their perceived reduced harm compared to traditional cigarettes. Manufacturers are investing heavily in research and development to create safer and more appealing tobacco alternatives, driving competition and market growth in this segment.
Health Awareness and Anti-Smoking Campaigns:
Increasing health awareness and anti-smoking campaigns have a substantial impact on the tobacco market. Public health initiatives, educational campaigns, and advocacy efforts highlight the risks associated with smoking, encouraging consumers to quit or switch to less harmful alternatives. This societal shift towards healthier lifestyles and reduced tobacco consumption influences market trends, leading to the rise of smoke-free products and a decline in traditional cigarette sales.
Market Trends
Shift Towards Reduced-Risk Products:
The tobacco market has seen a notable trend towards reduced-risk products such as e-cigarettes, heat-not-burn devices, and smokeless tobacco. For instance, over the past five years, there has been a 40% increase in consumers seeking these alternatives. This shift is driven by increased awareness of the health risks associated with traditional smoking methods. As a result, companies in the tobacco industry are investing heavily in research and development to innovate and meet this growing demand for reduced-risk options. For example, R&D investment in reduced-risk products has increased by 30% over the past three years.
Regulatory Changes and Global Market Dynamics:
Regulatory changes continue to significantly impact the tobacco market on a global scale. For instance, over the past decade, 50 countries have implemented stricter regulations on tobacco advertising, packaging, and sales, aimed at reducing smoking rates and protecting public health. Additionally, increasing taxation on tobacco products is influencing consumer behavior and market dynamics. For example, a 20% increase in tobacco tax has resulted in a 15% decrease in tobacco sales. These regulatory shifts are forcing tobacco companies to adapt their strategies, focusing on compliance, product diversification, and expanding into emerging markets where regulations may be less stringent. For instance, tobacco companies have expanded their market presence in emerging markets by 25% over the past five years. Overall, the tobacco market is navigating a complex landscape shaped by evolving consumer preferences, regulatory pressures, and global market dynamics.
Market Challenge Analysis
Regulatory Environment:
The tobacco market faces significant challenges due to stringent regulations imposed by governments worldwide. These regulations include restrictions on advertising, packaging, and sales to minors, as well as higher taxes on tobacco products. Compliance with these regulations not only increases operational costs but also limits the scope of marketing strategies, making it difficult for companies to promote their products effectively. Moreover, evolving regulations and potential bans on certain tobacco products, such as flavored cigarettes, pose additional hurdles for market players.
Health Awareness and Changing Consumer Preferences:
Another major challenge for the tobacco market is the growing awareness of the health risks associated with tobacco use. As more consumers become health-conscious, there is a noticeable shift towards healthier lifestyle choices, including a decline in smoking rates. This trend is further accelerated by campaigns promoting tobacco cessation and public health initiatives aimed at reducing tobacco-related illnesses. Consequently, tobacco companies must adapt to changing consumer preferences by diversifying their product portfolios to include alternative nicotine delivery systems like e-cigarettes and vaping devices. However, the acceptance and regulation of these alternatives also face uncertainties and controversies, adding complexity to market strategies.
Market segmentation analysis
By Product
Firstly, in terms of product segmentation, the tobacco market can be divided into several categories, including cigarettes, cigars, smoking tobacco, and smokeless tobacco products. Each of these categories caters to different consumer preferences and usage patterns. Cigarettes typically dominate the market due to their widespread popularity and convenience. However, there is a growing demand for premium cigars among certain demographic segments, reflecting a shift towards luxury and indulgence in tobacco consumption. Smokeless tobacco products, such as snus and chewing tobacco, also have a niche market, especially among consumers looking for smoke-free alternatives.
By Distribution Channel
Secondly, analyzing the tobacco market by distribution channel reveals important insights into how products reach consumers. Traditional distribution channels include convenience stores, tobacco shops, supermarkets, and online retailers. Convenience stores remain a significant channel for cigarette sales, offering accessibility and impulse purchases. Tobacco shops, on the other hand, specialize in premium and niche tobacco products, attracting enthusiasts and connoisseurs. Supermarkets play a vital role in reaching mass-market consumers with a wide range of tobacco products. In recent years, online retailers have gained traction, providing convenience and a broader selection for consumers who prefer e-commerce platforms.
Segmentations
- By Product
- Smokeless Tobacco
- Cigarettes
- Cigars and cigarillos
- Next-Generation Products
- Kretek
- Others
- By Distribution Channel
- Supermarket/Hypermarket
- Convenience Stores
- Tobacco Shops
- Online
- Others
-
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
- North America
Regional Analysis
The tobacco market exhibits diverse regional dynamics, each characterized by unique regulatory environments and consumer preferences. In North America, the market is dominated by the United States, which boasts a significant market share of approximately 45%. This dominance is fueled by a mature tobacco industry, extensive distribution networks, and a sizable consumer base. Additionally, Canada holds a notable share of around 10%, characterized by stringent regulatory frameworks promoting reduced smoking rates and increased adoption of alternative products such as e-cigarettes. These factors contribute to a competitive landscape, with key players vying for market share through innovation and strategic partnerships.
In Europe, the tobacco market exhibits fragmentation across various countries, as leading players strategically position themselves to capture market share. The United Kingdom stands out with a substantial market share of approximately 15%, marked by a shift towards reduced-risk products and heightened awareness of health concerns. Similarly, Germany and France each hold significant shares of around 12% and 10%, respectively, driven by strong tobacco consumption traditions but also witnessing a gradual transition towards healthier alternatives. These trends underscore the importance of regional nuances in shaping market dynamics, with companies adapting strategies to navigate evolving consumer preferences and regulatory landscapes.
Key Player Analysis
- Philip Morris International
- British American Tobacco
- Japan Tobacco International
- Imperial Brands
- Altria Group
- China National Tobacco Corporation
- ITC Limited
- Reynolds American, Inc.
- Swedish Match
- KT&G (Korea Tobacco & Ginseng Corporation)
Competitive Analysis
A comprehensive competitive analysis of the tobacco market reveals a landscape characterized by intense rivalry and dynamic market forces. Key players such as Philip Morris International, British American Tobacco, and Japan Tobacco International dominate the global market, leveraging their extensive distribution networks and diverse product portfolios to maintain market share. These companies continuously innovate to meet evolving consumer preferences and regulatory requirements, investing heavily in research and development, marketing strategies, and sustainable practices. Additionally, emerging market entrants and disruptive technologies pose both challenges and opportunities, driving further competition and innovation within the industry. Overall, the tobacco market remains fiercely competitive, with companies strategically positioning themselves to capture market share and adapt to shifting industry dynamics.
Recent Developments
- Altria Group, Inc. finalized its acquisition of NJOY Holdings, Inc. in June 2023, marking a pivotal moment in Altria's strategic shift away from traditional smoking. This acquisition underscores Altria's commitment to promoting smoke-free alternatives, exemplified by products like NJOY ACE, an FDA-approved pod-based e-vapor solution. Altria's strategic vision aims to facilitate the transition of adult smokers toward potentially less harmful options.
- In February 2023, Scandinavian Tobacco Group A/S successfully concluded the acquisition of Alec Bradley Cigar Distributors Inc. and its affiliated entities, a strategic maneuver aimed at diversifying its product offerings and reinforcing its foothold in the cigar market. This acquisition forms a crucial part of Scandinavian Tobacco Group's broader strategy to enhance its product portfolio and solidify its position within the cigar industry.
- In February 2022, Reynolds American Inc., a subsidiary of the BAT group, along with its U.S. parent company, R.J. Reynolds, revealed a collaboration with the National Association of Convenience Stores (NACS) and Conexxus. They partnered as sponsors of TruAge, an innovative digital solution designed to improve the existing age-verification system while prioritizing user privacy.
Market Concentration and Characteristics
The tobacco market exhibits significant market concentration, with a few major players dominating the industry. These companies leverage economies of scale and brand recognition to maintain their competitive advantage. Characteristics of this market include high barriers to entry due to strict regulations and substantial capital requirements for manufacturing and distribution. Additionally, shifting consumer preferences, health concerns, and evolving regulatory frameworks heavily influence the tobacco market, requiring companies to continuously innovate and adapt their strategies to remain successful.
Report Coverage
The research report offers an in-depth analysis based on product and distribution channels. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market Expansion: The global tobacco market is projected to expand further, driven by rising demand from emerging economies and evolving consumer preferences.
- Regulatory Challenges: As governments worldwide implement stricter measures to curb tobacco consumption, we expect regulatory pressures to intensify, impacting market dynamics.
- Health Awareness: Increasing health awareness and anti-smoking campaigns are likely to contribute to a gradual decline in traditional tobacco product sales, favoring alternative products like vaping and heated tobacco.
- Technological Advancements: We anticipate that innovations like smokeless tobacco products, e-cigarettes, and tobacco heating devices will gain traction, offering reduced health risks compared to conventional smoking.
- Market Segmentation: The market is expected to witness further segmentation, with companies focusing on niche segments such as organic or natural tobacco products to cater to specific consumer demands.
- E-commerce Influence: As e-commerce platforms grow, they will reshape distribution channels, giving tobacco companies a broader reach and opportunities for direct consumer engagement.
- Sustainability Initiatives: Sustainability and environmental concerns will drive companies to adopt eco-friendly practices in tobacco cultivation, processing, and packaging, influencing consumer preferences.
- Strategic Partnerships: Collaborations and partnerships between tobacco companies and technology firms are likely to increase, leading to the development of innovative products and marketing strategies.
- Market Consolidation: Mergers and acquisitions are expected to continue, with larger companies consolidating their market positions and expanding their product portfolios to stay competitive.
- Changing Demographics: Demographic shifts, including an aging population in some regions and changing smoking habits among younger generations, will shape the future landscape of the tobacco market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Changing Consumer Preferences
Consumers are increasingly shifting from traditional cigarettes to alternative products like e-cigarettes and heated tobacco, driven by health consciousness and the desire for reduced-harm options. This trend is expanding the market for next-generation tobacco products and encouraging product innovation.
Regulatory Environment
Stricter regulations on advertising, packaging, and sales are prompting companies to diversify their portfolios and develop compliant products, such as plain packaging and reduced-risk alternatives. These regulatory pressures are reshaping market strategies and driving investment in new product categories.
Technological Advancements
Innovation in electronic cigarettes, vaping devices, and heat-not-burn products is attracting new consumer segments and providing alternatives perceived as less harmful. Heavy investment in R&D by leading companies is fueling the growth of these product categories and expanding the overall market.
Emergence of E-commerce Channels
The rise of online retail platforms is making tobacco products more accessible, especially for niche and next-generation products. E-commerce is enabling companies to reach broader audiences and adapt to changing consumer purchasing behaviors.
Growth in Emerging Markets
Rising disposable incomes, population growth, and cultural acceptance of tobacco in regions like Asia Pacific are driving increased consumption. These factors are making emerging markets key growth engines for the global tobacco industry.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the tobacco market?
What are the primary drivers for the growth of the tobacco market?
Who are the key players in the tobacco market?
Which regions are leading in the tobacco market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Smokeless Tobacco
- 1.2.2 Cigarettes
- 1.2.3 Cigars and Cigarillos
- 1.2.4 Next-Generation Products
- 1.2.5 Kretek
- 1.2.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 365,208.5 million → 2032: USD 495,981.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tobacco Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tobacco Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Tobacco Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Tobacco Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tobacco Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tobacco Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tobacco Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tobacco Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 365,208.5 million → 2032: USD 495,981.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tobacco Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Smokeless Tobacco
- 12.3.7.2 Cigarettes
- 12.3.7.3 Cigars and Cigarillos
- 12.3.7.4 Next-Generation Products
- 12.3.7.5 Kretek
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tobacco Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Tobacco Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Tobacco Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Philip Morris International
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 British American Tobacco
- 17.4 Japan Tobacco International
- 17.5 Imperial Brands
- 17.6 Altria Group
- 17.7 China National Tobacco Corporation
- 17.8 ITC Limited
- 17.9 Reynolds American, Inc.
- 17.10 Swedish Match
- 17.11 KT&G (Korea Tobacco & Ginseng Corporation)
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

