
Chronic ulcers and home therapy reshape wound treatment
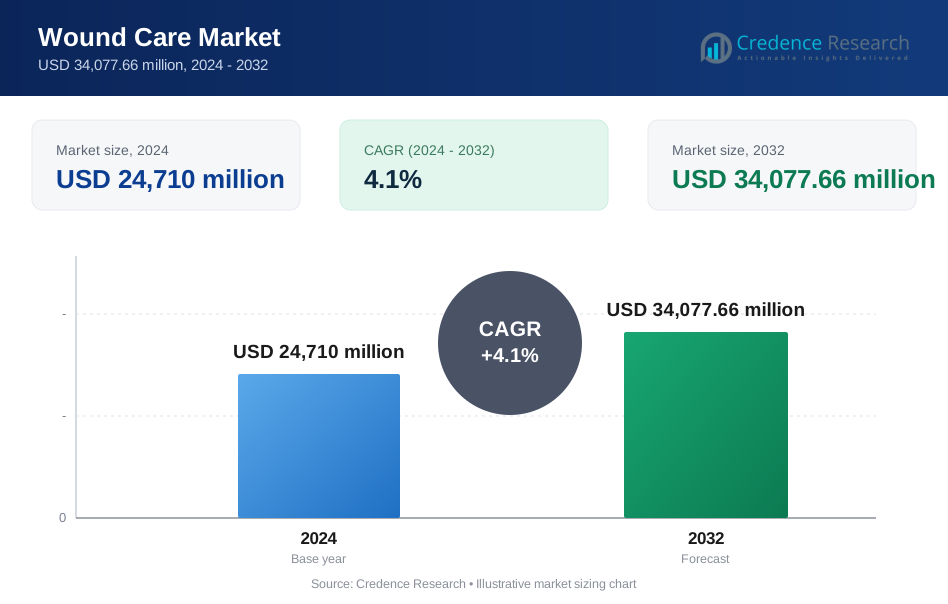
The global wound care products market was valued at USD 27.57 billion in 2025 and is projected to increase from USD 28.91 billion in 2026 to USD 44.25 billion by 2035, registering a CAGR of 4.84% during 2026–2035. Demand comes from people living with diabetic, pressure and venous leg ulcers, from rising surgical volumes and from older patients who need long courses of dressings at home. North America held the largest regional share, 38.0% in 2025, because U.S. hospitals and home health agencies treat chronic wounds at high volume and use premium dressings and negative pressure systems. Asia Pacific is the fastest-growing region at 6.1% a year, as China, India and Southeast Asian countries widen hospital access and diabetes screening. A major commercial change arrived in January 2026, when Medicare began paying for skin substitutes as supplies at a flat rate. As a result, suppliers of biological products now compete more on price and clinical evidence.
Which dressings, devices and biologics does this analysis cover?
The analysis counts antimicrobial, alginate, foam and hydrocolloid dressings, traditional gauze, bandages and tapes, negative pressure systems and their dressing kits, biological skin equivalents and growth factor products. Values are based on manufacturer selling prices to hospitals, clinics, home health providers and distributors across each region.
Surgical sutures, staplers, ostomy appliances and compression garments sold on their own sit outside the scope of this analysis. The value chain runs from fiber, foam and tissue suppliers through dressing makers and distributors to hospitals, wound clinics, nursing homes and patients treated at home.
Wound Care Products Market Insights
- The wound care products market grows from USD 27.57 billion in 2025 to USD 44.25 billion by 2035, a 4.84% CAGR as chronic ulcers and home-based therapy expand.
- North America held 38.0% of global wound treatment value in 2025, supported by high chronic wound volumes and wide use of premium dressings.
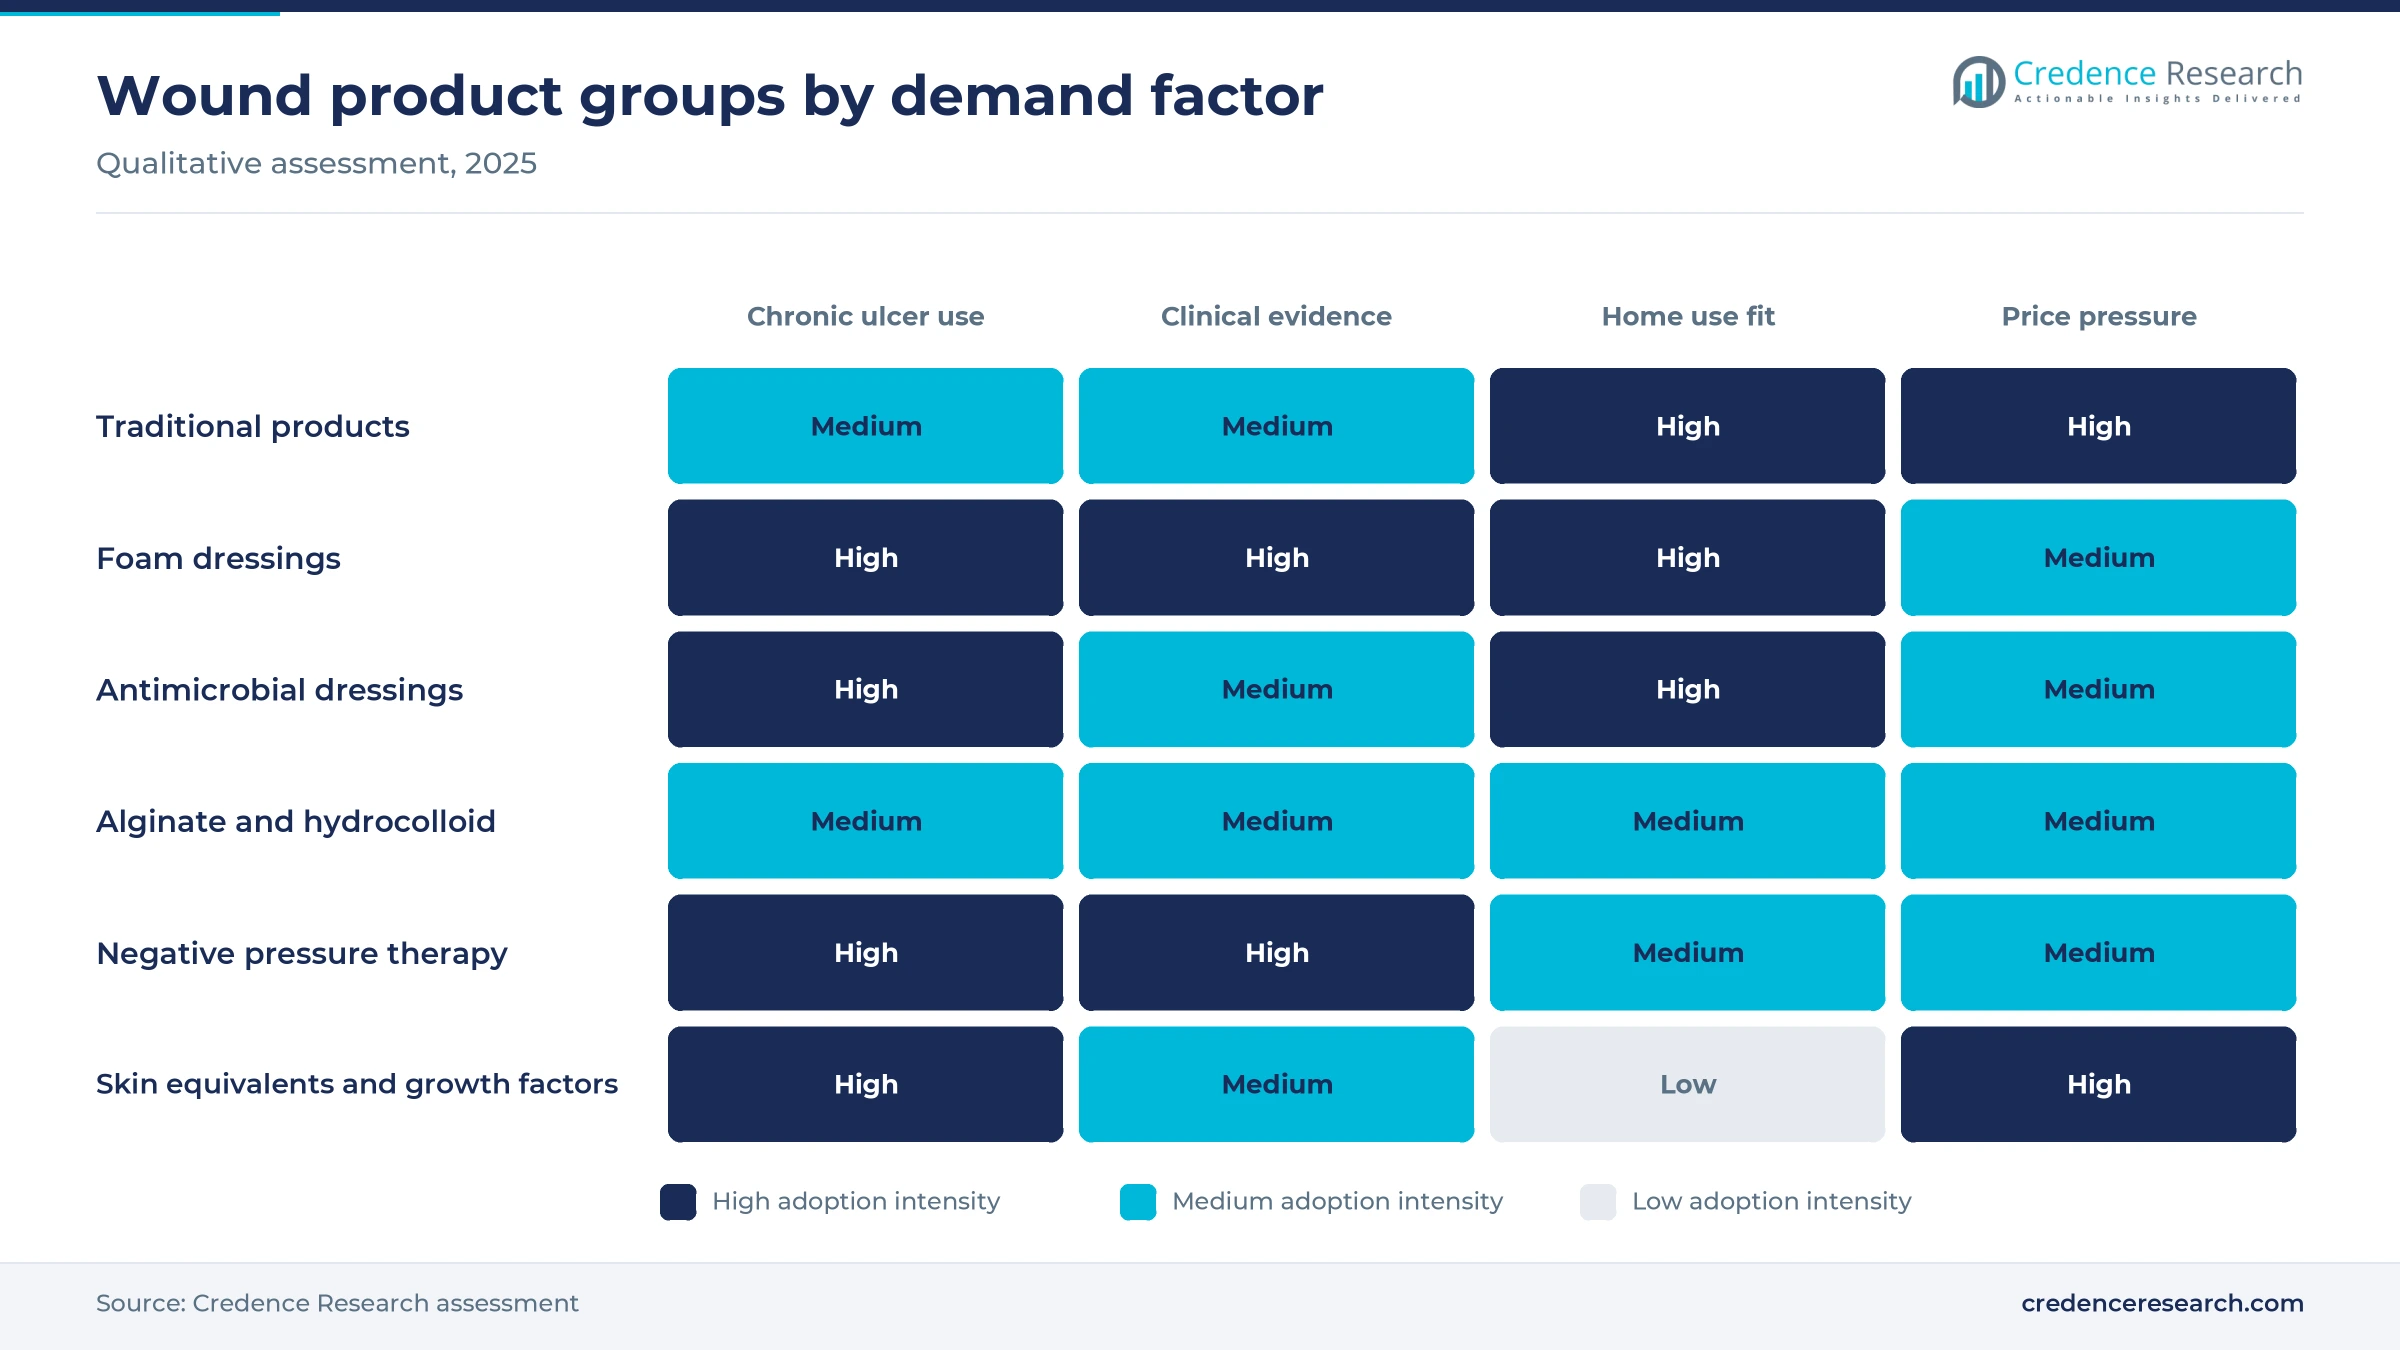
- Traditional wound care products led with 24.0% of 2025 value, while negative pressure wound therapy grows fastest among products at 5.9% a year.
- On Oct. 31, 2025, CMS said Medicare Part B spending on skin substitutes rose from USD 256 million in 2019 to over USD 10 billion in 2024.
- In December 2025, Solventum acquired Acera Surgical, and in October 2026 it gained FDA clearance to combine the Restrata matrix with V.A.C. Therapy.
Traditional dressings lead as suction therapy grows fastest
Why do traditional dressings still lead product spending?
Based on product, the market is categorized into antimicrobial, alginate, foam and hydrocolloid dressings, traditional wound care products, negative pressure wound therapy, biological skin equivalents, growth factors and others. Traditional Wound Care Products led with 24.0% of 2025 value, because gauze, bandages and tapes are used on almost every wound. Negative Pressure Wound Therapy grows fastest at 5.9% a year, as portable systems move into home settings. Foam and antimicrobial dressings gain steadily in chronic ulcers treated in clinics and at home.
Why do diabetic ulcers lead applications?
Based on application, the market is categorized into diabetic ulcers, pressure ulcers, venous leg ulcers, surgical wounds and others. Diabetic Ulcers led with 30.0% of 2025 value and also grow fastest at 5.4% a year, because diabetes cases keep rising worldwide. Surgical wounds form a close second, as operations rise with aging populations. Pressure and venous ulcers add steady demand among older adults with limited mobility.
Why do homecare settings grow fastest among end users?
Based on end user, the market is categorized into hospitals, clinics, homecare settings and others. Hospitals led with 50.0% of 2025 value, because surgical wounds and complex ulcers are treated in inpatient wards. Homecare Settings grow fastest at 6.1% a year, as payers shift long courses of treatment out of hospitals. Clinics add demand for follow-up visits and outpatient grafting procedures.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Traditional Wound Care Products | 24.0% | Negative Pressure Wound Therapy | 5.9% |
| By Application | Diabetic Ulcers | 30.0% | Diabetic Ulcers | 5.4% |
| By End User | Hospitals | 50.0% | Homecare Settings | 6.1% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Diabetes, aging and portable therapy lift dressing demand
How does the rise in diabetes lift demand for ulcer treatment?
Foot ulcers are among the most common and costly complications of diabetes, so rising case numbers raise spending on dressings and advanced therapies. The World Health Organization reported in November 2024 that more than 800 million adults live with diabetes and that adult prevalence doubled from 7% to 14% between 1990 and 2022. WHO also found that about 59% of adults with diabetes aged 30 and older remained untreated in 2022, which raises the risk of slow-healing foot wounds. The International Diabetes Federation estimated in April 2025 that adult cases will reach 853 million by 2050. As a result, diabetic ulcers lead applications with 30.0% of 2025 value, and demand for diabetic foot ulcer treatment keeps rising in clinics and hospitals.
Why do chronic wounds in older adults keep U.S. spending high?
Long healing times in elderly patients mean repeated dressing changes and specialist visits, which keeps chronic wound spending high in North America. Smith+Nephew, citing Medicare data, stated in April 2024 that chronic wounds affect some 8.2 million people in the United States. The same release put the annual U.S. financial burden of chronic wounds at an estimated USD 33 billion. The Centers for Disease Control and Prevention estimated that 40.1 million people in the United States had diagnosed or undiagnosed diabetes in 2023. In turn, North America leads regional spending, as hospitals, clinics and home health agencies treat pressure, venous and diabetic ulcers at high volume.
How do portable negative pressure systems move therapy home?
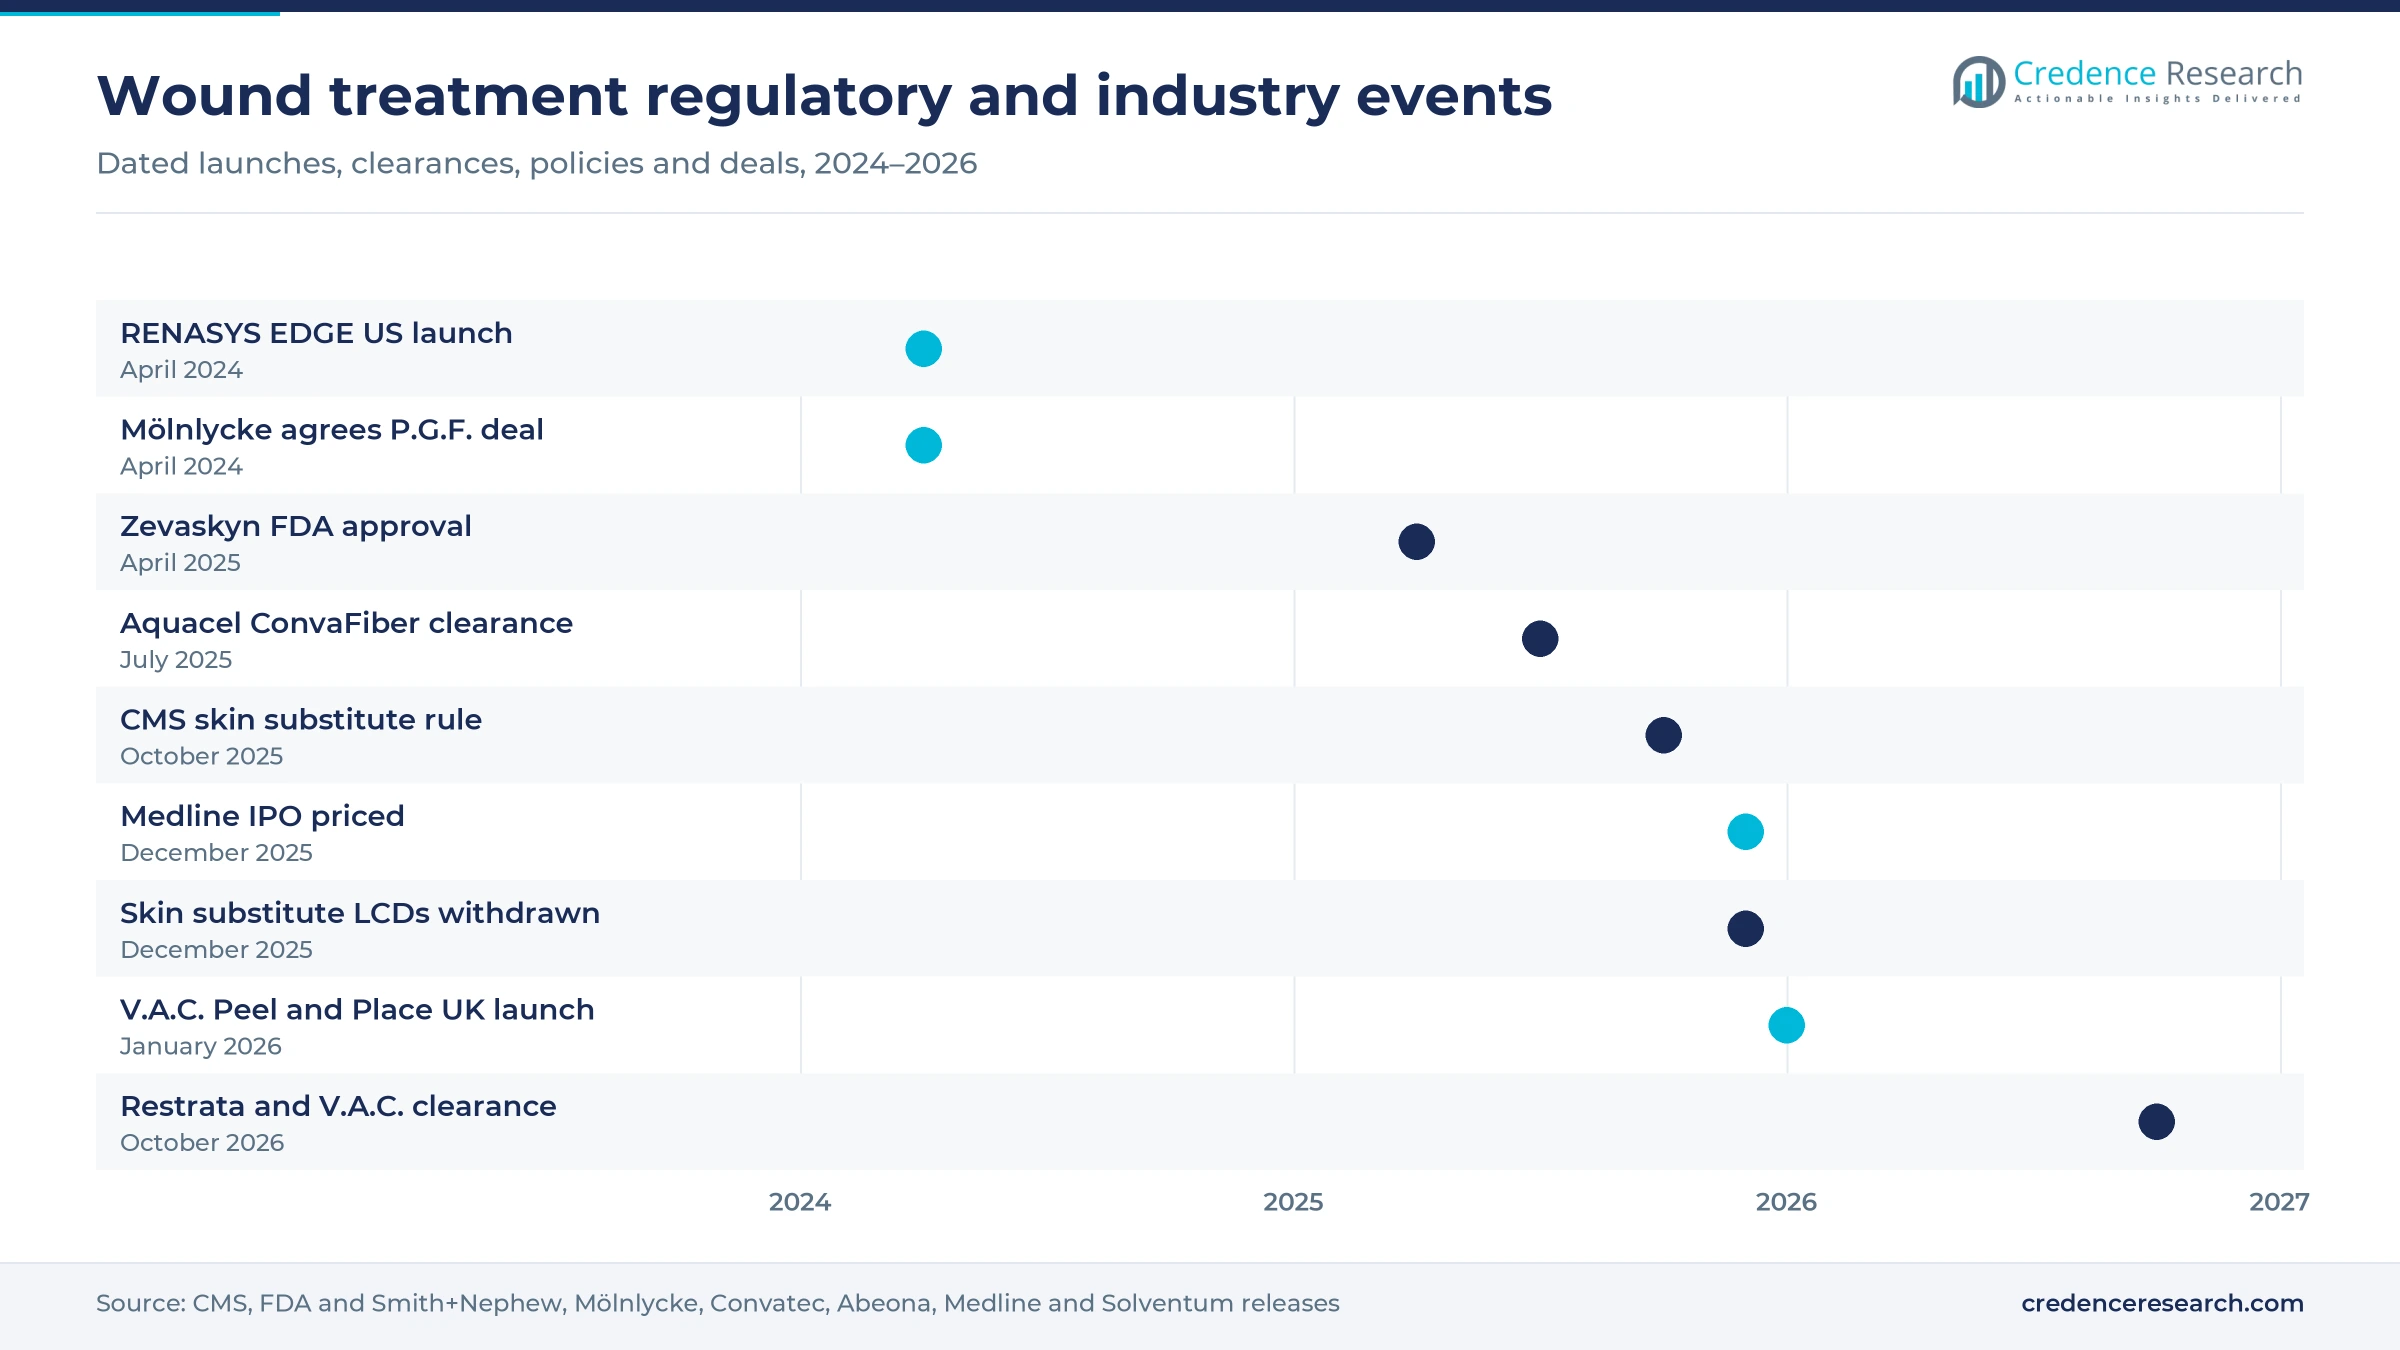
Patients can now receive suction-based therapy at home while keeping up their daily routines, so compact negative pressure systems lift demand outside hospitals. On April 1, 2024, Smith+Nephew launched its RENASYS EDGE system in the United States as a compact option for patients with chronic wounds who live at home. On Jan. 6, 2026, Solventum introduced its all-in-one Peel and Place dressing in the United Kingdom, with wear time of up to seven days. In a simulated test, users applied it in 1 minute 48 seconds, against four minutes 40 seconds for a traditional foam and drape setup. As a result, negative pressure wound therapy grows fastest among products at 5.9% a year, and negative pressure therapy reaches more patients at home.
Why do broad supply networks widen access to modern dressings?
Hospitals and home health agencies buy dressings alongside other everyday medical goods, so large distributors widen access to modern products. Medline priced its Nasdaq initial public offering at USD 29 per share on Dec. 16, 2025, and described itself as operating in more than 100 countries with over 43,000 employees. On April 12, 2024, Mölnlycke agreed to acquire P.G.F. Industry Solutions, the Austrian maker of Granudacyn wound cleansing solutions. Mölnlycke already distributed Granudacyn in more than 50 countries, so the deal secures supply for a widely used cleansing range. In turn, homecare settings grow fastest among end users at 6.1% a year, as home health services receive steady deliveries of dressings and cleansers.
Medicare reform and combined therapies change buying
How is Medicare payment reform shifting skin substitute buying?
U.S. clinics now face a flat supply rate instead of product-specific prices, so Medicare payment reform is shifting how they buy skin substitutes. On Oct. 31, 2025, the Centers for Medicare and Medicaid Services said Part B spending on skin substitutes rose from USD 256 million in 2019 to over USD 10 billion in 2024. CMS will pay for these products as incident-to supplies from Jan. 1, 2026, at about USD 127.28 per square centimeter, and expects spending on them to fall by nearly 90%. Coloplast lowered its growth outlook for Kerecis on April 23, 2026, citing disruption from the outpatient reimbursement change. As a result, makers of skin substitutes now compete more on clinical evidence and cost per healed wound.
Why are shifting coverage rules a rising factor for biologics?
Medicare contractors decide which wounds qualify for cellular and tissue-based products, so shifting coverage rules have become a rising factor for this segment. Convatec reported in January 2025 that the effective date of local coverage determinations for diabetic foot and venous leg ulcers had been postponed to April 13, 2025. The final determinations were later scheduled to take effect on Jan. 1, 2026. However, CMS announced on Dec. 24, 2025, that its Medicare Administrative Contractors were withdrawing those determinations with immediate effect. In turn, clinicians kept broader access to these products, while payment now rests mainly on the new flat supply rate. This pricing reset keeps North America growing at 4.4% a year, below the global pace.
Can combined matrix and negative pressure therapy open new demand?
Pairing tissue matrices with suction therapy can cut dressing changes for complex wounds, which opens a clear opportunity for combined systems. On Oct. 19, 2026, Solventum announced FDA 510(k) clearance for combined use of its Restrata synthetic matrix with its negative pressure therapy. The clearance followed the acquisition of Acera Surgical in December 2025, which brought the fully resorbable Restrata matrix into the Solventum portfolio. Solventum also notes that its negative pressure therapy has treated over 10 million wounds across nearly three decades of use. As a result, suppliers that link synthetic or biological scaffolds to negative pressure systems can win more complex surgical and chronic cases. This combination also strengthens demand for negative pressure systems in surgical wards and specialist wound clinics.
Where can new fiber dressings and cell-based grafts add value?
Hard-to-heal and rare wounds need options that plain gauze cannot provide, so new fiber dressings and cell-based grafts create openings there. On July 24, 2025, Convatec secured clearance for Aquacel ConvaFiber in the U.K., the European Union, Australia and the United States, with availability from 2026. The dressing covers venous leg ulcers, diabetic foot ulcers, pressure injuries and surgical wounds, and partial thickness burns in the U.S. In April 2025, the FDA approved Zevaskyn from Abeona Therapeutics, a gene therapy applied as cell sheets to wounds of recessive dystrophic epidermolysis bullosa. In its Phase III trial, 81% of treated wounds reached at least 50% healing at six months, against 16% of control wounds. In turn, burn treatment and rare skin disease programs gain new options.
Price cuts, infection risk and access gaps slow uptake
Why do payment cuts squeeze biological product makers?
The new flat Medicare rate sits far below the prices many skin substitutes carried before 2026, which squeezes makers of biological products. Smaller makers with a single graft product face the sharpest drop in sales. Clinics may also delay grafting while they review costs per case. As a result, companies are cutting prices, narrowing portfolios and funding outcome studies that show faster healing and fewer amputations under the new rules.
How does infection risk complicate chronic ulcer treatment?
Bacteria form biofilms that slow healing and raise the chance of hospital stays, so infection risk complicates chronic ulcer treatment. Resistant organisms limit the choice of antibiotics for deep foot and pressure wounds. Clinicians must therefore combine cleansing, debridement and antimicrobial dressings over long periods. In turn, treatment costs rise for each patient, while makers invest in silver, iodine and hypochlorous acid products that help control bioburden without adding antibiotic use.
Why do access gaps hold back demand in lower-income regions?
Many patients in poorer countries reach clinics only after ulcers become severe, so access gaps hold back demand in lower-income regions. WHO found that fewer than 4 in 10 adults with diabetes take glucose-lowering medication in the African, South-East Asia and Eastern Mediterranean regions. Advanced dressings also cost far more than gauze in public hospitals with tight budgets. As a result, traditional products dominate these markets, while makers offer lower-cost lines and training programs to widen use.
How do uneven clinical skills limit advanced therapy use?
Correct wound assessment, dressing choice and negative pressure setup need specialist training, so uneven clinical skills limit advanced therapy use. Many nursing homes and home health agencies lack certified wound nurses. Poor dressing choice can extend healing time and lead to more visits. In turn, makers fund education programs, simpler all-in-one dressings and digital assessment tools that help general nurses apply advanced therapy correctly.
North America leads as Asia Pacific gains pace
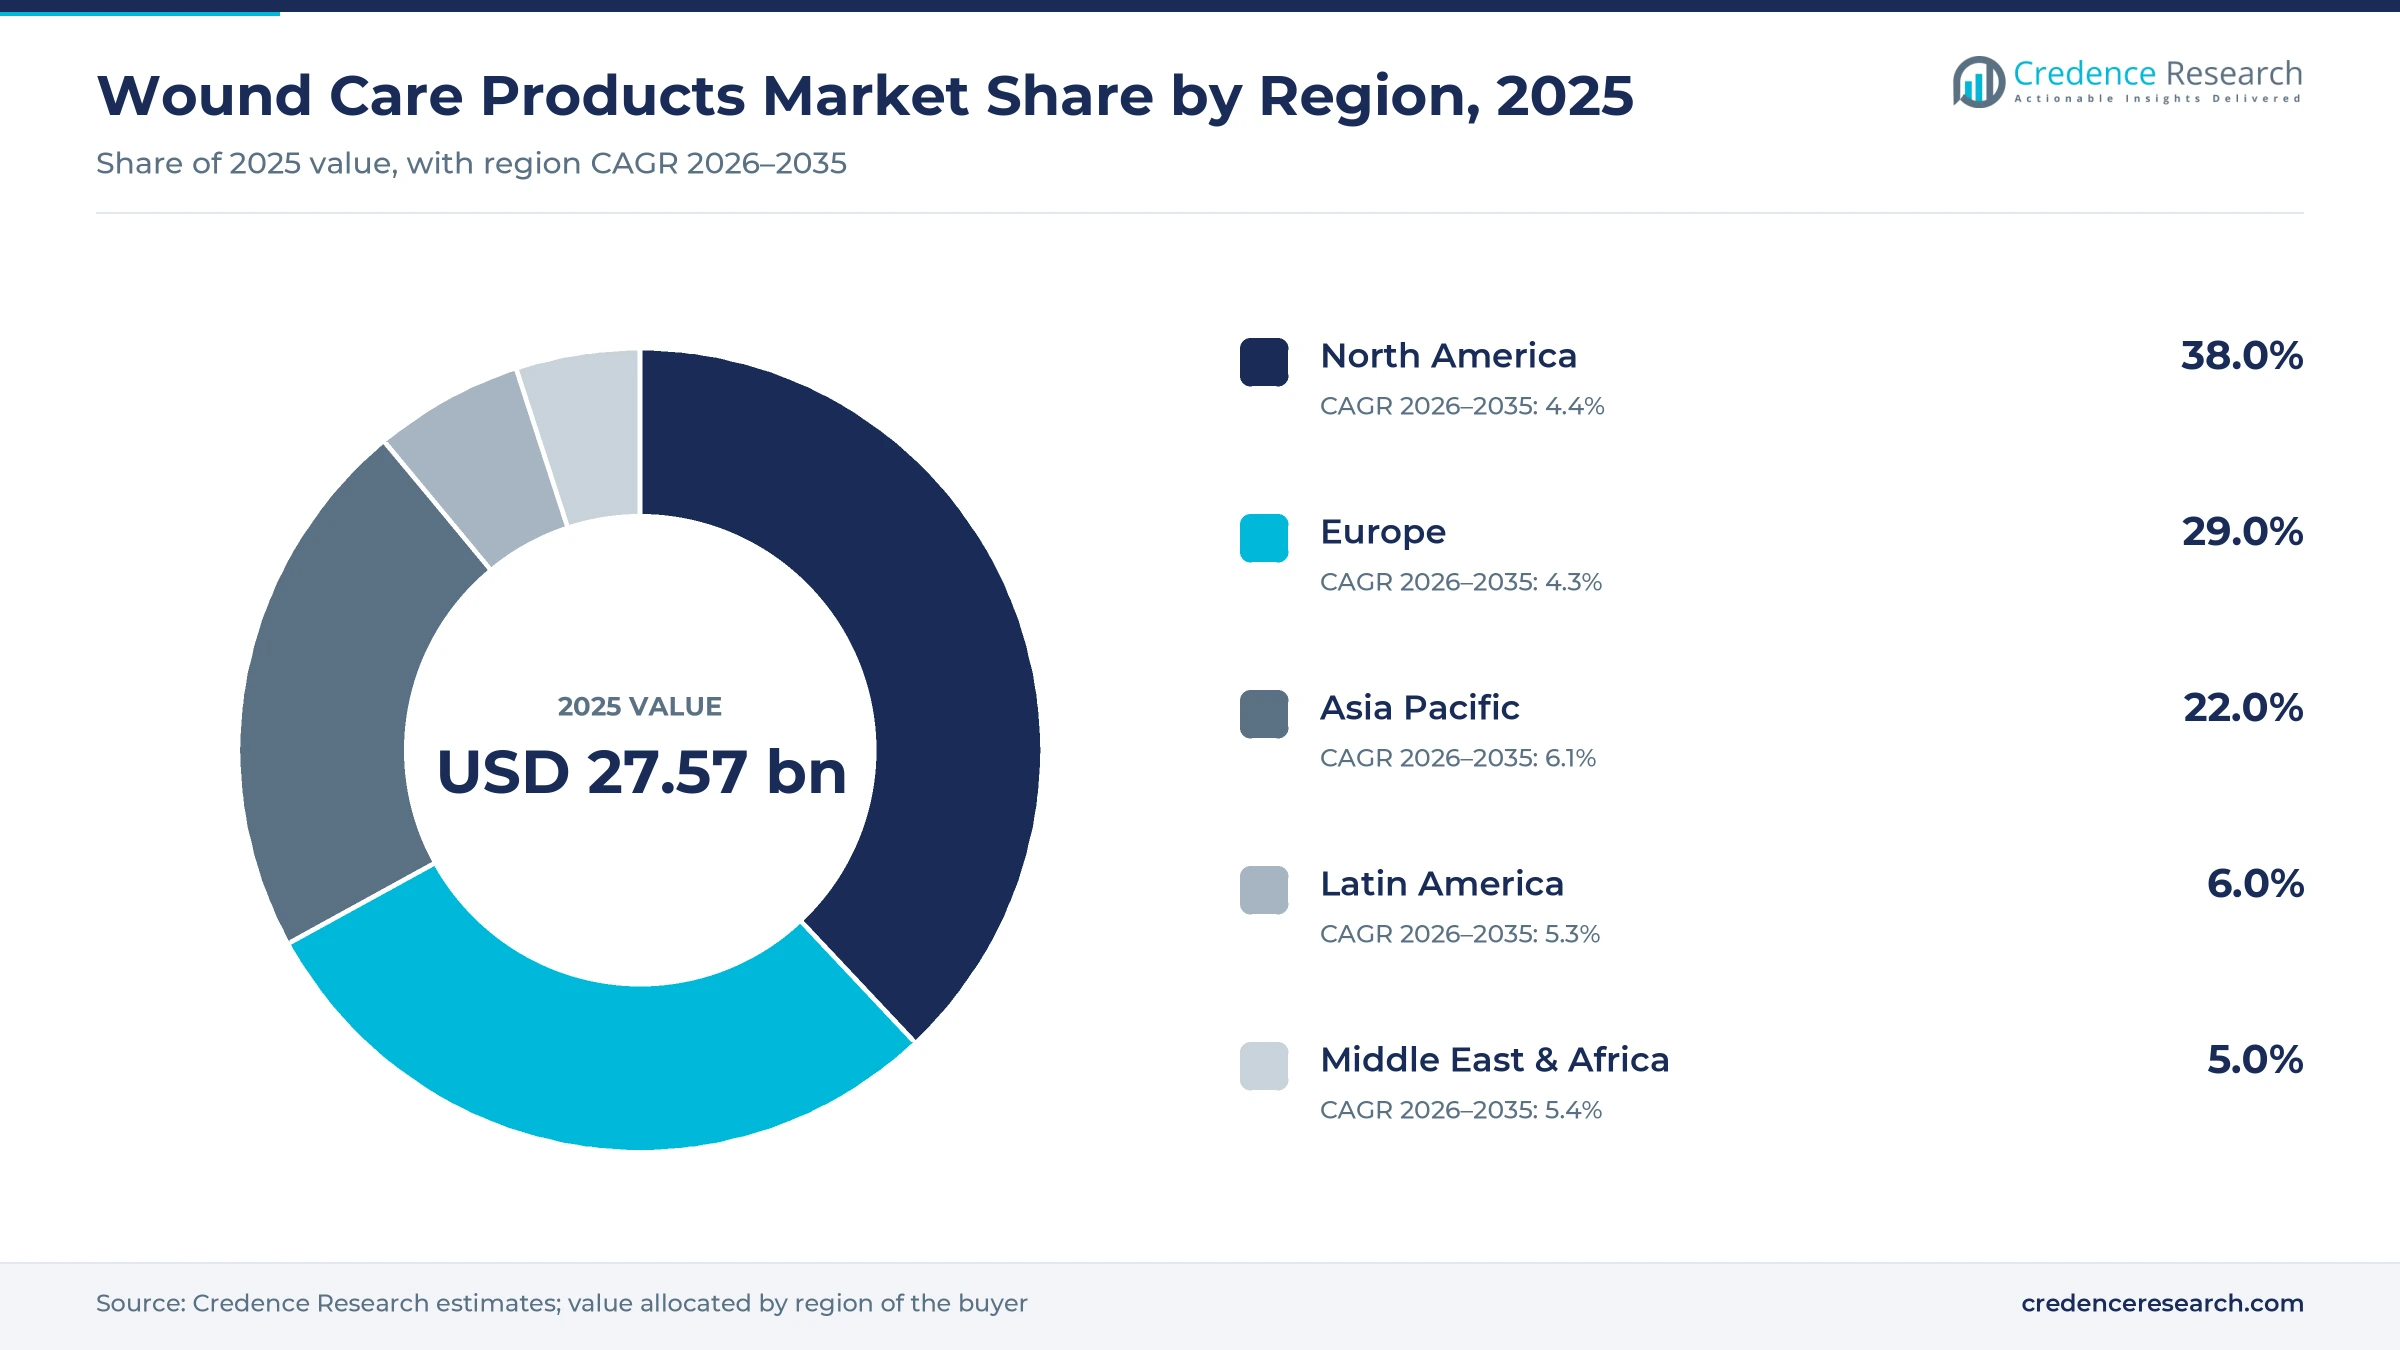
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 10.48 | 38.0% | 4.4% |
| Europe | 8.00 | 29.0% | 4.3% |
| Asia Pacific | 6.07 | 22.0% | 6.1% |
| Latin America | 1.65 | 6.0% | 5.3% |
| Middle East & Africa | 1.38 | 5.0% | 5.4% |
Why do high chronic wound volumes keep North America in the lead?
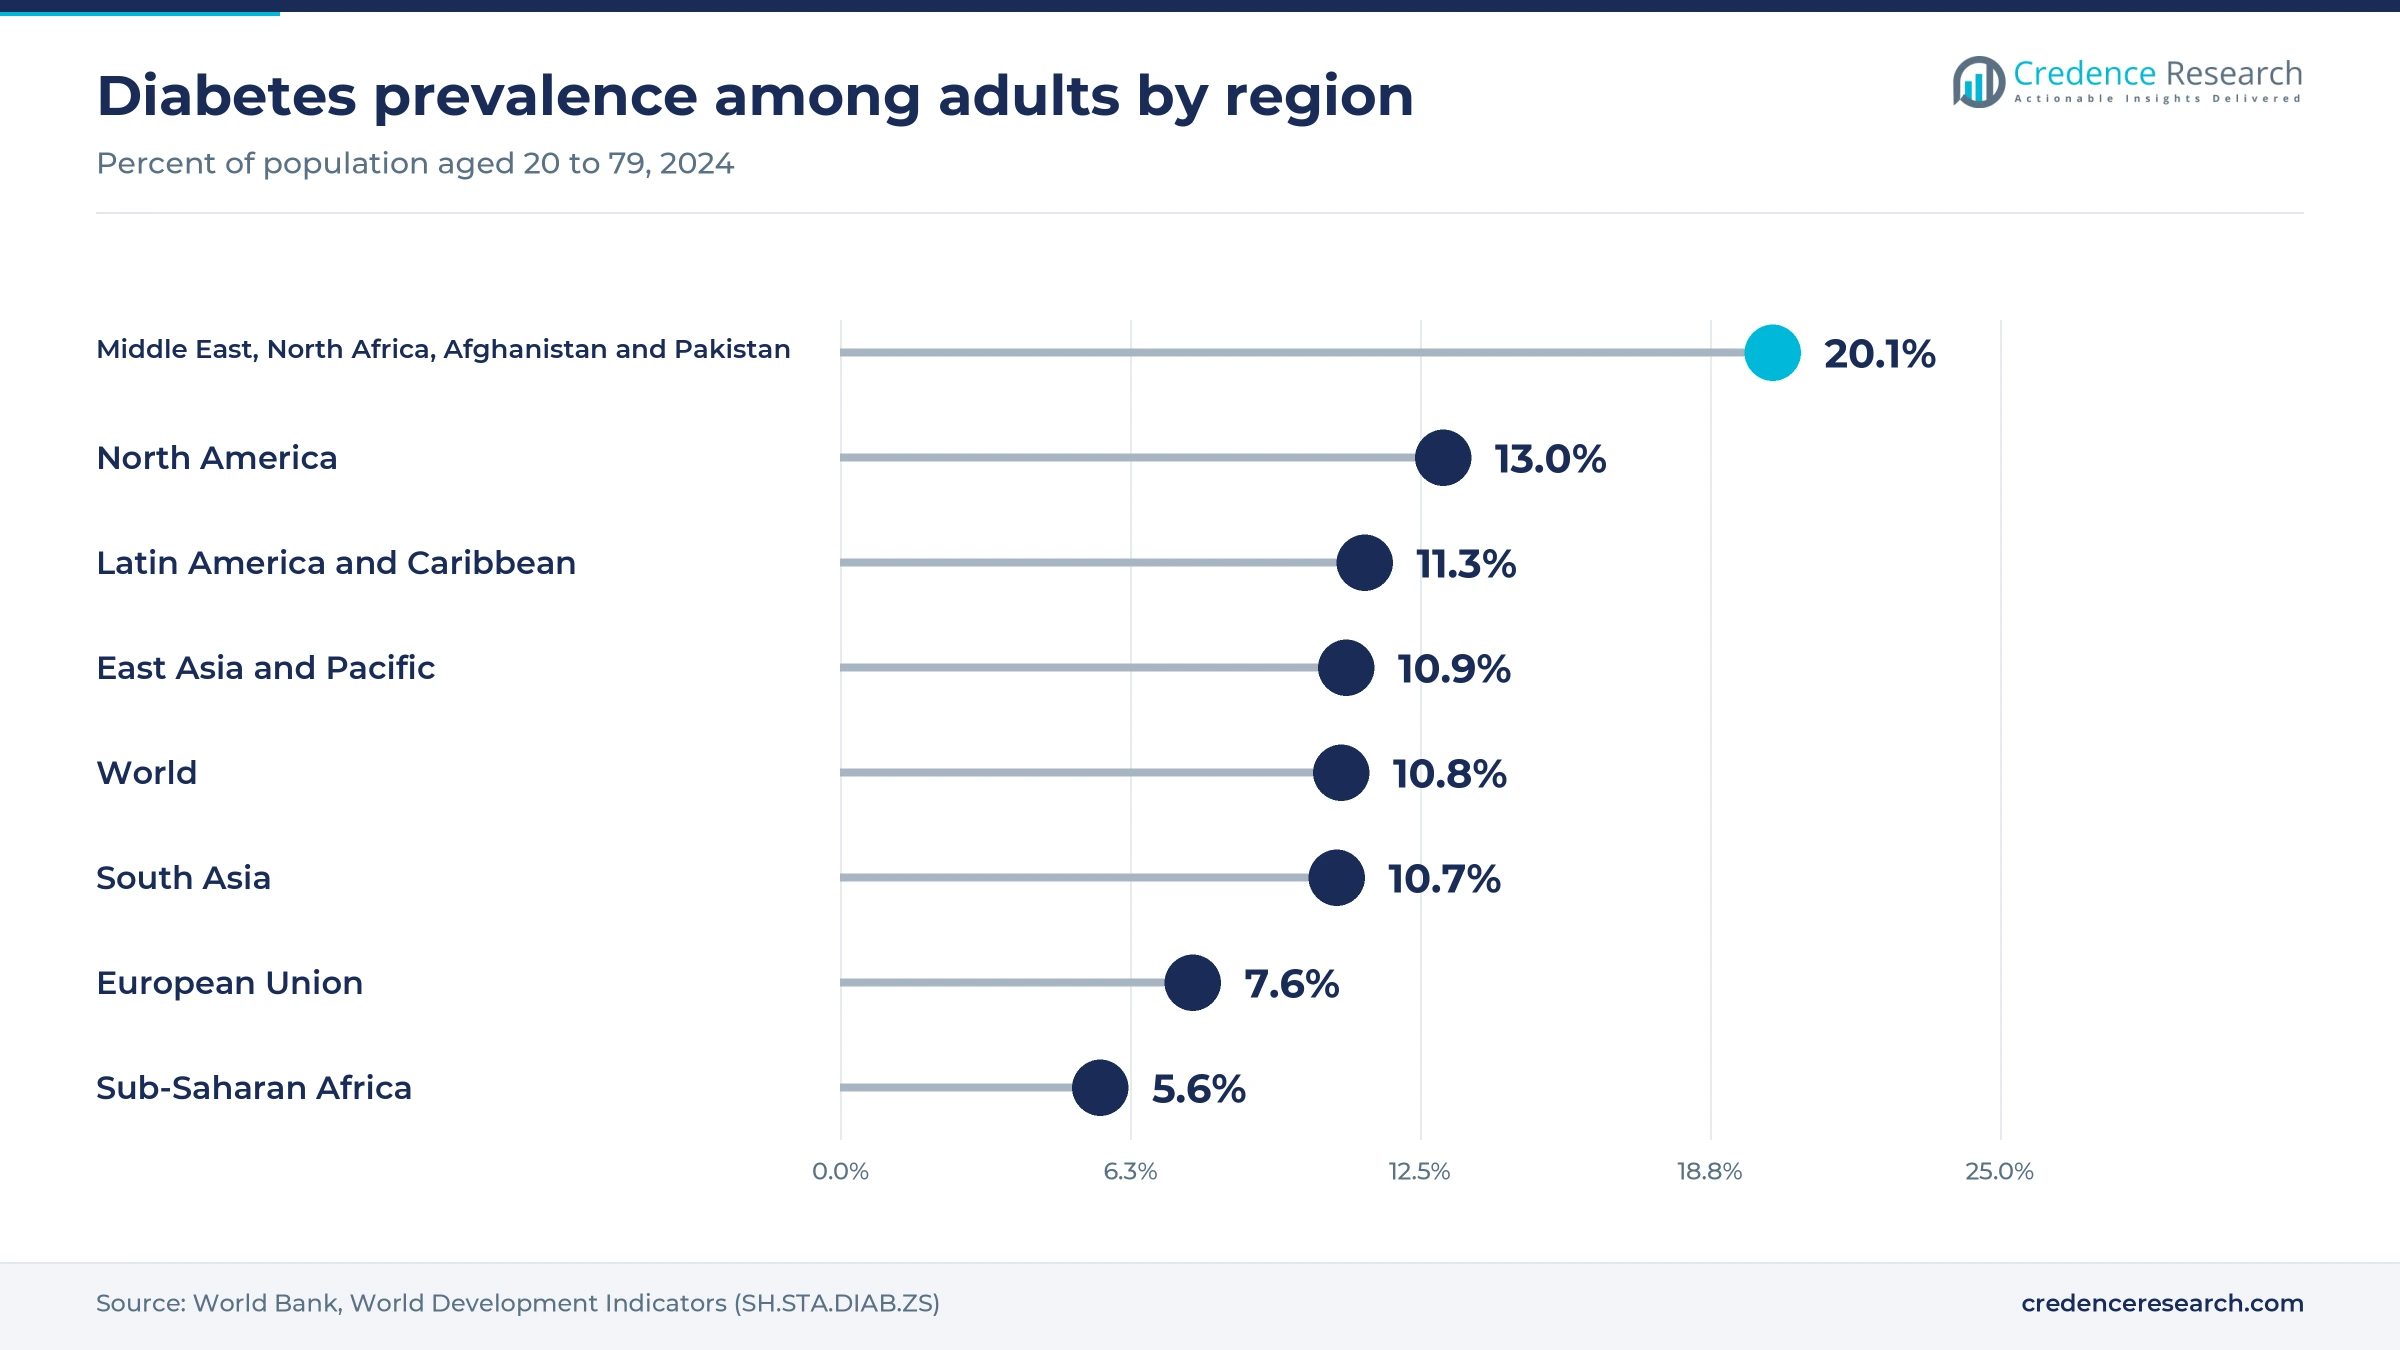
North America held 38.0% of 2025 value and grows at 4.4% a year through 2035. The United States drives this position, because hospitals and home health agencies use foam, antimicrobial and negative pressure products widely. World Bank data show adult diabetes prevalence in North America well above the world average in 2024. Smith+Nephew, Solventum Corporation, Medline Industries, LP, Cardinal Health and Organogenesis Inc. hold strong positions, while the 2026 Medicare payment reform slows growth in skin substitutes.
How does Europe balance strong clinics with budget limits?
Europe held 29.0% of 2025 value and grows at 4.3% a year through 2035. Germany, the United Kingdom, France and the Nordic countries lead regional spending, and Mölnlycke Health Care AB, Coloplast Corp., Convatec Group PLC and B. Braun SE are based in the region and supply hospitals across it. Solventum introduced its Peel and Place dressing in the United Kingdom in January 2026. However, public tenders and health technology reviews keep prices for advanced dressings under steady pressure.
Why do China and India drive Asia Pacific growth?
Asia Pacific held 22.0% of 2025 value and is the fastest-growing region at 6.1% a year. World Bank data put adult diabetes prevalence in East Asia and Pacific at about 10.9% and in South Asia at about 10.7% in 2024. China and India are adding hospital beds, wound clinics and diabetes screening, while Japan and Australia already use advanced dressings widely. As a result, demand for foam, antimicrobial and negative pressure products rises across the region.
Why do private hospitals lead adoption in Latin America?
Latin America held 6.0% of 2025 value and grows at 5.3% a year through 2035. World Bank data put adult diabetes prevalence in the region at about 11.3% in 2024. Brazil and Mexico lead spending, where private hospitals adopt advanced dressings faster than public systems with tight budgets.
Why does diabetes drive demand across the Middle East and Africa?
The Middle East and Africa held 5.0% of 2025 value and grows at 5.4% a year through 2035. World Bank data put adult diabetes prevalence in the Middle East and North Africa grouping at about 20.1% in 2024, against about 5.6% in Sub-Saharan Africa. Gulf states fund diabetic foot programs, while access remains thin elsewhere.
Launches, clearances and deals in wound treatment since 2024
| Development | Status and market relevance |
|---|---|
| In April 2024, Smith+Nephew launched the RENASYS EDGE negative pressure wound therapy system in the United States. | Launched; compact system for patients with chronic wounds treated at home |
| In April 2024, Mölnlycke agreed to acquire P.G.F. Industry Solutions, maker of Granudacyn wound cleansing solutions. | Agreed; secures supply of a range distributed in more than 50 countries |
| In July 2025, Convatec secured U.K., EU, Australian and U.S. clearance for Aquacel ConvaFiber. | Cleared; next-generation Hydrofiber dressing available from 2026 |
| In December 2025, Medline priced its initial public offering on the Nasdaq Global Select Market. | Completed; listed under the symbol MDLN at USD 29 per share |
| In October 2026, Solventum received FDA 510(k) clearance for combined use of the Restrata matrix and V.A.C. Therapy. | Cleared; follows the acquisition of Acera Surgical in December 2025 |
Fiber dressings, synthetic matrices and cell sheets advance
- Gelling fiber dressings absorb heavy exudate and conform to the wound bed, which reduces leaks and dressing changes.
- All-in-one negative pressure dressings combine foam and adhesive in one piece, which shortens application time for nurses.
- Synthetic resorbable matrices support tissue growth through structural cues, which avoids the early breakdown seen with some collagen dressings.
- Gene-corrected cell sheets use a patient’s own skin cells to cover wounds, which gives new options for rare genetic skin disease.
- Hypochlorous acid cleansers clean and moisten wounds without antibiotics, which helps clinics manage bioburden in chronic ulcers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Dressing makers compete on evidence, price and reach
Competition is led by Mölnlycke Health Care AB, Smith+Nephew, Convatec Group PLC and Solventum Corporation in advanced dressings and negative pressure systems. Coloplast Corp., Integra Lifesciences and Organogenesis Inc. focus on biological and regenerative products, a field now reshaped by the 2026 Medicare payment reform. Medline Industries, LP, Cardinal Health, DeRoyal Industries, Inc. and B. Braun SE compete on broad dressing ranges and supply contracts with hospitals and home health providers. Johnson & Johnson Services, Inc. serves surgical wound needs through its wound closure products for hospitals. As a result, companies compete on clinical evidence, wear time, price per case and distribution reach. Recent moves, such as the Solventum purchase of Acera Surgical and the Mölnlycke agreement for P.G.F. Industry Solutions, show leaders adding new technologies and securing supply rather than relying only on internal development.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Mölnlycke Health Care AB | Advanced dressings | Foam dressings and Granudacyn cleansers |
| Smith+Nephew | Advanced dressings | Foam dressings and RENASYS negative pressure systems |
| Convatec Group PLC | Advanced dressings | Aquacel Hydrofiber dressings and InnovaMatrix |
| Solventum Corporation | Negative pressure | V.A.C. Therapy and Restrata matrix |
| Coloplast Corp. | Biologics | Kerecis fish-skin grafts |
| Medline Industries, LP | Supplier | Broad dressing range and supply distribution |
| Cardinal Health | Supplier | Dressings and medical supply distribution |
| B. Braun SE | Diversified | Wound cleansing and dressing lines |
| Integra Lifesciences | Regenerative | Integra dermal regeneration template |
| Johnson & Johnson Services, Inc. | Diversified | Surgical wound closure products |
| Organogenesis Inc. | Regenerative | Bioengineered skin substitutes |
| DeRoyal Industries, Inc. | Supplier | Dressings and surgical supplies |
Home therapy and evidence will set the pace
Credence Research's view is that home-based therapy and clinical evidence will set the pace of growth through 2035, because payers now want faster healing at lower cost per patient. The overall market grows at 4.84% a year, supported by rising diabetes, aging populations and portable negative pressure systems. Traditional products keep the largest share, yet foam, antimicrobial and negative pressure products gain value in chronic ulcers. Companies that pair easy-to-use dressings with strong outcome data and broad supply networks will win the most hospital and home health contracts.
How Credence Research sized wound treatment spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by product, application, end user and region. Regional and segment splits are Credence Research estimates informed by World Health Organization, World Bank and CDC statistics, CMS releases, FDA decisions and company press releases and filings. No primary interviews or surveys were used in preparing this edition of the report.
Wound treatment outlook to 2035
By 2035, the wound care products market is projected to reach USD 44.25 billion, with growth led by diabetic ulcers, home-based negative pressure therapy and new fiber dressings. Traditional products will remain the largest group, as gauze and bandages stay basic to every wound. North America keeps the largest share, while Asia Pacific adds the most new patients. Skin substitutes will compete under flat Medicare rates that reward proof of faster healing. As a result, advantage will depend on evidence, price per healed wound and reach into home settings.
Frequently Asked Questions
How big is the global wound care products market?
Which product leads the wound care products market?
Which region leads spending on wound treatment?
Which application leads wound treatment demand?
How did Medicare change payment for skin substitutes?
Why are homecare settings growing in wound treatment?
Who are the leading wound care products companies?
What restrains growth in wound treatment?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Traditional Wound Care Products
- 1.2.2 Antimicrobial Dressings
- 1.2.3 Foam Dressings
- 1.2.4 Negative Pressure Wound Therapy
- 1.2.5 Biological Skin Equivalents
- 1.2.6 Hydrocolloid Dressings
- 1.2.7 Alginate Dressings
- 1.2.8 Growth Factors
- 1.2.9 Others
- 1.3 By Application
- 1.3.1 Diabetic Ulcers
- 1.3.2 Surgical Wounds
- 1.3.3 Pressure Ulcers
- 1.3.4 Venous Leg Ulcers
- 1.3.5 Others
- 1.4 By End User
- 1.4.1 Hospitals
- 1.4.2 Clinics
- 1.4.3 Homecare Settings
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 27.57 billion → 2035: USD 44.25 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wound Care Products Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wound Care Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wound Care Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wound Care Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wound Care Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wound Care Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wound Care Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wound Care Products Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 27.57 billion → 2035: USD 44.25 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wound Care Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traditional Wound Care Products
- 12.3.7.2 Antimicrobial Dressings
- 12.3.7.3 Foam Dressings
- 12.3.7.4 Negative Pressure Wound Therapy
- 12.3.7.5 Biological Skin Equivalents
- 12.3.7.6 Hydrocolloid Dressings
- 12.3.7.7 Alginate Dressings
- 12.3.7.8 Growth Factors
- 12.3.7.9 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diabetic Ulcers
- 12.4.7.2 Surgical Wounds
- 12.4.7.3 Pressure Ulcers
- 12.4.7.4 Venous Leg Ulcers
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Clinics
- 12.5.7.3 Homecare Settings
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wound Care Products End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wound Care Products Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wound Care Products Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wound Care Products Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mölnlycke Health Care AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smith+Nephew
- 18.4 Convatec Group PLC
- 18.5 Solventum Corporation
- 18.6 Coloplast Corp.
- 18.7 Medline Industries, LP
- 18.8 Cardinal Health
- 18.9 B. Braun SE
- 18.10 Integra Lifesciences
- 18.11 Johnson & Johnson Services, Inc.
- 18.12 Organogenesis Inc.
- 18.13 DeRoyal Industries, Inc.
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

