
A super-aged population shifts spending to catheter therapy
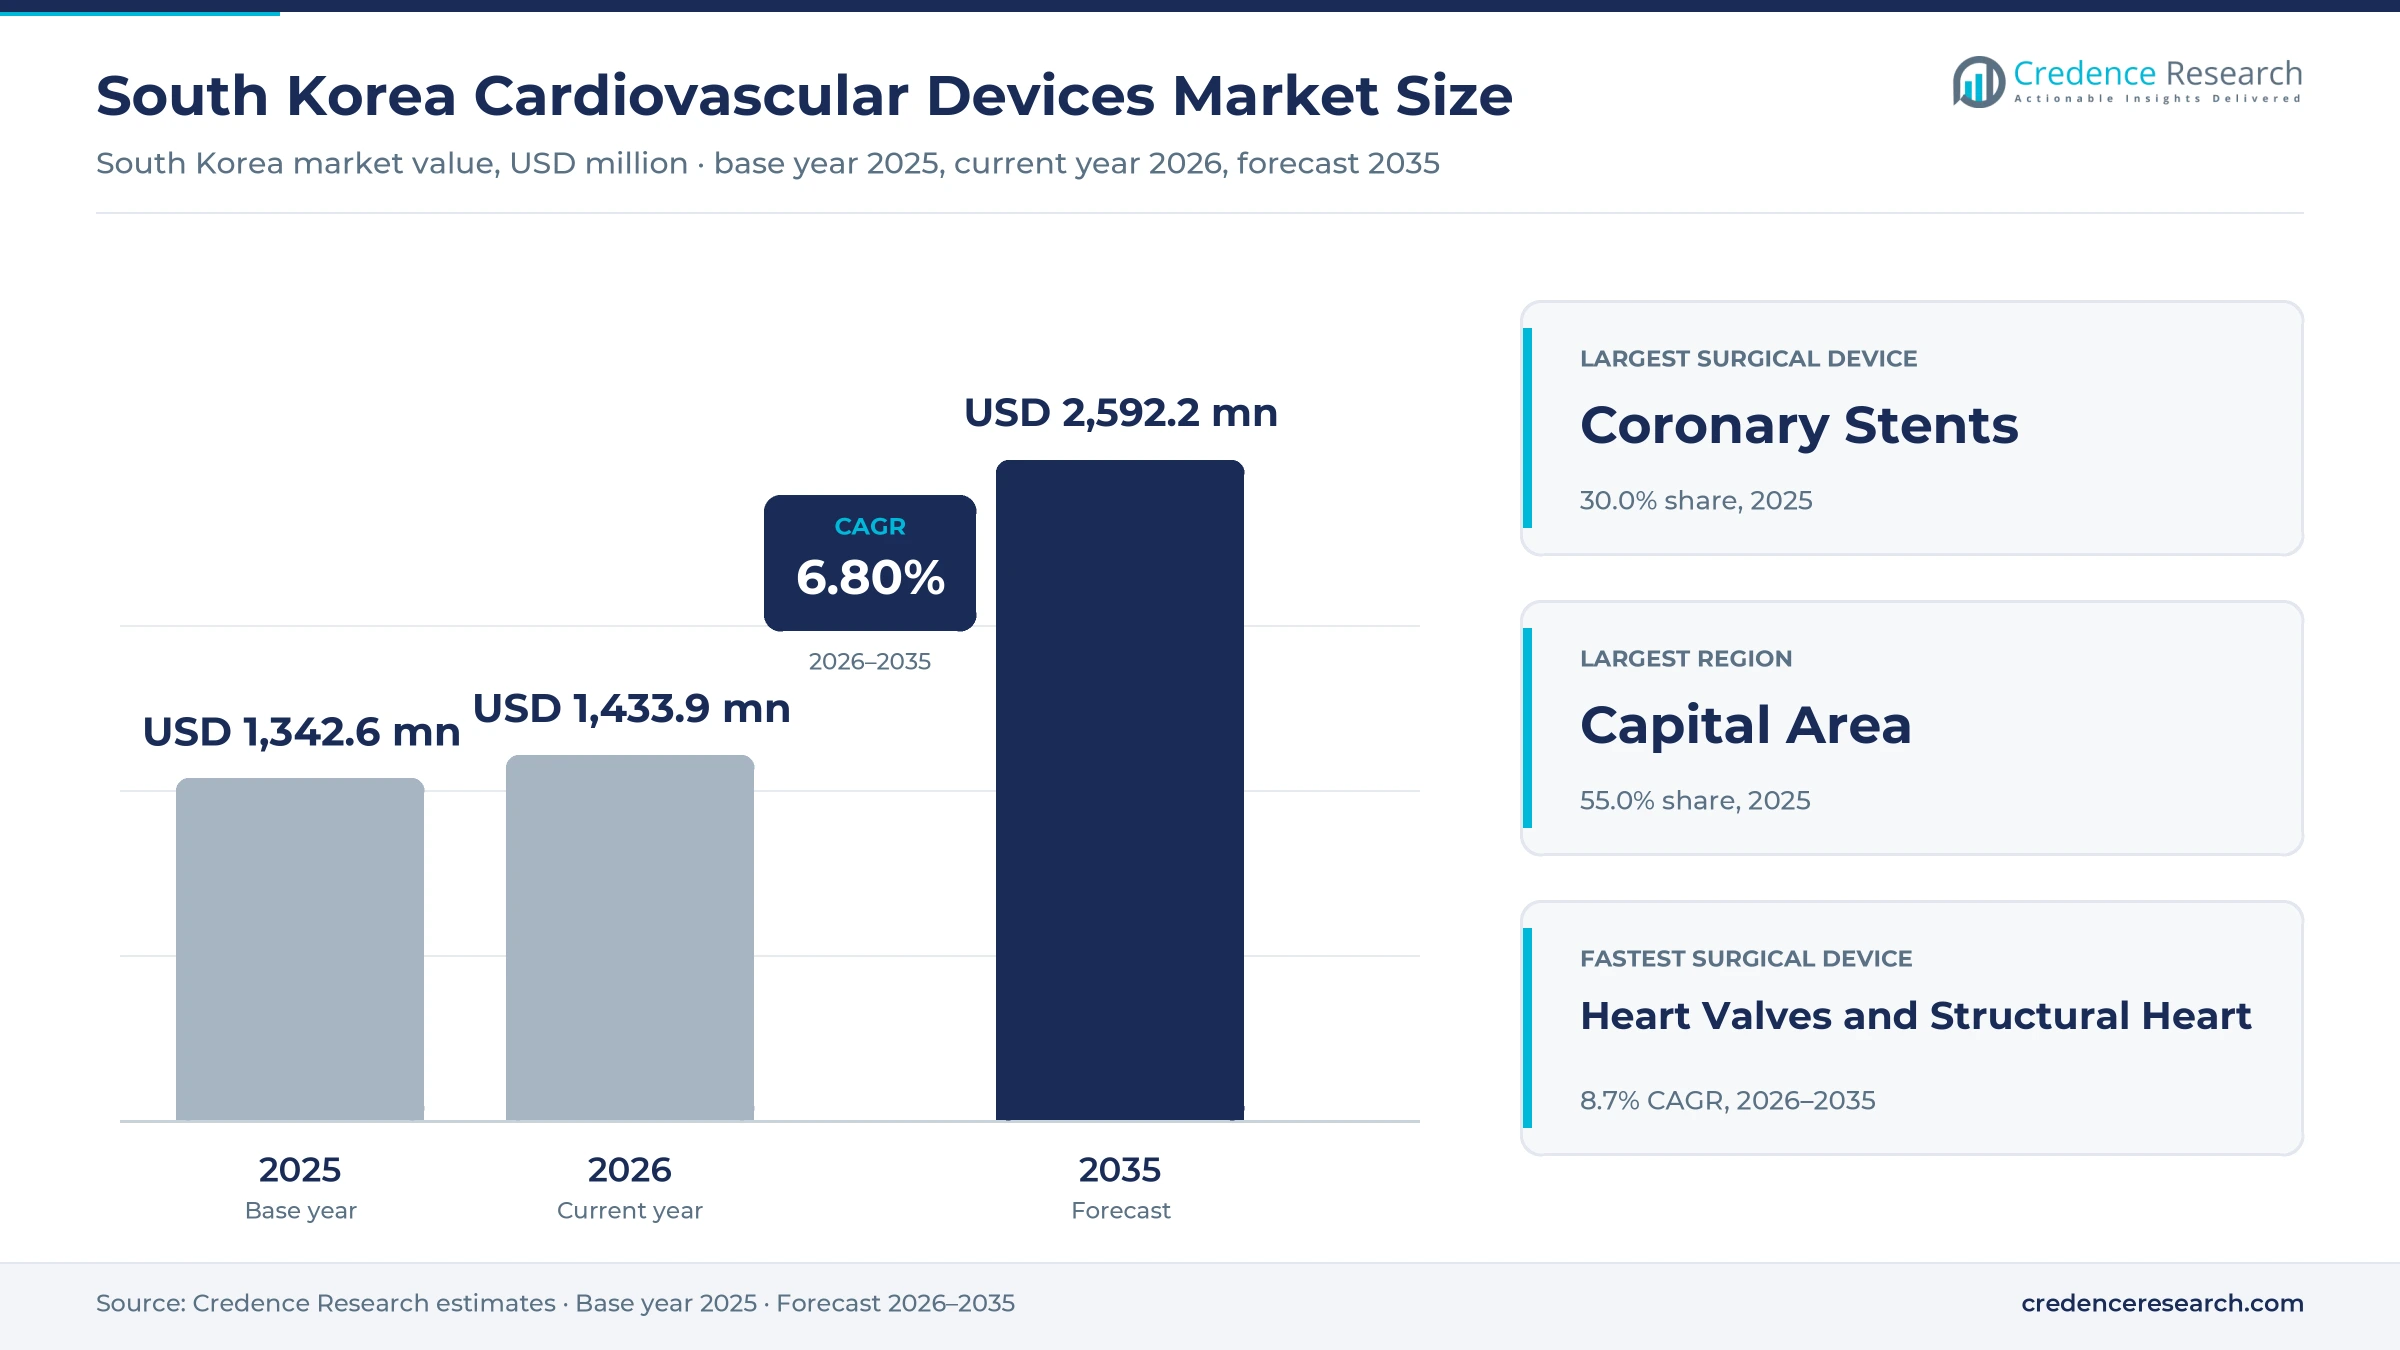
The South Korea cardiovascular devices market was valued at USD 1.34 billion in 2025 and is projected to increase from USD 1.43 billion in 2026 to USD 2.59 billion by 2035, registering a CAGR of 6.80% during 2026–2035. Demand comes from tertiary hospitals that perform coronary stenting, catheter ablation and valve replacement for a population in which more than one in five residents is 65 or older, and from wards that now monitor heart rhythm with wearable patches. The Capital Area held the largest regional share, 55.0% in 2025, because Seoul and Gyeonggi concentrate the large university hospitals that buy most implants. Honam is the fastest-growing region at 7.6% a year, as the oldest provinces gain regional heart centers. The main commercial change is reimbursement reform, because Korea widened TAVI eligibility and began covering pulsed field ablation in 2026, which moves spending toward higher-priced catheter therapies.
Implants, catheters and cardiac monitors bought by hospitals
The estimate covers coronary stents, electrophysiology and interventional catheters, pacemakers, implantable cardioverter defibrillators, cardiac resynchronization devices, heart valves and structural heart implants, and diagnostic and monitoring equipment such as ECG systems, Holter monitors, ward telemetry, implantable cardiac monitors and the cardiac share of MRI. Each device is counted once at the price paid by the hospital, clinic or patient.
The estimate excludes cardiovascular drugs, procedure fees paid to doctors, general ultrasound used outside cardiology and consumer smartwatches sold without a medical prescription. The value chain runs from multinational manufacturers and local makers through Korean subsidiaries and distributors to tertiary hospitals, which bill each item against National Health Insurance ceiling prices set by the Health Insurance Review and Assessment Service.
South Korea Cardiovascular Devices Market Insights
- The South Korea cardiovascular devices market was valued at USD 1.34 billion in 2025 and is projected to reach USD 2.59 billion by 2035, registering a CAGR of 6.80% during 2026–2035.
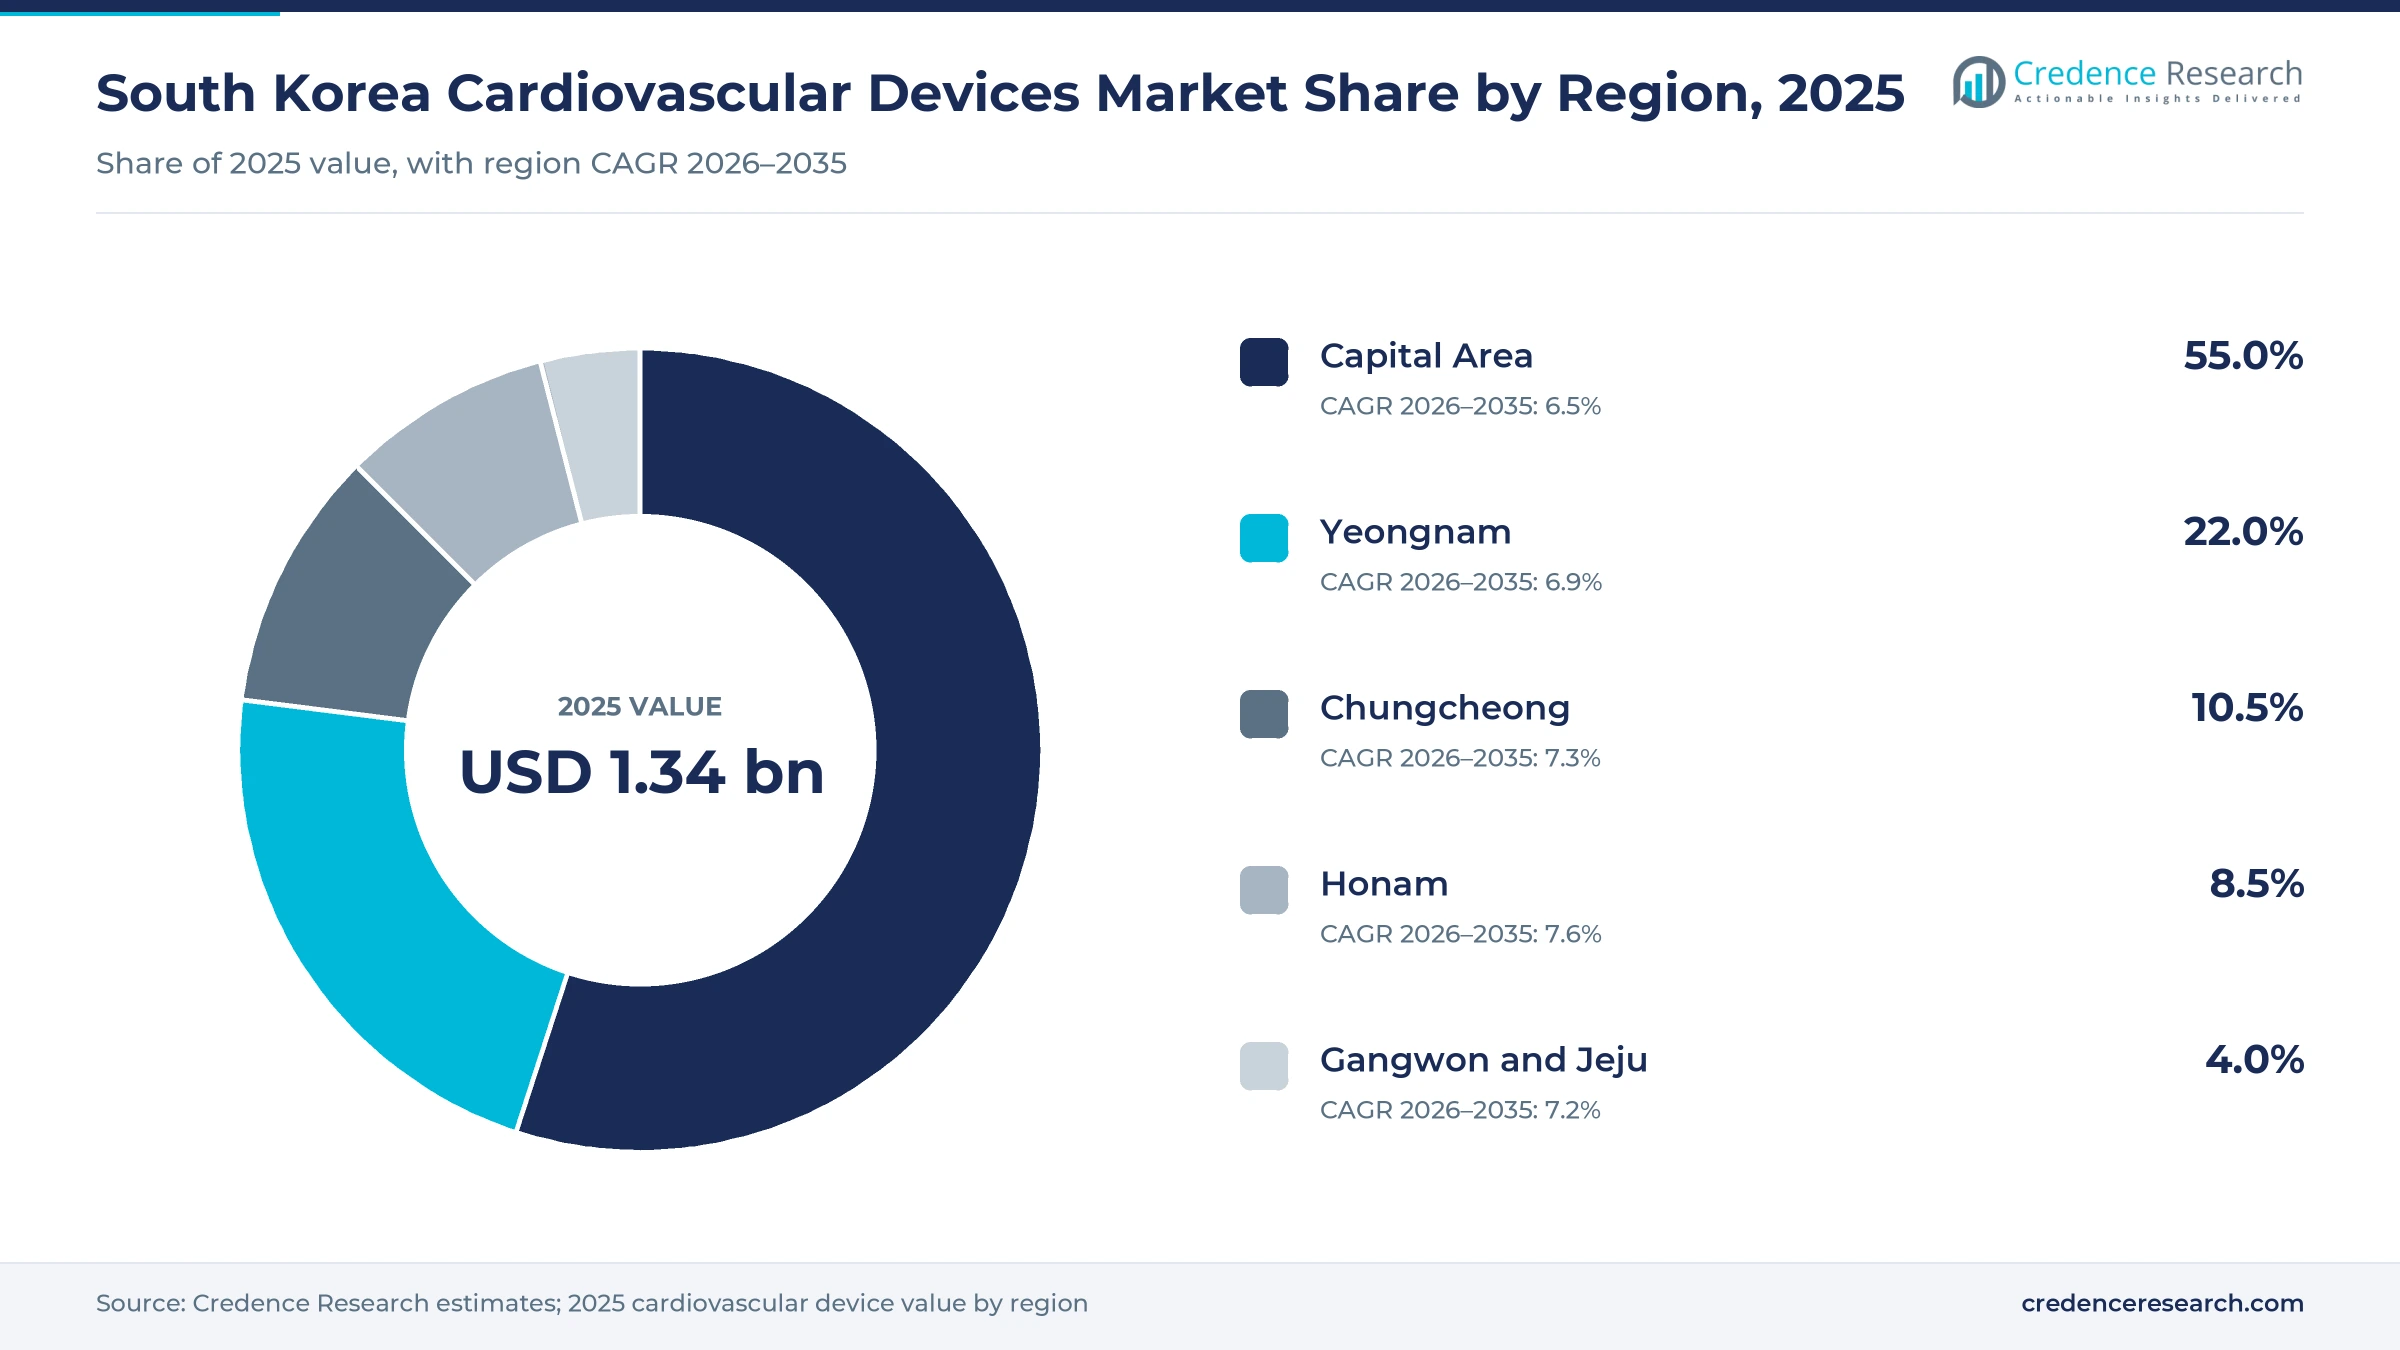
- The Capital Area held 55.0% of 2025 value, because Seoul and Gyeonggi host the university hospitals that perform most stenting, ablation and valve procedures.
- Surgical devices led product types with 64.0% of 2025 value, as stents, catheters and implants carry far higher unit prices than diagnostic equipment.
- From June 22, 2026, a full Heart Team can approve reimbursed TAVI for any patient it judges clinically necessary, which opens treatment to patients in their 70s.
- Pulsed field ablation gained National Health Insurance coverage on May 1, 2026, after the first Korean approval of a PFA system in September 2024.
Stents lead while valves and ward telemetry grow fastest
Why do surgical devices take most of the spending?
Based on product, the market is categorized into diagnostic and monitoring devices and surgical devices. Surgical Devices led with 64.0% of 2025 value, because each stent, ablation catheter or implant is billed per procedure at a much higher price than a reusable monitor, and the U.S. trade agency lists the coronary artery stent among the best prospects for U.S. medical suppliers in Korea. Diagnostic and Monitoring Devices grow fastest at 7.2% a year, as Sky Labs reports that its reimbursed ring-type blood pressure monitor has been prescribed more than 250,000 times at nearly 2,000 hospitals and clinics since June 2024.
Which monitoring devices are gaining ground?
Based on diagnostic and monitoring device type, the market is categorized into ECG, implantable cardiac monitors, Holter monitors, mobile cardiac telemetry, MRI and others. ECG led with 30.0% of 2025 value, because resting ECG is the first test in every chest pain and arrhythmia pathway, and Huinno holds more than 40% of the tertiary hospital market for Holter monitoring, according to a HIRA data analysis cited by EDAILY. Mobile Cardiac Telemetry grows fastest at 9.0% a year, as Huinno's distribution partner Yuhan Corporation placed a KRW 4 billion supply order for 1,000 beds of MEMO CUE wearable monitoring devices, EDAILY reported in July 2026.
Why do coronary stents still lead surgical devices?
Based on surgical device type, the market is categorized into cardiac resynchronization therapy, implantable cardioverter defibrillators, pacemakers, coronary stents, catheters and heart valves and structural heart devices. Coronary Stents led with 30.0% of 2025 value, because stenting is the default treatment for coronary disease, and a Korean-made sirolimus stent approved in 2016 was followed in a registry of 1,999 patients at 17 sites. Heart Valves and Structural Heart Devices grow fastest at 8.7% a year, as Medtronic launched the Evolut FX+ valve in March 2026 and wider TAVI criteria took effect in June 2026.
How much do hospitals account for?
Based on end user, the market is categorized into hospitals and clinics, diagnostic laboratories, ambulatory surgical centers and home care and others. Hospitals and Clinics led with 79.5% of 2025 value, because National Health Insurance reimburses stents, ablation and valve implants only when a hospital team performs them, and Dong-A ST says its HiCardi telemetry runs in more than 25 of the 47 tertiary hospitals. Home Care and Others grows fastest at 8.8% a year, as the Korean Society of Hypertension added ring-type cuffless monitoring to its sixth national guideline in June 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Surgical Devices | 64.0% | Diagnostic and Monitoring Devices | 7.2% |
| By Diagnostic and Monitoring Device Type | ECG | 30.0% | Mobile Cardiac Telemetry | 9.0% |
| By Surgical Device Type | Coronary Stents | 30.0% | Heart Valves and Structural Heart Devices | 8.7% |
| By End User | Hospitals and Clinics | 79.5% | Home Care and Others | 8.8% |
Ceiling prices and fees set what hospitals can spend
Prices for cardiovascular devices in Korea are set mainly by National Health Insurance, which lists a ceiling price for each reimbursed item and a separate procedure fee for the hospital. Patients pay a small share for covered procedures, often 5% for TAVI and qualifying leadless pacemakers, but far more when they fall outside the criteria. Imported implants face fixed won prices while costs rise with the dollar, so suppliers protect margins through service, training and new-generation products that earn new listings. Hospitals weigh the procedure fee against staff time, which keeps simpler stenting more attractive than complex valve programs.
| Item or fee | Typical price or fee | Basis |
|---|---|---|
| Coronary stenting procedure fee | About KRW 1.5 million per procedure | DailyPharm, January 2026 |
| TAVI procedure fee | About KRW 540,000 per procedure | DailyPharm, January 2026 |
| TAVI out of pocket, patient in 70s outside criteria | About KRW 27 million | Dong-A Ilbo, February 2026 |
| Wearable ward monitoring, supply price to distributor | About KRW 4 million per bed | Credence Research estimate from a KRW 4 billion distributor order for 1,000 beds, EDAILY, July 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Aging, wider coverage and fast-track entry lift device use
A super-aged population raises procedure volumes
Aging is the base driver, because coronary, valve and rhythm disease rise sharply after 70 and each case needs imaging, catheters or an implant. Korea became a super-aged society in December 2024, when one in five residents was 65 or older, and the share reached 21.21% by the end of 2025, according to the Ministry of the Interior and Safety. Myocardial infarction cases rose from 23,509 in 2012 to 34,969 in 2022, the Korea Disease Control and Prevention Agency reported, with incidence highest among people aged 80 and older. Heart disease was the second-leading cause of death in 2024, Statistics Korea said. Older patients often carry kidney and lung disease that makes open surgery risky, so cardiologists favor catheter treatment, which shifts value toward stents, ablation catheters and transcatheter valves.
Wider coverage brings TAVI and leadless pacing to more patients
Reimbursement decisions decide how fast new implants reach Korean patients, because uncovered devices cost tens of millions of won. Aortic stenosis patients rose from 16,537 in 2020 to 25,826 in 2024, and the Ministry of Health and Welfare widened TAVI coverage on June 22, 2026, letting a Heart Team approve any clinically necessary case, DailyPharm reported. The same notice cut the staffing rule from two thoracic surgeons to one with 10 years of experience, which brings smaller hospitals into reach. Since Dec. 1, 2025, patients without usable venous access or with a device infection pay 5% for a leadless pacemaker. Medtronic says more than 2,000 Korean patients had received its Micra device by July 2025.
A fast-track pathway shortens hospital entry for new devices
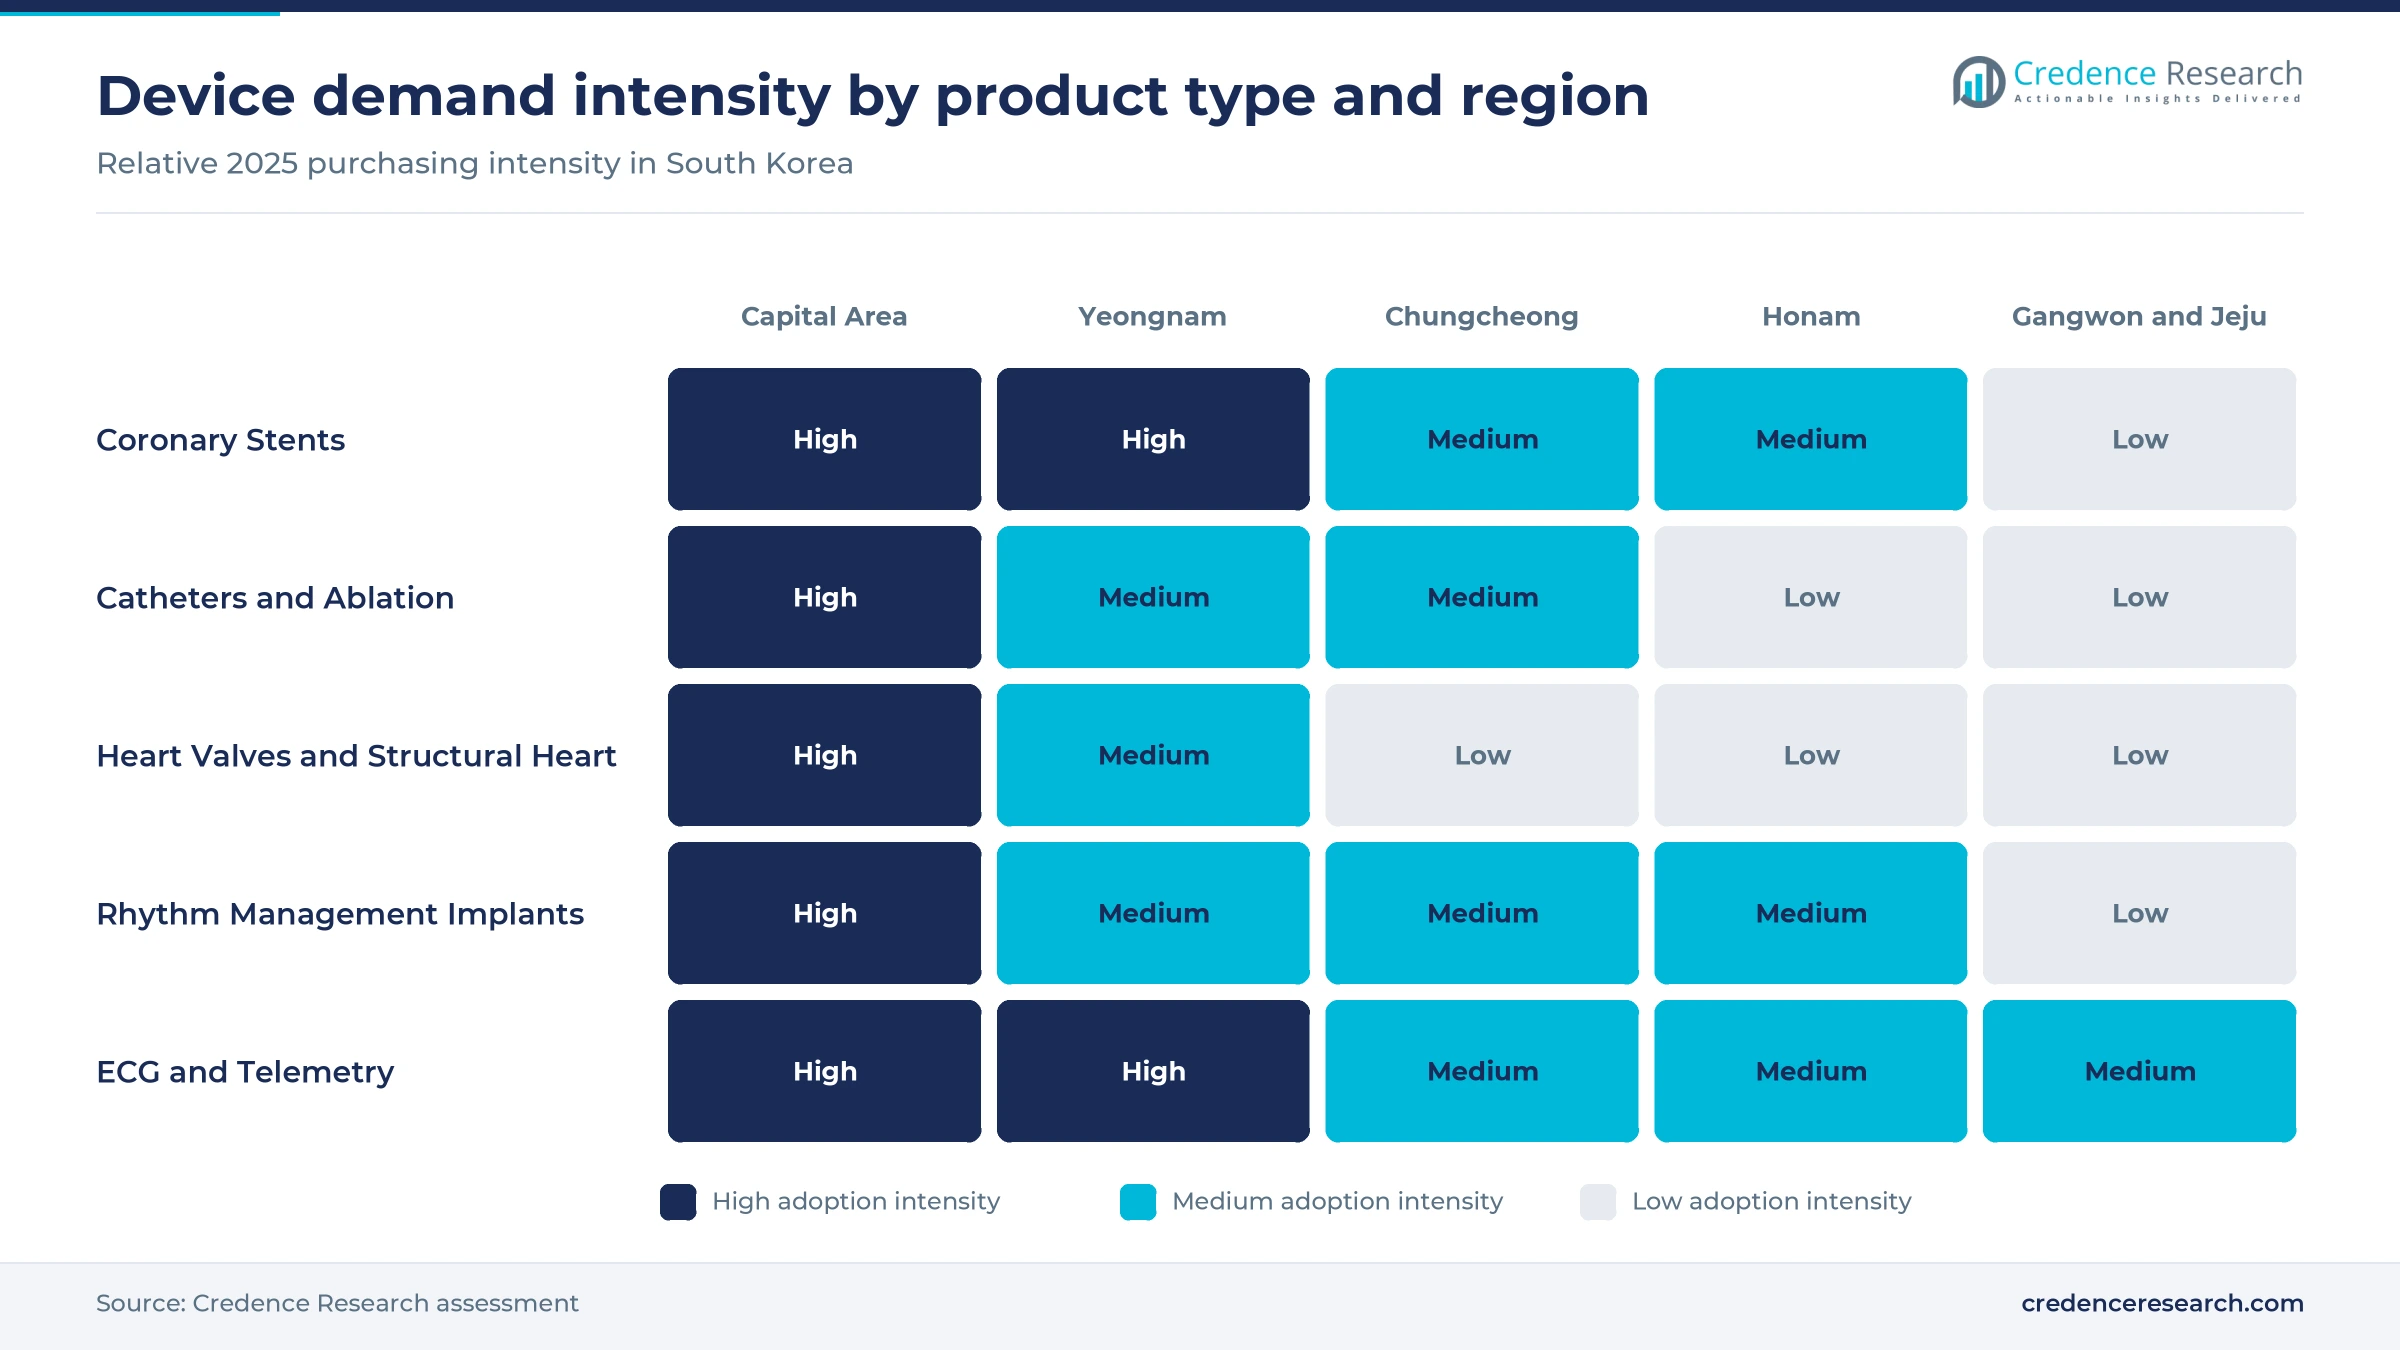
Faster market access lifts demand for new cardiac technology, because Korean hospitals could not use many novel devices until a separate health technology review was complete. The Ministry of Health and Welfare and the Ministry of Food and Drug Safety launched a market immediate entry pathway on Jan. 26, 2026, cutting the time to clinical use from up to 490 days to 80 to 140 days, Complife Group reported. The scope covers 199 device categories, including 113 digital devices such as AI-based software. Pulsed field ablation had already passed the new health technology assessment in December 2024, DailyPharm reported. Shorter entry lets suppliers recover launch costs sooner and encourages earlier Korean launches of AI ECG and imaging tools.
Regional heart centers add catheter labs outside Seoul
Government efforts to treat heart attacks close to home add cath lab and monitoring demand in provincial hospitals. On Feb. 26, 2026, the Ministry of Health and Welfare selected five more cardiovascular and cerebrovascular disease centers, including one regional hub in South Jeolla and local centers in Busan, Jeju, North Jeolla and South Chungcheong, Asia Economy reported. The ministry also planned another call for Gwangju, Daegu, Sejong and Gangwon, which still lack a local center. Speed matters, because 15.8% of myocardial infarction patients died within a year in 2022, and 14.3% of patients aged 65 or older died within 30 days, the disease agency reported. Each designated center needs round-the-clock angiography, stents and temporary pacing, which spreads orders beyond the Seoul hospitals.
Pulsed field ablation and patch telemetry reshape practice
Shift from thermal ablation to pulsed field ablation
Electrophysiologists are shifting toward pulsed field ablation to treat atrial fibrillation faster and with less risk to nearby tissue, creating openings for new catheters and mapping systems. The first Korean approval of a PFA system came in September 2024, and Severance Hospital performed the country's first PFA procedure in December 2024. About 35% of its AF ablations now use the method, which nearly halves procedure time, DailyPharm reported. Johnson & Johnson MedTech launched its VARIPULSE platform in Korea in April 2025, Korea Biomedical Review reported. National Health Insurance began covering FARAPULSE for drug-refractory patients on May 1, 2026, Boston Scientific said. Hospitals that perform electrophysiology procedures now need PFA generators and compatible maps.
Rise of wearable patch telemetry in hospital wards
Hospitals are shifting from bedside monitors and short recordings on Holter monitoring systems toward wireless ECG patches that follow patients around the ward. In December 2025, the Health Insurance Review and Assessment Service recognized Dong-A ST's HiCardi under the remote heart rate monitoring code EX871, which pays for monitoring patients who walk, Asia Economy reported. HiCardi now runs in more than 350 hospitals and clinics across the country. Its maker MeZoo says the HiCardi Plus device combines bedside patient monitoring with Holter-style continuous ECG, Korea Biomedical Review reported. Seoul National University Bundang Hospital adopted Huinno's system in August 2026, Venture Square reported. Suppliers now win contracts on alarm accuracy and central-station software, not only on sensor price.
Opportunity in TAVI for patients in their 70s
The largest open segment is TAVI for patients aged 70 to 79, who were mostly excluded by the age-80 rule. A patient in that group who was not rated high risk paid about KRW 27 million out of pocket for TAVI, against about KRW 1.5 million for surgery, the Dong-A Ilbo reported in February 2026. A national agency review of about 4,300 patients found no significant difference in 30-day or five-year mortality between the two treatments for patients aged 70 and older. Patients aged 80 and older with aortic stenosis nearly doubled between 2020 and 2024. Valve makers with transcatheter heart valve replacement training programs can grow volume as Heart Teams use the new rule.
Opportunity in AI-guided stenting and imaging
AI software that sizes stents from ordinary angiograms offers hospitals a cheaper route to image-guided stenting. In a study at 13 Korean institutions led by Asan Medical Center, AI-based angiography achieved a minimum stent area of 6.3 square millimeters against 6.2 for optical coherence tomography, with no major events at six months in either group of about 200 patients. Asan Medical Center said intravascular imaging is used in only 10% to 40% of procedures because each use costs several million won. VUNO's DeepECG software also received a breakthrough device designation from the Korean regulator. Vendors that bundle such tools with coronary stents and cath lab systems can win contracts on outcomes.
Walkout losses, a weak won and thin fees slow adoption
The trainee doctor walkout cut hospital activity
The mass resignation of trainee doctors from February 2024 reduced procedure capacity at the teaching hospitals that buy most implants. The U.S. trade agency says hospital budgets were constrained during the strike, which lasted until September 2025. At Jeju National University Hospital, daily admissions fell from 62.2 to 54.9 after the walkout, a 2025 Frontiers in Public Health study found. Tertiary hospitals deferred elective stenting and capital purchases, and suppliers of high-priced implants felt the delay most.
A record-weak won raises the cost of imported implants
Most high-end implants are imported, so the exchange rate cuts margins under fixed won ceiling prices. Korea imported USD 4,616 million of medical devices in 2024, and U.S. products alone held 27.4% of the market, the International Trade Administration reports. The won averaged a record-weak 1,422.16 per dollar in 2025, the Korea JoongAng Daily reported. Distributors and subsidiaries absorb the gap because reimbursed prices do not move with the currency.
Procedure fees do not reward complex heart teams
Low procedure fees discourage hospitals from expanding the most complex cardiac programs. The reimbursed TAVI procedure fee is about KRW 540,000, roughly a third of the KRW 1.5 million fee for coronary stenting, DailyPharm reported in January 2026. The fee must cover a full Heart Team of cardiologists, surgeons, anesthesiologists and radiologists. Hospitals can lose money as TAVI volume grows, so smaller centers delay programs until fees are reformed, which the ministry has not yet done.
Narrow eligibility rules limit new technology uptake
Coverage rules still restrict who can receive several new devices, which keeps volumes below clinical demand. Leadless pacemakers are covered only for patients without usable venous access or with a past device infection, and a Severance cardiologist said in April 2026 that these limits still restrict choice. PFA coverage from May 2026 applies only after drug therapy fails or cannot be tolerated. Patients outside the rules pay far more, so suppliers rely on private indemnity insurance and future coverage reviews.
Seoul-area hospitals lead while Honam grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
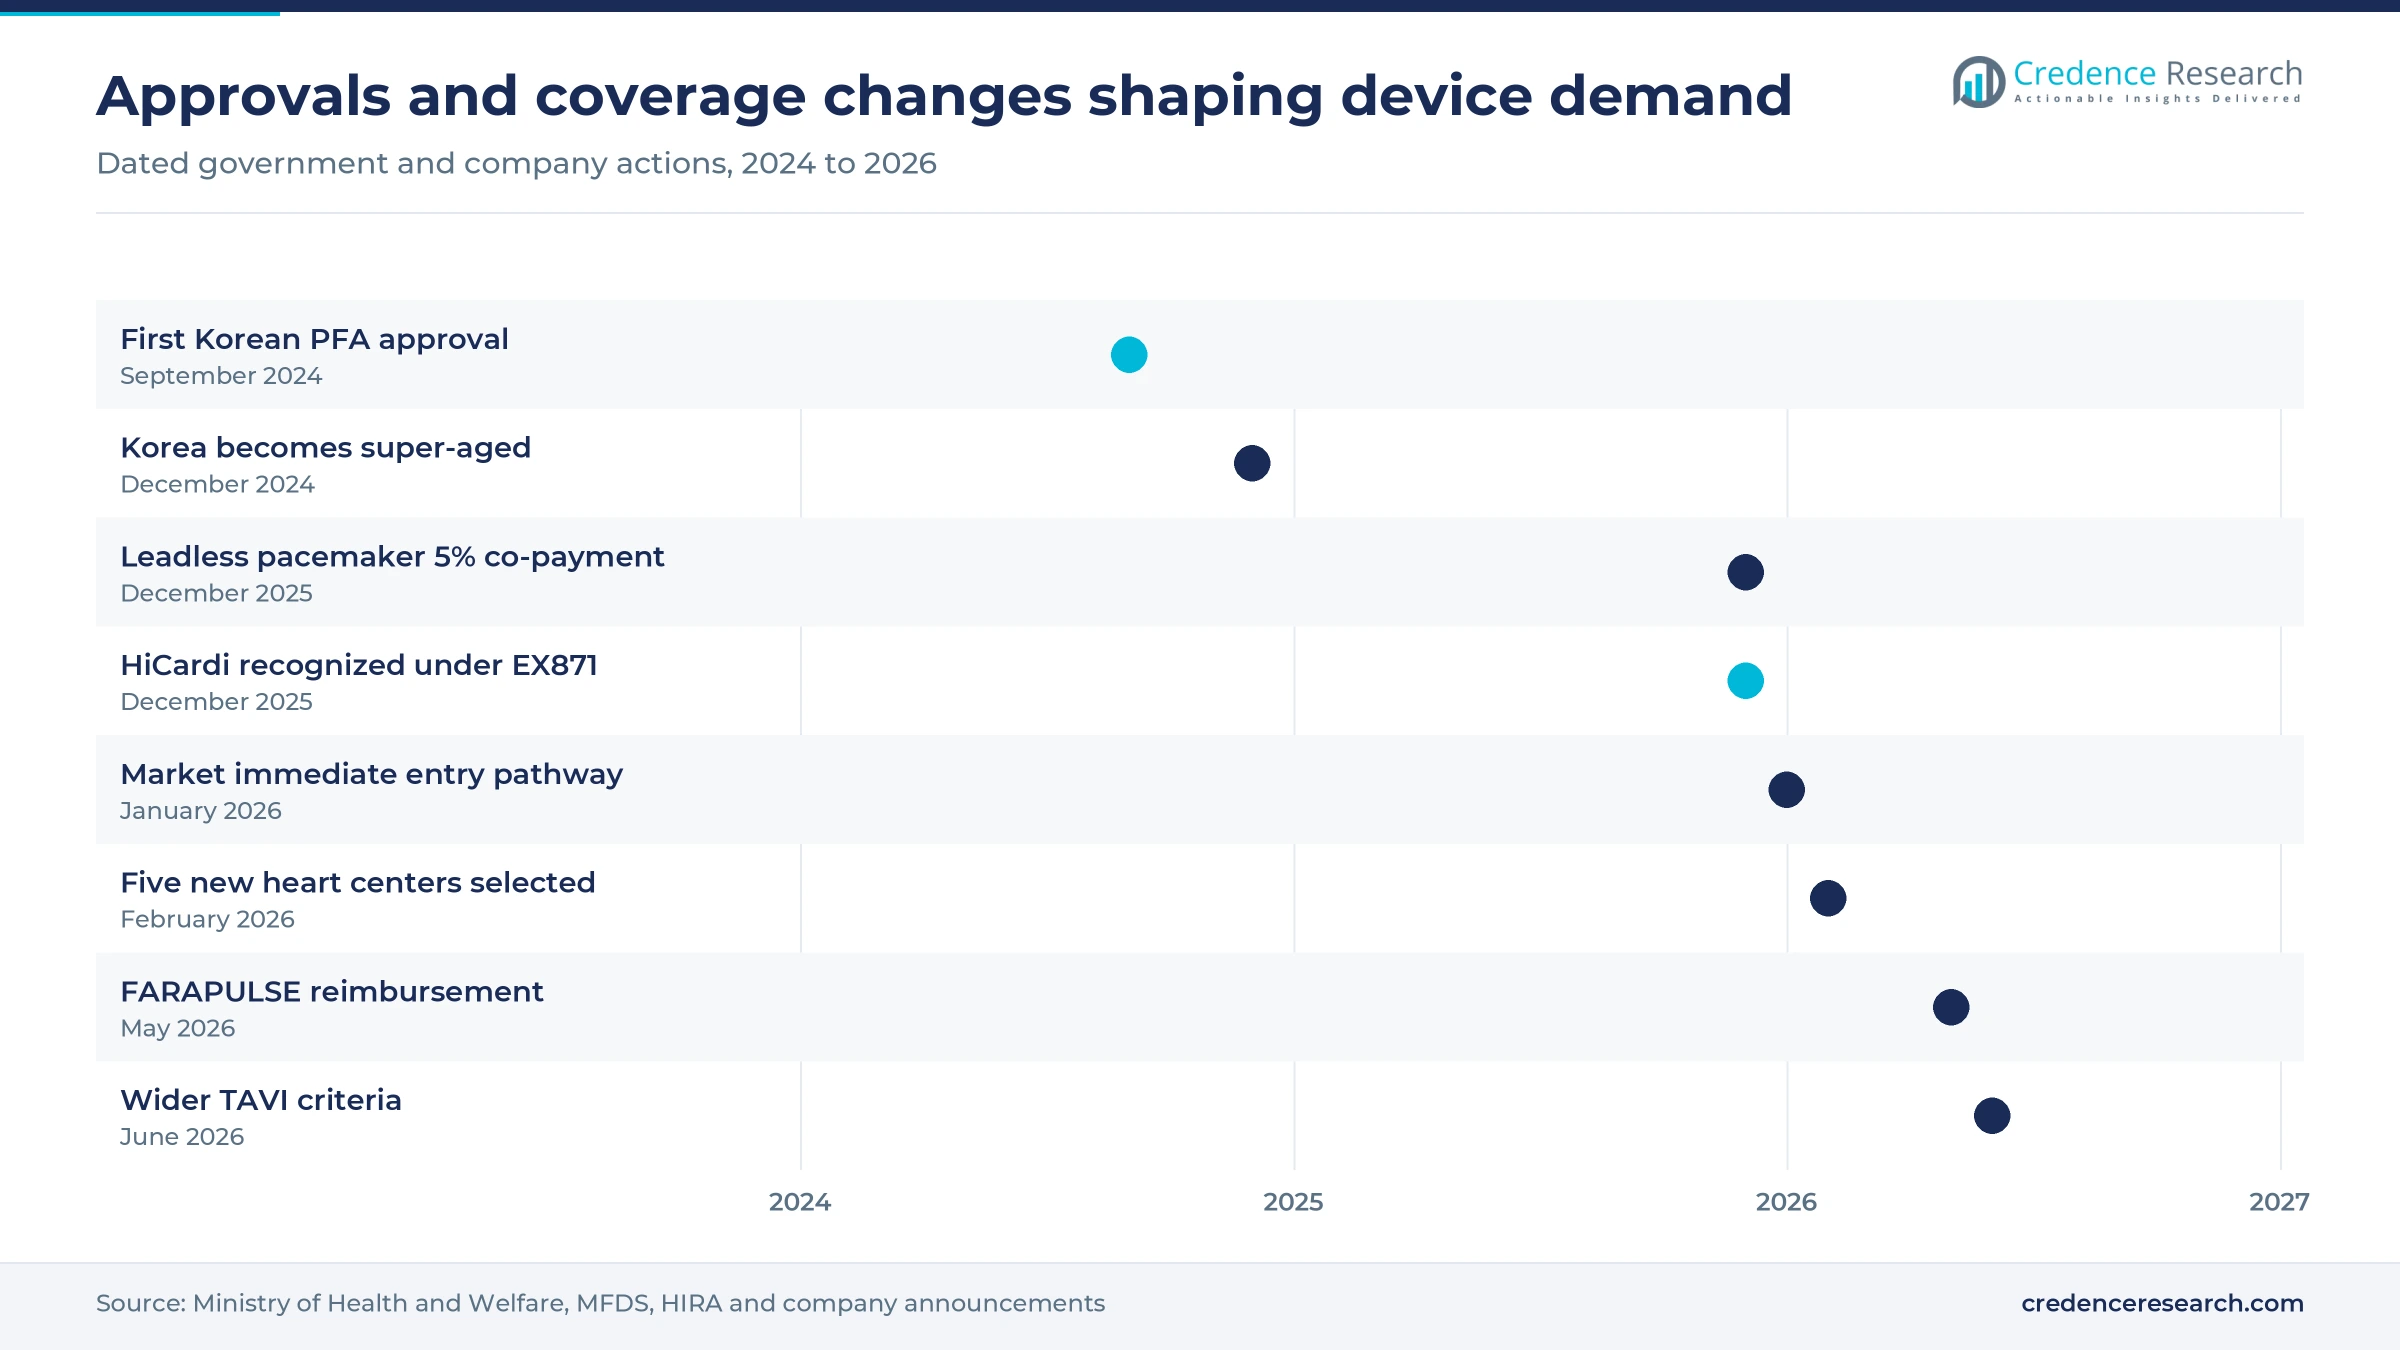
| Capital Area | 0.74 | 55.0% | 6.5% |
| Yeongnam | 0.30 | 22.0% | 6.9% |
| Chungcheong | 0.14 | 10.5% | 7.3% |
| Honam | 0.11 | 8.5% | 7.6% |
| Gangwon and Jeju | 0.05 | 4.0% | 7.2% |
Seoul, Gyeonggi and Incheon lead on tertiary hospitals
The Capital Area held 55.0% of 2025 value and grows at 6.5% a year. Seoul, Gyeonggi and Incheon had about 26 million residents in December 2024, about half of the national population, the Ministry of the Interior and Safety reported. The region hosts the large university hospitals that adopt new therapies first, including Severance, Asan and Seoul National University Bundang. Its 65+ share was 18.82% at the end of 2025, below the rest of the country, so growth leans on referrals and replacement rather than local aging.
Yeongnam combines old populations and large hospitals
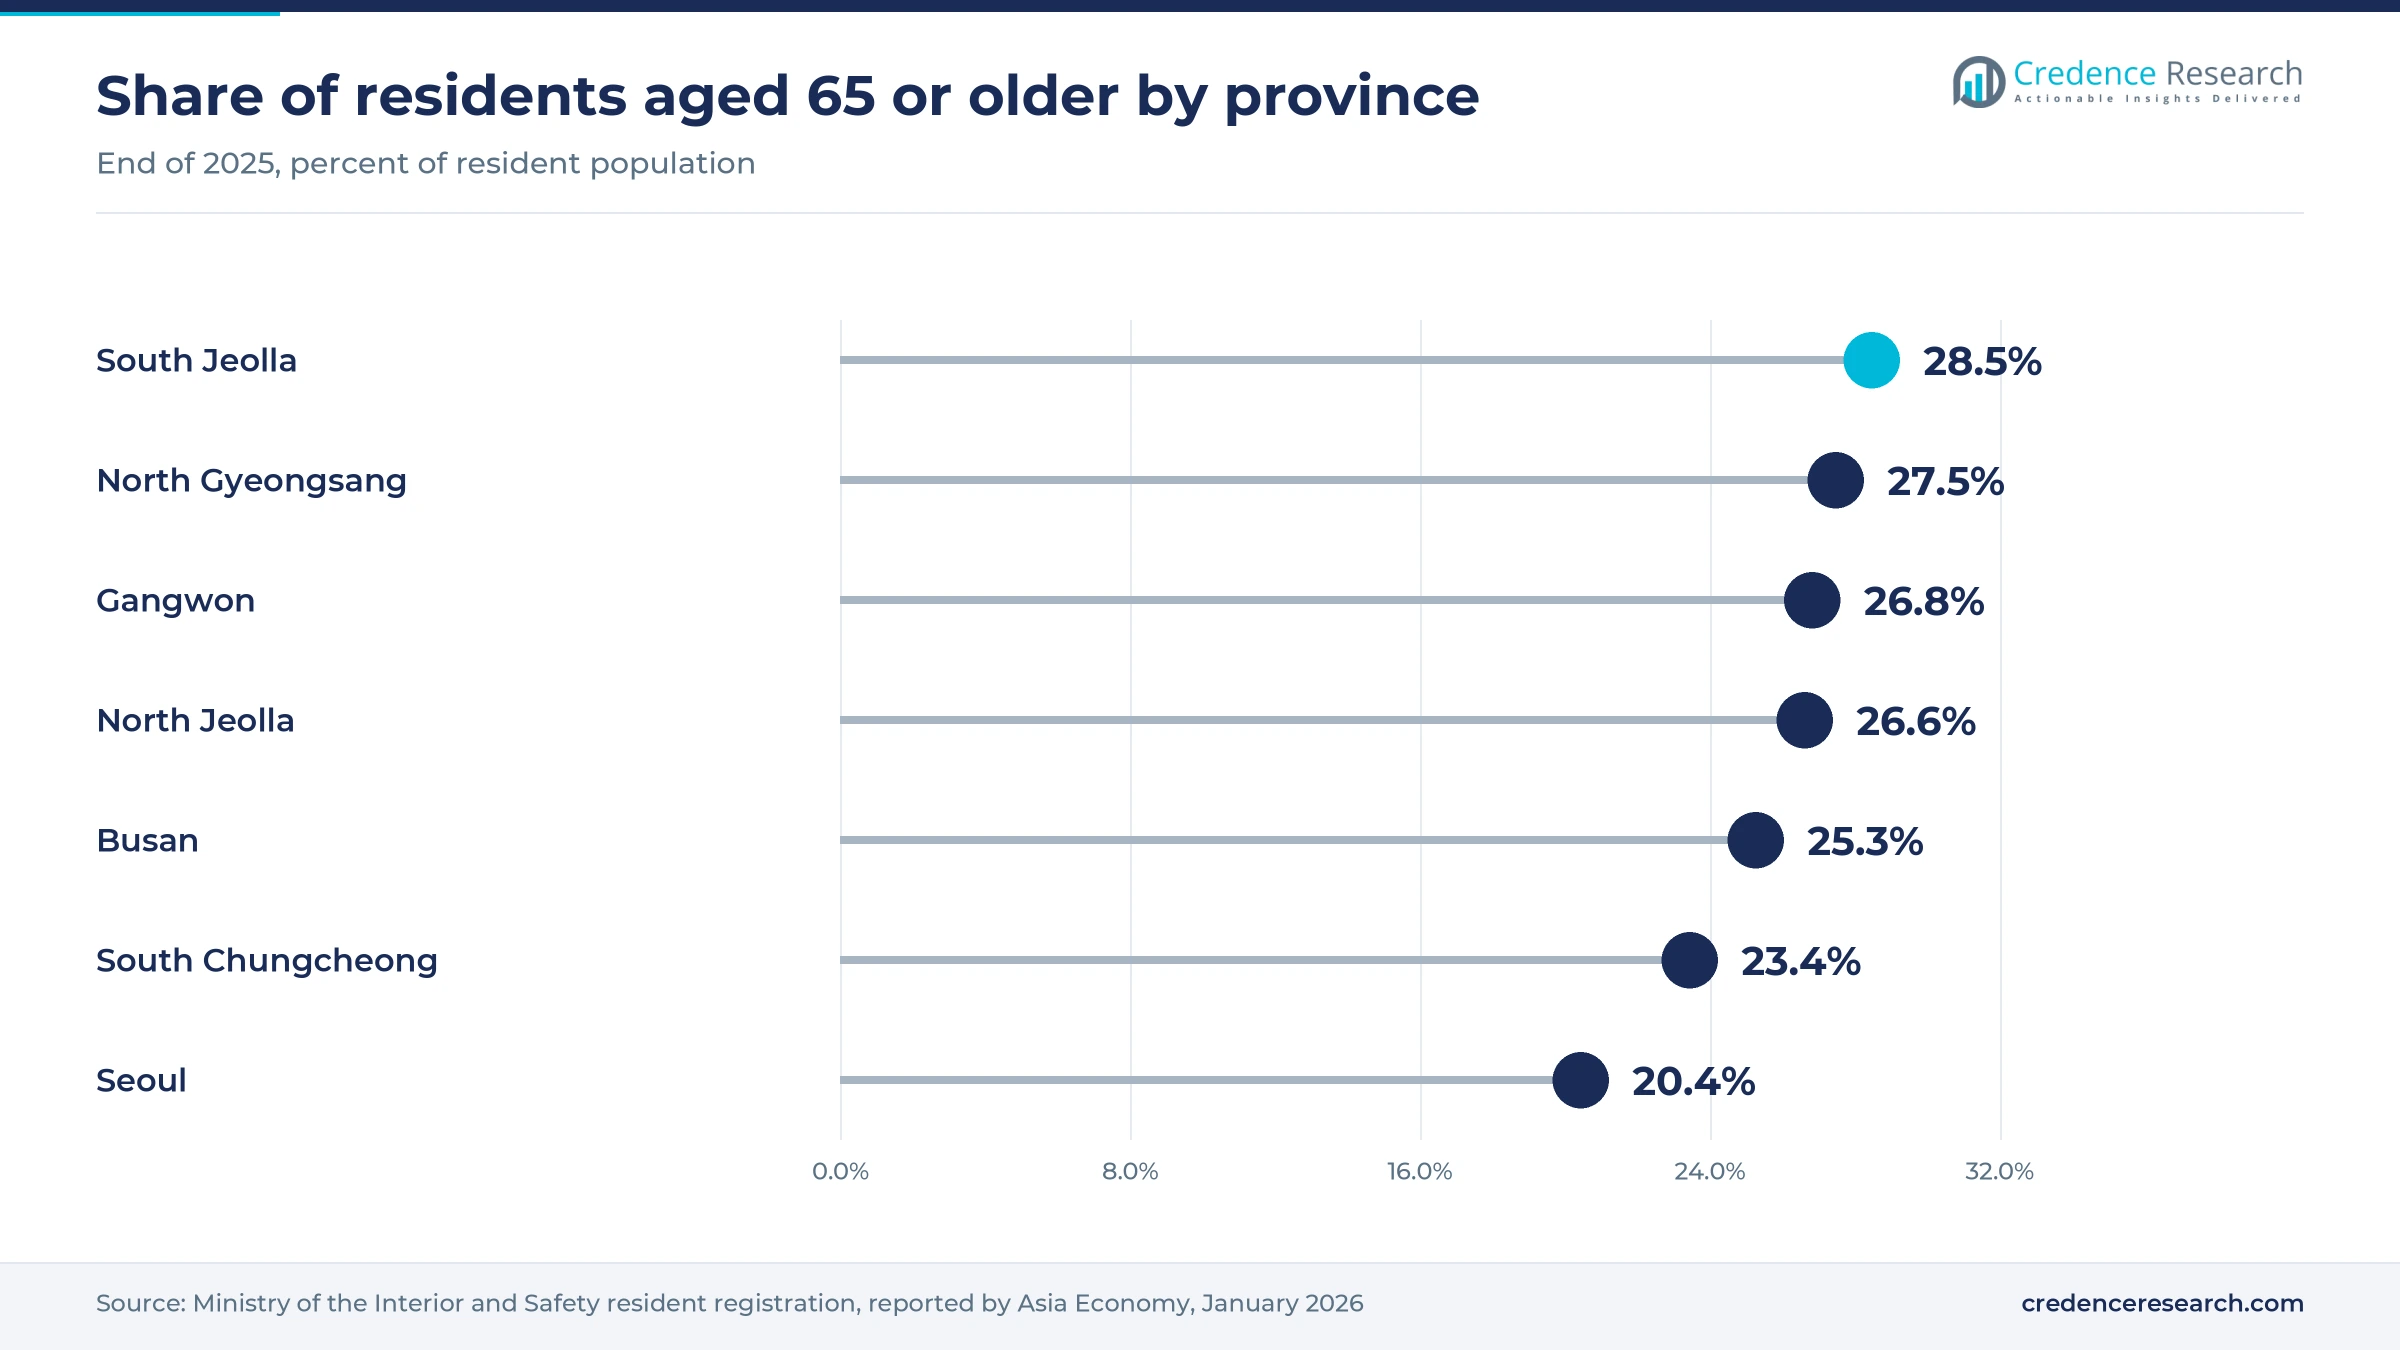
Yeongnam held 22.0% of 2025 value and grows at 6.9% a year. Busan had 25.26% of residents aged 65 or older and North Gyeongsang 27.46% at the end of 2025, among the highest shares in Korea. Inje University Busan Paik Hospital was designated a local heart and stroke center in February 2026. Busan Veterans Hospital has also deployed Huinno's ward telemetry in its cardiology department, EDAILY reported. Demand grows steadily, although Ulsan, an industrial city, recorded one of the lowest infarction rates in 2022.
Chungcheong gains as new centers open near Seoul
Chungcheong held 10.5% of 2025 value and grows at 7.3% a year. South Chungcheong had 23.43% of residents aged 65 or older and North Chungcheong 23.05% at the end of 2025. Cheonan Chungmu Hospital joined the national heart center network in February 2026, while Sejong was still waiting for a local center. Hospitals in Daejeon and Cheonan compete with Seoul for patients who can reach the capital by rail, which limits premium implant volumes.
Honam grows fastest on aging and infarction rates
Honam held 8.5% of 2025 value and grows fastest at 7.6% a year. South Jeolla had the oldest population in Korea, with 28.46% aged 65 or older at the end of 2025, and North Jeolla 26.61%. South Jeolla and Gwangju also had the highest myocardial infarction rates in 2022, at 53.4 and 45.2 per 100,000. Seonggarolo Hospital in Suncheon became a regional hub center in February 2026, which raises demand for angiography, stents and monitoring close to patients.
Gangwon and Jeju build care for remote patients
Gangwon and Jeju held 4.0% of 2025 value and grow at 7.2% a year. Gangwon had 26.81% of residents aged 65 or older at the end of 2025, and Jeju 20.09%. Jeju Halla General Hospital became a local heart center in February 2026, and Gangneung Korea University Hospital uses Huinno's ward telemetry. Long travel times favor remote monitoring and emergency stenting at a few hospitals rather than many small programs.
Approvals, launches and orders from 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In September 2024, Boston Scientific received the first Korean approval for a pulsed field ablation system, FARAPULSE. | Approved; National Health Insurance coverage took effect on May 1, 2026 |
| In December 2024, Severance Hospital performed the first pulsed field ablation procedure in Korea. | Completed; about 35% of its AF ablations now use PFA |
| In December 2025, Dong-A ST's HiCardi wearable telemetry was recognized under the EX871 remote heart rate monitoring code. | Reimbursement recognition; applies to all HiCardi products |
| In March 2026, Medtronic launched the Evolut FX+ transcatheter aortic valve in Korea. | Launched; competes with Edwards Lifesciences' SAPIEN valves |
| In July 2026, Huinno's distribution partner Yuhan Corporation placed a KRW 4 billion supply order for 1,000 beds of MEMO CUE wearable monitoring devices. | Supply order placed by a distributor; deliveries to hospital wards follow from the second half of 2026 |
PFA, leadless pacing and AI reading change procedures
- Pulsed field ablation uses short electric pulses instead of heat or cold to isolate the pulmonary veins, which shortens atrial fibrillation procedures.
- Leadless pacing places a capsule-sized pacemaker inside the heart, and the Micra AV2 launched in Korea in April 2026 lasts about 15.6 years.
- Patch-based telemetry replaces bedside cables with wireless ECG sensors, letting one central station watch up to 300 ward patients.
- AI-assisted reading sizes stents from angiograms and screens ECGs for arrhythmia, which spreads expert reading to hospitals with fewer specialists.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Multinationals lead implants as local firms win monitoring
Competition in the South Korea cardiovascular devices market splits by therapy. In structural heart, Edwards Lifesciences' SAPIEN valve was used in just over half of procedures in the 2015–2017 K-TAVI registry, and Medtronic, Abbott and MicroPort Scientific compete for the patients opened up by the June 2026 rule. In electrophysiology, Boston Scientific, Johnson & Johnson MedTech and Medtronic compete with pulsed field ablation catheters and mapping systems, and FARAPULSE gained National Health Insurance coverage in May 2026. Medtronic, Abbott and BIOTRONIK supply pacemakers, defibrillators and resynchronization devices, and Medtronic also offers the Micra leadless pacemaker. Genoss competes as a domestic maker of drug-eluting coronary stents. In monitoring, Huinno competes with patch telemetry and Holter analysis, while GE HealthCare and Samsung Medison supply ECG, MRI and cardiac ultrasound systems. Clinical data, reimbursement listing and training for hospital teams decide most contracts.
How concentrated is the supply side?
Supply is concentrated in implants and far more open in patient monitoring. Medtronic, Abbott, Boston Scientific, Edwards Lifesciences, Johnson & Johnson MedTech and BIOTRONIK sell most stents, ablation catheters, rhythm devices and valves through Korean subsidiaries. Entry barriers are MFDS approval, HIRA price listing and clinical training for Heart Teams. Monitoring is more crowded, and Korean firms such as Huinno and MeZoo, whose HiCardi patch Dong-A ST distributes, compete with wearable patches. Margins sit mainly in new-generation implants that win higher reimbursement listings.
Key cardiovascular device suppliers active in South Korea
| Company | Type | Role in the market |
|---|---|---|
| Medtronic | Full-line supplier | TAVI valves, leadless pacemakers, rhythm devices and PFA catheters |
| Abbott | Full-line supplier | Structural heart, rhythm management, vascular and heart failure devices |
| Boston Scientific Corporation | Full-line supplier | FARAPULSE pulsed field ablation, mapping, stents and rhythm devices |
| Edwards Lifesciences Corporation | Structural heart specialist | Transcatheter and surgical heart valves, led by the SAPIEN TAVI range |
| Johnson & Johnson MedTech | Electrophysiology specialist | VARIPULSE PFA catheters with CARTO 3 mapping systems |
| BIOTRONIK SE & Co. KG | Specialist | Pacemakers, defibrillators, CRT devices and vascular intervention products |
| GE HealthCare | Imaging and monitoring supplier | ECG, cardiac MRI, cath lab imaging and patient monitoring |
| Samsung Medison (Samsung Electronics) | Local imaging maker | Ultrasound systems with the Heart Assist AI diagnostic aid |
| Genoss | Local manufacturer | Korean-made sirolimus-eluting coronary stents |
| Huinno | Local monitoring specialist | MEMO patch ECG, Holter analysis and ward telemetry under code EX871 |
| MeZoo Co., Ltd. | Local monitoring specialist | HiCardi wireless ECG patch telemetry, distributed in Korea by Dong-A ST |
| MicroPort Scientific | Specialist | Transcatheter aortic valves competing for TAVI share in Korea |
Reimbursement, not evidence, now sets the pace of uptake
Credence Research's view is that Korean cardiovascular spending is moving from volume-driven stenting toward higher-value catheter therapies for older patients. Reimbursement, not clinical evidence, has been the main brake, and the 2026 changes for TAVI, pulsed field ablation and fast-track entry loosen it. Multinational suppliers keep the advantage in implants, where clinical data and training decide contracts. Korean firms are gaining in ward telemetry and AI reading, where software and reimbursement codes matter more than scale. The main risk is hospital capacity, because the walkout showed how quickly procedure volumes fall when teaching hospitals lose staff.
Device market data and procedure fees anchor the estimate
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which starts from the Korean medical device market reported by the Ministry of Food and Drug Safety, applies a cardiovascular share by product group and checks the result against procedure fees, reimbursement changes and the 2025 exchange rate. Segment and regional splits are Credence Research estimates based on resident population, 65+ shares, heart center locations and procedure patterns. Sources include Korean ministries and agencies, the U.S. International Trade Administration, peer-reviewed studies, company announcements and Korean health media. No interviews or surveys were conducted by Credence Research for this edition.
Structural heart and monitoring gain share to 2035
The market is expected to grow from USD 1.43 billion in 2026 to USD 2.59 billion by 2035 as the population ages and coverage widens. Heart valves and structural heart devices grow fastest among surgical devices at 8.7% a year, helped by TAVI for patients in their 70s. Mobile cardiac telemetry grows fastest in monitoring at 9.0% a year as wards replace cables with patches. Honam and Chungcheong gain share as regional heart centers mature, while the Capital Area keeps the largest absolute purchases. Coronary stents stay the largest item but lose share to newer therapies.
Coverage reform and hospital staffing decide the range
The spread between the cases depends on how far Korea widens coverage and how quickly teaching hospitals rebuild procedure capacity after the walkout. A fee reform for TAVI and wider leadless and PFA criteria would move volumes up, while a weaker won and new stent price cuts would hold value down. The base case keeps the 6.80% CAGR through 2035, led by structural heart and monitoring devices.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 5.4% | USD 2.30 billion | Staff shortages persist, the won weakens further and stent ceiling prices are cut again |
| Base | 6.80% | USD 2.59 billion | The June 2026 TAVI rule and May 2026 PFA coverage work as planned with current fees |
| Upside | 8.0% | USD 2.87 billion | TAVI fees are reformed and coverage extends to patients aged 75 and to more leadless cases |
Frequently Asked Questions
How big is the South Korea cardiovascular devices market?
Which region leads the market?
Which device type has the largest share?
How did the 2026 TAVI rule change demand for structural heart devices?
Is pulsed field ablation covered for atrial fibrillation in Korea?
How is wearable ambulatory and ward cardiac monitoring growing?
What are the main challenges for suppliers?
Who are the leading suppliers in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Surgical Devices
- 1.2.2 Diagnostic and Monitoring Devices
- 1.3 By Diagnostic and Monitoring Device Type
- 1.3.1 ECG
- 1.3.2 MRI
- 1.3.3 Holter Monitors
- 1.3.4 Mobile Cardiac Telemetry
- 1.3.5 Implantable Cardiac Monitors
- 1.3.6 Others
- 1.4 By Surgical Device Type
- 1.4.1 Coronary Stents
- 1.4.2 Catheters
- 1.4.3 Heart Valves and Structural Heart Devices
- 1.4.4 Pacemakers
- 1.4.5 Implantable Cardioverter Defibrillators (ICDs)
- 1.4.6 Cardiac Resynchronization Therapy (CRT)
- 1.5 By End User
- 1.5.1 Hospitals and Clinics
- 1.5.2 Diagnostic Laboratories
- 1.5.3 Ambulatory Surgical Centers
- 1.5.4 Home Care and Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.34 billion → 2035: USD 2.59 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 South Korea Cardiovascular Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 South Korea Cardiovascular Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 South Korea Cardiovascular Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 South Korea Cardiovascular Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 South Korea Cardiovascular Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 South Korea Cardiovascular Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 South Korea Cardiovascular Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 South Korea Cardiovascular Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.34 billion → 2035: USD 2.59 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 South Korea Cardiovascular Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Surgical Devices
- 12.3.7.2 Diagnostic and Monitoring Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diagnostic and Monitoring Device Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 ECG
- 12.4.7.2 MRI
- 12.4.7.3 Holter Monitors
- 12.4.7.4 Mobile Cardiac Telemetry
- 12.4.7.5 Implantable Cardiac Monitors
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Surgical Device Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Coronary Stents
- 12.5.7.2 Catheters
- 12.5.7.3 Heart Valves and Structural Heart Devices
- 12.5.7.4 Pacemakers
- 12.5.7.5 Implantable Cardioverter Defibrillators (ICDs)
- 12.5.7.6 Cardiac Resynchronization Therapy (CRT)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospitals and Clinics
- 12.6.7.2 Diagnostic Laboratories
- 12.6.7.3 Ambulatory Surgical Centers
- 12.6.7.4 Home Care and Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 South Korea Cardiovascular Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 South Korea Cardiovascular Devices Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 South Korea Cardiovascular Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 South Korea Cardiovascular Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott
- 18.4 Boston Scientific Corporation
- 18.5 Edwards Lifesciences Corporation
- 18.6 Johnson & Johnson MedTech
- 18.7 BIOTRONIK SE & Co. KG
- 18.8 GE HealthCare
- 18.9 Samsung Medison (Samsung Electronics)
- 18.10 Genoss
- 18.11 Huinno
- 18.12 MeZoo Co., Ltd.
- 18.13 MicroPort Scientific
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

