
Market Overview:
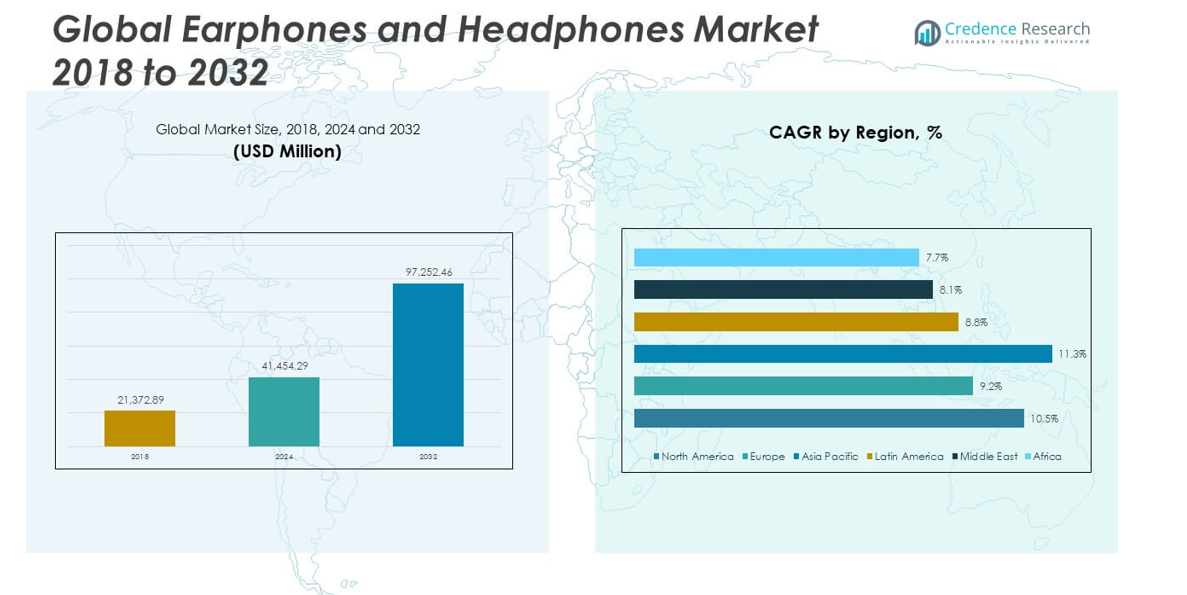
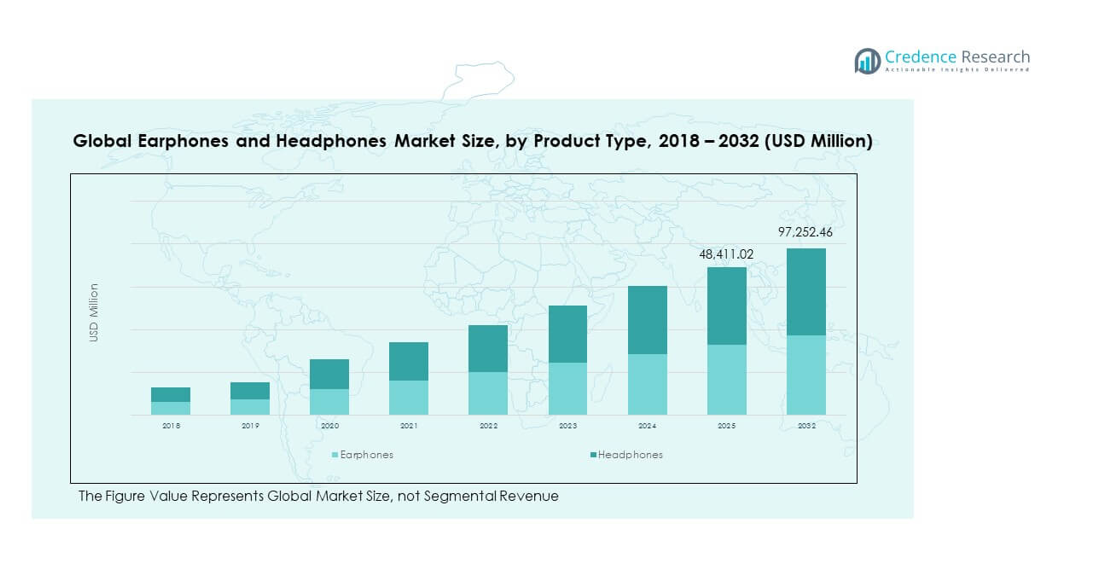
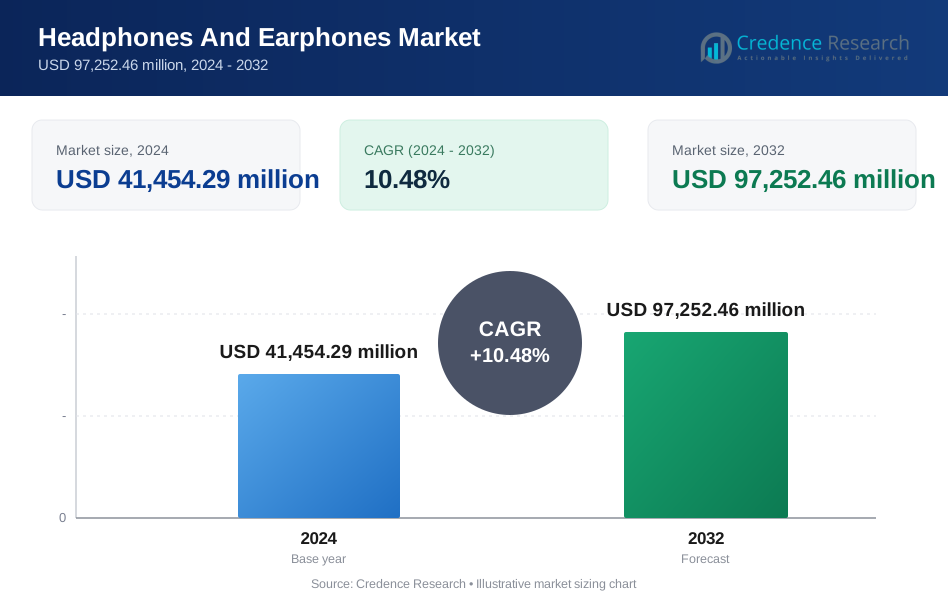
The Global Earphones and Headphones Market size was valued at USD 21,372.89 million in 2018, grew to USD 41,454.29 million in 2024, and is anticipated to reach USD 97,252.46 million by 2032, expanding at a CAGR of 10.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Earphones and Headphones Market Size 2024 | USD 41,454.29 million |
| Earphones and Headphones Market, CAGR | 10.48% |
| Earphones and Headphones MarketSize 2032 | USD 97,252.46 million |
Rising smartphone penetration and growing popularity of music and video streaming services are key drivers of market expansion. The adoption of wireless and noise-canceling technologies has accelerated demand among both professionals and everyday users. Increasing integration of AI voice assistants and health-tracking features in premium earphones enhances product functionality and user experience. Strong marketing by leading brands and frequent product innovations further stimulate consumer interest and brand loyalty.
North America dominates the market due to high disposable incomes, early adoption of smart devices, and strong brand presence. Europe follows, supported by steady demand for high-quality audio products and growing preference for sustainable, energy-efficient devices. The Asia-Pacific region is emerging rapidly, driven by expanding urbanization, rising youth population, and the popularity of affordable, feature-rich models in markets such as China, India, and South Korea.
Market Insights:
- The Global Earphones and Headphones Market was valued at USD 21,372.89 million in 2018, reached USD 41,454.29 million in 2024, and is projected to attain USD 97,252.46 million by 2032, expanding at a CAGR of 10.48% during 2024–2032.
- North America (35%), Asia Pacific (30%), and Europe (27%) collectively account for over 90% of the total revenue share, supported by high consumer spending, strong retail presence, and rapid technology adoption.
- Asia Pacific is the fastest-growing region, driven by rising smartphone usage, online retail expansion, and the growing popularity of affordable True Wireless Stereo (TWS) models in China, India, and Japan.
- Earphones dominate the market with around 60% share in 2024 due to compact size, affordability, and everyday usability, particularly among younger consumers.
- Headphones represent roughly 40% share, with increasing adoption among professionals, gamers, and audiophiles seeking premium noise-cancellation and sound precision.
Market Drivers:
Growing Consumer Preference for Wireless and Smart Audio Devices
The Global Earphones and Headphones Market is expanding rapidly with the increasing preference for wireless technology. Consumers favor Bluetooth-enabled models for convenience and mobility. The rise in smartphone adoption and streaming platforms fuels this demand. Brands are integrating AI assistants and touch controls to improve usability. Advancements in battery efficiency have extended usage time. Compact designs and fast charging options appeal to on-the-go users. It continues to gain momentum from lifestyle changes and the growing use of smart wearables.
- For instance, Sony’s WF-1000XM5 earbuds feature the Dynamic Driver X unit, 8 mm drivers, and dual processors (Integrated Processor V2 + HD Noise Cancelling Processor QN2e) that deliver up to 8 hours of playback (NC ON) and 24 hours with a charging case, supported by Bluetooth 5.3 and LDAC 990 kbps high‑resolution audio streaming.
Rising Demand from Gaming, Fitness, and Remote Work Segments
Gaming headsets with surround sound and noise-cancelling microphones have become essential for immersive play. Fitness enthusiasts prefer sweat-resistant, lightweight, and stable-fitting designs. The remote work boom increased headset demand for virtual meetings and communication. Companies now prioritize voice clarity and comfort in product design. Educational institutions adopting e-learning also contribute to demand. It benefits from multi-device compatibility, catering to PCs, smartphones, and consoles. These diverse applications are driving steady global sales growth.
- For instance, Razer’s BlackShark V2 Pro (2025) offers Triforce Titanium 50 mm drivers, THX Spatial Audio 7.1 surround sound, and up to 70 hours of battery life with HyperSpeed Wireless connectivity for lag‑free performance, designed for esports use.
Technological Advancements and Product Innovation Boosting Market Expansion
Continuous innovation strengthens the market’s growth potential. Brands invest heavily in R&D to integrate adaptive noise cancellation, spatial audio, and biometric sensors. Hybrid active noise-cancelling systems enhance sound quality in various environments. Smart connectivity features like multipoint pairing increase convenience. Customizable equalizers and app integration enable user personalization. It gains traction from smart assistant support and high-resolution audio playback. These advancements elevate consumer experience and brand differentiation.
Strong Brand Competition and Marketing Influence Consumer Behavior
Aggressive marketing campaigns by global brands shape consumer preferences. Collaborations with celebrities and influencers boost visibility and desirability. Product bundling with smartphones and tablets increases accessibility. Retail expansion and online promotions improve reach across demographics. Loyalty programs and limited-edition launches attract repeat buyers. It thrives in regions with high digital media consumption and strong retail infrastructure. Continuous rebranding and product diversification strengthen market dominance.
Market Trends:
Adoption of True Wireless Stereo (TWS) Technology Accelerating Market Growth
True wireless stereo earbuds dominate modern audio consumption trends. Consumers value their portability, comfort, and advanced connectivity. Rapid miniaturization of components allows premium sound in compact designs. Charging case innovations extend battery life and usability. Manufacturers focus on seamless pairing and touch control improvements. The market is shifting from wired and neckband models toward TWS. This trend reinforces premiumization and technological integration across product portfolios.
Integration of Health and Fitness Monitoring Features in Audio Devices
Manufacturers are merging audio technology with wellness functions. Sensors that track heart rate, motion, and calories burned are now integrated into select models. The trend aligns with rising interest in personal fitness and health tracking. It gains support from consumers adopting wearables and smart ecosystems. Brands highlight these features in premium product categories. Health-focused functionality strengthens long-term device engagement. The trend bridges entertainment and wellness technology innovation.
- For instance, Jabra’s Elite 8 Active (2025) is certified to military spec 810H with IP68 durability and integrates motion sensors for step count accuracy and heart rate tracking via the Jabra Sound+ app, enabling seamless fitness data sync across devices .
Sustainability and Eco-Friendly Product Design Gaining Momentum
Manufacturers are emphasizing recyclable materials and sustainable packaging. Consumers are becoming aware of electronic waste issues. Companies are reducing carbon footprints by reusing plastics and metals. Eco-conscious branding influences purchase decisions in mature markets. Regulations encouraging green manufacturing add further pressure. It aligns with global trends in responsible consumption and production. Sustainability now serves as both a moral and competitive advantage.
Growth of Premium Audio and Smart Noise-Cancelling Technologies
Premium headphones with adaptive sound settings attract professionals and travellers. Active noise cancellation (ANC) technology enhances listening experiences in noisy settings. AI-based sound optimization personalizes output to user preference. The integration of hi-res audio codecs improves clarity and richness. It benefits from the growing demand for luxury audio brands. Manufacturers are investing in multi-mode ANC and ambient awareness features. This trend highlights user-centric innovation and evolving sound expectations.
Market Challenges Analysis:
Price Sensitivity and Intense Market Competition Restraining Profit Margins
The Global Earphones and Headphones Market faces pricing pressure due to high competition. Numerous brands compete across low, mid, and premium segments. Price-sensitive consumers in developing regions limit margins for manufacturers. Counterfeit products disrupt genuine sales and damage brand credibility. Frequent product launches create inventory and differentiation challenges. Smaller players struggle to compete with global brands’ marketing budgets. It must address affordability while maintaining product quality and innovation.
Technical Limitations, Battery Life, and Connectivity Issues Affecting User Experience
Battery performance remains a critical challenge, especially for wireless and TWS devices. Shorter usage durations deter long-term customer satisfaction. Connectivity issues such as lag and pairing failures frustrate users. Compatibility problems with different devices reduce consumer confidence. Component shortages and logistics disruptions impact timely product availability. Environmental durability, like water and dust resistance, also affects reliability. It needs consistent technological improvement to overcome these operational constraints.
Market Opportunities:
Emergence of Smart Ecosystems and Expanding IoT Integration
The Global Earphones and Headphones Market is positioned to benefit from IoT connectivity. Smart home integration and voice assistants enhance user engagement. Brands can create cross-device ecosystems that increase loyalty. Opportunities exist in linking headphones with wearables, TVs, and smart speakers. It can leverage AI-driven personalization to deliver adaptive sound experiences. Expanding compatibility across digital platforms widens product appeal.
Rapid Urbanization and Evolving Consumer Lifestyle Driving Adoption
Urban populations continue to embrace premium lifestyle products. Growth in digital media, entertainment, and e-commerce supports market penetration. Fashion-conscious consumers view earphones as both accessories and tech devices. The demand for stylish, durable, and multifunctional models is rising. It can capitalize on regional e-retail expansion and influencer-driven marketing. Increasing youth demand for affordable yet feature-rich products enhances future opportunities.
Market Segmentation Analysis:
By Product Type
In-ear earphones hold the largest share due to their compact design and affordability. They cater to daily commuters, fitness users, and smartphone owners seeking portability. On-ear models appeal to casual listeners seeking comfort and moderate sound isolation. Over-ear headphones gain demand from professionals and audiophiles valuing superior soundstage and noise cancellation. The growing trend toward hybrid and adaptive sound models is expanding choices across these product types.
- For instance, Bose’s QuietComfort Ultra (2025) features 10 microphones and Adaptive Audio processing that automatically adjusts noise cancellation levels, delivering up to 24 hours of wireless playback for travel and mixed‑use scenarios .
By Connectivity
Wireless and True Wireless Stereo (TWS) segments dominate the market, driven by convenience and advanced Bluetooth technology. TWS models are favored for portability and long battery life. Wired headphones retain presence in professional studios and among cost-conscious users. It continues to experience a rapid shift toward wireless ecosystems, supported by smartphone brands eliminating audio jacks and improving connectivity standards.
- For instance, in December 2024, the Bluetooth SIG announced the upcoming High Data Throughput (HDT) enhancement for Bluetooth LE. HDT will eventually enable transmission speeds of up to 7.5 or 8 Mbps over the existing 2.4 GHz band to support high-resolution and lossless audio.
By Price Range
The medium price segment accounts for the majority of global demand due to balanced quality and affordability. Premium models attract professionals and enthusiasts seeking enhanced features such as active noise cancellation, spatial audio, and smart controls. Low-priced models remain popular in developing economies due to wider accessibility and budget constraints.
By Distribution Channel
Online sales are rising rapidly due to convenience, broad product variety, and promotional pricing. Offline channels, including specialty stores and retail chains, continue to provide hands-on experience and after-sales service. It benefits from omnichannel strategies combining online accessibility with offline trust.
By Application
Consumer applications dominate, fueled by entertainment and personal audio use. Professional and gaming segments show fast growth due to advanced sound demand and ergonomic designs. Sports-focused models gain traction for their durability and water resistance, expanding the user base further.
Segmentation:
By Product Type:- In-Ear
- On-Ear
- Over-Ear
- Wired
- Wireless
- True Wireless Stereo (TWS)
- Low
- Medium
- Premium
- Online
- Offline
- Specialty Stores
- Retail Chains
- Consumer
- Professional
- Sports
- Gaming
- Others
- China
- Japan
- India
- South Korea
- Australia
- Taiwan
- Singapore
- Thailand
- Indonesia
- Malaysia
- Vietnam
- Philippines
- New Zealand
- Rest of Asia Pacific
Regional Analysis:
North America
The North America Earphones and Headphones Market size was valued at USD 6,141.39 million in 2018, increased to USD 11,723.69 million in 2024, and is anticipated to reach USD 27,620.67 million by 2032, at a CAGR of 10.5% during the forecast period. North America holds the largest regional share of approximately 35% of the Global Earphones and Headphones Market. The region’s dominance stems from strong consumer purchasing power, high smartphone penetration, and widespread adoption of premium wireless audio devices. Leading brands such as Apple, Bose, and JBL continue to expand their product portfolios through AI integration and enhanced battery performance. The growing popularity of streaming services and mobile gaming also boosts market demand. It benefits from technological innovation, strong retail infrastructure, and early adoption of noise-canceling and spatial audio technologies.
Europe
The Europe Earphones and Headphones Market size was valued at USD 3,958.99 million in 2018, grew to USD 7,254.78 million in 2024, and is anticipated to reach USD 15,463.79 million by 2032, at a CAGR of 9.2% during the forecast period. Europe accounts for around 27% of the global market share, supported by the region’s growing preference for sustainable, high-fidelity, and eco-friendly headphones. Countries such as Germany, the UK, and France lead demand due to advanced consumer electronics ecosystems. The hybrid work trend fuels adoption of headsets designed for professional communication and remote collaboration. Strong R&D activities and environmental regulations are shaping innovation toward recyclable materials and lower energy consumption. It maintains growth through established brands like Sennheiser, Philips, and Sony emphasizing durability and audio precision.
Asia Pacific
The Asia Pacific Earphones and Headphones Market size was valued at USD 9,325.95 million in 2018, surged to USD 18,757.24 million in 2024, and is projected to reach USD 46,692.85 million by 2032, expanding at a CAGR of 11.3%. The region commands nearly 30% of the global share and is the fastest-growing regional market. Rapid urbanization, rising disposable incomes, and mass smartphone adoption drive growth across China, India, Japan, and South Korea. Local manufacturers like boAt, Xiaomi, and Realme are expanding through affordable yet feature-rich TWS models. Increasing demand for e-learning, fitness wearables, and digital entertainment supports market expansion. It benefits from strong online retail penetration, influencer marketing, and aggressive competition among regional and global brands.
Latin America
The Latin America Earphones and Headphones Market size was valued at USD 988.16 million in 2018, grew to USD 1,892.28 million in 2024, and is expected to reach USD 3,918.04 million by 2032, at a CAGR of 8.8% during the forecast period. Latin America contributes about 4% to the global market share, with Brazil and Mexico as primary growth hubs. The increasing popularity of online entertainment and music streaming services stimulates earphone sales. The demand for affordable wireless audio products is rising with expanding internet penetration and e-commerce accessibility. It continues to evolve with strong youth adoption and growing awareness of personal audio quality. Localized marketing campaigns and brand collaborations with telecom providers enhance regional distribution efficiency.
Middle East
The Middle East Earphones and Headphones Market size was valued at USD 584.45 million in 2018, increased to USD 1,033.83 million in 2024, and is anticipated to reach USD 2,036.38 million by 2032, at a CAGR of 8.1%. The region holds roughly 3% of the global market share. The market growth is supported by increasing urbanization, high smartphone usage, and rising demand for wireless products in countries like the UAE and Saudi Arabia. Consumers show growing interest in luxury audio brands, driven by fashion and lifestyle influences. E-commerce platforms play a key role in expanding product accessibility. It benefits from partnerships between electronics retailers and global brands targeting tech-savvy youth populations.
Africa
The Africa Earphones and Headphones Market size was valued at USD 373.94 million in 2018, increased to USD 792.48 million in 2024, and is forecast to reach USD 1,520.73 million by 2032, at a CAGR of 7.7%. Africa contributes around 2% to the overall market share. Growing smartphone ownership and mobile music consumption are creating opportunities for affordable earphone brands. Urban centers like South Africa, Nigeria, and Kenya are driving demand through e-commerce growth and youth-oriented promotions. Rising awareness of digital content and local music platforms supports steady adoption. It continues to expand through low-cost imports and increasing retail digitization.
Key Player Analysis:
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Sony Corporation
- Bose Corporation
- Sennheiser Electronic GmbH & Co. KG
- JBL (Harman International)
- Xiaomi Corporation
- Oppo Electronics Corp.
- OnePlus Technology
- Realme
- boAt
- Noise
- Audio-Technica Corporation
- Shure Incorporated
- Skullcandy Inc.
- Anker Innovations (Soundcore)
- Edifier International
- QCY
- 1MORE
Competitive Analysis:
Leading global audio brands compete vigorously in the Global Earphones and Headphones Market. Apple, Sony, Samsung, Bose, and JBL dominate through consistent product innovation and strong global presence. They invest heavily in R&D to integrate noise cancellation, spatial audio, and AI features. Smaller and niche firms like Shure, Skullcandy, and 1MORE differentiate via specialty sound quality or design. Distribution partnerships and brand positioning further elevate competition. It demands rapid response to market shifts, sound trends, and consumer expectations.
Recent Developments:
- In September 2025, Apple Inc. introduced the AirPods Pro 3, elevating its renowned headphone lineup with innovations like advanced noise cancellation, onboard camera remote capability, and live translation features designed to optimize the global audio experience. In a move to maintain its technology leadership, Samsung Electronics Co., Ltd. is poised to launch its collaborative Project Moohan XR headset, developed in partnership with Google and Qualcomm, at the “World’s Wide Open” virtual event on October 21, 2025, promising a cutting-edge 4K Micro OLED display and enhanced AI features for headphone and audio markets.
- In July 2025, Sony Corporation became the official technology partner for the NFL, with a partnership that will see new Sony-developed coach’s sideline headsets debut for the 2025 season, leveraging its noise-canceling expertise and audio technologies also recognized in its consumer headphone ranges.
Report Coverage:
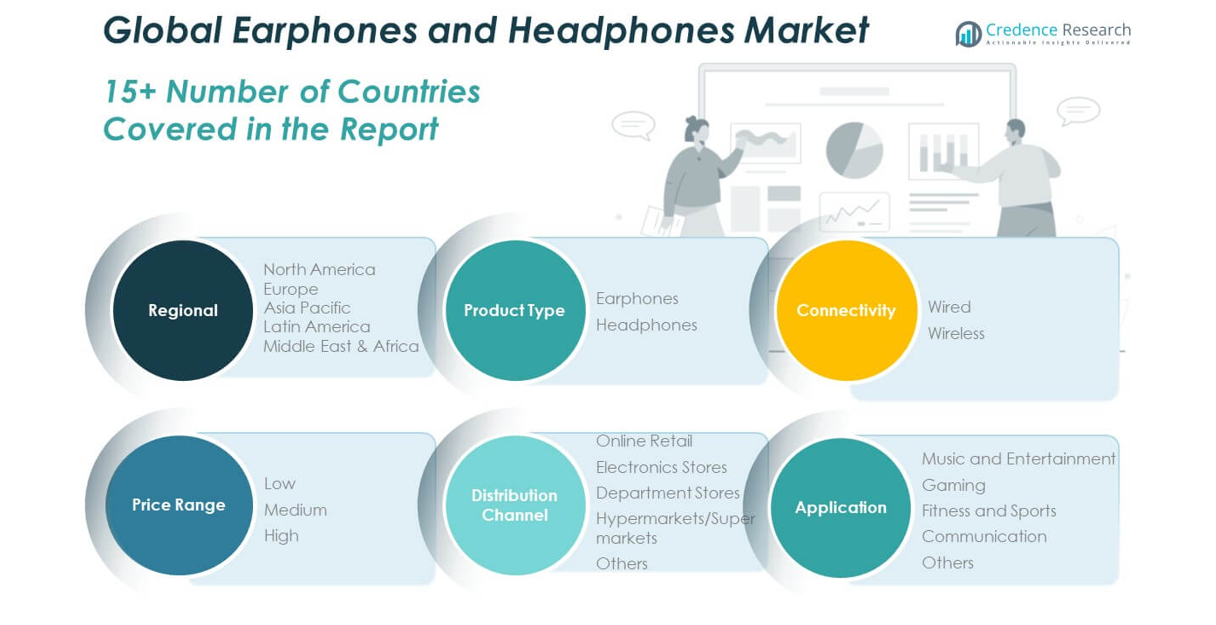
The research report offers an in-depth analysis based on product type, connectivity, price range, distribution channel, and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Greater convergence of audio devices with smart home systems
- Expansion in biometric and health-sensing features
- Stronger focus on sustainability and recyclable materials
- Rising adoption of spatial and immersive audio formats
- TWS models continue to capture new users
- Expansion of direct-to-consumer and subscription bundles
- Increased regional manufacturing to reduce supply chain risks
- Growth in gaming and virtual reality headsets
- Penetration into emerging economies via lower-cost variants
- Heightened competition from non-traditional tech entrants
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Consumer Preference for Wireless and Smart Audio Devices
Consumers increasingly favor wireless and Bluetooth-enabled earphones and headphones for their convenience, mobility, and integration with smart devices. The elimination of audio jacks in smartphones and advancements in battery life and connectivity are accelerating the shift toward wireless and TWS models.
Rising Demand from Gaming, Fitness, and Remote Work Segments
The proliferation of gaming, fitness activities, and remote work has driven demand for specialized audio devices with features like surround sound, sweat resistance, and noise-cancelling microphones. These segments require high-quality, comfortable, and multi-device compatible products, fueling market growth.
Technological Advancements and Product Innovation
Continuous R&D investment has led to innovations such as adaptive noise cancellation, spatial audio, biometric sensors, and AI voice assistants. These features enhance user experience, differentiate brands, and encourage consumers to upgrade to newer, more advanced models.
Expansion of Online Retail and Omnichannel Distribution
The growth of e-commerce and omnichannel strategies has made a wide variety of earphones and headphones accessible to consumers globally. Online platforms offer convenience, competitive pricing, and broad product selection, supporting rapid market penetration, especially in emerging economies.
Integration of Health and Fitness Monitoring Features
Manufacturers are embedding health-tracking sensors and fitness monitoring capabilities into premium audio devices, appealing to health-conscious consumers. This convergence of audio and wellness technology increases device utility and drives adoption among users seeking multifunctional products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Earphones and Headphones Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Earphones and Headphones Market projected to grow between 2024
What are some challenges faced by the Earphones and Headphones Market?
Who are the major players in the Earphones and Headphones Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Consumer
- 1.2.2 Professional
- 1.2.3 Sports
- 1.2.4 Gaming
- 1.2.5 Others
- 1.3 By Price Range
- 1.3.1 Low
- 1.3.2 Medium
- 1.3.3 Premium
- 1.4 By Connectivity
- 1.4.1 Wired
- 1.4.2 Wireless
- 1.4.3 True Wireless Stereo (TWS)
- 1.5 By Product Type
- 1.5.1 In-Ear
- 1.5.2 On-Ear
- 1.5.3 Over-Ear
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 41,454.29 million → 2032: USD 97,252.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Headphones And Earphones Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Headphones And Earphones Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Headphones And Earphones Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Headphones And Earphones Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Headphones And Earphones Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Headphones And Earphones Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Headphones And Earphones Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Headphones And Earphones Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 41,454.29 million → 2032: USD 97,252.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Headphones And Earphones Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer
- 12.3.7.2 Professional
- 12.3.7.3 Sports
- 12.3.7.4 Gaming
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low
- 12.4.7.2 Medium
- 12.4.7.3 Premium
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Connectivity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wired
- 12.5.7.2 Wireless
- 12.5.7.3 True Wireless Stereo (TWS)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 In-Ear
- 12.6.7.2 On-Ear
- 12.6.7.3 Over-Ear
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Headphones And Earphones End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Headphones And Earphones Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Headphones And Earphones Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Headphones And Earphones Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Apple Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsung Electronics Co., Ltd.
- 18.4 Sony Corporation
- 18.5 Bose Corporation
- 18.6 Sennheiser Electronic GmbH & Co. KG
- 18.7 JBL (Harman International)
- 18.8 Xiaomi Corporation
- 18.9 boAt
- 18.10 Shure Incorporated
- 18.11 Skullcandy Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

