
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Video Streaming Market Size 2024 | USD 1,95,295.88 million |
| Video Streaming Market, CAGR | 21.45% |
| Video Streaming Market Size 2032 | USD 9,20,875.25 million |
Market Overview:
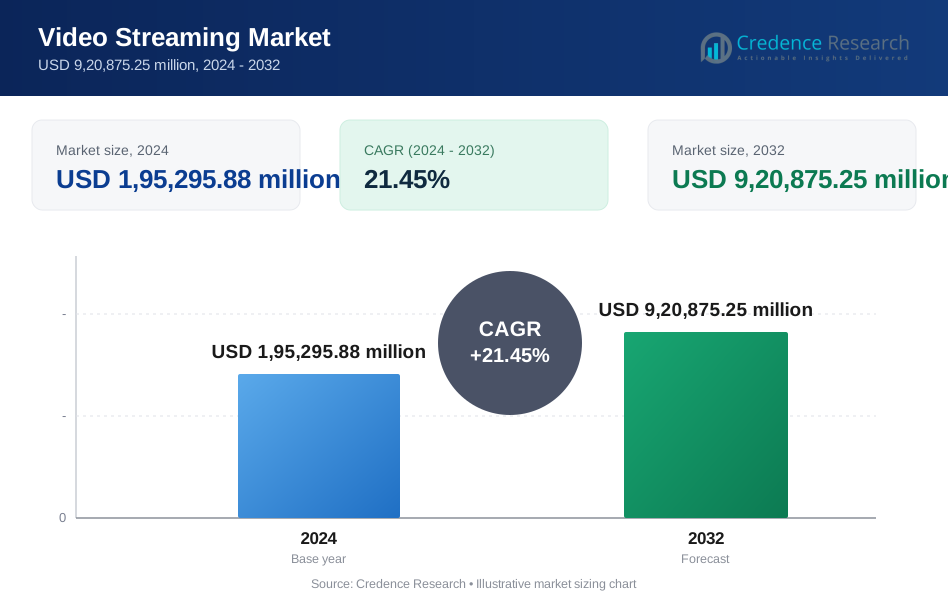
The Global Video Streaming Market size was valued at USD 1,02,300.00 million in 2018 to USD 1,95,295.88 million in 2024 and is anticipated to reach USD 9,20,875.25 million by 2032, at a CAGR of 21.45% during the forecast period.
Several key drivers continue to fuel the rapid expansion of the Global Video Streaming Market. One of the most significant is the increasing adoption of over-the-top (OTT) platforms that allow users to stream content directly without relying on cable or satellite services. Services like Netflix, Amazon Prime Video, Disney+, and regional OTTs have revolutionized how content is consumed, leveraging subscription-based and ad-supported models to cater to diverse demographics. The rise of hybrid monetization strategies-combining SVOD (Subscription Video on Demand) and AVOD (Advertising Video on Demand)-has allowed platforms to reach broader audiences while improving revenue generation. In parallel, technological advancements such as 5G, artificial intelligence (AI), machine learning (ML), and cloud computing are enhancing the quality and reliability of video delivery. These innovations support real-time analytics, personalized content recommendations, adaptive streaming quality, and dynamic ad insertion, improving the overall user experience. The growth of live streaming is another major factor, particularly in gaming, sports, concerts, corporate events, and influencer-led content.
Regionally, North America continues to dominate the Global Video Streaming Market, accounting for the largest revenue share in 2024 due to the widespread adoption of high-speed internet, early rollout of advanced streaming technologies, and the presence of major global content providers and technology firms. Europe follows closely, with strong demand for both local and international content, supported by stringent regulatory frameworks that promote local production and protect user privacy. Countries such as the U.K., Germany, and France have seen a surge in platform-specific investments, including original content development and multilingual support to enhance regional appeal. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing market, driven by increasing smartphone penetration, affordable mobile data plans, and the rapid digitization of media services in countries such as India, China, Indonesia, and South Korea. Regional players are gaining traction by offering localized content and pricing models that align with diverse consumer segments. In Latin America, the Middle East, and Africa, growth remains promising due to ongoing infrastructure development and rising internet adoption. Local content creation, telco partnerships, and mobile-first strategies are expected to drive expansion in these regions over the next decade.

Market Insights:
- The global video streaming market grew from USD 102,300 million in 2018 to approximately USD 195,296 million in 2024 and is expected to reach over USD 920,875 million by 2032, expanding at a CAGR of 21.45%.
- Widespread deployment of 4G and 5G networks, and increasing smartphone and smart device use, are enabling seamless access to video streaming across both urban and remote locations, boosting daily consumption.
- The popularity of OTT platforms such as Netflix, Amazon Prime Video, and Disney+ is rapidly transforming content viewing habits, using hybrid monetization models (subscriptions, ad-supported, transactional) to attract a broader audience.
- Cloud-based content delivery and AI-driven analytics support real-time video encoding, highly personalized recommendations, and adaptive streaming, ensuring reliability and user satisfaction at scale.
- Interactive and immersive formats-including live streaming, AR/VR experiences, 360° videos, and real-time audience engagement-are gaining traction, particularly in gaming, e-sports, virtual events, and educational content.
- High costs for producing and licensing quality content challenge profitability, especially for new streaming entrants facing competition for talent and exclusive rights.
- Infrastructure gaps and limited bandwidth in regions of Africa, Latin America, and rural Asia restrict streaming quality through buffering or low-resolution playback, but ongoing investment is improving coverage and service reliability. North America leads the market, with Europe following on strong local content and Asia-Pacific seeing the fastest growth thanks to mobile-first strategies and regional content localization.
Market Drivers:
Growing Penetration of Digital Infrastructure and Devices:
The Global Video Streaming Market continues to benefit from growing internet connectivity and smartphone usage worldwide. The spread of 4G and rollout of 5G networks facilitate fast, buffer-free video consumption, especially in mobile-first economies. Smart TVs, tablets, and connected devices enhance user accessibility across multiple screens. This transformation is reshaping entertainment habits, with users spending increasing hours streaming content daily. Device affordability and better network infrastructure are creating inclusive access to streaming platforms, even in remote areas.
- For instance, Samsung reported that its Tizen OS-powered Smart TVs delivered over 12 billion streaming hours in 2023 globally, highlighting how integrated 5G and broadband connectivity with apps like Netflix and YouTube support uninterrupted ultra-HD streaming in over 190 countries.
Rise of Over-the-Top (OTT) Services and Subscription Models:
The adoption of OTT platforms has surged globally due to consumer preference for ad-free, personalized, and on-demand content. Services such as Netflix, Amazon Prime, and Disney+ dominate this space, offering vast libraries of movies, series, and documentaries. The Global Video Streaming Market is increasingly shaped by hybrid monetization models, combining subscription (SVOD), ad-supported (AVOD), and transactional (TVOD) formats. Flexible pricing, multiple device support, and exclusive content boost subscriber retention and platform loyalty.
- For instance, Netflix reached 269.6 million paid global subscribers as of March 31, 2024, according to its official Q1 2024 earnings report.
Cloud-Based Video Delivery and Technological Integration:
Cloud computing plays a critical role in the video streaming ecosystem. The Global Video Streaming Market relies on cloud platforms for scalable content storage, real-time encoding, and global distribution. Companies utilize cloud-based solutions to reduce operational overhead, enhance reliability, and deliver adaptive streaming across regions. Integration of AI and machine learning improves metadata tagging, user behavior analysis, and recommendation accuracy. Cloud-native architectures ensure smooth delivery of ultra-HD and 4K content to large audiences simultaneously.
Growing Demand for Interactive and Immersive Streaming Experiences:
Consumer demand for immersive experiences is pushing streaming platforms to innovate beyond traditional formats. Interactive content, AR/VR streaming, 360-degree videos, and real-time audience engagement tools are transforming viewer participation. The Global Video Streaming Market leverages gamification elements, live chats, and in-stream purchasing to enhance monetization and viewer satisfaction. These advancements are particularly evident in sports, e-sports, education, and virtual concerts where active participation boosts brand engagement and advertising value.
Market Trends:
Emergence of Free Ad-Supported Streaming Television (FAST):
FAST platforms are disrupting traditional business models by offering free content supported entirely by advertisements. Platforms such as Pluto TV and Tubi are seeing increased adoption, especially in cost-sensitive markets. The Global Video Streaming Market is witnessing a rise in hybrid content delivery where AVOD and FAST complement premium SVOD offerings. This model appeals to users reluctant to pay for subscriptions and creates revenue streams through programmatic advertising.
- For instance, Pluto TV, a leader in the FAST segment, reported more than 80 million global monthly active users in 2024. Viewers consumed billions of minutes of ad-supported content each month across over 50 international markets.
Demand for Multi-Device and Multi-Screen Streaming Capabilities:
Viewers expect a seamless experience across phones, tablets, laptops, and smart TVs. The Global Video Streaming Market is driven by cross-device compatibility, allowing users to switch devices without losing viewing progress. Services are prioritizing responsive design, cross-platform synchronization, and cloud DVR capabilities. Multi-screen streaming has become a standard expectation, especially in households with shared accounts and varying content preferences.
- For instance, Disney+ allows up to four concurrent streams per account and supports content downloads on up to ten devices. These standards are officially confirmed for 2024, with streams available in up to 4K UltraHD resolution.
Localization and Expansion of Regional Content Libraries:
The success of streaming platforms now depends heavily on regional content production and localization. The Global Video Streaming Market benefits from rising investments in native language content, subtitling, and dubbing. Platforms are forming partnerships with local production houses to expand culturally relevant libraries. Regional originals are gaining popularity, especially in Asia Pacific and Latin America, where language-specific entertainment drives subscriber growth.
Evolution of Live Streaming and Real-Time Interaction:
Live streaming is gaining traction in news, sports, gaming, and e-commerce. The Global Video Streaming Market incorporates real-time features such as live polls, chats, and influencer-led product promotions. Platforms like Twitch, YouTube Live, and Facebook Live have transformed passive viewing into interactive communities. This trend is enabling deeper user engagement, data collection, and targeted advertising based on live user behavior.
Market Challenges Analysis:
High Cost Structure and Content Licensing Intensifies Competition:
The Global Video Streaming Market faces significant hurdles due to the escalating costs of content creation and licensing. Major platforms must compete fiercely for premium programming, exclusive rights, and talent, resulting in substantial investment commitments that squeeze profit margins. New entrants struggle to build attractive content libraries against deep-pocketed incumbents. Intense competition for intellectual property rights limits access to sought-after titles and increases reliance on expensive original programming. Regulatory demands for locally produced content add to financial pressures, especially in markets with strict quotas. Sophisticated rights management and anti-piracy measures incur additional operational expenses. These dynamics often force smaller providers to consolidate or seek niche strategies to remain relevant.
Quality of Service and Infrastructure Constraints Impact Global User Experience:
Quality of service inconsistencies present ongoing challenges for the Global Video Streaming Market, particularly in regions with limited broadband and digital infrastructure. Buffering, latency, and restricted streaming resolution erode user satisfaction, hampering subscriber growth outside established markets. Providers must invest heavily in content delivery networks and edge computing deployments to support reliable service at scale. Rapid increases in concurrent viewership during live events place added strain on networks, requiring robust capacity management. Power outages and last-mile connectivity gaps create service inconsistencies in developing economies. Security and privacy threats to user data, coupled with evolving regulatory requirements, complicate global expansion and introduce compliance risks. It must adapt its delivery and support frameworks to maintain audience engagement and scale operations across diverse geographic and technological landscapes.
Market Opportunities:
Expansion Across Emerging Markets and Untapped Demographics:
The Global Video Streaming Market presents vast opportunities in emerging economies, where rising internet penetration and smartphone adoption accelerate digital content consumption. It can cater to new audiences by offering localized programming, regional language support, and culturally relevant content. Many governments promote digital inclusion, creating a favorable environment for market entry and subscriber growth. Platforms that develop pricing models suited to varying income levels increase their addressable market dramatically. Partnerships with local telecom operators and device manufacturers enable wider distribution and user acquisition. The regional focus on live events, education, and sports allows platforms to differentiate their offerings and win market share.
Technological Advancements Drive Innovative User Experiences:
Rapid progress in cloud computing, AI, and 5G unlocks new growth avenues for the Global Video Streaming Market. It can harness these technologies to improve personalization, content discovery, and streaming quality. Platforms that invest in immersive features such as augmented reality, virtual reality, and interactive content elevate viewer engagement and boost retention. AI-driven analytics support smarter advertising, content recommendations, and predictive maintenance, increasing operational efficiency. Edge computing solutions help deliver ultra-low latency, enhancing live broadcasts and gaming. The push for technological integration supports scalable service delivery and enables platforms to manage global growth seamlessly.
Market Segmentation Analysis:
By Type
Live Video Streaming powers real-time content for events, sports, and entertainment, driving continuous user engagement and advertising value. Non-Linear Video Streaming enables on-demand content access, fueling the binge-watching trend and enhancing user choice across multiple genres.
- For instance, Amazon Prime Video’s live streams of Thursday Night Football in 2023 drew an average audience of 11.86 million viewers per game, using low-latency streaming technology for simultaneous, multi-device coverage across mobile, desktop, and smart TVs.
By Solution
Internet Protocol TV (IPTV) offers managed, high-quality streams, attracting traditional broadcasters and telecom operators. Over-the-Top (OTT) services dominate through direct-to-consumer platforms that bypass legacy distribution, supporting flexible business models and expanding international reach. Pay-TV remains relevant, catering to markets seeking premium content and bundled solutions.
By End-User
The market serves Enterprises leveraging video for communications, training, marketing, and virtual collaborations. Real-Time Entertainment, Web Browsing & Advertising, Gaming, Social Networking, and E-Learning represent dynamic consumer segments, driving innovation in user interface, content formats, and personalized recommendations.
By Service Industry
The focus rests on Consulting, Managed Services, and Training & Support. These segments ensure optimal platform integration, security, and operational efficiency, helping clients scale technology investments and boost service reliability.
By Platform
The market supports Gaming Consoles, Laptops & Desktops, Smartphones & Tablets, and Smart TVs as critical access points. It ensures multi-device compatibility to reach diverse audiences, adapting interfaces and functionality to changing consumer behaviors in a digital-first ecosystem.

Segmentation:
- By Type
- Live Video Streaming
- Non-Linear Video Streaming
- By Solution
- Internet Protocol TV (IPTV)
- Over-the-Top (OTT)
- Pay-TV
- By End-User
- Enterprise
- Corporate Communications
- Knowledge Sharing & Collaborations
- Marketing & Client Engagement
- Training & Development
- Consumer
- Real-Time Entertainment
- Web Browsing & Advertising
- Gaming
- Social Networking
- E-Learning
- By Service Industry
- Consulting
- Managed Services
- Training & Support
- By Platform
- Gaming Consoles
- Laptops & Desktops
- Smartphones & Tablets
- Smart TV
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Video Streaming Market size was valued at USD 32,173.35 million in 2018 to USD 60,560.08 million in 2024 and is anticipated to reach USD 2,85,104.64 million by 2032, at a CAGR of 21.5% during the forecast period. It leads the market with robust internet infrastructure, early tech adoption, and strong presence of OTT giants like Netflix and Hulu. High disposable income and premium content offerings fuel subscriber growth. Innovation in user experience, AI-driven personalization, and smart TV integration support continued dominance.
Europe
The Europe Video Streaming Market size was valued at USD 28,081.35 million in 2018 to USD 51,611.36 million in 2024 and is anticipated to reach USD 2,30,451.48 million by 2032, at a CAGR of 20.6%. Strong broadband networks, multilingual content, and regulatory compliance foster healthy growth. European users are embracing regional content alongside global productions. Partnerships with telecom operators and device manufacturers enhance distribution channels.
Asia Pacific
The Asia Pacific Video Streaming Market size was valued at USD 29,564.70 million in 2018 to USD 58,558.65 million in 2024 and is anticipated to reach USD 3,00,482.33 million by 2032, at a CAGR of 22.7%. It represents the fastest-growing region, fueled by mobile-first content consumption, regional language demand, and affordable data plans. China, India, and Southeast Asia are key contributors. Localized content, competitive pricing, and freemium models drive user acquisition.
Latin America
The Latin America Video Streaming Market size was valued at USD 5,912.94 million in 2018 to USD 11,168.97 million in 2024 and is anticipated to reach USD 48,502.49 million by 2032, at a CAGR of 20.2%. Growth is supported by smartphone usage, cultural content preferences, and expansion of global platforms. Economic factors encourage the popularity of ad-supported models. Brazil and Mexico are the region’s largest contributors.
Middle East
The Middle East Video Streaming Market size was valued at USD 3,529.35 million in 2018 to USD 6,267.73 million in 2024 and is anticipated to reach USD 26,342.10 million by 2032, at a CAGR of 19.7%. The market benefits from high mobile penetration and a young digital-savvy population. Regional streaming services coexist with international players. Arabic content, religious broadcasting, and sports streaming are key segments.
Africa
The Africa Video Streaming Market size was valued at USD 3,038.31 million in 2018 to USD 7,129.09 million in 2024 and is anticipated to reach USD 29,992.22 million by 2032, at a CAGR of 19.3%. Growth is driven by increasing mobile usage, low-cost smartphones, and regional OTT launches. Infrastructure gaps remain, but operators are expanding partnerships to improve access and affordability.
Key Player Analysis:
- Akamai Technologies
- Amazon Web Services, Inc.
- Apple Inc.
- Cisco Systems, Inc.
- Google LLC
- Kaltura, Inc.
- Netflix, Inc.
- International Business Machine Corporation (IBM Cloud Video)
- Wowza Media Systems, LLC
- Hulu, LLC
Competitive Analysis:
The Global Video Streaming Market is highly competitive, with major players such as Netflix, Amazon Prime Video, Disney+, YouTube, Apple TV+, Hulu, Tencent Video, and HBO Max dominating content delivery across geographies. It is shaped by continuous investment in original programming, regional language content, and advanced platform capabilities. Companies focus on enhancing user experience through AI-driven personalization, adaptive streaming, and multi-device integration. Competitive strategies include exclusive licensing deals, acquisition of production studios, and partnerships with telecom providers to expand reach. Pricing flexibility, content diversity, and real-time engagement features remain key differentiators. The market shows strong vertical integration trends, with players controlling both content and distribution infrastructure. New entrants face high barriers in content costs, user acquisition, and brand loyalty. The Global Video Streaming Market favors agile platforms that can respond to shifting viewer demands and innovate in monetization models. It continues to evolve with changing viewer behavior and digital media regulations.
Recent Developments:
- In July 2025, Amazon Web Services (AWS) announced the general availability of the EC2 P6e-GB200 UltraServers, powered by NVIDIA Grace Blackwell GB200 superchips. These servers are designed for high-performance computing, including AI and video streaming workloads. Concurrently, AWS introduced significant enhancements to its data management platform, such as Amazon S3 Vectors with native vector support, transforming large-scale storage for AI and video streaming with cost efficiencies and better integration.
- In June 2025, Cisco launched new AI-enabled networking products at Cisco Live 2025, with innovations in zero-trust network security and AI-driven networking tools tailored for enterprise and hyperscale environments. These products focus on simplifying policy management, boosting security, and integrating observability tools following Cisco’s acquisition of Splunk. Their Mesh Firewall and Zero Trust Network Access offer robust platforms for secure, AI-powered video streaming delivery.
- In May 2025, Netflix rolled out a major redesign of its TV digital experience, the first such overhaul in 12 years. The new interface features intuitive navigation, real-time recommendations, and enhanced use of AI to make content discovery and engagement easier for its global audience. Netflix has integrated generative AI capabilities to help users find shows with natural prompts, positioning itself at the forefront of user-centric streaming innovation.
- In March 2025, Akamai Technologies sharpened its AI edge by launching Akamai Cloud Inference-a new solution designed to help platform engineers and developers build and run AI applications and data-heavy workloads closer to end users. This product aims to enable faster, more efficient innovation in predictive analytics and large-scale data processing for global organizations.
Market Concentration & Characteristics:
The Global Video Streaming Market displays moderate-to-high concentration, with a few dominant players accounting for a significant portion of global revenue. It is characterized by rapid innovation, intense content-driven competition, and aggressive subscriber acquisition strategies. Leading platforms leverage exclusive content, global distribution networks, and advanced analytics to maintain competitive advantage. The market favors vertically integrated firms with strong control over content production and delivery infrastructure. It shows high scalability, with platforms expanding rapidly across regions and user segments. User engagement, retention, and monetization depend on consistent content refreshment, seamless streaming quality, and personalized viewing experiences. The Global Video Streaming Market continues to evolve with changing consumption patterns, regulatory shifts, and technological advancements.
Report Coverage:
The research report offers an in-depth analysis based on type, end user, service industry and platform. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Subscription and ad-supported models will coexist to meet diverse consumer preferences and maximize revenue.
- Mobile-first content strategies will dominate growth in emerging economies with expanding internet access.
- AI and machine learning will enhance content discovery, personalization, and viewer retention.
- Cloud-native streaming infrastructure will support scalable, real-time content delivery worldwide.
- Interactive formats such as live polls, Q&A, and in-stream shopping will gain wider adoption.
- Regional content production in local languages will accelerate subscriber growth across untapped markets.
- Integration with gaming, sports, and live events will boost engagement and monetization opportunities.
- Blockchain-based content rights management will improve transparency for creators and distributors.
- Strategic telecom partnerships will expand reach in price-sensitive and bandwidth-constrained regions.
- Regulatory compliance and data privacy standards will shape platform operations and content policies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of OTT Platforms and Hybrid Monetization
The rapid adoption of OTT services like Netflix, Amazon Prime Video, and Disney+ is transforming content consumption by offering flexible subscription and ad-supported models, expanding reach to diverse demographics and maximizing revenue streams.
Advancements in Network and Streaming Technology
The deployment of 4G/5G networks, cloud computing, and AI-driven analytics enables seamless, high-quality video delivery, real-time personalization, and adaptive streaming, which significantly enhance user experience and drive market growth.
Mobile-First and Multi-Device Consumption
Increasing smartphone penetration and affordable data plans, especially in Asia Pacific and emerging markets, are making video streaming accessible to a broader audience, while multi-device compatibility ensures users can stream content anywhere, anytime.
Growth of Live and Interactive Streaming
Live streaming for sports, gaming, events, and influencer content is gaining popularity, with platforms integrating real-time engagement tools such as live chats, polls, and interactive features to boost user engagement and monetization opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Video Streaming Market in 2023 and 2032?
What are the key drivers of the Global Video Streaming Market?
Which region is leading the Global Video Streaming Market?
What are the key trends shaping the Global Video Streaming Market?
Which companies are the key players in the Global Video Streaming Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Live Video Streaming
- 1.2.2 Non-Linear Video Streaming
- 1.3 By End-User
- 1.3.1 Enterprise
- 1.3.2 Consumer
- 1.3.3 Education
- 1.3.4 Gaming
- 1.3.5 Social Networking
- 1.4 By Platform
- 1.4.1 Smartphones & Tablets
- 1.4.2 Smart TV
- 1.4.3 Laptops & Desktops
- 1.4.4 Gaming Consoles
- 1.5 By Solution
- 1.5.1 Internet Protocol TV (IPTV)
- 1.5.2 Over-the-Top (OTT)
- 1.5.3 Pay-TV
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,95,295.88 million → 2032: USD 9,20,875.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Video Streaming Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Video Streaming Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Video Streaming Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Video Streaming Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Video Streaming Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Video Streaming Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Video Streaming Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Video Streaming Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,95,295.88 million → 2032: USD 9,20,875.25 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Video Streaming Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Live Video Streaming
- 12.3.7.2 Non-Linear Video Streaming
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Enterprise
- 12.4.7.2 Consumer
- 12.4.7.3 Education
- 12.4.7.4 Gaming
- 12.4.7.5 Social Networking
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Platform - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Smartphones & Tablets
- 12.5.7.2 Smart TV
- 12.5.7.3 Laptops & Desktops
- 12.5.7.4 Gaming Consoles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Solution - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Internet Protocol TV (IPTV)
- 12.6.7.2 Over-the-Top (OTT)
- 12.6.7.3 Pay-TV
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Video Streaming End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Video Streaming Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Video Streaming Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Video Streaming Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Netflix, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Amazon Web Services, Inc.
- 18.4 Apple Inc.
- 18.5 Google LLC (YouTube)
- 18.6 Disney+
- 18.7 Hulu, LLC
- 18.8 Tencent Video
- 18.9 Akamai Technologies
- 18.10 Kaltura, Inc.
- 18.11 Cisco Systems, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

