
Market Overview:
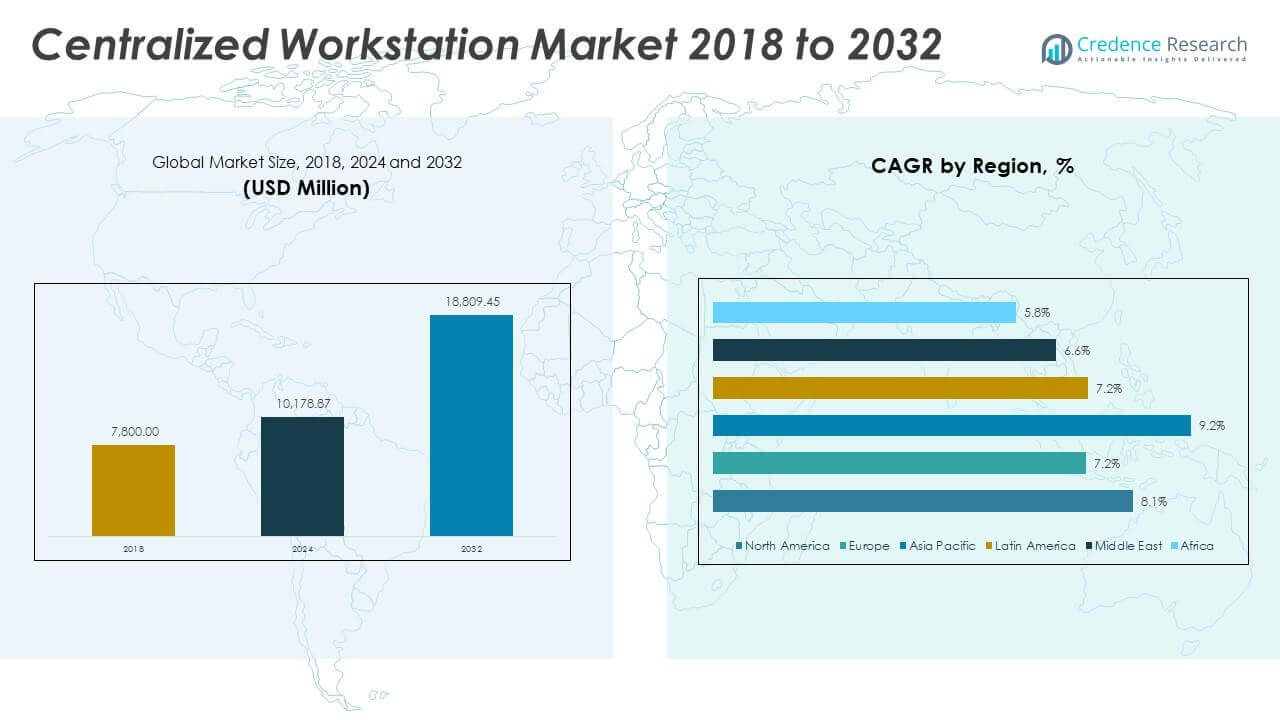
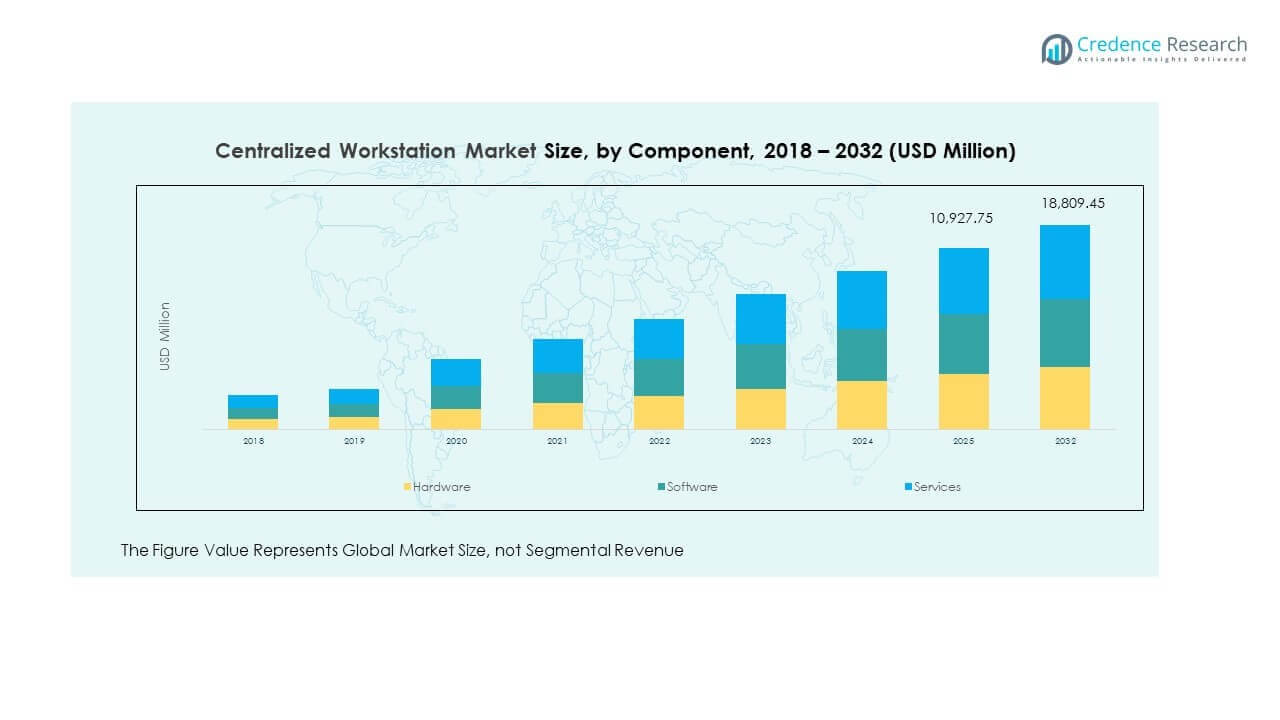
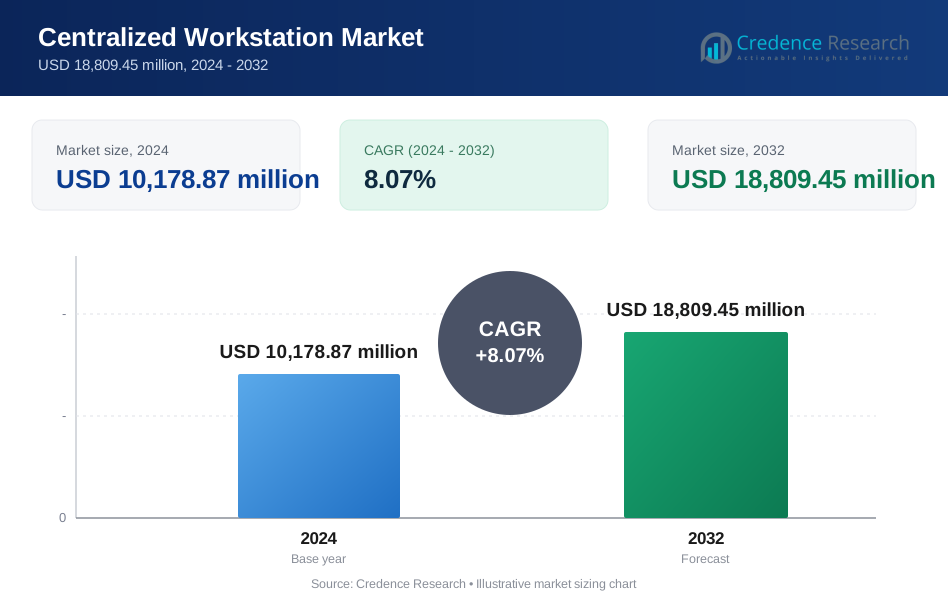
The Centralized Workstation Market size was valued at USD 7,800.00 million in 2018 to USD 10,178.87 million in 2024 and is anticipated to reach USD 18,809.45 million by 2032, at a CAGR of 8.07% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Centralized Workstation Market Size 2024 | USD 10,178.87 Million |
| Centralized Workstation Market, CAGR | 8.07% |
| Centralized Workstation Market Size 2032 | USD 18,809.45 Million |
The market is driven by rising demand for high-performance computing across industries including media, healthcare, engineering, and finance. Centralized workstations enable efficient data management, secure access, and improved scalability, supporting advanced workloads like AI, simulation, and 3D modeling. Growing adoption of cloud integration and virtualization further strengthens deployment, while enterprises continue to prioritize centralized solutions for cost efficiency, reduced downtime, and streamlined collaboration in distributed work environments.
North America leads the market due to strong technology adoption, robust IT infrastructure, and early enterprise digitization. Europe follows with significant demand from automotive and aerospace sectors, while Asia-Pacific is emerging rapidly, fueled by industrial expansion, government digitization initiatives, and growing IT service sectors. Countries such as China and India are driving opportunities through increasing investments in high-performance computing and large-scale enterprise applications.
Market Insights:
- The Centralized Workstation Market was valued at USD 7,800.00 million in 2018, reached USD 10,178.87 million in 2024, and is projected to hit USD 18,809.45 million by 2032, growing at a CAGR of 8.07%.
- North America (34.3%), Asia Pacific (30.5%), and Europe (21.6%) lead the market due to advanced IT infrastructure, strong industrial bases, and regulatory-driven modernization across enterprises.
- Asia Pacific is the fastest-growing region with 30.5% share in 2024, driven by rapid digitization, expanding IT services, and government initiatives supporting high-performance computing.
- Hardware accounts for the largest share of the market in 2024, reflecting demand for advanced processors, storage, and networking systems.
- Software and services together form a smaller portion, though services are expanding steadily with rising demand for integration and managed solutions.
Market Drivers:
Increasing Demand for High-Performance Computing Across Multiple Sectors
The Centralized Workstation Market is driven by the growing need for high-performance computing in sectors such as engineering, healthcare, media, and finance. Organizations seek advanced workstations to handle complex workloads, including 3D design, simulation, and medical imaging. It provides centralized processing power that enhances collaboration and efficiency across distributed teams. Enterprises also value centralized systems for data security, reducing risks linked to local device vulnerabilities. The demand is further supported by industries adopting AI and machine learning technologies that require high-speed computation. Centralized workstations simplify integration with advanced software applications, ensuring productivity and precision in critical workflows. Cost savings gained from shared infrastructure drive organizations to invest in centralized solutions. These factors collectively create strong momentum for widespread adoption in global enterprises.
- For example, Dell Technologies launched the Precision 7960 Tower workstation in 2023, featuring up to 56-core Intel Xeon W-3400 processors and support for up to 4 TB of DDR5 ECC memory, designed to handle advanced workloads such as engineering simulations and data-intensive applications.
Rising Adoption of Cloud Integration and Virtualization Technologies
Cloud integration is strengthening the appeal of the Centralized Workstation Market by offering seamless access to resources. Enterprises increasingly shift to hybrid or cloud-enabled environments to achieve scalability and resilience. It enables professionals to access heavy computing applications remotely without compromising performance. Virtualization reduces the need for physical hardware expansion, cutting operational costs while improving utilization. Organizations also deploy centralized workstations to ensure consistent environments across global teams. Enterprises benefit from improved collaboration and faster project execution with cloud support. Virtualized centralized systems help industries respond quickly to fluctuating demands. This trend positions centralized workstations as a core element of digital transformation strategies.
Growing Importance of Data Security and Enterprise Compliance
Data security remains a critical driver for the [Centralized Workstation Market], as organizations face rising cyber threats. Centralized systems offer better control over sensitive information by maintaining centralized storage and monitoring. It reduces vulnerabilities caused by scattered endpoint devices. Regulatory frameworks such as GDPR, HIPAA, and other data protection standards push enterprises to adopt secure workstation models. Enterprises trust centralized systems to manage compliance requirements without compromising efficiency. Centralized control enhances IT administrators’ ability to enforce uniform security policies. Organizations also rely on audit trails to maintain transparency in workflows. This need for secure and compliant infrastructure sustains long-term investments in centralized workstations.
Expanding Role of AI, Simulation, and Complex Workloads
The Centralized Workstation Market benefits from growing reliance on AI, simulation, and advanced analytics in industries. It supports complex workloads requiring high-speed data processing, such as predictive modeling and design optimization. Enterprises in automotive, aerospace, and healthcare depend on centralized platforms to drive innovation. AI applications demand scalable infrastructure that centralized workstations provide effectively. These systems enable faster turnaround of projects, reducing delays in product development cycles. Research institutions also deploy centralized workstations to handle computationally intensive tasks. Industries require platforms that can adapt to evolving workloads while maintaining efficiency. This increasing dependence reinforces market growth in high-tech sectors worldwide.
- For example, NVIDIA launched the RTX 6000 Ada Generation GPU in December 2022, offering 91.1 teraflops of performance, designed to accelerate demanding workloads such as simulation, AI, and advanced visualization.
Market Trends:
Rising Shift Toward Remote and Hybrid Work Environments
Remote work adoption strongly influences the Centralized Workstation Market as enterprises adjust to hybrid models. It provides centralized access to high-performance resources for remote teams. Centralized systems ensure consistent performance without requiring local device upgrades. Enterprises are investing in secure remote connectivity to maintain productivity. The demand for centralized solutions increases with the global shift toward flexible working. Remote deployment also supports global collaboration across industries with minimal latency. Enterprises prioritize centralized workstations to support large distributed workforces. This trend highlights the growing role of centralized systems in modern enterprise operations.
- For example, Hewlett Packard Enterprise offers HPE GreenLake for Virtual Desktop Infrastructure (VDI), allowing organizations to deliver secure, centralized virtual desktops for remote and hybrid work, with deployment options across on-premises and colocation environments.
Integration of Advanced Visualization and Virtual Reality Applications
The Centralized Workstation Market is witnessing a trend toward adoption of VR, AR, and advanced visualization tools. It enables industries to manage complex rendering tasks required in gaming, healthcare, and architecture. Centralized systems ensure real-time collaboration on 3D models across global teams. Professionals benefit from smoother design reviews and immersive experiences. Enterprises in construction and automotive sectors adopt these solutions for faster project validation. The integration of high-end visualization creates demand for powerful centralized hardware. It also strengthens the position of centralized workstations in research and simulation-intensive sectors. This shift drives innovation in specialized industries dependent on advanced visualization.
Increasing Use of Centralized Solutions for Collaborative Development Projects
Collaboration requirements push enterprises to adopt centralized systems for development and design workflows. The Centralized Workstation Market addresses the growing need for real-time access to shared resources. It supports simultaneous contributions from multiple stakeholders without performance bottlenecks. Enterprises benefit from reduced duplication of work and faster project completion cycles. Centralized infrastructure simplifies version control, reducing errors in collaborative processes. Industries including media and software development adopt these solutions to streamline creative projects. Teams in different regions gain equal access to high-performance tools. This trend strengthens centralized workstations as essential platforms for distributed project management.
Growing Demand for Energy-Efficient and Sustainable Workstation Solutions
Sustainability is shaping the [Centralized Workstation Market], with enterprises seeking energy-efficient infrastructure. It reduces operational costs while supporting environmental goals. Manufacturers focus on producing systems with lower power consumption and optimized cooling. Enterprises prefer centralized setups that reduce overall energy usage compared to multiple local devices. This shift is supported by global regulations promoting green IT practices. Energy-efficient centralized workstations also extend hardware lifespan through reduced strain. The emphasis on sustainability enhances adoption across environmentally conscious organizations. This focus positions centralized workstations as a viable solution for balancing performance with ecological responsibility.
- For example, Fujitsu’s CELSIUS W5012 workstation, introduced in fiscal 2023, features energy-efficient components and achieved a 44 % reduction in power consumption during use compared with previous models, while earning Japan’s AAA rating for energy efficiency under the FY 2022 standard.
Market Challenges Analysis:
High Cost of Deployment and Maintenance Across Enterprises
One of the major challenges in the Centralized Workstation Market is the high cost of implementation and ongoing maintenance. It requires enterprises to invest heavily in advanced infrastructure, high-performance servers, and specialized software. Smaller organizations struggle to allocate resources for large-scale centralized systems. Enterprises also face challenges in managing hardware upgrades and compatibility issues. Maintaining operational efficiency often demands skilled IT teams, further increasing expenses. Vendors must address the pricing barrier to encourage broader adoption. Enterprises weigh cost against potential long-term benefits before committing to centralized solutions. This challenge limits penetration in cost-sensitive markets.
Integration Complexity and Compatibility with Existing Systems
Integration challenges also hinder growth in the [Centralized Workstation Market], particularly with legacy systems. Enterprises face technical difficulties when aligning centralized solutions with existing IT environments. It may lead to workflow disruptions or performance bottlenecks during transition. Compatibility issues with older software and hardware remain significant. Enterprises require careful planning and significant resources to ensure smooth integration. Complex system management adds to operational burdens for IT teams. Organizations must allocate time and budget for training and adaptation. These barriers create resistance, slowing adoption in industries with established infrastructures.
Market Opportunities:
Growing Adoption Across Emerging Economies and SMEs
The Centralized Workstation Market presents opportunities in emerging economies and among small to medium enterprises. It offers cost-effective solutions for organizations seeking scalable computing resources without heavy infrastructure investments. SMEs can leverage centralized platforms for improved collaboration and security. Governments in developing nations also promote digitization, expanding the scope for adoption. Enterprises in manufacturing, healthcare, and finance create rising demand in these regions. Vendors focusing on tailored offerings for SMEs gain a competitive advantage. Emerging markets provide untapped growth potential with increasing awareness of centralized systems. This environment creates favorable conditions for future expansion.
Expansion Through Industry-Specific Applications and Customization
Industry-specific adoption creates further opportunities in the [Centralized Workstation Market]. It supports tailored solutions for healthcare, engineering, media, and financial services. Customized offerings allow enterprises to match infrastructure with sector-specific demands. Vendors focusing on vertical-specific features strengthen their market positioning. It also helps organizations improve efficiency and compliance within specialized industries. The ability to scale solutions according to workload requirements enhances market penetration. Enterprises value flexibility in design and deployment that centralized systems provide. This growing need for customization ensures consistent opportunities for long-term industry adoption.
Market Segmentation Analysis:
The Centralized Workstation Market is segmented
By component into hardware, software, and services. Hardware accounts for a major share due to demand for powerful processors, storage, and networking equipment. Software enhances system performance with virtualization and workflow management tools. Services are gaining importance as enterprises seek managed solutions, integration support, and maintenance to optimize workstation efficiency. It reflects a balanced structure where each component supports overall performance and scalability.
- For example, VMware introduced vSphere 8 Update 3 in 2024, adding features such as ESXi Live Patching, expanded GPU capabilities, and enhanced integration for modern workloads including AI and Kubernetes environments.
By application, the market covers graphic design and multimedia, data analysis and visualization, software development, scientific research, and virtual desktop infrastructure (VDI). Graphic design and multimedia drive adoption in creative industries, while data analysis and visualization gain traction in finance and engineering. Software development and scientific research rely on centralized platforms for simulation and high-speed processing. VDI is expanding with remote work and flexible IT environments.
- For example, The Lenovo ThinkStation P620 features up to 64-core AMD Ryzen Threadripper PRO processors, delivering high-performance computing for demanding workloads in industries such as data analysis, 3D rendering, and software development.
By end-users include the corporate sector, healthcare, education, government, manufacturing, and others. Corporates lead adoption due to centralized IT models, while healthcare and education increase usage for secure data handling and collaboration. Government and manufacturing sectors focus on efficiency and regulatory compliance.
By organization size, small and medium enterprises (SMEs) and large enterprises both contribute to demand. Large enterprises dominate due to established IT budgets, while SMEs adopt cloud-enabled solutions for cost-effective scalability.
By deployment type segments include on-premises, cloud-based, and hybrid models. On-premises models remain strong for security-sensitive industries, cloud-based solutions appeal to cost-conscious users, and hybrid models gain prominence for combining flexibility with control.
Segmentation:
By Component
- Hardware
- Software
- Services
By Application
- Graphic Design and Multimedia
- Data Analysis and Visualization
- Software Development
- Scientific Research
- Virtual Desktop Infrastructure (VDI)
By End-User
- Corporate Sector
- Healthcare
- Education
- Government
- Manufacturing
- Others
By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Deployment Type
- On-Premises
- Cloud-Based
- Hybrid Models
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Centralized Workstation Market size was valued at USD 2,714.40 million in 2018 to USD 3,497.40 million in 2024 and is anticipated to reach USD 6,453.56 million by 2032, at a CAGR of 8.1% during the forecast period. North America holds 34.3% of the global market share in 2024. The region leads due to advanced IT infrastructure and strong enterprise digitization. The Centralized Workstation Market here benefits from demand across healthcare, finance, and engineering sectors. It supports high adoption of AI, big data, and simulation workloads. Government policies encourage modernization of IT systems and secure data practices. Cloud-based and hybrid models see rising adoption among SMEs. Leading vendors maintain strong regional presence with investments in innovation. North America remains a key hub for technological leadership and enterprise-grade deployments.
Europe
The Europe Centralized Workstation Market size was valued at USD 1,762.80 million in 2018 to USD 2,196.32 million in 2024 and is anticipated to reach USD 3,794.86 million by 2032, at a CAGR of 7.2% during the forecast period. Europe accounts for 21.6% of the market share in 2024. The region emphasizes compliance, data security, and sustainable IT adoption. The Centralized Workstation Market benefits from industries such as automotive, aerospace, and research institutions. It aligns with regulatory frameworks that push enterprises toward centralized IT solutions. The corporate sector drives deployment in Germany, the UK, and France. Cloud integration is growing as enterprises adopt hybrid IT models. Vendors target the region with solutions tailored to data protection and efficiency. Europe’s focus on sustainability also supports demand for energy-efficient centralized systems.
Asia Pacific
The Asia Pacific Centralized Workstation Market size was valued at USD 2,293.20 million in 2018 to USD 3,102.99 million in 2024 and is anticipated to reach USD 6,231.59 million by 2032, at a CAGR of 9.2% during the forecast period. Asia Pacific represents 30.5% of the market share in 2024. The Centralized Workstation Market in this region expands rapidly due to industrial growth, digitization initiatives, and IT service expansion. It benefits from strong adoption in China, Japan, India, and South Korea. Enterprises invest in centralized solutions to support cloud adoption and remote workforces. Manufacturing and research sectors demand high-performance computing capabilities. Governments encourage digital transformation, further fueling adoption. Vendors see strong opportunities due to growing SME participation. Asia Pacific emerges as the fastest-growing regional market globally.
Latin America
The Latin America Centralized Workstation Market size was valued at USD 566.28 million in 2018 to USD 732.78 million in 2024 and is anticipated to reach USD 1,269.07 million by 2032, at a CAGR of 7.2% during the forecast period. Latin America holds 7.2% of the global share in 2024. The Centralized Workstation Market in the region is driven by expanding IT investments in Brazil, Mexico, and Argentina. It supports growing digitization across government and education sectors. Healthcare organizations adopt centralized systems to secure patient data and improve service delivery. SMEs increasingly explore cloud-based models to achieve cost efficiency. Large enterprises in finance and telecom sectors lead demand for centralized platforms. Vendors focus on regional expansion to meet evolving requirements. Latin America’s growth is steady but faces challenges linked to economic stability.
Middle East
The Middle East Centralized Workstation Market size was valued at USD 277.68 million in 2018 to USD 337.87 million in 2024 and is anticipated to reach USD 558.74 million by 2032, at a CAGR of 6.6% during the forecast period. The region accounts for 3.3% of the market share in 2024. The Centralized Workstation Market here grows through government-led digitization programs and smart city initiatives. It supports adoption in industries such as oil and gas, defense, and education. Enterprises deploy centralized solutions for secure and scalable IT infrastructures. Hybrid models gain popularity with organizations balancing local control and cloud flexibility. It strengthens collaboration across cross-border business networks. Vendors target the region with sector-specific offerings for government and corporate projects. Growth remains stable as enterprises modernize IT environments to support digital economies.
Africa
The Africa Centralized Workstation Market size was valued at USD 185.64 million in 2018 to USD 311.51 million in 2024 and is anticipated to reach USD 501.63 million by 2032, at a CAGR of 5.8% during the forecast period. Africa represents 3.1% of the market share in 2024. The Centralized Workstation Market in Africa develops gradually due to infrastructure gaps but gains momentum in South Africa and Egypt. It supports demand from education and government sectors prioritizing digital growth. Enterprises adopt centralized systems to improve security and operational efficiency. SMEs show interest in cloud-based platforms for scalability. Healthcare and manufacturing sectors also explore centralized deployments. Vendors face challenges linked to affordability and connectivity. Africa remains an emerging market with potential for long-term adoption as IT ecosystems mature.
Key Player Analysis:
- Citrix Systems Inc.
- Cisco Systems
- Dell Inc.
- Hewlett Packard Enterprise
- Fujitsu Ltd.
- Intel Corporation
- Microsoft Corporation
- Lenovo Group Ltd.
- NVIDIA Corporation
- Secunet AG
- Red Hat Inc.
- VMware
- Super Micro Computer Inc.
Competitive Analysis:
The Centralized Workstation Market is characterized by strong competition among global technology leaders and specialized vendors. It features companies such as Dell, Hewlett Packard Enterprise, Lenovo, Cisco, Citrix, NVIDIA, Microsoft, and VMware, each focusing on performance-driven solutions. Vendors emphasize hardware innovation, software integration, and service reliability to strengthen market presence. It reflects growing interest in hybrid models and cloud-enabled deployments that appeal to diverse enterprises. Partnerships, mergers, and product launches remain common strategies for expanding global reach. Vendors also prioritize compliance, energy efficiency, and AI integration to differentiate offerings. Competitive intensity increases with SMEs entering the market through scalable cloud-based solutions. This dynamic environment ensures continuous innovation, compelling companies to balance performance, affordability, and sustainability in order to secure long-term growth.
Recent Developments:
- In July 2025, CORSAIR introduced the CORSAIR AI WORKSTATION 300, an AI-optimized centralized workstation designed to address the needs of AI development and engineering. This launch demonstrates CORSAIR's strategy to expand into AI-focused markets by delivering specialized performance for machine learning and data-centric applications.
- In June 2025, Lenovo announced a new portfolio of workstation solutions at NXT BLD, unveiling their updated ThinkStation desktop series. These systems are specifically targeted at centralized workstation deployments, providing enhanced computing power and network management features to support industries requiring high levels of remote collaboration and centralized IT administration.
- In February 2025, HP revealed a definitive agreement to acquire key AI capabilities from Humane, most notably their Cosmos operating platform. This acquisition aims to integrate advanced AI and centralized workflow features into HP’s upcoming line of workstation products, supporting their evolution in the centralized workstation market.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application, End-User, Organization Size and Deployment Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Centralized Workstation Market will see rapid growth from enterprises adopting AI and simulation workloads.
- Expansion of remote and hybrid work models will drive investments in scalable centralized platforms.
- Integration with cloud ecosystems will strengthen demand for hybrid deployment models across industries.
- Rising focus on data compliance and cybersecurity will enhance adoption in regulated sectors.
- Demand for energy-efficient and sustainable workstation solutions will influence vendor strategies.
- SMEs will accelerate adoption through cost-effective cloud-based centralized workstation solutions.
- Emerging economies will offer significant opportunities due to growing IT infrastructure investments.
- Advanced visualization and VR applications will push adoption in creative and research industries.
- Strategic mergers and partnerships will shape competitive positioning and global expansion.
- Vendors will continue focusing on customization to meet industry-specific computing requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Centralized Workstation Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Centralized Workstation Market projected to grow between 2024 and 2032?
Which Centralized Workstation Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Centralized Workstation Market?
Who are the leading companies in the Centralized Workstation Market?
Which region commanded the largest share of the Centralized Workstation Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Centralized Workstation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Centralized Workstation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10,178.87 million → 2032: USD 18,809.45 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Centralized Workstation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Centralized Workstation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Centralized Workstation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Centralized Workstation Market Drivers
- 3.3 Centralized Workstation Market Restraints & Challenges
- 3.4 Centralized Workstation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Centralized Workstation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Centralized Workstation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Centralized Workstation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Centralized Workstation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Centralized Workstation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Centralized Workstation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Centralized Workstation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Centralized Workstation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Centralized Workstation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Centralized Workstation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Centralized Workstation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Centralized Workstation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Centralized Workstation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Centralized Workstation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Centralized Workstation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Centralized Workstation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Centralized Workstation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Centralized Workstation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Centralized Workstation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
