
Wireless Audio Device Market Overview:
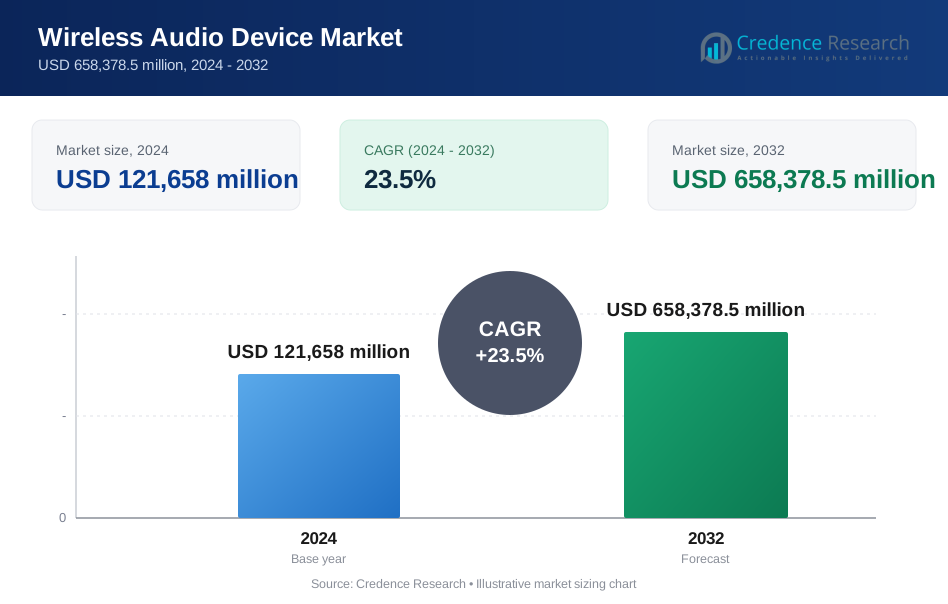
The Wireless Audio Device Market size was valued at USD 121,658 million in 2024 and is anticipated to reach USD 658,378.5 million by 2032, growing at a CAGR of 23.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wireless Audio Device Market Size 2024 | USD 121,658 million |
| Wireless Audio Device Market, CAGR | 23.5% |
| Wireless Audio Device Market Size 2032 | USD 658,378.5 million |
Wireless Audio Device Market Insights
- Market growth is driven by rising adoption of true wireless earbuds, which held a 44.6% segment share in 2024, along with increasing penetration of smart devices, streaming platforms, and remote working lifestyles.
- Key market trends include rapid advancements in Bluetooth technology holding a 61.9% share, integration of AI-driven features such as noise cancellation and voice assistants, and growing demand for smart audio devices with a 72.3% share.
- Market players focus on product innovation, ecosystem integration, premium audio performance, and frequent product launches to strengthen brand presence amid pricing pressure and short product life cycles.
- Regionally, North America led with a 34.8% share in 2024, followed by Asia Pacific at 30.4% and Europe at 26.1%, driven by high consumer adoption, rising disposable income, and expanding digital ecosystems.

Wireless Audio Device Market Segmentation Analysis:
By Product:
The Wireless Audio Device Market, by product, is led by True Wireless Hearables/Earbuds, which accounted for 44.6% market share in 2024, driven by rising smartphone penetration, elimination of headphone jacks, and strong demand for compact, cable-free audio solutions. Consumers increasingly prefer earbuds for daily commuting, fitness, and remote work due to features such as active noise cancellation, voice assistants, and long battery life. Headphones followed with a 27.8% share, supported by premium over-ear demand among audiophiles and gamers. Speaker systems and headsets gained traction in home entertainment and enterprise communication environments.
- For instance, Sony WF-1000XM5 earbuds feature industry-leading ANC with dual feedback microphones and a high-performance Dynamic Driver X for optimized noise suppression across environments.
By Technology:
By technology, Bluetooth dominated the Wireless Audio Device Market with a 61.9% share in 2024, supported by low power consumption, wide device compatibility, and continuous advancements such as Bluetooth LE Audio and LC3 codecs. Bluetooth technology remains the preferred choice across earbuds, headphones, and portable speakers due to its cost efficiency and stable connectivity. Bluetooth + Wi-Fi held a 19.4% share, driven by premium home audio systems offering high-resolution streaming. Wi-Fi and AirPlay adoption increased in smart speakers, supported by demand for multi-room audio, seamless Apple ecosystem integration, and improved streaming quality.
- For instance, Edifier's MS50A wireless smart speakers combine Bluetooth and Wi-Fi connectivity with AirPlay 2 support, allowing multi-room synchronized playback across devices for seamless home audio streaming.
By Functionality:
Based on functionality, Smart Devices led the market with a 72.3% share in 2024, driven by growing consumer preference for voice assistants, touch controls, AI-based noise cancellation, and health-tracking capabilities. Integration with virtual assistants such as Siri, Google Assistant, and Alexa significantly boosted adoption across earbuds, headphones, and speakers. Rising demand for connected ecosystems, smart homes, and wearable technology further strengthened this segment. Non-smart devices accounted for 27.7% share, primarily supported by budget-conscious consumers and institutional buyers seeking basic audio performance without advanced connectivity or software-driven features.
Key Growth Drivers
Rising Adoption of True Wireless and Wearable Audio Devices
The Wireless Audio Device Market is experiencing strong growth due to accelerating adoption of true wireless earbuds and wearable audio solutions. Consumers increasingly prefer compact, lightweight, and cable-free devices that offer portability and convenience for daily activities such as commuting, fitness, and remote work. Continuous innovation in battery efficiency, fast charging, and active noise cancellation enhances product usability and drives replacement demand. Growing integration of voice assistants and health-monitoring features further strengthens consumer engagement. Additionally, the expansion of mid-range and affordable product offerings enables wider adoption across emerging economies, significantly supporting overall market growth.
- For instance, Google Pixel Buds Pro 2 deliver twice the active noise cancellation of prior models via Tensor A1 chip, processing audio 3 million times per second to block traffic and conversations effectively.
Expansion of Smart Device Ecosystems and Connected Living
The rapid expansion of smart ecosystems is a major growth driver for the Wireless Audio Device Market. Seamless integration with smartphones, smart TVs, laptops, wearables, and smart home platforms increases the functional value of wireless audio products. Consumers increasingly seek devices that support voice control, multi-device connectivity, and cloud-based services. The rise of smart homes, digital assistants, and IoT-enabled environments drives demand for smart speakers, headphones, and earbuds. Continuous improvements in wireless standards and software-driven features further enhance user experience, accelerating adoption across both consumer and enterprise segments.
- For instance, Amazon Echo devices, powered by Alexa, connect seamlessly to smart home ecosystems via Wi-Fi, Bluetooth, Zigbee, and Matter protocols for voice-controlled automation.
Growth in Digital Content Consumption and Remote Lifestyles
Rising consumption of streaming music, podcasts, gaming, and video content strongly supports demand in the Wireless Audio Device Market. Increased usage of online entertainment platforms and cloud gaming services creates sustained demand for high-quality audio performance. The expansion of remote work, online education, and virtual collaboration has increased reliance on wireless headsets and microphones for communication. Enhanced call clarity, noise suppression, and low-latency audio features are increasingly prioritized. These lifestyle shifts continue to drive demand for advanced wireless audio devices across professional, educational, and personal entertainment applications.
Key Trends & Opportunities
Advancements in Audio Technologies and AI Integration
Technological innovation represents a key trend and opportunity in the Wireless Audio Device Market. Manufacturers are increasingly integrating artificial intelligence to enhance noise cancellation, adaptive sound control, and voice recognition accuracy. The adoption of Bluetooth LE Audio, spatial audio, and high-resolution codecs improves sound quality while reducing power consumption. Personalized audio experiences based on user behavior and environmental sensing create strong differentiation opportunities. These advancements enable premium pricing strategies and support growth in high-end segments, while also creating pathways for enterprise applications such as conferencing and professional audio solutions.
- For instance, Bose QuietComfort Ultra Earbuds (2nd Gen) leverage AI algorithms to smooth adaptive noise cancellation against sudden sounds like sirens, preventing audio interruptions.
Emerging Opportunities in Gaming, Fitness, and Healthcare Audio
The Wireless Audio Device Market is witnessing expanding opportunities across gaming, fitness, and healthcare applications. Wireless gaming headsets with low-latency connectivity and immersive audio features are gaining rapid traction. In fitness, demand for sweat-resistant, secure-fit earbuds continues to rise, supported by growth in wearable technology. Healthcare-oriented audio solutions, including hearing enhancement and wellness monitoring features, are also emerging. These applications open new revenue streams, encourage cross-industry collaborations, and enable manufacturers to diversify product portfolios beyond traditional consumer audio segments.
- For instance, SteelSeries Arctis Nova Pro Wireless offers ultra-low latency via 2.4GHz connection in Speed mode, ensuring audio-visual sync for competitive gaming, alongside Hi-Res certified audio and up to 25 hours of battery life.
Key Challenges
Connectivity Limitations and Audio Quality Consistency
Connectivity reliability remains a key challenge in the Wireless Audio Device Market. Issues such as signal interference, latency, and inconsistent audio performance can negatively impact user experience, particularly in crowded wireless environments. While advancements in Bluetooth and Wi-Fi standards address some limitations, performance variations across devices and platforms persist. Maintaining stable connections across multiple devices simultaneously also increases technical complexity. These challenges require continuous investment in R&D and firmware optimization, increasing development costs and creating barriers for smaller manufacturers seeking to compete effectively.
Pricing Pressure and Intense Market Saturation
The Wireless Audio Device Market faces significant challenges from intense competition and pricing pressure. The rapid entry of new brands, especially in the mid-range and budget segments, increases product commoditization. Short product life cycles and frequent feature upgrades strain profit margins and inventory management. Additionally, rising costs of advanced components, semiconductors, and logistics impact manufacturing economics. Balancing innovation, cost efficiency, and brand differentiation remains a persistent challenge for market participants aiming to sustain profitability and long-term growth.
Regional Analysis
North America
North America held a 34.8% market share in 2024 in the Wireless Audio Device Market, driven by high consumer spending on premium audio products and rapid adoption of smart devices. Strong demand for true wireless earbuds, noise-canceling headphones, and smart speakers supports market expansion. The presence of leading technology companies and early adoption of advanced wireless standards enhance product penetration. Growth in remote work, online gaming, and streaming services further accelerates demand for headsets and microphones. Continuous innovation, strong brand loyalty, and widespread availability through online and offline channels sustain regional market leadership.
Europe
Europe accounted for a 26.1% market share in 2024, supported by strong demand for high-fidelity audio products and growing preference for wireless headphones and smart speakers. Consumers increasingly value sound quality, ergonomic design, and sustainability, driving adoption of premium and mid-range devices. Expanding use of wireless audio in home entertainment, automotive infotainment, and enterprise communication strengthens market performance. Rising digital content consumption and hybrid work models further support demand. Regulatory focus on energy efficiency and environmental compliance encourages manufacturers to introduce advanced, eco-friendly wireless audio solutions across the region.
Asia Pacific
Asia Pacific captured a 30.4% market share in 2024, driven by large population bases, rapid urbanization, and rising smartphone penetration. Strong demand for affordable and mid-range wireless earbuds and headphones supports high sales volumes. Expansion of e-commerce platforms and increasing disposable income accelerate product accessibility across emerging economies. Growth in gaming, online education, and mobile entertainment further drives adoption. Local manufacturing capabilities and aggressive product launches by regional and global brands enhance competition, while continuous technological upgrades support long-term market expansion.
Latin America
Latin America held a 5.1% market share in 2024, supported by increasing adoption of smartphones and wireless accessories among young consumers. Demand for budget-friendly earbuds, portable speakers, and Bluetooth headphones drives market growth. Expansion of digital streaming platforms and social media usage strengthens consumer engagement with wireless audio products. Improving retail infrastructure and growth of online sales channels enhance product reach. Although price sensitivity remains a challenge, rising awareness of wireless convenience and improving connectivity infrastructure continue to support steady market development across the region.
Middle East & Africa
The Middle East & Africa accounted for a 3.6% market share in 2024, driven by increasing smartphone usage and growing demand for personal audio devices. Urbanization and rising youth populations support adoption of wireless earbuds and portable speakers. Growth in entertainment, fitness, and gaming activities strengthens demand for wireless headsets. Expanding retail networks and improving internet connectivity enhance product availability. While market penetration remains moderate, increasing disposable income and adoption of smart devices in urban centers are expected to support gradual growth across the region.
Wireless Audio Device Market Segmentations:
By Product
- Earphone
- Headphone
- True Wireless Hearables/Earbud
- Speaker Systems
- Microphones
By Technology
- Bluetooth
- Wi-Fi
- Bluetooth + Wi-Fi
- Airplay
- Others
By Functionality
- Smart Devices
- Non-smart Devices
By Application
- Residential/Individual
- Commercial
- Automotive
- Government
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Wireless Audio Device Market is characterized by strong brand competition, rapid product innovation, and continuous portfolio expansion. Apple Inc., Samsung Electronics, Sony Corporation, Bose Corporation, JBL (Harman International), Sennheiser Electronic, Jabra (GN Group), Bang & Olufsen, Beats by Dre, and Plantronics (Poly) dominate the market through diversified product offerings across true wireless earbuds, headphones, speakers, and headsets. Market participants focus heavily on advanced features such as active noise cancellation, spatial audio, AI-powered sound optimization, and seamless ecosystem integration to strengthen customer loyalty. Strategic investments in R&D, premium design, and audio performance differentiation remain central to competition. Companies also emphasize aggressive pricing strategies, frequent product launches, and expanded online distribution channels to capture broader consumer segments. Partnerships with smartphone manufacturers, streaming platforms, and gaming ecosystems further enhance brand visibility and drive long-term market positioning.
Key Player Analysis
- Bang & Olufsen
- Jabra (GN Group)
- Bose Corporation
- Plantronics (Poly)
- Samsung Electronics
- Sennheiser Electronic
- Beats by Dre (Apple Inc.)
- Sony Corporation
- JBL (Harman International)
- Apple Inc.
Recent Developments
- In November 2025, LG and Dolby announced a partnership to introduce the first Dolby Atmos FlexConnect soundbar (the H7) and modular wireless speaker suite for CES 2026, advancing wireless high-channel home audio setups.
- In October 2025, Edifier entered a distribution partnership with Officeworks to roll out its wireless headphones, speakers, and earbuds across 170+ stores in Australia, expanding retail reach.
- In December 2025, Portronics launched the Iron Beats 5 Prime wireless party speaker in India, featuring 250 W output and vibrant lighting effects for enhanced portable audio experiences.
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, Functionality, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Wireless Audio Device Market will continue to expand driven by rising adoption of true wireless earbuds and smart audio wearables.
- Advancements in Bluetooth LE Audio and low-latency connectivity will significantly enhance sound quality and power efficiency.
- Integration of artificial intelligence will improve noise cancellation, voice recognition, and personalized audio experiences.
- Demand for smart audio devices will grow with expanding smart home and connected ecosystem adoption.
- Gaming and immersive entertainment applications will drive increased demand for high-performance wireless headsets.
- Fitness and wellness-focused audio devices will gain traction through health tracking and ergonomic designs.
- Manufacturers will prioritize lightweight designs, extended battery life, and fast charging capabilities.
- Growth in emerging economies will accelerate due to rising smartphone penetration and affordable product offerings.
- Sustainability and eco-friendly materials will become more prominent in product development strategies.
- Continuous product innovation and shorter replacement cycles will sustain long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of True Wireless and Wearable Audio Devices
Consumers are increasingly choosing compact, cable-free audio solutions such as true wireless earbuds and wearable devices for convenience, portability, and features like active noise cancellation and voice assistants. This trend is fueled by smartphone penetration, elimination of headphone jacks, and demand for on-the-go audio experiences.
Expansion of Smart Device Ecosystems and Connected Living
The integration of wireless audio devices with smartphones, smart TVs, wearables, and smart home platforms enhances their functional value and drives adoption. Consumers seek seamless connectivity, voice control, and multi-device compatibility, which is accelerating demand for smart audio products.
Growth in Digital Content Consumption and Remote Lifestyles
Increased streaming of music, podcasts, gaming, and video content, along with the rise of remote work and online education, is boosting demand for high-quality wireless audio devices. Enhanced call clarity, noise suppression, and low-latency features are becoming essential for both personal and professional use.
Advancements in Audio Technologies and AI Integration
Continuous innovation in Bluetooth standards, AI-driven noise cancellation, spatial audio, and personalized sound experiences is improving product performance and user satisfaction. These advancements support premium pricing and open new opportunities in high-end and enterprise segments.
Emerging Opportunities in Gaming, Fitness, and Healthcare Audio
Specialized wireless audio devices for gaming, fitness, and healthcare are gaining traction, offering features like low-latency connectivity, sweat resistance, and health monitoring. These applications diversify revenue streams and encourage cross-industry collaborations, expanding the market beyond traditional consumer audio.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Wireless Audio Device Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wireless Audio Device Market projected to grow between 2024 and 2032?
Which Wireless Audio Device Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wireless Audio Device Market?
Who are the leading companies in the Wireless Audio Device Market?
Which region commanded the largest share of the Wireless Audio Device Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Earphone
- 1.2.2 Headphone
- 1.2.3 True Wireless Hearables/Earbud
- 1.2.4 Speaker Systems
- 1.2.5 Microphones
- 1.3 By Technology
- 1.3.1 Bluetooth
- 1.3.2 Wi-Fi
- 1.3.3 Bluetooth + Wi-Fi
- 1.3.4 Airplay
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Residential/Individual
- 1.4.2 Commercial
- 1.4.3 Automotive
- 1.4.4 Government
- 1.4.5 Others
- 1.5 By Functionality
- 1.5.1 Smart Devices
- 1.5.2 Non-smart Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 121,658 million → 2032: USD 658,378.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wireless Audio Device Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wireless Audio Device Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wireless Audio Device Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wireless Audio Device Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wireless Audio Device Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wireless Audio Device Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wireless Audio Device Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wireless Audio Device Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 121,658 million → 2032: USD 658,378.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wireless Audio Device Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Earphone
- 12.3.7.2 Headphone
- 12.3.7.3 True Wireless Hearables/Earbud
- 12.3.7.4 Speaker Systems
- 12.3.7.5 Microphones
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bluetooth
- 12.4.7.2 Wi-Fi
- 12.4.7.3 Bluetooth + Wi-Fi
- 12.4.7.4 Airplay
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential/Individual
- 12.5.7.2 Commercial
- 12.5.7.3 Automotive
- 12.5.7.4 Government
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Functionality - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Smart Devices
- 12.6.7.2 Non-smart Devices
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wireless Audio Device End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wireless Audio Device Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wireless Audio Device Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wireless Audio Device Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Apple Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsung Electronics
- 18.4 Sony Corporation
- 18.5 Bose Corporation
- 18.6 JBL (Harman International)
- 18.7 Sennheiser Electronic
- 18.8 Jabra (GN Group)
- 18.9 Bang & Olufsen
- 18.10 Beats by Dre
- 18.11 Plantronics (Poly)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

