
Market Overview
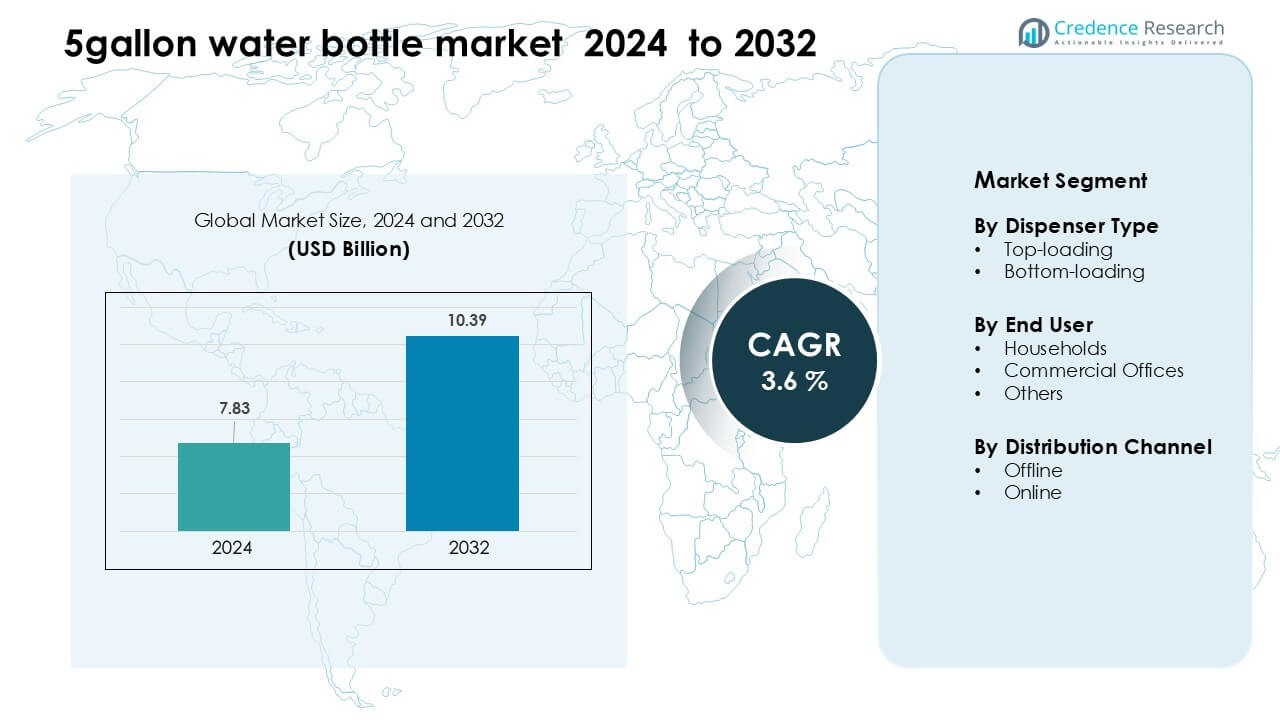
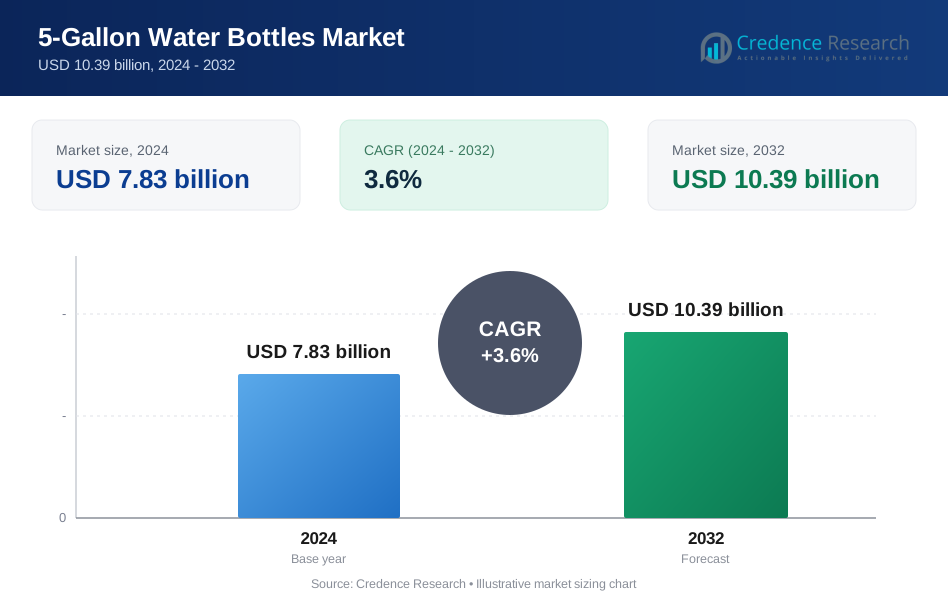
5-Gallon Water Bottles Market was valued at USD 7.83 billion in 2024 and is anticipated to reach USD 10.39 billion by 2032, growing at a CAGR of 3.6 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 5-Gallon Water Bottle Market Size 2024 | USD 7.83 Billion |
| 5-Gallon Water Bottle Market, CAGR | 3.6 % |
| 5-Gallon Water Bottle Market Size 2032 | USD 10.39 Billion |
In the global 5-gallon water bottle market, leading companies such as Primo Water Corporation, Culligan International Company, Danone S.A., Nestlé Waters, Niagara Bottling LLC and Absopure Water Company dominate through established delivery-and-refill programmes and large-scale bottle logistics. These players differentiate via returnable bottle systems, subscription services and service-level contracts with offices and homes. The leading region is North America, accounting for approximately 28 % of global revenue share.
Market Insights
- The global 5-gallon water bottle market is expected to reach USD 10.39 billion by 2032, growing at a CAGR of 3.6 %.
- A key driver is subscription-based delivery models for homes and offices, which increase recurring revenue and customer lock-in.
- A notable trend is rising demand for returnable/refillable bottles and sustainable packaging as consumers and regulators push for environmental responsibility.
- Competitive intensity is high: major players invest in distribution networks, automated logistics and regional consolidation, while obstacles include plastic-waste regulation and rising cost of materials.
- Regionally, North America leads with the highest value share (around 28 % of global revenue) and the household segment holds the largest application share within this market.
Market Segmentation Analysis
By Dispenser type
Top-loading models dominated the 5-gallon water bottle market in 2024 with about 61% share. Buyers preferred these units because the design is simple, affordable, and easy to install in homes and small offices. The segment grew as households increased bulk water use due to rising tap-water safety concerns. Bottom-loading units expanded at a steady pace as companies promoted spill-free designs and cleaner aesthetics. Higher prices limited faster adoption for bottom-loading dispensers, yet demand increased in premium office spaces.
- For instance, many common top-loading water dispensers designed for home and office use have a cold-water storage tank capacity that falls within or close to the 2.5 to 3.2 litre range mentioned in the statement.
By End user
Households led the 5-gallon water bottle market in 2024 with nearly 68% share. Strong demand came from urban families seeking low-cost, clean, and portable drinking water. Growth was also supported by rising awareness about waterborne diseases and the need for safer hydration. Commercial offices adopted large bottles to reduce single-use plastic and support shared hydration points, but household use remained ahead due to higher daily consumption volumes and broader distribution reach.
- For instance, Blue Star rolled out its BWD3FMRGA top-load dispenser for office use, offering a cooling rate of 3 litres/hour and accommodating a 5-gallon jug within a stainless cabinet.
By Distribution channel
Offline channels accounted for about 72% share of the 5-gallon water bottle market in 2024. Local distributors, neighborhood water stations, and retail shops drove this lead because buyers trusted direct delivery and quick refills. The channel expanded through established home-delivery networks that ensured steady repeat purchases. Online platforms grew as subscription-based delivery apps gained users, but offline channels stayed dominant due to faster turnaround times and higher consumer dependence on regional water suppliers.
Key Growth Drivers
Growing demand for safe and affordable drinking water
Rising concerns about tap-water quality continue to push families and small businesses toward bulk packaged water, which supports stable expansion in the 5-gallon water bottle market. Many urban areas rely on delivered water due to inconsistent municipal supply, which increases demand across both households and offices. Bulk bottles offer a low-cost hydration option compared with single-serve packages, helping buyers reduce monthly spending. Growth also rises as more regions promote purified water access through regulated suppliers and doorstep delivery networks. Strong refill systems and higher hygiene standards enhance trust among frequent users. Expanding apartment complexes and small commercial units further boost repeat purchases.
- For instance, Bisleri explicitly offers a doorstep delivery service called "Bisleri@doorstep," which includes its 20-litre jars. Customers can use the service for single orders or subscriptions.
Expansion of home-delivery and subscription models
Structured delivery networks drive strong growth as many customers prefer regular refill schedules for convenience. Subscription platforms simplify ordering and reduce dependency on ad-hoc store visits, helping suppliers secure predictable volumes. Delivery fleets expand in dense cities where demand remains high due to shifting consumer habits. Companies also add real-time tracking and digital payments to improve retention. These improvements help small suppliers scale faster and compete with branded water producers. The shift toward recurring monthly plans boosts loyalty and increases long-term usage in households and shared workspaces.
- For instance, Bisleri’s own app, Bisleri@Doorstep, supports subscription plans lasting from 1 up to 12 months, allowing customers to choose delivery days (Monday–Saturday) and payment frequency.
Rising office hydration needs and sustainability focus
Workplaces invest more in shared dispensers to offer employees clean water and reduce plastic waste from small bottles. The 5-gallon format supports this shift because each refill replaces multiple single-use units, making it a cost-efficient and eco-friendly choice. Increased awareness about employee health encourages firms to provide steady hydration access, especially in high-traffic corporate or co-working setups. Demand also rises as commercial buyers explore reusable containers that align with sustainability policies. This trend benefits large suppliers with strong delivery reach and compliance certifications.
Key Trends and Opportunities
Shift toward reusable and BPA-free containers
Buyers seek safer, durable containers for long-term use, which drives demand for BPA-free and improved-grade polycarbonate bottles. Manufacturers respond with designs that last longer and reduce wear during repeated refills. This shift supports a premium sub-segment and encourages higher hygiene standards across suppliers. Growing regulatory attention to material safety accelerates this trend and helps replace older bottle types. The rise of brand-conscious buyers also promotes better labeling and certified material use.
- For instance, Nalgene transitioned its reusable bottles to Tritan Renew, a material that is BPA-, BPS-, and phthalate-free, made with 50% certified recycled content, and is dishwasher safe on the top rack.
Growth of smart dispensers and contactless hydration points
Offices and premium homes adopt smart dispensers equipped with features like temperature control, child safety locks, and sensor-based dispensing. These upgrades boost demand for compatible 5-gallon formats because users prefer efficient refilling and cleaner hydration points. Contactless use gained traction as buyers sought safer shared access in commercial spaces. Improved dispenser compatibility encourages higher adoption of bulk bottles, especially in modern workplaces and service-sector hubs.
- For instance, Elkay offers hands-free ezH2O hydration stations with sensor-activated bottle fillers, built-in timing controls, and antimicrobial bubbler guards.
Key Challenge
High transportation and handling costs
Suppliers face rising fuel prices and labor costs, which directly increase the cost of bottle pickup, delivery, and cleaning. Bottles are heavy, require careful handling, and often demand repeat logistics due to refills. Small distributors struggle to maintain margins, especially when operating across wider delivery zones. These challenges create uneven pricing and limit upgrades in fleet capacity. Cost pressure slows adoption in price-sensitive regions where buyers compare rates between local suppliers.
Operational issues with bottle return and maintenance
The refill cycle depends on quick bottle returns and proper sanitation, yet many suppliers face delays due to inconsistent customer response and bottle misuse. Damaged or lost bottles increase replacement expenses and disrupt inventory flow. Maintaining hygiene also requires strict cleaning processes, which demand time and equipment. Lapses in sanitation increase health risks and reduce trust among consumers. These friction points affect supply reliability and create hurdles for large-scale expansion.
Regional Analysis
North America
North America held about 28% share of the 5-gallon water bottle market in 2024. Demand rose as households and offices used bulk water to offset concerns about aging pipelines and inconsistent municipal quality. The United States led due to strong home-delivery networks and high dispenser penetration. Canada showed stable growth as families adopted refill systems for cost savings. Growth also benefited from rising health awareness and a shift toward reusable bottles. Commercial buildings strengthened demand by replacing single-serve bottles with bulk formats to support sustainability and reduce waste.
Europe
Europe accounted for nearly 22% of the 5-gallon water bottle market in 2024. Demand increased as several regions faced hard water issues and older plumbing, which encouraged higher adoption of bulk purified options. Southern Europe saw faster expansion due to long summers and strong tourism activity, which boosted consumption in hotels and rental homes. Eastern Europe relied on cost-effective bulk formats for both homes and small offices. Sustainability trends supported reusable bottle circulation, while stricter hygiene rules pushed suppliers to improve cleaning systems and delivery quality.
Asia Pacific
Asia Pacific dominated the global market with around 34% share in 2024. Rapid urbanization, rising population density, and unreliable tap-water quality strengthened demand for 5-gallon bottled water across cities. China and India led due to large-scale home-delivery networks and strong use among both households and small businesses. Southeast Asia expanded fast as consumer hygiene awareness rose and refill stations grew in metropolitan hubs. The region’s large working population supported bulk purchases for offices, retail outlets, and co-working spaces. Strong distribution networks kept refill cycles frequent and steady.
Latin America
Latin America held close to 10% share of the 5-gallon water bottle market in 2024. Many countries relied on bulk bottled water due to concerns about supply reliability, which boosted household adoption. Mexico and Brazil represented the largest user base, supported by strong local distributors and recurring home-delivery services. Warmer climates further pushed consumption in residential and hospitality settings. Small and midsize businesses used bulk bottles to reduce costs linked to single-serve packaging. Adoption increased as suppliers improved sanitation processes and offered better-quality containers.
Middle East & Africa
The Middle East & Africa region captured about 6% share in 2024. Demand grew as water scarcity, high temperatures, and limited potable tap-water access encouraged reliance on bulk bottled options. Gulf countries led due to strong disposable incomes and established delivery systems supporting households and commercial offices. Africa saw steady adoption in urban centers where consumers preferred safer drinking options. Hotels, construction sites, and corporate setups boosted demand for dispensers paired with 5-gallon bottles. Growth improved as suppliers expanded refill plants and strengthened bottle-return processes.
Market Segmentations:
By Dispenser Type
- Top-loading
- Bottom-loading
By End User
- Households
- Commercial Offices
- Others
By Distribution Channel
- Offline
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The 5-gallon water bottle market features strong competition led by key players such as Nestlé Waters, Primo Water Corporation, Culligan International Company, Eden Springs Ltd., Danone S.A., Niagara Bottling LLC, Absopure Water Company, HINADA, and the International Bottled Water Association. These companies expand their market reach through large distribution networks, subscription-based delivery models, and advanced refill systems. Leading brands focus on durable bottle materials, improved sanitization processes, and returnable packaging to meet rising sustainability expectations. Many competitors invest in automated cleaning lines and smart dispensers to improve service speed and reduce operational errors. Partnerships with offices, industries, and residential communities help them secure long-term contracts. Market leaders also introduce BPA-free bottles and enhanced leak-proof designs to strengthen consumer trust. Growing demand for bulk hydration solutions pushes firms to scale production facilities while using cost-efficient logistics to maintain price competitiveness across regions.
Key Player Analysis
- Eden Springs Ltd.
- Culligan International Company
- Danone S.A.
- Primo Water Corporation
- International Bottled Water Association
- Niagara Bottling LLC
- Nestlé Waters
- Absopure Water Company
- HINADA
Recent Developments
- In May 2025, Primo Water Corporation (Primo Brands) Primo Brands published its inaugural 2024 Sustainability Report, highlighting that its reusable 3- and 5-gallon bottles can be reused up to 25 times and noting expansion to roughly 26,500 Water Exchange locations and 23,500 refill stations across North America.
- In July 2024, Eden Springs Ltd. Aquaservice acquired Eden Springs Portugal, the country’s leading bottled-water-with-dispenser provider, strengthening Iberian distribution of large water containers for homes and offices.
- In January 2024, Culligan International Company Culligan acquired most of Primo Water’s EMEA businesses (excluding the UK, Portugal, Israel, and Aimia Foods), expanding its European bottled-water cooler and 5-gallon delivery network to about 1.35 million customers.
Report Coverage
The research report offers an in-depth analysis based on Dispenser Type, End-User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The 5-gallon water bottle market will increasingly shift toward reusable and refill models.
- Companies will expand digital delivery tools and subscription-based models to boost customer retention.
- Sustainability demands will drive deployment of lighter bottles, recycled materials and reduced-waste programs.
- Growth in Asia-Pacific will accelerate as urbanization and income levels rise in China and India.
- The household end-user segment will grow faster than commercial offices, thanks to more home-based workers.
- Logistics efficiency and last-mile delivery investments will differentiate leading firms.
- Regulatory pressures on single-use plastics will push firms toward alternative packaging formats.
- Integration of smart tracking (e.g., bottle version control or dispenser usage) will enhance operational visibility.
- Pricing pressures from refill stations and municipal alternatives will force margin optimization.
- Mergers and acquisitions will increase as firms seek scale in regional markets and consolidate production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Subscription-Based Delivery Models
The proliferation of subscription-based delivery services for 5-gallon water bottles is driving market growth by providing households and offices with convenient, recurring access to safe drinking water. These models increase customer retention and predictable revenue streams for suppliers, while digital platforms and real-time tracking further enhance user experience and operational efficiency.
Rising Concerns Over Tap-Water Quality
Increasing apprehension about the safety and reliability of municipal tap water, especially in urban areas, is prompting more consumers and businesses to opt for bulk bottled water solutions. The 5-gallon format offers a cost-effective and trusted alternative, supporting stable demand across both residential and commercial segments.
Sustainability and Reusable Packaging Initiatives
Growing environmental awareness and regulatory pressure on single-use plastics are accelerating the shift toward returnable and refillable 5-gallon bottles. Leading companies are investing in durable, BPA-free containers and closed-loop logistics, which not only reduce waste but also appeal to eco-conscious consumers and corporate buyers.
Growth in Urbanization and Home-Based Work
Rapid urbanization, particularly in Asia Pacific, and the increase in home-based work are boosting demand for bulk water delivery to households. As more people work from home, daily water consumption rises, making the 5-gallon bottle an attractive solution for convenient and affordable hydration.
Corporate Focus on Employee Health and Cost Efficiency
Businesses are increasingly adopting 5-gallon water bottles and shared dispensers to provide employees with safe hydration while reducing costs associated with single-serve packaging. This trend is reinforced by corporate sustainability goals and the need to support employee well-being in high-traffic office environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for 5-gallon water bottle market, and what is its projected size in 2032?
The market reached USD 7.83 billion in 2024 and is projected to reach USD 10.39 billion by 2032.
Which 5-gallon water bottle market segment held the largest share in 2024?
What are the primary factors fueling the growth of 5-gallon water bottle market?
Who are the leading companies in 5-gallon water bottle market?
Which region commanded the largest share of 5-gallon water bottle market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Households
- 1.2.2 Commercial Offices
- 1.2.3 Others
- 1.3 By Dispenser Type
- 1.3.1 Top-loading
- 1.3.2 Bottom-loading
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7.83 billion → 2032: USD 10.39 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 5-Gallon Water Bottles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 5-Gallon Water Bottles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 5-Gallon Water Bottles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 5-Gallon Water Bottles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 5-Gallon Water Bottles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 5-Gallon Water Bottles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global 5-Gallon Water Bottles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 5-Gallon Water Bottles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7.83 billion → 2032: USD 10.39 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 5-Gallon Water Bottles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Households
- 12.3.7.2 Commercial Offices
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Dispenser Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Top-loading
- 12.4.7.2 Bottom-loading
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global 5-Gallon Water Bottles End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 5-Gallon Water Bottles Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 5-Gallon Water Bottles Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 5-Gallon Water Bottles Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nestlé Waters
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Primo Water Corporation
- 18.4 Culligan International Company
- 18.5 Eden Springs Ltd.
- 18.6 Danone S.A.
- 18.7 Niagara Bottling LLC
- 18.8 Absopure Water Company
- 18.9 HINADA
- 18.10 International Bottled Water Association
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

