
Africa Plasma-derived Therapies Market Overview:
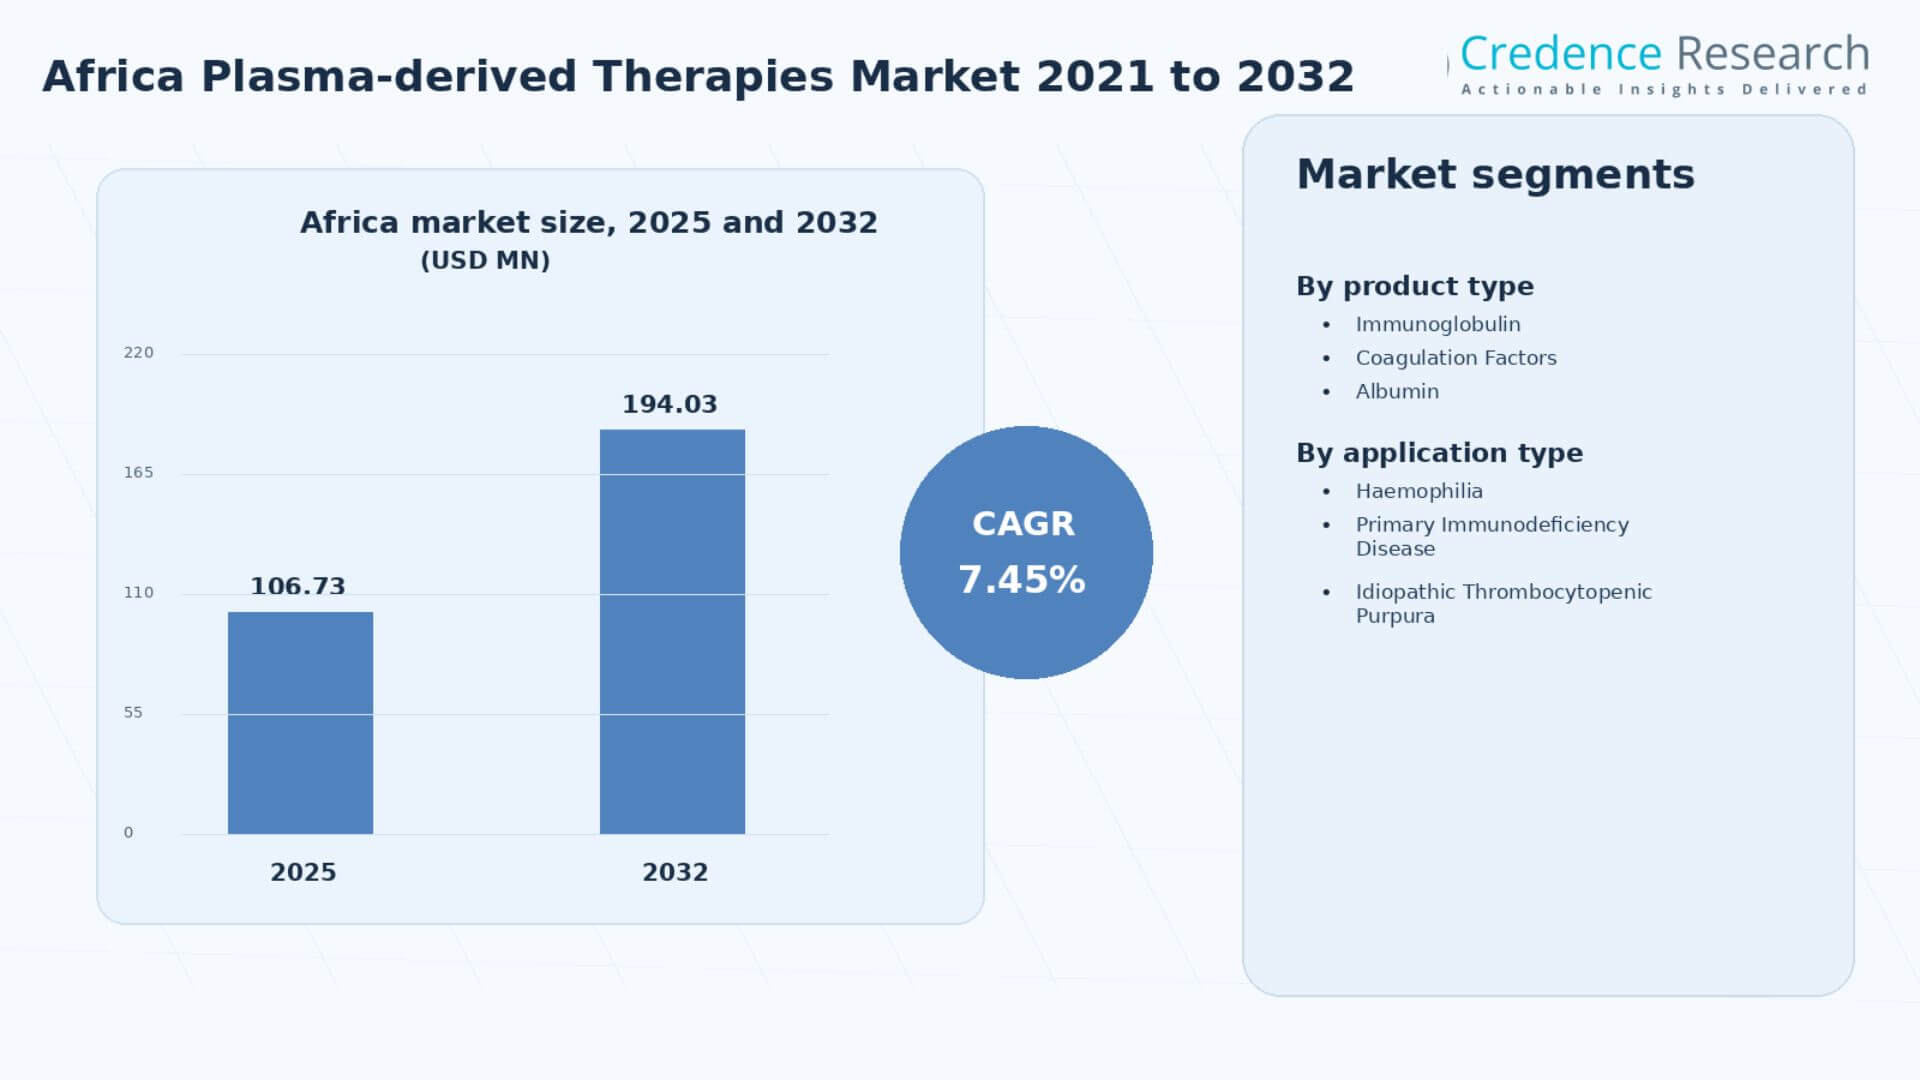
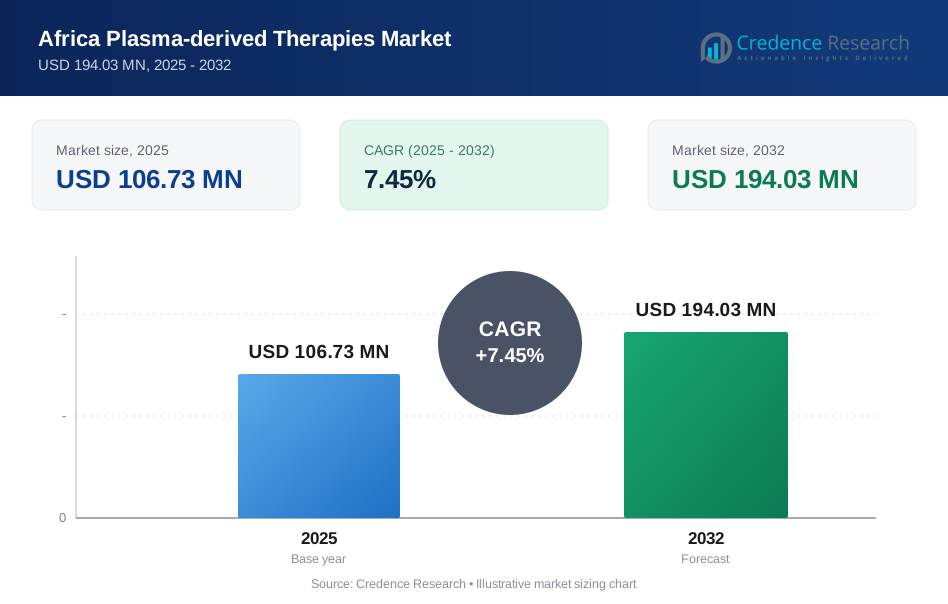
The Africa Plasma-derived Therapies Market size was valued at USD 77.18 MN in 2021 and reached USD 106.73 MN in 2025. It is anticipated to reach USD 194.03 MN by 2032, growing at a CAGR of 7.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2025-2032 |
| Africa Plasma-derived Therapies Market Size 2025 | USD 106.73 million |
| Africa Plasma-derived Therapies Market, CAGR | 7.45% |
| Africa Plasma-derived Therapies Market Size 2032 | USD 194.03 million |
Africa Plasma-derived Therapies Market Insights
- Market growth is supported by rising need for plasma-derived medicinal products, underpenetrated haemophilia care, immunoglobulin demand, albumin use in acute care and gradual strengthening of blood product access systems.
- Immunoglobulin holds a strong position because Primary Immunodeficiency Disease and immune-mediated conditions require long-term replacement therapy and specialist-supervised treatment.
- Coagulation Factors remain critical for Haemophilia care because patients require reliable factor replacement access to prevent or manage bleeding episodes.
- Hospital-based treatment remains central because plasma-derived therapies require diagnosis, cold-chain handling, clinical monitoring and safe administration.
Africa Plasma-derived Therapies Market Segment Insights
By product type
By product type, Immunoglobulin held the strongest position in 2025 because it supports long-term treatment of Primary Immunodeficiency Disease and selected immune-mediated conditions. Demand is concentrated in larger hospitals and specialist centers where diagnosis, dosing, infusion monitoring and cold-chain systems are available. Coagulation Factors remain essential for Haemophilia because factor replacement therapy supports bleeding control, perioperative management and long-term care. Albumin supports acute care, critical care, liver disease management, shock, burns and volume replacement in selected settings. Growth across product types will depend on diagnosis rates, affordability, public procurement, hospital access and reliable plasma-derived medicinal product supply.
By application type
By application type, Haemophilia held a strong position in 2025 because factor replacement remains a core treatment need for patients with inherited bleeding disorders. Access gaps across Africa create significant unmet demand, especially outside major urban hospitals. Primary Immunodeficiency Disease is gaining attention as immunology diagnosis improves and clinicians recognize patients who need immunoglobulin replacement therapy. Idiopathic Thrombocytopenic Purpura supports demand for immunoglobulin in acute immune-mediated platelet disorders and specialist hematology care. Application growth will depend on hematology capacity, immunology testing, patient registries, public reimbursement and donor-supported access programs.
Key Market Drivers
Need for safe and sufficient blood products
Need for safe and sufficient blood products represents a major growth driver for the Africa Plasma-derived Therapies Market. Plasma-derived medicinal products such as immunoglobulins and coagulation factors treat serious conditions that require dependable supply and high quality standards.
WHO reported that governments are responsible for sufficient and equitable supply of plasma-derived medicinal products, and only 49 of 168 reporting countries produced plasma-derived medicinal products through domestic plasma fractionation, while 119 countries imported all PDMPs or did not use them during the reporting period. This supports demand for Immunoglobulin, Coagulation Factors and Hospital-based access models across Africa. Growth will depend on stronger national blood systems, procurement planning, import reliability and safe distribution.
Haemophilia and immune deficiency treatment need
Haemophilia and immune deficiency treatment need supports strong demand for Coagulation Factors and Immunoglobulin. WHO says blood and plasma-derived medical products can dramatically improve life expectancy and quality of life for patients with life-threatening inherited disorders such as haemophilia and immune deficiency. This creates sustained demand across Haemophilia and Primary Immunodeficiency Disease, especially as diagnosis improves in referral hospitals. The market remains underpenetrated because many patients still face delayed diagnosis, limited specialist access and affordability barriers. Expanding hematology and immunology services will support broader use of plasma-derived therapies through 2032.
Growing concern over PDMP access in Africa
Growing concern over PDMP access in Africa is strengthening policy attention and market need. WHO’s 2022 survey report on blood availability, safety and quality in the WHO African Region raised concern about the growing need for plasma-derived medicinal products in Africa.
WHO Africa also reported that 30 countries listed plasma-derived medicinal products on their essential medicines lists, while patients in the region paid an average of USD 42 out of pocket to access safe blood. These figures show both demand recognition and affordability pressure. The driver supports Hospital access, public procurement and payer-led expansion of essential plasma-derived therapies.
Global company investment in plasma-derived portfolios
Global company investment in plasma-derived portfolios supports supply depth and future access in Africa. CSL reported 2025 CSL Behring revenue of USD 6.064 billion for Immunoglobulins, USD 1.297 billion for Albumin and USD 1.488 billion for Haemophilia products. Takeda reported Plasma-Derived Therapies revenue of 517.4 billion yen in the first half of fiscal 2025 and said immunoglobulin grew 3.1% at constant exchange rates, with demand remaining strong. These company trends support long-term supply, portfolio investment and broader availability of Immunoglobulin, Albumin and Coagulation Factors. Africa’s market will benefit as global manufacturers strengthen distribution partnerships and access programs.
Key Trends and Opportunities
Local plasma access and fractionation partnerships gain attention
Local plasma access and fractionation partnerships are gaining attention as African health systems seek more reliable access to plasma-derived medicinal products. WHO’s blood safety guidance emphasizes national blood systems, voluntary unpaid donation, plasma collection and processing systems that meet health care needs. Partnerships with global fractionators can help countries use domestic plasma more effectively where quality systems and regulatory controls support safe production. This trend supports Immunoglobulin, Coagulation Factors and Albumin. Growth will depend on donor recruitment, plasma quality, testing systems, regulatory oversight and commercial feasibility.
Immunoglobulin demand expands in specialty care
Immunoglobulin demand is expanding in specialty care as diagnosis of Primary Immunodeficiency Disease and immune-mediated disorders improves. Immunoglobulin therapy requires repeat dosing, specialist oversight and reliable product availability, making hospital and specialty-center access critical. ADMA Biologics reported full-year 2025 ASCENIV revenue of USD 363 million, up 51% year over year, and said it manufactures FDA-approved plasma-derived biologics for immune deficiencies and prevention of certain infectious diseases. This global commercial momentum supports wider recognition of immunoglobulin therapies. African demand will expand as immunology testing, physician awareness and reimbursement improve.
Albumin and coagulation factors support hospital formularies
Albumin and Coagulation Factors support hospital formularies because they serve acute care, hematology, surgery and inherited bleeding disorder needs. Grifols reported 2025 revenue of EUR 7.524 billion, up 7.0% at constant currency, driven by its Biopharma business and immunoglobulin franchise. It also reported EMA approval for Egypt-sourced plasma and fibrinogen approval by EMA and FDA. This is significant for Africa because Egypt-sourced plasma approval supports regional plasma infrastructure and validates the role of regional supply models. Hospitals with better procurement systems will be better positioned to add plasma-derived therapies to formularies.
Key Market Challenges
High cost and out-of-pocket burden
High cost and out-of-pocket burden remain major challenges for the Africa Plasma-derived Therapies Market. Plasma-derived therapies require complex plasma collection, testing, fractionation, viral safety controls, cold-chain distribution and specialist administration. These cost layers can limit public procurement and patient access. WHO Africa reported that patients in the region paid an average of USD 42 out of pocket to access safe blood, showing broader affordability pressure around blood products and related care. Immunoglobulin and coagulation factors are particularly vulnerable because they often require repeated treatment. Access programs, pooled procurement and donor-supported initiatives will remain important.
Cold-chain and quality system constraints
Cold-chain and quality system constraints can slow market expansion. Plasma-derived therapies require controlled storage, validated transport, batch traceability and hospital-level handling protocols. WHO says national blood systems should be governed by policy and legislative frameworks that promote consistency in quality and safety of blood and blood products. It also recommends quality-assured screening and systems for processing blood into blood products, including plasma-derived medicinal products. Many lower-resource settings still face gaps in testing, storage, distribution and haemovigilance. These constraints affect Immunoglobulin, Coagulation Factors and Albumin access.
Limited diagnosis and specialist capacity
Limited diagnosis and specialist capacity restrict therapy uptake. Haemophilia, Primary Immunodeficiency Disease and Idiopathic Thrombocytopenic Purpura require hematologists, immunologists, laboratory testing and structured follow-up. Patients in rural areas may remain undiagnosed or reach care only after severe complications. Hospital access is stronger in South Africa, Egypt, Kenya, Nigeria and large urban centers, but smaller markets face larger gaps. Limited patient registries make forecasting and procurement difficult. Companies and health systems must support clinician education, diagnostic pathways and treatment centers to expand demand responsibly.
Regional Analysis
South Africa
South Africa leads the Africa Plasma-derived Therapies Market due to stronger blood product regulation, specialist hospitals, hematology expertise and private insurance access. Hospitals manage Immunoglobulin, Coagulation Factors and Albumin through structured procurement and monitored administration. South Africa also has stronger experience with plasma-derived medicinal products than many regional peers. WHO’s global blood data show that government responsibility, national blood systems and safe plasma-derived product supply remain central to access, which aligns with South Africa’s more advanced market position. Growth will depend on reimbursement, public procurement, specialist capacity and supply continuity.
Egypt
Egypt represents a strong growth market due to large population, expanding tertiary hospitals and rising relevance in regional plasma infrastructure. Grifols reported EMA approval for Egypt-sourced plasma in 2025 and described it as a paradigm shift in the industry, reinforcing Egypt’s strategic role in plasma-derived medicine supply. Demand is supported by Albumin, Coagulation Factors and Immunoglobulin across hospitals and specialty hematology care. Growth will depend on regulatory execution, hospital access, public procurement and supply partnerships.
Nigeria
Nigeria offers long-term potential due to its large population and unmet need in hematology, immunology and critical care. Haemophilia and Primary Immunodeficiency Disease remain underdiagnosed, while Albumin demand is concentrated in larger private and public hospitals. Access constraints remain significant due to affordability, cold-chain infrastructure and limited specialist networks. Hospital procurement will remain the main access pathway for plasma-derived therapies. Growth will depend on diagnostic capacity, insurance expansion, public-sector procurement, donor support and private hospital investment.
Kenya
Kenya is an emerging market supported by growing specialist care, regional referral hospitals and improving private health care access. Demand is concentrated in Haemophilia, Primary Immunodeficiency Disease and acute hospital use of Albumin. Hospital systems remain the primary channel because plasma-derived therapies need specialist diagnosis and safe administration. Kenya can serve as an East African access hub if cold-chain logistics, regulation and payer coverage improve. Growth will depend on hematology networks, immunology testing, procurement reliability and manufacturer access programs.
Rest of Africa
Rest of Africa includes markets with diverse blood product capacity, funding levels and hospital access. Countries with stronger tertiary hospitals are expected to adopt plasma-derived therapies faster, while lower-resource countries may prioritize blood safety, donor recruitment and essential blood product access before broader PDMP use. WHO reported that 36 countries in the African Region were among countries collecting fewer than 10 blood donations per 1,000 people, highlighting supply constraints that affect blood product access. Long-term growth will depend on national blood policy, regional procurement, donor programs, regulatory oversight and hospital pharmacy readiness.
Report Attribute Details
| Report Attribute | Details |
| Historical Period | 2021–2024 |
| Base Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size in 2021 | USD 77.18 MN |
| Market Size in 2025 | USD 106.73 MN |
| Market Size in 2032 | USD 194.03 MN |
| CAGR | 7.45% |
| Segments Covered | Product Type, Application Type and Geography |
| Key Companies Covered | ADMA Biologics, Inc., Bio Products Laboratory (BPL), CSL Behring, Grifols, S.A. (Biotest AG), Kamada Ltd., Kedrion SpA, Octapharma AG, Pfizer, Inc., SK Plasma and Takeda Pharmaceutical Co. Ltd. |
Africa Plasma-derived Therapies Market Segmentations
By Product Type
- Immunoglobulin
- Coagulation Factors
- Albumin
By Application Type
- Haemophilia
- Primary Immunodeficiency Disease
- Idiopathic Thrombocytopenic Purpura
Key players
- ADMA Biologics, Inc.
- Bio Products Laboratory (BPL)
- CSL Behring
- Grifols, S.A. (Biotest AG)
- Kamada Ltd.
- Kedrion SpA
- Octapharma AG
- Pfizer, Inc.
- SK Plasma
- Takeda Pharmaceutical Co. Ltd.
Recent Developments
- In February 2026, Grifols reported 2025 revenue of EUR 7.524 billion, up 7.0% at constant currency, driven by its Biopharma business and immunoglobulin franchise. It also reported EMA approval for Egypt-sourced plasma and fibrinogen approval by EMA and FDA.
- In February 2026, ADMA Biologics reported full-year 2025 ASCENIV revenue of USD 363 million, up 51% year over year, and expanded access through a new authorized distribution agreement with McKesson Specialty for ASCENIV and BIVIGAM.
- In February 2026, Octapharma reported 2025 group sales of EUR 3.64 billion, up 5% year over year, and operating income of EUR 577 million, supported by efficiency improvements and economies of scale in plasma collection and production.
- In first-half fiscal 2025, Takeda reported Plasma-Derived Therapies revenue of 517.4 billion yen and said immunoglobulin grew 3.1% at constant exchange rates.
Report Coverage
The research report offers an in-depth analysis based on product type, application type and geography. It details leading market players, providing an overview of their business positioning, plasma-derived product portfolios, immunoglobulin capabilities, coagulation factor offerings, albumin supply, plasma collection networks, fractionation capacity and strategic relevance in the Africa Plasma-derived Therapies Market. The report includes insights into the competitive environment, market trends, growth drivers, restraints and opportunities. It also examines blood product access, haemophilia treatment need, primary immunodeficiency diagnosis, hospital formularies, plasma supply constraints, cold-chain requirements and regional procurement models as major factors shaping market development. The report assesses the impact of high therapy cost, out-of-pocket burden, limited specialist capacity, quality system gaps and cold-chain constraints on market growth. It provides strategic recommendations for plasma-derived therapy manufacturers, hospitals, blood services, procurement agencies, distributors, payers, investors and new entrants seeking to navigate Africa’s plasma-derived therapies ecosystem.
Future Outlook
- Demand for plasma-derived therapies will continue to rise as African health systems improve diagnosis and access for Haemophilia, Primary Immunodeficiency Disease and immune-mediated disorders.
- Immunoglobulin will remain a leading product type due to long-term replacement therapy demand in Primary Immunodeficiency Disease.
- Coagulation Factors will gain importance as haemophilia diagnosis, factor access and bleeding disorder care programs improve.
- Albumin will remain important in hospitals because it supports acute care, critical care and selected volume replacement needs.
- Haemophilia will remain a major application due to high unmet treatment needs and dependence on reliable factor access.
- Primary Immunodeficiency Disease will expand as immunology testing and specialist awareness improve.
- Idiopathic Thrombocytopenic Purpura will support demand for immunoglobulin in specialist hematology settings.
- South Africa and Egypt will remain key markets due to stronger hospital infrastructure, regulatory capacity and plasma-derived product access.
- Regional plasma programs and import partnerships will gain strategic value as countries seek reliable supply.
- Competition will increase as companies compete on product quality, supply reliability, cold-chain strength, access programs, pricing and hospital procurement relationships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Africa Plasma-derived Therapies Market and what is its projected size in 2032?
At what CAGR is the Africa Plasma-derived Therapies Market projected to grow?
Which product type segment is expected to lead the market?
Which application type supports strong market demand?
Which country leads the Africa market?
Who are the leading companies in the market?
What are the key challenges in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 106.73 MN → 2032: USD 194.03 MN
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Africa Plasma-derived Therapies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Africa Plasma-derived Therapies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Africa Plasma-derived Therapies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Africa Plasma-derived Therapies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Africa Plasma-derived Therapies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Africa Plasma-derived Therapies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Africa Plasma-derived Therapies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Africa Plasma-derived Therapies Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 106.73 MN → 2032: USD 194.03 MN)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Africa Plasma-derived Therapies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Africa Plasma-derived Therapies Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Country-Level Shares, 2025
- 13.2 Country Market Size Comparison, 2025
- 13.3 Country Market Forecasts, 2025-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Africa Plasma-derived Therapies Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Africa Plasma-derived Therapies Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

