
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aircraft Hangar Market Size 2024 | USD 1145 Million |
| Aircraft Hangar Market, CAGR | 6.4% |
| Aircraft Hangar Market Size 2032 | USD 1880.8 Million |
Market Overview:
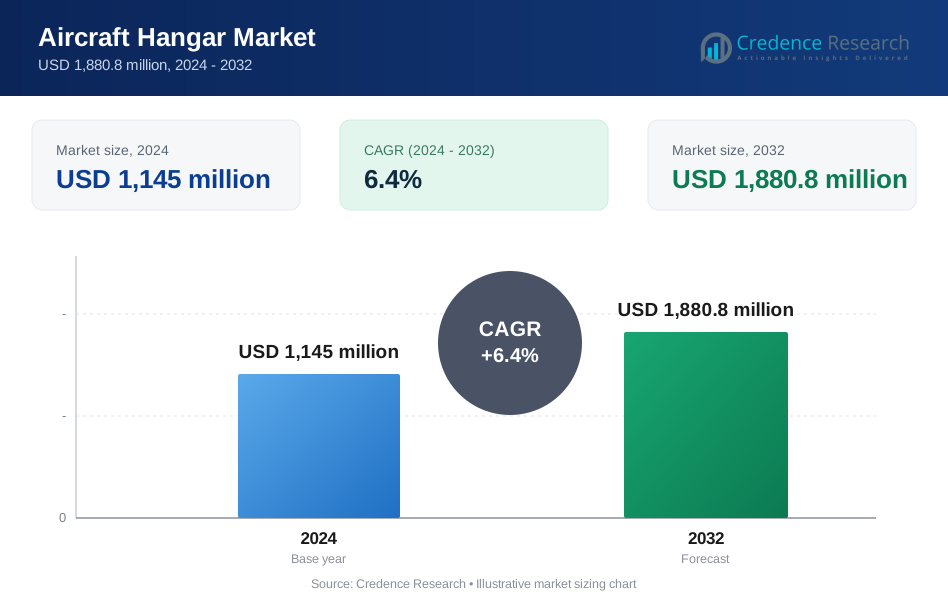
The Aircraft Hangar Market is projected to grow from USD 1145 million in 2024 to an estimated USD 1880.8 million by 2032, with a compound annual growth rate (CAGR) of 6.4% from 2024 to 2032.
Key drivers fueling the Aircraft Hangar Market include the rise in global air traffic, expansion of commercial airline fleets, and a notable increase in maintenance, repair, and overhaul (MRO) activities. Airports and private operators are investing in advanced hangar solutions to accommodate a wider range of aircraft sizes and to meet evolving service demands. Fabric and modular hangars are gaining popularity due to their cost-effectiveness, faster installation, and adaptability. Technological enhancements such as automated hangar doors, climate control systems, and energy-efficient lighting are also contributing to improved functionality and lower operational costs. Military modernization programs and the rise in business aviation are further supporting demand for customized and secure hangar facilities.
Regionally, North America holds the largest share of the Aircraft Hangar Market, driven by its high volume of air traffic, strong MRO sector, and the presence of established aviation infrastructure and major hangar solution providers. Europe follows closely, supported by ongoing investments in airport upgrades and a focus on environmentally sustainable building practices. The Asia-Pacific region is experiencing the fastest growth, led by rapid airport expansion, increasing aircraft procurement, and the growing popularity of private and business jets, particularly in China, India, and Southeast Asia. Meanwhile, markets in the Middle East, Latin America, and Africa are gradually emerging, spurred by strategic infrastructure projects, economic diversification plans, and efforts to develop aviation hubs across these regions.
Market Insights:
- The Aircraft Hangar Market is projected to grow from USD 1,145 million in 2024 to USD 1,880.8 million by 2032, registering a CAGR of 6.4%, driven by rising global air traffic and fleet expansions.
- Increased demand for wide-body aircraft storage and climate-controlled environments is encouraging airlines and private operators to invest in larger and more advanced hangar infrastructure.
- The growth of MRO activities, especially for aging fleets, is pushing demand for specialized hangars with integrated support systems that reduce downtime and improve operational efficiency.
- Military modernization programs in North America, Europe, and Asia-Pacific are boosting demand for secure, climate-controlled hangars designed for fighter jets, drones, and multi-role aircraft.
- The business aviation sector is driving demand for custom hangars that offer premium services, privacy, and integrated office or lounge spaces, especially near general aviation hubs.
- High capital investment, long construction timelines, and complex regulatory approval processes are major barriers that limit new entrants and delay infrastructure scaling, especially at smaller airports.
- North America leads the Aircraft Hangar Market in terms of share, followed by Europe, while Asia-Pacific shows the fastest growth, led by rapid airport development and aircraft procurement in China and India.
Market Drivers:
Rising Global Air Traffic and Fleet Expansion Fuel Infrastructure Needs:
The rapid growth in global air passenger traffic continues to drive investments in aviation infrastructure, including hangars. Airlines are expanding their fleets to meet increasing demand, leading to a greater need for secure and efficient aircraft storage and servicing facilities. The Aircraft Hangar Market benefits directly from this trend, particularly at major international and regional airports. Airlines and private operators are focusing on constructing hangars that can accommodate wide-body aircraft and support faster turnaround times. Hangar developments are aligning with long-term fleet modernization strategies adopted by commercial carriers. It responds to the increasing need for protected, climate-controlled environments to safeguard aircraft during idle and maintenance periods.
- For instance, in the United States, the Federal Aviation Administration awarded nearly $246 million in 2024 for airport infrastructure modernization across 37 states, directly supporting new and upgraded hangar facilities.
Accelerated Growth in MRO Activities Drives Specialized Hangar Demand:
Aircraft maintenance, repair, and overhaul (MRO) activities are becoming more frequent and complex due to aging fleets and evolving aviation regulations. Hangars play a critical role in housing aircraft during inspections, upgrades, and structural repairs. The Aircraft Hangar Market is witnessing rising demand for purpose-built MRO hangars equipped with integrated support systems. Airlines and third-party MRO service providers are investing in dedicated facilities to minimize downtime and extend aircraft lifecycle. It is also driven by the need for advanced tools and technology within hangars, such as overhead cranes, docking systems, and ventilation equipment. Efficient hangar design directly impacts operational efficiency and cost-effectiveness for MRO operations.
- For example, in Georgia, 7% of 1,298 existing hangar structures are dedicated to maintenance and MRO, reflecting the sector’s significance.
Military Modernization and Strategic Defense Infrastructure Programs Support Expansion:
Defense forces across the globe are modernizing their fleets and enhancing aviation support infrastructure. Secure and technologically advanced hangars are essential for military aircraft storage, rapid deployment readiness, and classified maintenance operations. The Aircraft Hangar Market is expanding in tandem with military infrastructure projects, especially in North America, Europe, and parts of Asia-Pacific. Governments are allocating substantial budgets for airbase upgrades, which include hardened and climate-controlled hangar facilities. It is influenced by the requirement to house a wide range of aircraft types, including drones, fighter jets, and heavy transport planes. Military hangars also integrate command and control capabilities, reflecting a shift toward multipurpose facility design.
Growth in Business Aviation and Private Jet Ownership Spurs Hangar Development:
The rise in high-net-worth individuals and corporate travel is driving growth in business aviation, leading to an increase in private jet ownership and charter operations. Private operators demand exclusive, high-end hangar space to ensure aircraft security and convenience. The Aircraft Hangar Market is seeing greater investment in custom-built hangars with advanced access control, aesthetic design, and integrated lounges or office spaces. Fixed-base operators (FBOs) and airport authorities are expanding hangar offerings to cater to this premium segment. It reflects a shift in market dynamics where customer experience and asset protection are equally prioritized. Hangar developers are responding with scalable and flexible designs suited for general aviation hubs.
Market Trends:
Rising Adoption of Modular and Fabric Hangars Enhances Flexibility:
Modular and fabric-based hangars are gaining traction due to their cost-efficiency, faster construction timelines, and adaptability across various airport environments. These structures are particularly valuable for temporary use or remote airfields where permanent infrastructure is not feasible. The Aircraft Hangar Market is benefiting from this shift, as operators seek scalable solutions that meet operational demands without heavy capital investment. Fabric hangars offer climate protection and structural integrity, making them suitable for both commercial and defense applications. It supports rapid deployment, which is essential for emergency response or military operations. Demand for flexible hangar options is expected to increase in markets with volatile climatic conditions and budget constraints.
- In Florida, the persistent shortage of hangar space and waiting lists at nearly every airport further highlight the need for scalable, quickly deployable hangar solutions.
Integration of Smart Technologies Improves Operational Efficiency:
Advanced technologies such as automation, IoT, and real-time monitoring are reshaping hangar operations. Smart hangars now include features like automated doors, energy-efficient lighting systems, and centralized climate control. The Aircraft Hangar Market is embracing digital transformation to improve safety, reduce energy consumption, and enable predictive maintenance. Sensors and connected systems allow operators to monitor structural health and environmental conditions continuously. It enables better decision-making and minimizes downtime during inspections or repairs. Integration of these technologies reflects a broader push toward intelligent infrastructure across the aviation sector.
- For example, the DARTeC hangar in the UK utilizes a high-performance computing ecosystem for automated inspection and real-time data analysis, enhancing safety and efficiency.
Sustainable Construction and Green Certifications Gain Importance:
Environmental considerations are influencing the design and construction of new hangar facilities. Airport authorities and private developers are prioritizing LEED-certified buildings and sustainable construction practices. The Aircraft Hangar Market is seeing increased demand for energy-efficient insulation, solar power integration, and water recycling systems. It aligns with global aviation sustainability goals and regulatory mandates on carbon footprint reduction. Use of eco-friendly building materials and renewable energy sources is becoming standard in new hangar projects. The trend is particularly strong in Europe and North America, where environmental standards are stricter and incentives support green infrastructure development.
Custom Hangar Solutions Rise with Diversified Aircraft Portfolios:
As airlines, private operators, and defense forces expand their fleets with varying aircraft models, demand for custom-designed hangars is growing. Hangars must now accommodate diverse requirements-from wide-body aircraft to drones and rotary-wing platforms. The Aircraft Hangar Market is evolving to support tailored layouts, integrated workshops, and multipurpose bays. It reflects the need for versatility in layout, access, and equipment to serve mixed-use operations efficiently. Customized hangars offer operational flexibility and maximize land use at airports. Developers and engineering firms are focusing on modular yet adaptable designs to meet client-specific needs.
Market Challenges Analysis:
High Capital Investment and Long Construction Timelines Limit Entry:
Constructing aircraft hangars involves significant upfront capital, specialized engineering, and strict regulatory approvals. These factors pose a substantial entry barrier, particularly for small airports and private operators. The Aircraft Hangar Market reflects these limitations, as large-scale developments often depend on government or institutional funding. Complexities in securing permits, land acquisition, and compliance with safety standards delay project timelines. It impacts market scalability, especially in regions with limited infrastructure or fluctuating budgets. Long lead times and high construction costs deter frequent upgrades or expansions, restricting market dynamism.
Regulatory Constraints and Land Availability Restrict Expansion:
Hangar construction is tightly regulated by aviation safety bodies and municipal authorities, creating operational and planning challenges. Zoning restrictions, height limits, and proximity regulations to runways and taxiways constrain available land for new developments. The Aircraft Hangar Market faces added pressure in urban or saturated airport environments, where suitable real estate is limited and expensive. It must balance operational efficiency with regulatory compliance, often leading to compromises in design or layout. Environmental assessments and public consultation processes further slowdown execution. These constraints collectively hinder timely deployment of new or expanded hangar facilities.
Market Opportunities:
Emerging Markets and Regional Airport Development Offer Growth Potential:
Expanding aviation infrastructure in emerging economies presents significant opportunities for hangar construction. Governments in Asia-Pacific, Latin America, and Africa are investing in regional airport development to support passenger growth and economic connectivity. The Aircraft Hangar Market stands to gain from increased demand for storage and maintenance facilities in secondary and tertiary cities. New airline routes and fleet introductions will require modern hangars capable of supporting both narrow-body and wide-body aircraft. It can capitalize on lower land costs and public-private partnerships to scale efficiently. Demand for cost-effective and modular hangar solutions remains strong in these regions.
Growth in Private Aviation and FBO Networks Fuels Specialized Demand:
The rise of business aviation and expanding networks of fixed-base operators (FBOs) create new market segments for premium hangar infrastructure. High-net-worth individuals and corporations are seeking customized facilities that offer privacy, aesthetics, and integrated services. The Aircraft Hangar Market can address this demand through flexible designs that include office space, VIP lounges, and advanced access control systems. It can also leverage growth in luxury travel and air charter services to deliver high-margin projects. Operators value proximity to terminals and quick turnaround, driving investment in hangars with advanced logistics support. This trend opens long-term opportunities in private aviation hubs across developed and developing regions.
Market Segmentation Analysis:
By Type
The Aircraft Hangar Market includes MRO, assembly, and storage hangars. MRO hangars dominate due to the growing need for scheduled maintenance and overhaul services. Assembly hangars support aircraft manufacturing, while storage hangars cater to idle aircraft protection in both commercial and private sectors.
- For instance, MRO hangars dominate due to the growing need for scheduled maintenance and overhaul services, as evidenced by the $90.56 billion global aircraft maintenance market in 2024 and the high occupancy rates of maintenance hangars in U.S. states like Georgia.
By Construction
Fixed installations lead the market with long-term, durable structures used in commercial and military applications. Portable installations are gaining traction for their rapid deployment and suitability in remote or temporary locations, especially for general aviation and military operations.
- For instance, In the U.S., 55% of hangars are corporate/box hangars, and 28% are T-hangars, reflecting the predominance of permanent structures.
By Material
Steel remains the most widely used material due to its strength and cost-efficiency. Concrete supports permanent infrastructure with high durability. Fabric hangars are emerging as flexible and eco-friendly alternatives. Wood sees limited use in small-scale or niche applications.
By Platform/Application
Commercial aviation holds the largest share due to high fleet volumes and expanding airport infrastructure. Military applications demand secure, specialized hangars. General aviation benefits from rising private jet and helicopter ownership.
By Aircraft Type
Hangars are segmented by aircraft size and design. Wide-body and narrow-body aircraft require larger, more complex hangars. Jets and helicopters have more compact spatial needs, while general aviation covers a broad range of smaller aircraft.
By Component
Hangar components include canopy, doors, ventilation, lighting, flooring, and others. Doors and ventilation systems are critical for operational efficiency and aircraft protection. Integrated systems enhance safety, energy use, and functionality.
Segmentation:
By Type- Maintenance, Repair, and Overhaul (MRO)
- Assembly
- Storage
- Fixed Installation
- Portable Installation
- Steel
- Concrete
- Fabric
- Wood
- Commercial
- Military
- General Aviation
- Wide Body
- Narrow Body
- Jets
- Helicopters
- General Aviation/Other
- Canopy
- Doors
- Ventilation
- Lighting
- Flooring
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Maintains Market Dominance with Strong Infrastructure and MRO Demand
North America holds the largest share in the Aircraft Hangar Market, accounting for approximately 38% of the global market. The region benefits from extensive aviation infrastructure, high air traffic volume, and a large presence of commercial airlines and defense organizations. Strong demand for MRO services and fleet modernization drives investment in both permanent and temporary hangar structures. The United States leads in hangar construction due to its active general aviation community and numerous fixed-base operators. It continues to witness public and private sector collaboration in expanding hangar capacity at regional and international airports. Technological integration and sustainability initiatives are also shaping hangar upgrades across key states.
Asia-Pacific Emerges as Fastest-Growing Market Backed by Fleet Expansion
Asia-Pacific represents around 26% of the Aircraft Hangar Market and is projected to register the fastest growth rate over the forecast period. Rapid fleet expansion, urban airport development, and increasing commercial and business aviation activities fuel demand in this region. China and India are key contributors, supported by rising air passenger traffic and government investments in aviation infrastructure. It sees growing adoption of modular hangars to meet space constraints in busy metropolitan airports. Emerging economies across Southeast Asia also show strong potential for new airport and hangar construction. The market responds to rising demand for efficient storage, maintenance, and ground support facilities across multiple aviation sectors.
Europe Focuses on Green Infrastructure and Military Modernization
Europe accounts for approximately 22% of the Aircraft Hangar Market, driven by a balanced demand from commercial, defense, and private aviation sectors. Countries like Germany, France, and the UK continue to invest in hangar upgrades aligned with energy efficiency standards and emissions regulations. It supports smart and sustainable hangar developments, often backed by EU environmental directives and funding programs. Military aircraft fleet expansion and NATO commitments also contribute to the demand for advanced hangar facilities. European airports are prioritizing the replacement of aging infrastructure with modern, tech-enabled structures. The regional market remains competitive, with growing interest in automation, climate control, and digital integration features.
Key Player Analysis:
- Rubb Buildings Ltd
- Erect-A-Tube, Inc.
- Diuk Arches Ltd.
- HTS TENTIQ GmbH
- Fulfab Inc.
- John Reid & Sons (Strucsteel) Ltd.
- BlueScope Buildings North America, Inc.
- Allied Steel Buildings Inc.
- J & M Steel Solutions Inc.
- Big Top Manufacturing Inc.
- AECOM Technology Corporation
- Alaska Structures
- ClearSpan Fabric Structures Inc.
- Centrex Construction Inc.
Competitive Analysis:
The Aircraft Hangar Market features a competitive landscape marked by the presence of established construction firms, aerospace infrastructure providers, and specialized modular hangar manufacturers. Key players focus on custom design, structural engineering expertise, and turnkey project execution to strengthen their market position. The market favors companies that offer energy-efficient, scalable, and technology-integrated hangar solutions tailored to commercial, military, and private aviation needs. It rewards firms that can deliver rapid deployment capabilities and comply with stringent regulatory and safety standards. Strategic partnerships with airport authorities, defense agencies, and FBOs are critical to securing long-term contracts. Companies with global supply chains, advanced fabrication capabilities, and a diverse project portfolio maintain a competitive edge. The Aircraft Hangar Market continues to see innovation in smart infrastructure, green building materials, and automated systems, driving differentiation among leading players and new entrants.
Recent Developments:
- In May 2023, John Reid & Sons (Strucsteel) Ltd. (REIDsteel) reached a significant milestone by acquiring a 2.2-acre plot adjacent to its headquarters in Christchurch, UK. This purchase is part of a multi-million-pound redevelopment plan to build a state-of-the-art manufacturing complex, new offices, and staff facilities. The expansion will enhance REIDsteel’s productivity and capabilities in designing and supplying steel structures, including aircraft hangars, and will support further growth and investment in the local economy.
- In June 2024, HTS TENTIQ GmbH was recognized for its exceptional service and innovation by winning the Hire & Rental Industry Association (HRIA) 2024 award for “Supplier of the Year – Events” at the HIRE24 event in Brisbane. This marks the second time HTS TENTIQ has received this prestigious industry award, reflecting its continued leadership and excellence in the sector.
- In October 2024, BlueScope Buildings North America, Inc. announced the extension of its Collaboration Partnership with the American Institute of Architects (AIA) through 2024. This ongoing partnership focuses on sustainability, decarbonization, and advancing energy-efficient building solutions, reinforcing BlueScope’s role as a transformative partner in the building and construction industry.
Market Concentration & Characteristics:
The Aircraft Hangar Market shows moderate concentration with a mix of global engineering firms, specialized hangar solution providers, and regional contractors competing for both commercial and defense projects. It requires high technical precision, compliance with aviation safety standards, and integration of smart infrastructure. The market values design flexibility, rapid deployment capability, and energy efficiency. It involves long project cycles, high capital investment, and strong reliance on public-private partnerships, especially at large airports. Competitive advantage depends on turnkey execution, customization, and adherence to environmental and regulatory mandates. The Aircraft Hangar Market continues to evolve with a growing shift toward modular structures and sustainable construction practices.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Construction, By Material, By Platform/Application, By Aircraft Type, By Component and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise with increasing global aircraft fleet size across commercial, military, and private sectors.
- Modular and prefabricated hangars will gain popularity for their speed of installation and cost advantages.
- Integration of smart systems and automation will enhance operational efficiency and safety in hangar operations.
- Sustainability goals will drive adoption of eco-friendly materials and energy-efficient hangar designs.
- MRO expansion will boost investment in specialized hangars equipped for maintenance and repair.
- Growth in private aviation will create opportunities for luxury and customized hangar solutions.
- Defense modernization programs will support demand for secure and multi-functional military hangars.
- Emerging markets will invest in regional airport hangars to support rising domestic air traffic.
- Hangar construction will increasingly align with airport master plans and infrastructure modernization.
- Strategic partnerships between OEMs, FBOs, and infrastructure firms will shape long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Air Traffic and Fleet Expansion
Increasing air passenger volumes and airline fleet expansions are driving the need for more and larger aircraft hangars to support storage, maintenance, and operational efficiency at airports worldwide.
Accelerated Growth in MRO Activities
Aging aircraft fleets and stricter aviation regulations are boosting demand for specialized MRO hangars equipped with advanced support systems, enabling airlines and service providers to minimize downtime and extend aircraft lifecycles.
Military Modernization and Strategic Defense Infrastructure
Ongoing defense modernization programs in North America, Europe, and Asia-Pacific are fueling investments in secure, climate-controlled hangars for military aircraft, drones, and multi-role platforms, supporting rapid deployment and classified operations.
Growth in Business Aviation and Private Jet Ownership
The rise in high-net-worth individuals and corporate travel is increasing demand for custom-built, premium hangar facilities that offer privacy, integrated office spaces, and advanced security, especially near general aviation hubs.
Adoption of Modular and Fabric Hangars
Operators are increasingly choosing modular and fabric hangars for their cost-effectiveness, rapid deployment, and adaptability, particularly in regions with volatile climates, budget constraints, or urgent infrastructure needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aircraft Hangar Market?
What factors are driving the growth of the Aircraft Hangar Market?
What are the key segments within the Aircraft Hangar Market?
What are some challenges faced by the Aircraft Hangar Market?
Who are the major players in the Aircraft Hangar Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Maintenance, Repair, and Overhaul (MRO)
- 1.2.2 Assembly
- 1.2.3 Storage
- 1.3 By Material
- 1.3.1 Steel
- 1.3.2 Concrete
- 1.3.3 Fabric
- 1.3.4 Wood
- 1.4 By Construction
- 1.4.1 Fixed Installation
- 1.4.2 Portable Installation
- 1.5 By Platform/Application
- 1.5.1 Commercial
- 1.5.2 Military
- 1.5.3 General Aviation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,145 million → 2032: USD 1,880.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aircraft Hangar Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aircraft Hangar Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aircraft Hangar Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aircraft Hangar Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aircraft Hangar Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aircraft Hangar Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aircraft Hangar Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aircraft Hangar Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,145 million → 2032: USD 1,880.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aircraft Hangar Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Maintenance, Repair, and Overhaul (MRO)
- 12.3.7.2 Assembly
- 12.3.7.3 Storage
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Steel
- 12.4.7.2 Concrete
- 12.4.7.3 Fabric
- 12.4.7.4 Wood
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Construction - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fixed Installation
- 12.5.7.2 Portable Installation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Platform/Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Commercial
- 12.6.7.2 Military
- 12.6.7.3 General Aviation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aircraft Hangar End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aircraft Hangar Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aircraft Hangar Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aircraft Hangar Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Rubb Buildings Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Erect-A-Tube, Inc.
- 18.4 HTS TENTIQ GmbH
- 18.5 BlueScope Buildings North America, Inc.
- 18.6 Allied Steel Buildings Inc.
- 18.7 John Reid & Sons (Strucsteel) Ltd.
- 18.8 Big Top Manufacturing Inc.
- 18.9 ClearSpan Fabric Structures Inc.
- 18.10 AECOM Technology Corporation
- 18.11 Alaska Structures
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

