
Parcel hubs and export cargo pull shippers to operators
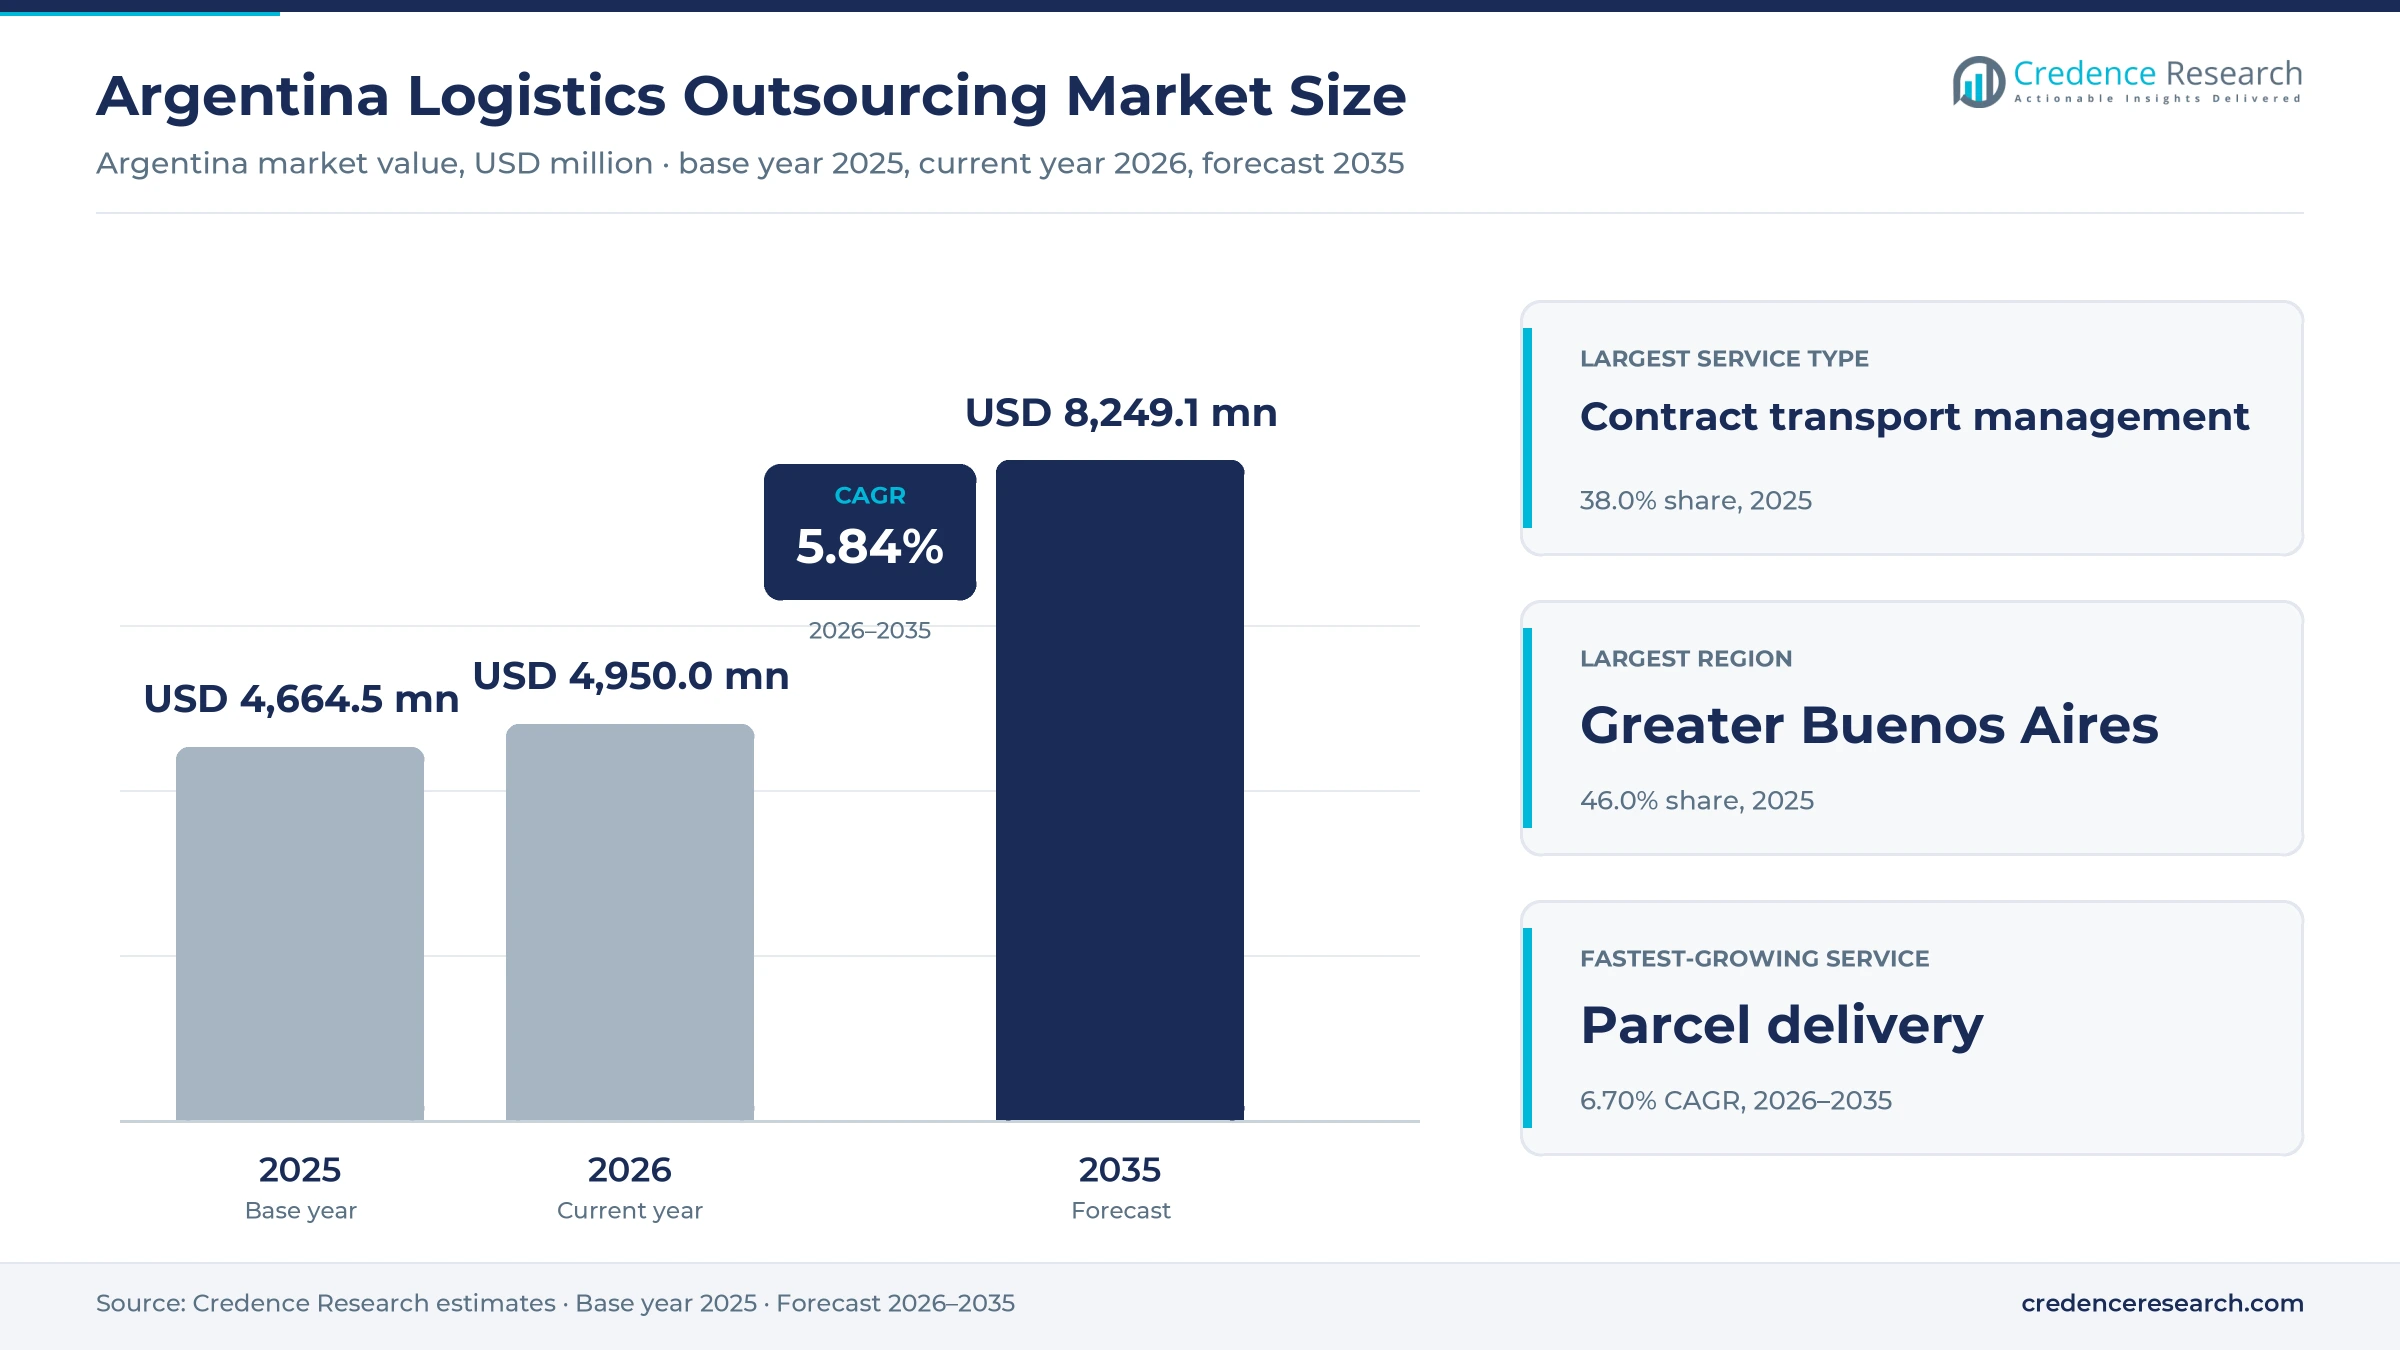
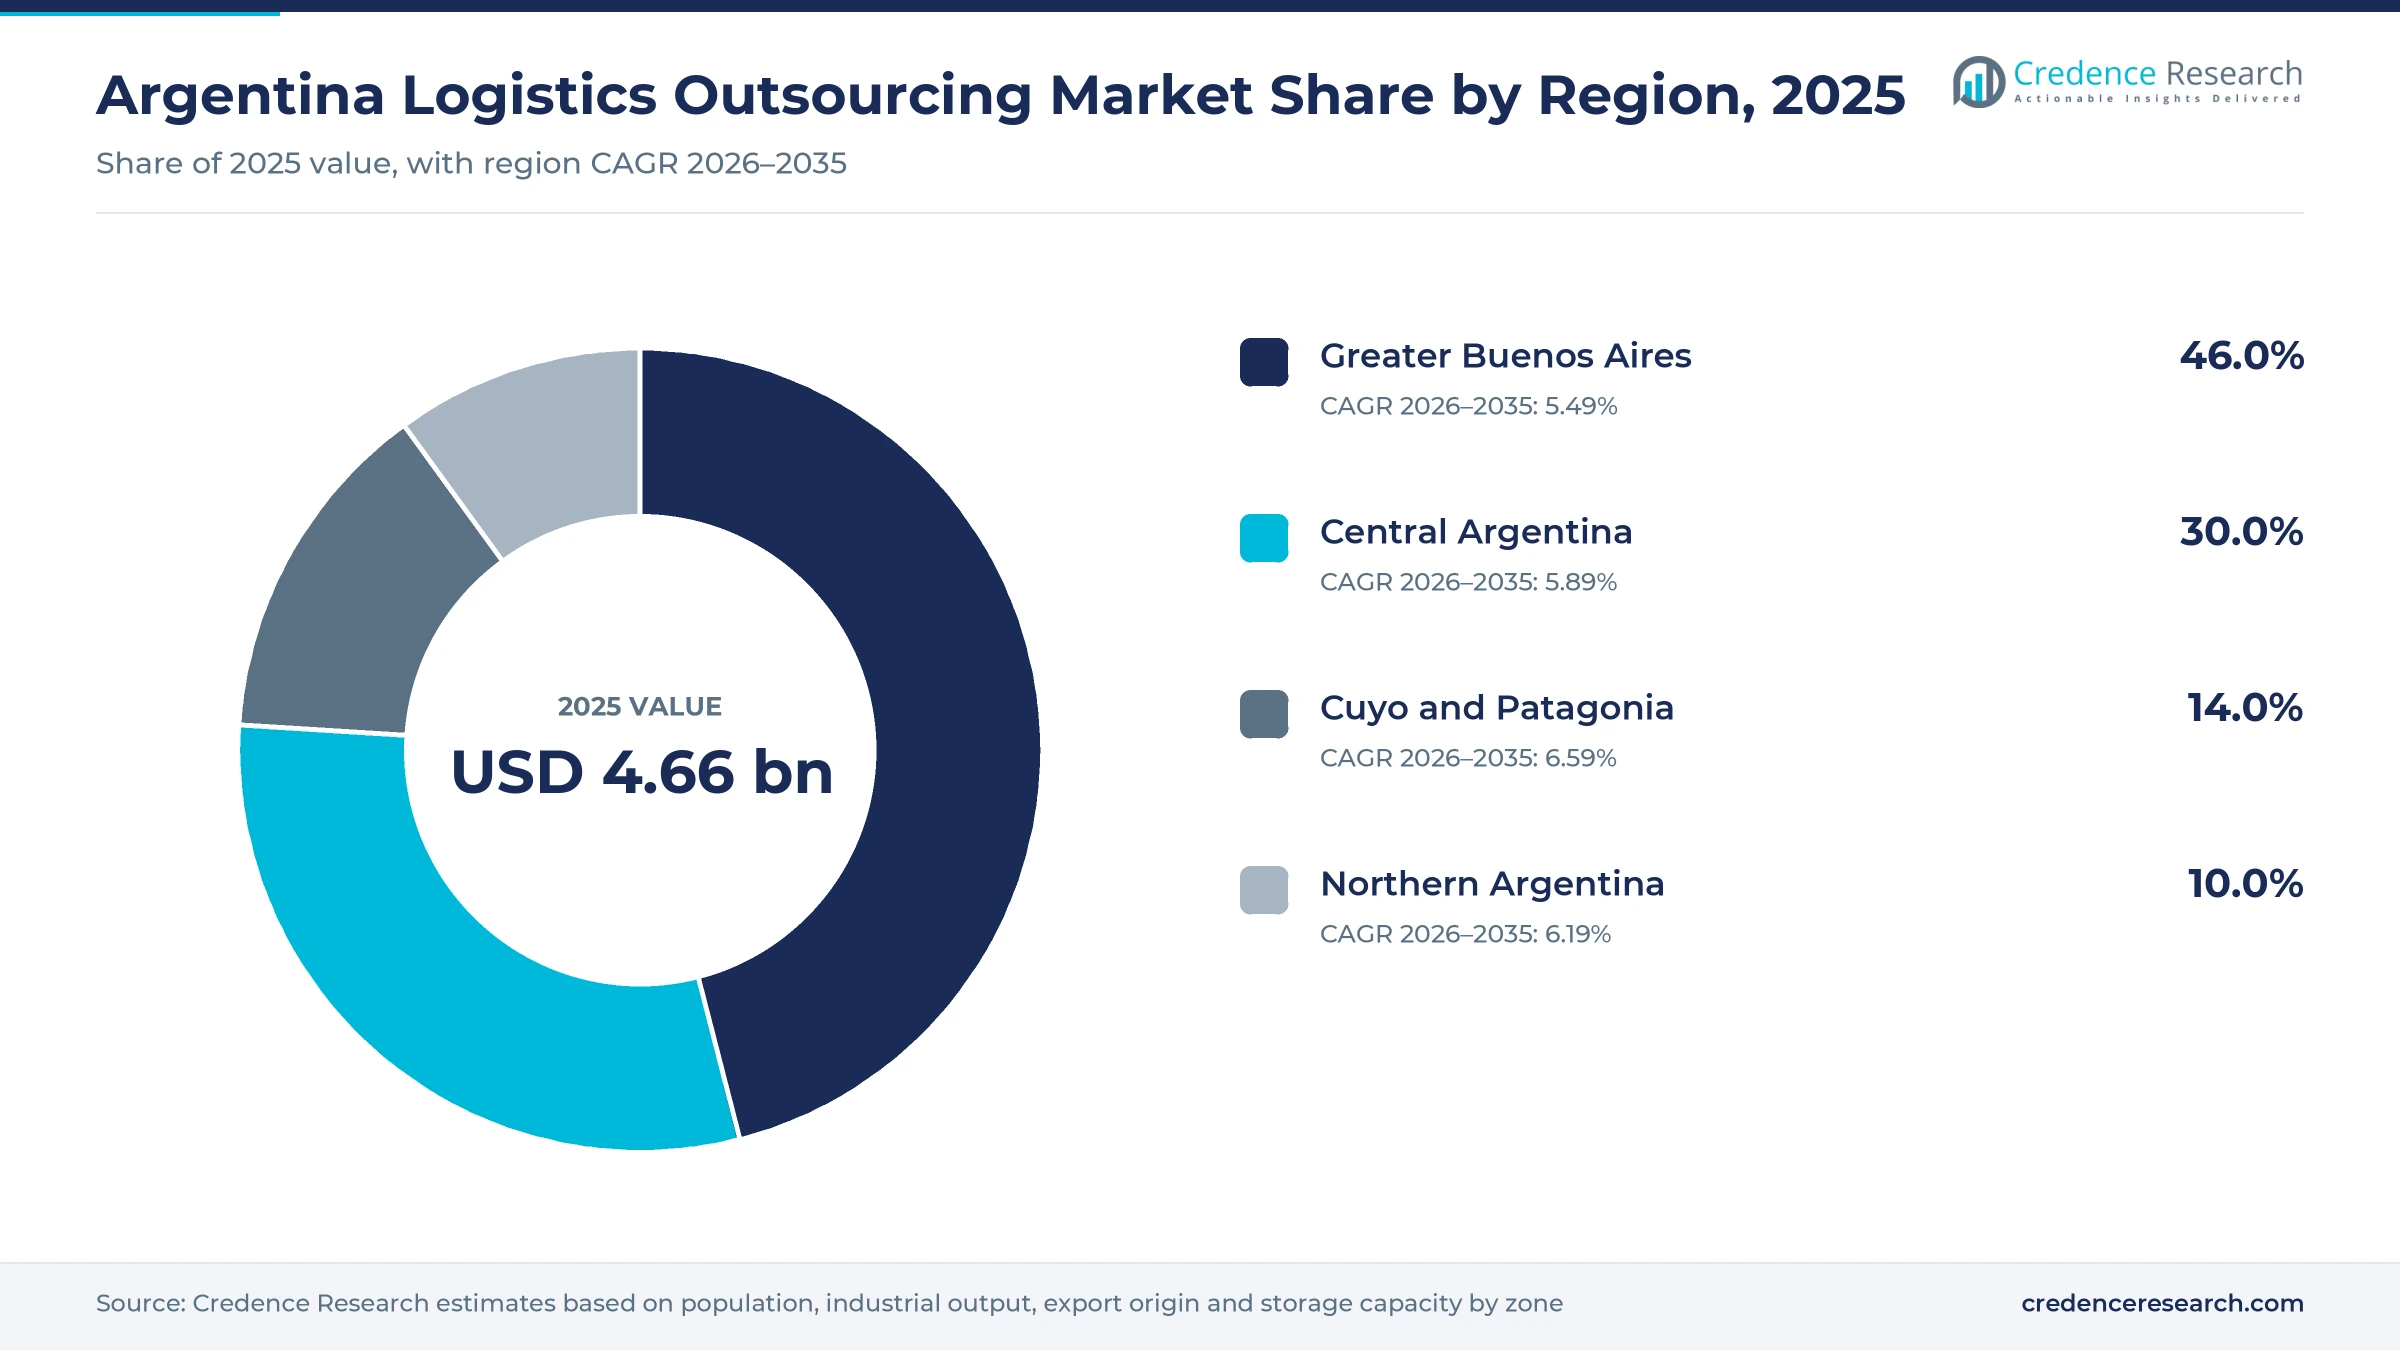
The Argentina logistics outsourcing market was valued at USD 4.66 billion in 2025 and is projected to increase from USD 4.95 billion in 2026 to USD 8.25 billion by 2035, registering a CAGR of 5.84% during 2026–2035. Demand comes from retailers, marketplaces, manufacturers, laboratories and energy and mining companies that hand transport, storage, parcel and specialist work to third-party operators instead of running their own fleets and warehouses. Greater Buenos Aires held the largest regional share, 46.0% in 2025, because the capital zone concentrates consumers, ports, the main airport and most automated storage centers. Cuyo and Patagonia is the fastest-growing region at 6.59% a year, as oil, gas and mining projects require dedicated supply lines far from the capital. The customs agency raised the courier import limit from USD 1,000 to USD 3,000 per shipment in December 2024, which opened a new stream of cross-border parcels for local operators to clear, sort and deliver.
What does the Argentine third-party operator estimate count?
The estimate measures the fees that shippers in Argentina pay to third-party operators for contract transport management, warehousing and value-added services, parcel delivery and specialist logistics. Buyers include large enterprise shippers on multi-year contracts, independent merchants who send parcels through shared networks and public and specialist buyers such as hospitals, laboratories and energy projects.
The estimate excludes freight moved by shippers with their own trucks and warehouses, port terminal charges and the value of the goods carried. The value chain runs from carriers, warehouse developers and technology providers through integrated operators and freight forwarders to the companies that buy their services across every province.
Argentina Logistics Outsourcing Market Insights
- The Argentina logistics outsourcing market was valued at USD 4.66 billion in 2025 and is projected to reach USD 8.25 billion by 2035, registering a CAGR of 5.84% during 2026–2035.
- Greater Buenos Aires held a 46.0% share of 2025 value, because the capital zone combines the main ports, the largest consumer base and most storage centers.
- Contract transport management led with a 38.0% share of 2025 value, as road freight still carries most domestic cargo for enterprise shippers.
- Online sales in Argentina moved 645 million units in 2025, up more than 28% on the year, which pushed parcel volumes through outsourced networks.
- Andreani completed a USD 30 million investment in an automated plant in General Pacheco in April 2026, with capacity to process 26,000 parcels per hour.
Transport management leads as parcel delivery grows fastest
Why does contract transport management hold the largest share?
Based on service type, the market is categorized into Contract transport management, Warehousing and value-added services, Parcel delivery and Specialist logistics. Contract transport management led with a 38.0% share of 2025 value, because consumer goods, automotive and agricultural shippers buy planned truck capacity on long contracts. Parcel delivery grows fastest at 6.70% a year, as marketplace orders and cross-border purchases raise the number of small shipments sent to homes.
How dominant are road-led services in Argentine contracts?
Based on mode of transport, the market is categorized into Road-led services, Ocean-linked services, Air-linked services and Multimodal services. Road-led services led with a 64.0% share of 2025 value, because trucks move most domestic freight between ports, plants and cities. Multimodal services grow fastest at 6.61% a year, as the freight rail tender and inland hubs make rail and road combinations more practical for bulk and mining cargo.
Which industries buy the most third-party services?
Based on end-use industry, the market is categorized into Retail and e-commerce, Manufacturing and automotive, Healthcare and pharmaceuticals, and Resources and infrastructure. Retail and e-commerce led with a 34.0% share of 2025 value, because marketplaces, supermarkets and brands outsource storage, picking and home delivery. Resources and infrastructure grows fastest at 6.44% a year, as oil, gas, lithium and copper projects need dedicated supply lines.
Why do dedicated contracts remain the main buying model?
Based on business model, the market is categorized into Dedicated contracts, Shared-user contracts and Managed logistics contracts. Dedicated contracts led with a 45.0% share of 2025 value, because large shippers want fixed fleets, sites and staff assigned to their volumes. Managed logistics contracts grow fastest at 6.33% a year, as shippers hand network design, carrier selection and software to a single lead operator.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Contract transport management | 38.0% | Parcel delivery | 6.70% |
| By Mode of Transport | Road-led services | 64.0% | Multimodal services | 6.61% |
| By End-Use Industry | Retail and e-commerce | 34.0% | Resources and infrastructure | 6.44% |
| By Business Model | Dedicated contracts | 45.0% | Managed logistics contracts | 6.33% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Parcels, cross-border trade and compliance drive contracts
How do parcel volumes add fulfillment complexity?
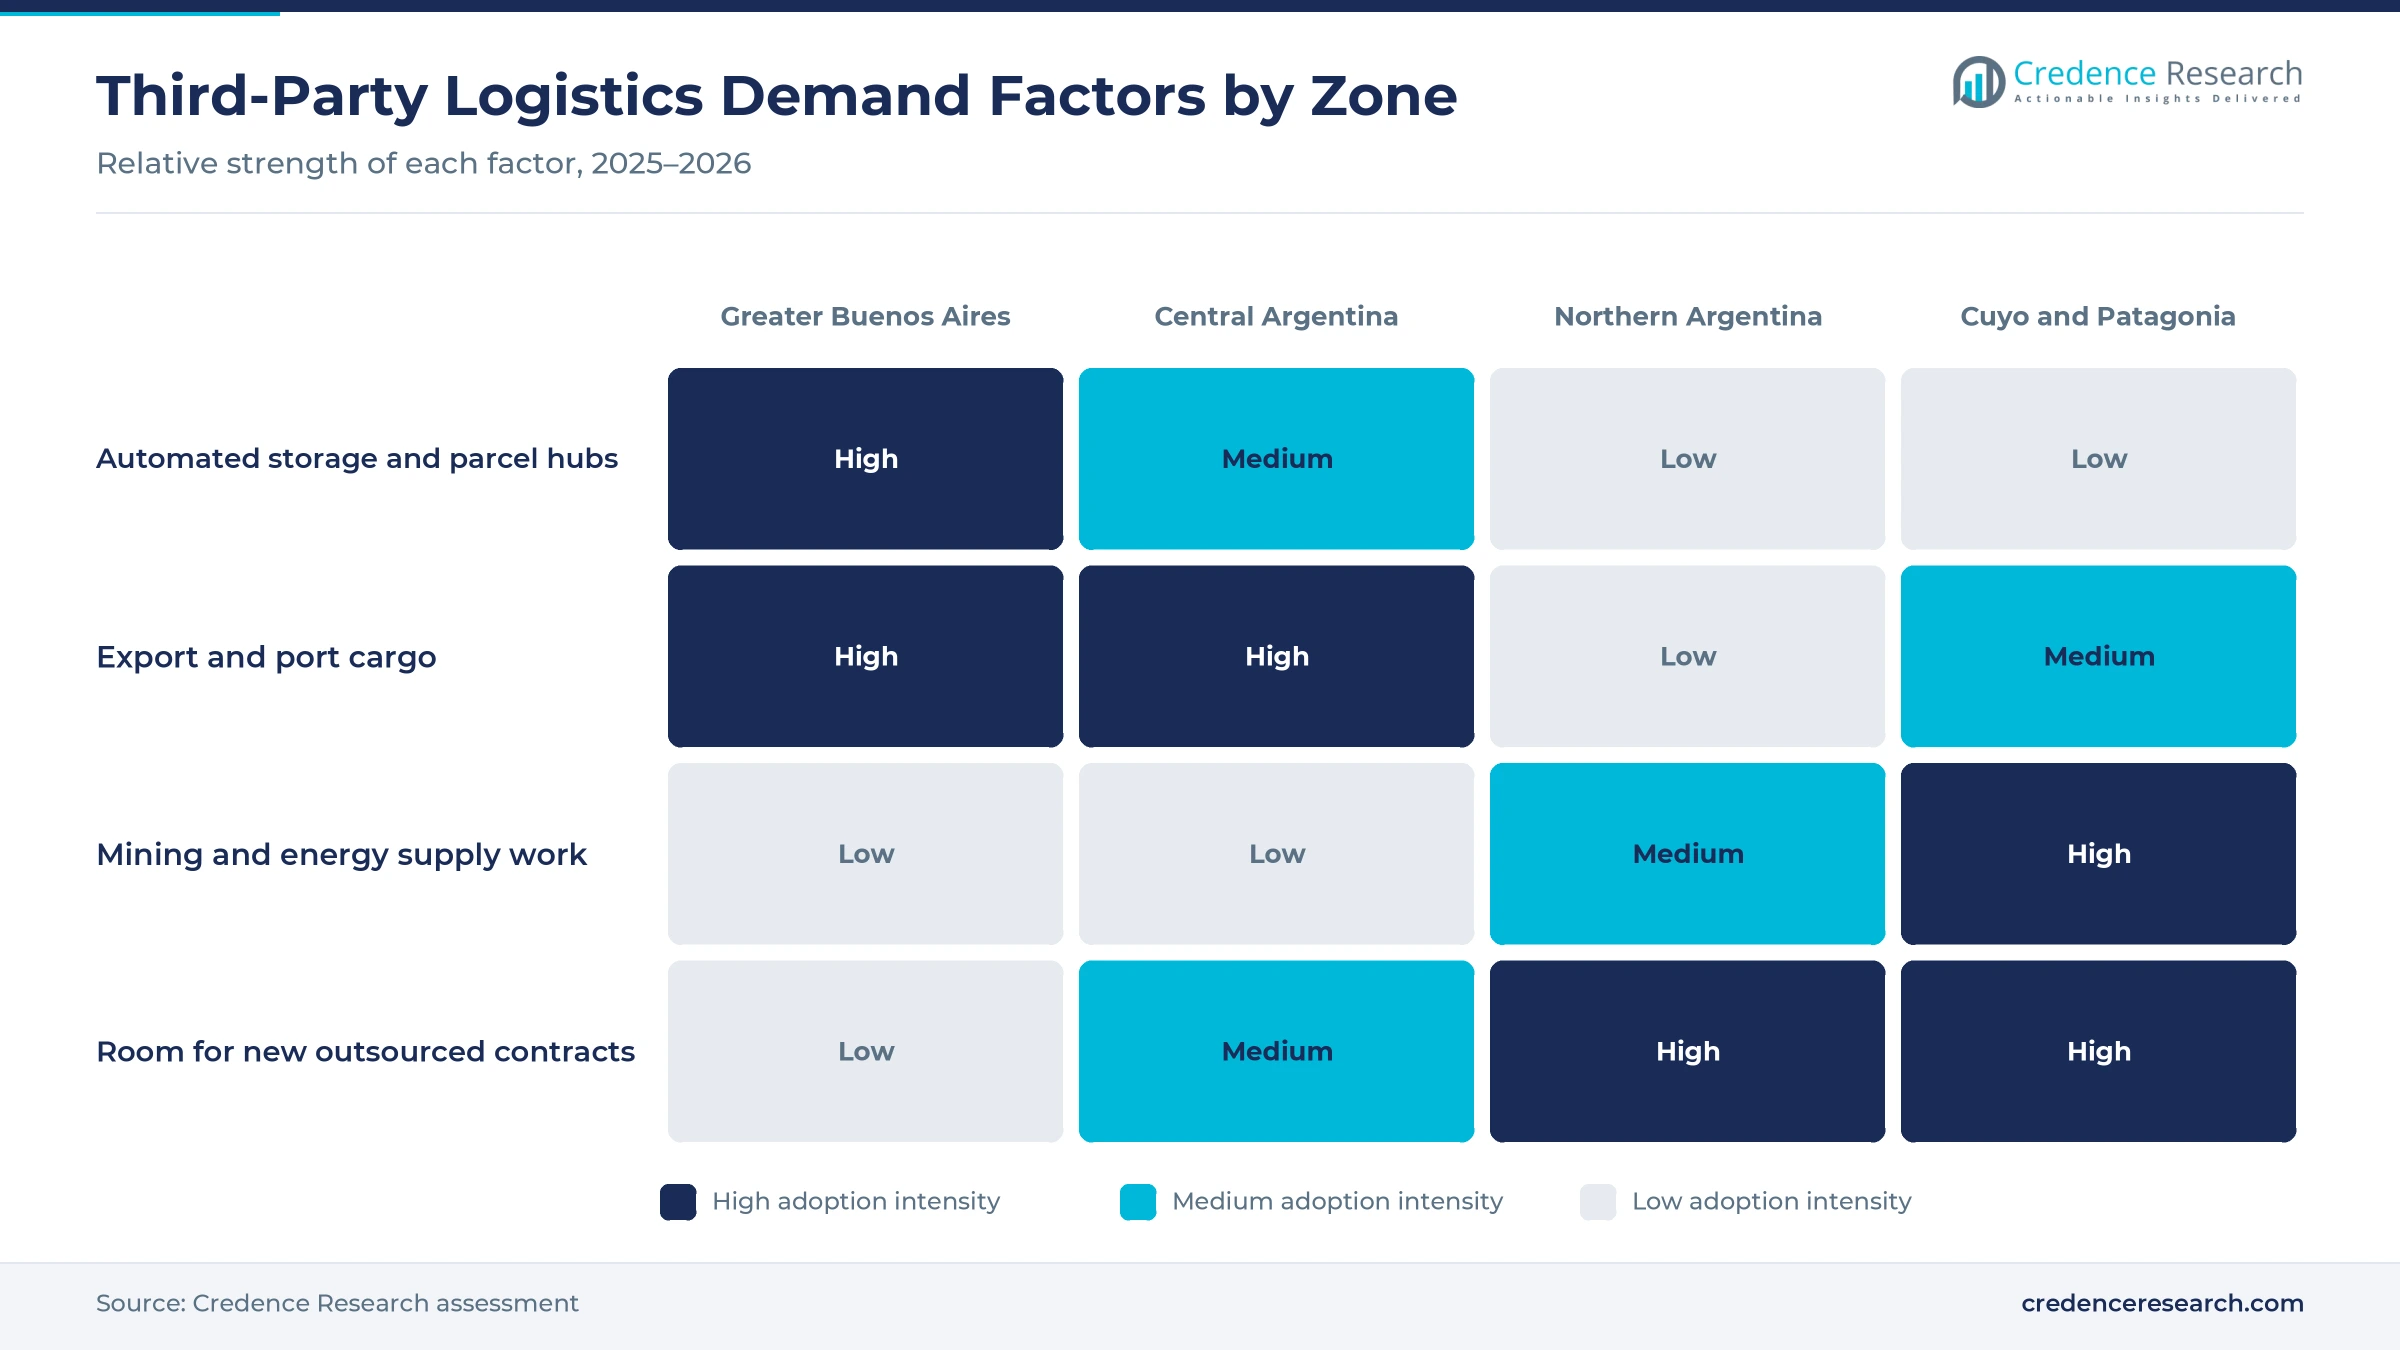
Rising parcel counts force retailers and brands to outsource picking, sorting and home delivery, because few shippers can fund automated hubs for volumes that peak on sale days. Online sales moved 645 million units in 2025, up more than 28%, while orders grew only 3%, according to the Argentine Chamber of Electronic Commerce as reported by Revista Mercado. Andreani completed a USD 30 million investment in a General Pacheco plant able to process up to 26,000 parcels per hour, according to La Nación on April 28, 2026. Mercado Libre is building a USD 115 million storage center in Escobar with Plaza Logística that can process 130,000 products per day, according to El Economista. As a result, parcel delivery grows fastest at 6.70% a year.
Why does cross-border access widen operator workloads?
Easier imports by courier and higher exports both add cargo that shippers prefer to route through specialist operators with customs and forwarding skills. The tax and customs agency ARCA raised the courier import limit from USD 1,000 to USD 3,000 per shipment under General Resolution 5608, with no duties on the first USD 400 of personal goods, according to an ARCA notice of Dec. 2, 2024. Andreani said it was processing 500,000 cross-border parcels a month in April 2026 and expected 700,000 to 800,000 by midyear. Exports reached USD 87.1 billion in 2025, up 9.3%, according to INDEC data reported by Ámbito. In turn, ocean-linked and air-linked services gain work from forwarding, customs and bonded storage.
How do compliance rules favor integrated operator networks?
Health, chemical and quality rules push shippers toward operators that already hold permits, cold rooms and audited processes, because building them in-house is slow and costly. Cruz del Sur reports cold chambers with 640 positions between 2 C and 8 C, ISO 9001 certification and compliance with ANMAT and RENPRE requirements, according to its 2025 press kit. Andreani runs 36 logistics hubs, 153 branches and 760,839 square meters of operating space in Argentina, according to its 2025 executive summary. DSV completed its EUR 14.3 billion purchase of Schenker on April 30, 2025, combining close to 160,000 employees in more than 90 countries. As shippers consolidate compliance-heavy work with fewer providers, managed logistics contracts grow fastest at 6.33% a year.
Can the freight rail tender lift multimodal demand?
Private operation of the national freight railway would give third-party operators new rail and road combinations for grain, minerals and containers moving to ports. Decree 67/2025 authorized the full privatization of Belgrano Cargas y Logística, and Ministry of Economy Resolution 1350/2026 of Aug. 20, 2026, opened the tender, according to the law firm Marval O'Farrell Mairal. The tender splits the network into three lots for the Belgrano, San Martín and Urquiza lines, with bids due on Nov. 11, 2026. Bidders may take the concession alone or the concession together with rolling stock. In turn, multimodal services grow fastest at 6.61% a year as operators design rail-linked supply chains for inland shippers.
Automation, mining cargo and inland hubs reshape networks
How is the shift toward automated hubs changing service levels?
Operators are replacing manual sorting with automated lines and data tools, which raises capacity per square meter and shortens delivery promises for shippers. Andreani inaugurated a Chinese-made sorter at a 20,000 square meter plant with room to expand by another 70,000 square meters, according to Forbes Argentina on May 4, 2026. The company handles about 5 million shipments a month and has used artificial intelligence for route planning for about two years. An Arlog survey of more than 500 professionals found that 82% of logistics companies planned to invest in 2025, and 51% would fund storage technology, robotics, automation or artificial intelligence. As a result, warehouse management systems become a standard part of tenders.
Why is mining and energy cargo rising in operator portfolios?
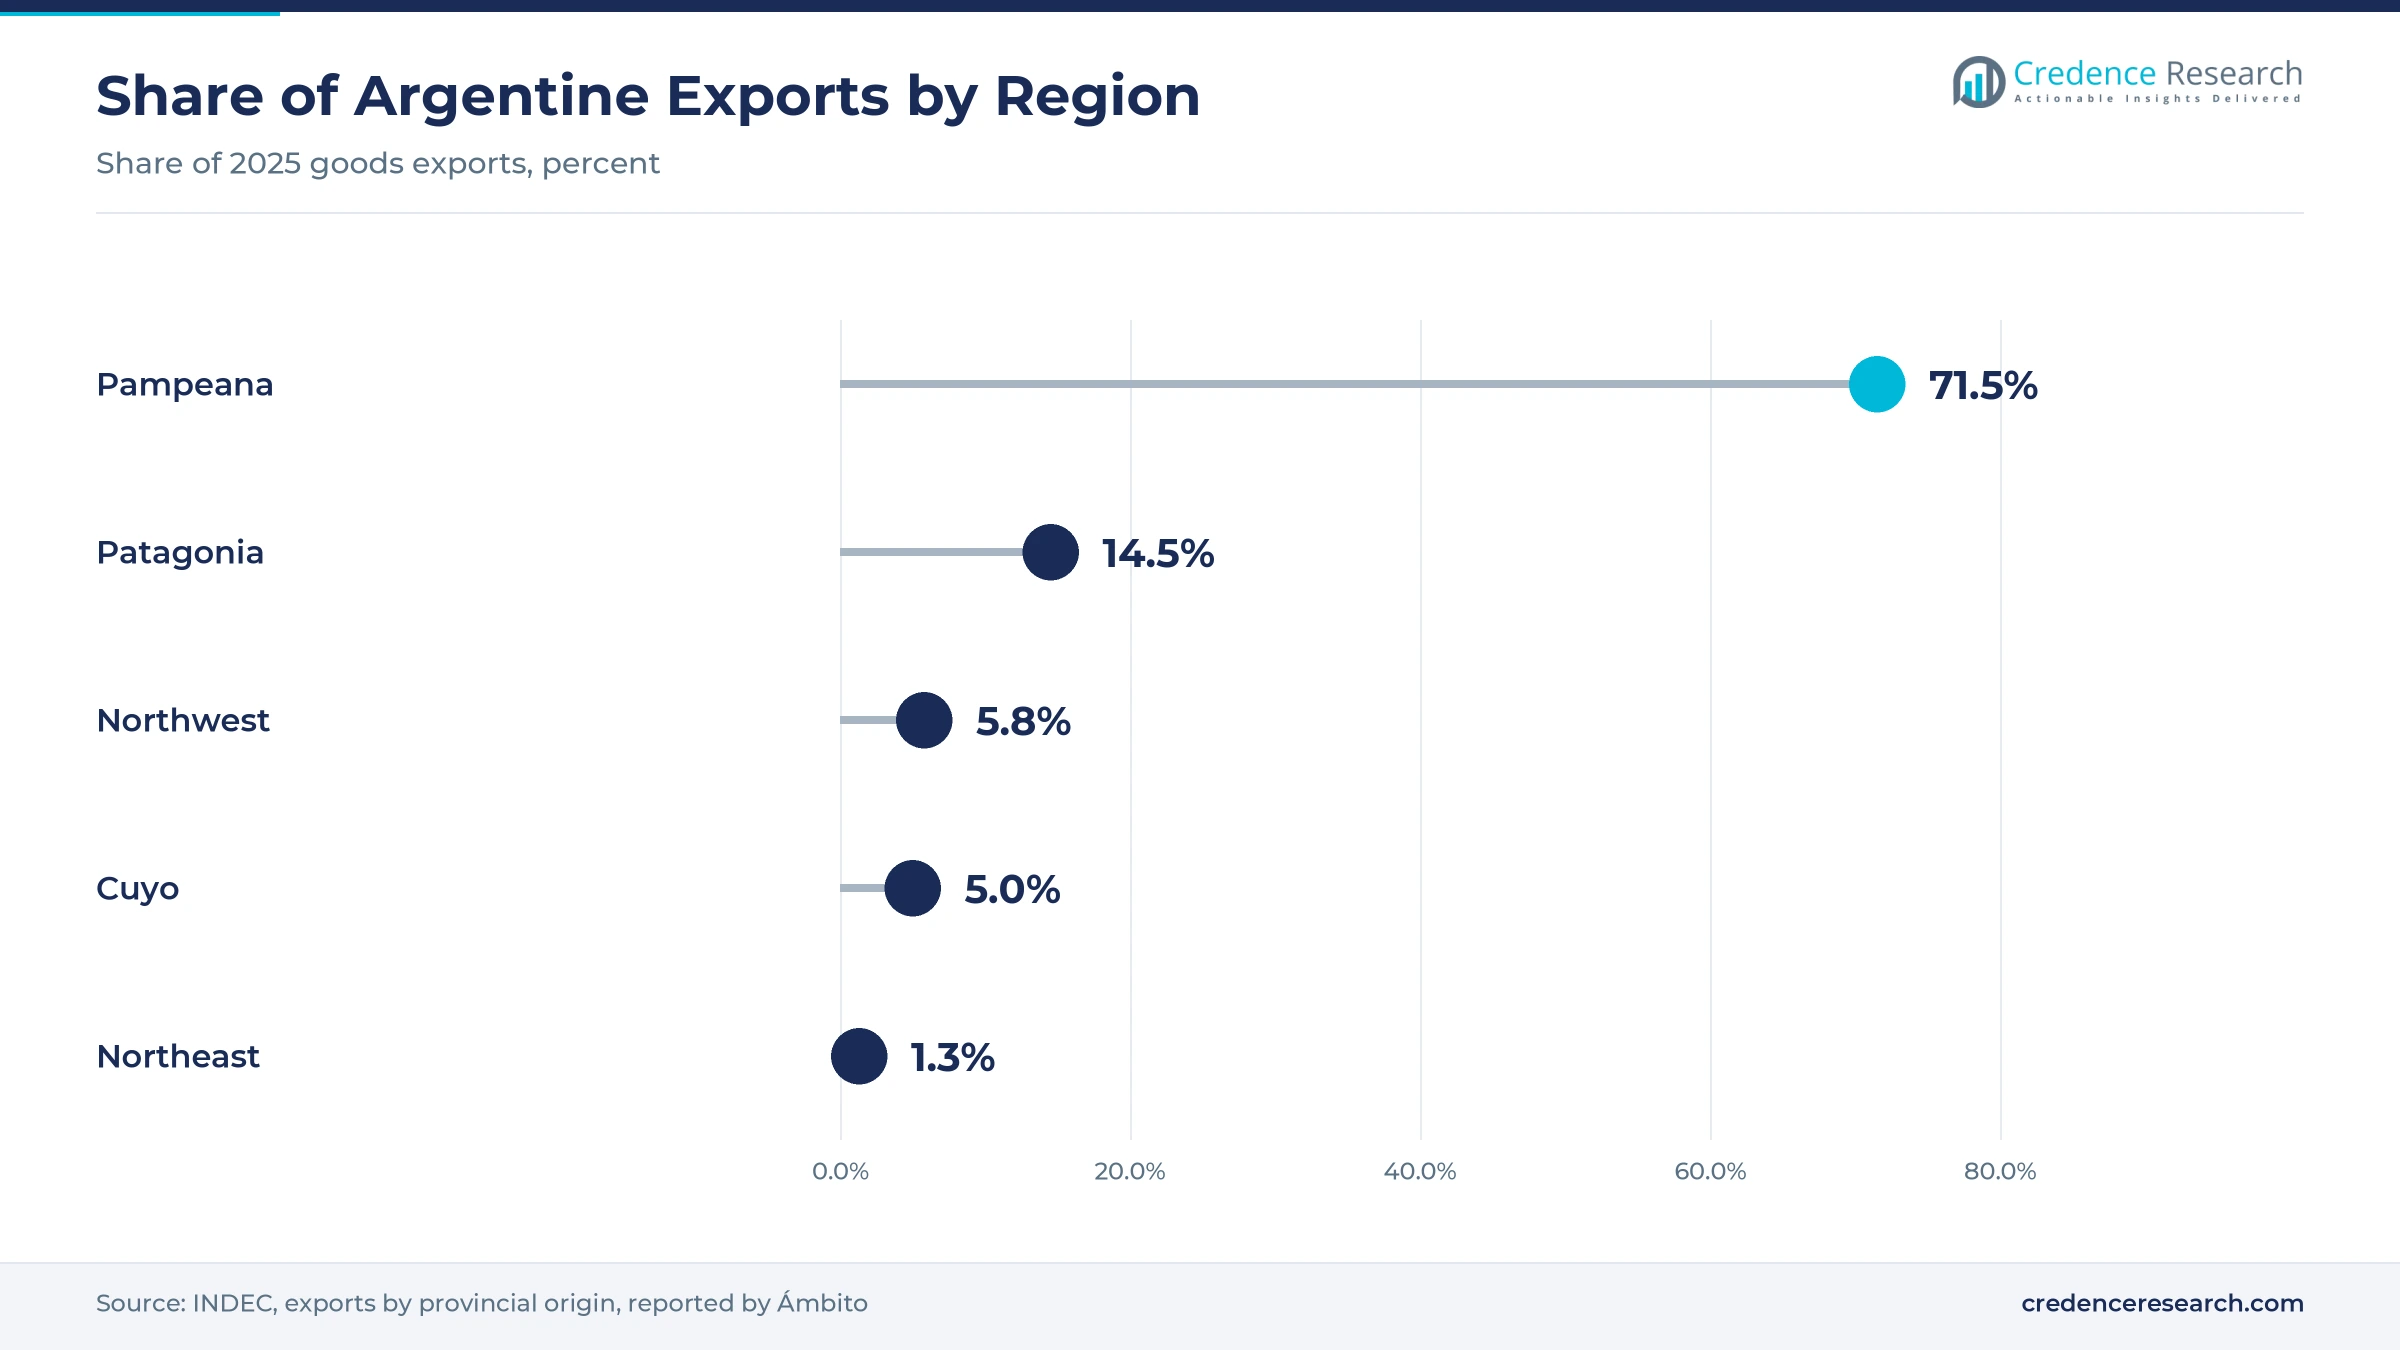
Oil, gas, lithium and gold projects in the west and south need dedicated supply chains, which brings new contract work to operators with long-distance fleets. Patagonia raised its share of national exports to 14.5% in 2025 from 13.3% in 2024, with Vaca Muerta crude and gold behind the gain, according to Ámbito. Cruz del Sur lists mining and energy among its dedicated services, with a national fleet of 800 specialized vehicles, according to its 2025 press kit. Andreani named mining, oil and gas and agribusiness among its fastest-growing segments for 2026. In turn, resources and infrastructure grows fastest among end-use industries at 6.44% a year.
Can inland storage centers open new contract work?
New storage capacity outside the capital creates an opening for operators to run regional distribution that was served from Buenos Aires warehouses. Mercado Libre chose Estación Juárez Celman in Córdoba for a USD 91 million, 60,000 square meter center able to hold up to 6 million products, according to El Economista on Aug. 10, 2026. The site, due by the end of 2027, will supply the central, northwest and northeast regions and create 2,000 direct jobs. DHL Express opened branches in Neuquén and Bahía Blanca in January 2025, reaching 28 branches nationwide, according to Revista Mercado. As a result, Central Argentina grows at 5.89% a year.
Is there room for operators in cross-border fulfillment hubs?
Argentine buyers ordering from foreign platforms create an opening for operators that can consolidate goods abroad and clear them quickly at home. Andreani plans to open a hub in Miami before the end of 2026 and an office in China in 2027, according to La Nación. Its courier division, created about three years earlier, grows at rates of 30% and above, according to Oscar Andreani. Customs processing for incoming products takes 15 to 18 days, according to Forbes Argentina, which leaves room for operators that cut clearance times. In turn, last-mile delivery networks gain cross-border parcels to handle.
Weak volumes, port decline and costs test operators
How do flat shipment volumes squeeze operator margins?
Parcel counts stopped growing at Andreani, the largest operator, in 2025, which leaves new automated capacity underused and puts pressure on prices. Andreani processed 54.6 million shipments in Argentina in 2025, slightly below 55.1 million in 2024, according to its executive summary. As a result, operators compete harder for the same shippers on rates and payment terms. Operators that balance domestic contracts with cross-border and mining work are better placed to fill their sites.
Why do falling port volumes limit forwarding revenue?
Container traffic through Argentine ports has fallen well below earlier peaks, which reduces the volume available to forwarders, customs brokers and bonded warehouses. Port traffic reached 1.47 million TEU in 2024 against 2.18 million TEU in 2018, according to the World Bank. In turn, ocean-linked services depend on a recovery in imports of inputs and capital goods. Operators reduce exposure by adding air, courier and inland services.
How do infrastructure gaps raise service costs?
Long distances and uneven roads raise transit times and fuel costs, especially for deliveries to the north and to Patagonia. Infrastructure was the top pending issue for 81% of professionals in an Arlog survey, ahead of paperwork and technology adoption, according to La Nación on Nov. 28, 2024. As a result, shippers outside the capital zone pay more per shipment and wait longer for deliveries. Rail concessions and regional hubs could narrow this gap after 2027.
Why does price instability complicate long contracts?
Inflation fell sharply in 2025 yet remained at 31% for the year, according to the Argentine Chamber of Electronic Commerce, which still forces operators to renegotiate rates often. Wages, fuel and tolls move at different speeds, so fixed-price dedicated contracts carry margin risk for both sides. In turn, operators add indexation clauses and shorter review cycles to keep contracts viable for shippers and providers alike.
Greater Buenos Aires leads while the south grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Greater Buenos Aires | 2.15 | 46.0% | 5.49% |
| Central Argentina | 1.40 | 30.0% | 5.89% |
| Cuyo and Patagonia | 0.65 | 14.0% | 6.59% |
| Northern Argentina | 0.47 | 10.0% | 6.19% |
Ports and automated hubs keep Greater Buenos Aires ahead
Greater Buenos Aires held a 46.0% share of 2025 value and grows at 5.49% a year. The zone hosts the port of Buenos Aires, Ezeiza airport and most automated storage centers, including Andreani's plant in General Pacheco and the planned Mercado Libre site in Escobar. Consumer goods companies and marketplaces serve the whole country from this belt. As a result, the capital zone keeps the largest share while its growth stays below the national rate.
Grain, autos and new hubs anchor Central Argentina
Central Argentina held a 30.0% share of 2025 value and grows at 5.89% a year. The zone covers Córdoba, Santa Fe, Entre Ríos, La Pampa and the rest of Buenos Aires province, home to the Rosario grain ports and automotive plants. CEVA Logistics runs inbound parts, warehousing and line feeding for the Volkswagen transmission plant in Córdoba under a contract signed in July 2022. In turn, the Córdoba storage center will add regional distribution work from 2027.
Why do Cuyo and Patagonia grow fastest?
Cuyo and Patagonia held a 14.0% share of 2025 value and grow fastest at 6.59% a year. Vaca Muerta oil and gas, gold mining and wine exports create steady demand for dedicated fleets, project logistics and bonded storage. Patagonia supplied 14.5% of national exports in 2025, up from 13.3% a year earlier. As a result, operators open branches in Neuquén and invest in long-distance supply lines to the oil and mining fields.
Lithium and inland centers lift Northern Argentina
Northern Argentina held a 10.0% share of 2025 value and grows at 6.19% a year. The northwest supplied 5.8% of national exports in 2025 and the northeast 1.3%, a small base for outsourced logistics. Long distances to ports have kept most outsourced work small and seasonal. In turn, the planned Córdoba center and rail concessions should bring faster regional service after 2027.
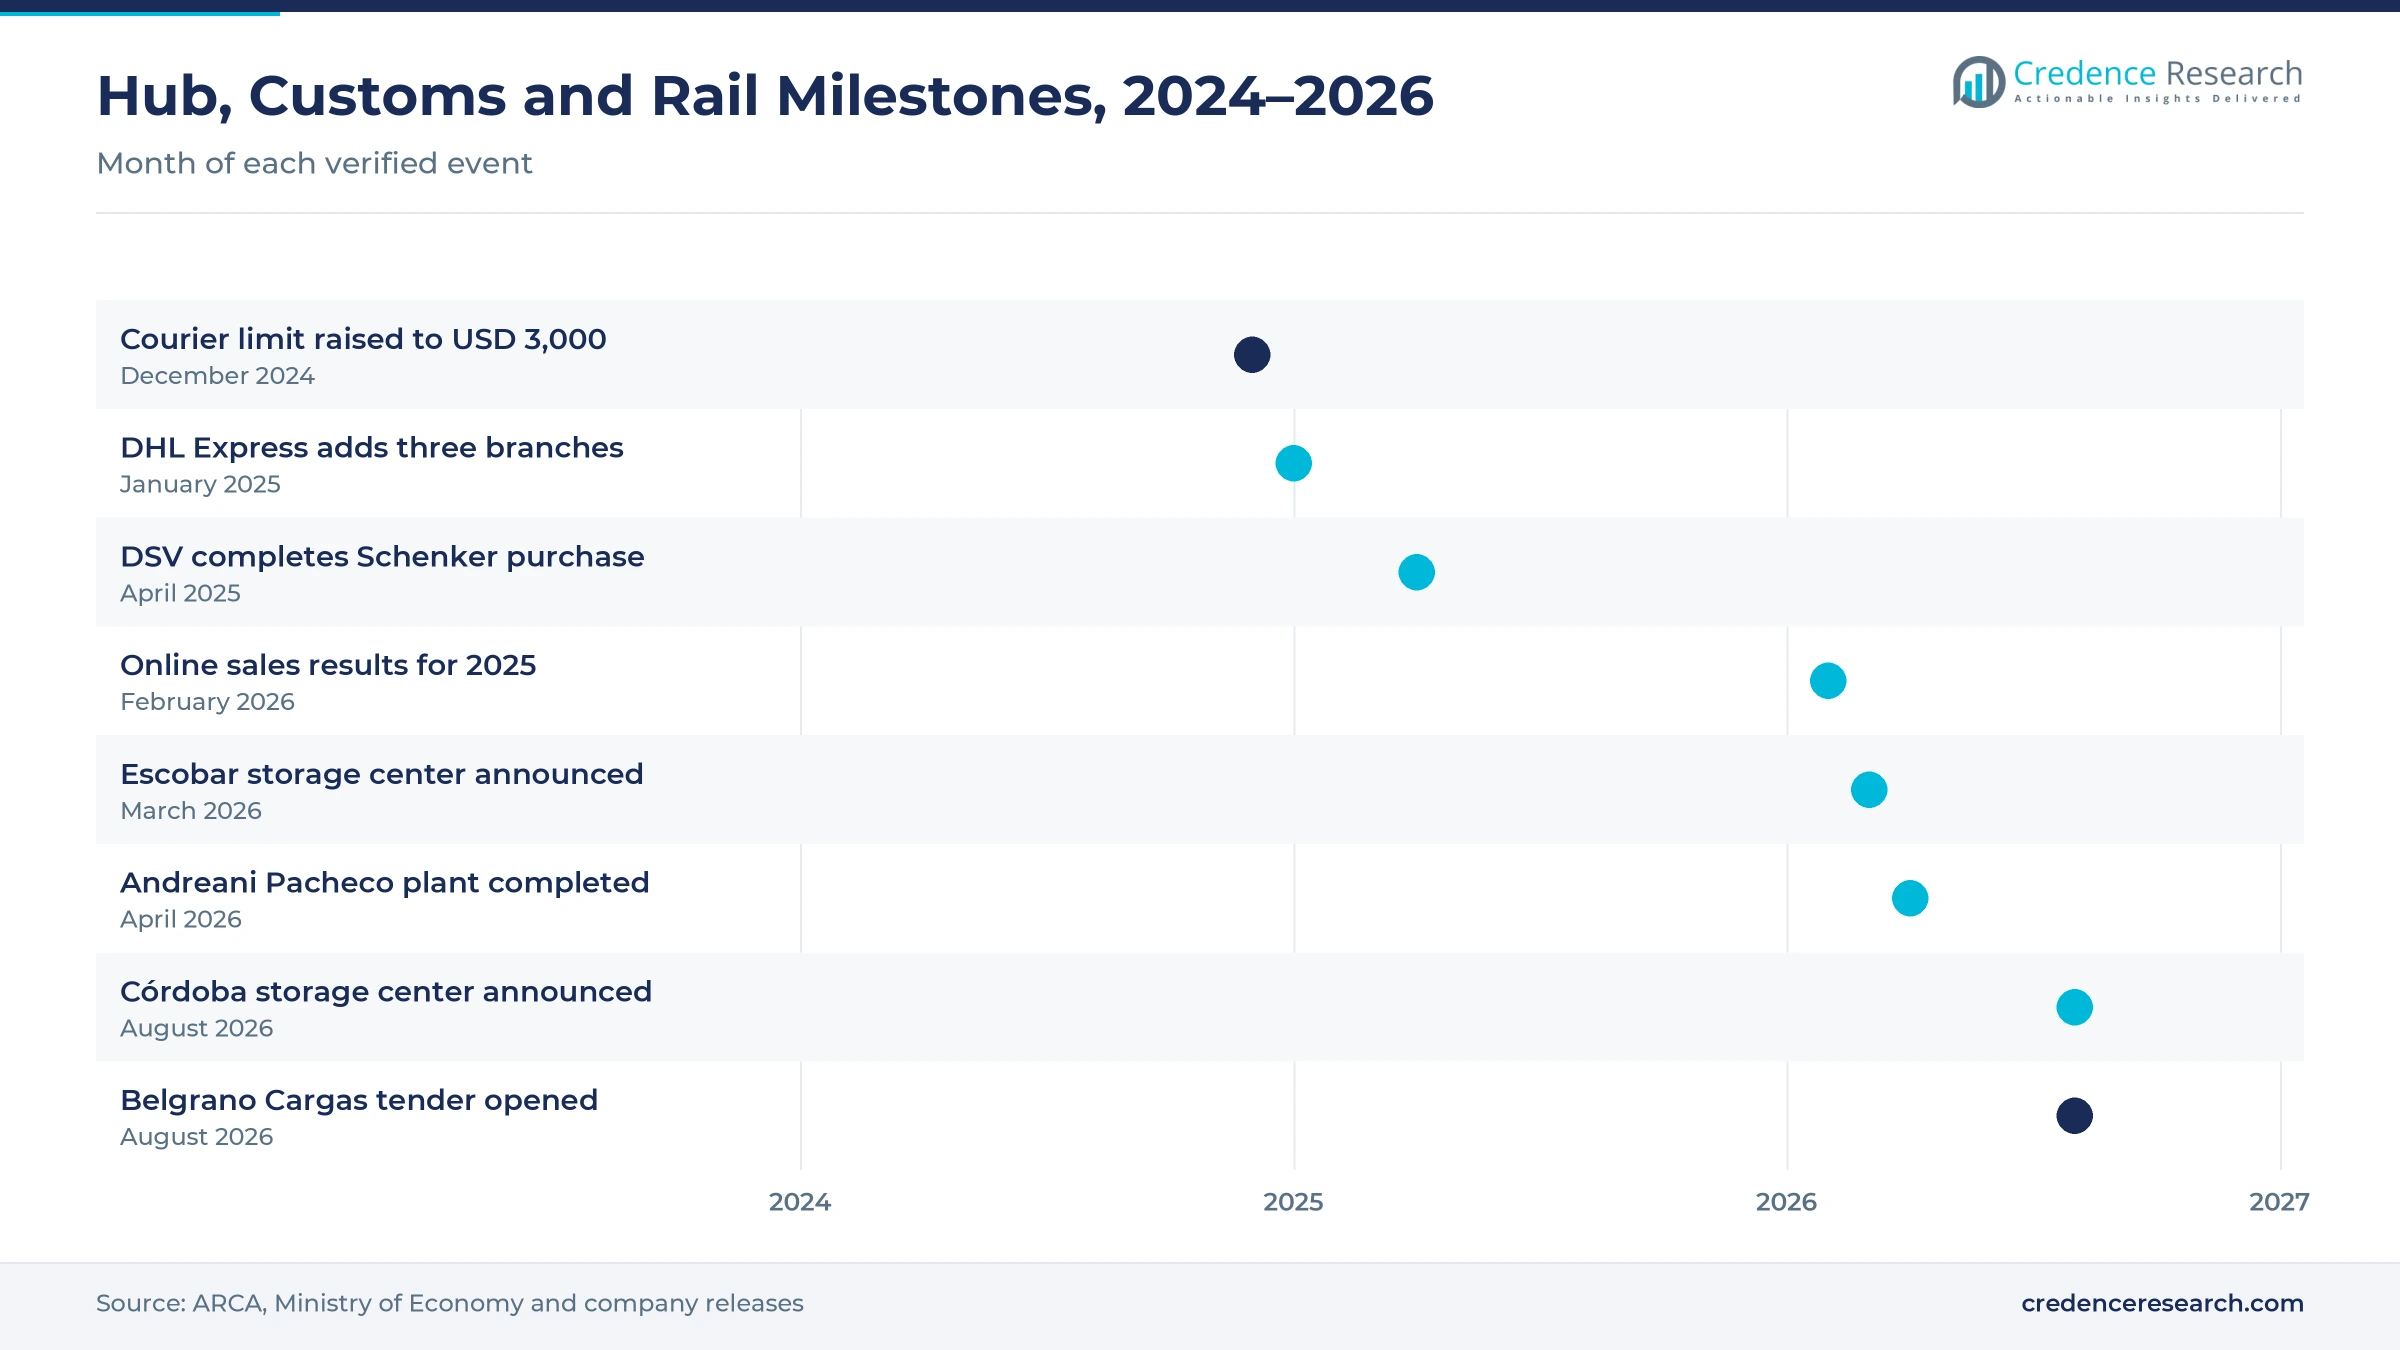
Hub, customs and rail milestones, 2024–2026
| Development | Status and market relevance |
|---|---|
| In December 2024, ARCA raised the courier import limit to USD 3,000 per shipment under General Resolution 5608. | Adds cross-border parcels for local operators |
| In April 2025, DSV completed its purchase of Schenker, combining close to 160,000 employees in more than 90 countries. | Merges two global forwarders active in Argentina |
| In March 2026, Mercado Libre announced a USD 115 million storage center in Escobar built by Plaza Logística. | Adds capacity in the capital zone |
| In April 2026, Andreani completed a USD 30 million automated plant in General Pacheco with capacity for 26,000 parcels per hour. | Raises parcel sorting capacity |
| In August 2026, the Ministry of Economy opened the tender to privatize the Belgrano Cargas freight railway in three lots. | Opens multimodal options for inland shippers |
Sorters, routing software and cold rooms set service levels
- Automated sorters scan and route parcels at high speed, which lets operators absorb sale-day peaks without extra staff.
- Routing and planning software uses order data and artificial intelligence to build delivery routes, which cuts kilometers driven and raises on-time rates for freight forwarders and parcel networks alike.
- Cold rooms and monitored storage keep medicines and biological products between 2 C and 8 C, which lets operators meet ANMAT requirements for laboratories and hospitals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Andreani leads as global forwarders and local fleets compete
Competition splits between national operators with dense domestic networks and global groups that link Argentina to foreign trade. Andreani runs 36 hubs and 153 branches and is adding cross-border hubs abroad, while Cruz del Sur connects more than 5,200 localities with 800 vehicles and 80 branches. TASA Logística bought the domestic contract logistics operations of Kuehne+Nagel in October 2020, adding three storage centers and 230 employees, while Kuehne+Nagel kept its focus on foreign trade. DSV now combines its own network with Schenker, and CEVA Logistics serves automotive clients in Córdoba. GEODIS offers air and sea freight, customs clearance and distribution from Buenos Aires. Providers compete on coverage, automation, compliance credentials and the ability to manage several modes under one contract.
Which companies shape Argentine third-party services?
| Company | Type | Role in the market |
|---|---|---|
| Grupo Logístico Andreani | National integrated operator | Runs 36 hubs, 153 branches and an automated plant in General Pacheco |
| Cruz del Sur Logística | National cargo and parcel network | Connects more than 5,200 localities with 800 vehicles and cold chambers |
| TASA Logística | Contract logistics provider | Acquired the domestic contract logistics business of Kuehne+Nagel in 2020 |
| Kuehne+Nagel Argentina | Freight forwarder | Focuses on sea and air foreign trade services |
| DSV and Schenker Argentina | Global forwarder and contract operator | Combined after the April 2025 acquisition of Schenker |
| CEVA Logistics Argentina | Contract logistics provider | Manages inbound parts and line feeding for Volkswagen in Córdoba |
| DHL Supply Chain and Global Forwarding Argentina | Global logistics group | Contract logistics and air and sea forwarding under DHL Group, and sister unit DHL Express reached 28 branches in January 2025 |
| GEODIS Argentina | Freight forwarder | Offers air and sea freight, customs clearance and distribution from Buenos Aires |
Credence Research view on Argentine third-party operators
Credence Research's view is that Argentine shippers will keep moving work to third-party operators, because automated parcel hubs, customs skills and compliance credentials are expensive to build in-house. Parcel delivery and resources logistics will grow fastest, while dedicated road contracts keep the largest share of spending. Operators that combine domestic networks with cross-border hubs and mining supply lines will gain share, and rail concessions could open multimodal contracts after 2027. Price stability and a recovery in imports are the main conditions for the Argentina logistics outsourcing opportunity to reach its full potential through 2035.
How the Argentine third-party operator estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines official trade and export statistics, World Bank port traffic and output data, online sales data from the national electronic commerce chamber, customs rules and company announcements. Segment splits and zone shares and growth rates are Credence Research estimates built from population, industrial output, export origin and storage capacity by zone. Sources used are official statistics, regulations, trade body releases, news reports and company releases, and Credence Research conducted no interviews or surveys of its own for this report.
Parcel, mining and multimodal work lead growth to 2035
Spending is expected to reach USD 8.25 billion by 2035, a 5.84% CAGR during 2026–2035, as more shippers hand transport, storage and parcel work to specialist operators. Growth should come from parcel delivery, resources and infrastructure clients, managed contracts and the western and southern provinces. A recovery in imports and steadier prices would support contract renewals, while weak consumption or renewed inflation would slow new tenders. Investment in automation, inland hubs and rail links is expected to decide which operators gain share by 2035.
Frequently Asked Questions
How big is the Argentina logistics outsourcing market?
Which service type leads Argentine third-party logistics?
Which region leads the Argentine market?
How did the courier reform affect operators?
How are operators investing in automation?
Why are resources and infrastructure clients growing fastest?
Which companies are active in the Argentine market?
What are the main challenges for operators in Argentina?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Contract transport management
- 1.2.2 Warehousing and value-added services
- 1.2.3 Parcel delivery
- 1.2.4 Specialist logistics
- 1.3 By Mode of Transport
- 1.3.1 Road-led services
- 1.3.2 Ocean-linked services
- 1.3.3 Air-linked services
- 1.3.4 Multimodal services
- 1.4 By End-Use Industry
- 1.4.1 Retail and e-commerce
- 1.4.2 Manufacturing and automotive
- 1.4.3 Healthcare and pharmaceuticals
- 1.4.4 Resources and infrastructure
- 1.5 By Business Model
- 1.5.1 Dedicated contracts
- 1.5.2 Shared-user contracts
- 1.5.3 Managed logistics contracts
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4.66 billion → 2035: USD 8.25 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Argentina Logistics Outsourcing Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Argentina Logistics Outsourcing Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Argentina Logistics Outsourcing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Argentina Logistics Outsourcing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Argentina Logistics Outsourcing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Argentina Logistics Outsourcing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Argentina Logistics Outsourcing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Argentina Logistics Outsourcing Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4.66 billion → 2035: USD 8.25 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Argentina Logistics Outsourcing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Contract transport management
- 12.3.6.2 Warehousing and value-added services
- 12.3.6.3 Parcel delivery
- 12.3.6.4 Specialist logistics
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Mode of Transport - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Road-led services
- 12.4.6.2 Ocean-linked services
- 12.4.6.3 Air-linked services
- 12.4.6.4 Multimodal services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Retail and e-commerce
- 12.5.6.2 Manufacturing and automotive
- 12.5.6.3 Healthcare and pharmaceuticals
- 12.5.6.4 Resources and infrastructure
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Business Model - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Dedicated contracts
- 12.6.6.2 Shared-user contracts
- 12.6.6.3 Managed logistics contracts
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Argentina Logistics Outsourcing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Argentina Logistics Outsourcing Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Argentina Logistics Outsourcing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Argentina Logistics Outsourcing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Grupo Logístico Andreani
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 TASA Logística
- 18.4 Cruz del Sur Logística
- 18.5 DHL Supply Chain and Global Forwarding Argentina
- 18.6 Kuehne+Nagel Argentina
- 18.7 OCASA
- 18.8 DSV and Schenker Argentina
- 18.9 CEVA Logistics Argentina
- 18.10 GEODIS Argentina
- 18.11 Exologística
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

