
Employers fund AI, cloud and cyber skills across Australia
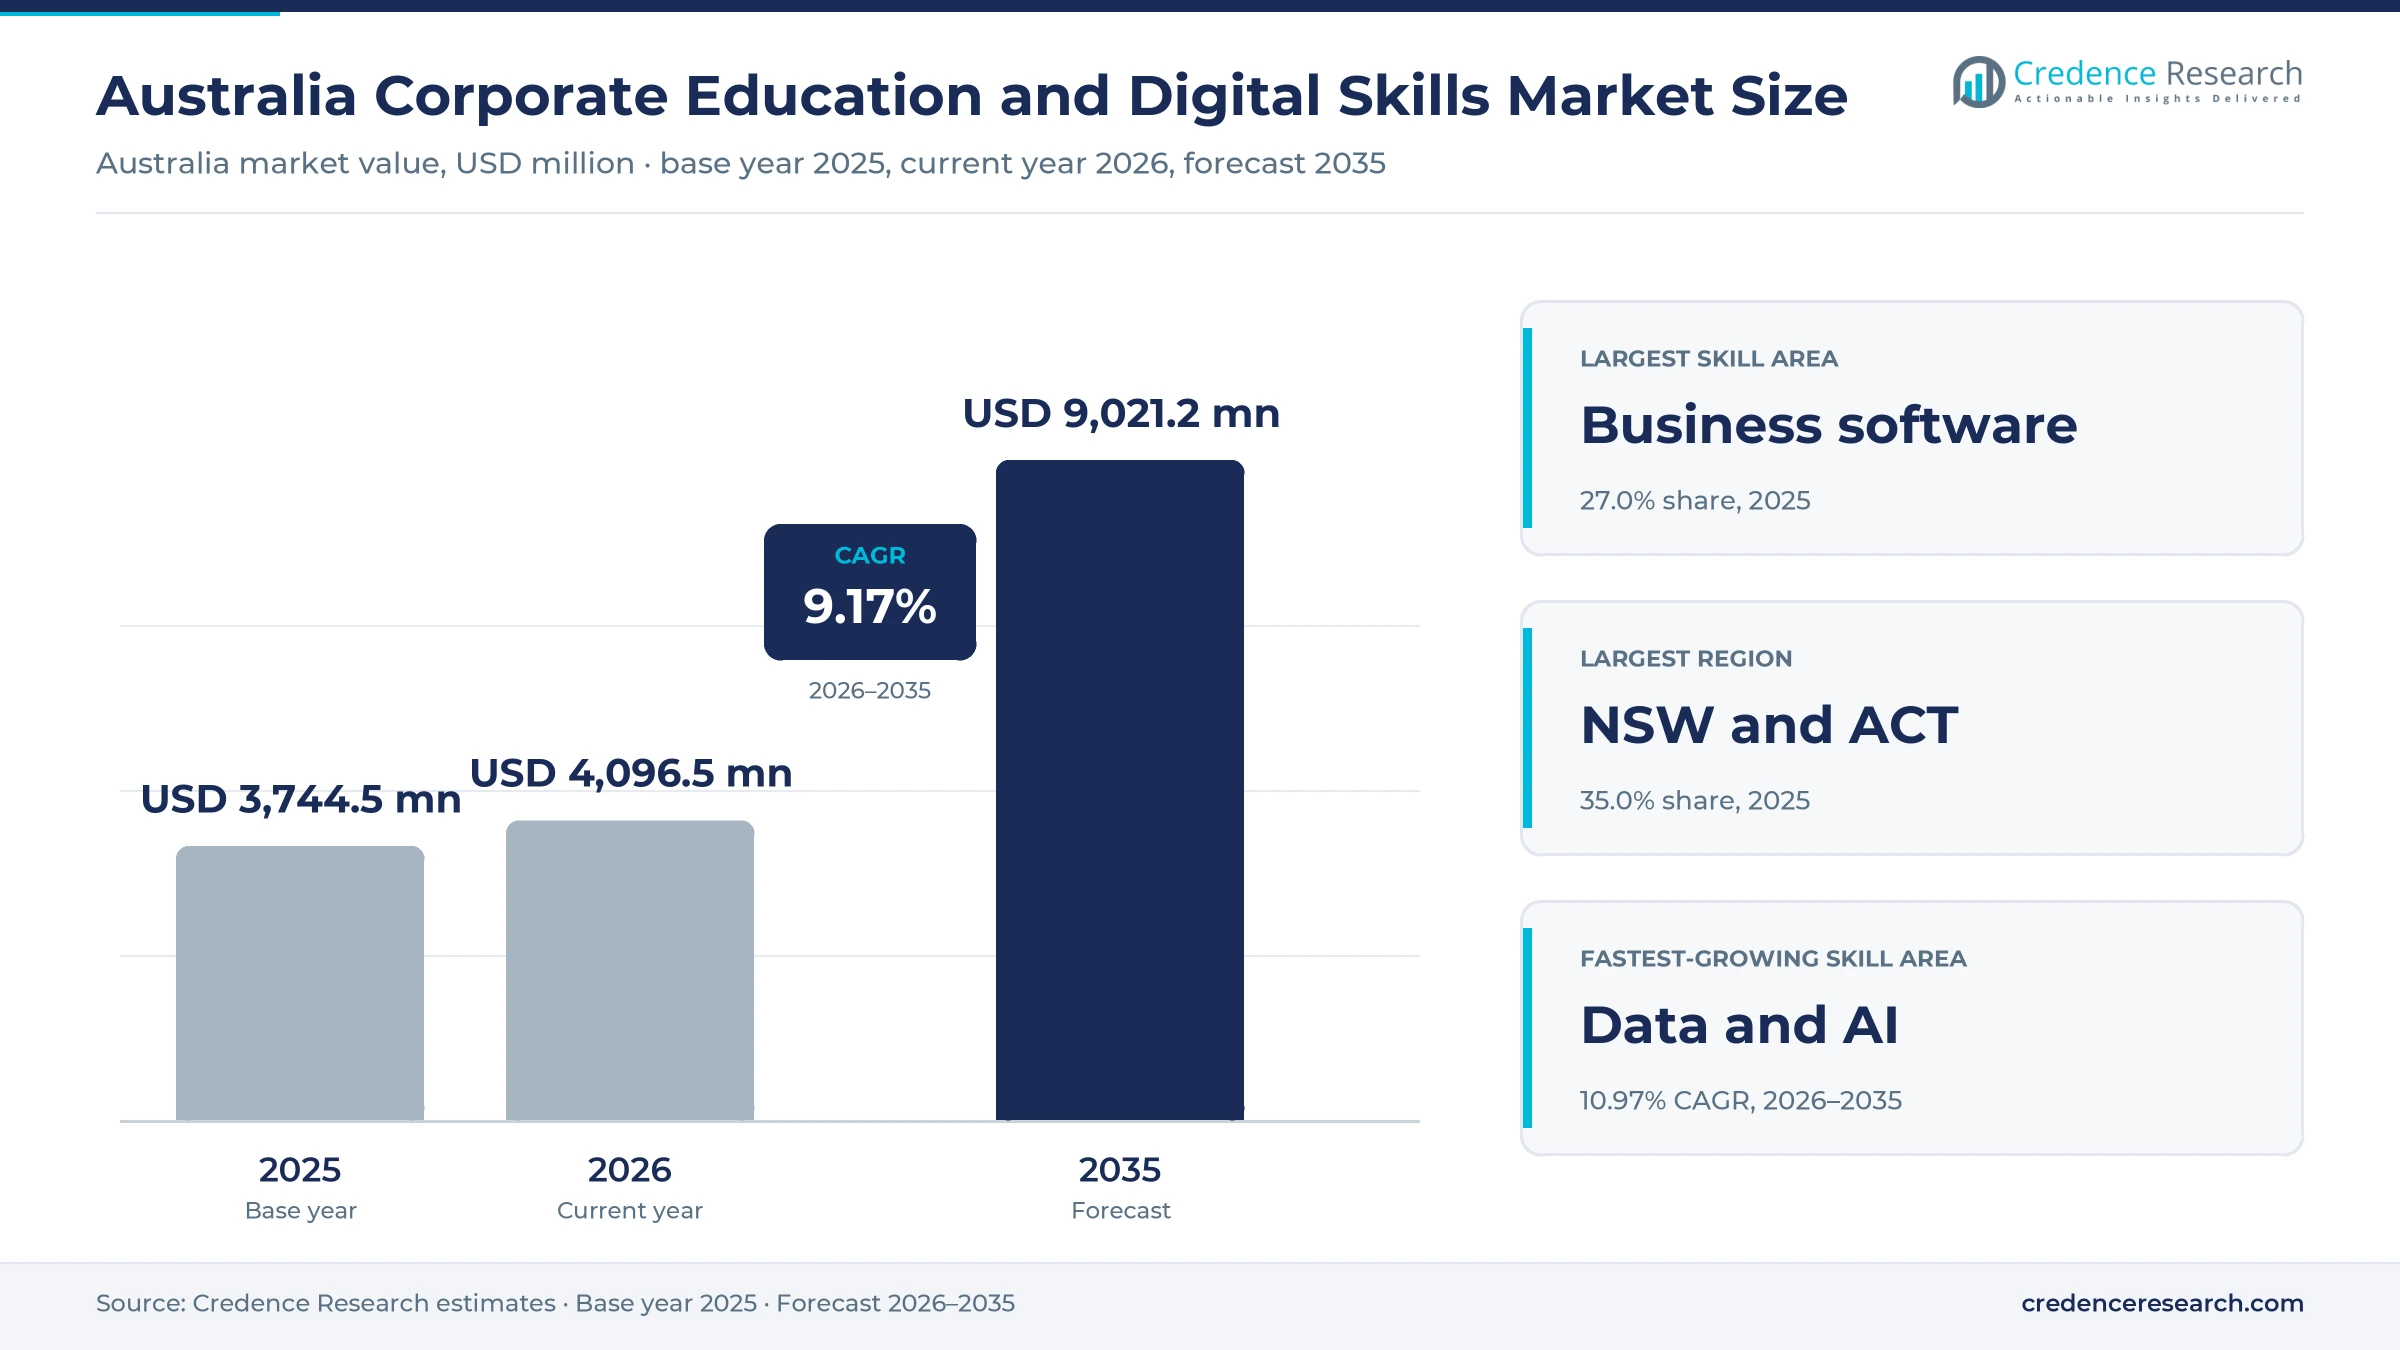
The Australia corporate education and digital skills market was valued at USD 3.74 billion in 2025 and is projected to increase from USD 4.10 billion in 2026 to USD 9.02 billion by 2035, registering a CAGR of 9.17% during 2026–2035. Demand comes from employers that must teach staff to use generative AI, run cloud platforms and defend networks, while technical roles spread into banking, retail, mining and government. New South Wales and the Australian Capital Territory held the largest regional share, 35.0% in 2025, because Sydney and Canberra concentrate corporate head offices, federal agencies and national IT training campuses. Queensland is the fastest-growing region at 9.58% a year, as its workforce expands and learning technology firms such as Go1 grow from Brisbane. The National AI Plan released in December 2025 and subsidized AI microskills courses have also pushed AI literacy onto the training agendas of large and small employers.
Which employer-funded learning does the estimate count?
The estimate measures what Australian employers and public agencies spend on structured education and digital skills training for their staff. It covers vendor certification courses, instructor-led and virtual classes, self-paced content subscriptions, university short courses and customized programs delivered by TAFEs, universities, private training providers and learning platforms.
The estimate excludes degree tuition paid by individual students, school education and the salary cost of internal trainers. The value chain runs from technology vendors and content creators that set curricula and exams, through training providers and platforms that deliver courses, to the learning and development teams that select, fund and track training for their workforces.
Australia Corporate Education and Digital Skills Market Insights
- The Australia corporate education and digital skills market was valued at USD 3.74 billion in 2025 and is projected to reach USD 9.02 billion by 2035, registering a CAGR of 9.17% during 2026–2035.
- New South Wales and the Australian Capital Territory held a 35.0% share of 2025 value, because head offices, federal agencies and national training campuses cluster in Sydney and Canberra.
- Software and business applications led with a 27.0% share of 2025 value, because employers retrain large numbers of office staff whenever productivity and enterprise software changes.
- Australia's tech workforce reached about 977,000 people by November 2025, and about 553,000 of them held technical roles outside direct tech firms.
- Data and AI courses grow fastest at 10.97% a year during 2026–2035, as employers move from trial use of generative AI to formal staff capability programs.
Business software leads while data and AI grow fastest
Why do business software courses hold the largest share?
Based on skill area, the market is categorized into software and business applications, cloud and infrastructure, cybersecurity, data and AI, and leadership and professional skills. Software and Business Applications led with a 27.0% share of 2025 value, because office productivity and enterprise software courses reach the largest number of employees. Data and AI grow fastest at 10.97% a year, as firms train analysts, managers and frontline staff to apply AI tools safely.
How do classroom and online formats split training spend?
Based on delivery mode, the market is categorized into classroom instructor-led, virtual instructor-led, self-paced online and blended programs. Classroom Instructor-Led training led with a 33.0% share of 2025 value, because certification boot camps and hands-on labs carry the highest fees per learner. Self-Paced Online learning grows fastest at 10.13% a year, as content subscriptions replace many short classes for dispersed teams.
Which employers carry the largest training budgets?
Based on enterprise size, the market is categorized into large enterprises, government and public sector, and small and medium enterprises. Large Enterprises led with a 52.0% share of 2025 value, because banks, telecom operators, miners and retailers run structured learning programs. Small and Medium Enterprises grow fastest at 10.03% a year, as subsidized AI microskills courses bring smaller firms into formal training.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Skill Area | Software and Business Applications | 27.0% | Data and AI | 10.97% |
| By Delivery Mode | Classroom Instructor-Led | 33.0% | Self-Paced Online | 10.13% |
| By Enterprise Size | Large Enterprises | 52.0% | Small and Medium Enterprises | 10.03% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
AI gaps, tech roles and cyber demand lift training budgets
How does the AI adoption gap push employers into training?
Many Australian firms have started using AI before their staff know how to apply it, so employers now fund structured courses to close that capability gap. About 44% of small and medium firms were adopting AI in February 2026, yet 19% did not know how to use it in their business, according to the National AI Centre. Cisco's AI Readiness Index found that only 4% of Australian businesses were fully ready to capture AI's potential, compared with 13% globally. LinkedIn ranked AI literacy as the top skill on its 2025 Australian list, and 87% of surveyed professionals said they use AI tools at work. As a result, data and AI courses grow at 10.97% a year, the fastest skill area rate.
Why do tech roles across the economy widen demand?
More than half of Australia's technical workers now sit outside tech firms, which widens the pool of employees who need regular digital skills training. Australia's tech workforce reached about 977,000 people by November 2025, according to the Tech Council of Australia. About 553,000 of those workers held technical roles in industries such as banking, retail and mining rather than in direct tech firms. Software engineering roles grew 7% year on year and remain the largest technical occupation, while technical jobs in regional Australia grew 12% over five years. In turn, large enterprises held a 52.0% share of 2025 value, because banks, miners and retailers employ most of these technical staff and fund their workplace upskilling.
How does cybersecurity hiring pressure lift course demand?
Employers cannot fill security roles from the open market alone, so many now certify existing IT staff through paid courses. Cybersecurity employment is projected to grow 14.2% by 2029, and about 70,900 people work as database and system administrators and ICT security specialists, according to the October 2025 Australian Labour Market for Migrants report, as summarized by Learning People. The ACS 2025 Digital Pulse report estimates that 54,000 more skilled people will be needed in cybersecurity operations and management by 2030. Job advertisements for these roles averaged about 621 a month from September 2024 to September 2025. As a result, cybersecurity courses for CompTIA, ISC2 and ISACA credentials gain a growing share of IT training budgets.
Why do public and vendor skilling programs expand the base?
Free introductory AI courses from government and vendors reach millions of workers, and many of them later need paid certification that their employers fund. Microsoft aims to help one million Australians and New Zealanders gain AI skills by the end of 2026, building on an October 2023 pledge to train 300,000 Australians, according to TechPartner News. The National AI Centre and the TAFE NSW Institute of Applied Technology Digital launched fully subsidized AI microskills courses in December 2025 that aim to reach more than one million Australians. The Commonwealth is also funding up to 20 TAFE Centres of Excellence through a A$325 million program. In turn, small and medium enterprises grow at 10.03% a year, the fastest enterprise rate.
Online delivery, platforms and short credentials gain ground
How is the shift to online delivery changing course design?
Employers now expect short modules that staff can complete between tasks, and providers have rebuilt many courses for screens instead of classrooms. Online learning delivered 55% of work-related training in 2020-21, up from 19% in 2016-17, according to the Australian Bureau of Statistics. About 42% of people spent less than 10 hours on their most recent work-related course, which favors compact modules similar to professional e-learning content. Employees were also more than twice as likely as business owners and managers to train in their current job, at 33% compared with 15%. As a result, self-paced online learning grows at 10.13% a year, the fastest delivery rate, while classroom courses keep the largest share.
Why is the rise of platform consolidation reshaping buying?
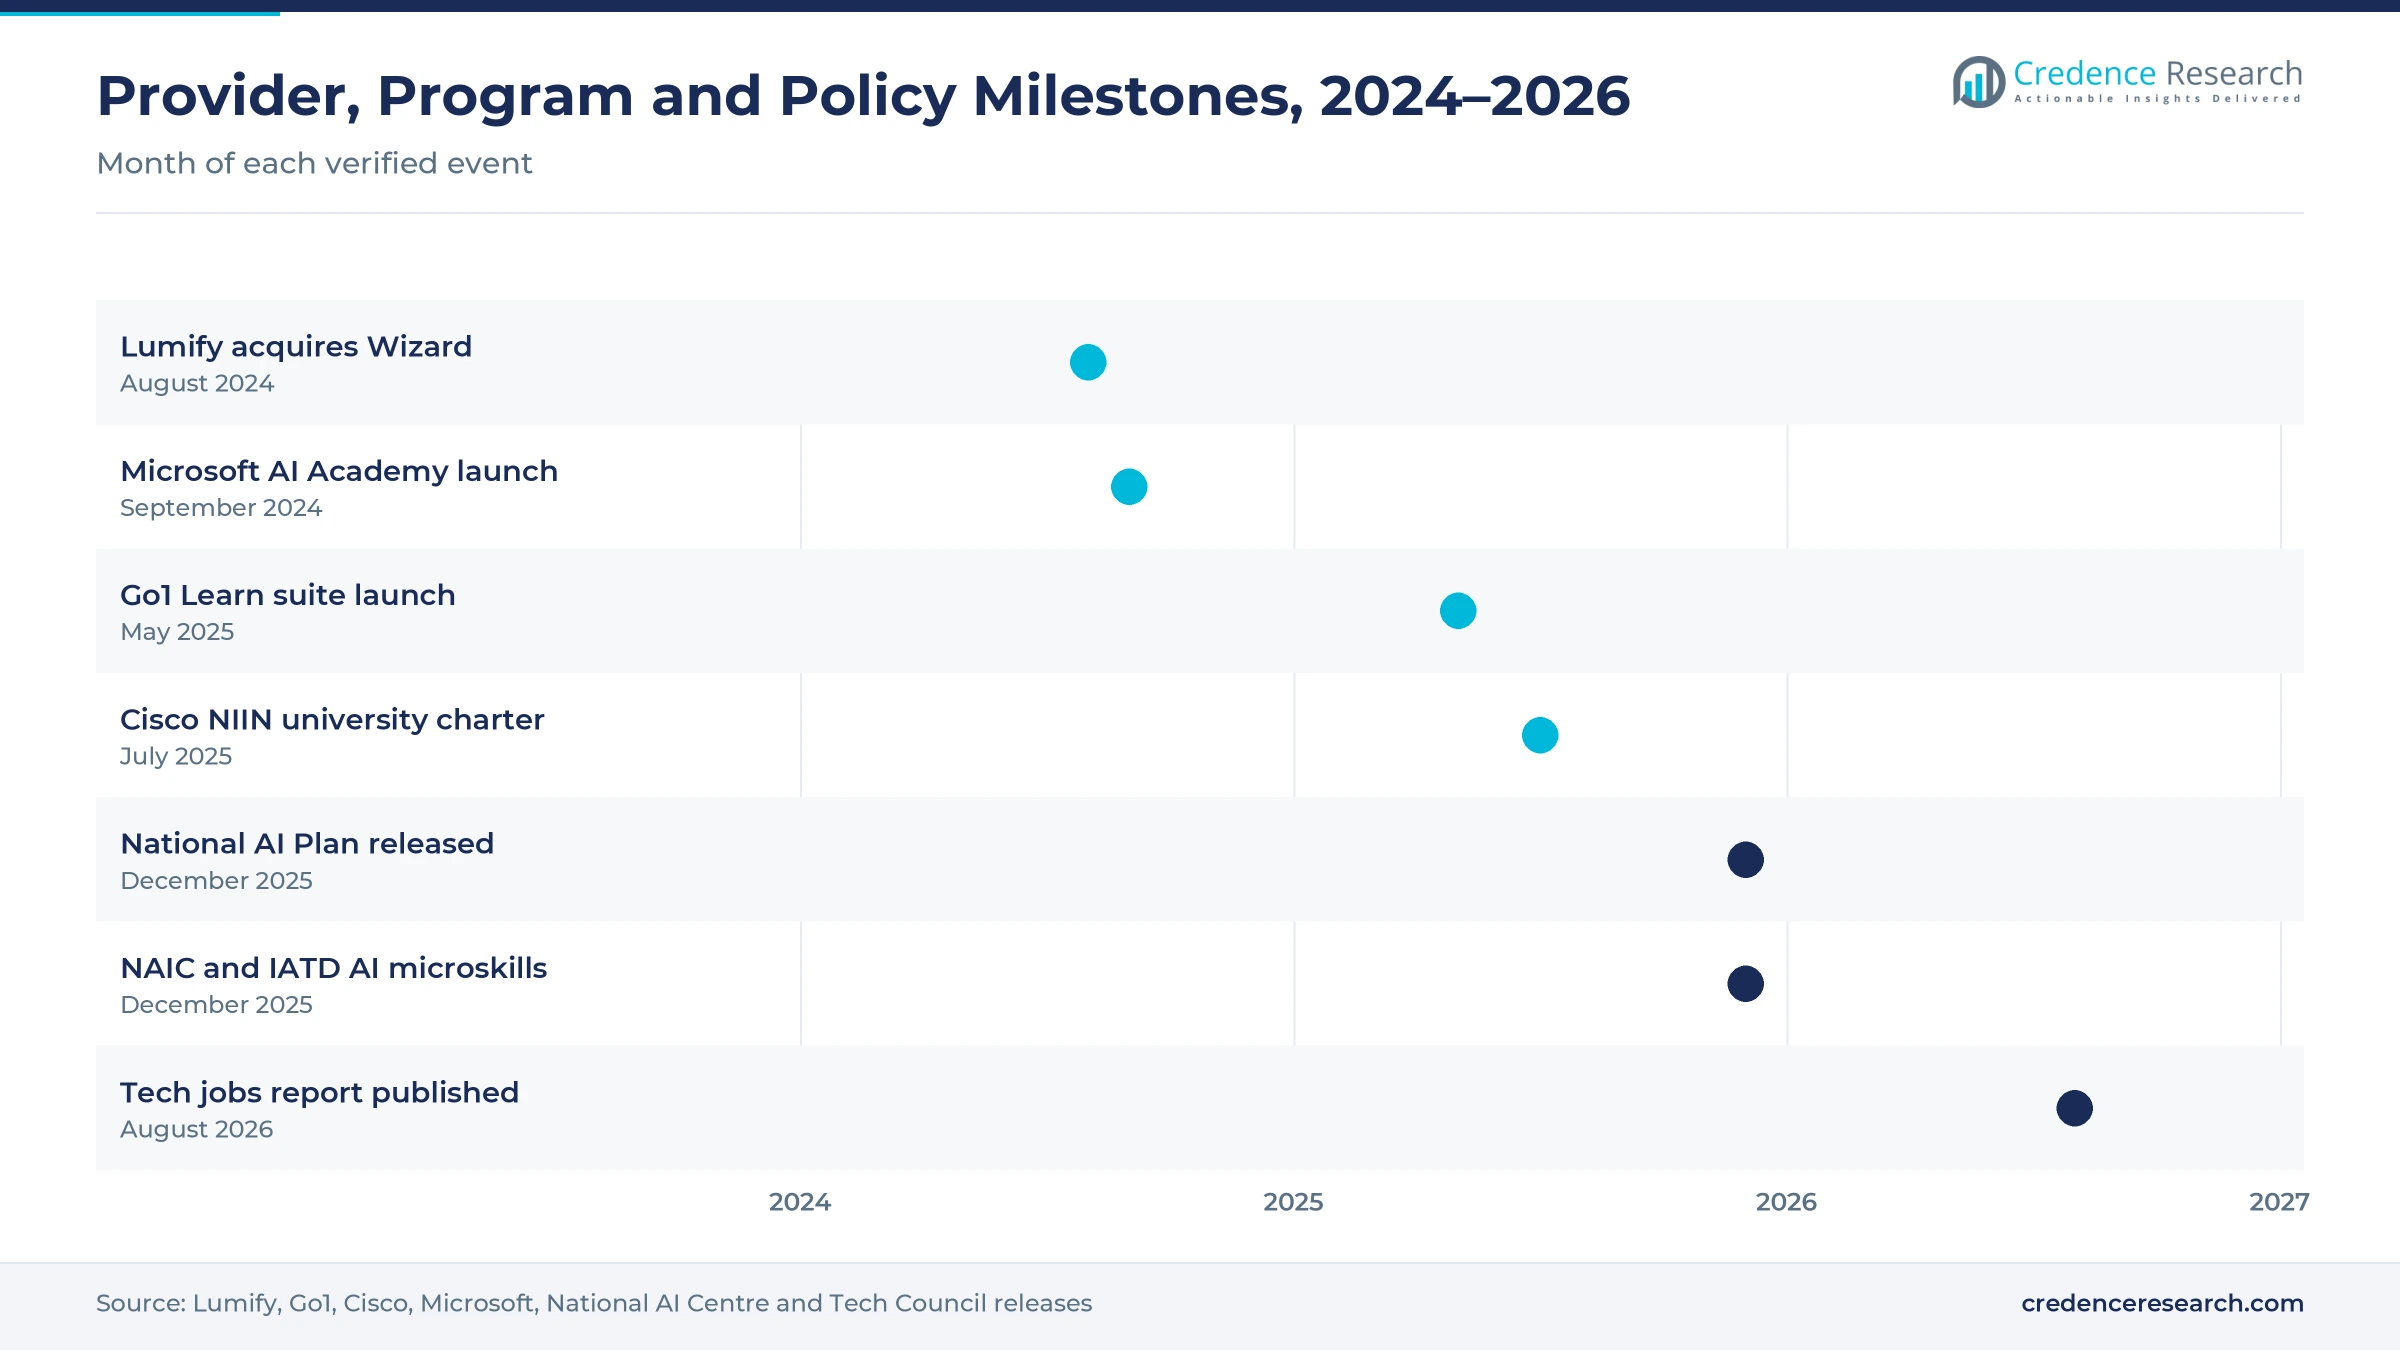
Learning teams want fewer supplier contracts that still cover technical, compliance and leadership content, which favors large aggregated libraries. Brisbane-founded Go1 launched its Go1 Learn product suite on May 14, 2025, and serves more than 10,000 organizations, according to a Go1 release. Its survey of more than 600 learning leaders in the U.S., the U.K. and Australia found that 40% use five or more content providers and 47% struggle to find upskilling content that meets all needs. Lumify Group added 25 professional development courses when it acquired Wizard Corporate Training in August 2024. In turn, buyers increasingly pair content libraries with learning management systems to track skills.
Can university short credentials open a new growth lane?
Managers want AI and data skills without committing to a full degree, which gives universities room to sell short paid courses to employers. RMIT Online sells AI short courses that include an eight-week Agentic AI course for A$1,000 and a four-week AI for Business Leaders course for A$750. DeakinCo., the workplace education division of Deakin University, co-designed machine learning programs with Tata Consultancy Services in three streams for executives, managers and practitioners. Cisco and 10 Australian universities signed a charter for its National Industry Innovation Network in July 2025. As a result, universities can win employer budgets that previously went to leadership programs alone.
Is regional and remote delivery a growth opening?
Technical jobs are growing outside the capital cities, and near-universal internet access makes live virtual classes practical for employers far from training campuses. About 96.1% of Australians used the internet in 2024, according to the World Bank. Technical jobs in regional Australia grew 12% over five years, more than twice the rate of regional jobs overall. TAFE NSW delivers Cisco networking training to learners from Sydney to Broken Hill and aligns CCNA modules with Certificate IV qualifications. In turn, virtual instructor-led courses let providers serve mining, agriculture and health employers that cannot release staff for city training trips.
Budget scrutiny, thin courses and trainer gaps slow buyers
How does budget scrutiny slow training purchases?
Learning budgets face tight review when profits soften, which makes discretionary courses an early target for cuts. As a result, providers must show completion rates, certification passes and on-the-job gains before buyers renew contracts. Employers respond by funding fewer, more targeted programs and by asking platforms for skills analytics. More than half of the learning leaders in a 2025 Go1 survey said 10% to 25% of their budget went to ineffective or unused content.
Why can short courses leave skills gaps?
Short modules suit busy staff, yet they rarely build the depth needed to run cloud platforms or secure complex networks. In turn, employers that rely only on brief online content may still face project delays and outside hiring costs. Providers respond with stackable pathways that link microskills to vendor certifications and accredited qualifications. Only 38% of Australians spent 20 hours or more on their most recent work-related course, according to the Australian Bureau of Statistics.
How do trainer shortages constrain delivery?
Qualified instructors in cloud, cybersecurity and AI are also in demand as practitioners, which makes them expensive and hard to retain as trainers. As a result, providers can struggle to schedule enough specialist classes in smaller cities and during peak certification periods. Firms respond with virtual classrooms that let one instructor serve several states and with vendor train-the-trainer programs. Cybersecurity professionals earned a median of A$2,284 a week in full-time non-managerial roles, as summarized by Learning People.
Why do smaller firms struggle to release staff?
Small and medium firms often lack learning teams and cannot easily cover staff who leave the floor for training. In turn, many owners delay formal courses even when they know staff need digital skills. Governments and providers respond with free microskills, short online modules and courses timed outside peak trading hours. Half of business owners and managers paid personal costs for their most recent work-related course, compared with one in ten employees, according to the Australian Bureau of Statistics.
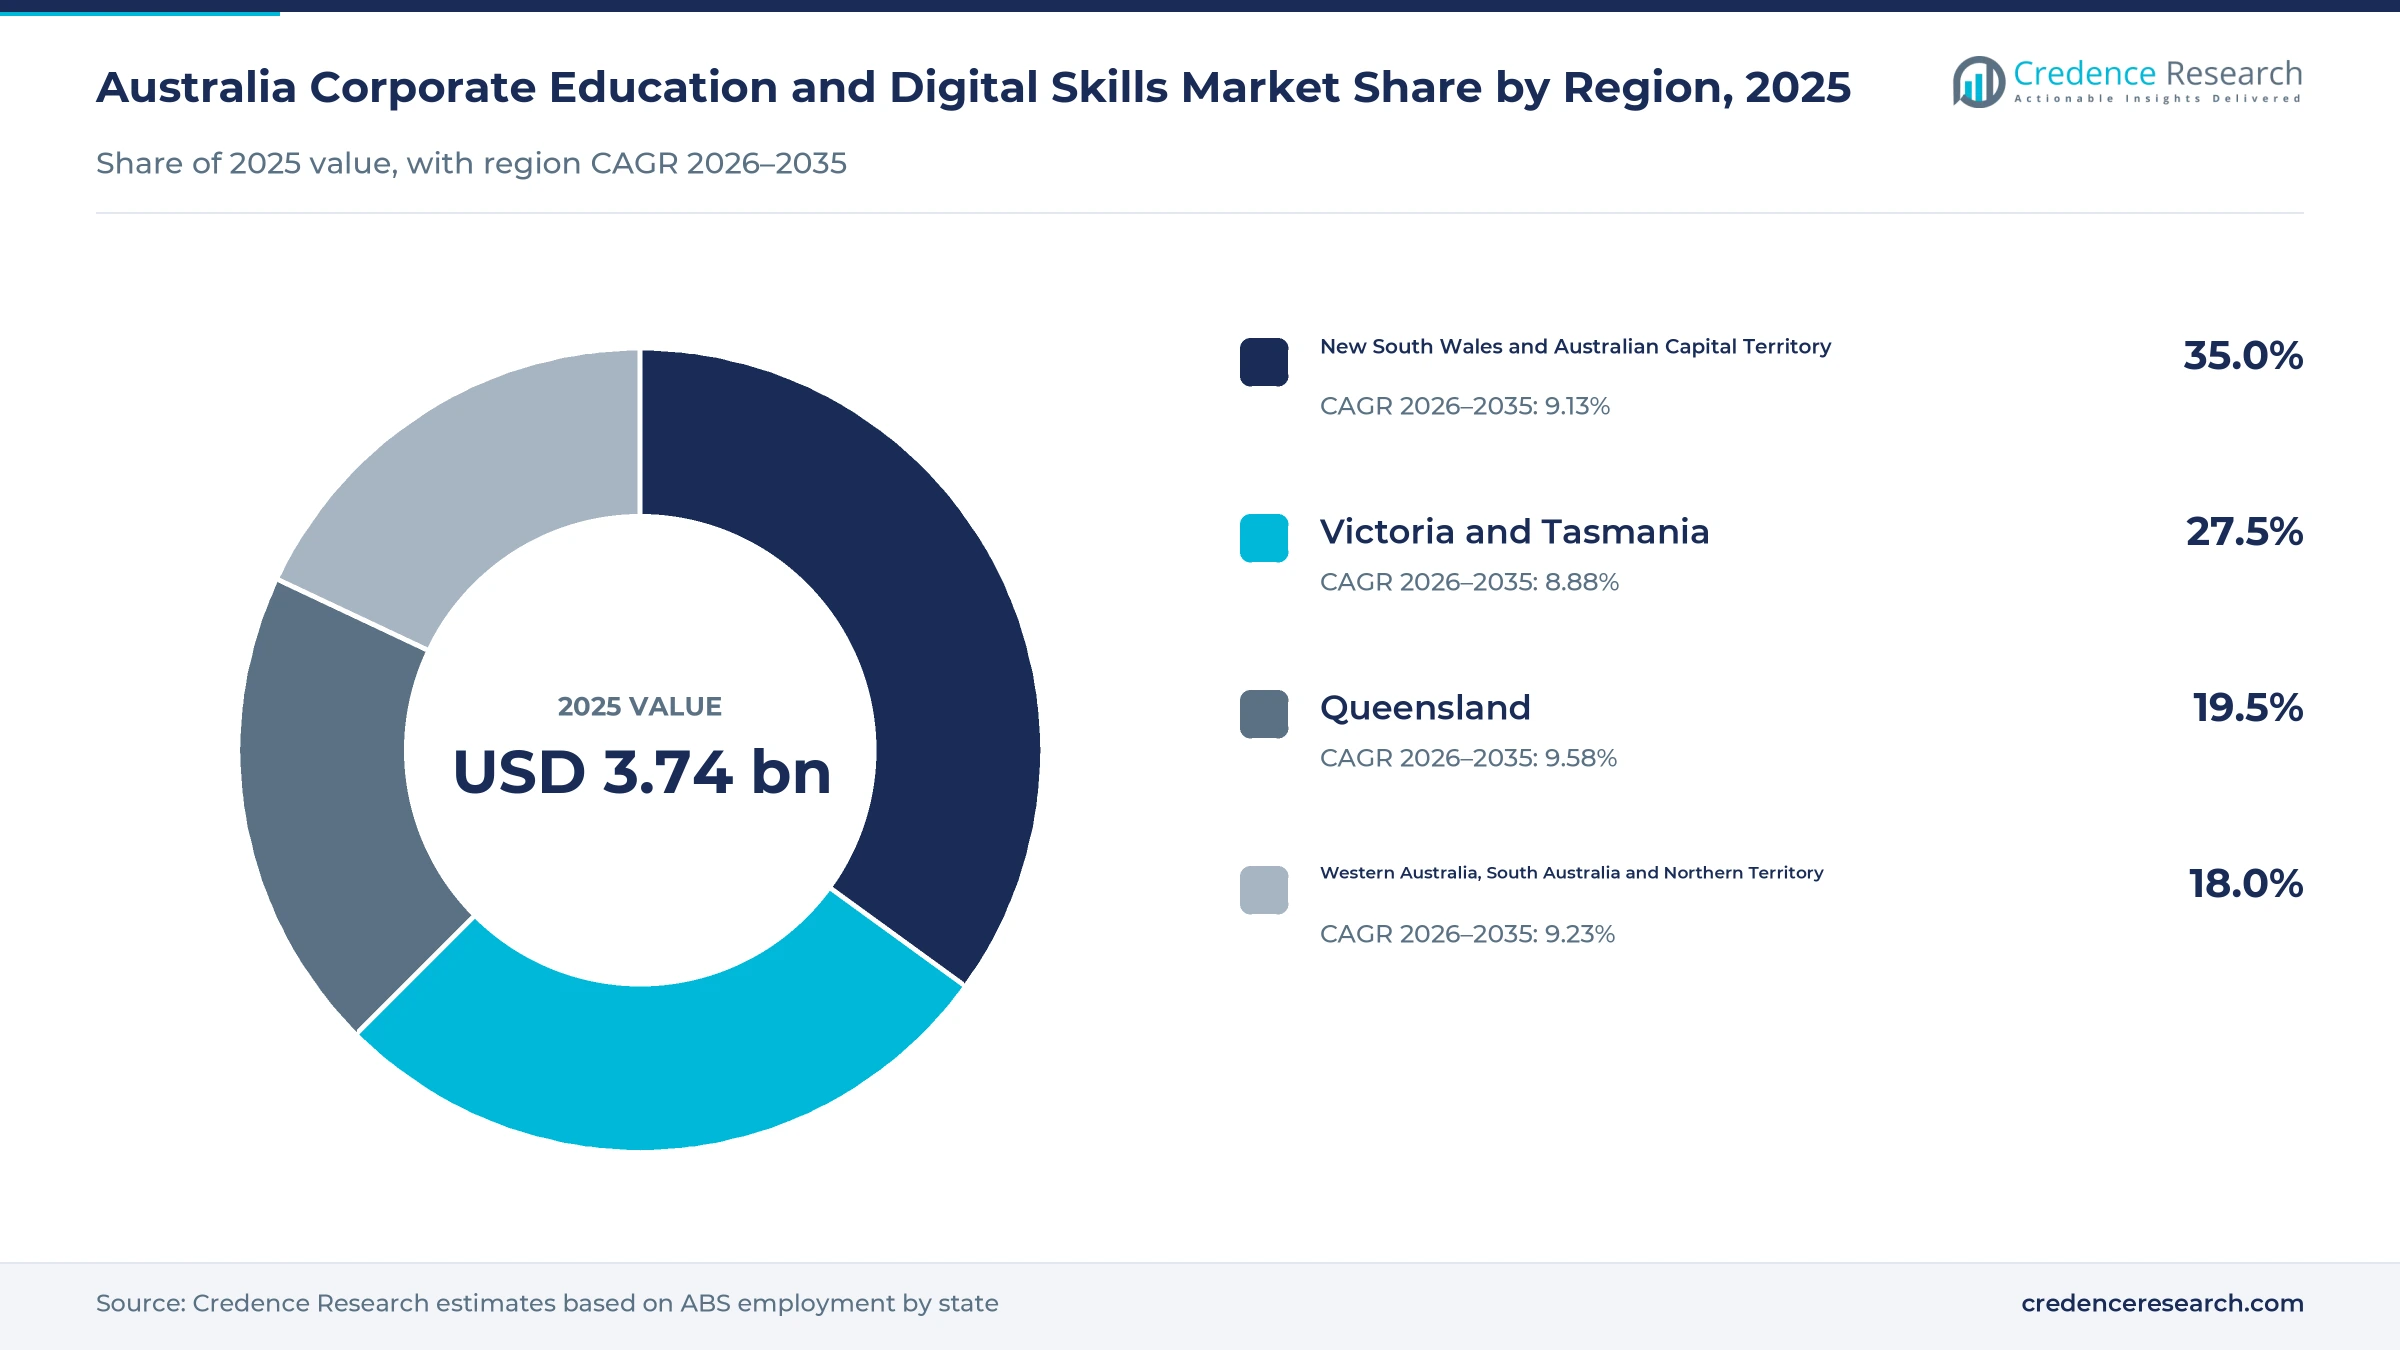
New South Wales and Australian Capital Territory lead
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 1.31 | 35.0% | 9.13% |
| Victoria and Tasmania | 1.03 | 27.5% | 8.88% |
| Queensland | 0.73 | 19.5% | 9.58% |
| Western Australia, South Australia and Northern Territory | 0.67 | 18.0% | 9.23% |
How do Sydney and Canberra employers anchor training spend?
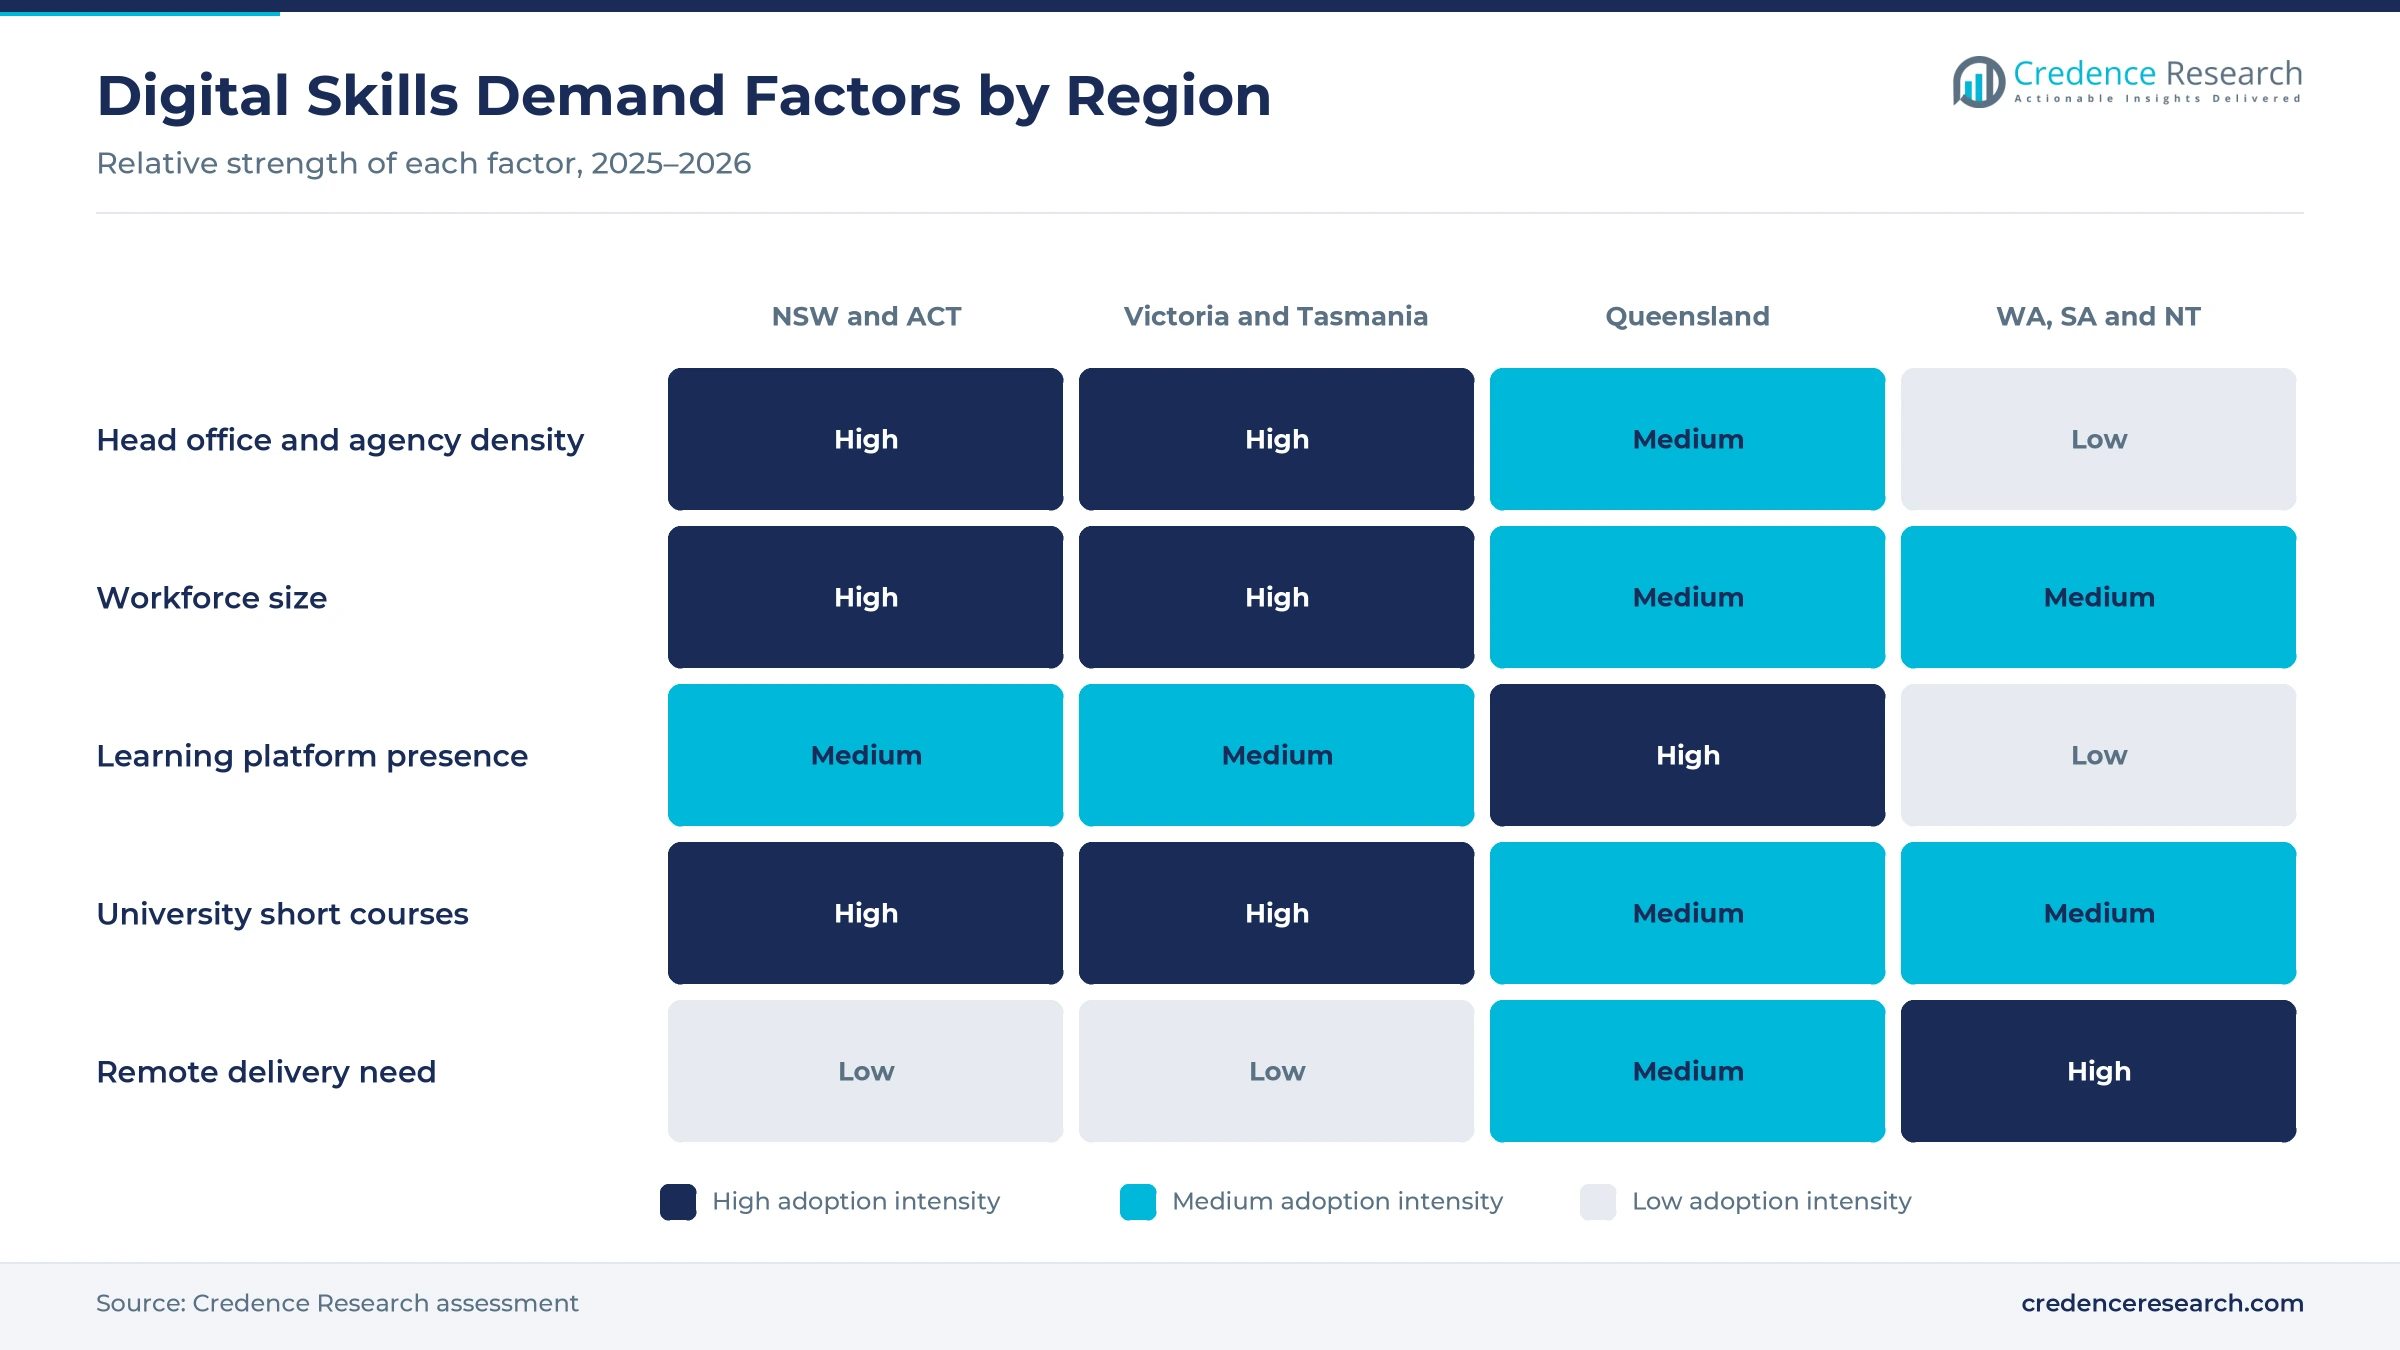
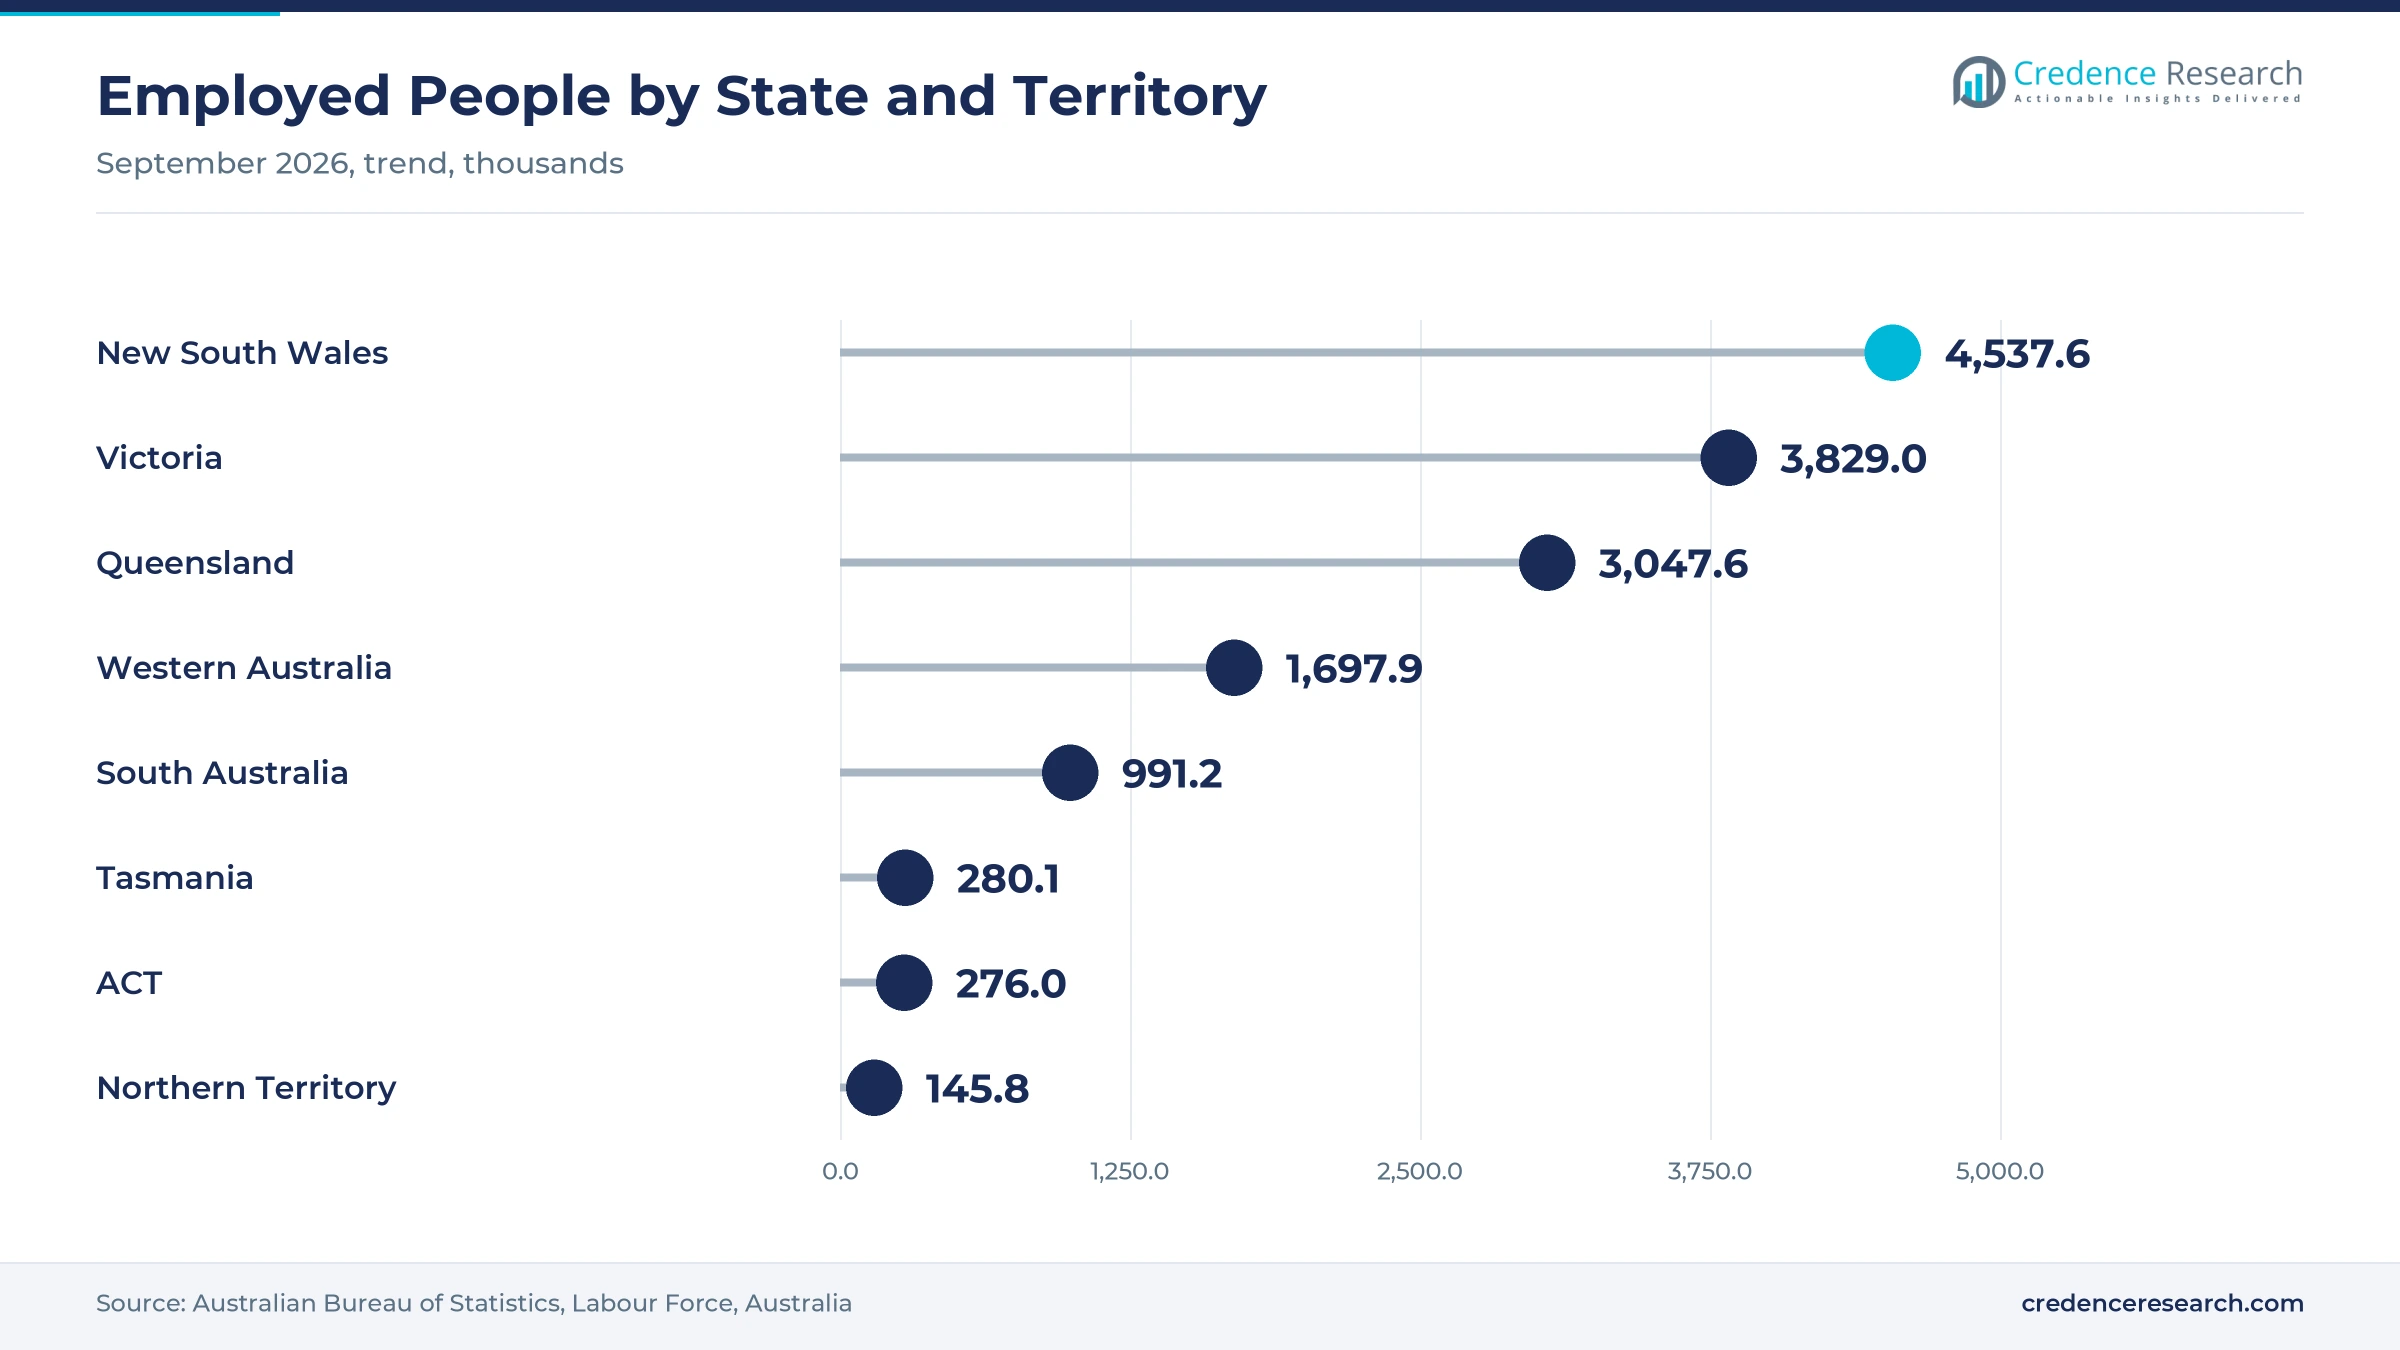
New South Wales and the Australian Capital Territory held a 35.0% share of 2025 value and grow at 9.13% a year, because the zone has the largest workforce. New South Wales had about 4.54 million employed people and the ACT about 276,000 in September 2026, in trend terms. Sydney-based Lumify Group and the TAFE NSW digital institute at Meadowbank, which opened in 2023, give employers local access to vendor certification and AI courses. As a result, the zone leads spending on cloud, security and public sector digital programs.
How do Victoria and Tasmania build on university providers?
Victoria and Tasmania held a 27.5% share of 2025 value and grow at 8.88% a year, because Melbourne hosts several university-linked corporate education arms. Victoria had about 3.83 million employed people and Tasmania about 280,100 in September 2026, in trend terms. Victorian universities RMIT and Deakin run RMIT Online and DeakinCo., which sell AI, data and machine learning programs to employers. In turn, the zone grows steadily from a broad base of professional services and public sector buyers.
Why does Queensland lead growth in employer digital training?
Queensland held a 19.5% share of 2025 value and grows fastest at 9.58% a year, because its workforce and its learning technology sector are both expanding. Queensland had about 3.05 million employed people in September 2026, in trend terms. Go1 remains headquartered in Underwood, Brisbane and its users complete about 50,000 training hours a day, according to the Australian Computer Society. As a result, employers in the state gain local access to platforms and talent pipelines.
Why do Western Australia, South Australia and Northern Territory add demand?
Western Australia, South Australia and the Northern Territory held 18.0% of 2025 value, and the zone grows at 9.23% a year. Western Australia had about 1.70 million employed people, South Australia about 991,200 and the Northern Territory about 145,800 in September 2026, in trend terms. Lumify Work runs campuses in Perth and Adelaide for vendor-certified IT courses. In turn, mining, defense and energy employers drive demand for remote-friendly technical training across large distances.
Acquisitions, AI programs and national plans since 2024
| Development | Status and market relevance |
|---|---|
| In August 2024, Lumify Group acquired Wizard Corporate Training, adding 25 professional development courses and a stronger ACT presence. | Widens application and short-course training |
| In May 2025, Go1 launched its Go1 Learn product suite with tools for learning budgets and skills insights. | Supports content consolidation for employers |
| In July 2025, Cisco and 10 Australian universities signed a charter for the National Industry Innovation Network. | Links industry projects with university talent |
| In December 2025, the federal government released the National AI Plan, including A$29.9 million for an AI Safety Institute. | Places AI skills on the national agenda |
| In December 2025, the National AI Centre and TAFE NSW launched subsidized AI microskills courses for over one million Australians. | Expands free entry-level AI training |
Labs, platforms and vendor exams shape skills delivery
- Hands-on cloud and security labs give learners live sandbox environments for AWS, Microsoft and Cisco exams, which shortens the path from class to certified work.
- Learning experience platforms aggregate content from many publishers in one subscription, as Go1 does for more than 10,000 organizations.
- Virtual classrooms let one instructor teach learners across several states in real time, which suits regional employers and dispersed teams.
- Skills analytics map completed courses to job roles and certifications, which helps learning teams prove training value to finance leaders.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
TAFEs, universities and IT trainers compete for employers
Competition combines public TAFEs, university corporate education arms, private IT training providers and global learning platforms. TAFE NSW runs the Institute of Applied Technology Digital, which has recorded more than 180,000 enrolments, and trains Cisco Networking Academy instructors across New South Wales. Lumify Work, the trading name of DDLS Australia, offers more than 700 ICT courses through partnerships with AWS, Cisco, CompTIA and Microsoft. RMIT Online sells AI and data short courses, while DeakinCo. designs workplace education and skills recognition programs for employers. Learning People offers career-change courses in IT support, networking, coding and cybersecurity tied to vendor certifications. Go1 competes as a content aggregator for enterprise learning teams. Rivals compete on vendor accreditation, course breadth, delivery flexibility, credential value and skills analytics.
Which TAFEs, universities and platforms lead employer training?
| Company | Type | Role in the market |
|---|---|---|
| TAFE NSW | Public training provider | Institute of Applied Technology Digital and Cisco instructor training |
| Lumify Work (DDLS) | Private IT training provider | Vendor-certified ICT courses across six Australian cities |
| RMIT University | University provider | RMIT Online AI, data and business short courses |
| DeakinCo. | University corporate education arm | Workplace education and skills recognition programs |
| Learning People | Private IT training provider | Career-change courses in IT support, networking and cyber |
| Go1 | Learning platform | Brisbane-founded content aggregator for enterprise learning |
| Cisco Networking Academy | Vendor skills program | Networking and security curricula delivered through partners |
Credence Research view on Australian digital upskilling
Credence Research's view is that Australian employer spending on digital skills will rise faster than general workplace training, because AI adoption, cloud migration and security threats all require new capabilities at once. Business software courses keep the largest share, yet data and AI programs add the fastest growth as firms formalize AI use. Free public microskills courses should widen the funnel for paid certification rather than replace it. Providers that combine vendor accreditation, flexible delivery and skills analytics should gain the most share by 2035.
Employment, training and AI adoption data behind the model
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines ABS employment and work-related training data, Tech Council workforce figures, National AI Centre adoption surveys, government program announcements and provider releases on courses and acquisitions. Segment splits, zone shares and zone growth rates are Credence Research estimates. Sources used are statistics agency and government publications, industry body reports, company releases and international agency data, and no interviews or surveys were used.
AI adoption and tech hiring carry training demand to 2035
The Australia corporate education and digital skills market is expected to reach USD 9.02 billion by 2035, a 9.17% CAGR during 2026–2035, as employers train staff for AI, cloud and security work across every industry. Growth should be strongest in data and AI courses, self-paced online learning, small and medium enterprises and Queensland, because these areas gain most from subsidized entry courses and platform delivery. Budget scrutiny and trainer shortages could slow some programs, while the national AI agenda should support demand after 2030.
Frequently Asked Questions
How big is the Australia corporate education and digital skills market?
Which skill area leads Australian employer training spend?
Which region leads the market?
How many tech workers does Australia have?
How widely do Australian small businesses use AI?
What free AI training is available to Australian workers?
Who are the leading companies in the market?
What are the main challenges for training providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Skill Area
- 1.2.1 Software and Business Applications
- 1.2.2 Cloud and Infrastructure
- 1.2.3 Cybersecurity
- 1.2.4 Data and AI
- 1.2.5 Leadership and Professional Skills
- 1.3 By Delivery Mode
- 1.3.1 Classroom Instructor-Led
- 1.3.2 Virtual Instructor-Led
- 1.3.3 Self-Paced Online
- 1.3.4 Blended Programs
- 1.4 By Enterprise Size
- 1.4.1 Large Enterprises
- 1.4.2 Government and Public Sector
- 1.4.3 Small and Medium Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3.74 billion → 2035: USD 9.02 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Corporate Education and Digital Skills Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Corporate Education and Digital Skills Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Corporate Education and Digital Skills Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Corporate Education and Digital Skills Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Corporate Education and Digital Skills Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Corporate Education and Digital Skills Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Corporate Education and Digital Skills Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Corporate Education and Digital Skills Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3.74 billion → 2035: USD 9.02 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Corporate Education and Digital Skills Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Skill Area - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software and Business Applications
- 12.3.7.2 Cloud and Infrastructure
- 12.3.7.3 Cybersecurity
- 12.3.7.4 Data and AI
- 12.3.7.5 Leadership and Professional Skills
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Delivery Mode - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Classroom Instructor-Led
- 12.4.7.2 Virtual Instructor-Led
- 12.4.7.3 Self-Paced Online
- 12.4.7.4 Blended Programs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Enterprises
- 12.5.7.2 Government and Public Sector
- 12.5.7.3 Small and Medium Enterprises
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Corporate Education and Digital Skills Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Corporate Education and Digital Skills Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Corporate Education and Digital Skills Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 TAFE NSW
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 RMIT University
- 17.4 DeakinCo.
- 17.5 Learning People
- 17.6 DDLS
- 17.7 Lumify Work
- 17.8 Go1
- 17.9 SEEK Learning
- 17.10 LinkedIn Learning
- 17.11 Cisco Networking Academy
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

