
Boards and managers turn AI risk into a learning budget
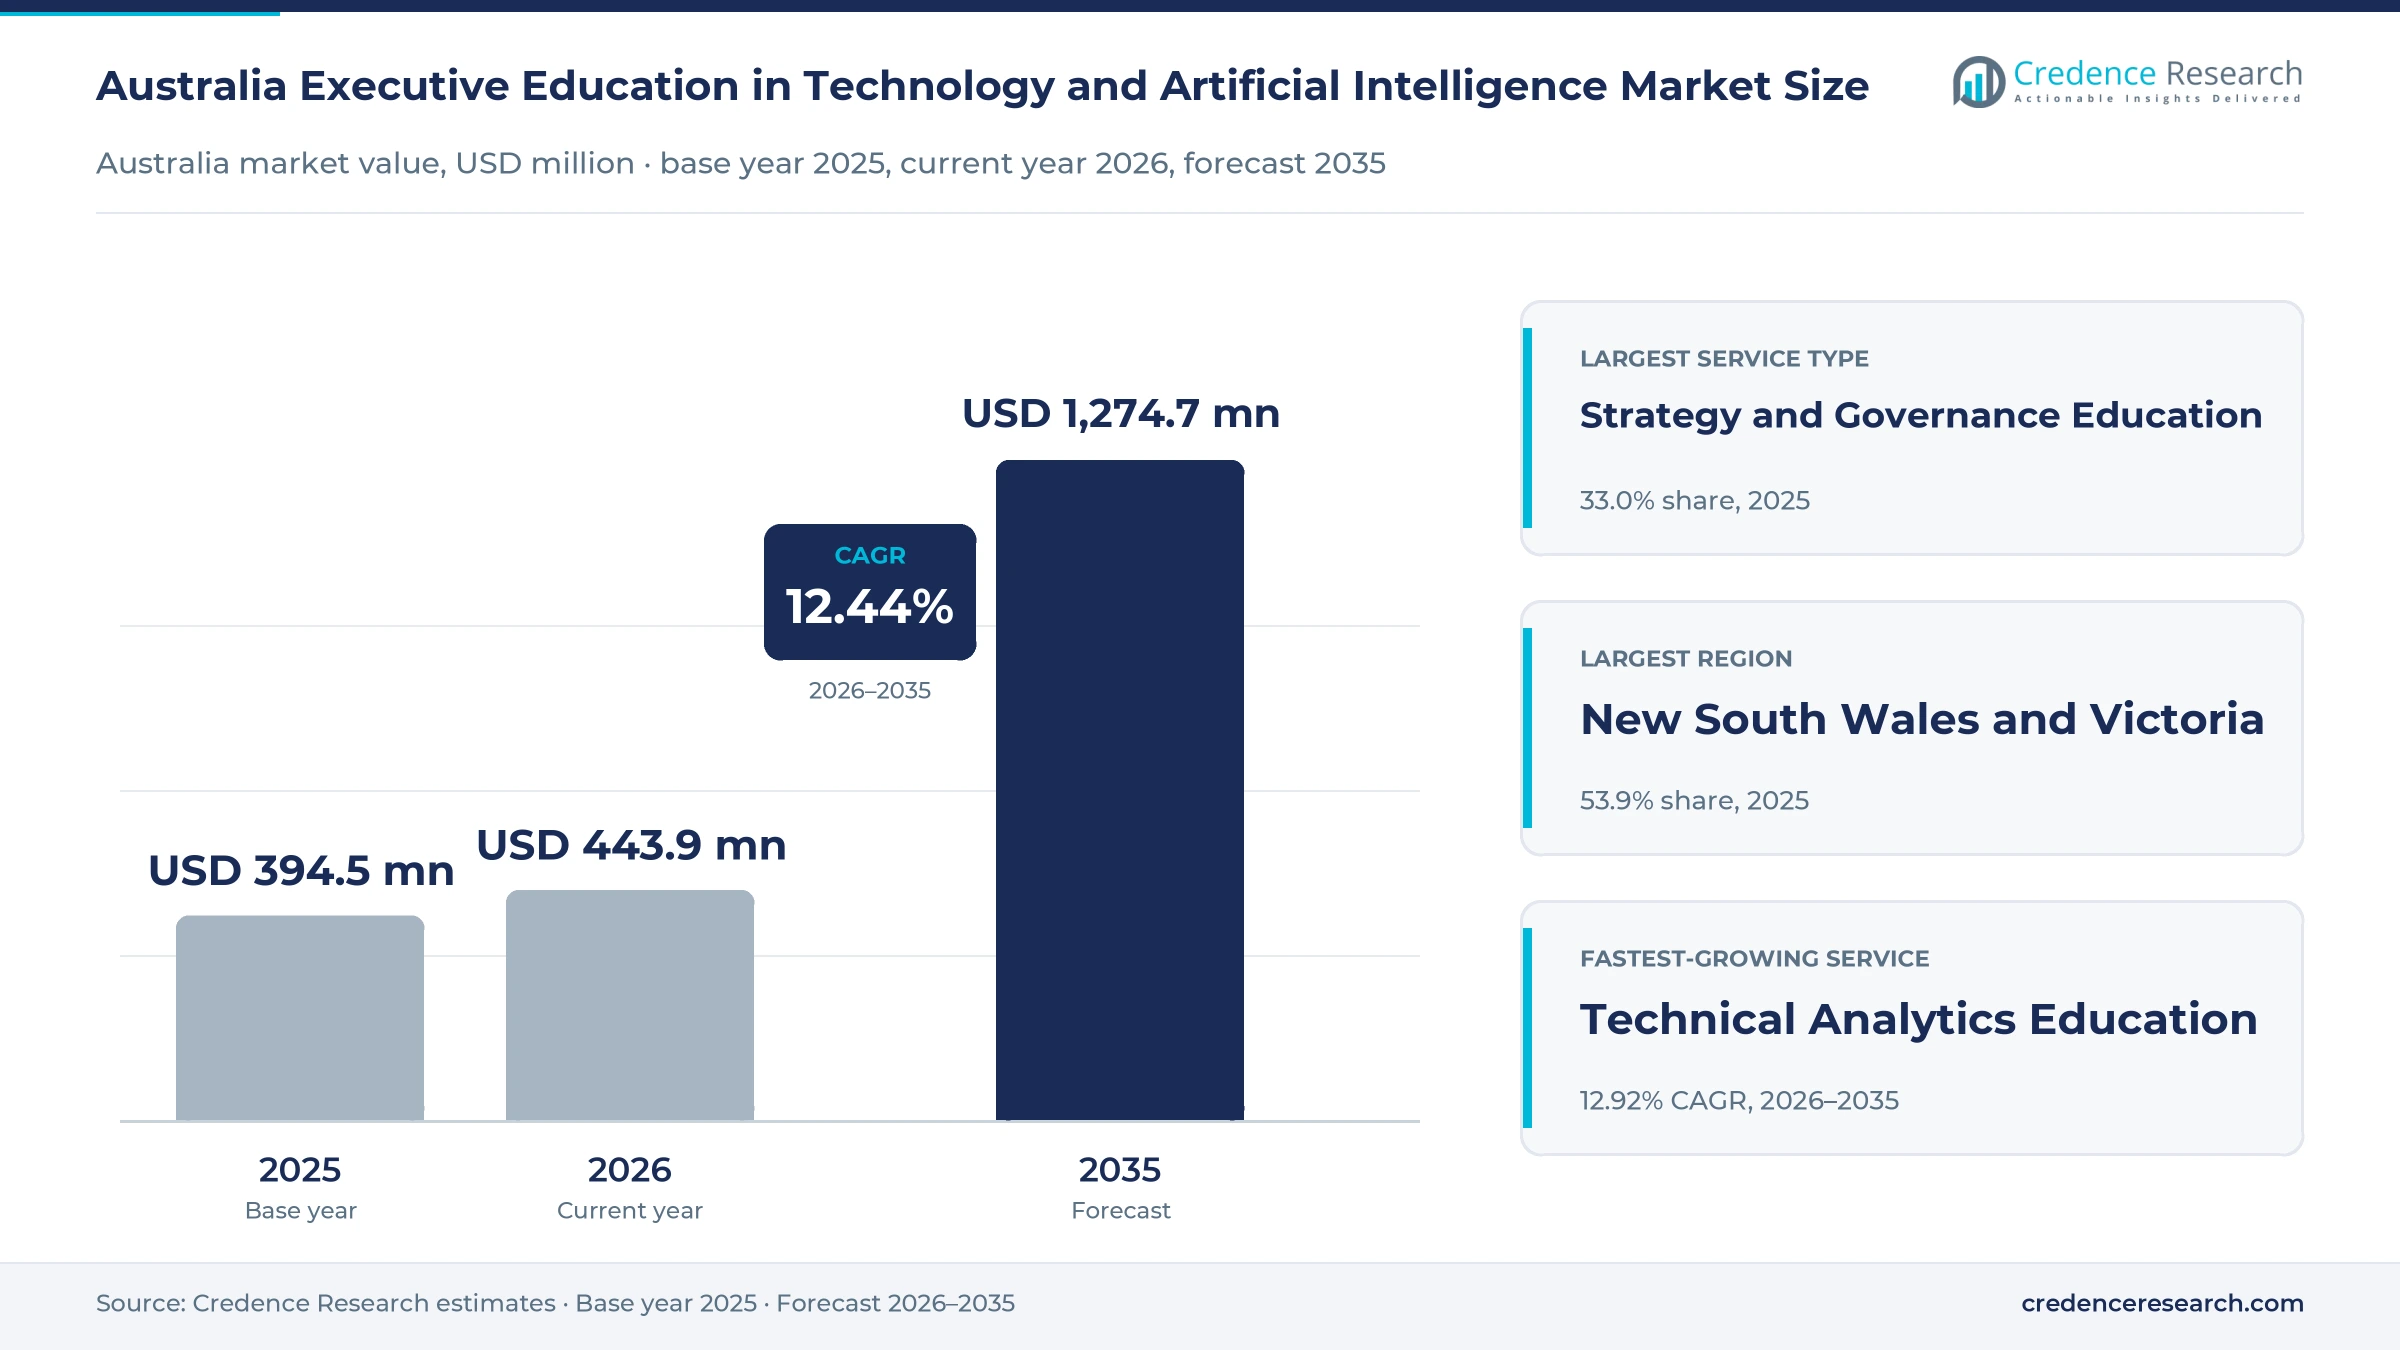
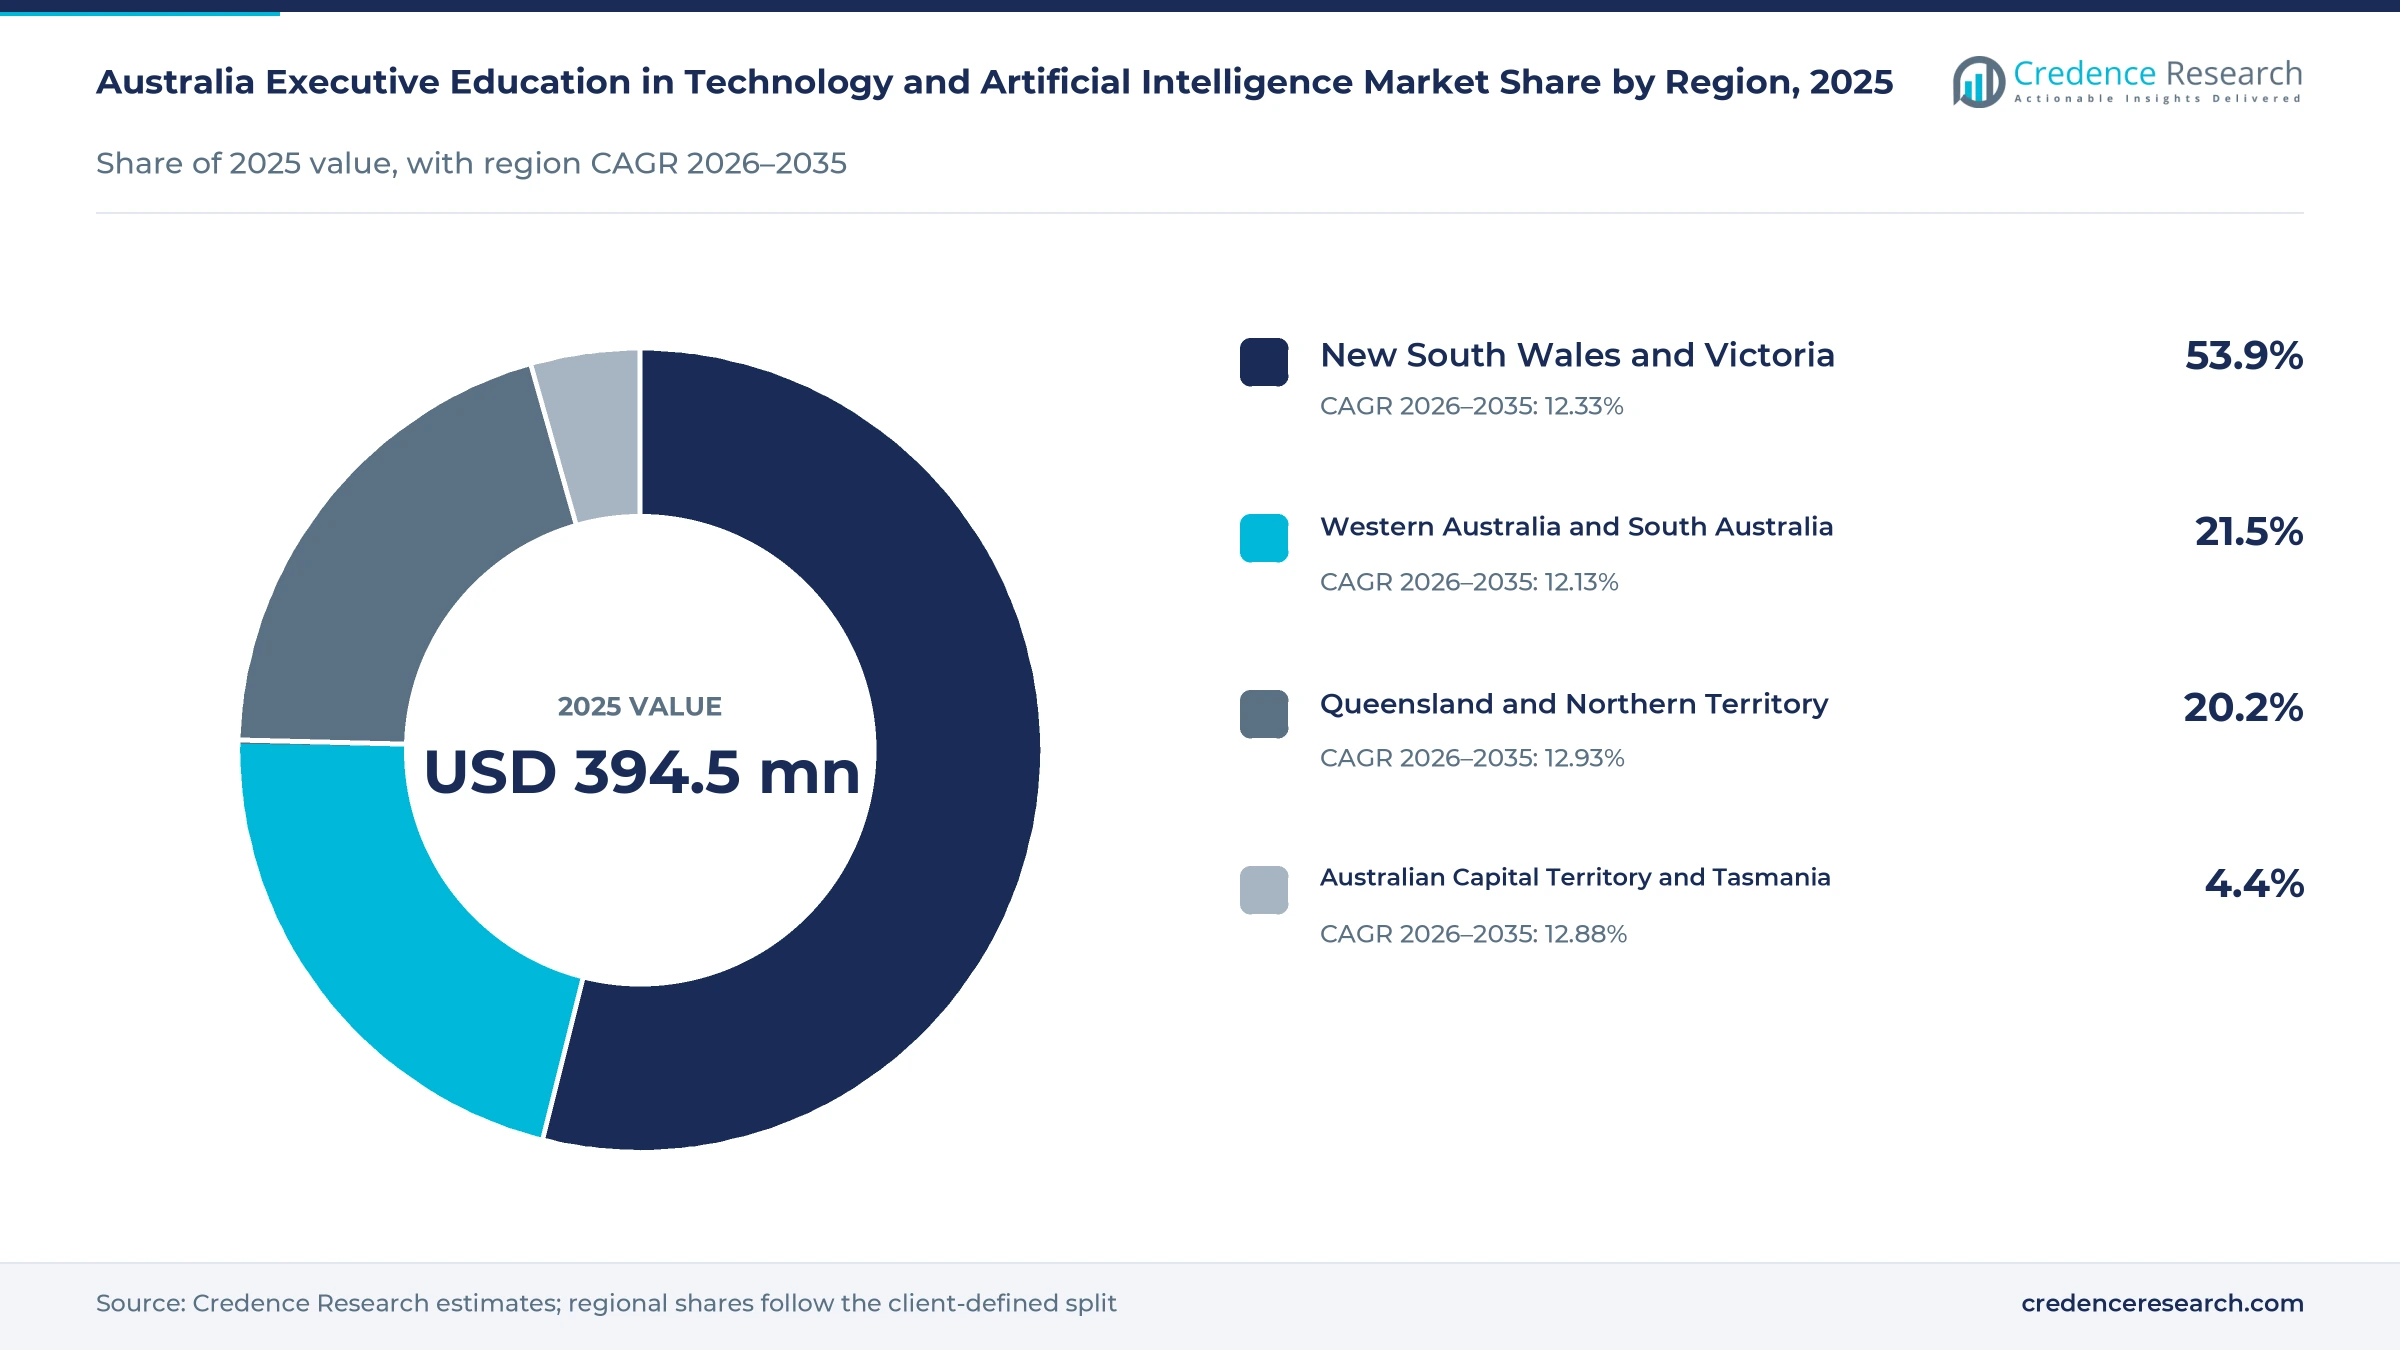
The Australia executive education in technology and artificial intelligence market was valued at USD 394.5 million in 2025 and is projected to increase from USD 443.9 million in 2026 to USD 1.27 billion by 2035, registering a CAGR of 12.44% during 2026–2035. Demand comes from boards, senior managers and experienced technical staff who must decide where artificial intelligence fits, how it is governed and how data, cloud and analytics teams are led. Buyers are mostly employers that fund short courses, custom cohorts and credential pathways from established learning budgets. New South Wales and Victoria held the largest regional share, 53.9% in 2025, because Sydney and Melbourne host most corporate head offices and leading business schools. Queensland and Northern Territory is the fastest-growing region at 12.93% a year. In turn, the National AI Plan released on Dec. 2, 2025, and the Guidance for AI Adoption issued on Oct. 21, 2025, give leaders a clearer set of practices to learn and apply.
What spending does the Australian estimate count?
The estimate measures fees paid in Australia for non-degree and short credential programs that teach leaders and senior professionals how to plan, govern and manage artificial intelligence, data analytics and digital technology. It counts open-enrollment courses, custom programs built for one employer, subscription access to leadership and technology content, and stackable credentials sold by universities, business schools, specialist trainers, learning platforms and technology vendors.
The estimate excludes full degree tuition, school and entry-level vocational training, free vendor courses that carry no fee, and general software licenses for learning systems. The value chain runs from faculty, content producers and cloud vendors through providers and platforms to employer learning teams, which choose programs, negotiate cohort pricing and measure whether leaders apply what they learn.
Australia Executive Education in Technology and Artificial Intelligence Market Insights
- The market was valued at USD 394.5 million in 2025 and is projected to reach USD 1.27 billion by 2035, registering a CAGR of 12.44% during 2026–2035 as AI governance needs grow.
- New South Wales and Victoria held a 53.9% share of 2025 value, because Sydney and Melbourne concentrate head offices and business schools.
- Strategy and Governance Education led with a 33.0% share of 2025 value, as boards and executives seek structured guidance on AI oversight and risk.
- The Australian Government released the National AI Plan on Dec. 2, 2025, after publishing the Guidance for AI Adoption with six essential practices on Oct. 21, 2025.
- Custom Corporate Cohorts grow at 12.84% a year during 2026–2035, as employers buy programs that link AI lessons to their own projects and risks.
Governance courses lead as analytics training grows fastest
Why does governance education hold the largest share?
Based on service type, the market is categorized into Strategy and Governance Education, Technical Analytics Education, Digital Transformation Education and Technology Management Education. Strategy and Governance Education led with a 33.0% share of 2025 value, because directors and executives need frameworks for AI oversight before they fund projects. Technical Analytics Education grows fastest at 12.92% a year, as experienced staff move from dashboards to model evaluation and data engineering decisions.
Which leaders account for most enrollments?
Based on learner segment, the market is categorized into Board and C-Suite Leaders, Senior and Functional Managers, and Experienced Technical Professionals. Senior and Functional Managers led with a 46.0% share of 2025 value, because employers train large groups of managers who must run AI projects day to day. Board and C-Suite Leaders grow fastest at 13.00% a year, as boards respond to governance guidance and new disclosure duties.
How do online and blended formats split spending?
Based on delivery model, the market is categorized into Online Delivery, Blended Delivery and In-Person Delivery. Online Delivery led with a 45.0% share of 2025 value, because busy leaders prefer programs that fit around work and travel. Blended Delivery grows fastest at 12.87% a year, as schools pair short campus sessions with online modules, coaching and applied projects.
Why are custom cohorts gaining on open courses?
Based on program type, the market is categorized into Open-Enrolment Short Courses, Custom Corporate Cohorts and Extended Credential Pathways. Open-Enrolment Short Courses led with a 45.0% share of 2025 value, because single leaders and small teams can join scheduled intakes quickly. Custom Corporate Cohorts grow fastest at 12.84% a year, as employers ask providers to build corporate leadership training around their own AI use cases.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Strategy and Governance Education | 33.0% | Technical Analytics Education | 12.92% |
| By Learner Segment | Senior and Functional Managers | 46.0% | Board and C-Suite Leaders | 13.00% |
| By Delivery Model | Online Delivery | 45.0% | Blended Delivery | 12.87% |
| By Program Type | Open-Enrolment Short Courses | 45.0% | Custom Corporate Cohorts | 12.84% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
AI skill gaps, board duties and training budgets lift demand
Why does employer demand for applied AI skills lift spending?
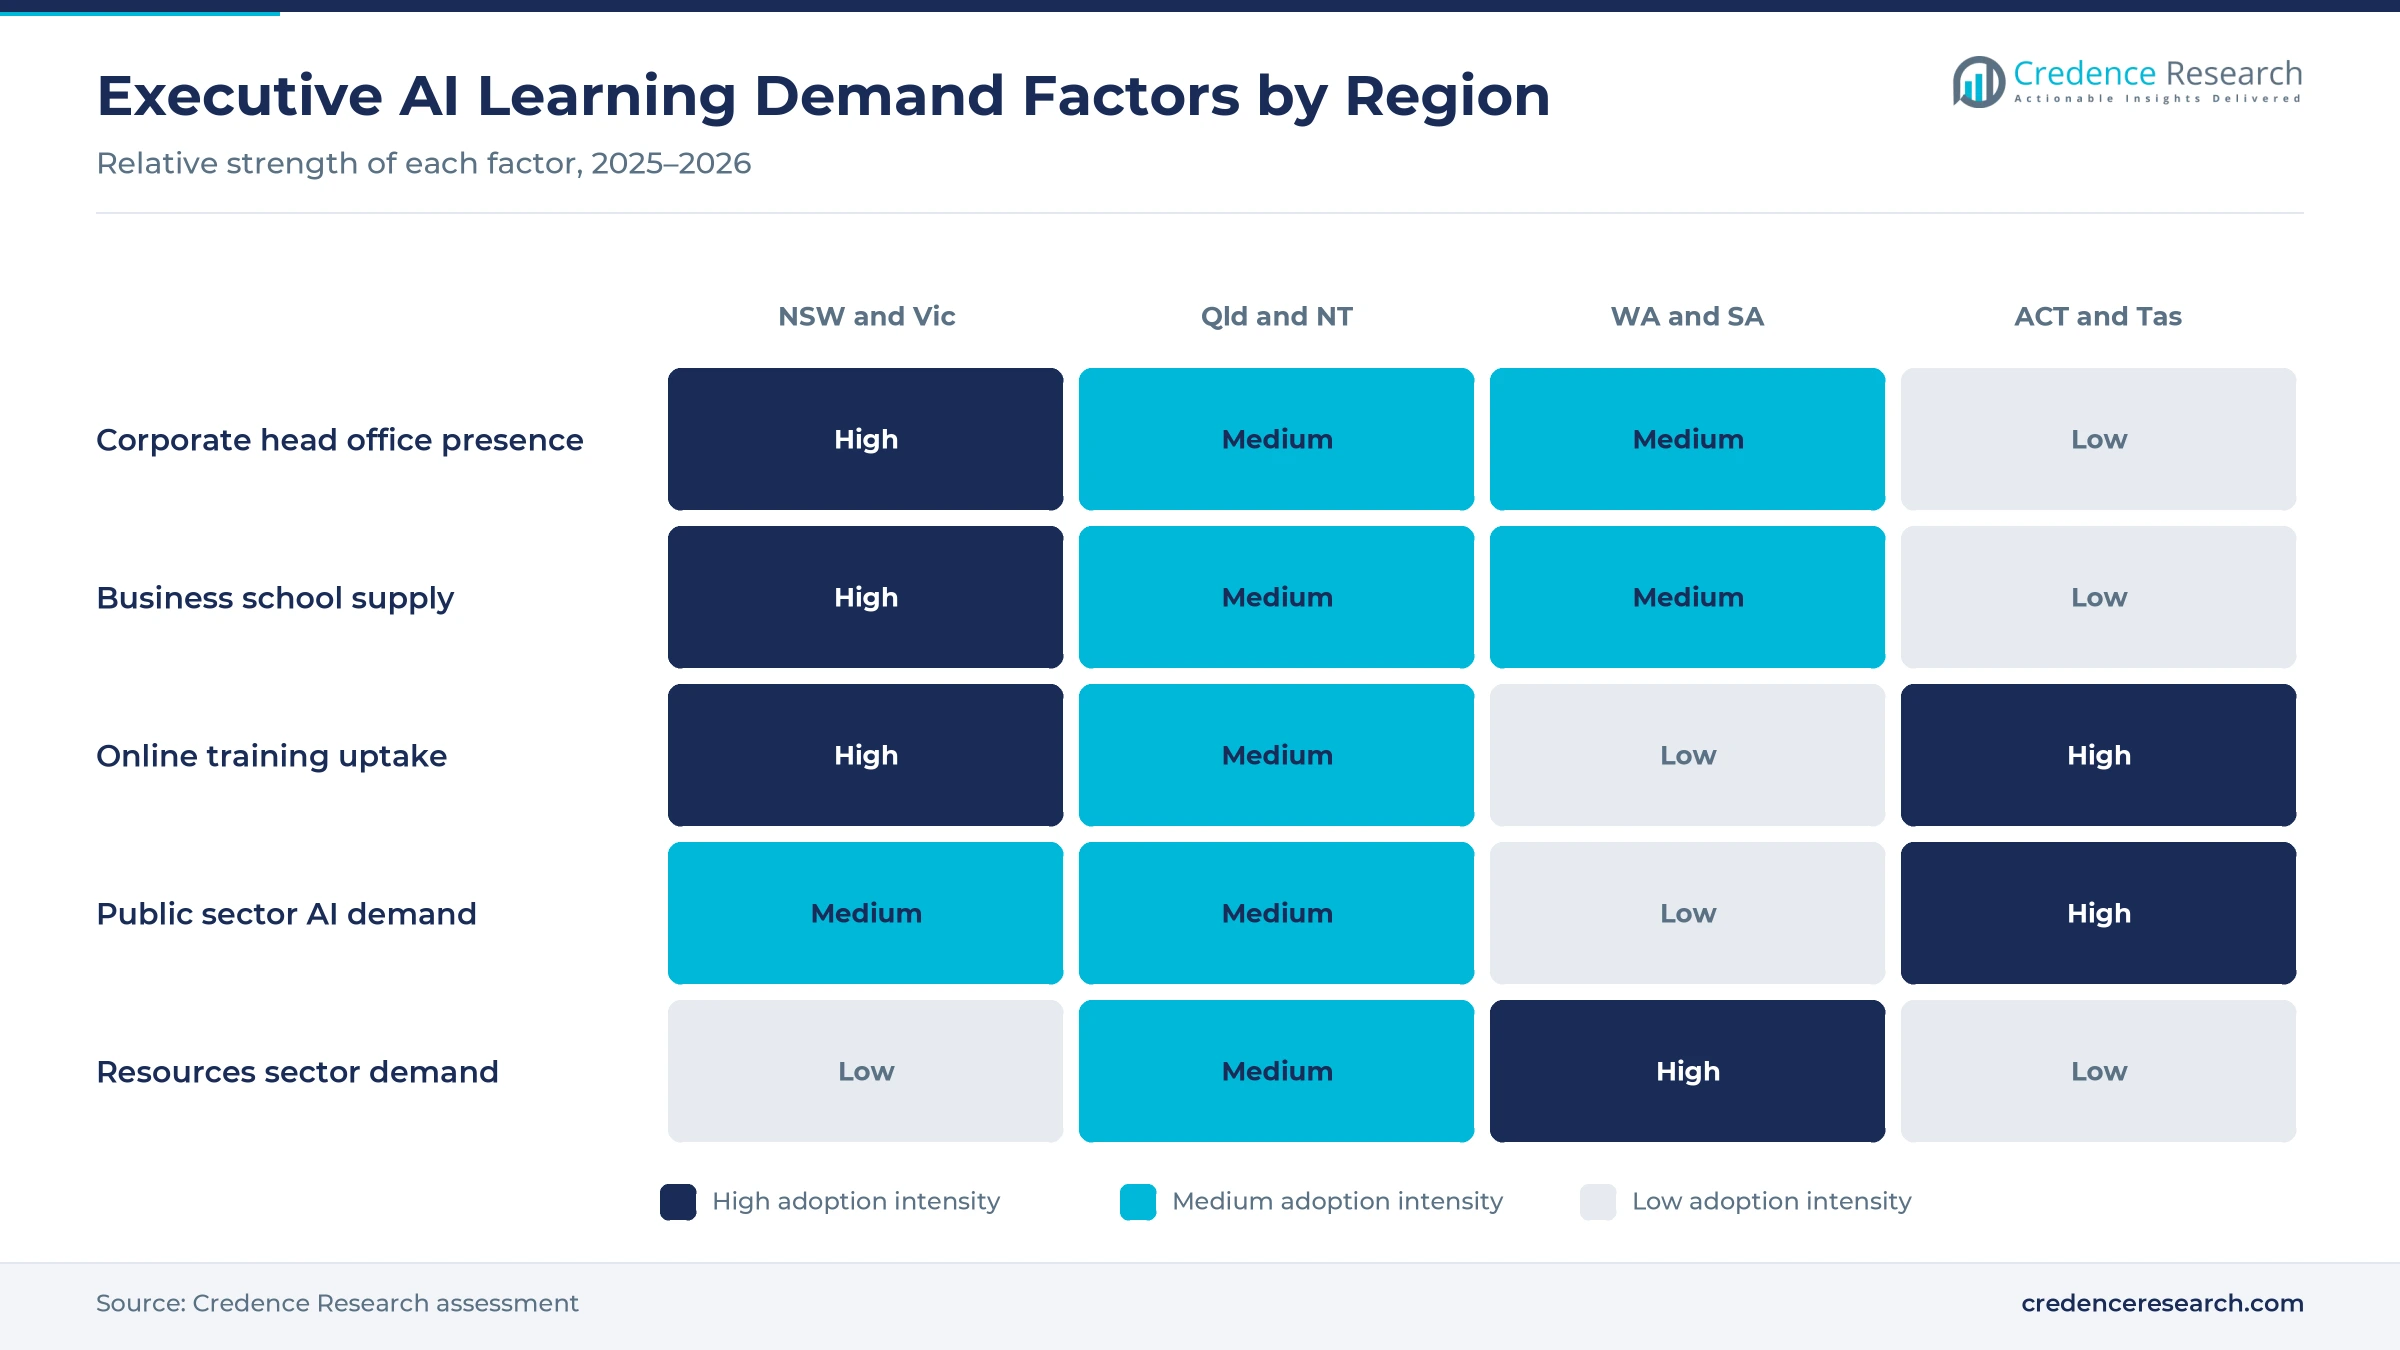
Employers want leaders and senior specialists who can turn AI pilots into working processes, which pushes them to fund applied programs rather than general awareness sessions. Demand for AI-skilled workers has tripled since 2015, according to the National AI Plan released on Dec. 2, 2025. The Reserve Bank of Australia found that about two-thirds of 105 surveyed firms had adopted AI in some form, while many reported difficulty finding data engineers and scientists, according to its Nov. 13, 2025, Bulletin. The Institute of Applied Technology's AI microcredential courses have also passed 150,000 enrollments, which shows how quickly short AI learning formats are being taken up. As a result, Technical Analytics Education grows at 12.92% a year.
How do governance duties create leadership learning needs?
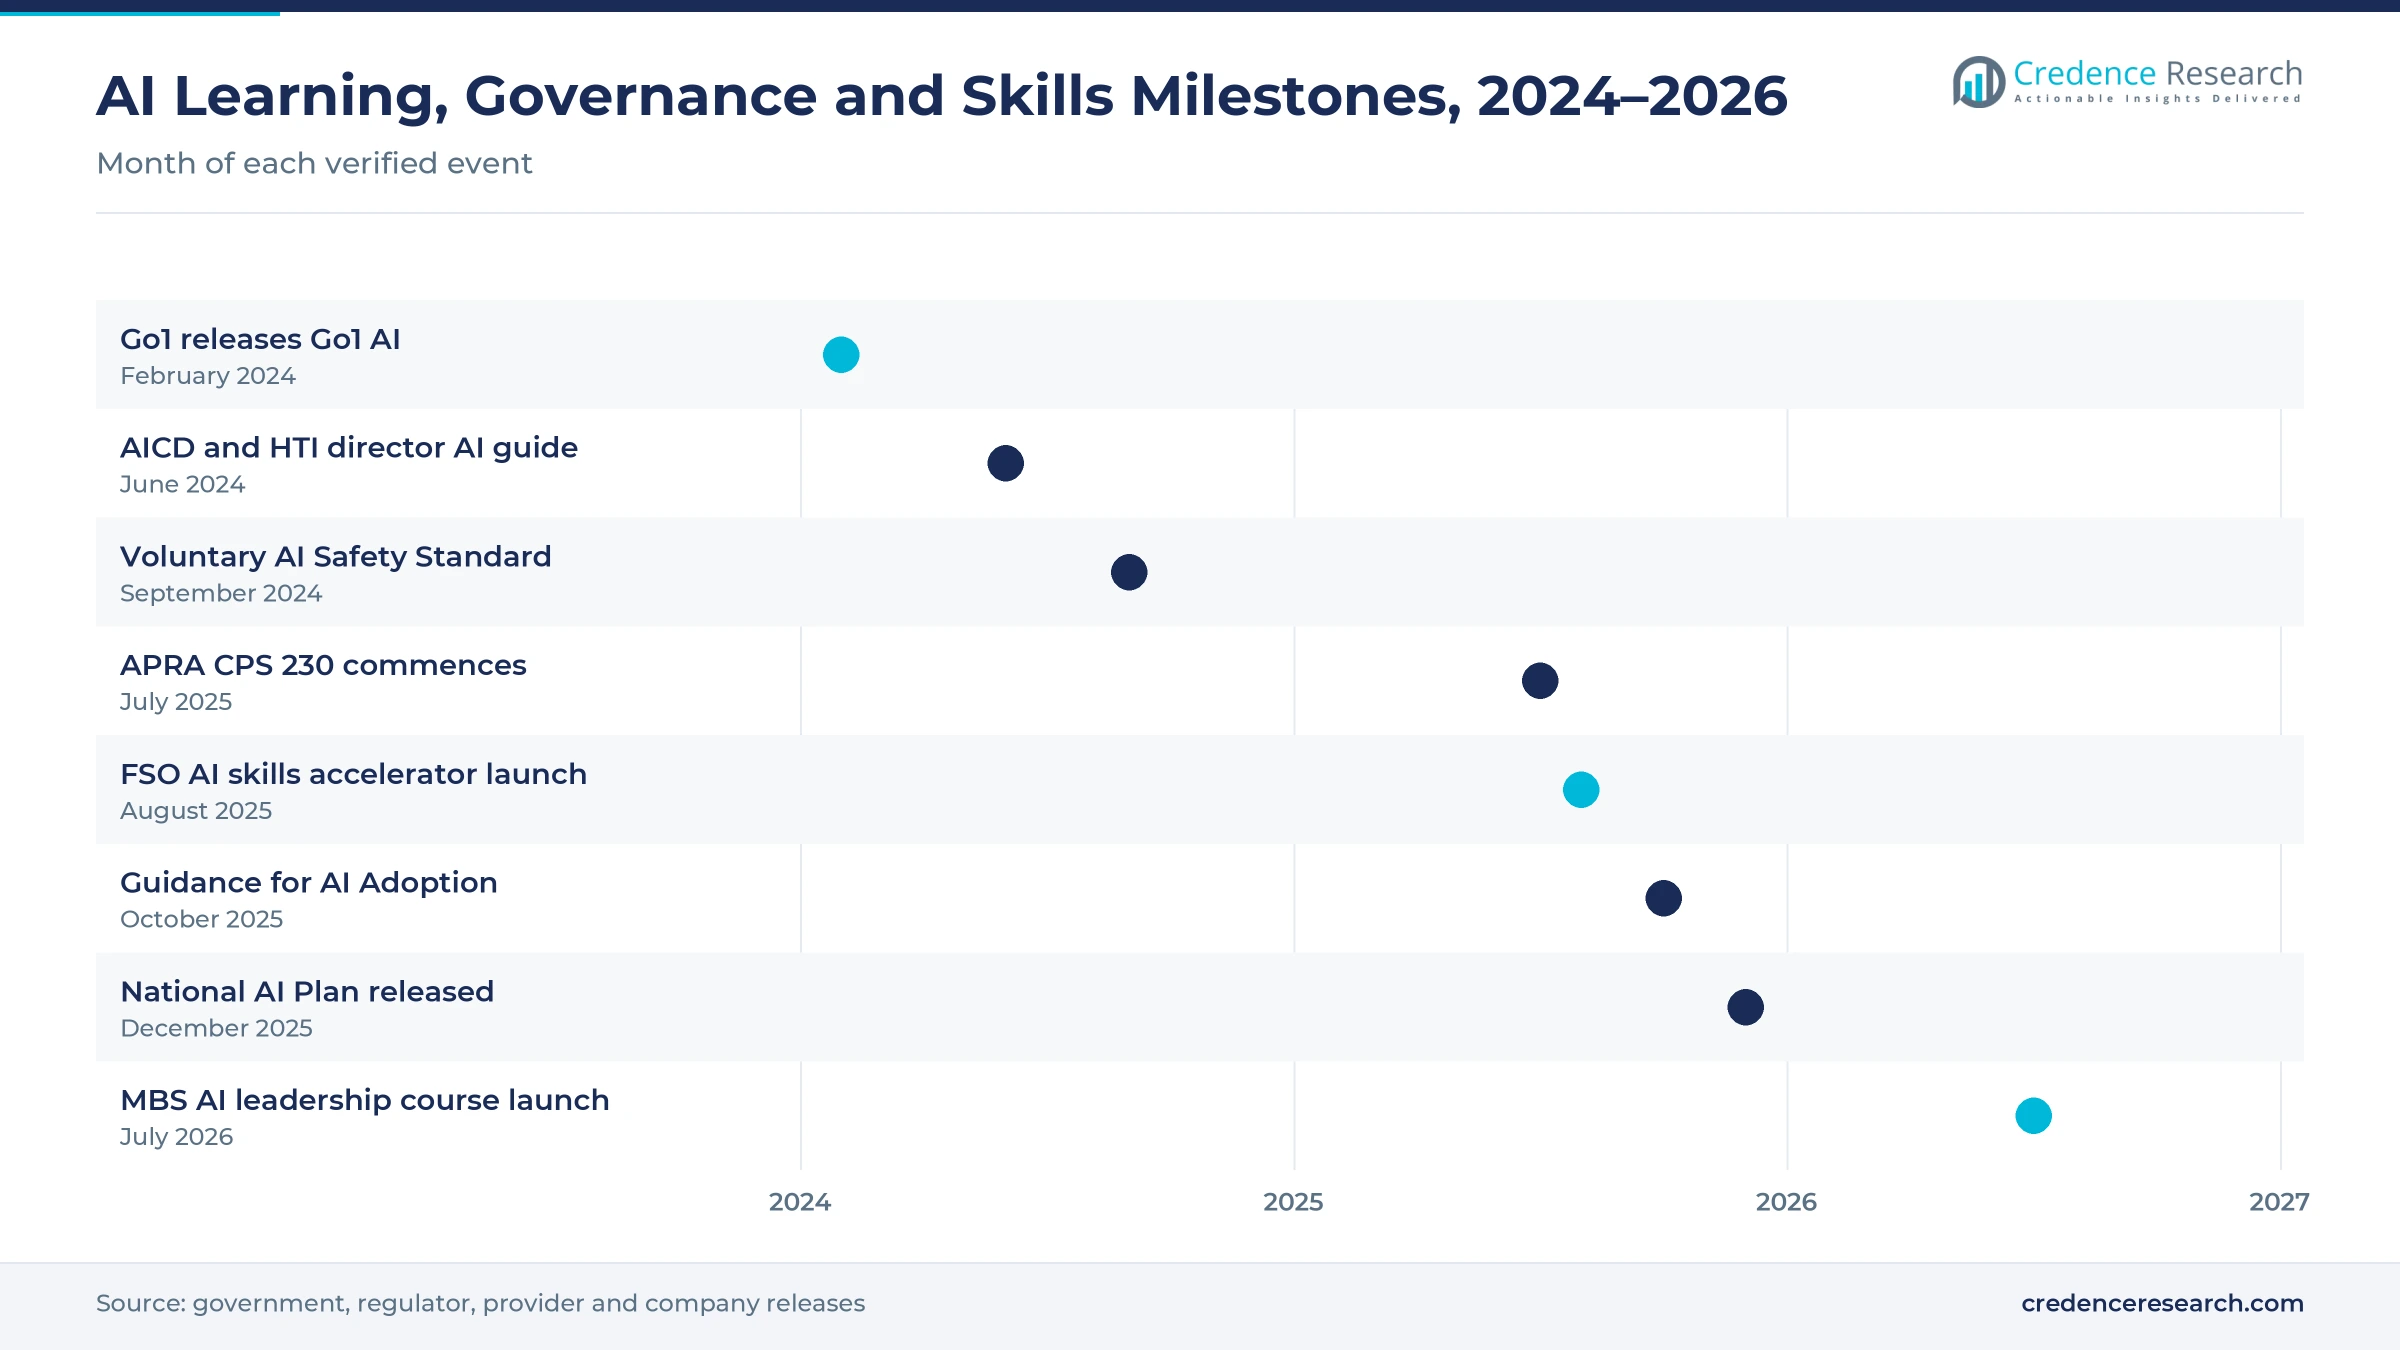
Directors and executives now carry clearer responsibilities for how AI is used, which turns governance knowledge into a board-level training need. The Australian Institute of Company Directors and the Human Technology Institute released a director's guide to AI governance on June 12, 2024, after finding that many directors had limited understanding of where their organizations used AI. The Voluntary AI Safety Standard set out 10 guardrails on Sept. 5, 2024, and the Guidance for AI Adoption evolved it into six essential practices on Oct. 21, 2025. APRA's CPS 230 operational risk standard, which makes boards ultimately accountable for operational risk, commenced on July 1, 2025. In turn, Board and C-Suite Leaders grow at 13.00% a year.
How do established employer learning budgets support conversion?
Most work-related training in Australia is already funded outside the learner's own pocket, which makes it easier for providers to convert interest into paid AI enrollments. About 3.7 million people, or 19% of those aged 15 to 74, did work-related training in 2024-25, according to the Australian Bureau of Statistics. Only 17% of people paid personal costs for their most recent training, and the share was 11.8% among managers. Managers and professionals are also frequent learners, with 47.9% of managers and 56.7% of professionals completing three or more courses. As a result, Senior and Functional Managers hold 46.0% of 2025 value.
How do cloud vendor skilling pledges widen the learner base?
Large cloud vendors are funding AI skills programs in Australia, which builds a pipeline of professionals who later buy deeper leadership and technical courses. Microsoft committed to train an additional 300,000 Australians alongside an AUD 5 billion infrastructure investment announced on Nov. 16, 2023, according to the Prime Minister's office. Amazon said AWS has trained more than 400,000 people in Australia since 2017, in its June 2025 release on an AUD 20 billion data center plan for 2025 to 2029. Microsoft also became founding partner of the Future Skills Organisation's AI skills accelerator, launched on Aug. 13, 2025, targeting more than 30,000 vocational educators. In turn, vendor training widens the pool of Experienced Technical Professionals who are ready for advanced leadership and technical programs.
Blended formats, AI curation and public sector demand rise
How is the shift to blended delivery changing program design?
Providers are shifting from single campus formats to blended programs that combine short in-person sessions with online modules, which suits leaders who travel or work across states. In 2024-25, 49% of people who did work-related training took their most recent course online or virtually, down from 55% in 2020-21, so face-to-face time still matters. Internet use reached 96.1% of Australians in 2024, according to the World Bank, which supports reliable online delivery. AGSM at UNSW runs AI for Business Leaders as a two-day Sydney course or a four-week online program, while Melbourne Business School offers a three-day or five-week format. As a result, Blended Delivery grows at 12.87% a year.
Why are AI-curated learning libraries rising in enterprises?
Enterprise learning platforms are adding AI search and curation, which lets employers assemble technology programs for each manager without building every course themselves. Go1 released Go1 AI on Feb. 7, 2024, with AI search, chat and playlists drawn from more than 130,000 courses, according to Business Wire. The Queensland-based company had about 10,000 organizational customers when it acquired the AI curation firm Anders Pink in January 2023, according to Business News Australia. Udemy reported that AI-related enrollments in Australia rose 61% in its fourth-quarter 2024 index, while leadership course enrollments rose 39%, according to ChannelLife. In turn, these libraries increasingly sit inside learning management systems that employers already run.
Can public sector AI plans open a new buyer group?
Federal agencies now have a formal AI capability agenda, which opens an opportunity for providers that can train senior public servants at scale. The AI Plan for the Australian Public Service, issued on Nov. 12, 2025, sets 15 initiatives across trust, people and tools pillars. It commits every public servant to foundational training on using generative AI safely and responsibly, and it creates Chief AI Officer roles to lead adoption. The Digital Transformation Agency also ran a six-month Microsoft 365 Copilot trial for the public service from January to June 2024, with training and onboarding support. As a result, Australian Capital Territory and Tasmania grows at 12.88% a year.
Is there room to serve regional and smaller business leaders?
Smaller and regional firms lag in AI adoption, which creates an opening for affordable programs aimed at owners and senior managers outside capital cities. Only 29% of regional organizations are adopting AI, compared with 40% in metropolitan areas, and 26% of regional businesses are unaware of AI opportunities, according to the National AI Plan. The plan also notes that over one-third of small and medium businesses have adopted AI and that the AUD 17 million AI Adopt Program will move into the National AI Centre. RMIT Online sells a four-week AI for Business Leaders course for AUD 750, which shows lower price points are emerging. In turn, Open-Enrolment Short Courses keep a broad base, building on demand for professional upskilling online.
Time, cost and proof of return slow enrollment growth
How do time and cost barriers limit enrollments?
Leaders who want more training often cannot fit it around work, which caps the number of seats employers can fill. Among people who wanted work-related training but faced barriers in 2024-25, 44% cited too much work or not enough time, and 26% cited financial reasons. As a result, multi-day programs struggle to recruit senior staff. Providers respond with shorter modules, evening sessions and online formats that reduce time away from work.
Why does fast-changing AI content raise delivery costs?
AI tools and model capabilities change within months, so course material on platforms, risks and use cases dates quickly. Providers must refresh case studies, labs and assessment tasks several times a year to stay credible with technical buyers. In turn, faculty and content costs rise faster than course fees. Free vendor training from cloud providers also anchors price expectations, so paid programs must offer deeper strategy, governance and applied project work.
How does unclear return on AI spending affect budgets?
Employers want proof that training changes how AI is used, yet many still see limited returns from AI itself. The Reserve Bank of Australia reported that returns from AI were mixed and that adoption was often employee-led rather than employer-led. As a result, learning teams face harder questions when they request funding for leadership programs. Providers respond by building applied projects and measurable outcomes into custom cohorts.
Why is experienced faculty hard to secure?
Programs need teachers who understand both AI systems and executive decision making, and that mix is scarce in Australia. Firms already report difficulty hiring data engineers and scientists, so universities and trainers compete with employers for the same experts. In turn, providers rely on adjunct practitioners whose availability is limited. Schools respond by partnering with technology vendors and specialist platforms to extend teaching capacity.
Head offices lead while Queensland and NT grow fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Victoria | 212.6 | 53.9% | 12.33% |
| Western Australia and South Australia | 84.8 | 21.5% | 12.13% |
| Queensland and Northern Territory | 79.7 | 20.2% | 12.93% |
| Australian Capital Territory and Tasmania | 17.4 | 4.4% | 12.88% |
New South Wales and Victoria lead on schools and head offices
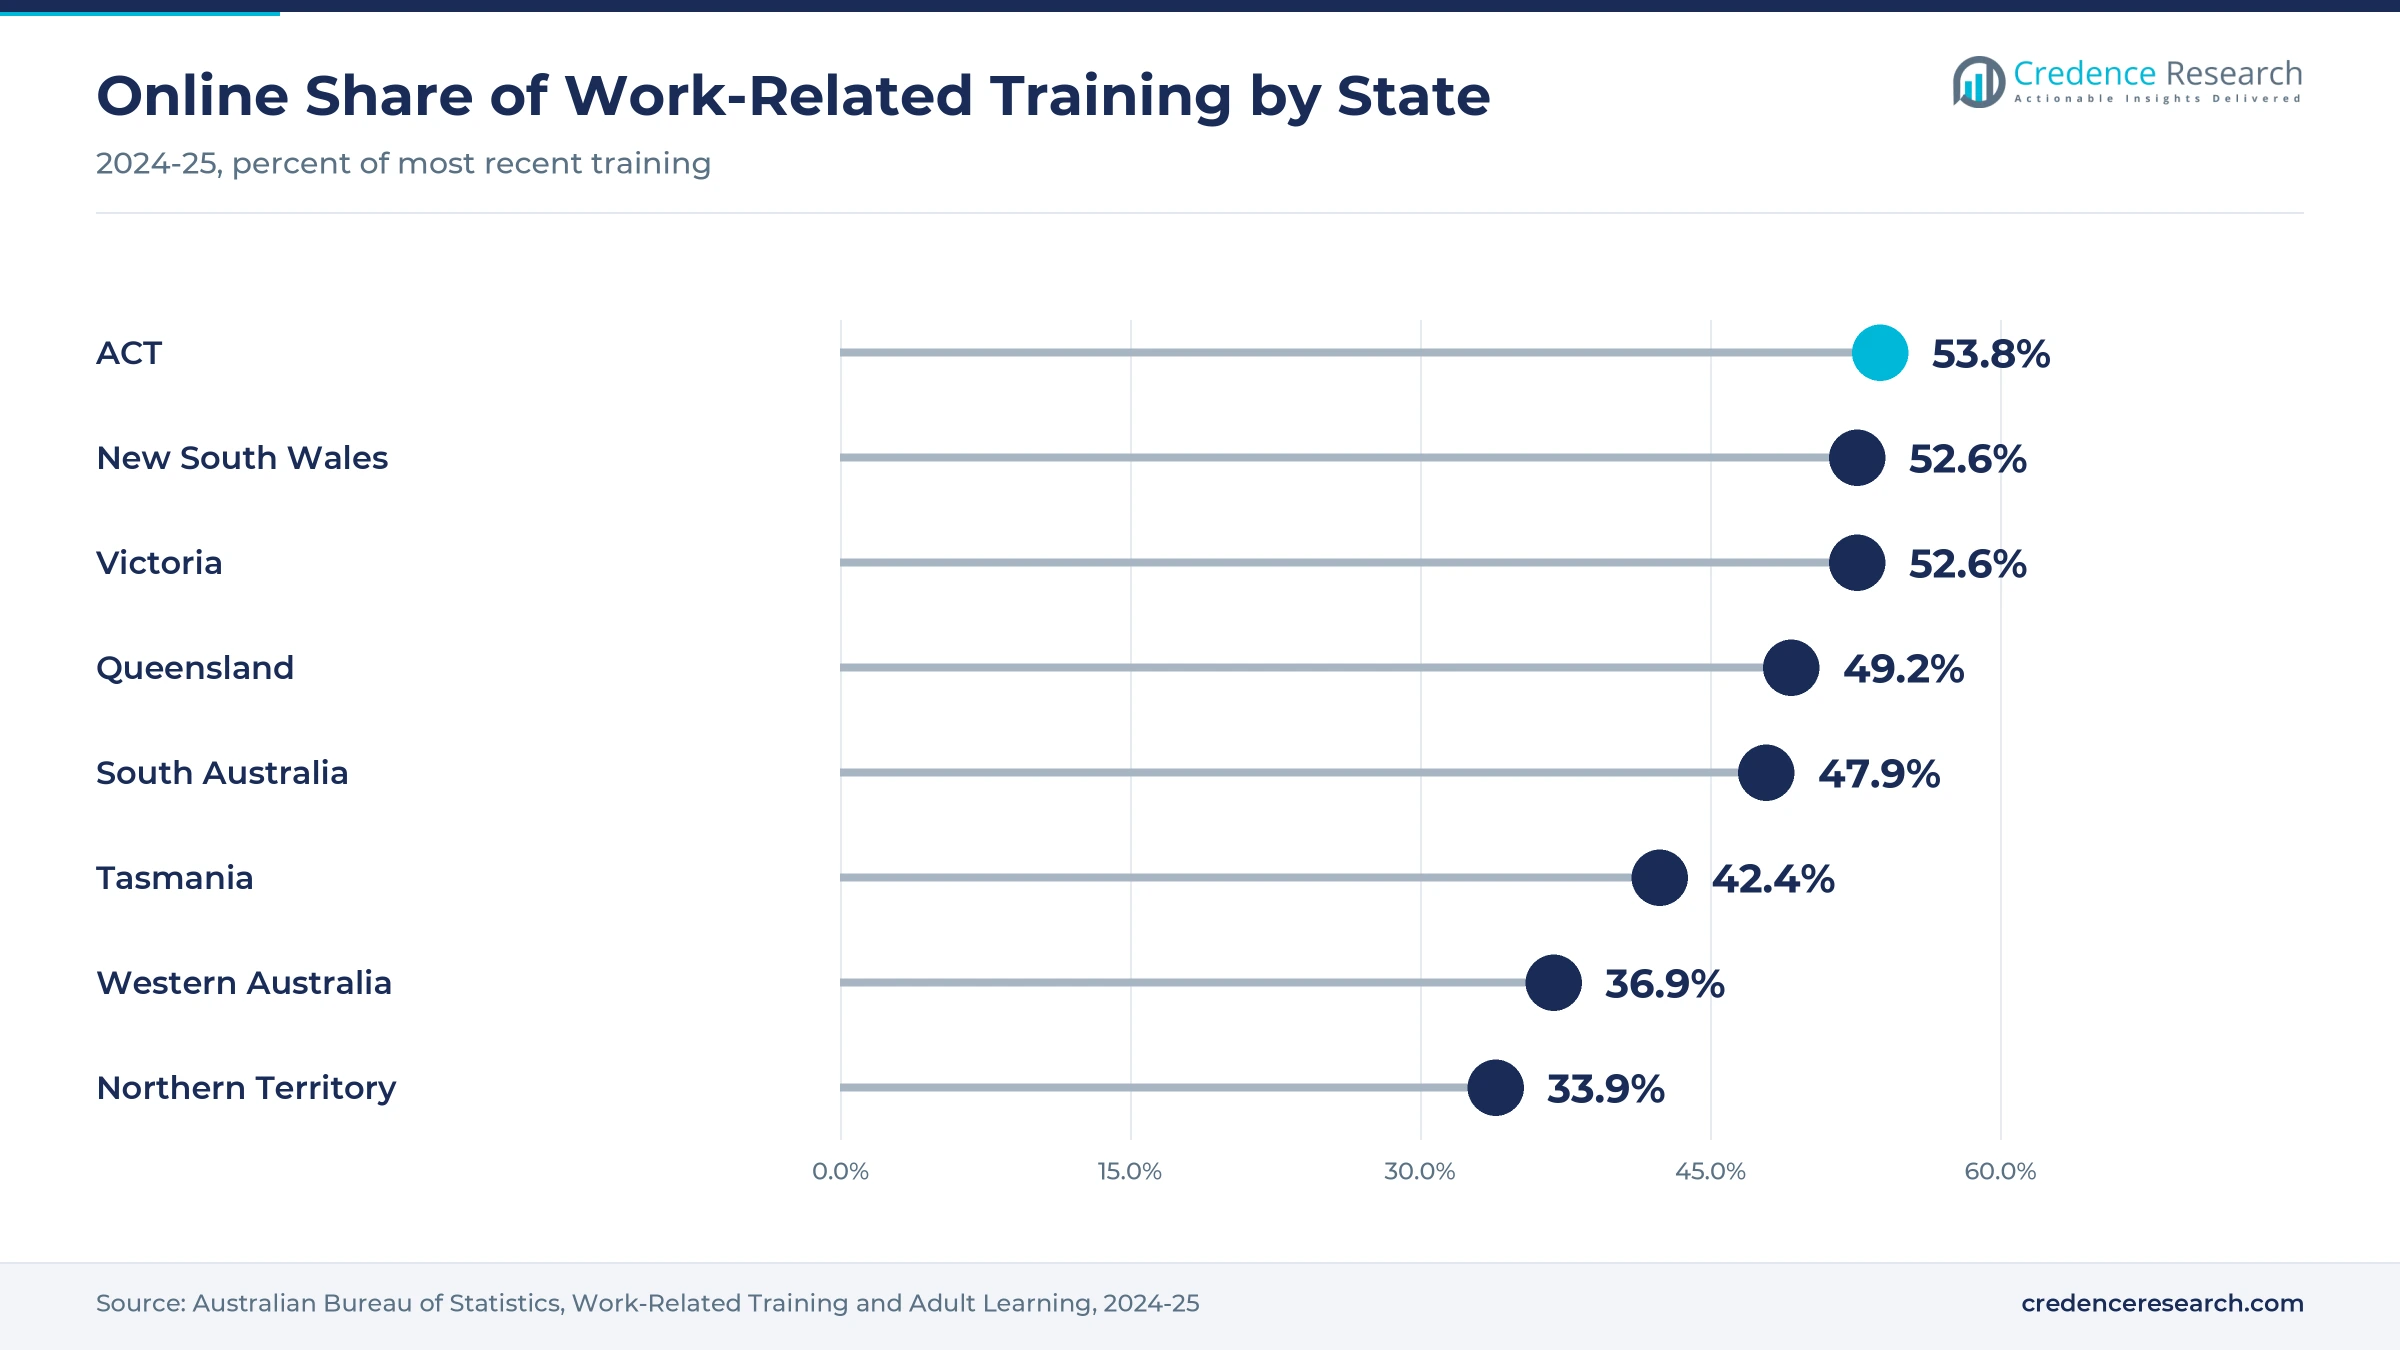
New South Wales and Victoria held a 53.9% share of 2025 value and grow at 12.33% a year. Sydney hosts AGSM at UNSW Business School, while Melbourne hosts Melbourne Business School in Carlton and RMIT Online. Both states also lead online uptake, with 52.6% of work-related training in each delivered online or virtually in 2024-25. As a result, banks, insurers and listed companies in the two capitals buy most custom cohorts and board programs.
Platform growth puts Queensland and Northern Territory ahead
Queensland and Northern Territory held a 20.2% share of 2025 value and grows fastest at 12.93% a year. Queensland is home to Go1, the enterprise learning platform, and Lumify runs a Brisbane campus for technology training. Online delivery reached 49.2% of work-related training in Queensland in 2024-25, close to the national level. In turn, service firms and public agencies in Brisbane can draw on a local platform provider and campus training for managers.
Western Australia and South Australia favor classroom formats
Western Australia and South Australia held a 21.5% share of 2025 value and grow at 12.13% a year. Western Australia shows the strongest preference for classroom learning, with 60% of work-related training delivered face-to-face and 36.9% online in 2024-25. Lumify Group lists technology training campuses in both Perth and Adelaide for local employers. As a result, resources and engineering employers favor in-person and blended cohorts for technology managers.
Public service demand shapes the ACT and Tasmania
Australian Capital Territory and Tasmania held a 4.4% share of 2025 value and grows at 12.88% a year. The Australian Capital Territory had the highest online share of work-related training at 53.8% in 2024-25, while Tasmania recorded 42.4%. Canberra concentrates the federal public service, which now has a dedicated AI plan for its workforce. In turn, public sector demand drives most new spending in this region.
AI courses, skills pledges and governance guides, 2024–2026
| Development | Status and market relevance |
|---|---|
| In February 2024, Go1 released Go1 AI with AI search, chat and playlists drawn from more than 130,000 courses. | Brings AI curation to enterprise learning libraries |
| In June 2024, the Australian Institute of Company Directors and the Human Technology Institute released AI governance resources for directors. | Sets a reference curriculum for board education |
| In June 2025, Amazon announced an AUD 20 billion data center investment in Australia for 2025 to 2029. | Expands AWS skills and AI adoption programs locally |
| In August 2025, the Future Skills Organisation and Microsoft launched a 12-month AI skills accelerator pilot. | Targets more than 30,000 vocational educators and administrators |
| In July 2026, Melbourne Business School launched Leading Strategically with AI in three-day and five-week formats. | Adds hands-on agent building to executive programs |
Agent labs, curated libraries and digital credentials spread
- Agent-building labs let executives build and test simple AI agents during a program, as Melbourne Business School does in its three-day AI strategy course.
- AI-curated content libraries match courses to each manager's goals and skills gaps, drawing on large catalogs such as the 130,000 courses behind Go1 AI.
- Digital cohort platforms combine self-paced modules with live workshops and peer forums, as AGSM does through its Navigator platform for online programs.
- Digital credentials and assessment record completed modules toward stackable awards, supported by online assessment software that checks applied project work.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Business schools, specialists and platforms split the field
Competition is split between business schools, specialist trainers, enterprise platforms and technology vendor academies. Melbourne Business School and AGSM at UNSW Business School compete on faculty, brand and board-level governance content, with short courses priced in the thousands of dollars. RMIT Online and Academy Xi sell shorter, practical AI courses to managers and technical teams who want applied skills quickly. Lumify Group runs vendor-aligned technology training from campuses across Australian capitals. Go1, Coursera for Business and Udemy Business sell subscription libraries that employers use to reach large numbers of staff. AWS Training and Certification and Microsoft Learning offer free and paid vendor courses that build cloud and AI skills across large learner groups. Providers compete on applied projects, credential value, cohort customization and the ability to tie lessons to an employer's own AI governance needs.
Which providers shape executive AI learning in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Melbourne Business School | Business school | Runs Leading Strategically with AI program |
| AGSM at UNSW Business School | Business school | Offers AI for Business Leaders course |
| RMIT Online | University online arm | Sells four-week AI for Business Leaders |
| Lumify Group | Specialist training provider | Partner in FSO AI skills accelerator |
| Academy Xi | Specialist training provider | Delivers AI training for banks and agencies |
| Go1 | Enterprise learning platform | Queensland-based, launched Go1 AI curation |
| Coursera for Business | Enterprise learning platform | Platform data covered 1.1 million Australian learners |
| Udemy Business | Enterprise learning platform | Reported 61% rise in Australian AI enrollments |
| AWS Training and Certification | Technology academy | Trained over 400,000 people in Australia since 2017 |
| Microsoft Learning | Technology academy | Committed to train 300,000 more Australians |
Governance duty will outlast the AI tool hype cycle
Credence Research's view is that the Australia executive education in technology and artificial intelligence market will keep growing well after the current wave of AI tool launches slows. Governance duties for boards, operational risk rules and new transparency obligations make AI literacy a lasting leadership requirement rather than a passing trend. Providers that combine governance content with applied projects and custom cohorts are best placed, while generic awareness courses will face price pressure from free vendor training and subscription libraries.
Model built from training, labor and policy statistics
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model draws on national training and labor statistics, government AI policy documents, central bank research, regulator releases, published course formats and prices, and company announcements on programs and skills pledges. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are official statistics, government documents, provider websites, trade press and company releases, and no interviews or surveys were used.
Custom cohorts and blended formats gain share by 2035
The Australia executive education in technology and artificial intelligence market is expected to reach USD 1.27 billion by 2035, a 12.44% CAGR during 2026–2035, as AI moves from pilots into core operations. Custom Corporate Cohorts and Blended Delivery should gain share as employers link learning to their own projects and risk controls. New automated decision transparency duties from Dec. 10, 2026, should add steady demand for governance programs. Slower AI returns or tighter employer budgets would hold back growth, while stronger national adoption targets would lift it.
Frequently Asked Questions
How big is the Australia executive education in technology and artificial intelligence market?
Which service type leads the Australian market?
Which region leads the Australian market?
Why are boards investing in AI governance education?
How much work-related training is delivered online in Australia?
Which learner segment grows fastest?
Who are the leading providers in this market?
What are the main challenges for providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Strategy and Governance Education
- 1.2.2 Technical Analytics Education
- 1.2.3 Digital Transformation Education
- 1.2.4 Technology Management Education
- 1.3 By Learner Segment
- 1.3.1 Board and C-Suite Leaders
- 1.3.2 Senior and Functional Managers
- 1.3.3 Experienced Technical Professionals
- 1.4 By Delivery Model
- 1.4.1 Online Delivery
- 1.4.2 Blended Delivery
- 1.4.3 In-Person Delivery
- 1.5 By Program Type
- 1.5.1 Open-Enrolment Short Courses
- 1.5.2 Custom Corporate Cohorts
- 1.5.3 Extended Credential Pathways
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 394.5 million → 2035: USD 1.27 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Executive Education in Technology and Artificial Intelligence Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Executive Education in Technology and Artificial Intelligence Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Executive Education in Technology and Artificial Intelligence Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Executive Education in Technology and Artificial Intelligence Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Executive Education in Technology and Artificial Intelligence Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Executive Education in Technology and Artificial Intelligence Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Executive Education in Technology and Artificial Intelligence Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Executive Education in Technology and Artificial Intelligence Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 394.5 million → 2035: USD 1.27 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Executive Education in Technology and Artificial Intelligence Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Strategy and Governance Education
- 12.3.7.2 Technical Analytics Education
- 12.3.7.3 Digital Transformation Education
- 12.3.7.4 Technology Management Education
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Learner Segment - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Board and C-Suite Leaders
- 12.4.7.2 Senior and Functional Managers
- 12.4.7.3 Experienced Technical Professionals
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Delivery Model - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Online Delivery
- 12.5.7.2 Blended Delivery
- 12.5.7.3 In-Person Delivery
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Program Type - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Open-Enrolment Short Courses
- 12.6.7.2 Custom Corporate Cohorts
- 12.6.7.3 Extended Credential Pathways
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Executive Education in Technology and Artificial Intelligence Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Executive Education in Technology and Artificial Intelligence Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Executive Education in Technology and Artificial Intelligence Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Lumify Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Go1
- 17.4 Melbourne Business School
- 17.5 AGSM at UNSW Business School
- 17.6 AWS Training and Certification
- 17.7 Microsoft Learning
- 17.8 Academy Xi
- 17.9 RMIT Online
- 17.10 Coursera for Business
- 17.11 Udemy Business
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

