
Record enrolments and state school builds lift upkeep needs
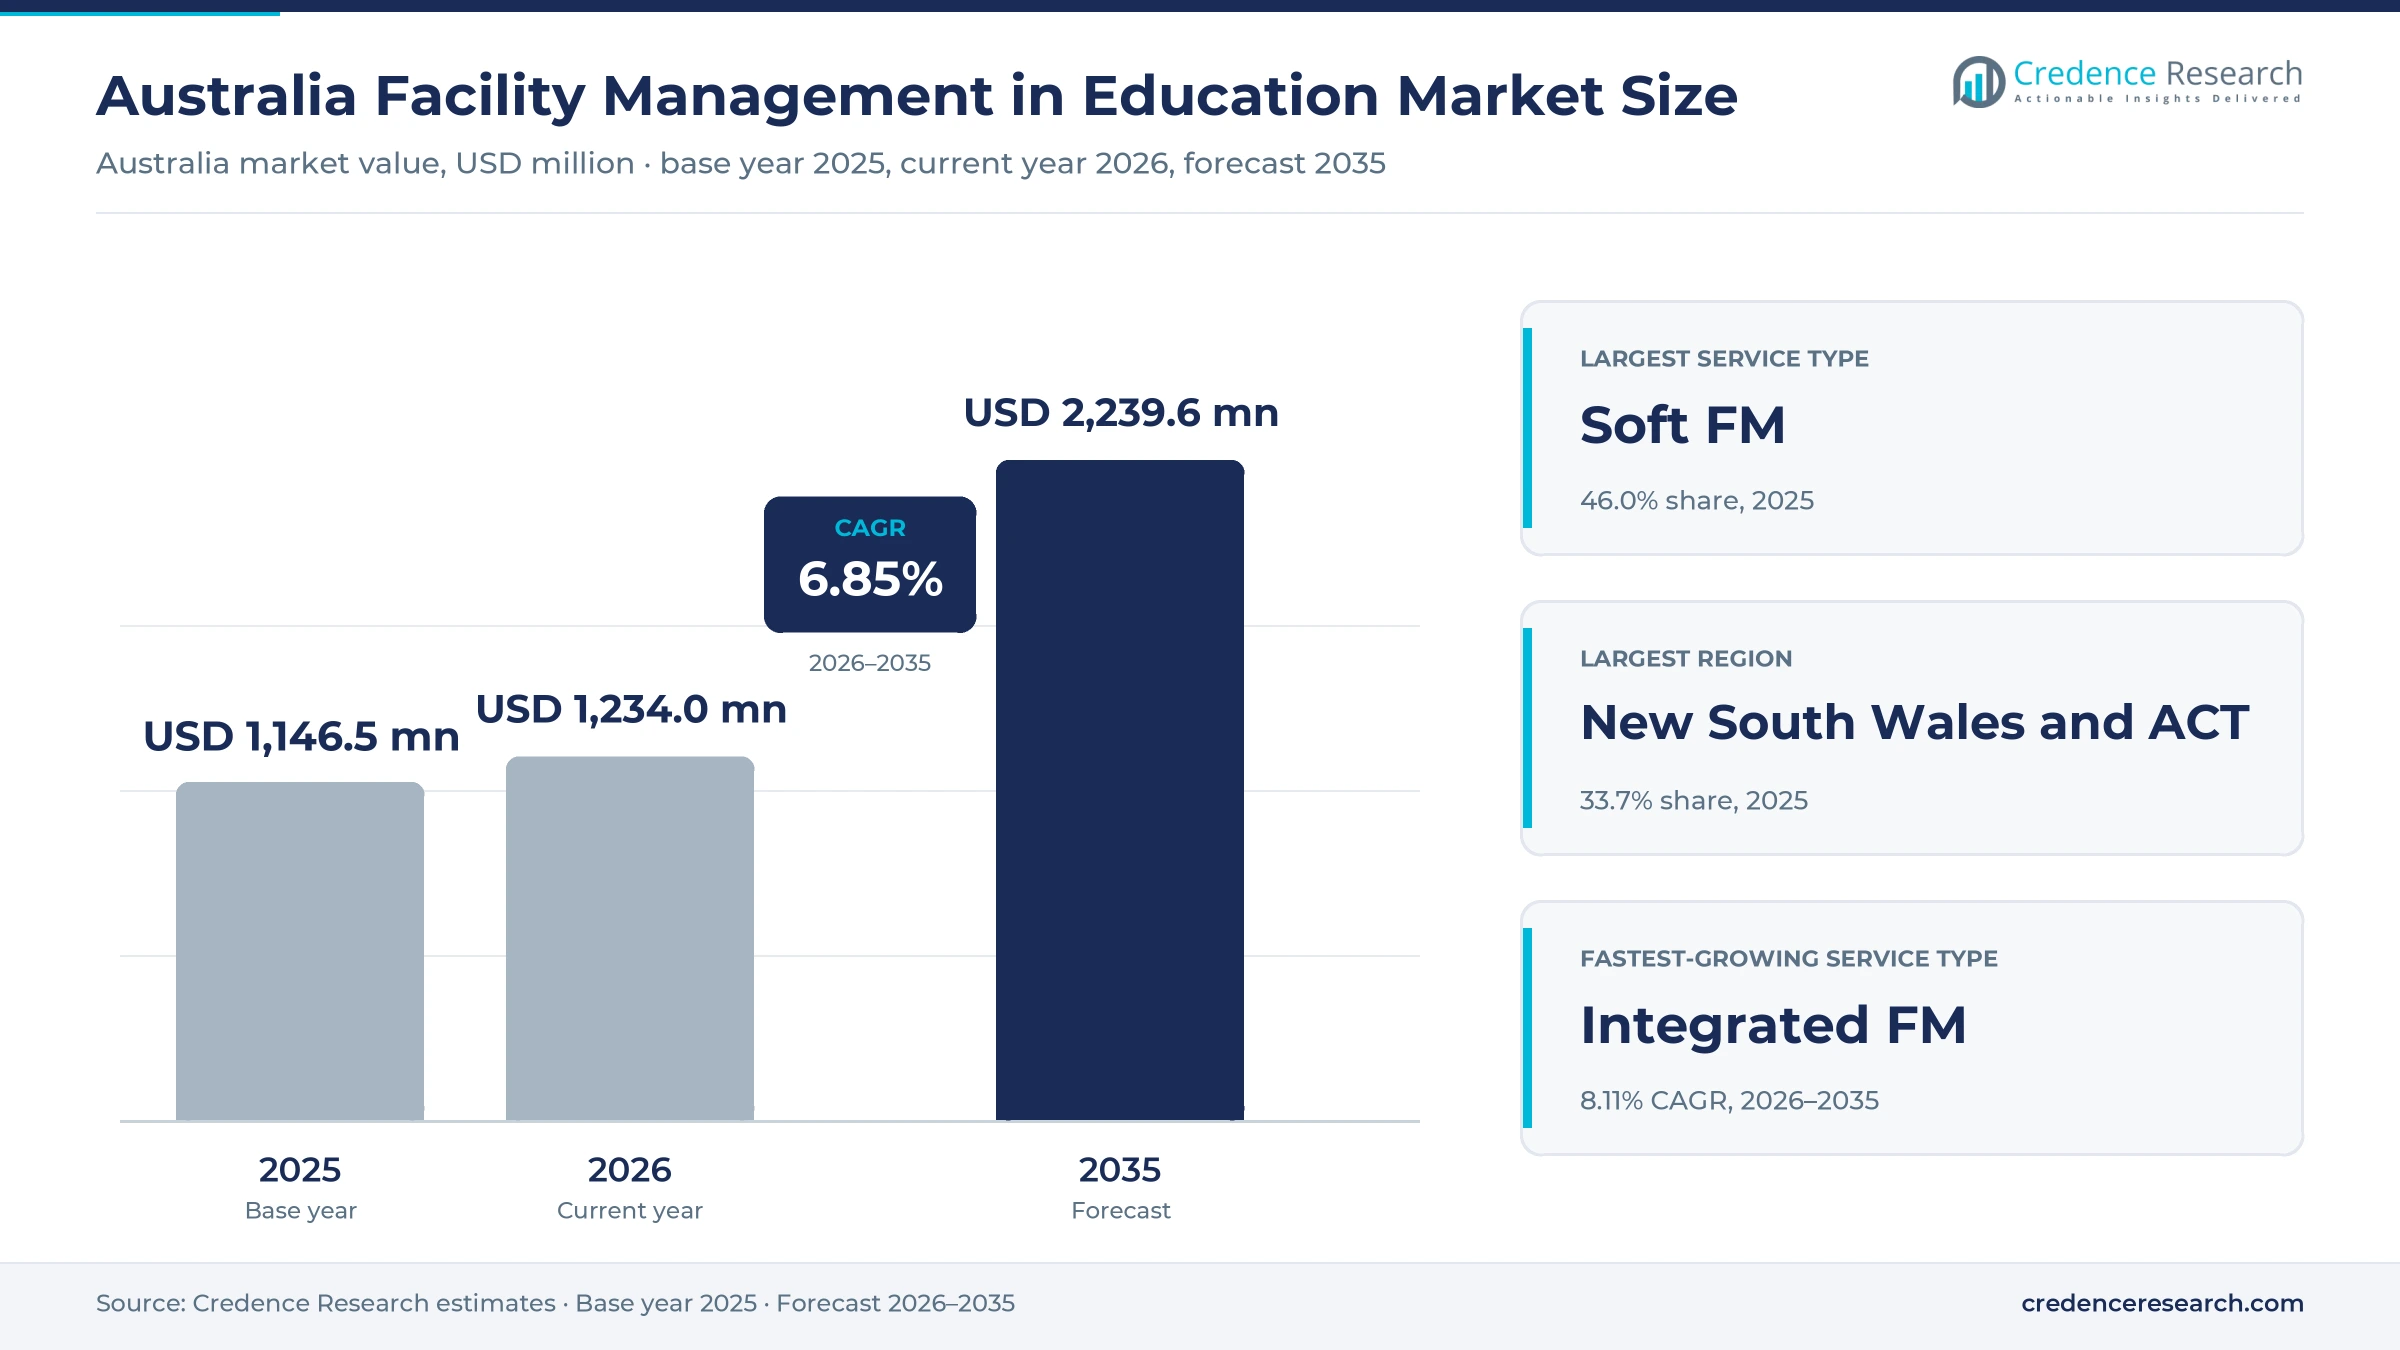
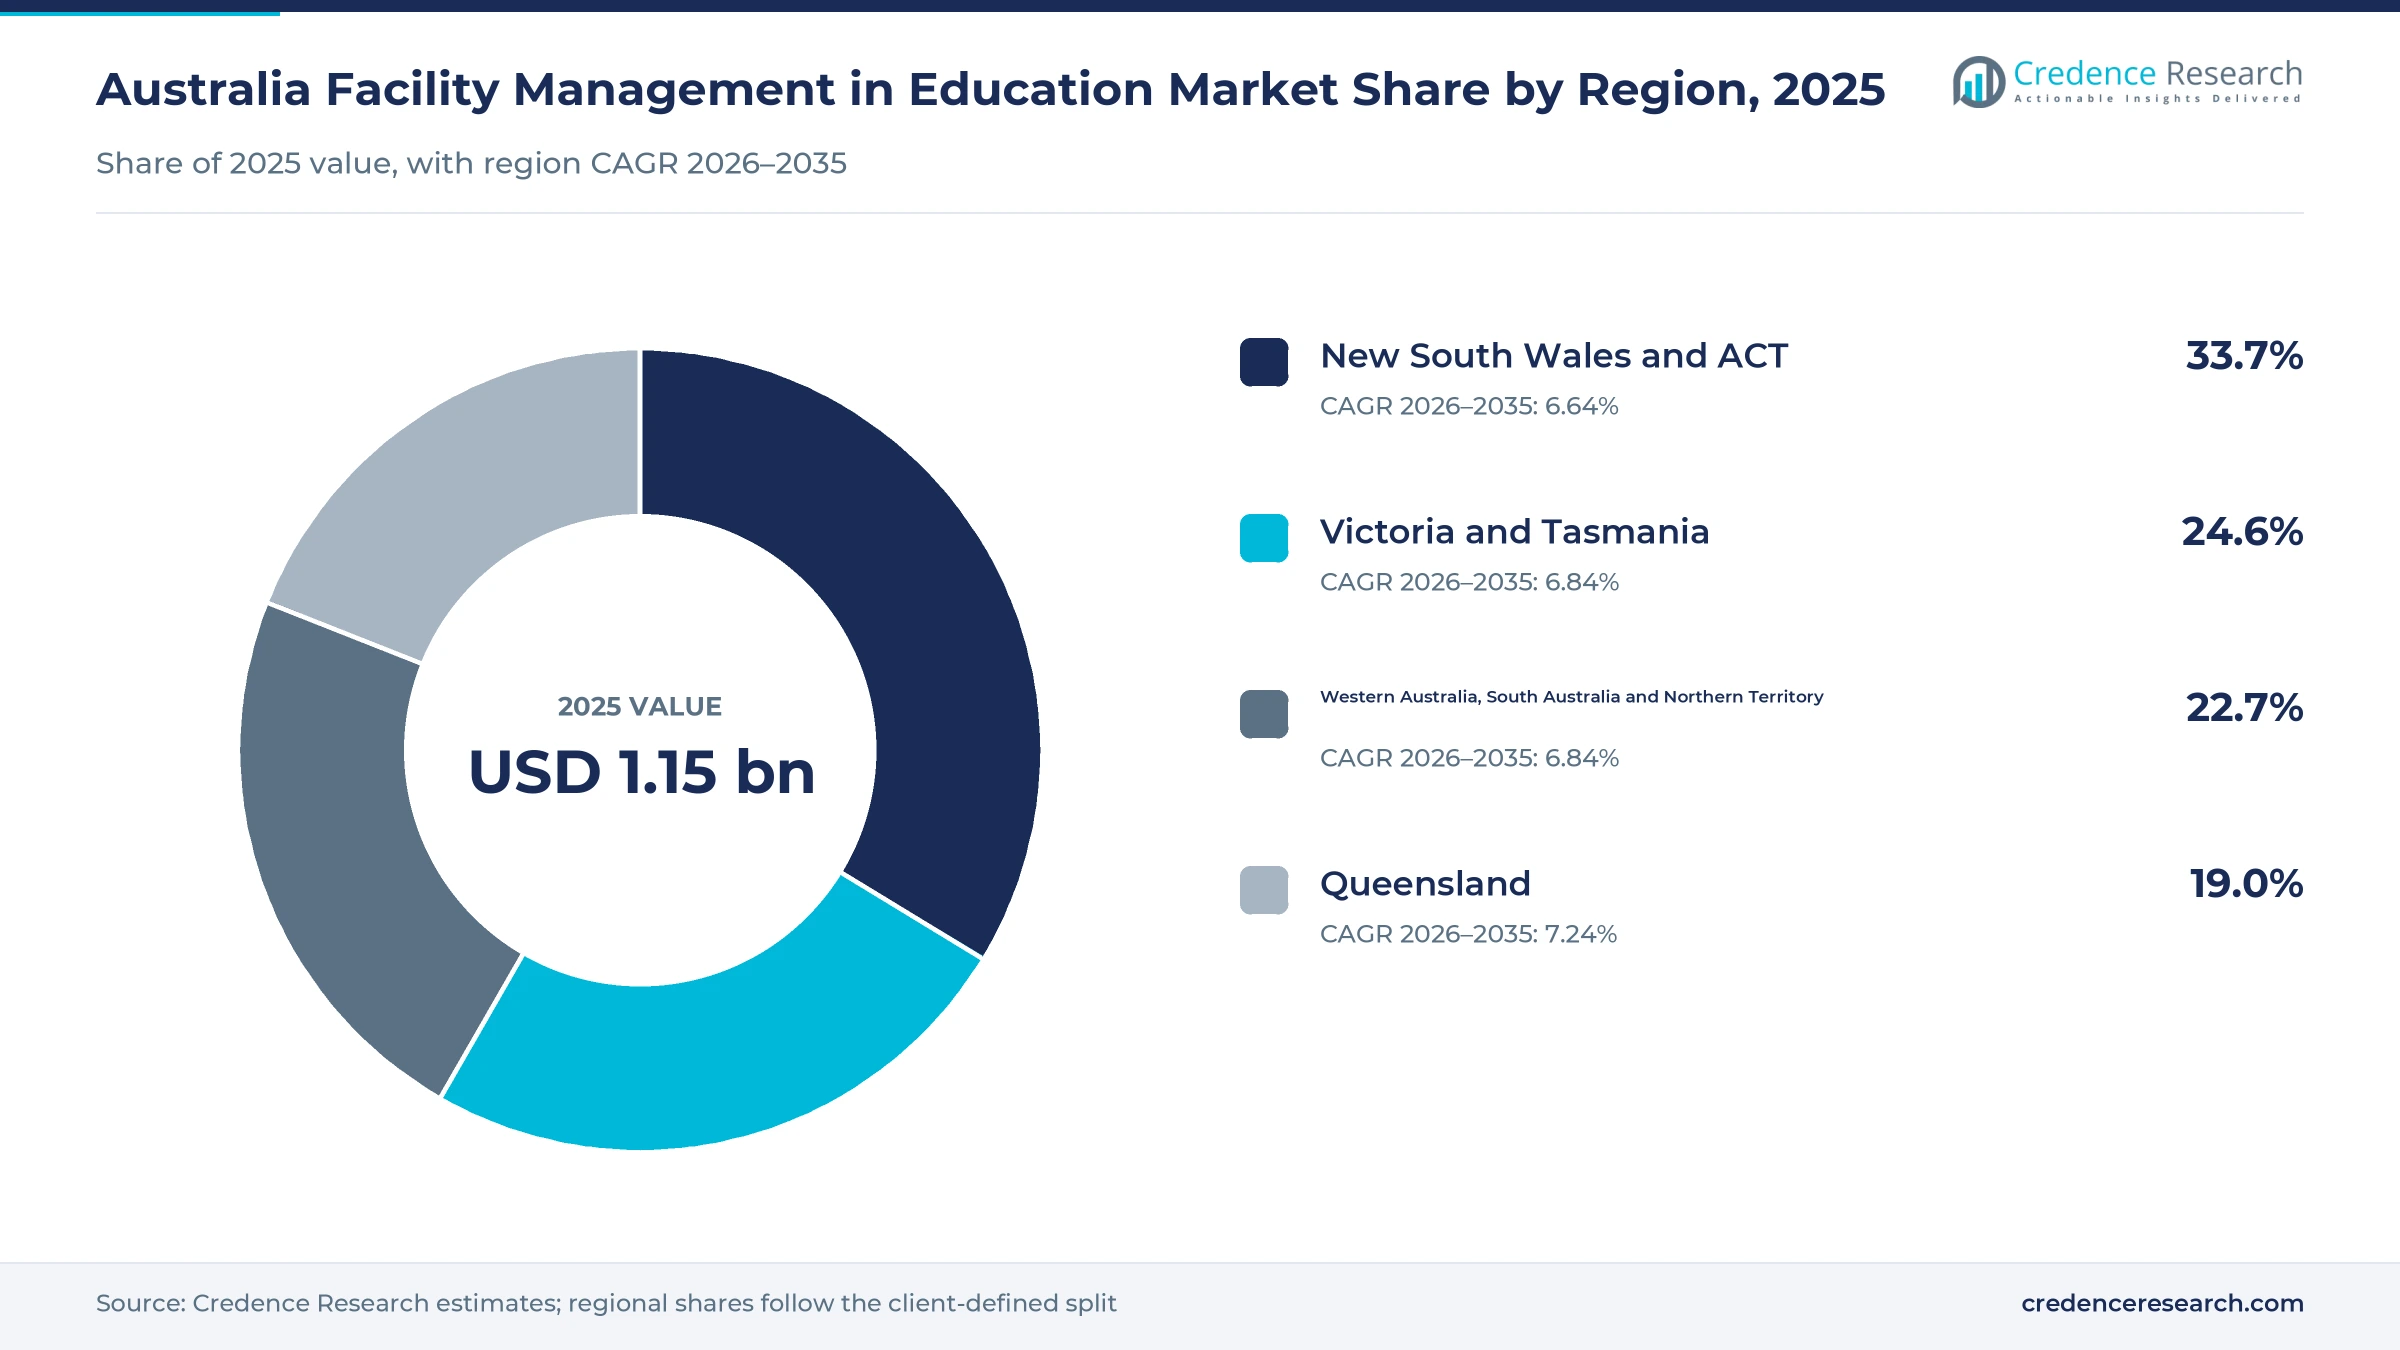
The Australia facility management in education market was valued at USD 1.15 billion in 2025 and is projected to increase from USD 1.23 billion in 2026 to USD 2.24 billion by 2035, registering a CAGR of 6.85% during 2026–2035. Demand comes from government and non-government schools that need daily cleaning, grounds care, security and repairs, and from universities and TAFE institutes that run large campuses with laboratories, workshops and student services. New South Wales and ACT held the largest regional share, 33.7% in 2025, because the zone has the most students and the largest public school estate. Queensland is the fastest-growing region at 7.24% a year, as the state opens new schools in fast-growing suburbs. In turn, state agencies are moving from school-by-school maintenance toward large regional contracts that bundle proactive and reactive work, which favors providers that can manage local trades across hundreds of sites.
Which school and campus services does the estimate cover?
The estimate measures the value of outsourced soft services such as cleaning, grounds care, security and waste handling, hard services such as mechanical, electrical, fire and plumbing maintenance, and integrated contracts that bundle both. It counts spending by government and non-government schools, universities and TAFE institutes in every state and territory.
The estimate excludes new construction, major capital works delivered under building contracts, and work done by in-house staff employed directly by schools or campuses. The value chain runs from education departments and campus estates teams through national service providers to the local trades and specialist subcontractors that carry out most site work.
Australia Facility Management in Education Market Insights
- The Australia facility management in education market was valued at USD 1.15 billion in 2025 and is projected to reach USD 2.24 billion by 2035, registering a CAGR of 6.85% during 2026–2035.
- New South Wales and ACT held a 33.7% share of 2025 value, because the zone has the largest number of enrolled students.
- Soft FM led with a 46.0% share of 2025 value, because cleaning, grounds care and security run every school day.
- The NSW Government committed a record AUD 9 billion over four years to school infrastructure in June 2025, which adds new floor area to maintain.
- Integrated FM grows fastest at 8.11% a year during 2026–2035, as universities and state agencies bundle services under fewer, larger contracts.
Soft services lead while integrated contracts grow fastest
Why do soft services hold the largest share?
Based on service type, the market is categorized into soft FM, hard FM and integrated FM. Soft FM led with a 46.0% share of 2025 value, because cleaning, grounds care and security are needed every day that students attend. Integrated FM grows fastest at 8.11% a year, as universities and state agencies combine maintenance, cleaning and helpdesk work under single contracts.
How do government schools and universities split demand?
Based on customer type, the market is categorized into government K-12 schools, non-government K-12 schools, universities and TAFE institutes. Government K-12 Schools led with a 44.0% share of 2025 value, because state departments manage the largest number of school sites. Non-Government K-12 Schools grow fastest at 7.43% a year, as independent and Catholic schools add students and buildings faster than the public system.
Why do self-delivered contracts still lead?
Based on operating model, the market is categorized into self-delivered contracts, subcontractor-managed contracts and hybrid delivery contracts. Self-Delivered Contracts led with a 41.0% share of 2025 value, because providers employ their own cleaners and technicians on most campus contracts. Hybrid Delivery Contracts grow fastest at 7.43% a year, as agencies ask lead contractors to combine their own staff with local trades.
How do tenders and panels reach education buyers?
Based on sales channel, the market is categorized into open tender procurement, panel procurement and direct negotiation. Open Tender Procurement led with a 47.0% share of 2025 value, because public agencies and universities must test the market for large contracts. Panel Procurement grows fastest at 7.47% a year, as state departments appoint regional contractors that then call on approved local trades.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Soft FM | 46.0% | Integrated FM | 8.11% |
| By Customer Type | Government K-12 Schools | 44.0% | Non-Government K-12 Schools | 7.43% |
| By Operating Model | Self-Delivered Contracts | 41.0% | Hybrid Delivery Contracts | 7.43% |
| By Sales Channel | Open Tender Procurement | 47.0% | Panel Procurement | 7.47% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Enrolments, vocational campuses and regional contracts
How does occupied learning space lift daily service needs?
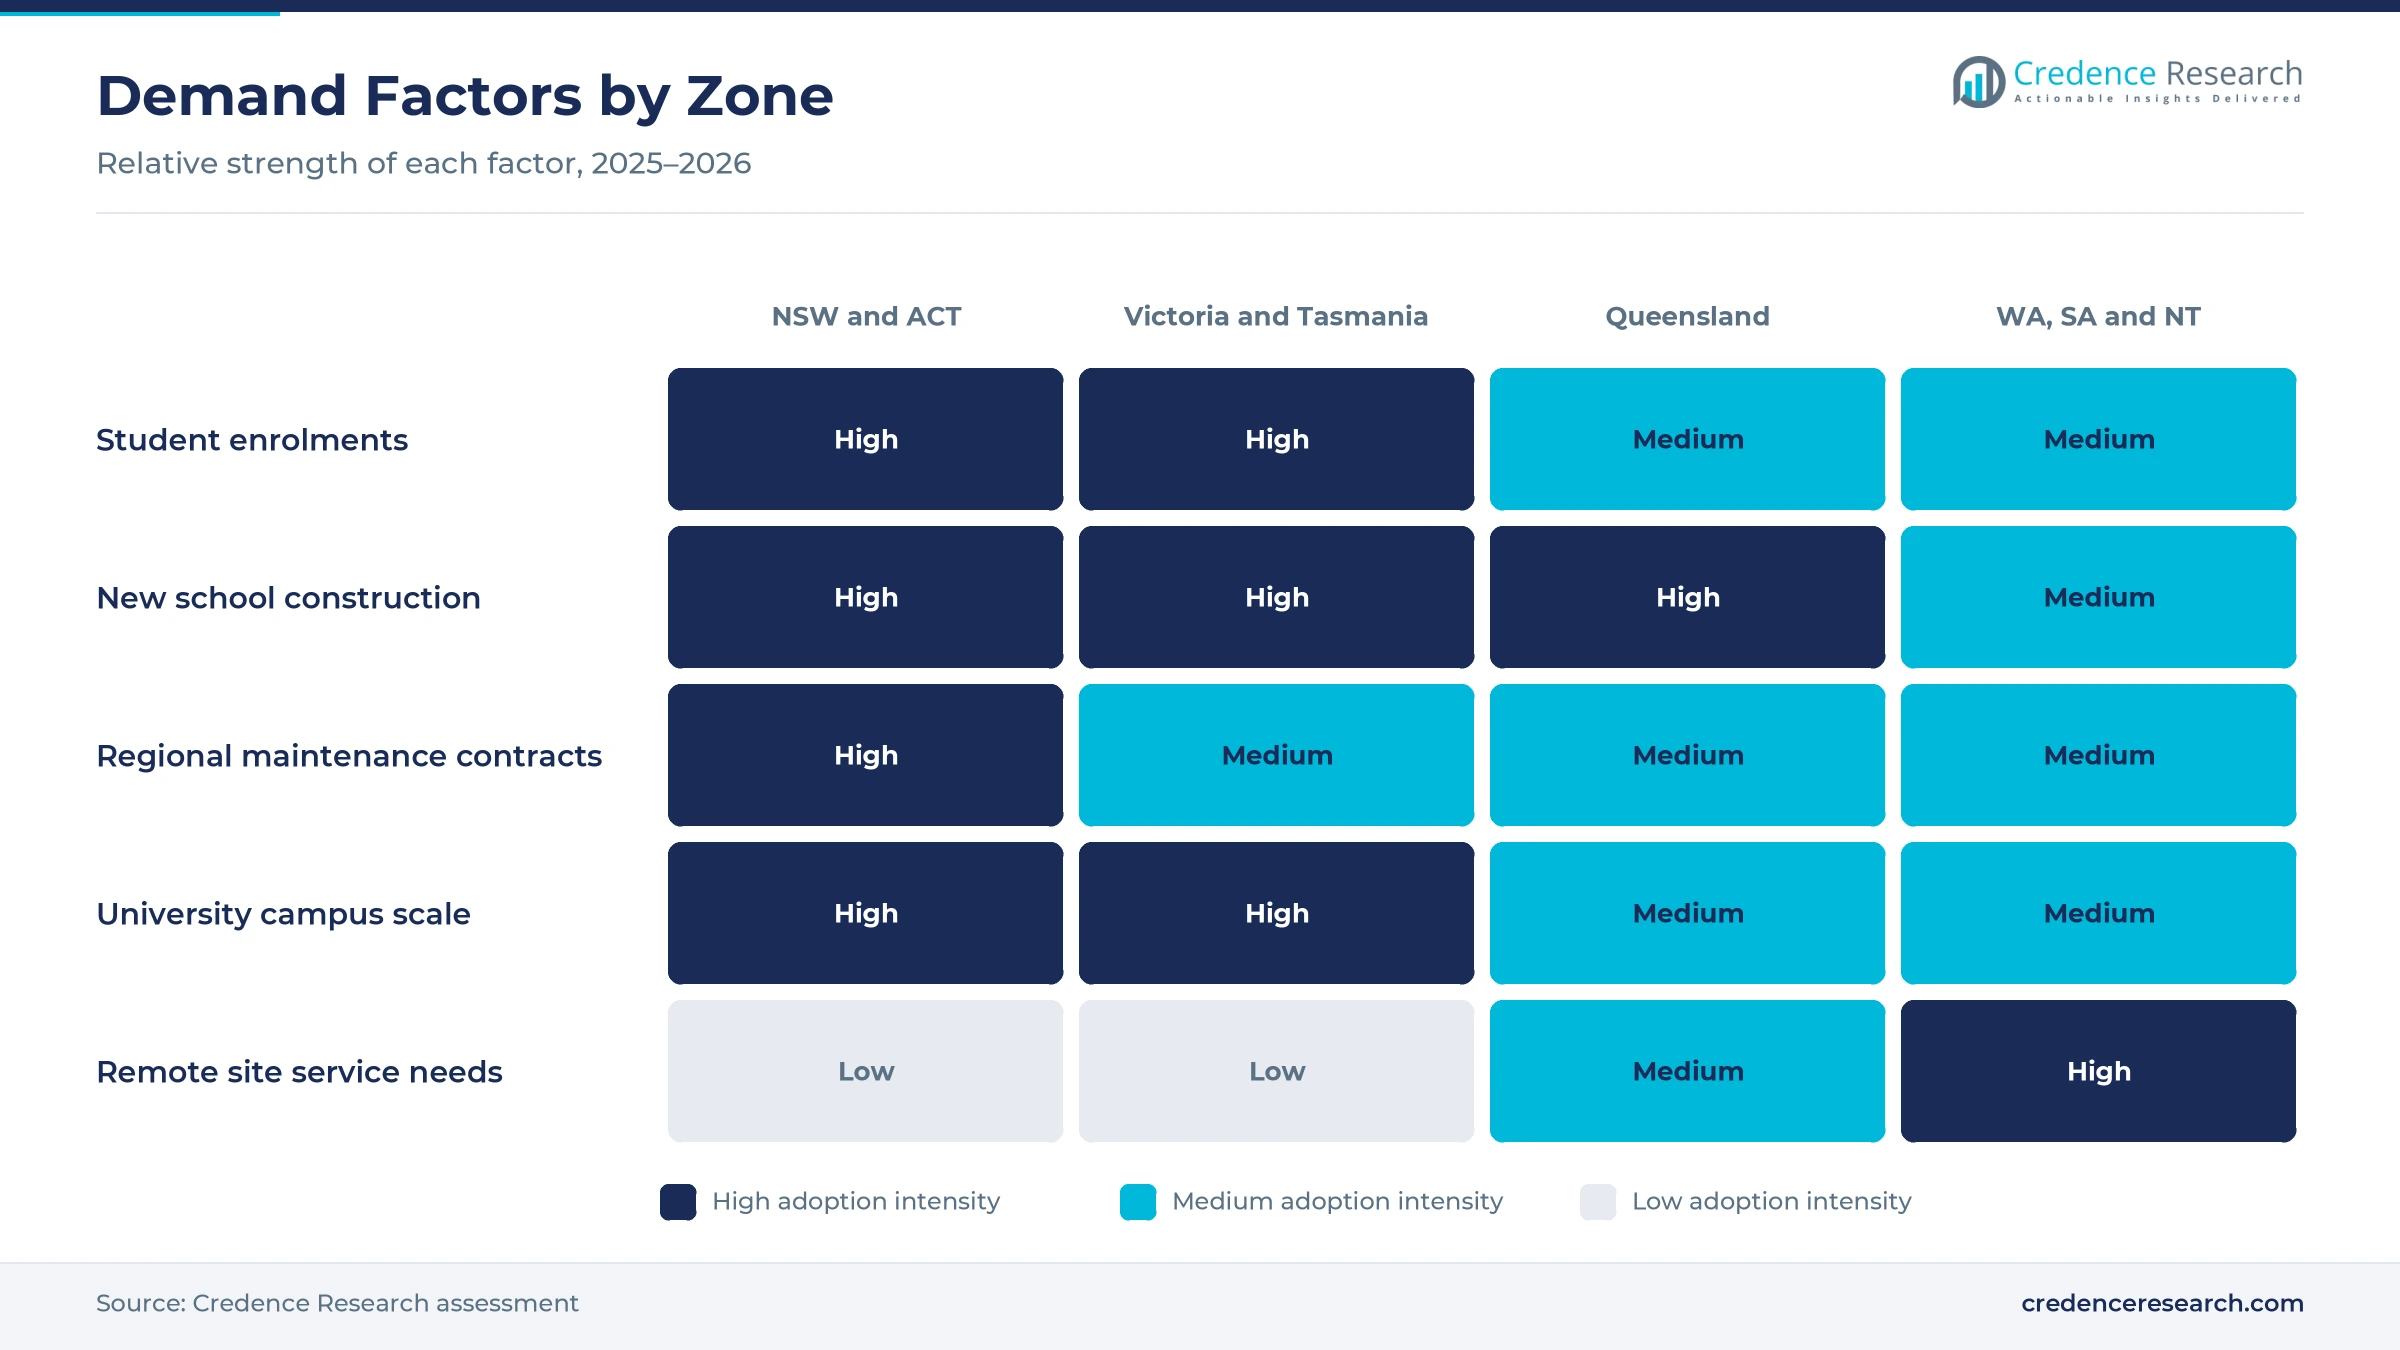
Occupied learning space lifts daily service needs, because every classroom in use needs cleaning, security, grounds care and repairs across the school year. Australian schools enrolled 4,160,918 students across 9,673 schools in 2025, the highest count on record, according to the Australian Bureau of Statistics. Independent school enrolments rose 3.4% in 2025 and 15.3% between 2021 and 2025, which adds occupied floor space outside the public system. Western Australia recorded the fastest enrolment growth among the states in 2025, at 1.5%. As a result, non-government schools add cleaning and repair work faster than the public system, while government K-12 schools still hold 44.0% of 2025 value because of their large estate.
Why does vocational estate expansion widen contract scope?
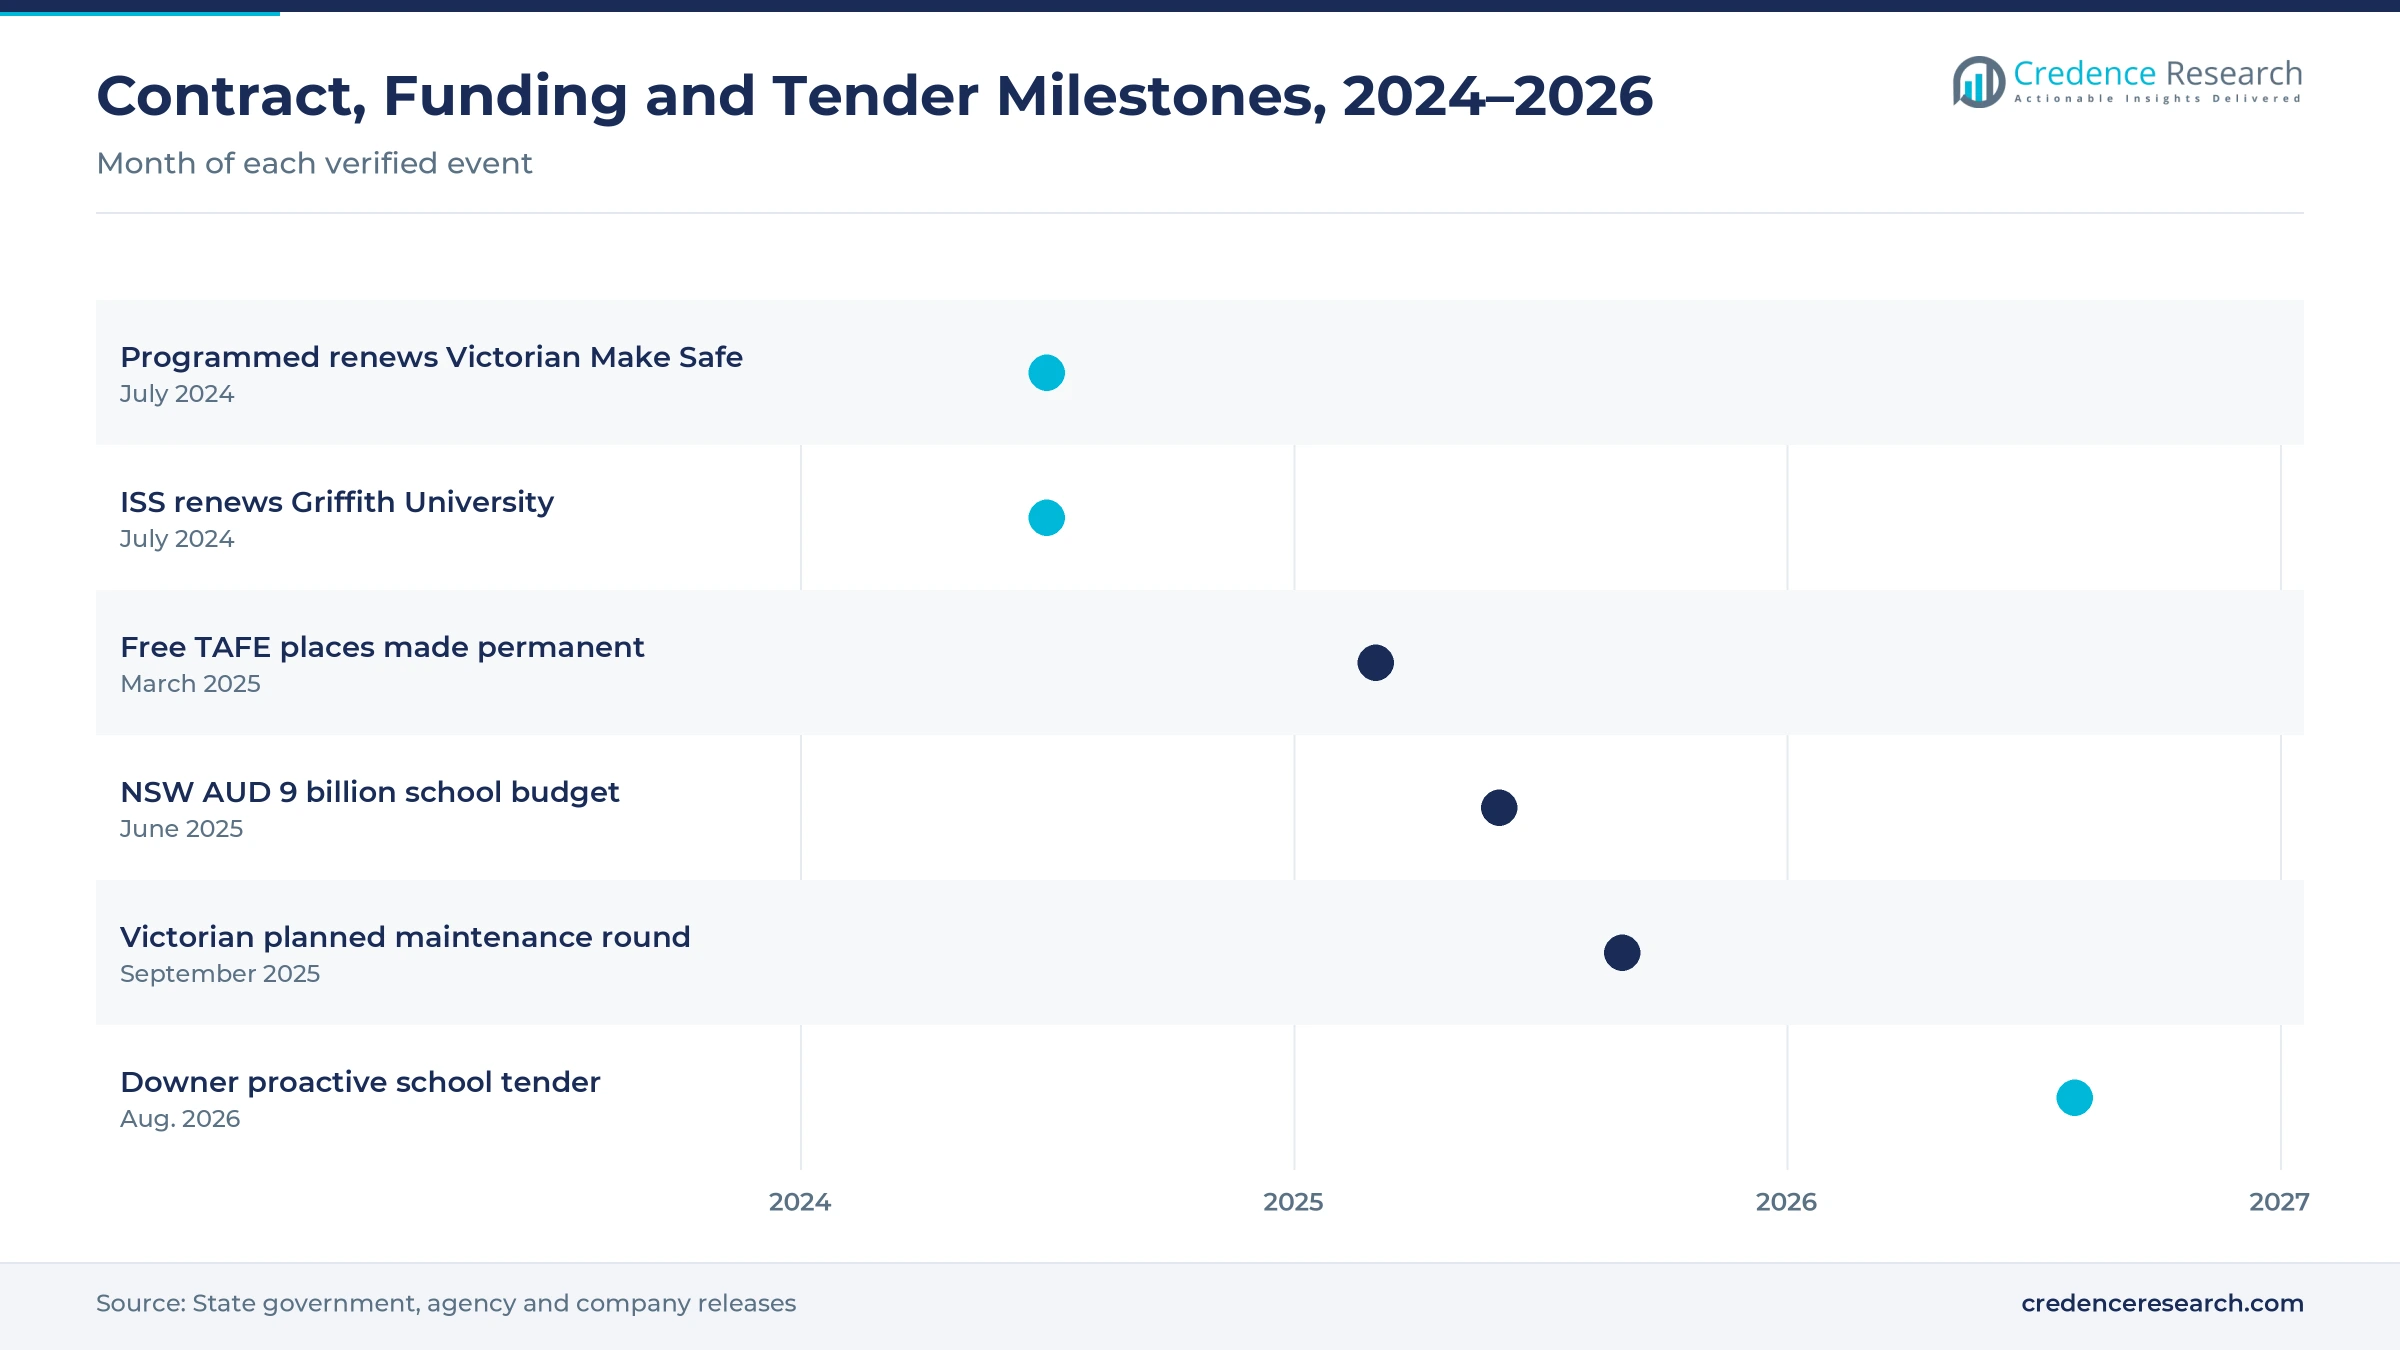
Vocational estate expansion widens contract scope, because TAFE campuses run trade workshops, laboratories and simulated worksites that need specialist maintenance and cleaning. Federal parliament made 100,000 Free TAFE places a year permanent from 2027, a change that the national teachers union welcomed on March 27, 2025. Government-funded training still reached 1,137,645 students in 2025, according to the National Centre for Vocational Education Research, even after a 6.7% fall from 2024. Australia also recorded a gross tertiary enrollment ratio of 108.4% in 2024, which shows how heavily post-school campuses are used. In turn, TAFE institutes and universities need contractors that can maintain workshops and campus support buildings to industry standards.
How do portfolio contracting and renewal shape spending?
Portfolio contracting and renewal shape spending, because state agencies now buy upkeep for hundreds of schools at once instead of site by site. School Infrastructure NSW began managing public school maintenance directly in 2023 through five contractors that cover eight regions and more than 2,000 schools, according to School Infrastructure NSW. Downer acts as the maintenance contractor for 300 schools in South-Western Sydney, and its proactive tender for 11 services closed on Aug. 10, 2026. Programmed renewed its Make Safe partnership with the Victorian School Building Authority in July 2024, covering 1,743 public school campuses. As a result, panel procurement grows fastest at 7.47% a year.
Why do state school building programs add upkeep demand?
State school building programs add upkeep demand, because every new school or upgrade joins a maintenance contract when it opens. The NSW Government committed a record AUD 9 billion over four years to school infrastructure in its 2025-26 Budget, including AUD 2.6 billion for the first year, according to the NSW Government. Victoria pledged 100 new schools by 2026 and set aside AUD 342 million for maintenance in its 2025-26 Budget. Queensland allocated AUD 1.09 billion for 15 new state schools and campuses in fast-growing areas. As a result, facility management in education grows with each new school that opens in the growing suburbs of Brisbane, Melbourne and Sydney.
Planned upkeep, campus bundling and local supplier programs
How is the shift to planned maintenance changing work orders?
The shift to planned maintenance is changing work orders, because agencies now fund repairs from condition data instead of waiting for faults. Victoria funded 300 projects at 280 schools worth AUD 105.5 million under its Planned Maintenance Program in 2025, according to the Victorian Government. A round announced on Sept. 17, 2025, gave more than AUD 16 million to 30 schools for roofs, windows, painting and floors. Projects are chosen through a rolling facilities evaluation that tracks school conditions. The Downer tender in South-Western Sydney also listed 11 proactive services, including fire safety, lifts and water testing. In turn, hard FM work is moving toward scheduled programs that suit larger contractors.
Why is the rise of bundled campus contracts notable?
The rise of bundled campus contracts is notable, because universities want one provider to manage maintenance, cleaning and helpdesk services across all their sites. ISS renewed its partnership with Griffith University from July 2024, adding work-integrated learning for students and Indigenous supplier development. BGIS listed La Trobe University, Murdoch University and University of Melbourne work in an April 2025 tertiary flyer. Ventia serves as the prime maintenance provider for the University of Sydney across three campuses under a three-year contract. Its La Trobe work covers heating, cooling and mechanical plant across all five campuses. As a result, integrated FM grows at 8.11% a year, the fastest service rate, and providers that link building automation systems to their work orders gain an edge in campus tenders.
Can local and Aboriginal supplier programs open new work?
Local and Aboriginal supplier programs can open new work, because state agencies now require lead contractors to spend more with regional trades and First Nations businesses. School Infrastructure NSW includes Aboriginal businesses through its First Nations Engagement in School Infrastructure Program and opened trade applications from July 1, 2023. Its maintenance model directs over AUD 500 million to local contractors over the life of the contracts. Downer is helping the agency procure local trades that contract directly, with proactive awards estimated by Aug. 31, 2026. ISS also runs Indigenous supplier development within its Griffith University contract. In turn, specialist providers of pest control services, cleaning and small repairs can win direct school work.
Is there room to win work as large contracts are rebid?
Providers have room to win work as large contracts are rebid, because several statewide arrangements reach decision points before 2030. South Australia's across-government arrangement, which covers schools, hospitals and police stations for more than 47 agencies, runs until July 2027 with up to three two-year extensions. Government spending on education reached 5.1% of GDP in 2022, according to the World Bank, which keeps upkeep budgets large. Victoria also renewed its Make Safe contract with Programmed for terms of up to six years. As a result, providers that offer computer-aided maintenance planning and clear cost reporting can challenge incumbents at renewal.
Trade shortages, tight budgets and site access test vendors
How do trade shortages slow response times?
Trade shortages slow response times, because schools in regional and fast-growing areas compete with housing and infrastructure projects for electricians, plumbers and mechanical technicians. As a result, contractors struggle to meet response targets and must pay more to keep subcontractors. Providers respond with apprenticeships, regional trade panels and longer agreements with local firms, which helps them hold skilled crews through peak building periods and school holiday works. Remote sites also rely on fly-in visits that raise the cost of every job.
Why do fixed budgets squeeze contract margins?
Fixed budgets squeeze contract margins, because education agencies set maintenance funds in annual budgets while labor, materials and insurance costs keep rising. In turn, providers on fixed-fee contracts carry the risk of cost increases between price reviews. Contractors respond by seeking indexation clauses, schedule-of-rates pricing for reactive work and planned programs that let them schedule labor more efficiently across many sites. Agencies, in turn, gain clearer cost data for future budget bids.
How do school hours and child safety rules limit site access?
School hours and child safety rules limit site access, because most noisy or disruptive work must wait for weekends, evenings or school holidays. Every worker on site also needs child safety checks and induction, which adds time and cost for subcontractors. As a result, holiday periods become crowded with projects that compete for the same trades. Providers respond with careful scheduling, approved worker pools and digital sign-in systems that track who is on each school site.
Why does fragmented procurement raise bidding costs?
Fragmented procurement raises bidding costs, because each state, university and school system writes its own contract terms, service levels and reporting rules. In turn, providers must prepare separate tenders and run different systems for each client. Smaller firms find it hard to bid for large regional packages. Contractors respond by forming partnerships and joining state panels, which lets them reach more buyers without bidding for every individual contract. This approach also spreads bid costs across several partner firms.
New South Wales and ACT lead as Queensland grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and ACT | 0.39 | 33.7% | 6.64% |
| Victoria and Tasmania | 0.28 | 24.6% | 6.84% |
| Western Australia, South Australia and Northern Territory | 0.26 | 22.7% | 6.84% |
| Queensland | 0.22 | 19.0% | 7.24% |
Why do New South Wales and ACT hold the top share?
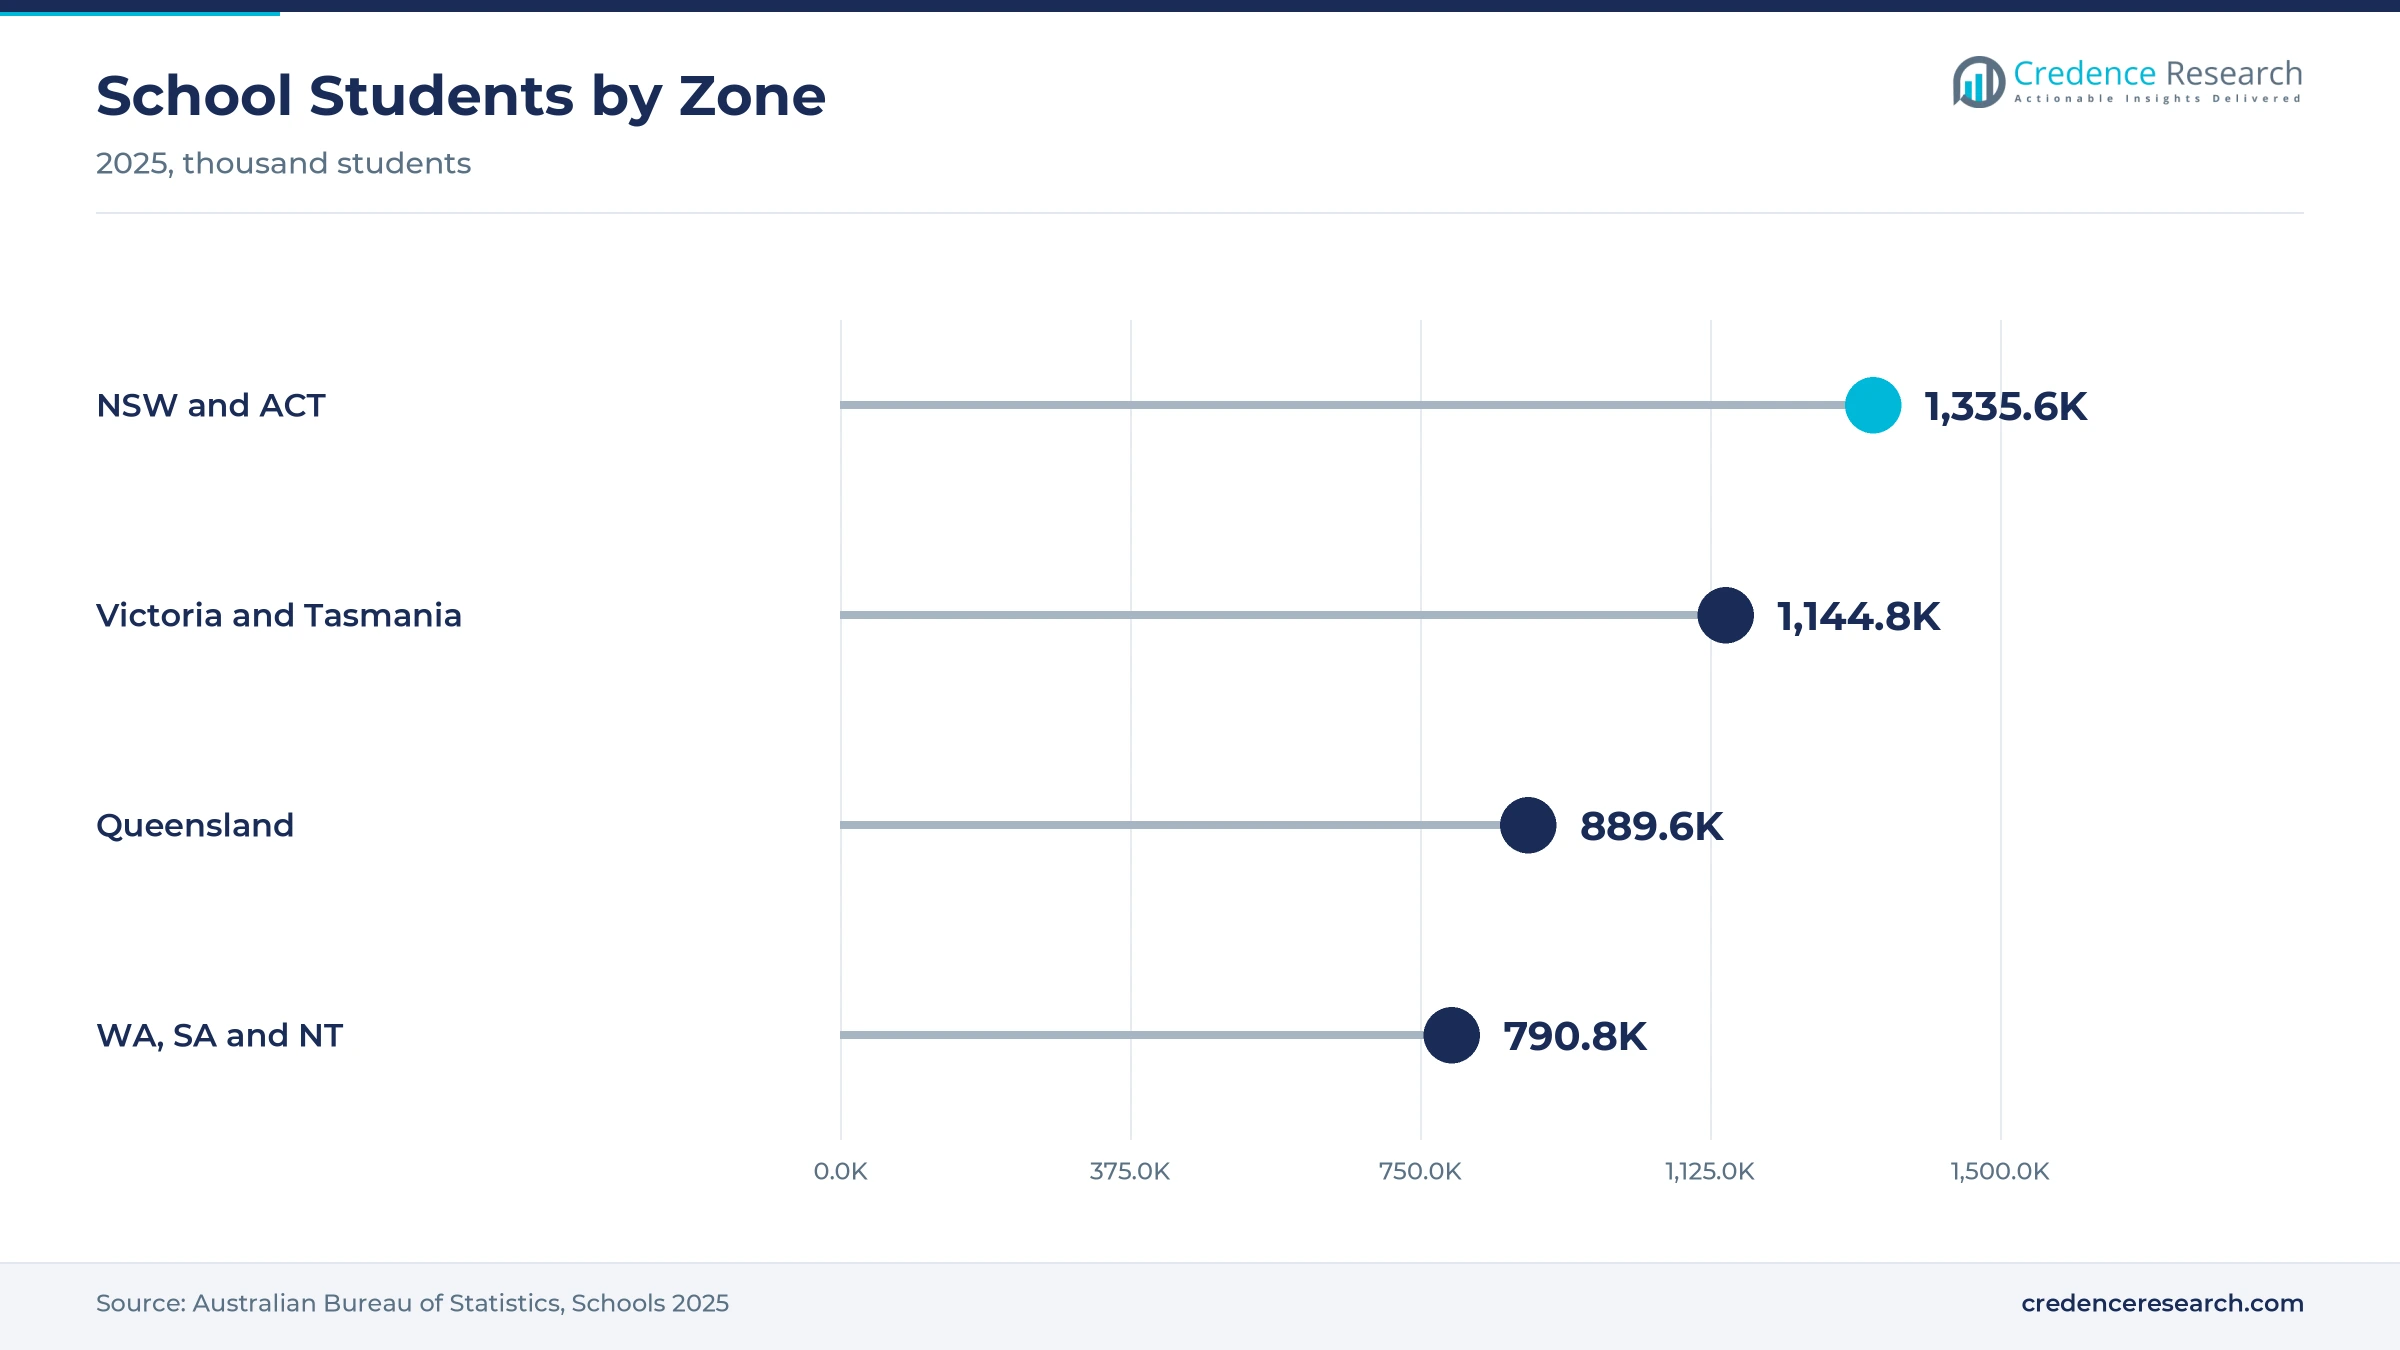
New South Wales and ACT held a 33.7% share of 2025 value and grow at 6.64% a year, because the zone enrolled about 1.34 million school students in 2025. The NSW public estate alone covers more than 2,000 schools under regional maintenance contracts. Sydney also hosts large university campuses that buy integrated services and contract cleaning services on multi-year terms. As a result, the zone leads both school maintenance and campus contract spending.
How do Victoria and Tasmania support demand?
Victoria and Tasmania held a 24.6% share of 2025 value and grow at 6.84% a year, because the zone enrolled about 1.14 million school students in 2025. Victoria funds a rolling program of planned maintenance and a statewide Make Safe contract for 1,743 public school campuses. In turn, Melbourne universities also buy maintenance and campus services from national providers, which keeps the zone second in value.
Why is Queensland growing fastest?
Queensland held a 19.0% share of 2025 value and grows fastest at 7.24% a year, because the state is building 15 new schools and campuses in fast-growing areas. Queensland enrolled about 890,000 school students in 2025, the third-largest total of any zone. Griffith University on the Gold Coast and in Brisbane also renewed its campus services contract with ISS in July 2024. As a result, new floor area and campus contracts lift demand.
What shapes demand in the western, southern and northern states?
Western Australia, South Australia and Northern Territory held a 22.7% share of 2025 value and grow at 6.84% a year, because the zone enrolled about 790,000 school students in 2025. Western Australia recorded the fastest enrolment growth of any state. South Australia buys school maintenance through a statewide arrangement that also covers hospitals and police stations.
Contract renewals, budgets and tenders, 2024–2026
| Development | Status and market relevance |
|---|---|
| In July 2024, Programmed renewed its Make Safe partnership with the Victorian School Building Authority for 1,743 public school campuses. | Terms of up to six years |
| In July 2024, ISS began a renewed campus services partnership with Griffith University in Queensland. | Adds student learning and Indigenous supplier programs |
| In June 2025, the NSW Government committed a record AUD 9 billion over four years to school infrastructure. | Adds new schools and upgrades that need upkeep |
| In September 2025, Victoria announced more than AUD 16 million for 30 schools under its Planned Maintenance Program. | Part of AUD 105.5 million for 300 projects in 2025 |
| In August 2026, Downer closed a proactive maintenance tender for 11 services across 300 schools in South-Western Sydney. | Awards to local trades estimated by Aug. 31, 2026 |
Condition data, building systems and work-order platforms
- Condition assessment data ranks building faults across many sites, which lets agencies fund roofs, windows and floors before they fail. Victoria uses a rolling facilities evaluation of this kind to choose its planned maintenance projects each year.
- Connected building systems report heating, cooling and lighting faults automatically, which helps campus teams cut energy use and send technicians faster. Universities with large laboratories and lecture halls gain the most from these alerts.
- Mobile work-order platforms send jobs to local trades, record site sign-in and capture photos, which gives agencies proof of work across hundreds of schools. These platforms also help contractors check that every worker holds current child safety clearance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
National service groups compete for school and campus work
Competition is split between national service groups that hold large regional and campus contracts and local trades that deliver much of the site work. Downer acts as the maintenance contractor for 300 schools in South-Western Sydney and manages local trade procurement for the state agency. Programmed delivers Make Safe services for 1,743 Victorian public school campuses. ISS renewed its campus services partnership with Griffith University in July 2024, while Ventia is the prime maintenance provider for the University of Sydney. BGIS maintains heating and mechanical plant across all five La Trobe University campuses. Rivals compete on response times, local trade networks, safety records, data reporting and price. Because agencies now buy by region, providers with strong subcontractor management win the largest contracts.
Which companies serve schools and campuses in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Downer Group | National service provider | Maintenance contractor for 300 schools in South-Western Sydney |
| Programmed | National service provider | Make Safe services for 1,743 Victorian public school campuses |
| ISS Australia | Integrated service provider | Renewed Griffith University campus services contract in July 2024 |
| Ventia | National service provider | Prime maintenance provider for the University of Sydney |
| BGIS Australia | Integrated service provider | Mechanical plant maintenance across La Trobe University campuses |
Credence Research view on school and campus upkeep
Credence Research's view is that Australian spending on school and campus upkeep will grow steadily because enrolments are at record levels and states are building new schools in growing suburbs. Soft services remain the largest value pool, while integrated contracts add the fastest growth as universities and agencies bundle work. Regional contracting in New South Wales and planned maintenance in Victoria are likely to set the pattern for other states. Providers that manage local trades well, report clearly and meet child safety rules should gain share fastest.
How the national school and campus upkeep estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines school enrolment statistics, state budget papers, vocational training statistics, agency procurement notices and company announcements. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the client-defined split. Sources used are official statistics, government releases and company releases, and no interviews or surveys were used.
New schools and contract rebids carry growth to 2035
Spending on school and campus services is expected to reach USD 2.24 billion by 2035, a 6.85% CAGR during 2026–2035, as new schools open and older buildings need more repairs. Growth should be strongest through 2030 while states finish large building programs. After that, contract renewals and planned maintenance will carry more of the value. Tighter state budgets would slow discretionary work, while stronger enrolment growth would lift demand. Providers with local trade networks are expected to gain the most.
Frequently Asked Questions
How big is the Australia facility management in education market?
Which service type leads Australian education spending?
Which region leads the Australian market?
How many students attend Australian schools?
How do NSW public schools buy maintenance?
Which customer type is growing fastest?
Who are the leading companies in the Australian market?
What are the main challenges for providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Soft FM
- 1.2.2 Hard FM
- 1.2.3 Integrated FM
- 1.3 By Customer Type
- 1.3.1 Government K-12 Schools
- 1.3.2 Non-Government K-12 Schools
- 1.3.3 Universities
- 1.3.4 TAFE Institutes
- 1.4 By Operating Model
- 1.4.1 Self-Delivered Contracts
- 1.4.2 Subcontractor-Managed Contracts
- 1.4.3 Hybrid Delivery Contracts
- 1.5 By Sales Channel
- 1.5.1 Open Tender Procurement
- 1.5.2 Panel Procurement
- 1.5.3 Direct Negotiation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.15 billion → 2035: USD 2.24 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Facility Management in Education Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Facility Management in Education Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Facility Management in Education Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Facility Management in Education Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Facility Management in Education Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Facility Management in Education Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Facility Management in Education Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Facility Management in Education Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.15 billion → 2035: USD 2.24 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Facility Management in Education Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Soft FM
- 12.3.7.2 Hard FM
- 12.3.7.3 Integrated FM
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Government K-12 Schools
- 12.4.7.2 Non-Government K-12 Schools
- 12.4.7.3 Universities
- 12.4.7.4 TAFE Institutes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operating Model - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Self-Delivered Contracts
- 12.5.7.2 Subcontractor-Managed Contracts
- 12.5.7.3 Hybrid Delivery Contracts
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Open Tender Procurement
- 12.6.7.2 Panel Procurement
- 12.6.7.3 Direct Negotiation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Facility Management in Education End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Facility Management in Education Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Facility Management in Education Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Facility Management in Education Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ISS Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Downer Group
- 18.4 BGIS Australia
- 18.5 Ventia
- 18.6 Programmed
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

