
Market Overview
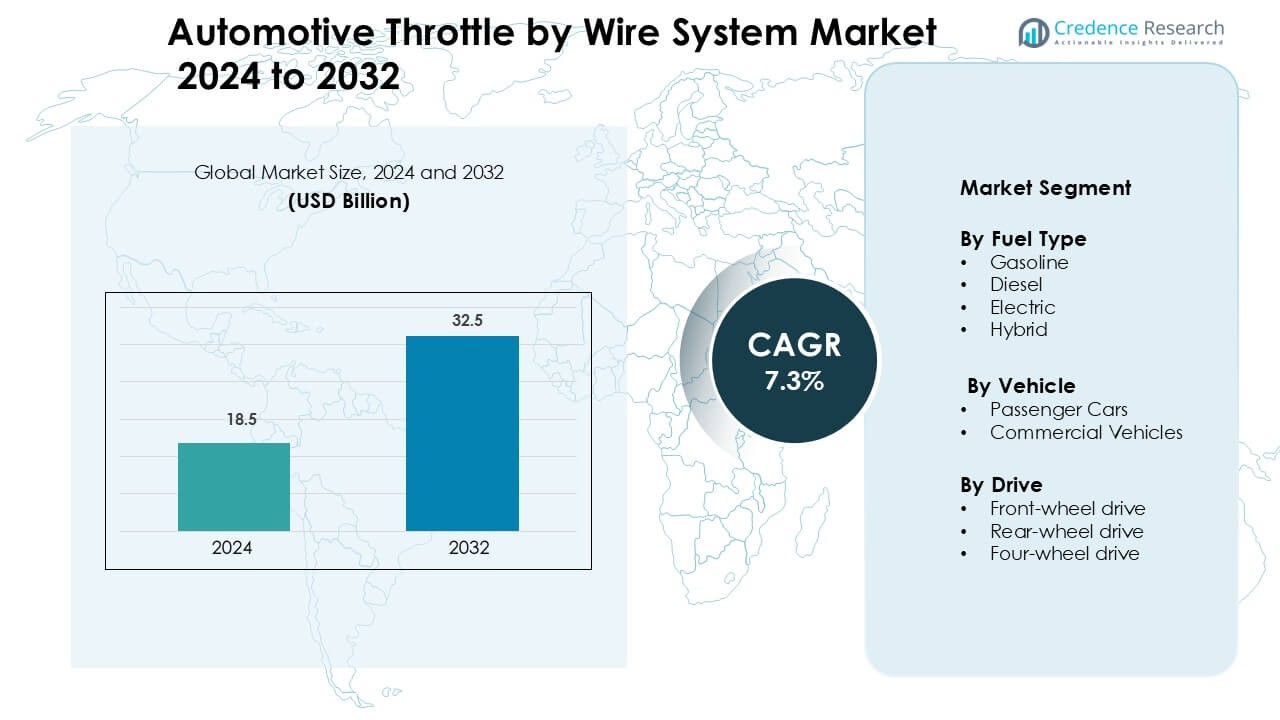
Automotive Throttle by Wire System Market was valued at USD 18.5 billion in 2024 and is anticipated to reach USD 32.5 billion by 2032, growing at a CAGR of 7.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Throttle by Wire System Market Size 2024 | USD 18.5 Billion |
| Automotive Throttle by Wire System Market, CAGR | 7.3% |
| Automotive Throttle by Wire System Market Size 2032 | USD 32.5 Billion |
Key players in the Automotive Throttle‑By‑Wire System Market include Robert Bosch GmbH, Continental AG, Denso Corporation, ZF Friedrichshafen AG and Aptiv PLC, which command the industry through extensive OEM relationships, global manufacturing presence and advanced R&D capabilities. These firms lead by delivering high‑precision sensor‑actuator modules and full throttle‑by‑wire systems for ICE and EV applications. Regionally, the North America region dominates the market, accounting for 31.8 % of global share in 2023, thanks to strong EV uptake, mature automotive electronics infrastructure and stringent emissions regulations.
Market Insights
- Market size reached USD 18.5 billion in 2024 and is projected to grow at a CAGR of 7.3% through to 2035.
- Stringent emissions norms and rising EV/hybrid adoption drive demand for electronic throttle‑by‑wire systems, especially in the gasoline fuel type sub‑segment holding the largest share.
- Key trends include the shift to electric and hybrid vehicles, integration of throttle‑by‑wire into ADAS and drive‑by‑wire architectures, plus rising aftermarket retrofit opportunities.
- Competitive dynamics reflect consolidation among Tier‑1 suppliers with global footprints; development cost and integration complexity act as market restraints, especially for smaller OEMs.
- Regionally, North America dominates the market with the highest share (over 30 %), while Asia‑Pacific offers the fastest growth thanks to large automotive production hubs and electrification momentum.
Market Segmentation Analysis:
By Fuel Type
In the fuel type segmentation of the Automotive Throttle‑By‑Wire System Market, the gasoline sub‑segment holds dominance, capturing the largest share due to its established base in internal combustion engine (ICE) vehicles. This leads growth because throttle‑by‑wire technology allows manufacturers to meet stricter emissions and fuel‑efficiency demands for gasoline engines. Meanwhile, the electric and hybrid sub‑segments are registering the fastest growth, driven by the electrification trend and regulatory mandates favouring lower‑emission powertrains.
- For instance, Bosch is a major global supplier of electronic throttle control (ETC) systems and has supplied over 100 million throttle valves.
By Vehicle Type
In the vehicle‑type segmentation, the passenger car segment is the dominant sub‑segment in the throttle‑by‑wire systems market, reflecting the large volume of light vehicles and strong adoption of advanced control technologies therein. Passenger cars push demand via enhanced driver‑assistance and fuel‑savings features, prompting OEMs to integrate throttle‑by‑wire systems. Meanwhile, the commercial vehicle segment is also growing as stricter emission regulations and fleet electrification drive the use of electronic throttle control in trucks and buses.
- For instance, Denso Corporation reports supplying electronic throttle-body modules for over 20 million passenger cars globally, demonstrating strong passenger-car penetration.
By Drive Type
Within the drive‑type segmentation, front‑wheel drive (FWD) is the dominant sub‑segment, securing the largest market share, owing to its prevalence in compact and midsize passenger cars globally. FWD’s cost‑effectiveness and fuel‑efficiency advantages make it a preferred configuration for vehicles adopting throttle‑by‑wire technologies. Meanwhile, rear‑wheel drive (RWD) and four‑wheel drive (4WD) segments are gaining ground as SUVs and performance vehicles increasingly incorporate advanced throttle control systems to satisfy off‑road, performance and all‑terrain requirements.
Key Growth Drivers
Stringent Emissions and Fuel Efficiency Regulations
Global regulatory bodies continue tightening emissions and fuel‑economy standards, compelling automakers to adopt advanced systems like throttle‑by‑wire (TBW). The shift from mechanical linkage to electronically controlled throttle enables more accurate air‑fuel control and reduced emissions, aligning with mandates in regions such as Europe and North America. Consequently, demand for TBW systems rises as manufacturers integrate them to ensure compliance while sustaining performance and efficiency.
- For instance, Bosch’s electronic throttle valve model DV-E/RKL-E5.9 has been supplied in over 100 million units worldwide and features a throttle-plate actuation time of under 100 milliseconds, enabling faster and more precise air-mass regulation.
Electrification of Powertrains and EV/Hybrid Growth
The accelerating uptake of electric vehicles (EVs) and hybrid powertrains boosts the need for TBW technologies. These systems provide precise throttle management and smoother torque control in EVs and hybrids, which lack mechanical throttle linkages As OEMs scale battery electric vehicles and plug‑in hybrids, the TBW market expands accordingly, driven by the novel control demands of electrified vehicles.
- For instance, Denso produces powertrain components for EVs and hybrids (including power control units and battery monitoring units), accelerator pedal/throttle-by-wire modules.
Integration with Advanced Driver Assistance Systems (ADAS) and Automotive Electronics
Modern vehicles increasingly feature ADAS, connectivity, and semi‑autonomous systems, which rely on electronic throttle inputs for rapid response and system coordination. The TBW architecture enables seamless integration with electronic control units (ECUs), traction/stability control, and drive‑by‑wire subsystems. This growing integration requirement prompts OEMs and suppliers to adopt TBW solutions, further propelling market growth.
Key Trends & Opportunities
Growing Demand in Electric and Hybrid Vehicle Segments
As automakers pivot toward EVs and hybrids, TBW systems emerge as core enablers of the electrified drivetrain. Enhanced management of throttle response, energy efficiency, and torque delivery in battery‑electric and hybrid models positions TBW as a strategic component. Suppliers and vehicle manufacturers have the opportunity to develop optimized TBW modules tailored for electrified platforms and thereby capture early‑mover advantages.
- For instance, Denso Corporation reports supplying TBW modules tailored for hybrid-electric applications that have undergone more than 10 million cumulative vehicle installations.
Emergence of Connected, Autonomous and Drive‑by‑Wire Architectures
Vehicles increasingly rely on electronic control over traditional mechanical systems-accelerator, steering, braking-creating synergy with TBW architectures. The trend toward fully drive‑by‑wire systems and autonomous vehicles offers TBW providers a pathway to embed their technologies within broader vehicle electronic frameworks Additionally, aftermarket opportunities exist for retrofits or upgrades in connected vehicles, where TBW systems improve responsiveness and safety‑related control functions.
- For instance, Wipro is involved in automotive engineering and software, specific, highly detailed hardware specifications for a safety-critical "drive-by-wire" system in production vehicles would typically be subject to rigorous industry standards and testing.
Key Challenges
High Cost and Complexity of Development & Integration
Implementing TBW systems involves significant investment in sensors, actuators, software and failsafe architectures. Smaller OEMs or component suppliers may face cost barriers, particularly when shifting from mechanical to electronic throttle systems. The complexity of integration with other vehicle control systems increases certification burdens and may slow widespread adoption in cost‑sensitive vehicle segments.
Safety, Reliability and Cyber‑Security Concerns
Electronic throttle systems replace mechanical linkages, raising questions around system failures, unintended acceleration risks and cyber‑vulnerability in connected vehicles. Manufacturers must ensure TBW systems meet stringent safety, redundancy and cybersecurity standards, which adds design and validation burden. This challenge can delay adoption or increase costs for vehicle programs that require full system assurance under regulatory scrutiny.
Regional Analysis
North America
North America holds an estimated ~25% of the global throttle-by-wire systems market. The region benefits from strong OEM presence, advanced vehicle electronics adoption, and regulatory pressure on emissions and fuel-efficiency. The United States, in particular, is a leading adopter of electronic throttle systems in mainstream and premium vehicles, and Tier-1 suppliers are actively integrating these systems into hybrid and EV architectures. The favourable infrastructure and high per-vehicle electronics content continue to support market growth and strengthen the region’s share.
Europe
Europe captures approximately ~20% of the market for throttle-by-wire systems. Stringent emission standards (such as Euro 6/7), a strong automotive manufacturing base in Germany, France and the UK, and an early shift toward electrified powertrains drive demand for advanced throttle control systems. OEMs are focusing on improving mechatronic integration, actuation precision and software-driven control in European platforms, helping the region to maintain a significant presence in this market segment.
Asia-Pacific
Asia-Pacific commands the largest share of the global market roughly ~35-40% thanks to its massive vehicle production base, rapid EV and hybrid vehicle deployment, and strong automotive component industry in China, Japan, South Korea and India. The region’s scale in passenger vehicle output, rising vehicle electronics budgets and favourable government policies for electrification drive high adoption of throttle-by-wire systems. Consequently, Asia-Pacific remains the dominant regional market.
Latin America
Latin America contributes a more modest share around ~7-8% of the throttle-by-wire market. Growth is led by Brazil and Mexico, where increasing local vehicle production and component localisation are enhancing availability of electronic throttle systems. However, economic volatility, lower average vehicle content than developed markets and slower transition to electrified powertrains limit the region’s share relative to larger regions.
Middle East & Africa
The Middle East & Africa region holds roughly ~5-6% of the global market for throttle-by-wire systems. Vehicle markets in the UAE, Saudi Arabia and South Africa are gradually transitioning toward more electronics‐intensive components, but lower manufacturing base, less stringent regulatory pressure and a slower rate of electrification mean that uptake is behind other regions. Still, rising premium vehicle sales and aftermarket modernisation are improving penetration over time.
Market Segmentations:
By Fuel Type
- Gasoline
- Diesel
- Electric
- Hybrid
By Vehicle
- Passenger Cars
- Commercial Vehicles
By Drive
- Front-wheel drive
- Rear-wheel drive
- Four-wheel drive
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Automotive Throttle‑By‑Wire System Market remains moderately concentrated, dominated by well‑established automotive Tier‑1 suppliers such as Robert Bosch GmbH, Continental AG and Denso Corporation, which collectively hold significant global market shares. These leading players enjoy advantages through global manufacturing footprints, deep OEM relationships and extensive R&D investment in sensor‑actuator integration and electronic control units. Meanwhile, a broader tier of suppliers, including Magneti Marelli S.p.A., ZF Friedrichshafen AG and Aptiv PLC, actively compete by innovating on cost‑effective architectures, modular systems and drive‑by‑wire platforms. As electrification and autonomy trends accelerate, suppliers expand collaborations and pursue strategic partnerships to differentiate offering, create scale and address evolving OEM demands for electronic throttle control systems.
Key Player Analysis
- Cruise LLC
- Lyft, Inc.
- MOIA
- Uber Technologies INC.
- NAVYA
- Beijing Xiaoju Technology Co., Ltd.
- Zoox, Inc.
- Aptiv
- Tesla
- Waymo LLC
Recent Developments
- In September 2025, Lyft Launched a robotaxi pilot in Atlanta with May Mobility. Vehicles feature a redundant drive-by-wire stack and 360° sensing.
- In June 2025, MOIA Held the world premiere of the series ID. Buzz AD in Hamburg.
Report Coverage
The research report offers an in-depth analysis based on Fuel Type, Vehicle, Drive and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness stronger integration of throttle‑by‑wire systems in electric and hybrid vehicles as OEMs prioritize powertrain efficiency.
- Manufacturers will invest in modular and scalable electronic throttle platforms to support various vehicle types and worldwide regulatory demands.
- Throttle‑by‑wire systems will become more deeply embedded within ADAS and autonomous driving architectures, boosting demand from connected vehicle uptake.
- Growth will accelerate in Asia‑Pacific as production volumes rise and vehicle electrification expands across China, India and Southeast Asia.
- Suppliers will increasingly form strategic alliances and joint ventures to share R&D costs and penetrate new regional markets faster.
- Front‑wheel‑drive vehicles will continue dominating sub‑segment share, but four‑wheel‑drive applications will gain traction due to SUV and off‑road demand.
- Automation of throttle mapping and real‑time diagnostics will advance, enabling predictive maintenance and over‑the‑air updates for electronic systems.
- Entry into emerging regions (“Latin America & Middle East & Africa”) will broaden as local manufacturers adopt electronic throttle systems to meet emissions standards.
- Cost pressures and complexity will lead suppliers to focus on lighter, low‑power actuator designs and integrated ECU modules.
- Regulatory pressures on emissions and safety will compel faster replacement of mechanical throttle linkages, driving retrofit and aftermarket opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Automotive Throttle by Wire System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Automotive Throttle by Wire System Market projected to grow between 2025 and 2032?
Which Automotive Throttle by Wire System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Automotive Throttle by Wire System Market?
Who are the leading companies in Automotive Throttle by Wire System Market?
Which region commanded the largest share of Automotive Throttle by Wire System Market 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18.5 billion → 2032: USD 32.5 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Throttle by Wire System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Throttle by Wire System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Throttle by Wire System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Throttle by Wire System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Throttle by Wire System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Throttle by Wire System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Throttle by Wire System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Throttle by Wire System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18.5 billion → 2032: USD 32.5 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Throttle by Wire System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Throttle by Wire System Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Throttle by Wire System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Throttle by Wire System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

