
Market Overview
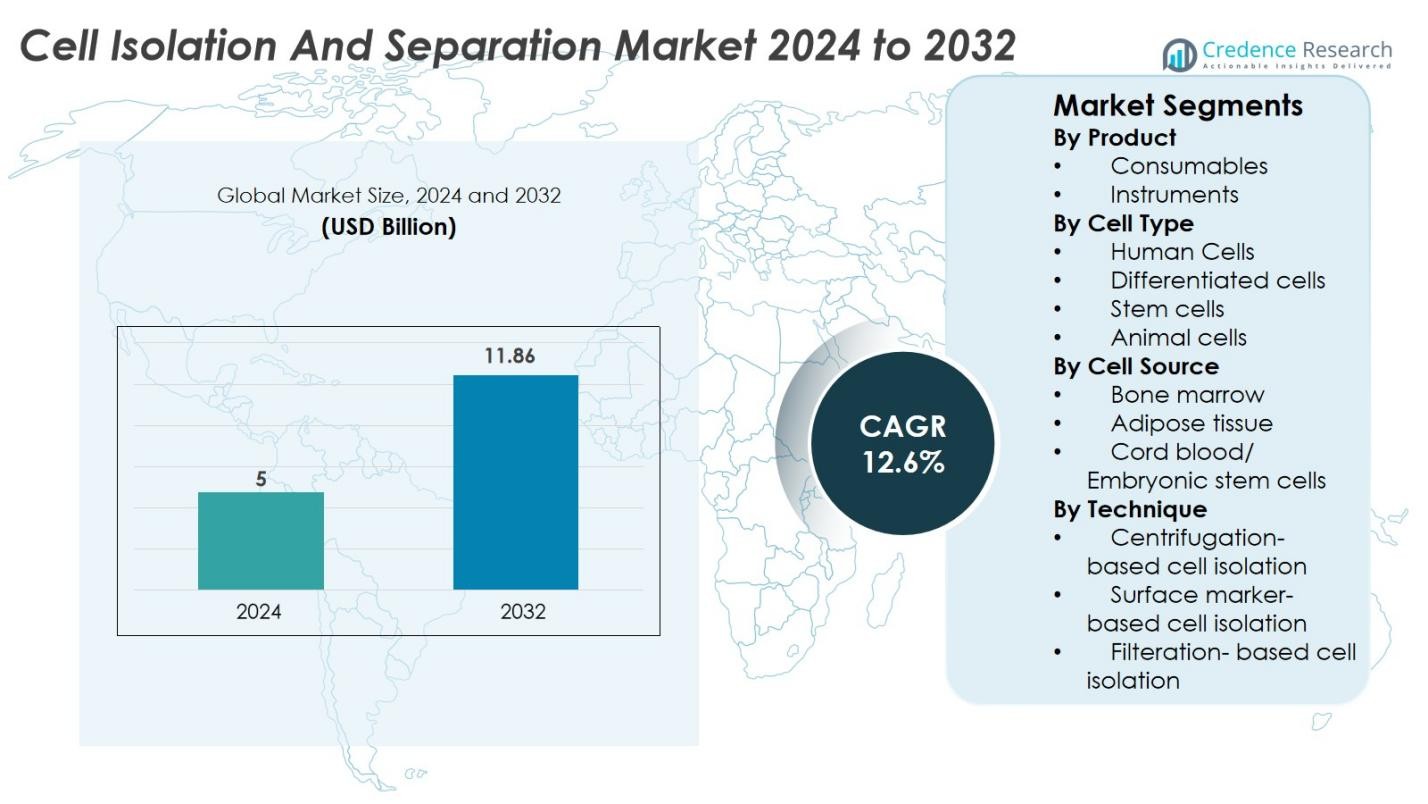
The Cell Isolation and Separation Market size was valued at USD 5 billion in 2024 and is anticipated to reach USD 11.86 billion by 2032, at a CAGR of 12.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cell Isolation and Separation Market Size 2024 | USD 5 Billion |
| Cell Isolation and Separation Market, CAGR | 12.6% |
| Cell Isolation and Separation Market Size 2032 | USD 11.86 Billion |
The Cell Isolation and Separation Market feature prominent players including Thermo Fisher Scientific, Inc., Becton, Dickinson and Company, Merck KGaA, Bio‑Rad Laboratories, Inc., Miltenyi Biotec GmbH, STEMCELL Technologies Inc., Terumo BCT, Inc. and pluriSelect Life Science UG & Co. KG. Thermo Fisher leads with 20% market share, followed by BD and Merck with shares 17%. Regionally, North America dominates with 32% of the global market, driven by strong R&D investment and infrastructure, while Asia‑Pacific follows with 25%, emerging rapidly due to rising biotech activity and healthcare spending.
Market Insights
- The global Cell Isolation and Separation Market was valued at USD 5 billion in 2024 and is expected to reach USD 11.86 billion by 2032, with a CAGR of 12.6% during the forecast period.
- The rising demand for personalized medicine is a key driver, as it requires precise cell isolation techniques for individualized treatments. This demand is particularly strong in oncology and regenerative medicine, boosting market growth.
- Increasing integration of automation and AI into cell isolation processes is a notable trend, improving efficiency and precision in clinical and research applications.
- Leading companies such as Thermo Fisher Scientific, Becton Dickinson, and Merck KGaA hold significant market shares, with ongoing investments in R&D and strategic partnerships to enhance product portfolios and regional reach.
- North America dominates the market with 36.5% share, followed by Europe at 30% and Asia Pacific at 25%, with the fastest growth expected in emerging Asia-Pacific markets.
Market Segmentation Analysis
By Product
The Cell Isolation and Separation Market is segmented into consumables and instruments. Consumables dominate this segment, accounting for approximately 65% of the market share due to their critical role in maintaining the efficiency and functionality of cell isolation processes. Consumables, including reagents, kits, and media, are essential for separating and isolating cells from samples. The growing demand for consumables is driven by the increasing use of cell-based therapies and research applications in biotechnology and pharmaceuticals. Instruments, while important, follow with 35% market share, as they are typically higher in cost and require regular updates and maintenance.
- For instance, Beckman Coulter’s high-performance flow cytometry instruments, including the CytoFLEX SRT, enable precise and automated cell sorting, improving operational throughput and accuracy by handling up to 20,000 events per second.
By Cell Type
The cell type segment is categorized into human cells, differentiated cells, stem cells, and animal cells. Human cells lead this segment, holding 70% of the market share due to their extensive use in clinical applications such as drug development, regenerative medicine, and cancer research. Stem cells, accounting for around 20% of the market share, are growing rapidly due to advancements in regenerative medicine and stem cell therapies. Differentiated and animal cells, while smaller in market share, contribute to the segment's diversity, with stem cells being a key driver for market growth.
- For instance, ViaCyte’s stem cell-based therapies, designed for diabetes treatment, have demonstrated the potential to generate insulin-producing cells in clinical trials, marking a significant breakthrough in stem cell research and regenerative medicine.
By Cell Source
The cell source segment includes bone marrow, adipose tissue, and cord blood/embryonic stem cells. Bone marrow is the dominant sub-segment, capturing nearly 50% of the market share, attributed to its critical role in hematopoietic stem cell therapy and regenerative medicine. Adipose tissue follows with 30% market share, gaining traction due to its less invasive collection methods and potential for use in a variety of regenerative treatments. Cord blood/embryonic stem cells account for around 20% of the market, driving innovation in stem cell therapies and contributing to the segment's growth.
Key Growth Drivers
Rising Demand for Personalized Medicine
The growing demand for personalized medicine is one of the key drivers of the Cell Isolation and Separation Market. Personalized medicine involves tailoring medical treatment to individual characteristics, including genetic makeup, which requires precise cell isolation and analysis. As personalized therapies, especially in oncology and regenerative medicine, gain prominence, the demand for efficient cell separation techniques increases. Cell isolation allows for the extraction of specific cells needed for these personalized treatments, enhancing therapeutic outcomes. Additionally, the use of patient-derived cells for drug testing, as part of personalized treatment protocols, further contributes to the rising need for cell separation technologies.
- For instance, Illumina’s next-generation sequencing platforms are widely used to analyze patient genomes, enabling the precise identification of genetic markers to develop tailored therapies, particularly in oncology, where early detection of genetic mutations is crucial for targeted treatments.
Growth in Regenerative Medicine and Stem Cell Therapy
The expanding field of regenerative medicine, particularly stem cell therapy, is a significant driver for the Cell Isolation and Separation Market. Stem cells have shown great potential in treating a wide range of conditions, including degenerative diseases, spinal injuries, and heart disease, which has spurred increased investment in stem cell-based therapies. The ability to isolate and purify specific stem cells from tissue samples is crucial for these applications. As the research and clinical adoption of stem cell therapies expand, the demand for advanced cell separation technologies grows. Innovations in stem cell therapies are expected to further accelerate, with applications in organ regeneration, wound healing, and immune system reprogramming, driving the demand for highly specialized cell isolation methods in the coming years.
- For instance, Thermo Fisher Scientific’s Gibco™ stem cell media are used extensively in stem cell therapy research, providing a reliable platform for culturing stem cells and advancing clinical trials in areas like heart disease and neurological conditions.
Advancements in Biotechnology and Research
Ongoing advancements in biotechnology and research are fueling the growth of the Cell Isolation and Separation Market. With new technologies emerging in genomics, proteomics, and cell-based therapies, the need for accurate and efficient cell isolation techniques has grown significantly. Biotech companies are increasingly focused on developing advanced cell isolation methods that can process large volumes of samples with greater accuracy and speed. Innovations like microfluidic devices, automated systems, and high-throughput technologies are making it easier to isolate rare and difficult-to-isolate cells. This enables researchers to make groundbreaking discoveries in drug development, disease mechanisms, and therapeutic applications. As the global investment in biotechnology research continues to increase, the demand for specialized cell separation technologies will continue to drive market growth.
Key Trends & Opportunities
Integration of Automation and AI in Cell Isolation
One of the most significant trends in the Cell Isolation and Separation Market is the integration of automation and artificial intelligence (AI) into the process. Automation improves the efficiency, accuracy, and scalability of cell isolation by reducing human error and increasing throughput. AI technologies enable more precise sorting and analysis, allowing for the identification of rare cell types and improving the quality of isolated samples. With the growing demand for high-throughput cell isolation in research and clinical applications, the adoption of automated systems equipped with AI is poised to be a key growth factor. These systems not only improve the speed of cell separation but also offer better reproducibility and consistency, making them essential tools in both laboratory and clinical settings.
- For instance, the AutoMACS Pro Separator from Miltenyi Biotec automates cell isolation using magnetic beads, improving throughput and reducing human error in large-scale cell-based research applications, which is critical in clinical settings like immunotherapy development.
Emergence of Point-of-Care Diagnostics
Point-of-care (POC) diagnostics is emerging as a significant opportunity within the Cell Isolation and Separation Market. The ability to quickly and accurately isolate and analyze cells at the point of care-such as in emergency rooms, remote clinics, or even home settings-is revolutionizing diagnostics and treatment. POC testing for infectious diseases, cancer, and other conditions requires rapid cell isolation techniques to ensure timely and accurate results. As healthcare systems move toward decentralized models and patient-centric care, the demand for portable, easy-to-use cell separation devices at the point of care is growing.
- For instance, Applied Cells' MARS® Atlas system automates point-of-care cell manufacturing, integrating cell selection, transduction, and expansion into a compact platform capable of producing CAR-T cell therapies within 72 hours, significantly accelerating treatment timelines.
Key Challenges
High Cost of Advanced Cell Isolation Technologies
One of the key challenges faced by the Cell Isolation and Separation Market is the high cost of advanced technologies. The development and implementation of specialized equipment, reagents, and consumables for cell separation can be expensive, particularly for smaller laboratories and healthcare facilities with limited budgets. High capital expenditures for instruments and operational costs associated with consumables and maintenance are barriers to widespread adoption, especially in emerging markets. Additionally, the complexity of integrating advanced automation and AI into existing workflows adds to the overall cost. As a result, many organizations may be reluctant to invest in cutting-edge technologies, hindering market growth.
Regulatory and Quality Control Challenges
The regulatory environment and the need for stringent quality control are significant challenges in the Cell Isolation and Separation Market. Given that the technologies involved are used in clinical and therapeutic applications, such as stem cell therapy and personalized medicine, regulatory approvals are critical. Meeting the required regulatory standards for safety, efficacy, and manufacturing processes can be time-consuming and costly. Furthermore, ensuring the consistency and purity of isolated cells is essential for clinical applications, and failures in quality control can lead to safety concerns and affect the effectiveness of treatments. As the market grows, maintaining compliance with evolving regulations and ensuring robust quality control processes will remain key challenges for companies operating in this space.
Regional Analysis
North America
The North America region commands the largest share of the global Cell Isolation and Separation Market, capturing 36.5% of revenue in 2024. This dominance stems from the presence of mature biopharmaceutical and biotechnology industries, heavy investments in research and development across the U.S. and Canada, and strong adoption of advanced cell-separation technologies in both clinical and academic settings. High incidence of chronic diseases, robust healthcare infrastructure, and favorable regulatory frameworks further reinforce the region’s leadership in market uptake.
Europe
Europe holds the second-largest regional share, estimated at around 30%, driven by strong activity across Germany, the UK, France, and the Nordics. The region benefits from extensive academic research, government support for regenerative medicine, and a rapidly growing cell-therapy ecosystem. A key driver is the high demand for precision cell separation in oncology and immunotherapy research, with manufacturers leveraging Europe as a base for commercialization of new consumables and instruments. Cross-border regulatory harmonization and increasing adoption in emerging EU markets further support growth.
Asia Pacific
The Asia Pacific region is poised to register the fastest growth rate, though currently holds a smaller share of 25% of the market. Growth is propelled by expanding life-science research infrastructure in China, India, Japan, and South Korea, increasing healthcare expenditure, and rising adoption of cell-based therapies. Emerging economies within the region are investing heavily in biotechnology and diagnostics, creating significant opportunity for suppliers of instruments and consumables. The large patient populations and growing awareness of advanced therapy offerings underpin this rising regional importance.
Latin America
Latin America controls a modest market share, estimated at roughly 10-12%, with Brazil and Mexico being the primary contributors. Growth in the region is driven by improving healthcare infrastructure, increased investment in stem-cell research and regenerative medicine applications, and a rising need for diagnostics and cell therapy platforms. While still emerging, the region offers vendors opportunities to establish early-mover positions as research and clinical adoption accelerate, especially in private-sector specialized treatment centers.
Middle East & Africa
The Middle East & Africa region holds the smallest share of the market 8%, but is expected to experience steady expansion. Growth drivers include rising government expenditure in healthcare systems (especially in Gulf Cooperation Council countries), increasing partnerships for cell-therapy development, and the establishment of biotechnology hubs in select African nations. However, lower per-capita research funding and limited access to advanced technologies still restrain rapid uptake.
Market Segmentations
By Product
- Consumables
- Instruments
By Cell Type
- Human Cells
- Differentiated cells
- Stem cells
- Animal cells
By Cell Source
- Bone marrow
- Adipose tissue
- Cord blood/ Embryonic stem cells
By Technique
- Centrifugation- based cell isolation
- Surface marker- based cell isolation
- Filteration- based cell isolation
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the Cell Isolation and Separation Market is dynamic and increasingly driven by technological innovation and strategic consolidation among key players. Industry leaders such as Thermo Fisher Scientific, Inc., Becton, Dickinson and Company (BD), Danaher Corporation, Bio‑Rad Laboratories, Inc., Merck KGaA, Miltenyi Biotec GmbH, STEMCELL Technologies Inc. and Terumo Corporation consistently invest in enhancing their portfolios of instruments, consumables and automation. For instance, Thermo Fisher holds a broad product range spanning magnetic bead‑based kits, reagents and instruments and maintains a dominant global position. The market features a moderate level of concentration, with the top firms controlling well over half of total market share, yet continues to invite smaller niche players that compete via specialised microfluidics, label‑free sorting or AI‑enabled platforms. Mergers, acquisitions and partnerships remain pivotal strategies for competitive differentiation and geographic expansion, as companies strive to address emerging demands in cell therapy, regenerative medicine and single‑cell analysis.
Key Player Analysis
- Merck KGaA (Germany)
- Becton, Dickinson and Company (U.S.)
- Bio-Rad Laboratories Inc. (U.S.)
- GE Healthcare (U.S.)
- Beckman Coulter Inc. (U.S.)
- Miltenyi Biotec (Germany)
- STEMCELL Technologies Inc. (Canada)
- pluriSelect Life Science UG & Co. KG (Germany)
- Thermo Fisher Scientific Inc. (U.S.)
- Terumo BCT, Inc. (U.S.)
Recent Developments
- In August 2025, Akadeum Life Sciences partnered with Lonza Group and Excellos to integrate flotation‑based cell separation with cell‑therapy manufacturing workflows.
- In June 2025, STEMCELL Technologies Inc. acquired Cellular Highways Ltd, a company specialising in advanced cell‑sorting technologies for cell and gene therapy.
- In April 2024, Miltenyi Biotec and MiLaboratories announced a strategic partnership to combine MiLaboratories’ RNA‑kit and software technology with Miltenyi’s production capabilities to drive next‑generation therapies.
Report Coverage
The research report offers an in-depth analysis based on Product, Cell Type, Cell Source, Technique and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to continue its strong growth, driven by the increasing demand for advanced cell-based therapies and personalized medicine.
- Technological advancements in automation and AI will further enhance the precision and efficiency of cell isolation processes, facilitating high-throughput applications.
- The increasing adoption of cell isolation technologies in emerging markets, particularly in Asia-Pacific and Latin America, will provide new growth opportunities.
- Ongoing investments in regenerative medicine and stem cell therapies will drive demand for specialized cell isolation techniques, especially for stem cell research and treatment applications.
- Companies will continue to focus on the development of microfluidic-based and automated systems to reduce human error and improve scalability in cell separation processes.
- The trend towards point-of-care diagnostics will lead to the emergence of portable and user-friendly cell isolation devices.
- Regulatory advancements and approval for new cell-based therapies will expand the market scope, particularly in oncology and immunology.
- Rising healthcare expenditure globally, especially in biotechnology and pharmaceuticals, will support continued market growth and innovation.
- Strategic mergers and acquisitions among key players will continue, allowing for greater market consolidation and regional expansion.
- Increased focus on high-quality consumables, reagents, and kits will drive market competition, with a focus on cost-efficiency and product differentiation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Personalized Medicine
The need for individualized therapies, especially in oncology and regenerative medicine, is driving demand for precise cell isolation techniques to enable tailored treatments and improve patient outcomes.
Growth in Regenerative Medicine and Stem Cell Therapy
Increasing clinical adoption and research in regenerative medicine and stem cell therapies require advanced cell separation technologies to isolate and purify specific cell types for therapeutic applications.
Advancements in Automation and AI
Integration of automation and artificial intelligence into cell isolation processes is enhancing throughput, accuracy, and reproducibility, making these technologies more attractive for both research and clinical settings.
Rising Biotechnology and Pharmaceutical R&D Investments
Growing investments in biotechnology and pharmaceutical research are fueling the need for efficient cell isolation methods to support drug discovery, disease modeling, and cell-based therapy development.
Emergence of Point-of-Care Diagnostics
The shift toward decentralized healthcare and rapid diagnostics is increasing demand for portable, user-friendly cell isolation devices that can deliver timely results in clinical and remote settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cell Isolation and Separation Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cell Isolation and Separation Market projected to grow between 2025 and 2032?
Which Cell Isolation and Separation Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cell Isolation and Separation Market?
Who are the leading companies in the Cell Isolation and Separation Market?
Which region commanded the largest share of the Cell Isolation and Separation Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Consumables
- 1.2.2 Instruments
- 1.3 By Cell Type
- 1.3.1 Human Cells
- 1.3.2 Differentiated Cells
- 1.3.3 Stem Cells
- 1.3.4 Animal Cells
- 1.4 By Technique
- 1.4.1 Centrifugation-based Cell Isolation
- 1.4.2 Surface Marker-based Cell Isolation
- 1.4.3 Filtration-based Cell Isolation
- 1.5 By Cell Source
- 1.5.1 Bone Marrow
- 1.5.2 Adipose Tissue
- 1.5.3 Cord Blood/Embryonic Stem Cells
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5 billion → 2032: USD 11.86 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cell Isolation And Separation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cell Isolation And Separation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cell Isolation And Separation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cell Isolation And Separation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cell Isolation And Separation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cell Isolation And Separation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cell Isolation And Separation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cell Isolation And Separation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5 billion → 2032: USD 11.86 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cell Isolation And Separation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumables
- 12.3.7.2 Instruments
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Cell Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Human Cells
- 12.4.7.2 Differentiated Cells
- 12.4.7.3 Stem Cells
- 12.4.7.4 Animal Cells
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technique - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Centrifugation-based Cell Isolation
- 12.5.7.2 Surface Marker-based Cell Isolation
- 12.5.7.3 Filtration-based Cell Isolation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Cell Source - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Bone Marrow
- 12.6.7.2 Adipose Tissue
- 12.6.7.3 Cord Blood/Embryonic Stem Cells
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cell Isolation And Separation Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cell Isolation And Separation Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cell Isolation And Separation Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Thermo Fisher Scientific Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Becton, Dickinson and Company
- 17.4 Merck KGaA
- 17.5 Bio-Rad Laboratories Inc.
- 17.6 Miltenyi Biotec GmbH
- 17.7 STEMCELL Technologies Inc.
- 17.8 Terumo BCT, Inc.
- 17.9 pluriSelect Life Science UG & Co. KG
- 17.10 Beckman Coulter Inc.
- 17.11 GE Healthcare
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

