
Market Overview
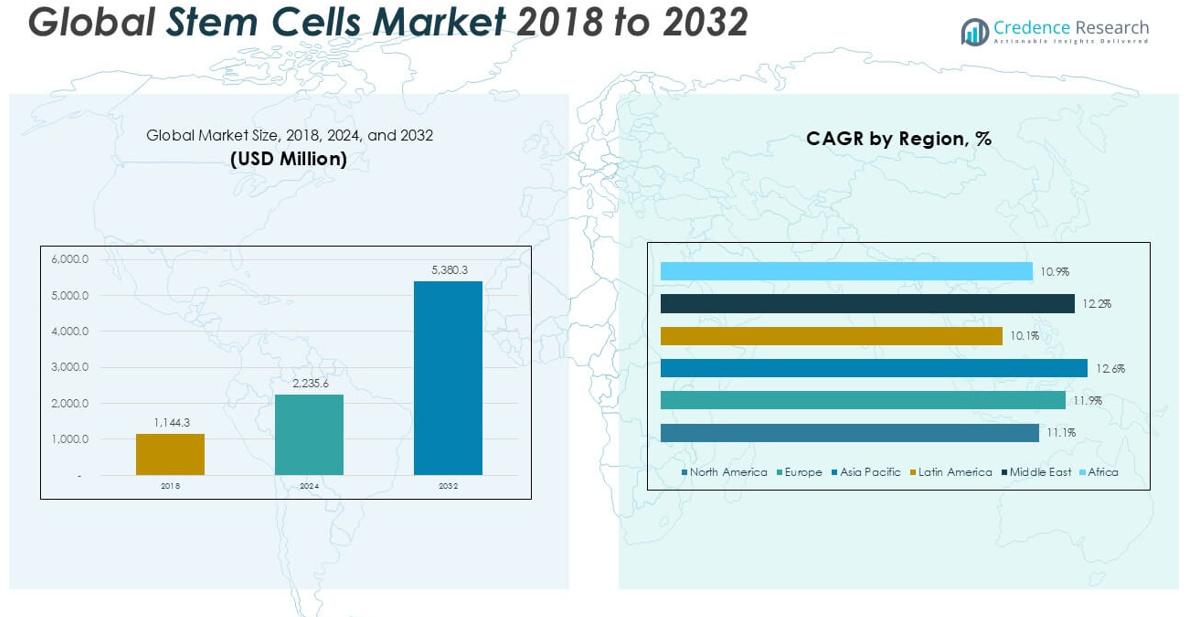
The Stem Cells Market size was valued at USD 1,144.3 million in 2018, increased to USD 2,235.6 million in 2024, and is anticipated to reach USD 5,380.3 million by 2032, at a CAGR of 11.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Stem Cells Market Size 2024 | USD 2,235.6 million |
| Stem Cells Market, CAGR | 11.66% |
| Stem Cells Market Size 2032 | USD 5,380.3 million |
The stem cells market is driven by leading players such as Advanced Cell Technology, Inc., Biotime, Inc., BrainStorm Cell Therapeutics, Caladrius, Cellartis AB, CellGenix GmbH, Genea BioCells, PromoCell GmbH, TiGenix, and Takara Holdings, Inc. These companies are focused on expanding their stem cell therapy portfolios, accelerating clinical trials, and strengthening their global presence through strategic collaborations and product innovations. North America dominates the global stem cells market, holding approximately 31.4% of the total market share in 2024, supported by advanced healthcare infrastructure, strong research funding, and a high concentration of key market players. Europe follows with a significant market share, while Asia Pacific is emerging as the fastest-growing region driven by rising clinical research activities and increasing healthcare investments.
Market Insights
- The global stem cells market was valued at USD 2,235.6 million in 2024 and is expected to reach USD 5,380.3 million by 2032, growing at a CAGR of 11.66% during the forecast period.
- Market growth is primarily driven by increasing applications in regenerative medicine, rising demand for personalized therapies, and expanding stem cell banking services.
- A key market trend is the growing focus on induced pluripotent stem cells (iPSCs) and strategic collaborations among major players to accelerate product development and global expansion.
- The market is competitive, with major players like Thermo Fisher Scientific, Lonza Group, and Takara Holdings focusing on innovation, while strict regulatory approvals and high therapy costs remain significant restraints.
- North America held the largest market share of around 31.4% in 2024, followed by Europe at 26.2%, and Asia Pacific as the fastest-growing region; Adult Stem Cells dominated the product segment due to broad clinical applications.
Market Segmentation Analysis:
By Product:
The Stem Cells market, segmented by product, is predominantly driven by the Adult Stem Cells (ASCs) category, which holds the largest market share due to their lower ethical concerns and widespread clinical applications. Within ASCs, Mesenchymal Stem Cells (MSCs) dominate, supported by their extensive use in regenerative therapies and immunomodulation. Increasing clinical trials and expanding indications in tissue repair and inflammatory diseases propel their growth. Human Embryonic Stem Cells (HESCs), Induced Pluripotent Stem Cells (iPSCs), and Very Small Embryonic Like Stem Cells follow, with iPSCs gaining traction due to their versatility and potential in personalized medicine despite regulatory hurdles.
- For instance, Mesoblast Limited has conducted over 15 Phase 3 clinical trials using its proprietary MSC-based platform for conditions like chronic heart failure and back pain.
By Type
In the Stem Cells market by type, the Allogeneic segment leads with a significant market share, owing to its advantages in off-the-shelf availability and large-scale production. Allogeneic stem cell therapies are increasingly preferred in clinical practices, particularly in oncology and hematology, where donor-derived cells offer robust treatment outcomes. The Autologous segment also holds a strong position, especially in personalized therapies, but is limited by higher preparation times and costs. The growing demand for ready-to-use products and expanding stem cell banking practices further strengthen the dominance of allogeneic stem cells in the market.
- For instance, Gamida Cell’s allogeneic cell therapy, Omidubicel, has been evaluated in a Phase 3 study involving 125 patients for hematologic malignancies, demonstrating faster neutrophil recovery compared to standard umbilical cord blood.
By Application
Based on application, Regenerative Medicine emerges as the dominant segment, capturing the largest market share, particularly driven by advancements in Neurology and Orthopedics. Neurological applications, including treatments for Parkinson’s disease, stroke, and spinal cord injuries, are expanding rapidly due to increasing disease prevalence and promising clinical results. Orthopedics follows closely, supported by rising cases of bone and joint disorders and the effectiveness of stem cell therapies in cartilage and bone regeneration. Drug Discovery and Development remains a key supporting segment, leveraging stem cells for toxicity testing and disease modeling, which accelerates pharmaceutical research and development processes.
Market Overview
Expanding Applications in Regenerative Medicine
The increasing adoption of stem cell therapies in regenerative medicine significantly drives market growth. Stem cells offer promising solutions for tissue repair and organ regeneration, addressing complex conditions such as neurodegenerative diseases, orthopedic injuries, and cardiovascular disorders. Continuous advancements in stem cell technologies, along with supportive clinical outcomes, are boosting their therapeutic acceptance. Additionally, the growing geriatric population, which is highly susceptible to chronic diseases, further fuels demand for regenerative treatments, positioning stem cell-based therapies as a critical component in modern healthcare solutions.
- For instance, Athersys, Inc. has enrolled over 1,000 patients globally in clinical trials for MultiStem®, an adult stem cell therapy targeting ischemic stroke and acute respiratory distress syndrome.
Rising Investments and Research Initiatives
Substantial investments by both public and private sectors in stem cell research are accelerating the development of advanced therapies. Governments worldwide are funding stem cell projects, while pharmaceutical and biotech companies are increasing R&D budgets to explore new clinical applications. The surge in clinical trials and collaborations between research institutes and key market players are enhancing the pipeline of stem cell-based treatments. These investments are not only expanding the therapeutic potential but are also fostering innovation in manufacturing and storage technologies, thereby supporting overall market expansion.
- For instance, the California Institute for Regenerative Medicine (CIRM) has allocated over $3.3 billion in funding for stem cell research projects across more than 300 programs since its inception.
Advancements in Stem Cell Banking
The growth of stem cell banking services has emerged as a pivotal market driver, offering secure preservation of valuable biological materials for future therapeutic use. Increasing awareness among parents about cord blood storage and the rising number of stem cell banks are contributing to this growth. Enhanced storage technologies and improved regulatory frameworks support the reliability and safety of stem cell preservation. The accessibility of stem cells for personalized therapies and the growing practice of preventive healthcare are further encouraging consumers to invest in stem cell banking solutions.
Key Trends & Opportunities
Emergence of Induced Pluripotent Stem Cells (iPSCs)
The rising interest in induced pluripotent stem cells presents a significant market trend, as iPSCs offer considerable advantages in disease modeling, drug discovery, and potential therapeutic applications without the ethical concerns linked to embryonic stem cells. Researchers are increasingly exploring iPSCs for personalized regenerative therapies and genetic disease treatment. Advancements in iPSC reprogramming techniques and increasing clinical trials are likely to expand their use in complex disease management. The versatility and compatibility of iPSCs position them as a transformative opportunity in the future of stem cell research.
- For instance, FUJIFILM Cellular Dynamics developed 12 distinct iPSC-derived cell types including cardiomyocytes, neurons, and hepatocytes and opened a USD 21 million cGMP facility in 2020 to support clinical-grade production of dopamine-producing neural cells and cardiac progenitors.
Strategic Collaborations and Global Expansion
Key players in the stem cells market are actively engaging in partnerships, mergers, and global expansions to strengthen their market presence and accelerate product development. Collaborations between biotech firms, pharmaceutical companies, and research institutes are facilitating the advancement of stem cell technologies and the commercialization of innovative therapies. Additionally, companies are expanding their operations into emerging markets, where regulatory support and growing healthcare infrastructure offer new growth avenues. This trend of strategic alliances is expected to unlock further opportunities and enhance market competitiveness.
- For instance, Catalent opened a 60,000 sq ft commercial-scale cell therapy manufacturing facility in Gosselies, Belgium, with 12 GMP clean rooms and 67,000 sq ft of clinical space to support both autologous and allogeneic programs.
Key Challenges
Stringent Regulatory and Ethical Constraints
The stem cells market faces significant regulatory and ethical challenges, particularly concerning embryonic stem cell research. Strict approval processes, regional regulatory variations, and ongoing ethical debates limit the pace of clinical adoption and commercialization. These constraints increase the time and cost involved in product development, discouraging smaller companies from entering the market. Compliance with evolving guidelines remains a major hurdle, potentially slowing down innovation and limiting the scope of certain stem cell therapies in various countries.
High Cost of Stem Cell Therapies
The high cost associated with stem cell treatments poses a considerable challenge to market growth. Expenses related to stem cell harvesting, processing, storage, and clinical application make these therapies unaffordable for a large segment of the population, particularly in low- and middle-income countries. Additionally, limited insurance coverage for stem cell procedures restricts patient access. The financial burden on both healthcare providers and patients remains a key barrier, necessitating cost optimization and broader reimbursement frameworks to support market scalability.
Complexity in Manufacturing and Standardization
Stem cell manufacturing involves complex, highly sensitive processes that require strict quality control and specialized infrastructure. Variability in stem cell sources, handling procedures, and cultivation techniques makes achieving product consistency a significant challenge. The lack of standardized protocols affects scalability and raises concerns about safety and efficacy. These complexities not only slow down production but also contribute to higher operational costs. Overcoming these technical barriers is essential for ensuring large-scale, reliable stem cell production and maintaining regulatory compliance.
Regional Analysis
North America
North America held the largest market share of approximately 31.4% in the global stem cells market in 2024, with a market size rising from USD 373.05 million in 2018 to USD 709.25 million in 2024, and is projected to reach USD 1,644.22 million by 2032 at a CAGR of 11.1%. The region’s leadership is driven by advanced healthcare infrastructure, strong research funding, and the rapid adoption of regenerative therapies. Increasing clinical trials, supportive regulatory frameworks, and the presence of key biotechnology firms further support market dominance, particularly in the United States and Canada.
Europe
Europe accounted for a market share of approximately 26.2% in 2024, growing from USD 298.78 million in 2018 to USD 592.24 million in 2024, and is anticipated to reach USD 1,452.68 million by 2032 at a CAGR of 11.9%. The region benefits from extensive research collaborations, favorable government initiatives, and growing stem cell banking awareness. Countries like Germany, the UK, and France are key contributors to market growth, supported by the rising demand for advanced regenerative treatments and increasing prevalence of chronic diseases. Expanding applications in neurology and orthopedics further drive the European market.
Asia Pacific
Asia Pacific is witnessing the fastest growth in the stem cells market, with a CAGR of 12.6% and a market share of around 24% in 2024. The market expanded from USD 264.34 million in 2018 to USD 544.20 million in 2024, and is projected to reach USD 1,398.88 million by 2032. Rapidly developing healthcare infrastructure, increasing investment in stem cell research, and the growing presence of clinical research organizations are key growth factors. Countries like China, Japan, and India are emerging as major hubs for stem cell therapies due to regulatory support and growing medical tourism.
Latin America
Latin America captured a market share of approximately 9.5% in 2024, growing from USD 119.24 million in 2018 to USD 215.51 million in 2024, with expected growth to USD 462.71 million by 2032 at a CAGR of 10.1%. The region shows steady progress driven by expanding healthcare access, increasing public awareness of regenerative medicine, and improving investment climate in biotechnology. Brazil and Mexico are key contributors, supported by growing stem cell research initiatives. However, the market still faces moderate growth limitations due to cost barriers and limited clinical infrastructure in some countries.
Middle East
The Middle East stem cells market demonstrated strong growth with a CAGR of 12.2%, increasing from USD 53.44 million in 2018 to USD 107.56 million in 2024, and is projected to reach USD 269.01 million by 2032, capturing a market share of approximately 4.7% in 2024. The market benefits from rising healthcare investments, growing stem cell banking, and increasing demand for advanced treatments, particularly in countries like the UAE and Saudi Arabia. Government-backed healthcare reforms and partnerships with international research organizations are further accelerating the adoption of stem cell therapies in the region.
Africa
Africa accounted for a modest market share of 3% in 2024, growing from USD 35.47 million in 2018 to USD 66.81 million in 2024, and is anticipated to reach USD 152.80 million by 2032 at a CAGR of 10.9%. The African market is gradually developing due to improving healthcare access and rising awareness of stem cell therapies. South Africa leads the regional market, driven by growing medical research activities and expanding stem cell banking services. Despite growth opportunities, the region still faces challenges such as limited infrastructure, affordability issues, and regulatory constraints that may slow widespread adoption.
Market Segmentations:
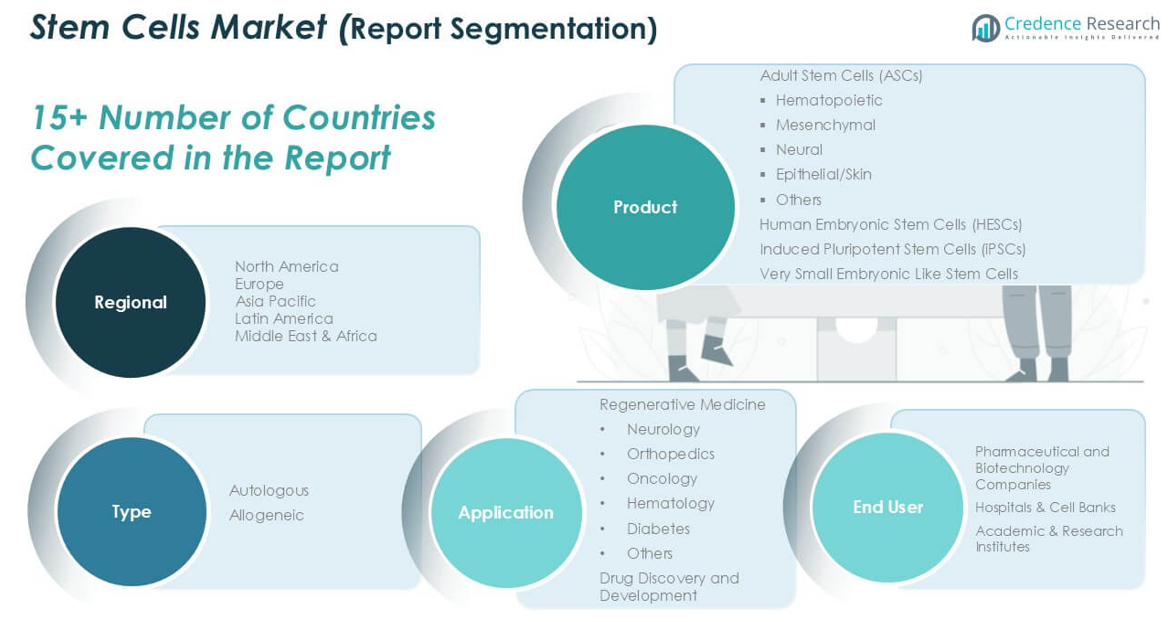
By Product
- Adult Stem Cells (ASCs)
- Hematopoietic
- Mesenchymal
- Neural
- Epithelial/Skin
- Others
- Human Embryonic Stem Cells (HESCs)
- Induced Pluripotent Stem Cells (iPSCs)
- Very Small Embryonic Like Stem Cells
By Type
- Autologous
- Allogeneic
By Application
- Regenerative Medicine
- Neurology
- Orthopedics
- Oncology
- Hematology
- Diabetes
- Others
- Drug Discovery and Development
By End User
- Pharmaceutical and Biotechnology Companies
- Hospitals & Cell Banks
- Academic & Research Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The stem cells market is highly competitive, featuring a mix of established biotechnology companies and emerging players focused on developing advanced stem cell therapies. Major companies such as Advanced Cell Technology, Inc., Biotime, Inc., BrainStorm Cell Therapeutics, Caladrius, Cellartis AB, CellGenix GmbH, Genea BioCells, PromoCell GmbH, TiGenix, and Takara Holdings, Inc. are actively engaged in research, clinical trials, and the commercialization of innovative stem cell solutions. These firms leverage strategic partnerships, mergers, and acquisitions to strengthen their market positions and expand their global reach. Continuous investment in R&D, expansion of product portfolios, and advancements in stem cell manufacturing are key competitive strategies. North America and Europe remain major hubs for these companies due to favorable regulatory support and a well-established healthcare infrastructure. Additionally, several players are exploring growth opportunities in Asia Pacific, driven by rising healthcare demand and improving clinical capabilities. The market remains dynamic, driven by rapid technological progress and competitive innovation.
Key Player Analysis
- Advanced Cell Technology, Inc.
- Biotime, Inc.
- BrainStorm Cell Therapeutics
- Caladrius
- Cellartis AB
- CellGenix GmbH
- Genea BioCells
- PromoCell GmbH
- TiGenix
- Takara Holdings, Inc.
Recent Developments
- In November 2024, Advanced Cell Technologyannounced the successful generation of human embryonic stem cells using nuclear transfer technology. This involved fusing a human somatic cell with a bovine egg cell (after the nucleus was removed from the egg cell). This method has the potential to produce patient-specific stem cells, which could be used to overcome issues like tissue rejection in transplantation therapies.
- In April 2023, US FDA approved Omisirge (omidubicel-onlv), a substantially modified allogeneic (donor) cord blood-based cell therapy. In July 2022, CORESTEM (South Korea) continued enrolling participants for the Phase 3 clinical trial of NeuroNata-R. This therapy has received conditional approval for treating ALS patients in South Korea
- In April 2024, PromoCell GmbH launched the Cryo-SFM Plus cryopreservation medium to preserve primary cells, stem cells, or established cell lines.
- In January 2024, STEMCELL Technologies, Inc. acquired Propagenix Inc., enabling STEMCELL to develop products based on Propagenix’s EpiX technology in regenerative medicine.
- In December 2023, the University of Texas at San Antonio (UTSA) and GenCure, a subsidiary of BioBridge Global, formalized their collaboration through the signing of a master services agreement. This agreement outlines their joint efforts in advancing the development of cellular therapy products, services, and testing.
- In October 2023, bio, a company dedicated to programming human cells for innovative treatments, unveiled its latest product, ioCRISPR-Ready Cells. These cells are tailored for scientists aiming to create gene knockouts in human cells with physiological relevance.
- In September 2023, SKAN Research Trust(SKAN) collaborated with the Wellcome-MRC Cambridge Stem Cell Institute (CSCI) based in the UK. The partnership includes a joint research initiative focused on investigating the genomic patterns associated with age-related neurodegenerative diseases within an Indian cohort.
Market Concentration & Characteristics
The Stem Cells Market demonstrates a moderately concentrated structure, with several leading global and regional players competing for market share. It is characterized by rapid technological advancements, extensive clinical research, and growing commercialization of stem cell therapies. The market shows strong alignment with regenerative medicine, drug discovery, and personalized healthcare, which drives consistent demand. Companies in this market actively pursue partnerships, acquisitions, and product development to strengthen their competitive positions. It requires significant investment in research and compliance with strict regulatory standards, which limits the entry of smaller players. The market also relies on the availability of skilled professionals and advanced infrastructure, particularly in North America and Europe. Product innovation, stem cell banking expansion, and rising clinical trials influence the competitive dynamics. The demand for adult stem cells, especially mesenchymal stem cells, remains dominant due to their safety profile and clinical acceptance. The market continues to evolve with increasing applications in neurology, orthopedics, and oncology.
Report Coverage
The research report offers an in-depth analysis based on Product, Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The stem cells market is expected to witness steady growth driven by increasing demand for regenerative therapies.
- Advancements in stem cell banking and preservation technologies will support long-term market expansion.
- The use of induced pluripotent stem cells (iPSCs) will continue to rise due to their versatility and ethical acceptance.
- Growing investment in clinical trials will accelerate the development of new stem cell-based treatments.
- Asia Pacific is likely to emerge as a key growth region due to improving healthcare infrastructure and regulatory support.
- Collaborations between biotechnology companies and research institutes will drive innovation and product development.
- The demand for allogeneic stem cell therapies will increase owing to their ready-to-use availability.
- Neurology, orthopedics, and oncology will remain dominant application areas for stem cell therapies.
- Ongoing regulatory improvements are expected to streamline the approval process for stem cell products.
- The market will face continued challenges related to therapy costs, manufacturing complexities, and standardization.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Applications in Regenerative Medicine
Stem cells are increasingly used for tissue repair and organ regeneration, addressing complex conditions such as neurodegenerative diseases, orthopedic injuries, and cardiovascular disorders. This broadening of clinical applications is driving market growth as more therapies reach clinical and commercial stages.
Rising Investments and Research Initiatives
Substantial funding from both public and private sectors is accelerating the development of advanced stem cell therapies. Increased R&D budgets, government grants, and collaborative clinical trials are expanding the pipeline of stem cell-based treatments and supporting innovation in manufacturing and storage technologies.
Advancements in Stem Cell Banking
The growth of stem cell banking services, including cord blood and tissue preservation, is making stem cells more accessible for future therapeutic use. Improved storage technologies and regulatory frameworks are increasing consumer confidence and driving adoption of banking services.
Emergence of Induced Pluripotent Stem Cells (iPSCs)
iPSCs offer significant advantages for disease modeling, drug discovery, and personalized regenerative therapies without the ethical concerns of embryonic stem cells. Ongoing advancements in iPSC technology and increasing clinical trials are expanding their use in complex disease management.
Strategic Collaborations and Global Expansion
Key market players are engaging in partnerships, mergers, and global expansions to accelerate product development and reach new markets. These collaborations facilitate the advancement of stem cell technologies and the commercialization of innovative therapies, especially in emerging regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Stem Cells Market?
What are the key segments within the Stem Cells Market?
What are some challenges faced by the Stem Cells Market?
Who are the major players in the Stem Cells Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Autologous
- 1.2.2 Allogeneic
- 1.3 By Product
- 1.3.1 Adult Stem Cells (ASCs)
- 1.3.2 Human Embryonic Stem Cells (HESCs)
- 1.3.3 Induced Pluripotent Stem Cells (iPSCs)
- 1.3.4 Very Small Embryonic Like Stem Cells
- 1.4 By End User
- 1.4.1 Pharmaceutical and Biotechnology Companies
- 1.4.2 Hospitals & Cell Banks
- 1.4.3 Academic & Research Institutes
- 1.5 By Application
- 1.5.1 Regenerative Medicine
- 1.5.2 Drug Discovery and Development
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,235.6 million → 2032: USD 5,380.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Stem Cells Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Stem Cells Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Stem Cells Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Stem Cells Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Stem Cells Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Stem Cells Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Stem Cells Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Stem Cells Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,235.6 million → 2032: USD 5,380.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Stem Cells Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Autologous
- 12.3.7.2 Allogeneic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Adult Stem Cells (ASCs)
- 12.4.7.2 Human Embryonic Stem Cells (HESCs)
- 12.4.7.3 Induced Pluripotent Stem Cells (iPSCs)
- 12.4.7.4 Very Small Embryonic Like Stem Cells
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pharmaceutical and Biotechnology Companies
- 12.5.7.2 Hospitals & Cell Banks
- 12.5.7.3 Academic & Research Institutes
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Regenerative Medicine
- 12.6.7.2 Drug Discovery and Development
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Stem Cells End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Stem Cells Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Stem Cells Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Stem Cells Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Advanced Cell Technology, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Biotime, Inc.
- 18.4 BrainStorm Cell Therapeutics
- 18.5 Caladrius
- 18.6 Cellartis AB
- 18.7 CellGenix GmbH
- 18.8 Genea BioCells
- 18.9 PromoCell GmbH
- 18.10 TiGenix
- 18.11 Takara Holdings, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

