
Market Overview
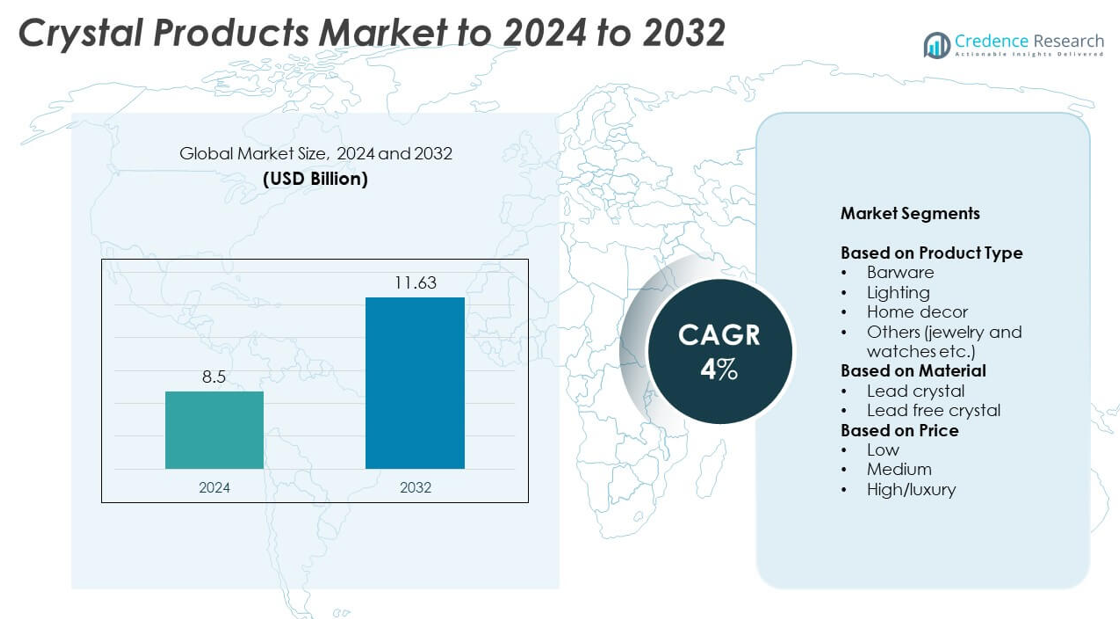
Crystal Products Market size was valued USD 8.5 Billion in 2024 and is anticipated to reach USD 11.63 Billion by 2032, at a CAGR of 4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Crystal Products Market Size 2024 | USD 8.5 Billion |
| Crystal Products Market, CAGR | 4% |
| Crystal Products Market Size 2032 | USD 11.63 Billion |
The crystal products market is led by major players such as Swarovski, Waterford, Baccarat, Lalique, Bormioli Rocco, Dartington Crystal, Lucaris, and Crystal Bohemia. These companies dominate through a combination of craftsmanship, premium quality, and innovative design. They focus on expanding product portfolios across luxury home décor, tableware, and lighting segments to cater to rising consumer demand for aesthetic and personalized items. North America leads the global market with a 34% share, driven by strong purchasing power and a mature luxury retail sector. Europe follows with 29%, supported by its deep-rooted crystal manufacturing heritage and growing tourism-driven demand.
Market Insights
- The crystal products market was valued at USD 8.5 Billion in 2024 and is projected to reach USD 11.63 Billion by 2032, expanding at a CAGR of 4% during the forecast period.
- Growing demand for luxury home décor, gifting products, and premium tableware drives global market expansion, supported by rising disposable incomes and urban lifestyle upgrades.
- The market trends highlight increasing adoption of sustainable, lead-free crystals and personalized designs enhanced through advanced cutting and engraving technologies.
- Competition remains strong as global brands focus on product differentiation, craftsmanship, and online retail expansion, while smaller players face high production costs and limited scalability.
- Regionally, North America leads with a 34% share, followed by Europe with 29% and Asia Pacific with 25%; within product types, barware dominates with 38% of the market due to strong consumer preference for luxury dining and entertainment accessories.
Market Segmentation Analysis:
By Product Type
The barware segment dominated the crystal products market in 2024 with a 38% share. Rising consumer preference for premium glassware in restaurants, hotels, and luxury homes drives this dominance. Growth in gifting culture and increasing household spending on aesthetic tableware further enhance segment expansion. Manufacturers are introducing hand-cut and laser-engraved crystal barware to meet rising demand for customized products. The lighting segment follows, supported by the growing trend of decorative crystal chandeliers in commercial and residential spaces, reflecting luxury and sophistication in interior design.
- For instance, Moser confirms its luxury crystal is lead-free (0%), positioning it as a non-toxic alternative to traditional lead crystal.
By Material
Lead crystal held the largest market share of 56% in 2024, driven by its superior clarity and brilliance. Its popularity in fine dining, luxury lighting, and collectible products continues to support dominance. The material’s refractive properties make it ideal for intricate designs and high-end decorative pieces. However, environmental concerns and consumer shift toward non-toxic materials are driving growth in lead-free crystal products. Manufacturers are adopting sustainable production methods to align with global health and environmental safety standards, gradually increasing the adoption of eco-friendly alternatives.
- For instance, In a 2016 factory visit, it was noted that Riedel's machine-production lines could make approximately 91,000 pieces per day.
By Price
The high or luxury segment accounted for 47% of the market in 2024, leading the price-based segmentation. Demand for handcrafted crystal pieces, designer collections, and limited-edition decor items drives segment growth. Consumers in premium income groups and hospitality sectors increasingly favor luxury crystal brands for exclusivity and artistic craftsmanship. Additionally, global expansion of luxury retail outlets and online luxury marketplaces has strengthened distribution. While medium-priced products serve the mid-tier consumer base, the luxury segment remains the key growth contributor due to brand prestige and gifting demand.
Key Growth Drivers
Rising Demand for Luxury Home Décor
Growing consumer preference for luxury home décor products drives crystal product adoption. Increasing disposable income and urbanization encourage investment in aesthetic interior designs. Crystal-based lighting, vases, and decorative pieces enhance premium interiors, boosting residential and commercial demand. The expansion of online luxury retail platforms also fuels accessibility and awareness, supporting market penetration across emerging economies.
- For instance, Preciosa Lighting installed its "Pearl Wonder" installation in the Broadway Ballroom at the New York Marriott Marquis. This project consists of eight fixtures, with each being approximately 40 meters in length. These fixtures utilize a total of 4,250 hand-blown, triplex-opal spheres, each measuring 12 centimetres in diameter.
Expanding Hospitality and Gifting Sectors
Hotels, resorts, and event venues increasingly use crystal tableware, lighting, and decorative pieces to elevate guest experience. The hospitality sector’s focus on luxury aesthetics has raised global demand. Similarly, gifting occasions such as weddings, anniversaries, and corporate events promote personalized crystal products. The integration of engraving and customized designs enhances product appeal, strengthening sales in premium retail channels.
- For instance, Waterford’s city-centre facility in Ireland melts over 750 tonnes of crystal annually and serves visitors at its experience centre.
Innovation in Design and Manufacturing Technology
Advanced manufacturing technologies, including laser cutting and 3D crystal engraving, are transforming product appeal. These innovations improve precision, durability, and artistic value, attracting high-end buyers. Brands are focusing on blending traditional craftsmanship with modern techniques to cater to evolving consumer preferences. This technological shift supports consistent quality and enables mass customization, expanding product offerings across global markets.
Key Trends and Opportunities
Shift Toward Sustainable and Lead-Free Crystals
Growing environmental awareness is promoting lead-free crystal production. Consumers are increasingly opting for eco-friendly alternatives that maintain brilliance without harmful materials. Manufacturers are investing in green production processes and recycled materials to align with global sustainability goals. This shift presents a major opportunity for brands to attract health-conscious and environmentally aware customers.
- For instance, RCR Cristalleria Italiana specifies its Eco-Crystal is 100% recyclable, aligning with greener material trends.
Growth of Online and Omnichannel Retailing
Digitalization is reshaping the crystal products market. Premium crystal brands are expanding through e-commerce platforms and omnichannel strategies, enhancing product reach. Online stores offer detailed customization, secure delivery, and wider product visibility. The convenience of digital shopping, coupled with immersive virtual showrooms, strengthens consumer engagement and drives cross-border sales.
- For instance, Daum regularly issues numbered limited editions, such as a centerpiece limited to 125 pieces and vases limited to 375 pieces-supporting customization and exclusivity.
Rising Popularity of Personalized Luxury Products
Consumers increasingly favor unique, custom-designed crystal pieces reflecting personal taste and exclusivity. Brands offering engraving and bespoke options experience higher brand loyalty. This trend is especially strong in corporate gifting and event décor segments. The personalization movement allows manufacturers to charge premium prices while differentiating their collections in a competitive market.
Key Challenges
High Production Costs and Energy Consumption
Crystal production involves complex processes requiring high temperatures and skilled craftsmanship, increasing operational costs. Energy-intensive melting and cutting stages raise production expenses and limit scalability. Small manufacturers struggle to maintain profitability under these conditions. The reliance on skilled labor also increases production lead time, posing a significant cost management challenge.
Rising Competition from Alternative Materials
The market faces increasing competition from glass, acrylic, and ceramic substitutes. These materials offer similar aesthetic appeal at lower prices, attracting cost-sensitive consumers. Innovations in synthetic glass designs also reduce the visual difference between real and imitation crystal. Such competition pressures manufacturers to differentiate through quality, craftsmanship, and branding to sustain market share.
Regional Analysis
North America
North America held a 34% share of the global crystal products market in 2024. The region’s dominance stems from strong consumer preference for luxury home décor and premium dining products. The United States leads due to high purchasing power and an established hospitality industry. Demand for crystal barware and lighting products continues to grow, driven by upscale restaurants and interior design trends. Expanding e-commerce and personalized gifting options further enhance regional sales. Manufacturers are also focusing on sustainable and lead-free crystal variants to align with growing environmental awareness across North American consumers.
Europe
Europe accounted for 29% of the crystal products market share in 2024, driven by a rich tradition of glassmaking and craftsmanship. Countries such as France, Germany, and Italy remain major producers and exporters of luxury crystal goods. The region benefits from a well-established retail network and strong demand for decorative and collectible crystal items. Growth in luxury tourism and hospitality continues to support high-end product sales. European brands are focusing on combining artisanal techniques with modern design trends, maintaining the region’s stronghold in the global premium crystal industry.
Asia Pacific Asia Pacific captured 25% of the market share in 2024, emerging as one of the fastest-growing regions. Rising disposable incomes and expanding urban lifestyles in China, Japan, and India drive crystal product demand. Growing adoption of luxury home décor and increasing wedding and gifting activities contribute to market expansion. Domestic manufacturers are introducing affordable yet premium-quality crystal goods, making them accessible to middle-income consumers. The growth of online retail channels and a shift toward eco-friendly materials further strengthen the market outlook across the Asia Pacific region.
Latin America
Latin America held an 8% share of the crystal products market in 2024, supported by growing interest in premium interior products. Countries such as Brazil and Mexico are seeing higher consumer spending on home décor and lifestyle goods. The region’s expanding hospitality sector also contributes to increased use of decorative crystal lighting and tableware. However, import dependency and fluctuating economic conditions limit large-scale adoption. Manufacturers are targeting affluent urban consumers and luxury hotels through exclusive retail partnerships to enhance their market presence in this emerging region.
Middle East and Africa
The Middle East and Africa accounted for 4% of the global market share in 2024. Rising investments in luxury hospitality, tourism, and real estate developments drive demand for crystal lighting and decorative accessories. Wealthy consumer segments in the UAE, Saudi Arabia, and South Africa favor high-end crystal pieces for aesthetic interiors. Luxury retail expansion and increased availability of international brands support regional growth. However, the market remains concentrated in premium urban centers. Continued infrastructure development and rising lifestyle spending are expected to support gradual market expansion across the region.
Market Segmentations:
By Product Type
- Barware
- Lighting
- Home decor
- Others (jewelry and watches etc.)
By Material
- Lead crystal
- Lead free crystal
By Price
- Low
- Medium
- High/luxury
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The crystal products market features prominent players such as Swarovski, Bormioli Rocco, Dartington Crystal, Lalique, Ravenscroft Crystal, Lucaris, Waterford, Baccarat, Anchor Hocking, Saint-Louis, Williams-Sonoma, Crystal Bohemia, Lladro, La Opala, MCM, Asfour Crystal, and NDK. The market is characterized by intense competition, with companies focusing on design innovation, premium quality, and brand differentiation. Manufacturers are investing in advanced production techniques such as precision cutting, 3D engraving, and lead-free compositions to meet evolving consumer preferences. Sustainability, personalization, and craftsmanship remain central to competitive strategies, especially in luxury and gifting segments. Several firms are expanding through e-commerce and omnichannel retailing to strengthen global reach and customer engagement. Collaborations with designers and interior brands enhance aesthetic appeal and diversify product portfolios. Overall, competitive rivalry continues to intensify as global and regional producers emphasize exclusivity, quality, and sustainability to maintain their share in the evolving crystal products industry.
Key Player Analysis
- Swarovski
- Bormioli Rocco
- Dartington Crystal
- Lalique
- Ravenscroft Crystal
- Lucaris
- Waterford
- Baccarat
- Anchor Hocking
- Saint-Louis
- Williams-Sonoma
- Crystal Bohemia
- Lladro
- La Opala
- MCM
- Asfour Crystal
- NDK
Recent Developments
- In 2025, NDK announced the launch of differential output crystal oscillators with frequencies of 156.25 MHz and 312.5 MHz to support next-generation optical communication from 800G to 1.6T.
- In 2024, MCM introduces a limited-edition Swarovski Crystal fragrance with a redesigned bottle featuring about 1,100 hand-applied Swarovski crystals. Only 150 bottles are available globally.
- In 2023, Asfour Crystal showcased its creations at Gewan Island in Qatar, a prominent project in the Middle East.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Price and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for luxury and decorative crystal products will continue to rise in premium households.
- Manufacturers will focus on lead-free and sustainable crystal materials to meet eco regulations.
- Advancements in laser engraving and 3D cutting will enhance design precision and creativity.
- Online retail and virtual showrooms will become major sales channels for global brands.
- Personalized and custom-designed crystal pieces will gain strong traction among consumers.
- Growth in hospitality and tourism sectors will boost use of crystal décor and tableware.
- Partnerships between artisans and designers will expand product innovation and variety.
- Emerging markets in Asia and the Middle East will experience rapid adoption of luxury crystal goods.
- Increased gifting culture will drive steady demand across corporate and personal segments.
- Integration of digital marketing and social media influence will strengthen brand visibility worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Luxury Home Décor Demand
Increasing disposable incomes and urbanization are driving consumers to invest in premium home décor, with crystal products such as lighting, vases, and decorative pieces enhancing the aesthetic appeal of interiors in both residential and commercial spaces.
Expanding Hospitality and Gifting Sectors
Hotels, resorts, and event venues are increasingly adopting crystal tableware and lighting to elevate guest experiences, while the popularity of personalized crystal gifts for weddings, anniversaries, and corporate events is boosting market growth.
Innovation in Design and Manufacturing
Advancements in laser cutting, 3D engraving, and precision manufacturing are enabling brands to offer intricate, customized, and high-quality crystal products, attracting high-end buyers and supporting mass customization.
Shift Toward Sustainable and Lead-Free Crystals
Growing environmental awareness and health concerns are prompting manufacturers to develop lead-free and eco-friendly crystal alternatives, appealing to health-conscious and environmentally aware consumers and opening new market opportunities.
Growth of Online and Omnichannel Retailing
The expansion of e-commerce and omnichannel strategies is increasing the accessibility of crystal products, allowing brands to reach a wider audience, offer customization, and enhance consumer engagement through digital platforms.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Crystal Products Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Crystal Products Market projected to grow between 2025 and 2032?
Which Crystal Products Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Crystal Products Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Price
- 1.2.1 Low
- 1.2.2 Medium
- 1.2.3 High/luxury
- 1.3 By Material
- 1.3.1 Lead crystal
- 1.3.2 Lead free crystal
- 1.4 By Product Type
- 1.4.1 Barware
- 1.4.2 Lighting
- 1.4.3 Home decor
- 1.4.4 Others (jewelry and watches etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8.5 Billion → 2032: USD 11.63 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Crystal Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Crystal Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Crystal Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Crystal Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Crystal Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Crystal Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Crystal Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Crystal Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8.5 Billion → 2032: USD 11.63 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Crystal Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Price - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Low
- 12.3.7.2 Medium
- 12.3.7.3 High/luxury
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lead crystal
- 12.4.7.2 Lead free crystal
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Barware
- 12.5.7.2 Lighting
- 12.5.7.3 Home decor
- 12.5.7.4 Others (jewelry and watches etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Crystal Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Crystal Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Crystal Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Swarovski
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Waterford
- 17.4 Baccarat
- 17.5 Lalique
- 17.6 Bormioli Rocco
- 17.7 Dartington Crystal
- 17.8 Lucaris
- 17.9 Crystal Bohemia
- 17.10 Asfour Crystal
- 17.11 Saint-Louis
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

