
Market Overview:
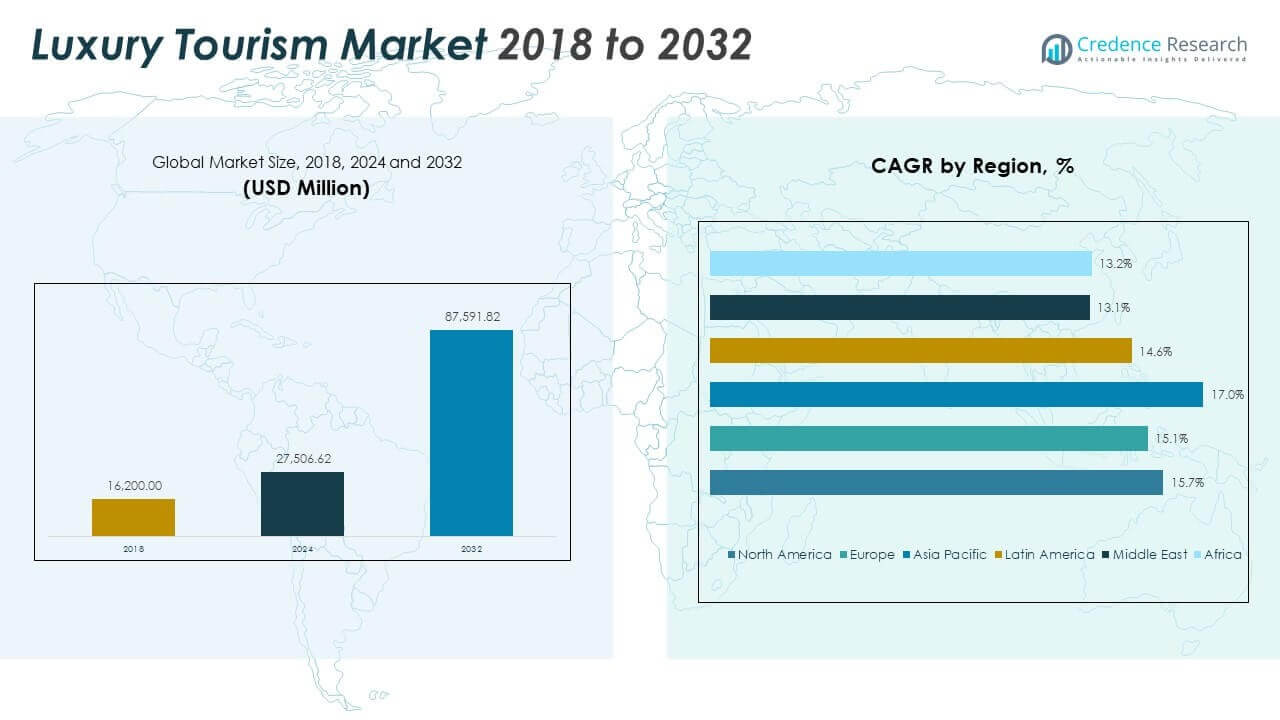
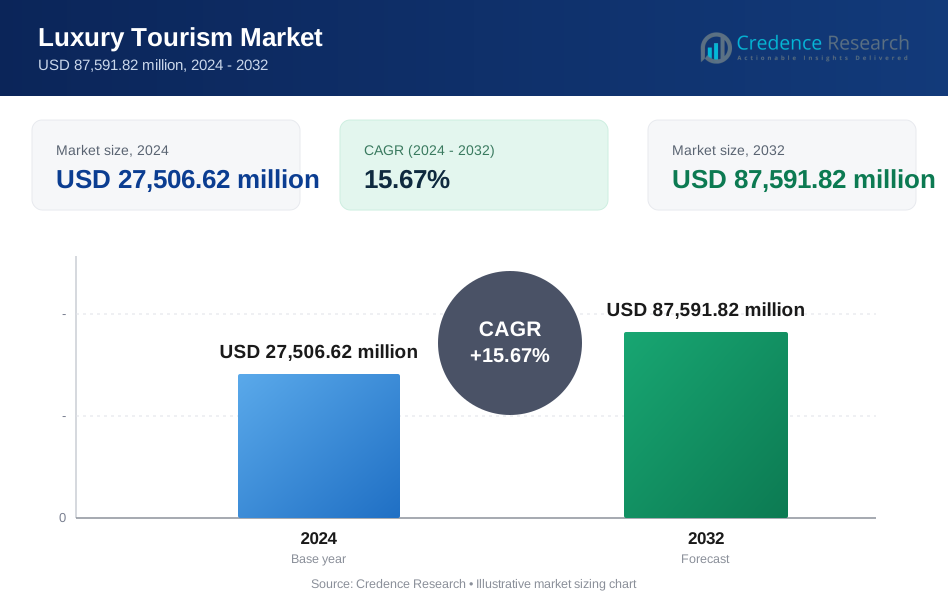
The Luxury Tourism Market size was valued at USD 16,200.00 million in 2018 to USD 27,506.62 million in 2024 and is anticipated to reach USD 87,591.82 million by 2032, at a CAGR of 15.67% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Tourism Market Size 2024 | USD 27,506.62 Million |
| Luxury Tourism Market, CAGR | 15.67% |
| Luxury Tourism Market Size 2032 | USD 87,591.82 Million |
High-net-worth individuals and affluent travelers are driving strong demand for bespoke travel services. Travelers increasingly prefer privacy, personalization, and premium experiences over traditional package tours. Wellness retreats, cultural immersion, and adventure-based luxury tours are gaining traction. Technological advancements such as AI-powered concierge apps and virtual booking assistants improve service delivery. Growing interest in eco-luxury and responsible tourism also supports demand. Premium airlines, boutique hotels, and curated itineraries shape the evolving market landscape. Rising disposable income and expanding luxury infrastructure in emerging economies boost growth.
Europe currently dominates the market due to strong travel infrastructure, luxury brand presence, and cultural appeal. North America follows closely, with steady demand from outbound U.S. travelers and corporate luxury segments. Asia Pacific is the fastest-growing region, driven by rising affluence in China, India, and Southeast Asia. The Middle East shows strong momentum through strategic investments in high-end hospitality. Latin America and Africa are emerging as niche destinations for eco-luxury, heritage, and expedition travel. Demand in these regions grows with infrastructure development and interest in unique, less crowded experiences.
Market Insights:
- The Luxury Tourism Market was valued at USD 16,200.00 million in 2018, USD 27,506.62 million in 2024, and is projected to reach USD 87,591.82 million by 2032, growing at a CAGR of 15.67%.
- Europe led the market with a 37.47% share in 2024 due to strong infrastructure and cultural depth; North America followed with 25.15% share, driven by outbound travelers and corporate luxury demand; Asia Pacific held 26.20% share with growing HNWIs and premium offerings.
- Asia Pacific is the fastest-growing region with a 17.0% CAGR, fueled by rising affluence, expanding hospitality infrastructure, and high digital travel adoption.
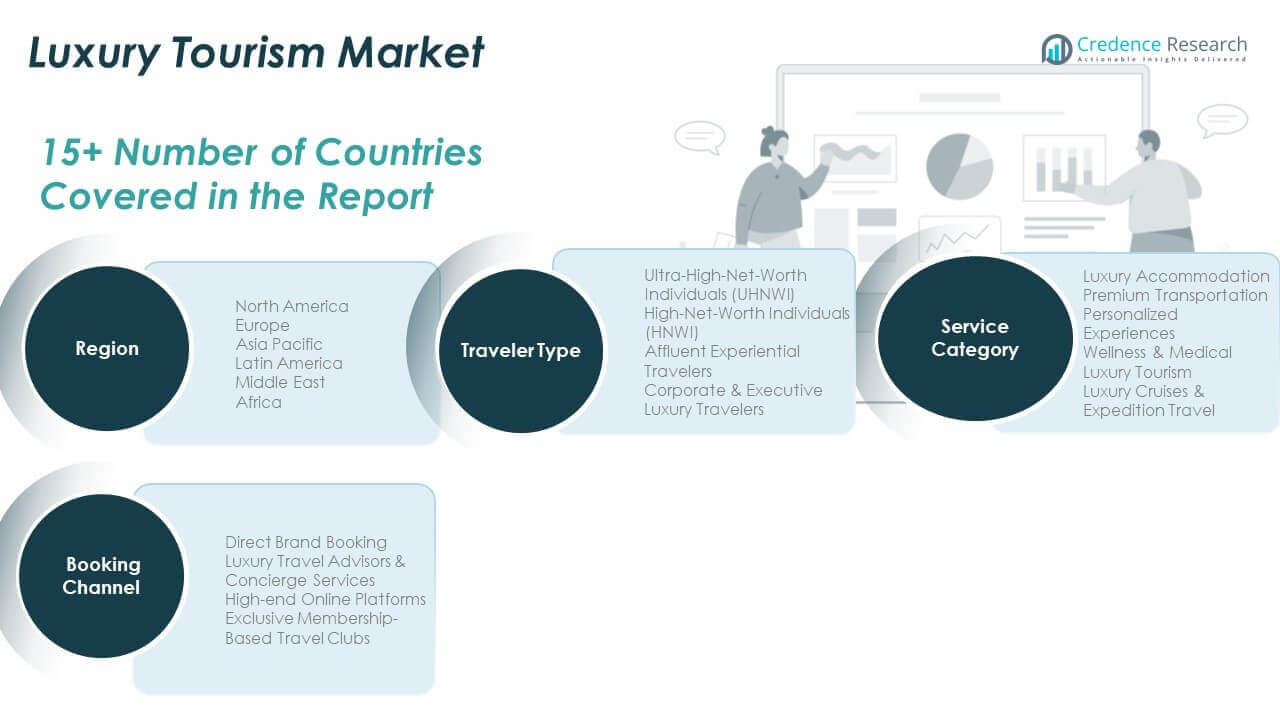
- In 2024, Direct Brand Booking and High-end Online Platforms together accounted for over 50% of global market revenue, showing strong preference for digital and branded engagement.
- Exclusive Membership-Based Travel Clubs showed steady growth, contributing around 20% in 2024, appealing to repeat travelers seeking privacy and curated access.
Market Drivers
Rising High-Net-Worth Individuals (HNWIs) and Increasing Global Affluence are Expanding Premium Travel Demand
A growing number of HNWIs worldwide fuels the expansion of the Luxury Tourism Market. Wealth accumulation in emerging economies creates a broader client base for premium travel services. Countries like China, India, and the UAE are experiencing a steady increase in affluent consumers seeking high-end vacations. Luxury travel brands expand operations in these regions to meet demand. The market responds by offering customized travel packages and curated experiences. Personal concierge services and private aviation are becoming standard offerings. This affluence shift is redefining traditional tourist behavior, with more focus on exclusivity and comfort. The Luxury Tourism Market adapts to this shift by personalizing itineraries and providing superior service delivery.
- For instance, in 2025, Four Seasons and RAK Properties announced a new resort in Mina Al Arab, Ras Al Khaimah, featuring around 150 hotel keys and 130 private residences. Designed by Killa Design, it will include a marina, wellness center, and luxury amenities, with opening planned in 2026.
Increased Preference for Unique and Experiential Journeys Over Traditional Sightseeing Packages
Luxury travelers now value immersive, authentic experiences over mass-market packages. Tourists seek private cultural interactions, guided adventures, and bespoke culinary tours. This shift encourages luxury operators to partner with local experts and communities. Customized experiences such as private wildlife safaris, remote island stays, or vineyard immersions are gaining popularity. Travelers are prioritizing destination storytelling, heritage value, and sustainability. The Luxury Tourism Market responds by creating high-touch itineraries and destination-led marketing. Exclusive retreats with themes such as wellness, gastronomy, or adventure gain momentum. Experiential travel helps brands differentiate and attract affluent millennial and Gen Z travelers.
- For instance, Abercrombie & Kent offers exclusive private safaris in Botswana’s Okavango Delta through access to vast private concessions. These luxury experiences feature highly intimate game drives with customized itineraries tailored to small private groups.
Technology Integration Enhancing Personalization, Booking, And In-Trip Luxury Experience Management
Technology adoption enables seamless trip planning, real-time personalization, and enhanced guest control. AI-powered chatbots, smart apps, and virtual concierges improve the luxury experience. Brands use analytics to predict preferences and offer tailored travel suggestions. From luxury cruise lines to boutique resorts, personalization through tech defines modern premium travel. Mobile check-ins, biometric security, and in-room automation improve convenience. The Luxury Tourism Market leverages tech to enhance engagement and reduce friction across the journey. Blockchain ensures payment security and transparent loyalty rewards. This trend attracts tech-savvy affluent consumers who value convenience without compromising on luxury.
Growth In Luxury Hospitality Infrastructure And Premium Airline Services Driving Market Penetration
Massive investment in high-end resorts, luxury villas, and business-class airline upgrades supports market growth. Top destinations upgrade airports, rail networks, and hospitality offerings for elite travelers. Airlines enhance first-class cabins with lie-flat seating, fine dining, and personalized inflight service. Premium hotel chains launch new properties in scenic or underserved regions. The Luxury Tourism Market benefits from this ecosystem expansion as demand shifts from traditional centers to exclusive getaways. Branded residences, luxury cruise lines, and eco-lodges emerge across Europe, Southeast Asia, and Africa. These developments support an end-to-end luxury experience for discerning global tourists.
Market Trends
Rise of Wellness-Focused Luxury Travel Experiences Targeting Mental, Physical, And Emotional Rejuvenation
Luxury travelers are increasingly prioritizing mental and physical wellbeing during vacations. Demand for yoga retreats, digital detox programs, and nature immersion packages is growing. High-end resorts now integrate spa therapies, nutrition plans, and mindfulness sessions. Wellness tourism is evolving into a core pillar of the Luxury Tourism Market. Resorts in Bali, Costa Rica, and the Maldives are offering week-long wellness residencies. Personalized fitness coaching and medical diagnostics are part of premium offerings. Tourists are also seeking silent retreats and forest-bathing experiences. Wellness-driven travel helps reduce stress and aligns with the desire for inner balance among wealthy consumers.
- For instance, in 2025, Six Senses Douro Valley launched a Female Wellness Program offering two-week continuous glucose monitors and sleep trackers. The program includes personalized sessions with specialists and is available across all 71 accommodations.
Emergence of Luxury Eco-Tourism with Strong Focus On Sustainability And Responsible Travel
Environmentally responsible luxury tourism is gaining traction across affluent traveler segments. Tourists are actively choosing carbon-neutral stays, low-impact adventures, and conservation-driven destinations. Eco-lodges, sustainable cruises, and regenerative travel packages are redefining luxury experiences. High-end brands now commit to net-zero goals and support local biodiversity efforts. The Luxury Tourism Market integrates eco-conscious options into mainstream offerings. Travelers are willing to pay a premium for ethical and green alternatives. Supply chains are shifting toward locally sourced food, solar energy use, and eco-certifications. Responsible travel behavior among wealthy guests drives this structural transformation.
- For instance, in October 2024, Aman Resorts activated a 1.8 MW solar microgrid at Amanpulo, supplying over 50% of the resort’s energy needs. This shift is expected to cut diesel use by approximately 750,000 liters annually, supporting Aman’s sustainability goals.
Popularity of Remote Destinations and Off-The-Grid Experiences for Complete Privacy and Exclusivity
Discerning travelers prefer destinations that offer solitude, safety, and exclusivity. Demand for private islands, polar expeditions, and secluded mountain lodges is rising. Operators offer customized access to rare and pristine natural environments. Helicopter transfers, private chefs, and no-network zones define ultra-luxury getaways. The Luxury Tourism Market evolves by creating high-security, low-density packages. These locations reduce exposure to crowds and provide unmatched serenity. Privacy-seeking celebrities and billionaires drive bookings in remote destinations. High-level personalization, safety, and discretion are central to this trend.
Adoption of Hyper-Personalized Loyalty Programs and Luxury Subscription-Based Travel Models
Luxury travelers seek recognition, rewards, and exclusivity from brands they frequent. Hyper-personalized loyalty programs track guest behavior to offer curated upgrades and elite services. Subscription-based luxury travel memberships are gaining ground. These offer access to jets, yachts, private homes, and curated experiences under fixed pricing. The Luxury Tourism Market uses digital tools to automate loyalty perks and surprise upgrades. Membership models help brands retain affluent customers with consistent, value-driven travel access. This trend reflects a shift from ownership to experience access in the high-end tourism space. The approach increases brand engagement while supporting predictable revenue for operators.
Market Challenges Analysis
High Vulnerability to Economic Downturns, Geopolitical Tensions, And Global Health Crises
The Luxury Tourism Market remains sensitive to macroeconomic shifts and global instability. Recessions reduce discretionary income and delay travel plans for many potential customers. Political unrest, terrorism risks, and regional conflicts disrupt high-end travel circuits. COVID-19 exposed structural weaknesses in luxury travel due to border closures and consumer fear. Ongoing health emergencies continue to affect confidence in long-haul and international travel. Visa restrictions and changing international regulations complicate planning and reduce bookings. The market’s dependency on stability means quick recovery is often difficult after major shocks. Operators must build resilient strategies and diversify geographies to sustain demand.
Limited Skilled Workforce in Ultra-Luxury Service Delivery And Rising Operating Costs Across Premium Segments
Delivering consistent luxury service demands highly trained personnel across all customer touchpoints. Many regions struggle to recruit and retain skilled workers in luxury hospitality. Language barriers, cultural sensitivity, and precision in service make staffing a challenge. Rising operational costs across hotels, airlines, and bespoke service providers compress margins. Inflation impacts raw materials, labor, and utilities that define luxury standards. Smaller operators may struggle to maintain service excellence under cost pressure. The Luxury Tourism Market faces cost-quality balancing issues, especially in emerging economies. Maintaining exclusivity while scaling service quality remains a complex operational challenge.
Market Opportunities
Expansion into Untapped Regions and Second-Tier Cities with Emerging Wealth and Tourism Infrastructure
There is strong potential in second-tier cities and untapped regions with rising affluence. Countries like Vietnam, Colombia, and Kenya attract new investment in premium travel. Improving infrastructure and local tourism boards' support create new luxury corridors. The Luxury Tourism Market can explore tailored experiences in less-saturated destinations. These areas offer cost benefits and cultural richness with less competition.
Demand for Intergenerational Luxury Travel and Multi-Thematic Travel Packages Is Growing Rapidly
Affluent families are booking multi-generational trips, combining luxury with bonding time. Operators design packages for grandparents, parents, and children together. Themed itineraries like adventure-wellness or cultural-culinary tours attract broad demographics. The Luxury Tourism Market benefits from this shift in family travel dynamics. It opens new revenue streams for resorts, cruises, and bespoke travel designers.
Market Segmentation Analysis:
By Traveler Type
The Luxury Tourism Market serves four major traveler groups, each driving demand in unique ways. Ultra-High-Net-Worth Individuals (UHNWI) contribute the highest per-trip spending. These travelers favor private islands, superyachts, and exclusive resorts with full-service privacy. High-Net-Worth Individuals (HNWI) follow closely, seeking tailored experiences in iconic destinations with premium transport and accommodations. Affluent experiential travelers focus on cultural immersion, guided adventures, and meaningful journeys. They prioritize authenticity and access to local heritage over brand prestige. Corporate and executive luxury travelers value efficiency, comfort, and personalization during business-leisure trips.
- For instance, in 2024, NetJets operated a fleet of 687 fractional jets across North America, recording 575,848 total flight hours. This reflects sustained demand for private aviation within the Luxury Tourism Market.
By Service Category
The market offers a wide range of services to meet diverse luxury expectations. Luxury accommodation remains the most preferred service, spanning from boutique resorts to branded residences. Premium transportation, including private jets, luxury trains, and chauffeured vehicles, ensures seamless high-end mobility. Personalized experiences are critical for differentiation, offering curated itineraries, private guides, and themed retreats. Wellness and medical tourism have grown as clients seek preventive care, detox programs, and therapeutic packages. Traditional luxury tourism focused on top-tier destinations and elite resorts continues to hold strong appeal. Luxury cruises and expedition travel cater to adventure seekers looking for remote, high-service exploration.
- For instance, in 2024, AirSprint operated a fleet of 39 private jets and recorded nearly 38,000 flight hours. The company captured close to 29% of Canada's private business jet departures, reflecting strong demand in the Luxury Tourism Market.
By Booking Channel
Booking preferences in the Luxury Tourism Market reflect a blend of digital convenience and trusted human service. Direct brand booking remains dominant, especially among loyal clients of global hotel chains and cruise operators. Luxury travel advisors and concierge services are favored for complex or multi-stop journeys, where curated planning is essential. High-end online platforms are gaining popularity, especially among younger affluent travelers who prefer mobile-first booking and on-demand assistance. These platforms offer speed, transparency, and real-time customization. Exclusive membership-based travel clubs appeal to repeat travelers seeking privileged access, loyalty rewards, and guaranteed privacy.
Segmentation:
By Traveler Type
- Ultra-High-Net-Worth Individuals (UHNWI)
- High-Net-Worth Individuals (HNWI)
- Affluent Experiential Travelers
- Corporate & Executive Luxury Travelers
By Service Category
- Luxury Accommodation
- Premium Transportation
- Personalized Experiences
- Wellness & Medical
- Luxury Tourism
- Luxury Cruises & Expedition Travel
By Booking Channel
- Direct Brand Booking
- Luxury Travel Advisors & Concierge Services
- High-end Online Platforms
- Exclusive Membership-Based Travel Clubs
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Luxury Tourism Market size was valued at USD 4,147.20 million in 2018 to USD 6,920.50 million in 2024 and is anticipated to reach USD 21,994.46 million by 2032, at a CAGR of 15.7% during the forecast period. North America accounted for 25.15% of the global market share in 2024. The region is led by the United States, where high-net-worth individuals actively seek premium travel experiences. Demand is rising for private island stays, mountain resorts, and luxury wellness retreats. Canada also contributes through nature-based luxury lodges and cruise offerings. Strong infrastructure, premium airlines, and a mature hospitality sector support growth. The market benefits from early technology adoption in travel personalization. Demand from business executives and family travelers further fuels high-value bookings. Partnerships between luxury brands and tourism boards enhance visibility across affluent traveler groups.
Europe
The Europe Luxury Tourism Market size was valued at USD 6,237.00 million in 2018 to USD 10,308.73 million in 2024 and is anticipated to reach USD 31,598.98 million by 2032, at a CAGR of 15.1% during the forecast period. Europe contributed 37.47% of the global market share in 2024, making it the leading regional segment. Countries like France, Italy, and Switzerland offer historical sites, exclusive resorts, and high-end culinary tourism. The region benefits from short-haul luxury travel between EU states, supported by world-class rail and air networks. Affluent travelers enjoy access to designer fashion hubs, vineyard tours, and art-focused retreats. Wellness tourism in the Alps and the Mediterranean attracts high-spending visitors. Europe also hosts several global events that drive luxury hospitality bookings. It remains a year-round destination, serving both summer and winter luxury travelers. The market benefits from established luxury brands and cultural richness.
Asia Pacific
The Asia Pacific Luxury Tourism Market size was valued at USD 4,069.44 million in 2018 to USD 7,207.99 million in 2024 and is anticipated to reach USD 25,270.31 million by 2032, at a CAGR of 17.0% during the forecast period. Asia Pacific held 26.20% of the global market share in 2024, driven by economic growth and a rising HNWI base. China, Japan, and Australia lead in outbound and domestic luxury travel. Southeast Asian countries such as Thailand, Indonesia, and Vietnam are developing world-class resorts and exclusive travel experiences. Improved air connectivity, rising disposable income, and digital-first travel behavior support rapid growth. The region sees strong demand for wellness tourism, cultural immersion, and coastal retreats. High-end online booking platforms are popular among younger affluent travelers. The market benefits from public-private partnerships to promote tourism infrastructure. Asia Pacific is emerging as a global epicenter for luxury tourism investment.
Latin America
The Latin America Luxury Tourism Market size was valued at USD 988.20 million in 2018 to USD 1,661.12 million in 2024 and is anticipated to reach USD 4,893.75 million by 2032, at a CAGR of 14.6% during the forecast period. Latin America represented 6.04% of the global market share in 2024. Brazil, Mexico, and Argentina are key contributors due to their unique landscapes, heritage sites, and wildlife reserves. Luxury eco-lodges and boutique hotels are growing across coastal and rainforest regions. Adventure-driven premium travel is gaining popularity, especially in Patagonia and the Andes. The region is attracting affluent North American and European tourists seeking offbeat experiences. Infrastructure remains a growth barrier in remote areas, though investments are rising. Local operators partner with international brands to elevate service quality. Cruise tourism along the Pacific and Amazon also adds value to the regional market.
Middle East
The Middle East Luxury Tourism Market size was valued at USD 382.32 million in 2018 to USD 582.96 million in 2024 and is anticipated to reach USD 1,550.86 million by 2032, at a CAGR of 13.1% during the forecast period. It contributed 2.12% of the global market share in 2024. The region's growth is anchored by the UAE, Saudi Arabia, and Qatar, where governments invest heavily in luxury hospitality and tourism infrastructure. Dubai leads in ultra-luxury offerings, from iconic hotels to premium desert safaris. Saudi Arabia’s Vision 2030 promotes new cultural and leisure zones to attract affluent travelers. High-end shopping festivals, sports events, and private beach resorts boost visitor numbers. Religious tourism is also evolving to include luxury experiences. The region attracts both business and leisure tourists, particularly from Asia and Europe. Favorable visa policies and premium airlines support long-haul connectivity.
Africa
The Africa Luxury Tourism Market size was valued at USD 375.84 million in 2018 to USD 825.31 million in 2024 and is anticipated to reach USD 2,283.45 million by 2032, at a CAGR of 13.2% during the forecast period. Africa held 3.00% of the global market share in 2024. South Africa, Kenya, and Morocco lead in luxury safari, heritage, and resort tourism. Unique wildlife experiences, cultural immersion, and scenic landscapes appeal to international HNWIs. Boutique lodges, private game reserves, and conservation-based tourism drive segment growth. Investment in airport infrastructure and high-end hospitality is growing across the continent. Africa's appeal lies in exclusivity, nature, and underexplored destinations. Operators offer personalized itineraries combining wildlife, wellness, and cultural themes. Challenges remain in connectivity and skilled workforce, though improvements are ongoing. The market is attracting premium travelers seeking off-grid, purpose-driven experiences.
Key Player Analysis:
- Abercrombie & Kent
- Belmond Ltd.
- Four Seasons Hotels & Resorts
- Virtuoso
- TUI Group
Competitive Analysis:
The Luxury Tourism Market is highly competitive, with a mix of global hotel chains, boutique operators, cruise lines, and premium travel agencies. Leading players focus on brand prestige, personalized service, and exclusive offerings to retain high-net-worth clients. Companies like Four Seasons, Aman Resorts, and Belmond invest in unique destination experiences and private residences. Cruise operators such as Silversea and Seabourn differentiate through small-ship luxury and curated expeditions. Digital platforms like Virtuoso and Inspirato use technology to enhance itinerary customization and loyalty programs. Airlines with premium cabin services also compete for affluent international travelers. Local players gain traction by offering cultural authenticity and eco-luxury in emerging markets. The market favors brands that combine privacy, service consistency, and flexible booking options. Mergers, strategic partnerships, and portfolio expansion remain common strategies to strengthen competitive positioning. Innovation in wellness, sustainability, and hyper-personalization shapes future growth across all segments.
Recent Developments:
- In January 2025, the Luxurist, backed by HBX Group, launched as the world's first comprehensive luxury travel ecosystem. This platform connects top travel advisors with over 3,300 premium properties across 141 countries, featuring AI-enhanced itinerary planning, real-time bookings, and 24/7 concierge services to streamline high-end travel experiences.
Report Coverage:
The research report offers an in-depth analysis based on Traveler Type, Service Category and Booking Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market will grow rapidly due to rising demand for customized, high-end travel experiences across income brackets.
- Asia Pacific is expected to lead in growth rate, driven by expanding affluent middle-class travelers.
- Online luxury travel platforms will see strong adoption, especially among tech-savvy, younger HNWIs.
- Sustainable and eco-luxury tourism offerings will reshape brand positioning and long-term competitiveness.
- Personalized wellness retreats and medical tourism will remain key drivers in premium travel packages.
- Cruise and expedition-based tourism will attract interest from affluent adventure and experience seekers.
- Second-tier cities and emerging destinations will witness growing luxury infrastructure investments.
- AI-driven personalization and smart booking tools will improve customer satisfaction and retention.
- Exclusive loyalty programs and membership-based models will gain traction in high-repeat segments.
- Strategic collaborations between hotels, airlines, and tourism boards will deepen market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising High-Net-Worth Individuals and Global Affluence
The increasing number of HNWIs, especially in emerging economies like China, India, and the UAE, is expanding the client base for luxury tourism. This wealth accumulation drives demand for premium travel services, personalized itineraries, and exclusive experiences.
Preference for Unique and Experiential Journeys
Affluent travelers are shifting away from traditional sightseeing packages toward immersive, authentic, and bespoke experiences. This trend encourages operators to offer private safaris, cultural immersions, and adventure-based luxury tours, fueling market growth.
Technology Integration and Personalization
The adoption of AI-powered concierge apps, smart booking platforms, and virtual assistants enhances the luxury travel experience by enabling real-time personalization, seamless planning, and tailored service delivery, attracting tech-savvy affluent consumers.
Expansion of Luxury Hospitality Infrastructure
Significant investments in high-end resorts, premium airline services, and exclusive travel corridors in both established and emerging destinations are making luxury tourism more accessible and appealing, supporting market penetration and growth.
Growth in Wellness and Sustainable Luxury Tourism
Increasing demand for wellness retreats, medical tourism, and eco-luxury experiences is reshaping the market. Affluent travelers are seeking mental, physical, and emotional rejuvenation, as well as responsible travel options, prompting brands to innovate and differentiate their offerings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Luxury Tourism Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Luxury Tourism Market projected to grow between 2024 and 2032?
Which Luxury Tourism Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Luxury Tourism Market?
Who are the leading companies in the Luxury Tourism Market?
Which region commanded the largest share of the Luxury Tourism Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Traveler Type
- 1.2.1 Ultra-High-Net-Worth Individuals (UHNWI)
- 1.2.2 High-Net-Worth Individuals (HNWI)
- 1.2.3 Affluent Experiential Travelers
- 1.2.4 Corporate & Executive Luxury Travelers
- 1.3 By Booking Channel
- 1.3.1 Direct Brand Booking
- 1.3.2 Luxury Travel Advisors & Concierge Services
- 1.3.3 High-end Online Platforms
- 1.3.4 Exclusive Membership-Based Travel Clubs
- 1.4 By Service Category
- 1.4.1 Luxury Accommodation
- 1.4.2 Premium Transportation
- 1.4.3 Personalized Experiences
- 1.4.4 Wellness & Medical
- 1.4.5 Luxury Cruises & Expedition Travel
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 27,506.62 million → 2032: USD 87,591.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Luxury Tourism Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Luxury Tourism Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Luxury Tourism Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Luxury Tourism Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Luxury Tourism Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Luxury Tourism Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Luxury Tourism Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Luxury Tourism Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 27,506.62 million → 2032: USD 87,591.82 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Luxury Tourism Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Traveler Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Ultra-High-Net-Worth Individuals (UHNWI)
- 12.3.6.2 High-Net-Worth Individuals (HNWI)
- 12.3.6.3 Affluent Experiential Travelers
- 12.3.6.4 Corporate & Executive Luxury Travelers
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Booking Channel - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Direct Brand Booking
- 12.4.6.2 Luxury Travel Advisors & Concierge Services
- 12.4.6.3 High-end Online Platforms
- 12.4.6.4 Exclusive Membership-Based Travel Clubs
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Service Category - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Luxury Accommodation
- 12.5.6.2 Premium Transportation
- 12.5.6.3 Personalized Experiences
- 12.5.6.4 Wellness & Medical
- 12.5.6.5 Luxury Cruises & Expedition Travel
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Luxury Tourism Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Luxury Tourism Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Luxury Tourism Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Abercrombie & Kent
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Belmond Ltd.
- 17.4 Four Seasons Hotels & Resorts
- 17.5 Virtuoso
- 17.6 TUI Group
- 17.7 Aman Resorts
- 17.8 Silversea Cruises
- 17.9 Seabourn
- 17.10 Inspirato
- 17.11 The Leading Hotels of the World
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

