
Market Overview
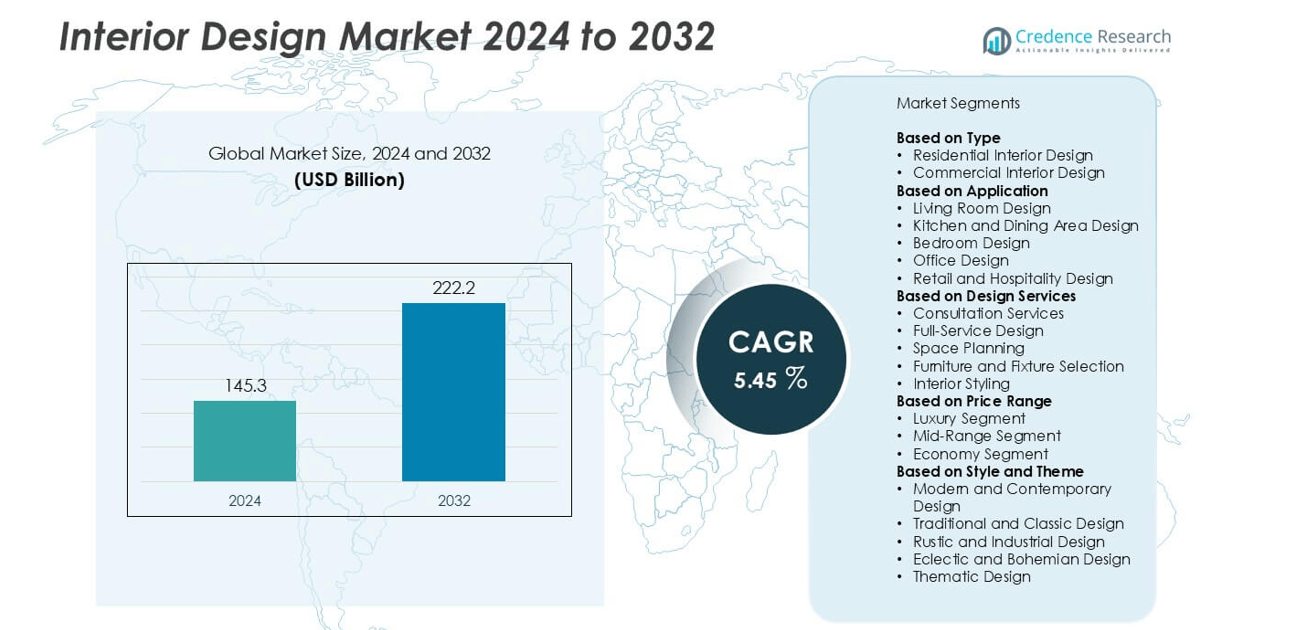
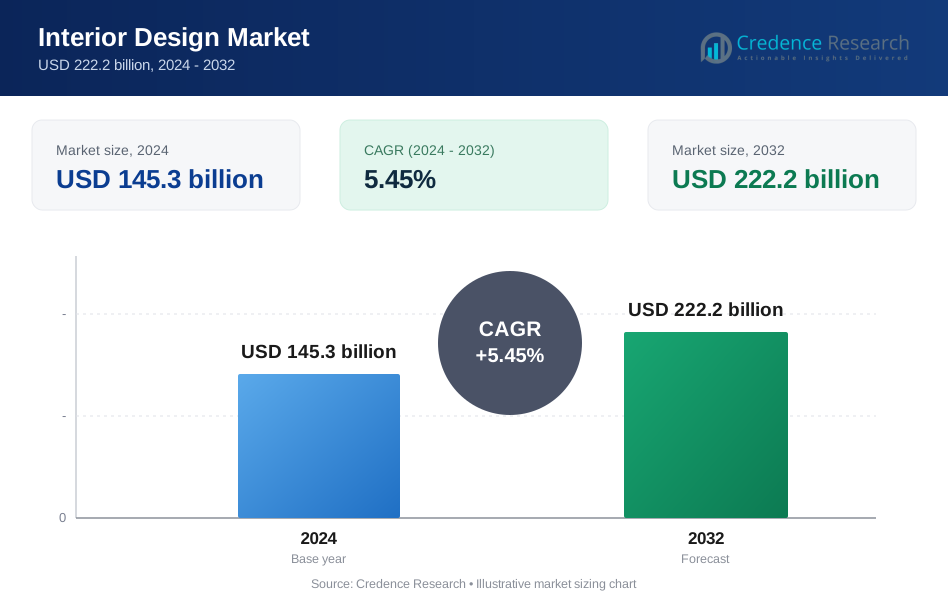
The Interior Design Market was valued at USD 145.3 billion in 2024 and is projected to reach USD 222.2 billion by 2032, growing at a CAGR of 5.45% during the forecast period (2024–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Interior Design Market Size 2024 | USD 145.3 billion |
| Interior Design Market, CAGR | 5.45% |
| Interior Design Market Size 2032 | USD 222.2 billion |
North America led the global interior design market in 2024 with a 34% share, supported by high residential renovation spending and corporate redesign projects. Companies such as Livspace, Sobha Interiors, and Bonito Designs expanded their operations through digital design platforms and integrated project management solutions. Europe followed with a 29% share, driven by eco-friendly architecture and modular furniture demand from firms like Carafina Interior Designers and Lipika Sud Interiors Pvt. Ltd. Asia-Pacific, holding 26%, showed the fastest growth, led by Futomic Design Services Pvt. Ltd, Ace Interiors, and Chaukor Studio, which are leveraging smart design technologies and urban housing projects.
Market Insights
- The global Interior Design market was valued at USD 145.3 billion in 2024 and is projected to reach USD 222.2 billion by 2032, registering a CAGR of 5.45%.
- Rising urbanization, growing residential renovations, and expansion of commercial infrastructure are driving market growth, supported by increasing investments in smart and sustainable interiors.
- Key trends include the adoption of eco-friendly materials, digital visualization tools, and smart home integration, which enhance efficiency and personalization in design projects.
- The market is highly competitive, with major players such as Livspace, Sobha Interiors, Ace Interiors, and Bonito Designs leading through turnkey solutions, sustainability, and digital design innovations.
- North America held the largest share at 34%, followed by Europe (29%) and Asia-Pacific (26%), while the residential interior design segment dominated with over 60% share, driven by growing demand for modern and energy-efficient living spaces.
Market Segmentation Analysis:
By Type
The residential interior design segment dominated the global market in 2024, accounting for over 60% share. Growth is driven by rising urbanization, higher disposable incomes, and increasing demand for customized home interiors. Consumers are investing in functional and aesthetic designs that improve comfort and sustainability. Smart home integration and eco-friendly materials further enhance adoption across urban households. Meanwhile, commercial interior design is expanding due to strong demand from offices, retail outlets, and hospitality sectors emphasizing brand identity and employee well-being.
- For instance, IKEA introduced its Home Smart line, featuring integrated lighting and energy-efficient control systems, which it sells across hundreds of its stores and online worldwide, supporting eco-friendly residential interiors.
By Application
The living room design segment led the market with around 30% share in 2024, supported by its central role in home décor investments. Homeowners prioritize aesthetic appeal and multifunctional layouts for entertainment and social interaction. Kitchen and dining areas follow closely, driven by open-plan concepts and modern cabinetry solutions. In the commercial space, office design remains vital due to the growing emphasis on collaborative workspaces and ergonomic layouts that improve productivity. Retail and hospitality design segments continue to grow with the expansion of themed and experience-driven spaces.
- For instance, Livspace has executed over 75,000 home interior projects across multiple cities in Asia, which include customizable furniture and lighting systems.
By Design Services
Full-service design dominated the market, contributing more than 40% share in 2024. Clients increasingly prefer turnkey solutions covering concept creation, material selection, and project execution. The demand is fueled by time efficiency, cost optimization, and professional management across large-scale residential and commercial projects. Space planning and furniture selection services are also gaining traction due to the rise in compact living spaces and modular furniture trends. Consultation and interior styling services continue to attract individual homeowners and small businesses seeking personalized yet affordable design solutions.
Key Growth Drivers
Rising Urbanization and Residential Renovation Demand
Rapid urbanization and increasing housing investments are major growth drivers for the interior design market. Expanding urban populations and rising disposable incomes are encouraging homeowners to spend more on home aesthetics and functionality. The trend of home renovation and remodeling has intensified, especially in metropolitan areas where compact apartments demand efficient space utilization. Consumers are focusing on modern layouts, smart lighting, and sustainable materials to enhance comfort and reduce energy consumption. Additionally, government initiatives supporting urban housing and smart city projects are fueling new residential construction, further boosting demand for professional interior design services globally.
- For instance, Livspace has delivered a high volume of residential renovation projects across India and Southeast Asia, integrating modular storage and energy-efficient lighting systems to optimize compact spaces.
Growth in Commercial Infrastructure and Corporate Spaces
The expansion of commercial infrastructure, including offices, hotels, retail spaces, and hospitality establishments, is a key growth factor. Businesses are increasingly recognizing the importance of interior design in improving employee productivity, brand image, and customer engagement. The post-pandemic return to offices has led to significant investments in flexible, wellness-oriented workspaces. Similarly, hotels and retail brands are redesigning interiors to enhance guest experience and brand differentiation. Rapid growth in co-working spaces and hybrid offices also contributes to higher adoption of modular layouts, energy-efficient lighting, and ergonomic furniture, creating consistent demand for interior design services across sectors.
- For instance, Beginning in 2017, Steelcase collaborated with Microsoft to launch a line of five distinct Creative Spaces, seamlessly integrating Microsoft Surface devices with Steelcase furniture to enhance creative work. The long-term partnership has since evolved to focus on creating solutions for hybrid work environments, including AI-integrated technology and ergonomic setups.
Technological Advancements in Design Tools and Visualization
Digital transformation is reshaping the interior design landscape, enabling faster project execution and improved client collaboration. The adoption of 3D visualization, Building Information Modeling (BIM), and augmented reality (AR) tools allows designers to create accurate, interactive models that optimize decision-making. Virtual design consultations and AI-driven layout planning are reducing design errors and shortening project timelines. The integration of cloud-based platforms enhances workflow efficiency and enables real-time collaboration between designers, contractors, and clients. This technological evolution is not only improving service quality but also expanding access to design services for small and medium-sized projects.
Key Trends & Opportunities
Growing Focus on Sustainable and Eco-Friendly Interiors
Sustainability has become a defining trend in the global interior design market. Consumers and developers are increasingly seeking eco-friendly materials, energy-efficient lighting, and recyclable furniture to reduce environmental impact. Green certification programs like LEED and BREEAM further encourage sustainable construction and design practices. The shift toward natural finishes, non-toxic paints, and locally sourced materials aligns with global climate goals. This trend creates vast opportunities for manufacturers offering low-carbon products and for designers specializing in sustainable concepts. Companies adopting circular design principles and renewable energy-powered operations are gaining competitive advantages in the evolving market landscape.
- For instance, Interface Inc. produces carbon-negative carpet tiles using 100% recycled nylon and reports a 96% reduction in greenhouse gas emissions across its manufacturing facilities since 1996.
Expansion of Smart and Connected Interiors
Smart home and office integration is driving a major opportunity in the interior design sector. IoT-enabled systems, automated lighting, temperature control, and voice-assisted devices are reshaping modern interiors. Designers now collaborate with tech firms to incorporate intelligent solutions that balance functionality and style. The rising popularity of AI-driven home automation and centralized control systems among middle- and high-income households supports market growth. Additionally, commercial clients are embracing smart energy management and space optimization solutions. This integration of technology with design enhances efficiency, user comfort, and long-term cost savings, positioning connected interiors as a core growth area.
Key Challenges
High Cost of Design Implementation and Skilled Labor Shortage
The high cost of interior design services and materials remains a significant barrier, particularly in emerging economies. Premium raw materials, branded furnishings, and advanced technologies increase project expenses, limiting access for budget-conscious clients. Moreover, the industry faces a shortage of skilled designers, craftsmen, and project managers, which delays timelines and affects quality. Fluctuating labor and construction costs also disrupt pricing stability. Small and medium-sized firms struggle to balance cost and creativity due to tight budgets. Addressing this challenge requires training programs, local sourcing, and adoption of cost-effective digital tools to improve affordability and efficiency.
Supply Chain Disruptions and Material Availability
Global supply chain instability continues to challenge the interior design industry. Delays in raw material imports, rising transportation costs, and fluctuating availability of key components such as wood, metal, and fabric affect project timelines. The heavy reliance on international suppliers for premium materials and furnishings exposes designers to price volatility and logistical risks. Sustainability-related import restrictions further complicate procurement. These challenges pressure firms to find local alternatives and diversify supplier networks. Strengthening supply resilience through partnerships with regional manufacturers and digital inventory management can mitigate disruptions and ensure timely project completion.
Regional Analysis
North America
North America dominated the global interior design market in 2024, accounting for 34% of total share. The region’s growth is fueled by strong demand for residential remodeling, sustainable interiors, and smart home integrations. The United States leads due to higher disposable incomes, modern housing trends, and extensive commercial renovation activities. Corporate investments in flexible office designs and hospitality refurbishments also support expansion. Canada’s market benefits from increased construction and eco-friendly material adoption. A mature design culture, digital visualization tools, and the presence of leading design firms solidify North America’s leadership through consistent innovation and high client spending.
Europe
Europe captured nearly 29% market share in 2024, driven by strong emphasis on sustainable architecture and high-end residential design. The region showcases advanced aesthetic preferences blending modern and classical elements. The United Kingdom, Germany, and France remain key contributors, supported by renovation projects and energy-efficient building standards. Demand for green-certified materials and luxury interiors continues to rise. Growing urban redevelopment and adaptive reuse of heritage spaces further strengthen the market. European firms are also integrating digital design tools and modular furniture systems to enhance productivity and environmental compliance across commercial and residential interiors.
Asia-Pacific
Asia-Pacific accounted for about 26% of the market share in 2024 and is expected to grow fastest during the forecast period. Rapid urbanization, expanding middle-class populations, and rising housing investments are major growth enablers. China, Japan, and India drive demand through increased home renovations and large-scale construction projects. Technological integration, cost-efficient design solutions, and smart city initiatives contribute to the region’s momentum. Commercial developments, such as hotels, offices, and retail hubs, are adopting contemporary and functional interior designs. The shift toward sustainable and space-efficient living also fosters significant opportunities for regional and international design firms.
Latin America
Latin America represented around 7% of the global market share in 2024, supported by steady growth in residential and hospitality sectors. Brazil and Mexico lead due to expanding urban populations and rising interior design adoption in middle-income households. Increasing investments in tourism infrastructure and modern retail spaces are boosting professional design demand. The growing preference for locally sourced, eco-friendly materials reflects sustainability awareness among consumers. However, economic fluctuations and limited access to premium materials remain challenges. Despite this, Latin America’s rising real estate activities and creative design trends position it as a promising emerging market.
Middle East & Africa
Middle East & Africa (MEA) held approximately 4% share of the global interior design market in 2024. Growth is driven by large-scale infrastructure development, luxury real estate projects, and tourism expansion across the UAE, Saudi Arabia, and South Africa. The region is witnessing increasing demand for premium, culturally inspired interiors in hospitality and residential sectors. Government initiatives like Saudi Vision 2030 and Dubai’s smart city programs encourage sustainable and modern design practices. While market maturity remains limited in parts of Africa, rising urbanization and commercial investments are gradually expanding the adoption of interior design services.
Market Segmentations:
By Type
- Residential Interior Design
- Commercial Interior Design
By Application
- Living Room Design
- Kitchen and Dining Area Design
- Bedroom Design
- Office Design
- Retail and Hospitality Design
By Design Services
- Consultation Services
- Full-Service Design
- Space Planning
- Furniture and Fixture Selection
- Interior Styling
By Price Range
- Luxury Segment
- Mid-Range Segment
- Economy Segment
By Style and Theme
- Modern and Contemporary Design
- Traditional and Classic Design
- Rustic and Industrial Design
- Eclectic and Bohemian Design
- Thematic Design
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The interior design market is highly competitive, featuring a mix of global firms and regional specialists focusing on residential and commercial spaces. Leading companies such as Livspace, Sobha Interiors, Acme Interiors, Ace Interiors, Lipika Sud Interiors Pvt. Ltd, Chaukor Studio, Futomic Design Services Pvt. Ltd, Bonito Designs, and Carafina Interior Designers dominate through innovation, digital integration, and end-to-end service delivery. These firms emphasize customized design, 3D visualization, and sustainable material use to attract diverse clients. The competitive edge is shaped by technological adoption, brand reputation, and portfolio diversity. Partnerships with construction firms and furniture manufacturers further strengthen market reach. Growing demand for modular solutions and eco-friendly interiors drives firms to invest in research, automation, and AI-based design tools. Startups and online design platforms are intensifying competition by offering affordable, tech-driven services that appeal to millennial homeowners, making innovation and customer experience critical differentiators across the global interior design landscape.
Key Player Analysis
- Livspace
- Sobha Interiors
- Acme Interiors
- Ace Interiors
- Lipika Sud Interiors Pvt. Ltd
- Chaukor Studio
- Futomic Design Services Pvt. Ltd
- Bonito Designs
- Carafina Interior Designers
Recent Developments
- In June 2023, Asian Paints elevated luxury design with the launch of its Beautiful Homes Studio and the Soft Decor 2023 Collection. These new offerings aim to provide comprehensive design solutions, combining aesthetics with functionality. The Beautiful Homes Studio offers a personalized design experience, while the Soft Decor Collection features a range of sophisticated and elegant decor items. This launch marks a significant step in Asian Paints’ strategy to strengthen its position in the luxury home decor market and offer customers innovative and stylish design solutions.
- In December 2022, home improvement giant Livspace launched Livspace for Business, an initiative aimed at providing interior design services to corporate clients. This new segment will cater to offices, retail spaces, hospitality venues, and warehouses, allowing Livspace to expand its business-to-business (B2B) vertical. The move is designed to address the growing demand for professional and tailored interior design solutions in the corporate sector, further establishing Livspace as a leader in the comprehensive interior design market.
- In May 2022, the interior design startup Havenly, known for its digital services, expanded into physical spaces with its new IRL services. This initiative allows Havenly's designers to visit clients' homes in person, conduct measurements, and ensure alignment with the client's vision before delivering a virtual design via digital layouts and 3D renderings.
- In March 2022, Modsy, a prominent female-led online interior design company, introduced a groundbreaking virtual remodeling service. This innovative offering uses 3D technology to enable customers to visualize and virtually explore every aspect of their remodeling project.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Design Services, Price Range, Style and Theme and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The interior design market will continue growing due to rising demand for personalized spaces.
- Digital tools like 3D visualization and AR will redefine design collaboration and execution.
- Sustainable and eco-friendly materials will gain greater adoption in residential and commercial projects.
- Smart home integration will become a core part of modern design solutions.
- Modular and space-saving furniture will see strong demand in urban housing developments.
- Increased renovation activities will drive steady growth in mature markets.
- AI-driven design recommendations will enhance project efficiency and accuracy.
- Emerging economies in Asia-Pacific will become major contributors to market expansion.
- Online design platforms and e-design services will attract cost-conscious and tech-savvy consumers.
- Global competition will intensify, pushing firms to focus on innovation, branding, and sustainable design practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Residential Renovation Demand
Rapid urbanization and increasing investments in housing are encouraging homeowners to spend more on home aesthetics, functionality, and renovations, especially in metropolitan areas where efficient space utilization is critical.
Growth in Commercial Infrastructure and Corporate Spaces
Expansion of offices, hotels, retail, and hospitality establishments is driving demand for professional interior design services, as businesses seek to enhance brand image, employee productivity, and customer experience through modern, flexible, and wellness-oriented interiors.
Technological Advancements in Design Tools and Visualization
The adoption of 3D visualization, BIM, AR, and cloud-based collaboration platforms is streamlining project execution, improving client engagement, and expanding access to design services for both large and small projects.
Growing Focus on Sustainable and Eco-Friendly Interiors
Increasing consumer and regulatory emphasis on sustainability is boosting demand for eco-friendly materials, energy-efficient lighting, and recyclable furniture, creating opportunities for designers and manufacturers specializing in green solutions.
Expansion of Smart and Connected Interiors
Integration of IoT-enabled systems, automated lighting, and AI-driven home automation is transforming interior spaces, with both residential and commercial clients seeking intelligent solutions that enhance comfort, efficiency, and long-term cost savings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Interior Design market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Interior Design market projected to grow between 2025 and 2032?
Which Interior Design market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Interior Design market?
Who are the leading companies in the Interior Design market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Residential Interior Design
- 1.2.2 Commercial Interior Design
- 1.3 By Application
- 1.3.1 Living Room Design
- 1.3.2 Kitchen and Dining Area Design
- 1.3.3 Bedroom Design
- 1.3.4 Office Design
- 1.3.5 Retail and Hospitality Design
- 1.4 By Price Range
- 1.4.1 Luxury Segment
- 1.4.2 Mid-Range Segment
- 1.4.3 Economy Segment
- 1.5 By Design Services
- 1.5.1 Consultation Services
- 1.5.2 Full-Service Design
- 1.5.3 Space Planning
- 1.5.4 Furniture and Fixture Selection
- 1.5.5 Interior Styling
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 145.3 billion → 2032: USD 222.2 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Interior Design Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Interior Design Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Interior Design Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Interior Design Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Interior Design Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Interior Design Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Interior Design Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Interior Design Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 145.3 billion → 2032: USD 222.2 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Interior Design Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential Interior Design
- 12.3.7.2 Commercial Interior Design
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Living Room Design
- 12.4.7.2 Kitchen and Dining Area Design
- 12.4.7.3 Bedroom Design
- 12.4.7.4 Office Design
- 12.4.7.5 Retail and Hospitality Design
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Price Range - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Luxury Segment
- 12.5.7.2 Mid-Range Segment
- 12.5.7.3 Economy Segment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Design Services - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Consultation Services
- 12.6.7.2 Full-Service Design
- 12.6.7.3 Space Planning
- 12.6.7.4 Furniture and Fixture Selection
- 12.6.7.5 Interior Styling
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Interior Design End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Interior Design Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Interior Design Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Interior Design Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Livspace
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sobha Interiors
- 18.4 Bonito Designs
- 18.5 Ace Interiors
- 18.6 Futomic Design Services Pvt. Ltd
- 18.7 Carafina Interior Designers
- 18.8 Lipika Sud Interiors Pvt. Ltd
- 18.9 Chaukor Studio
- 18.10 Acme Interiors
- 18.11 Havenly
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

