
Market overview
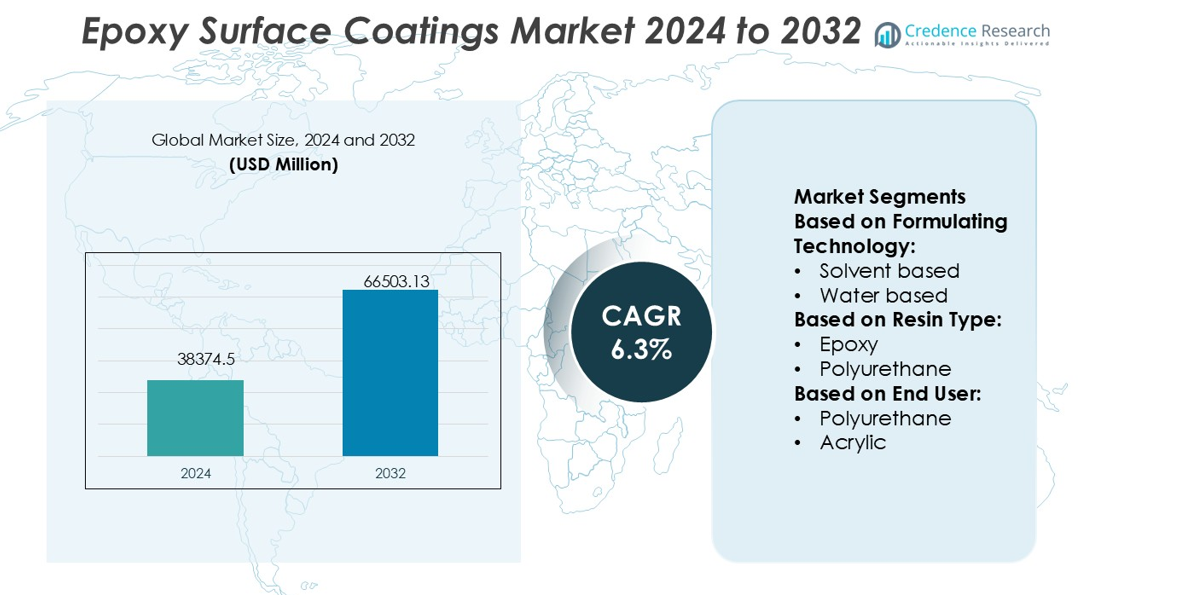
Epoxy Surface Coatings Market size was valued USD 38374.5 million in 2024 and is anticipated to reach USD 66503.13 million by 2032, at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Epoxy Surface Coatings Market Size 2024 | USD 38374.5 million |
| Epoxy Surface Coatings Market, CAGR | 6.3% |
| Epoxy Surface Coatings Market Size 2032 | USD 66503.13 million |
The epoxy surface coatings market is driven by major players such as PPG Industries Inc., Akzo Nobel N.V., Sherwin-Williams Company, Axalta Coating Systems, RPM International Inc., Kansai Paint Co., Ltd., Asian Paints, Berger Paints India, BASF SE, and Nippon Paint Private Limited. These companies focus on advanced resin technologies, eco-friendly product development, and strategic expansions to strengthen their market positions. Asia-Pacific leads the global market with a 36% share, fueled by rapid urbanization, infrastructure investments, and strong industrial growth in China, India, and Southeast Asia. The region’s dominance is reinforced by large-scale construction projects and rising demand for high-performance protective coatings.
Market Insights
- The Epoxy Surface Coatings Market size was valued at USD 38374.5 million in 2024 and is projected to reach USD 66503.13 million by 2032, growing at a CAGR of 6.3%.
- Market growth is driven by rising infrastructure projects, industrial applications, and increasing demand for durable, corrosion-resistant coatings across automotive, marine, and construction sectors.
- Key trends include the shift toward water-based and low-VOC coatings, advancements in resin technologies, and sustainability-focused innovations catering to regulatory compliance and eco-friendly requirements.
- Competitive dynamics are shaped by leading players such as PPG Industries, Sherwin-Williams, BASF SE, Akzo Nobel, and Asian Paints, emphasizing R&D, product diversification, and global expansion while restraints include volatile raw material prices and stringent environmental regulations.
- Asia-Pacific leads with 36% market share, supported by rapid industrialization in China and India, while epoxy resin dominates with 46% share among resin types, highlighting its superior adhesion, durability, and protective properties across critical applications.
Market Segmentation Analysis:
By Formulating Technology
The solvent-based segment dominates the epoxy surface coatings market with a share of 42%. Its strength lies in superior adhesion, chemical resistance, and ability to deliver durable finishes across industrial and infrastructure applications. Despite regulatory pressure, the segment remains strong due to performance in heavy-duty environments. Water-based coatings are expanding, driven by environmental compliance and lower VOC emissions, while powder coatings gain traction for their efficiency and waste reduction. The shift toward sustainability is accelerating innovation, but solvent-based coatings maintain dominance due to high performance in demanding sectors.
- For instance, Berger Paints' total installed capacity is significantly higher than the 33,000 KL/MT per month mentioned, which only refers to its Sandila plant. The total capacity of the company was approximately 745,000 KL/MT per annum as of FY23 and has since been expanded.
By Resin Type
Epoxy resin coatings hold the largest market share at 46%, driven by their superior corrosion resistance, adhesion, and versatility across industries. They are widely used in protective coatings for infrastructure, marine, and industrial floors. Polyurethane resins follow closely due to their weather resistance and flexibility, making them suitable for automotive and construction applications. Acrylic and alkyd resins contribute to decorative and cost-effective solutions, while zinc coatings provide strong anti-corrosion performance for steel structures. The epoxy segment leads, supported by strong demand for durability and long-term protection in industrial applications.
- For instance, Sherwin-Williams Company launched its FIRETEX® FX6010 intumescent epoxy coating, tested to protect structural steel for up to 180 minutes under cellulosic fire exposure. Its fast-drying properties allow for a certified film thickness reduction of up to 25%, enabling lower material consumption and faster application across industrial and commercial projects.
By End User
Infrastructure represents the leading end-user segment with a 38% share, fueled by rising urbanization, government projects, and investments in smart cities. Epoxy coatings dominate within this segment due to their durability and resistance to chemicals and moisture, making them ideal for bridges, highways, and water treatment facilities. Polyurethane and acrylic coatings also support architectural and commercial projects with flexible and aesthetic finishes. Industrial flooring, pipelines, and protective steel structures further strengthen infrastructure demand. The dominance of this segment is reinforced by ongoing construction growth, stringent safety standards, and the increasing need for long-lasting protective solutions.
Key Growth Drivers
Rising Demand from Infrastructure Development
The growth of infrastructure projects worldwide is a major driver for the epoxy surface coatings market. Rapid urbanization, government-led construction initiatives, and smart city programs have created strong demand for protective and durable coatings. Epoxy coatings are widely applied in bridges, highways, airports, and water treatment plants due to their chemical resistance and long service life. Increasing investments in developing economies, particularly in Asia-Pacific and the Middle East, continue to fuel the adoption of epoxy coatings, reinforcing their importance in meeting modern infrastructure requirements.
- For instance, Kansai Paint, through its Helios industrial coatings arm, recently launched a water-thinnable two-part epoxy primer whose anti-corrosion performance exceeds 1,500 hours in a salt-humidity chamber without defects.
Expanding Industrial Applications
Industrial sectors such as automotive, aerospace, and marine are contributing significantly to epoxy coating demand. Their superior adhesion, corrosion resistance, and durability make them essential in protecting equipment, vehicles, and structural components. Industries rely on epoxy surface coatings to enhance performance and extend service life, particularly in high-wear environments. The growing focus on operational efficiency and preventive maintenance is pushing manufacturers to use high-performance coatings. As industrial activity rises globally, epoxy coatings remain a preferred choice for ensuring safety, reliability, and cost efficiency in critical applications.
- For instance, PPG’s electrocoat (e-coat) systems deliver 98 % transfer efficiency in dip coating processes, yielding uniform films even on complex metal parts.Their Powercron® 160 anionic epoxy electrocoat achieved film builds beyond 6 mils (≈150 µm) across diverse substrate pretreatment chemistries, earning PPG an R&D 100 Award.
Shift Toward Sustainable and Low-VOC Solutions
Environmental regulations and consumer preference for eco-friendly products are accelerating the demand for water-based and low-VOC epoxy coatings. Governments across North America, Europe, and Asia-Pacific are enforcing stricter emission standards, compelling manufacturers to innovate sustainable formulations. The push for green building certifications and circular economy models further enhances the relevance of eco-friendly coatings. Companies investing in bio-based epoxy resins and recyclable coating systems are capturing new market opportunities. This trend positions sustainability not only as a compliance factor but also as a competitive advantage for long-term growth.
Key Trends & Opportunities
Technological Advancements in Coating Formulations
Innovation in resin chemistry and nanotechnology is transforming epoxy surface coatings. Advancements in self-healing coatings, antimicrobial finishes, and high-solids formulations are improving performance and broadening applications. These innovations address emerging needs in healthcare, electronics, and renewable energy sectors where durability and specialized properties are crucial. R&D investments are enabling manufacturers to deliver coatings that combine sustainability with enhanced functionality, creating opportunities for market expansion. Companies that leverage advanced materials and automation in production are positioned to meet evolving industry requirements and capture new growth avenues.
- For instance, BASF has made strides in epoxy curing technology through its Baxxodur® EC 151 curing agent. In a joint development with Sika, this hardener enables formulations that emit up to 90 % less VOCs compared to conventional hardeners.
Growth in Emerging Economies
The epoxy surface coatings market is witnessing strong potential in Asia-Pacific, Latin America, and Africa. Rapid construction growth, expanding industrial bases, and rising disposable incomes are fueling demand for premium coatings. Emerging economies are investing heavily in infrastructure modernization, industrial corridors, and housing projects, which directly support coating consumption. Local manufacturing expansion and international collaborations are enabling wider availability of cost-effective epoxy solutions. This trend highlights a clear opportunity for players to establish early presence, build distribution networks, and capitalize on the fast-growing demand in developing regions.
- For instance, Nippon Paint Marine has released FASTAR®, a nanodomain antifouling epoxy product, which has been applied to over 1,000 vessels since its 2021 launch. The coating yields fuel savings of up to 8 % and lower friction via hydrogel water-trapping technology.
Key Challenges
Volatility in Raw Material Prices
Fluctuations in crude oil prices directly affect the cost of key raw materials such as epichlorohydrin and bisphenol-A, used in epoxy resin production. These price instabilities create supply chain uncertainties and margin pressures for manufacturers. The dependence on petrochemical-derived inputs makes the market vulnerable to global energy dynamics. Producers are challenged to balance competitive pricing with profitability, pushing them to explore alternative raw materials and long-term supplier agreements. Managing cost volatility remains a significant hurdle to ensuring stable growth and competitiveness in the epoxy coatings market.
Stringent Environmental Regulations
Compliance with evolving environmental and safety regulations presents a major challenge for epoxy coating manufacturers. Strict limits on VOC emissions and hazardous substances demand costly reformulations and investments in sustainable technologies. Smaller companies, in particular, face difficulties in aligning with these requirements due to limited R&D budgets. Failure to comply risks market restrictions and reputational damage. While regulations encourage sustainability, they also increase production costs and complexity. Navigating this regulatory environment requires strategic investment and innovation to maintain market presence and long-term resilience.
Regional Analysis
North America
North America holds a 28% share of the epoxy surface coatings market, driven by strong demand from construction, automotive, and aerospace industries. The U.S. dominates regional consumption, supported by infrastructure renovation projects and strict safety standards. Water-based and low-VOC epoxy coatings are witnessing rising adoption due to environmental regulations from agencies like the EPA. Canada contributes significantly through industrial flooring and marine applications, while Mexico’s growing automotive and manufacturing sectors add to regional demand. Investments in smart infrastructure and industrial modernization continue to reinforce North America’s leading position in the global market.
Europe
Europe accounts for 24% of the global epoxy surface coatings market, led by Germany, France, and the UK. The region’s focus on sustainability and compliance with REACH and VOC regulations has accelerated the shift toward water-based epoxy solutions. Demand is driven by applications in automotive manufacturing, aerospace, and marine industries. Germany leads with a strong automotive sector, while France and the UK contribute through construction and infrastructure projects. Eastern Europe is witnessing growing adoption in industrial and commercial sectors, creating expansion opportunities. Europe’s commitment to green building and eco-friendly technologies strengthens long-term market growth.
Asia-Pacific
Asia-Pacific dominates the epoxy surface coatings market with a 36% share, fueled by rapid urbanization, industrialization, and infrastructure investments. China leads demand through construction and large-scale industrial activities, while India records strong growth in residential and commercial projects. Japan, South Korea, and Southeast Asian nations contribute significantly through automotive, marine, and electronics applications. The region’s cost-effective manufacturing base and government-driven infrastructure programs enhance market growth. Asia-Pacific also shows rising adoption of water-based epoxy coatings due to environmental initiatives. Strong population growth and expansion of industrial hubs ensure Asia-Pacific remains the largest and fastest-growing market globally.
Latin America
Latin America represents 6% of the epoxy surface coatings market, with Brazil and Mexico driving regional demand. Infrastructure modernization, industrial expansion, and growth in automotive manufacturing are key drivers. Brazil’s construction sector supports adoption of epoxy coatings for commercial buildings and public infrastructure. Mexico benefits from increasing demand in automotive and industrial applications, supported by trade integration with North America. Chile, Argentina, and Colombia show emerging opportunities with infrastructure projects and industrial development. Although growth is slower compared to Asia-Pacific, Latin America’s market is expanding steadily, supported by rising urbanization and government-led infrastructure investments.
Middle East & Africa (MEA)
The Middle East & Africa hold a 6% share of the epoxy surface coatings market, supported by infrastructure investments and oil and gas projects. GCC countries such as Saudi Arabia and the UAE lead demand, driven by construction of smart cities, airports, and industrial complexes. Epoxy coatings are widely used for corrosion protection in pipelines and offshore structures. In Africa, South Africa and Nigeria contribute through building projects and industrial applications. Increasing investments in energy, infrastructure, and commercial real estate create opportunities, while sustainability initiatives encourage adoption of low-VOC coatings across the region.
Market Segmentations:
By Formulating Technology:
- Solvent based
- Water based
By Resin Type:
- Epoxy
- Polyurethane
By End User:
- Polyurethane
- Acrylic
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The epoxy surface coatings market is characterized by intense competition among leading players including Berger Paints India, Sherwin-Williams Company, Kansai Paint Co., Ltd., PPG Industries Inc., BASF SE, Nippon Paint Private Limited, RPM International Inc., Asian Paints, Akzo Nobel N.V., and Axalta Coating Systems. The epoxy surface coatings market features a highly competitive environment shaped by innovation, sustainability, and regional expansion strategies. Companies are investing heavily in research and development to introduce advanced formulations, including water-based and low-VOC solutions, to comply with stringent environmental regulations. The market also sees growing emphasis on high-performance coatings that provide superior durability, corrosion resistance, and long-term protection across infrastructure, automotive, marine, and industrial applications. Expansion into emerging economies, supported by infrastructure growth and rising industrialization, is a key strategy for strengthening market presence. Strategic collaborations, acquisitions, and eco-friendly product launches continue to define competitive differentiation and long-term growth.
Key Player Analysis
- Berger Paints India
- Sherwin-Williams Company
- Kansai Paint Co., Ltd.
- PPG Industries Inc.
- BASF SE
- Nippon Paint Private Limited
- RPM International Inc.
- Asian Paints
- Akzo Nobel N.V.
- Axalta Coating Systems
Recent Developments
- In May 2024, Sherwin-Williams packaging coatings expanded its non-BPA (non-bisphenol A) epoxy coatings production in Europe after a multi-year investment with the production of its value V70 coatings for beverage drink cans. Further, this plant will produce commercial batches of the valPure V70 series to market and distribute across Europe, the Middle East, Africa, and the Indian region.
- In March 2024, Grasim Industries Limited, a subsidiary of Aditya Birla Group, in its chemical business inaugurated the capacity expansion project of Epoxy resins and formulation capacity at Vilayat, Gujarat. With this capacity expansion, the company’s overall capacity of its advanced materials will increase to 246,000 tons per annum.
- In February 2024, BASF Coatings partnered with INEOS Automotive for their program known as “Global Body and Paint Program” that involves meeting industry standards and using sustainable refinish solutions. This collaboration also supplements sustainable refinish solutions, proficiency, digital color-matching solutions, and training.
- In September 2023, PPG announced that it completed the capacity expansion of its powder coating plant located in Sumaré, Brazil. With an investment of the company expanded the production capacity of the plant by 40%
Report Coverage
The research report offers an in-depth analysis based on Formulating Technology, Resin Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness strong demand from infrastructure development and urbanization projects worldwide.
- Water-based and low-VOC epoxy coatings will gain wider adoption due to stricter regulations.
- Industrial applications such as automotive, aerospace, and marine will continue driving growth.
- Emerging economies will remain key hotspots with rising construction and industrial investments.
- Sustainability initiatives will push manufacturers to develop bio-based and recyclable formulations.
- Technological innovations will enhance performance with self-healing and antimicrobial coating solutions.
- Expansion of smart cities will increase the use of durable epoxy coatings in public projects.
- Strategic mergers and acquisitions will shape competitive dynamics across global markets.
- Digital tools and automation in coating production will improve efficiency and consistency.
- Long-term growth will rely on balancing cost, compliance, and high-performance demands in diverse sectors.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand from Infrastructure Development
Global infrastructure projects, urbanization, and government-led construction initiatives are fueling demand for durable, protective epoxy coatings in bridges, highways, airports, and water treatment plants, especially in developing economies.
Expanding Industrial Applications
Automotive, aerospace, and marine sectors increasingly rely on epoxy surface coatings for their superior adhesion, corrosion resistance, and durability, which are essential for protecting equipment and extending service life in high-wear environments.
Shift Toward Sustainable and Low-VOC Solutions
Stricter environmental regulations and consumer preference for eco-friendly products are accelerating the adoption of water-based and low-VOC epoxy coatings, prompting manufacturers to innovate and capture new market opportunities.
Technological Advancements in Coating Formulations
Innovations in resin chemistry, nanotechnology, and self-healing or antimicrobial coatings are enhancing performance and expanding the range of applications, particularly in sectors like healthcare, electronics, and renewable energy.
Growth in Emerging Economies
Rapid construction growth, industrialization, and rising disposable incomes in Asia-Pacific, Latin America, and Africa are driving demand for premium epoxy coatings, supported by local manufacturing expansion and international collaborations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Epoxy Surface Coatings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Epoxy Surface Coatings Market projected to grow between 2025 and 2032?
Which Epoxy Surface Coatings Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Epoxy Surface Coatings Market?
Who are the leading companies in the Epoxy Surface Coatings Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Infrastructure
- 1.2.2 Automotive
- 1.2.3 Marine
- 1.2.4 Industrial Flooring
- 1.2.5 Commercial & Residential Construction
- 1.3 By Resin Type
- 1.3.1 Epoxy
- 1.3.2 Polyurethane
- 1.3.3 Acrylic
- 1.3.4 Alkyd
- 1.3.5 Zinc
- 1.4 By Formulating Technology
- 1.4.1 Solvent based
- 1.4.2 Water based
- 1.4.3 Powder coatings
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 38,374.5 million → 2032: USD 66,503.13 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Epoxy Surface Coatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Epoxy Surface Coatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Epoxy Surface Coatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Epoxy Surface Coatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Epoxy Surface Coatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Epoxy Surface Coatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Epoxy Surface Coatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Epoxy Surface Coatings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 38,374.5 million → 2032: USD 66,503.13 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Epoxy Surface Coatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Infrastructure
- 12.3.7.2 Automotive
- 12.3.7.3 Marine
- 12.3.7.4 Industrial Flooring
- 12.3.7.5 Commercial & Residential Construction
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Resin Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Epoxy
- 12.4.7.2 Polyurethane
- 12.4.7.3 Acrylic
- 12.4.7.4 Alkyd
- 12.4.7.5 Zinc
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Formulating Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Solvent based
- 12.5.7.2 Water based
- 12.5.7.3 Powder coatings
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Epoxy Surface Coatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Epoxy Surface Coatings Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Epoxy Surface Coatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Epoxy Surface Coatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 PPG Industries Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Akzo Nobel N.V.
- 18.4 Sherwin-Williams Company
- 18.5 Axalta Coating Systems
- 18.6 RPM International Inc.
- 18.7 Kansai Paint Co., Ltd.
- 18.8 Asian Paints
- 18.9 Berger Paints India
- 18.10 BASF SE
- 18.11 Nippon Paint Private Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

