
Infusion therapy devices market moves toward smart pumps
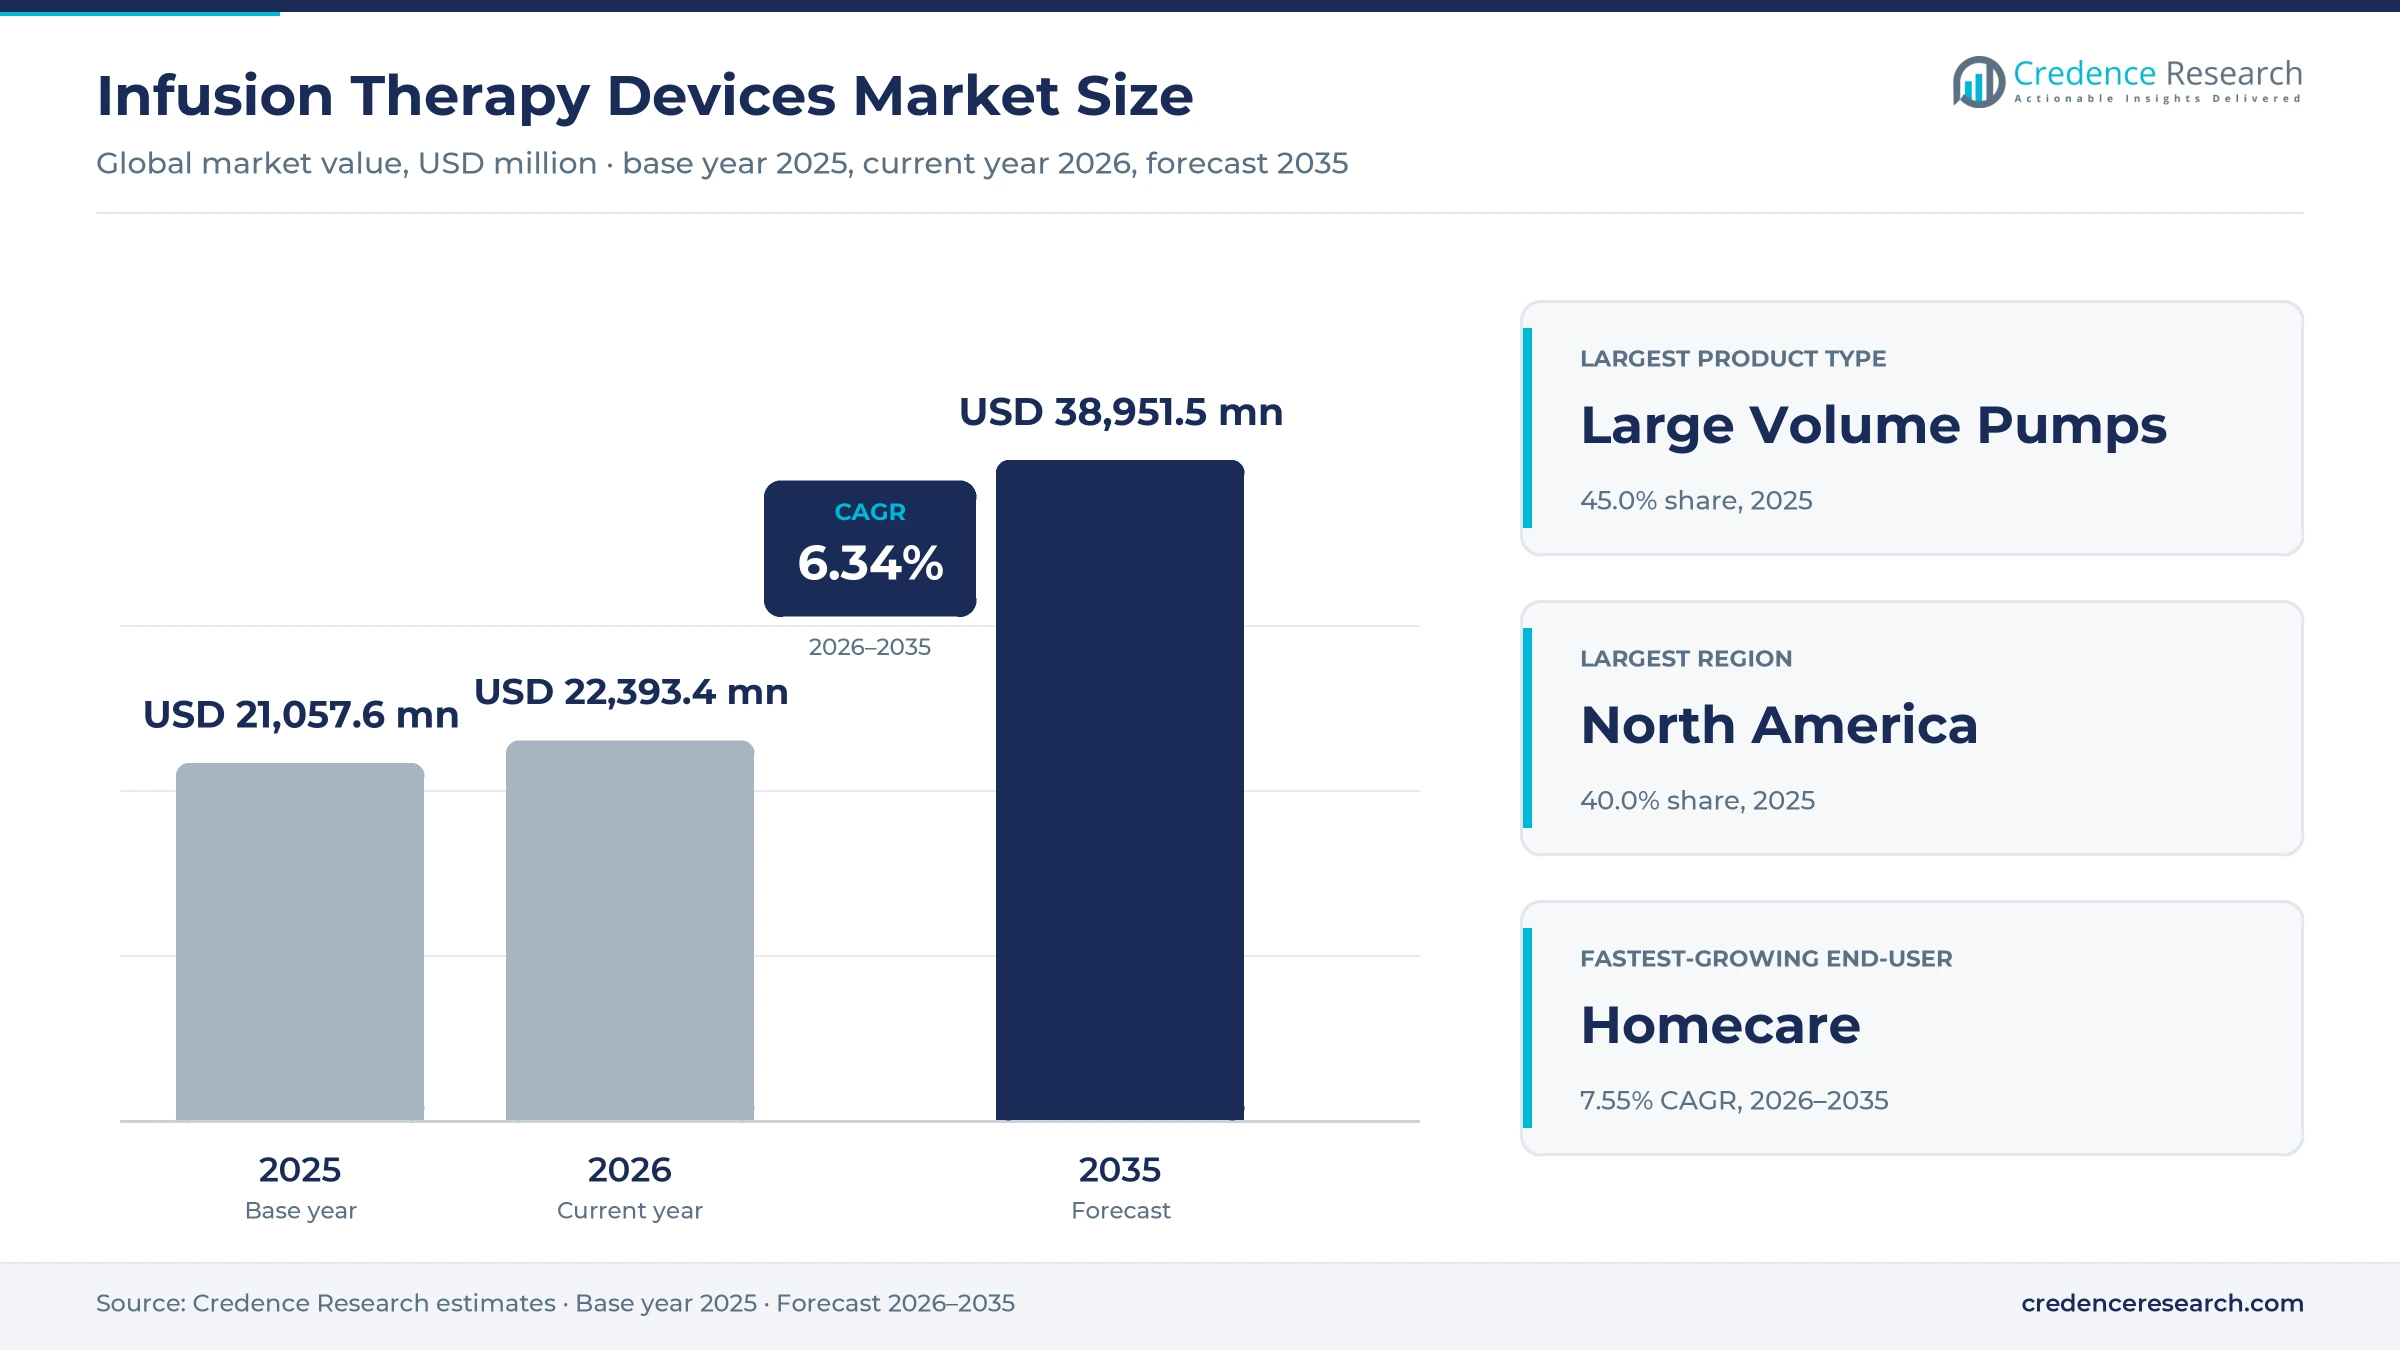
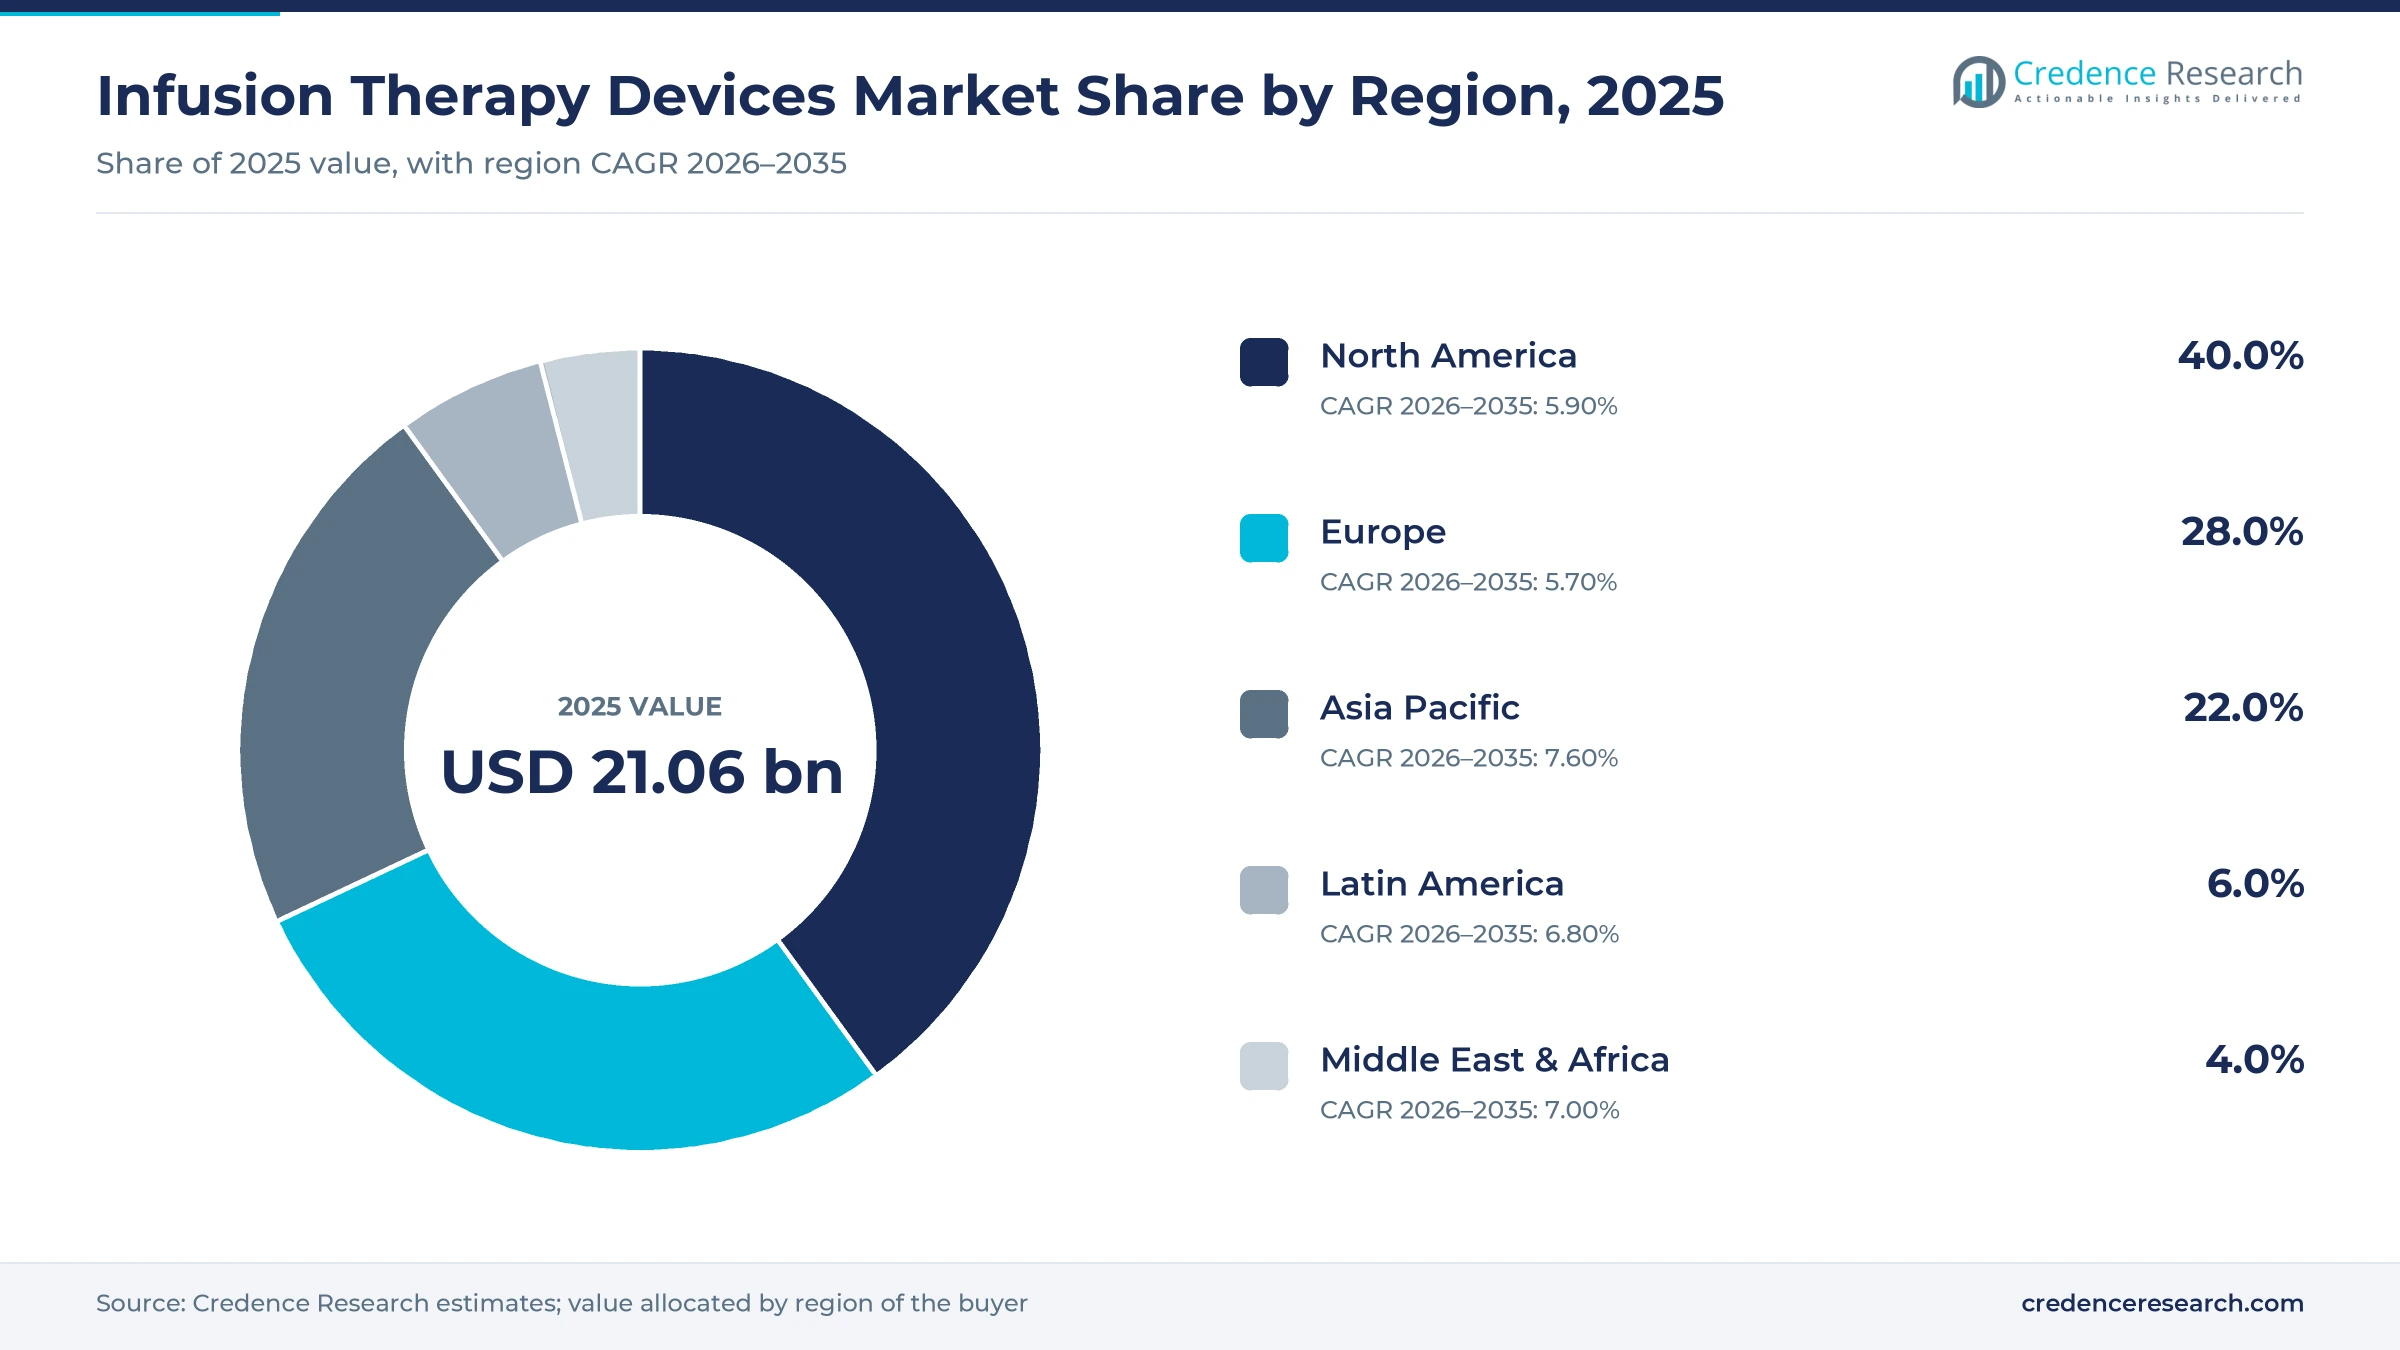
The global infusion therapy devices market was valued at USD 21.06 billion in 2025 and is projected to increase from USD 22.39 billion in 2026 to USD 38.95 billion by 2035, registering a CAGR of 6.34% during 2026–2035. Demand comes from a rising number of cancer and chronic disease patients who need intravenous medicines, wider use of subcutaneous and ambulatory dosing, and hospital programs that replace older pumps with connected systems. North America held the largest regional share, 40.0% in 2025, because U.S. hospitals buy smart pumps with drug libraries and electronic record links. Asia Pacific is the fastest-growing region at 7.60% a year, as China and India add hospital beds and oncology centers. The competitive picture changed in April 2025, when ICU Medical received U.S. clearance for a new single-channel precision pump. As a result, U.S. hospitals now compare several new pump platforms during replacement cycles.
Which pumps and care settings does this analysis cover?
The analysis counts large volume pumps, syringe pumps, elastomeric pumps and other infusion pumps such as patient-controlled analgesia and enteral units, valued at manufacturer selling prices. Hospitals buy most pumps through multiyear contracts that bundle hardware, safety software, service and dedicated administration sets.
Intravenous fluids, the medicines delivered and stand-alone catheters sit outside the scope of this analysis. The value chain runs from component and software suppliers through pump makers to distributors, group purchasing organizations, hospitals, ambulatory centers and home infusion providers, which manage pumps for patients treated outside hospitals.
Infusion Therapy Devices Market Insights
- The infusion therapy devices market grows from USD 21.06 billion in 2025 to USD 38.95 billion by 2035, a 6.34% CAGR as hospitals replace older pumps with connected systems.
- North America held 40.0% of global infusion pump value in 2025, supported by smart pump adoption and electronic record integration in U.S. hospitals.
- Large volume pumps led product types with 45.0% of 2025 value, while elastomeric pumps grow fastest at 7.31% a year through 2035.
- In April 2025, ICU Medical received FDA 510(k) clearance for the Plum Solo precision IV pump, adding a new platform to U.S. hospital replacement choices.
- In December 2025, the FDA flagged a correction for Baxter Novum IQ large volume pumps as the most serious recall type, which keeps safety central to purchasing.
Large volume pumps lead as homecare gains ground
Why do large volume pumps lead product spending?
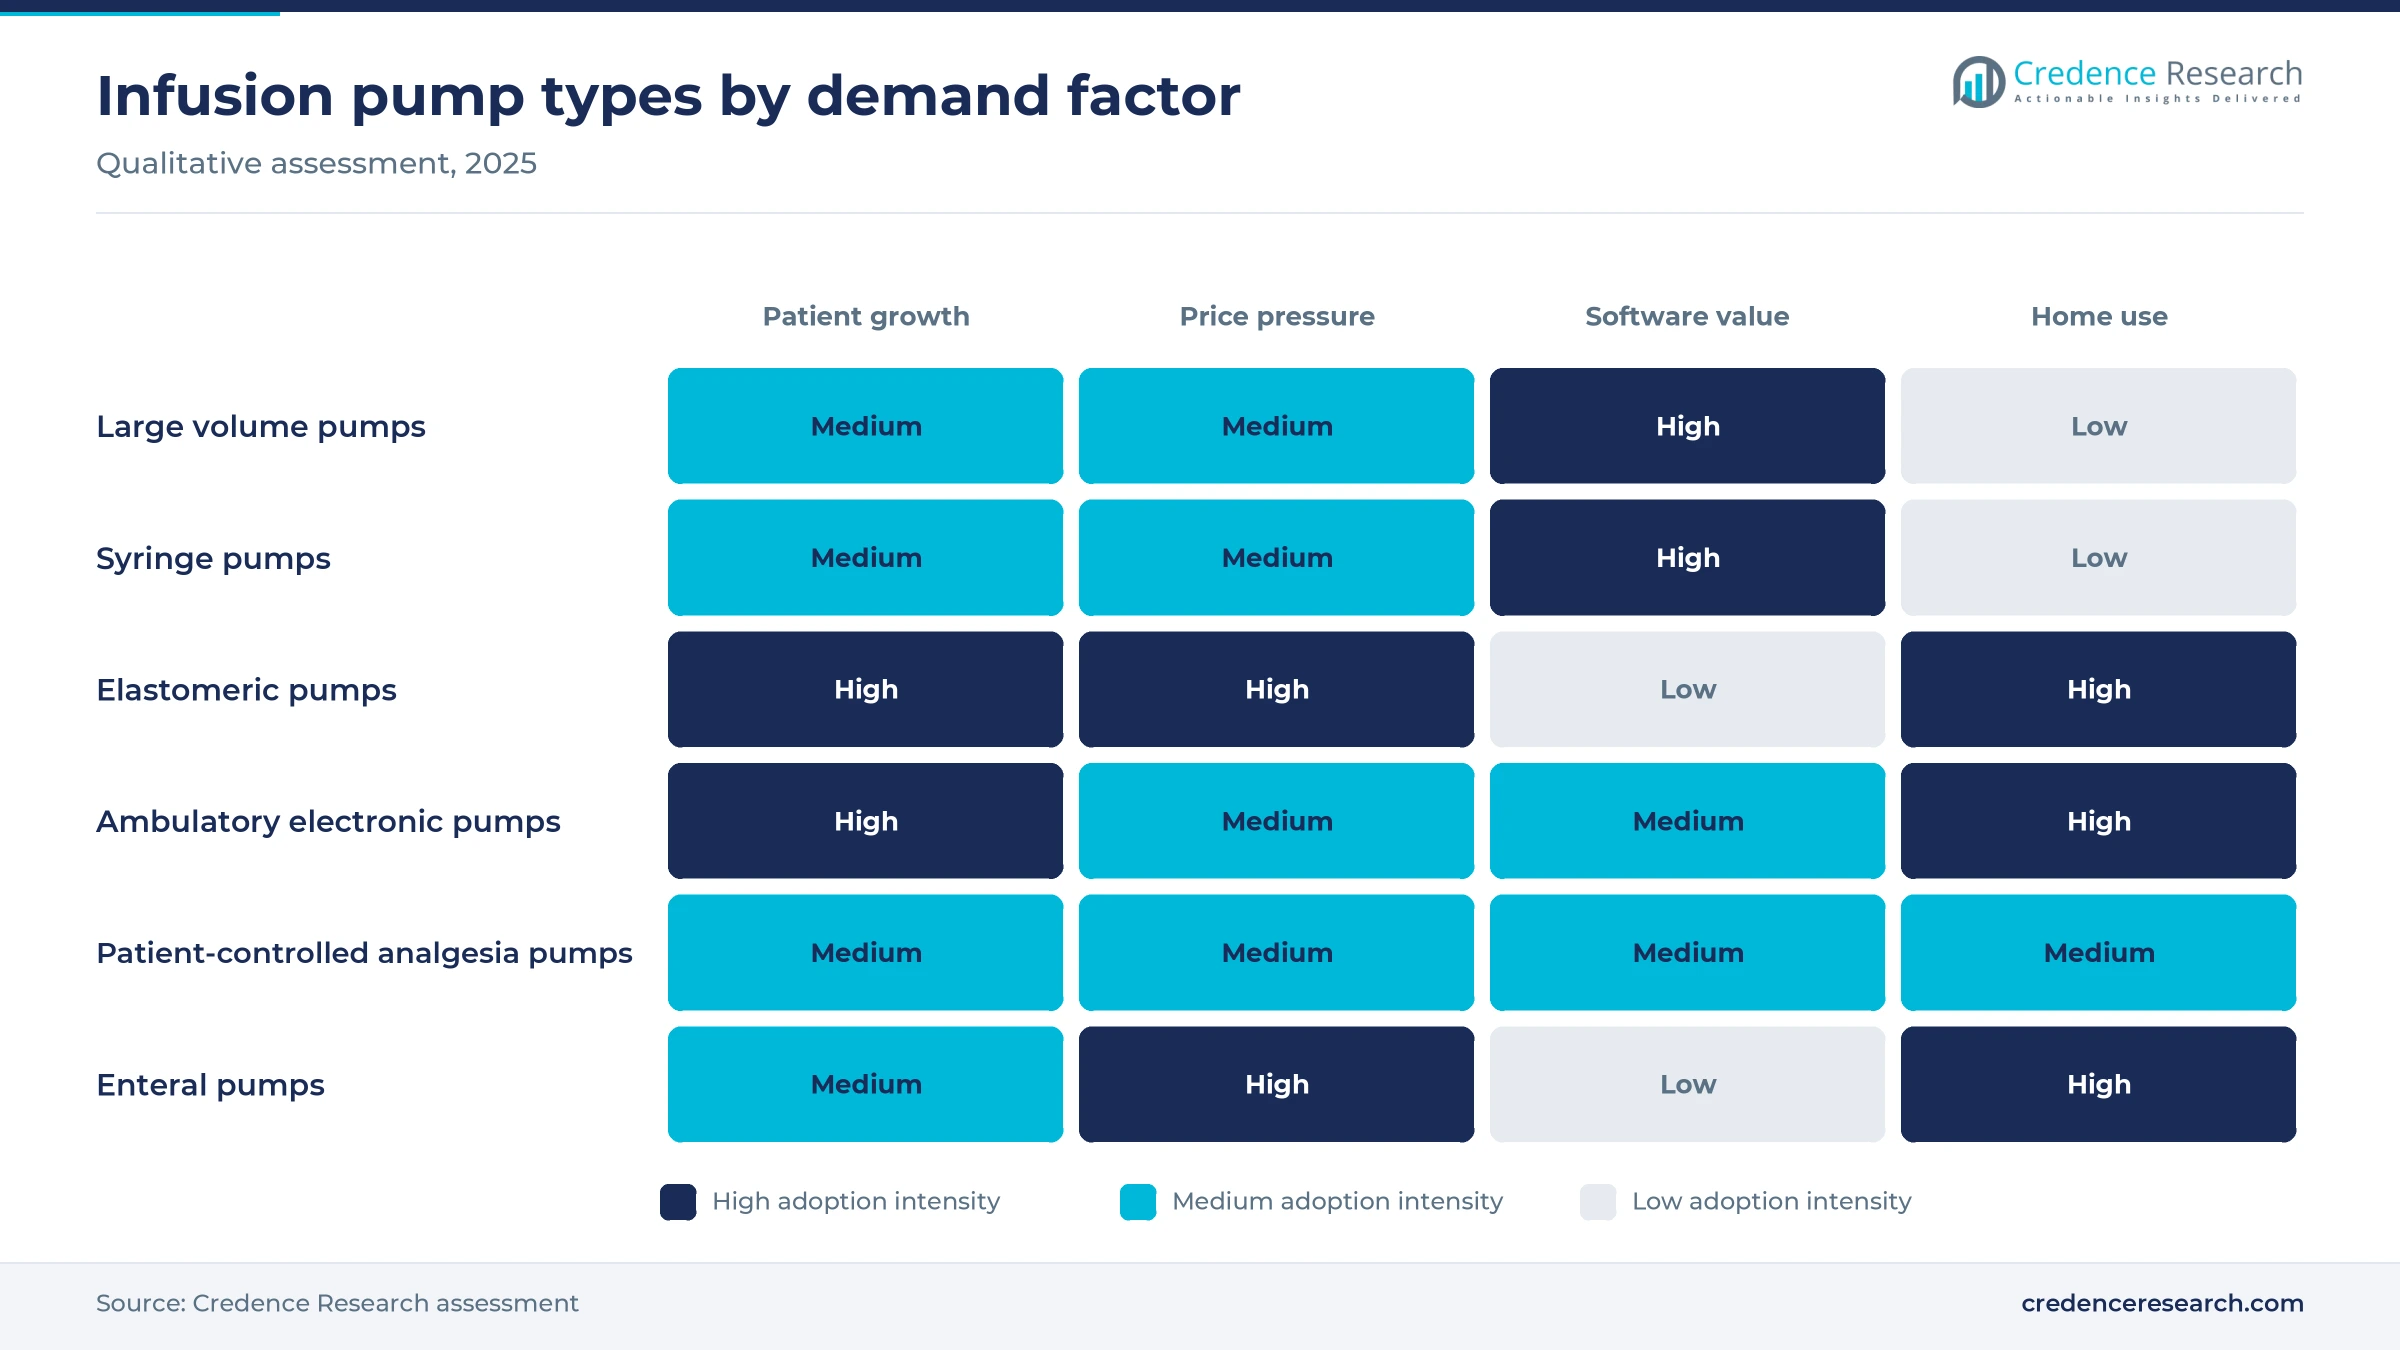
Based on product type, the market is categorized into syringe infusion pumps, large volume pumps, elastomeric pumps and others. Large Volume Pumps led with a 45.0% share of 2025 value, because nearly every hospital bed needs one for fluids, antibiotics and chemotherapy. Elastomeric Pumps grow fastest at 7.31% a year, as single-use elastomeric pumps support antibiotic and pain therapy at home. Syringe pumps remain essential in intensive care units and neonatal wards.
How fast are portable pumps gaining share?
Based on mobility, the market is categorized into portable infusion pumps and stationary infusion pumps. Stationary Infusion Pumps led with a 64.0% share of 2025 value, because bedside units dominate hospital fleets and carry higher prices. Portable Infusion Pumps grow fastest at 7.16% a year, as ambulatory chemotherapy, pain control and home antibiotic programs move patients out of hospital beds. This shift favors lightweight pumps with long battery life and simple programming.
Why does cancer care account for the largest application?
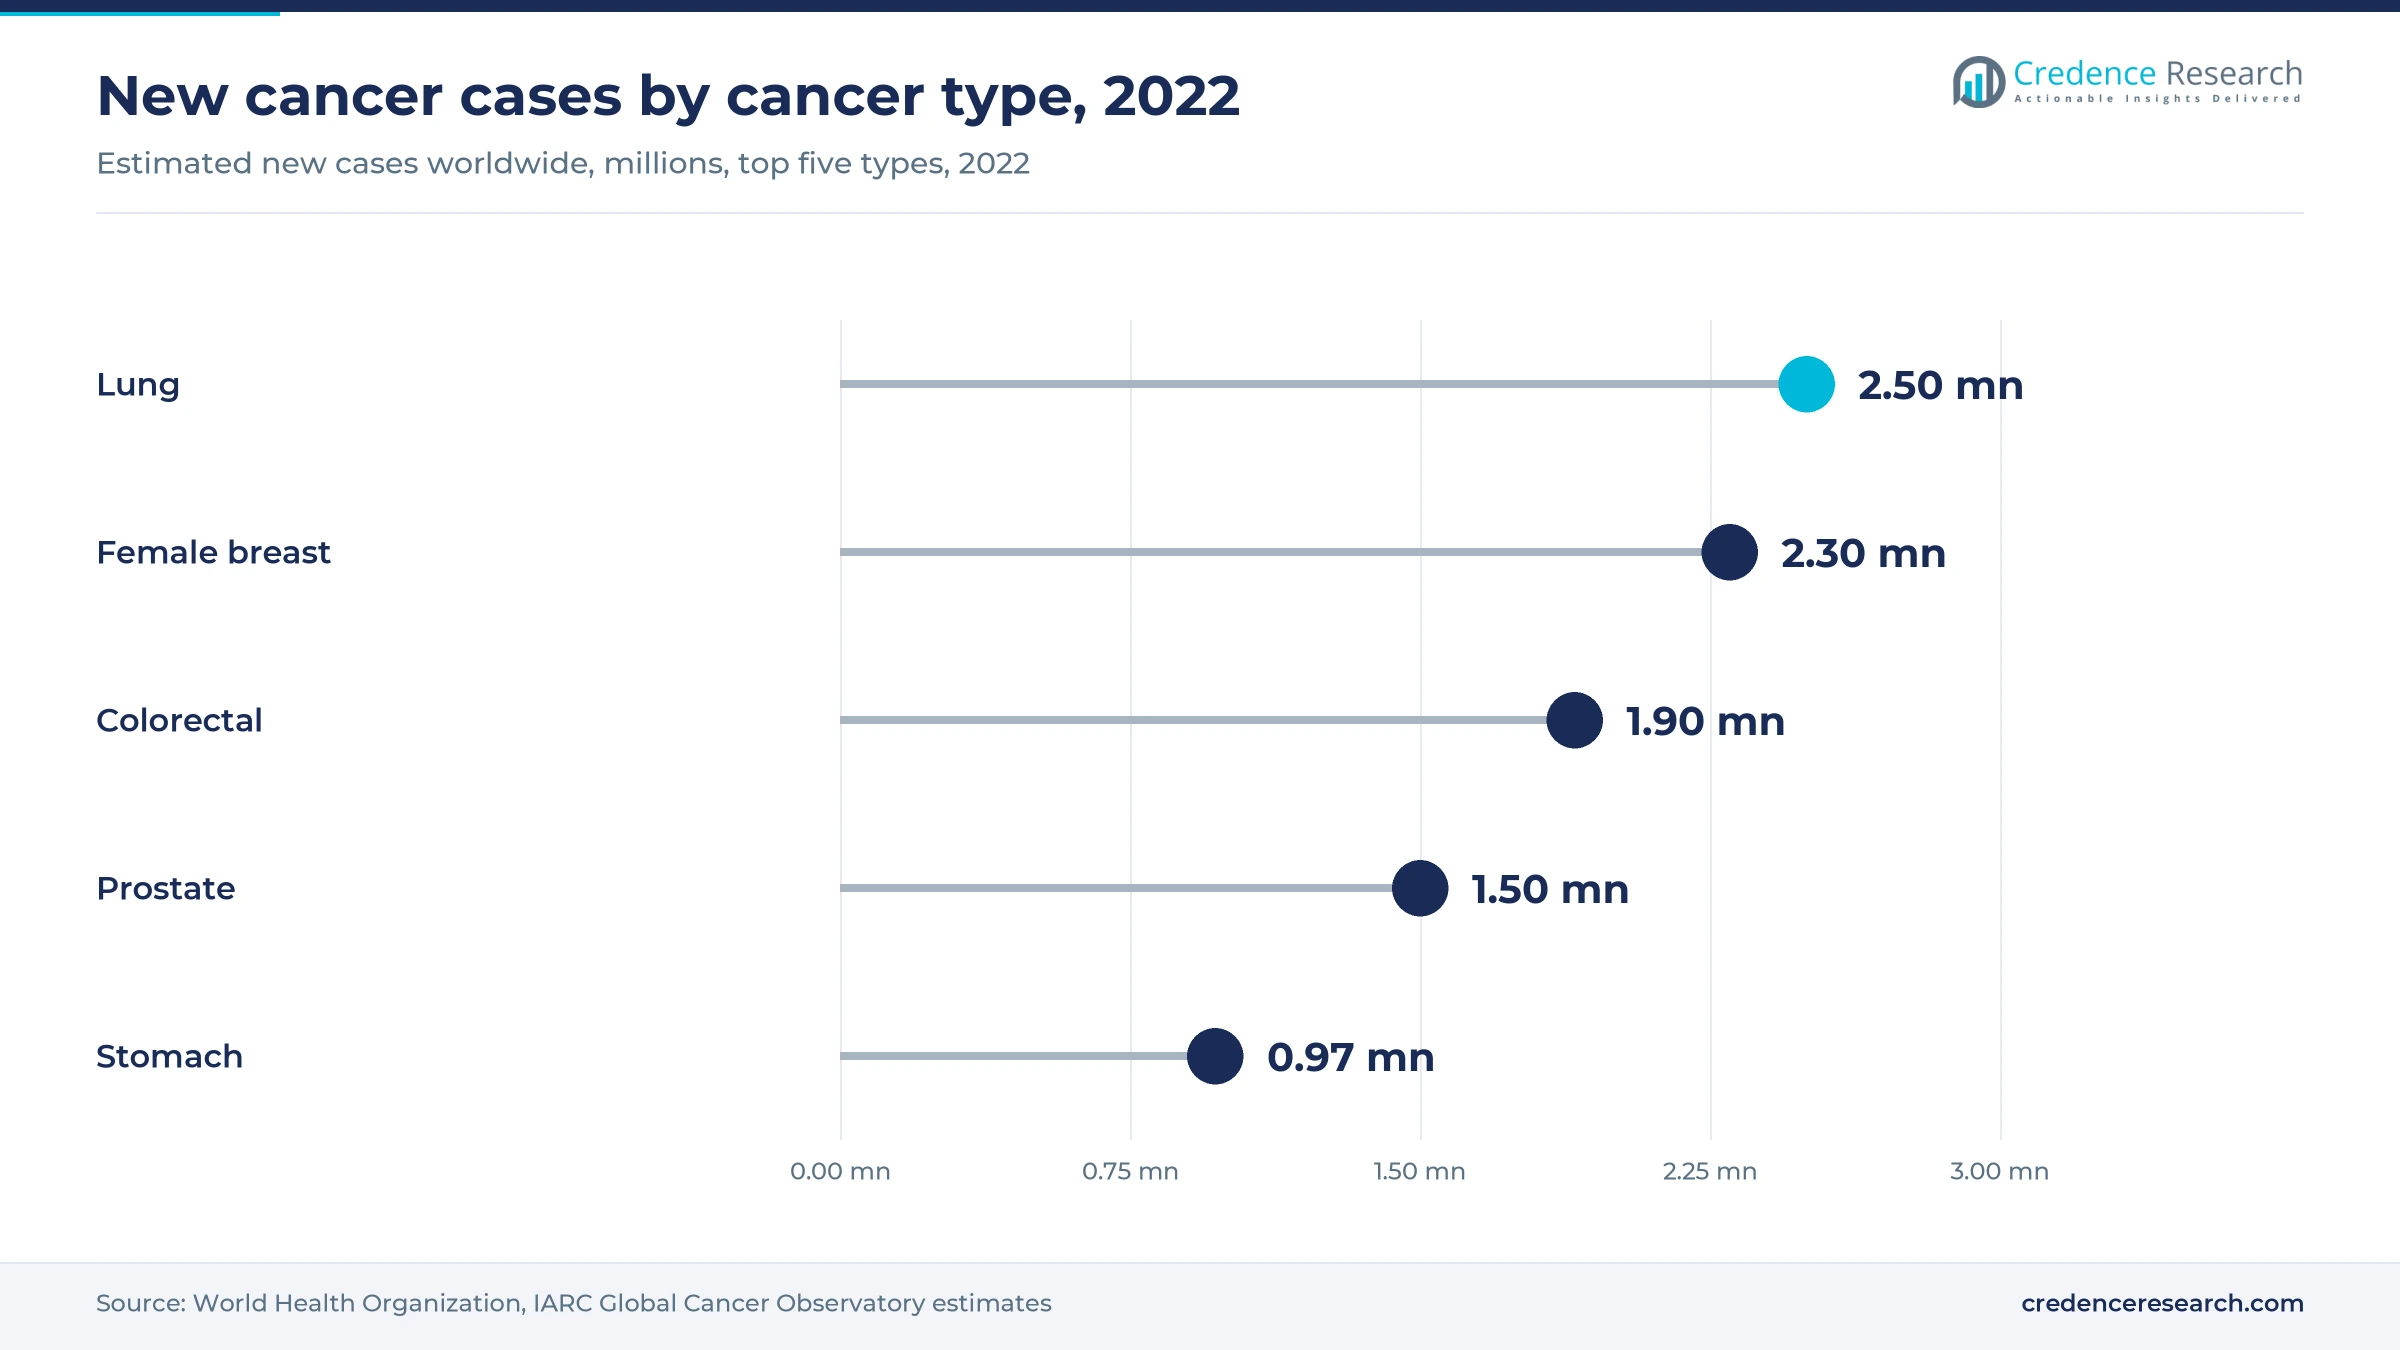
Based on application, the market is categorized into multiple sclerosis, diabetes, rheumatoid arthritis, cancer and others. Cancer led with a 32.0% share of 2025 value, because chemotherapy and supportive medicines need precise intravenous dosing over many cycles. This segment also grows fastest at 6.85% a year, as female breast cancer with 2.3 million new cases and colorectal cancer with 1.9 million new cases in 2022 add treatment courses. Diabetes uses dedicated insulin pumps, while multiple sclerosis and rheumatoid arthritis rely on clinic-based biologic infusions.
Where are infusion pumps used most often?
Based on end-user, the market is categorized into hospitals and clinics, ambulatory surgical centers, homecare and others. Hospitals and Clinics led with a 62.0% share of 2025 value, because inpatients receive most intravenous therapy and hospitals renew large pump fleets every several years. Homecare grows fastest at 7.55% a year, as payers prefer lower-cost settings for long antibiotic, nutrition and chemotherapy courses. Ambulatory surgical centers add steady demand for anesthesia and pain control pumps.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Large Volume Pumps | 45.0% | Elastomeric Pumps | 7.31% |
| By Mobility | Stationary Infusion Pumps | 64.0% | Portable Infusion Pumps | 7.16% |
| By Application | Cancer | 32.0% | Cancer | 6.85% |
| By End-User | Hospitals and Clinics | 62.0% | Homecare | 7.55% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Cancer, diabetes and hospital safety needs lift demand
How does the rising cancer burden sustain pump demand?
The rising cancer burden sustains pump demand, because most chemotherapy and many supportive medicines are given by infusion. The World Health Organization reported in February 2024 that an estimated 20 million new cancer cases and 9.7 million deaths occurred in 2022. Lung cancer led with 2.5 million new cases, or 12.4% of the total. The same agency projects over 35 million new cases in 2050, a 77% increase. As a result, oncology centers keep adding infusion chairs and pumps, both in hospitals and in outpatient clinics.
Why does the growing diabetes population matter for infusion?
The growing diabetes population matters for infusion, because patients need insulin delivery and frequent hospital care for complications. The International Diabetes Federation reported in April 2025 that 589 million adults now live with diabetes, and 252 million of them are unaware of the condition. Hospitalized patients with diabetes often receive intravenous insulin through large volume or syringe pumps, and the federation projects 853 million adults with diabetes by 2050. In turn, this patient base adds steady demand across hospital and home settings.
How do medication safety programs drive pump replacement?
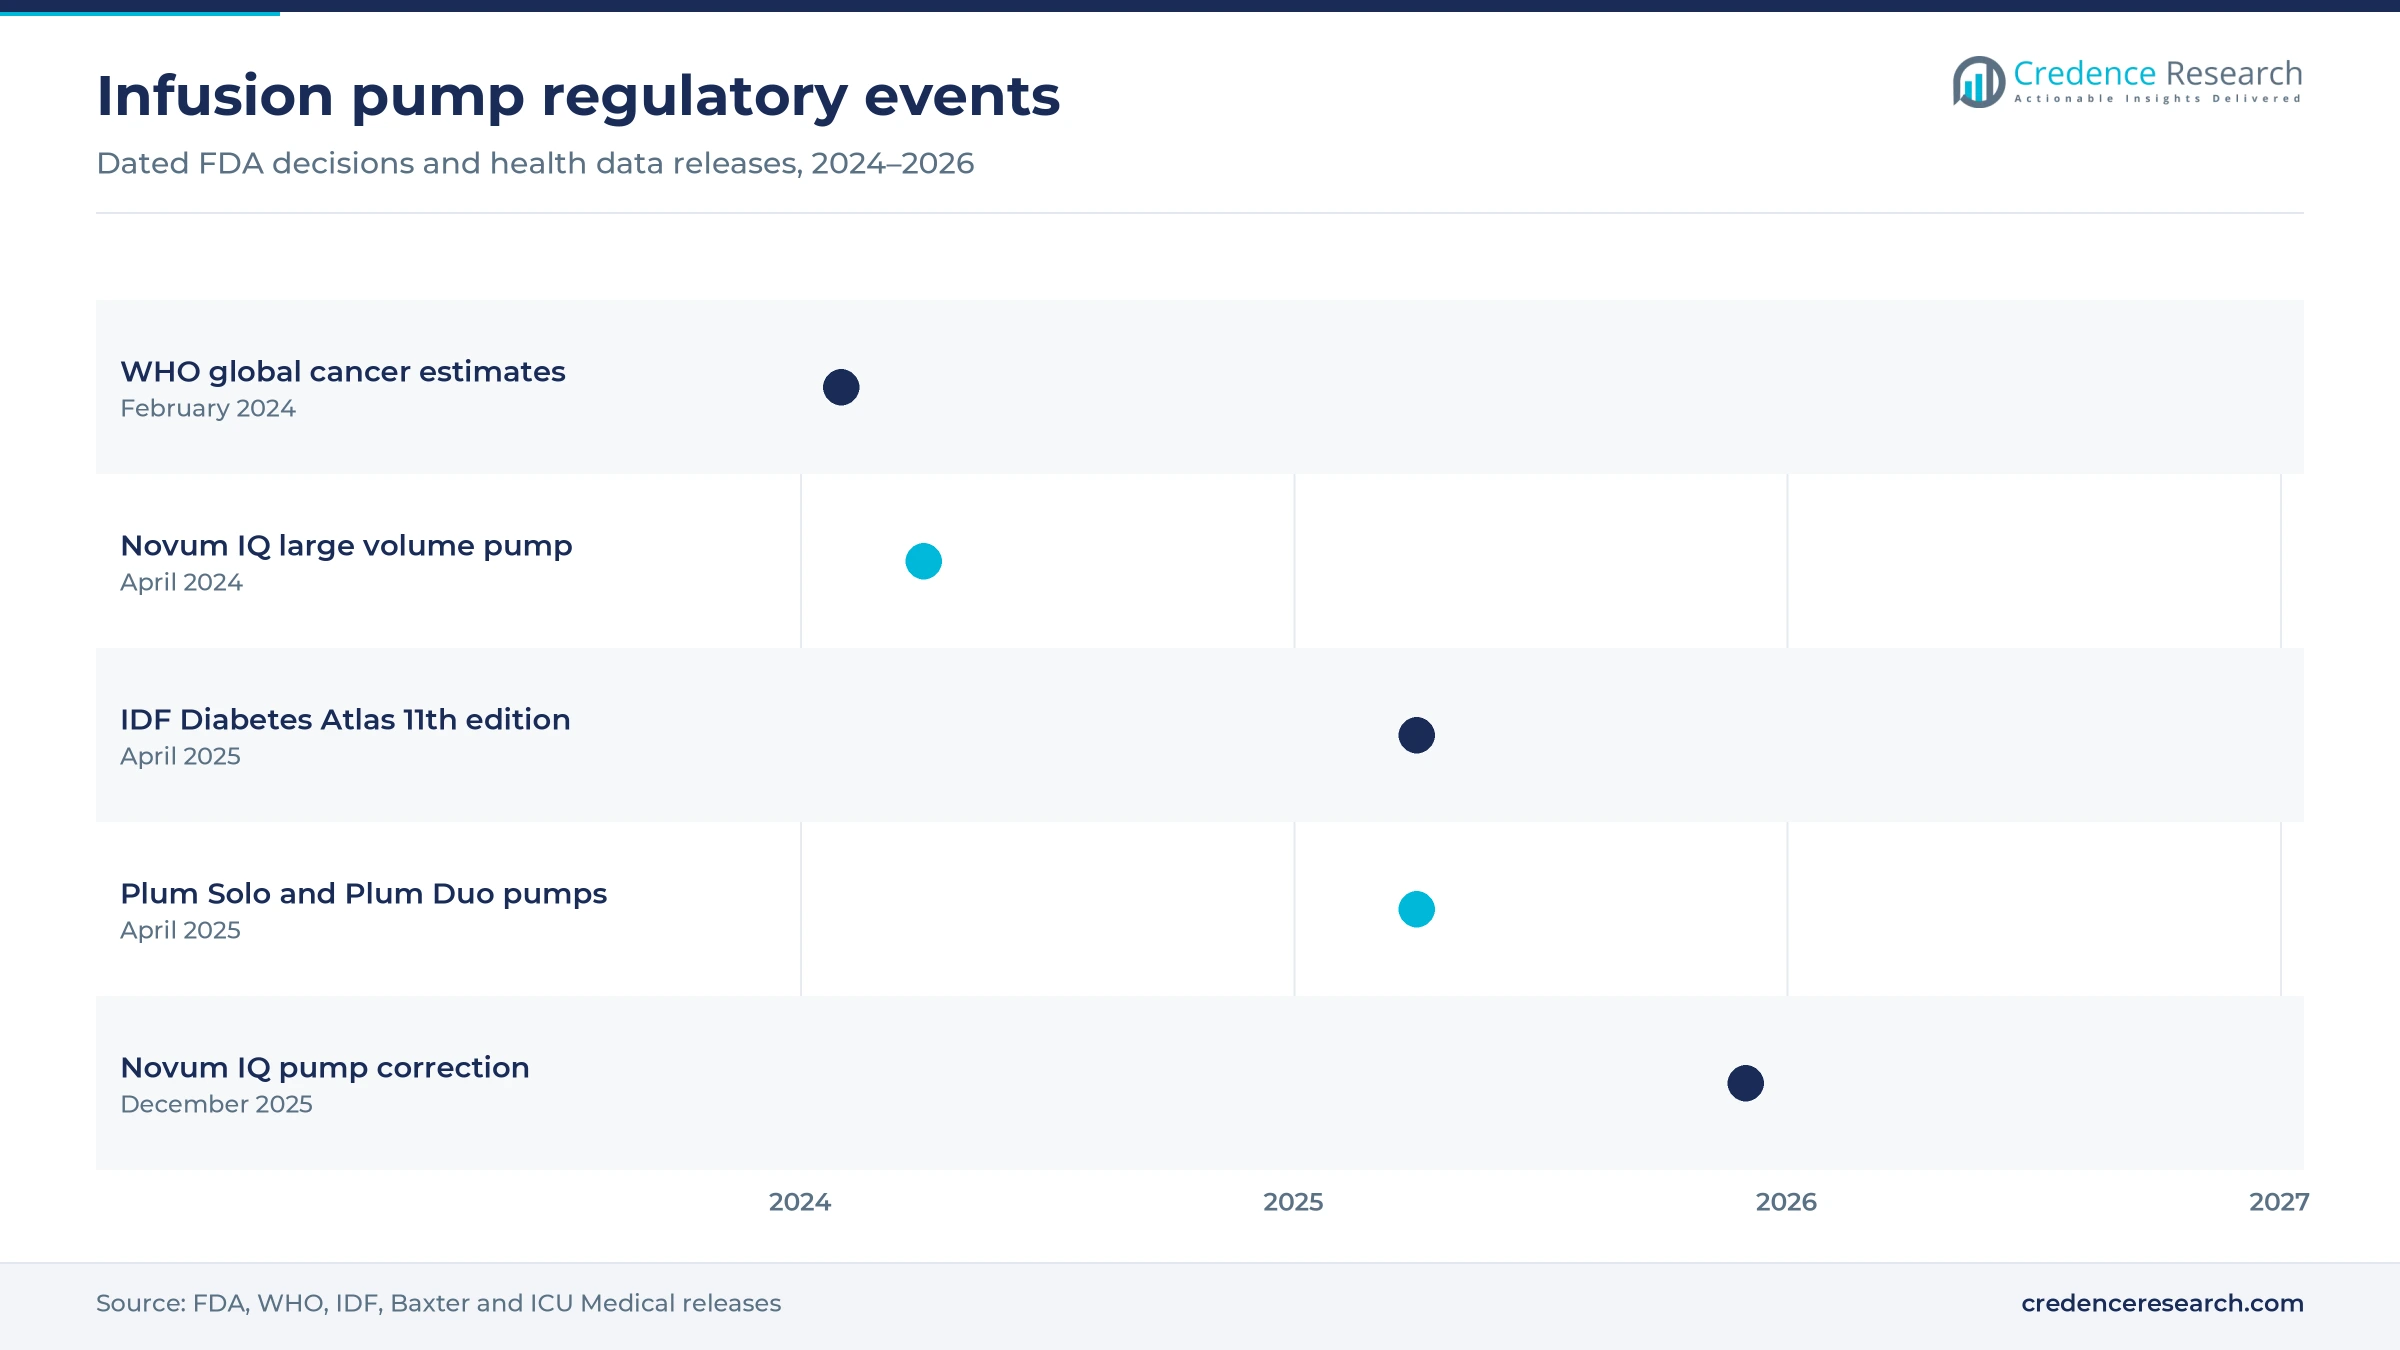
Medication safety programs drive pump replacement, because hospitals want drug libraries and dose limits that prevent programming errors. In April 2024, Baxter announced FDA clearance of the Novum IQ large volume pump with Dose IQ safety software, which links pumps to electronic medical records for automatic programming. The Dose IQ and IQ Enterprise tools are both certified to the UL 2900 series of cybersecurity standards, according to Baxter. As a result, hospitals that upgrade record systems often replace entire pump fleets within the same project.
Why does the shift to outpatient care lift portable pump use?
The shift to outpatient care lifts portable pump use, because payers prefer to treat stable patients outside hospital beds. Home infusion providers now deliver antibiotics, parenteral nutrition, chemotherapy and immune globulin to patients at home. This model depends on lightweight pumps, elastomeric devices and reliable central venous catheters for long courses. The World Health Organization estimates that about 1 in 5 people develop cancer in their lifetime, and many of them receive chemotherapy in outpatient chairs. In turn, homecare and ambulatory settings grow faster than hospitals through 2035.
Connected pumps and home infusion reshape purchasing
How is electronic record integration shifting pump purchasing?
Electronic record integration is shifting pump purchasing, because hospitals want orders sent directly from the record to the pump. Interoperable systems cut manual programming steps and document each infusion automatically. Baxter, ICU Medical and other major suppliers now market pumps with two-way record links in the United States. In April 2024, Baxter announced that both its Novum IQ large volume and syringe pumps were available to order in the United States. As a result, software capability now weighs as heavily as hardware price in many hospital tenders.
Why are precision IV pumps rising as a new category?
Precision IV pumps are rising as a new category, because hospitals want accurate delivery across many fluid types and container heights. In April 2025, ICU Medical announced 510(k) clearance of the Plum Solo precision IV pump, a single-channel complement to its dual-channel Plum Duo. The company also received clearance for updated LifeShield infusion safety software. In turn, competition for U.S. hospital fleet contracts intensified between 2024 and 2026.
Can home infusion services open new demand for portable pumps?
Pump makers have a clear opening in home infusion services, because more patients receive long therapy courses outside hospitals. Home healthcare providers need pumps that patients can carry, alarms they understand and remote monitoring for nurses. Elastomeric and ambulatory electronic pumps fit this model, since they need little training. As a result, suppliers that pair devices with service and supplies can capture recurring revenue streams.
Where can biologic infusions add pump users in chronic disease?
Biologic infusions give device makers room to add users, because multiple sclerosis and rheumatoid arthritis patients often receive scheduled intravenous treatment. Many multiple sclerosis medicines given in infusion centers require controlled rates and monitoring during each session. Infusion centers and home providers both treat these patients, which widens the buyer base. In turn, pumps with drug libraries tailored to biologics gain demand in outpatient settings.
Recalls, cyber risk and price pressure slow upgrades
Why do recalls and corrections weigh on buyer confidence?
Recalls and corrections weigh on buyer confidence, because pump failures can cause over-infusion, under-infusion or delayed therapy. In December 2025, the FDA posted a correction for Baxter Novum IQ large volume pumps and identified it as the most serious type of recall. Eitan Medical also corrected 1,383 Sapphire pumps in the United States in 2023 for air detection failures, after letters sent on Sept. 11 and 12, 2023. As a result, hospitals extend evaluations and demand stronger service commitments before replacing fleets.
How do cybersecurity requirements raise development costs?
Cybersecurity requirements raise development costs, because connected pumps exchange data with hospital networks and record systems. Regulators expect makers to document software security, patching processes and vulnerability handling before clearance. Smaller manufacturers often lack the teams needed to meet these rules across several markets and product generations. Hospitals also ask suppliers to keep issuing security patches over the long service lives of installed pumps. In turn, compliance costs favor large suppliers and slow the entry of new pump makers.
Why does price pressure limit value growth in emerging markets?
Price pressure limits value growth in emerging markets, because public hospitals buy pumps through tenders that reward the lowest bid. Local makers in China and India compete strongly on basic volumetric and syringe pumps. Buyers there often skip drug library software to save cost, which lowers average selling prices. Many public tenders also bundle pumps with consumables at fixed prices over several contract years. As a result, unit volumes grow faster than value in these regions.
How do staffing shortages slow adoption of advanced systems?
Staffing shortages slow adoption of advanced systems, because nurses need training time to learn new pumps and workflows. Hospitals with high nurse turnover hesitate to change platforms during busy periods, even when Hospitals and Clinics hold 62.0% of 2025 value. Integration projects also require pharmacy and IT staff to build drug libraries and record interfaces, which often takes many months in large health systems. In turn, many replacement projects take longer than planned, which delays orders for suppliers.
North America leads as Asia Pacific gains pace
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 8.42 | 40.0% | 5.90% |
| Europe | 5.90 | 28.0% | 5.70% |
| Asia Pacific | 4.63 | 22.0% | 7.60% |
| Latin America | 1.26 | 6.0% | 6.80% |
| Middle East & Africa | 0.84 | 4.0% | 7.00% |
Why does North America hold the largest regional share?
North America held a 40.0% share of 2025 value and grows at 5.90% a year through 2035. The United States drives this position, because hospitals use smart pumps with drug libraries and record integration as standard practice. U.S. regulators cleared new pumps from Baxter and ICU Medical between 2024 and 2025, which triggered fleet evaluations. In April 2025, ICU Medical announced the launch of its IV Performance Platform after the Plum Solo clearance. Home infusion is also well established, because many payers cover therapy outside hospitals.
How fast is Asia Pacific adding pump capacity?
Asia Pacific held a 22.0% share of 2025 value and is the fastest-growing region at 7.60% a year. China and India add hospital beds, cancer centers and intensive care units, which all need large volume and syringe pumps. Japan and South Korea buy higher-priced connected systems for aging populations. Local makers such as Mindray compete strongly, which keeps prices competitive across the region.
What shapes demand across Europe?
Europe held a 28.0% share of 2025 value and grows at 5.70% a year, the slowest pace of the five regions. Germany, France, the United Kingdom and Italy account for most spending, because national health systems run regular pump tenders. German suppliers such as Fresenius Kabi AG hold strong positions in their home markets. However, tender-based purchasing and long replacement cycles keep value growth below the global average.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 6.80% a year through 2035. Brazil and Mexico lead regional spending, because private hospital groups upgrade intensive care and oncology units. Public buyers still favor basic pumps without safety software, which limits average prices.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 7.00% a year through 2035. Gulf states fund new hospitals with modern infusion systems, while much of Africa relies on gravity drips and donated pumps. This gap limits the use of electronic pumps outside major cities and private hospitals.
FDA clearances and corrections for IV pumps since 2024
| Development | Status and market relevance |
|---|---|
| In April 2024, Baxter received FDA 510(k) clearance for the Novum IQ large volume pump with Dose IQ safety software. | Cleared; joins the Novum IQ syringe pump on one platform with record integration |
| In April 2025, ICU Medical received FDA 510(k) clearance for the Plum Solo precision IV pump and updated Plum Duo pump. | Cleared; completes the initial launch of the ICU Medical IV Performance Platform |
| In April 2025, ICU Medical also received FDA clearance for updated LifeShield infusion safety software. | Cleared; supports drug library and record connectivity for Plum pumps |
| In December 2025, the FDA posted a correction for all Baxter Novum IQ large volume pumps, identified as the most serious recall type. | Correction; devices stay in use with recommended actions from Baxter |
Dose error software and EMR links lead innovation
- Dose error reduction software checks each program against hospital drug libraries, which blocks doses outside safe limits and alerts nurses to soft-limit breaches.
- Electronic record integration sends orders from the record to the pump and documents each infusion, which cuts manual entry and improves billing accuracy for hospitals.
- Precision delivery mechanisms keep flow accurate across fluid types and container heights, which supports critical care and pediatric dosing at very low rates.
- Over-the-air software updates let hospitals update pump fleets remotely, which keeps devices on nursing floors and reduces downtime for biomedical teams.
- Single-use elastomeric pumps deliver medicine without power or programming, which suits home antibiotic courses and post-surgical pain control.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Pump makers compete on safety software and service
Competition is led by diversified medical technology companies with large hospital installed bases and long service relationships. Baxter, ICU Medical, Becton, Dickinson and Company and Fresenius Kabi AG compete for U.S. and European hospital fleets with large volume and syringe pumps linked to safety software. Smiths Group plc remains a recognized name in the field through its legacy medical device activities. Mindray competes strongly in Asia and emerging markets on price and service. Eitan Medical, Micrel Medical Devices SA, Monidor Oy and AKAS Infusions focus on specialty pumps, ambulatory use or infusion monitoring. Narang Medical Limited, Trivitron Healthcare, Ace-medical, Chmyx Inc. and Ossila serve regional or niche demand. As a result, buyers increasingly favor suppliers that combine reliable hardware, software integration and responsive field service.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Baxter | Diversified | Novum IQ large volume and syringe pumps with Dose IQ safety software |
| ICU Medical | Specialist | Plum Solo and Plum Duo precision IV pumps and LifeShield software |
| Becton, Dickinson and Company | Diversified | Alaris infusion system and related administration sets |
| B. Braun SE | Diversified | Space infusion pumps and hospital infusion consumables |
| Fresenius Kabi AG | Diversified | Infusion pumps alongside intravenous fluids and medicines |
| Mindray | Diversified | BeneFusion volumetric and syringe pumps for hospitals |
| Smiths Group plc | Diversified | Legacy medical device activities in infusion |
| Eitan Medical | Specialist | Sapphire multi-therapy, epidural and Plus infusion pumps |
| Micrel Medical Devices SA | Specialist | Ambulatory infusion pumps for outpatient care |
| Monidor Oy | Specialist | Infusion monitoring technology |
| AKAS Infusions | Specialist | Infusion products for hospitals |
| Narang Medical Limited | Regional supplier | Hospital equipment including infusion products |
| Trivitron Healthcare | Regional supplier | Medical devices for hospitals in India and export markets |
| Ace-medical | Regional supplier | Infusion and hospital devices |
| Chmyx Inc. | Niche supplier | Infusion-related products |
| Ossila | Niche supplier | Laboratory fluid-handling equipment |
Smart pump replacement sets the growth pace to 2035
Credence Research's view is that smart pump replacement will set the pace of growth through 2035, because hospitals link pumps to electronic records and drug libraries. The overall market grows at 6.34% a year, supported by a rising cancer burden and the shift of long therapy courses to homecare. Elastomeric and portable pumps grow faster than bedside units as outpatient care expands. Companies that combine reliable pumps, interoperable software and strong field service will win the most hospital fleet contracts.
How Credence Research sized infusion pump spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by product type, mobility, application, end-user and region. Regional and segment splits are Credence Research estimates informed by World Health Organization and International Diabetes Federation statistics, U.S. regulator notices and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Infusion pump spending outlook to 2035
By 2035, the infusion therapy devices market is projected to reach USD 38.95 billion, with growth led by connected large volume pumps, portable pumps and home infusion. Large volume pumps will remain the largest product area, as hospitals renew fleets with record-linked systems. North America keeps the highest spending per bed, while Asia Pacific adds the most new pumps. Homecare will take a larger share of value, because payers move stable patients out of hospitals. As a result, advantage will depend on safety, interoperability and service.
Frequently Asked Questions
How big is the global infusion therapy devices market?
Which product type leads the infusion therapy devices market?
Which region leads infusion pump spending?
Which application accounts for most infusion pump use?
Why are portable infusion pumps gaining share?
What recent FDA actions affect infusion pumps?
Who are the leading infusion therapy device companies?
What restrains growth in infusion therapy devices?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Large Volume Pumps
- 1.2.2 Syringe Infusion Pumps
- 1.2.3 Elastomeric Pumps
- 1.2.4 Others
- 1.3 By Mobility
- 1.3.1 Stationary Infusion Pumps
- 1.3.2 Portable Infusion Pumps
- 1.4 By Application
- 1.4.1 Cancer
- 1.4.2 Diabetes
- 1.4.3 Multiple Sclerosis
- 1.4.4 Rheumatoid Arthritis
- 1.4.5 Others
- 1.5 By End-User
- 1.5.1 Hospitals and Clinics
- 1.5.2 Ambulatory Surgical Centers
- 1.5.3 Homecare
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 21.06 billion → 2035: USD 38.95 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Infusion Therapy Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Infusion Therapy Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Infusion Therapy Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Infusion Therapy Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Infusion Therapy Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Infusion Therapy Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Infusion Therapy Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Infusion Therapy Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 21.06 billion → 2035: USD 38.95 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Infusion Therapy Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Large Volume Pumps
- 12.3.7.2 Syringe Infusion Pumps
- 12.3.7.3 Elastomeric Pumps
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Mobility - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Stationary Infusion Pumps
- 12.4.7.2 Portable Infusion Pumps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cancer
- 12.5.7.2 Diabetes
- 12.5.7.3 Multiple Sclerosis
- 12.5.7.4 Rheumatoid Arthritis
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospitals and Clinics
- 12.6.7.2 Ambulatory Surgical Centers
- 12.6.7.3 Homecare
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Infusion Therapy Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Infusion Therapy Devices Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Infusion Therapy Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Infusion Therapy Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Fresenius Kabi AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ossila
- 18.4 Ace-medical
- 18.5 ICU Medical
- 18.6 Chmyx Inc.
- 18.7 Mindray
- 18.8 Baxter
- 18.9 Becton, Dickinson and Company
- 18.10 Micrel Medical Devices SA
- 18.11 AKAS Infusions
- 18.12 Narang Medical Limited
- 18.13 Monidor Oy
- 18.14 Smiths Group plc
- 18.15 B. Braun SE
- 18.16 Trivitron Healthcare
- 18.17 Eitan Medical
- 18.18 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

