
Cardiovascular devices market grows on catheter therapies
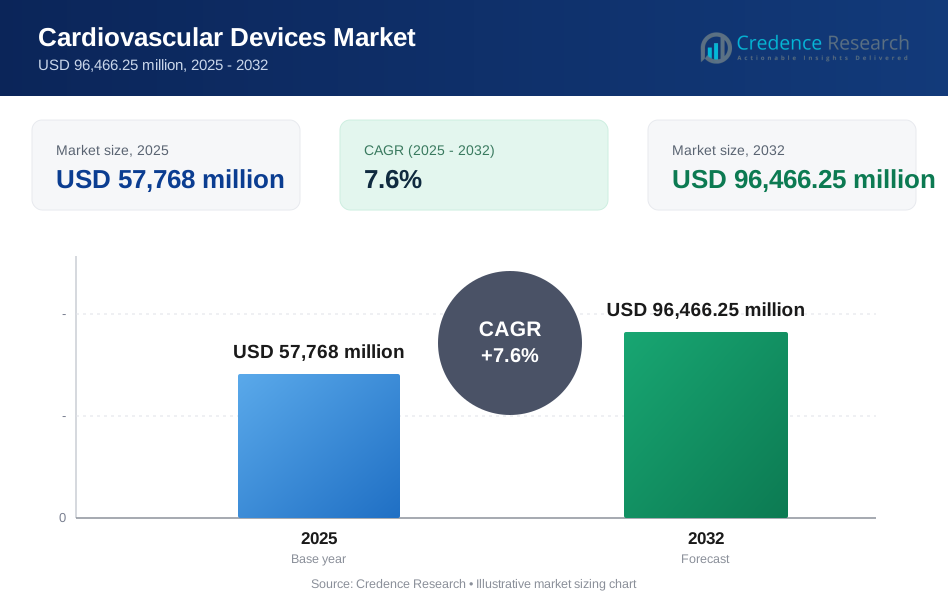
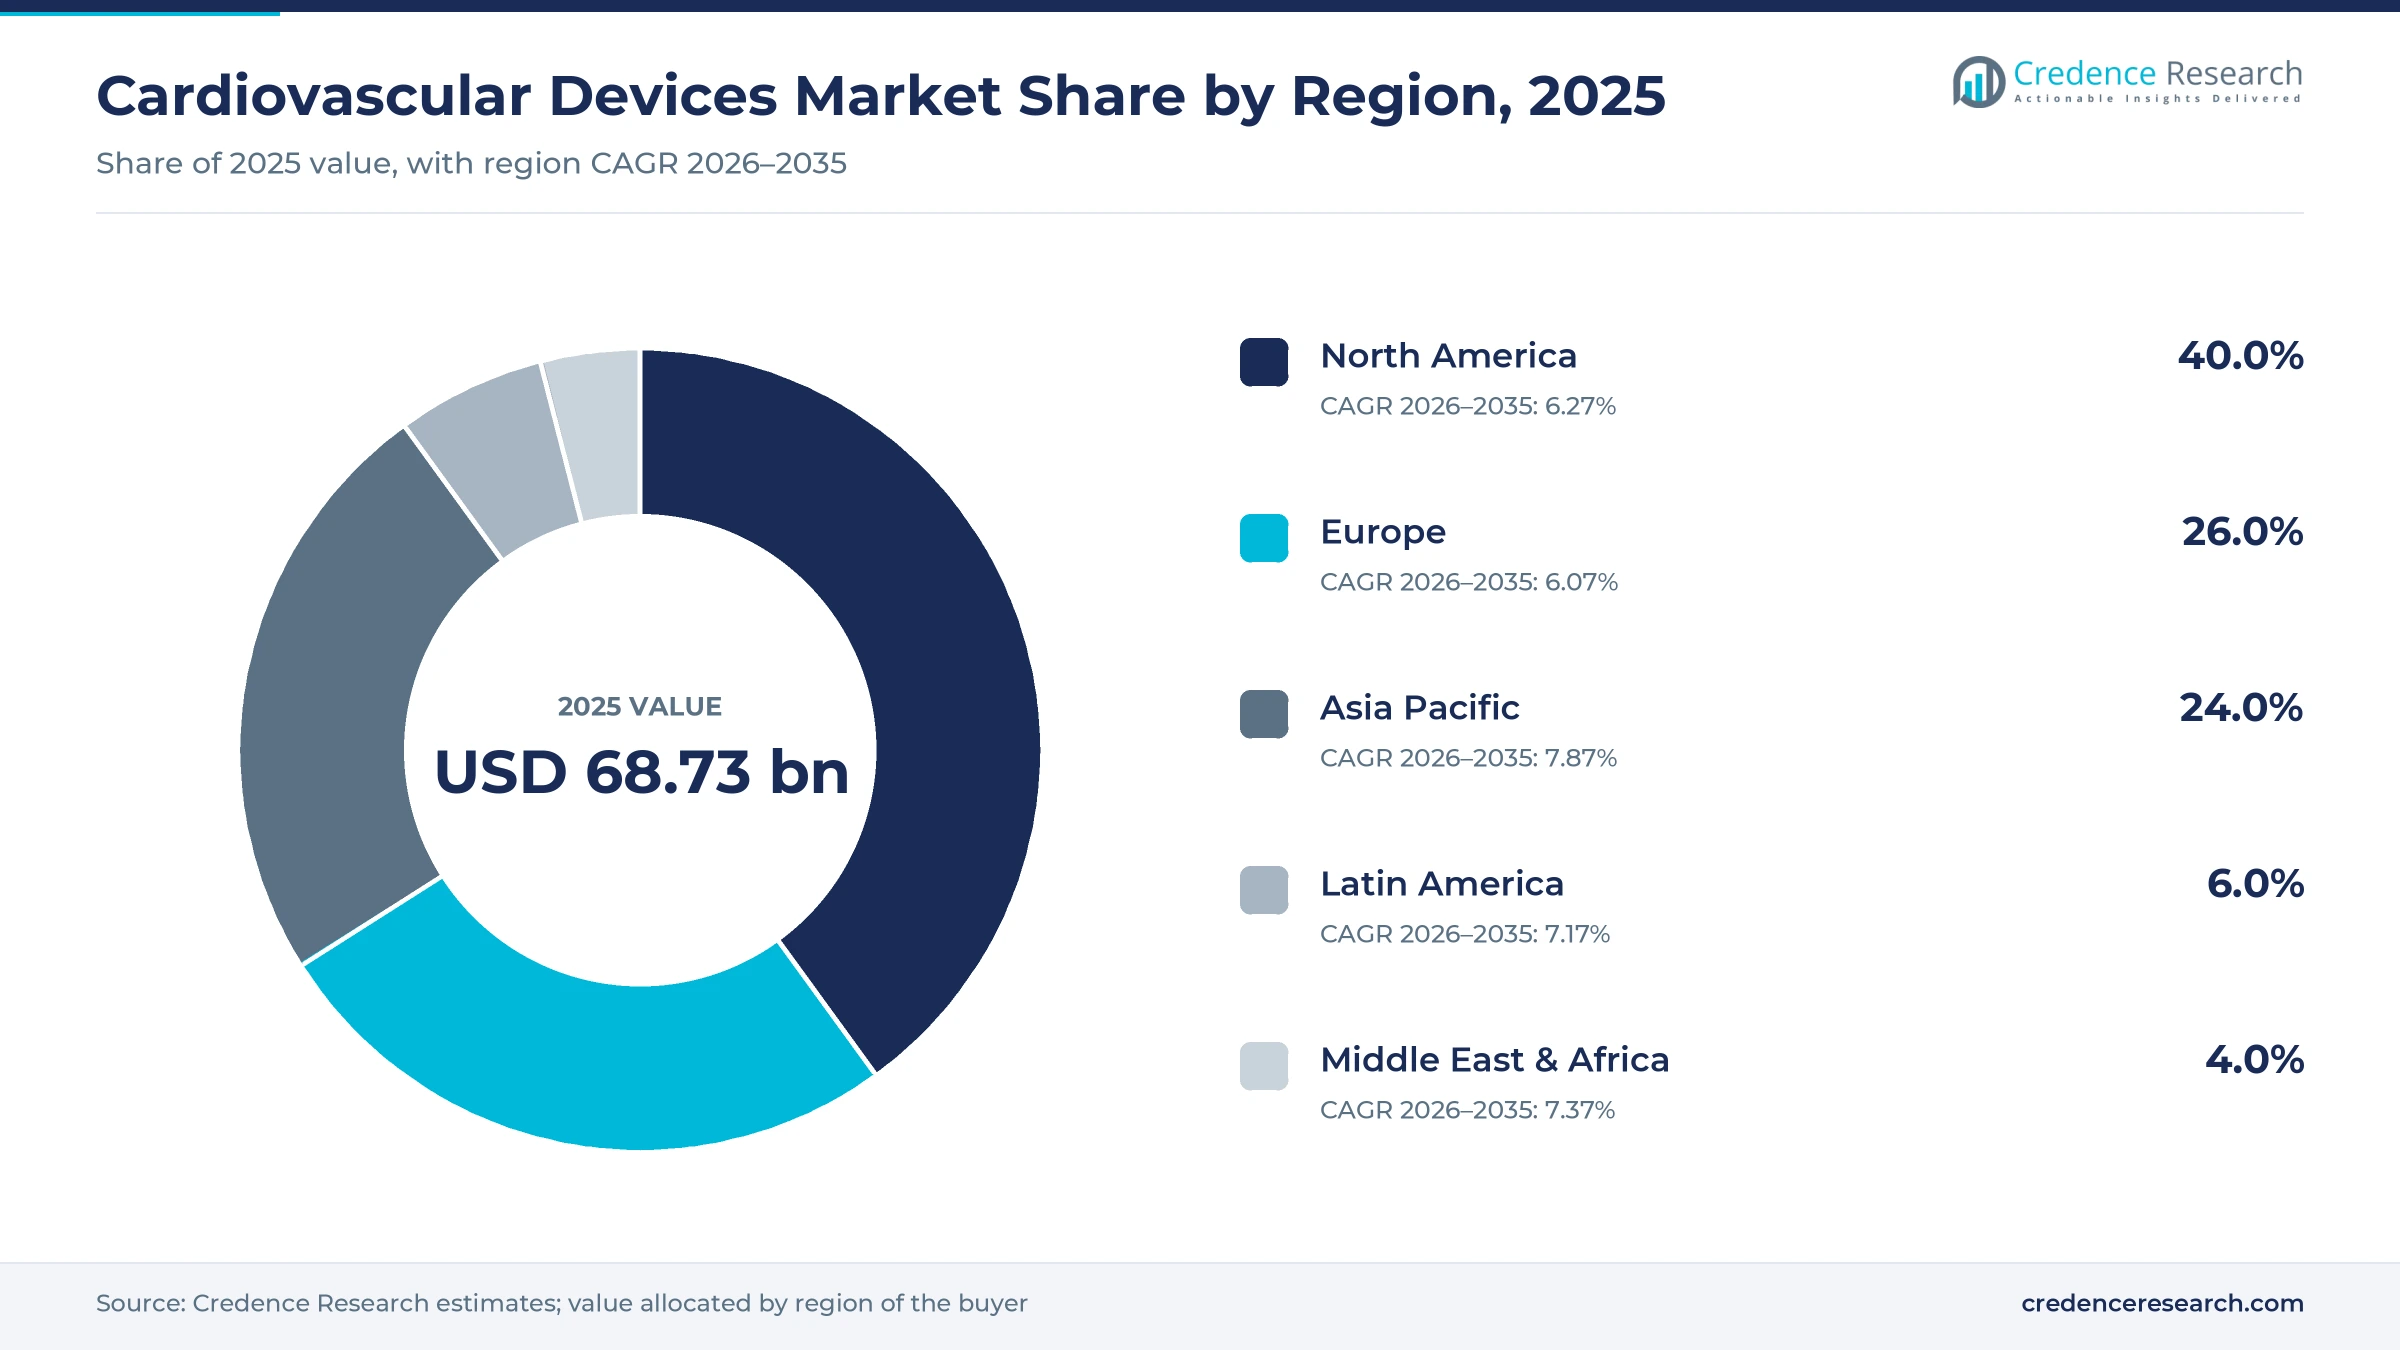
The global cardiovascular devices market was valued at USD 68.73 billion in 2025 and is projected to increase from USD 73.35 billion in 2026 to USD 131.73 billion by 2035, registering a CAGR of 6.72% during 2026–2035. Demand comes from aging populations, rising rates of coronary artery disease, atrial fibrillation and heart failure, and a steady shift from open surgery toward catheter-based treatment. North America held the largest regional share, 40.0% in 2025, because high procedure volumes and broad reimbursement support premium implants and ablation systems. Asia Pacific is the fastest-growing region at 7.87% a year, as China, India and Southeast Asia add catheterization laboratories and wider insurance coverage. The technology picture shifted in 2024 and 2025, when U.S. regulators approved several pulsed field ablation systems for atrial fibrillation. As a result, electrophysiology has become the most dynamic product area, while imaging and monitoring keep a large installed base.
Which products and care settings does this analysis cover?
The analysis counts cardiac imaging systems, rhythm management implants, cardiac assist devices, interventional cardiology products, electrophysiology systems and cardiac monitoring equipment, valued at manufacturer selling prices. Hospitals buy most capital equipment and implants through group purchasing contracts, while clinics, ambulatory surgical centers and home care providers buy monitors and lower-acuity procedure kits.
Heart medicines, standalone laboratory tests and software sold without hardware sit outside the scope of this analysis. The value chain runs from component and sensor suppliers through device makers to distributors, hospital purchasing groups and the cardiologists and surgeons who select products for each procedure.
Cardiovascular Devices Market Insights
- The cardiovascular devices market grows from USD 68.73 billion in 2025 to USD 131.73 billion by 2035, a 6.72% CAGR driven by catheter procedures and aging cardiac patients.
- North America held 40.0% of global cardiovascular device value in 2025, supported by high procedure density and established reimbursement for implants.
- Interventional cardiology led product types with 30.0% of 2025 value, while electrophysiology grows fastest at 9.46% a year.
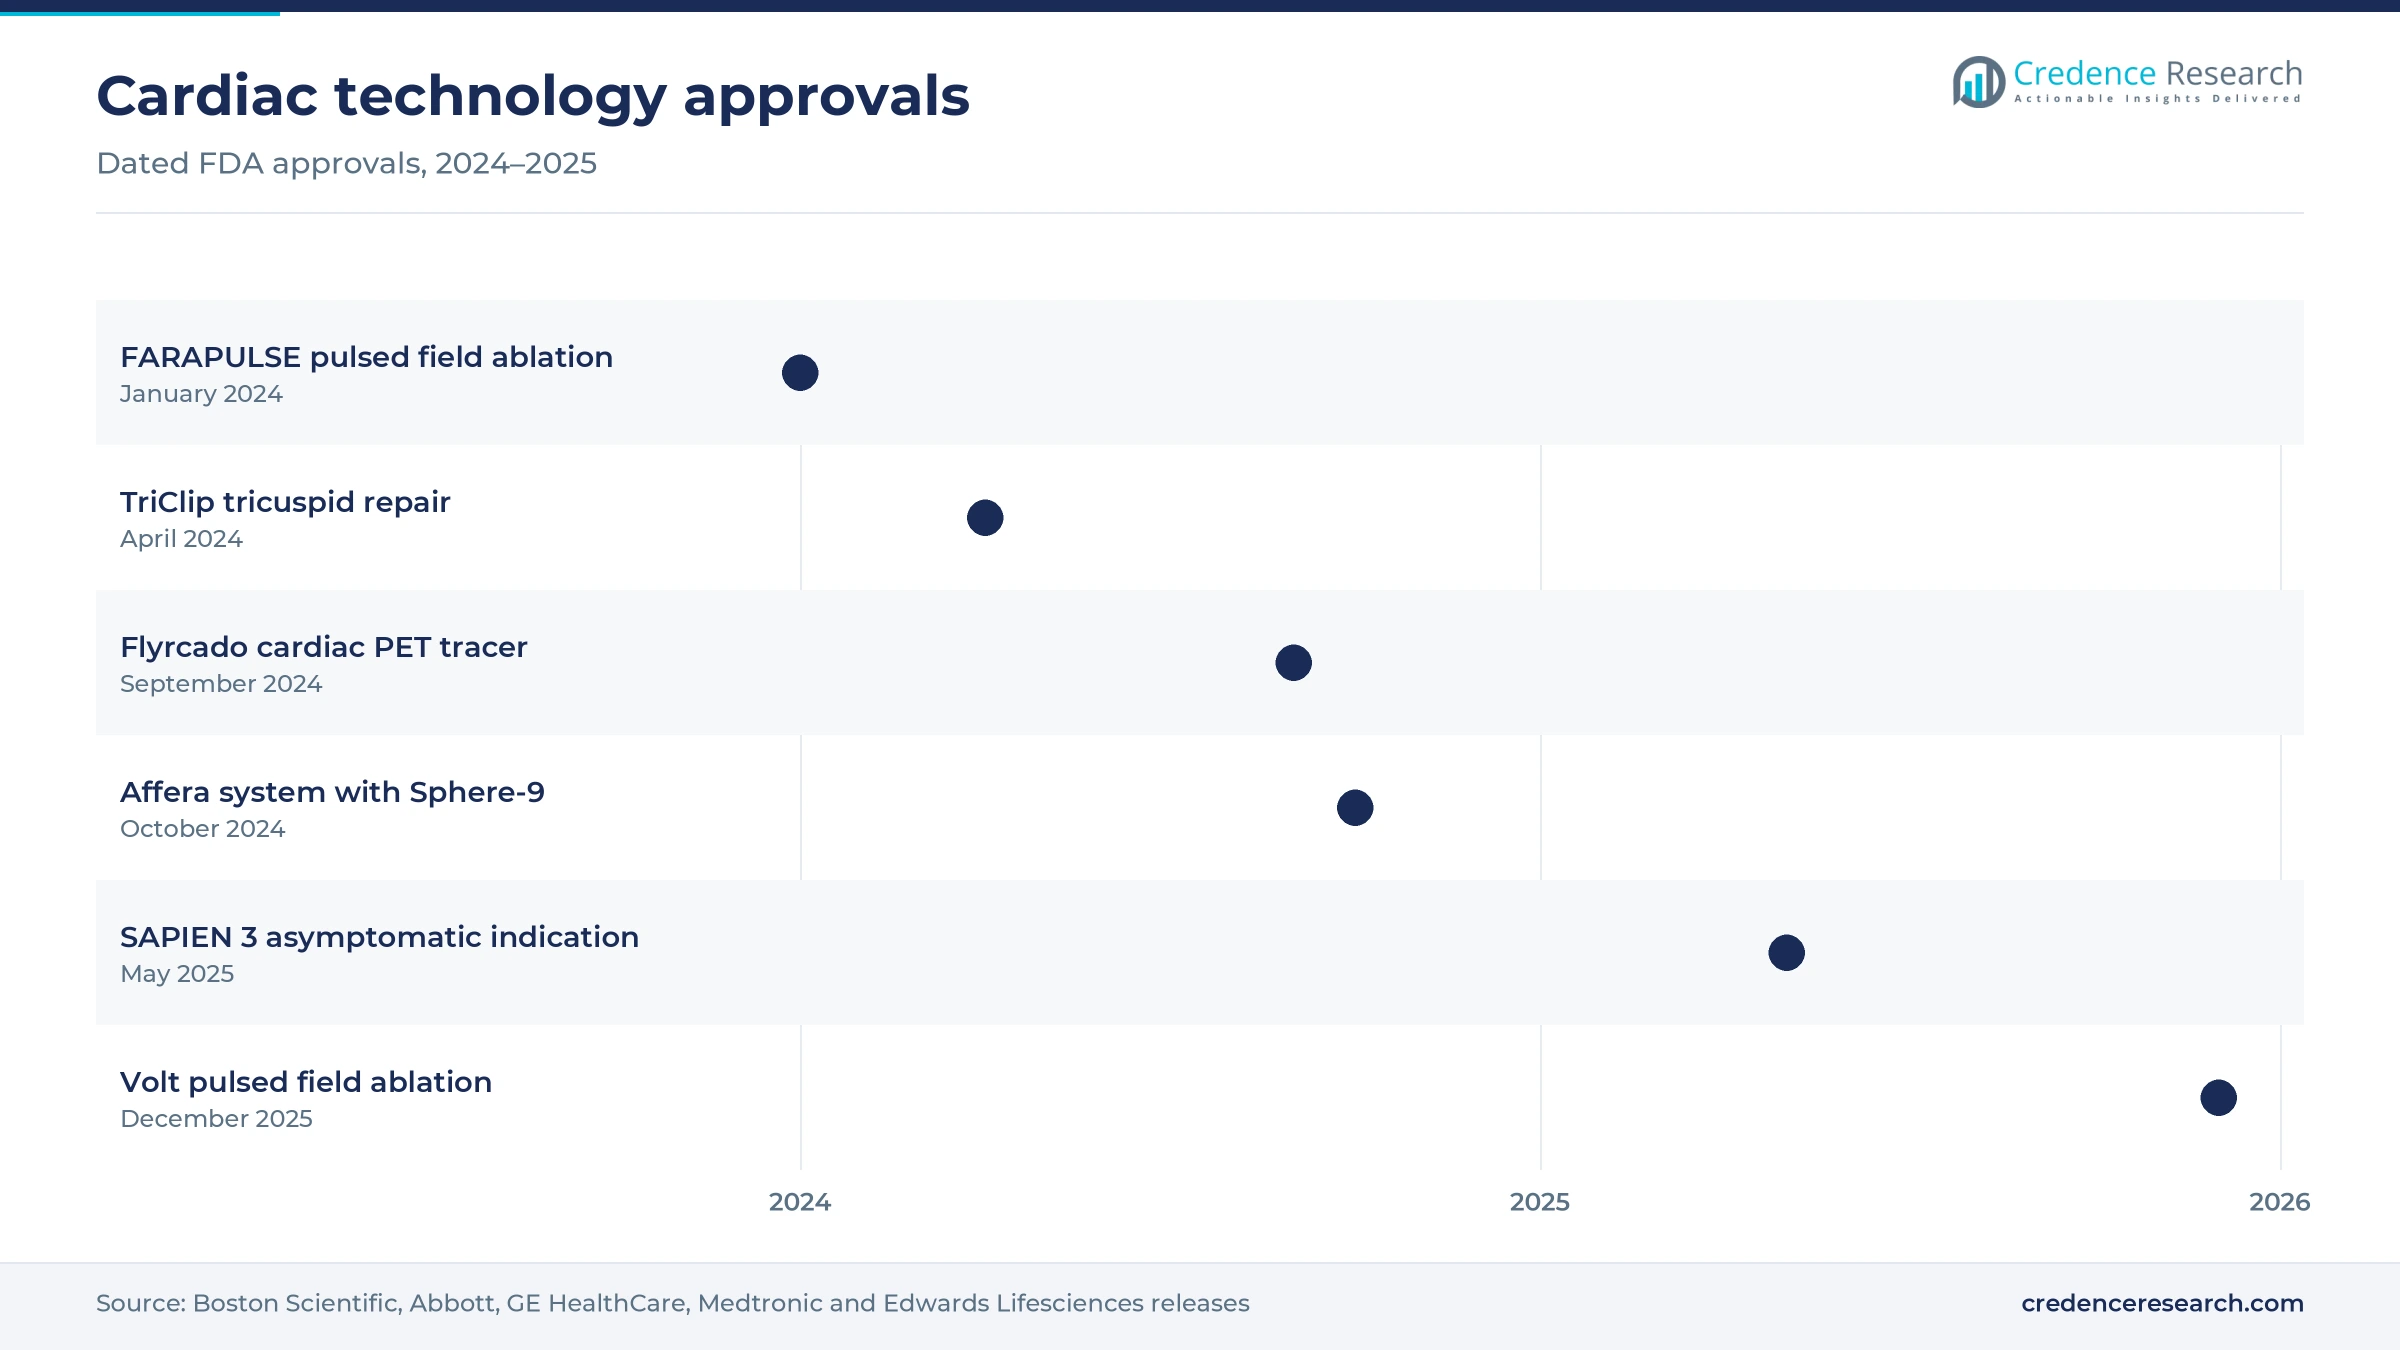
- In January 2024, Boston Scientific received FDA approval for its FARAPULSE pulsed field ablation system, opening a new energy class for atrial fibrillation care.
- Medtronic, Abbott and Boston Scientific each won U.S. approval for a pulsed field ablation platform between 2024 and 2025, which intensifies electrophysiology competition.
Interventional cardiology leads as ablation gains pace
Why does interventional cardiology still lead product spending?
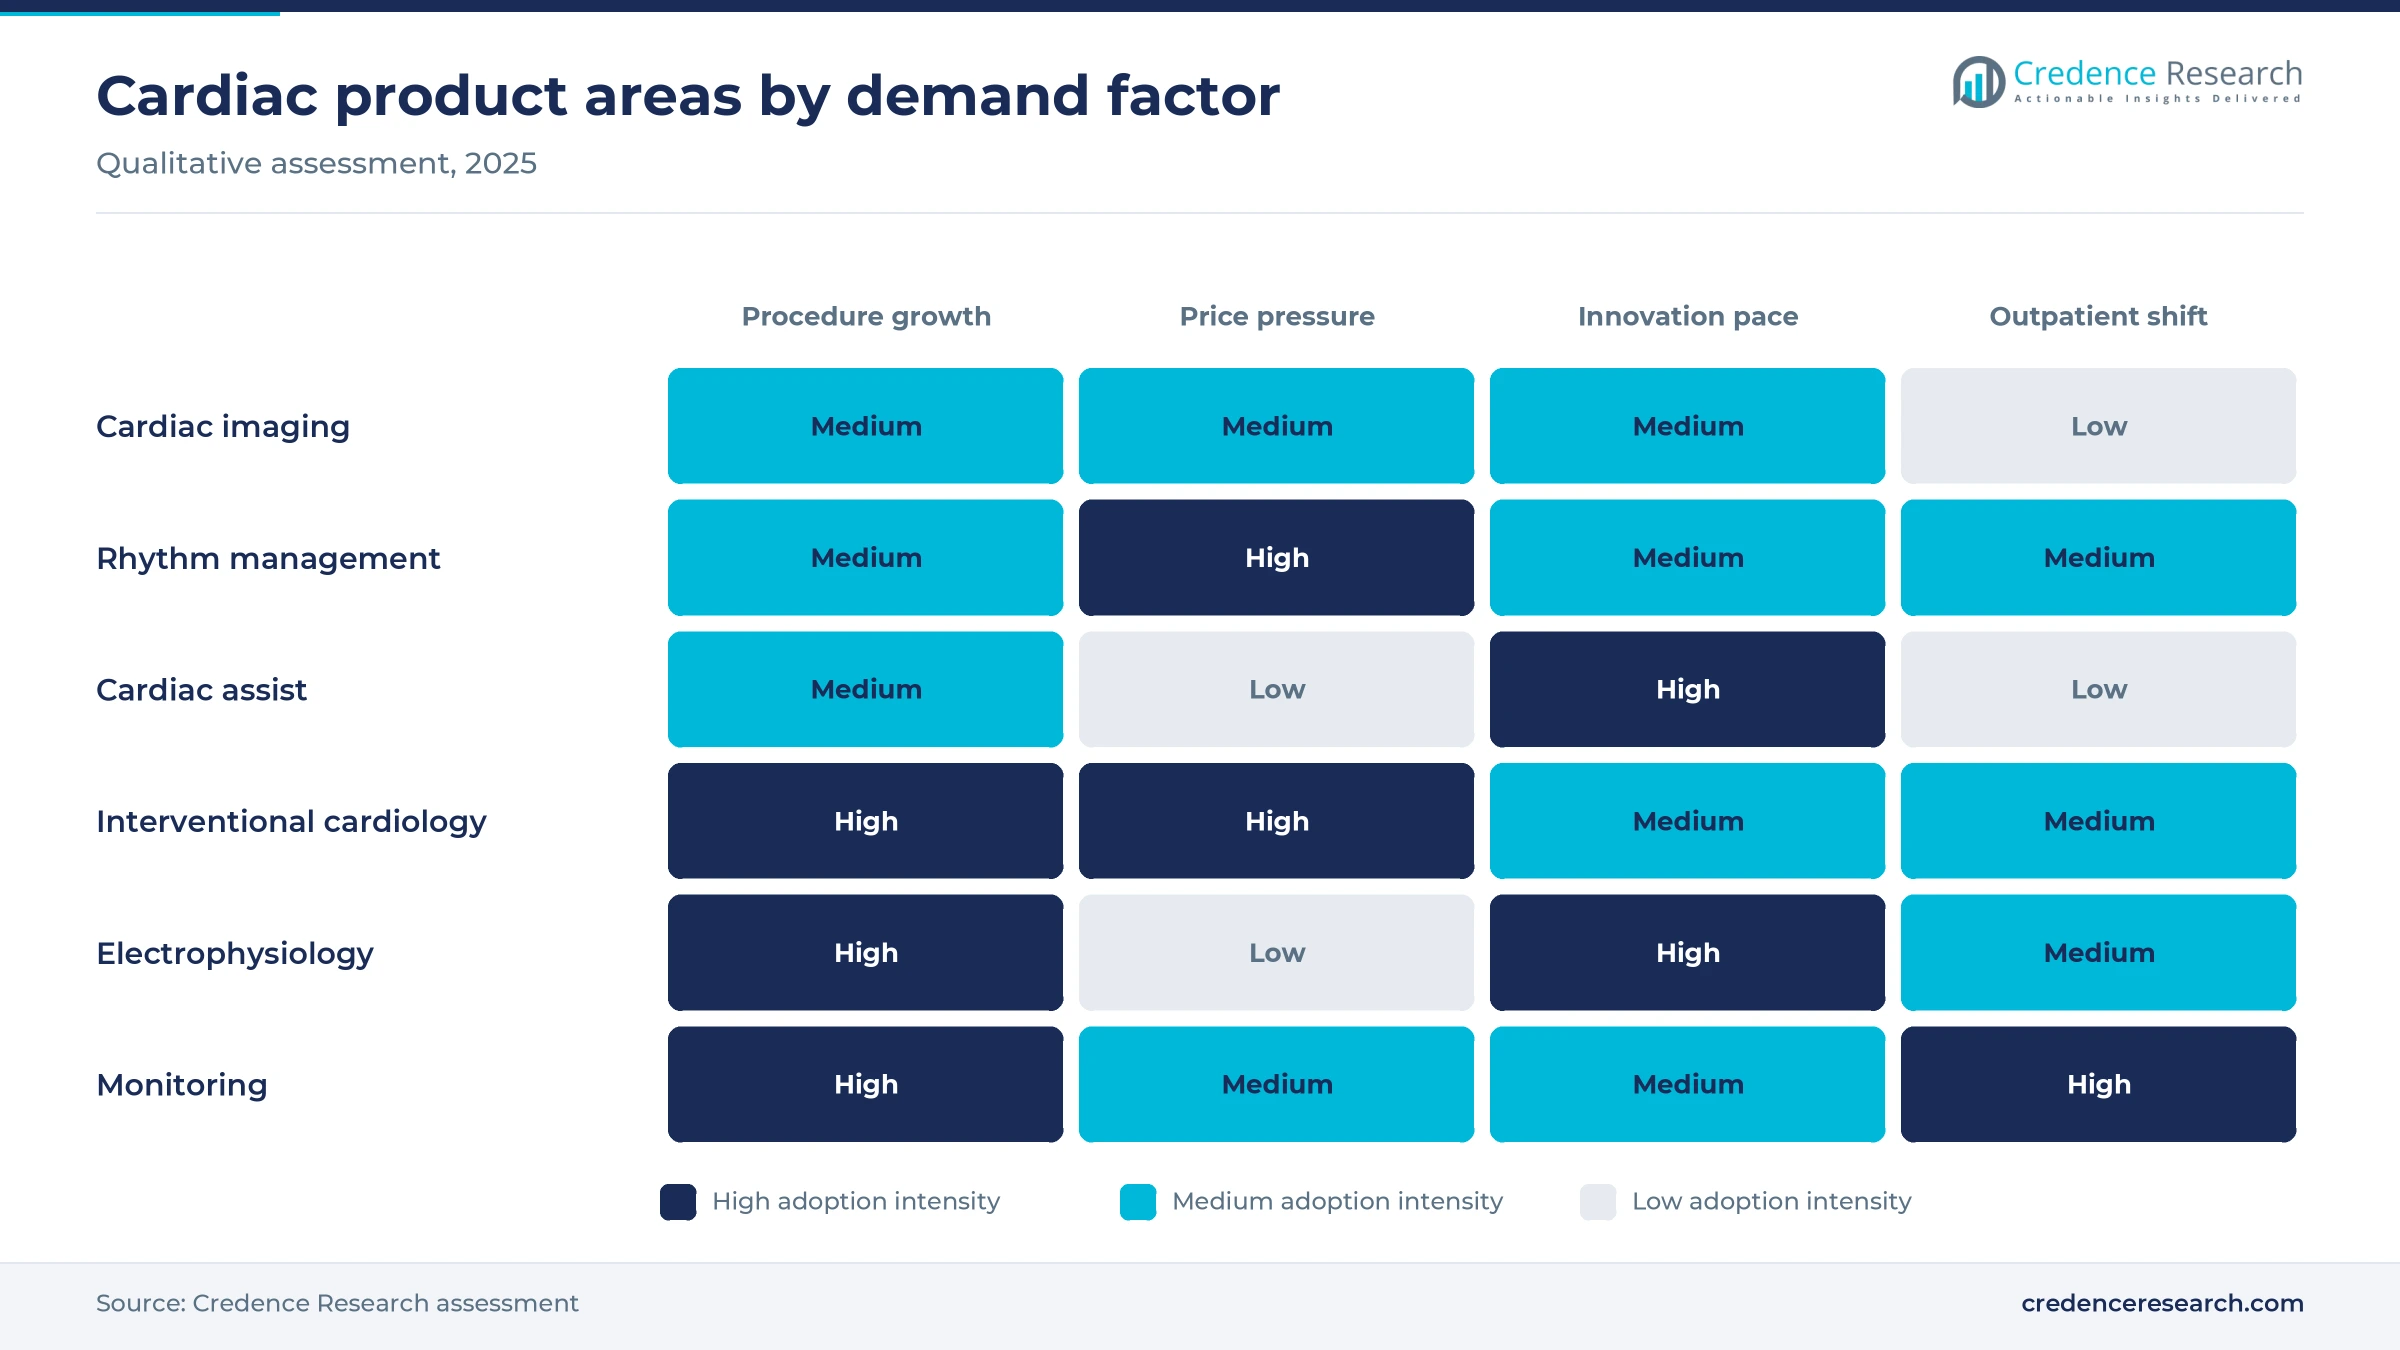
Based on product, the market is categorized into cardiac imaging, rhythm management, cardiac assist devices, interventional cardiology, electrophysiology and monitoring. Interventional Cardiology led with a 30.0% share of 2025 value, because coronary stents, balloons, guidewires and catheters are used in high volumes in every catheterization laboratory. Electrophysiology grows fastest at 9.46% a year, as pulsed field ablation systems widen treatment for atrial fibrillation. Rhythm management keeps a large base of implants that need periodic battery replacement.
Which care settings buy most cardiac technology?
Based on end user, the market is categorized into hospitals, home care settings, ambulatory surgical centers, research institutes and clinics. The Hospital segment led with a 62.0% share of 2025 value, because hospitals house the catheterization laboratories, hybrid operating rooms and intensive care units that complex procedures require. The Home Care Setting segment grows fastest at 8.42% a year, as wearable monitors and remote follow-up of implants move routine care into the home. Ambulatory surgical centers also gain volume as payers accept more outpatient cardiac procedures.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Interventional Cardiology | 30.0% | Electrophysiology | 9.46% |
| By End User | Hospital | 62.0% | Home Care Setting | 8.42% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Heart disease burden and aging patients lift procedures
How does the global burden of heart disease sustain demand?
Cardiovascular disease creates the core demand, because heart attacks, strokes, arrhythmias and valve disease all require diagnosis and often a device-based treatment. The World Health Organization estimates that 19.8 million people died from cardiovascular diseases in 2022, about 32% of all global deaths. Heart attack and stroke caused 85% of these deaths, and many survivors later need stents, monitors or implants. As a result, procedure volumes rise steadily with population growth and longer survival after a first cardiac event.
Why do aging patients widen the structural heart pool?
Aging populations widen the pool of structural heart patients, because aortic stenosis and leaky heart valves become far more common in later life. In May 2025, Edwards Lifesciences announced FDA approval of its SAPIEN 3 platform for severe aortic stenosis patients without symptoms, the first such approval for transcatheter aortic valve replacement. The decision rests on trial data showing better outcomes than watchful waiting. In turn, valve programs can treat patients earlier, which lifts implant volumes in North America first.
How is earlier atrial fibrillation treatment lifting ablation volumes?
Rising treatment of atrial fibrillation drives electrophysiology spending, because catheter ablation is now offered earlier instead of after years of drug therapy. In January 2024, Boston Scientific announced FDA approval of its FARAPULSE system, a pulsed field ablation platform that isolates the pulmonary veins with electrical pulses rather than heat or cold. Shorter procedures let electrophysiology laboratories treat more patients each day. As a result, hospitals are adding mapping systems, catheters and laboratory capacity across the United States and Europe.
Why does chronic disease monitoring add recurring demand?
Chronic disease monitoring adds recurring demand, because large populations with hypertension, heart failure and arrhythmia need regular tracking outside hospitals. The World Health Organization reported in September 2025 that 1.4 billion people lived with hypertension in 2024, and just over one in five had it under control. Wearable patches, implantable loop recorders and remote patient monitoring platforms help clinicians detect problems before patients need emergency care. In turn, home care settings become a growing buyer of cardiac monitoring equipment.
Pulsed field ablation and valve repair reshape demand
How is pulsed field ablation shifting electrophysiology?
Pulsed field ablation is replacing thermal energy as the preferred approach in many laboratories, because it targets heart tissue while sparing nearby structures. In October 2024, Medtronic announced FDA approval of its Affera mapping and ablation system with the Sphere-9 catheter, which combines high-density mapping with pulsed field and radiofrequency energy. Abbott followed in December 2025, when it announced that U.S. regulators had approved its Volt pulsed field ablation system for atrial fibrillation. As a result, competition now centers on catheter design and mapping integration.
Why is transcatheter repair rising beyond the aortic valve?
Catheter-based repair is spreading to the mitral and tricuspid valves, because many older patients are too frail for open-heart surgery. In April 2024, Abbott announced FDA approval of TriClip, a first-of-its-kind transcatheter edge-to-edge repair system for a leaky tricuspid valve. Structural heart programs that already perform aortic valve replacement can add these procedures with existing imaging and catheter skills. In turn, hospitals spend more on imaging guidance, delivery systems and dedicated heart team staff.
Can new imaging agents open a cardiac PET opportunity?
Cardiac imaging vendors have a clear opening in positron emission tomography, because PET perfusion scans can deliver higher diagnostic accuracy than the SPECT scans still used in most nuclear cardiology. In September 2024, GE HealthCare announced FDA approval of Flyrcado, a fluorine-18 radiotracer for diagnosing coronary artery disease. Its half-life is more than 10 times longer than other approved cardiac PET tracers, which makes exercise stress testing with PET practical. As a result, more hospitals and imaging centers could justify PET scanners for cardiology.
Where can device makers win share in emerging markets?
Device makers have room to grow in Asia, Latin America and the Middle East, where many hospitals are still opening their first catheterization laboratories. Patients in these regions often reach treatment late, so new laboratories quickly fill with coronary and rhythm cases. Companies that pair affordable products with physician training and service networks can build loyalty early. As a result, mid-priced platforms and refurbished imaging systems have strong prospects in these regions over the next decade.
Pricing, safety rules and staffing gaps slow uptake
Why does hospital price pressure limit value growth?
Price pressure is the main commercial constraint, because hospitals buy stents, catheters and implants through large tenders and group purchasing contracts. Volume-based procurement in China has cut prices for coronary stents and other high-use products, and similar tender models exist across Europe. Suppliers must therefore lower prices while keeping quality and service standards high. As a result, unit volumes can rise faster than market value, especially for mature products with many competing makers.
How do safety rules and recalls slow product launches?
Strict safety rules slow product launches, because implantable heart products carry high clinical risk and require extensive trial data. Approval of a new valve, ablation catheter or assist pump can take several years, and post-market surveillance continues after launch. Recalls of implants or leads can damage physician trust and lead hospitals to switch suppliers. In turn, smaller companies often need partners with large clinical and regulatory teams to bring new technologies to market.
Why do staffing gaps cap procedure capacity?
Shortages of trained staff limit how many procedures hospitals can perform, because electrophysiology and structural heart cases need specialized physicians, nurses and imaging technicians. Many regions outside large cities lack cardiologists who can perform catheter ablation or valve replacement. Training programs take years to expand, even when hospitals can afford new equipment. As a result, installed systems in some emerging markets run below capacity, which slows repeat purchases of catheters and implants.
How do capital costs and reimbursement gaps slow adoption?
High capital costs slow adoption of imaging systems, mapping platforms and hybrid operating rooms, because each installation requires a major hospital budget. Reimbursement for newer procedures often lags behind clinical evidence, which delays uptake in public health systems. Patients in low- and middle-income countries frequently pay out of pocket for implants such as pacemakers and heart valves. In turn, many eligible patients go untreated, and suppliers must offer financing or leasing models to win contracts.
North America leads as Asia Pacific builds cath labs
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 27.49 | 40.0% | 6.27% |
| Europe | 17.87 | 26.0% | 6.07% |
| Asia Pacific | 16.50 | 24.0% | 7.87% |
| Latin America | 4.12 | 6.0% | 7.17% |
| Middle East & Africa | 2.75 | 4.0% | 7.37% |
Why does North America hold the largest regional share?
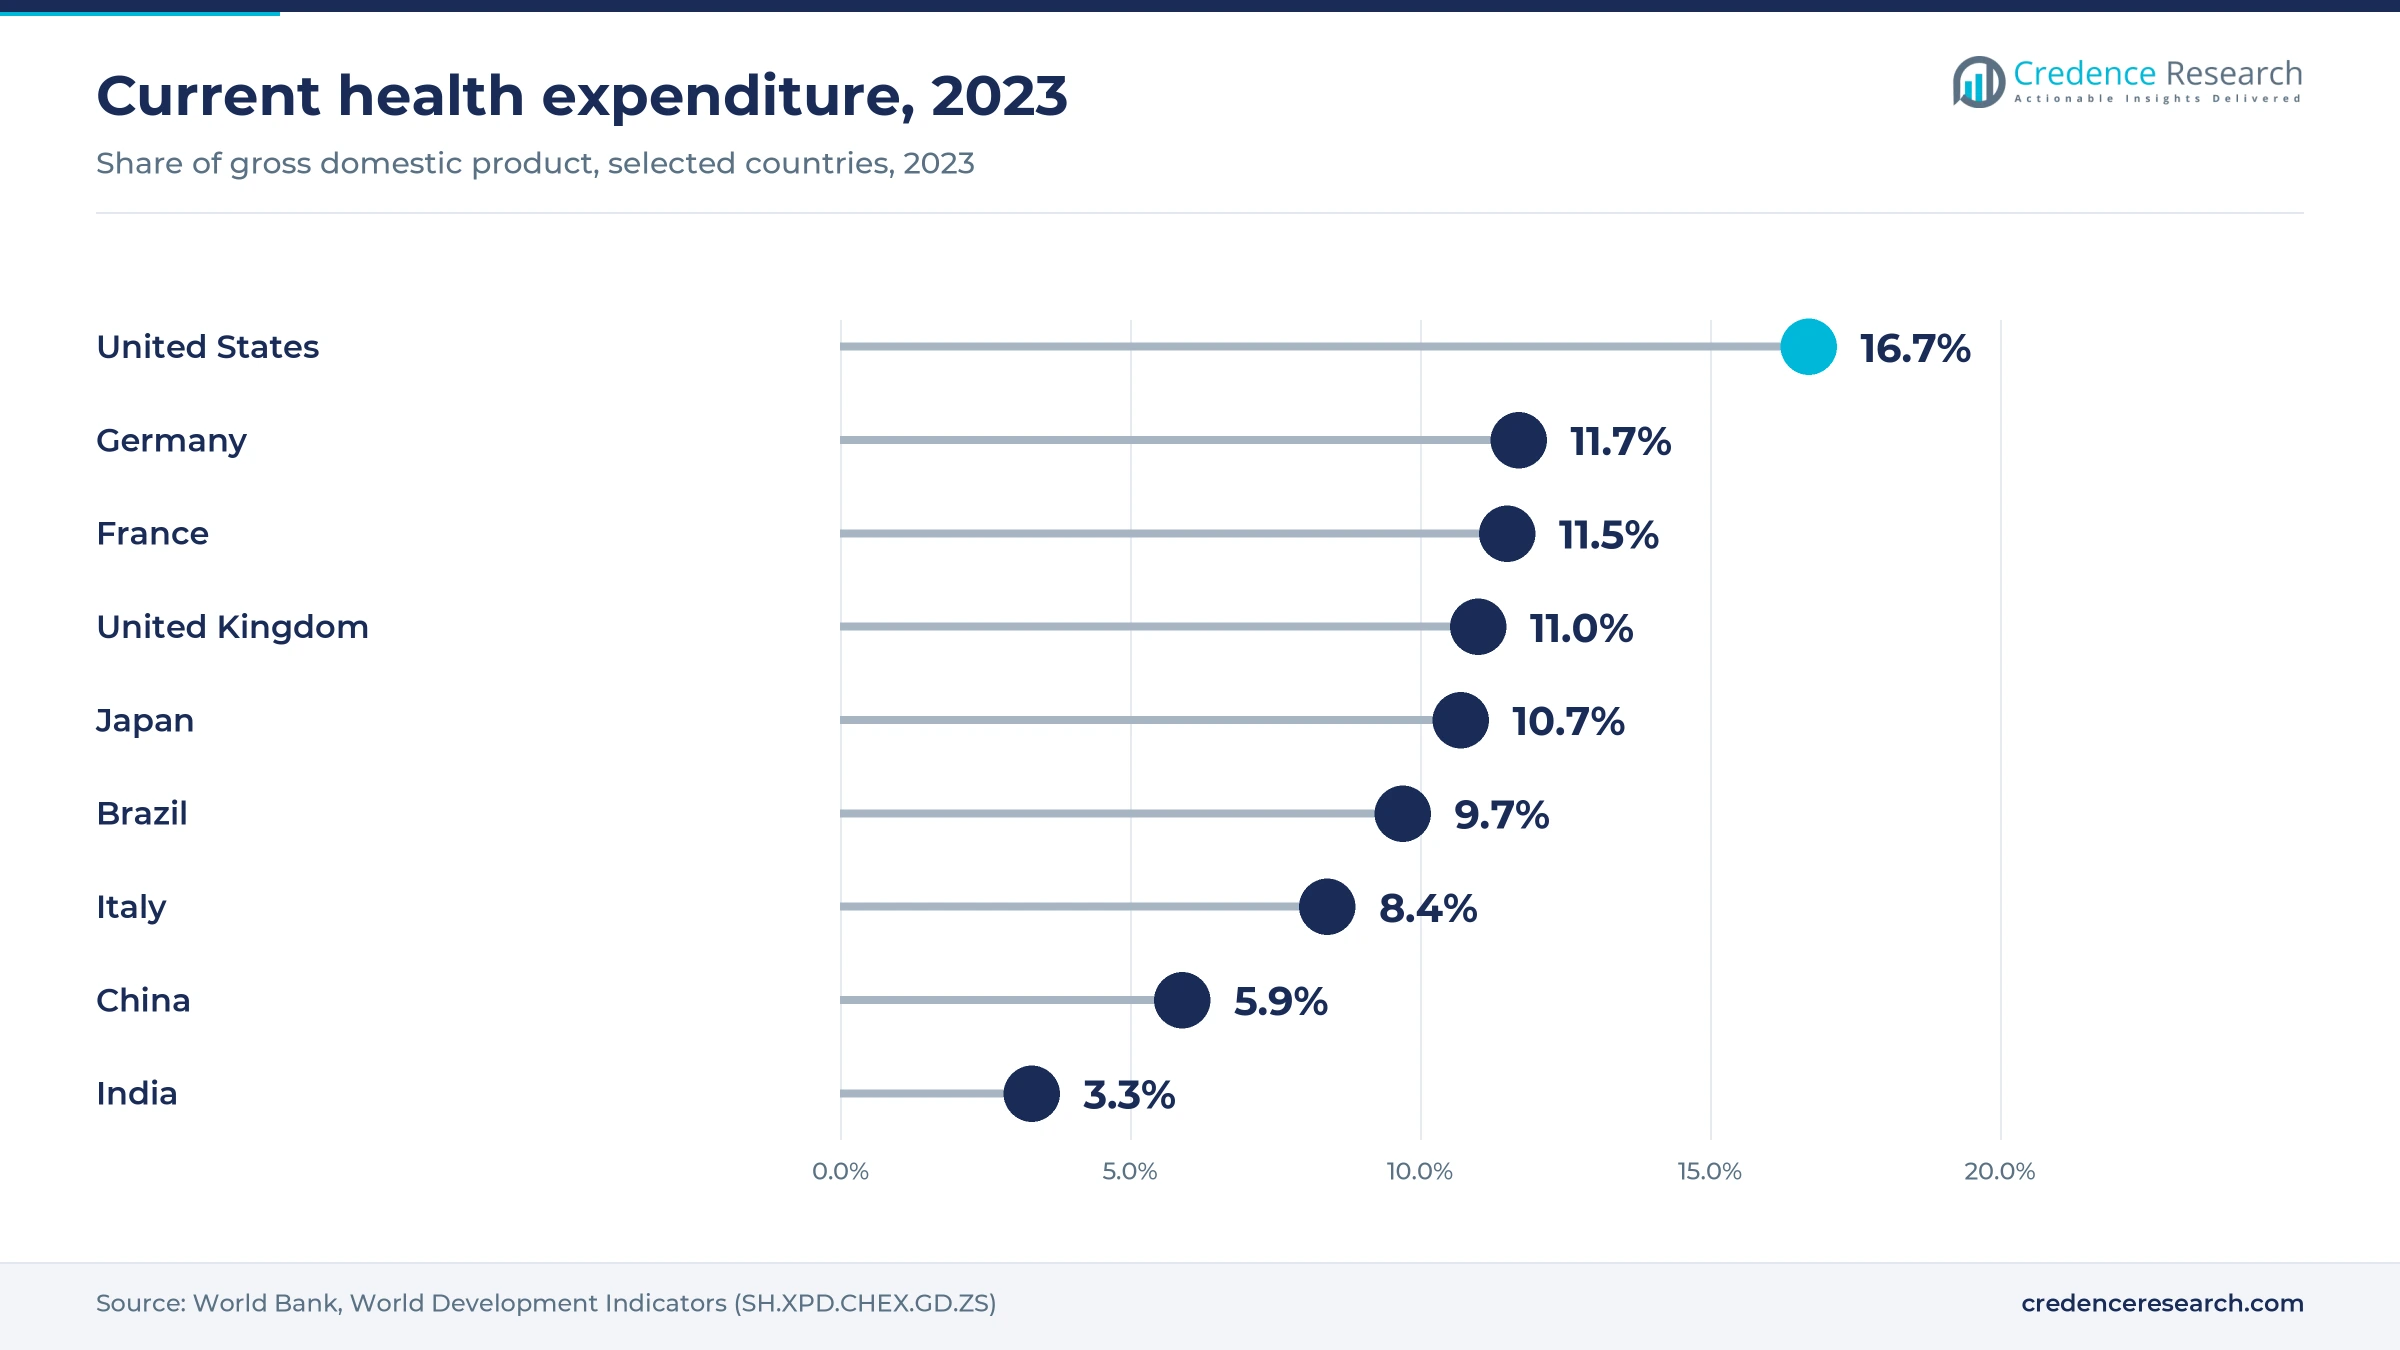
North America held a 40.0% share of 2025 value and grows at 6.27% a year through 2035. The United States drives this position, because hospitals there perform large volumes of ablation, valve replacement and coronary procedures. U.S. health spending reached 16.7% of gross domestic product in 2023, according to World Bank data, the highest among major economies, and 17.9% of U.S. residents were 65 or older in 2024. Regulators approved several new ablation and valve products between 2024 and 2025, which keeps premium technologies reaching this region first.
How fast is Asia Pacific adding cardiac capacity?
Asia Pacific held a 24.0% share of 2025 value and is the fastest-growing region at 7.87% a year. China, India and Southeast Asia are expanding catheterization laboratory capacity, which brings procedural treatment to patients who previously received medicines alone. Japan contributes high-value demand from an aging population, where people aged 65 and older made up 29.8% of residents in 2024 and health spending reached 10.7% of GDP in 2023. China spent 5.9% of GDP on health in 2023 and India 3.3%, which leaves wide room for investment in cardiac care. Local manufacturers in China and India compete strongly on stents and basic monitoring equipment.
What shapes demand across Europe?
Europe held a 26.0% share of 2025 value and grows at 6.07% a year, the slowest pace of the five regions. Germany, France, the United Kingdom and Italy account for most spending, and health spending equaled 11.7% of GDP in Germany, 11.5% in France and 11.0% in the United Kingdom in 2023. Tender-based purchasing and stricter rules under the European Medical Device Regulation hold back price growth and launch speed. However, aging populations keep demand for valves, implants and ablation steady, since people aged 65 and older made up 24.6% of Italy's population and 23.2% of Germany's in 2024.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 7.17% a year through 2035. Brazil and Mexico lead regional demand, and Brazil spent 9.7% of GDP on health in 2023, with private hospitals investing in catheterization laboratories and imaging systems. Public health systems buy stents and implants through tenders, which keeps prices low but supports steady volume.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 7.37% a year through 2035. Gulf states add higher-value demand from new cardiac centers that buy advanced imaging and structural heart products. Access in sub-Saharan Africa remains limited, because many countries have few catheterization laboratories outside major cities.
FDA approvals in ablation and valve therapy since 2024
| Development | Status and market relevance |
|---|---|
| In January 2024, Boston Scientific received FDA approval for the FARAPULSE pulsed field ablation system for atrial fibrillation. | On market; opened pulsed field ablation as a new energy class in U.S. electrophysiology laboratories |
| In October 2024, Medtronic received FDA approval for the Affera mapping and ablation system with the Sphere-9 catheter. | On market; combines high-density mapping with pulsed field and radiofrequency energy for persistent atrial fibrillation |
| In May 2025, Edwards Lifesciences received FDA approval for the SAPIEN 3 platform in asymptomatic severe aortic stenosis. | Approved; first transcatheter aortic valve indication for patients without symptoms |
| In July 2025, Boston Scientific received FDA approval to expand FARAPULSE labeling to drug refractory, symptomatic persistent atrial fibrillation. | Label expanded; widens the eligible pulsed field ablation population beyond paroxysmal atrial fibrillation |
| In December 2025, Abbott received FDA approval for the Volt pulsed field ablation system to treat atrial fibrillation. | Approved; adds a third major supplier to U.S. pulsed field ablation |
Energy sources, imaging agents and sensors lead innovation
- Pulsed field ablation uses short electrical pulses to isolate heart tissue, which reduces the risk of heat damage to nearby structures such as the esophagus.
- Transcatheter repair and replacement systems deliver valves and clips through blood vessels, which lets frail patients avoid open-heart surgery.
- Cardiac PET radiotracers such as flurpiridaz F 18 allow perfusion imaging with exercise stress, which supports diagnosis of coronary artery disease.
- Wearable and implantable monitors send heart rhythm data to clinicians remotely, which supports earlier detection of arrhythmias and implant problems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Diversified medtech leaders compete on full cardiac suites
Competition is led by diversified medical technology companies that sell across several cardiac product areas, from ablation catheters to valves and implants. Medtronic, Abbott and Boston Scientific Corporation compete directly in electrophysiology, where each now markets a pulsed field ablation system in the United States. Edwards Lifesciences Corporation focuses on transcatheter heart valves and structural heart repair, while W.L. Gore & Associates supplies vascular grafts, stent grafts and septal occluders used in cardiac and vascular procedures. GE HealthCare, Siemens Healthcare GmbH and Canon Medical Systems compete in cardiac imaging, including ultrasound, computed tomography and angiography systems. BIOTRONIK SE & Co. KG specializes in pacemakers, defibrillators and remote monitoring, and LivaNova PLC supplies cardiopulmonary equipment for heart surgery, while Cardinal Health and B. Braun SE add catheters, drug-coated balloons, consumables and hospital distribution services across many countries. As a result, buyers often favor suppliers that offer complete laboratory suites, training and service under a single contract.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Medtronic | Diversified | Rhythm management, Affera pulsed field ablation, transcatheter valves and coronary products |
| Abbott | Diversified | Structural heart repair including TriClip, Volt pulsed field ablation and rhythm management |
| Boston Scientific Corporation | Diversified | FARAPULSE pulsed field ablation, interventional cardiology and rhythm management |
| Edwards Lifesciences Corporation | Specialist | Transcatheter aortic valve replacement and structural heart repair |
| W. L. Gore & Associates, Inc. | Specialist | Vascular grafts, stent grafts and septal occluders |
| GE HealthCare | Imaging | Cardiac ultrasound, CT, angiography and the Flyrcado PET radiotracer |
| Siemens Healthcare GmbH | Imaging | Cardiac CT, MRI, angiography and ultrasound systems |
| Canon Medical Systems | Imaging | Cardiac CT, angiography and ultrasound systems |
| BIOTRONIK SE & Co. KG | Specialist | Pacemakers, defibrillators and remote monitoring |
| LivaNova PLC | Specialist | Heart-lung machines and cardiopulmonary products for cardiac surgery |
| B. Braun SE | Diversified | Catheters, drug-coated balloons and interventional consumables |
| Cardinal Health | Distribution | Hospital distribution of cardiology consumables and procedure supplies |
Electrophysiology and structural heart set the growth pace
Credence Research's view is that electrophysiology and structural heart products will set the pace of growth through 2035, because both replace drug therapy or open surgery with shorter catheter procedures. The overall market grows at 6.72% a year, supported by aging populations and higher procedure capacity in Asia Pacific. Imaging and monitoring keep large installed bases, but price pressure limits their value growth. Companies that combine strong clinical data with training, service and financing will win the most new laboratories, while single-product suppliers face pressure from bundled contracts.
How Credence Research sized cardiac device spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by product, end user and region. Regional and segment splits are Credence Research estimates informed by World Health Organization and World Bank statistics, U.S. regulator decisions and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Cardiac device spending outlook to 2035
By 2035, the cardiovascular devices market is projected to reach USD 131.73 billion, with growth led by electrophysiology, structural heart programs and home monitoring. Interventional cardiology will remain the largest product area, although price pressure will keep its value growth moderate. North America keeps the highest spending per patient, while Asia Pacific adds the most new laboratories and implant users. Outpatient and home settings will take a larger share of routine procedures and follow-up care. As a result, advantage will depend on clinical evidence, laboratory integration and service reach.
Frequently Asked Questions
How big is the global cardiovascular devices market?
Which product leads the cardiovascular devices market?
Which region leads cardiovascular device spending?
Which end user buys the most cardiac technology?
Why does pulsed field ablation matter for this market?
What recent approvals shaped structural heart demand?
Who are the leading cardiovascular device companies?
What restrains growth in cardiovascular devices?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Cardiac Imaging
- 1.2.2 Rhythm Management
- 1.2.3 Cardiac Assist Devices
- 1.2.4 Interventional Cardiology
- 1.2.5 Electrophysiology
- 1.2.6 Monitoring
- 1.3 By End User
- 1.3.1 Hospital
- 1.3.2 Home Care Setting
- 1.3.3 Ambulatory Surgical Centers
- 1.3.4 Research Institutes
- 1.3.5 Clinics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 68.73 billion → 2035: USD 131.73 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cardiovascular Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cardiovascular Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cardiovascular Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cardiovascular Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cardiovascular Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cardiovascular Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cardiovascular Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cardiovascular Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 68.73 billion → 2035: USD 131.73 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cardiovascular Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cardiac Imaging
- 12.3.7.2 Rhythm Management
- 12.3.7.3 Cardiac Assist Devices
- 12.3.7.4 Interventional Cardiology
- 12.3.7.5 Electrophysiology
- 12.3.7.6 Monitoring
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospital
- 12.4.7.2 Home Care Setting
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.7.4 Research Institutes
- 12.4.7.5 Clinics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cardiovascular Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cardiovascular Devices Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cardiovascular Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cardiovascular Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE HealthCare
- 18.4 Edwards Lifesciences Corporation
- 18.5 W. L. Gore & Associates, Inc.
- 18.6 Siemens Healthcare GmbH
- 18.7 BIOTRONIK SE & Co. KG
- 18.8 Canon Medical Systems
- 18.9 B. Braun SE
- 18.10 LivaNova PLC
- 18.11 Cardinal Health
- 18.12 Medtronic
- 18.13 Boston Scientific Corporation
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

