
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
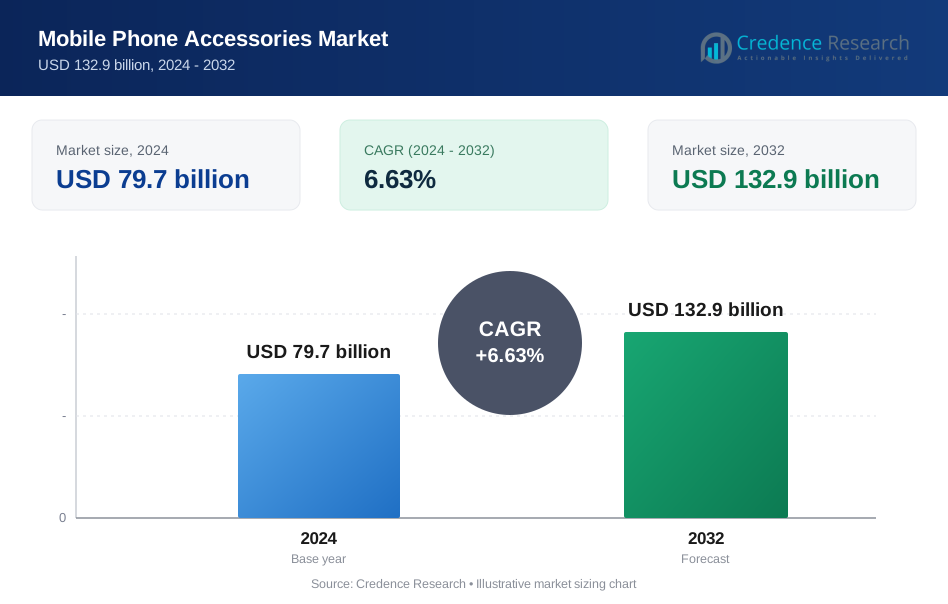
| Mobile Phone Accessories Market Size 2024 | USD 79.7 billion |
| Mobile Phone Accessories Market CAGR | 6.63% |
| Mobile Phone Accessories Market Size 2032 | USD 132.9 billion |
Market Overview
The Mobile Phone Accessories market size was valued at USD 54.6 billion in 2018 and USD 79.7 billion in 2024, and is anticipated to reach USD 132.9 billion by 2032, at a CAGR of 6.63% during the forecast period. The Mobile Phone Accessories market is characterized by strong competition among top players such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Inc., Anker Innovations Limited, Logitech International S.A., Aukey Technology Co., Ltd., RAVPower, Mophie, OtterBox, and Case-Mate. These companies maintain their leadership through robust product portfolios, continuous innovation, and expansive global distribution networks. Asia Pacific leads the market with a 35.6% share, driven by high smartphone adoption and large consumer bases in countries like China and India. North America and Europe follow, with market shares of 15.4% and 18.7% respectively, supported by premium product demand and advanced retail infrastructure.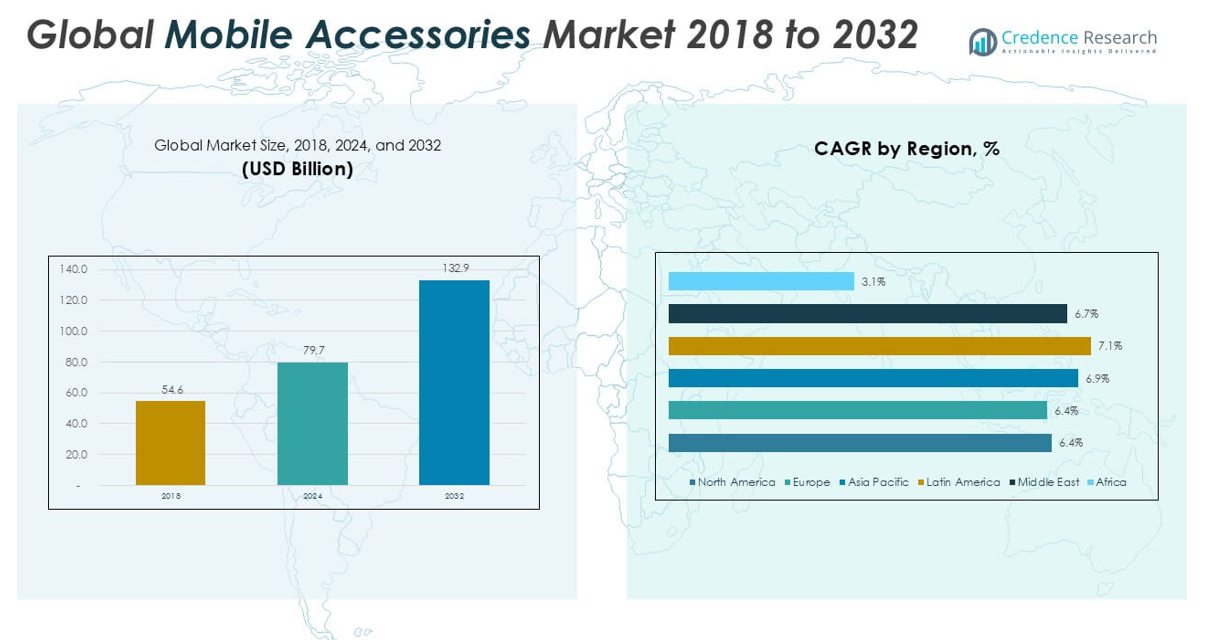
Market Insights
- The Mobile Phone Accessories market reached USD 79.7 billion in 2024 and is projected to achieve USD 132.9 billion by 2032, registering a CAGR of 6.63% during the forecast period.
- Rising global smartphone adoption, increasing demand for protective and functional accessories, and frequent device upgrades continue to drive robust market growth across all regions.
- Key trends include the shift toward wireless and smart accessories, rapid innovation in fast-charging and eco-friendly products, and growing consumer preference for customization and premium quality.
- The market is highly competitive, led by major players such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Anker Innovations Limited, Logitech, and others, with Asia Pacific holding a dominant 35.6% regional share and mobile cases being the leading product segment.
Market Segmentation Analysis:
By Product Type: Mobile cases represent the largest share within the product type segment, primarily driven by the consistent demand for device protection and personalization. Rugged and designer cases dominate this space, appealing to a wide spectrum of consumers who value both durability and style. Chargers account for a substantial share of the Mobile Phone Accessories market, with fast-charging and wireless chargers emerging as the leading sub-segments. Consumer preference for efficient and quick power solutions drives this segment, especially as device usage intensifies. Mobile earphones & chargers form a robust segment, where true wireless earbuds command the highest market share. The battery segment captures a notable portion of the market, with replacement batteries and extended-life options leading the way. Consumers are replacing batteries more frequently due to increased mobile usage for gaming, streaming, and business. Power banks have become an indispensable accessory, especially among travelers and professionals requiring uninterrupted connectivity.- For instance, Xiaomi’s Mi Power Bank 3 Ultra Compact provides a capacity of 10,000 mAh and supports up to three devices simultaneously with its dual USB-A and single USB-C ports.
- For instance, Caterpillar’s Cat S62 Pro smartphone is designed for tough environments, meeting MIL-STD-810H standards for drop resistance up to 1.8 meters onto steel.
Market Overview
Rising Smartphone Penetration Growing global smartphone adoption drives robust demand for Mobile Phone Accessories. As emerging economies witness higher smartphone ownership, the need for protective cases, chargers, earphones, and power banks continues to rise. Consumers are increasingly seeking products that enhance device functionality, comfort, and longevity, which directly fuels market expansion. The proliferation of affordable smartphones in both urban and rural markets ensures sustained growth for the accessory ecosystem across diverse user demographics.- For instance, Samsung shipped 272 million smartphones worldwide in 2022, supporting increased demand for corresponding accessories.
- or instance, Belkin’s BOOST↑CHARGE PRO 3-in-1 Wireless Charger with MagSafe delivers up to 15 watts of wireless power for iPhone 12 and later, enabling simultaneous charging for iPhone, Apple Watch, and AirPods.
Key Trends & Opportunities
Shift Toward Wireless and Smart Accessories Consumer preference is shifting toward wireless and smart accessories, such as Bluetooth earphones, wireless chargers, and smart wearables. The convenience of untethered devices and integration with IoT ecosystems appeal to tech-focused users. This trend creates opportunities for manufacturers to introduce innovative products that address seamless connectivity, portability, and multi-device compatibility, expanding their footprint among early adopters and lifestyle-driven buyers.- For instance, Apple’s AirPods Max are equipped with custom-built 40-mm dynamic drivers and nine microphones, offering high-fidelity audio and adaptive noise cancellation, while seamlessly connecting across Apple devices using the H1 chip.
Key Challenges
Intense Market Competition and Price Pressure The Mobile Phone Accessories market faces intense competition, particularly from low-cost manufacturers and unbranded products. This environment puts pressure on established brands to differentiate through quality, innovation, and marketing. Price wars can erode profit margins, making it challenging for premium brands to maintain market share while balancing affordability and profitability. Counterfeit and Low-quality Products The prevalence of counterfeit and substandard products poses a significant challenge to the market. Fake accessories often fail to meet safety and performance standards, undermining consumer trust and damaging brand reputations. Regulatory oversight and consumer education are required to combat this issue and ensure the market’s healthy, sustainable growth. Rapid Technological Change Frequent advances in mobile device technology can render certain accessories obsolete. Manufacturers must invest continuously in research and development to stay ahead of changing compatibility requirements and evolving consumer preferences. Failure to adapt quickly risks inventory obsolescence and loss of relevance in a highly dynamic market.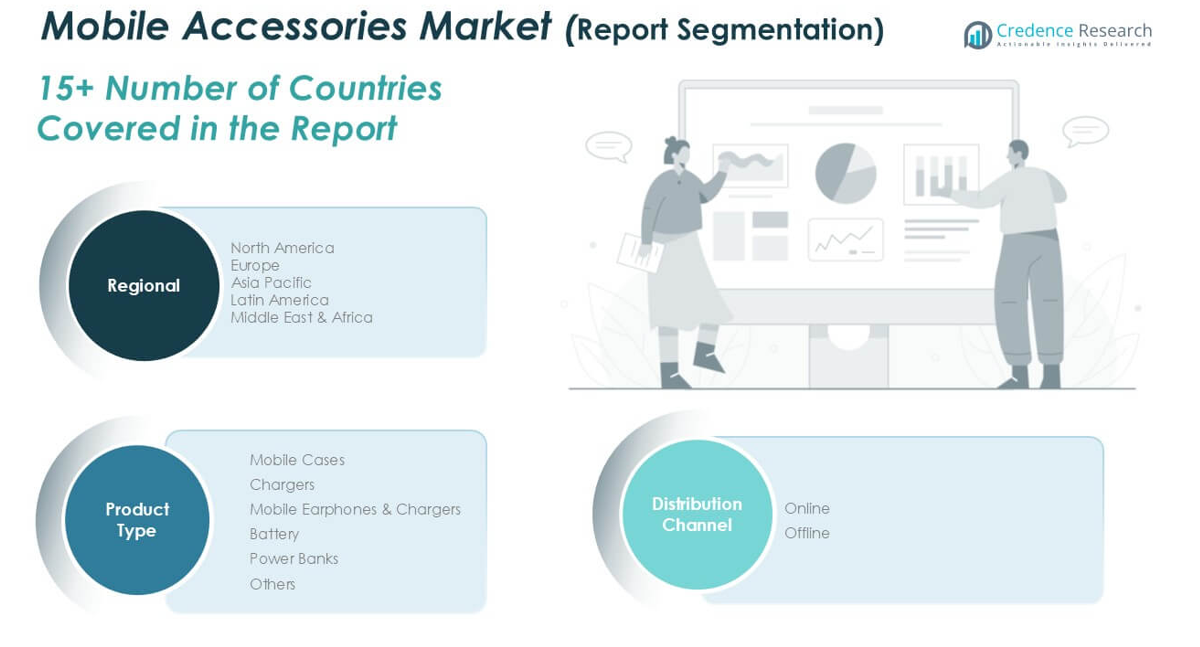
Regional Analysis
North America North America accounted for USD 10.25 billion in 2018, rising to USD 14.81 billion in 2024, and is projected to reach USD 24.36 billion by 2032, with a CAGR of 6.4%. The region commands an estimated 15.4% market share in 2024, supported by strong smartphone adoption, frequent device upgrades, and high consumer spending on premium accessories. Technological advancements and widespread e-commerce channels further drive market growth. Early adoption of wireless charging and smart wearables reinforces North America’s role as a key revenue contributor in the global Mobile Phone Accessories market. Europe Europe reached a value of USD 12.49 billion in 2018, which grew to USD 17.96 billion in 2024 and is forecast to reach USD 29.36 billion by 2032, reflecting a CAGR of 6.4%. Holding a 18.7% share in 2024, Europe’s market is propelled by growing demand for stylish, functional accessories and the trend toward sustainability. Regulatory emphasis on product quality and safety boosts consumer trust. Robust retail networks and rapid uptake of new technologies ensure Europe remains a critical market for mobile accessory manufacturers. Asia Pacific Asia Pacific leads the global Mobile Phone Accessories market, valued at USD 22.68 billion in 2018, USD 33.60 billion in 2024, and expected to hit USD 57.13 billion by 2032, at a CAGR of 6.9%. Representing 35.6% of the market in 2024, the region benefits from surging smartphone penetration, population growth, and affordable device options. China and India are primary demand centers, fueled by price sensitivity and tech-savvy consumers. Expanding online retail and continuous innovation reinforce Asia Pacific’s dominant position. Latin America Latin America recorded USD 3.39 billion in 2018, increasing to USD 5.08 billion in 2024, and is projected to reach USD 8.78 billion by 2032, registering the highest CAGR at 7.1%. The region holds a 5.4% share in 2024, driven by expanding smartphone access and a youthful population. Market growth is supported by increasing internet connectivity, rising disposable incomes, and strong demand for affordable accessories. Local manufacturing and growing online distribution further fuel Latin America’s Mobile Phone Accessories sector. Middle East The Middle East market reached USD 4.67 billion in 2018, expanded to USD 6.85 billion in 2024, and is estimated to achieve USD 11.48 billion by 2032, with a CAGR of 6.7%. Capturing a 7.2% share in 2024, the market benefits from rising urbanization, increased smartphone usage, and a growing preference for high-quality accessories. Regional investments in digital infrastructure and a vibrant retail environment support further expansion, while consumer interest in premium products strengthens the market outlook. Africa Africa’s market grew from USD 1.09 billion in 2018 to USD 1.36 billion in 2024 and is forecast at USD 1.74 billion by 2032, with a CAGR of 3.1%. The region holds a modest 1.4% market share in 2024, limited by lower smartphone penetration and economic challenges. However, ongoing efforts to improve digital access and the popularity of low-cost accessories are gradually increasing demand. Urban centers show faster growth, supported by expanding retail networks and the adoption of entry-level smartphones across key African marketsMarket Segmentations:
By Product Type- Mobile Cases
- Chargers
- Mobile Earphones & Chargers
- Battery
- Power Banks
- Others
- Construction
- Bricks and Blocks
- Road Construction
- Portland Cement and Concrete
- Agriculture
- Mining
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Mobile Phone Accessories market features a mix of global technology leaders, specialized accessory manufacturers, and innovative new entrants. Major players such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Inc., and Anker Innovations Limited dominate through strong brand recognition, extensive product portfolios, and continuous innovation in design and functionality. Companies like Logitech International S.A., Aukey Technology Co., Ltd., RAVPower, Mophie, OtterBox, and Case-Mate further intensify market competition by targeting niche segments and delivering specialized solutions such as rugged cases, advanced power banks, and wireless charging devices. These key players leverage wide distribution channels, strategic collaborations, and frequent product launches to maintain their competitive edge. The market also sees increasing competition from regional brands and low-cost manufacturers, which challenge established players on pricing and local relevance. Continuous investment in research, sustainable materials, and technology integration remains vital for sustaining market leadership.Key Player Analysis
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Belkin International, Inc.
- Anker Innovations Limited
- Logitech International S.A.
- Aukey Technology Co., Ltd.
- RAVPower
- Mophie
- OtterBox
- Case-Mate
Recent Developments
- In March 2024, Apple has launched a new mobile phone case, watch band and iPhone camera mount accessories which will be available in pastel colors.
- In September 2024, Belkin, a leading consumer electronics brand for over 40 years, announced 11 new travel-ready products across its mobile charging category, as well as solutions to enable more flexible options to work while on the go.
- In July 2024, Samsung's accessory brand, Samsung Friends, is preparing to launch a number of new cases and add-ons for its latest mobile devices, including the Galaxy Buds 3 series, Galaxy Watches, and Galaxy Z Fold 6 and Z Flip 6 foldable phones.
- In September 2023, Samsung electronics co have launched a new Samsung eco friends accessories lineup which have made accessories from recycling materials.
- In April 2022, Samsung Electronics Co., Ltd. announced a partnership with plant-based designer Sean Wotherspoon to launch an eco-friendly smartphone case and watch accessories. The device accessories are all sourced sustainably using 100% recycled materials, also all the cases and watch bands are biodegradable.
Market Concentration & Characteristics
The Mobile Phone Accessories Market displays moderate to high market concentration, with a few global leaders holding significant market share and a broad base of regional and local players operating in competitive niches. It is characterized by constant innovation, fast-paced product life cycles, and high consumer sensitivity to trends, design, and technology integration. Leading companies such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, and Anker Innovations Limited shape product standards and set pricing benchmarks, while emerging brands compete on affordability and specialized features. The market benefits from strong brand loyalty and extensive distribution networks, particularly in Asia Pacific, North America, and Europe. It exhibits a clear segmentation by product type, with mobile cases and chargers commanding the largest shares, and a growing emphasis on wireless, eco-friendly, and smart accessory categories. Intense competition, rapid technological changes, and consumer demand for both quality and affordability define its key characteristics, keeping the market dynamic and highly responsive.Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- Anticipated acceleration in wireless charging and true wireless audio accessory adoption
- Continued expansion of sustainable and recycled-material products
- Growth of smart accessories integrating IoT features and health monitoring
- Rising customization demand for personalized cases and skins
- Increased focus on fast-charging capabilities and high-capacity power banks
- Expansion of accessory ecosystems tied to foldable and 5G devices
- E-commerce dominance powering direct-to-consumer accessory sales
- Emerging regional penetration in Asia Pacific and Latin America markets
- Ongoing consolidation and partnerships among major brands to innovate
- Strengthening of quality and safety standards to counter counterfeit products
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mobile Phone Accessories Market?
What are the key segments within the Mobile Phone Accessories Market?
What are some challenges faced by the Mobile Phone Accessories Market?
Who are the major players in the Mobile Phone Accessories Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mobile Phone Accessories Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mobile Phone Accessories Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 79.7 billion → 2032: USD 132.9 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mobile Phone Accessories Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mobile Phone Accessories Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mobile Phone Accessories Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mobile Phone Accessories Market Drivers
- 3.3 Mobile Phone Accessories Market Restraints & Challenges
- 3.4 Mobile Phone Accessories Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mobile Phone Accessories Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mobile Phone Accessories Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mobile Phone Accessories category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mobile Phone Accessories Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Mobile Phone Accessories Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Mobile Phone Accessories. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mobile Phone Accessories Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mobile Phone Accessories Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Mobile Phone Accessories Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mobile Phone Accessories (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Mobile Phone Accessories
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mobile Phone Accessories Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Mobile Phone Accessories Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mobile Phone Accessories Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mobile Phone Accessories Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mobile Phone Accessories Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mobile Phone Accessories Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mobile Phone Accessories Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mobile Phone Accessories Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
