
Market Overview:
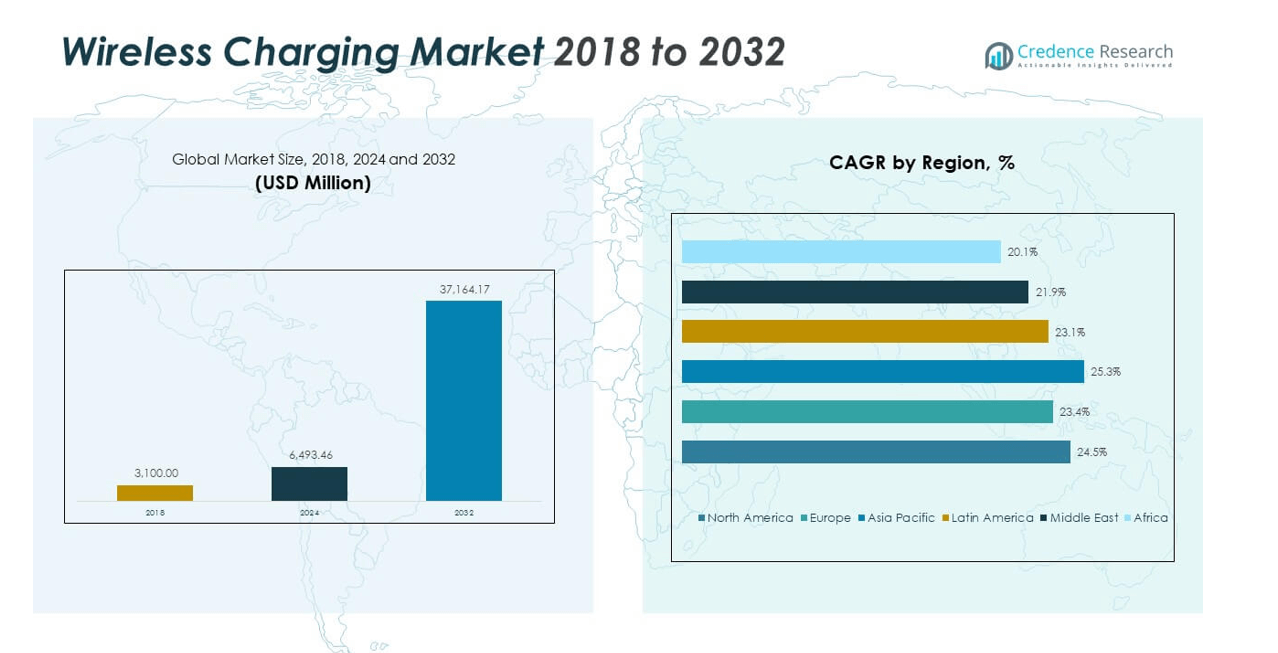
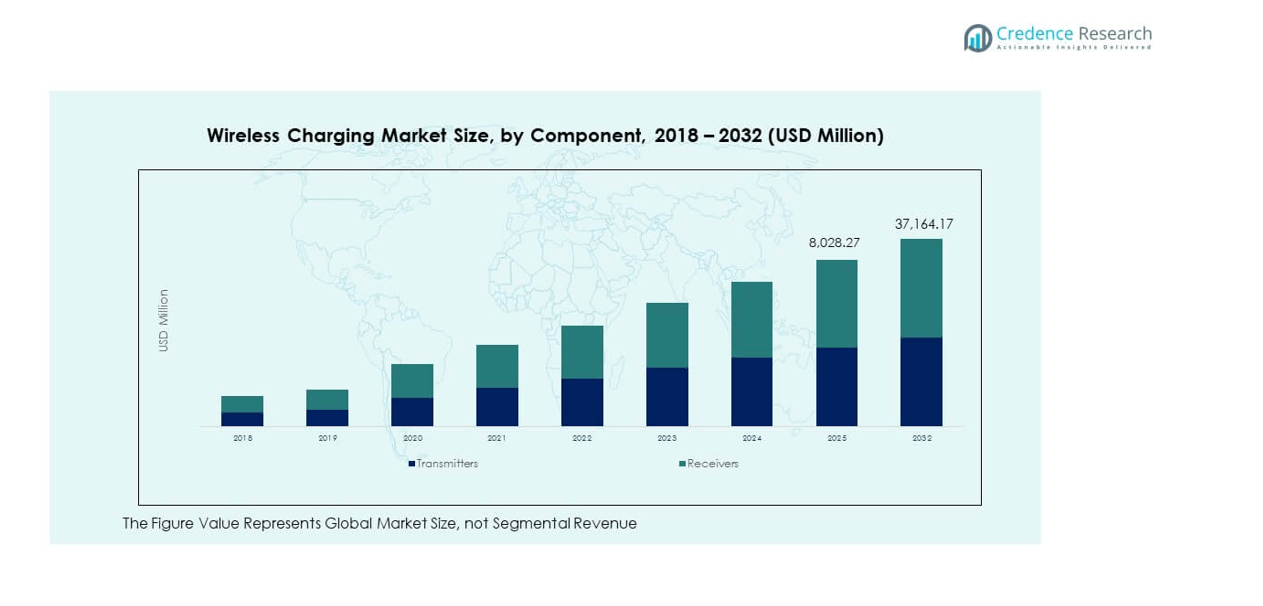
The Wireless Charging Market size was valued at USD 3,100.00 million in 2018 to USD 6,493.46 million in 2024 and is anticipated to reach USD 37,164.17 million by 2032, at a CAGR of 24.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wireless Charging Market Size 2024 | USD 6,493.46 million |
| Wireless Charging Market, CAGR | 24.47% |
| Wireless Charging Market Size 2032 | USD 37,164.17 million |
Rising use of smartphones, wearables, and electric vehicles drives strong demand for wireless charging systems. Manufacturers invest in R&D to enhance energy transfer speed, safety, and multi-device compatibility. Growing awareness of sustainable energy and convenience-based technology supports adoption across households and commercial sectors. Partnerships among electronics producers and automakers continue to expand market applications. The emergence of standardization protocols ensures interoperability and boosts consumer confidence globally.
North America leads the market with strong adoption across consumer electronics and EV applications, supported by robust R&D investments. Europe follows with significant expansion in sustainable transport and industrial automation. Asia Pacific emerges as the fastest-growing region driven by high smartphone production, technological innovation, and manufacturing capacity in China, Japan, and South Korea. Latin America, the Middle East, and Africa are developing markets showing steady progress through expanding digital infrastructure and government-backed modernization initiatives.
Market Insights:
- The Wireless Charging Market was valued at USD 3,100.00 million in 2018, reached USD 6,493.46 million in 2024, and is projected to attain USD 37,164.17 million by 2032, registering a CAGR of 24.47% during the forecast period.
- Asia Pacific dominates the global market with a 47.9% share, driven by extensive smartphone production, rapid technology adoption, and strong manufacturing bases in China, Japan, and South Korea.
- North America holds a 24.9% share due to widespread EV usage and high R&D investments, while Europe follows with a 19.0% share, supported by sustainability goals and automotive innovation.
- Asia Pacific stands as the fastest-growing region, propelled by growing demand for efficient wireless solutions, expansion of EV infrastructure, and rising consumer electronics penetration.
- In component distribution, transmitters account for roughly 45% of total revenue, while receivers represent around 55%, reflecting increasing device integration and broader end-user adoption across industries.
Market Drivers
Rising Demand for Consumer Electronics and Smart Devices
The increasing use of smartphones, wearables, and tablets drives strong demand for wireless charging solutions. Manufacturers focus on integrating advanced charging pads and docks into consumer devices. The Wireless Charging Market benefits from the global shift toward convenience-based power transfer technologies. Consumers prefer cable-free and clutter-free charging experiences. It supports a seamless connection between smart devices, reducing reliance on traditional cords. The rise in multi-device households increases product adoption. Major smartphone brands are embedding wireless charging compatibility across new models. Continuous innovation in consumer electronics is strengthening market penetration.
- For instance, Apple’s MagSafe charger, released for the iPhone 16 series in October 2024, provides up to 25W wireless charging when paired with a 30W power adapter, achieving a 46% battery charge in 30 minutes on the iPhone 16 Pro and showing at least 10–18% faster speed compared to leading Qi2 products.
Growing Adoption of Electric Vehicles and In-Vehicle Charging Integration
The rising production of electric vehicles (EVs) creates new applications for wireless charging. Automakers are developing inductive systems that support fast, contactless charging for EVs. The Wireless Charging Market gains momentum from government incentives promoting sustainable transport. Charging pads embedded in parking spaces and garages enhance convenience for users. It offers a safer and more efficient alternative to plug-in chargers. Leading automotive firms invest in R&D to standardize power transfer infrastructure. Smart mobility initiatives encourage deployment of dynamic charging systems for EV fleets. The integration of wireless EV charging improves charging accessibility and efficiency worldwide.
Technological Advancements in Resonant and Inductive Charging Systems
Advances in magnetic resonance and inductive charging technologies are transforming power transfer efficiency. Companies develop multi-device chargers capable of handling varied power outputs. The Wireless Charging Market expands as new technologies support high-speed energy transfer. It ensures minimal heat generation and better alignment accuracy between devices. Semiconductor innovations enhance charging pad performance and cost-effectiveness. Global R&D investments target interoperability across brands and form factors. Increased focus on power density and compact designs improves usability. These innovations strengthen wireless power ecosystems across industries and consumer applications.
- For instance, NXP Semiconductors’ MWCT controller, announced in August 2020, powers vehicle wireless charging solutions allowing the simultaneous wireless charging of two 15W Qi devices in production vehicles, supported by their Qi-certified ICs and patented Clean EMC technology for improved compatibility and millions of deployed in-vehicle chargers.
Government Policies Supporting Sustainable Power and Infrastructure
Supportive regulations encourage adoption of energy-efficient charging technologies. Governments promote clean energy integration within urban infrastructure. The Wireless Charging Market benefits from policy-driven EV adoption and sustainability targets. It aligns with smart city initiatives focusing on green mobility solutions. Public transport systems explore inductive charging for electric buses and taxis. Global funding programs assist companies in developing scalable wireless energy networks. Industry collaborations with policymakers ensure standardized frameworks. This collaboration accelerates the transition toward eco-friendly power transmission systems.
Market Trends
Integration of Wireless Charging in Smart Homes and IoT Ecosystems
The incorporation of wireless power into smart homes is a rising trend. IoT-enabled devices use embedded transmitters for seamless energy transfer. The Wireless Charging Market gains from the expansion of interconnected consumer ecosystems. It promotes convenience through multi-device charging hubs. Smart furniture and office systems integrate wireless pads into tables and counters. Growth in IoT appliances encourages mass deployment of universal charging standards. Brands are developing adaptive charging surfaces for multi-room connectivity. This trend enhances energy management efficiency and user experience in digital homes.
Expansion of Public Wireless Charging Infrastructure in Urban Areas
Cities are increasingly investing in public wireless charging networks. Urban planners incorporate inductive pads into airports, cafes, and transport hubs. The Wireless Charging Market benefits from rising demand for shared charging solutions. It enhances mobility and reduces downtime for connected devices. Hospitality and retail sectors deploy commercial charging stations to attract customers. Public EV charging zones use inductive technology to support sustainable transport. Partnerships between municipalities and technology providers accelerate installations. Growing accessibility of public charging infrastructure fuels global adoption rates.
- For instance, WiTricity deployed its commercial wireless EV charging for autonomous e-buses with YuTong Bus in Zhengzhou, China, in 2023, featuring wireless inductive chargers for the Level 4 Xiaoyu 2.0 minibus fleet each bus seats 10 passengers and operates on a 150 km range powered entirely by wireless pad-based infrastructure.
Miniaturization and Design Innovation in Charging Components
Manufacturers emphasize compact, efficient, and aesthetically integrated wireless charging systems. Miniaturized coils and micro-transmitters improve portability and compatibility. The Wireless Charging Market is witnessing advancements in form factor flexibility. It allows embedding of transmitters in wearables, phones, and furniture. Product design focuses on low-heat, high-efficiency modules. Companies use composite materials to enhance durability and safety. Multi-coil platforms enable simultaneous device charging without placement precision. These innovations expand design freedom and consumer adoption.
Shift Toward Interoperable Multi-Standard Wireless Charging Solutions
The industry moves toward universal compatibility across devices and brands. Developers focus on integrating multiple standards such as Qi, PMA, and A4WP. The Wireless Charging Market evolves with efforts toward global interoperability. It ensures consistent user experience across electronics and vehicles. Organizations collaborate to set certification guidelines for safe power transfer. Manufacturers implement adaptive systems supporting varied wattage ranges. Such cross-platform compatibility increases adoption in both consumer and industrial domains. Standardization drives manufacturing efficiency and product reliability.
- For instance, Energous partnered with a Fortune 10 US retailer in April 2025 to modernize infrastructure at 4,700 stores nationwide with PowerBridge Pro transmitters, which support scalable wireless power networks able to charge diverse asset tags, sensors, and retail devices wirelessly regardless of device brand or standard, with interoperability central to the rollout.
Market Challenges Analysis
High Cost and Efficiency Limitations of Current Charging Technologies
The deployment of wireless charging remains expensive for both consumers and manufacturers. Complex coil designs and advanced power electronics increase production costs. The Wireless Charging Market faces difficulties in achieving optimal efficiency across devices. It suffers from energy losses during power transmission and heat buildup. Performance inconsistencies arise from misalignment between transmitter and receiver coils. Manufacturers must balance cost, durability, and efficiency to sustain competitiveness. Limited power output restricts large-scale use in industrial and automotive sectors. Overcoming these technical constraints requires significant investment and innovation.
Lack of Standardization and Compatibility Across Devices and Regions
The absence of unified global standards hampers seamless device compatibility. Competing protocols create confusion among consumers and slow adoption rates. The Wireless Charging Market struggles to integrate varying technologies under one framework. It faces interoperability issues between brands and product types. Regional disparities in certification hinder cross-border market expansion. Businesses invest heavily to comply with different regional requirements. Without a unified system, scaling remains limited in both consumer and automotive industries. Achieving harmonization across global standards is essential for sustained growth.
Market Opportunities
Expansion Across Electric Mobility and Infrastructure Sectors
The increasing use of EVs and e-bikes presents vast opportunities for wireless charging deployment. Urban mobility networks integrate dynamic charging lanes and smart parking pads. The Wireless Charging Market stands to benefit from this mobility revolution. It enables uninterrupted power transfer during vehicle operation or idle states. Governments and energy firms are investing in city-wide inductive charging grids. Automotive OEMs are incorporating wireless systems to enhance driver convenience. These developments unlock long-term growth potential for infrastructure and component providers.
Emerging Applications in Healthcare, Industrial, and Consumer Electronics
New use cases in healthcare and industrial automation open growth pathways. Hospitals use wireless charging for medical devices to ensure hygiene and mobility. The Wireless Charging Market gains momentum from factory automation systems integrating cable-free power. It supports safe and continuous energy delivery in harsh environments. Wearables and AR devices increasingly adopt embedded wireless modules. Industrial robots and sensors rely on inductive energy for extended uptime. These diversified applications expand market scope across end-user industries.
Market Segmentation Analysis:
The Wireless Charging Market is segmented by component, application, and technology, reflecting its diverse adoption across industries.
By component, transmitters hold a significant share due to their integration into charging pads, automotive stations, and smart furniture. Receivers are rapidly advancing with compact designs and higher energy transfer efficiency, driving adoption in mobile devices and wearables. Continuous improvements in receiver sensitivity and interoperability enhance user convenience and system reliability. It benefits from the integration of semiconductors that optimize performance, safety, and power conversion efficiency across multiple devices.
- For example, in October 2023, NuCurrent announced its NFC wireless charging technology used in the Poly Voyager Surround 85 UC headset. The innovation enables fast, connectorless charging, providing up to 21 hours of talk time and achieving an IP68 waterproof and dustproof rating through sealed charging ports.
By application, consumer electronics dominate due to the widespread use of smartphones, tablets, and wearables that support wireless charging. Automotive applications are growing quickly with the expansion of electric vehicles and in-vehicle charging features. Industrial and healthcare sectors adopt wireless systems for safety, automation, and uninterrupted power delivery in sensitive environments. Defense and other specialized applications benefit from secure, contactless power transfer that reduces maintenance and operational risks.
- For instance, Samsung’s Galaxy S24 Ultra, launched in 2024, supports up to 15W fast wireless charging and uses Wireless PowerShare enabling other Galaxy devices to be recharged wirelessly, as verified by Samsung’s product specifications and independent reviews.
By technology, inductive charging leads due to its maturity, safety, and high efficiency for short-range power transfer. Resonant technology follows, offering flexibility and multi-device charging capability. Radio frequency-based systems are gaining attention for long-distance energy transmission. It continues to evolve through research focused on power density, alignment accuracy, and cross-compatibility, enabling future-ready applications in both consumer and industrial domains.
Segmentation:
By Component
- Transmitters
- Receivers
By Application
- Automotive
- Consumer Electronics
- Industrial
- Healthcare
- Defense
- Others
By Technology
- Inductive
- Resonant
- Radio Frequency
- Others
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Wireless Charging Market size was valued at USD 788.33 million in 2018 to USD 1,622.68 million in 2024 and is anticipated to reach USD 9,268.81 million by 2032, at a CAGR of 24.5% during the forecast period. North America holds a market share of 24.9%. Strong demand for wireless power solutions in consumer electronics and electric vehicles drives regional growth. It benefits from advanced R&D capabilities and early adoption of innovative technologies. Automakers and tech companies invest heavily in developing in-vehicle charging and smart infrastructure. The U.S. dominates the region with strong manufacturing and innovation ecosystems. Increasing deployment of public charging stations enhances convenience for users. Strategic collaborations between OEMs and energy firms strengthen wireless charging penetration across industries.
Europe
The Europe Wireless Charging Market size was valued at USD 663.40 million in 2018 to USD 1,323.19 million in 2024 and is anticipated to reach USD 7,052.00 million by 2032, at a CAGR of 23.4% during the forecast period. Europe accounts for a market share of 19.0%. Growing adoption of electric mobility and sustainability goals fuel regional expansion. Governments support clean energy transitions through favorable incentives and public infrastructure. It benefits from strong automotive manufacturing bases in Germany, France, and the UK. Technology developers are focusing on interoperability and standardization across devices and vehicles. Integration of wireless charging in public transport enhances energy efficiency. Increasing consumer demand for convenience-based solutions strengthens market development. Industrial applications in automation and robotics further expand the regional footprint.
Asia Pacific
The Asia Pacific Wireless Charging Market size was valued at USD 1,373.92 million in 2018 to USD 2,948.33 million in 2024 and is anticipated to reach USD 17,857.42 million by 2032, at a CAGR of 25.3% during the forecast period. Asia Pacific dominates the global market with a share of 47.9%. Rapid growth in consumer electronics and EV adoption propels the region’s expansion. China, Japan, and South Korea lead due to strong manufacturing capabilities and government support for clean technologies. It benefits from high smartphone penetration and advanced electronics supply chains. Local manufacturers focus on fast-charging and multi-device platforms. Investment in public wireless charging infrastructure enhances accessibility. Strong competition among regional brands accelerates innovation cycles and cost efficiency.
Latin America
The Latin America Wireless Charging Market size was valued at USD 161.20 million in 2018 to USD 333.70 million in 2024 and is anticipated to reach USD 1,741.88 million by 2032, at a CAGR of 23.1% during the forecast period. Latin America represents a 4.7% share of the global market. Expanding urbanization and smartphone adoption drive market demand. Brazil leads with growing EV penetration and consumer awareness of advanced charging solutions. It benefits from import-friendly policies supporting technology inflow. Partnerships between telecom and energy sectors promote wireless power deployment. Retail and residential sectors increasingly adopt inductive charging systems. Rising e-commerce and connected device ecosystems strengthen regional adoption. Ongoing infrastructure investments create growth opportunities for manufacturers.
Middle East The Middle East Wireless Charging Market size was valued at USD 75.95 million in 2018 to USD 143.46 million in 2024 and is anticipated to reach USD 691.46 million by 2032, at a CAGR of 21.9% during the forecast period. The region contributes a 1.9% share of the global market. Growth is driven by smart city initiatives and investments in clean transportation. The UAE and Saudi Arabia are at the forefront of implementing inductive EV charging projects. It benefits from collaborations between technology providers and government entities. Wireless solutions are increasingly integrated into public spaces and hospitality sectors. Industrial automation and healthcare systems adopt contactless power for operational efficiency. Favorable regulations encourage private sector participation in infrastructure development.
Africa
The Africa Wireless Charging Market size was valued at USD 37.20 million in 2018 to USD 122.10 million in 2024 and is anticipated to reach USD 552.60 million by 2032, at a CAGR of 20.1% during the forecast period. Africa accounts for a 1.6% global share. Growing mobile connectivity and renewable energy adoption support early-stage market expansion. South Africa and Egypt lead in integrating wireless charging for consumer electronics. It faces challenges from limited infrastructure and high device costs. International collaborations improve access to affordable charging solutions. Emerging startups focus on localized innovation suited for energy-constrained areas. Public and private sector partnerships promote technological awareness. Expanding digitalization and urbanization will drive gradual adoption across the continent.
Key Player Analysis:
- Belkin International, Inc.
- ConvenientPower HK Ltd.
- Energous Corporation
- Ossia Inc.
- Plugless Power LLC
- Powercast Corporation
- Powermat Technologies
- Renesas Electronics Corporation
- Samsung Electronics
- Texas Instruments, Inc.
- WiTricity Corporation
Competitive Analysis:
The Wireless Charging Market features strong competition among global and regional players focusing on innovation, efficiency, and integration. Leading companies such as Samsung Electronics, Texas Instruments, WiTricity Corporation, Powermat Technologies, and Belkin International dominate through advanced product portfolios and extensive patent ownership. It emphasizes partnerships with automotive OEMs and consumer electronics brands to expand application reach. Firms invest in research to improve energy transfer speed, alignment precision, and multi-device compatibility. Emerging players like Ossia Inc. and Energous Corporation drive innovation in long-range and radio frequency-based charging. Strategic mergers, product launches, and technological collaborations strengthen market presence and scalability. Competition centers on cost optimization, performance reliability, and compliance with global standards. Growing emphasis on interoperability and safety standards will continue shaping future market positioning and differentiation among key participants.
Recent Developments:
- In October 2025, Belkin International announced the launch of its UltraCharge collection and other high-speed wireless charging solutions, designed to deliver up to 25W charging speeds. These products debuted at major events like IFA and are now available widely, marking Belkin’s most sustainable charging collection yet.
- In September 2025, ConvenientPower HK Ltd. entered a partnership with Avnet to accelerate innovation in wireless charging across the Asia-Pacific region. This strategic alliance enables both companies to leverage their strengths to enhance wireless charging solutions and market reach for consumer electronics and other applications.
- In September 2025, YFORE made headlines by debuting its latest wireless charging products at IAA MOBILITY 2025. During the event held from September 9 to 12, YFORE showcased innovative magnetic and supercharging technologies, fully supporting Qi 2.2 and Qi 1.3 protocols. The new chargers boast private protocols with boosted 50W power output and multiple protective features, offering both speed and safety improvements across a wide range of device categories.
- In September 2024, Apple unveiled its new 25W MagSafe wireless charger, designed to offer faster charging speeds with enhanced MagSafe technology for its current range of mobile devices. This launch represented Apple’s continued focus on improving user convenience through efficient, cable-free charging systems, and the product was officially introduced in September 2024 during its fall event.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application and Technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing integration of wireless power systems in electric vehicles will strengthen automotive charging adoption globally.
- Expansion of 5G and IoT ecosystems will enhance the demand for fast, contactless charging solutions across connected devices.
- Ongoing R&D will improve energy transfer efficiency, alignment accuracy, and power density for multi-device platforms.
- Growth in public charging infrastructure and smart furniture integration will drive commercial and residential adoption.
- Advancements in resonant and radio frequency technologies will unlock new use cases in industrial and healthcare environments.
- Strategic alliances between tech firms and automakers will accelerate wireless EV charging deployment and infrastructure scalability.
- Regulatory emphasis on energy efficiency and safety standards will shape product innovation and certification frameworks.
- Miniaturization of charging components will enable wider use in wearables, AR devices, and compact electronics.
- Emerging markets will witness rising adoption supported by infrastructure development and increasing consumer awareness.
- Continuous standardization efforts will ensure interoperability and drive consistent user experiences across global markets.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Consumer Electronics and Smart Devices
The proliferation of smartphones, wearables, and tablets is fueling demand for wireless charging solutions, as consumers seek cable-free convenience and multi-device compatibility. Major brands are embedding wireless charging in new models, driving widespread adoption.
Growing Adoption of Electric Vehicles and In-Vehicle Charging Integration
The surge in electric vehicle production is creating new opportunities for wireless charging, with automakers developing inductive systems for fast, contactless charging. Government incentives and smart mobility initiatives are accelerating the deployment of wireless EV charging infrastructure.
Technological Advancements in Resonant and Inductive Charging
Innovations in magnetic resonance and inductive charging are improving power transfer efficiency, enabling multi-device charging and reducing heat generation. Enhanced semiconductor designs and R&D investments are making wireless charging more reliable and cost-effective.
Government Policies Supporting Sustainable Power and Infrastructure
Supportive regulations and sustainability targets are encouraging the adoption of energy-efficient wireless charging technologies, especially in urban infrastructure and public transport. Policy-driven initiatives are aligning with smart city goals and expanding the market’s reach.
Expansion of Public and Commercial Wireless Charging Infrastructure
Cities and commercial venues are increasingly integrating wireless charging pads in public spaces, airports, and retail environments, making charging more accessible and convenient. This trend is boosting adoption rates and supporting the growth of the wireless charging market globally.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wireless Charging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wireless Charging Market projected to grow between 2024 and 2032?
Which Wireless Charging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wireless Charging Market?
Which is major segment in Wireless Charging market by technology?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Transmitters
- 1.2.2 Receivers
- 1.3 By Technology
- 1.3.1 Inductive
- 1.3.2 Resonant
- 1.3.3 Radio Frequency
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Automotive
- 1.4.2 Consumer Electronics
- 1.4.3 Industrial
- 1.4.4 Healthcare
- 1.4.5 Defense
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,493.46 million → 2032: USD 37,164.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wireless Charging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wireless Charging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wireless Charging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wireless Charging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wireless Charging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wireless Charging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wireless Charging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wireless Charging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,493.46 million → 2032: USD 37,164.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wireless Charging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Transmitters
- 12.3.7.2 Receivers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Inductive
- 12.4.7.2 Resonant
- 12.4.7.3 Radio Frequency
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Consumer Electronics
- 12.5.7.3 Industrial
- 12.5.7.4 Healthcare
- 12.5.7.5 Defense
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wireless Charging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wireless Charging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wireless Charging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wireless Charging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Electronics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Texas Instruments, Inc.
- 18.4 WiTricity Corporation
- 18.5 Belkin International, Inc.
- 18.6 Powermat Technologies
- 18.7 Energous Corporation
- 18.8 Ossia Inc.
- 18.9 ConvenientPower HK Ltd.
- 18.10 Plugless Power LLC
- 18.11 Renesas Electronics Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

