
Market Overview
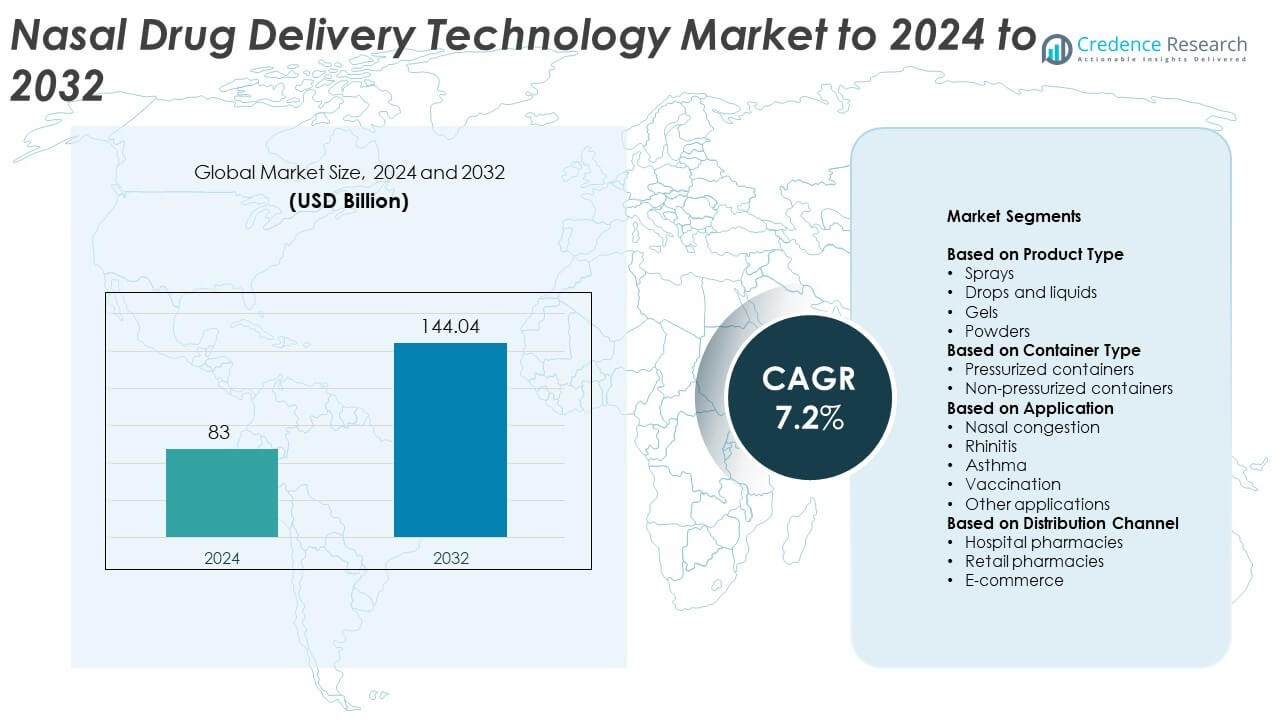
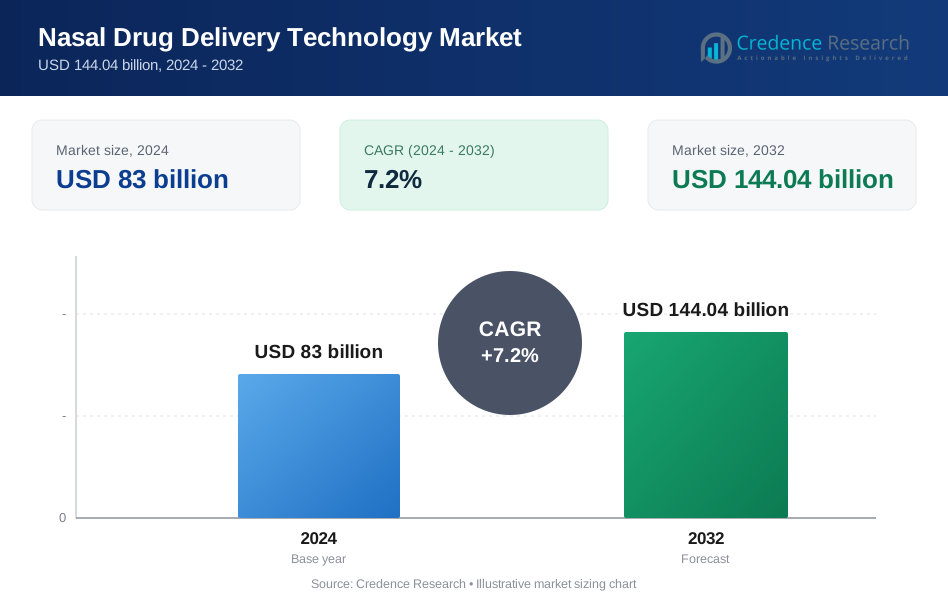
Nasal Drug Delivery Technology Market size was valued at USD 83 Billion in 2024 and is anticipated to reach USD 144.04 Billion by 2032, at a CAGR of 7.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Nasal Drug Delivery Technology Market Size 2024 | USD 83 Billion |
| Nasal Drug Delivery Technology Market, CAGR | 7.2% |
| Nasal Drug Delivery Technology Market Size 2032 | USD 144.04 Billion |
The nasal drug delivery technology market is led by major players including GlaxoSmithKline, Johnson & Johnson, Pfizer, Boehringer Ingelheim, Eli Lilly and Company, Merck, F. Hoffmann-La Roche AG, Takeda Pharmaceutical Company, Regeneron Pharmaceuticals, and AptarGroup. These companies dominate through extensive product portfolios, continuous innovation in intranasal formulations, and advanced device integration. Strategic partnerships and investments in R&D have strengthened their presence in both prescription and over-the-counter nasal therapies. Regionally, North America holds the largest share at 38.6% in 2024, supported by strong healthcare infrastructure and rapid adoption of nasal spray products, followed by Europe with 28.4% and Asia Pacific with 22.7%.
Market Insights
- The nasal drug delivery technology market was valued at USD 83 billion in 2024 and is projected to reach USD 144.04 billion by 2032, expanding at a CAGR of 7.2%.
- Rising demand for non-invasive, fast-acting drug delivery methods and growing cases of respiratory and allergic disorders are driving market expansion.
- Technological advances in smart nasal devices, powder formulations, and intranasal vaccines are shaping emerging trends and expanding therapeutic applications.
- The market remains highly competitive with strong participation from global pharmaceutical and biotech companies focusing on innovation and patient convenience.
- North America leads with a 38.6% share, followed by Europe at 28.4% and Asia Pacific at 22.7%, while sprays dominate by product type with a 46.7% segment share, supported by widespread adoption in allergy and pain management treatments.
Market Segmentation Analysis:
By Product Type
Sprays dominate the nasal drug delivery technology market with a 46.7% share in 2024. Their leadership is driven by ease of administration, rapid absorption, and suitability for self-medication. The growing adoption of metered-dose and multidose spray systems supports consistent dosing and patient compliance. Increased use of sprays for allergy, migraine, and pain therapies further strengthens their demand. Drops and liquids follow due to their effectiveness in pediatric and geriatric care, while gels and powders are expanding with innovations in controlled-release formulations and improved mucosal retention.
- For instance, Aptar Pharma reports “over 280” nasal spray and powder market references across Unidose/Bidose and multidose systems, showing wide spray adoption.
By Container Type
Non-pressurized containers lead the market with a 57.4% share in 2024. The segment benefits from lower manufacturing costs, lightweight design, and reduced environmental impact compared to pressurized formats. These containers are widely used in over-the-counter nasal sprays and solutions due to their convenience and safety. Rising adoption of pump bottles and squeezable containers enhances dosing precision. Pressurized containers maintain demand for aerosol-based and metered formulations, particularly in asthma and allergy treatments, where controlled spray patterns and fine mist dispersion remain critical for therapeutic efficiency.
- For instance, Glenmark confirms Ryaltris has launched in 34 markets as of March 2024, with later updates noting approvals and rollouts continuing across additional countries.
By Application
Nasal congestion holds the largest share of 39.6% in 2024, driven by the high prevalence of allergies, colds, and sinusitis globally. Decongestant sprays and saline formulations provide fast relief, boosting consumer preference for self-care products. Rhinitis and asthma segments are also expanding as nasal corticosteroids and bronchodilator therapies gain traction. Moreover, nasal vaccination emerges as a promising area due to needle-free delivery and rapid immune response, with ongoing research supporting intranasal vaccine formulations for influenza and other respiratory diseases.
Key Growth Drivers
Rising Demand for Non-Invasive Drug Delivery
Growing patient preference for non-invasive administration boosts nasal drug delivery adoption. The method offers rapid onset, improved bioavailability, and bypasses first-pass metabolism, enhancing therapeutic outcomes. Pharmaceutical companies increasingly develop intranasal formulations for pain, migraine, and hormone therapies to improve convenience and compliance. The expanding use of nasal routes for central nervous system and peptide-based drugs strengthens this trend, supporting continuous innovation in formulation and delivery systems.
- For instance, Amphastar’s Baqsimi (nasal glucagon) is marketed in 27 countries, evidencing patient pull for needle-free, rapid-onset delivery.
Advancements in Nasal Formulation Technologies
Technological innovation in nasal formulations drives market growth by improving absorption efficiency and stability. Developments in mucoadhesive gels, powder-based systems, and nanoparticle carriers enhance drug retention and controlled release. These advances enable the delivery of larger biomolecules such as proteins and vaccines, expanding therapeutic applications. Continuous R&D investments from leading pharmaceutical manufacturers promote better patient outcomes and broaden adoption across chronic disease treatments.
- For instance, SNBL’s SMART nasal powder platform has been evaluated in “more than 150” human subjects, supporting tech advances that improve retention and stability.
Increasing Incidence of Respiratory and Allergic Disorders
The surge in allergic rhinitis, sinusitis, and asthma cases globally accelerates demand for nasal delivery products. Urbanization, pollution, and lifestyle factors contribute to growing respiratory complications. Nasal sprays and decongestants remain first-line therapies, offering quick relief and ease of use. Rising awareness of self-care and availability of over-the-counter treatments further drive volume growth across both developed and emerging markets.
Key Trends and Opportunities
Emergence of Intranasal Vaccination Platforms
The development of needle-free nasal vaccines is transforming immunization practices. Intranasal delivery enables rapid mucosal immunity, reducing the need for trained healthcare professionals. Research on influenza, COVID-19, and RSV vaccines via nasal routes showcases expanding opportunities. This trend aligns with global healthcare focus on accessible, patient-friendly, and cost-effective vaccination models.
- For instance, CyanVac received U.S. BARDA Project NextGen support for an intranasal COVID-19 vaccine trial enrolling 10,000 volunteers, highlighting momentum in mucosal vaccination.
Integration of Smart and Digital Nasal Devices
Smart nasal delivery systems with sensors and Bluetooth connectivity are gaining traction. These devices allow dosage monitoring, compliance tracking, and real-time data integration with mobile apps. The combination of digital health and nasal delivery enhances patient adherence and treatment personalization. Pharmaceutical collaborations with medtech firms continue to expand this high-potential segment.
- For instance, Kurve Technology notes its ViaNase electronic atomizer has been used in numerous studies and research programs-specifically, an article published in a peer-reviewed journal in 2023 references 16 programs, 14 in-clinic, associated with the device, reflecting growing interest in smart/electronic nasal delivery systems for applications like nose-to-brain delivery.
Expansion into Central Nervous System Therapies
Nasal routes are emerging as efficient alternatives for brain-targeted drugs. Direct delivery through the olfactory region enables bypassing the blood-brain barrier, improving treatment for conditions such as epilepsy and depression. Pharmaceutical companies are exploring intranasal formulations for rapid-acting therapies, creating new growth avenues within neurological and psychiatric drug segments.
Key Challenges
Formulation Stability and Drug Absorption Limitations
Achieving consistent bioavailability and stability in nasal formulations remains a technical challenge. Factors like mucociliary clearance, enzymatic degradation, and variable absorption rates limit performance. Manufacturers must invest in advanced excipients and enhancers to ensure reliable therapeutic effects. These complexities slow development timelines and increase regulatory hurdles.
Stringent Regulatory and Manufacturing Constraints
The nasal drug delivery sector faces strict quality and safety regulations across global markets. Compliance with Good Manufacturing Practices and validation of device-drug combinations increase operational costs. Varying regional approval standards also delay commercialization. These regulatory pressures require continuous testing, documentation, and post-market surveillance, impacting product launch efficiency.
Regional Analysis
North America
North America leads the nasal drug delivery technology market with a 38.6% share in 2024. The dominance stems from advanced healthcare infrastructure, strong pharmaceutical innovation, and high adoption of self-administration drug systems. The U.S. drives market leadership through rapid uptake of nasal sprays for allergy, migraine, and pain management. Growing approvals of intranasal vaccines and emergency drugs, such as naloxone for opioid overdose, further expand market penetration. Increasing focus on patient convenience and digital integration in nasal devices continues to enhance growth across the region.
Europe
Europe holds a 28.4% share of the global market in 2024, supported by strong R&D investments and robust regulatory frameworks. The region benefits from rising prevalence of allergic rhinitis and chronic sinusitis, encouraging demand for over-the-counter nasal sprays. Germany, France, and the U.K. lead adoption due to advanced healthcare systems and growing awareness of non-invasive delivery methods. Strategic collaborations between pharmaceutical and biotech companies accelerate innovation in powder-based and controlled-release nasal formulations across the continent.
Asia Pacific
Asia Pacific accounts for a 22.7% share in 2024, emerging as the fastest-growing regional market. Expansion is driven by increasing respiratory disease prevalence, urban pollution, and rising healthcare expenditure. Japan and China lead adoption, supported by strong local manufacturing and government initiatives to promote intranasal vaccination. Rapid penetration of e-commerce channels and expanding access to affordable generic formulations boost consumer reach. Growing interest in innovative nasal drug delivery technologies for chronic and neurological diseases also strengthens market prospects across the region.
Latin America
Latin America captures a 6.2% share of the global market in 2024, driven by rising incidence of respiratory allergies and asthma. Brazil and Mexico dominate due to expanding pharmaceutical distribution networks and improved access to non-prescription nasal therapies. Increased awareness of nasal drug delivery benefits and the growing availability of cost-effective generics support steady growth. However, limited healthcare reimbursement and uneven regulatory harmonization across countries remain moderate restraints on faster adoption within the region.
Middle East and Africa
The Middle East and Africa region holds a 4.1% share in 2024, showing gradual but steady market growth. Expansion is supported by rising healthcare modernization, urbanization, and awareness of nasal delivery for allergy and cold treatment. Gulf countries such as Saudi Arabia and the UAE lead adoption due to improved healthcare access and strong retail pharmacy presence. Increasing partnerships between global pharmaceutical firms and regional distributors are expanding product availability. Nonetheless, affordability and infrastructure gaps continue to limit market penetration in several African nations.
Market Segmentations:
By Product Type
- Sprays
- Drops and liquids
- Gels
- Powders
By Container Type
- Pressurized containers
- Non-pressurized containers
By Application
- Nasal congestion
- Rhinitis
- Asthma
- Vaccination
- Other applications
By Distribution Channel
- Hospital pharmacies
- Retail pharmacies
- E-commerce
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The nasal drug delivery technology market is characterized by strong competition among leading pharmaceutical, biotechnology, and device manufacturing companies such as GlaxoSmithKline, Regeneron Pharmaceuticals, Aegis Therapeutics, Johnson & Johnson, Neuralstem, Takeda Pharmaceutical Company, Boehringer Ingelheim, Pfizer, AptarGroup, F. Hoffmann-La Roche AG, Horizon Therapeutics, Merck, Eli Lilly and Company, and Nasal Technologies. The competitive environment is driven by innovation in formulation design, device integration, and patient-focused delivery systems. Market players are emphasizing the development of advanced nasal sprays, powders, and gels that ensure improved absorption, bioavailability, and dosing precision. Strategic collaborations between drug manufacturers and device engineers are enhancing the efficiency of combination therapies and expanding therapeutic reach into CNS, vaccine, and pain management areas. The growing adoption of smart inhalation technologies, coupled with regulatory support for needle-free delivery systems, continues to fuel new product launches and strengthen the overall competitive positioning of leading companies.
Key Player Analysis
- GlaxoSmithKline
- Regeneron Pharmaceuticals
- Aegis Therapeutics
- Johnson & Johnson
- Neuralstem
- Takeda Pharmaceutical Company
- Boehringer Ingelheim
- Pfizer
- AptarGroup
- F. Hoffmann-La Roche AG
- Horizon Therapeutics
- Merck
- Eli Lilly and Company
- Nasal Technologies
Recent Developments
- In 2025, Aptar's nasal delivery system was used in a brain imaging study confirming effective delivery of intranasal insulin to brain memory regions, supporting new Alzheimer's treatments.
- In 2024, Regeneron collaborated with healthcare providers to expand access to Dupixent® for nasal polyposis.
- In 2023, Aptar Pharma launched a recyclable, metal-free, multidose nasal spray pump.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Container Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow with rising preference for non-invasive drug delivery methods.
- Intranasal vaccines will gain momentum due to increased demand for needle-free immunization.
- Digital and smart nasal devices will improve patient adherence and remote monitoring capabilities.
- Advancements in powder and gel formulations will enhance stability and absorption.
- More pharmaceutical companies will invest in nasal delivery for CNS-targeted therapies.
- Over-the-counter nasal products will see steady demand from allergy and cold treatment segments.
- Emerging markets will drive future growth through improved access and awareness.
- Regulatory approvals for combination device-drug nasal products will expand product portfolios.
- E-commerce will play a bigger role in retail distribution and direct-to-consumer models.
- Collaborations between pharma and biotech firms will accelerate innovation in nasal delivery platforms.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Nasal Drug Delivery Technology Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Nasal Drug Delivery Technology Market projected to grow between 2025 and 2032?
Which Nasal Drug Delivery Technology Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Nasal Drug Delivery Technology Market?
Who are the leading companies in the Nasal Drug Delivery Technology Market?
Which region commanded the largest share of the Nasal Drug Delivery Technology Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Nasal Drug Delivery Technology Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Nasal Drug Delivery Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 83 billion → 2032: USD 144.04 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Nasal Drug Delivery Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Nasal Drug Delivery Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Nasal Drug Delivery Technology Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Nasal Drug Delivery Technology Market Drivers
- 3.3 Nasal Drug Delivery Technology Market Restraints & Challenges
- 3.4 Nasal Drug Delivery Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Nasal Drug Delivery Technology Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Nasal Drug Delivery Technology Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Nasal Drug Delivery Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Nasal Drug Delivery Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Nasal Drug Delivery Technology Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Nasal Drug Delivery Technology. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Nasal Drug Delivery Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Nasal Drug Delivery Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Nasal Drug Delivery Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Nasal Drug Delivery Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Nasal Drug Delivery Technology
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Nasal Drug Delivery Technology Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Nasal Drug Delivery Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Nasal Drug Delivery Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Nasal Drug Delivery Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Nasal Drug Delivery Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Nasal Drug Delivery Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Nasal Drug Delivery Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Nasal Drug Delivery Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
