
Market Overview
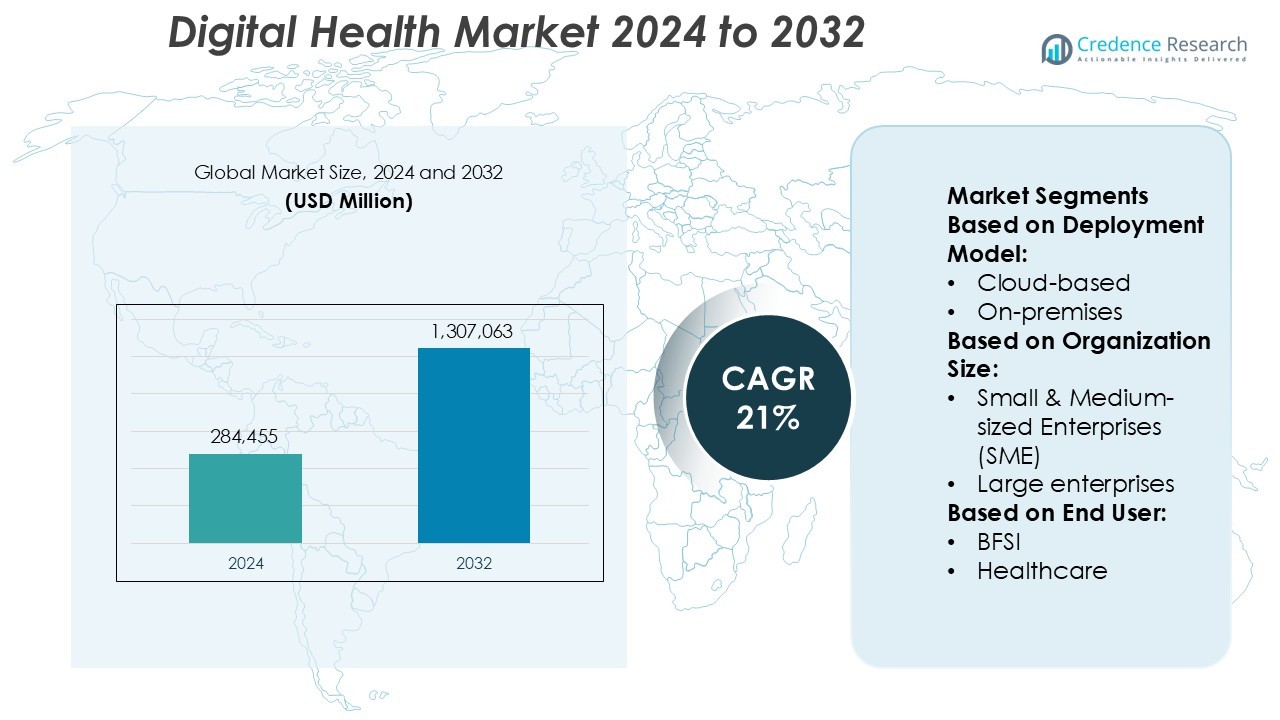
Digital Health Market size was valued USD 284,455 million in 2024 and is anticipated to reach USD 1,307,063 million by 2032, at a CAGR of 21% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Health Market Size 2024 | USD 284,455 Million |
| Digital Health Market, CAGR | 21% |
| Digital Health Market Size 2032 | USD 1,307,063 Million |
The digital health market is highly competitive, driven by the presence of global technology firms and healthcare innovators advancing digital transformation. Leading players focus on expanding their product portfolios, integrating AI and cloud solutions, and forming cross-sector partnerships to strengthen service delivery. Companies are investing in telemedicine, digital therapeutics, and remote monitoring technologies to meet the rising demand for accessible healthcare. North America leads the market with a 39% share, supported by advanced infrastructure, favorable regulations, and early adoption of digital platforms. Strong R&D investments, strategic collaborations, and growing consumer awareness continue to define the competitive dynamics of the global digital health landscape.
Market Insights
- The digital health market was valued at USD 284,455 million in 2024 and is projected to reach USD 1,307,063 million by 2032, registering a CAGR of 21% during the forecast period.
- Key drivers include increasing adoption of telemedicine, AI-based diagnostics, and digital therapeutics enhancing remote patient management and real-time care.
- The market trends highlight rapid integration of cloud-based platforms and wearable health technologies supporting data-driven personalized healthcare solutions.
- Competitive dynamics are shaped by strategic collaborations, R&D investments, and expansion by major global technology firms and healthcare innovators.
- North America leads with a 39% market share, supported by strong infrastructure and regulatory frameworks, while the cloud-based deployment segment continues to dominate due to scalability and interoperability advantages.
Market Segmentation Analysis:
By Deployment Model
The cloud-based segment dominates the digital health market with a market share of 68%. Its growth is driven by scalable data storage, remote accessibility, and lower infrastructure costs. Healthcare providers increasingly prefer cloud platforms for integrating telemedicine, electronic health records, and patient monitoring systems. The adoption of AI-enabled cloud analytics enhances real-time diagnostics and personalized treatment plans. On-premises solutions remain relevant for institutions requiring tighter data control, yet the rapid expansion of hybrid and multi-cloud models strengthens the cloud segment’s leadership in the digital health ecosystem.
- For instance, AirStrip Technologies uses Microsoft Azure’s HIPAA-compliant cloud to enable secure access to patient waveform data through its mobile platform. The system processes over 3 terabytes of patient monitoring data daily, allowing physicians to review ECG and fetal heart rate patterns remotely within seconds.
By Organization Size
Large enterprises hold a major share of 61% in the digital health market. Their dominance stems from higher investments in digital transformation, cybersecurity, and enterprise-level data integration systems. These organizations leverage advanced analytics and IoT-enabled devices to streamline workflows and improve patient engagement. Meanwhile, small and medium-sized enterprises (SMEs) are adopting modular SaaS-based platforms due to affordability and flexibility. Government incentives and cloud-based healthcare ecosystems further enable SMEs to close the digital gap, but large enterprises continue to lead through comprehensive adoption of health IT infrastructure.
- For instance, Orange Healthcare, a subsidiary of Orange Group, operates over 40 secure data centers across Europe to support large-scale healthcare digitization. The company’s Flexible Engine Cloud, built on OpenStack architecture, processes more than 100 million healthcare transactions annually for hospitals and research institutions.
By End User
The healthcare segment leads the digital health market with a 54% share. Rising adoption of telehealth, remote diagnostics, and AI-driven patient management tools fuels this dominance. Hospitals and clinics are investing in digital platforms to enhance clinical efficiency and patient outcomes. BFSI and IT & telecom sectors follow, integrating wellness programs and employee health monitoring systems. The retail and e-commerce sectors are expanding digital wellness offerings, while manufacturing and travel industries adopt health management apps for workforce well-being. However, healthcare remains the primary growth driver due to continuous innovation in digital therapeutics and connected care.
Key Growth Drivers
- Rising Adoption of Telemedicine and Remote Patient Monitoring The growing demand for telemedicine and remote patient monitoring drives digital health market expansion. Increasing internet penetration and smartphone adoption enable patients to access healthcare from anywhere. Providers use digital platforms to monitor chronic conditions, reducing hospital visits and costs. The integration of IoT-based medical devices and wearables allows real-time health tracking and early intervention. This digital shift enhances healthcare accessibility, especially in rural and underserved regions, supporting efficient management of large patient populations while improving treatment outcomes.
- For instance, QSI Management, LLC, through its subsidiary NextGen Healthcare, operates one of the largest connected care platforms in the U.S., supporting over 100,000 providers and 150 million patient records.
- Increasing Integration of Artificial Intelligence in Healthcare Artificial intelligence (AI) is revolutionizing digital health through predictive analytics, imaging diagnostics, and personalized treatment. AI-powered algorithms process massive healthcare datasets to detect diseases faster and improve accuracy. Hospitals and research institutions utilize machine learning tools for early disease detection, optimizing patient care pathways. AI chatbots and virtual assistants improve engagement and support telehealth services. As healthcare digitization accelerates, AI integration enhances operational efficiency and clinical decision-making, driving adoption across diagnostic imaging, drug discovery, and patient management applications.
- For instance, Hims & Hers Health, Inc. leverages AI within its virtual care platform to optimize clinical matching and prescription accuracy. The company’s proprietary CareAI Engine analyzes over 400,000 anonymized patient interactions weekly to personalize treatment recommendations for dermatology, sexual health, and mental wellness.
- Government Initiatives and Digital Infrastructure Development Government investments in digital health infrastructure significantly propel market growth. Many countries are implementing national electronic health record (EHR) systems and telehealth reimbursement policies to enhance healthcare delivery. Regulatory support for digital platforms and interoperability standards promotes innovation. Public-private partnerships further drive the development of secure data exchange networks and connected care systems. Initiatives such as digital health missions and e-health programs encourage hospitals and clinics to transition from manual systems to cloud-based solutions, ensuring improved access, transparency, and continuity of care.
Key Trends & Opportunities
- Expansion of Wearable Health Technologies Wearable devices are becoming central to preventive healthcare and patient engagement. Smartwatches, fitness bands, and biosensors continuously monitor parameters like heart rate, glucose, and oxygen levels. Data collected from wearables supports predictive analytics and personalized treatment. Technology firms and healthcare providers are partnering to create connected ecosystems integrating wearables with digital platforms. The rising consumer interest in self-monitoring and fitness tracking presents strong opportunities for companies developing advanced wearable sensors and AI-driven health monitoring applications.
- For instance, AT&T provides the foundational secure network connectivity (including 5G and IoT services) that numerous third-party healthcare companies use to power their remote patient monitoring and connected health solutions, enabling real-time collection of biometric data from various FDA-cleared devices.
- Growth of Cloud-Based Healthcare Solutions The migration toward cloud-based digital health systems offers scalability, interoperability, and cost efficiency. Cloud platforms support centralized data management, enabling secure access to patient information across multiple providers. Healthcare organizations benefit from reduced IT overheads and enhanced collaboration between teams. The use of cloud infrastructure also facilitates big data analytics, AI model deployment, and telehealth scalability. This trend creates new business models for health IT providers and strengthens digital transformation efforts across global healthcare networks.
- For instance, Google launched its Cloud Healthcare API, a fully-managed service that ingests, stores and transforms clinical data in FHIR, HL7v2 and DICOM formats, supporting thousands of requests per second and delivering 11-9-9 (99.999999999%) annual data durability for healthcare datasets.
Key Challenges
- Data Privacy and Cybersecurity Concerns The growing volume of sensitive medical data increases vulnerability to cyberattacks and breaches. Ensuring compliance with regulations such as HIPAA and GDPR remains a top priority for healthcare providers. Weak encryption, inadequate access control, and poor cybersecurity infrastructure create major risks. Data theft and ransomware incidents undermine patient trust and slow digital adoption. Companies must invest in advanced encryption, multi-factor authentication, and real-time threat detection systems to maintain security and safeguard healthcare information.
- Interoperability and System Integration Issues Interoperability challenges among healthcare systems hinder seamless data exchange and clinical coordination. Many hospitals use outdated software that lacks compatibility with modern digital platforms. The absence of standardized protocols complicates integration across devices, EHRs, and telehealth applications. As a result, data silos and inefficiencies persist within healthcare networks. Achieving interoperability requires unified frameworks, open APIs, and consistent data formats, enabling smooth communication between healthcare providers and improving overall digital ecosystem performance.
Regional Analysis
North America
North America dominates the digital health market with a 39% share. Strong healthcare infrastructure, early adoption of advanced technologies, and supportive government policies drive regional growth. The U.S. leads due to its extensive use of telemedicine, AI-driven diagnostics, and electronic health record (EHR) systems. Major players such as Teladoc Health and Cerner Corporation continue to invest in AI and data analytics for personalized care. Increasing healthcare digitization, favorable reimbursement frameworks, and rising demand for remote patient monitoring reinforce North America’s leadership in global digital health innovation.
Europe
Europe accounts for 27% of the digital health market share, supported by strong regulatory frameworks and digital transformation initiatives. Countries like Germany, the U.K., and France are advancing telehealth and e-prescription systems to enhance accessibility. The European Commission’s Digital Health Strategy and investments in cross-border health data exchange promote interoperability. Growing aging populations and rising chronic disease prevalence accelerate digital adoption. Healthcare providers increasingly integrate AI-enabled tools and cloud solutions, while strict data protection under GDPR ensures patient trust. These factors collectively strengthen Europe’s position as a key digital health hub.
Asia-Pacific
Asia-Pacific holds a 24% share of the digital health market and exhibits the fastest growth rate globally. Rapid urbanization, rising healthcare expenditure, and strong government support for telemedicine drive market expansion. Countries such as China, India, Japan, and South Korea are heavily investing in mobile health apps and AI-based diagnostics. Start-ups and tech giants collaborate to enhance digital accessibility in rural regions. Increasing smartphone penetration and growing awareness of preventive healthcare contribute to the adoption of digital platforms. The region’s dynamic digital ecosystem positions it as a major growth frontier in healthcare technology.
Latin America
Latin America captures an 6% share of the digital health market, with Brazil and Mexico leading adoption. Governments across the region are introducing telehealth regulations to extend medical access in underserved areas. The growing use of mobile health platforms and wearable technologies supports chronic disease management. However, infrastructure gaps and data security concerns remain challenges. Private investments in health tech start-ups are increasing, aiming to modernize healthcare systems. As digital literacy improves and public initiatives expand, Latin America continues to emerge as an evolving digital healthcare landscape.
Middle East & Africa
The Middle East & Africa region represents 4% of the global digital health market. Increasing government investments in smart hospitals and e-health platforms drive market progress. The UAE and Saudi Arabia lead with strong national digital health strategies and telemedicine adoption. Expanding internet connectivity and mobile-based healthcare services support remote patient care. Despite limited healthcare infrastructure in parts of Africa, international partnerships and funding initiatives are bridging gaps. The region’s ongoing focus on healthcare modernization positions it for gradual yet sustained growth in digital health technologies.
Market Segmentations:
By Deployment Model:
- Cloud-based
- On-premises
By Organization Size:
- Small & Medium-sized Enterprises (SME)
- Large enterprises
By End User:
- BFSI
- Healthcare
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The digital health market features strong competition among key players such as AirStrip Technologies, Orange, QSI Management, LLC, Hims & Hers Health, Inc., AT&T, Epic Systems Corporation, Google, Inc., Telefónica S.A., Computer Programs and Systems, Inc., and Softserve. The digital health market is defined by continuous innovation, strategic collaborations, and rapid technological advancement. Companies are investing heavily in AI, big data analytics, and cloud computing to enhance patient care and optimize healthcare operations. Partnerships between technology firms and healthcare providers are expanding access to telemedicine and remote monitoring services. The focus on interoperability and secure data sharing strengthens system efficiency and compliance with global health standards. Additionally, the rise of digital therapeutics, mobile health applications, and wearable integration is reshaping healthcare delivery models, fostering patient-centered and data-driven ecosystems worldwide.
Key Player Analysis
- AirStrip Technologies
- Orange
- QSI Management, LLC
- Hims & Hers Health, Inc.
- AT&T
- Epic Systems Corporation
- Google, Inc.
- Telefónica S.A.
- Computer Programs and Systems, Inc.
- Softserve
Recent Developments
- In March 2025, Prudential Group Holdings (UK) and Vama Sundari Investments (Delhi) Private Limited, an HCL Group promoter company, announced to enter a joint venture to launch a standalone health insurance business in India. This strategic move aims to capitalize on India's rapidly growing health insurance market and contribute to the Indian government's vision of "Insurance for All by 2047".
- In March 2025, Adobe launched the Adobe Experience Platform Agent Orchestrator, enabling businesses to use AI agents for optimizing websites, automating content production, refining audiences, and scaling digital media. The company also introduced Brand Concierge, an AI-driven app that delivers personalized, brand-centric customer experiences by leveraging a company's unique attributes and customer data.
- In February 2025, Bajaj Allianz's launched HERizon Care, a comprehensive health insurance plan specifically designed for women. It is notable for being the first health insurance plan in India to integrate multiple specialized benefits tailored to women's unique healthcare needs within a single policy. HERizon Care is structured around two primary covers:Vita Shield and Cradle Care.
- In August 2024, ICICI Lombard partnered with seven institutions to enhance its distribution network. The partnership aims to increase the company's reach and provide insurance products to a wider audience. This partnership is likely to have a positive impact on ICICI Lombard's business, enabling the company to expand its customer base and increase its market share in the insurance industry.
Report Coverage
The research report offers an in-depth analysis based on Deployment Model, Organization Size, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Artificial intelligence will enhance predictive diagnostics and personalized treatment plans.
- Telemedicine adoption will expand with stronger broadband and 5G infrastructure.
- Cloud-based healthcare platforms will dominate data management and interoperability.
- Wearable devices will play a greater role in preventive and continuous health monitoring.
- Integration of digital therapeutics will become a standard in chronic disease management.
- Blockchain technology will improve data security and patient record transparency.
- Virtual and augmented reality tools will advance remote training and rehabilitation programs.
- Governments will increase investments in digital health infrastructure and e-health policies.
- Partnerships between tech firms and healthcare providers will accelerate digital innovation.
- Patient-centric digital ecosystems will redefine care delivery through connected health solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Digital Health Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Digital Health Market projected to grow between 2025 and 2032?
Which Digital Health Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Digital Health Market?
Who are the leading companies in the Digital Health Market?
Which region commanded the largest share of the Digital Health Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 284,455 million → 2032: USD 1,307,063 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Health Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Health Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Digital Health Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Digital Health Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Health Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Health Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Health Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Health Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 284,455 million → 2032: USD 1,307,063 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Health Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Health Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Digital Health Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Digital Health Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

